
- Home
- »
- Medical Devices
- »
-
Clinical Chemistry Analyzers Market Size, Growth Report, 2026-2033GVR Report cover

Clinical Chemistry Analyzers Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Analyzers, Reagents), By Test (Basic Metabolic Panel, Electrolyte Panel), By End-use, By Region, And Segment Forecasts
Market Size, 2025
$20.6BMarket Estimate, 2026
$21.6BMarket Forecast, 2033
$30.7BCAGR, 2026–2033
5.2%Clinical Chemistry Analyzers Market Summary
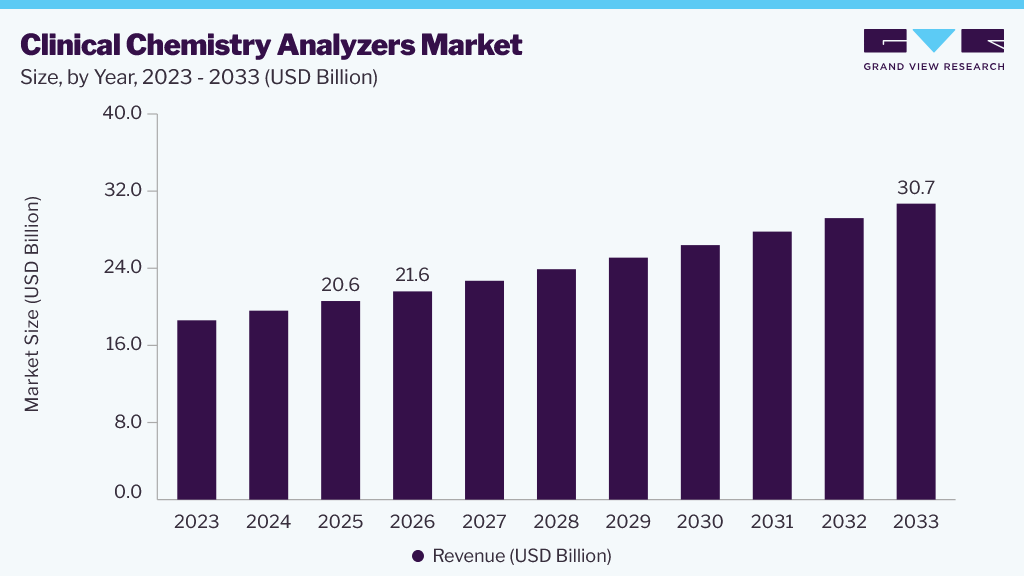
The global clinical chemistry analyzers market size was valued at USD 20.6 billion in 2025 and is projected to grow from USD 21.6 billion in 2026 to USD 30.7 billion by 2033, at a CAGR of 5.2% from 2026 to 2033. The market in North America dominated the market, accounting for a revenue share of 36.0% in 2025. The rising prevalence of chronic diseases, including diabetes, is a key factor driving market growth by increasing the demand for advanced diagnostic solutions. In response to the growing need for efficient disease diagnosis and monitoring, companies are expanding their clinical chemistry analyzer portfolios, driving greater innovation and competition in the market.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: The reagents segment dominated the market, with a revenue share of about 56.0% in 2025.
- By test: The basic metabolic panel (BMP) segment dominated the market, with a revenue share of about 31.0% in 2025.
- By end use: The hospitals segment dominated the market, with a revenue share of about 60.0% in 2025.
Regional Highlights
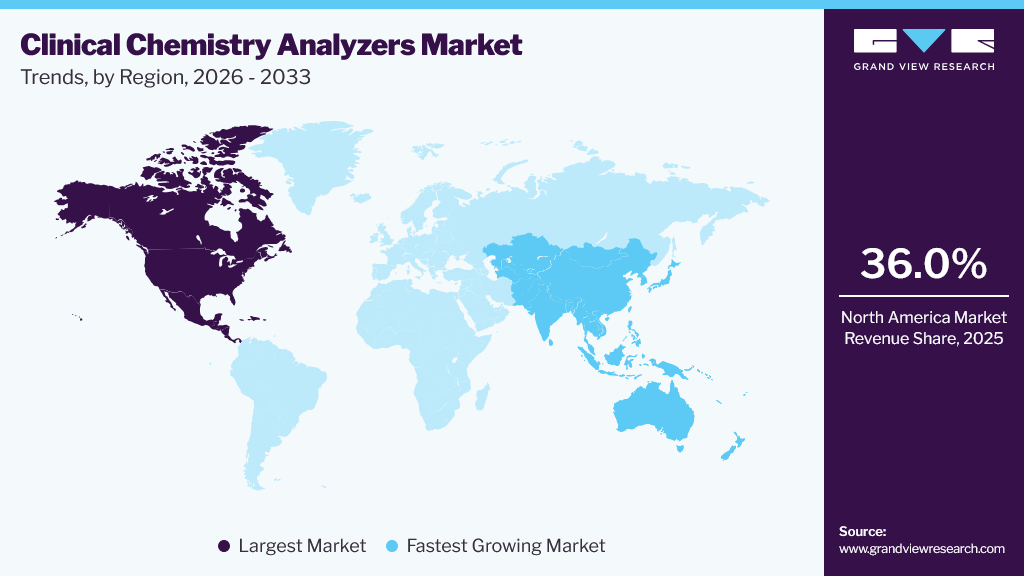
- Largest regional market: North America (36.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 20.6 Billion
- Estimated market size in 2026: USD 21.6 Billion
- Projected market size by 2033: USD 30.7 Billion
- CAGR (2026-2033): 5.2%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The technological innovations in clinical chemistry products have led to early disease detection and specialized diagnosis in the areas of oncology, gynecology, & endocrinology, and enabled testing on a larger scale. The advancements comprise better resolution, advanced modeling & parameter estimation, computer-assisted interpretation, improved pattern recognition, and artificial intelligence (AI).
The benefits of the above-mentioned advancements and automated analyzers are automatic data acquisition, greater process control allowing real-time automation, efficient parameter monitoring, and automatic variable adjustment. These tools also offer analysis of a wide range of samples and facilitate the immediate generation of results, reflecting their potential use in the intensive care unit, outpatient clinics, and emergency and surgical wards in the future. These benefits are expected to drive physicians' preference for these solutions, creating high-potential growth opportunities during the forecast period.
However, one of the major restraints for laboratories, hospitals, and manufacturers in the global market is the high capital investments required for these instruments, which will lead to a high cost of the tests, decreased affordability, and increase the entry and exit barriers for new entrants. However, various steps are being taken to decrease the initial setup cost, such as reagent rental agreements and cost-per-test, which will help in a significant reduction of cost and help in the growth of the market. Also, limited investments and reimbursements for these diagnostic tests and the availability of cheaper diagnostic methods are expected to hinder the growth of the market.
Analyst Perspective
The clinical chemistry analyzers market is expected to experience robust growth, driven by the rising prevalence of chronic diseases, the growing demand for early disease diagnosis, and expanding laboratory testing volumes worldwide. Increasing use of automation in diagnostic labs is increasing efficiency, accuracy, and speed of testing, thus driving the growth of the market. Rising incidences of diabetes, heart problems, and liver disorders are causing high demand for clinical chemistry testing. Further, technological developments such as analyzer integration, increased throughput technologies, and digital lab technologies are contributing to operations. However, high equipment costs and maintenance requirements may moderately restrain market growth in the coming years.
Product Insights
The reagents segment dominated the market, accounting for about 56.0% of revenue in 2025. The substantial share is predicted to result from an array of reagents on the market, catering to the different requirements of clinicians. These reagents predominantly include enzymes, substrates, specific proteins, electrolytes, lipids, and other components, which are imperative for obtaining accurate results in analytical procedures. In addition, reagents are believed to be highly cost-efficient and possess optimum sensitivity, linearity, and precision, which thereby ensures minimized performance variation. The aforementioned benefits are expected to be a major driver of clinicians' use of reagents for accurate diagnosis.
The analyzers segment is expected to grow the fastest CAGR over the forecast period, owing to the wide product range and extensive utilization in the diagnosis of chronic diseases. Moreover, technological advancements and high R&D expenditure have led to the development of advanced analyzers that offer advantages such as higher resolution, faster diagnosis, improved point-of-care testing capabilities, computer-assisted interpretation, and more. The above-mentioned advantages are expected to boost the analyzer market over the forecast period.
Test Insights
The basic metabolic panel (BMP) segment dominated the market, with a revenue share of about 31.0% in 2025, owing to the growing prevalence of lifestyle-induced diseases, such as obesity and other metabolic abnormalities. The rising importance of and awareness regarding point-of-care testing is also one of the key contributing factors toward the segment share. BMP comprises a set of tests that provide medical examiners with clinical information about problems caused by a chemical imbalance in the body. The associated benefits of this test have resulted in the high acceptance of the same, thereby widening the segment share over the years. Moreover, BMP is increasingly used and accepted across a wide array of applications, such as newborn screening, which facilitates early detection of congenital genetic and metabolic disorders.
The electrolyte panel segment is anticipated to witness significant growth over the forecast period. Electrolyte tests are vital for the estimation of sodium, potassium, chloride, and bicarbonate, which are key parameters in measuring the health status of the kidneys, fluid levels, and acid-base balance in the body. The rising cases of chronic kidney disease, heart problems, and diabetes have created a high demand for the need to test electrolytes. Moreover, the rising cases of hospitalization and emergency care will positively contribute towards segment growth owing to the importance of electrolyte tests in diagnosing diseases.
End Use Insights
The hospitals segment dominated the market, with a revenue share of about 60.0% in 2025, owing to the high patient volume, frequent readmissions, and large sample volumes. Moreover, supportive infrastructure facilitates successful diagnostic procedures, thus resulting in a higher share of hospitals. The increasing number of government initiatives aimed at promoting efficient diagnostic facilities to generate quick results and improve overall efficiency also serves as a key contributing factor to the substantial share of the segment.
In addition, in the current scenario, hospitals are increasingly inclined to acquire fully automated systems with built-in quality-assurance capabilities and the ability to process a large number of samples. These factors are expected to positively influence segment growth.
The diagnostic laboratories segment is expected to grow at the fastest CAGR over the forecast period. Automated analyzers enhance efficiency, reducing turnaround times. Increasing public awareness fosters proactive health monitoring, amplifying diagnostic test volumes. The emphasis of governments on accurate diagnostics and healthcare infrastructure investments is also expected to propel the adoption of advanced clinical chemistry analyzers. These factors are projected to collectively drive the growth of the segment over the forecasted period.
Regional Insights
North America dominated the market, accounting for a revenue share of 36.0% in 2025, due to rising healthcare spending in countries such as the U.S. The healthcare infrastructure in the U.S. is well established, which has led to a huge adoption rate for clinical chemistry and reagents in laboratories and hospitals. Moreover, favorable healthcare reimbursement policies in such regions have also driven greater adoption of automated chemistry analyzers. The growth in healthcare expenditure was facilitated by higher utilization of healthcare services and growth in Medicare, Medicaid, and private health insurance expenditures. According to the Centers for Medicare & Medicaid Services (CMS), U.S. national health expenditures increased by 7.2% to USD 5.3 trillion in 2024, accounting for 18.0% of GDP. The increase in healthcare expenditure indicates consistent investment in hospitals, clinical services, and diagnostic facilities, thereby supporting the adoption of advanced laboratory technologies, including automated clinical chemistry analyzers, across the United States.
 To learn more about this report, Download Free Sample Report
U.S. Clinical Chemistry Analyzers Market Trends
The U.S. dominated the North American clinical chemistry analyzers market in 2025, supported by the widespread adoption of advanced diagnostic analyzers across healthcare settings, continuous technological advancements, and the strong presence of leading market participants. The country’s well-established healthcare infrastructure, high diagnostic testing volumes, and increasing demand for automated laboratory solutions further contribute to market growth. Key players operating in the U.S. market include Beckman Coulter, ELITechGroup, HORIBA, Johnson & Johnson, Mindray Medical International, Ortho Clinical Diagnostics, and Siemens Healthineers.
Asia Pacific Clinical Chemistry Analyzers Market Trends
The clinical chemistry analyzers industry in the Asia Pacific region is anticipated to grow at the fastest CAGR during the forecast period, owing to the presence of a large target population and increasing penetration of leading clinical chemistry product manufacturers in countries such as India and China. Furthermore, high R&D investment by the global players and the presence of unexplored opportunities in this region serve as high-growth rendering drivers. For instance, in August 2024, Sysmex Corporation announced the completion of its largest manufacturing base in India. The plant has the capacity of manufacturing diagnostic machines and reagents. It was set up to meet increasing demands for tests and expand its business activities in India owing to fast economic development, rising health care investments, and rising demands for diagnostics. This highlights the significant growth opportunities available to diagnostic manufacturers in Asia Pacific.
The Japan clinical chemistry analyzers industry’s dominance is attributed to the high demand for diagnostic reagents and devices, driven by the largest aging population in the world. The increasing prevalence of chronic diseases and the need for advanced diagnostic solutions have contributed to the growth of this market in Japan. F. Hoffmann-La Roche is the leading manufacturer of clinical chemistry analyzers in Japan, further underlining the country's importance in this market.
Key Clinical Chemistry Analyzers Company Insights
The key players in the clinical chemistry analyzers market are using different strategies to strengthen their market positions. Companies are involved in expanding their market reach by signing agreements with other players in emerging economies. Product approval is another strategy adopted by these companies. Additionally, key players are taking different strategic initiatives, such as collaborations & partnerships with key participants and other players in the industry to enhance their presence. Capturing niche areas of supply chain, such as the distribution and delivery of products & solutions, to establish themselves.
Key Clinical Chemistry Analyzers Companies
The following key companies have been profiled for this study on the clinical chemistry analyzers market:
-
Shenzhen Mindray Bio-Medical Electronics Co., Ltd.
-
Thermo Fisher Scientific, Inc.
-
Danaher Corporation (Beckman Coulter)
-
Abbott
-
Siemens Healthineers AG
-
F. Hoffmann-La Roche Ltd
-
Horiba, Ltd.
-
ELITech Group
-
QuidelOrtho Corporation
-
Randox Laboratories Ltd
Recent Developments
-
In July 2024, Roche launched the cobas c 703 and cobas ISE neo analytical units for its cobas pro integrated solutions platform. The new clinical chemistry modules increase testing capacity and automation, with the cobas c 703 delivering up to 2,000 tests per hour for high-volume laboratories.
-
In April 2024, Mindray launched new mid-volume laboratory solutions, including the BS-1000M clinical chemistry analyzer, expanding its biochemistry testing portfolio. This move is geared towards enhancing laboratory efficiency as well as tackling the increasing workload in testing procedures.
-
In January 2024, Beckman Coulter launched the DxC 500 AU Chemistry Analyzer, an automated clinical chemistry analyzer designed for satellite laboratories and community hospitals. It has more than 120 assays and onboard workflows, along with standard reagents, available on the company's chemistry platform.
Clinical Chemistry Analyzers Market Report Scope
Report Attribute
Details
Market size in 2025
USD 20.6 billion
Estimated market size in 2026
USD 21.6 billion
Projected market size by 2033
USD 30.7 billion
Growth rate
CAGR of 5.2% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments Covered
Product, test, end use, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; and MEA
Country Scope
U.S.; Canada; UK; Germany; Spain; Denmark; Sweden; Norway; France; Italy; China; India; Japan; Thailand; South Korea; Australia; Brazil; Mexico; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Shenzhen Mindray Bio-Medical Electronics Co., Ltd.; Thermo Fisher Scientific, Inc.; Danaher Corporation (Beckman Coulter); Abbott, Siemens Healthineers AG; F. Hoffmann-La Roche Ltd; Horiba, Ltd.; ELITech Group; QuidelOrtho Corporation; Randox Laboratories Ltd.
Customization scope
Free report customization (equivalent to up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Clinical Chemistry Analyzers Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global clinical chemistry analyzers market report based on product, test, end use, and region:
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Analyzers
-
Small
-
Medium
-
Large
-
Very Large
-
-
Reagents
-
Calibrators
-
Controls
-
Standards
-
Others
-
-
Others
-
-
Test Outlook (Revenue, USD Billion, 2021 - 2033)
-
Basic Metabolic Panel (BMP)
-
Electrolyte Panel
-
Liver Panel
-
Lipid Profile
-
Renal Profile
-
Thyroid Function Panel
-
Specialty Chemical Tests
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Hospitals
-
Academic Research Centers
-
Diagnostic Laboratories
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
Germany
-
UK
-
Spain
-
France
-
Italy
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
South Korea
-
Thailand
-
Australia
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
MEA
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Frequently Asked Questions About This Report
Key players in the market include Shenzhen Mindray Bio-Medical Electronics Co., Ltd.; Thermo Fisher Scientific, Inc.; Danaher Corporation (Beckman Coulter); Abbott, Siemens Healthineers AG; F. Hoffmann-La Roche Ltd; Horiba, Ltd.; ELITech Group; QuidelOrtho Corporation; Randox Laboratories Ltd., and others.
The reagents segment dominated the market, with a revenue share of about 56.0% in 2025.
The global Clinical Chemistry Analyzers market size was valued at USD 20.6 billion in 2025 and is estimated at USD 21.6 billion for 2026
The global Clinical Chemistry Analyzers market is expected to grow at a CAGR of 5.2% from 2026 to 2033, reaching USD 30.7 billion.
North America dominated with an approximately 36.0% revenue share in 2025.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


