
- Home
- »
- Biotechnology
- »
-
Clinical Oncology Next Generation Sequencing Market Report, 2033GVR Report cover

Clinical Oncology Next Generation Sequencing Market (2026 - 2033)
Size, Share & Trends Analysis Report By Workflow (NGS Pre-Sequencing, NGS Sequencing, NGS Data Analysis), By Technology, By Application, By End-use, By Region, And Segment Forecasts
Market Size, 2025
$558.6MMarket Estimate, 2026
$648.0MMarket Forecast, 2033
$1,930.2MCAGR, 2026–2033
16.9%Clinical Oncology Next Generation Sequencing Market Summary
The global clinical oncology next generation sequencing market size was valued at USD 558.6 million in 2025 and is projected to grow from USD 648.0 million in 2026 to USD 1,930.2 million by 2033, growing at a CAGR of 16.9% from 2026 to 2033. North America dominated the market, accounting for the largest global share of 43.8% in 2025. The key drivers responsible for the growth of the clinical oncology next generation sequencing (NGS) industry are increasing technological advancements, growing competition among players, increasing healthcare spending, and the rise in the prevalence of cancer.
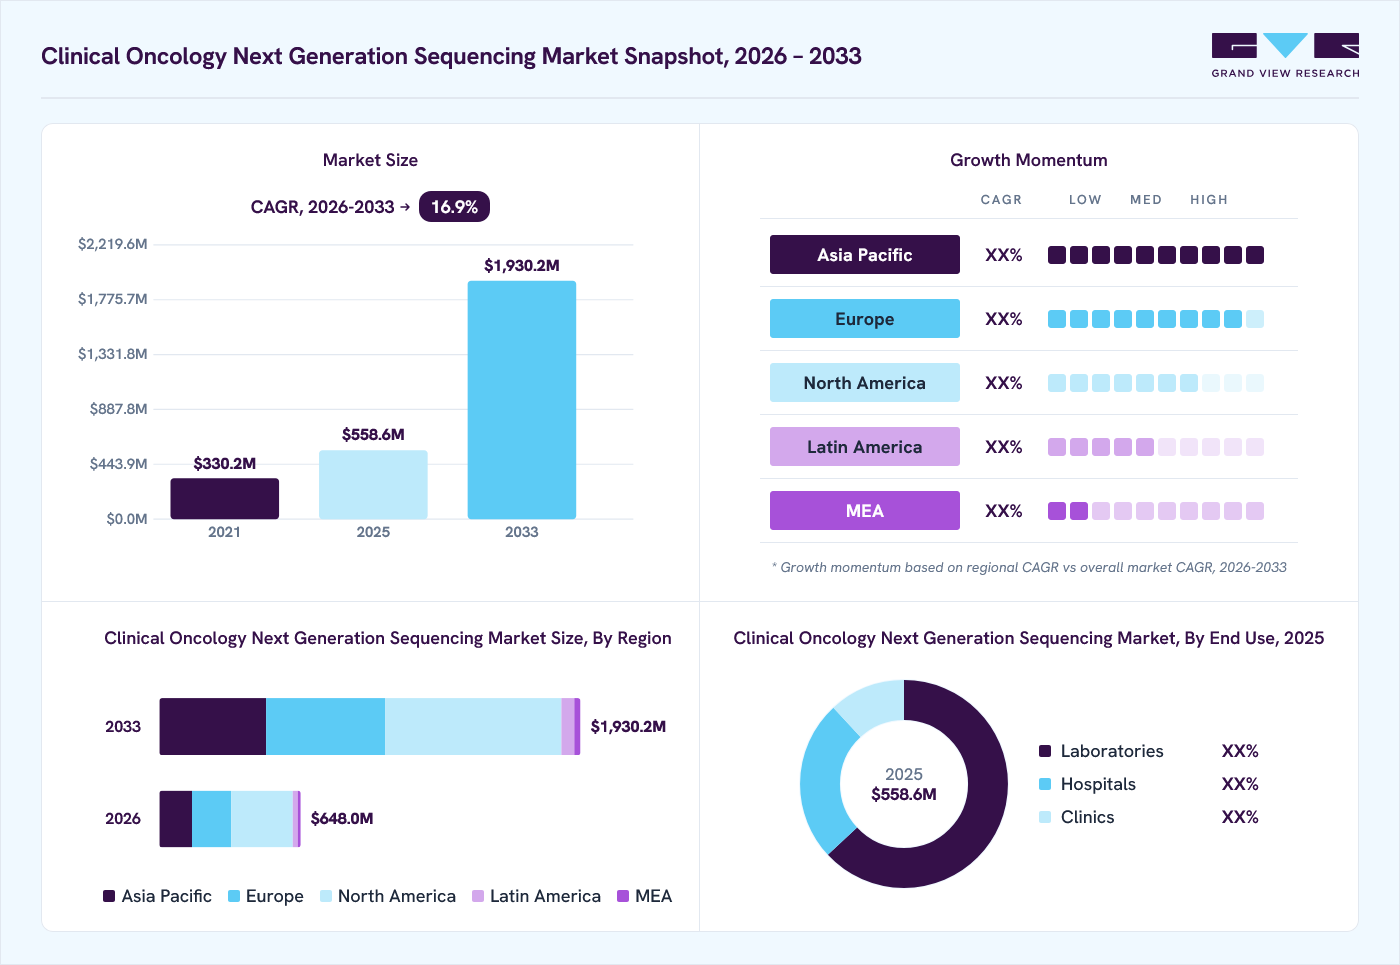 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By technology: Targeted sequencing & resequencing segment held the largest share of 63.7% in 2025.
- By workflow: NGS sequencing segment accounted for the largest revenue share, 57.0%, in 2025.
- By application: Companion diagnostics dominated the market with a revenue share of 72.2% in 2025.
- By end-use: Laboratories segment led the market with the largest revenue share of 63.0%.
Regional Highlights
- Largest regional market: North America (43.8% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest share of North America in 2025.
Market Size & Forecast
- Market size in 2025: USD 558.6 Million
- Estimated market size in 2026: USD 648.0 Million
- Projected market size by 2033: USD 1,930.2 Million
- CAGR (2026-2033): 16.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
In addition, augmenting research & development activities to invent solutions is expected to fuel the market growth over the forecast period.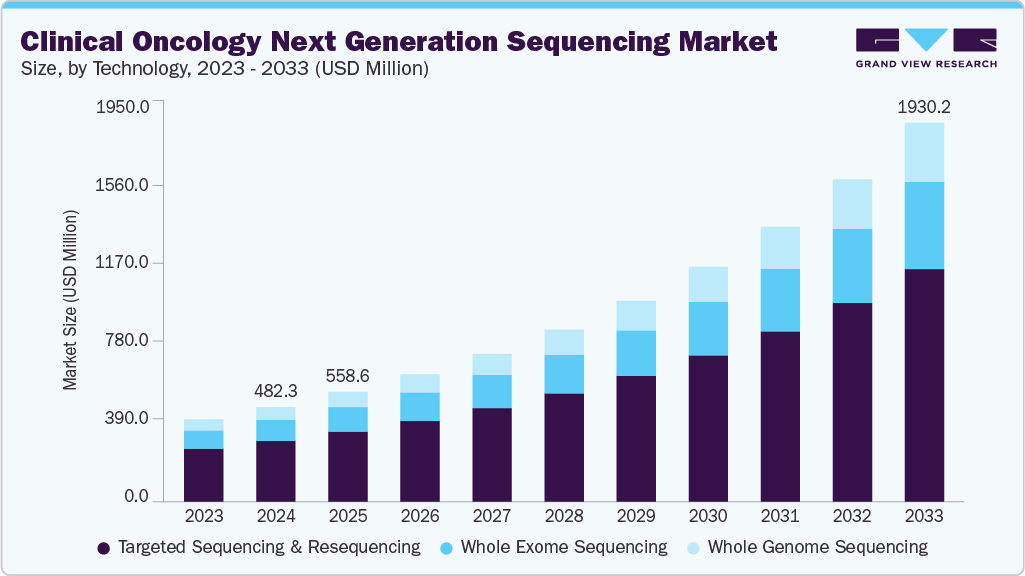 To learn more about this report, Download Free Sample Report
Escalating Cancer Rates Propel Adoption of NGS in Oncology
The global surge in cancer incidence has emerged as a significant public health challenge, significantly influencing diagnostic and treatment strategies. According to the World Health Organization, cancer is one of the leading causes of death globally, with millions of new cases reported each year. This alarming rise is attributed to aging populations, environmental factors, and changing lifestyle habits. As cancer becomes increasingly prevalent, healthcare systems are shifting focus toward early and accurate detection to improve treatment outcomes and reduce mortality. This trend fuels demand for advanced molecular diagnostic tools, particularly next-generation sequencing (NGS), which offers a comprehensive understanding of cancer genetics.
NGS technology enables the detection of multiple genetic mutations in a single test, making it a powerful tool in oncology. Its ability to analyze tumor heterogeneity and provide detailed genomic insights is critical for identifying cancer subtypes and developing targeted therapies. The rising incidence of complex and rare cancers has further amplified the need for precision diagnostics, where NGS plays a vital role in guiding clinicians toward personalized treatment approaches. As a result, hospitals, diagnostic laboratories, and cancer centers are increasingly integrating NGS platforms into their diagnostic workflows, recognizing their value in enhancing diagnostic accuracy and therapeutic decision-making.
Furthermore, as cancer cases continue to climb across both developed and emerging markets, governments and private stakeholders are investing heavily in genomic infrastructure. National genomic programs, increased reimbursement for NGS tests, and ongoing clinical trials using NGS-driven biomarkers reinforce the technology's role in routine cancer diagnostics. This upward trend in cancer incidence is expected to sustain and accelerate the adoption of NGS in clinical oncology, establishing it as a cornerstone of modern cancer care.
Advancing NGS Platforms Fuel Clinical Oncology Integration
The clinical oncology NGS market is witnessing robust growth driven by continuous technological advancements that enhance sequencing accuracy, speed, and usability. Innovations such as high-throughput platforms, error-correction algorithms, and improved chemistry have significantly increased the sensitivity and specificity of NGS, making it highly suitable for clinical oncology applications. Platforms such as Illumina’s NovaSeq and Thermo Fisher’s Ion Torrent systems have enabled comprehensive genomic profiling at lower turnaround times, facilitating faster diagnosis and treatment planning for cancer patients.
The emergence of integrated, automated workflows and cloud-based data interpretation tools has streamlined complex NGS procedures, making them more accessible to clinical laboratories with limited expertise. These advancements reduce operational burdens and improve scalability, accelerating the clinical adoption of NGS in oncology. As a result, healthcare providers can efficiently detect actionable mutations, monitor disease progression, and personalize therapies with greater precision. The convergence of NGS technologies with digital health solutions and AI-driven analytics is further expected to revolutionize cancer care, supporting the ongoing shift toward precision oncology.
Market Dynamics
The clinical oncology next generation sequencing (NGS) industry is witnessing high growth, driven by the increasing adoption of precision medicine, expanding use of biomarker-driven therapies, and the growing clinical utility of comprehensive genomic profiling across the cancer care continuum. Technological advancements in high-throughput sequencing platforms, declining sequencing costs, and the integration of artificial intelligence (AI)-enabled bioinformatics are improving the speed, accuracy, and accessibility of oncology testing. In addition, the expanding number of targeted therapies and companion diagnostic approvals is strengthening the role of NGS in routine clinical practice. However, challenges such as complex regulatory pathways, reimbursement variability, data interpretation complexities, and the need for specialized laboratory infrastructure continue to influence the pace of market adoption.
The increasing global prevalence of cancer is a major driver of the clinical oncology next generation sequencing (NGS) market. The growing incidence of both solid tumors and hematological malignancies has intensified the demand for advanced genomic testing that enables accurate diagnosis, molecular profiling, and personalized treatment selection. According to the National Cancer Institute (NCI), approximately 2,041,910 new cancer cases are expected to be diagnosed in the U.S. in 2025, with an estimated 618,120 cancer-related deaths, highlighting the substantial disease burden and the urgent need for improved diagnostic and therapeutic strategies. NGS enables the simultaneous analysis of multiple cancer-associated genes, facilitating the identification of actionable mutations, tumor mutational burden (TMB), microsatellite instability (MSI), and other clinically relevant biomarkers. As healthcare systems increasingly adopt precision oncology approaches, NGS has become an essential tool for guiding targeted therapies and immunotherapies, and for monitoring disease progression. Furthermore, the rising number of cancer patients, expanding screening programs, and increasing availability of companion diagnostics continue to accelerate the adoption of clinical oncology NGS solutions across hospitals, diagnostic laboratories, and cancer research centers, thereby driving sustained market growth.
NGS offers benefits by sequencing gene panels and clinical exomes. The volume of genetic data produced per test rapidly increased. Before NGS, the diagnostics of the rarest diseases followed a step-wise approach where various genes involved in the disorder were sequenced consecutively. NGS facilitates larger procedures like the sequencing of gene panels (i.e., all genes contributing to specific diseases are sequenced simultaneously, normally 5-100 genes). Accordingly, the amount of data required to be analyzed, pre-processed, interpreted, and stored per case is also dramatically augmented. Decreasing the cost of sequencing and increasing the number of sequences reads being produced are putting tremendous demand on the computational knowledge and resources necessary to handle sequence data. The need for scalable and proper storage to grow data accessibility for research is rising with the decrease in sequencing costs. Sequencing platform installation involves the immense fixed cost associated with buying a machine, followed by lower variable costs for the actual running of the machine.
On the contrary, cloud computing and its associated concepts, such as platform, software, and infrastructure as a service, remove the need for such a large initial fixed-cost investment. However, the variable costs associated with access to cloud computing are significantly higher, restraining the adoption rate of NGS techniques in clinical settings and diagnostic laboratories. The absence of data management and abstraction tools with the required parameters, such as distributed and parallel cloud computing software for integrative analysis and protocols for securing the individual data specifically within a cloud-computing environment, impedes the implementation of NGS-based data for translational research in clinical oncology.
Market Concentration & Characteristics
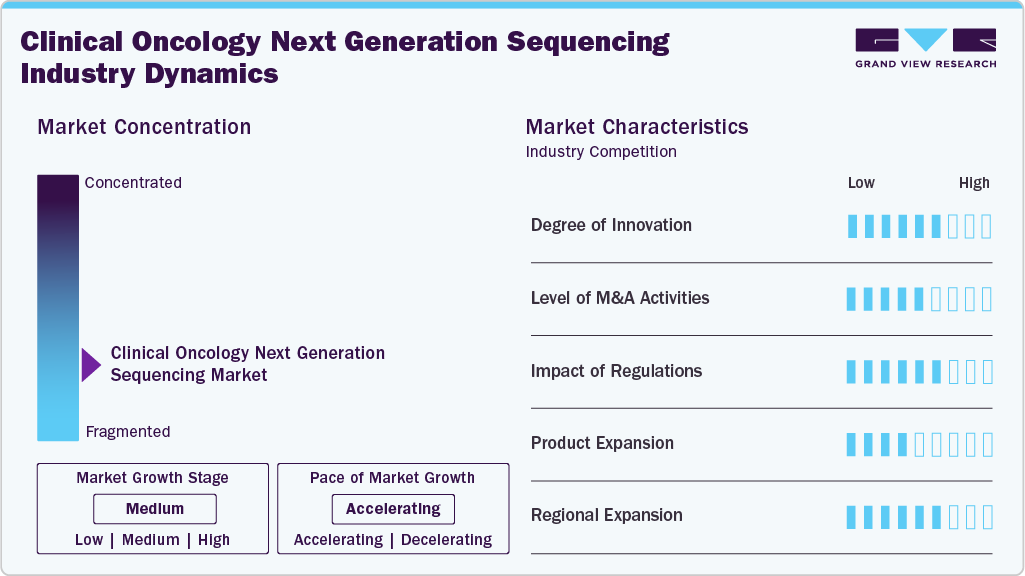
The clinical oncology NGS industry is highly innovative, owing to the rapid evolution of sequencing technologies, integration of AI-driven analytics, and development of automated, high-throughput platforms. These innovations enable faster, more accurate genomic profiling and support the shift toward precision oncology and personalized treatment strategies across diverse cancer types.
The moderate increase in mergers and acquisitions (M&A) in the clinical oncology NGS industry is attributed to companies seeking to expand their technological capabilities, enhance product portfolios, and strengthen their market position. Strategic collaborations also aim to accelerate innovation, streamline R&D pipelines, and integrate complementary expertise in bioinformatics, diagnostics, and sequencing platforms to meet the growing demand for precision oncology solutions.
 To learn more about this report, Download Free Sample Report
Regulations play a dual role in shaping demand within the clinical oncology NGS industry by ensuring test accuracy and patient safety while influencing market accessibility. Stringent regulatory approvals build trust and drive clinical adoption, but complex compliance requirements can delay product launches and increase costs. Harmonized global frameworks and expedited pathways, such as the FDA’s Breakthrough Device designation, are helping balance innovation with oversight, thereby supporting market growth and broader implementation in clinical settings.
Product expansion is a significant driving factor for the growth in the clinical oncology NGS industry. Introducing advanced panels, liquid biopsy tests, and companion diagnostics enables broader cancer coverage and improved clinical utility. This strategic expansion enhances diagnostic accuracy, supports personalized treatment approaches, and reinforces competitive positioning in a rapidly evolving precision oncology market.
Regional expansion is the primary demand driver in the clinical oncology NGS industry, owing to the increasing adoption of precision medicine across emerging markets, rising healthcare investments, and improved access to advanced diagnostic technologies. Companies are targeting high-growth regions such as Asia Pacific and Latin America to tap into unmet clinical needs, expand patient reach, and leverage supportive government initiatives, fueling overall market growth and accelerating the global adoption of NGS in oncology care.
Analyst Perspective
The clinical oncology NGS market is transitioning from a specialized diagnostic approach to a standard component of personalized cancer management. Future market leadership is expected to be driven by companies offering integrated end-to-end solutions that combine sequencing platforms, bioinformatics capabilities, clinical interpretation, and companion diagnostic partnerships. Emerging opportunities are likely to arise from the growing adoption of liquid biopsy-based NGS assays, decentralized genomic testing, and multi-cancer early detection (MCED) applications. Moreover, increasing collaboration between sequencing technology providers, pharmaceutical companies, and healthcare institutions to support biomarker discovery and targeted drug development is expected to accelerate innovation and strengthen long-term market growth.
Technology Insights
Based on the technology, the market is segmented into whole genome sequencing, targeted sequencing & resequencing, and whole exome sequencing. The targeted sequencing & resequencing segment held the largest market share of 63.7% in 2025 in terms of revenue, owing to the various benefits associated with this technology, such as decreased time, cost, and quantity of data analyzed during the tumor samples sequencing Furthermore, the clinical utility of targeted panels is increased due to their efficiency in detecting malignant tumors.
Whole-Genome Sequencing (WGS) is anticipated to be the fastest-growing segment with 18.5% CAGR over the forecast period, owing to the usage of this technology to compare and differentiate tumor tissues from normal tissues. In addition, WGS of cancer patients enables the identification of treatments for current mutations and aids in targeting mutations in advance. This also supports analyzing cancer prognosis.
Workflow Insights
The market is segmented by workflow into NGS pre-sequencing, NGS sequencing, and NGS data analysis. The NGS sequencing segment accounted for the largest revenue share, 57.0%, in 2025, and it is expected to grow at the fastest CAGR over the forecast period in the workflow segment, and it is expected to grow at the fastest CAGR over the forecast period. This is attributed to its central role in genomic analysis, continuous technological advancements, and increasing demand for high-throughput, accurate sequencing solutions in clinical oncology for personalized treatment and early cancer detection.
The NGS data analysis segment in the clinical oncology NGS market is expected to register a significant CAGR of 16.2% during the forecast period driven by the growing complexity of genomic data, increased need for accurate interpretation tools, and the integration of AI and machine learning to enhance clinical decision-making and streamline personalized cancer treatment planning.
Application Insights
Based on application, companion diagnostics dominated the market with a revenue share of 72.2% in 2025 and are anticipated to grow at the fastest CAGR over the forecast period. This is attributed to the rising demand for targeted cancer therapies, increased FDA approvals of biomarker-driven treatments, and the growing emphasis on precision medicine. These diagnostics enable clinicians to identify the most effective therapy based on a patient’s genetic profile, improving treatment outcomes and driving widespread adoption across oncology practices.
The screening application segment in the clinical oncology NGS market is expected to register a significant CAGR of 12.6% during the forecast period. This growth is driven by the increasing emphasis on early cancer detection, rising awareness of genetic risk factors, and the growing adoption of non-invasive screening methods such as liquid biopsy. These factors enable timely diagnosis and intervention, improving patient outcomes and reducing cancer treatment costs.
End Use Insights
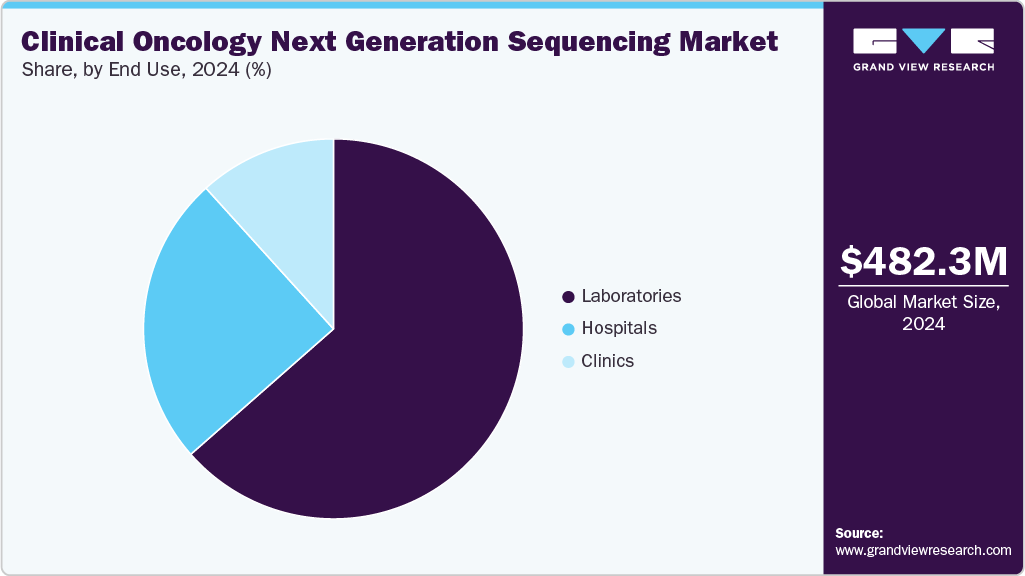
Based on end-use, the laboratories segment led the market with the largest revenue share of 63.0%, driven by their advanced infrastructure, specialized expertise in genomic testing, and high testing volumes. The increasing outsourcing of NGS services by hospitals and research institutions to certified laboratories and the availability of integrated data analysis capabilities have further solidified their dominant position in the clinical oncology NGS market.
 To learn more about this report, Download Free Sample Report
The clinics in the end use segment of the clinical oncology NGS industry are expected to register the fastest CAGR of 19.3% during the forecast period. The rising adoption of protein-based diagnostics drives this growth, the increasing use of biomarkers for disease monitoring, and the growing integration of personalized medicine in clinical settings. Hospitals are expanding their in-house capabilities to support advanced testing and targeted therapeutic development.
Regional Insights
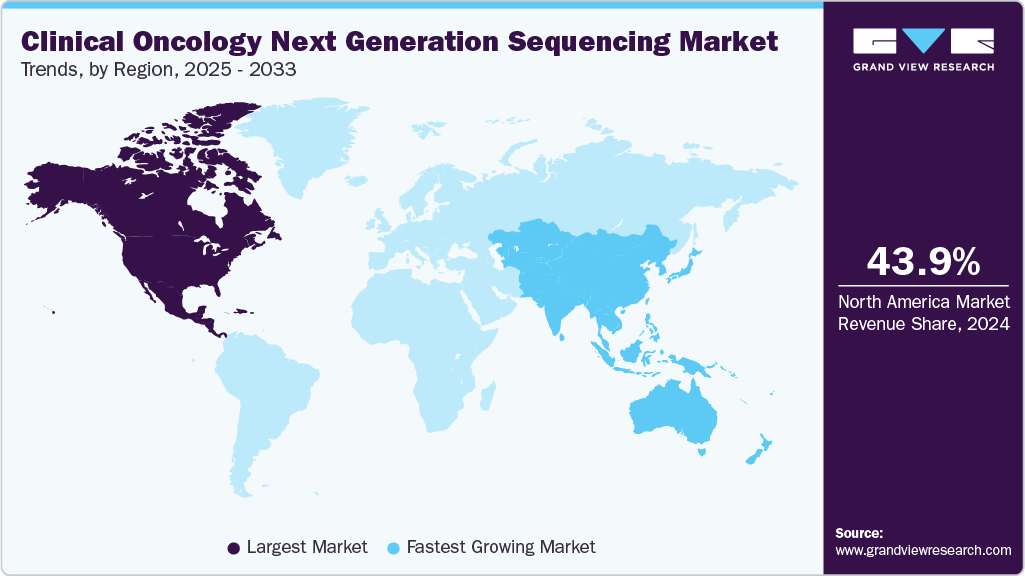
North America dominated the clinical oncology next generation sequencing market with the largest revenue share of 43.8% in 2025. The dominance can be attributed to the region’s advanced healthcare infrastructure, high adoption of precision medicine, and strong presence of key market players. Additionally, favorable reimbursement policies, significant investments in cancer genomics research, and early regulatory approvals for NGS-based diagnostics have accelerated clinical adoption. The region also benefits from high awareness among healthcare professionals and patients, driving demand for targeted therapies and companion diagnostics in oncology.
 To learn more about this report, Download Free Sample Report
U.S. Clinical Oncology Next Generation Sequencing Market Trends
The clinical oncology next generation sequencing market in the U.S. held the largest share in the North America region in 2025, owing to its robust healthcare infrastructure, early adoption of advanced genomic technologies, and substantial investment in cancer research. Supportive regulatory frameworks, widespread use of companion diagnostics, and a strong presence of leading NGS companies further contributed to the country’s leadership in integrating NGS into routine oncology care.
Europe Clinical Oncology Next Generation Sequencing Market Trends
The European clinical oncology NGS market is expected to grow in the forecast period, driven by increasing adoption of personalized medicine, expanding genomic research initiatives, and growing government support for cancer diagnostics. Rising cancer prevalence, along with improvements in healthcare infrastructure and access to advanced sequencing technologies, is fueling demand across the region. Additionally, collaborations between research institutions and biotechnology firms are accelerating the development of NGS-based clinical applications in oncology.
The UK clinical oncology NGS industry is expected to grow rapidly in the coming years due to strong government initiatives supporting genomics, such as the 100,000 Genomes Project, and increased investment in precision oncology research. The presence of leading academic institutions, expanding access to advanced diagnostic technologies, and growing partnerships between the public and private sectors further accelerate the integration of NGS into clinical cancer care.
The Germany clinical oncology NGS market held a substantial market share in 2025, owing to its well-established healthcare infrastructure, strong emphasis on precision medicine, and robust funding for cancer genomics research. The country's proactive regulatory environment, widespread adoption of advanced diagnostic technologies, and presence of key biotechnology and pharmaceutical companies further contributed to its leading position in the European clinical oncology NGS landscape.
Asia Pacific Clinical Oncology Next Generation Sequencing Market Trends
The clinical oncology NGS market in Asia Pacific is expected to register the fastest growth, with a CAGR of 18.4% during the forecast period. This growth is fueled by rising cancer prevalence, increasing demand for personalized medicine, and expanding healthcare infrastructure across emerging economies. Government initiatives supporting genomics research, growing awareness of early cancer detection, and increasing investments by domestic and international players are also driving market expansion. Additionally, the adoption of cost-effective NGS platforms and the rise of local laboratory services offering advanced genomic testing are accelerating clinical integration. Countries like China, India, and Japan are at the forefront of this regional growth momentum.
The China clinical oncology NGS market is expected to grow in the forecast period. This is attributed to rising cancer incidence, strong government support for genomics research, expanding local biotech companies, and increasing adoption of precision medicine in clinical practice across major healthcare institutions.
The Japan clinical oncology NGS market is witnessing significant growth over the forecast period, driven by increasing government and private funding for cancer genomics research, strong emphasis on precision medicine integration, and supportive healthcare policies. The presence of advanced sequencing infrastructure, growing collaboration between domestic biotech firms and global players, and rising demand for targeted therapies and companion diagnostics in oncology are further catalyzing market expansion.
Middle East & Africa Clinical Oncology Next Generation Sequencing Market Trends
The MEA clinical oncology NGS market is expected to grow exponentially over the forecast period. This is attributed to the rising cancer burden, increasing investments in healthcare infrastructure, and growing awareness of personalized cancer care. Government-led genomic initiatives, expanding access to advanced diagnostic technologies, and partnerships with global biotech firms are further driving the adoption of NGS-based oncology solutions across the region.
The Kuwait clinical oncology NGS market is projected to grow steadily over the forecast period. This is attributed to rising cancer prevalence, government investment in precision medicine, and increased adoption of advanced genomic diagnostics in leading healthcare institutions.
Key Clinical Oncology Next Generation Sequencing Company Insights
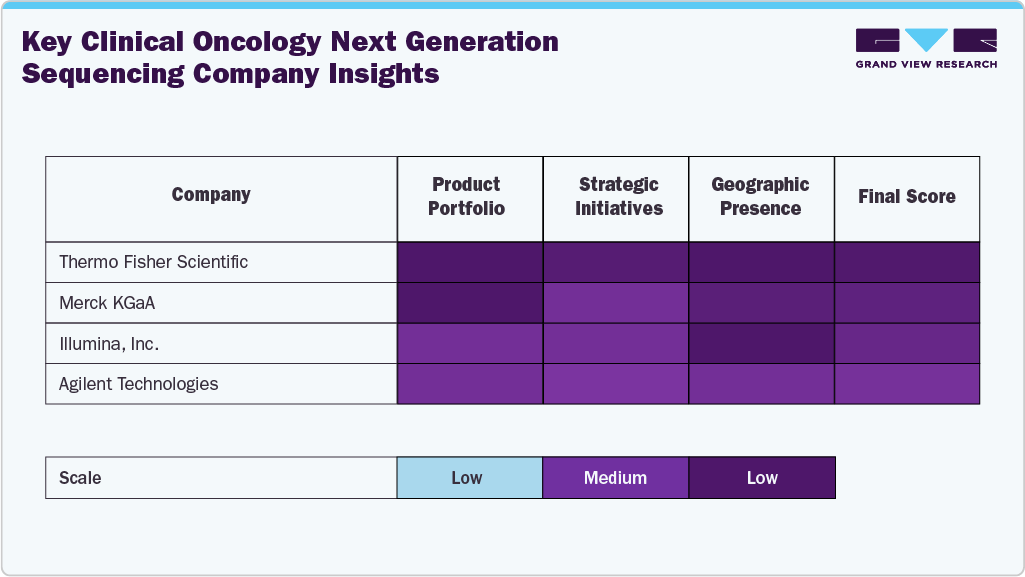
The clinical oncology NGS market is characterized by a high degree of consolidation, with major players such as Illumina, Inc. and Thermo Fisher Scientific dominating the global landscape due to their comprehensive sequencing platforms and robust distribution networks. Illumina continues to lead the market with its cutting-edge instruments and consumables tailored for oncology applications, while Thermo Fisher offers a wide range of solutions, including Ion Torrent systems and Oncomine assays. These companies benefit from strong brand recognition, consistent product innovation, and strategic collaborations with healthcare institutions, enabling them to maintain a competitive edge and high market share.
Other key players such as F. Hoffmann-La Roche Ltd., Agilent Technologies, and Myriad Genetics are expanding their footprint through targeted acquisitions and the development of oncology-focused genomic solutions. Roche’s AVENIO NGS platform and Myriad’s myRisk hereditary cancer test exemplify the push toward personalized treatment strategies. Agilent Technologies continues to leverage its strength in genomic sample preparation and data analysis tools, reinforcing its position in the oncology NGS ecosystem. Similarly, through its genomics services and clinical diagnostics segment, PerkinElmer contributes to the growing demand for cancer screening and genetic risk assessments, particularly in emerging markets.
 To learn more about this report, Download Free Sample Report
Emerging and specialized firms such as Pacific Biosciences, Oxford Nanopore Technologies Ltd., Eurofins Scientific S.E., and Qiagen N.V. are pivotal in shaping the market’s next growth phase. Pacific Biosciences and Oxford Nanopore are bringing long-read and real-time sequencing capabilities into clinical oncology, helping decode complex mutations. With their strong presence in molecular diagnostics and bioinformatics, Eurofins and Qiagen are enhancing service-based offerings to support clinical labs. As the demand for precision oncology continues to rise, these companies will likely witness accelerated growth, particularly in the companion diagnostics and liquid biopsy segments.
Key Clinical Oncology Next Generation Sequencing Companies:
The following are the leading companies in the clinical oncology next generation sequencing market.
-
Illumina, Inc.
-
Thermo Fisher Scientific
-
F. Hoffmann-La Roche Ltd.
-
Agilent Technologies
-
Myriad Genetics
-
Perkin Elmer
-
Pacific Bioscience
-
Oxford Nanopore Technologies Ltd.
-
Eurofins Scientific S.E.
-
Qiagen N.V.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Illumina, Inc., Thermo Fisher Scientific, F. Hoffmann-La Roche Ltd,etc)
- Strengthen precision oncology portfolios by integrating NGS platforms with companion diagnostics, biomarker discovery, and clinical decision-support solutions.
- Comprehensive oncology testing ecosystems combining sequencing platforms, bioinformatics, regulatory expertise, and global clinical laboratory networks.
- Significant investment is required to maintain technological leadership amid rapidly evolving sequencing and diagnostic innovations.
Emerging Players (Myriad Genetics, PerkinElmer, Pacific Biosciences, etc)
- Focus on differentiated oncology sequencing technologies and specialized genomic testing solutions for translational and clinical research.
- Expertise in niche applications such as long-read sequencing, hereditary cancer testing, and advanced genomic characterization.
- Smaller commercial footprint and narrower clinical adoption than established integrated diagnostics providers.
Recent Developments
-
In May 2026, Illumina and SPT Labtech launched the fireflyGO automation platform globally, integrating automated library preparation with sequencing workflows to improve efficiency, reduce manual intervention, enhance reproducibility, and expand accessibility of oncology NGS research.
“The fireflyGO platform, paired with Illumina MiSeq i100 sequencers and Pillar Biosciences targeted panel assays, advances research and serves as a catalyst for broadening genomic testing in cancer, driving shorter turnaround times leading to fast results.”
- Illumina global clinical solutions vice-president and general manager Sandy Ottensmann
Clinical Oncology Next Generation Sequencing Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 558.6 million
Market size value in 2026
USD 648.0 million
Revenue forecast in 2033
USD 1,930.2 million
Growth rate
CAGR of 16.9% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Workflow, application, technology, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Spain; Italy; Sweden; Norway; Denmark; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; UAE; Saudi Arabia; Kuwait
Key companies profiled
Illumina, Inc.; Thermo Fisher Scientific; F. Hoffmann-La Roche Ltd.; Agilent Technologies; Myriad Genetics; Perkin Elmer; Pacific Bioscience; Oxford Nanopore Technologies Ltd.; Eurofins Scientific S.E.; Qiagen N.V.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Clinical Oncology Next Generation Sequencing Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and analyzes the latest industry trends in each sub-segment from 2021 to 2033. Grand View Research has segmented the global clinical oncology next generation sequencing market report based on workflow, technology, application, end use, and region.
-
Workflow Outlook (Revenue, USD Million, 2021 - 2033)
-
NGS Pre-Sequencing
-
NGS Sequencing
-
NGS Data Analysis
-
-
Technology Outlook (Revenue, USD Million, 2021 - 2033)
-
Whole Genome Sequencing
-
Whole Exome Sequencing
-
Targeted Sequencing & Resequencing
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Screening
-
Sporadic Cancer
-
Inherited Cancer
-
-
Companion Diagnostics
-
Others
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Clinics
-
Laboratories
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The clinical oncology next generation sequencing market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each clinical oncology next generation sequencing segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Workflow
Revenue capture definition
NGS Pre-Sequencing
Revenue is generated from sample preparation products and services, including nucleic acid extraction, library preparation, target enrichment, quality control, and other pre-sequencing consumables and workflows used in clinical oncology testing.
NGS Sequencing
Revenue is generated from sequencing instruments, consumables, reagents, and sequencing services used to generate genomic data for cancer detection, molecular profiling, and treatment selection.
NGS Data Analysis
Revenue is generated from bioinformatics software, cloud-based analysis platforms, data interpretation tools, variant annotation solutions, and related services used to process, analyze, and interpret oncology sequencing data.
Segment - Technology
Revenue capture definition
Whole Genome Sequencing
Revenue is generated from sequencing solutions that analyze the complete genome of cancer samples to identify genetic alterations, structural variants, and other clinically relevant biomarkers.
Whole Exome Sequencing
Revenue is generated from sequencing solutions that analyze the protein-coding regions (exome) of the genome to detect clinically significant mutations associated with cancer.
Targeted Sequencing & Resequencing
Revenue is generated from targeted gene panels and resequencing assays that analyze predefined cancer-associated genes or genomic regions for mutation detection, biomarker identification, and companion diagnostics.
Segment - Application
Revenue capture definition
Screening
Revenue is generated from NGS-based tests used for cancer screening, early detection, and risk assessment in asymptomatic or high-risk populations.
A) Sporadic Cancer: Revenue is generated from NGS solutions used to diagnose and characterize non-hereditary (sporadic) cancers for precision treatment and disease management.
B) Inherited Cancer: Revenue is generated from NGS tests used to identify hereditary cancer-associated genetic variants for risk assessment, diagnosis, and family screening.
Companion Diagnostics
Revenue is generated from NGS assays used to identify predictive biomarkers that guide the selection and monitoring of targeted therapies and immunotherapies.
Others
Revenue is generated from NGS applications including disease monitoring, recurrence assessment, therapy response evaluation, clinical research, and other oncology-related uses.
Segment - End Use
Revenue capture definition
Hospitals
Revenue is generated from NGS products, consumables, software, and testing services utilized by hospitals for cancer diagnosis, molecular profiling, and personalized treatment planning.
Clinics
Revenue is generated from oncology clinics utilizing NGS-based testing for patient diagnosis, treatment selection, and disease monitoring.
Laboratories
Revenue is generated from independent, reference, and hospital-affiliated laboratories performing NGS-based oncology testing, genomic analysis, and companion diagnostic services.
Estimation Model
Clinical Oncology Next Generation Sequencing Market
TOP-DOWN - Company Revenue Analysis
Aggregated revenues of leading clinical oncology NGS companies, including sequencing platform manufacturers, reagent and consumable suppliers, bioinformatics solution providers, and clinical testing service providers. Revenue estimates were mapped across workflow segments (pre-sequencing, sequencing, and data analysis) and validated using annual reports, investor presentations, SEC filings, paid databases, product portfolios, and primary interviews to derive the overall market size.
BOTTOM-UP - Technology Penetration Assessment
Derived the global market size from the broader molecular diagnostics and oncology diagnostics markets and allocated revenues across regions and countries based on cancer incidence, precision oncology adoption, availability of NGS testing infrastructure, reimbursement landscape, healthcare expenditure, and utilization of genomic testing in clinical oncology.
PRIMARY RESEARCH - Conducting Interviews with Industry Experts
Conducted interviews with executives from NGS platform manufacturers, oncology diagnostic laboratories, hospital molecular pathology departments, bioinformatics providers, oncologists, pathologists, KOLs, and distributors to validate market size, pricing trends, technology adoption, workflow utilization, competitive positioning, and future demand for oncology NGS solutions.
FORECASTING - Forecasting & CAGR Modeling
Forecasts were developed using historical market performance, projected cancer incidence, expansion of precision oncology programs, companion diagnostic approvals, advances in sequencing technologies, declining sequencing costs, reimbursement trends, and increasing adoption of AI-enabled bioinformatics and genomic testing in routine clinical practice.
VALIDATION - Data Triangulation & Validation Model
Validated market estimates by triangulating company-level revenue analysis, product launch activity, laboratory testing volumes, demand from hospitals and diagnostic laboratories, secondary research findings, and primary interviews to ensure consistency across technologies, applications, workflows, and regional markets.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Cancer-Type Level NGS Adoption Analysis
Provided detailed adoption and utilization analysis of clinical oncology NGS across major cancers such as lung, breast, colorectal, prostate, ovarian, hematologic malignancies, and other tumor types, including testing volumes and growth potential.
Enables clients to prioritize high-growth therapeutic areas and optimize market entry and investment decisions.
Laboratory Adoption & Customer Buying Criteria Assessment
Analyzed purchasing behavior of hospitals, reference laboratories, and cancer centers, covering vendor selection criteria, pricing preferences, workflow requirements, reimbursement considerations, and purchasing challenges.
Helps clients refine product positioning, sales strategies, and customer engagement initiatives.
Companion Diagnostic & Biomarker Landscape Analysis
Delivered a comprehensive assessment of FDA/EMA-approved companion diagnostics, associated genomic biomarkers, targeted therapies, and their linkage with NGS-based oncology testing across major cancer types.
Helps clients identify high-value biomarker opportunities, align product development with precision oncology trends, and strengthen commercialization strategies.
Frequently Asked Questions About This Report
Some key players operating in the clinical oncology NGS market include Illumina, Roche, Agilent; Thermo Fisher Scientific; Myriad Genetics; Beijing Genomics Institute (BGI); Perkin Elmer, Inc.; Qiagen NV; Partek, Inc.; Pacific Bioscience, Inc.; Foundation Medicine; Oxford Nanopore Technologies Ltd.; Paradigm Diagnostics, Inc.; Caris Life Sciences; and Eurofins Scientific.
Key factors that are driving the clinical oncology NGS market growth include a decrease in costs for genetic sequencing, advancements in the field of personalized medicine, growing adoption of NGS over single gene testing, and others.
The global clinical oncology NGS market is expected to grow at a compound annual growth rate of 16.9% from 2026 to 2033 to reach USD 1.9 billion by 2033.
Government support to conduct large-scale sequencing, and analysis of NGS data through BigData are some of the key factors that provide growth opportunities to the clinical oncology NGS market.
North America dominated with a 43.8% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
Based on technology, the targeted sequencing & resequencing segment held the largest market share of 63.7% in 2025.
Based on workflow, the NGS sequencing segment accounted for the largest revenue share, 57.0%, in 2025, and it is expected to grow at the fastest CAGR over the forecast period.
The global clinical oncology NGS market size was valued at USD 558.6 million in 2025 and is estimated at USD 648.0 million in 2026.
About the Author(s)
Biotechnology Research Team
Healthcare · BiotechnologyThis report was authored by the biotechnology research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the biotechnology segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


