
- Home
- »
- Healthcare IT
- »
-
Clinical Workflow Solutions Market Size Report, 2026-2033GVR Report cover

Clinical Workflow Solutions Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Data Integration Solutions, Workflow Automation Solutions), By End Use (Hospitals, Ambulatory Care Centers), By Region, And Segment Forecasts
Market Size, 2025
$13.8BMarket Estimate, 2026
$15.7BMarket Forecast, 2033
$37.1BCAGR, 2026–2033
13.1%Clinical Workflow Solutions Market Summary
The global clinical workflow solutions size was valued at USD 13.8 billion in 2025 and is projected to grow from USD 15.7 billion in 2026 to USD 37.1 billion by 2033, at a CAGR of 13.1% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 42.0% in 2025. The increasing initiatives undertaken by public and private organizations, growing demand for standardized clinical workflows in developed markets such as the U.S., and the need to provide clinicians with remote access to data-driven insights, scalable solutions, and healthcare information are key factors driving demand for advanced healthcare systems.
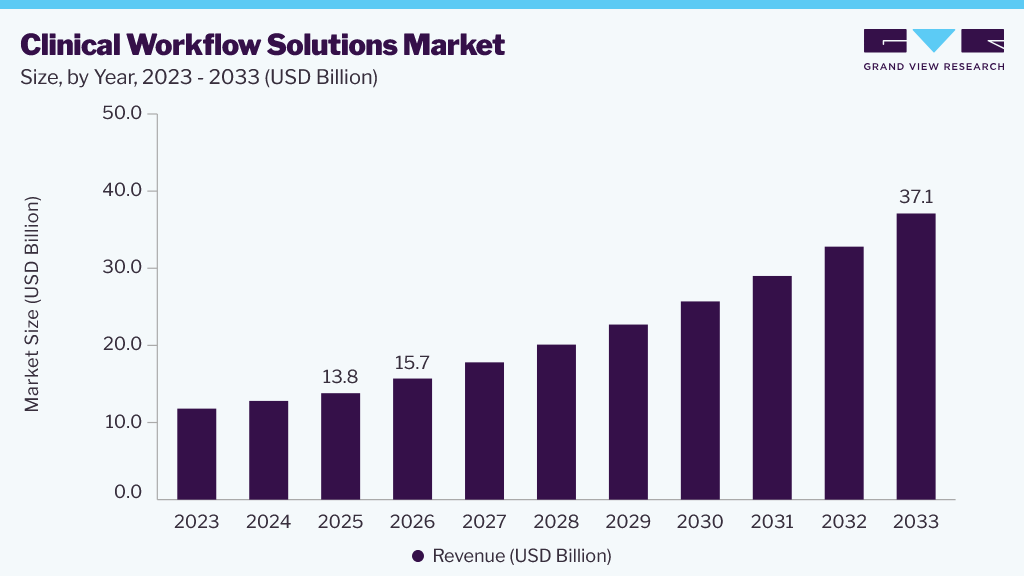 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Data integration solutions segment held the largest market share of around 27.0% in 2025.
- By end use: Hospitals segment dominated the market with a revenue share of approximately 45.0% in 2025.
Regional Highlights
- Largest regional market: North America (42.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 13.8 Billion
- Estimated market size in 2026: USD 15.7 Billion
- Projected market size by 2033: USD 37.1 Billion
- CAGR (2026-2033): 13.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Furthermore, hospitals are increasingly using technology-driven frameworks to upgrade their healthcare facilities and meet the increasing demands of both patients and clinicians. This trend is expected to further fuel the expansion of the market during the forecast period.
Market Dynamics
The increasing prevalence of chronic conditions, including diabetes and end-stage renal disease (ESRD), coupled with growing demand for coordinated and efficient care delivery, is supporting the adoption of clinical workflow solutions across healthcare organizations. These solutions enable healthcare professionals to access patient information and workflow data more efficiently, including through mobile and remote-access capabilities, thereby supporting clinical decision-making and continuity of care. The broader shift toward value-based care and the increasing digitalization of healthcare delivery are further encouraging hospitals and health systems to adopt workflow automation and coordination solutions. In October 2024, Oracle unveiled its Oracle Health Clinical AI Agent, an AI-powered solution integrated with its EHR that automates and streamlines clinical workflows, including documentation, clinical decision support, coding, and follow-up activities. Oracle subsequently reported that physicians using the Clinical AI Agent experienced an average reduction of nearly 30% in daily documentation time, highlighting the potential of AI-enabled workflow automation to improve clinical efficiency. Growing interoperability capabilities and the adoption of AI-driven automation are expected to further improve workflow efficiency and support demand for clinical workflow management solutions.Limited interoperability among healthcare IT systems remains a key challenge for the clinical workflow solutions market. Although healthcare organizations have rapidly adopted digital technologies, many continue to operate heterogeneous or legacy systems, making it difficult to exchange and integrate clinical information seamlessly. Fragmented data sources can create information silos, duplicate records, manual data entry, and additional administrative workload for healthcare professionals. Oracle itself highlights the importance of interoperability solutions that enable clinicians to collect and organize data from disparate systems and make patient information more accessible across care settings. In addition, integration across multiple EHR platforms and healthcare data standards can increase implementation complexity and costs. These interoperability and integration challenges can therefore delay deployment, particularly among organizations operating complex legacy IT environments.
The rapid adoption of AI-powered clinical workflow automation and ambient documentation represents a significant growth opportunity for market participants. Healthcare organizations are increasingly seeking solutions that can automate documentation, scheduling, patient communication, care coordination, and other administrative and clinical processes while integrating with existing EHR environments. Oracle's Clinical AI Agent, for example, uses generative AI and voice-based interaction to automate documentation, surface relevant patient information, and support clinical decision-making within the EHR workflow.
The clinical workflow solutions market is expected to grow as healthcare providers prioritize digital transformation, interoperability, and operational efficiency. Rising healthcare data volumes and fragmented IT systems are driving demand for data integration and care coordination solutions, while AI automation and ambient clinical documentation are creating opportunities to reduce administrative burdens and streamline clinical workflows. Hospitals are expected to remain key end users due to their complex operational requirements, while expanding digital health adoption is likely to support growth across ambulatory care settings. North America is anticipated to maintain its leading position, whereas APAC is expected to offer significant growth opportunities, supported by healthcare infrastructure development and increasing digital health investments. However, integration challenges, legacy systems, data security concerns, and high implementation costs may restrain market growth.
Type Insights
The data integration solutions segment held the largest market share, accounting for around 27.0% of revenue in 2025. Growing volumes of healthcare data and the increasing need to connect disparate information systems are driving demand for data integration technologies. Healthcare providers are increasingly adopting integrated solutions that enable secure and timely access to patient information across different points of care. The expansion of electronic health records (EHRs), growing interoperability requirements, regulatory initiatives, and the transition toward value-based care are further supporting growth in the segment. In addition, healthcare organizations are increasingly seeking solutions to consolidate information across hospitals, laboratories, outpatient facilities, and other care settings to improve clinical decision-making and care coordination.
The care coordination solutions segment is expected to register the fastest CAGR during the forecast period, driven by the increasing emphasis on patient-centric and coordinated care delivery. Healthcare providers, payers, employer groups, and government organizations are increasingly adopting care coordination solutions to improve communication, streamline workflows, and facilitate the management of patients across multiple care settings. These solutions reduce administrative inefficiencies, improve information sharing among care teams, and support continuity of care. The growing adoption of value-based care models and increasing collaboration among providers and payers are expected to further accelerate demand for care coordination solutions.
End Use Insights
The hospitals segment dominated the market, accounting for around 45.0% of revenue in 2025. Hospitals generate and manage large volumes of clinical, administrative, and patient data, creating substantial demand for integrated workflow management and data coordination solutions. The increasing adoption of EHRs, connected hospital infrastructure, interoperability technologies, and digital clinical communication platforms is further supporting segment growth. In addition, government initiatives promoting healthcare digitization and the growing emphasis on secure data exchange are encouraging hospitals to invest in clinical workflow solutions. Demand for collaborative care delivery, unified clinical communications, automated scheduling, and streamlined administrative processes is also contributing to the segment's leading market position.
The ambulatory care centers segment is anticipated to register the fastest CAGR during the forecast period. Increasing outpatient volumes, the expansion of ambulatory care delivery, and the growing adoption of digital healthcare technologies are driving demand for clinical workflow solutions in these facilities. Workflow technologies facilitate information sharing among physicians, nurses, pharmacists, and other care teams while supporting scheduling, documentation, patient communication, and care coordination. The increasing focus on cost-efficient care delivery, shorter hospital stays, and technology-enabled outpatient services is expected to further support segment growth. In addition, the growing adoption of home healthcare and long-term care services is creating additional opportunities for workflow solutions that enable remote coordination, information exchange, and collaboration between providers and patients.
Regional Insights
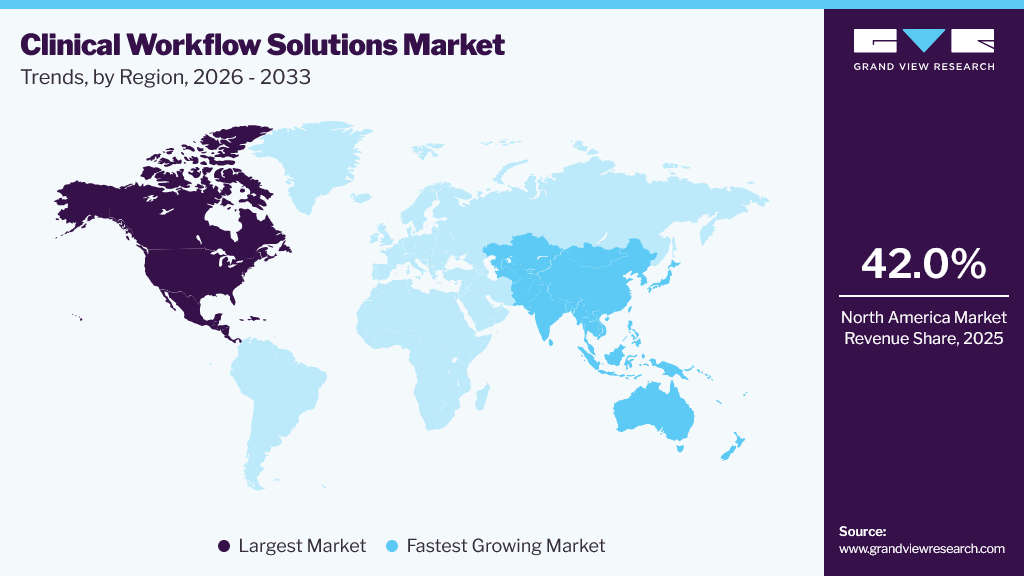
North America clinical workflow solutions market dominated the global market, accounting for around 42.0% of revenue in 2025. The region's leading position is supported by the widespread adoption of EHR systems, advanced healthcare IT infrastructure, and interoperability solutions, as well as high healthcare expenditure and substantial investment in digital transformation. The presence of major healthcare technology providers and ongoing R&D activities further supports market development. In addition, government initiatives aimed at improving healthcare interoperability, secure data exchange, and digital health adoption are encouraging healthcare organizations to modernize clinical workflows. The growing volume of healthcare data and increasing demand for coordinated patient-centric care are also contributing to the region's strong market position.
 To learn more about this report, Download Free Sample Report
Asia Pacific Clinical Workflow Solutions Market Trends
Asia Pacific is expected to be the fastest-growing regional market during the forecast period. Growth is expected to be driven by increasing healthcare digitization, improving healthcare infrastructure, rising adoption of EHR and health information systems, and growing demand for efficient clinical data management. Government initiatives supporting eHealth and digital healthcare, combined with rising healthcare expenditure and the expansion of hospitals and outpatient facilities, are creating additional opportunities for clinical workflow solution providers. In addition, rising medical tourism and growing demand for high-quality, technology-enabled healthcare services are encouraging healthcare organizations across the region to adopt integrated workflow, interoperability, and care coordination solutions.
Key Clinical Workflow Solutions Market Company Insights
The global clinical workflow solutions market is highly competitive, with established healthcare IT providers, clinical communication specialists, and emerging AI-driven technology companies competing through product innovation, workflow automation, interoperability, and strategic partnerships. Leading players are increasingly incorporating artificial intelligence, data integration, clinical communication, and automation capabilities into their platforms to improve clinical efficiency, reduce administrative workloads, and support coordinated care delivery.
Clinical Workflow Solutions Companies
The following key companies have been profiled for this study on the clinical workflow solutions market.
- AMETEK, Inc.
- Cisco Systems, Inc.
- Getinge AB.
- Koninklijke Philips N.V.
- McKesson Corporation
- NXGN Management, LLC
- Oracle Health (formerly Cerner Corporation)
- Spok Inc.
- Veradigm Inc. (formerly Allscripts Healthcare Solutions, Inc.)
- Vocera (a Stryker company)
Recent Development
-
In June 2026, Oracle Health partnered with Theator to extend AI-powered surgical intelligence into the operating room. The solution combines surgical video analysis with EHR data to automate reporting and improve documentation accuracy, billing workflows, and clinical decision-making. The integration demonstrates the growing use of AI to automate complex clinical workflows and connect procedural data with electronic health records
-
In February 2026, UCHealth expanded its deployment of Abridge's ambient AI platform across its healthcare system, following a nine-month pilot involving 250 providers. The platform captures patient-provider conversations and generates draft clinical documentation directly in the patient chart, supporting more efficient clinical workflows and reducing documentation burden
Clinical Workflow Solutions Market Report Scope
Report Attribute
Details
Market size in 2025
USD 13.8 billion
Estimated market size in 2026
USD 15.7 billion
Projected market size by 2033
USD 37.1 billion
Growth rate
CAGR of 13.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, end use, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; Australia; Thailand; South Korea; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Veradigm Inc. (formerly Allscripts Healthcare Solutions, Inc.); Oracle Health (formerly Cerner Corporation); NXGN Management, LLC; McKesson Corporation; Koninklijke Philips N.V.; Cisco Systems, Inc.; Getinge AB.; Vocera (a Stryker company); Spok Inc.; AMETEK, Inc.
Customization scope
Free report customization (equivalent to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Clinical Workflow Solutions Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest trends in each of the sub-segments from 2021 to 2033. For this report, Grand View Research has segmented the global clinical workflow solutions market by type, end use, and region:
- Type Outlook (Revenue, USD Billion, 2021 - 2033)
- Data Integration Solutions
- EMR Integration Solutions
- Medical Image Integration Solutions
- Real-time Communication Solutions
- Nurse Call Alert Systems
- Unified Communication Solutions
- Workflow Automation Solutions
- Patient Flow Management Solutions
- Nursing & Staff Scheduling Solutions
- Care Collaboration Solutions
- Medication Administration Solutions
- Perinatal Care Management Solutions
- Rounding Solutions
- Other Care Collaboration Solutions (Specimen Collection Solutions and Blood Products Administration Solutions)
- Enterprise Reporting & Analytics Solutions
- Data Integration Solutions
- End Use Outlook (Revenue, USD Billion, 2021 - 2033)
- Hospitals
- Long-term Care Facilities
- Ambulatory Care Centers
- Regional Outlook (Revenue, USD Billion, 2021 - 2033)
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- UK
- France
- Italy
- Spain
- Denmark
- Sweden
- Norway
- Asia Pacific
- Japan
- China
- India
- Australia
- South Korea
- Thailand
- Latin America
- Brazil
- Argentina
- Middle East and Africa (MEA)
- South Africa
- Saudi Arabia
- UAE
- Kuwait
- North America
Frequently Asked Questions About This Report
The global clinical workflow solutions market size was valued at USD 13.8 billion in 2025 and is estimated at USD 15.7 billion for 2026.
The global clinical workflow solutions market is expected to grow at a CAGR of 13.1% from 2026 to 2033, reaching USD 37.1 billion by 2033.
North America dominated with approximately 42.0% revenue share in 2025.
Key players in the market include Veradigm Inc., Oracle Health, NXGN Management, LLC, McKesson Corporation, Koninklijke Philips N.V., Cisco Systems, Inc., Getinge AB., Vocera (a Stryker company), Spok Inc., AMETEK, Inc, and others.
The hospitals segment accounted for the largest market share of around 45.0% in 2025.
About the Author(s)
Healthcare IT Research Team
Healthcare · Healthcare ITThis report was authored by the healthcare it research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the healthcare it segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


