
- Home
- »
- Specialty Glass, Ceramic & Fiber
- »
-
Clothing Fibers Market Size, Share & Growth Report, 2033GVR Report cover

Clothing Fibers Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Cotton, Synthetic, Animal-based, Others), By End Use (Women’s Wear, Men’s Wear, Kid's Wear), By Region, And Segment Forecasts
Market Size, 2025
$232.6BMarket Estimate, 2026
$242.1BMarket Forecast, 2033
$337.2BCAGR, 2026–2033
4.8%Clothing Fibers Market Summary
The global clothing fibers market size was valued at USD 232.6 billion in 2025 and is projected to grow from USD 242.1 billion in 2026 to USD 337.2 billion by 2033, at a CAGR of 4.8% from 2026 to 2033. The market in Asia Pacific dominated with a revenue share of 45.2% in 2025. The demand for clothing fibers is rising steadily due to the expanding global population and increasing urbanization, which drive greater apparel consumption.
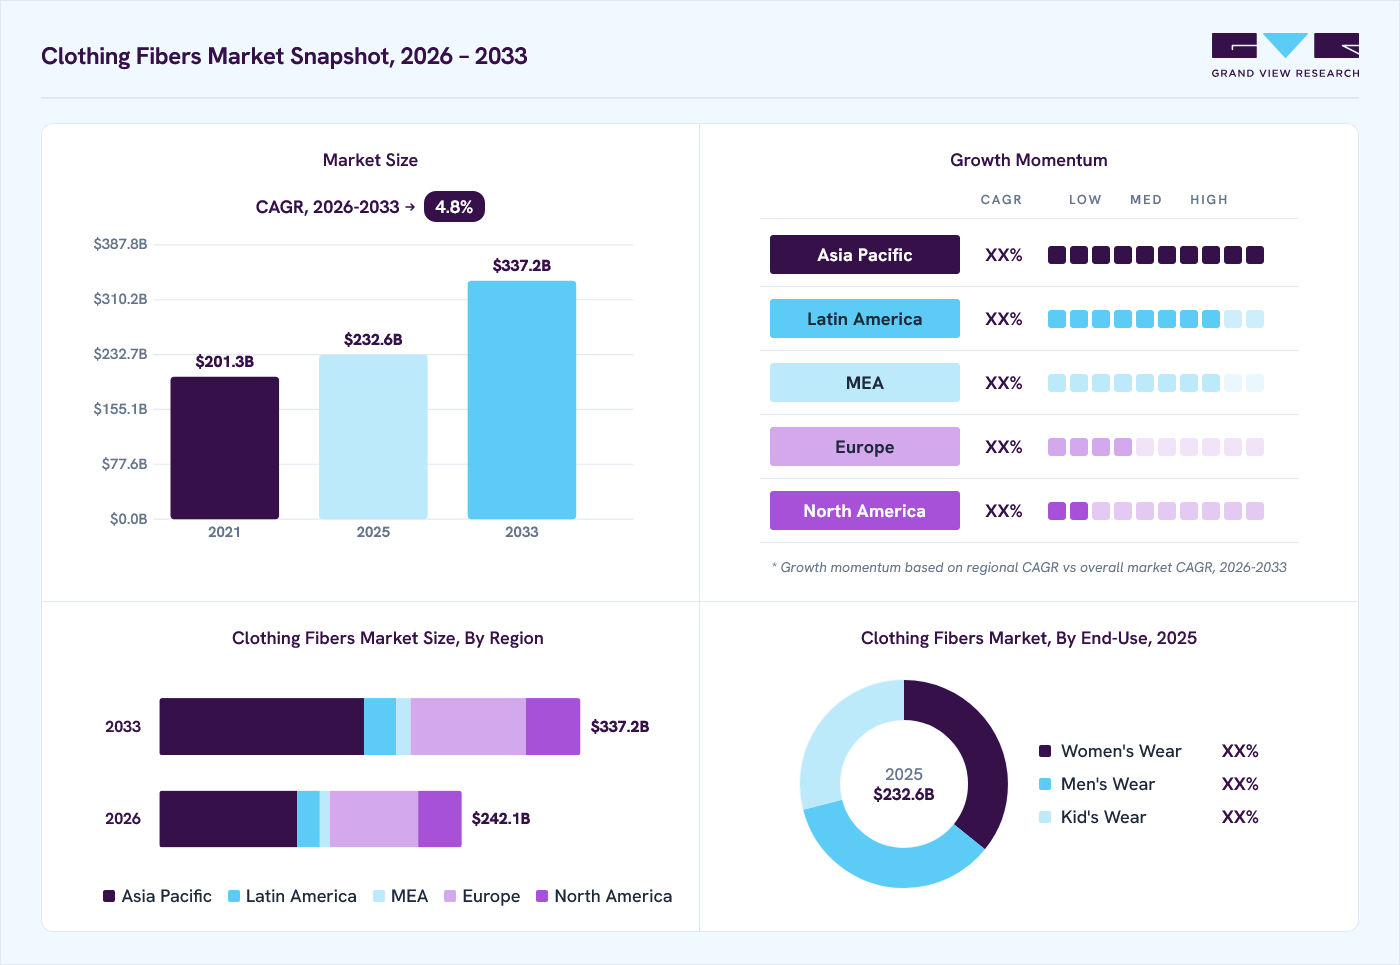 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: The synthetic segment held the largest market share of 58.8% in 2025.
- By end use: The women's wear segment held the largest market share of 35.8% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (45.2% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 232.6 Billion
- Estimated market size in 2026: USD 242.1 Billion
- Projected market size by 2033: USD 337.2 Billion
- CAGR (2026-2033): 4.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The rising disposable income levels, especially in emerging economies, have led to a surge in demand for fashion and comfort-oriented clothing. E-commerce growth has made clothing more accessible, further accelerating fiber demand. Consumers are also increasingly prioritizing sustainable and eco-friendly fashion, which boosts demand for natural and regenerated fibers. Seasonal fashion cycles and fast fashion trends contribute to high turnover rates in apparel, requiring constant fiber production. The shift toward performance wear and functional textiles is fueling specialized fiber segments.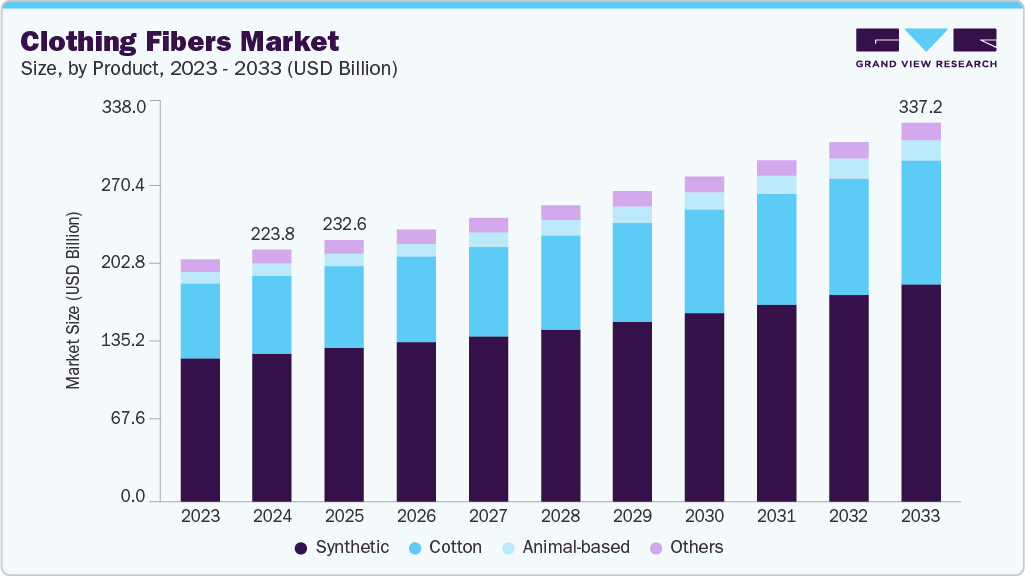 To learn more about this report, Download Free Sample Report
Key growth drivers for the clothing fibers industry include the increasing inclination toward sustainable textiles, the growth of technical textiles, and innovation in fiber blends. Demand for natural fibers like organic cotton, hemp, and bamboo is expanding due to environmental concerns. Synthetic fibers like polyester and nylon continue to dominate due to their low cost, durability, and versatility in different weather conditions. Additionally, advancements in fiber engineering have led to high-performance blends catering to specific use cases such as sportswear, casual wear, and formalwear. A robust global textile and apparel industry, coupled with trade liberalization and favorable sourcing practices, is sustaining fiber demand. The rapid emergence of textile recycling technologies is also reshaping how fibers are produced and consumed.
A notable trend is the rising use of bio-based and biodegradable fibers, such as lyocell and polylactic acid (PLA), in sustainable fashion. The integration of nanotechnology and smart fibers in clothing is gaining ground, especially in functional and wearable technology segments. Companies are also exploring recycled polyester (rPET) and circular design models to reduce fiber waste. Blended fabrics combining natural and synthetic fibers for improved comfort, elasticity, and durability are becoming more popular. Digital fashion trends and 3D knitting technologies are reshaping fiber usage by minimizing waste and enabling on-demand production. There’s also a growing focus on traceability and certification, with consumers preferring brands that ensure fiber origin transparency.
Market Dynamics
The clothing fibers market is witnessing steady growth owing to rising global apparel consumption, increasing demand for sustainable and high-performance textiles, and continuous innovation in fiber manufacturing technologies. Rapid urbanization, changing fashion trends, and growing disposable incomes are fueling demand for both natural and synthetic clothing fibers across developed and emerging economies. Manufacturers are investing in recycled fibers, bio-based materials, and advanced production technologies to align with evolving environmental regulations and consumer preferences. Additionally, the expansion of e-commerce, fast fashion, sportswear, and technical apparel segments continues to create significant opportunities for fiber producers worldwide.
Sustainability has become one of the primary growth drivers for the clothing fibers market as consumers, fashion brands, and governments increasingly prioritize environmentally responsible materials. Rising concerns regarding carbon emissions, water consumption, and textile waste have accelerated the adoption of organic cotton, recycled polyester, regenerated cellulose fibers, hemp, and other bio-based alternatives. Major apparel brands are incorporating recycled and sustainably sourced fibers into their product portfolios while committing to circular economy initiatives, boosting long-term demand for eco-friendly clothing fibers.
In addition, governments and international organizations are introducing stricter environmental regulations and extended producer responsibility (EPR) policies for the textile industry. Investments in fiber recycling technologies, chemical recycling, closed-loop manufacturing, and traceable supply chains are expanding rapidly. These developments encourage fiber manufacturers to innovate sustainable products while enabling apparel companies to meet ESG commitments and consumer expectations, thereby supporting consistent market growth.
The clothing fibers market faces significant challenges due to fluctuations in raw material prices, including cotton, crude oil derivatives used for synthetic fibers, and wood pulp utilized in regenerated fibers. Climate-related disruptions affecting cotton production, geopolitical uncertainties, trade restrictions, and fluctuations in energy costs increase manufacturing expenses and create pricing instability across the textile value chain. These factors reduce profitability for fiber manufacturers and complicate procurement planning for apparel producers.
Technological innovation presents substantial opportunities for the clothing fibers market through the development of high-performance, recycled, biodegradable, and smart textile fibers. Advancements in bio-based polymers, chemical fiber recycling, nanotechnology, moisture-management fibers, antimicrobial treatments, and digital manufacturing processes are enabling the production of next-generation apparel materials with enhanced functionality and lower environmental impact. Growing investments in circular textile ecosystems and fiber-to-fiber recycling technologies are expected to unlock new revenue streams while supporting long-term sustainability objectives across the global apparel industry.
Market Concentration & Characteristics
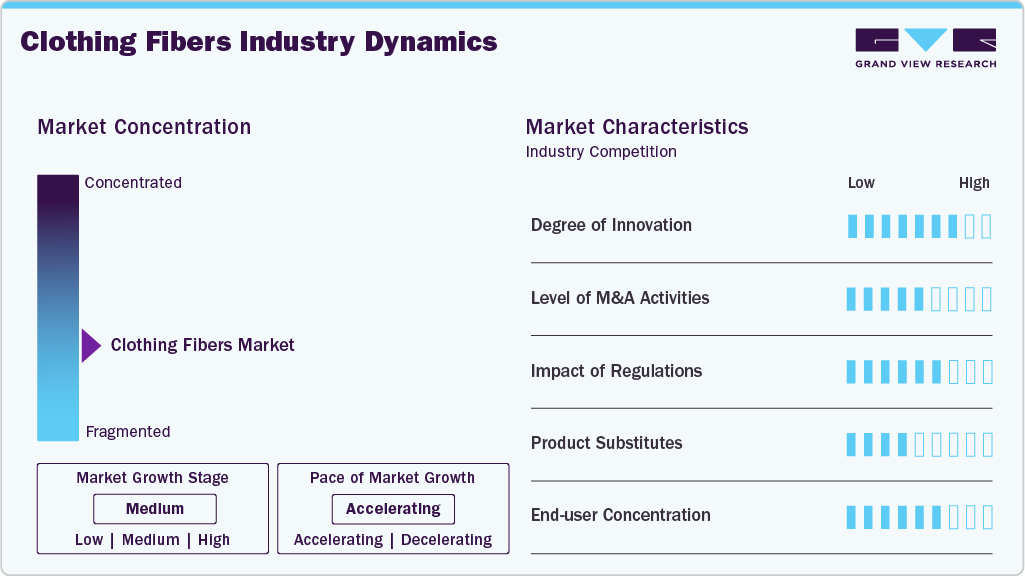
The clothing fibers market is moderately fragmented, with a mix of large-scale chemical corporations dominating the synthetic fiber space and various regional players catering to natural and specialty fibers. The presence of integrated companies with in-house fiber-to-garment capabilities gives them a competitive edge. Meanwhile, startups and small firms are disrupting the market with sustainable fiber innovations. Consolidation is seen in segments like polyester and viscose due to economies of scale, while eco-fiber niches remain open to new entrants. The global nature of sourcing and production also dilutes market concentration across geographies, although vertical integration is a growing trend among top players.
 To learn more about this report, Download Free Sample Report
The threat of substitutes in the clothing fibers industry is moderate, as each fiber type has specific properties suited for different applications. However, innovations in lab-grown fibers and leather alternatives pose future threats. Natural fibers may be substituted with synthetic or regenerated alternatives for cost or performance reasons. Similarly, the rise of second-hand clothing, rental fashion, and digital wearables could indirectly reduce demand for virgin fibers. Yet, due to the deeply embedded use of traditional fibers in garment manufacturing, immediate substitution remains unlikely. However, increasing consumer consciousness about fiber origin and sustainability may cause market shifts over time.
Analyst Perspective
The clothing fibers market is evolving from a conventional textile raw materials market into a technology-driven industry centered on sustainable fiber innovation, recycled and bio-based materials, advanced polymer technologies, circular textile manufacturing, and high-performance functional fibers. The strongest growth opportunities are emerging from sportswear and athleisure, fast fashion, luxury apparel, technical textiles, children's wear, and eco-conscious clothing segments seeking superior comfort, durability, moisture management, and reduced environmental impact while complying with increasingly stringent sustainability regulations. The key differentiator for companies will not be clothing fiber production capacity alone, but their ability to develop sustainable and application-specific fibers, improve fiber performance, enhance softness and durability, reduce carbon emissions and water consumption, increase recyclability, and deliver innovative textile solutions tailored to evolving consumer and apparel manufacturer requirements. Players with proprietary fiber technologies, advanced polymer and cellulose processing capabilities, strong R&D investments, integrated manufacturing operations, diversified fiber portfolios, and strategic partnerships with apparel brands, textile mills, fashion retailers, and recycling companies are expected to capture premium market share and long-term growth opportunities.
Product Insights
Based on product, the synthetic segment led the market with the largest revenue share of 58.8% in 2025 and is expected to grow at a CAGR of 4.5% over the forecast period, due to their cost-effectiveness, durability, and versatility across various apparel segments. Fibers such as polyester, nylon, and acrylic are widely used for their resistance to shrinkage, high tensile strength, and ability to retain colors and shapes, making them ideal for both casual and performance wear. Their compatibility with advanced manufacturing techniques and ease of mass production have given them a competitive edge, particularly in fast fashion. Moreover, innovations in recycled synthetic fibers like rPET are helping brands align with sustainability goals while maintaining performance, further reinforcing the dominance of synthetics in the global market.
The cotton segment is expected to grow at a significant CAGR of 5.4% over the forecast period, driven by rising consumer preference for breathable, skin-friendly, and biodegradable fabrics. Growing awareness of sustainable fashion and the harmful environmental impact of synthetic fibers has accelerated demand for organic and responsibly sourced cotton. Cotton's versatility in both luxury and everyday wear also boosts its appeal across demographics. Government support for cotton farming, including subsidies and organic certification programs, has further improved its production and global trade. Additionally, fashion brands are increasingly incorporating cotton into their collections to meet eco-conscious consumer expectations and ESG commitments.
End Use Insights
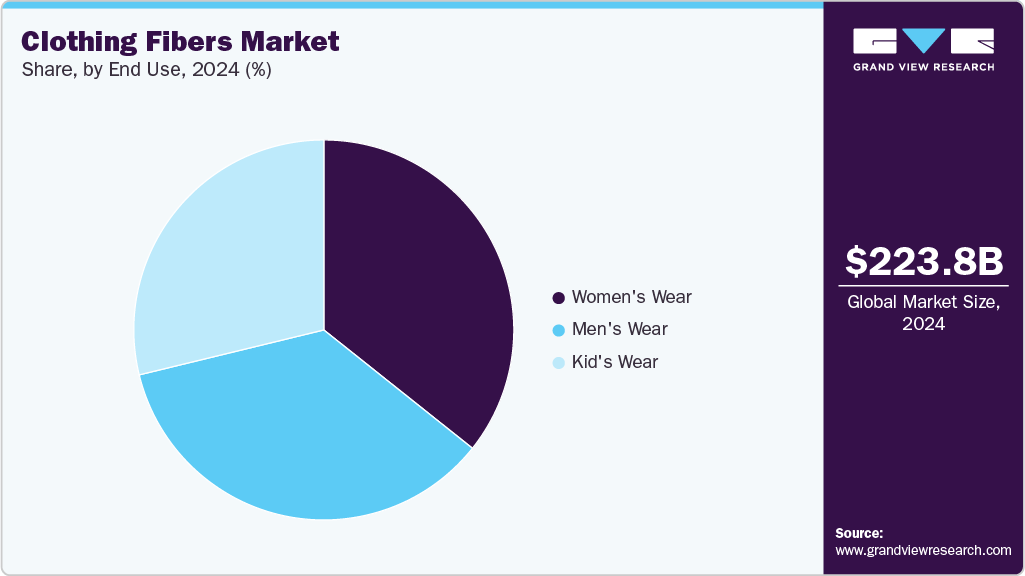
Based on end use, the women's wear segment led the market with the largest revenue share of 35.8% in 2025 and is expected to grow at a CAGR of 5.1% over the forecast period, driven by evolving fashion trends, higher garment variety, and increasing purchasing frequency among female consumers. The segment exhibits strong demand for both natural fibers like cotton and premium options such as silk and viscose, used in dresses, tops, and athleisure. The rise of fashion-conscious and digitally active female shoppers is pushing brands to frequently update collections, resulting in higher fiber usage. Moreover, growing awareness around sustainability and body-inclusive fashion has led to increased use of innovative and comfortable fibers tailored to diverse needs. This dynamic consumer base is accelerating fiber innovation and demand in women's wear.
 To learn more about this report, Download Free Sample Report
The kid’s wear segment is expected to grow at the fastest CAGR of 5.5% over the forecast period, due to increasing demand for comfortable, safe, and sustainable materials. Parents are showing a strong preference for organic and skin-friendly fabrics such as cotton, bamboo, and Tencel, driving innovation and diversification in fiber usage. The rise of children's activewear has also pushed demand for performance-enhancing fibers like spandex and polyester blends that offer flexibility and durability. Additionally, growing awareness around eco-conscious fashion and ethical manufacturing is accelerating the adoption of natural and regenerated fibers in children's clothing.
Regional Insights
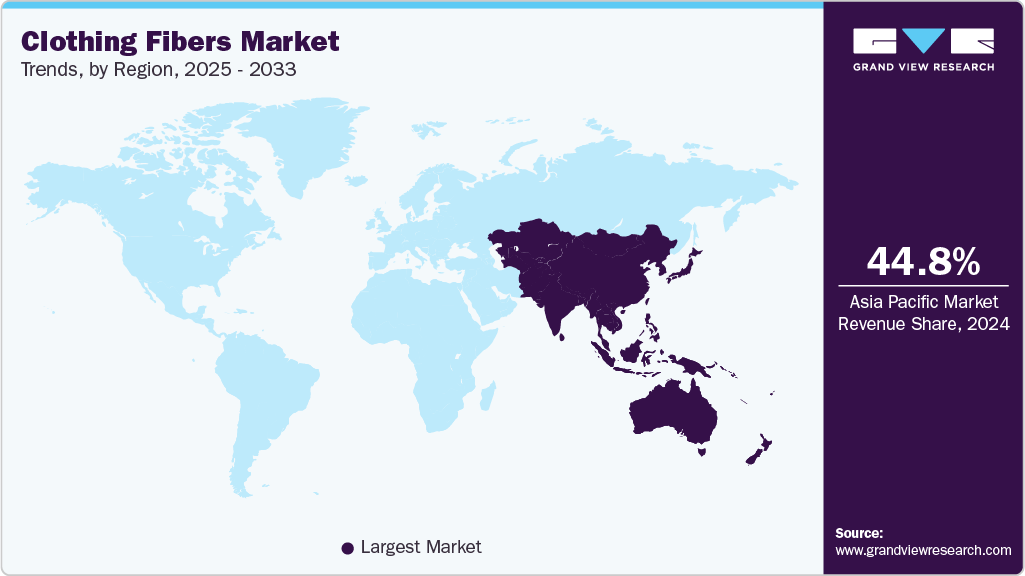
Asia Pacific dominated the clothing fibers market with the largest revenue share of 45.2% in 2025, owing to its vast textile manufacturing ecosystem, cost-effective labor, and abundant availability of raw materials like cotton, jute, and viscose. China, India, Bangladesh, and Vietnam are key contributors to both fiber production and apparel exports. Government schemes supporting textile parks and man-made fiber clusters have strengthened the industry. The region is also witnessing rising domestic consumption driven by a growing middle class and urbanization. Technological advancements in spinning and dyeing, along with increased focus on eco-friendly production methods, are enhancing competitiveness. The rising participation of regional manufacturers in global supply chains positions Asia Pacific as a dominant force in both volume and innovation.
 To learn more about this report, Download Free Sample Report
China Clothing Fibers Market Trends
The clothing fibers market in China held the largest share in the Asia Pacific region in 2025. China remains the world’s leading producer of polyester, viscose, and nylon, supported by a strong petrochemical base and vertically integrated manufacturing. It is also increasing its focus on sustainability, with domestic brands and manufacturers adopting recycled polyester and cleaner fiber processing technologies. The Chinese government is encouraging green production through subsidies and emission regulations. Moreover, the country is shifting towards high-end textile exports and investing in automation and AI for fiber processing. Its growing domestic fashion market, driven by young consumers and digital platforms, is further boosting fiber demand. Partnerships with international apparel brands are driving innovation in high-performance and functional clothing fibers.
North America Clothing Fibers Market Trends
The North America clothing fibers industry is evolving with increased adoption of eco-conscious textiles and support for reshoring fiber and textile manufacturing. Manufacturers are investing in advanced fiber technologies such as moisture-wicking, temperature-regulating, and anti-microbial fabrics, especially for sportswear and outdoor clothing. The rise of slow fashion, local sourcing, and consumer demand for organic and traceable fibers is transforming the market landscape. U.S. and Canadian companies are also exploring innovative blends combining natural and synthetic fibers to improve comfort and longevity. Recycling infrastructure for polyester and post-consumer textile waste is gaining traction, promoting circular economy models.
U.S. Clothing Fibers Market Trends
The U.S. is focusing on high-performance fibers used in sports, outdoor wear, and technical apparel. There is a growing push towards sustainability, with consumer awareness encouraging the adoption of organic cotton, hemp, and rPET. U.S.-based brands are increasingly partnering with textile recyclers and sustainable fiber innovators. Government support for domestic textile manufacturing, including recent incentives for reshoring and clean energy adoption, is improving local competitiveness. Demand for traceable and certified clothing fibers has also surged due to ESG considerations. Innovation in fiber biotechnology is another area of growth, with several startups working on lab-grown and carbon-negative fibers.
Europe Clothing Fibers Market Trends
Europe is leading in sustainable fiber innovation, driven by stringent EU regulations and an environmentally conscious consumer base. The region is highly focused on circular fashion, with brands emphasizing fiber traceability, recyclability, and lifecycle impact. Countries like Italy, France, and the Netherlands are investing in next-generation materials such as regenerated cellulosics and biodegradable synthetics. Extended Producer Responsibility (EPR) regulations are pushing fiber producers to innovate in end-of-life solutions. The rise of ethical fashion movements, combined with pressure from NGOs and consumer advocacy groups, is reshaping fiber choices in apparel. The region also supports textile R&D hubs and academic-industry collaborations.
The Germany clothing fibers market is expected to grow during the forecast period. Germany stands out for its leadership in technical and functional fibers, driven by advanced R&D capabilities and a strong machinery sector. The country emphasizes high-quality synthetic and performance fibers used in sportswear, medical textiles, and protective clothing. Its focus on sustainability has led to significant investments in fiber recycling technologies, bio-based polymers, and energy-efficient manufacturing. German consumers show high awareness of environmental impact, which is pushing retailers to adopt certified and traceable fiber inputs. The country’s well-regulated textile supply chain, along with EU funding for green technologies, makes it a key hub for sustainable fiber development.
Central & South America Clothing Fibers Market Trends
Central & South America is showing growth potential in natural clothing fibers, particularly in cotton and alpaca wool. Countries like Brazil, Peru, and Colombia are increasing investments in textile production, driven by both export and domestic demand. Rising incomes and fashion consciousness are pushing consumers toward diverse apparel choices, thereby increasing fiber demand. However, the region faces challenges in large-scale synthetic fiber production due to limited petrochemical infrastructure. Governments are supporting the development of sustainable fiber value chains, particularly in organic farming and indigenous fiber crafts. Regional players are also exploring export opportunities for niche and luxury fibers in global markets.
Middle East & Africa Clothing Fibers Market Trends
The Middle East & Africa region is gradually expanding its footprint in the clothing fibers industry, driven by investments in textile zones, trade partnerships, and increasing consumer demand. Countries like Egypt and Ethiopia are gaining attention as emerging textile hubs due to their cotton-growing potential and labor availability. Gulf countries are investing in synthetic fiber production and downstream textile industries as part of their diversification strategies. In Africa, donor-backed programs are supporting sustainable cotton farming and local fiber processing. While infrastructural limitations exist, increasing urbanization and demand for affordable clothing are pushing growth. Export-driven fiber development is gaining ground, especially in East Africa.
Key Clothing Fibers Company Insights
Some of the key players operating in the market include Eastman Chemical Company and Asahi Kasei Corporation.
-
Eastman Chemical Company is a U.S.-based specialty materials manufacturer known for producing innovative, sustainable fiber solutions for textiles and apparel. Its Naia cellulosic fiber is gaining popularity in the fashion industry for being eco-friendly, soft, and biodegradable. The company leverages closed-loop production and sustainable sourcing to support circular fashion initiatives.
-
Asahi Kasei is a Japanese multinational that produces a range of synthetic and regenerated fibers. It is best known for Bemberg, a premium cupro fiber made from cotton linter, and Roica, a high-performance stretch fiber (spandex). Asahi Kasei focuses heavily on sustainable innovation and technical performance in the fashion and sportswear sectors.
Toray Industries, Inc. and Indorama Ventures Public Company Limited are some of the emerging participants in the clothing fibers market.
-
Toray Industries is a leading Japanese manufacturer of synthetic fibers such as polyester and nylon, widely used in apparel, sportswear, and industrial textiles. It is known for its proprietary technologies in ultra-microfiber and recycled fiber production. Toray plays a major role in promoting sustainability through advanced materials like ECOSUEDE and &+ (And Plus) fibers.
-
Headquartered in Thailand, Indorama Ventures is one of the world’s largest producers of polyester fibers, yarns, and PET resins used in clothing, home textiles, and industrial fabrics. The company emphasizes recycling and circular economy practices, with a strong presence in post-consumer PET recycling for fiber applications, particularly through its DEJA brand.
Key Clothing Fibers Companies:
The following key companies have been profiled for this study on the clothing fibers market.
-
Eastman Chemical Company
-
Teijin Ltd.
-
Toray Industries, Inc.
-
Asahi Kasei Corporation
-
The Bombay Dyeing and Manufacturing Co. Ltd.
-
Reliance Industries Limited
-
Indorama Ventures Public Company Limited
-
Invista
-
Hyosung TNC Corporation
-
Lenzing AG
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Toray Industries, Inc., Asahi Kasei Corporation, Teijin Ltd., Eastman Chemical Company, Reliance Industries Limited)
- Invest in vertically integrated fiber production and global supply chain optimization.
- Expand portfolios through recycled, bio-based, and high-performance fiber innovations.
- Strengthen market presence through strategic acquisitions, joint ventures, and long-term partnerships with apparel brands.
- Extensive global manufacturing footprint with large-scale production capacities.
- Strong R&D capabilities enabling continuous product innovation and sustainability improvements.
- Diversified customer base across fashion, sportswear, luxury apparel, and industrial textile segments.
- High exposure to fluctuations in cotton, petrochemical feedstock, and energy prices.
- Significant capital investment required for modernization and sustainability compliance.
- Complex global supply chains increase operational and geopolitical risks.
Emerging Players (The Bombay Dyeing and Manufacturing Co. Ltd., Hyosung TNC Corporation)
- Focus on regional market expansion and cost-efficient manufacturing operations.
- Develop niche and specialty fibers to differentiate product offerings.
- Establish partnerships with domestic textile mills and apparel manufacturers to increase market penetration.
- Greater flexibility in responding to changing fashion trends and customer requirements.
- Competitive pricing supported by lower operating costs and localized production.
- Strong presence in fast-growing regional textile and garment manufacturing hubs.
- Limited financial resources for large-scale R&D and capacity expansion.
- Lower international brand recognition and comparatively smaller customer base.
- Higher dependence on regional demand and contract manufacturing, making revenues more vulnerable to local economic conditions.
Recent Developments
-
In February 2026, Eastman Chemical Company introduced Naia Lyte, a cellulose acetate filament yarn designed for lightweight premium fabrics. The commercially produced fiber offers enhanced tenacity, a silky feel, and moisture-management properties for apparel applications.
-
In May 2025, Teijin Frontier, a subsidiary of Teijin Ltd., introduced a high-performance recycled polyester fabric that mimics the look and feel of natural fibers through proprietary spinning and finishing. The fabric features cooling touch, UV protection, anti-stick and quick-dry properties, and is made from 100% recycled polyester, with a commercial launch planned for spring/summer 2026.
-
In February 2025, Hyosung, Loop Industries, and Pleatsmama collaborated to pioneer circular fashion with infinite Loop textile-to-textile recycling technology. The collaboration highlights the growing demand for recycled polyester fibers in apparel.
Clothing Fibers Market Report Scope
Report Attribute
Details
Market size in 2025
USD 232.6 billion
Estimated market size in 2026
USD 242.1 billion
Projected market size by 2033
USD 337.2 billion
Growth rate
CAGR of 4.8% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Volume in kilotons, Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, end use, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Spain; Italy; China; Japan; India; South Korea; Brazil; South Africa; Morocco
Key companies profiled
Eastman Chemical Company; Teijin Ltd.; Toray Industries, Inc.; Asahi Kasei Corporation; The Bombay Dyeing and Manufacturing Co. Ltd.; Reliance Industries Limited; Indorama Ventures Public Company Limited; Invista; Hyosung TNC Corporation; Lenzing AG
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Clothing Fibers Market Report Segmentation
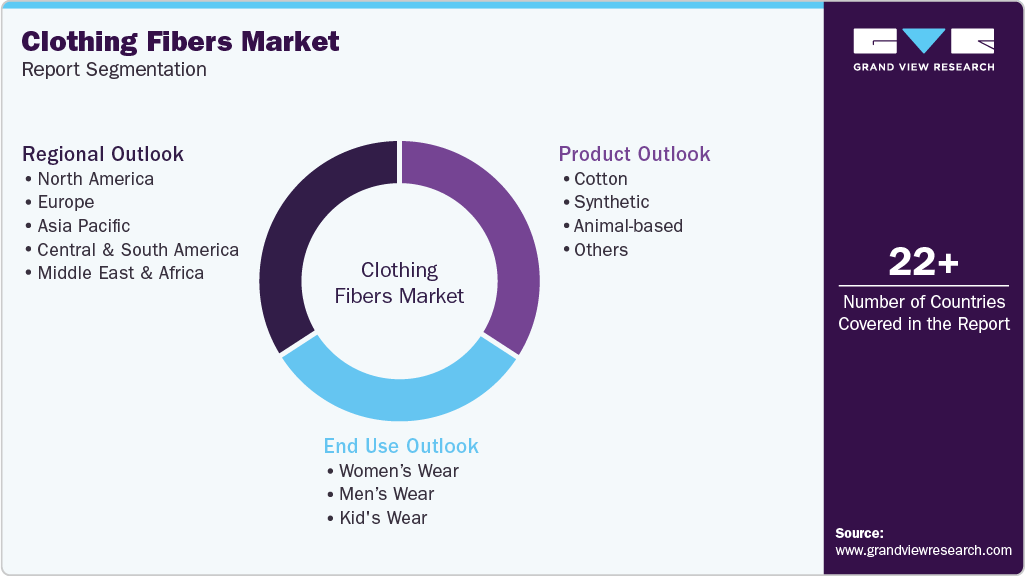
This report forecasts volume & revenue growth at the global, regional & country levels and provides an analysis of the industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the clothing fibers market report based on product, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Cotton
-
Synthetic
-
Animal-based
-
Others
-
-
End Use Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Women’s Wear
-
Men’s Wear
-
Kid's Wear
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
-
Central & South America
-
Brazil
-
-
Middle East & Africa
-
South Africa
-
Morocco
-
-
Research Methodology
The clothing fibers market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each clothing fibers segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Cotton
Revenue generated from the sale of cotton fibers used in the production of apparel across residential and commercial textile manufacturing operations. This segment captures revenues from natural cotton fibers supplied for casual wear, formal wear, denim, knitwear, innerwear, sportswear, children's clothing, and fashion apparel. It includes revenues from conventional cotton, organic cotton, combed cotton, and blended cotton fibers utilized by spinning mills, textile manufacturers, and garment producers worldwide.
Synthetic
Revenue generated from the sale of synthetic clothing fibers used in manufacturing a wide range of apparel products. This segment captures revenues from fibers such as polyester, nylon, acrylic, polypropylene, and elastane supplied for activewear, athleisure, outerwear, workwear, fashion garments, and blended fabrics. It also includes high-performance synthetic fibers designed for durability, stretchability, moisture management, wrinkle resistance, and easy-care clothing applications.
Animal Based
Revenue generated from the sale of animal-derived clothing fibers used in premium and specialty apparel manufacturing. This segment captures revenues from wool, silk, cashmere, alpaca, mohair, angora, and other natural animal fibers supplied for luxury garments, knitwear, winter clothing, suits, scarves, sweaters, formal wear, and designer fashion collections. The segment also includes specialty fibers processed for high-value textile applications requiring superior softness, insulation, and comfort.
Others
Revenue generated from the sale of other natural, regenerated, and bio-based clothing fibers used in apparel manufacturing. This segment captures revenues from viscose, lyocell, modal, linen, hemp, bamboo, ramie, recycled fibers, and other innovative textile materials supplied for sustainable fashion, casual wear, premium apparel, and blended fabrics. It also includes emerging next-generation fibers developed from renewable resources and recycled textile waste to support circular economy initiatives.
Segment - End Use
Revenue capture definition
Women's Wear
Revenue generated from the sale of clothing fibers used in the production of women's apparel across fashion, casual, formal, and performance clothing categories. This segment captures revenues from fibers supplied for dresses, tops, blouses, trousers, skirts, denim, ethnic wear, lingerie, maternity wear, sportswear, activewear, outerwear, and luxury garments. It also includes fibers utilized by fashion brands, apparel manufacturers, and private-label clothing companies serving the women's clothing market.
Men's Wear
Revenue generated from the sale of clothing fibers used in the production of men's apparel for everyday, formal, and specialty applications. This segment captures revenues from fibers supplied for shirts, trousers, suits, denim, T-shirts, jackets, coats, uniforms, workwear, sportswear, activewear, knitwear, and innerwear. It also includes fibers used by textile mills and garment manufacturers producing apparel for fashion brands, retailers, and institutional clothing suppliers.
Kid's Wear
Revenue generated from the sale of clothing fibers used in the production of apparel for infants, toddlers, and children. This segment captures revenues from fibers supplied for baby clothing, school uniforms, casual wear, sleepwear, sportswear, festive wear, outerwear, and children's fashion garments. It also includes fibers selected for their softness, comfort, durability, breathability, hypoallergenic properties, and ease of maintenance to meet the performance and safety requirements of children's clothing.
Estimation Model
Layer Name
Key Question
Description
Global Fiber Production Analysis
What is the total production and consumption of clothing fibers worldwide?
The first layer estimates the overall clothing fibers market by analyzing global production volumes and revenues across natural, synthetic, animal-based, regenerated, and recycled fibers. It evaluates manufacturing capacity, trade flows, fiber pricing, and consumption trends using data from textile associations, industry reports, government statistics, and company disclosures.
Application & End-use Mapping
How are clothing fibers consumed across different apparel categories?
The second layer segments the market based on fiber utilization across women's wear, men's wear, and kids' wear. It assesses fiber consumption patterns by garment type, fashion trends, textile manufacturing output, and demand from fast fashion, premium apparel, sportswear, luxury clothing, and workwear manufacturers to estimate revenue contribution by end-use segment.
Regional Demand Assessment
Which regions contribute the highest demand for clothing fibers?
The third layer evaluates regional market size by analyzing apparel production, textile exports, retail clothing sales, consumer spending, population demographics, disposable income, and manufacturing hubs across Asia Pacific, North America, Europe, Latin America, and the Middle East & Africa. Country-level demand and supply dynamics are incorporated to refine regional revenue estimates.
Company Revenue Validation & Market Triangulation
Do company revenues validate the estimated market size?
The final layer validates market estimates through revenue benchmarking of leading clothing fiber manufacturers, textile producers, and integrated apparel supply chain participants. Company financial reports, production capacities, pricing analysis, import-export statistics, and primary interviews are triangulated to ensure consistency and accuracy of the final market size and forecast estimates.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Sustainability & Circular Textile Ecosystem Analysis
Evaluation of recycled fibers, fiber-to-fiber recycling technologies, bio-based materials, ESG initiatives, circular economy trends, and regulatory developments impacting the textile value chain.
Supports strategic planning related to sustainability compliance, carbon reduction goals, circular business models, and environmentally responsible product development.
Regional Demand & End-user Opportunity Analysis
Comprehensive analysis of apparel production, clothing consumption, textile manufacturing hubs, consumer spending patterns, and demand trends across women's wear, men's wear, and kids' wear by region and country.
Enables companies to identify high-potential markets, optimize geographic expansion strategies, and target the most attractive end-user segments.
Competitive Landscape & Benchmarking Study
In-depth evaluation of leading fiber manufacturers, market share positioning, product portfolios, sustainability initiatives, capacity expansions, and strategic developments.
Provides actionable competitive intelligence to support market entry, partnership decisions, investment planning, and long-term business strategy.
Frequently Asked Questions About This Report
The global clothing fibers market size was valued at USD 232.6 billion in 2025 and is estimated at USD 242.1 billion for 2026.
Some of the key players operating in the clothing fibers market include Eastman Chemical Company, Teijin Ltd., Toray Industries, Inc., Asahi Kasei Corporation, The Bombay Dyeing and Manufacturing Co. Ltd., Reliance Industries Limited, Indorama Ventures Public Company Limited, Invista, Hyosung TNC Corporation, and Lenzing AG.
Asia Pacific held the highest revenue market share of 45.2% in 2025, driven by its large-scale textile manufacturing base, abundant raw material availability, cost-competitive production, and strong apparel demand from countries such as China, India, Bangladesh, and Vietnam.
The global clothing fibers market is expected to grow at a CAGR of 4.8% from 2026 to 2033, reaching USD 337.2 billion by 2033.
The synthetic segment held the highest revenue market share of 58.8% in 2025, owing to its cost-effectiveness, superior durability, versatility, and extensive use in mass-market apparel, sportswear, activewear, and fast-fashion applications.
The animal based segment is the fastest growing product segment in the clothing fibers market.
The kid’s wear segment is the fastest growing end use in the clothing fibers market.
The women's wear segment accounted for the largest revenue share of 35.8% in 2025, driven by high fashion consumption, frequent product launches, diverse apparel categories, and strong demand for casual, formal, and activewear globally.
The clothing fibers market is primarily driven by rising global apparel consumption, growing demand for sustainable and recycled fibers, expanding fast fashion and athleisure industries, and continuous advancements in high-performance textile materials.
About the Author(s)
Specialty Glass, Ceramic & Fiber Research Team
Advanced Materials · Specialty Glass, Ceramic & FiberThis report was authored by the specialty glass, ceramic & fiber research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the specialty glass, ceramic & fiber segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


