
- Home
- »
- Advanced Interior Materials
- »
-
CO2 Compressor Market Size, Share & Trends Report, 2033GVR Report cover

CO2 Compressor Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product Type (Reciprocating Compressors, Screw Compressor, Centrifugal Compressor), By Application (Refrigeration), By Type, By Power Source, By End-use, By Region, And Segment Forecasts
Market Size, 2025
$2.3BMarket Estimate, 2026
$2.4BMarket Forecast, 2033
$3.5BCAGR, 2026–2033
5.8%CO2 Compressor Market Summary
The global CO2 compressor market size was valued at USD 2.3 billion in 2025 and is projected to grow from USD 2.4 billion in 2026 to USD 3.5 billion by 2033, growing at a CAGR of 5.8% from 2026 to 2033. North America dominated the market, accounting for the largest global share of 36.8% in 2025.The global CO2 compressor market is growing due to several key factors.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product type: Reciprocating compressors segment led the market with the largest share of 40.3% in 2025.
- By application: Refrigeration segment led the market with the largest revenue share of 40.6% in 2025.
- By type: Oil-cooled compressors segment led the market with the largest revenue share of 73.2% in 2025.
- By power source: Electric compressors segment led the market with the largest revenue share of 75.2% in 2025.
- By end-use: Oil & gas segment led the market with the largest revenue share of 29.8% in 2025.
Regional Highlights
- Largest regional market: North America (36.8% revenue share, 2025)
- By country: The U.S. held the largest share of North America in 2025.
Market Size & Forecast
- Market size in 2025: USD 2.3 Billion
- Estimated market size in 2026: USD 2.4 Billion
- Projected market size by 2033: USD 3.5 Billion
- CAGR (2026-2033): 5.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Technological advancements in CO2 compressor systems, increasing demand for energy-efficient refrigeration solutions, and the growing focus on reducing carbon emissions are primary drivers. Industries such as food and beverage, healthcare, and industrial applications are also adopting CO2 compressors for their eco-friendly and efficient cooling capabilities. Furthermore, stringent environmental regulations, along with the shift towards natural refrigerants, contribute to the market’s expansion.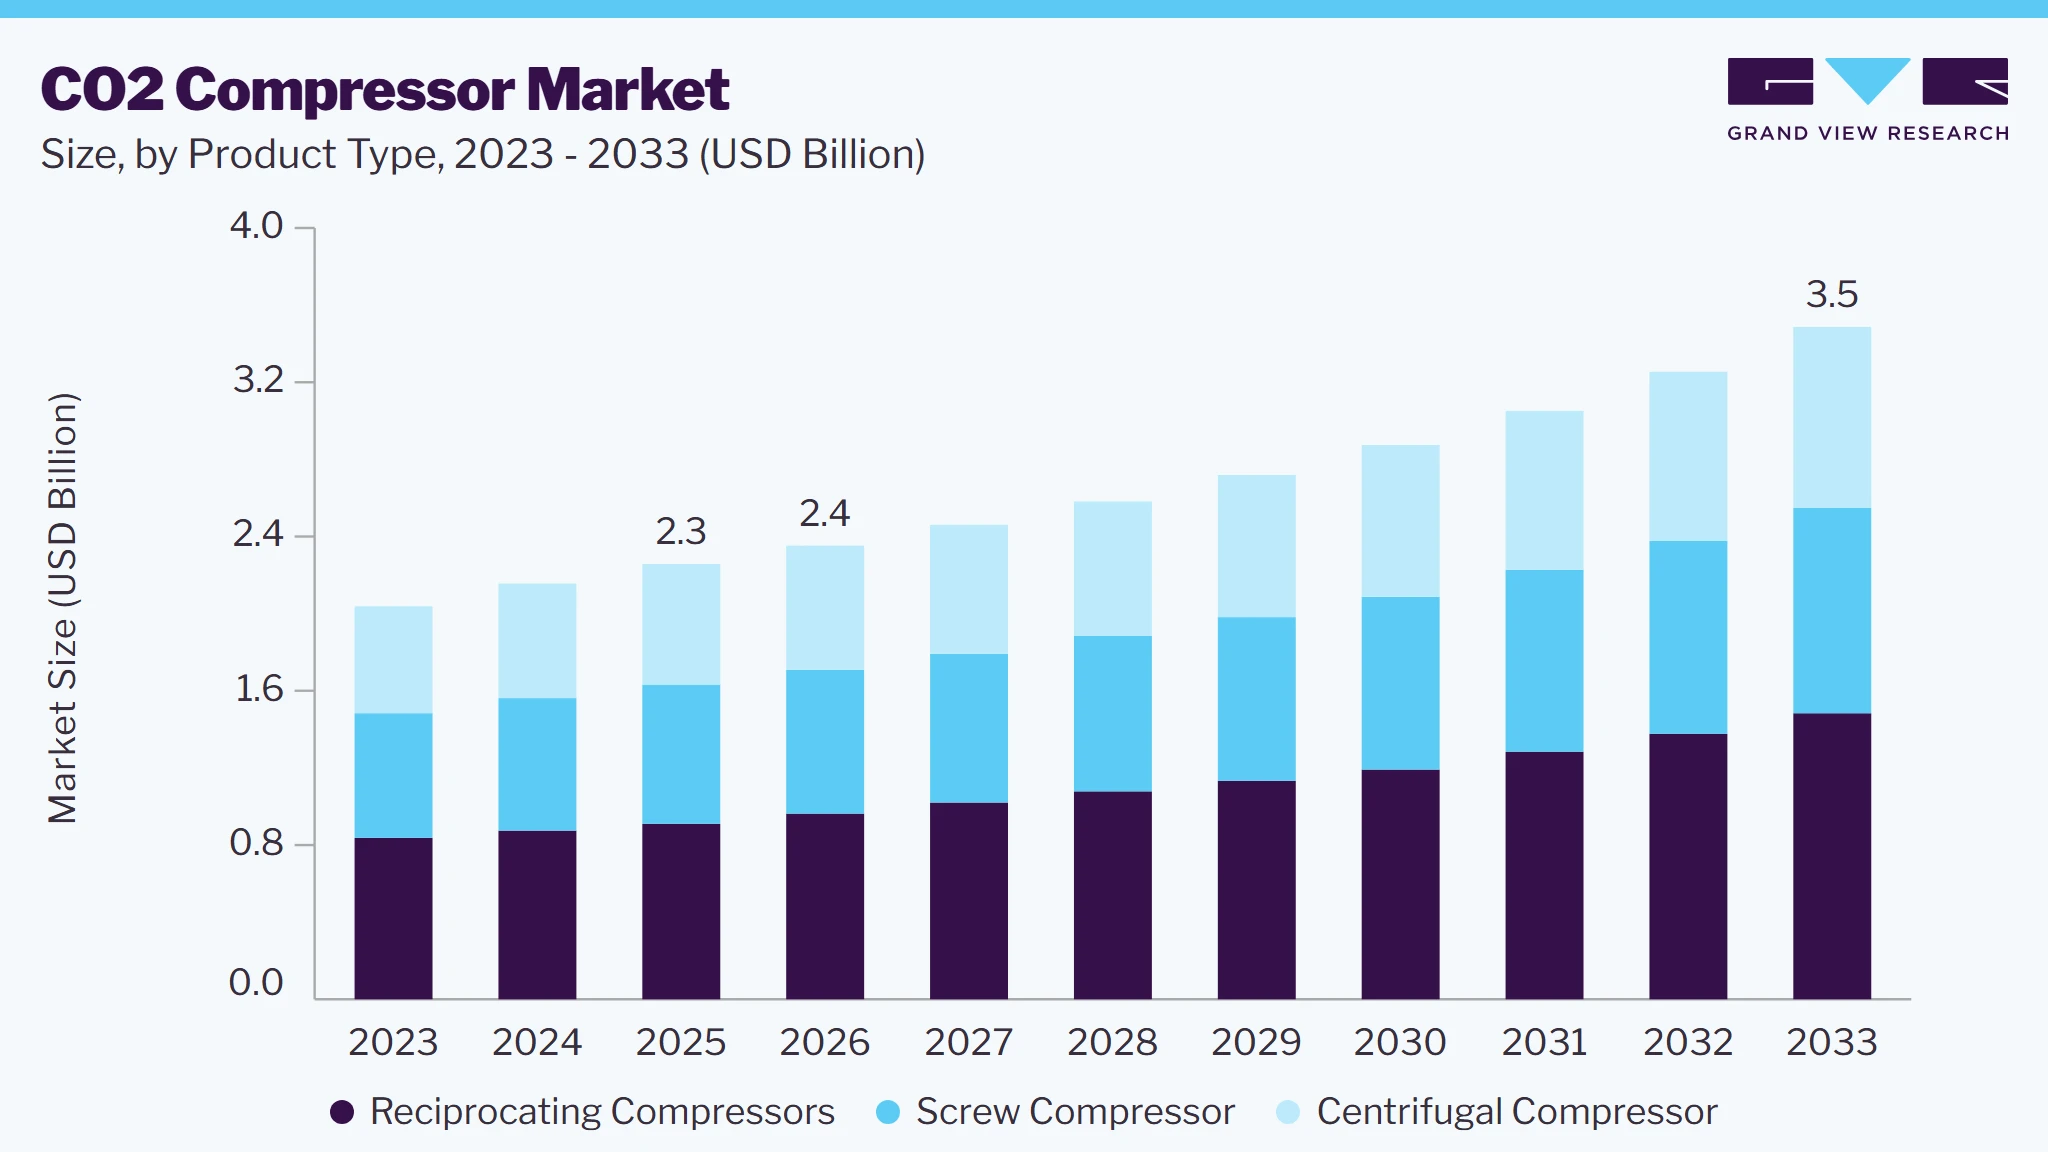 To learn more about this report, Download Free Sample Report
Market Dynamics
The CO2 compressor market is primarily driven by the increasing adoption of natural refrigerants, stringent environmental regulations, and the growing demand for energy-efficient cooling solutions across commercial and industrial applications. Expanding applications in refrigeration, food & beverage processing, healthcare, oil & gas, and industrial systems are contributing to sustained market growth. Technological advancements in compressor design, including improved efficiency, reliability, and integration of smart monitoring capabilities, are shaping competitive dynamics. However, high initial investment costs, operational complexities, and the need for specialized technical expertise continue to influence adoption rates. Market participants are focusing on product innovation, efficiency improvements, and application-specific solutions to strengthen their competitive positioning.
The increasing deployment of carbon capture, utilization, and storage (CCUS) projects across power generation, oil & gas, cement, steel, and other carbon-intensive industries is a major growth driver for the CO2 compressor market. As industries face growing pressure to reduce greenhouse gas emissions and comply with global decarbonization targets, the demand for efficient CO2 compression systems is rising to enable the transportation, storage, and utilization of captured carbon dioxide.
Government funding programs, carbon reduction initiatives, and investments in large-scale carbon management infrastructure are further accelerating the adoption of advanced compression technologies, creating long-term growth opportunities for compressor manufacturers.
The CO2 compressor market is constrained by the high initial investment required for specialized compression equipment designed to handle high-pressure and demanding operating environments. These systems require advanced engineering, corrosion-resistant materials, precision components, and complex sealing technologies, which contribute to higher equipment costs and longer project development timelines.
In addition, energy-intensive operations, maintenance requirements, and the need for skilled personnel for installation and servicing can increase overall lifecycle costs, creating challenges for adoption among smaller industrial users and cost-sensitive markets.
The growing integration of CO2 compression systems with emerging low-carbon technologies presents significant opportunities for market expansion. Increasing investments in green hydrogen, synthetic fuels, carbon utilization, and industrial decarbonization projects are creating new demand for reliable CO2 handling and compression solutions. Furthermore, advancements in energy-efficient compressor designs, digital monitoring systems, and predictive maintenance technologies are enabling manufacturers to improve system performance, reduce operating costs, and develop innovative solutions tailored to evolving sustainability requirements across multiple industries.
Market Concentration & Characteristics
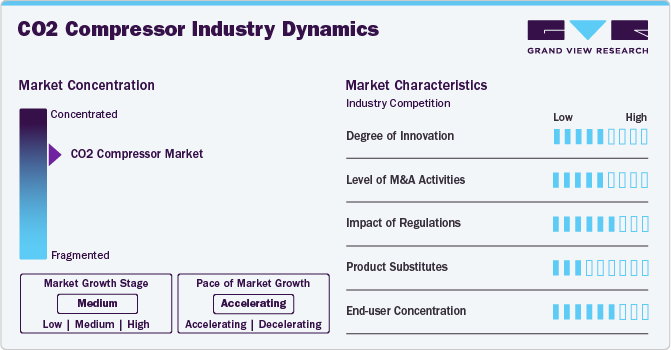
The global CO2 compressor market is moderately fragmented, with a combination of large multinational companies and regional players vying for market share. Key manufacturers focus on developing high-performance, energy-efficient CO2 compressors for a variety of applications, including refrigeration, air conditioning, and industrial processes. Innovation in the market is driven by the growing demand for eco-friendly refrigerants, energy efficiency, and regulatory compliance, leading manufacturers to invest in more sustainable and advanced compressor technologies.
Regulatory pressures from organizations like the EU and EPA are playing a crucial role in shaping the market, with stringent standards focused on emissions reduction, energy efficiency, and the use of natural refrigerants. Compliance with these regulations is essential for manufacturers to remain competitive, as businesses strive to meet sustainability goals and reduce carbon footprints. As the demand for environmentally friendly technologies rises across industries such as food processing, pharmaceuticals, and HVAC, the need for CO2 compressors designed for energy efficiency and low emissions continues to grow.
 To learn more about this report, Download Free Sample Report
While opportunities abound, the CO2 compressor market also faces competition from alternative refrigerant solutions, such as ammonia-based systems and synthetic refrigerants. To maintain market leadership, manufacturers must continue innovating, integrating smart technologies like IoT for real-time monitoring, and adapting to evolving regulatory landscapes. Emphasizing sustainability and energy efficiency will be key in capturing the expanding market for low-emission and high-performance compressor systems.
Analyst Perspective
The CO₂ compressor market is gaining significant momentum as industries accelerate investments in carbon capture, utilization, and storage (CCUS) projects and low-carbon industrial processes. Growing regulatory pressure to reduce greenhouse gas emissions, coupled with increasing deployment of carbon capture systems across power generation, cement, chemicals, and oil & gas industries, is driving demand for high-pressure, reliable CO₂ compression solutions. In addition, expanding applications of CO₂ in refrigeration, food & beverage processing, hydrogen production, and enhanced oil recovery are creating new growth opportunities for compressor manufacturers. Technological advancements focused on improving compression efficiency, reducing energy consumption, and enabling operation under high-pressure conditions are further strengthening market adoption. As global decarbonization initiatives continue to advance, manufacturers offering energy-efficient, high-performance, and application-specific CO₂ compressor solutions are expected to benefit from sustained long-term market growth.
Product Type Insights
Based on product type, the reciprocating compressors segment led the market with the largest revenue share of 40.3% in 2025, driven by the demand for high-pressure performance and reliability. They are popular for their cost-effectiveness and ability to handle fluctuating loads, making them ideal for smaller industrial applications, including HVAC systems, refrigeration, and certain petrochemical processes. Their robust design allows them to operate efficiently in extreme conditions, contributing to their demand in sectors that prioritize performance under varying loads and operational conditions.
Centrifugal compressors are gaining popularity in applications that require high flow rates and consistent pressure, such as large-scale industrial and commercial systems. Their ability to efficiently compress gases at higher capacities and with lower energy consumption makes them ideal for sectors like petrochemicals, refrigeration, and air conditioning.
End Use Insights
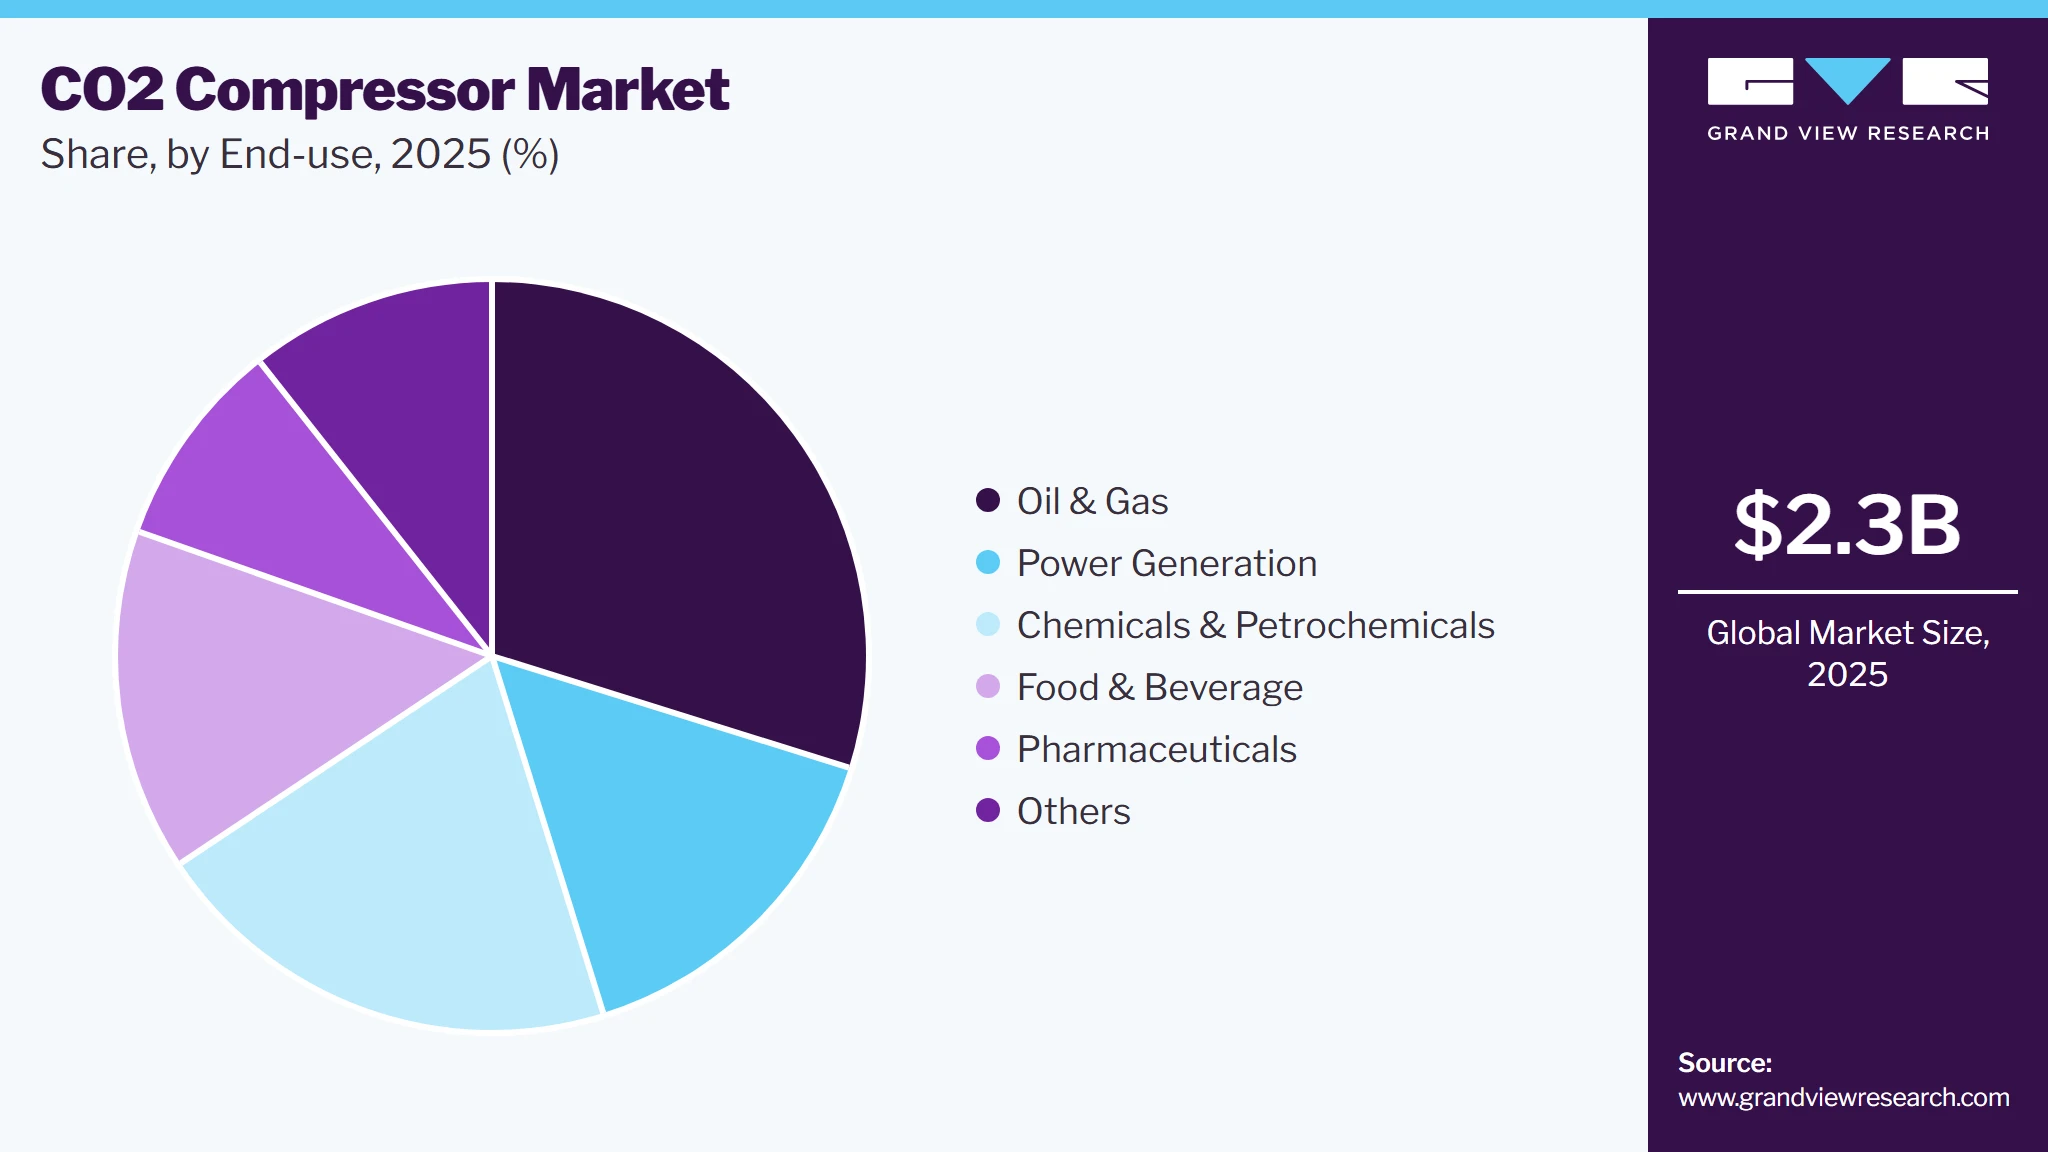
Based on end-use, the oil & gas segment led the market with the largest revenue share of 29.8% in 2025. In the oil and gas industry, CO2 compressors are integral to enhancing oil recovery, transporting CO2 for injection into reservoirs, and ensuring proper pressure maintenance in pipelines. The demand for CO2 as a secondary recovery method for increasing oil production is expanding, driving the need for high-efficiency compressors. As the industry focuses on improving recovery rates and reducing carbon footprints, CO2 compressors are becoming crucial for these applications, boosting market growth.
 To learn more about this report, Download Free Sample Report
In the food and beverage industry, CO2 compressors are crucial for processes such as carbonation, packaging, and refrigeration. The increasing demand for high-quality, fresh products with longer shelf lives is driving the need for efficient CO2 systems. CO2 compressors are widely used for controlling the temperature in food storage and distribution, as well as in carbonation for soft drinks and beer.
Application Insights
Based on application, the refrigeration segment led the market with the largest revenue share of 40.6% in 2025. As refrigeration systems shift toward more sustainable and energy-efficient solutions, the demand for CO2 as a natural refrigerant is increasing. The ability of CO2 compressors to handle these requirements while minimizing environmental impact makes them highly sought after in sectors such as food processing, retail, and pharmaceuticals, where temperature control is critical.
The increasing demand for carbonated beverages is driving the adoption of efficient CO2 compression systems. These compressors provide the necessary pressure for dissolving CO2 gas into liquids, ensuring consistent carbonation levels and product quality. As the beverage industry continues to focus on energy efficiency and sustainability, CO2 compressors are also being used to minimize energy consumption while maintaining high-performance standards, contributing to cost savings and improved environmental impact in the carbonating process.
Type Insights
Based on type, the oil-cooled compressors segment led the market with the largest revenue share of 73.2% in 2025. Oil-cooled compressors are favored in applications requiring consistent cooling performance, especially in industrial environments. The oil helps lubricate and cool the compressor, increasing its lifespan and reducing wear and tear. This makes them ideal for high-load industrial processes, such as refrigeration in large commercial systems and industrial gas compression, where reliability and prolonged operation are crucial to ensuring system uptime.
Water-cooled compressors are increasingly used in industries that require efficient heat exchange and cooling performance, especially in large-scale applications. The cooling water absorbed from the environment helps dissipate the heat generated during compression, improving energy efficiency. These compressors are commonly used in sectors such as manufacturing and commercial refrigeration, where high cooling capacity and stable performance are essential.
Power Source Insights
Based on power source, the electric compressors segment led the market with the largest revenue share of 75.2% in 2025. Electric compressors are increasingly preferred across various industries for their efficiency, lower maintenance costs, and environmental benefits. Unlike gas-powered compressors, electric compressors rely on a stable electrical supply, making them ideal for settings where continuous operation and high performance are required. They are commonly used in applications such as refrigeration, HVAC systems, and industrial processes, where precise control and consistent power are necessary.
Gas-powered compressors are a popular choice in industries where mobility and flexibility are required, such as in remote locations or outdoor settings. They offer the advantage of being able to operate independently of the electrical grid, making them ideal for construction, mining, and offshore operations. Their ability to deliver reliable power without the need for external power sources is a key driver of their adoption in sectors where operational flexibility is crucial.
Regional Insights
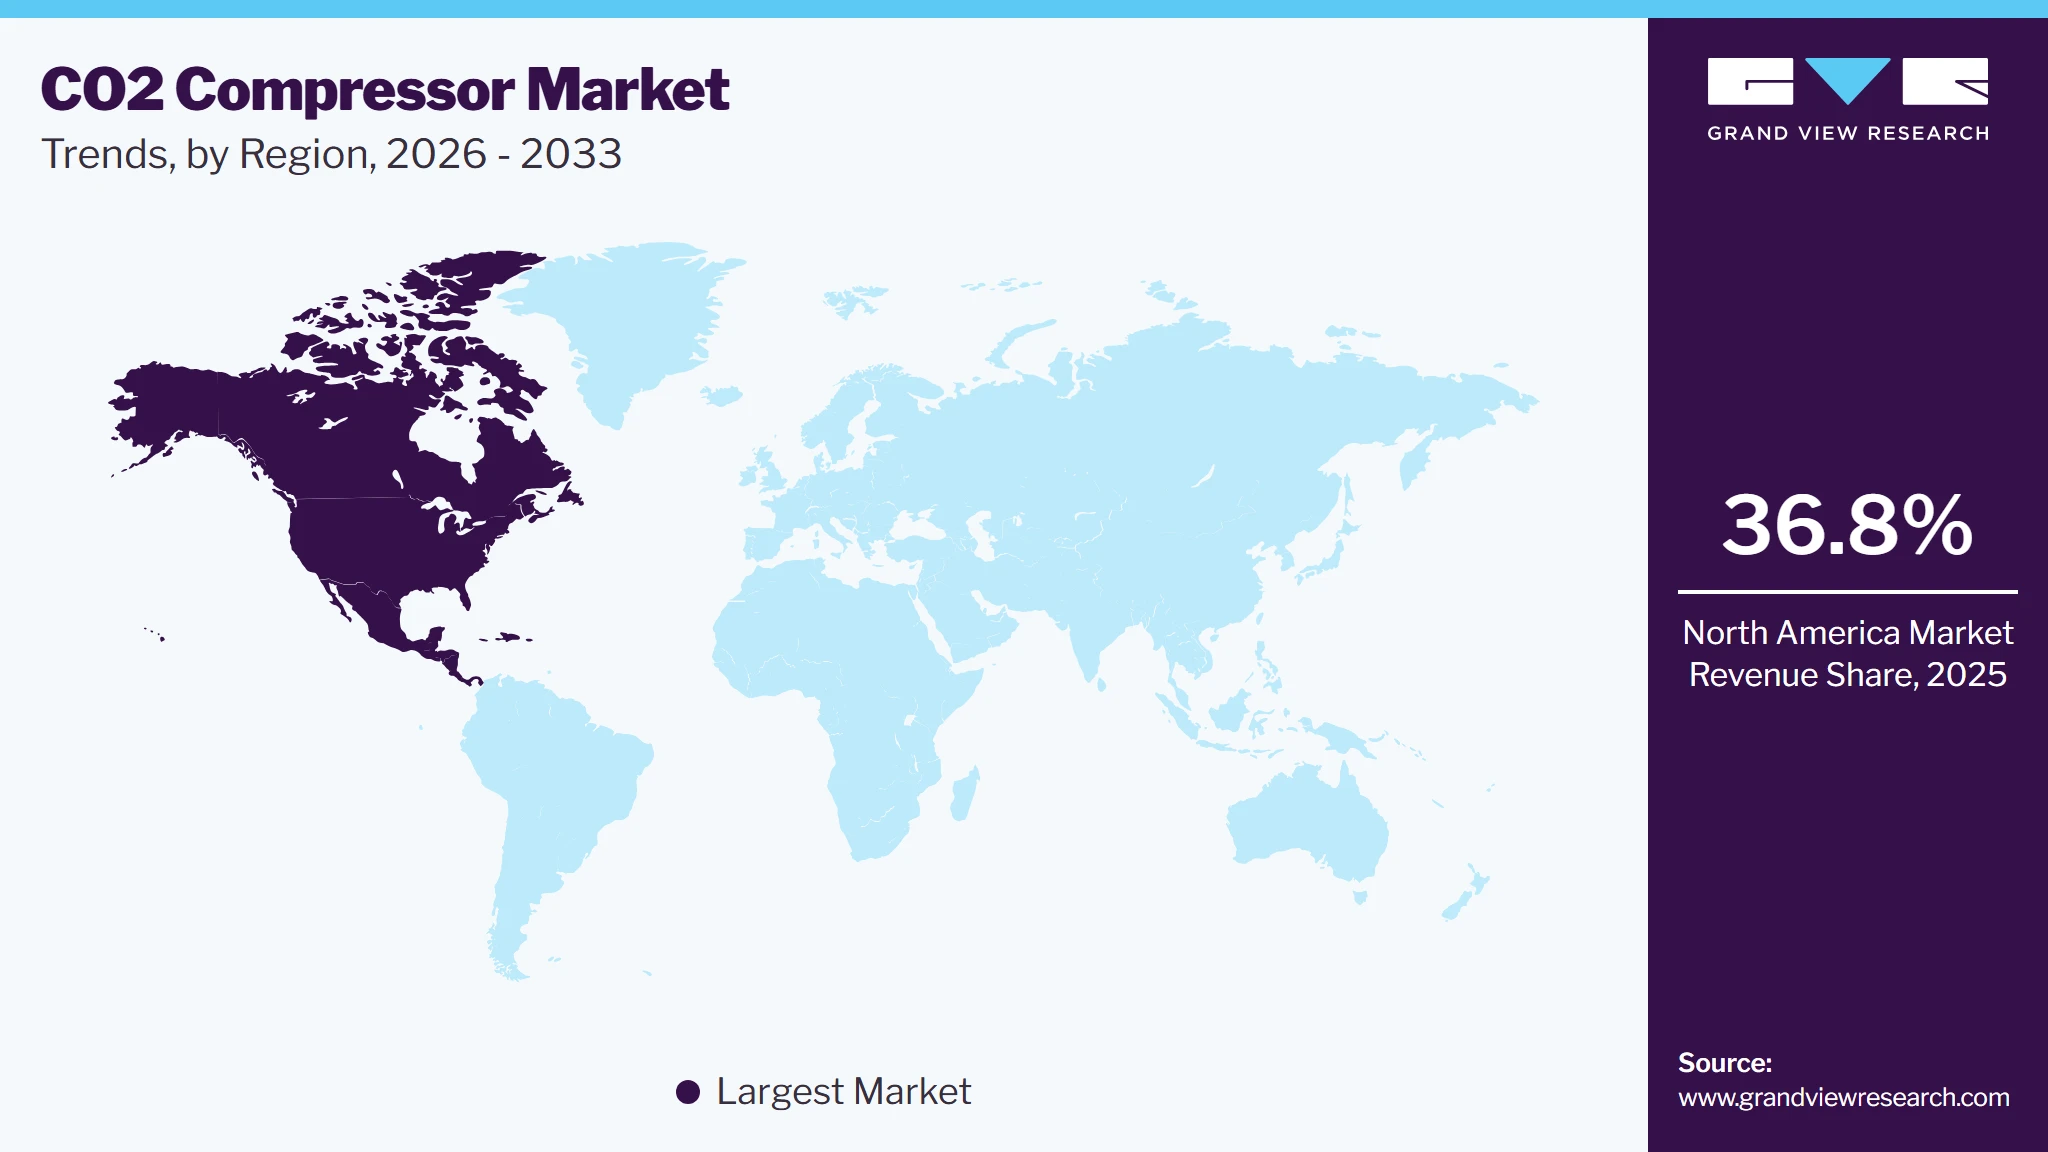
North America dominated the CO2 compressor market with the largest revenue share of 36.8% in 2025. The North America CO2 compressor industry is benefiting from strict environmental regulations, a shift towards sustainable refrigerants, and increasing demand from sectors like food processing and pharmaceuticals. These industries require more efficient and eco-friendly cooling systems, pushing the demand for CO2 compressors.
 To learn more about this report, Download Free Sample Report
U.S. CO2 Compressor Market Trends
The CO2 compressor market in U.S. held the largest share in the North America region in 2025. In the U.S., stringent environmental regulations and the increasing adoption of natural refrigerants in HVAC systems are major drivers for the CO2 compressor market, particularly in industries focusing on sustainability and energy efficiency.
Europe CO2 Compressor Market Trends
Europe CO2 compressor industry growth is driven by a strong emphasis on environmental sustainability, the European Union’s regulations on refrigerants, and the rising adoption of CO2-based refrigeration systems, especially in supermarkets and retail. These factors are propelling demand for more energy-efficient, eco-friendly solutions.
The CO2 compressor industry in Spain is projected to expand at a CAGR of 6.4% over the forecast period In Spain, the market is driven by the country’s increasing focus on sustainable refrigeration and HVAC solutions, especially within the food and beverage industry. Spain’s commitment to meeting European environmental standards and reducing carbon emissions boosts the demand for eco-friendly compressor technologies across commercial and industrial sectors.
Italy CO2 compressor industry is projected to expand at a CAGR of 7.8% over the forecast period due to the country’s emphasis on green technologies and energy-efficient solutions, particularly in refrigeration for food processing and storage. Italy’s strict environmental regulations and its push for reducing carbon footprints across industries make CO2 compressors an essential part of their sustainable approach to cooling systems.
Asia Pacific CO2 Compressor Market Trends
In Asia Pacific CO2 compressor industry, rapid industrialization, increasing investment in HVAC systems, and growing awareness of the need for eco-friendly refrigeration are key drivers of market growth. The region’s focus on sustainability in industrial operations and commercial sectors further boosts CO2 compressor demand.
The CO2 compressor industry in China is expected to grow at a CAGR of 6.9% over the forecast period. China’s market is experiencing significant growth due to rapid industrial expansion, increased demand for cooling in various industries, and a rising focus on environmental protection. The country is increasingly adopting sustainable refrigerant technologies to meet these needs.
India CO2 compressor industry is expected to grow at a CAGR of 7.1% over the forecast period. India is seeing increased demand for CO2 compressors as industrial applications expand and the need for energy-efficient refrigeration solutions grows. Government incentives and rising industrialization play a significant role in the market’s development.
Latin America CO2 Compressor Market Trends
The growth in CO2 compressor industry in Latin America is propelled by the expanding food and beverage sector, which drives the need for efficient refrigeration solutions. Additionally, increasing environmental regulations in the region are encouraging the adoption of more sustainable cooling technologies.
Brazil CO2 compressor industry is projected to grow at a CAGR of 5.2% over the forecast period. In Brazil, the demand for sustainable refrigeration, particularly in the food industry, is a primary driver of market growth. Additionally, government support for environmentally friendly technologies helps fuel the adoption of CO2 compressors.
Middle East & Africa CO2 Compressor Market Trends
The CO2 compressor industry in the Middle East and Africa are experiencing growth due to rising demand for cooling systems across both industrial and residential sectors. Government initiatives aimed at promoting energy-efficient solutions further stimulate the adoption of CO2 compressors in these regions.
Saudi Arabia CO2 compressor industry is projected to expand at a CAGR of 5.1% over the forecast period. Saudi Arabia’s CO2 compressor market is growing rapidly due to the country’s hot climate, which drives demand for cooling systems in various sectors. Furthermore, government initiatives promoting energy-efficient technologies are encouraging the adoption of CO2 compressors in the region.
Key CO2 Compressor Company Insights
Some key players operating in the market include Atlas Copco AB. and Siemens AG among others.
-
Atlas Copco operates through four primary business areas: Compressor Technique, Vacuum Technique, Industrial Technique, and Power Technique. This structure allows the company to deliver specialized products and services across diverse industries such as manufacturing, construction, pharmaceuticals, automotive, and electronics.
-
Siemens AG is a global technology company thatconcentrates on intelligent infrastructure for buildings and decentralized energy systems, as well as automation and digitalization in the process and manufacturing industries. The company is one of the largest industrial manufacturing entity in Europe and holds a prominent position in industrial automation and software
Key CO2 Compressor Companies
The following key companies have been profiled for this study on the CO2 compressor market.
-
Wärtsilä
-
Atlas Copco AB
-
Siemens AG
-
Mitsubishi Heavy Industries, Ltd.
-
danfoss
-
Copeland LP
-
Dorin S.p.A.
-
HAUG Sauer Kompressoren AG
-
bei Mehrer Compression GmbH
-
SANDEN CORPORATION.
-
Panasonic Corporation
-
Pentair
-
Haier Carrier
-
Bengbu AOT Compressor Co., Ltd.
-
Sollant Group
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Atlas Copco AB; Danfoss; Copeland LP; Mitsubishi Heavy Industries, Ltd.; Panasonic Corporation; SANDEN CORPORATION)
- Focus on global market expansion through broad product portfolios, strategic partnerships, and technology-driven compressor solutions.
- Invest in energy-efficient CO2 compression technologies, including transcritical refrigeration and industrial CO2 applications.
- Leverage strong distribution networks and established customer relationships across industrial and commercial sectors.
- Concentrate on specialized CO2 compressor solutions targeting niche applications and regional industrial requirements.
- Compete through application-specific engineering, customization, and close customer engagement.
- Expand market presence through partnerships, regional distribution channels, and focused product development.
- Higher product costs due to advanced technologies and established operational structures.
- Complex organizational structures may slow customization and response times compared with smaller competitors.
- Greater exposure to mature markets, increasing pressure to maintain growth through innovation.
Emerging & Regional Players (e.g., Dorin S.p.A.; HAUG Sauer Kompressoren AG; Mehrer Compression GmbH; Mayekawa Mfg. Co., Ltd.)
- Concentrate on specialized CO2 compressor solutions targeting niche applications and regional industrial requirements.
- Compete through application-specific engineering, customization, and close customer engagement.
- Expand market presence through partnerships, regional distribution channels, and focused product development.
- Limited global distribution networks compared with multinational competitors.
- Lower economies of scale may result in higher production costs and pricing challenges.
- Limited resources for large-scale R&D investments and global market expansion.
Recent Developments
-
In October 2025, Dorin S.p.A. announced the upcoming launch of its CD1000 range, the "largest" transcritical CO2 compressor, expected in the second half of 2025. This 8-cylinder compressor, driven by 500 to 750HP electric motors, aims to meet the demand for megawatt capacities in industrial heat systems.
-
In July 2024, Danfoss introduced new compressor ranges, one of which is the BOCK HGX56 CO2 T for large industrial heat pumps. The BOCK HGX56 CO2 T is a 6-cylinder semi-hermetic compressor that can achieve water temperatures up to 90°C and provides an efficient alternative to ammonia and synthetic refrigerants, simplifying system design and reducing costs.
CO2 Compressor Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 2.3 billion
Market size value in 2026
USD 2.4 billion
Revenue forecast in 2033
USD 3.5 billion
Growth rate
CAGR of 5.8% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product type, end-use, application, power source, type, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Japan; China; India; Australia; South Korea; Brazil; Argentina; Saudi Arabia; South Africa; UAE
Key companies profiled
Atlas Copco AB; Danfoss; Copeland LP; Dorin S.p.A.; HAUG Sauer Kompressoren AG; Mehrer Compression GmbH; Mitsubishi Heavy Industries, Ltd.; SANDEN CORPORATION; Panasonic Corporation; Mayekawa Mfg. Co., Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global CO2 Compressor Market Report Segmentation
This report forecasts revenue growth at global, regional & country levels and provides an analysis of the industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global CO2 compressor market report based on product type, end use, application, power source, type, and region:
-
Product Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Reciprocating Compressors
-
Screw Compressor
-
Centrifugal Compressor
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Oil & Gas
-
Power Generation
-
Chemicals & Petrochemicals
-
Food & Beverage
-
Pharmaceuticals
-
Others
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Refrigeration
-
Air Conditioning
-
Carbonating
-
Carbon Capture Application
-
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Oil-Cooled Compressors
-
Water-Cooled Compressors
-
-
Power Source (Revenue, USD Million, 2021 - 2033)
-
Electric Compressors
-
Gas-Powered Compressors
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
France
-
Germany
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
-
Research Methodology
The CO2 compressor market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each CO2 compressor segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product Type
Revenue Capture Definition
Reciprocating Compressors
Revenue generated from the sale of CO2 reciprocating compressor systems used in high-pressure applications across refrigeration, carbon capture, oil & gas, and industrial sectors. Excludes installation, maintenance, and aftermarket services.
Screw Compressors
Revenue generated from the sale of CO2 screw compressor systems used in refrigeration, HVAC, food processing, and industrial cooling applications. Excludes installation, maintenance, and aftermarket services.
Centrifugal Compressors
Revenue generated from the sale of CO2 centrifugal compressor systems used in large-scale industrial, power generation, chemical, and carbon capture applications. Excludes installation, maintenance, and aftermarket services.
Segment - End Use
Revenue Capture Definition
Oil & Gas
Revenue generated from the sale of CO2 compressor systems for CO2 injection, enhanced oil recovery, gas processing, and pipeline compression applications. Excludes installation and service revenues.
Power Generation
Revenue generated from the sale of CO2 compressor systems for carbon capture, CO2 handling, and advanced power generation applications. Excludes installation and maintenance services.
Chemicals & Petrochemicals
Revenue generated from the sale of CO2 compressor systems for process compression, carbon utilization, and industrial gas handling applications. Excludes installation and aftermarket services.
Food & Beverage
Revenue generated from the sale of CO2 compressor systems for carbonation, refrigeration, and food processing applications. Excludes installation and maintenance services.
Pharmaceuticals
Revenue generated from the sale of CO2 compressor systems for specialized cooling, processing, and pharmaceutical production applications. Excludes installation and service revenues.
Others
Revenue generated from the sale of CO2 compressor systems across manufacturing, research, wastewater, and other industrial applications. Excludes installation and maintenance services.
Segment - Application
Revenue Capture Definition
Refrigeration
Revenue generated from the sale of CO2 compressor systems used in commercial, industrial, and cold storage refrigeration applications. Excludes installation and aftermarket services.
Air Conditioning
Revenue generated from the sale of CO2 compressor systems used in commercial and industrial HVAC applications. Excludes installation and maintenance services.
Carbonating
Revenue generated from the sale of CO2 compressor systems used in beverage carbonation and food processing applications. Excludes installation and service revenues.
Carbon Capture Application
Revenue generated from the sale of CO2 compressor systems used in CCUS projects for CO2 compression, transport, and storage preparation. Excludes installation and operational services.
Segment - Type
Revenue Capture Definition
Oil-Cooled Compressors
Revenue generated from the sale of CO2 oil-cooled compressor systems used for industrial and commercial compression applications. Excludes installation and maintenance services.
Water-Cooled Compressors
Revenue generated from the sale of CO2 water-cooled compressor systems used in high-capacity and continuous operation applications. Excludes installation and aftermarket services.
Segment - Power Source
Revenue Capture Definition
Electric Compressors
Revenue generated from the sale of CO2 electric compressor systems used in refrigeration, HVAC, industrial, and carbon capture applications. Excludes installation and maintenance services.
Gas-Powered Compressors
Revenue generated from the sale of CO2 gas-powered compressor systems used in large-scale industrial and remote applications. Excludes installation and aftermarket services.
Estimation Model
Layer Name
Key Question
Description
CO2 Compressor Demand Base Layer
Where are CO₂ compressors required?
Analyze demand across carbon capture, utilization & storage (CCUS), oil & gas, food & beverage, chemical processing, refrigeration, power generation, hydrogen production, and other industrial sectors.
Industrial Infrastructure & Decarbonization Investment Layer
Where is new equipment demand being created?
Evaluate investments in carbon capture projects, CO₂ transportation infrastructure, enhanced oil recovery (EOR), industrial gas processing facilities, food & beverage manufacturing, and refrigeration systems.
Technology Adoption Layer
Which CO₂ compressor technologies are being deployed?
Estimate CO2 compressor penetration by compressor type, application, end-use industry, and geography. Account for adoption of reciprocating, screw, and centrifugal compressors along with alternative compression technologies and system configurations.
Revenue Generation Layer
How is market revenue generated ?
Estimate annual shipments of CO₂ compressors by compressor type, pressure range, application, end-use industry, and region. Quantify revenues generated exclusively from the sale of new CO₂ compressors supplied to industrial facilities, EPC contractors, OEMs, and carbon capture project developers.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Benchmarking
Benchmarked leading CO2 compressor manufacturers based on product portfolio strength, compressor technology capabilities, application coverage, geographic presence, customer base, and strategic positioning, while differentiating established players from emerging and regional competitors.
Provided a comprehensive view of the competitive landscape, enabling assessment of market positioning, technology differentiation, competitive intensity, and potential partnership or expansion opportunities.
Regional Segmentation
Refined regional analysis by evaluating CO2 compressor demand across North America, Europe, Asia Pacific, Latin America, and Middle East & Africa based on refrigeration adoption, industrial activities, carbon capture investments, regulatory initiatives, and infrastructure development.
Identified high-growth regions, application-driven demand centers, and market expansion opportunities to support regional prioritization and investment planning.
Opportunity Assessment
Evaluated growth opportunities across key CO2 compressor applications, including transcritical refrigeration, industrial CO2 compression, carbon capture and storage (CCUS), heat pump systems, and emerging low-carbon technologies.
Highlighted high-potential market segments, evolving application trends, and strategic growth areas to support long-term business planning and revenue expansion.
Frequently Asked Questions About This Report
Asia Pacific is anticipated to be one of the fastest-growing regional markets over the forecast period, driven by expanding industrial infrastructure, increasing investments in CCUS projects, growing adoption of natural refrigerants, and rising demand from the chemical and energy sectors.
The reciprocating compressors segment led the market with the largest revenue share of 40.3% in 2025.
The refrigeration segment accounted for the largest revenue share of 40.6% in 2025.
The oil & gas segment led the market with the largest revenue share of 29.8% in 2025.
North America dominated the CO₂ compressor market with the largest revenue share of 36.8% in 2025.
Key factors driving the CO2 compressor market include increasing environmental regulations pushing for natural refrigerants and the growing demand for energy-efficient, sustainable solutions across various industries like refrigeration, HVAC, and food processing. Technological advancements in compressor efficiency and integration with smart systems further boost market growth
The global CO₂ compressor market size was estimated at USD 2.3 billion in 2025 and is expected to be USD 2.4 billion in 2026.
The global CO₂ compressor market, in terms of revenue, is expected to grow at a compound annual growth rate of 5.8% from 2026 to 2033 to reach USD 3.5 billion by 2033.
Some of the key players operating in the CO2 Compressor Market are Atlas Copco AB, Siemens AG, Mitsubishi Heavy Industries, Ltd., Danfoss, Copeland LP, Dorin S.p.A., HAUG Sauer Kompressoren AG, Mehrer Compression GmbH, SANDEN CORPORATION, Panasonic Corporation, Pentair, Haier Carrier, Bengbu AOT Compressor Co., Ltd., and Sollant Group
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


