
- Home
- »
- Next Generation Technologies
- »
-
Connected Agriculture Market Size & Share Report, 2033GVR Report cover

Connected Agriculture Market (2026 - 2033)
Size, Share & Trends Analysis Report By Component (Solution, Services), By Deployment (Cloud, On-premises), By Application (Livestock Monitoring, Precision Farming, Supply Chain Management), By Region, And Segment Forecasts
Market Size, 2025
$6.6BMarket Estimate, 2026
$7.6BMarket Forecast, 2033
$22.7BCAGR, 2026–2033
16.9%Connected Agriculture Market Size & Trends
The global connected agriculture market size was valued at USD 6.6 billion in 2025 and is projected to grow from USD 7.6 billion in 2026 to USD 22.7 billion by 2033, at a CAGR of 16.9% from 2026 to 2033. The market in North America dominated with a revenue share of 37.3% in 2025. This growth is driven by increasing adoption of precision agriculture practices.
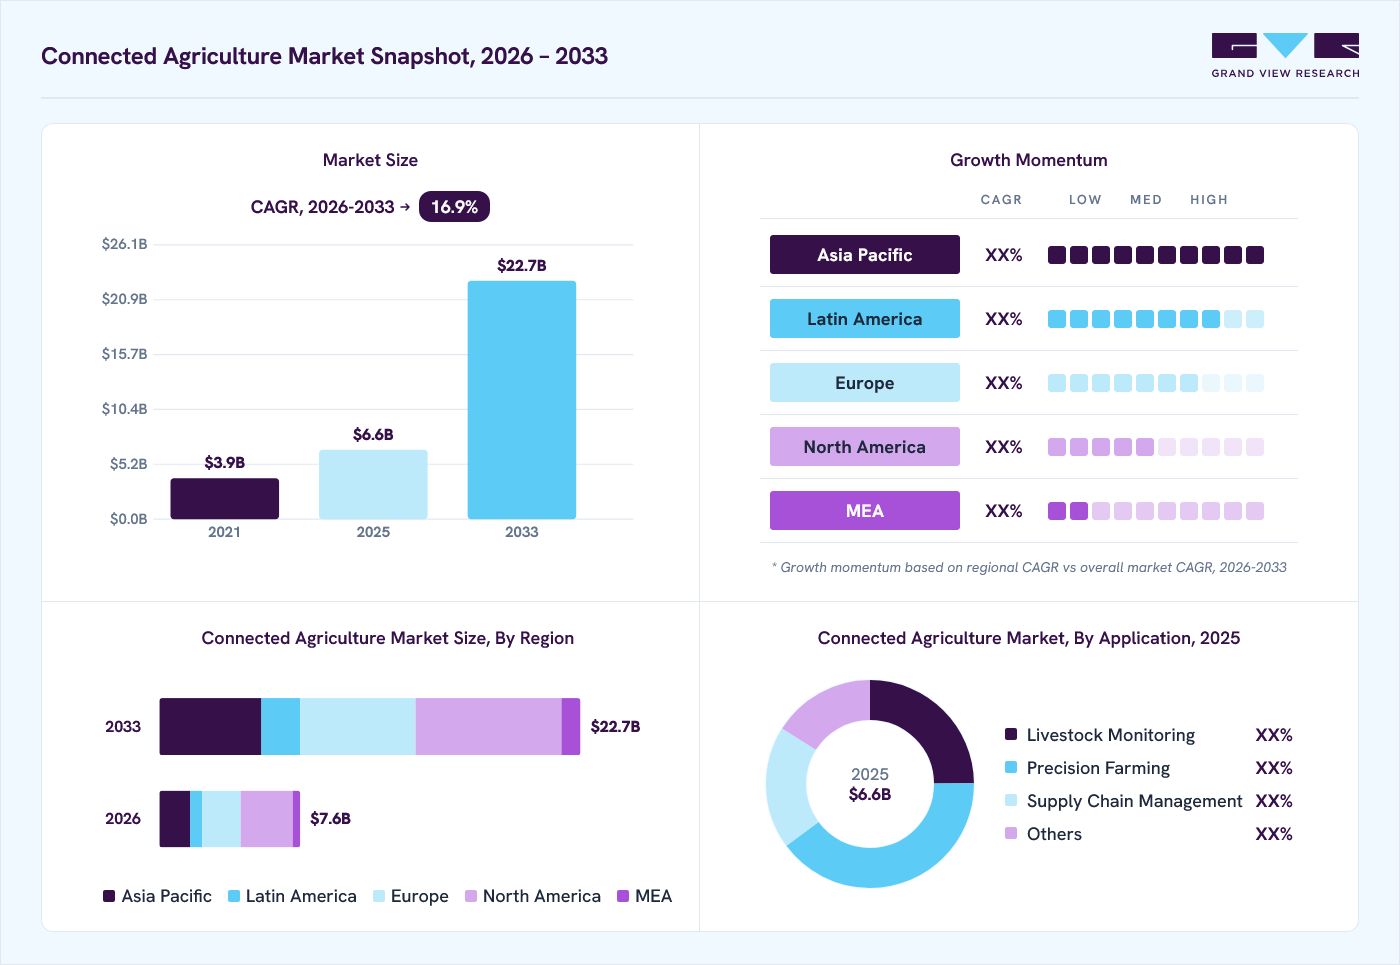 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By component: Solution segment held the largest market share of 74.1% in 2025.
- By deployment: Cloud segment held the largest market share of 70.6% in 2025.
- By application: Precision farming segment held the largest market share of 40.0% in 2025.
Regional Highlights
- Largest regional market: North America (37.3% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 6.6 Billion
- Estimated market size in 2026: USD 7.6 Billion
- Projected market size by 2033: USD 22.7 Billion
- CAGR (2026-2033): 16.9%
Prism AI by Grand View Research Free to tryAsk a question about the connected agriculture marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
The global market is experiencing robust growth due to factors such as increasing food demand, technological advancements, government support, the need for climate resilience, and a strong focus on sustainability. Connected agriculture refers to the integration of digital and communication technologies, such as the Internet of Things (IoT), big data, mobile devices, and cloud computing, into agricultural practices. Connected Agriculture offers numerous benefits, such as enhanced efficiency, resource optimization, and improved traceability and food safety. Automating and optimizing farming practices reduces the need for manual labor, lowers costs, and increases output. Moreover, connected agriculture systems enable detailed tracking of food products from farm to table, improving traceability and ensuring food safety. They also ensure the efficient use of resources like water, fertilizers, and energy, reducing environmental impact.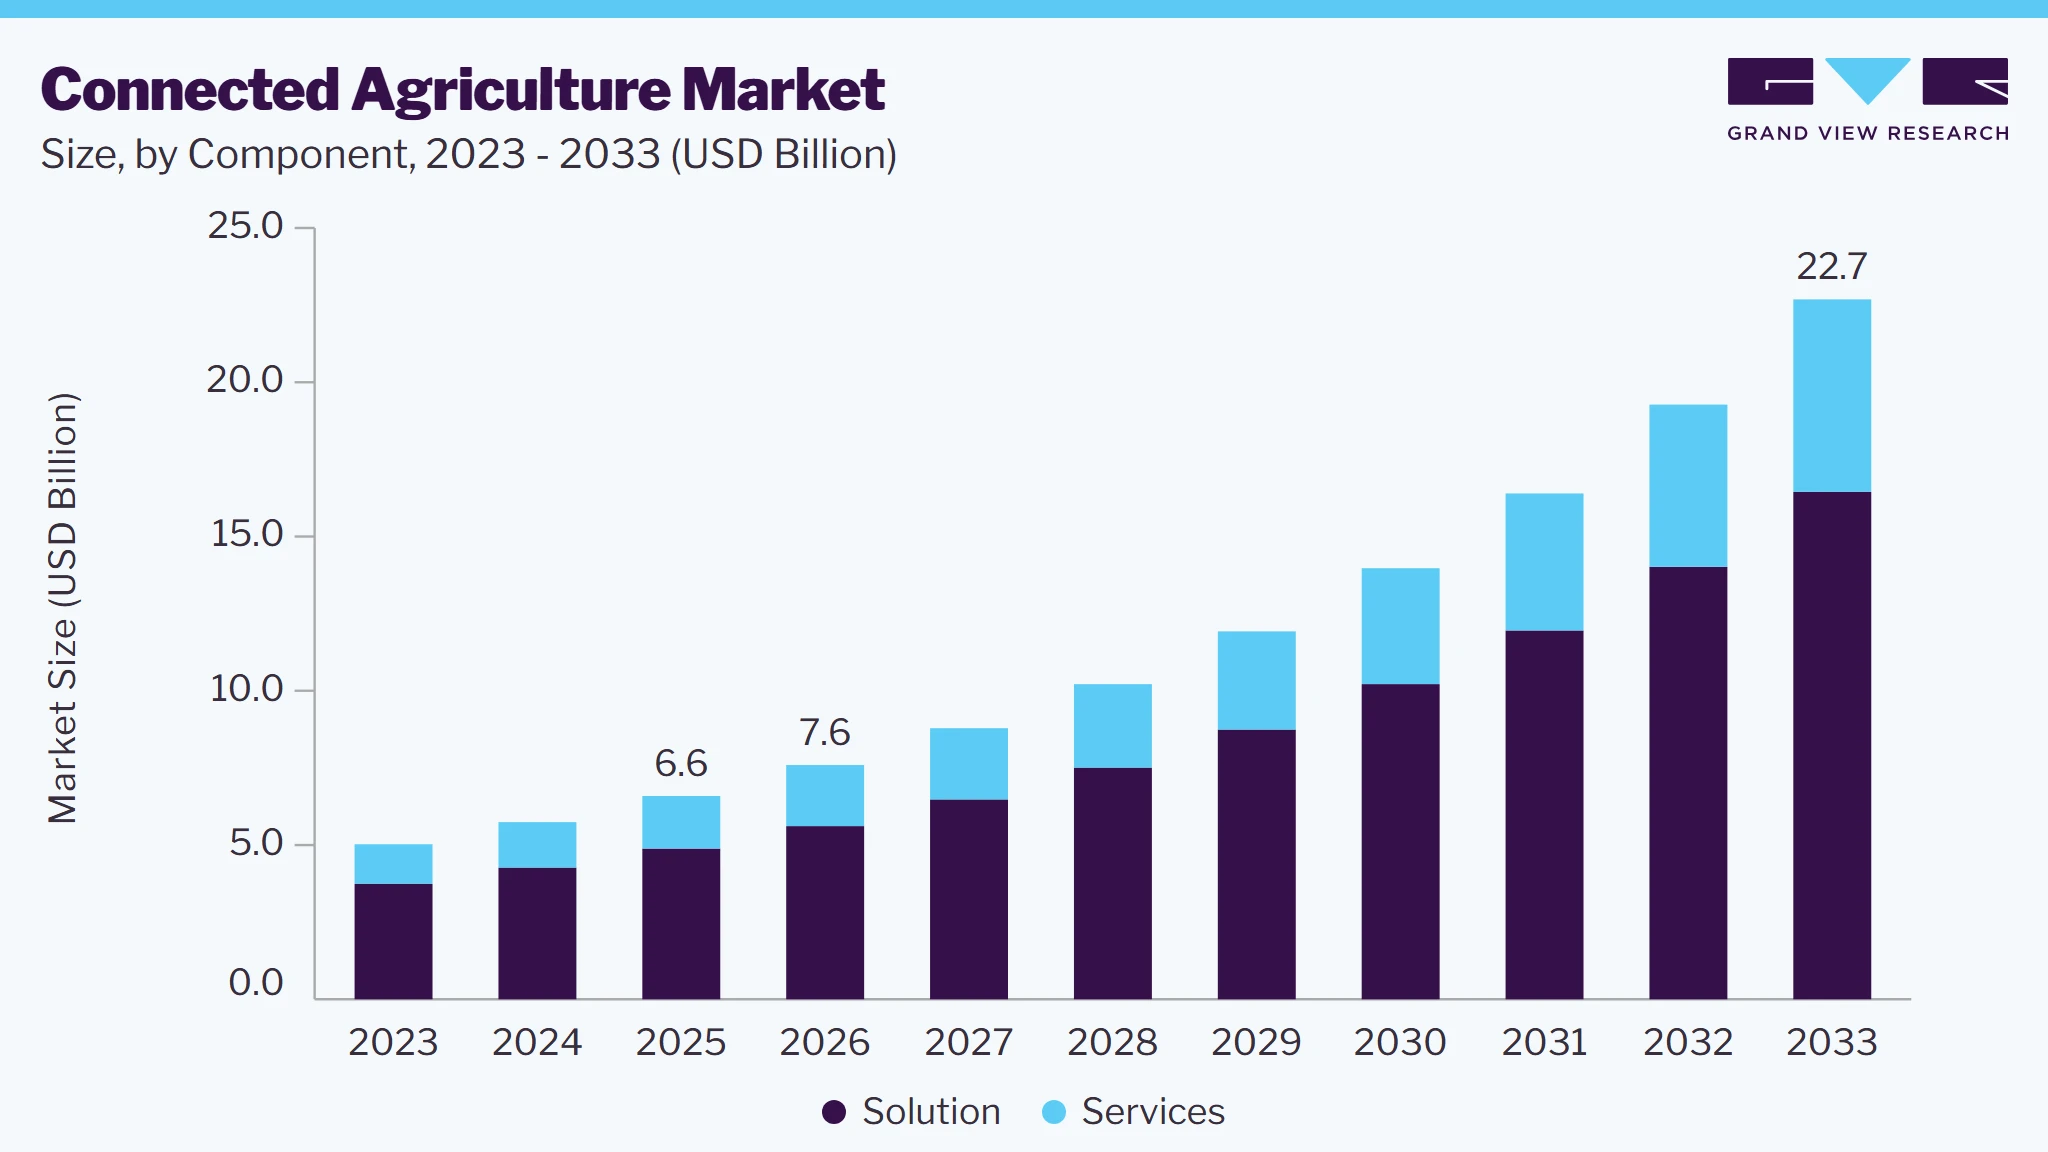 To learn more about this report, Download Free Sample Report
The proliferation of mobile devices and improved internet connectivity in rural areas are making it easier for farmers to access connected agriculture solutions, including mobile apps for farm management, weather forecasts, and market prices. Mobile platforms are facilitating better communication between farmers, suppliers, and buyers, enhancing market access and price transparency.
Machine Learning (ML) and Artificial Intelligence (AI) are being increasingly utilized for predictive analytics in agriculture. These technologies analyze vast amounts of data from various sources to predict outcomes like yield, pest outbreaks, and optimal planting times. This enables farmers to make more informed decisions, optimize inputs, and reduce waste. Sophisticated IoT sensors across fields and farms allow for real-time monitoring of soil moisture, nutrient levels, weather conditions, and crop health. These sensors provide critical data that helps in the precise application of fertilizers, water, and pesticides, improving efficiency and reducing environmental impact.
Companies are continually innovating and launching advanced solutions for agricultural applications, positively impacting the growth of the connected agriculture market. For instance, in July 2024, Taranis launched Ag Assistant, an AI-driven tool that transforms crop management by integrating diverse data sources-including text, images, and audio-to provide precise, actionable insights for agriculture professionals. This innovative model enhances decision-making efficiency and accuracy, allowing growers and advisors to address field-specific issues with unprecedented speed and effectiveness, revolutionizing farm management in the AI era.
Market Dynamics
The connected agriculture market is expanding as farms and agribusinesses increasingly connect equipment, sensors, irrigation systems, livestock monitoring devices, and farm management platforms to create more coordinated and data-driven agricultural operations. Connected technologies enable real-time monitoring of field conditions, machinery performance, crop health, weather patterns, and livestock activity, allowing farmers to respond more quickly to changing conditions and improve operational visibility. The growing availability of IoT devices, cloud platforms, wireless connectivity, and agricultural data analytics is accelerating the integration of previously disconnected farming systems. In addition, rising pressure to improve productivity, optimize input usage, address labor shortages, and strengthen supply chain traceability is supporting the adoption of connected agriculture solutions.
The increasing use of sensors and connected agricultural equipment is driving market growth in the connected agriculture market by creating a continuous flow of real-time information from farms, machinery, crops, livestock, soil, and irrigation systems. Farmers increasingly use soil sensors, weather stations, crop monitoring devices, equipment telematics, GPS systems, and connected machinery to collect data related to field conditions and farm operations. This information enables agricultural businesses to monitor activities remotely and make decisions based on current operating conditions rather than relying only on periodic manual inspections. The growing deployment of connected devices is expanding the volume of agricultural data available for analysis and is propelling demand for connected agriculture platforms, software, and services.
High initial costs of connected agricultural technologies are restraining the growth of the connected agriculture market, particularly among small and medium-sized farms. Connected agriculture deployments often require investments in sensors, telematics systems, GPS-enabled machinery, connectivity infrastructure, cloud platforms, data management software, and technical integration. Farmers may also face additional expenses related to installation, equipment upgrades, maintenance, training, and system customization. The combined cost of adopting multiple connected technologies can make digital transformation difficult for agricultural businesses with limited capital availability. This financial barrier can delay technology adoption and restrict the expansion of connected agriculture solutions across a broader base of farming operations.
The growing adoption of 5G and edge computing in agriculture is creating significant opportunities in the connected agriculture market by enabling faster transmission and processing of data generated by sensors, machinery, drones, cameras, autonomous equipment, and livestock monitoring devices. Traditional connectivity can create delays when large volumes of agricultural data need to be transferred to distant cloud platforms for analysis. 5G networks can enable faster communication between connected equipment, while edge computing allows data to be processed closer to the farm, field, greenhouse, or agricultural facility. This combination creates opportunities for real-time monitoring and rapid decision-making across connected agricultural operations.
Analyst Perspective
The connected agriculture market is evolving from isolated precision farming applications toward a broader digital infrastructure layer that links physical farm assets, biological processes, and operational workflows. The key commercial challenge is not simply connecting more devices but ensuring that data from tractors, sensors, drones, irrigation systems, livestock platforms, and farm management software can work together to support timely operational decisions. Market participants that can overcome interoperability challenges and provide reliable connectivity across diverse farm environments are likely to establish stronger long-term positions. As agriculture becomes increasingly dependent on continuous data exchange, the market is expected to move toward more autonomous and coordinated farming operations in which connected systems actively support resource allocation, equipment utilization, crop management, and supply chain visibility.
Component Insights
Based on component, the solution segment led the market with the largest revenue share of 74.1% in 2025. The segment’s growth is attributed to the growing need for data-driven decision-making and the increased investment in AgTech startups. The need for real-time data and insights to make informed decisions about crop management, soil health, and weather conditions is driving the demand for integrated solutions that offer comprehensive data analysis and reporting. Moreover, significant investment in AgTech startups is driving innovation and the development of new solutions that cater to the evolving needs of the agricultural sector, further fueling the growth of the solution segment.
The services segment is projected to grow at the fastest CAGR of 17.8% from 2026 to 2033. The increasing complexities and the advancements in technology are driving the segment’s growth. As agricultural technologies become more complex, farmers and agribusinesses increasingly rely on managed services to help with the implementation, maintenance, and optimization of connected solutions. This demand for specialized support drives the growth of services such as system integration, support, and consultancy. The rapid advancement of connected agriculture technologies necessitates comprehensive integration and support services. These services ensure that new technologies are effectively incorporated into existing systems and that users receive the necessary training and support.
Deployment Insights
Based on deployment, the cloud segment led the market with the largest revenue share of 70.6% in 2025. The segment's growth is attributed to the scalability and flexibility of the cloud solutions. Cloud deployment provides scalable resources that can be adjusted based on demand, allowing agricultural businesses to expand or reduce their IT infrastructure as needed. This flexibility is crucial for managing varying data loads and operational requirements. Moreover, cloud deployment allows for remote access to agricultural data and applications, facilitating collaboration among farm managers and other stakeholders. This accessibility is especially important for managing operations across multiple locations.
The on-premises segment is projected to grow at a considerable CAGR of 15.2% from 2026 to 2033. The segment’s growth is attributed to the limited internet connectivity in rural areas. In rural or remote areas where internet connectivity is limited or unreliable, on-premises deployments ensure that agricultural operations can continue without relying on external cloud services. On-premises systems can operate independently of internet access, making them suitable for locations where connectivity issues could disrupt cloud-based solutions. Moreover, on-premises deployment allows agricultural businesses to maintain full control over their data, addressing concerns about data security and privacy.
Application Insights
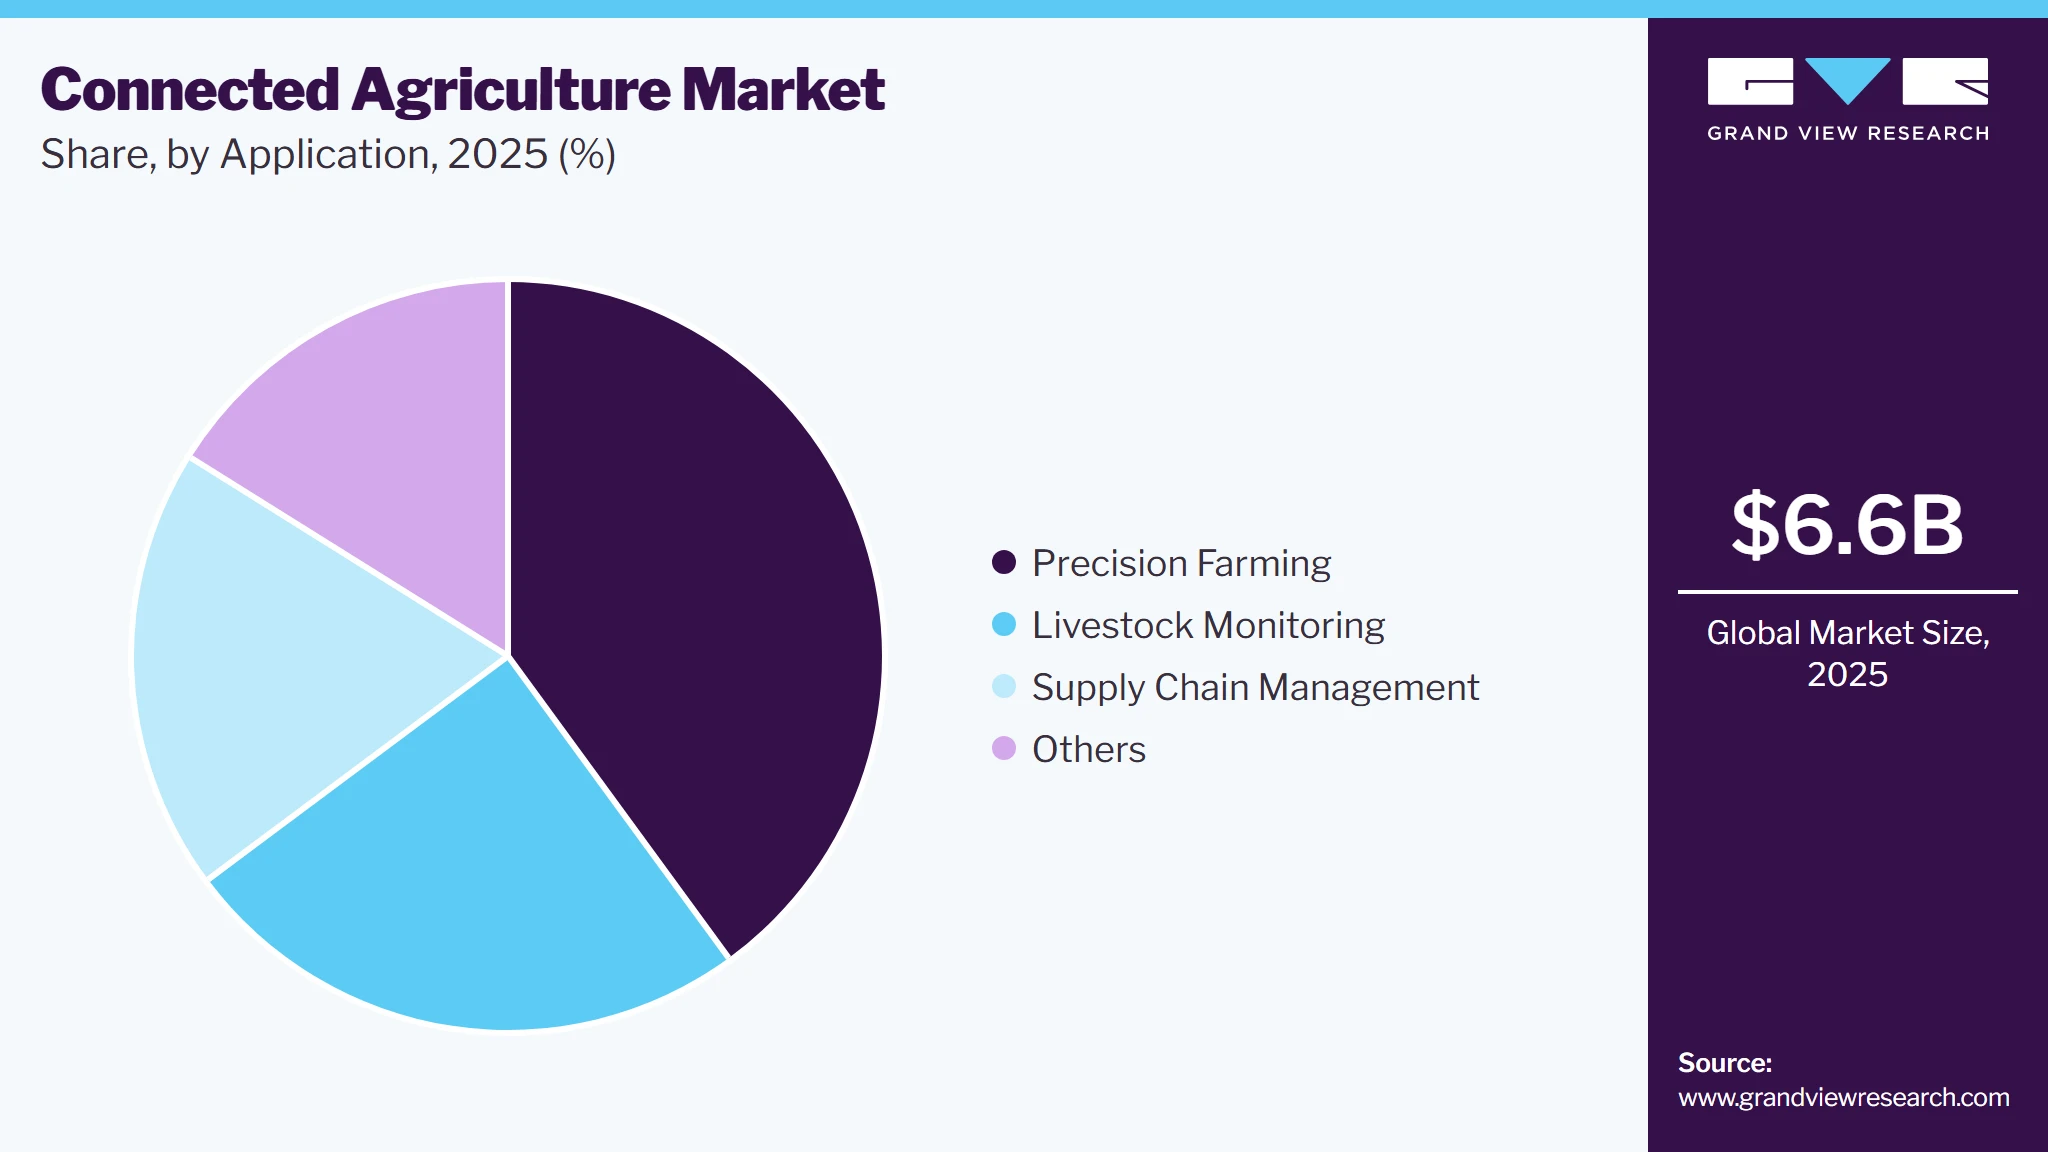
Based on application, the precision farming segment led the market with the largest revenue share of 40.0% in 2025. The increase in demand for food production efficiency and rising concerns about climate change and the environment are driving the segment’s growth. Precision farming technologies help optimize crop yields by using data-driven approaches to monitor and manage field conditions. This ensures that resources such as water, fertilizers, and pesticides are used efficiently, enhancing overall productivity. Moreover, it helps adapt to climate change by enabling farmers to monitor and respond to changing weather patterns and soil conditions. This proactive approach helps mitigate the impacts of climate variability on crop production. This is driving the adoption of connected agriculture solutions and services for precision farming applications.
 To learn more about this report, Download Free Sample Report
The livestock monitoring segment is projected to grow at the fastest CAGR of 19.0% from 2026 to 2033. The segment's growth is attributed to the rising consumer demand for quality and traceability. Monitoring livestock health and diet directly impacts the quality of animal products such as meat, milk, and eggs. This ensures that consumers receive higher-quality products, which can command premium prices. This is driving the growing adoption of connected agriculture solutions and services in livestock monitoring. Moreover, livestock monitoring systems contribute to improved animal welfare by enabling farmers to monitor and address the needs of individual animals. This aligns with growing consumer demand for ethically produced animal products.
Regional Insights
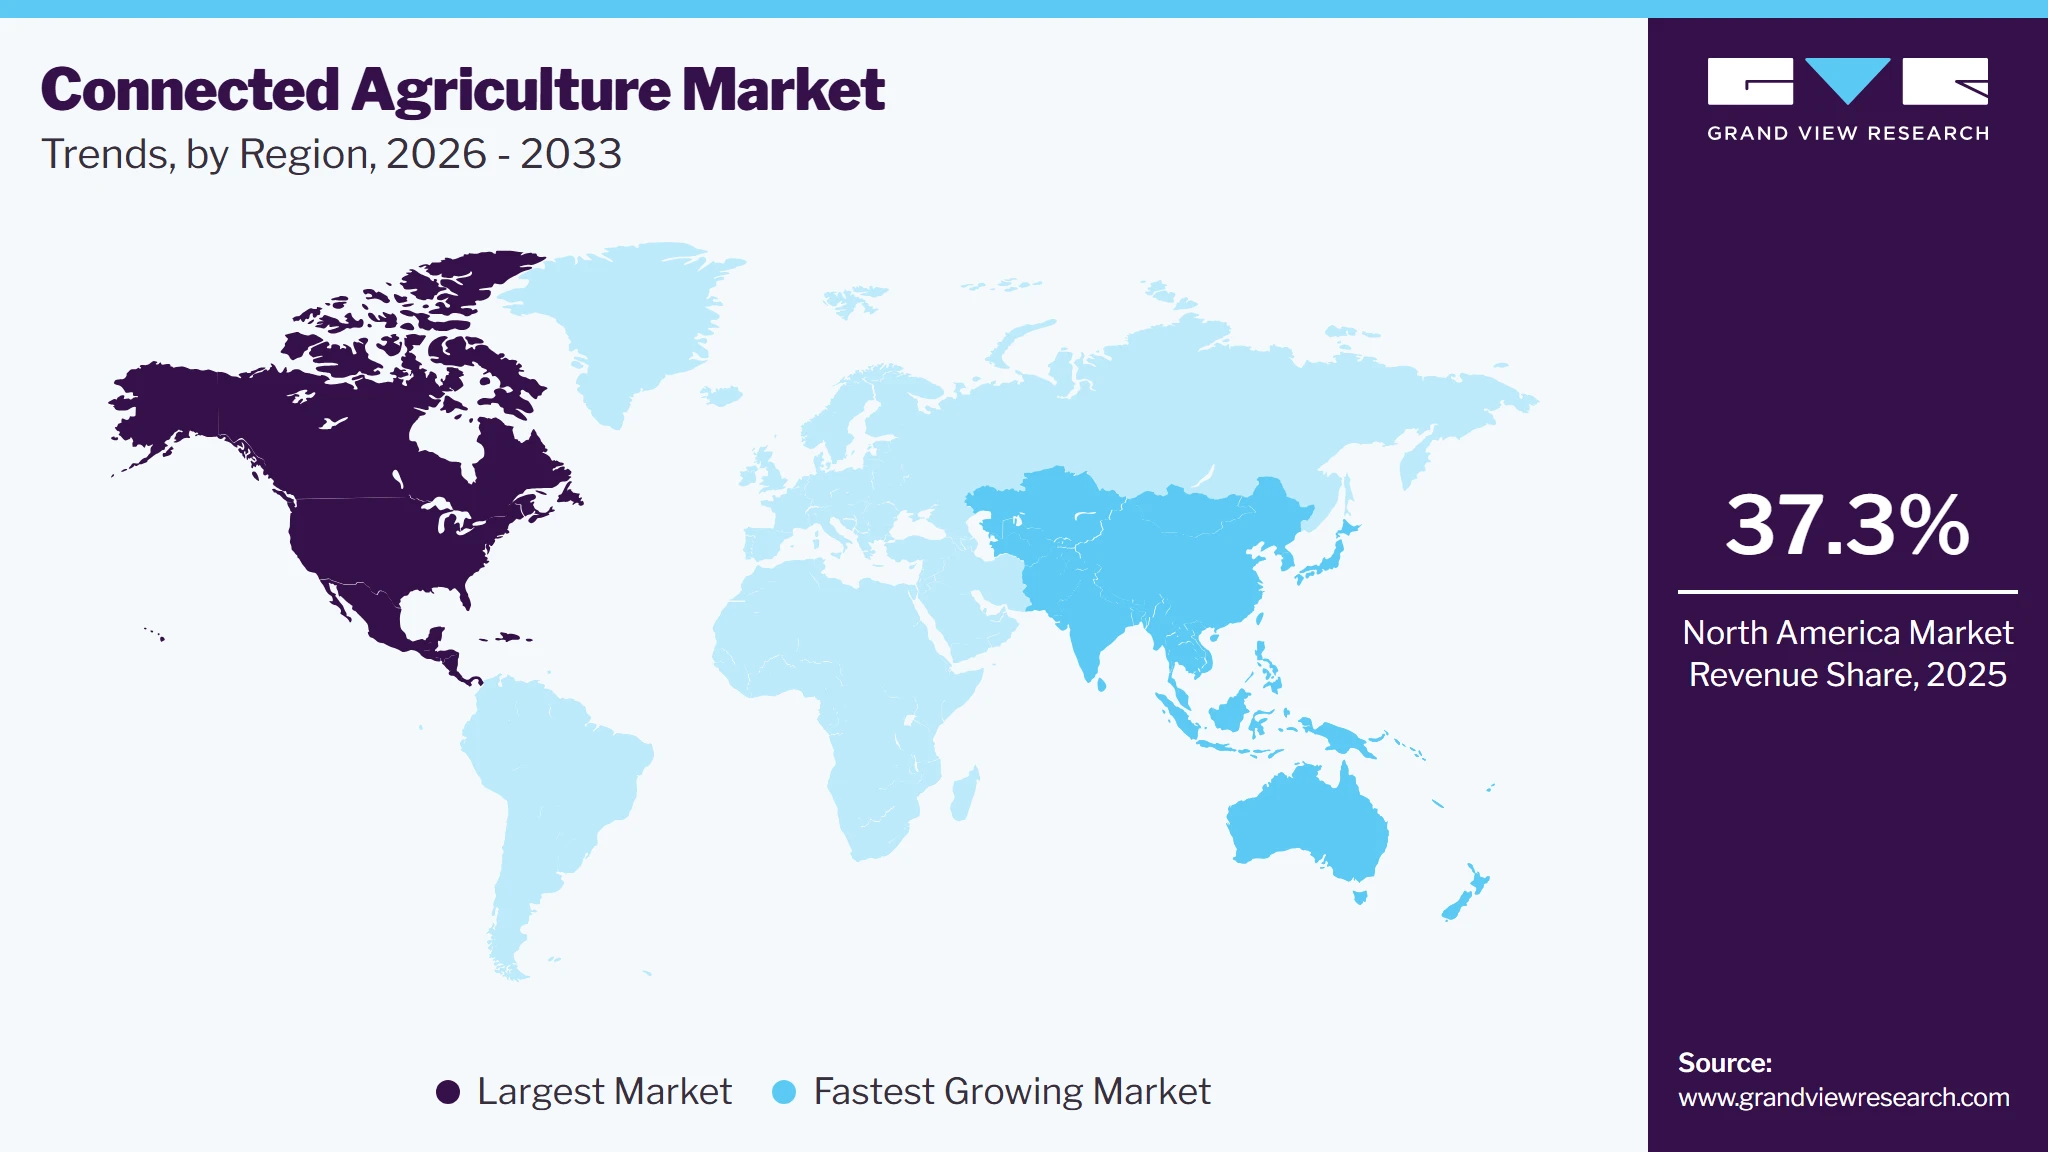
North America dominated the global connected agriculture market with the largest revenue share of 37.3% in 2025. The market's growth in the region is attributed to the high technology adoption and the availability of advanced connectivity infrastructure in the region. North America has extensive high-speed internet coverage and, advanced IoT connectivity, and growing connectivity in rural and agricultural areas. This infrastructure supports the deployment of connected agriculture solutions, enabling seamless data transmission and real-time monitoring of farm operations.
 To learn more about this report, Download Free Sample Report
U.S. Connected Agriculture Market Trends
The connected agriculture market in the U.S. held the largest share in the North America region in 2025. The market's growth in the country is attributed to the need to enhance efficiency and increase agricultural output in the country. According to the U.S. Department of Agriculture (USDA), in 2023, agriculture, food, and related industries contributed approximately USD 1.5 trillion to the country's gross domestic product (GDP), representing 5.6% of the total GDP. The adoption of connected agriculture solutions and services can further drive the agricultural output in the country.
Asia Pacific Connected Agriculture Market Trends
The connected agriculture market in Asia Pacific is expected to grow at the highest CAGR of 18.7% from 2026 to 2033. The market’s growth in the region can be attributed to the increasing population and food demand in the region. Asia Pacific is home to a rapidly growing population, leading to increased demand for food. This drives the adoption of connected agriculture technologies to enhance productivity and meet the rising food needs. Moreover, governments across the Asia Pacific region are actively promoting the adoption of smart agriculture technologies through subsidies, grants, and supportive policies. These initiatives lower the financial barriers for farmers to invest in connected agriculture solutions. In August 2024, the Government of India introduced the National Pest Surveillance System (NPSS) to link farmers with agricultural experts for efficient pest management through their smartphones. This initiative seeks to decrease farmers' dependence on pesticide vendors and encourage a more scientific approach to pest control by leveraging AI to analyze pest data and deliver timely, precise recommendations.
Europe Connected Agriculture Market Trends
The connected agriculture market in Europe is expected to grow at a significant CAGR of 17.0% from 2026 to 2033. The market's growth can be attributed to the growing focus on sustainable farming in the region. There is a strong emphasis on reducing the environmental impact of agriculture in Europe. Connected agriculture solutions help in monitoring and managing resources such as water, fertilizers, and pesticides more efficiently, supporting sustainable farming practices.
Key Connected Agriculture Company Insights
Some of the key companies operating in the market include Deere & Company, Trimble Inc., Hexagon AB, Topcon, and BASF SE, among others.
-
Deere & Company is an American multinational corporation founded in 1837. It is a leading manufacturer of agricultural, construction, and forestry machinery. The company is a prominent player in the agriculture industry, with a presence in over 30 countries. The company’s extensive portfolio includes tractors, combine harvesters, planters, sprayers, and various other machinery used in farming.
Sentera and Farmers Edge Inc. are some of the emerging companies in the target market.
-
Sentera, founded in 2014 and headquartered in Minnesota, U.S., is a leading technology company specializing in agricultural data solutions. The company focuses on providing innovative tools for precision agriculture through its advanced imaging and data analytics technologies. The company has made significant advancements in the integration of machine learning and artificial intelligence into its data analysis tools. These innovations enhance the accuracy and speed of crop monitoring and yield predictions. The company has also expanded its product offerings to include more user-friendly and scalable solutions for various farming operations.
Key Connected Agriculture Companies
The following key companies have been profiled for this study on the connected agriculture market.
-
Deere & Company
-
Trimble Inc.
-
AGCO Corporation
-
BASF SE
-
Bayer AG
-
Hexagon AB
-
Topcon
-
Sentera
-
Farmers Edge Inc.
-
CLAAS KGaA mbH
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Pentair; Nelson and Pade; The Aquaponic Source; UrbanFarmers AG; Superior Fresh)
- Established players focus on integrated connected agriculture platforms combining machinery, sensors, telematics, software, and analytics. They invest in autonomous farming, equipment connectivity, and data-driven farm management. Their strategies also emphasize interoperability and long-term relationships with commercial farms.
- Their broad product portfolios and established dealer networks provide strong market access. Large installed equipment bases support faster adoption of connected services. Extensive precision agriculture expertise strengthens their ability to deliver integrated solutions.
- High technology development and infrastructure costs can increase solution prices. Integrating legacy equipment and different digital systems remains complex. Smaller farms may face affordability and connectivity barriers.
Emerging Players (AquaSprouts; EcoGro; Upward Farms; Edenworks; Japan Connected Agriculture
- Emerging players focus on specialized solutions for crop monitoring, irrigation, pest control, and field intelligence. They use sensors, AI, cloud platforms, and wireless connectivity to deliver targeted farm insights. Their modular and subscription-based models support flexible adoption.
- Specialized technologies provide detailed real-time information for specific agricultural applications. Agile development enables faster innovation and customization. Their focused solutions can address needs that broader platforms may not fully cover.
- Limited production capacity and smaller distribution networks can restrict expansion. Lower brand recognition may slow adoption among large farms. Connectivity challenges and the need to prove measurable returns can further delay market penetration.
Recent Developments
-
In August 2023, Trimble Inc. released a flexible API for its Trimble Agriculture Cloud. This API allows third-party agriculture applications to connect with Trimble Inc.'s equipment and data, streamlining farming operations. The API supports various workflows like farm setup, task records, materials management, and vehicle setup.
-
In September 2022, Deere & Company released a Request for Proposal (RFP) to the satellite industry, looking for satellite services and terminals that offer continuous connectivity for its agricultural machinery. This initiative is designed to facilitate real-time data analysis and autonomous farming, enhancing productivity for Deere & Company’s customers and boosting food and fuel production.
Connected Agriculture Market Report Scope
Report Attribute
Details
Market size in 2025
USD 6.6 billion
Estimated market size in 2026
USD 7.6 billion
Projected market size by 2033
USD 22.7 billion
Growth rate
CAGR of 16.9% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company market share analysis, competitive landscape, growth factors, and trends
Segments covered
Component, deployment, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; China; India; Japan; Australia; South Korea; Brazil; UAE; Saudi Arabia; South Africa
Key companies profiled
Deere & Company; Trimble Inc.; AGCO Corporation; BASF SE; Bayer AG; Hexagon AB; Topcon; Sentera; Farmers Edge Inc.; CLAAS KGaA mbH
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Connected Agriculture Market Report Segmentation
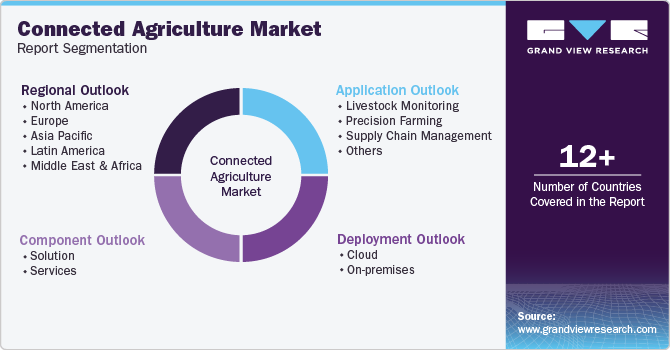
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global connected agriculture market report based on component, deployment, application, and region:
 To learn more about this report, Download Free Sample Report
-
Component Outlook (Revenue, USD Million, 2021 - 2033)
-
Solution
-
Services
-
-
Deployment Outlook (Revenue, USD Million, 2021 - 2033)
-
Cloud
-
On-premises
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Livestock Monitoring
-
Precision Farming
-
Supply Chain Management
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
India
-
China
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East and Africa (MEA)
-
Kingdom of Saudi Arabia (KSA)
-
UAE
-
South Africa
-
-
Research Methodology
The connected agriculture market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each connected agriculture segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Component
Revenue capture definition
Solution
The largest component segment, capturing value through connected agriculture platforms that integrate IoT sensors, farm management software, GPS/GNSS systems, AI analytics, automation tools, and real-time dashboards. Providers monetize through software licensing, recurring subscriptions, equipment-linked platforms, and integrated solutions that help farmers convert operational data into actionable decisions.
Services
Commercial opportunities arise from installation, system integration, data analytics, consulting, technical support, managed connectivity, and equipment maintenance. Service providers help agricultural organizations deploy connected technologies across farms while ensuring that data from sensors, machinery, livestock, and external systems can be effectively utilized.
Segment - Deployment
Revenue capture definition
Cloud
The dominant deployment model is supported by scalable data storage, remote farm monitoring, real-time analytics, and access to connected agriculture applications from multiple locations. Cloud platforms enable recurring subscription models and allow farms to integrate data from IoT devices, machinery, drones, weather systems, and supply chain platforms without maintaining extensive local infrastructure.
On-Premise
Adoption is concentrated among large agricultural enterprises, agribusinesses, food processors, and organizations requiring direct control over operational data and internal technology infrastructure. This model remains relevant where connectivity is limited or data governance, security, and integration requirements favor locally managed systems.
Segment - Application
Revenue capture definition
Livestock Monitoring
Market value is created through connected collars, ear tags, cameras, environmental sensors, and analytics platforms that track animal health, movement, feeding behavior, fertility, and productivity. Farmers and livestock operators invest in these technologies to identify health issues earlier, improve herd management, reduce losses, and increase operational efficiency.
Precision Farming
The largest application segment is supported by connected systems that combine field sensors, satellite data, machinery telemetry, weather information, and AI analytics to optimize planting, irrigation, fertilization, and crop protection. The commercial value of connected agriculture increases as growers seek higher yields, lower input consumption, and more accurate field-level decision-making.
Supply Chain Management
Commercial activity is driven by connected technologies that provide visibility across harvesting, storage, transportation, processing, and distribution activities. Agribusinesses utilize real-time tracking, IoT monitoring, and data platforms to improve traceability, reduce spoilage, manage inventory, and strengthen coordination between producers and downstream buyers.
Others
This category includes smart irrigation, greenhouse automation, farm equipment monitoring, agricultural weather monitoring, crop storage management, autonomous farming, and farm security applications. Expanding connectivity across agricultural operations continues to create new opportunities for specialized solutions that improve resource efficiency and operational visibility.
Estimation Model
Layer Name
Key Question
Description
Farm Connectivity Layer
What agricultural assets need to be connected?
Identify the farms, fields, machinery, irrigation systems, livestock facilities, greenhouses, storage units, and supply chain assets that generate operational data. This layer defines the market based on the growing need to connect dispersed agricultural assets and create continuous visibility across production activities that were traditionally managed through manual observation and disconnected equipment.
Data Infrastructure Layer
What enables agricultural assets to communicate and share information?
Assess the role of IoT sensors, wireless networks, GPS, satellite connectivity, edge computing, cloud platforms, gateways, and farm management systems in creating a connected agricultural environment. Adoption depends on network coverage, device interoperability, power availability, data security, and the ability to integrate information from different equipment manufacturers and technology platforms.
Connected Decision & Automation Layer
How is agricultural connectivity converted into operational action?
Analyze how real-time data from soil sensors, weather stations, farm machinery, livestock monitoring systems, irrigation infrastructure, and crop monitoring tools is used to support automated and data-driven decisions. Connected agriculture enables remote equipment control, precision irrigation, predictive maintenance, livestock tracking, variable-rate input application, crop monitoring, and coordinated farm operations across geographically distributed assets.
Data-Driven Agricultural Value Layer
How is commercial value generated from connected agricultural ecosystems?
Evaluate revenue streams from connected hardware, IoT platforms, farm management software, cloud subscriptions, connectivity services, data analytics, equipment telematics, and technology-enabled agricultural advisory services. Additional value is created through higher yields, reduced input waste, improved equipment utilization, lower labor requirements, predictive maintenance, and recurring data-service revenues, shifting agricultural technology from standalone equipment sales toward continuously connected and service-oriented operating models.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Connected Farm Operations & IoT Adoption Trends
Conducted a focused analysis of connected agriculture ecosystems covering IoT sensors, connected tractors, farm machinery telematics, weather stations, livestock monitoring, and remote field data collection across commercial farms and agricultural enterprises.
Helps stakeholders identify high-value connectivity applications, evaluate the transition toward data-enabled farming, and assess commercialization opportunities in connected agricultural ecosystems.
Real-Time Farm Monitoring & Automated Decision Support Trends
Evaluated adoption trends for remote crop monitoring, livestock tracking, smart irrigation, connected greenhouse systems, and AI-powered farm alerts, with emphasis on real-time data exchange between field devices, farm management platforms, and agricultural machinery.
Provides insights into operational visibility requirements, automation opportunities, and commercially attractive solutions supporting faster and more informed farm-level decisions.
Agricultural Connectivity Infrastructure & Digital Ecosystem Opportunity Assessment
Assessed demand for cloud-based farm platforms, edge computing, satellite connectivity, LPWAN networks, digital farm records, and interoperability between agricultural devices and software systems, along with challenges related to rural connectivity, data ownership, cybersecurity, and fragmented technology ecosystems.
Supports investment and expansion strategies by identifying connectivity gaps, evaluating digital agriculture readiness, and strengthening long-term growth opportunities in integrated and intelligent farming infrastructure.
Frequently Asked Questions About This Report
The solution segment led with an 74.1% revenue share in 2025, while services segment is the fastest-growing segment.
The cloud segment led with an 70.6% revenue share in 2025 and it is the fastest-growing segment.
Key players operating in the connected agriculture market include Deere & Company; Trimble Inc.; AGCO Corporation; BASF SE; Bayer AG; Hexagon AB; Topcon; Sentera; Farmers Edge Inc.; CLAAS KGaA mbH.
Key factors include increasing adoption of precision agriculture practices, increasing use of sensors and connected agricultural equipment, and growing adoption of 5G and edge computing in agriculture.
The precision farming segment held the largest share (over 40.0%), while livestock monitoring is the fastest-growing segment.
The global connected agriculture market size was valued at USD 6.6 billion in 2025 and is estimated at USD 7.6 billion for 2026.
The global connected agriculture market is expected to grow at a CAGR of 16.9% from 2026 to 2033, reaching USD 22.7 billion by 2033.
North America dominated the market with 37.3% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


