
- Home
- »
- Agrochemicals & Fertilizers
- »
-
Copper Fungicides Market Size & Share Report, 2026-2033GVR Report cover

Copper Fungicides Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Copper Oxychloride, Copper Hydroxide, Cuprous Oxide, Copper Sulfate), By Application (Fruits & Vegetables, Cereals & Grains, Pulses & Oilseed), By Region, And Segment Forecasts
Market Size, 2025
$367.1MMarket Estimate, 2026
$386.0MMarket Forecast, 2033
$563.9MCAGR, 2026–2033
5.6%Copper Fungicides Market Summary
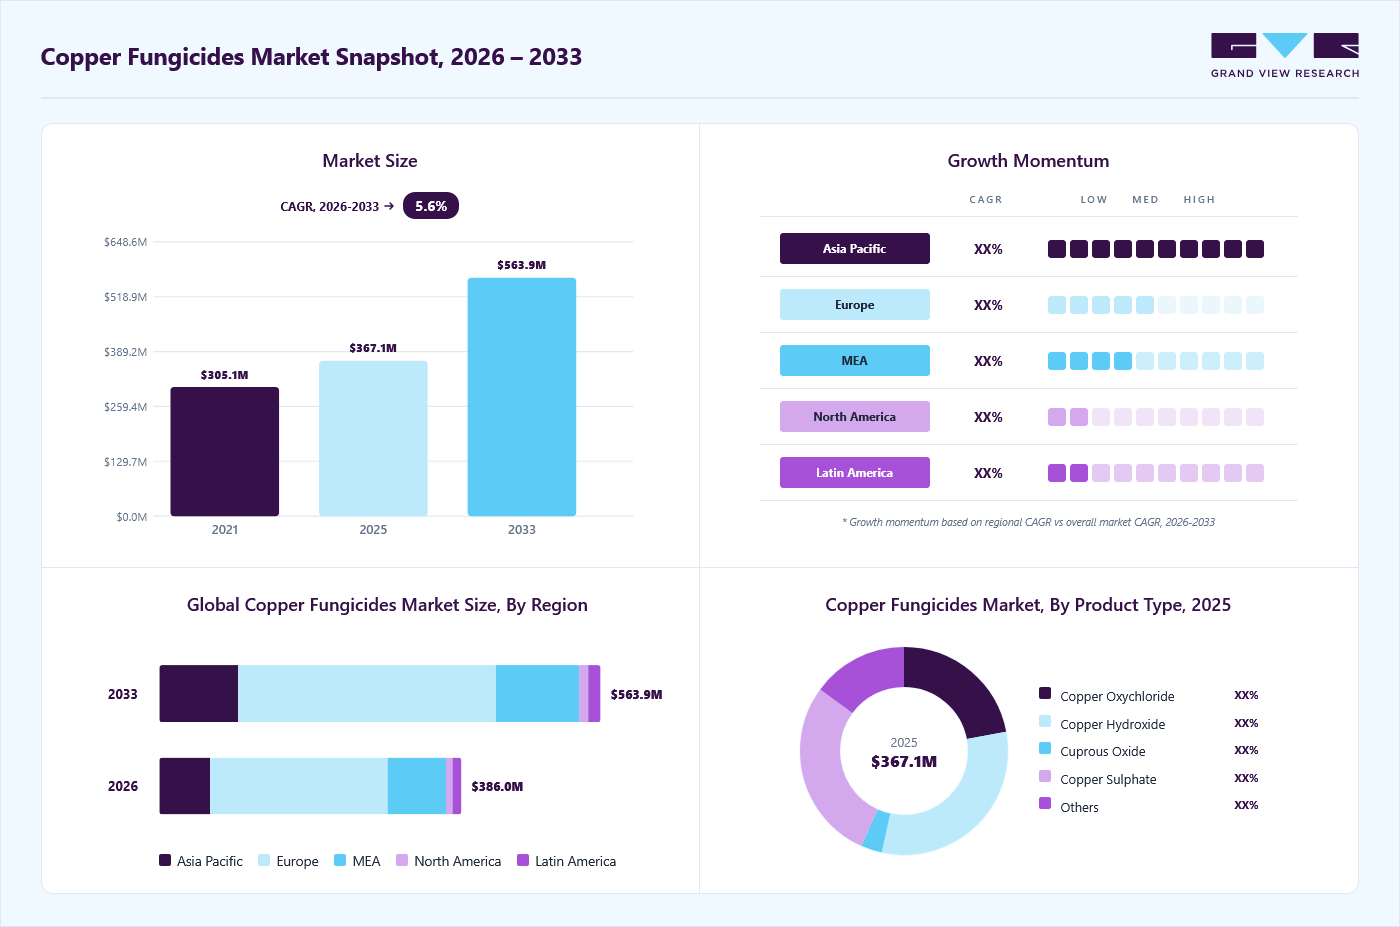
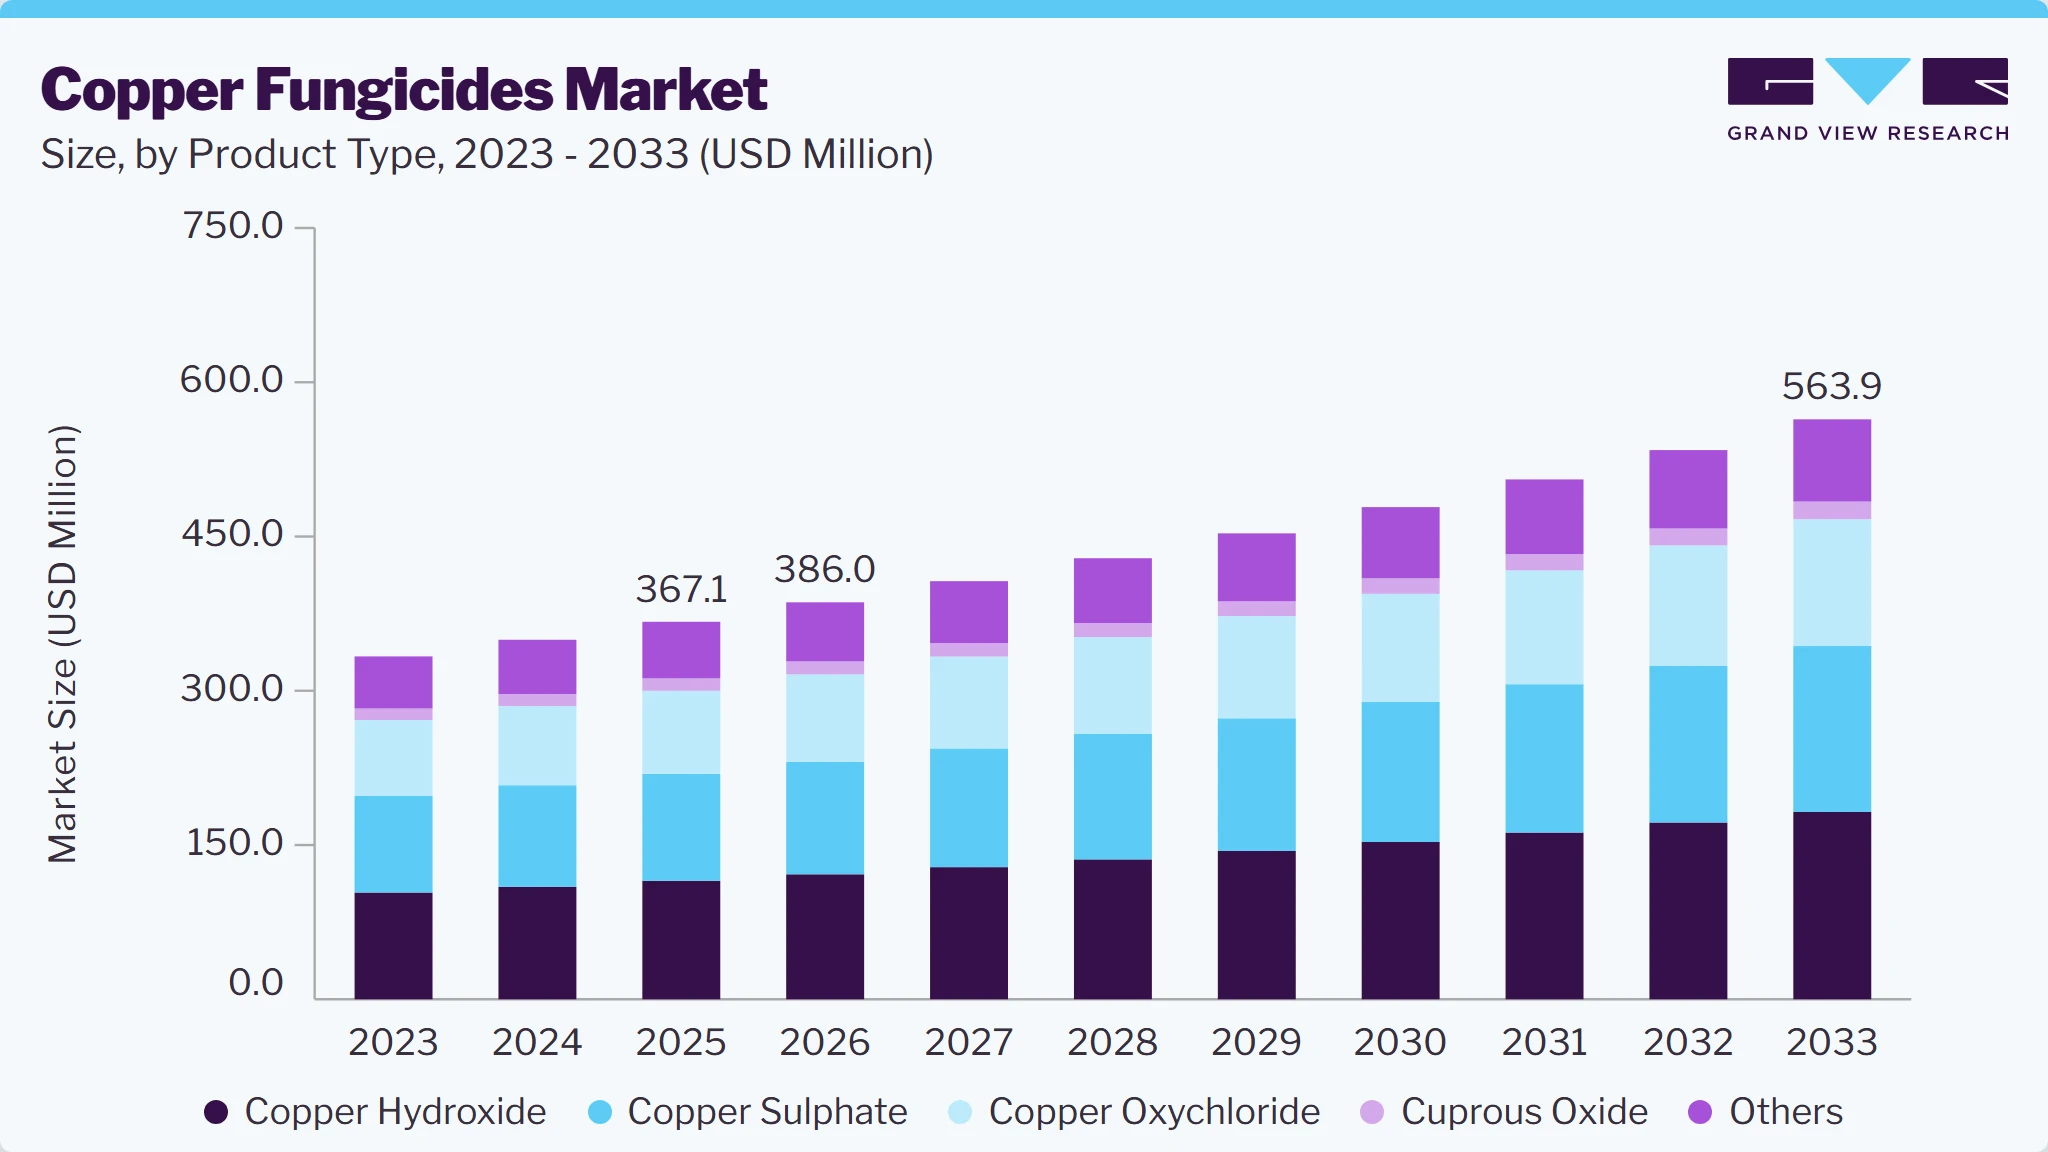
The global copper fungicides market size was valued at USD 367.1 million in 2025 and is projected to grow from USD 386.0 million in 2026 to USD 563.9 million by 2033, at a CAGR of 5.6% from 2026 to 2033. Europe accounted for 58.8% of the global market revenue in 2025. The increase in fungal diseases among plants can be attributed to several factors, including changes in global climatic conditions, the emergence of invasive fungal species, and the growing need for stronger fungal resistance in crops.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Copper sulphate segment accounted for the largest revenue share of 28.3% in 2025.
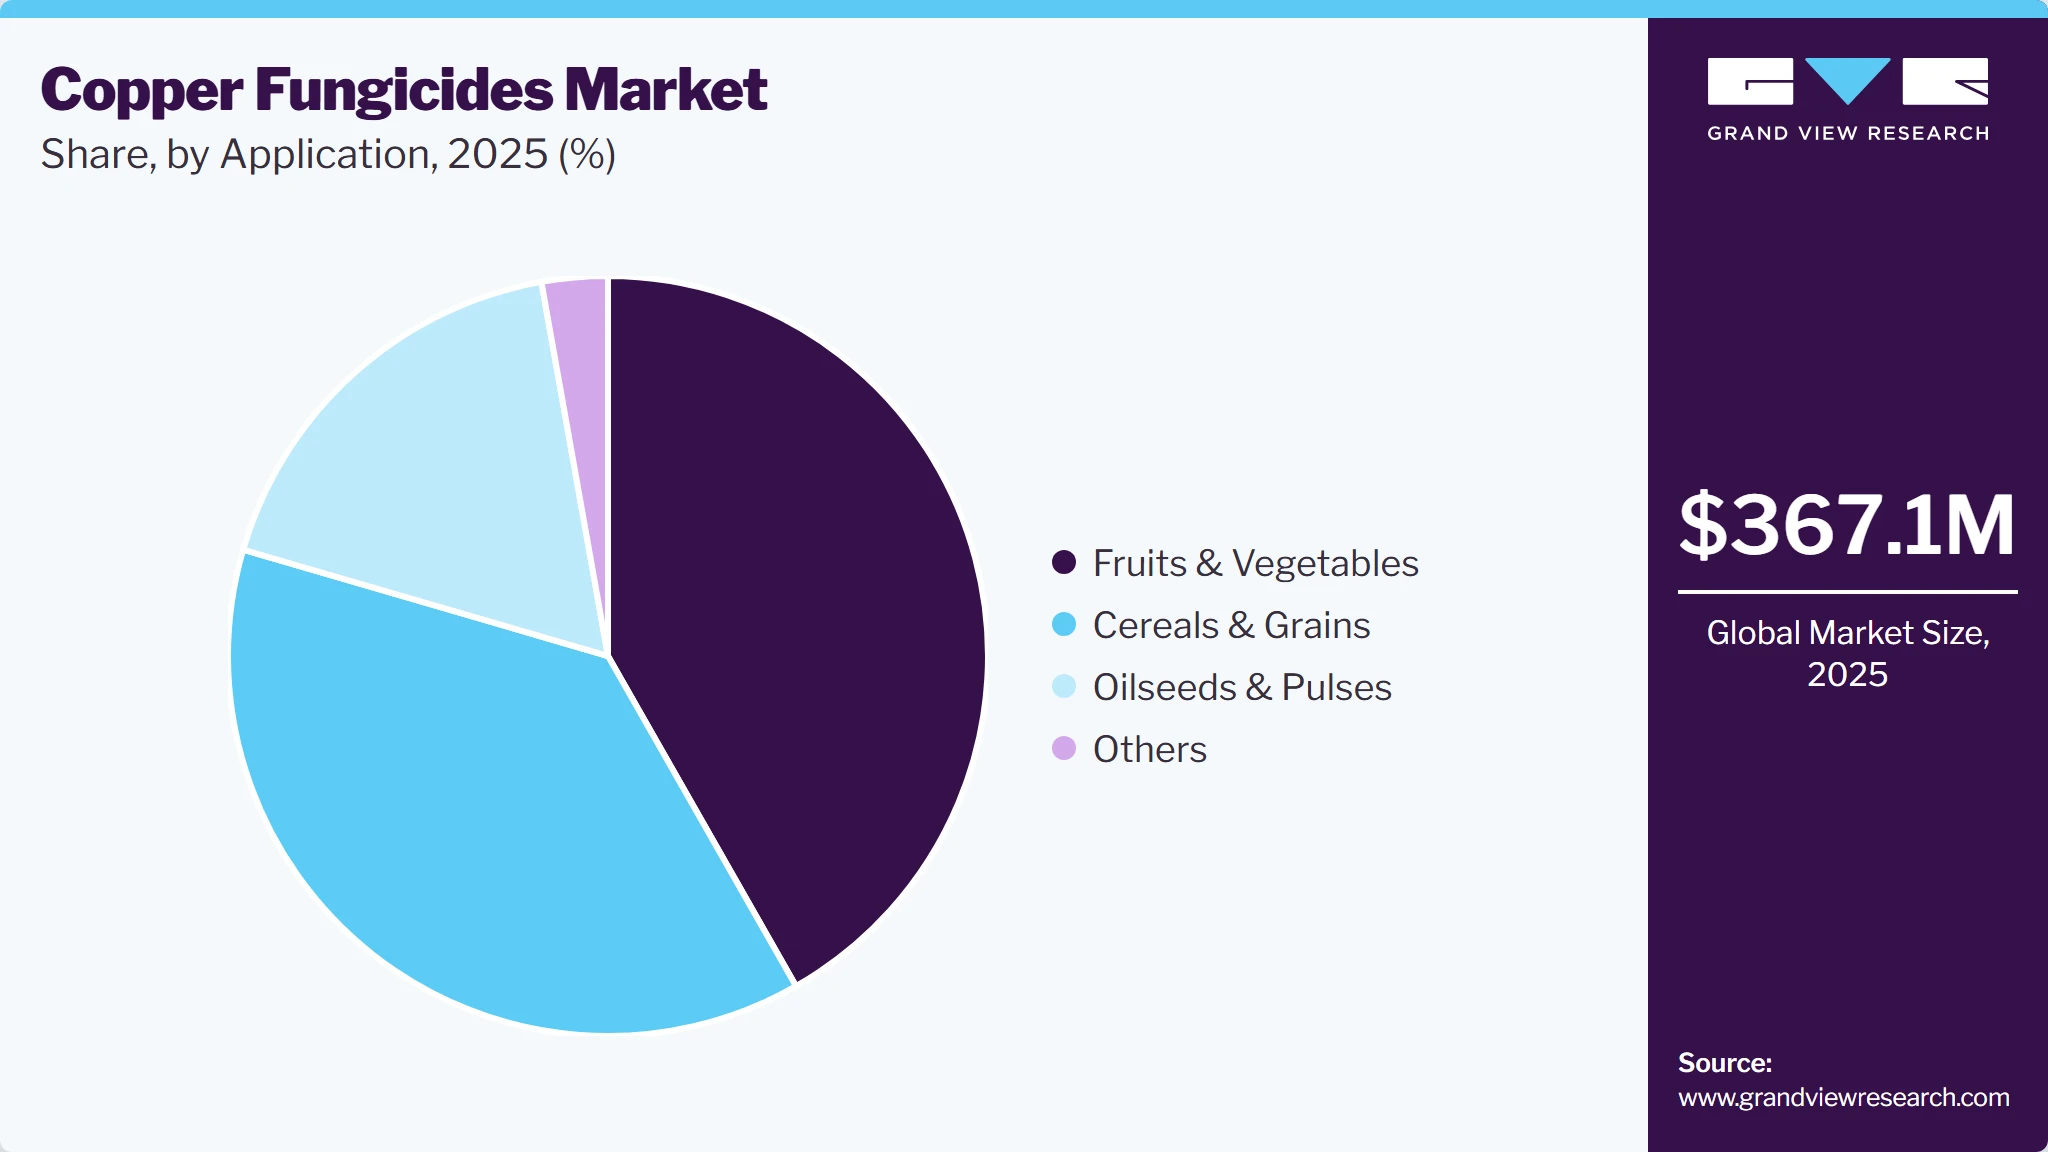
- By application: Fruits & vegetables dominated the application segment at a market share of 41.8% in 2025.
Regional Highlights
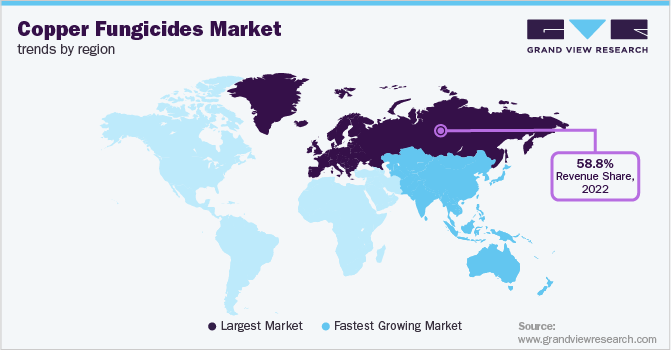
- Largest regional market: Europe (58.8% revenue share, 2025)
- By country: Italy held the largest revenue share in 2025.
Market Size & Forecast
- Market size in 2025: USD 367.1 Million
- Estimated market size in 2026: USD 386.0 Million
- Projected market size by 2033: USD 563.9 Million
- CAGR (2026-2033): 5.6%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The increase in fungal diseases among plants can be attributed to several factors, including changes in global climatic conditions, the emergence of invasive fungal species, and the growing need for stronger fungal resistance in crops. Fungi are the largest group of plant pathogens responsible for many serious plant diseases, particularly vegetables. Familiar sources of fungal infections in plants include seeds, soil, weeds, crop debris, and neighboring crops.Controlling fungal diseases that affect plants is crucial for meeting the increasing global food demand driven by a growing population. The United Nations projects that the worldwide population may reach 9.7 billion by 2050. According to the Harvard Business Review, food demand worldwide is expected to rise by approximately 98% by the same year. The Food and Agriculture Organization estimates that 2050 the demand for cereals will reach 3 billion tons. This demand includes both animal feed and food for people. These factors are expected to significantly boost product demand to increase crop yields in the coming years.
 To learn more about this report, Download Free Sample Report
Organic plant growers often rely on copper fungicides because they are the only organic products effective against plant diseases like downy mildew and late blight. These diseases can devastate crops, making the control of diseases through copper fungicides essential for both conventional and organic farming worldwide. This necessity is driven by high crop demand in the region, which is influenced by a growing population and the limited expansion of arable land.
Stringent regulations and a growing focus on sustainable development have resulted in a constant decline in chemical production in the European Union. This factor, coupled with relatively higher prices in the EU and the U.S., has provided a competitive advantage to the Asia Pacific countries, including China, Japan, South Korea, India, and Taiwan, due to the abundant availability of raw materials and economical prices.
Some major raw materials used to produce copper fungicides include sodium chloride, sodium hydroxide, sulfuric acid, copper oxide, and others. Sodium hydroxide is the most widely used strong alkali in various industries. The electrolytic dissociation of sodium chloride produces it. Also, it is more soluble compared to sodium chloride. However, copper hydroxide and copper oxychloride being the most widely used copper fungicides, the demand for their raw materials, including sodium chloride, copper chloride, and sodium hydroxide, is expected to rise, which is likely to fuel their prices in the coming years.
Market Dynamics
The copper fungicides market is witnessing steady growth driven by the increasing need for effective crop protection solutions in agriculture. Copper fungicides are widely used to control fungal and bacterial diseases in fruits, vegetables, cereals, pulses, and plantation crops. Rising global food demand, the need to improve crop productivity, and increasing awareness regarding disease management are supporting market expansion. The growing adoption of integrated pest management (IPM) practices and the continued acceptance of copper-based products in both conventional and organic farming systems further contribute to market growth.
The copper fungicides market is experiencing significant growth due to the increasing need to protect crops from fungal and bacterial diseases that can severely impact agricultural yields and quality. Copper fungicides are extensively used in crops such as grapes, citrus fruits, potatoes, tomatoes, apples, and various vegetables to prevent diseases including downy mildew, late blight, bacterial spot, and leaf curl. Growing global population and food security concerns are encouraging farmers to adopt effective disease management solutions that enhance crop productivity and reduce economic losses.
The impact of this trend extends across commercial agriculture, horticulture, greenhouse cultivation, and organic farming sectors. Copper fungicides remain among the most trusted broad-spectrum disease control products due to their effectiveness, relatively low resistance development, and compatibility with integrated pest management programs. As agricultural producers increasingly focus on maximizing crop yields and improving produce quality, demand for copper-based fungicides is expected to remain strong throughout the forecast period.
Environmental sustainability concerns and stringent regulatory frameworks present significant challenges for the copper fungicides market. Continuous application of copper-based fungicides can lead to copper accumulation in soil, potentially affecting soil microorganisms, biodiversity, and long-term soil health. Regulatory authorities in several regions are imposing restrictions on application rates, permissible residue levels, and overall copper usage in agricultural practices to minimize environmental impact.
Manufacturers and growers must comply with evolving regulations related to environmental protection, food safety, and sustainable farming practices. Meeting these requirements often involves additional investments in product development, testing, registration, and compliance management. Furthermore, increasing scrutiny of heavy metal usage in agriculture may limit product adoption in certain markets and encourage the development of alternative disease control solutions.
The growing adoption of organic farming and sustainable crop protection practices is creating substantial opportunities for the copper fungicides market. Copper-based fungicides are among the few disease control products permitted for use in many organic farming systems, making them essential tools for organic growers worldwide. Rising consumer demand for organic food products and increasing government support for sustainable agriculture are driving the expansion of organic cultivation areas and boosting demand for approved copper fungicide formulations.
Manufacturers are developing innovative products with enhanced adhesion, better rainfastness, and improved disease control performance. As farmers increasingly seek solutions that balance crop protection effectiveness, regulatory compliance, and environmental sustainability, suppliers offering advanced and eco-friendly copper fungicide products are expected to strengthen their market position and capitalize on growth opportunities across global agricultural markets.
Analyst Perspective
The copper fungicides market is expected to maintain steady growth over the forecast period, supported by increasing global demand for crop protection solutions and the growing need to improve agricultural productivity. Copper fungicides continue to play a critical role in managing fungal and bacterial diseases across a wide range of crops, including fruits, vegetables, cereals, oilseeds, and plantation crops. Their broad-spectrum efficacy, low resistance development potential, and compatibility with integrated pest management (IPM) programs make them a preferred disease control option for growers worldwide.
Drivers, Opportunities & Restraints
Fungi constitute the highest number of plant pathogens and cause numerous serious diseases in plants. Fungi cause the majority of diseases in vegetables worldwide. Various sources of fungal infections in plants are soil, seed, crop debris, weeds, and nearby crops. Water splashes, wind, animal movement, soil, seedlings, machines, etc., spread fungi. Some of the prevalent foliar diseases caused by fungi are powdery mildews, downy mildews, and white blisters.
Unlike other agrochemicals, evidence exists that copper fungicides can have a long-term effect on a wide range of soil biota. Effects can occur even at a low concentration of copper and impact several soil processes such as bioturbation, earthworm activity, and microbial activity. Copper residues are expected to remain indefinitely in soil, thereby influencing its overall health.
The shrinkage of cultivable land owing to its usage for non-agricultural purposes, such as the construction of buildings, roads, railways, etc., is predicted to generate the requirement for high crop productivity and minimize the occurrence of crop-related diseases to improve agricultural yields per hectare worldwide. This is expected to be a market growth opportunity in the coming years.
Product Insights
The copper sulphate segment accounted for the largest share of the copper fungicides market, representing 28.3% of total revenue in 2025 and is expected to continue to dominate the industry over the forecast period. This is owing to its broad range of properties, which control fungal and bacterial diseases through contact action. Furthermore, it has low aqueous solubility and low volatility. Copper itself cannot break down in the environment because it is a heavy metal, which makes it an effective fungicide. It is moderately toxic to mammals and most biodiversity. Its fine particles stick to the leaves and hinder the growth of the fungus.
Copper hydroxide fungicide is a major copper fungicide used to protect dozens of vegetables, fruit, and nut crops against many fungal infections. Bayer AG, a prominent manufacturer of Copper Fungicides, produces copper hydroxide under the brand “Blue Shield. " This product protects the crop against peppery leaf spots, downy mildew, black rot, and ring spots in pears, apples, and citrus fruit, along with anthracnose and bacterial black spots in mangoes.
Application Insights
Fruits & vegetables dominated the application segment at a market share of 41.8% in 2025, during the forecast period. Increasing health consciousness among consumers and the growing demand for fresh fruits and vegetables worldwide is expected to boost segment growth. Furthermore, fruit and vegetable production is rising at a high pace, which is expected to drive the copper fungicide market. This is attributed to the increasing consumption of vegetarian foods globally. Globally, growing health awareness among consumers is driving the demand for fruits & vegetables, which, in turn, is expected to propel the copper fungicide market growth.
 To learn more about this report, Download Free Sample Report
Oilseeds and pulses include various types of seeds, such as sunflower seeds, soybeans, and leguminous seeds (pulses). The increasing focus of farmers on oilseed production is expected to drive the copper fungicide market. Soybeans are commonly used oilseeds. China is the world's major producer of soybeans. In terms of rapeseed production, Europe, India, and Ontario are the top producers, while China leads peanut production, and Ukraine leads sunflower production. Rising demand for these oilseeds and pulses is expected to positively influence the demand for copper fungicides in the above regions.
Regional Insights
The copper fungicides market in North America is expected to grow significantly over the forecast period. North America is among the largest crop producers in the world, mainly responsible for producing corn, soybeans, oats, barley, etc. The increasing share of North America in global agricultural production is mainly driven by the flourishing agricultural sector in the U.S. Canada and Mexico are also witnessing surging crop yields, which contribute to the growth of the agricultural market in North America. Increasing agricultural activities in the region due to rising food requirements have fueled the demand for crop protection chemicals such as copper fungicides in North America.
U.S. Copper Fungicides Market Trends
The U.S. copper fungicides market is expected to grow significantly over the forecast period. This growth is attributable to the increasing crop production capacity of the U.S., which was at an all-time high with 177.0 bushels per acre registered in 2021. This was 5.6 bushels higher than 171.4 bushels per acre recorded in the country in 2020. The U.S. witnessed its highest soybean production in 2021, with over 4.44 billion bushels, registering a hike of approximately 5.0% in soybean production compared with that of 2020. Nearly 21 states across the U.S. produced an all-time high of soybeans in 2021.
Europe Copper Fungicides Market Trends
Europe accounted for 58.8% of the copper fungicides market revenue in 2025, making it the largest regional market as they are the leading producer of copper fungicides in the world. Copper fungicides were discovered in the region and have been used as fungicides in this geography since then. Most key copper fungicide manufacturers are in Europe due to the easy and adequate availability of raw materials such as copper sulfate required for developing these chemicals. Some other copper-based chemicals produced in this region are copper oxychloride, copper hydroxide, and cuprous oxide. The flourishing market for grapes in Europe owing to surging production and consumption of wine is estimated to fuel the growth of the market for copper fungicides in the region in the foreseeable period.
 To learn more about this report, Download Free Sample Report
Italy Copper Fungicides Market Trends
Italy held the largest share of the Europe copper fungicides market in 2025.
Asia Pacific Copper Fungicides Market Trends
The copper fungicides market in Asia Pacific is expected to grow at a significant CAGR during the forecast period. Agriculture is a primary sector in several countries in Asia Pacific, including India, Bangladesh, and Sri Lanka. The flourishing agriculture sector in these countries is expected to drive the consumption of copper fungicides in the region. Moreover, China and India being powerhouses in terms of the production of crops such as rice, wheat, and cotton, have emerged as global export hubs for rice, wheat, and cotton. It is expected that the consumption of pesticides will increase exponentially in Asia Pacific in the coming years, thereby leading to market growth in the region.
Latin America Copper Fungicides Market Trends
The copper fungicides market in Latin America is among the key producers of bananas, sugar, coffee, cocoa, wheat, and corn. Brazil, Argentina, and Colombia are the major contributors to the growth of agricultural production in Latin America. The region represents immense growth potential for crop protection chemicals such as copper fungicides due to rising crop cultivation driven by increasing demand for food.
Middle East & Africa Copper Fungicides Market Trends
The copper fungicides market in MEA is expected to grow significantly due to the rising input costs for agricultural production and limited water availability, which pose major threats to crop cultivation in the Middle East. The U.S. Department of Agriculture (USDA) estimates that wheat production in the region is expected to deteriorate further in the coming years with the limited availability of water in the Middle East. The region accounts for a share of 5.0% of the global wheat production yearly. It mainly relies on wheat imports and other crops to cater to domestic requirements. In addition, the Middle East has the most water scarcity in the world.
Key Copper Fungicides Company Insights
Some of the key players operating in the market include UPL Limited India, Albaugh, LLC, and Bayer AG.
-
Albaugh LLC is a global business offering an ever-expanding portfolio of crop protection products in the key agricultural regions of North America, Latin America, Europe, Middle East & Africa, and Asia Pacific. Albaugh LLC is a manufacturer and formulator of agricultural crop protection products based in Ankeny, Iowa. The company's core product portfolio is based on five key active ingredients, offering herbicides, fungicides, insecticides, seed treatments, and plant growth regulators to help farmers with crop protection requirements.
-
Nufarm is a global agricultural products manufacturer. The company develops, manufactures, and sells crop protection products, including insecticides, fungicides, and herbicides. It is also an expert in seed technologies and crop protection solutions. The company’s crop protection solutions protect crops against pests, weeds, and diseases. Its product portfolio includes seed treatments, herbicides, fungicides, insecticides, and plant growth regulators. Key crop chemicals are related to cereals, corn, soybean, pasture, turf, ornamentals, trees, nuts, vines, and vegetables.
Key Copper Fungicides Companies:
The following are the leading companies in the copper fungicides market. These companies collectively hold the largest market share and dictate industry trends.
- UPL Limited India
- Albaugh, LLC
- Nufarm
- Certis USA LLC
- Bayer AG
- Isagro S.p.A.
- Nordox AS
- ADAMA
- Quimetal
- Cosaco
- Cinkara Celje dd
- Corteva
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (UPL Limited, Bayer AG, Nufarm, Corteva, ADAMA)
- Focus on broad portfolios of copper-based fungicides and integrated crop protection solutions.
- Invest heavily in R&D to develop advanced formulations with improved efficacy and environmental performance.
- Expand distribution networks and strengthen relationships with distributors, cooperatives, and large farming operations.
- High costs associated with regulatory approvals, environmental compliance, and product stewardship.
- Exposure to fluctuating raw material prices and agricultural demand cycles.
- Large organizational structures may limit agility in responding to niche market opportunities.
- Dependence on mature markets for a significant portion of revenues.
- Strong brand recognition and established customer trust across agricultural markets.
- Extensive global manufacturing, regulatory, and distribution capabilities.
- Broad product portfolios that enable cross-selling opportunities.
- Significant financial resources to support innovation, market expansion, and regulatory compliance.
Emerging and Regional Players (Albaugh, LLC, Certis USA LLC, Isagro S.p.A., Nordox AS, Quimetal, Cosaco, Cinkarna Celje d.d.)
- Focus on copper fungicides, specialty crop protection products, and region-specific agricultural requirements.
- Expand through strategic alliances, local distribution partnerships, and targeted product registrations.
- Offer customized formulations for specific crops, climatic conditions, and disease management programs.
- Target high-growth agricultural regions and specialty crop markets.
- Greater operational flexibility and faster response to changing farmer requirements.
- Strong specialization in copper-based fungicides and disease management solutions.
- Competitive pricing and strong regional market relationships.
- Ability to develop customized products for local agricultural conditions and crop requirements.
- Smaller production capacities and more limited geographic reach compared with multinational competitors.
- Lower R&D and marketing budgets than leading agrochemical companies.
- Greater dependence on regional demand patterns and crop cycles.
- Limited ability to compete for large-scale global distribution contracts and multinational farming accounts..
Recent Developments
-
In March 2023, Corteva Agriscience announced the commercial launch of Adavel Active. This innovative fungicide has recently obtained product registrations in Australia, Canada, and South Korea. Adavel Active is distinguished by its unique mode of action, which protects against various diseases that can significantly impact crop yields.
Copper Fungicides Market Report Scope
Report Attribute
Details
Market size in 2025
USD 367.1 million
Estimated market size in 2026
USD 386.0 million
Projected market size by 2033
USD 563.9 million
Growth rate
CAGR of 5.6% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; India; Japan; South Korea; Brazil; Argentina; Saudi Arabia; South Africa
Key companies profiled
UPL Limited India; Albaugh, LLC; Nufarm; Certis USA LLC; Bayer AG; Isagro S.p.A.; Nordox AS; ADAMA; Quimetal; Cosaco; Cinkara Celje dd; Corteva
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Copper Fungicides Market Report Segmentation
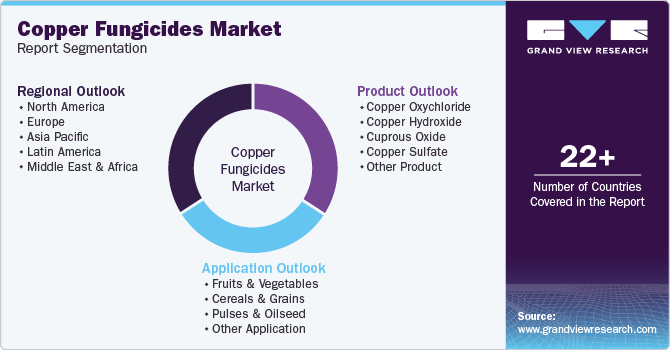
This report forecasts revenue and volume growth at global, regional, and country levels and analyzes the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global copper fungicides market report by product, application, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Volume, Tons; Revenue, USD Million, 2021 - 2033)
-
Copper Oxychloride
-
Copper Hydroxide
-
Cuprous Oxide
-
Copper Sulfate
-
Other Product
-
-
Application Outlook (Volume, Tons; Revenue, USD Million, 2021 - 2033)
-
Fruits & Vegetables
-
Cereals & Grains
-
Pulses & Oilseed
-
Other Application
-
-
Regional Outlook (Volume, Tons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The copper fungicides market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each copper fungicides segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Copper Oxychloride
Revenue generated from the sale of copper oxychloride-based fungicides used for the prevention and control of fungal and bacterial diseases in fruits, vegetables, plantation crops, and ornamental plants.
Copper Hydroxide
Revenue generated from copper hydroxide fungicide products utilized in agricultural disease management, particularly for controlling blights, leaf spots, mildews, and bacterial infections across various crops.
Cuprous Oxide
Revenue generated from cuprous oxide-based fungicides used for crop protection against fungal pathogens and bacterial diseases, especially in specialty crops, orchards, and horticultural applications.
Copper Sulphate
Revenue generated from copper sulphate fungicides and related formulations employed for disease control, seed treatment, soil treatment, and crop protection applications in agriculture.
Other Products
Revenue generated from other copper-based fungicide formulations, blends, mixtures, and specialty copper compounds used for disease management in agricultural and horticultural crops.
Segment -End Use
Revenue capture definition
Fruits & Vegetables
Revenue generated from the use of copper fungicides in fruit and vegetable cultivation for controlling fungal and bacterial diseases, improving crop quality, reducing yield losses, and enhancing productivity.
Cereals & Grains
Revenue generated from copper fungicide applications in cereal and grain crops, including wheat, rice, maize, barley, and other grains, for disease prevention and crop health management.
Oilseeds & Pulses
Revenue generated from the use of copper fungicides in oilseed and pulse crops such as soybean, sunflower, groundnut, lentils, peas, and chickpeas to manage disease outbreaks and support yield performance.
Other End Uses
Revenue generated from copper fungicide applications in plantation crops, turf and ornamentals, forestry, nurseries, greenhouse cultivation, vineyards, and other agricultural or non-agricultural uses.
Estimation Model
Layer Name
Key Question
Description
Copper Fungicides Production Layer
What forms is the supply base?
Identify global production capacity of copper fungicides, including copper oxychloride, copper hydroxide, cuprous oxide, copper sulphate, and other copper-based formulations. Assess manufacturing infrastructure, availability of copper raw materials, formulation technologies, regulatory approvals, production facilities, and regional manufacturing capabilities to establish the foundational supply base for the agricultural fungicides industry.
Agricultural End-Use Adoption Layer
Where are copper fungicides utilized?
Estimate the proportion of copper fungicides consumed across fruits and vegetables, cereals and grains, oilseeds and pulses, plantation crops, vineyards, horticulture, greenhouse cultivation, and ornamental crops based on disease prevalence, crop acreage, farming practices, and fungicide application requirements.
Consumption Intensity Layer
How much copper fungicide is used?
Analyze crop-specific application rates, disease management programs, frequency of fungicide treatments, seasonal usage patterns, cultivation area, climatic conditions, and regional agricultural practices to determine annual copper fungicide consumption across major crop categories and geographic markets.
Revenue Layer
How is market revenue generated?
Market revenue is quantified through the sale of copper oxychloride, copper hydroxide, cuprous oxide, copper sulphate, and other copper-based fungicide formulations supplied to farmers, agricultural cooperatives, distributors, crop protection companies, horticultural producers, plantation operators, and greenhouse cultivators for disease prevention and crop protection applications worldwide.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Cross-Segmentation Analysis
Detailed cross-segmentation assessment evaluating the relationship between copper fungicide product, crop applications, and end-use agricultural sectors within the copper fungicides market. Analysis identifies consumption patterns, application intensity, disease management requirements, crop-specific usage trends, and revenue contribution across intersecting segments such as copper oxychloride in fruits and vegetables, copper hydroxide in horticultural crops, cuprous oxide in specialty crops, and copper sulphate in cereals and grains.
Supports product portfolio optimization and market prioritization by identifying the most attractive product-crop-end-use combinations, enabling improved resource allocation, sales targeting, distribution planning, and strategic growth initiatives.
Competitive Benchmarking
Comparative evaluation of leading Copper Fungicides manufacturers based on product portfolio breadth, formulation capabilities, production capacity, geographic presence, distribution networks, regulatory approvals, innovation capabilities, customer relationships, manufacturing footprint, and strategic developments across key agricultural markets.
Assists competitive intelligence, partnership evaluation, and supplier assessment by providing deeper visibility into market positioning, product differentiation strategies, technological strengths, distribution advantages, innovation capabilities, and areas of competitive advantage.
Opportunity Assessment
Comprehensive assessment of emerging opportunities associated with organic farming expansion, sustainable agriculture practices, integrated pest management (IPM) adoption, high-value horticultural cultivation, specialty crop production, greenhouse farming, and advanced copper fungicide formulations. The analysis also evaluates opportunities in low-copper formulations, environmentally sustainable crop protection solutions, and emerging agricultural markets.
Helps identify high-growth investment areas, product development priorities, market expansion opportunities, and strategic business initiatives, supporting long-term revenue growth and competitive positioning across the Copper Fungicides value chain.
Frequently Asked Questions About This Report
The global copper fungicide market size was estimated at USD 367.1 million in 2025 and is expected to reach USD 386.0 million in 2026.
The copper fungicide market is expected to grow at a compound annual growth rate of 5.6% from 2026 to 2030 to reach USD 563.9 million by 2033.
Europe accounted for the largest market share of 58.8% in 2025.
Copper sulphate segment accounted for the largest revenue share of 28.3% in 2025 while
The fruits & vegetables segment dominated the market in 2025, accounting for 41.8% of total revenue while oilseeds and pulses is the fastest-growing segment.
Key factors that are driving the copper fungicide market growth include factors such as the change in global climatic conditions, the emergence of invasive fungal species, and the need for strong fungal resistance in crops.
Some key players operating in the copper fungicide market include UPL Limited India; Albaugh, LLC; Nufarm; Certis USA LLC; Bayer AG; Isagro S.p.A.; Nordox AS; ADAMA; Quimetal; Cosaco; Cinkara Celje dd; Corteva.
About the Author(s)
Agrochemicals & Fertilizers Research Team
Bulk Chemicals · Agrochemicals & FertilizersThis report was authored by the agrochemicals & fertilizers research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the agrochemicals & fertilizers segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


