
- Home
- »
- Network Security
- »
-
Critical Infrastructure Protection Market Size Report, 2033GVR Report cover

Critical Infrastructure Protection Market (2026 - 2033) Size, Share & Trends Analysis Report By Type (Solution, Services), By Security (Cyber Security, Physical Safety & Security), By End-use (BFSI, Energy & Utilities, Oil & Gas, Government & Defense), By Region, And Segment Forecasts
Market Size, 2025
$151.0BMarket Estimate, 2026
$156.9BMarket Forecast, 2033
$229.1BCAGR, 2026–2033
5.6%Critical Infrastructure Protection Market Summary
The global critical infrastructure protection market size was valued at USD 151.0 billion in 2025 and is projected to grow from USD 156.9 billion in 2026 to USD 229.1 billion by 2033, growing at a CAGR of 5.6% from 2026 to 2033. North America dominated the global industry with a revenue share of 38.6% in 2025. Growing cyber insurance adoption and board-level focus on operational resilience contributes to the market growth for critical infrastructure protection.
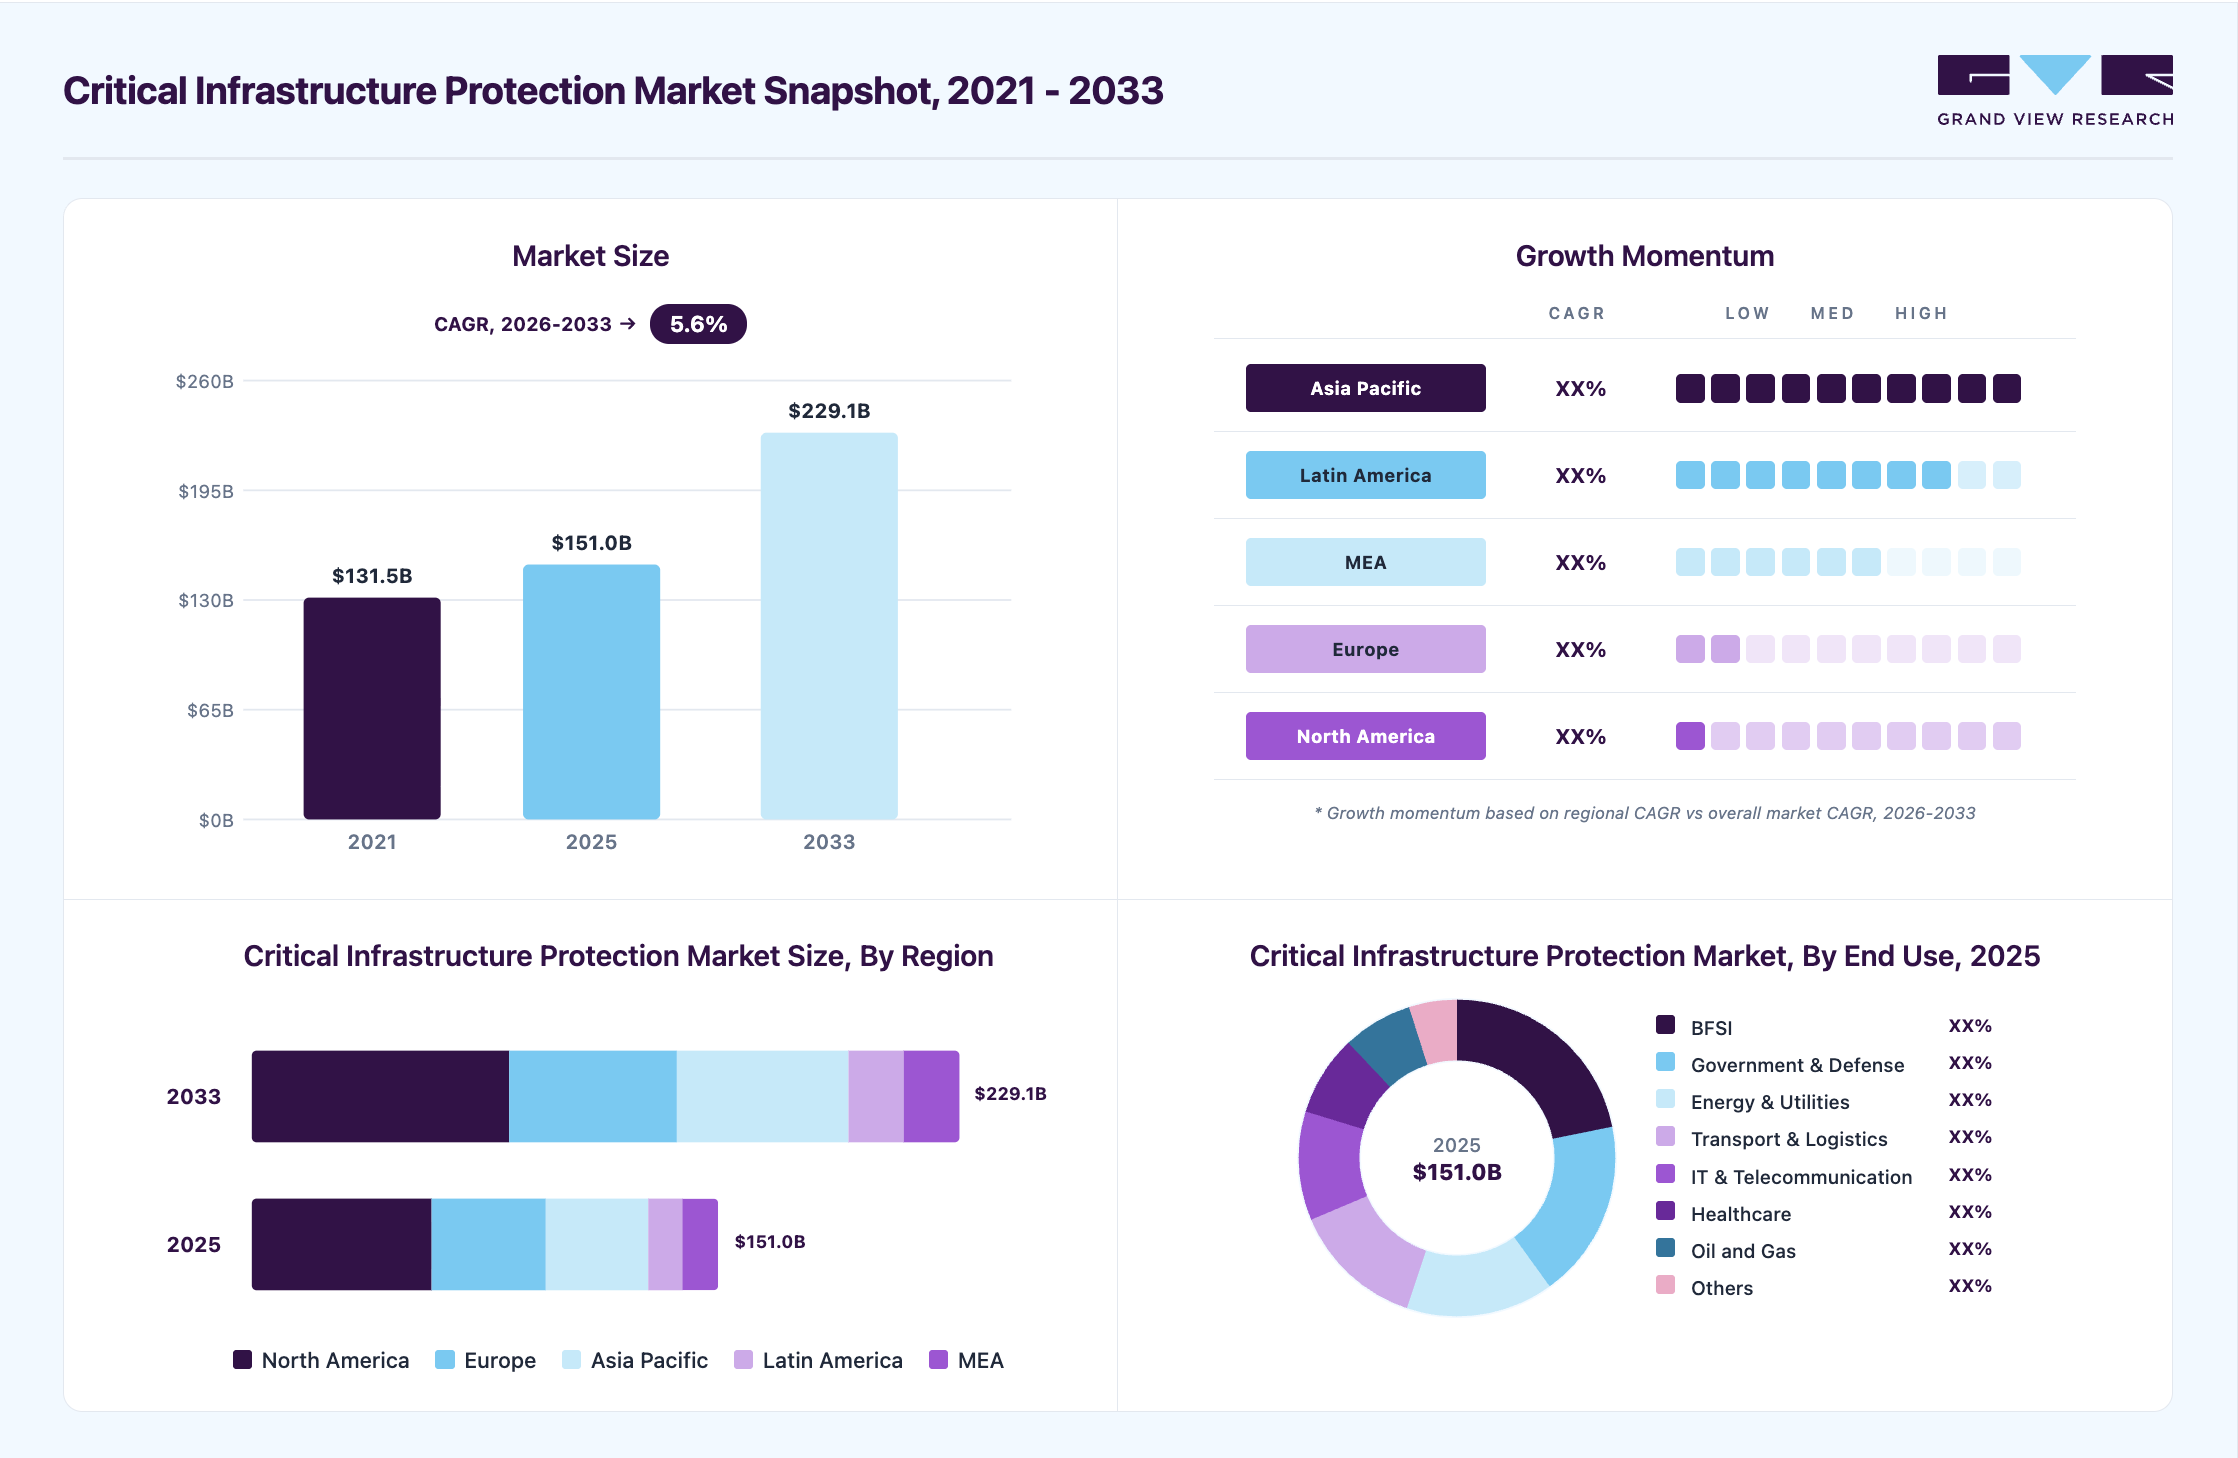 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Solution segment held the largest revenue share of 72.1% in 2025.
- By security: Physical safety and security segment held the largest revenue share in 2025.
- By end use: BFSI segment held the largest revenue share in 2025.
Regional Highlights
- Largest regional market: North America (38.6% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- In the U.S. the growth of mega-infrastructure projects is accelerating the demand for critical infrastructure protection systems.
Market Size & Forecast
- Market size in 2025: USD 151.0 Billion
- Estimated market size in 2026: USD 156.9 Billion
- Projected market size by 2033: USD 229.1 Billion
- CAGR (2026-2033): 5.6%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Rising concerns about cyber threats have encouraged multiple businesses to adopt critical infrastructure protection solutions and services. In addition, government initiatives have been fostering collaborative efforts to strengthen cybersecurity. The increasing number of cyber threats and frauds committed with the help of computing technology has created an alarming situation for numerous businesses that heavily rely on data transfer and the use of remote networks. For instance, according to the Federal Bureau of Investigation, the 2024 Internet Crime Report compiles data from 859,532 suspected internet crime complaints, revealing reported losses of over USD 16 billion, marking a 33% increase compared to 2023. To learn more about this report, Download Free Sample Report
The growing digitalization and interconnectivity of operational technology (OT) and information technology (IT) in critical sectors is driving market growth. Industrial control systems (ICS), Physical Safety and Security networks, and IoT devices are essential types of power plants, airports, and manufacturing facilities. While these systems enhance efficiency and real-time decision-making, they also broaden the attack surface. The convergence of OT and IT has made traditional perimeter defenses obsolete, prompting operators to adopt more advanced, layered security models. This has accelerated the demand for CIP solutions that offer intrusion detection, asset visibility, anomaly detection, and secure remote access tailored to industrial environments.
The implementation of strict government regulations and compliance mandates is also a significant force driving the CIP market. National cybersecurity policies in countries such as the United States (e.g., CISA guidelines), the United Kingdom (NIS Regulations), and India (CERT-In directives) require critical infrastructure operators to adopt robust protection frameworks. These regulations often include mandatory risk assessments, incident reporting, and minimum security controls. As a result, organizations are compelled to invest in advanced security technologies, risk management platforms, and compliance-driven solutions to meet regulatory requirements and avoid penalties.
Furthermore, the rising adoption of cloud, edge computing, and 5G networks in critical sectors is creating new vulnerabilities that demand updated protection strategies. As more critical infrastructure systems migrate to the cloud or adopt edge-based architectures for real-time processing, there is a growing need for cloud-native security platforms, secure network segmentation, and zero-trust architectures. These trends are prompting both public and private entities to partner with technology vendors and managed security providers to implement scalable, real-time, and policy-driven protection strategies, ensuring the resilience and continuity of essential services in an increasingly complex threat landscape.
Market Dynamics
The rising frequency of cyberattacks, geopolitical tensions, sabotage incidents, and vulnerabilities in critical infrastructure networks is driving governments and enterprises to adopt advanced critical infrastructure protection solutions. Operators across sectors such as energy, utilities, transportation, telecommunications, defense, and water management are increasingly investing in cybersecurity platforms, industrial control system (ICS) security, threat intelligence, video surveillance, access control, and real-time monitoring systems to strengthen operational resilience and prevent large-scale disruptions. Additionally, the growing convergence of IT and OT environments, along with the increasing adoption of smart infrastructure and connected industrial systems, is accelerating demand for integrated infrastructure protection technologies globally.
For instance, in 2025, the Cybersecurity and Infrastructure Security Agency (CISA) highlighted increasing cyber threats targeting critical infrastructure sectors such as energy, transportation, water utilities, and healthcare. According to CISA’s 2025 Year in Review, the agency blocked nearly 2.62 billion malicious connections across federal networks and 371 million malicious connections within critical infrastructure environments, while also conducting 148 cyber and physical security exercises involving over 10,000 participants. The agency emphasized the growing need for AI-enabled threat detection, continuous monitoring, and industrial cybersecurity frameworks to strengthen infrastructure resilience and reduce operational disruptions, thereby supporting the growth of the critical infrastructure protection market.
High deployment costs, integration complexities, and stringent regulatory requirements are emerging as major restraints for the critical infrastructure protection market. Critical infrastructure environments often rely on legacy operational technology systems that are difficult to modernize and integrate with advanced cybersecurity and monitoring platforms. This creates challenges related to interoperability, scalability, operational downtime, and system compatibility during deployment.
In addition, concerns regarding data privacy, cross-border data sharing restrictions, and compliance with evolving cybersecurity regulations are limiting adoption across several industries and regions. Infrastructure operators must comply with multiple standards and frameworks related to industrial cybersecurity, safety, and national security, increasing operational and compliance burdens.
For instance, in 2025, several European infrastructure operators and cybersecurity agencies highlighted growing compliance challenges under the European Union NIS2 Directive, particularly around incident reporting, supply chain risk management, and governance requirements for critical sectors. According to ENISA’s 2025 cybersecurity investment report, 76% of organizations faced difficulties attracting cybersecurity talent, while 71% struggled with retention, further increasing compliance burdens. These challenges are raising implementation costs and delaying infrastructure modernization projects, thereby restraining growth in the critical infrastructure protection market.
Market Concentration & Characteristics
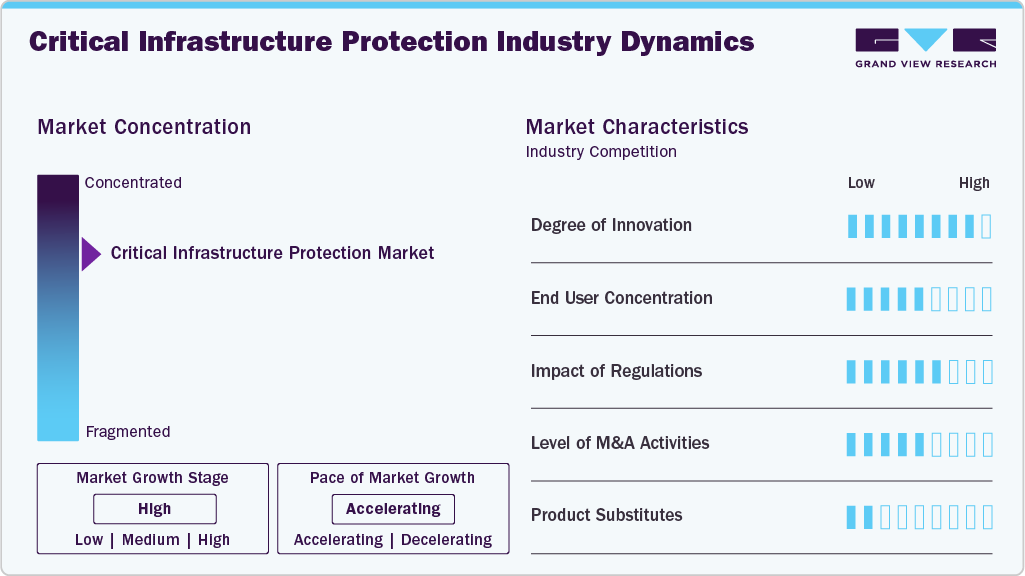
The critical infrastructure protection market is moderately concentrated, with the presence of major global cybersecurity, defense, industrial automation, and surveillance technology providers alongside specialized infrastructure security vendors. Leading companies maintain strong market positions through extensive technology portfolios, strategic government partnerships, and long-term contracts across sectors such as energy, transportation, utilities, telecommunications, defense, and public infrastructure. These players offer integrated solutions, including cybersecurity, physical security, access control, video surveillance, threat intelligence, industrial control system (ICS) security, and incident response platforms, creating high barriers to entry due to strict regulatory requirements, national security concerns, and complex procurement processes.
 To learn more about this report, Download Free Sample Report
In terms of market characteristics, the industry is highly technology-intensive and driven by continuous innovation in artificial intelligence, cloud-based security platforms, IoT security, predictive analytics, and real-time threat monitoring. Rising cyberattacks on critical infrastructure assets, increasing geopolitical tensions, and growing investments in smart infrastructure modernization are major demand drivers. Additionally, the market is characterized by high compliance standards, lengthy deployment cycles, and strong vendor dependency, as organizations prioritize reliability, interoperability, and long-term operational security for mission-critical infrastructure environments.
Type Insights
The solution segment dominated the market with a revenue share of 72.1% in 2025. The growth of this segment is attributed to the rising digitization across different private and government organizations in multiple industries, growing dependability on computing technology, and inclination towards the installation of robust protection solutions to avoid future threats of cybercrimes and data breaches. The need for software and hardware solutions is rising as it provides a holistic approach to securing critical infrastructure and effectively safeguarding against cyber threats. This segment helps users in addressing diverse cybersecurity requirements.
The services segment is projected to be the fastest-growing segment from 2026 to 2033. The increase in demand for infrastructure security and services is providing a combination of information, disaster recovery, and physical infrastructure protection with cyber and incident management to ensure resilience to cyber threats. The service segment ensures prevention, response, preparedness, and recovery from cyber fraud. These factors have contributed to the growth of this segment in recent years.
Security Insights
The physical safety and security segment dominated the market in 2025. The growing occurrence of cyber frauds and attacks primarily drives the growth of this segment. Frauds and crimes committed through modern infrastructures have developed an increasing need for physical safety and security of multiple related dynamics. This segment includes physical identity and access control systems, perimeter intrusion detection systems, video surveillance systems, and screening and scanning. The physical safety and security solution protects property and people from threats and ensures that critical infrastructures function uninterruptedly.
The cybersecurity segment is projected to be the fastest-growing segment from 2026 to 2033. This segment is divided into encryption, network access controls and firewalls, threat intelligence, and others. The increase in smart devices with IoT and advanced technologies has amplified the risk of cyber threats. The critical infrastructures include banking & finance, defense & national security, healthcare, water, food & grocery products and distribution networks, data & cloud, space technology, transport, communication, and others. Innovations like AI, big data analytics, and machine learning have played a crucial role in the growth of this segment in recent years.
End-use Insights
The BFSI segment dominated the market in 2025. In recent years, multiple cyberattacks and data breaches related to stock exchanges, private organizations, insurance agencies, financial trusts, banks, and cryptocurrency platforms have been recorded worldwide. The economic expansion, which involves innovation such as financial inclusion initiatives, payment banks, and fintech advancements, has accelerated the credit cycles and economic development linked to each other. This segment makes it convenient for users to purchase and install critical infrastructure protection in their businesses. Cyber or physical attacks on critical infrastructures related to banking, finance services, and insurance could cripple communities and nations. This has led to an inevitable need for enhanced security solutions and protocols in this sector.
 To learn more about this report, Download Free Sample Report
The oil & gas segment is projected to be the fastest-growing segment from 2026 to 2033. Oil and gas activities, such as refining, drilling, and distribution, are complex and widespread, often covering large geographic areas. These tasks depend on advanced operational technology (OT) systems to streamline control machinery and guarantee efficient resource management and procedures. The vulnerability of sites and operations related to the oil and gas industry to physical as well as cyber-attacks has developed the need for developing protection solutions for the prevention of damaging incidences. High susceptibility to exploitation, the interdependent nature of operations, a lack of skilled professionals in terms of cybersecurity, rising cases of intrusion, and the growing need for security and monitoring are expected to drive an upsurge in demand for critical infrastructure protection solutions in the oil and gas industry during the forecast period.
Regional Insights
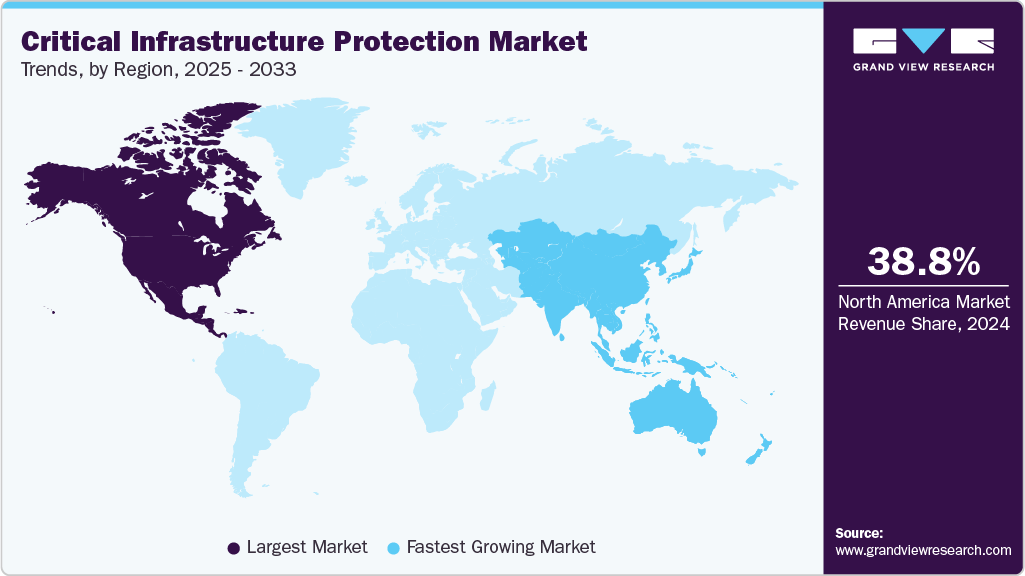
North America critical infrastructure protection market dominated the global industry with a revenue share of 38.6% in 2025. Multiple attempts to gain access to control systems and critical infrastructure networks related to different industries in the region, such as food & agriculture, healthcare, oil & gas, water, and wastewater management, are expected to lead to an increase in demand for this regional market in the approaching years. The history of cyberattacks on critical infrastructure networks related to countries such as the U.S. and Canada has encouraged nations and businesses to adopt or develop effective critical infrastructure protection solutions.
 To learn more about this report, Download Free Sample Report
U.S. Critical Infrastructure Protection Market Trends
The U.S. critical infrastructure protection industry is projected to grow during the forecast period. The emphasis on public-private partnerships as a national strategy is propelling the growth of the market. The U.S. government recognizes that nearly 85% of critical infrastructure is privately owned and has launched initiatives to enhance collaboration, intelligence sharing, and coordinated response among federal agencies, private companies, and technology vendors. Programs such as the National Risk Management Center (NRMC) and sector-specific Information Sharing and Analysis Centers (ISACs) are playing a central role in aligning standards, sharing real-time threat information, and driving adoption of best practices.
Asia Pacific Critical Infrastructure Protection Market Trends
The Asia Pacific critical infrastructure protection industry is expected to be the fastest growing over the forecast period. The rapid expansion of manufacturing and industrial automation in the Asia Pacific is driving market growth. As the region cements its position as the global manufacturing hub, particularly for electronics, automotive, pharmaceuticals, and heavy machinery, there is an urgent need to secure supply chains, production lines, and logistics networks. The use of robotics, cloud-connected sensors, and predictive analytics in factories enhances efficiency but also introduces multiple entry points for cyber threats. To mitigate these risks, industrial firms are investing in security frameworks that offer real-time monitoring, anomaly detection, secure firmware updates, and endpoint protection across all industrial assets.
The critical infrastructure protection industry in India is projected to grow during the forecast period. Increasing digital transformation activities by the public and private sector companies, unprecedented growth in online transactions, increasing adoption of smartphone technology, alignment of multiple departments of government authority with the Digital India initiative implemented by the Government in the country, and a growing threat of cyberattacks are anticipated to drive growth for this market.
Europe Critical Infrastructure Protection Trends
The critical infrastructure protection industry in Europe is expected to grow during the forecast period. The growth of this market is primarily influenced by the growing digital transformational activities adopted by the business and authorities in the region. According to the Council of the EU and the European Council, ransomware attacks and distributed denial of service (DDoS) have troubled Europe in recent years. The region experiences nearly 10 terabytes of data theft every month.
The critical infrastructure protection industry in the UK is growing during the forecast period. This is attributed to multiple factors such as growing digitization trends, increasing dependence of critical infrastructures on computing and network technologies, a growing number of cyberattack incidences related to private organizations, the BFSI sector, and the telecommunication industry. The history of cybercrimes and identified potential threats has encouraged authorities and businesses to increase investments in critical infrastructure protection services and solutions.
Key Critical Infrastructure Protection Company Insights
BAE Systems, Lockheed Martin Corporation, among others are some of the leading participants in the critical infrastructure protection industry.
-
BAE Systems is a multinational company specializing in defense, aerospace, and security. Within its broader architecture, BAE Systems maintains a specialized division, BAE Systems Applied Intelligence, rebranded as BAE Systems Digital Intelligence, that focuses on safeguarding critical infrastructure and mission-critical systems. This unit delivers a full suite of cyber and technological solutions, including threat intelligence, incident response, managed detection, and industrial control-system protection.
-
Lockheed Martin Corporation is a preeminent aerospace, defense, and security organization. Within the critical infrastructure protection, Lockheed Martin plays a critical role by blending cutting-edge cyber technologies, battle-management systems, and industrial-control solutions. Its Rotary and Mission Systems division offers advanced C4ISR capabilities, including radar sensors and communication networks vital for maintaining situational awareness across military, energy, and transportation grids.
Module X Solutions and OPSWAT Inc. are some of the emerging market participants in the critical infrastructure protection industry.
-
Module X Solutions is a privately held engineering and manufacturing firm specializing in modular protective structures for critical infrastructure. The company designs, engineers, and installs modular systems capable of safeguarding key government, utility, and defense sector facilities. These units are specifically built to withstand a wide range of threats, including explosions, ballistic attacks, electromagnetic interference, forced entry, fires, and chemical releases, making them suitable for sensitive environments like command centers, SCIFs, and secure telecommunication hubs.
-
OPSWAT Inc. is a cybersecurity firm. It specializes in protecting critical infrastructure through solutions tailored to both IT and operational technology (OT) environments. OPSWAT’s offerings include two major platforms: MetaDefender, which secures file transfers by dissecting and rebuilding content to remove threats, and MetaAccess, which governs device access via posture checks and vulnerability assessments. Together, they enable secure workflows for email, file sharing, cloud uploads, removable media, and remote devices, crucial for organizations with air-gapped or hybrid IT/OT systems.
Key Critical Infrastructure Protection Companies:
The following key companies have been profiled for this study on the critical infrastructure protection market
- BAE Systems
- Lockheed Martin Corporation
- Honeywell International Inc.
- Thales
- Raytheon Technologies Corporation
- Airbus
- Booz Allen Hamilton Inc.
- Hexagon AB
- TYCO International
- General Dynamics Corporation
- Johnson Controls Inc.
- Axis Communications AB
- Module X Solutions
- Exiger
- OPSWAT Inc.
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weakness
Mature Players: BAE Systems; Lockheed Martin Corporation; Thales; Honeywell International Inc.; Raytheon Technologies Corporation
- Expanding integrated cybersecurity, surveillance, and OT security platforms for critical infrastructure sectors.
- Investing in AI-driven threat detection, industrial cybersecurity, and cloud-based infrastructure monitoring solutions.
- Strong long-term contracts and trusted relationships with governments, defense agencies, and infrastructure operators.
- Broad end-to-end portfolios covering physical security, cybersecurity, industrial automation, and secure communications.
- Legacy systems are often costly and complex to modernize or migrate to cloud-native environments.
- Large organizational structures can slow innovation and responsiveness to emerging cyber threats.
Emerging Players: Module X Solutions; OPSWAT Inc.; TYCO International; Exiger
- Focusing on niche areas such as OT cybersecurity, AI-powered threat analytics, and supply chain risk management.
- Developing lightweight and API-driven platforms that integrate easily with legacy industrial systems.
- Faster deployment of innovative technologies and greater flexibility in addressing evolving infrastructure security needs.
- Strong specialization in targeted areas such as industrial malware protection, compliance, and predictive threat intelligence.
- Limited global presence and smaller support networks compared to established market leaders.
- Dependence on partnerships and integrations to deliver complete end-to-end infrastructure protection solutions..
Recent Developments
-
In July 2025, Booz Allen Hamilton announced a strategic investment in Corsha through its corporate venture capital arm, Booz Allen Ventures. This investment aims to accelerate the adoption of cutting-edge technologies to strengthen U.S. defenses against the growing frequency and sophistication of cyberattacks. Corsha employs advanced behavioral analytics to identify unusual activity and detect potential threats, effectively preventing adversaries from gaining access to American operational technology (OT), particularly within domestic defense manufacturing and other critical infrastructure sectors.
-
In May 2025, Honeywell International Inc. partnered with Nutanix to provide a modern, secure, and scalable infrastructure for Honeywell’s Integrated Control and Safety System (ICSS). This collaboration is designed to help organizations across critical industries accelerate their digital transformation while improving operational efficiency, strengthening cybersecurity, and boosting system resilience. Through this partnership, Honeywell will integrate Nutanix’s leading hybrid cloud platform with its Experion Process Knowledge System (PKS) and other advanced control technologies.
-
In November 2024, National Highways partnered with BAE Systems, allocating up to USD 21.8 million to implement a cyber-first, resilient approach across all major projects and programmes within the UK’s road network. Under the new three-year contract, BAE Systems will deliver support in key areas such as cybersecurity and data protection, information security analysis, and the delivery of cyber threat intelligence services.
Critical Infrastructure Protection Market Report Scope
Report Attribute
Details
Market size in 2025
USD 151.0 billion
Estimated market size in 2026
USD 156.9 billion
Projected market size by 2033
USD 229.1 billion
Growth rate
CAGR of 5.6% from 2026 to 2033
Actual data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company share, competitive landscape, growth factors, and trends
Segments covered
Type, security, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; China; India; Japan; Australia; South Korea; Brazil; UAE; Saudi Arabia; South Africa
Key companies profiled
BAE Systems; Lockheed Martin Corporation; Honeywell International Inc.; Thales; Raytheon Technologies Corporation; Airbus; Booz Allen Hamilton Inc.; Hexagon AB; TYCO International; General Dynamics Corporation; Johnson Controls Inc.; Axis Communications AB; Module X Solutions; Exiger; OPSWAT Inc.
Customization scope
Free report customization (equivalent to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Critical Infrastructure Protection Market Report Segmentation
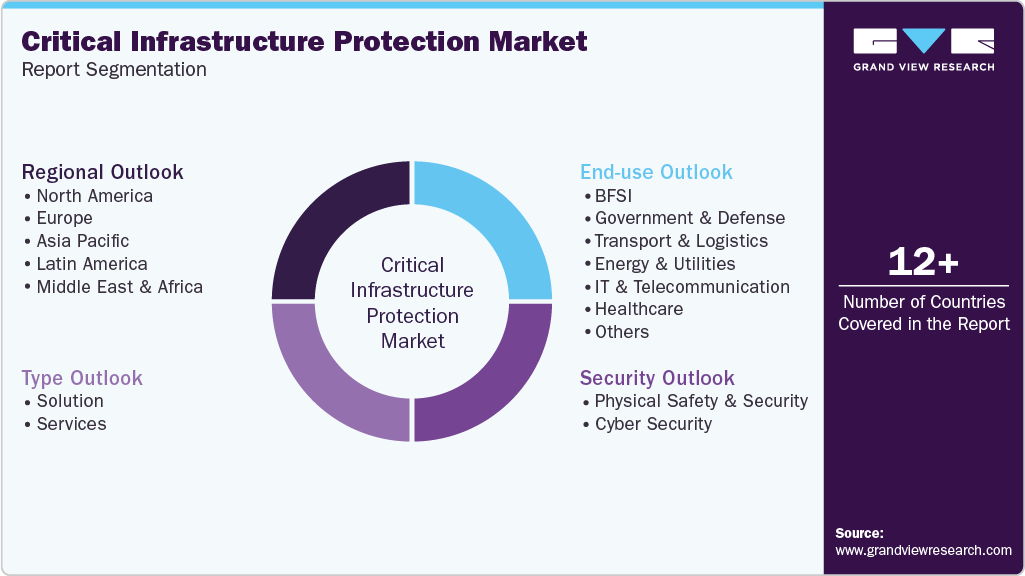
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global critical infrastructure protection market report based on type, security, end-use, and region.
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Solution
-
Services
-
-
Security Outlook (Revenue, USD Billion, 2021 - 2033)
-
Physical Safety and Security
-
Physical Identity and Access Control Systems
-
Perimeter Intrusion Detection Systems
-
Video Surveillance Systems
-
Screening and Scanning
-
Others
-
-
Cyber Security
-
Identity & Access Management (IAM)
-
Network Security
-
Risk & Compliance Management
-
Application Security
-
Endpoint Security
-
Security Information and Event Management (SIEM)
-
Cloud Security
-
Data Loss Prevention (DLP)
-
Web Security
-
Threat Intelligence & Incident Response
-
Encryption and Tokenization
-
Others
-
-
-
End-use Outlook (Revenue, USD Billion, 2021 - 2033)
-
BFSI
-
Government & Defense
-
Transport & Logistics
-
Energy and Utilities
-
IT & Telecommunication
-
Healthcare
-
Oil & Gas
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
UAE
-
Saudi Arabia
-
South Africa
-
-
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Critical infrastructure protection opportunity assessment for a cybersecurity and industrial security provider
- Assessment of infrastructure security demand across regions and critical sectors such as energy, utilities, transportation, telecom, and defense.
- Analysis of adoption trends for OT security, industrial cybersecurity, AI-enabled threat detection, surveillance systems, and critical asset monitoring platforms.
- Benchmarking of key vendors, solution capabilities, and deployment models.
- Identified high-growth infrastructure security segments and emerging technology opportunities.
- Supported product positioning, expansion planning, and competitive differentiation strategies.
- Highlighted key growth drivers, cybersecurity risks, and regulatory developments influencing market demand.
Customized cross-segmentation analysis for critical infrastructure protection by solution type and end user
- Conducted cross-segmentation analysis based on solution type and infrastructure sector.
- Evaluated categories such as industrial control system (ICS) security, access control, video surveillance, threat intelligence, and incident response platforms across energy, transportation, utilities, and government sectors.
- Identified high-adoption technologies driving infrastructure modernization and cyber resilience initiatives.
- Highlighted infrastructure sectors with the strongest demand for advanced protection solutions.
- Supported strategic understanding of technology penetration across critical infrastructure environments.
Critical infrastructure cybersecurity modernization and market entry assessment for a technology vendor
- Analysis of regional infrastructure security investments, cybersecurity mandates, and procurement trends.
- Evaluation of operator requirements for cloud-based monitoring, AI-driven analytics, OT security integration, and real-time threat intelligence sharing.
- Identified attractive regional market opportunities and infrastructure modernization trends.
- Supported with GTM, partnership, and infrastructure security expansion strategies.
- Enabled strategic entry into critical infrastructure, industrial cybersecurity, and national resilience markets.
Frequently Asked Questions About This Report
Some key players operating in the market include BAE Systems, Lockheed Martin Corporation, Honeywell International Inc., Thales, Raytheon Technologies Corporation, Airbus, Booz Allen Hamilton Inc., Hexagon AB, TYCO International, General Dynamics Corporation, Johnson Controls Inc., Axis Communications AB, Module X Solutions, Exiger, OPSWAT Inc.
Key factors include growing cyber insurance adoption and board-level focus on operational resilience are the key factors driving the market growth.
Asia Pacific is the fastest-growing region over the forecast period.
North America dominated with a 38.6% revenue share in 2025.
The global critical infrastructure protection market size was estimated at USD 151.0 billion in 2025 and is expected to reach USD 156.9 billion in 2026.
The global critical infrastructure protection market is expected to grow at a compound annual growth rate of 5.6% from 2026 to 2033 to reach USD 229.1 billion by 2033.
The solution segment segment led with a72.1% revenue share in 2025, while services is the fastest-growing segment.
The physical safety and security segment dominated the market in 2025, while cybersecurity is the fastest-growing segment.
The BFSI segment dominated the market in 2025, while oil & gas is the fastest-growing segment.
About the Author(s)
Network Security Research Team
Technology · Network SecurityThis report was authored by the network security research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the network security segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


