
- Home
- »
- Semiconductors
- »
-
DC Circuit Breaker Market Size Report, 2026-2033GVR Report cover

DC Circuit Breaker Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Solid State, Hybrid), By Insulation, By Voltage (Low Voltage, Medium Voltage, High Voltage), By End-use, By Region, And Segment Forecasts
Market Size, 2025
$4.7BMarket Estimate, 2026
$5.0BMarket Forecast, 2033
$10.9BCAGR, 2026–2033
11.8%DC Circuit Breaker Market Summary
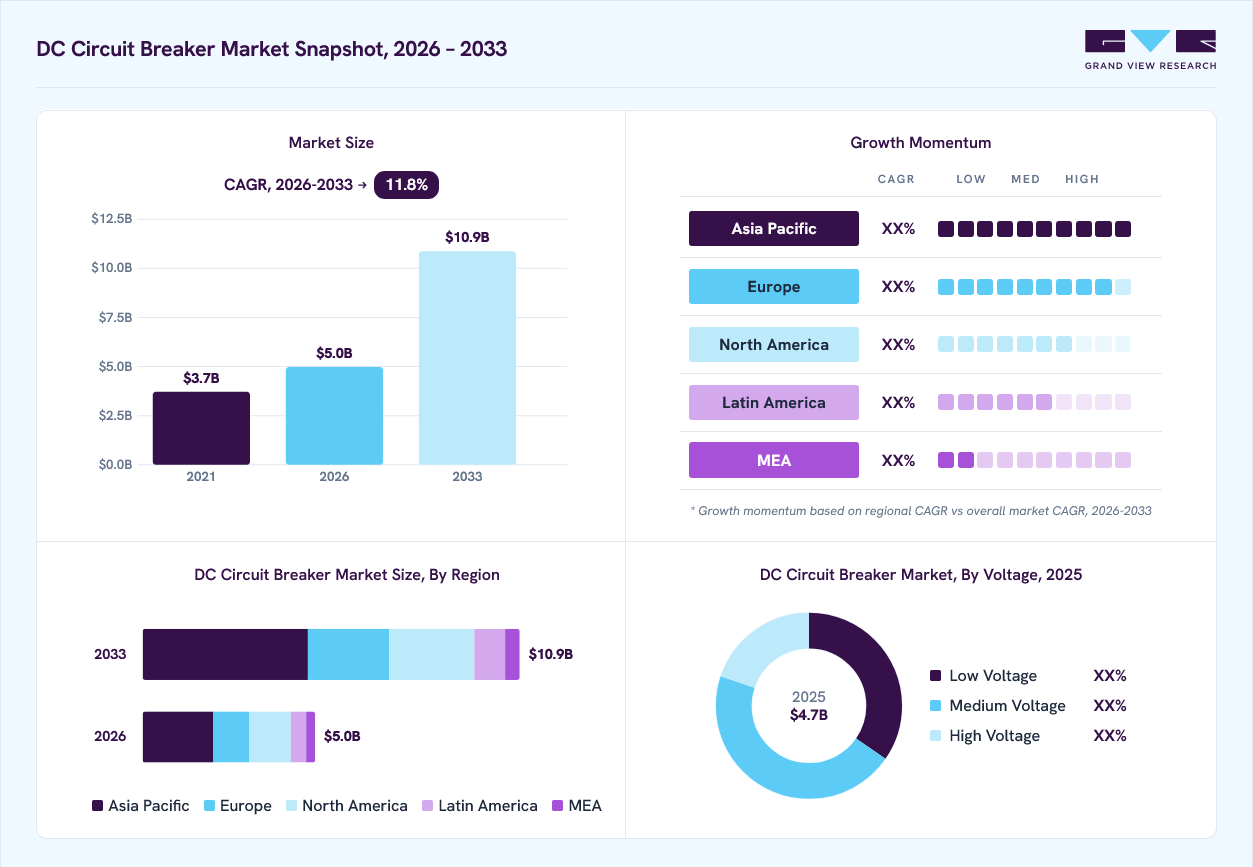
The global DC circuit breaker market size was valued at USD 4.7 billion in 2025 and is projected to grow from USD 5.0 billion in 2026 to USD 10.9 billion by 2033, at a CAGR of 11.8% from 2026 to 2033. Asia Pacific dominated the global market with the largest revenue share of 40.6% in 2025. The market is experiencing significant growth driven by several key trends and drivers.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Solid State segment dominated the market, with a revenue share of 53.2% in 2025
- By insulation: Vacuum segment accounted for the largest revenue share of 58.4% in 2025.
- By voltage: Medium voltage segment accounted for the largest revenue share of 45.4% in 2025.
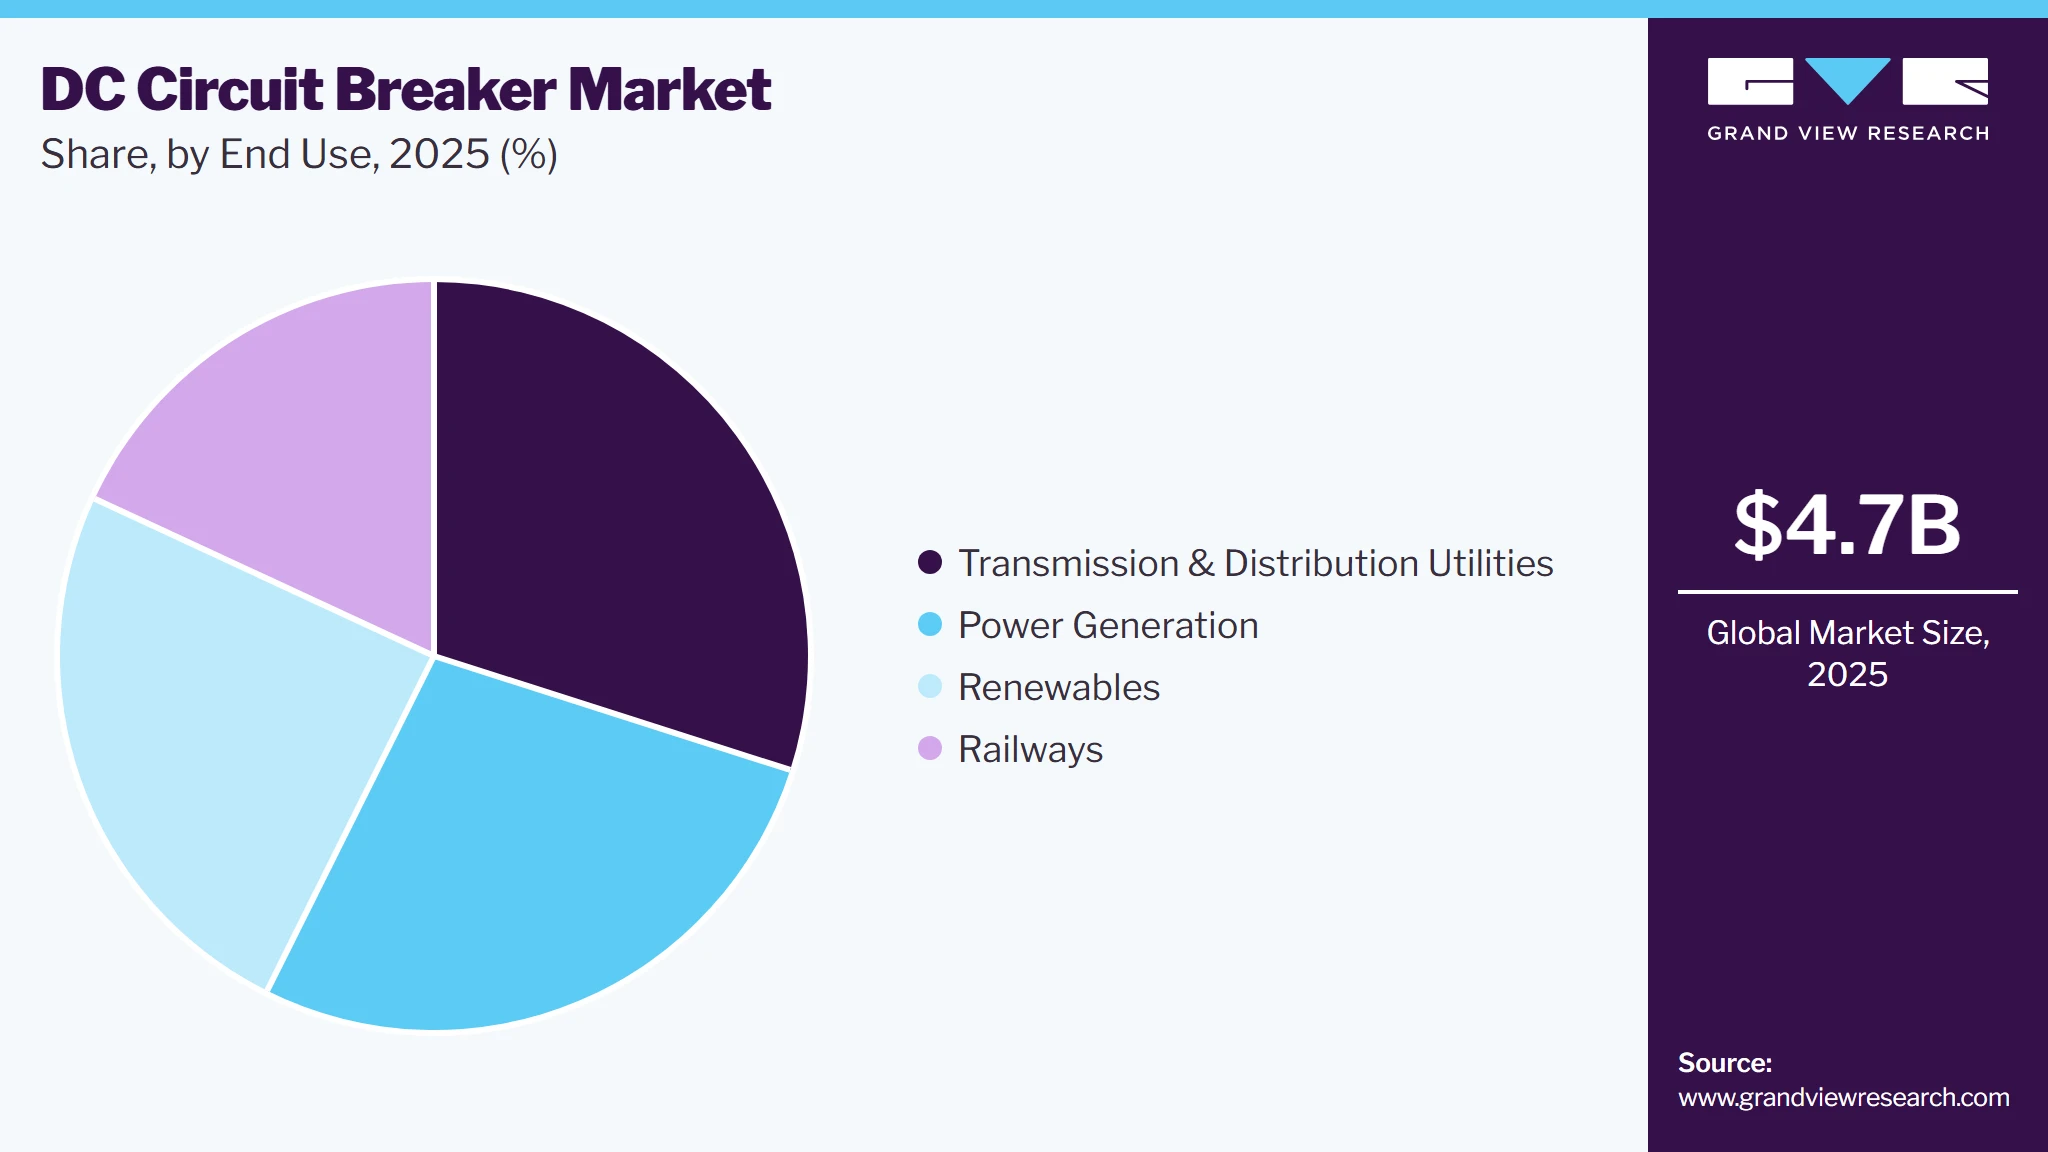
- By end use: Transmission & distribution utilities segment accounted for the largest revenue share of 29.9% in 2025.
Regional Highlights
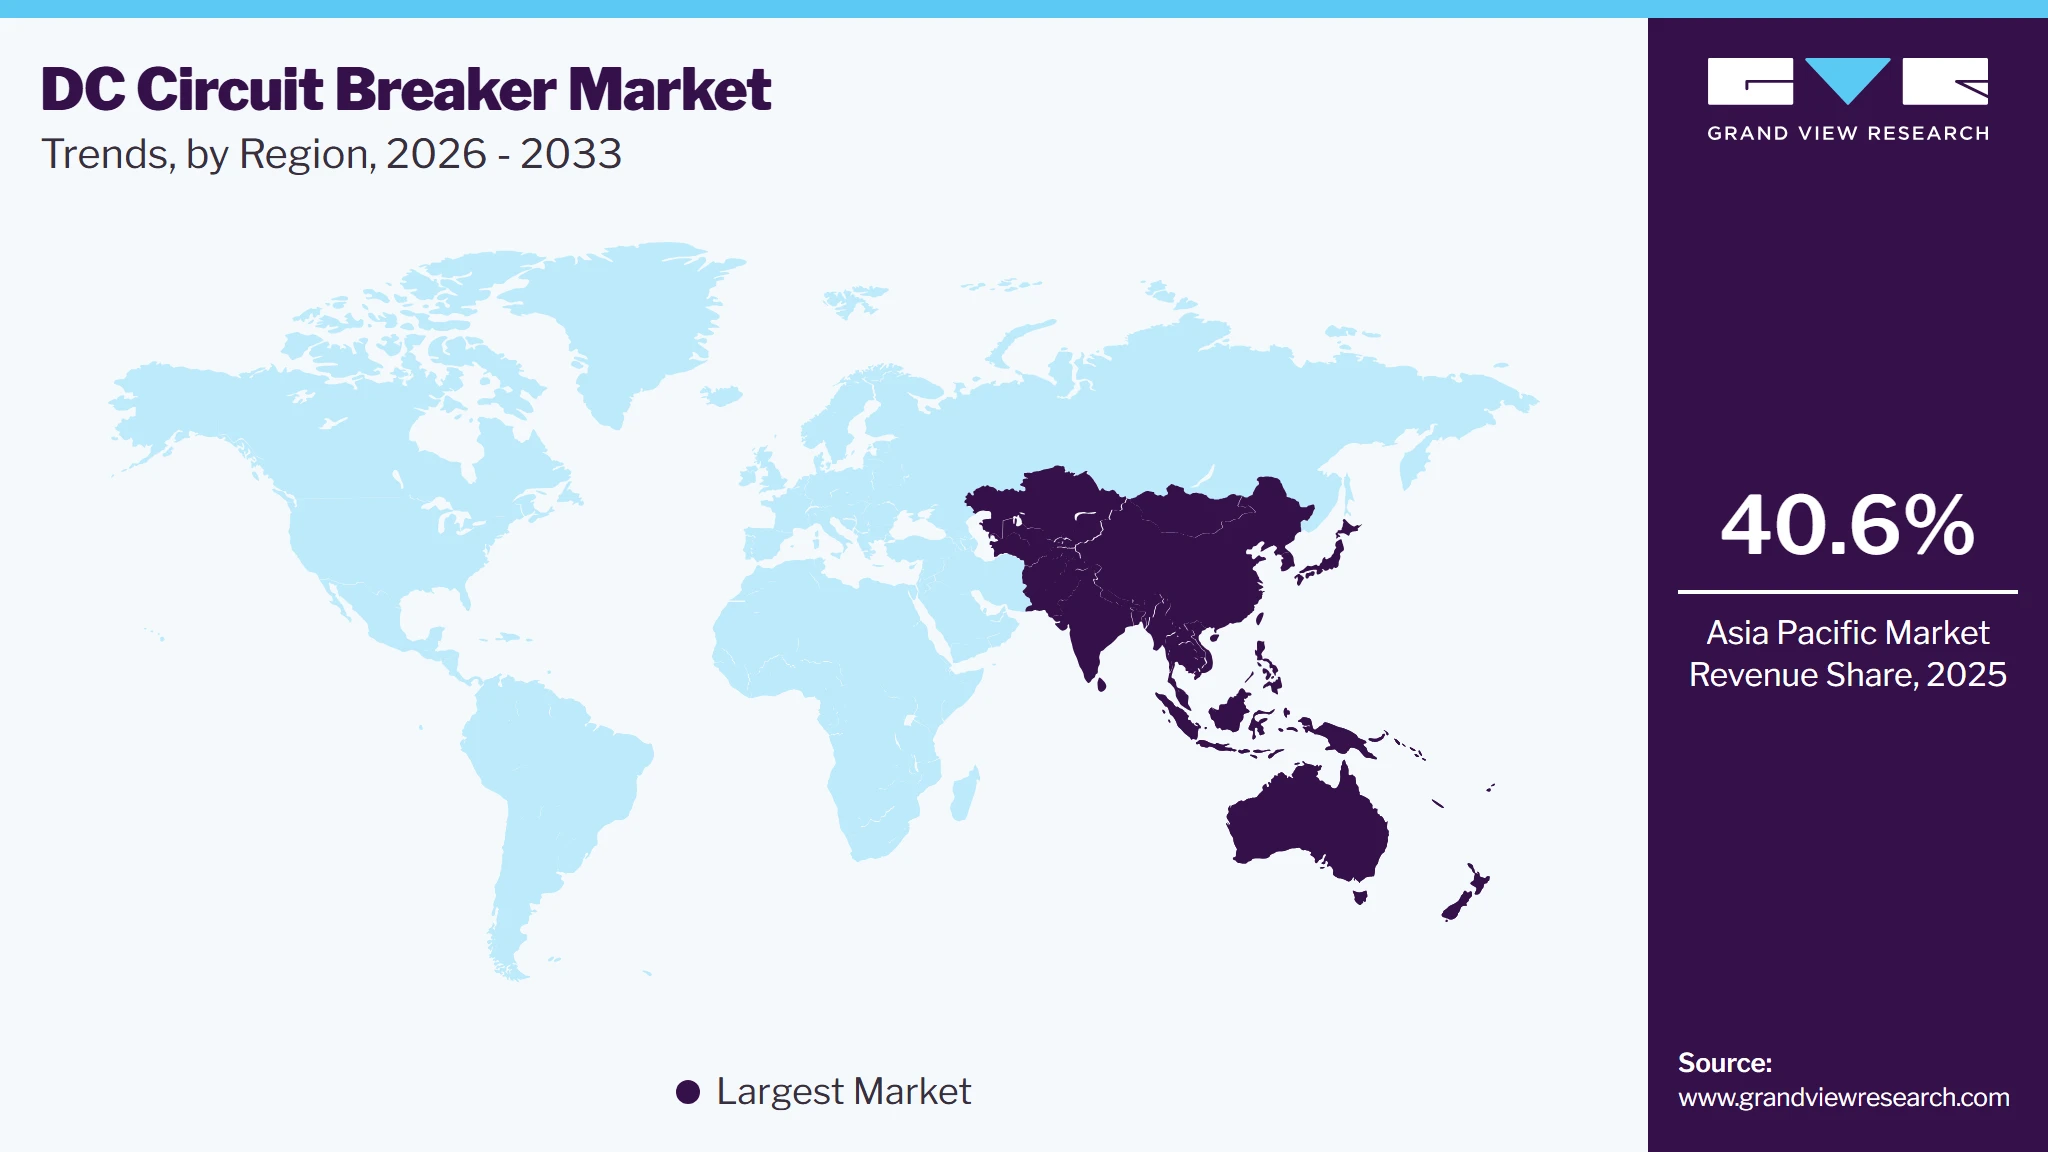
- Largest regional market: Asia Pacific (40.6% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 4.7 Billion
- Estimated market size in 2026: USD 5.0 Billion
- Projected market size by 2033: USD 10.9 Billion
- CAGR (2026-2033): 11.8%
Prism AI by Grand View Research Free to tryAsk a question about the DC circuit breaker marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
One prominent trend is the increasing adoption of renewable energy sources, such as solar and wind power, which require efficient and reliable circuit protection. As countries worldwide strive to reduce carbon emissions and transition to sustainable energy systems, the deployment of DC circuit breakers is becoming crucial for integrating these renewable sources into the grid. Additionally, the rise of electric vehicles (EVs) and the expansion of EV charging infrastructure are creating a substantial demand for DC circuit breakers, which are essential for protecting charging stations and ensuring safe and efficient power distribution.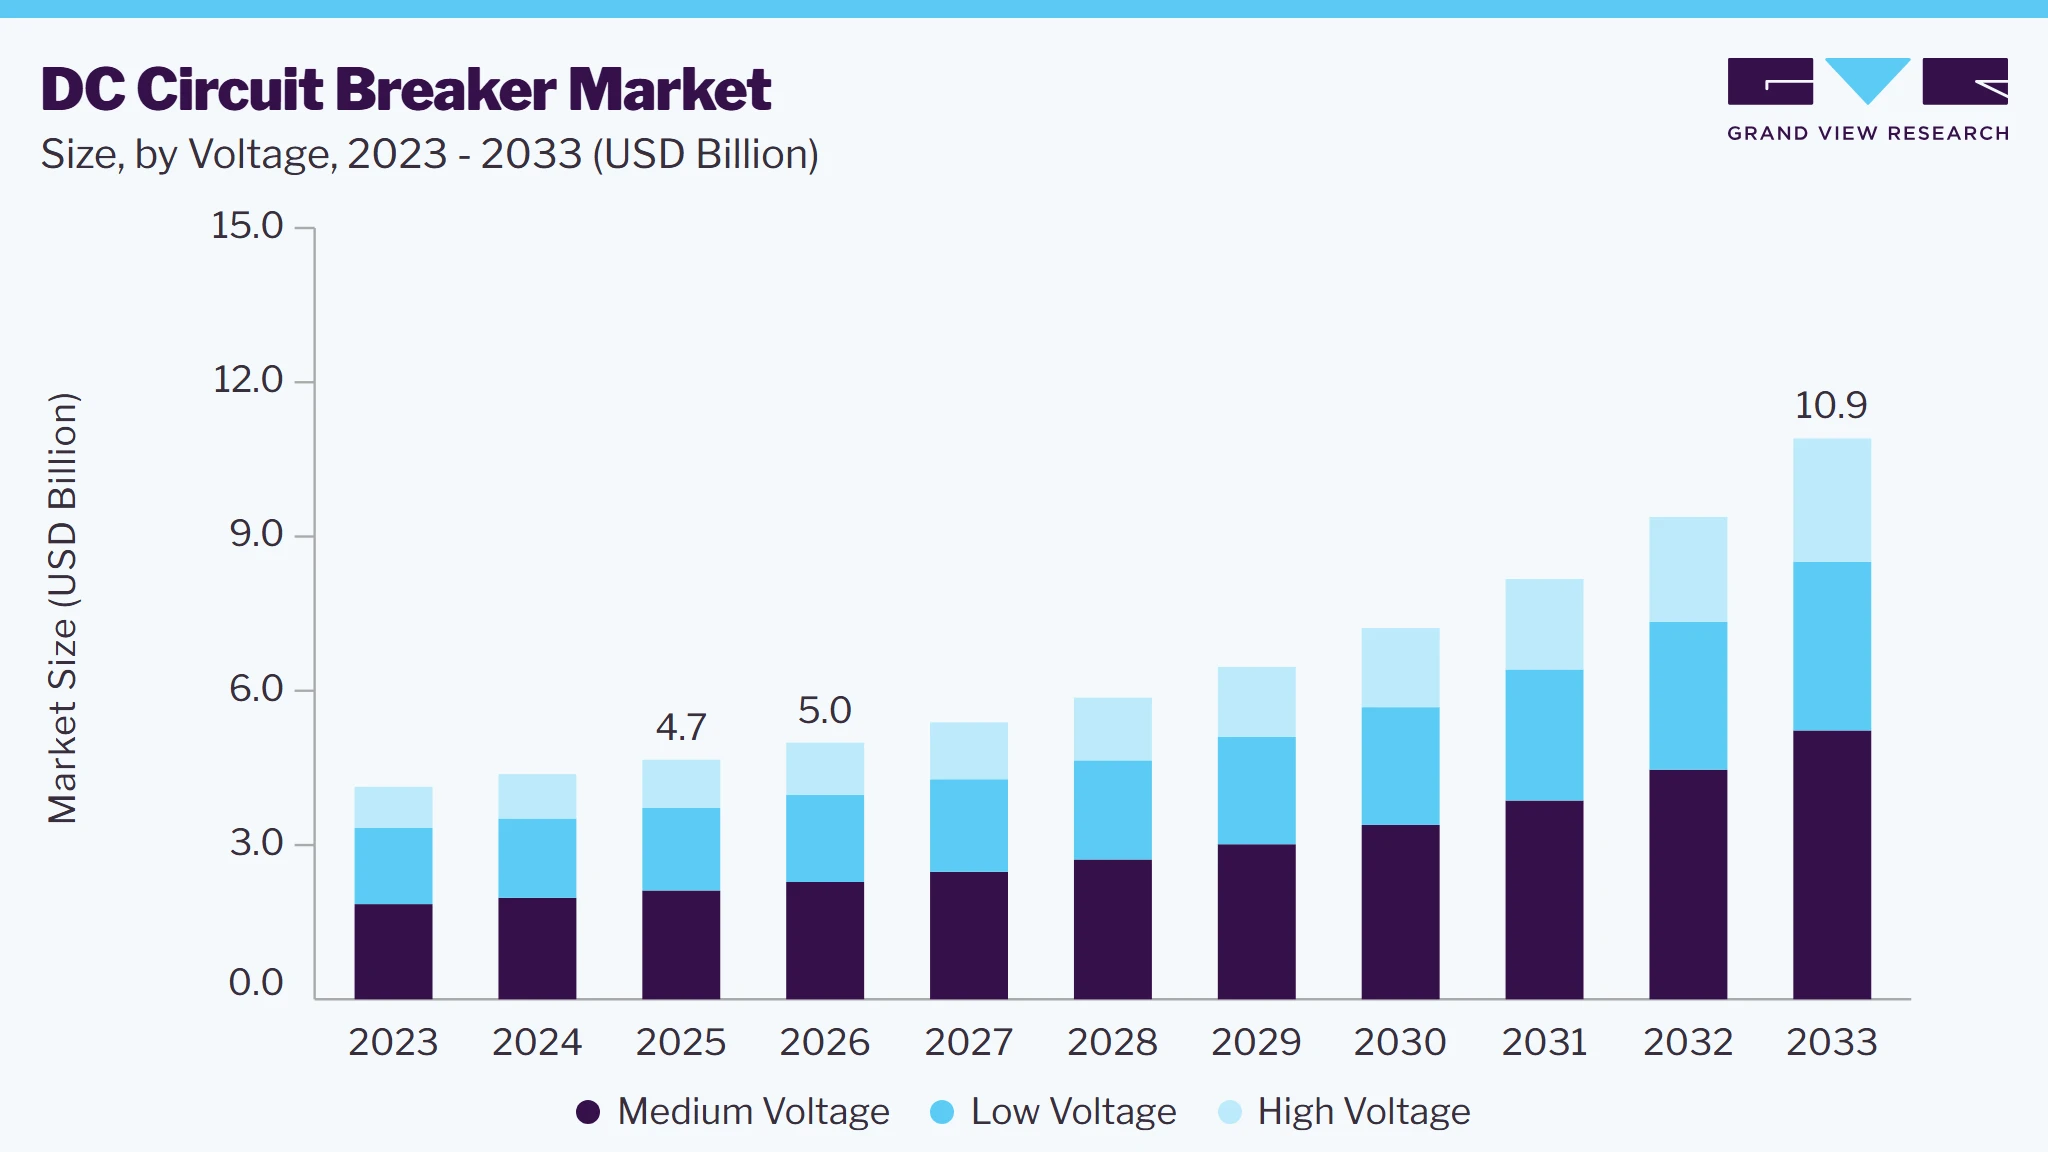 To learn more about this report, Download Free Sample Report
Market drivers include the ongoing modernization of aging power infrastructure and the implementation of smart grid technologies. These initiatives aim to enhance grid reliability, reduce transmission losses, and improve energy efficiency, thereby driving the demand for advanced DC circuit breakers. Moreover, the expansion of high voltage direct current (HVDC) transmission systems, which are essential for long-distance power transmission and integrating remote renewable energy sources, is significantly boosting the market. The increasing need for robust and efficient circuit protection in industrial applications and data centers further fuels market growth.
Market opportunities are abundant, particularly in emerging economies where rapid industrialization and urbanization are taking place. These regions are investing heavily in power infrastructure and renewable energy projects, creating a substantial demand for DC circuit breakers. Advancements in technology, such as the development of solid state and hybrid DC circuit breakers, are also opening new opportunities. These breakers offer superior performance, reliability, and efficiency, making them attractive for a wide range of applications. Furthermore, supportive government policies and incentives for renewable energy adoption and infrastructure development are expected to drive market growth.
Market Dynamics
The DC circuit breaker market is experiencing steady growth due to the rapid expansion of renewable energy systems, battery energy storage systems (BESS), electric vehicle charging infrastructure, rail electrification, and modern DC power distribution networks. Growing investments in grid modernization and the increasing deployment of high-voltage direct current (HVDC) transmission systems are driving demand for advanced protection devices capable of quickly and reliably interrupting DC faults. Moreover, technological advancements such as solid-state switching, hybrid breaker architecture, digital monitoring, and predictive maintenance are improving operational safety and system reliability. As utilities and industrial users increasingly adopt DC-based power systems, demand for high-performance DC circuit breakers continues to expand across multiple end-use sectors.
The increasing installation of battery energy storage systems and renewable energy plants has significantly increased the need for reliable DC protection equipment. Solar photovoltaic plants, utility-scale battery storage facilities, and microgrids operate primarily on DC power, in which fault currents behave differently from those in conventional AC systems and are more difficult to interrupt due to the absence of natural current zero crossings. As countries continue investing in renewable energy integration and grid decarbonization, utilities require advanced protection technologies capable of maintaining system stability while minimizing equipment damage and operational downtime. DC circuit breakers directly address these protection challenges by providing rapid fault detection and interruption capabilities across various voltage levels. Modern hybrid and solid-state
DC circuit breakers reduce interruption times, improve grid reliability, and protect expensive assets such as battery storage systems, power converters, and HVDC transmission equipment. Their ability to isolate faults without affecting the overall network enhances power availability and operational efficiency. Consequently, rising investments in renewable energy infrastructure and energy storage deployments continue to create sustained demand for advanced DC circuit breaker solutions.
Advanced DC circuit breakers, particularly hybrid and solid-state designs, involve sophisticated power electronics, semiconductor components, high-speed sensors, and complex control systems. Compared with conventional AC breakers, these technologies require significantly higher manufacturing investment, specialized engineering expertise, and extensive testing to ensure reliable interruption under demanding operating conditions. The resulting higher procurement and installation costs create adoption challenges, particularly for projects with limited capital budgets.
The financial burden is more evident in developing economies where grid modernization programs progress gradually, and utilities remain highly cost sensitive. Small industrial facilities, commercial users, and regional power operators often continue relying on traditional protection solutions due to budget limitations. In addition, the lack of standardized DC protection practices in several markets increases engineering complexity and extends project implementation timelines. These factors collectively slow the adoption of advanced DC circuit breaker technologies despite their long-term operational benefits.
Growing investments in long-distance electricity transmission and cross-border power interconnections are creating substantial opportunities for DC circuit breaker manufacturers. Governments and utilities are increasingly deploying HVDC transmission systems to transport renewable electricity efficiently over long distances while minimizing transmission losses. Offshore wind integration, regional power trading, and large-scale renewable energy projects are further accelerating the deployment of multi-terminal HVDC grids, in which advanced DC fault protection is essential.
This evolving infrastructure creates strong growth opportunities for manufacturers offering high-voltage hybrid and solid-state DC circuit breakers capable of supporting complex HVDC networks. Companies with expertise in power electronics, digital grid protection, and intelligent monitoring systems are well positioned to benefit from utility investments. Vendors developing compact, faster-switching, and digitally integrated breaker technologies are expected to capture increasing demand as next-generation HVDC projects expand globally.
Analyst Perspective
The DC circuit breaker market is transitioning from a niche power protection segment to a critical component of modern DC power infrastructure. Rising investments in renewable energy, battery energy storage, EV charging networks, and HVDC transmission projects continue to strengthen long-term market fundamentals. Technological innovation is shifting the industry toward hybrid and solid-state breakers that offer faster interruption speeds, improved digital monitoring, and enhanced operational reliability. Manufacturers are increasingly investing in intelligent protection platforms, advanced semiconductor technologies, and grid automation capabilities to differentiate their product portfolios. Over the coming years, strategic partnerships with utilities, renewable developers, and transmission operators are expected to shape competitive positioning as demand for high-performance DC protection solutions continues to expand.
Type Insights
Based on type, the solid state segment led the market with the largest revenue share of 53.2% in 2025 and accounted for a more than 56% share of global revenue. This is due to their balanced combination of mechanical robustness and electronic efficiency. These breakers incorporate both mechanical and solid-state elements, offering the best of both worlds: the high-speed interruption capabilities of solid-state devices and the durability and reliability of mechanical systems. This hybrid approach makes them ideal for a wide range of applications, including transportation, power distribution, and industrial systems, where both reliability and performance are critical.
The ongoing expansion of renewable energy projects and the modernization of power grids further boost the demand for hybrid DC circuit breakers. Their ability to handle high power levels and provide fast, reliable switching makes them essential for integrating renewable energy sources and ensuring grid stability. Moreover, advancements in hybrid technology are continually improving their performance, efficiency, and cost-effectiveness, reinforcing their dominance in the market. The versatility and adaptability of hybrid DC circuit breakers make them a preferred choice for many industries, ensuring their continued leadership in the market.
The solid-state DC circuit breaker segment is projected to witness high CAGR from 2024 to 2030. Solid state DC circuit breakers are witnessing rapid growth due to their superior efficiency, reliability, and quick switching capabilities. These breakers use semiconductor devices to interrupt the current flow, eliminating the mechanical wear and tear associated with traditional mechanical breakers. This characteristic makes them particularly suitable for applications requiring frequent switching and high-speed operation, such as renewable energy systems, data centers, and electric vehicles. The increasing deployment of smart grids and advanced power distribution networks also drives the demand for solid state DC circuit breakers.
As power systems become more complex and distributed, the need for precise and reliable control grows, further propelling the adoption of solid-state technology. Additionally, ongoing advancements in semiconductor materials and technology are expected to enhance the performance and reduce the costs of these breakers, making them more accessible for various applications. The trend towards electrification and digitalization in multiple sectors underscores the significant growth potential of solid-state DC circuit breakers, positioning them as a key component in the evolving energy landscape.
Insulation Insights
Based on insulation, the vacuum segment led the market with the largest revenue share of 58.4% in 2025 due to their high reliability, efficiency, and ability to operate in harsh environments. These breakers use a vacuum as the insulating medium, which provides excellent arc-quenching capabilities and minimal maintenance requirements. Vacuum insulation is particularly advantageous in high-voltage applications, where the efficient interruption of high currents is critical. This makes vacuum-insulated DC circuit breakers a preferred choice for power generation, industrial applications, and transmission and distribution utilities.
The increasing adoption of renewable energy sources and the expansion of smart grid technologies further drive the demand for vacuum-insulated breakers. As power systems become more decentralized and complex, the need for reliable and efficient circuit protection grows, reinforcing the dominance of vacuum-insulated DC circuit breakers. Additionally, ongoing advancements in vacuum technology are enhancing the performance and reducing the costs of these breakers, making them more attractive for a wider range of applications.
The gas-insulated DC circuit breakers are the fastest-growing segment in the DC Circuit Breaker market driven by their compact size, high insulation properties, and suitability for urban and offshore installations. These breakers use gas, typically sulfur hexafluoride (SF6), as the insulating medium, providing excellent dielectric strength and arc-quenching capabilities. The compact design of gas-insulated breakers makes them ideal for applications where space is limited, such as in densely populated urban areas and offshore platforms.
The increasing focus on renewable energy projects and the modernization of power grids drive the demand for gas-insulated DC circuit breakers. As more renewable energy sources are integrated into the grid, the need for reliable and efficient circuit protection grows, boosting the adoption of gas-insulated technology. Moreover, advancements in gas insulation technology are enhancing the performance and environmental impact of these breakers, further supporting their growth. The trend towards urbanization and the expansion of offshore energy projects underscores the significant growth potential of gas-insulated DC circuit breakers.
Voltage Insights
Based on voltage, the medium voltage segment led the market with the largest revenue share of 45.4% in 2025 due to their widespread use in power distribution and industrial applications. These breakers are essential for managing and protecting electrical systems in utilities, manufacturing plants, and large commercial facilities. The growth of smart grid technologies and the increasing deployment of renewable energy sources drive the demand for medium voltage DC circuit breakers. These breakers provide reliable and efficient interruption of current, ensuring the stability and safety of electrical systems.
The modernization of aging infrastructure and the expansion of power distribution networks further boost the adoption of medium voltage breakers. Additionally, advancements in medium voltage technology are enhancing the performance, efficiency, and cost-effectiveness of these breakers, making them more attractive for a wide range of applications. The critical role of medium voltage DC circuit breakers in ensuring reliable power distribution and protecting electrical systems underpins their dominant position in the market.
The high voltage DC circuit breakers segment is experiencing significant growth in the DC Circuit Breaker market due to the increasing deployment of high voltage direct current (HVDC) transmission systems. These breakers are essential for managing and protecting HVDC networks, which are crucial for long-distance power transmission and integrating renewable energy sources into the grid. The rapid expansion of renewable energy projects, such as offshore wind farms and large solar installations, drives the demand for high voltage DC circuit breakers.
These breakers provide reliable and efficient interruption of high currents, ensuring the stability and safety of HVDC systems. The ongoing investments in HVDC infrastructure and the modernization of power grids further boost the adoption of high voltage DC circuit breakers. Additionally, advancements in high voltage technology are enhancing the performance, efficiency, and cost-effectiveness of these breakers, making them more attractive for a wider range of applications. The critical role of high voltage DC circuit breakers in supporting the growth of renewable energy and ensuring the reliability of HVDC networks underscores their significant growth potential.
End-use Insights
Based on end use, the transmission & distribution utilities segment led the market with the largest revenue share of 29.9% in 2025 due to the critical need for reliable and efficient circuit protection in maintaining grid stability. These utilities rely on DC circuit breakers to manage and protect their power distribution networks, ensuring the continuous and safe delivery of electricity. The increasing adoption of renewable energy sources and the expansion of smart grid technologies drive the demand for DC circuit breakers in this segment.
 To learn more about this report, Download Free Sample Report
As power systems become more complex and decentralized, the need for advanced circuit protection solutions grows, reinforcing the dominance of transmission and distribution utilities in the market. The modernization of aging infrastructure and ongoing investments in grid expansion further boost the adoption of DC circuit breakers. Additionally, advancements in DC circuit breaker technology are enhancing their performance, efficiency, and cost-effectiveness, making them more attractive for transmission and distribution utilities.
The renewables segment is experiencing significant growth due to the global push towards sustainable energy sources. The increasing deployment of solar, wind, and other renewable energy systems drives the demand for reliable and efficient circuit protection. DC circuit breakers play a crucial role in managing and protecting the electrical systems of renewable energy installations, ensuring the safe and stable integration of these sources into the grid.
The ongoing investments in renewable energy projects and the expansion of green energy infrastructure further boost the adoption of DC circuit breakers in this segment. Additionally, advancements in DC circuit breaker technology are enhancing their performance and cost-effectiveness, making them more attractive for renewable energy applications. The growing focus on sustainability and the transition towards a low-carbon energy system underscore the significant growth potential of the renewables segment.
Regional Insights
The DC Circuit Breaker market in North America is expected to hold a prominent position in the DC Circuit Breaker market driven by substantial investments in smart grid technologies and renewable energy projects. The region's focus on upgrading aging infrastructure and integrating advanced power distribution systems fuels market growth. The United States, in particular, plays a crucial role with its ongoing investments in HVDC transmission systems and renewable energy integration. The increasing adoption of electric vehicles and the expansion of data centers also drive the demand for DC circuit breakers in North America. Moreover, advancements in DC circuit breaker technology are enhancing the performance and cost-effectiveness of these solutions, making them more attractive for various applications. The region's commitment to sustainability and the transition towards a low-carbon energy system further support the market growth.
U.S. DC Circuit Breaker Market Trends
The DC circuit breaker market in the U.S. is expected to grow at a significant CAGR from 2024 to 2030 and is characterized by substantial investments in upgrading the aging power infrastructure and expanding renewable energy projects. The country's focus on enhancing grid reliability and integrating more renewable energy sources drives the demand for advanced DC circuit breakers. The increasing adoption of electric vehicles and the expansion of EV charging infrastructure also contribute significantly to market growth. Moreover, the U.S. is investing heavily in smart grid technologies and HVDC transmission systems to improve the efficiency and reliability of its power distribution network. These factors, combined with ongoing technological advancements in DC circuit breakers, enhance their performance and cost-effectiveness, making them more attractive for a wide range of applications. The U.S. market's commitment to sustainability and reducing carbon emissions further supports the market growth.
Asia Pacific DC Circuit Breaker Market Trends
Asia Pacific dominated the global DC circuit breaker market with the largest revenue share of 40.6% in 2025, driven by the rapid industrialization, urbanization, and significant investments in renewable energy and HVDC projects. Countries like China, India, and Japan are key contributors, with substantial investments in power infrastructure and renewable energy integration. The region's focus on expanding and modernizing its power grid to meet the growing energy demand fuels the adoption of DC circuit breakers. The increasing deployment of renewable energy systems and the expansion of electric vehicle charging infrastructure further boost market growth. Additionally, advancements in DC circuit breaker technology are enhancing their performance, efficiency, and cost-effectiveness, making them more attractive for a wide range of applications. The region's commitment to sustainability and the transition towards a low carbon energy system underscores the significant growth potential of the market in Asia Pacific.
 To learn more about this report, Download Free Sample Report
China DC Circuit Breaker Market Trends
The DC circuit breaker market in the China held the largest share in the Asia Pacific region in 2025.
Europe DC Circuit Breaker Market Trends
The DC circuit breaker market in Europe is characterized by stringent environmental regulations and a strong commitment to renewable energy. The region's extensive HVDC projects and smart grid initiatives drive the demand for DC circuit breakers. Countries like Germany, France, and the United Kingdom are key contributors, with significant investments in renewable energy and grid modernization. The increasing focus on integrating renewable energy sources into the grid and enhancing grid stability further boosts the adoption of DC circuit breakers. Additionally, advancements in DC circuit breaker technology are improving their performance, efficiency, and environmental impact, making them more attractive for various applications. The region's emphasis on sustainability and energy efficiency underscores the significant growth potential of the market in Europe.
Key DC Circuit Breaker Company Insights
Key players operating in the DC Circuit Breaker market are focusing on various strategic initiatives, including new product development, partnerships & collaborations, and agreements to gain a competitive advantage over their rivals. The following are some instances of such initiatives.
-
In February 2023, Mitsubishi Electric Corporation has completed the acquisition of Scibreak AB, a Swedish company that provides direct current circuit breakers (DCCBs). This strategic acquisition is intended to boost the competitive advantage of both companies by jointly advancing DCCB technologies for high-voltage direct current (HVDC) systems, this collaboration aims to support the global shift towards renewable energy sources.
-
In September 2022, ABB has launched the SACE Infinitus, an advanced solid-state circuit breaker aimed at streamlining the integration, protection, and management of DC network architectures for a wide range of ships. According to ABB, SACE Infinitus is the first circuit breaker globally to be certified with IEC 60947-2 standards while incorporating semiconductor technology. Moreover, this innovative device will also come with DNV certification for low-voltage maritime applications.
Key DC Circuit Breaker Companies:
The following key companies have been profiled for this study on the DC circuit breaker market.
-
ABB Ltd
-
Larsen & Toubro Limited
-
Mitsubishi Electric Corporation
-
GEYA Electrical Co.
-
Entec Electric & Electronic Co Ltd
-
Hyundai Electric & Energy Systems Company
-
Rockwell Automation
-
Eaton Corporation PLC
-
Siemens AG
-
Nader Electrical
-
Fuji Electric Co Ltd
-
Powell Industries, Inc.
-
Schneider Electric SE
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (ABB Ltd, Siemens AG, Eaton Corporation PLC, Mitsubishi Electric Corporation)
- These companies focus on expanding DC protection portfolios for renewable energy, battery energy storage systems (BESS), EV charging infrastructure, industrial automation, and utility applications. They invest in advanced arc-extinguishing technologies, smart protection systems, and global distribution networks while strengthening partnerships with utilities, EPC contractors, and renewable energy developers.
- Strong global presence, extensive R&D capabilities, diversified electrical equipment portfolios, established customer relationships, and comprehensive after-sales support provide significant competitive advantages.
- Dependence on capital-intensive infrastructure projects, long procurement cycles, and fluctuations in raw material prices may affect profitability and project execution timelines.
Emerging Players (Larsen & Toubro Limited, Hyundai Electric & Energy Systems Company, GEYA Electrical Co.)
- These companies focus on cost-effective DC circuit protection products, expanding regional distribution channels, and developing solutions for solar PV systems, EV charging, industrial DC applications, and low-voltage DC networks. They emphasize product innovation, competitive pricing, and customized solutions for regional markets.
- Agile product development, competitive pricing, specialization in DC protection technologies, and the ability to address niche application requirements help these companies compete effectively.
- Compared to larger multinational manufacturers, these companies generally have smaller global market shares, lower brand recognition, and more limited financial resources for large-scale expansion and advanced product development.
DC Circuit Breaker Market Report Scope
Report Attribute
Details
Market size in 2025
USD 4.7 billion
Estimated market size in 2026
USD 5.0 billion
Projected market size by 2033
USD 10.9 billion
Growth rate
CAGR of 11.8% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company market share, competitive landscape, growth factors, and trends
Segments covered
Type, insulation, voltage, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; U.K.; France; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; UAE; and South Africa
Key companies profiled
ABB Ltd; Larsen & Toubro Limited; Mitsubishi Electric Corporation; GEYA Electrical Co.; Entec Electric & Electronic Co Ltd; Hyundai Electric & Energy Systems Company; Rockwell Automation; Eaton Corporation PLC; Siemens AG; Nader Electrical
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global DC Circuit Breaker Market Report Segmentation
The report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global DC circuit breaker market report based on type, insulation, voltage, end-use, and region:
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Solid State
-
Hybrid
-
-
Insulation Outlook (Revenue, USD Million, 2021 - 2033)
-
Vacuum
-
Gas
-
-
Voltage Outlook (Revenue, USD Million, 2021 - 2033)
-
Low Voltage
-
Medium Voltage
-
High Voltage
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Transmission & Distribution Utilities
-
Power Generation
-
Renewables
-
Railways
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
UAE
-
Kingdom of Saudi Arabia
-
South Africa
-
-
Research Methodology
The dc circuit breaker market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each dc circuit breaker segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Solid State
The segment generates revenue from the sale of semiconductor-based DC circuit breakers.
Hybrid
The segment generates revenue from the sale of hybrid DC circuit breakers combining mechanical switching and power electronic components.
Segment - Insulation
Revenue capture definition
Vacuum
The segment generates revenue from DC circuit breakers using vacuum interrupters for arc extinction, including medium and high voltage switching equipment supplied to industrial facilities, renewable energy projects, railway networks, and utility applications.
Gas
The segment generates revenue from gas insulated DC circuit breakers utilizing insulating gases for arc interruption, including high voltage protection systems, GIS compatible breakers, utility substations, and HVDC transmission infrastructure.
Segment - Voltage
Revenue capture definition
Low Voltage
The segment generates revenue from DC circuit breakers rated for low-voltage DC applications, including EV charging stations, battery storage systems, telecom infrastructure, commercial buildings, residential solar systems, and industrial control panels.
Medium Voltage
The segment generates revenue from medium voltage DC circuit breakers deployed in industrial distribution systems, railway electrification, renewable energy plants, microgrids, and medium scale battery energy storage installations.
High Voltage
The segment generates revenue from high voltage DC circuit breakers used in HVDC transmission systems, offshore wind farms, utility substations, long-distance power transmission, and large-scale grid interconnection projects.
Segment - End-use
Revenue capture definition
Transmission & Distribution Utilities
The segment generates revenue from DC circuit breakers supplied for HVDC transmission lines, substations, grid modernization projects, utility distribution infrastructure, and power network protection systems.
Power Generation
The segment generates revenue from DC circuit breakers installed in conventional and renewable power generation facilities, including auxiliary DC systems, generator protection, battery backup systems, and plant electrical infrastructure.
Renewables
The segment generates revenue from DC circuit breakers deployed in solar photovoltaic plants, battery energy storage systems, wind farms, microgrids, and hybrid renewable energy installations requiring DC protection.
Railways
The segment generates revenue from DC circuit breakers used in railway traction substations, metro systems, electric locomotives, signaling infrastructure, and rail electrification networks for DC fault protection.
Estimation Model
Layer Name
Key Question
Description
DC Power Infrastructure Base Layer
Which applications require DC power distribution and protection?
This layer establishes the total potential demand base by identifying DC power infrastructure across renewable energy systems, battery energy storage systems (BESS), electric vehicle charging infrastructure, railways, data centers, industrial automation, telecommunications, marine systems, and other DC-powered applications. It evaluates factors such as installed DC capacity, electrification trends, and power distribution requirements.
Addressable DC Circuit Breaker Market Layer
Which DC power systems can realistically deploy DC circuit breakers?
This layer refines the total DC power ecosystem into the serviceable DC circuit breaker market by considering factors such as safety regulations, voltage levels, renewable energy deployment, energy storage adoption, EV charging infrastructure expansion, industrial modernization, and investments in DC distribution networks. It determines the share of DC systems that require dedicated circuit protection solutions.
DC Circuit Breaker Adoption Layer
Who is actively deploying DC circuit breakers?
This layer estimates annual demand generation by analyzing adoption among renewable energy developers, battery energy storage operators, EV charging infrastructure providers, railway operators, utilities, industrial facilities, telecom operators, and data center operators. It converts the addressable market into measurable installations of low-, medium-, and high-voltage DC circuit breakers.
Monetization Layer
How does DC circuit breaker adoption translate into market revenue?
This layer converts adoption into market revenue through sales of DC circuit breakers. Revenue is generated by applying average selling prices and service revenues across voltage levels, applications, and end-use industries.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional DC Circuit Breaker Market Opportunity Assessment
Country/region-wise market sizing and forecasts
Analysis of demand, adoption trends, and regulatory landscape
Identification of high-growth regions and investment hotspots
Identified region-specific growth opportunities
Supported expansion and go-to-market strategy
Enabled informed regional investment decisions
Cross-Segmentation Analysis for the DC Circuit Breaker Market
Criss-cross market analysis by type and end use
Demand and adoption assessment across key segments
Segment attractiveness and growth potential benchmarking
Identified high-potential market segments
Supported targeted product positioning and marketing strategy
Improved customer and segment prioritization
Competitive Benchmarking and Strategic Positioning in the DC Circuit Breaker Market
Benchmarking of key competitors across products, pricing, partnerships, and innovation
Comparative assessment of market share, capabilities, and strategies
Analysis of competitive strengths, gaps, and differentiation areas
Identified competitive white spaces and growth gaps
Supported strategic positioning and differentiation
Enabled data-driven competitive strategy development
Frequently Asked Questions About This Report
The global DC circuit breaker market size was estimated at USD 4.7 billion in 2025 and is expected to reach USD 5.0 billion in 2026.
The global DC circuit breaker market is expected to grow at a compound annual growth rate of 11.8% from 2026 to 2033, reaching USD 10.9 billion by 2033.
Solid State segment dominated the market, with a revenue share of 53.2% in 2025. Solid state DC circuit breakers are witnessing rapid growth due to their superior efficiency, reliability, and quick switching capabilities. These breakers use semiconductor devices to interrupt the current flow, eliminating the mechanical wear and tear associated with traditional mechanical breakers.
Some key players operating in the DC circuit breaker market include ABB Ltd, Larsen & Toubro Limited, Mitsubishi Electric Corporation, GEYA Electrical Co., Entec Electric & Electronic Co Ltd, Hyundai Electric & Energy Systems Company, Rockwell Automation, Eaton Corporation PLC, Siemens AG, Nader Electrical, Fuji Electric Co Ltd, Powell Industries, Inc., and Schneider Electric SE.
Asia Pacific dominated the global market with the largest revenue share of 40.6% in 2025, driven by the rapid industrialization, urbanization, and significant investments in renewable energy and HVDC projects. Countries like China, India, and Japan are key contributors, with substantial investments in power infrastructure and renewable energy integration.
Vacuum segment accounted for the largest revenue share of 58.4% in 2025 and is the fastest-growing segment over the forecast period.
Medium Voltage segment accounted for the largest revenue share of 45.4% in 2025, while high voltage is the fastest-growing segment over the forecast period.
Transmission & Distribution Utilities segment accounted for the largest revenue share of 29.9% in 2025, while renewables is the fastest-growing segment over the forecast period.
One prominent trend is the increasing adoption of renewable energy sources, such as solar and wind power, which require efficient and reliable circuit protection.
About the Author(s)
Semiconductors Research Team
Semiconductors & Electronics · SemiconductorsThis report was authored by the semiconductors research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the semiconductors segment of the semiconductors & electronics industry. All findings are based on proprietary semiconductors & electronics databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


