
- Home
- »
- Clinical Diagnostics
- »
-
STD Diagnostics Market Size And Share Report, 2026-2033GVR Report cover

STD Diagnostics Market (2026 - 2033)
Size, Share & Trends Analysis Report By Application (HIV Testing, HSV Testing, Chlamydia Testing), By Product, By Technology, By Location Of Testing, By Region, And Segment Forecasts
Market Size, 2025
$11.4BMarket Estimate, 2026
$12.2BMarket Forecast, 2033
$19.7BCAGR, 2026–2033
7.1%STD Diagnostics Market Summary
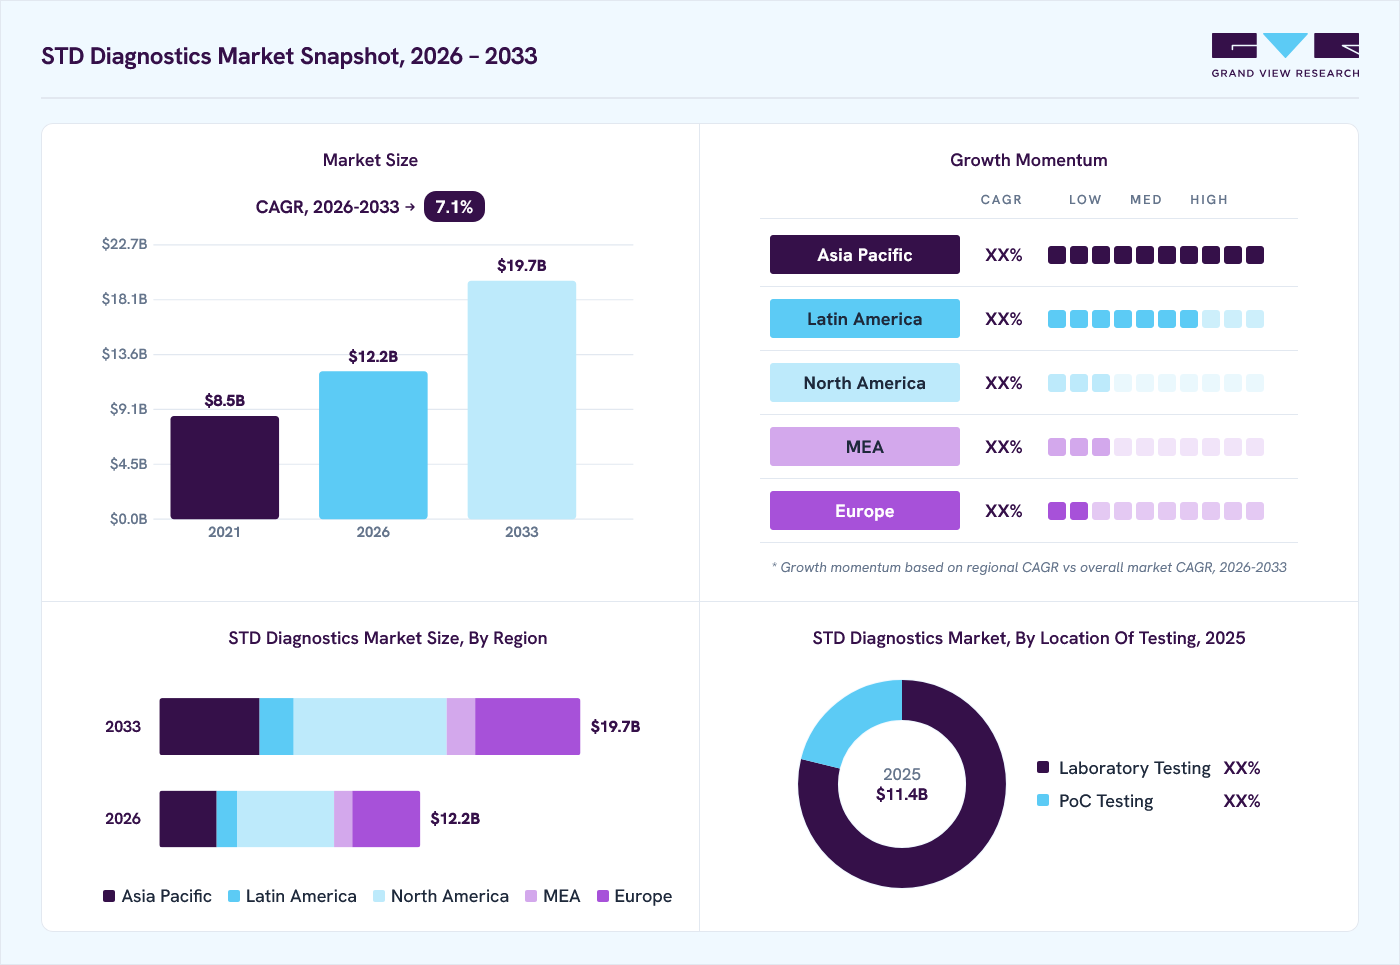
The global STD diagnostics market size was valued at USD 11.4 billion in 2025 and is projected to grow from USD 12.2 billion in 2026 to USD 19.7 billion by 2033, at a CAGR of 7.1% from 2026 to 2033. The market in North America dominated with a revenue share of 37.3% in 2025. The market is primarily influenced by advancements in diagnostic technology and increased government efforts to promote early detection and treatment.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Consumables segment held the largest market share of 69.8% in 2025.
- By application: HIV testing segment held the largest market share of 29.9% in 2025.
- By technology: Immunoassay segment held the largest market share of 45.0% in 2025.
- By location of testing: Laboratory testing segment held the largest market share of 78.8% in 2025.
Regional Highlights
- Largest regional market: North America (37.3% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 11.4 Billion
- Estimated market size in 2026: USD 12.2 Billion
- Projected market size by 2033: USD 19.7 Billion
- CAGR (2026-2033): 7.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The growing burden of STDs serves as a key driver for the industry. This growth can also be attributed to rapid technological advancements, and high R&D investments by key players to introduce novel & innovative products such as genetic biomarkers for antibiotic-resistant strains of bacteria, multiplex Point-of-Care (PoC), & self-testing products in the market.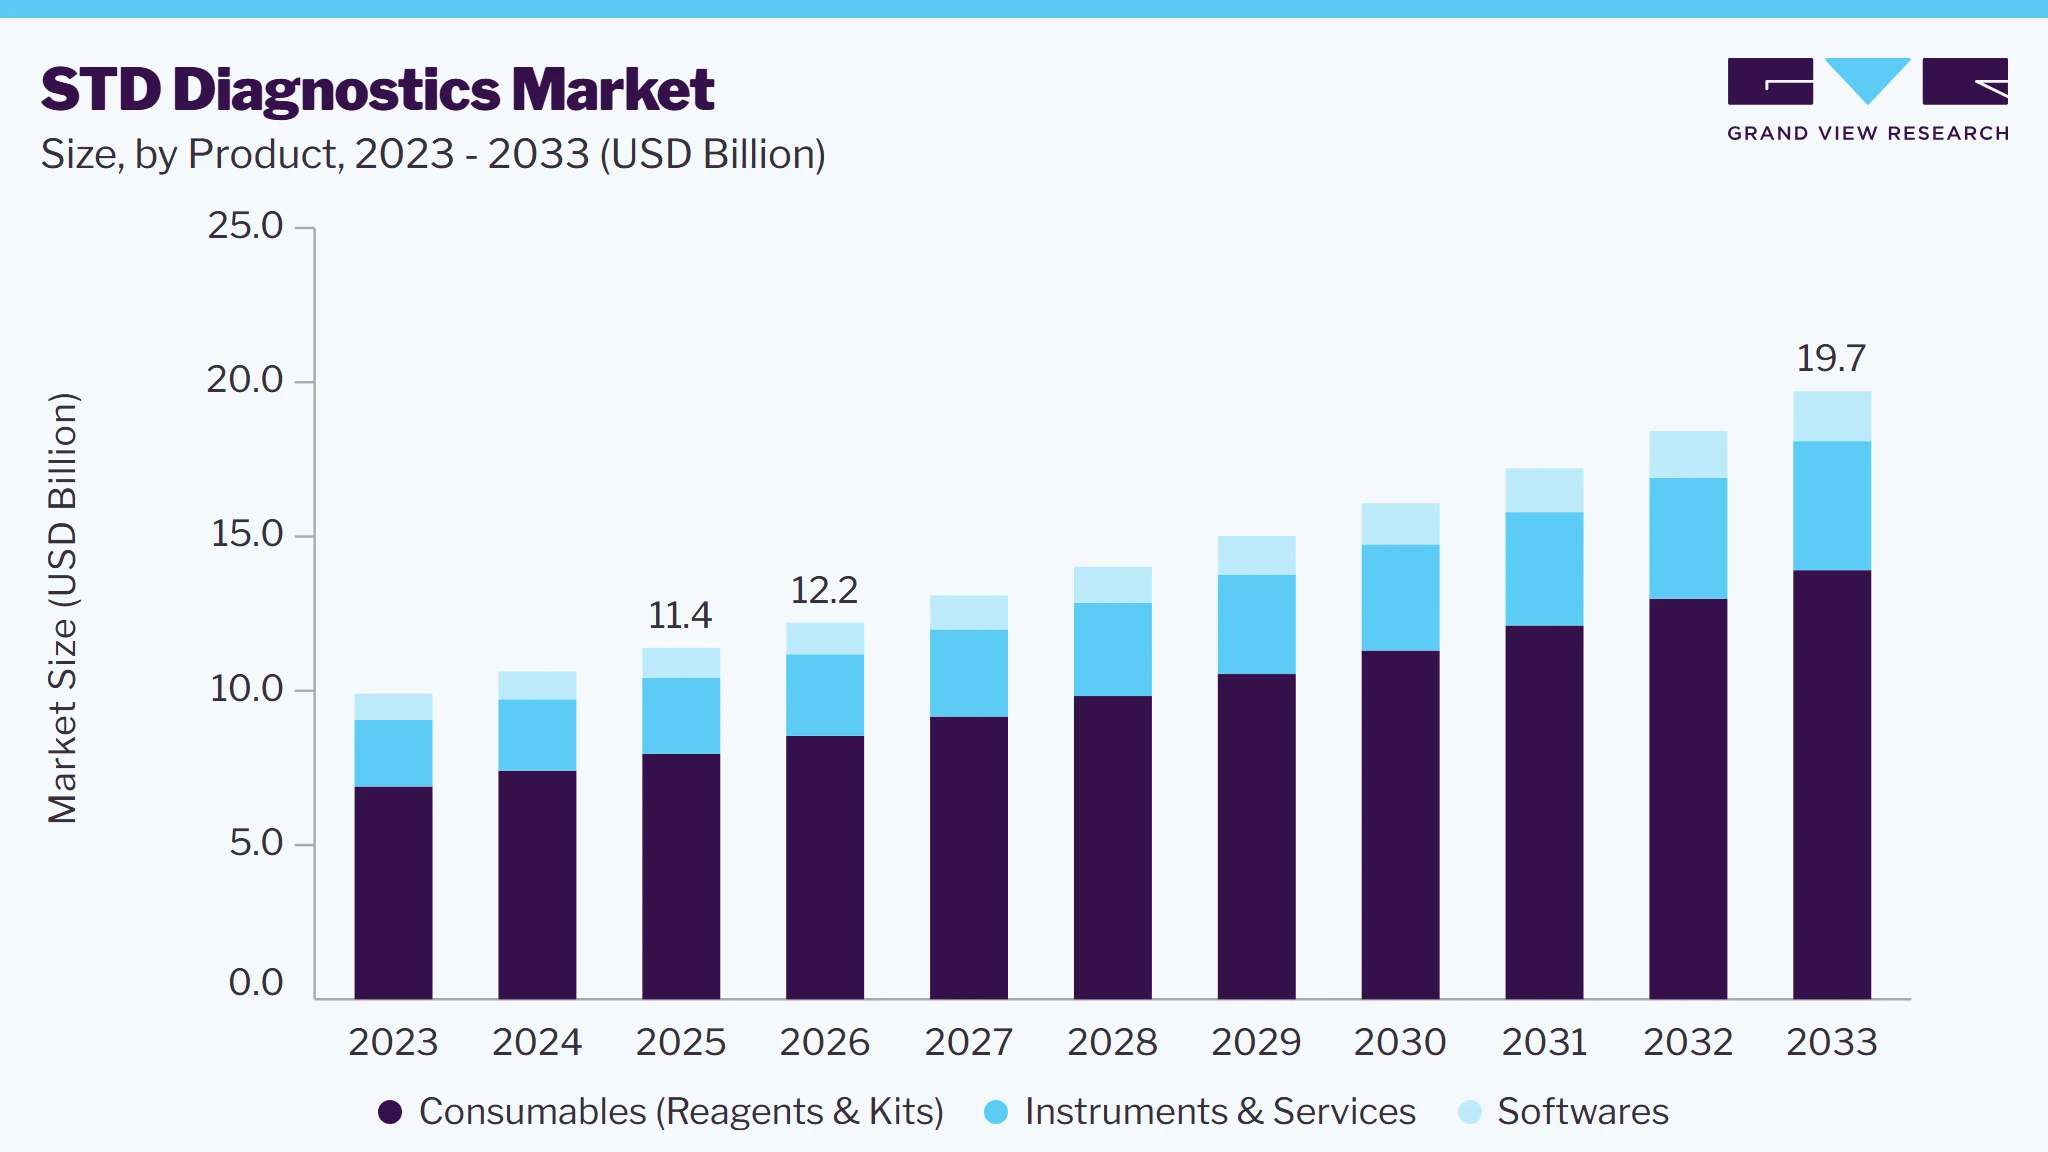 To learn more about this report, Download Free Sample Report
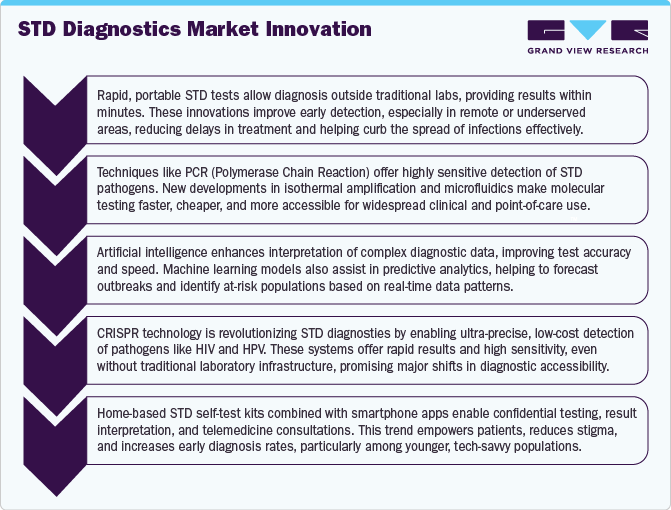
Technological advancements related to accuracy, portability, and cost-effectiveness are expected to drive the Sexually Transmitted Disease (STD) diagnostics market over the forecast period. Key players are expanding their test portfolios by investing in R&D to develop diagnostic kits that can identify emerging diseases or by entering into agreements with other kit manufacturing companies. For instance, in June 2023, Linear Diagnostics secured funding to create an STI rapid test. The UK-based company, a spinout from the University of Birmingham, received support from the UK's National Institute for Health and Care Research (NIHR). The funding aims to facilitate the development of a 20-minute test for diagnosing gonorrhoea and Chlamydia, addressing the need for faster and more accessible STI diagnostics.
 To learn more about this report, Download Free Sample Report
Furthermore, in the ever-evolving landscape of STD diagnostics, key trends point towards integrating advanced technologies, contributing significantly to market growth. The introduction of sophisticated tools, such as multiplex PCR products and next-generation HIV testing kits, stands out as a pivotal development. Companies such as Seegene, with products like Anyplex, Allplex, and Seeplex, have played a crucial role in expanding diagnostic capabilities. For instance, the Allplex STI/BV Panel Assay can distinguish among 28 different causative agents in a single test, showcasing the substantial progress made in diagnostic precision. This technological advancement not only broadens the spectrum of detectable sexually transmitted infections but also facilitates more accurate and targeted treatments.
Better reimbursement facilities overcome the high pricing issue to some extent in developed regions such as the U.S. and Europe. According to WHO, about 50% of healthcare financing in low-income countries comes from out-of-pocket payments, compared to ~14% in high-income countries and ~30% in middle-income countries. When payments from public health insurance, general government expenditure, and prepaid private insurance are combined, approximately 38% of healthcare financing in low-income countries is combined in funding pools, which allow the risks of healthcare costs to be shared across population groups, as compared to 80% in high-income countries and approximately 60% in middle-income countries.
Market Dynamics
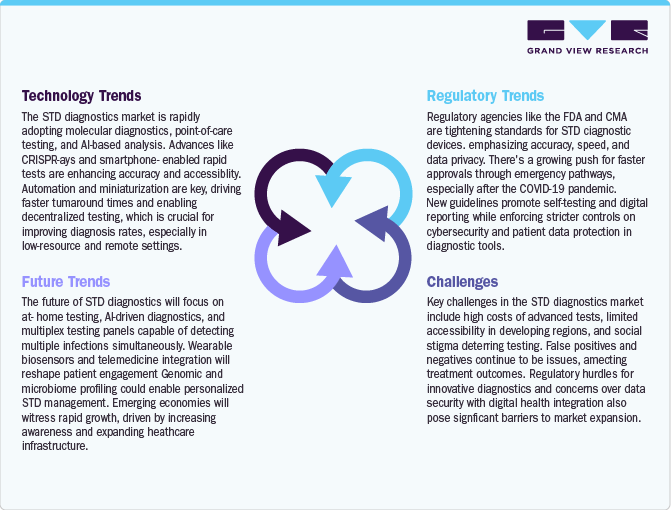
The STD diagnostics market is driven by the increasing prevalence of sexually transmitted infections, growing awareness of early diagnosis, and rising adoption of molecular and point-of-care testing technologies. Expansion of self-testing kits and telehealth platforms is improving accessibility and privacy. However, market growth is restrained by social stigma, limited diagnostic access in low-resource settings, and high costs of advanced testing. Opportunities exist in home-based diagnostics, AI-enabled testing, multiplex PCR technologies, and expanding sexual health programs in emerging economies.
 To learn more about this report, Download Free Sample Report
The STD diagnostics market is strongly driven by the rising prevalence of sexually transmitted infections (STIs), increasing awareness of sexual health, and expansion of routine screening programs. Rising infection rates are increasing demand for rapid, accurate, and early diagnostic testing for infections such as chlamydia, gonorrhea, syphilis, HIV, and HPV. According to the WHO report published in September 2025, more than 1 million curable STIs are acquired every day globally, and approximately 374 million new infections of chlamydia, gonorrhea, syphilis, and trichomoniasis occur annually among people aged 15–49. Additionally, the asymptomatic nature of many infections is increasing dependence on laboratory diagnostics and molecular testing for early identification.
Recent developments are accelerating growth further. In the U.S., the CDC reported more than 2.2 million STI cases in 2024, while congenital syphilis cases continued rising, reaching nearly 4,000 reported cases, highlighting the need for early maternal screening and faster diagnostics. Technological innovation is also supporting adoption, including multiplex molecular assays and point-of-care STI testing, enabling simultaneous detection of multiple infections with faster turnaround time and improved patient compliance.
Social stigma surrounding sexual health testing remains one of the most significant barriers to STD diagnostics adoption because many individuals avoid screening due to embarrassment, fear of judgment, privacy concerns, or discrimination. In many communities, STI testing is still associated with social shame or perceived promiscuity, discouraging proactive healthcare behavior even among high-risk populations. This stigma often results in delayed diagnosis, untreated infections, and continued disease transmission. According to the CDC, stigma related to HIV and sexual health discourages people from seeking testing, prevention, and care, directly affecting disease detection and treatment outcomes. At the same time, STI burden remains high, with the U.S. reporting more than 2.2 million STI cases in 2024, indicating persistent unmet testing needs.
Recent evidence highlights how stigma continues to suppress testing behavior despite rising awareness. In 2024, FDA authorization of the first over-the-counter syphilis self-test was partly positioned as a solution to barriers such as stigma and fear of visiting clinics, allowing patients to test privately at home. Health experts noted that confidential testing options are increasingly important because many people postpone screening due to discomfort discussing sexual health with providers or partners. Additionally, recent behavioral research discussed in public health reporting found that only around half of individuals disclose—or believe they should disclose—having an STI before sexual contact, illustrating how stigma can reduce openness and delay diagnosis.
One major opportunity in the STD diagnostics industry is the increasing adoption of home-based and self-testing solutions, driven by demand for privacy, convenience, and faster diagnosis. Many people avoid clinic visits due to stigma, scheduling barriers, or confidentiality concerns, creating strong demand for at-home sample collection and rapid testing kits. Recent regulatory momentum is accelerating this trend. In March 2024, the U.S. FDA approved the first over-the-counter syphilis self-test, expanding access to STI screening outside traditional healthcare settings. Additionally, HIV self-testing has gained traction globally, with the WHO supporting self-testing as a strategy to improve diagnosis among underserved populations. (fda.gov)
The opportunity is substantial because undiagnosed infections remain widespread. According to the WHO, more than 1 million curable STIs are acquired every day globally, while CDC data indicate millions of annual STI cases continue despite available treatments, emphasizing the need for easier testing access. Digital health integration is strengthening this opportunity further, with telehealth platforms increasingly linking at-home tests to online consultations and prescription services. This model is improving screening participation, particularly among younger adults and people seeking confidential care, creating long-term growth potential for diagnostic providers.
Market Concentration & Characteristics
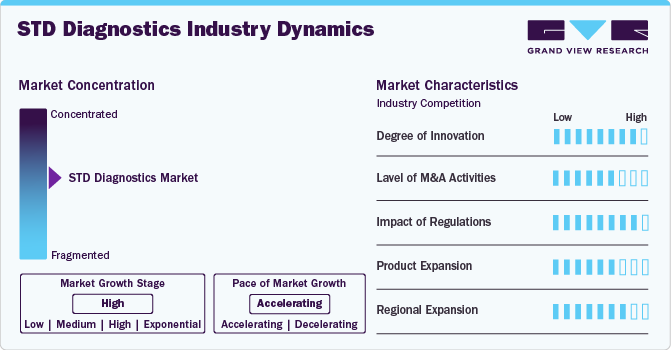
The market shows a high degree of innovation, driven by molecular technologies, AI-based tools, and home-testing kits. Companies are developing faster, more accurate, and user-friendly solutions. Innovations like CRISPR diagnostics and digital health platforms are redefining detection methods, emphasizing patient privacy, real-time monitoring, and accessibility, especially critical in underserved and emerging markets.
Mergers and acquisitions are increasing as larger players seek to expand their diagnostic portfolios. Companies acquire smaller innovators specializing in molecular diagnostics, AI integration, or point-of-care technologies. This consolidation helps accelerate innovation adoption, expand geographical reach, and compete effectively against emerging startups in a rapidly evolving market with growing demand for faster and decentralized testing.
 To learn more about this report, Download Free Sample Report
Regulatory frameworks significantly influence product development and market entry. Agencies demand higher sensitivity, faster turnaround, and strong data protection. Self-testing devices face rigorous scrutiny to ensure reliability. Global harmonization of standards is slowly improving, but varying regional requirements continue challenging companies, particularly those aiming for multinational expansion and rapid launch of innovative diagnostics.
Companies are broadening their STD diagnostics portfolios by adding multiplex testing kits, home-testing solutions, and AI-enabled digital health platforms. Expansion focuses on tests detecting multiple infections simultaneously, such as HIV, HPV, chlamydia, and gonorrhea, to meet growing demand for comprehensive, user-friendly, and cost-effective solutions that can be used both in clinics and at home.
Emerging markets present significant opportunities, particularly in Asia Pacific, Latin America, and Africa. Companies invest heavily in regional partnerships, localized manufacturing, and distribution networks. Efforts focus on affordability, awareness campaigns, and overcoming stigma barriers. North America and Europe continue to lead in technology adoption, but high growth rates are seen in underserved global regions.
Analyst Perspective
The STD diagnostics market is expected to witness sustained growth driven by rising STI prevalence, increasing awareness of early detection, and expanding access to molecular and point-of-care testing technologies. Analysts observe growing demand for rapid, confidential, and home-based diagnostic solutions, particularly among younger populations and underserved groups seeking privacy. Technological advances in multiplex PCR, AI-enabled diagnostics, and telehealth-integrated testing are improving accuracy and accessibility. However, social stigma, reimbursement limitations, and healthcare access disparities remain challenges. Companies emphasizing affordable, decentralized, and digitally connected testing solutions are likely to gain a stronger competitive position in the evolving market.
Product Insights
Based on product, the consumables segment led the market with the largest revenue share of 69.8% in 2025 and is anticipated to grow at the fastest CAGR over the forecast period, owing to increased demand for consumables coupled with the introduction of innovative solutions. Increasing product approvals for addressing the high demand for diagnosis of STDs may contribute to the growth of respective consumables in the market. For instance, in May 2022, Abbott’s Alinity m STI Assay received FDA clearance. It is a multiplex test that can detect and differentiate four common STDs simultaneously-Neisseria gonorrhoeae (NG), Chlamydia trachomatis (CT), Mycoplasma genitalium (MG), and Trichomonas vaginalis (TV). In addition, companies such as Ortho-Clinical Diagnostics, Inc. recently received approval for the VITROS Immunodiagnostic HIV Combo Reagent Pack.
Furthermore, the instruments and services segment within the market is experiencing robust growth, propelled by technological advancements and the increasing global burden of sexually transmitted infections. Laboratory instruments such as PCR thermal cyclers, flow cytometers, and lateral flow readers are essential for precise and efficient STD detection, particularly in centralized laboratory settings. Simultaneously, point-of-care (POC) devices, including portable rapid diagnostic kits and microfluidic-integrated phone chips, are gaining traction due to their ability to deliver quick results in decentralized locations, enhancing accessibility and timely treatment. The services component, encompassing laboratory testing and diagnostic services, is expanding in response to the growing demand for early and accurate STD detection. This expansion is further supported by increased investments in healthcare infrastructure and public health initiatives aimed at controlling the spread of STDs. Collectively, these factors contribute to the significant growth of the Instruments and Services market segment.
Application Insights
Based on application, the HIV testing segment led the market with the largest revenue share of 29.9% in 2025 and is anticipated to witness the fastest growth at a CAGR over the forecast period, owing to high testing rates, increased product approvals, such as fourth-generation HIV tests & self-testing kits, and significant R&D initiatives relevant to novel products. In March 2023, the CDC announced the launch of a Together TakeMeHome (TTMH) project to distribute up to 1 million HIV self-tests over 5 years. These tests can be ordered by people aged 17 years and older in the U.S., including Puerto Rico, via an online portal. The CDC develops the test in partnership with Building Healthy Online Communities (BHOC), OraSure Technologies, Emory University, Signal Group, and NASTAD.
The HPV testing segment is expected to grow at a significant CAGR during the forecast period. Traditionally, the Pap smear has been the primary screening method for cervical cancer. However, there has been a shift towards HPV testing as a more sensitive and reliable method for detecting high-risk HPV strains that are associated with the development of cervical cancer. New product launches specifically by a reputed organization such as UNICEF play an important role in creating awareness of cervical cancer. In January 2023, UNICEF launched a new comprehensive cervical cancer toolkit, including an HPV DNA-based diagnostic tool, a preventive HPV vaccine, and a treatment pool. Launching this kit will benefit women in lower-income countries.
Technology Insights
Based on technology, the immunoassay segment led the market with the largest revenue share of 45.0% in 2025, owing to higher testing rates for Sexually Transmitted Disease (STD) diagnostics. Moreover, the approval of new immunoassay products for the diagnosis of sexually transmitted diseases may impel market growth. For instance, in August 2020, DiaSorin, Inc. received 510 (k) approval from the U.S. FDA for introducing LIAISON XL MUREX anti-HBe, which is used to diagnose HBV infection.
The molecular diagnostics segment is expected to exhibit the fastest growth rate over the forecast period. An increase in the use of high-throughput PCR technology to detect Sexually Transmitted Diseases (STDs) is expected to drive the NAAT segment. Advantages such as cost-effectiveness, user-friendliness, and accuracy are estimated to increase the adoption of this technology. Most of the urine tests for STDs are performed using NAATs owing to their high sensitivity. In January 2025, Roche announced that the U.S. Food and Drug Administration (FDA) had granted 510(k) clearance and a Clinical Laboratory Improvement Amendments of 1988 (CLIA) waiver for its cobas liat sexually transmitted infection (STI) multiplex assay panels. These panels-covering chlamydia and gonorrhea (CT/NG), as well as chlamydia, gonorrhea, and Mycoplasma genitalium (CT/NG/MG)-enable clinicians to diagnose and distinguish between multiple STIs using a single patient sample.
Location of Testing Insights
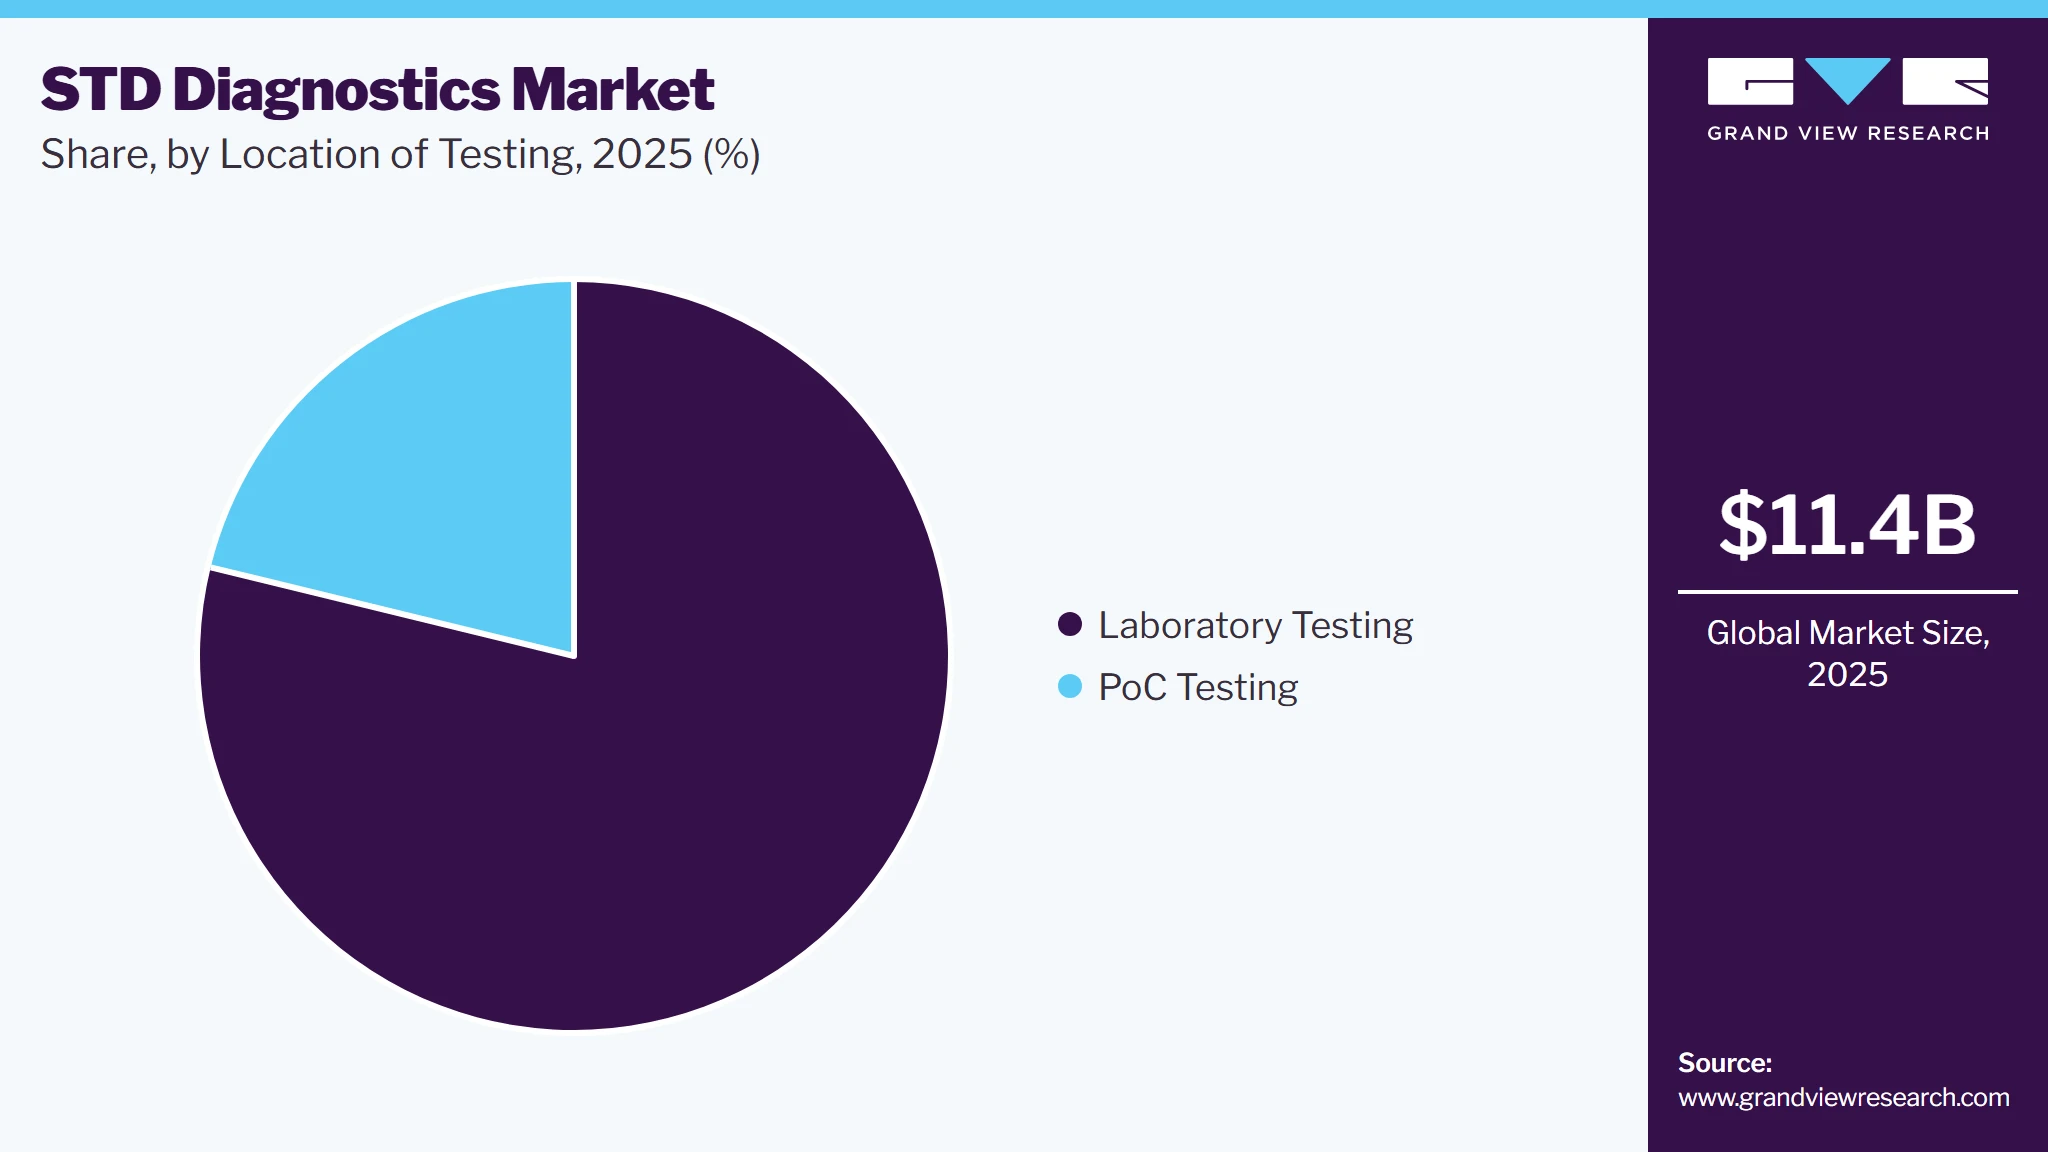
Based on location of testing, the laboratory testing segment led the market with the largest revenue share of 78.8% in 2025, driven by a high market penetration rate and procedure volumes. The presence of extensive ancillary support with respect to manpower and infrastructure is also a key driver. Many healthcare institutions are working with laboratories to integrate different tests. Public health laboratories are important in performing high-quality testing for STDs and associated antimicrobial resistance. According to the Public Health England report, in 2023, the number of sexual health screenings-including diagnostic tests for chlamydia, gonorrhoea, syphilis, and HIV-increased by 8.3%, rising from 2,177,325 in 2022 to 2,358,987. New STI diagnoses grew 4.7% during the same period, from 383,789 to 401,800. The most frequently diagnosed STIs in 2023 were chlamydia (194,970 cases, accounting for 48.5% of all new STI cases), gonorrhoea (85,223 cases, 21.2%), first-episode genital herpes (27,167 cases, 6.8%), and first-episode genital warts (26,133 cases, 6.5%).
 To learn more about this report, Download Free Sample Report
The point-of-care testing segment is estimated to witness the fastest growth over the forecast period. There is an increasing interest in developing such products owing to shorter turnaround times, enabling healthcare providers to make treatment decisions at clinicians’ offices promptly. Therefore, various companies are designing assays & molecular diagnostic platforms for POC or near-patient testing. For instance, digene HC2 CT-GC Dual ID DNA Test, digene HC2 GC-ID DNA Test for the diagnosis of Neisseria gonorrhoeae and Chlamydia trachomatis by QIAGEN and ResistancePlus MG FleXible for diagnosing Mycoplasma genitalium with macrolide-resistance detection by Danaher Corporation (Cepheid) are among such products.
Regional Insights
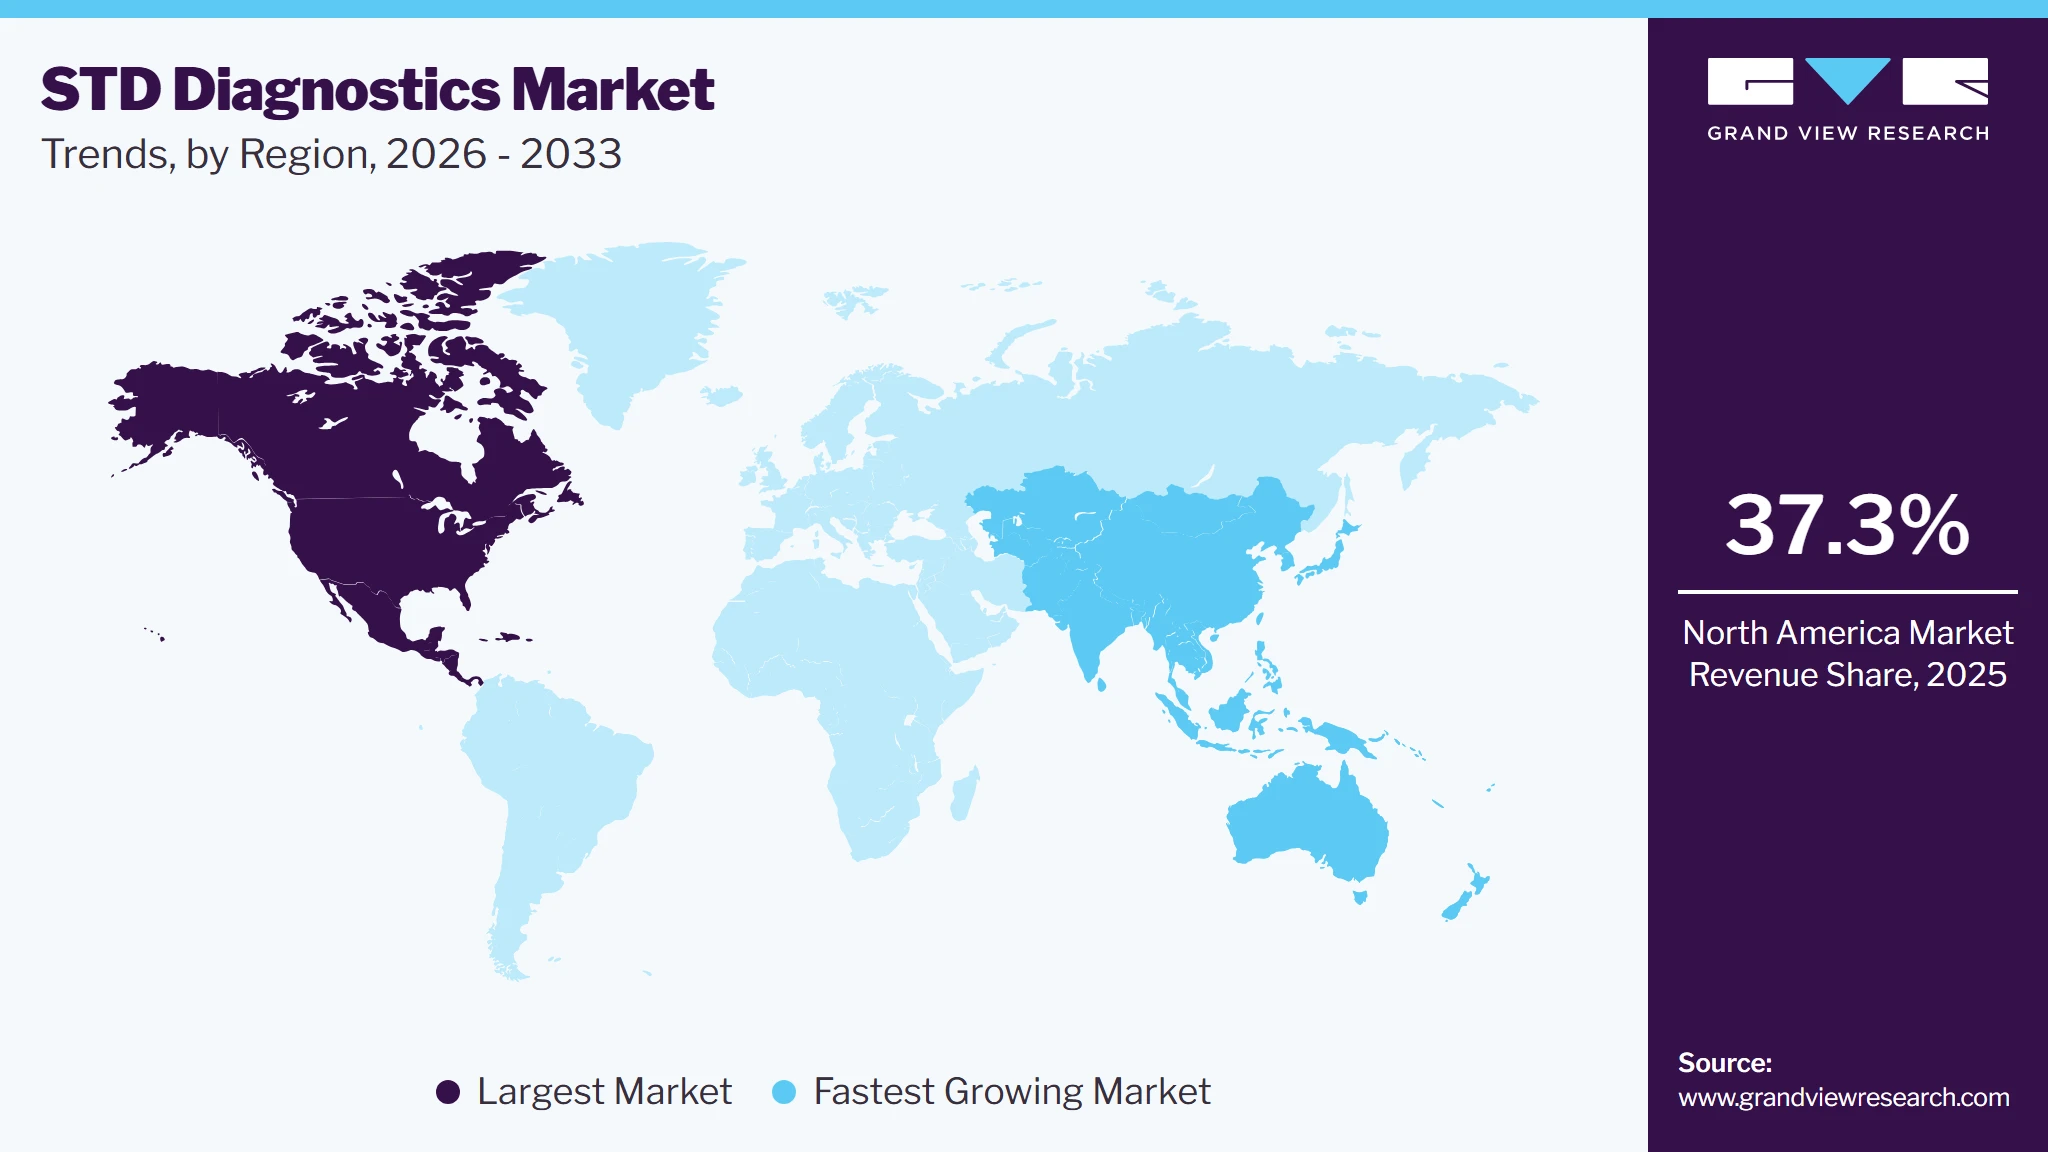
North America dominated the STD diagnostics market with the largest revenue share of 37.3% in 2025. This dominance can be attributed to the high testing rates, technological advancements, proactive government measures, improvements in healthcare infrastructure, and the presence of major players. Reimbursement policies and favorable government initiatives are likely to drive market growth. The CMS has introduced the New Technology Add-on Payment (NTAP) program to reduce hospital financial losses. An increase in the number of partnerships between in-vitro diagnostic companies and non-profit organizations for spreading awareness about STDs is creating lucrative growth opportunities in the STD diagnostics industry.
 To learn more about this report, Download Free Sample Report
U.S. STD Diagnostics Market Trends
The STD diagnostics market in the U.S. held the largest share in the North America region in 2025. The STD diagnostics market in the U.S. is experiencing significant growth, driven by rising infection rates, increased public awareness, and advancements in diagnostic technologies. This growth is fueled by factors such as the increasing prevalence of STDs, government initiatives promoting early detection and treatment, and the adoption of point-of-care testing and self-testing kits. Integrating digital health platforms and telemedicine services also enhances patient access to diagnostic services, expanding the market.
Europe STD Diagnostics Market Trends
The STD diagnostics market in Europe is experiencing steady growth, driven by rising infection rates and increased public health initiatives. This expansion is fueled by the increasing prevalence of sexually transmitted infections (STIs), with over 230,000 chlamydia cases and nearly 97,000 gonorrhoea cases reported in 2023. The demand for advanced diagnostic tools, including point-of-care testing and self-testing kits, is rising to address these public health challenges.
The UK STD diagnostics market is experiencing significant growth driven by several factors: increasing prevalence of STDs, government initiatives promoting regular screening, and advances in diagnostic technologies. Moreover, public awareness campaigns, adopting point-of-care tests, and expanding self-testing kits contribute significantly. The growing number of young adults engaging in at-risk sexual behaviors also drives market demand.
The STD diagnostics market in Germany benefits from robust healthcare infrastructure, mandatory health insurance, and strong public health policies. In addition, the rising prevalence of STDs and the emphasis on early detection in clinical settings fuel market growth. Technological advancements in diagnostic tools and the increasing use of molecular diagnostics and point-of-care testing drive adoption. Moreover, government support for sexually transmitted infection prevention and control plays a key role.
Asia Pacific STD Diagnostics Market Trends
The STD diagnostics market in Asia Pacific is estimated to witness the fastest growth rate over the forecast period. The high growth rate can be attributed to the rising disease burden of STIs and increasing testing rates. The report released by The Institute for New Era Strategy in August 2023 noted that in 2020, approximately 641,000 individuals in Japan were diagnosed with HCV. Among them, over 530,000 were under the age of 80, and 157,000 were under the age of 60. These findings emphasize the significance of addressing the situation in the STD diagnostic market to ensure effective healthcare responses.
China STD diagnostics market is experiencing significant growth, driven by several key factors. The increasing prevalence of sexually transmitted diseases (STDs), particularly HIV/AIDS, syphilis, and gonorrhea, has heightened the demand for effective diagnostic solutions. Government initiatives to enhance public health awareness and expand access to healthcare services are further propelling market expansion. Technological advancements in diagnostic tools, such as the development of point-of-care (POC) devices and molecular diagnostics, are improving the accuracy and efficiency of STD testing. Furthermore, the rising adoption of home care diagnostics and the expansion of diagnostic centers contribute to market growth. These factors collectively underscore the dynamic market evolution.
The STD diagnostics market in India is experiencing robust growth, driven by several key factors. An expanding middle class with increased disposable income increases demand for healthcare services, including diagnostic testing. Government initiatives such as Ayushman Bharat and the National Health Mission are enhancing healthcare accessibility and affordability, thereby encouraging more individuals to seek diagnostic services. Technological advancements, including integrating artificial intelligence and digital platforms, are improving diagnostic accuracy and efficiency, making testing more reliable and accessible. Moreover, the rise in health awareness and preventive healthcare trends is prompting individuals to opt for regular screenings, further boosting the demand for STD diagnostics. These factors collectively contribute to the significant expansion of the STD diagnostics market in India.
Latin America STD Diagnostics Market Trends
The STD diagnostics market in Latin America is expanding due to several key factors. Technological advancements, such as developing cost-effective and rapid diagnostic tools, have improved accessibility and efficiency in detecting sexually transmitted infections (STIs). Government initiatives, including public-private partnerships, have enhanced healthcare infrastructure and increased STI prevention and treatment awareness. The growing demand for point-of-care testing solutions, which offer quick results and convenience, has also contributed to market growth. The rising prevalence of STIs and the need for early detection further drive the demand for diagnostic services in the region.
Middle East and Africa STD Diagnostics Market Trends
The STD diagnostics market in the Middle East and Africa (MEA) is experiencing significant growth, driven by several key factors. The rising prevalence of sexually transmitted diseases (STDs) in the region has heightened the demand for effective diagnostic solutions. Governments and non-governmental organizations are increasing awareness and implementing public health campaigns to promote early detection and treatment of STDs. Advancements in diagnostic technologies, such as point-of-care testing and self-testing kits, have improved accessibility and convenience for patients.
Key STD Diagnostics Company Insights
Key players are focusing on gaining market approvals for innovative products to diagnose various STDs, regional & product expansions, and collaborations to maintain their share in the market. For instance, in January 2023, Molbio Diagnostics launched the Truenat HSV 1/2 test for herpes simplex virus. With the ability to provide results within an hour, this product significantly boosts the company's STD diagnostic portfolio.
Key STD Diagnostics Companies
The following key companies have been profiled for this study on the STD diagnostics market.
-
BD
-
F. Hoffmann-La Roche Ltd
-
Hologic Inc.
-
Abbott
-
Cepheid (Danaher)
-
Qiagen
-
OraSure Technologies, Inc.
-
Bio-Rad Laboratories, Inc.
-
bioMérieux SA
-
Thermo Fisher Scientific, Inc.
-
Seegene Inc.
-
DiaSorin S.p.A
Recent Developments
-
In March 2025, bioLytical Laboratories Inc. announced the introduction of its INSTI HIV-1/2 Syphilis Test in Australia. This dual HIV-syphilis test delivers results in only 60 seconds, enabling healthcare professionals to diagnose HIV and syphilis quickly and connect patients to care without delay.
-
In January 2025, OraSure Technologies, Inc., announced that the Center for Biologics Evaluation and Research (CBER) of the U.S. Food and Drug Administration (FDA) approved a labeling update for the OraQuick HIV Self-Test. This update broadens the age range of individuals eligible for the test, including adolescents aged 14 and older, whereas it was previously approved for those 17 and older. This change aims to improve access to HIV testing for younger individuals.
-
In February 2023, Mylab introduced a series of rapid tests designed for STD diagnostics. These tests are simple to use, can be stored at room temperature, and are suitable for use at point-of-care facilities in places with limited resources. Moreover, they find utility in blood banks for efficiently identifying transfusion-transmissible infections (TTIs) among blood donors, reducing transmission.
STD Diagnostics Market Report Scope
Report Attribute
Details
Market size in 2025
USD 11.4 billion
Estimated market size in 2026
USD 12.2 billion
Projected market size by 2033
USD 19.7 billion
Growth rate
CAGR of 7.1% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, technology, testing location, regional
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; ; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait
Key companies profiled
BD; F. Hoffmann-La Roche Ltd.; Hologic, Inc.; bioMérieux SA; Abbott; Cepheid (Danaher Corporation); Qiagen; Seegene Inc.; Thermo Fisher Scientific Inc.; DiaSorin S.p.A.; OraSure Technologies Inc.; Bio-Rad Laboratories, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global STD Diagnostics Market Report Segmentation
This report forecasts revenue growth at global, regional, & country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this report, Grand View Research has segmented the global STD diagnostics market based on product, technology, application, location of testing, and region:
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Instruments and Services
-
Consumables
-
Software
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
CT/NG testing
-
Syphilis testing
-
PCR testing
-
Non-PCR testing
-
-
Gonorrhea testing
-
HSV testing
-
PCR testing
-
Non-PCR testing
-
-
HPV testing
-
HIV testing
-
Ureaplasma & Mycoplasma testing
-
Trichomonas
-
VZV testing
-
PCR testing
-
Non-PCR testing
-
-
Others
-
-
Technology Outlook (Revenue, USD Million, 2021 - 2033)
-
Immunoassay
-
Molecular Diagnostics
-
Other
-
-
Location of Testing Outlook (Revenue, USD Million, 2021 - 2033)
-
Laboratory Testing
-
Commercial/Private labs
-
Public Health Labs
-
-
Point of Care Testing
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
India
-
China
-
Japan
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Argentina
-
Brazil
-
-
Middle East & Africa
-
Saudi Arabia
-
UAE
-
South Africa
-
Kuwait
-
-
Research Methodology
The std diagnostics market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each std diagnostics segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Instruments & Services
Revenue generated from diagnostic instruments such as PCR analyzers, immunoassay systems, point-of-care devices, and associated services including maintenance, calibration, installation, laboratory support, and workflow optimization.
Consumables
Revenue generated through recurring sales of diagnostic reagents, assay cartridges, test kits, sample collection materials, and chemicals used for STD detection, confirmation, and routine laboratory testing.
Software
Revenue generated from diagnostic software platforms used for test interpretation, laboratory information management, reporting, data integration, workflow automation, patient tracking, and digital connectivity in STD diagnostics.
Segment - Application
Revenue capture definition
CT/NG Testing
(Chlamydia trachomatis
/ Neisseria gonorrhoeae)
Revenue generated from diagnostic tests, reagents, PCR assays, and screening services used for simultaneous detection of chlamydia and gonorrhea infections in clinical and point-of-care settings.
Syphilis Testing
Revenue generated through serological assays, rapid diagnostic kits, confirmatory testing, and laboratory services for identifying Treponema pallidum infections in prenatal, hospital, and screening programs.
Gonorrhea Testing
Revenue generated from molecular diagnostics, culture tests, NAAT assays, and rapid screening tools used for diagnosis and antimicrobial resistance monitoring of gonorrhea infections.
HSV Testing (Herpes Simplex Virus)
Revenue generated from PCR assays, serological testing kits, viral cultures, and confirmatory diagnostics for detecting HSV-1 and HSV-2 infections in symptomatic and asymptomatic patients.
HPV Testing (Human Papillomavirus)
Revenue generated through HPV DNA/RNA testing kits, molecular diagnostics, cervical cancer screening assays, and co-testing procedures supporting early identification of high-risk HPV strains.
HIV Testing
Revenue generated from rapid HIV tests, ELISA assays, nucleic acid tests (NAT), confirmatory diagnostics, and monitoring solutions for early HIV detection and disease management.
Chancroid Testing
Revenue generated from specialized laboratory tests, bacterial culture methods, and molecular diagnostics used to detect Haemophilus ducreyi, particularly in high-prevalence or outbreak-prone regions.
Ureaplasma Testing
Revenue generated from PCR assays, culture diagnostics, and reproductive health screening tests used to identify Ureaplasma infections associated with urogenital complications and infertility.
Trichomonas Testing
Revenue generated through rapid antigen tests, molecular assays, wet mount diagnostics, and laboratory screening solutions for detecting Trichomonas vaginalis infections in sexual health programs.
Ureaplasma + Mycoplasma Testing
Revenue generated from multiplex PCR panels, reproductive diagnostics, and STI screening kits designed to simultaneously detect Ureaplasma and Mycoplasma pathogens in urogenital infections.
VZV Testing (Varicella-Zoster Virus)
Revenue generated from PCR, antibody tests, and viral detection assays used for diagnosing varicella-zoster infections, particularly in immunocompromised and differential diagnostic cases.
Others
Revenue generated from diagnostics for less common STDs and co-infections, including lymphogranuloma venereum (LGV), donovanosis, and emerging sexually transmitted pathogens requiring specialized testing.
Segment – Technology
Revenue capture definition
Molecular Diagnostics
Revenue generated from PCR, NAAT, multiplex molecular panels, and genetic testing platforms used for highly sensitive and accurate detection of sexually transmitted pathogens and co-infections.
Immunoassay
Revenue generated through antibody- and antigen-based diagnostic tests, ELISA kits, rapid assays, and automated immunoassay systems for screening and monitoring sexually transmitted infections.
Others
Revenue generated from culture-based testing, microscopy, cytology, hybrid technologies, and emerging diagnostic methods supporting STD detection where molecular or immunoassay testing is limited.
Segment – Location of Setting
Revenue capture definition
Laboratory Testing
Revenue generated from centralized laboratory-based STD diagnostic services, including molecular testing, immunoassays, confirmatory diagnostics, sample processing, and high-throughput screening performed in hospitals and reference laboratories.
PoC (Point-of-Care) Testing
Revenue generated from rapid STD diagnostic devices, test kits, and decentralized testing services conducted at clinics, pharmacies, community centers, and physician offices for immediate results.
Estimation Model
The STD diagnostics market estimation model is typically based on a combination of epidemiological data, testing volumes, pricing analysis, technology adoption, and healthcare expenditure trends. Revenue is estimated by evaluating infection prevalence (HIV, HPV, chlamydia, gonorrhea, syphilis), diagnostic test utilization, reimbursement patterns, and adoption of molecular and point-of-care technologies across regions. Market sizing also incorporates company revenues, regulatory approvals, screening program expansion, hospital procurement, and demand from laboratories, clinics, and home-testing platforms to forecast future growth.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
STD Diagnostics Competitive Landscape & Technology Assessment
Assessed the global STD diagnostics market across molecular diagnostics, immunoassays, rapid diagnostic tests, culture methods, and point-of-care testing. Evaluated company portfolios, technology advancements, regulatory approvals, testing guidelines, and competitive positioning across laboratory and decentralized healthcare settings.
Helped the client identify technology adoption opportunities, benchmark competitor capabilities, evaluate product differentiation, prioritize strategic investments, and assess market expansion opportunities across sexually transmitted disease diagnostics.
STD Diagnostics Product & Technology Benchmarking Study
Delivered comprehensive benchmarking of STD diagnostic platforms based on analytical sensitivity, specificity, turnaround time, multiplexing capability, workflow efficiency, automation, ease of use, and laboratory integration. Compared commercial assays and diagnostic systems from leading manufacturers.
Enabled the client to evaluate technology competitiveness, identify product innovation opportunities, benchmark development strategies, and prioritize investments in rapid, multiplex, and point-of-care diagnostic solutions.
STD Diagnostics Clinical Adoption & Commercialization Assessment
Assessed disease prevalence, screening guidelines, reimbursement landscape, healthcare infrastructure, laboratory capacity, physician adoption, patient screening programs, procurement practices, and commercialization pathways influencing STD diagnostic adoption across key regional markets.
Supported commercialization planning by identifying high-growth market opportunities, evaluating customer adoption patterns, assessing reimbursement and operational considerations, mitigating commercialization risks, and strengthening long-term market expansion strategies across hospitals, diagnostic laboratories, public health agencies, and sexual health clinics.
Frequently Asked Questions About This Report
North America held the largest market share of 37.3% in 2025 and is expected to maintain its dominance over the forecast period. This dominance can be attributed to the high testing rates, technological advancements, proactive government measures, improvements in healthcare infrastructure, and the presence of major players.
The immunoassay segment dominated the market with a 45.0% revenue share in 2025, owing to higher testing rates for Sexually Transmitted Disease (STD) diagnostics. Moreover, the approval of new immunoassay products for the diagnosis of sexually transmitted diseases may impel market growth.
The global STD diagnostics market size was valued at USD 11.4 billion in 2025 and is estimated at USD 12.2 billion for 2026.
The global STD diagnostics market is expected to grow at a CAGR of 7.1% from 2026 to 2033, reaching USD 19.7 billion by 2033.
Some key players operating in the STD diagnostics market BD; F. Hoffmann-La Roche Ltd.; Hologic, Inc.; bioMérieux SA; Abbott; Cepheid (Danaher Corporation); Qiagen; Seegene Inc; Thermo Fisher Scientific Inc.; DiaSorin S.p.A; OraSure Technologies Inc.; Bio-Rad Laboratories, Inc.
Key factors driving the STD diagnostics market growth include rising incidence of STDs, growing government policies to promote early diagnostics, increasing patient awareness, and technological advancement in STD diagnostics.
Laboratory testing segment held the largest share (over 78.0%) in 2025, while the point-of-care testing segment is the fastest-growing.
The STD diagnostics market in Asia Pacific is estimated to witness the fastest growth rate over the forecast period. The high growth rate can be attributed to the rising disease burden of STIs and increasing testing rates.
The HIV testing segment dominated the market with a share of 29.9% in 2025 and is anticipated to witness the fastest growth at a CAGR over the forecast period, owing to high testing rates, increased product approvals, such as fourth-generation HIV tests & self-testing kits, and significant R&D initiatives relevant to novel products.
The consumables segment held the largest share of 69.8% in 2025, owing to the increased demand for consumables, increasing product approvals, and the introduction of innovative solutions.
About the Author(s)
Clinical Diagnostics Research Team
Healthcare · Clinical DiagnosticsThis report was authored by the clinical diagnostics research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clinical diagnostics segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


