
- Home
- »
- Clinical Diagnostics
- »
-
In Vitro Diagnostics Market Size & Share Report, 2026-2033GVR Report cover

In Vitro Diagnostics Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Instruments, Reagents), By End-use (Hospitals, Home care), By Technology (Molecular Diagnostics, Coagulation), By Test Location, By Application, By Region, And Segment Forecasts
Market Size, 2025
$107.4BMarket Estimate, 2026
$111.0BMarket Forecast, 2033
$160.7BCAGR, 2026–2033
5.4%In Vitro Diagnostics Market Summary
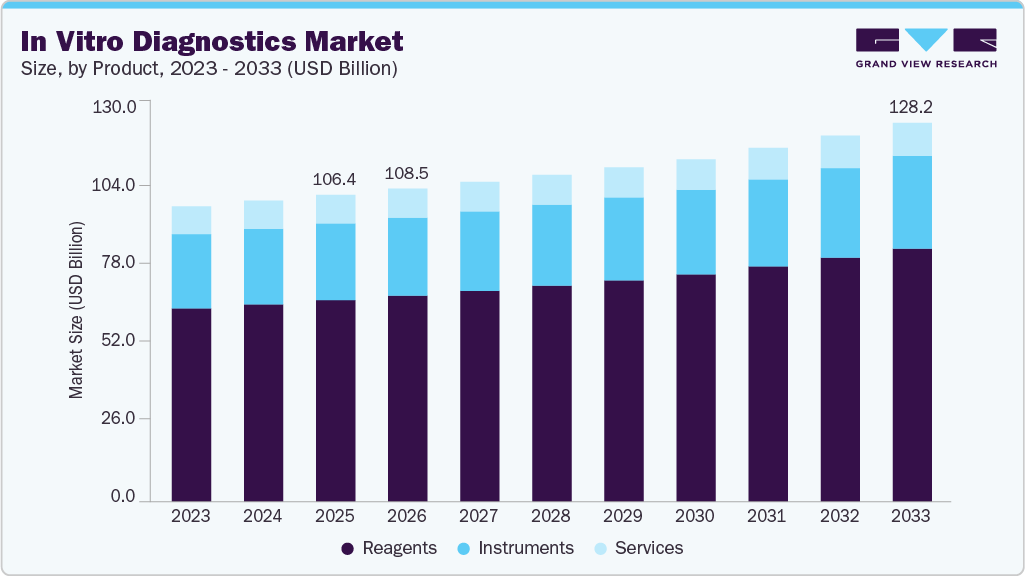
The global in vitro diagnostics market size was valued at USD 107.4 billion in 2025 and is projected to grow from USD 111.0 billion in 2026 to USD 160.7 billion by 2033, at a CAGR of 5.4% from 2026 to 2033. North America dominated the market, accounting for 47.3% revenue share in 2025. The market growth is being driven by the increasing demand for rapid, accurate, and highly sensitive diagnostic testing, particularly as healthcare systems place greater emphasis on early disease detection, targeted treatment, disease monitoring, and preventive care.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: The reagents segment held the largest market share of 65.7% in 2025.
- By test location: The PoC segment held the largest market share in 2025
- By technology: The molecular diagnostics-based products held the largest market share of 25.8% in 2025.
- By application: The infectious diseases segment held the largest market share of 39.7% in 2025.
- By end use: The hospitals segment held the largest market share of 44.5% in 2025.
Regional Highlights
- Largest regional market: North America (47.3% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (fastest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 107.4 Billion
- Estimated market size in 2026: USD 111.0 Billion
- Projected market size by 2033: USD 160.7 Billion
- CAGR (2026-2033): 5.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Key Takeaways from the Report
-
The increasing prevalence of chronic and genetic diseases is broadening the range of applications for in vitro biomarkers and genetic testing. The need for early detection, disease characterization, and personalized treatment options drives this rise in demand. The market is shifting towards wider clinical applications, including infectious diseases, oncology, genetic disorders, and precision medicine. These new decentralized testing methods are anticipated to foster sustained long-term growth in the market.
-
Infectious diseases accounted for a significant market share, reflecting continued demand for pathogen detection, screening, and surveillance. At the same time, oncology represents a major growth opportunity as biomarker testing, companion diagnostics, liquid biopsy, and molecular residual disease testing expand.
-
North America accounted for the largest market share, supported by advanced healthcare infrastructure, high diagnostic utilization, established laboratory networks, and strong adoption of automated and molecular technologies. Asia Pacific is expected to register the fastest growth.
-
Manufacturers are increasingly integrating automation, AI, digital pathology, data analytics, and connectivity into diagnostic workflows to improve throughput, interpretation, quality control, and clinical utility.
-
Leading in vitro diagnostics (IVD) companies are using acquisitions, collaborations, product launches, and regulatory approvals to strengthen capabilities in higher-value areas such as precision oncology, molecular diagnostics, digital pathology, and decentralized testing. Abbott's March 2026 acquisition of Exact Sciences illustrates the increasing focus on cancer diagnostics and early disease detection.
The growing burden of chronic diseases, infectious diseases, and cancer is increasing demand for diagnostic solutions that enable early detection, disease monitoring, risk assessment, and treatment decisions. The need extends across molecular diagnostics, immunoassays, clinical chemistry, hematology, microbiology, and coagulation testing. According to the CDC, 90% of the USD 5.3 trillion spent annually on healthcare in the U.S. is associated with people with chronic and mental health conditions, highlighting the sustained need for diagnostic testing across disease management and preventive care. In the IVD market, molecular diagnostics represented a significant share, reflecting the growing importance of advanced testing technologies alongside established diagnostic methods.
 To learn more about this report, Download Free Sample Report
Technological advancements are reshaping IVD by improving testing speed, sensitivity, automation, portability, and accessibility. Molecular assays and NGS are expanding capabilities in pathogen detection, genetic testing, and biomarker analysis, while advances in immunoassays, clinical chemistry, hematology, and coagulation are improving analytical performance and laboratory efficiency. Point-of-care (POC) testing is also expanding access to rapid diagnostics outside centralized laboratories. Recent FDA CLIA-waiver decisions for molecular and near-patient testing systems further demonstrate the continued movement of selected diagnostic tests toward decentralized settings.
Automation, digital connectivity, artificial intelligence, and advanced data analytics are further transforming IVD workflows. Automated sample handling, integrated analyzers, laboratory information systems, and connected diagnostic platforms can improve throughput, reduce manual intervention, support quality control, and facilitate more efficient interpretation and reporting of results. AI-enabled technologies are also expanding applications in areas such as digital pathology, image analysis, biomarker interpretation, and clinical decision support. Miniaturization and microfluidic technologies are enabling more compact diagnostic platforms that require smaller sample volumes and can support rapid testing in decentralized environments. These developments are particularly relevant to emergency care, primary care, infectious disease surveillance, and resource-constrained settings where timely diagnostic information can influence clinical decisions.
Precision medicine and oncology represent additional areas of application for the in vitro diagnostics industry. Biomarker testing, companion diagnostics, NGS-based genomic profiling, liquid biopsy, circulating tumor DNA (ctDNA), and minimal residual disease (MRD) assessment are extending diagnostics beyond disease identification toward treatment selection and longitudinal monitoring. In May 2026, the FDA approved Signatera CDx, a personalized tumor-informed multiplex PCR and NGS-based assay for detecting molecular residual disease in patients with muscle-invasive bladder cancer who may benefit from specified therapies. The development illustrates the expanding role of IVD in precision oncology, while advances in liquid biopsy and genomic testing are creating opportunities for earlier detection, therapy selection, and monitoring of treatment response.
External funding and collaborative research are also supporting innovation across the IVD landscape, particularly in infectious disease and decentralized testing. For instance, in January 2025, CARB-X awarded Rhode Island Hospital USD 1.0 million to demonstrate a PCR-based approach, informed by RNA sequencing, for detecting bacterial pneumonia directly from whole blood. Such initiatives highlight efforts to develop faster, more accessible diagnostic approaches for conditions in which conventional testing can delay treatment decisions.
Continued investment by governments, research institutions, diagnostic manufacturers, and healthcare organizations is expected to support development across molecular diagnostics, POC testing, biomarker assays, digital diagnostics, and other advanced IVD technologies.
Market Dynamics
The in vitro diagnostics market is being supported by rising demand for rapid, accurate, and clinically actionable testing as healthcare systems place greater emphasis on early disease detection, disease monitoring, preventive care, and personalized treatment. The growing burden of chronic diseases, infectious diseases, and cancer is increasing the need for diagnostic tests that enable the timely identification of disease, the assessment of biomarkers, and the monitoring of treatment response. According to the CDC, chronic diseases remain major drivers of healthcare utilization and costs in the U.S., with 90% of the country’s USD 5.3 trillion in annual healthcare expenditures associated with people with chronic and mental health conditions.
Overall, the IVD market is transitioning toward faster, more decentralized, automated, and clinically integrated testing. Increasing investment in precision medicine, infectious disease surveillance, POC diagnostics, molecular testing, and digital health infrastructure is expected to create new opportunities for diagnostic manufacturers. However, the ability to balance analytical performance with affordability, workflow simplicity, regulatory compliance, and accessibility will remain critical to sustaining adoption across both developed and emerging healthcare markets.
The introduction of technologically advanced diagnostic products is a key factor supporting growth in the IVD market. Advances in molecular diagnostics, next-generation sequencing (NGS), automated analyzers, multiplex testing, artificial intelligence (AI), and point-of-care (POC) platforms are improving diagnostic accuracy, sensitivity, turnaround times, and workflow efficiency. Molecular diagnostics represented the largest technology segment, reflecting the growing importance of nucleic acid-based testing, genetic analysis, biomarker detection, and precision medicine. These technologies are increasingly relevant across infectious diseases, oncology, genetic disorders, and disease monitoring, while advances in automation and integrated platforms are helping laboratories manage growing testing volumes and operational pressures.
Technological development is also expanding the role of IVD beyond conventional centralized laboratory testing. Molecular assays, multiplex platforms, microfluidics, miniaturized systems, and connected POC technologies are enabling faster testing closer to patients, while AI and digital pathology are improving image analysis, data interpretation, and workflow automation. In May 2026, Roche agreed to acquire PathAI to strengthen AI-enabled digital pathology and precision diagnostics capabilities. Similarly, in March 2026, Integrated DNA Technologies launched Archer FUSIONPlex-HT Dx and VARIANTPlex HT Dx, expanding its presence in NGS-based IVD and oncology diagnostics. Advances in molecular testing are also supporting applications in infectious disease, with automated and multiplex assays enabling rapid identification of pathogens that are difficult to detect with conventional methods. The increasing adoption of decentralized and home-based testing further reinforces demand for compact, simplified, and connected diagnostic platforms.
Technology and innovation are expected to remain major competitive differentiators as manufacturers seek to improve diagnostic performance while addressing affordability, portability, ease of use, and laboratory productivity. The reagents segment accounted for a significant market share, highlighting the importance of recurring assay and consumable demand, while instruments are expected to register faster growth as laboratories invest in automation, higher throughput, and integrated workflows. Overall, the market is shifting toward integrated diagnostic ecosystems combining reagents, instruments, molecular technologies, automation, software, connectivity, and AI.
Regulatory complexity and the absence of globally harmonized standards represent a significant restraint on the growth of the IVD market. IVD products require rigorous evaluation of analytical and clinical performance, safety, manufacturing quality, labeling, and post-market surveillance as their results directly influence diagnosis, treatment selection, and patient management. Differences in regulatory classification, evidence requirements, documentation, and approval pathways across countries increase development and compliance costs and can extend commercialization timelines. Companies operating across multiple markets often must adapt their products and supporting evidence to regional requirements, creating additional operational complexity. These challenges are particularly relevant for small and emerging diagnostic companies, which may have limited financial and regulatory resources.
The evolving regulatory environment is especially significant in Europe following the implementation of the In Vitro Diagnostic Regulation (IVDR), which introduced more stringent requirements for clinical evidence, performance evaluation, conformity assessment, and post-market surveillance. Limited notified-body capacity and evolving interpretations of regulatory requirements have added complexity to certification and transition processes for certain products. Moreover, differences among regulatory frameworks, such as those of the U.S. Food and Drug Administration (FDA), the European Union IVDR, and national authorities, can influence product development strategies, launch sequencing, and geographic expansion. Regulatory approval also needs to be followed by commercial adoption, as manufacturers may need to meet separate reimbursement and health technology assessment requirements to establish the economic value of diagnostic products. Although regulatory requirements are essential for ensuring diagnostic reliability and patient safety, fragmented frameworks, evolving compliance obligations, lengthy validation processes, and uncertain reimbursement pathways can increase costs and delay the adoption of innovative IVD technologies.
The integration of AI, machine learning, and digital technologies into diagnostic workflows is creating significant opportunities for the IVD market. AI-enabled systems can automate data interpretation, image analysis, pathology assessment, and laboratory workflows, improving diagnostic consistency, operational efficiency, and turnaround times. The promising opportunity is particularly relevant to oncology and digital pathology, where large volumes of complex diagnostic data require efficient interpretation. Roche’s agreement to acquire PathAI in May 2026 highlights increasing industry investment in AI-driven pathology and precision diagnostics. As laboratories face growing testing volumes and workforce constraints, AI-enabled interpretation, laboratory automation, and digitally connected platforms are expected to improve clinical decision-making.
The increasing decentralization and digitalization of diagnostic testing is creating another important avenue for market expansion. Portable analyzers, automated POC platforms, connected devices, and simplified testing workflows are enabling selected diagnostic procedures to move closer to patients and outside conventional laboratories. At-home and OTC testing is also gaining importance as consumers seek greater convenience and faster access to diagnostic information. For manufacturers, this creates opportunities to develop compact, automated, user-friendly, and connected IVD platforms that combine testing with digital data capture and remote clinical communication.
Market Opportunities
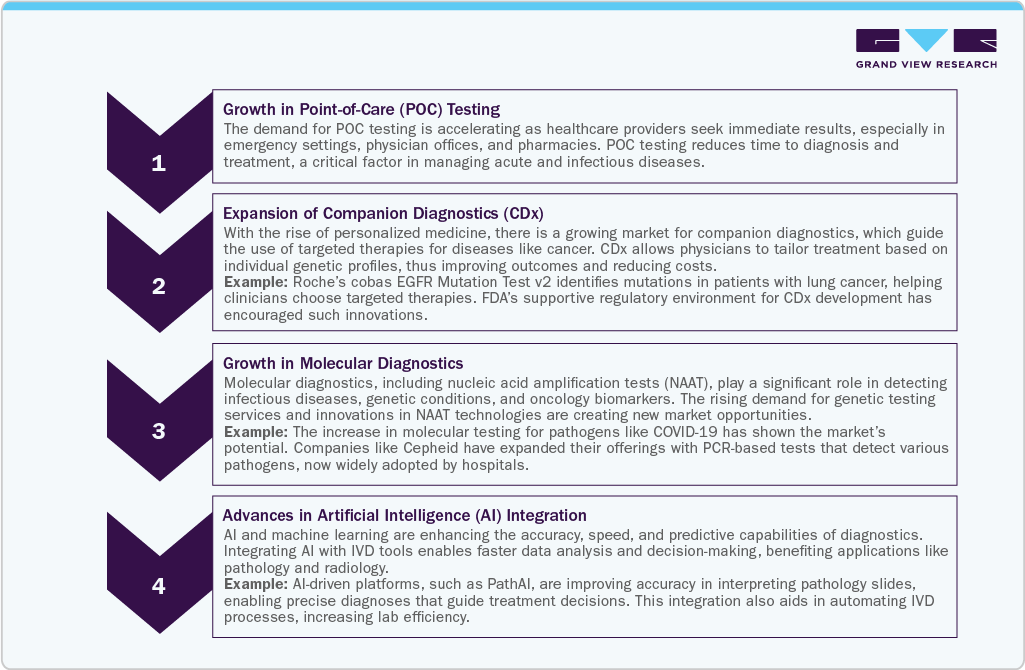
The in vitro diagnostics industry is experiencing substantial growth and offers multiple opportunities, driven by technological advancements, an increasing emphasis on personalized medicine, and a demand for rapid diagnostics. The following figure describes the detailed opportunity analysis for IVD, along with examples:
 To learn more about this report, Download Free Sample Report
Market Concentration & Characteristics
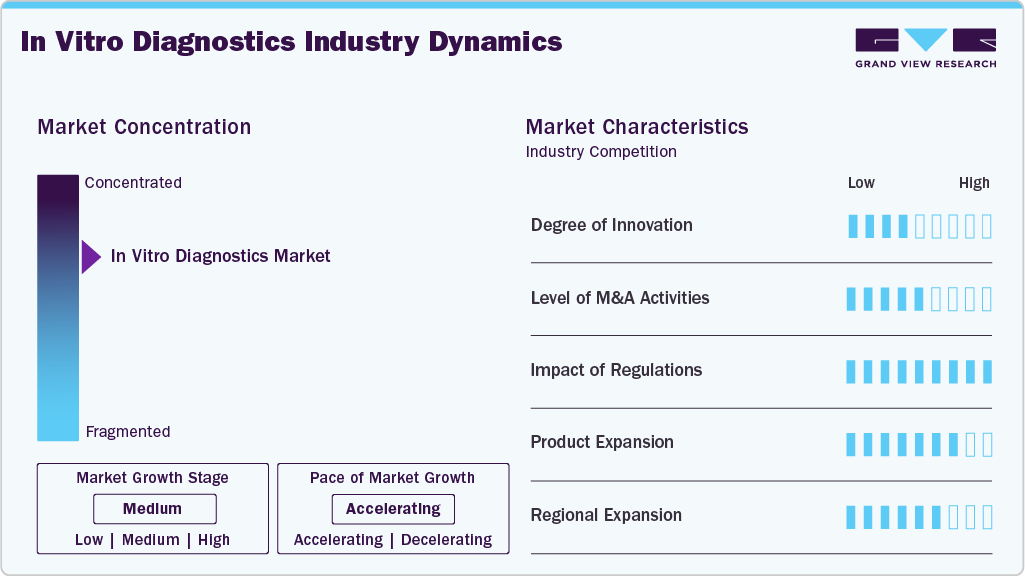
The IVD market is characterized by a high degree of technological innovation, with manufacturers continuously investing in molecular diagnostics, next-generation sequencing (NGS), immunoassays, clinical chemistry, digital pathology, and point-of-care (POC) testing. R&D increasingly focuses on improving analytical accuracy, sensitivity, turnaround time, workflow efficiency, and ease of use while expanding diagnostic applications. Integration of artificial intelligence (AI) and machine learning is gaining importance in digital pathology, image analysis, biomarker interpretation, and clinical decision support. For example, Roche agreed to acquire PathAI in May 2026 for USD 750 million upfront plus up to USD 300 million in milestone payments, strengthening its AI-enabled digital pathology and diagnostics capabilities.
Innovation is also expanding IVD applications beyond conventional diagnosis toward early detection, disease monitoring, and personalized healthcare. Developments in liquid biopsy, companion diagnostics, biomarker testing, MRD assessment, and automated sequencing are creating opportunities in precision medicine and oncology. Roche's planned acquisition of SAGA Diagnostics, announced in April 2026, is expected to add a tumor-informed MRD platform combining whole-genome sequencing and digital PCR. Roche also received CE Mark approval in 2026 for its Elecsys ApoE4 immunoassay, which identifies ApoE4 carriers from a blood sample, highlighting the expanding role of minimally invasive, biomarker-based diagnostics.
 To learn more about this report, Download Free Sample Report
M&A activity remains an important competitive strategy as leading companies seek to strengthen technology capabilities, expand portfolios, and access higher-growth applications. In March 2026, Abbott acquired Exact Sciences, strengthening its cancer diagnostics portfolio by adding capabilities in molecular oncology and early cancer detection. Overall, competition is shaped by R&D, product launches, regulatory approvals, collaborations, and M&A. Large companies leverage global distribution, regulatory expertise, and financial resources, while specialized technology companies contribute differentiated solutions. Increasing convergence of IVD with genomics, AI, digital health, and precision medicine is expected to sustain portfolio expansion and technology-focused investment.
Analyst Perspective
The IVD market is expanding as chronic and infectious diseases increase demand for timely, accurate, and accessible testing. Aging populations, preventive healthcare, and personalized medicine are further supporting demand for advanced diagnostics. Molecular diagnostics, point-of-care testing, NGS, immunoassays, microfluidics, and digital technologies are improving testing speed, sensitivity, automation, and accessibility. AI, data analytics, and connected platforms are enhancing result interpretation and clinical decision-making, while decentralized and home-based testing is extending diagnostics beyond traditional laboratories. Manufacturers are increasingly developing integrated, automated, and user-friendly platforms that improve turnaround times and workflow efficiency. Future market development will depend on technological innovation, regulatory and reimbursement support, affordability, laboratory automation, and integration with decentralized and personalized healthcare models.
The Evolving Role of In Vitro Diagnostics in Healthcare Delivery
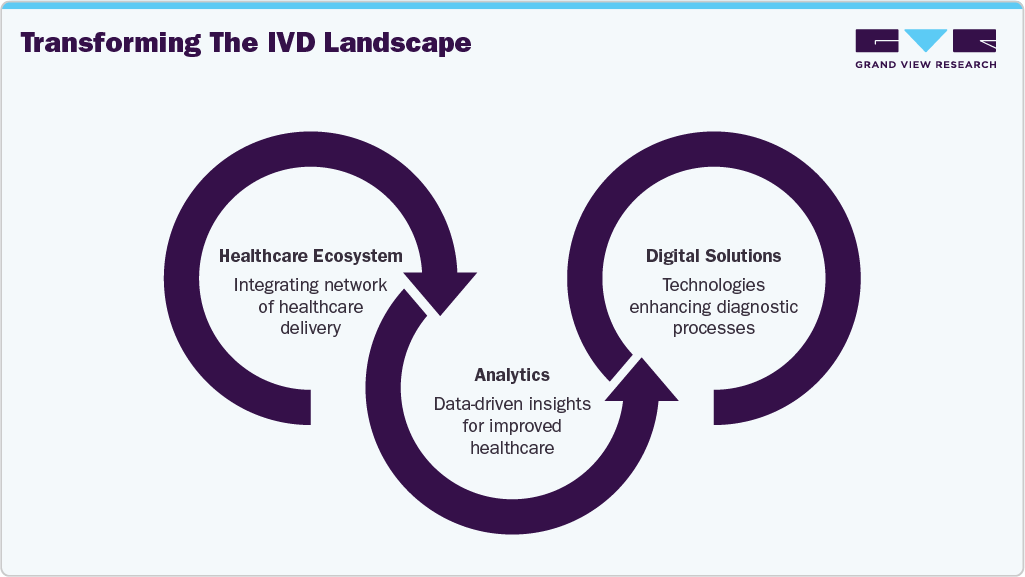
The in vitro diagnostics (IVD) industry is evolving from its traditional role as a back-office, pay-for-service function to becoming a central player within the healthcare delivery system. This transformation is fueled by three key trends that are generating significant opportunities for digital solutions and analytics to redefine the IVD landscape.
 To learn more about this report, Download Free Sample Report
Enhancing Diagnostic Tests: Healthcare systems are increasingly emphasizing diagnostic tests that provide clinically meaningful, outcome-oriented insights. Rather than providing isolated measurements, diagnostics are expected to connect results with patient outcomes, such as linking reductions in HbA1c levels with lower complication risks. Integrating patient history, local clinical context, and longitudinal trends can further transform test results into actionable insights, enabling more personalized assessments and supporting informed clinical decision-making.
Revolutionizing Care Delivery: Diagnostics is increasingly shaping healthcare delivery through the adoption of home-based and virtual care, greater emphasis on preventive screening, and the shift toward personalized medicine. Emerging diagnostic workflows support remote testing while maintaining accuracy and quality, and cost-effective, high-accuracy screening tools enable earlier disease detection. In parallel, advanced IVD panels incorporating molecular and biomarker-based testing can support treatment selection tailored to individual patients, improving clinical decision-making and patient outcomes.
Expanding Diagnostics Role in Healthcare:The role of diagnostics is expanding beyond conventional disease detection, creating greater value across healthcare delivery and IVD development. Diagnostics increasingly support pandemic preparedness while also contributing to drug development and precision medicine. Companion diagnostics, in particular, help identify patients most likely to benefit from targeted therapies or those at greater risk of adverse reactions, enabling more informed treatment selection and improving therapeutic outcomes.
Supply Chain Analysis
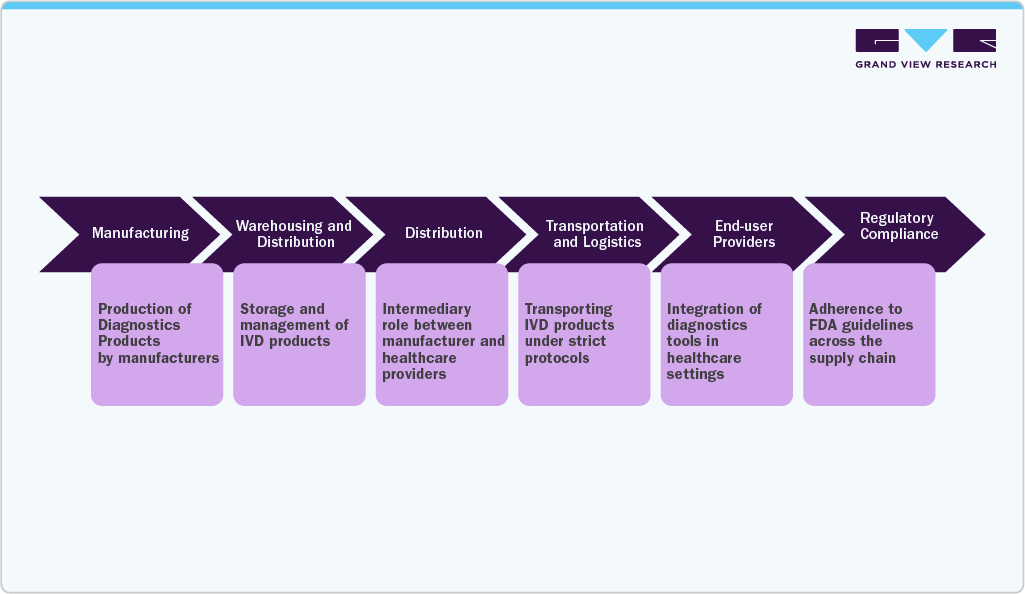
The IVD supply chain encompasses a series of interconnected activities that facilitate the efficient movement of diagnostic products from manufacturers to healthcare providers and end users. It typically includes manufacturing, warehousing, distribution, transportation, and end-use application. Each stage is shaped by regulatory requirements, product quality standards, demand patterns, and the need for timely availability, which is particularly important for settings requiring rapid diagnostic results, including emergency and urgent care.
 To learn more about this report, Download Free Sample Report
Distribution Channel
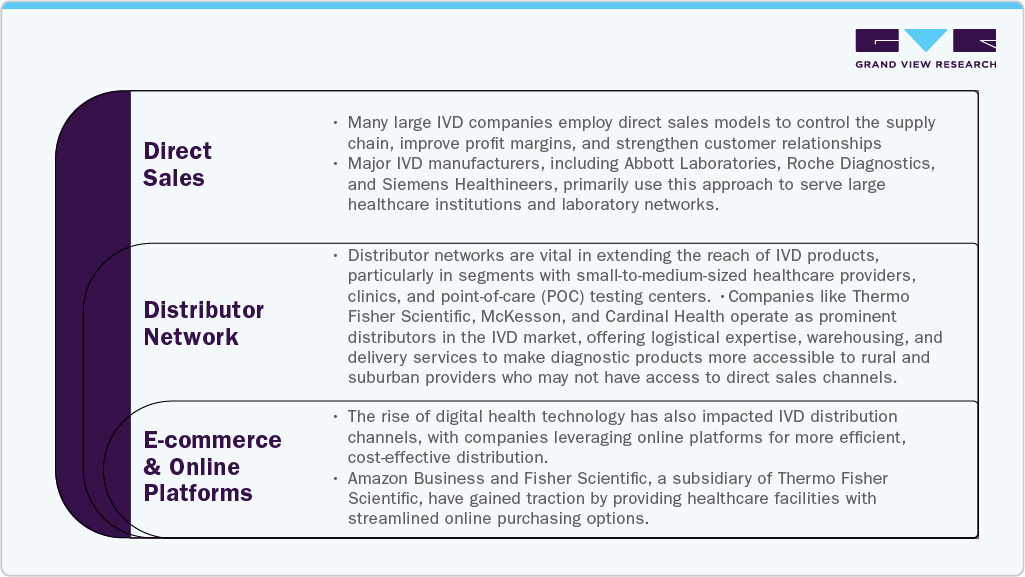
The distribution channels in the IVD market play a critical role in determining how efficiently diagnostic products reach healthcare facilities, laboratories, and end users. IVD products, including reagents, instruments, and diagnostic systems, are primarily distributed through direct sales, third-party distributors, and e-commerce platforms.
Large manufacturers such as Abbott, Roche Diagnostics, and Siemens Healthineers commonly rely on direct sales, particularly for high-value and complex equipment. This model enables greater control over customer relationships and supports installation, technical training, maintenance, customization, and after-sales services, while strengthening customer retention.
 To learn more about this report, Download Free Sample Report
Distributors provide broader market coverage, particularly among smaller hospitals, clinics, laboratories, and point-of-care testing centers across geographically dispersed markets. Companies such as Thermo Fisher Scientific, McKesson, and Cardinal Health provide warehousing, logistics, inventory management, and delivery capabilities and often offer products from multiple manufacturers.
E-commerce is also becoming increasingly relevant, particularly for reagents, consumables, and lower-complexity diagnostic products. Platforms such as Amazon Business and Fisher Scientific facilitate streamlined procurement, pricing transparency, and faster fulfillment. The growing adoption of digital purchasing is improving procurement efficiency and expanding access to IVD products across customer segments.
Pricing Analysis
Pricing of IVD products varies according to product type, technological complexity, performance characteristics, and intended application. Instruments such as automated analyzers and molecular diagnostic platforms generally entail higher upfront costs due to advanced technology, automation, and system integration, and manufacturers often provide associated maintenance and service contracts.
Reagent pricing is based on a consumption-based model, with costs influenced by assay complexity, sensitivity, specificity, and testing volume. Molecular diagnostic and high-performance immunoassay reagents typically command premium prices, whereas routine clinical chemistry and hematology reagents are generally more competitively priced.
The following table outlines typical pricing ranges for IVD instruments and reagents:
Product Type
Category
Price Range (USD)
Pricing Notes
Instruments
Clinical Chemistry Analyzers
USD 15,000 - USD 200,000
Pricing varies based on throughput and automation levels.
Immunoassay Analyzers
USD 19,500 - USD 250,000
Higher-end models offer multiplexing and enhanced sensitivity.
Molecular Diagnostics Platforms
USD 50,000 - USD 500,000
Premium pricing due to advanced technology and versatility.
Hematology Analyzers
USD 5,000 - USD 360,000
Costs depend on throughput and parameters analyzed.
Reagents
Clinical Chemistry Reagents
USD 1 - USD 20 per test
High-volume, lower-margin consumables.
Immunoassay Reagents
USD 5 - USD 100+ per test
Priced higher due to assay complexity and specificity.
Molecular Diagnostic Reagents
USD 20 - USD 100+ per test
High pricing reflects complex assays (e.g., PCR, NGS).
Hematology Reagents
USD 0.50 - USD 5 per test
Lower-cost consumables for routine blood analysis.
Product Insights
The reagents segment dominated the in vitro diagnostics market, accounting for 65.7% of global revenue in 2025, driven by the recurring nature of reagent consumption, the broad application of IVD testing across disease areas, and continued R&D activities focused on developing more sensitive, specific, and application-specific assays. Increasing demand for molecular, immunoassay, clinical chemistry, and other diagnostic tests is supporting the commercialization of new reagents and assay kits. The growing adoption of automated and high-throughput testing platforms is also driving demand for compatible reagent systems to improve workflow efficiency and testing capacity. In addition, the expansion of biomarker-based testing and precision medicine is encouraging manufacturers to develop specialized reagents for applications such as infectious disease detection, oncology, genetic testing, and disease monitoring.
The instruments segment is anticipated to grow at the fastest CAGR over the forecast period, supported by advances in laboratory automation, rising testing volumes, workforce constraints, and demand for higher-throughput, more efficient diagnostic workflows. Recent product developments increasingly focus on automation, scalability, throughput, and reduced hands-on requirements. For instance, in March 2026, Roche received FDA 510(k) clearance for the cobas c 703 and cobas ISE neo analytical units, which form part of its modular cobas pro integrated solutions. The cobas c 703 can process up to 2,000 tests per hour and accommodate up to 70 reagent positions, while the cobas ISE neo can process up to 1,800 tests per hour and features automated maintenance to reduce hands-on time. The launch illustrates the industry's shift toward high-throughput and automated IVD systems capable of addressing increasing testing volumes and laboratory staffing constraints.
Innovation in IVD instrumentation is also extending into molecular diagnostics and next-generation sequencing. In July 2026, Roche highlighted its new AXELIOS next-generation sequencing platform, along with other laboratory automation, digital pathology, and AI-enabled diagnostic technologies, at ADLM 2026. Such developments reflect the increasing convergence of advanced analytical technologies, automation, and data-driven workflows within clinical laboratories.
Technology Insights
The molecular diagnostics segment dominated the in vitro diagnostics industry, accounting for 25.8% of global revenue in 2025, supported by the increasing use of nucleic acid-based testing for pathogen identification, genetic analysis, biomarker detection, and disease monitoring. Molecular diagnostic technologies enable sensitive and specific detection of disease-associated genetic material and are increasingly being incorporated into infectious disease testing, oncology, genetic testing, and precision medicine workflows. PCR remains a widely adopted molecular diagnostic technology, while next-generation sequencing (NGS), digital PCR, and other advanced molecular platforms are expanding the range of clinically actionable applications. The growing adoption of molecular testing in decentralized settings is also driving market development, particularly as manufacturers introduce automated, integrated platforms that reduce workflow complexity and turnaround times.
The coagulation segment is anticipated to grow at the fastest CAGR over the forecast period. Coagulation diagnostics play an important role in evaluating hemostasis and identifying abnormalities in blood-clotting pathways, supporting the diagnosis and management of bleeding and thrombotic disorders. Demand for coagulation testing is driven by the rising prevalence of cardiovascular and blood-related disorders, the growing need to monitor anticoagulant therapy, and ongoing improvements in automated hemostasis analyzers. Modern coagulation systems increasingly incorporate automated sample handling, integrated testing workflows, high-throughput processing, and digital connectivity to improve laboratory efficiency and reduce manual intervention.
Application Insights
The infectious diseases segment dominated the IVD market in 2025, driven by the ongoing need for rapid, accurate pathogen detection across hospitals, laboratories, and decentralized care settings. The adoption of multiplex molecular assays capable of identifying multiple respiratory pathogens, including influenza A/B, COVID-19, and RSV, from a single patient sample is a key driver of segment growth. As laboratories optimize their diagnostic infrastructure following elevated pandemic-era investment, IVD companies are also seeking growth beyond respiratory testing. Expansion into high-burden conditions, including lower respiratory tract infections, streptococcal infections, tuberculosis, and other infectious diseases, could provide opportunities across both developed and emerging markets.
The oncology segment is anticipated to grow at the fastest CAGR over the forecast period, reflecting the rising global cancer burden and increasing demand for more precise diagnostic and monitoring solutions. The expanding focus on early detection, biomarker identification, treatment selection, and monitoring of residual disease is broadening the role of IVD beyond conventional cancer diagnosis. Advances in next-generation sequencing, digital pathology, AI-enabled image analysis, and multiplex biomarker testing are supporting more comprehensive tumor characterization while improving laboratory workflow efficiency. In addition, liquid biopsy approaches, including circulating tumor DNA-based testing, are gaining importance as they enable minimally invasive molecular profiling and longitudinal disease monitoring. The growing integration of these technologies into precision oncology is expected to create new opportunities for IVD manufacturers, particularly in companion diagnostics, treatment-response assessment, and early-stage cancer detection.
Test Location Insights
The PoC segment held the largest share of the IVD industry in 2025, as clinical laboratories and centralized testing facilities continue to be the core of diagnostic testing, supporting high testing volumes and accommodating complex, specialized, and confirmatory assays that are not always suitable for decentralized formats. Hospitals, reference laboratories, public health laboratories, and other institutional facilities also continue to invest in automated analyzers, molecular diagnostic platforms, and integrated laboratory workflows to improve throughput and operational efficiency. The increasing decentralization of diagnostics is reshaping the role of conventional laboratories. As routine and selected rapid tests move closer to patients with home care services, centralized laboratories are increasingly focused on high-complexity testing, specialized assays, confirmatory testing, and advanced molecular and genomic applications. This creates ongoing opportunities for IVD manufacturers to offer high-throughput, automated, and digitally connected laboratory solutions.
The home care segment is expected to grow at the fastest CAGR over the forecast period, supported by growing consumer acceptance of self-testing and increasing availability of reliable diagnostic solutions outside traditional healthcare facilities. Home-based testing can improve accessibility, reduce the need for in-person visits, and enable patients to obtain results more rapidly for selected conditions. In addition to infectious disease testing, manufacturers are expanding home and near-patient applications across areas such as chronic disease monitoring, women’s health, cardiometabolic conditions, and other routine diagnostics. As healthcare systems place greater emphasis on convenient and decentralized care, continued innovation in easy-to-use, digitally connected, and clinically reliable home-testing solutions is expected to support segment growth.
End Use Insights
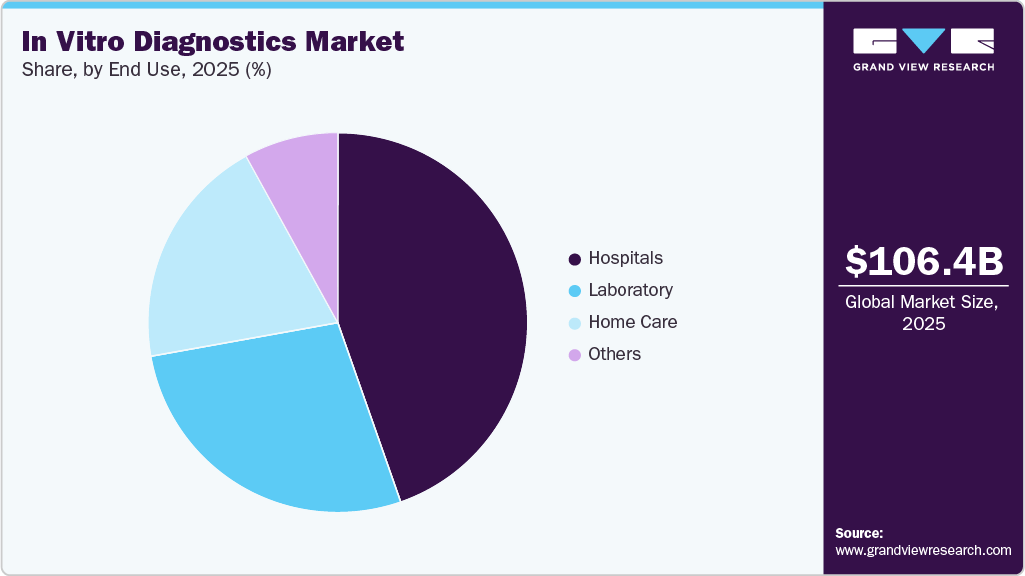
The hospital segment held the largest share of the global IVD market in 2025, reflecting its role as a major center for routine, specialized, and urgent diagnostic testing. Hospitals require a broad range of IVD solutions to support diagnosis, treatment selection, disease monitoring, and clinical decision-making across multiple specialties. The continued expansion and modernization of hospital infrastructure, particularly in emerging economies, is also supporting demand for laboratory analyzers, molecular diagnostic platforms, immunoassays, clinical chemistry systems, and other automated testing technologies. In addition, hospitals are increasingly adopting high-throughput and integrated diagnostic systems to manage growing test volumes while addressing workforce constraints and the need for faster turnaround times. The continued development of hospital-based oncology, infectious disease, cardiology, and critical-care services is expected to sustain demand for IVD testing. In addition, the increasing adoption of point-of-care testing in hospitals is enabling selected diagnostic procedures to be performed closer to patients, while centralized laboratories continue to handle complex and high-volume testing.
 To learn more about this report, Download Free Sample Report
The home care segment is expected to grow at the fastest CAGR over the forecast period, supported by increasing consumer acceptance of self-testing and the expansion of diagnostic technologies designed for use outside conventional healthcare settings. Advances in molecular diagnostics, biosensors, connected devices, and simplified sample-collection methods are enabling patients with limited professional assistance to perform a broader range of tests. Beyond infectious disease testing, home-based diagnostics are increasingly being explored for areas such as women’s health, chronic disease monitoring, cardiometabolic conditions, and other routine health assessments. The growing integration of home tests with digital health platforms can further support remote monitoring by allowing results to be captured and shared with healthcare providers. This shift toward decentralized and patient-centric care, combined with the convenience of avoiding unnecessary healthcare visits, is expected to support continued investment in homecare IVD solutions.
Regional Insights
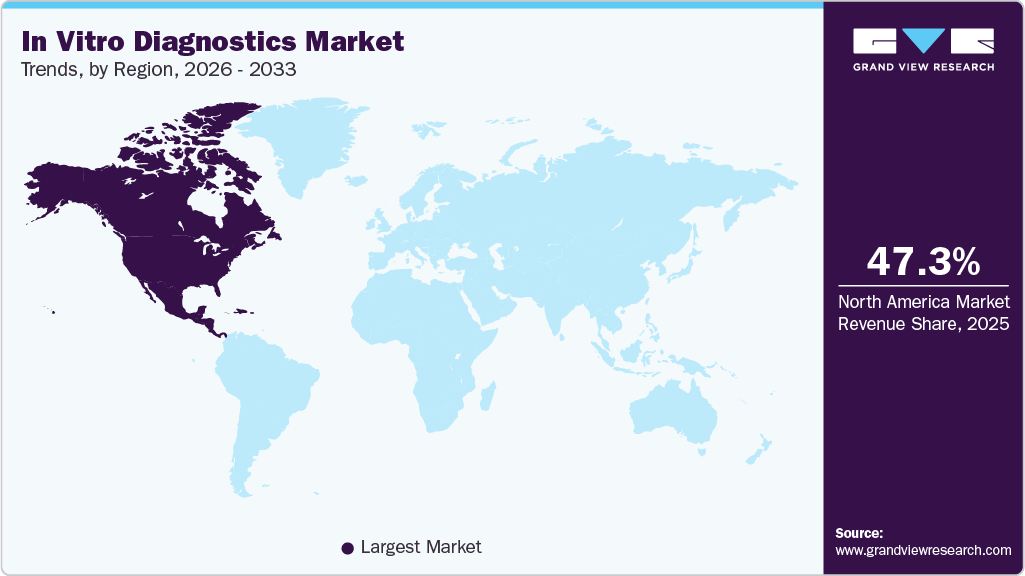
North America dominated the global in vitro diagnostics market in 2025, accounting for 47.3% of total revenue, owing to its well-established laboratory infrastructure, high diagnostic testing volumes, strong adoption of advanced technologies, and substantial healthcare expenditure. The growing burden of chronic diseases continues to support demand for diagnostic testing, particularly for cardiovascular conditions, cancer, diabetes, and other diseases requiring regular screening and monitoring. In addition, increasing adoption of molecular diagnostics, genetic testing, and other precision-medicine technologies is expanding the range of applications for IVD solutions. The region also benefits from a strong presence of leading diagnostic companies and an established ecosystem for research, clinical development, regulatory approvals, and commercialization.
 To learn more about this report, Download Free Sample Report
The U.S. in vitro diagnostics market accounted for the largest share of North America in 2025, supported by its advanced healthcare infrastructure, high diagnostic utilization, and presence of major industry participants such as Roche Diagnostics, Abbott, and Danaher. Continued investment in R&D is supporting the development and adoption of molecular diagnostics, next-generation sequencing, companion diagnostics, and other advanced testing technologies. The country’s substantial cancer and chronic disease burden further sustains demand for screening, diagnosis, treatment selection, and disease monitoring. The combination of a sophisticated healthcare system, a strong diagnostic technology base, and continued innovation is expected to keep the U.S. the leading national market for IVD solutions.
Europe In Vitro Diagnostics Market Trends
Europe is experiencing continued expansion of the in vitro diagnostics industry, supported by the growing adoption of molecular diagnostics, precision medicine, and advanced laboratory technologies. PCR and next-generation sequencing (NGS) are increasingly important across oncology, infectious disease, genetic testing, and biomarker analysis, enabling more targeted diagnosis and treatment decisions. The region also has a well-established network of hospitals, clinical laboratories, and reference testing facilities that support demand for both routine and specialized IVD solutions. In addition, healthcare systems are placing greater emphasis on laboratory automation, faster turnaround times, and decentralized testing to improve diagnostic capacity and address operational pressures. Leading companies, including Roche, Thermo Fisher Scientific, Illumina, bioMérieux, and QIAGEN, continue to expand their diagnostic portfolios through product development, regulatory approvals, and strategic investments.
The UK IVD market is supported by its established healthcare infrastructure, extensive laboratory network, and continued efforts to improve diagnostic capacity within the National Health Service (NHS). The growing emphasis on earlier disease detection, precision medicine, and faster access to diagnostic testing is reinforcing demand for molecular diagnostics. NHS initiatives aimed at expanding diagnostic capacity and reducing waiting times are also encouraging investment in laboratory infrastructure, automation, and decentralized testing.
The in vitro diagnostics market in France is witnessing continued growth, driven by technological advances, an established healthcare system, and rising demand for rapid and specialized diagnostics. The market is also benefiting from investment in technologies that can bring sophisticated testing capabilities closer to patients. For example, in January 2025, bioMérieux acquired SpinChip Diagnostics, adding a compact near-patient diagnostic platform capable of delivering high-sensitivity results from whole-blood samples within approximately 10 minutes. France's established presence of global IVD manufacturers and growing adoption of advanced testing technologies are expected to support market growth.
The growth of the Germany IVD market is supported by its advanced healthcare infrastructure, extensive laboratory network, and strong industrial and research base. Adoption of PCR, NGS, and other molecular technologies is expanding diagnostic capabilities across infectious diseases, oncology, genetic disorders, and precision medicine. Germany's strong biotechnology and medical technology ecosystem provides a favorable environment for the development and commercialization of advanced diagnostic platforms. Continued integration of molecular testing, digital technologies, and automated laboratory systems is expected to contribute to the development of the country's IVD market over the forecast period.
Asia Pacific In Vitro Diagnostics Market Trends
Asia Pacific is expected to remain the fastest-growing regional market for in vitro diagnostics over the forecast period, supported by a high burden of infectious and chronic diseases, expanding healthcare infrastructure, increasing diagnostic testing volumes, and rising adoption of molecular and other advanced technologies. The region's large and aging population is creating sustained demand for screening, disease monitoring, and early diagnosis, while improvements in laboratory infrastructure are expanding access to sophisticated testing in emerging economies. Infectious diseases, particularly tuberculosis, continue to represent an important area of unmet diagnostic need, while oncology and chronic disease management are creating additional demand for molecular diagnostics and biomarker-based testing. India, China, Japan, and other major markets are also strengthening domestic diagnostic capabilities through investments in healthcare infrastructure, local manufacturing, and technology development. The increasing adoption of automated analyzers, point-of-care platforms, molecular testing, and digitally connected diagnostic systems is expected to support regional growth further.
The China in vitro diagnostics marketis experiencing continued expansion, driven by rising healthcare expenditure, population aging, increasing diagnostic testing, and investments in domestic healthcare and biotechnology capabilities. The country is placing greater emphasis on early disease detection, precision medicine, and the development of advanced diagnostic technologies, particularly in oncology and molecular testing. Increasing adoption of PCR, next-generation sequencing, biomarker testing, and other molecular approaches is broadening the scope of diagnostic applications. China is also strengthening its domestic IVD ecosystem as manufacturers expand local R&D and product portfolios and healthcare institutions upgrade laboratory infrastructure.
The growth of the in vitro diagnostics market in Japan is supported by its aging population, high prevalence of cancer and chronic diseases, and sophisticated healthcare infrastructure. The country's demographic profile is increasing the need for screening, disease monitoring, and diagnostics associated with age-related conditions, while the growing focus on precision oncology is creating opportunities for molecular profiling and biomarker-based testing. Japan also has a strong research and pharmaceutical ecosystem that supports the development and adoption of advanced diagnostic technologies.
Latin America In Vitro Diagnostics Market Trends
Latin America is expected to experience continued growth, supported by expanding healthcare infrastructure, increasing diagnostic testing, and the gradual adoption of advanced technologies. The region continues to face a substantial burden of infectious diseases, while the rising prevalence of cancer, diabetes, cardiovascular conditions, and other chronic diseases is increasing demand for screening, diagnosis, and disease monitoring. Growing healthcare expenditure and efforts to strengthen diagnostic capacity are creating opportunities for IVD manufacturers, particularly in molecular diagnostics, immunoassays, and point-of-care testing.
The growth of Brazil IVD market is supported by its large population, extensive healthcare system, and substantial burden of infectious and chronic diseases. Conditions including dengue, tuberculosis, HIV, and other infectious diseases continue to generate demand for timely diagnostic testing, while the growing prevalence of cancer and diabetes is strengthening demand for screening and disease monitoring. Molecular diagnostics are gaining importance for their ability to provide sensitive and specific detection across a range of clinical applications, particularly in infectious diseases and oncology. Brazil's expanding laboratory network and investments in healthcare infrastructure are also supporting the adoption of automated and advanced diagnostic technologies.
Middle East and Africa In Vitro Diagnostics Market Trends
The Middle East & Africa (MEA) IVD market is expected to continue growing over the forecast period, owing to the persistent burden of infectious diseases, the rising prevalence of chronic conditions, and the ongoing development of healthcare infrastructure. Cancer, cardiovascular diseases, diabetes, and other noncommunicable diseases are increasing the need for screening, early diagnosis, treatment monitoring, and disease-management testing, while infectious diseases continue to sustain demand for pathogen detection and routine diagnostic services. Adoption is further supported by increasing awareness of preventive healthcare and the need for faster, more reliable testing. However, differences in healthcare infrastructure, affordability, reimbursement, and access to skilled personnel continue to influence technology adoption across the region.
The Saudi Arabia IVD market growth is supported by healthcare system modernization, increasing diagnostic requirements, and the growing burden of both communicable and noncommunicable diseases. Cardiovascular diseases, diabetes, cancer, and other chronic conditions are strengthening the demand for routine screening, disease monitoring, and specialized diagnostic testing. In addition, infectious disease surveillance continues to support demand for molecular and other pathogen-detection technologies. Government-led healthcare transformation and investments in healthcare infrastructure are encouraging the modernization of laboratories and the greater adoption of automated, digitally connected, and advanced diagnostic platforms.
Key In Vitro Diagnostics Company Insights
The global in vitro diagnostics market is highly competitive, with major players including Abbott, bioMérieux, F. Hoffmann-La Roche, Siemens Healthineers, Thermo Fisher Scientific, and Bio-Rad leading the way. These companies are focusing on technological advancements in molecular diagnostics, immunodiagnostics, and automation, while emphasizing digital connectivity and data analytics. Their strategies include new product launches, collaborations, and mergers to strengthen capabilities and expand into high-growth areas.
In addition to established firms, specialized companies such as ARUP Laboratories, RayBiotech, and Everlywell are driving innovation in laboratory testing and decentralized diagnostics. These smaller players often differentiate themselves with unique technologies and targeted solutions. As demand for rapid and specialized testing rises, partnerships and technological innovation are key competitive strategies in the industry.
Key In Vitro Diagnostics Companies:
The following key companies have been profiled for this study on the in vitro diagnostics market.
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Abbott; Bio-Rad Laboratories, Inc.; F. Hoffmann-La Roche Ltd.; Siemens Healthineers AG; bioMérieux SA; QuidelOrtho Corporation
- Mature IVD players focus on broad product portfolios, global distribution, acquisitions, automation, and long-term hospital/laboratory contracts. They invest heavily in R&D, regulatory compliance, companion diagnostics, and digital platforms while strengthening installed systems to ensure recurring revenue from reagents, consumables, and service agreements.
- Mature players benefit from strong brand recognition, established installed bases, regulatory expertise, large capital availability, global reach, and diversified diagnostics portfolios. Their economies of scale, long-standing customer relationships, and ability to integrate automation and precision medicine solutions create high barriers to entry for competitors.
- Mature players often face slower decision-making cycles, high operational costs, legacy systems, organizational complexity, and pricing pressure. Large-scale infrastructure can reduce agility in responding to market shifts, while dependence on established technologies may slow adaptation to emerging molecular, AI-driven, or decentralized diagnostic trends.
Emerging Players: Agilent Technologies, Inc.; Quidel Corporation; QIAGEN N.V.
- Emerging IVD players prioritize niche diagnostics, molecular testing, AI-enabled tools, precision medicine, partnerships, and faster product innovation. They commonly focus on underserved segments, agile commercialization, and strategic collaborations to scale technology adoption while incrementally expanding geographic presence and regulatory approvals.
- Emerging players possess agility, faster innovation, specialized expertise, and a strong focus on advanced technologies such as molecular diagnostics, liquid biopsy, and digital pathology. Their leaner organizational structures enable rapid market adaptation, while niche specialization helps them differentiate from larger competitors and address targeted diagnostic needs.
- Emerging players face limited global reach, smaller installed bases, lower brand recognition, regulatory barriers, funding constraints, and commercialization challenges. Dependence on partners, narrower product portfolios, and vulnerability to acquisition or competitive pressure from established leaders may restrict long-term market scalability and profitability.
Recent Developments
-
In January 2026, Illumina secured CMS reimbursement for TruSight Oncology Comprehensive, expanding access to NGS-based precision oncology testing. Effective January 1, 2026, the test received a defined Medicare reimbursement pathway under the Clinical Laboratory Fee Schedule, supporting broader clinical adoption of comprehensive genomic profiling for cancer biomarker identification and treatment selection.
-
In March 2026, QIAGEN received U.S. FDA clearance for its gastrointestinal panels on the fully automated QIAstat-Dx Rise syndromic testing system. The clearance enables laboratories to run respiratory and gastrointestinal panels on a single scalable platform capable of processing up to 160 tests per day, strengthening automation and throughput in molecular infectious-disease diagnostics.
-
In March 2026, Illumina and Labcorp expanded their collaboration to broaden access to precision oncology testing. The partnership will support distributed cancer biomarker testing, generate evidence for payer coverage, and develop new comprehensive genomic profiling and whole-genome sequencing tests addressing unmet clinical needs, reinforcing the role of NGS-based IVDs in decentralized precision oncology.
“These new partnerships represent an important step in strengthening QIAGEN’s leadership in oncology by aiming to bring innovative MRD technologies into clinical practice. “We want to, in particular, strengthen our scalable, cost-effective solutions based on our QIAcuity digital PCR system and enable laboratories and healthcare providers worldwide to use MRD insights for guiding personalized treatment decisions for cancer patients.”
- said Jonathan Arnold, Vice President, Head of Precision Partnering Diagnostics at QIAGEN
-
In June 2026, bioMérieux submitted the BIOFIRE FILMARRAY Gastrointestinal 1.1 Panel and Gastrointestinal 1.1 Panel Mid to the U.S. FDA for 510(k) review. The PCR-based panels are designed to detect 22 and 11 gastrointestinal pathogens, respectively, from a single sample, with results available in approximately one hour, supporting continued expansion of multiplex infectious-disease diagnostics.
“As recently announced, ABL Diagnostics continues to strengthen and expand its presence in molecular testing and precision medicine by integrating the high-quality expertise developed over many years by a highly experienced team of professionals in Luxembourg into our own state-of-the-art molecular diagnostics portfolio. This means great things for all of our customers around the world and better outcomes for their patients.”
-Dr. Chalom B. Sayada, Managing Director of ABL Diagnostics
-
In June 2026, bioMérieux submitted a Dual 510(k)/CLIA Waiver application to the U.S. FDA for the BIOFIRE SPOTFIRE Vaginitis Panel. The automated multiplex PCR test is designed to simultaneously detect common causes of vaginitis in approximately 20 minutes at the point of care, expanding the SPOTFIRE platform into women’s and sexual health diagnostics.
“QIAGEN has the only offering of both comprehensive and targeted syndromic panels for gastrointestinal testing. This provides dramatically new ways for clinicians to approach important diagnostic evaluations in inpatient and outpatient care. Our range of panels enables healthcare professionals to tailor testing to their specific needs, ensuring fast and accurate diagnosis while supporting better treatment decisions.”
-Nadia Aelbrecht, Vice President and Head of the Syndromic Testing Franchise at QIAGEN.
-
In July 2026, ABL Diagnostics announced the UltraGene Respiratory Pathogens 21 following CE-IVD registration by ABL SA Luxembourg. The development expands ABL Diagnostics’ PCR-based respiratory testing portfolio and strengthens its syndromic molecular diagnostics offering, supporting broader detection of respiratory pathogens through its UltraGene platform.
"Many patients are uncomfortable with the intimate nature of a pelvic exam; also, many people live in areas without a local doctor or clinician trained to obtain a sample with a speculum. The option to self-collect in a clinical setting can help women overcome some of these barriers."
-Dr. Jeff Andrews, board-certified gynecologist and vice president of Global Medical Affairs for Diagnostic Solutions at BD.”
-
In August 2026, QIAGEN received U.S. FDA clearance for the QIAstat-Dx BCID GPF Plus AMR Panel, its first QIAstat-Dx panel for bloodstream infections. The multiplex molecular panel detects 20 pathogen targets and 10 antimicrobial resistance markers from positive blood cultures in about one hour, expanding QIAGEN’s U.S. syndromic testing portfolio into bloodstream infection diagnostics.
“The medical community continues to bring enhanced technology closer to patients, allowing clinicians to have more information to make real-time decisions. Regarding strep throat, Group A Streptococcus accounts for approximately 20% of sore throat cases and has historically been diagnosed via antigen tests. Including it on this PCR panel with common viral causes of strep throat, including rhinovirus, represents a step forward in healthcare, ultimately increasing diagnostic yield and removing the need to reflex to culture in most patients.”
-Dr. Charles K. Cooper, Executive Vice-President, Chief Medical Officer
Value Chain Analysis
The in vitro diagnostics market value chain extends from raw material and reagent suppliers to technology and platform providers, IVD manufacturers, distributors, clinical laboratories, healthcare providers, and patients. Each stage contributes to the development, commercialization, delivery, and clinical utilization of diagnostic tests. The value chain is increasingly characterized by integration among reagents, instruments, software, and testing services, as manufacturers seek to improve workflow efficiency, automate laboratory processes, and deliver faster, more actionable diagnostic results.
Raw Material and Reagent Suppliers: The upstream stage comprises suppliers of biological, chemical, and consumable inputs required for diagnostic testing. Key materials include enzymes, antibodies, antigens, nucleotides, primers, probes, buffers, substrates, calibrators, controls, plastics, membranes, and sample collection components. Product quality, consistency, purity, and supply reliability are critical as variations in raw materials can affect assay performance and regulatory compliance. Suppliers of specialized biological inputs or proprietary components can hold strategically important positions, particularly in molecular diagnostics, immunoassays, and advanced biomarker testing.
Technology and Platform Providers: Technology providers supply the platforms and components that enable diagnostic testing, including PCR and digital PCR systems, next-generation sequencing (NGS) platforms, microfluidics, biosensors, automation technologies, imaging systems, laboratory information systems, and diagnostic software. These technologies support sample preparation, amplification, sequencing, detection, image analysis, data processing, and result interpretation. Increasing integration of automation, artificial intelligence, digital connectivity, and software is shifting value creation toward complete diagnostic workflows. Platform providers therefore differentiate through throughput, analytical performance, interoperability, ease of use, and workflow integration.
IVD Manufacturers: IVD manufacturers represent the central commercial stage of the value chain, converting raw materials and technologies into marketable diagnostic products. These companies develop instruments, reagents, assays, test kits, controls, calibrators, and consumables across molecular diagnostics, immunodiagnostics, clinical chemistry, hematology, microbiology, coagulation, and other testing areas. Manufacturers invest in assay development, instrument engineering, clinical validation, regulatory submissions, manufacturing scale-up, and quality management. Growing demand for automation, multiplex testing, decentralized diagnostics, precision medicine, and high-throughput testing is encouraging manufacturers to develop integrated platforms rather than standalone products. Recurring reagent and consumable requirements also provide an important source of ongoing revenue.
Distribution and Commercialization: Once developed and approved, IVD products reach customers through direct sales, distributors, laboratory suppliers, hospital procurement systems, and specialized channels. Large hospitals and reference laboratories may purchase directly from manufacturers through institutional or long-term agreements, while distributors remain important for smaller laboratories, physician practices, and geographically dispersed facilities. Commercial value is also supported by installation, calibration, technical support, operator training, maintenance, reagent supply, and application assistance. For sophisticated analyzers and molecular platforms, after-sales service is an important factor in customer retention and long-term adoption.
Clinical Laboratories and Diagnostic Service Providers: Clinical laboratories are a critical downstream component, transforming diagnostic products into testing services and clinically interpretable results. Centralized, hospital, reference, public health, and specialized laboratories perform routine, specialized, and confirmatory testing across infectious diseases, oncology, genetic disorders, chronic diseases, and other applications. Laboratories increasingly prioritize automation, throughput, turnaround time, workflow integration, accuracy, interoperability, and total cost of ownership when selecting IVD systems. Laboratory information systems, connected analyzers, automated sample handling, and digital workflows are further strengthening integration between instruments, software, and laboratory operations.
Healthcare Providers and Clinical Decision-Making: Physicians, hospitals, diagnostic centers, and other healthcare providers use IVD results to support disease detection, diagnosis, screening, treatment selection, disease monitoring, and assessment of treatment response. The value of an IVD product, therefore, extends beyond analytical performance to its ability to generate clinically relevant information within an appropriate timeframe. Molecular profiling, biomarker testing, and companion diagnostics are increasing IVD's role in precision medicine, particularly in oncology. Point-of-care and decentralized testing also enable selected diagnostic decisions to be made closer to the patient, reducing reliance on centralized laboratories when rapid results are required.
Patients and End Users: Patients represent the ultimate beneficiaries and increasingly direct users of IVD products. While traditional laboratory testing remains largely provider- or laboratory-mediated, self-testing and home-based diagnostics are expanding consumer participation in the value chain. Simplified sample collection, rapid testing formats, connected devices, and digital platforms are enabling the delivery of selected tests outside conventional healthcare facilities. This trend is increasing the importance of usability, affordability, accessibility, result interpretation, and digital connectivity alongside analytical performance. Diagnostic results can support earlier disease identification, ongoing monitoring, treatment decisions, and personalized healthcare.
Overall, value creation within the IVD market is shifting toward integrated diagnostic ecosystems rather than individual tests or instruments. Manufacturers and technology providers are increasingly combining reagents, instruments, automation, software, connectivity, and data analytics to deliver more efficient testing workflows. At the same time, decentralization is expanding the value chain toward point-of-care and home-based settings, while centralized laboratories remain essential for high-volume, specialized, and complex testing. As a result, competitive advantage increasingly depends on the ability to combine reliable assay performance with automation, workflow integration, regulatory capability, clinical utility, service support, and scalable distribution.
In Vitro Diagnostics Market Report Scope
Report Attribute
Details
Market size in 2025
USD 107.4 billion
Estimated market size in 2026
USD 111.0 billion
Projected market size by 2033
USD 160.7 billion
Growth rate
CAGR of 5.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, volume (number of units installed and reagents sold), and CAGR from 2026 to 2033
Report coverage
Revenue forecast, volume forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Products, technology, application, test location, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; UK; Germany; France; Spain; Italy; Denmark; Sweden; Norway; Japan; China; India; South Korea; Australia; Thailand; Brazil; Mexico; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Abbott; Thermo Fisher Scientific, Inc.; Bio-Rad Laboratories, Inc.; Siemens Healthineers AG; BIOMÉRIEUX; BD; QIAGEN; QuidelOrtho; F. Hoffmann-La Roche Ltd.; Danaher; Quest Diagnostics Incorporated; Agilent Technologies, Inc.; Illumina; Sysmex Corporation
Customization scope
Free report customization (equivalent to up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global In Vitro Diagnostics Market Report Segmentation
This report forecasts revenue & volume growth at the global, regional & country levels and provides an analysis of the latest industry trends across sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global in vitro diagnostics market report based on product, technology, application, test location, end use, and region:
-
Product Outlook (Revenue, USD Billion, 2021 - 2033) (Volume, Number of Instruments, in Thousands, Volume, Reagents, Number of Tests in Million)
-
Instruments
-
Reagents
-
Services
-
-
Technology Outlook (Revenue, USD Billion, 2021 - 2033) (Volume, Number of Instruments, in Thousands, Volume, Reagents, Number of Tests in Million)
-
Immunoassay
-
Instruments
-
Reagents
-
Services
-
-
Hematology
-
Instruments
-
Reagents
-
Services
-
-
Clinical Chemistry
-
Instruments
-
Reagents
-
Services
-
-
Molecular Diagnostics
-
Instruments
-
Reagents
-
Services
-
-
Coagulation
-
Instruments
-
Reagents
-
Services
-
-
Microbiology
-
Instruments
-
Reagents
-
Services
-
-
Others
-
Instruments
-
Reagents
-
Services
-
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033) (Volume, Number of Instruments, in Thousands, Volume, Reagents, Number of Tests in Million)
-
Infectious Diseases
-
Diabetes
-
Oncology
-
Cardiology
-
Nephrology
-
Autoimmune Diseases
-
Drug Testing
-
Other applications
-
-
Test Location Outlook (Revenue, USD Billion, 2021 - 2033) (Volume, Number of Instruments, in Thousands, Volume, Reagents, Number of Tests in Million)
-
Point of Care
-
Home-care
-
Services
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033) (Volume, Number of Instruments, in Thousands, Volume, Reagents, Number of Tests in Million)
-
Hospitals
-
Laboratory
-
Home Care
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033) (Volume, Number of Instruments, in Thousands, Volume, Reagents, Number of Tests in Million)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Spain
-
Italy
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Scope & Research Methodology
The market study on the In Vitro diagnostics market has been developed using a structured, multi-stage research framework designed to ensure accuracy, consistency, and reliability of the market size estimates and forecasts. The methodology combines quantitative modeling techniques with qualitative validation to arrive at a defensible view of market size, segmentation, and growth trends.
The in vitro diagnostics (IVD) market comprises products, technologies, and services used to analyze biological specimens collected from the human body for the detection, diagnosis, screening, monitoring, and management of diseases and health conditions. IVD solutions include diagnostic reagents, test kits, instruments, analyzers, consumables, and associated software and services used across clinical chemistry, immunoassays, hematology, microbiology, molecular diagnostics, coagulation, genetic testing, and other diagnostic applications. Technologies employed in IVD include polymerase chain reaction (PCR), next-generation sequencing (NGS), digital PCR, immunoassays, nucleic acid amplification, biosensing, and other analytical methods. Testing can be performed in centralized clinical laboratories, hospitals, physician practices, point-of-care settings, and, increasingly, home-based environments. IVD solutions generate information that supports disease detection, risk assessment, treatment selection, treatment monitoring, and clinical decision-making across infectious diseases, oncology, chronic diseases, genetic disorders, and other medical conditions. The market is evolving toward automated, connected, decentralized, and data-enabled diagnostic workflows that improve testing efficiency, accessibility, and clinical utility.
The global in vitro diagnostics market has been segmented into product, technology, application, test location, end use, and region.
Based on product, the market has been further segmented into:
• Instruments: Includes analyzers, testing platforms, readers, automation systems, and other capital equipment used to perform, process, or interpret in vitro diagnostic tests. Revenue is generated from the sale, lease, or placement of diagnostic hardware. Excludes consumables, reagents, software-only services, and testing services.
• Reagent: Includes assay kits, test cartridges, calibrators, controls, stains, buffers, primers, probes, antibodies, enzymes, and other consumable materials required to perform in vitro diagnostic testing. Excludes diagnostic instruments and laboratory testing services.
• Services: Includes laboratory testing services, instrument maintenance, calibration, validation, installation, training, technical support, contract testing, and managed diagnostic services associated with IVD products. Excludes revenue from the sale of instruments and reagents.
Based on technology, the market has been further segmented into:
• Immunoassay: IVD tests that detect or quantify analytes through antigen-antibody interactions, including immunoassays, chemiluminescent immunoassays, fluorescence immunoassays, and related methodologies. Excludes tests primarily classified under molecular diagnostics, hematology, coagulation, microbiology, or clinical chemistry.
• Hematology: IVD tests and systems used for the analysis of blood cells and blood components, including complete blood count (CBC), differential counts, erythrocyte sedimentation rate (ESR), and related hematological parameters. Excludes coagulation testing and immunoassay-based blood tests.
• ClinicalChemistry: IVD tests that measure chemical constituents and metabolites in biological samples to assess organ function and metabolic status, including glucose, lipid, electrolyte, liver function, renal function, and enzyme testing. Excludes immunoassay, molecular, hematology, coagulation, and microbiology tests.
• MolecularDiagnostics: IVD tests that identify, amplify, detect, or analyze nucleic acids (DNA or RNA) or genetic markers using technologies such as PCR, RT-PCR, NGS, hybridization, and sequencing. Excludes protein-based immunoassays and culture-based microbiology testing.
• Coagulation: IVD tests used to assess hemostasis and blood clotting function, including PT, aPTT, D-dimer, fibrinogen, and other coagulation-related assays. Excludes general hematology testing and immunoassay-based assays not primarily intended for coagulation assessment.
• Microbiology: IVD tests used to detect, identify, or characterize microorganisms through culture, staining, microbial identification systems, antimicrobial susceptibility testing (AST), and other phenotypic microbiology techniques. Excludes nucleic acid-based tests classified under molecular diagnostics and immunoassay-based infectious disease tests classified under immunoassay.
• Others: Includes emerging and specialized IVD technologies not primarily categorized under immunoassay, hematology, clinical chemistry, molecular diagnostics, coagulation, or microbiology, such as cytology, histocompatibility testing, flow cytometry, and multiplex technologies.
Based on application, the market has been further segmented into:
• Infectious Diseases: The segment includes revenues generated the sale of POC MDx tests for infectious diseases, such as Chlamydia trachomatis/Neisseria gonorrhoeae (CT/NG), HIV, Clostridium difficile, HBV, pneumonia or streptococcal infections, Respiratory Syncytial Virus (RSV), HPV, influenza/flu, Hepatitis C Virus (HCV), MRSA, TB & drug-resistant TB, Herpes Simplex Virus (HSV), COVID-19, and other infectious diseases
• Diabetes: IVD tests primarily intended for diagnosis, monitoring, or management of diabetes and glycemic control, including glucose, HbA1c, insulin, and related biomarkers.
• Oncology: IVD tests used for cancer detection, screening, diagnosis, prognosis, treatment selection, monitoring, or recurrence assessment. Includes tumor markers, companion diagnostics, and molecular oncology tests.
• Cardiology: IVD tests intended for diagnosing, assessing, or monitoring cardiovascular diseases and cardiac events, including cardiac biomarkers, lipid profiling, and heart failure markers.
• Nephrology: IVD tests primarily used for evaluating kidney function, renal disease diagnosis, progression monitoring, and treatment assessment, including creatinine, BUN, eGFR-associated markers, and urine protein testing.
• AutoimmuneDisease: IVD tests are used to detect, diagnose, or monitor autoimmune disorders through the measurement of autoantibodies, inflammatory markers, and immune system biomarkers.
• DrugTesting: IVD tests designed to detect the presence, absence, or concentration of prescription drugs, illicit substances, alcohol metabolites, or therapeutic compounds in biological specimens.
• Others: Includes IVD testing applications not primarily associated with infectious diseases, diabetes, oncology, cardiology, nephrology, autoimmune diseases, or drug testing, including fertility testing, endocrinology, toxicology, allergy testing, and genetic screening.
Based on test location, the market has been further segmented into:
• Point of care: IVD testing performed at or near the site of patient care by healthcare professionals, providing rapid results that support immediate clinical decision-making. Includes hospitals, physician offices, clinics, emergency departments, and ambulatory care settings. Excludes patient self-testing conducted at home.
• Home Care: IVD testing performed directly by patients or caregivers in residential settings using self-testing or self-monitoring devices without the need for a healthcare facility visit. Includes home glucose monitoring, pregnancy tests, and home infectious disease tests.
• Others: IVD testing conducted outside traditional point-of-care and home-care settings, including centralized laboratories, reference laboratories, public health laboratories, academic institutions, and workplace testing environments.
Based on end use, the market has been further segmented into:
• Hospitals: Healthcare institutions that purchase and utilize IVD products and services for inpatient, outpatient, emergency, surgical, and critical care diagnostic testing. Includes hospital-owned and hospital-operated laboratories.
• Laboratory: Independent diagnostic laboratories, reference laboratories, pathology laboratories, and public health laboratories that primarily provide diagnostic testing services for external healthcare providers and organizations. Excludes hospital-owned laboratories.
• HomeCare: Individual patients and caregivers using IVD products in residential settings for self-testing, self-monitoring, or disease management purposes.
• Others: Includes all remaining end users not classified as hospitals, laboratories, or home care, such as physician offices, academic research institutions, nursing homes, long-term care facilities, occupational health centers, military healthcare facilities, and community clinics.
Based on region, the market has been further segmented into North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa.
• North America: The North America regional market includes the markets of the U.S., Canada, and Mexico.
• Europe: The Europe regional market includes the markets of the UK, Germany, France, Spain, Italy, Denmark, Sweden, and Norway.
• Asia Pacific: The Asia Pacific regional market includes the markets of Japan, China, India, Australia, South Korea, and Thailand.
• LatinAmerica: The Latin America regional market includes the markets of Brazil and Argentina.
• MiddleEast & Africa: The Middle East & Africa regional market includes the markets of South Africa, Saudi Arabia, the UAE, and Kuwait.
The study began with secondary research to understand the market landscape, key trends, competitive dynamics, and historical data. Sources included company annual reports, investor presentations, regulatory filings, industry publications, government and trade databases, paid research platforms, press releases, and reputable trade publications. This phase also supported historical data mapping (2021 onward), the identification of key market participants, and the development of preliminary hypotheses regarding segment shares and regional trends, which were subsequently validated through primary research.
Market sizing was conducted using a combination of top-down and bottom-up approaches, with results triangulated to arrive at a converged, validated estimate.
Under the top-down approach, the global IVD market was estimated by assessing the broader diagnostics and healthcare testing landscape using industry databases, company filings, healthcare expenditure data, government statistics, and other secondary sources. The proportion attributable to IVD was determined based on diagnostic testing utilization, technology penetration, industry participation, and the scope of IVD products and services. The resulting market value was allocated across product, technology, application, test location, and end-use segments using adoption patterns, company participation, testing intensity, and industry benchmarks. Geographic market values were subsequently derived for North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa based on healthcare expenditure, disease burden, testing utilization, laboratory infrastructure, and technology adoption. Finally, top-down estimates were reconciled with bottom-up results and validated through company revenue benchmarking, primary interviews, and expert feedback to ensure consistency across segments and regions.
Under the bottom-up approach, the IVD market was estimated by assessing diagnostic infrastructure, testing utilization, product consumption, and spending across major countries and healthcare settings. The analysis considered hospitals, clinical and diagnostic laboratories, physicians' offices, diagnostic centers, and home-based testing environments, as well as testing volumes and utilization across key disease areas. Average annual spending on instruments, reagents, consumables, software, and diagnostic services was evaluated, incorporating instrument replacement cycles, utilization rates, procurement patterns, and adoption levels. Market revenues were then calculated across product, technology, application, test location, and end-use segments, followed by company-level revenue mapping using annual reports, investor presentations, product portfolios, regulatory information, and primary research. Where segment-specific revenues were not publicly reported, estimates were developed using product-level analysis, technology participation, market share benchmarking, and industry-level indicators.
The two approaches were cross-checked, and any significant differences led to a review of the assumptions, data, and segment definitions until the estimates aligned.
To validate and refine assumptions derived from secondary research and modeling, structured primary interviews were conducted with a cross-section of industry stakeholders and experts, such as pathologists and clinical laboratory specialists, hospital procurement personnel, diagnostic laboratory executives, and regulatory experts. These interviews served to validate market size estimates and growth assumptions, confirm segment- and region-level share distributions, identify emerging trends and adoption barriers, and verify qualitative findings.
All primary inputs were systematically triangulated against secondary data and the top-down/bottom-up model outputs. Where material inconsistencies arose, additional interviews or data points were sourced until a consistent, well-supported view was established, ensuring the final estimates reflect both quantitative rigor and real-world market intelligence.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
IVD Demand Analysis
Assessment of IVD demand across infectious diseases, oncology, chronic diseases, genetic disorders, and other key applications.
Identifies high-growth testing areas and future market opportunities.
Laboratory Adoption & Testing Workflow Analysis
Evaluation of IVD adoption across hospitals, diagnostic laboratories, reference laboratories, and point-of-care testing settings, including automation and workflow integration.
Supports customer targeting and market expansion strategies.
Technology & Platform Assessment
Analysis of molecular diagnostics, immunoassays, clinical chemistry, hematology, microbiology, coagulation, automation, and multiplex testing platforms.
Tracks technology evolution and supports product positioning decisions.
Innovation & Future Technology Landscape
Assessment of AI-enabled diagnostics, digital pathology, point-of-care testing, liquid biopsy, NGS, connected diagnostics, and other emerging IVD technologies.
Highlights emerging innovation areas and long-term growth opportunities.
Frequently Asked Questions About This Report
The global in vitro diagnostics market is expected to grow at a CAGR of 5.4% from 2026 to 2033, reaching USD 160.7 billion by 2033.
North America dominated with a 47.3% revenue share in 2025.
Key players include Abbott; Thermo Fisher Scientific, Inc.; Bio-Rad Laboratories, Inc.; Siemens Healthineers AG; BIOMÉRIEUX; BD; QIAGEN; QuidelOrtho; F. Hoffmann-La Roche Ltd.; Danaher; Quest Diagnostics Incorporated; Agilent Technologies, Inc.; Illumina; Sysmex Corporation
Key factors include the increasing prevalence of chronic and infectious diseases, advancements in diagnostic technologies, and the shift toward value-based healthcare emphasizing early detection and preventive care.
Reagent segment led the market with a revenue share of 65.7% in 2025, while instruments was the fastest-growing segment.
Molecular diagnostics segment dominated the market with a revenue share of 25.8% in 2025, while coagulation segment is expected to grow with the fastest CAGR.
Asia Pacific is the fastest-growing region over the forecast period.
The global in vitro diagnostics market size was valued at USD 107.4 billion in 2025 and is estimated at USD 111.0 billion in 2026.
About the Author(s)
Clinical Diagnostics Research Team
Healthcare · Clinical DiagnosticsThis report was authored by the clinical diagnostics research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clinical diagnostics segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


