
- Home
- »
- Network Security
- »
-
Distributed Denial of Service Protection Market Report, 2033GVR Report cover

Distributed Denial Of Service Protection Market (2026 - 2033)
Size, Share & Trends Analysis Report By Component (Software Solutions, Services), By Application (Network Security, End Use Security), By Deployment, By Enterprise Size, By End Use, By Region, And Segment Forecasts
Market Size, 2025
$5.2BMarket Estimate, 2026
$5.8BMarket Forecast, 2033
$19.7BCAGR, 2026–2033
19.2%Distributed Denial of Service Protection Market Summary
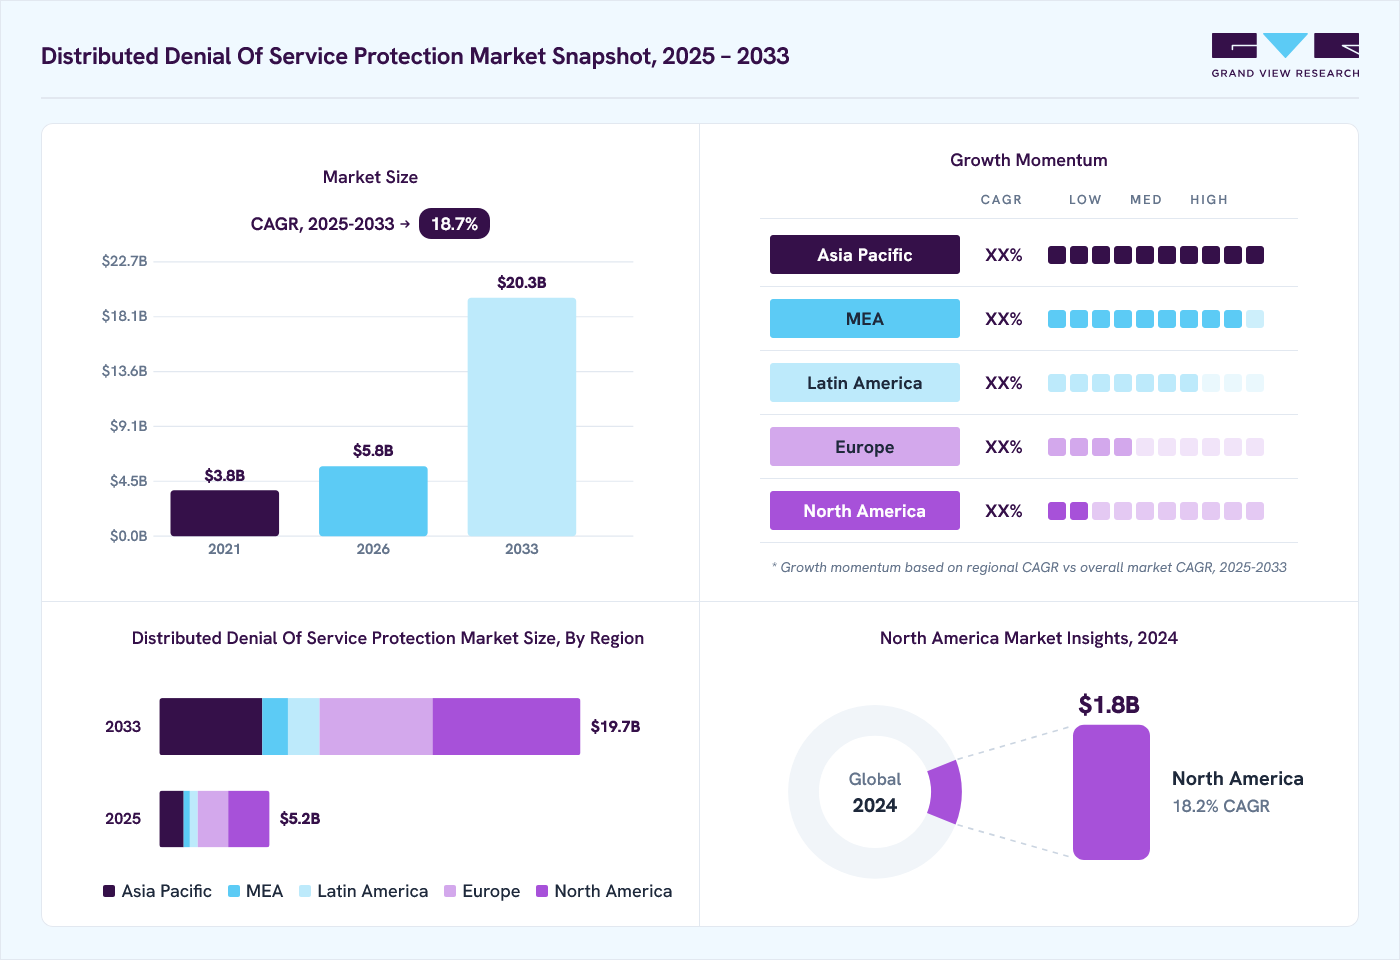
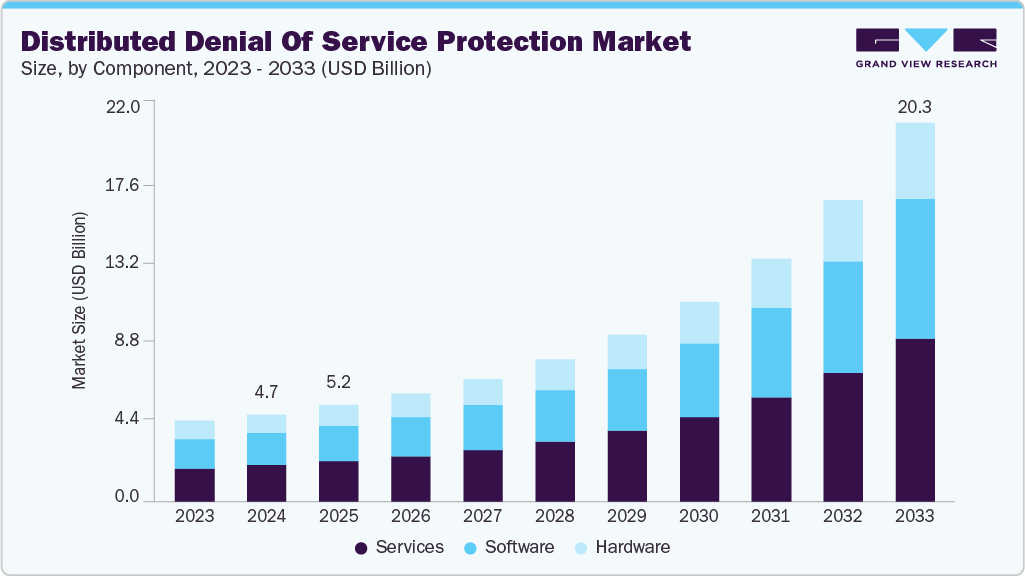
The global distributed denial of service protection market size was valued at USD 5.2 billion in 2025 and is projected to grow from USD 5.8 billion in 2026 to USD 19.7 billion by 2033, at a CAGR of 19.2% from 2026 to 2033. The North America dominated the market, accounting for a revenue share of 37.5% in 2025. The rapid proliferation of connected devices and the widespread adoption of the Internet of Things (IoT) are key factors driving the growth of the distributed denial of service (DDoS) protection market.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By component: The software solutions segment dominated the market, with a revenue share of 40.6% in 2025
- By deployment: The cloud segment dominated the market, with a revenue share of 56.1% in 2025
- By enterprise size: The large enterprises segment dominated the market of 64.8% in 2025
- By application: The network security segment dominated the market of 44.9% in 2025
- By end use: The IT and telecommunications segment held the largest market share of 28.5% in 2025
Regional Highlights
- Largest regional market: North America (37.5% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecasts
- Market size in 2025: USD 5.2 billion
- Estimated market size in 2026: USD 5.8 billion
- Projected market size by 2033: USD 19.7 billion
- CAGR (2026-2033): 19.2%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The rising frequency and sophistication of DDoS attacks play a significant role in driving market growth. Attackers have developed more advanced techniques to overwhelm and disrupt these systems as businesses and critical infrastructure become more reliant on digital systems. Modern DDoS attacks often involve large-scale botnets and sophisticated methods to bypass traditional security measures, necessitating more advanced protection solutions. This constant evolution in attack methods creates a persistent demand for cutting-edge DDoS protection technologies.Moreover, the growing awareness among organizations about financial and reputational damage that can result from a successful DDoS attack fuels market growth. High-profile service outages and data breaches have highlighted the importance of robust security measures. As a result, companies across various industries are increasingly investing in DDoS protection solutions to safeguard their operations, enhance customer trust, and avoid the substantial costs associated with downtime and recovery. This heightened awareness drives both increased adoption and expenditure on DDoS protection services.
 To learn more about this report, Download Free Sample Report
The rise of cloud computing and edge services is driving distributed denial of service protection market growth. As organizations shift infrastructure and end uses to public or hybrid clouds, securing the extended perimeter becomes critical. DDoS protection vendors are offering cloud-native and edge-integrated solutions that combine real-time threat intelligence with automated mitigation techniques. These services can absorb volumetric attacks at the edge or redirect malicious traffic through scrubbing centers without interrupting legitimate user activity. The adaptability and scalability of cloud-based DDoS protection make it especially appealing to enterprises undergoing digital transformation.
Moreover, the growing regulatory pressure around cybersecurity and data protection is driving organizations to prioritize their defensive posture against DDoS threats. Governments and industry bodies across the U.S., Europe, and Asia-Pacific are mandating stricter compliance standards, especially for sectors handling sensitive data or critical infrastructure. Non-compliance can result in hefty penalties, making it imperative for organizations to demonstrate resilience against attacks, including DDoS. This regulatory landscape is encouraging proactive investment in comprehensive DDoS defense solutions that include real-time monitoring, incident response planning, and forensic analysis.
Market Dynamics
The distributed denial of service (DDoS) protection market is strongly shaped by the rapid evolution of cyber threats and the increasing complexity of digital ecosystems. A key recent trend is the surge in large-scale, multi-vector DDoS attacks powered by globally distributed botnets and IoT-enabled devices, which has significantly increased both attack volume and sophistication. As organizations accelerate cloud migration and adopt hybrid and multi-cloud infrastructures, the attack surface has expanded, making traditional perimeter-based security models less effective. This has driven strong demand for cloud-native, AI-driven, and real-time mitigation solutions capable of detecting anomalies and responding instantly to high-volume traffic floods without disrupting legitimate users.
Another important market dynamic is the growing shift toward managed security services and integrated cybersecurity platforms. Enterprises, particularly SMEs, are increasingly outsourcing DDoS protection to managed service providers due to the shortage of in-house cybersecurity expertise and the rising cost of maintaining advanced defense systems. At the same time, regulatory pressure and compliance requirements across sectors such as BFSI, telecom, and government are pushing organizations to adopt more resilient and automated security frameworks. The convergence of DDoS protection with broader cybersecurity ecosystems such as Web Application Firewalls (WAF), cloud security, and Zero Trust architectures is also becoming a defining trend, enabling more holistic and proactive threat prevention strategies.
The increasing frequency and sophistication of distributed denial of service (DDoS) attacks is a major driver fueling the growth of the DDoS protection market. Cyber attackers are continuously evolving their tactics by leveraging large-scale botnets, IoT-compromised devices, and AI-enabled attack methods to generate massive traffic volumes aimed at overwhelming enterprise networks and critical infrastructure. These advanced attack patterns are becoming harder to detect and mitigate using traditional security solutions, pushing organizations to adopt more intelligent, adaptive, and automated DDoS protection technologies.
As businesses continue to digitize operations and rely heavily on cloud-based applications and interconnected systems, the potential impact of service disruptions has become significantly more severe. This has elevated DDoS protection from a supplementary security measure to a mission-critical requirement across industries such as BFSI, telecom, healthcare, and government. Consequently, enterprises are increasingly investing in next-generation solutions that offer real-time monitoring, behavioral analytics, and rapid mitigation capabilities to ensure uninterrupted service availability.
One of the key restraints in the DDoS protection market is the high cost and operational complexity associated with deploying advanced security solutions. Sophisticated DDoS mitigation systems, particularly those offering AI-driven analytics, multi-layer protection, and cloud-native scalability, often require significant upfront investment along with ongoing maintenance expenses. This can be a major barrier, especially for small and medium-sized enterprises with limited cybersecurity budgets.
Additionally, integrating DDoS protection solutions into existing IT infrastructure can be complex and resource-intensive. Organizations often face challenges related to configuration, interoperability with legacy systems, and the need for skilled cybersecurity professionals to manage and optimize these solutions. These factors can slow down adoption rates and create hesitation among cost-sensitive enterprises, thereby restraining overall market expansion.
The rapid expansion of cloud computing and increasing adoption of digital transformation strategies present significant opportunities for the DDoS protection market. As enterprises migrate workloads to public, private, and hybrid cloud environments, the demand for cloud-native DDoS protection solutions is accelerating. These solutions offer scalability, flexibility, and real-time mitigation capabilities, making them highly suitable for modern distributed IT environments.
In addition, the growing preference for Managed Security Service Providers (MSSPs) is creating new revenue streams in the market. Organizations are increasingly outsourcing cybersecurity operations to specialized providers to reduce complexity, improve threat response times, and access advanced expertise. This shift is particularly strong among SMEs and mid-sized enterprises, opening substantial growth opportunities for vendors offering subscription-based, fully managed DDoS protection services.
Analyst Perspective
From an analyst perspective, the distributed denial of service protection market is undergoing a clear structural shift from traditional hardware-centric security to cloud-native and service-oriented architectures. The increasing scale and sophistication of DDoS attacks, driven by IoT-enabled botnets and AI-assisted attack automation, has made legacy perimeter-based defenses less effective. As a result, market leaders such as Cloudflare, Akamai Technologies, and NETSCOUT are strengthening their global scrubbing networks and integrating advanced analytics, behavioral detection, and real-time mitigation capabilities. Analysts observe that competitive differentiation is increasingly shifting toward response latency, global network footprint, and the ability to provide always-on, automated protection without impacting application performance.
Component Insights
Based on component, the software solutions segment led the market with the largest revenue share of 40.6% in 2025. Many organizations are opting for managed DDoS protection services as they seek to leverage the expertise and resources of specialized service providers. Managed services offer several advantages, including 24/7 monitoring, dedicated support, and expertise in dealing with complex attacks. This demand for outsourced solutions, driven by the need for specialized skills and cost efficiency, is contributing to the expansion of the DDoS protection service market.
The software segment is projected to grow at a significant CAGR from 2025 to 2033. The rapid advancements in software technology play a crucial role in the growth of this segment. Modern DDoS protection software leverages artificial intelligence (AI) and machine learning innovations to enhance threat detection and response capabilities. These technologies enable software solutions to analyze patterns, identify anomalies, and respond to real-time attacks, improving their effectiveness. Continuous updates and improvements in software capabilities ensure that organizations have access to the latest defense mechanisms against evolving DDoS threats, further fueling the demand for sophisticated software solutions.
Application Insights
Based on the application, the network security segment led the market with the largest revenue share of 44.9% in 2025. The widespread shift to remote work, accelerated by the COVID-19 pandemic, and the ongoing digital transformation across industries have also contributed to the growth of DDoS protection for network security applications. With more employees accessing corporate networks remotely, the attack surface has expanded, making it easier for cybercriminals to launch DDoS attacks. Moreover, as businesses continue to digitize their operations, integrating cloud services and online platforms, their network security requirements have become more complex. There is an increased demand for robust DDoS protection solutions to secure these increasingly distributed and digitalized networks.
The application security segment is projected to be the fastest-growing segment from 2025 to 2033. The increasing prevalence of application-layer DDoS attacks is driving the market's growth. Unlike traditional DDoS attacks that target network infrastructure, application-layer attacks focus on specific web applications, aiming to exhaust server resources by overwhelming them with seemingly legitimate requests. These attacks are insidious because they mimic regular user behavior, making them harder to detect and mitigate with traditional network-based defenses.
Deployment Insights
Based on the deployment, the cloud segment led the market with the largest revenue share of 56.1% in 2025. The widespread adoption of cloud computing across various industries is a major driver for the growth of cloud-based DDoS protection. As more organizations migrate their operations, applications, and data to the cloud, securing these environments from DDoS attacks has become critical. Cloud environments, while offering numerous benefits such as scalability and flexibility, are also exposed to a broader range of cyber threats. As a result, organizations are increasingly turning to cloud-based DDoS protection solutions designed to safeguard cloud infrastructure and applications from potential attacks. This trend is accelerating as businesses embrace cloud services as part of their digital transformation strategies.
The hybrid segment is projected to grow at a significant CAGR from 2025 to 2033. The hybrid approach combines the best aspects of on-premise and cloud-based DDoS protection. On-premise solutions provide rapid response capabilities, low latency, and direct control over security measures, which are crucial for immediate threat mitigation and compliance with regulatory requirements. In contrast, cloud-based solutions offer scalability, redundancy, and the ability to handle large-scale attacks that exceed the capacity of on-premise infrastructure. By integrating these two approaches, hybrid solutions ensure organizations have a layered defense strategy capable of addressing localized and widespread threats. This comprehensive coverage is a significant advantage, driving the adoption of hybrid DDoS protection in various industries.
Enterprise Size Insights
Based on the enterprise size, the large enterprises segment led the market with the largest revenue share of 64.8% in 2025. Maintaining customer trust and ensuring business continuity are paramount for large enterprises. A successful DDoS attack that disrupts services can lead to customer dissatisfaction, loss of confidence, and potential customer churn. Large enterprises recognize the importance of safeguarding their operations against such threats and are investing in DDoS protection to ensure that their services remain uninterrupted.
 To learn more about this report, Download Free Sample Report
The small & medium enterprises (SMEs) segment is projected to be the fastest-growing segment from 2025 to 2033. Compared to larger enterprises, the increasing frequency of targeted cyberattacks against smaller businesses drives market growth. Historically, SMEs were not considered primary targets for DDoS attacks, which were more commonly directed at larger enterprises. However, cybercriminals have increasingly recognized that SMEs often lack the sophisticated security infrastructure of larger organizations, making them easier targets. As a result, DDoS attacks on SMEs have risen, prompting these businesses to invest in protection solutions to safeguard their operations.
End Use Insights
Based on the end use, the IT and telecommunications segment led the market with the largest revenue share of 28.5% in 2025. The expansion of 5G and fiber-optic networks, which is rapidly increasing bandwidth and the number of connected endpoints, is driving segment growth. While this growth supports faster and more reliable digital services, it also creates greater exposure to DDoS threats by widening the attack surface. Telecom operators must ensure that their core and edge networks can withstand high-throughput DDoS attacks without affecting service quality.
To meet this demand, DDoS protection solutions are increasingly being embedded directly into telecom infrastructure, including at the DNS, CDN, and BGP levels, offering multi-layered security that shields against both volumetric and protocol-based threats. The shift toward software-defined networking (SDN) and network function virtualization (NFV) further supports dynamic, scalable DDoS protection across complex telecom environments.
The retail and e-commerce segment is projected to be the fastest-growing segment from 2025 to 2033. Adopting omnichannel retail strategies, where businesses integrate their online and offline operations to provide a seamless customer experience, also drives the need for robust DDoS protection. In an omnichannel environment, online service disruptions can have ripple effects on other parts of the business, such as inventory management, in-store services, and customer support. Ensuring the continuous availability of digital platforms is essential for maintaining the smooth operation of these interconnected systems. As more retailers embrace omnichannel strategies, the importance of comprehensive DDoS protection becomes increasingly apparent.
Regional Insights
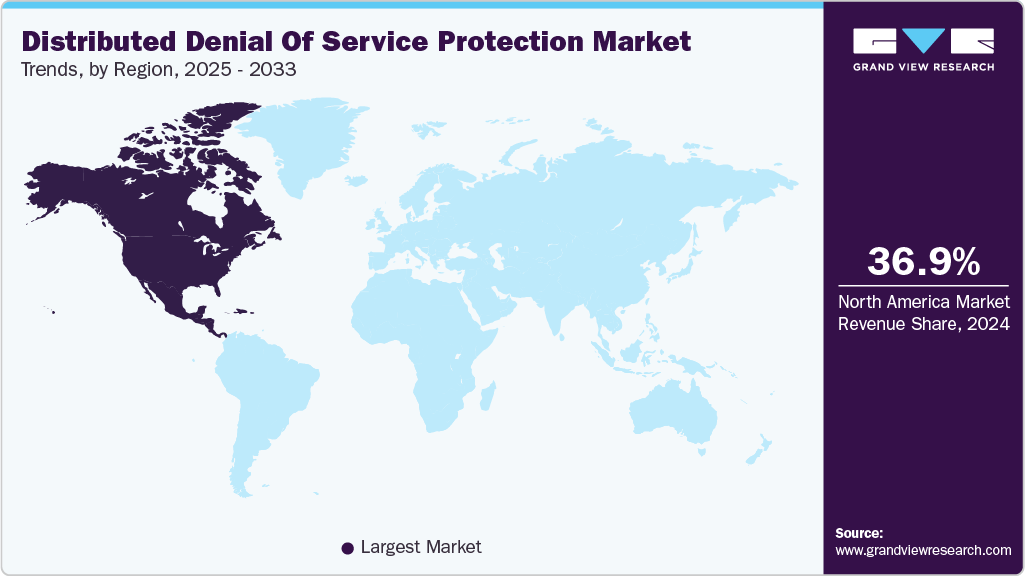
North America dominated the global distributed denial of service protection market, with the largest revenue share of 37.5% in 2025. The rapid expansion of the Internet of Things (IoT) in North America significantly contributes to the growth of DDoS protection. The increasing number of connected devices in industries such as manufacturing, healthcare, and smart cities has created new opportunities for cybercriminals to launch DDoS attacks by exploiting vulnerabilities in IoT networks.
 To learn more about this report, Download Free Sample Report
U.S. Distributed Denial of Service (DDoS) Protection Market Trends
The distributed denial of service protection market in the U.S. held the largest share of the North American market in 2025. The integration of DDoS protection with broader cybersecurity strategies is fueling growth in the U.S. By integrating DDoS protection with other security measures, such as firewalls, intrusion detection systems, and security information and event management (SIEM) solutions, businesses create a comprehensive defense strategy that addresses a wide range of cyber threats. This integrated approach underscores the importance of DDoS protection as a critical component of overall cybersecurity efforts.
Asia Pacific Distributed Denial of Service (DDoS) Protection Trends
The Asia Pacific distributed denial of service protection market is expected to be the fastest-growing, with a CAGR of 20.7% over the forecast period. The growth can be attributed to the growing awareness regarding the benefits of distributed. The region has experienced significant internet and mobile penetration growth over the past decade. This rapid digital expansion has increased reliance on online platforms and services, making businesses more vulnerable to DDoS attacks. As the number of digital users and online transactions rises, the need for effective DDoS protection solutions becomes more pressing to ensure the security and availability of these critical digital assets.
The distributed denial of service protection market in China is projected to grow during the forecast period. China’s expanding use of smart city infrastructure and IoT deployments is also amplifying the need for advanced DDoS defenses. As cities roll out connected systems for transportation, energy, surveillance, and public services, the number of networked endpoints has surged, creating more entry points for cybercriminals to exploit. IoT devices, often lacking robust security protocols, are particularly vulnerable to being hijacked by botnets that execute distributed attacks. To mitigate these risks, municipalities and service providers are deploying network-wide DDoS protection solutions integrated with AI and threat intelligence to guard critical services and ensure urban resilience in the face of cyber threats.
Europe Distributed Denial of Service (DDoS) Protection Market Trends
The distributed denial of service protection industry in Europe is expected to grow during the forecast period. Ongoing investment in technology and infrastructure upgrades in Europe significantly drives the growth of DDoS protection. As businesses and governments modernize their IT infrastructure and adopt new technologies, such as cloud computing and Internet of Things (IoT) devices, the need for adequate DDoS protection becomes more apparent.
The distributed denial of service protection market in the UK is grow during the forecast period. The expansion of hybrid work environments and cloud adoption across UK enterprises has also driven demand for DDoS protection. With employees accessing corporate resources remotely, often from personal devices or unsecured networks, the digital perimeter has widened, creating more vulnerabilities that attackers can exploit. Simultaneously, organizations are hosting an increasing number of services in public and private clouds, making them reliant on third-party platforms where service availability is critical. As such, cloud-native DDoS protection solutions that can dynamically scale to absorb attacks and automatically filter malicious traffic are becoming essential to prevent disruptions across digital business operations.
Key Distributed Denial of Service Protection Company Insights
Some key companies operating in the market, Akamai Technologies and Cloudflare, Inc., among others, are some leading participants in the distributed denial of service protection market.
-
Akamai Technologies is a content delivery network (CDN) service and cloud security solutions provider. Akamai provides robust DDoS mitigation through its Prolexic platform, a globally distributed DDoS scrubbing service designed to detect, absorb, and neutralize large-scale attacks before they reach a client’s infrastructure. Leveraging its vast global network, Akamai can redirect and inspect potentially malicious traffic at the edge, far from the targeted origin, minimizing disruption and maintaining service availability.
-
Cloudflare, Inc. is a U.S.-based global cybersecurity and web infrastructure company. Cloudflare’s DDoS protection operates autonomously using machine learning and heuristics to detect anomalies in traffic patterns, enabling it to stop both volumetric floods and more subtle, application-layer attacks. This automation reduces response times and ensures business continuity even under persistent threats. Cloudflare also offers a user-friendly dashboard that allows customers to monitor and manage DDoS events in real-time, enhancing visibility and control.
Imperva, and NETSCOUT are some emerging market participants in the distributed denial of service protection market.
-
Imperva is a U.S.-based cybersecurity company that specializes in protecting critical data, applications, and websites from cyber threats. Imperva’s DDoS protection solutions are distinguished by their always-on and automatic mitigation capabilities. These features ensure that traffic is continuously monitored and that threats are neutralized instantly without the need for manual intervention. The company also integrates real-time dashboards, advanced analytics, and threat intelligence into its platform, enabling security teams to gain immediate insight into attack activity and response effectiveness.
-
NETSCOUT Systems, Inc. is a U.S.-based technology company that provides advanced service assurance, cybersecurity, and network performance management solutions. A major focus area for NETSCOUT is Distributed Denial of Service (DDoS) protection, offered through its Arbor DDoS product line, which is widely recognized for delivering industry-leading threat mitigation. Arbor solutions are trusted globally by internet service providers (ISPs), data centers, and enterprises to safeguard against DDoS attacks that could cripple websites, disrupt services, or compromise network availability.
Key Distributed Denial of Service (DDoS) Protection Companies:
The following are the leading companies in the distributed denial of service protection market.
- A10 Networks, Inc.
- Akamai Technologies
- Cloudflare, Inc.
- Corero Network Security
- F5, Inc.
- Fortinet, Inc.
- Imperva
- NETSCOUT Systems Inc.
- Radware
- TransUnion LLC
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Mature Players (A10 Networks, Akamai Technologies, Cloudflare, Corero Network Security, F5, Fortinet, Imperva, NETSCOUT, Radware, TransUnion LLC)
- Focus on multi-layer DDoS mitigation platforms combining cloud scrubbing, on-premise appliances, and hybrid security architectures to protect complex enterprise environments.
- Strong emphasis on AI/ML-driven threat intelligence, global traffic monitoring networks, and integration with broader cybersecurity ecosystems such as WAF, CDN, Zero Trust, and SIEM platforms.
- Extensive global threat intelligence networks and high-capacity mitigation infrastructure enabling rapid response to large-scale volumetric attacks.
- Strong enterprise trust, brand recognition, and long-term contracts with BFSI, telecom, government, and large digital enterprises.
- High pricing and complex deployment models, making solutions less accessible for SMEs and mid-market organizations.
- Increasing risk of vendor dependency and ecosystem lock-in, especially where integrated security stacks are heavily bundled.
Emerging Players (Radware, Corero Network Security, A10 Networks, StackPath, Link11, Reblaze, and StormWall)
- Emphasis on cloud-native, API-first DDoS protection solutions designed for rapid deployment in DevOps and hybrid cloud environments.
- Adoption of flexible, subscription-based pricing models with a strong focus on scalability and ease of integration.
- Faster onboarding and simplified architecture, making solutions more attractive for agile enterprises and digital-native businesses.
- Strong ability to address modern attack surfaces such as APIs, microservices, and edge networks with lightweight protection layers.
- Limited global infrastructure and mitigation capacity compared to established players during large-scale attack events.
- Fewer advanced enterprise features such as deep compliance management, unified security orchestration, and long-term threat intelligence maturity.
Recent Developments
-
In February 2025, NETSCOUT Systems, Inc. launched enhancements to its Arbor Threat Mitigation System Adaptive DDoS Protection solution by incorporating advanced artificial intelligence (AI) and machine learning (ML) technologies. The company utilizes a hybrid AI/ML approach that blends large-scale, cloud-based analysis with supervised learning and integrates AI/ML capabilities directly into its software solutions. This approach allows NETSCOUT to monitor and analyze an exceptional 550 Tbps of Internet traffic in the cloud, with human oversight ensuring accuracy and reliability in detecting and blocking malicious traffic.
-
In June 2024, Nokia unveiled advanced countermeasures to maintain protection against distributed denial-of-service (DDoS) attacks, particularly those originating from botnets and targeting application-level vulnerabilities. The new solutions leverage the Nokia 7750 Defender Mitigation System, which utilizes an advanced countermeasures engine to detect and mitigate real-time DDoS attacks. By employing sophisticated analytics and machine learning, the system can identify abnormal traffic patterns and automatically deploy targeted defenses, significantly reducing the impact of attacks on critical services.
-
In April 2024, Lightpath launched its enhanced DDoS protection solution, the LP DDoS Shield, designed to safeguard networks against the increasing sophistication and scale of distributed denial-of-service (DDoS) attacks. The system utilizes advanced detection and mitigation technologies from Radware, a recognized leader in cybersecurity solutions. The LP DDoS Shield employs AI-powered algorithms to identify and neutralize zero-day attacks effectively without prior data-along with various other threats, including IoT-based attacks and phantom floods.
-
In April 2024, Corero Network Security launched its new distributed denial of service cloud-backup service. This offering enhances Corero’s portfolio by integrating its on-premises solutions with Akamai’s cloud infrastructure to provide hybrid DDoS protection. The Corero SmartWall ONE Hybrid Cloud DDoS Protection solution ensures seamless automatic switching to cloud-based mitigation during large-scale distributed denial of service attacks, safeguarding continuous service availability.
Distributed Denial of Service Protection Market Report Scope
Report Attribute
Details
Market size in 2025
USD 5.2 billion
Estimated market size in 2026
USD 5.8 billion
Projected market size by 2033
USD 19.7 billion
Growth rate
CAGR of 19.2% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecasts period
2026 - 2033
Quantitative units
Revenue in USD billion/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecasts, company market share analysis, competitive landscape, growth factors, and trends
Segments covered
Component, deployment, enterprise size, application, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; South Africa; UAE
Key companies profiled
A10 Networks, Inc.; Akamai Technologies; Cloudflare, Inc.; Corero Network Security; F5, Inc.; Fortinet, Inc.; Imperva; NETSCOUT System Inc.; Radware; TransUnion LLC
Customization scope
Free report customization (equivalent to up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Distributed Denial of Service (DDoS) Protection Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global distributed denial of service protection market report based on component, application, deployment, enterprise size, end use, and region.
-
Component Outlook (Revenue, USD Billion, 2021 - 2033)
-
Hardware
-
Software
-
Services
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Network Security
-
End Use Security
-
Database Security
-
Endpoint Security
-
-
Deployment Outlook (Revenue, USD Billion, 2021 - 2033)
-
Cloud
-
On-Premise
-
Hybrid
-
-
Enterprise Size Outlook (Revenue, USD Billion, 2021 - 2033)
-
Small & Medium Enterprises
-
Large Enterprises
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
BFSI
-
IT and Telecommunications
-
Government and Public Sector
-
Energy and Utilities
-
Manufacturing
-
Retail and E-commerce
-
Media & Entertainment
-
Healthcare
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
UAE
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The distributed denial of service protection market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each distributed denial of service protection segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Component
Revenue Capture Definition
Hardware Solutions
Revenue generated from dedicated DDoS mitigation appliances and on-premise security hardware deployed within enterprise and data center environments to filter, detect, and block malicious traffic at the network edge.
Software Solutions
Revenue from cloud-native and software-based DDoS protection platforms that provide real-time traffic monitoring, AI-driven threat detection, automated mitigation, and integration with web application firewalls and security orchestration tools.
Services
Revenue from managed DDoS protection services, consulting, deployment, incident response, traffic scrubbing services, threat intelligence, and ongoing support provided by MSSPs and cybersecurity vendors.
Segment - Deployment
Revenue Capture Definition
Cloud
Revenue generated from SaaS-based and cloud-delivered DDoS protection services, including subscription models, pay-as-you-go traffic filtering, and globally distributed scrubbing center access.
On-Premise
Revenue from internally deployed DDoS protection systems, including hardware appliances, licensed software, and maintenance contracts installed within enterprise data centers.
Hybrid
Revenue generated from integrated deployment models combining on-premise infrastructure with cloud-based scrubbing and mitigation services for flexible and scalable protection.
Segment - Enterprise Size
Revenue Capture Definition
Large Enterprises
Revenue generated from advanced, scalable DDoS protection platforms offering high-capacity mitigation, global threat intelligence, customization, and integration across complex IT ecosystems.
SMEs
Revenue from standardized, cost-effective, and subscription-based DDoS protection solutions designed for small and medium enterprises with moderate traffic exposure and limited security budgets.
Segment - Application
Revenue Capture Definition
Network Security
Revenue from solutions that protect network infrastructure against volumetric and protocol-based DDoS attacks targeting bandwidth, routers, and core network resources.
Application Security
Revenue generated from protecting web applications, APIs, and digital services from application-layer (Layer 7) DDoS attacks and service disruption attempts.
Database Security
Revenue from securing databases against traffic flooding, query overload attacks, and service disruption targeting backend systems and data availability.
Endpoint Security
Revenue generated from protecting endpoints and distributed devices from botnet infection and participation in DDoS attack networks.
Segment - Vertical
Revenue Capture Definition
BFSI
Revenue from protecting banking platforms, digital payment systems, trading platforms, and financial infrastructure against service disruption and cyberattacks.
IT and Telecommunications
Revenue generated from safeguarding telecom networks, cloud infrastructure, data centers, and digital service providers from large-scale DDoS attacks.
Government & Defense
Revenue from securing critical public infrastructure, defense networks, citizen services, and national cybersecurity systems.
Energy and Utilities
Revenue generated from protecting smart grids, energy management systems, and utility infrastructure from cyber disruption.
Manufacturing
Revenue from securing industrial control systems, IoT-enabled production environments, and smart factory networks.
Retail and E-commerce
Revenue generated from protecting online retail platforms, payment gateways, and customer-facing digital services.
Media & Entertainment
Revenue from securing streaming platforms, content delivery networks, and digital media services against traffic flooding attacks.
Healthcare
Revenue generated from protecting healthcare IT systems, patient data platforms, telemedicine applications, and hospital networks.
Others
Revenue from additional sectors such as education, logistics, travel & hospitality, and other digitally dependent industries requiring DDoS protection.
Estimation Model
Layer
Question
Analysis
Threat Exposure Layer (TAM)
Who can potentially require DDoS protection?
All organizations and digital infrastructure operators exposed to internet-facing services form the total addressable market. This includes enterprises, SMEs, cloud service providers, BFSI institutions, telecom operators, government agencies, healthcare systems, and e-commerce platforms that are vulnerable to volumetric, protocol, and application-layer DDoS attacks.
Security Readiness & Infrastructure Layer (SAM)
Who can technically adopt DDoS protection solutions?
Organizations with established digital infrastructure such as cloud adoption, hybrid IT environments, APIs, and always-on online services represent the serviceable market. Enterprises using CDN networks, cloud platforms, and managed security frameworks are more capable of integrating advanced DDoS mitigation solutions.
Active Protection Adoption Layer (SOM)
Who actively deploys DDoS protection today?
Organizations currently implementing DDoS mitigation solutions such as cloud scrubbing services, on-premise appliances, and hybrid protection systems. Key adopters include BFSI institutions, large enterprises, government networks, telecom operators, and digital-native businesses that experience frequent or high-risk attack exposure.
Revenue Realization Layer
How is revenue generated?
Revenue is generated through subscription-based pricing (SaaS/cloud DDoS protection), managed security services (MSSP offerings), hardware appliance sales, hybrid deployment contracts, and value-added services such as real-time monitoring, traffic analytics, incident response, and integration with broader cybersecurity ecosystems (WAF, Zero Trust, and SIEM platforms).
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
DDoS threat exposure & risk assessment
Assessed enterprise exposure to volumetric, protocol, and application-layer DDoS attacks across cloud, APIs, and hybrid infrastructure, including IoT-driven botnet risks.
Helps identify critical assets, prioritize protection, and strengthen resilience against evolving multi-vector DDoS threats.
DDoS protection architecture & integration review
Evaluated cloud-based, on-premise, and hybrid mitigation models, including integration with WAF, SIEM, Zero Trust, and CDN ecosystems.
Enables optimized deployment, faster threat response, and stronger integration with existing cybersecurity frameworks.
Competitive benchmarking & vendor positioning
Benchmarked key players including Akamai Technologies, Cloudflare, NETSCOUT, F5, Fortinet, Radware, Imperva, A10 Networks, and Corero Network Security on mitigation capability, scalability, latency, and cloud readiness.
Supports vendor selection, investment decisions, and modernization strategies through clear competitive positioning insights.
Frequently Asked Questions About This Report
North America dominated the market, accounting for a revenue share of 37.5% in 2025.
Some key players operating in the DDoS protection market include A10 Networks, Inc., Akamai Technologies, Cloudflare, Inc., Corero Network Security, F5, Inc., Fortinet, Inc., Imperva, NETSCOUT System Inc., Radware, TransUnion LLC
Factors such the proliferation of connected devices and the expansion of the Internet of Things (IoT) and the rising frequency and sophistication of DDoS attacks is driving the distributed denial of service protection market growth.
Asia Pacific is the fastest-growing region over the forecast period.
The software solutions segment led with a 40.6% revenue share in 2025 while software segment is also the fastest-growing segment.
The network security segment led with a 44.9% revenue share in 2025, while application security segment is the fastest-growing segment.
The cloud segment led with a 56.1% revenue share in 2025.The widespread adoption of cloud computing across various industries is a major driver for the growth of cloud-based DDoS protection.
The global distributed denial of service protection market size was valued at USD 5.2 billion in 2025 and is estimated at USD 5.8 billion for 2026.
The global distributed denial of service protection market is expected to grow at a CAGR of 19.2% from 2026 to 2033, reaching USD 19.7 billion by 2033.
About the Author(s)
Network Security Research Team
Technology · Network SecurityThis report was authored by the network security research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the network security segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


