
- Home
- »
- Next Generation Technologies
- »
-
Drone Fleet Management Software Market Report, 2033GVR Report cover

Drone Fleet Management Software Market (2026 - 2033)
Size, Share & Trends Analysis Report By Deployment Mode (Cloud-Based, On-Premises), By Enterprise Size, By Fleet Size, By Functionality, By End Use, By Region, And Segment Forecasts
Market Size, 2025
$3.2BMarket Estimate, 2026
$3.5BMarket Forecast, 2033
$8.3BCAGR, 2026–2033
12.8%Drone Fleet Management Software Market Summary
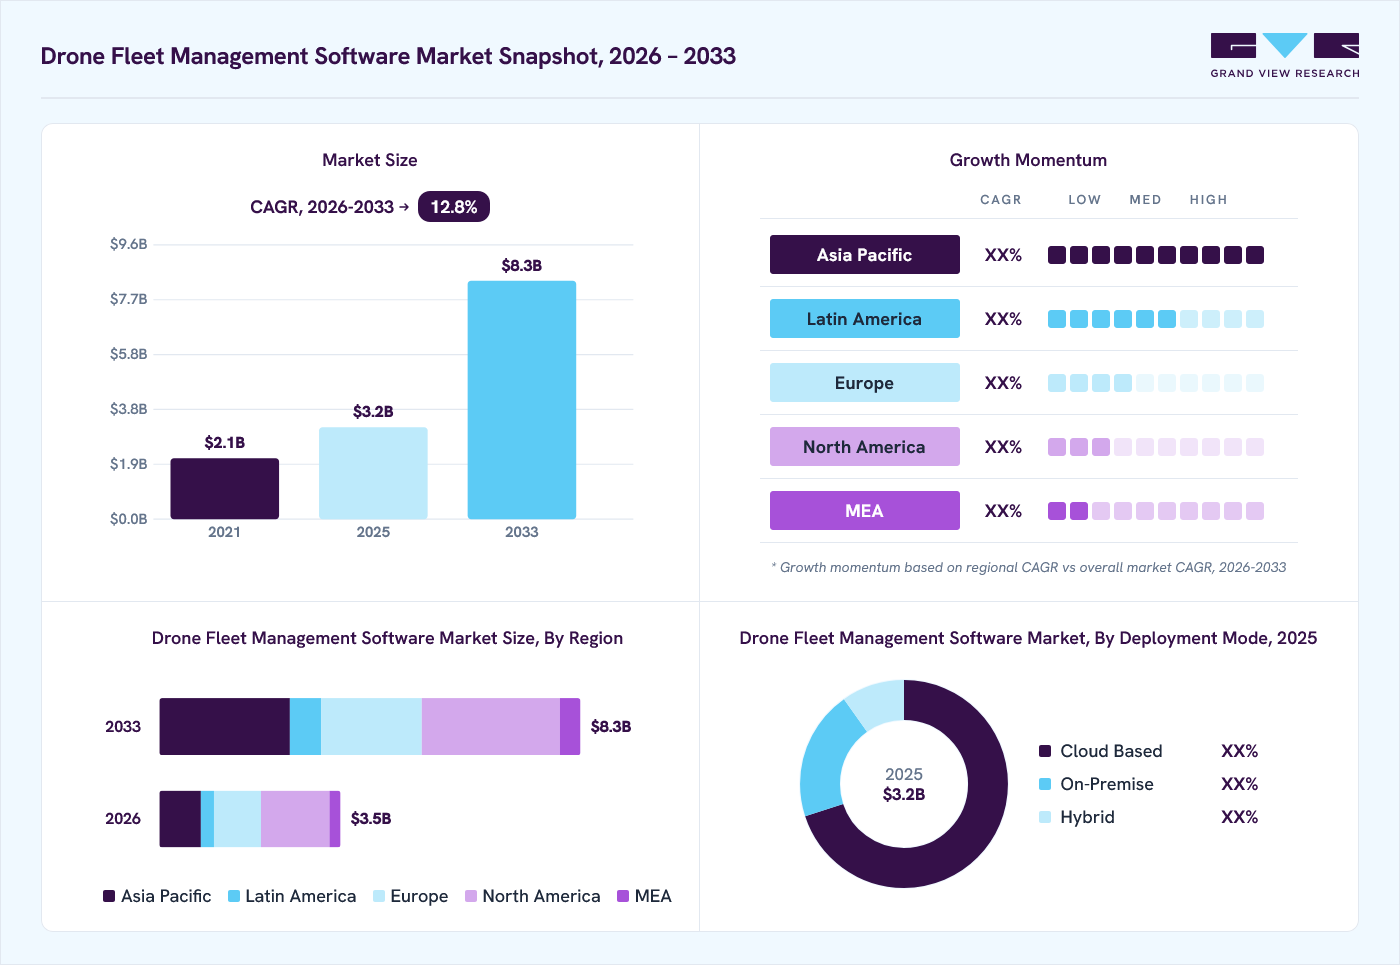
The global drone fleet management software market size was valued at USD 3.2 billion in 2025 and is projected to grow from USD 3.5 billion in 2026 to USD 8.3 billion by 2033, at a CAGR of 12.8% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 38.5% in 2025. The market is driven by increasing adoption of commercial and enterprise drone operations and increasing integration of autonomous flight and remote operations capabilities.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By deployment mode: Cloud-based segment held the largest market share of 69.9% in 2025.
- By enterprise size: Large enterprises segment held the largest market revenue share in 2025.
- By fleet size: Small fleet segment led the market with the largest revenue share in 2025.
- By functionality: Fleet tracking & monitoring segment held the largest market revenue share in 2025.
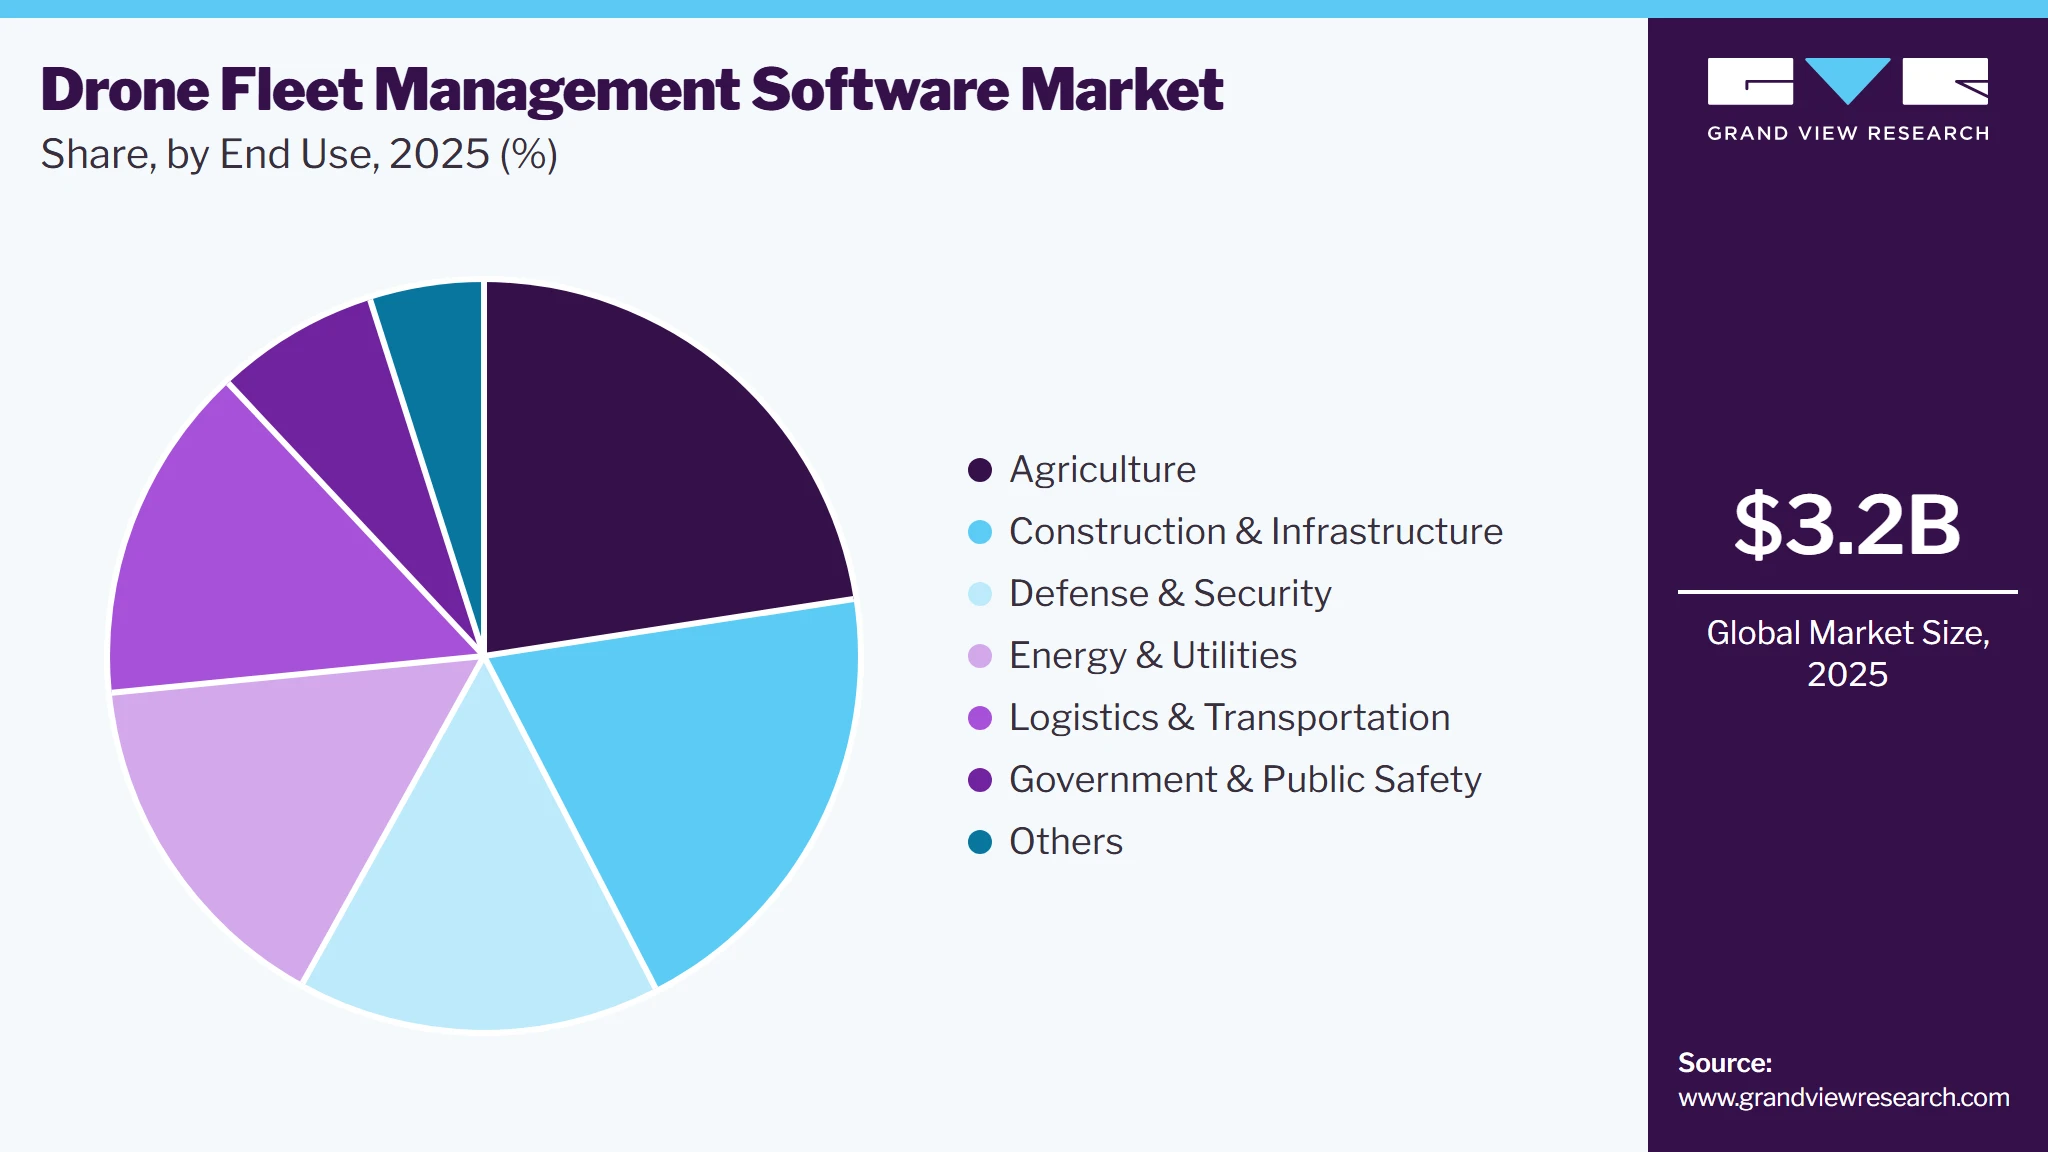
- By end use: Agriculture segment led the market with the largest revenue share in 2025.
Regional Highlights
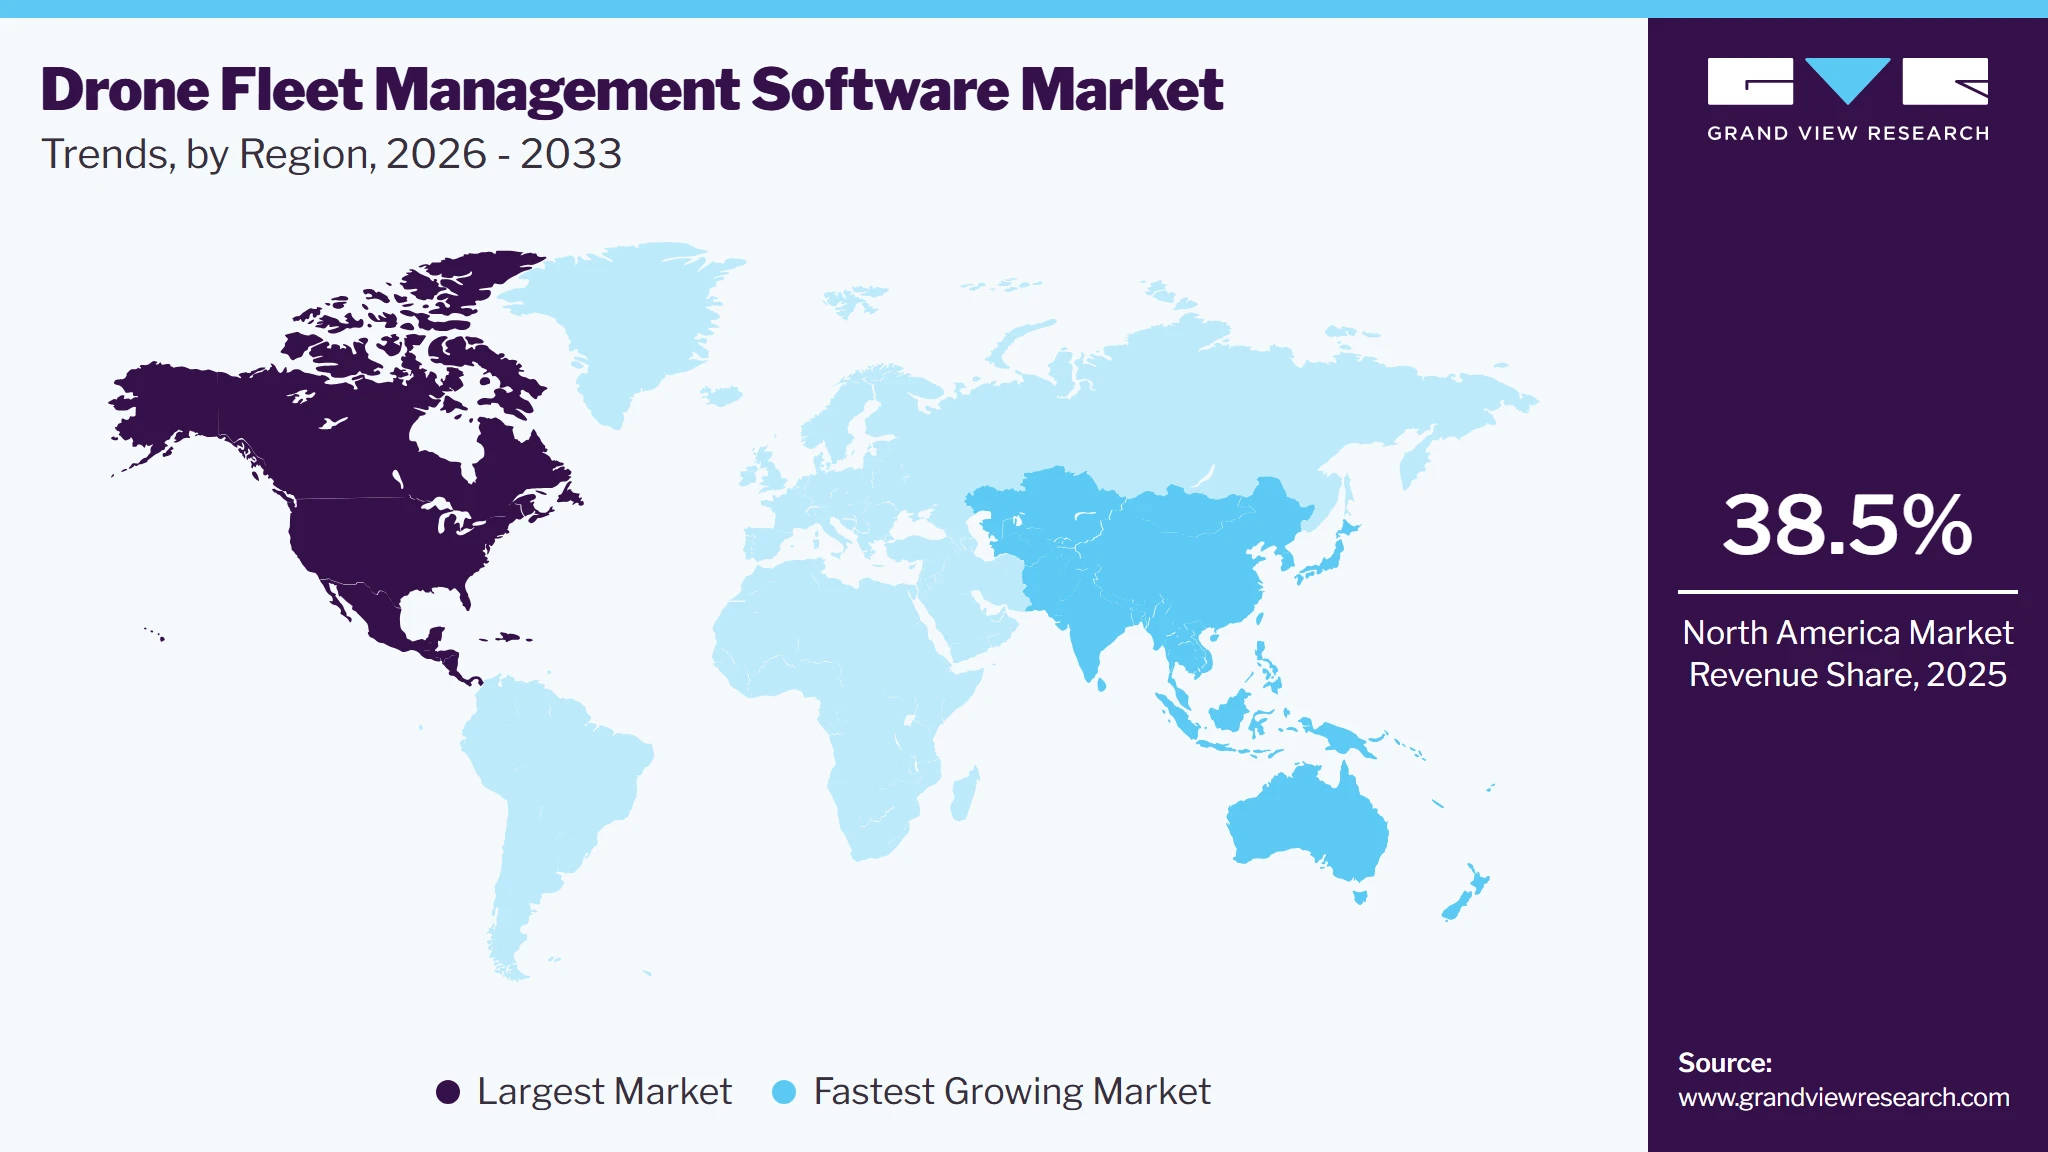
- Largest regional market: North America (38.5% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: U.S. held the largest share in 2025
Market Size & Forecasts
- Market size in 2025: USD 3.2 Billion
- Estimated market size in 2026: USD 3.5 Billion
- Projected market size by 2033: USD 8.3 Billion
- CAGR (2026-2033): 12.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The demand for drone fleet management software is increasing as organizations expand commercial, industrial, defense, and public-sector drone operations and require centralized platforms to manage increasingly complex fleets. Organizations are investing in software solutions for fleet tracking and monitoring, flight planning and scheduling, mission management, maintenance and asset management, regulatory compliance, pilot management, and operational analytics to improve coordination across multiple drones and missions. At the same time, the growing adoption of autonomous flight, remote operations, cloud-based platforms, real-time telemetry, and AI-enabled analytics is improving fleet visibility, asset utilization, mission efficiency, safety, and regulatory compliance, strengthening demand for advanced drone fleet management software.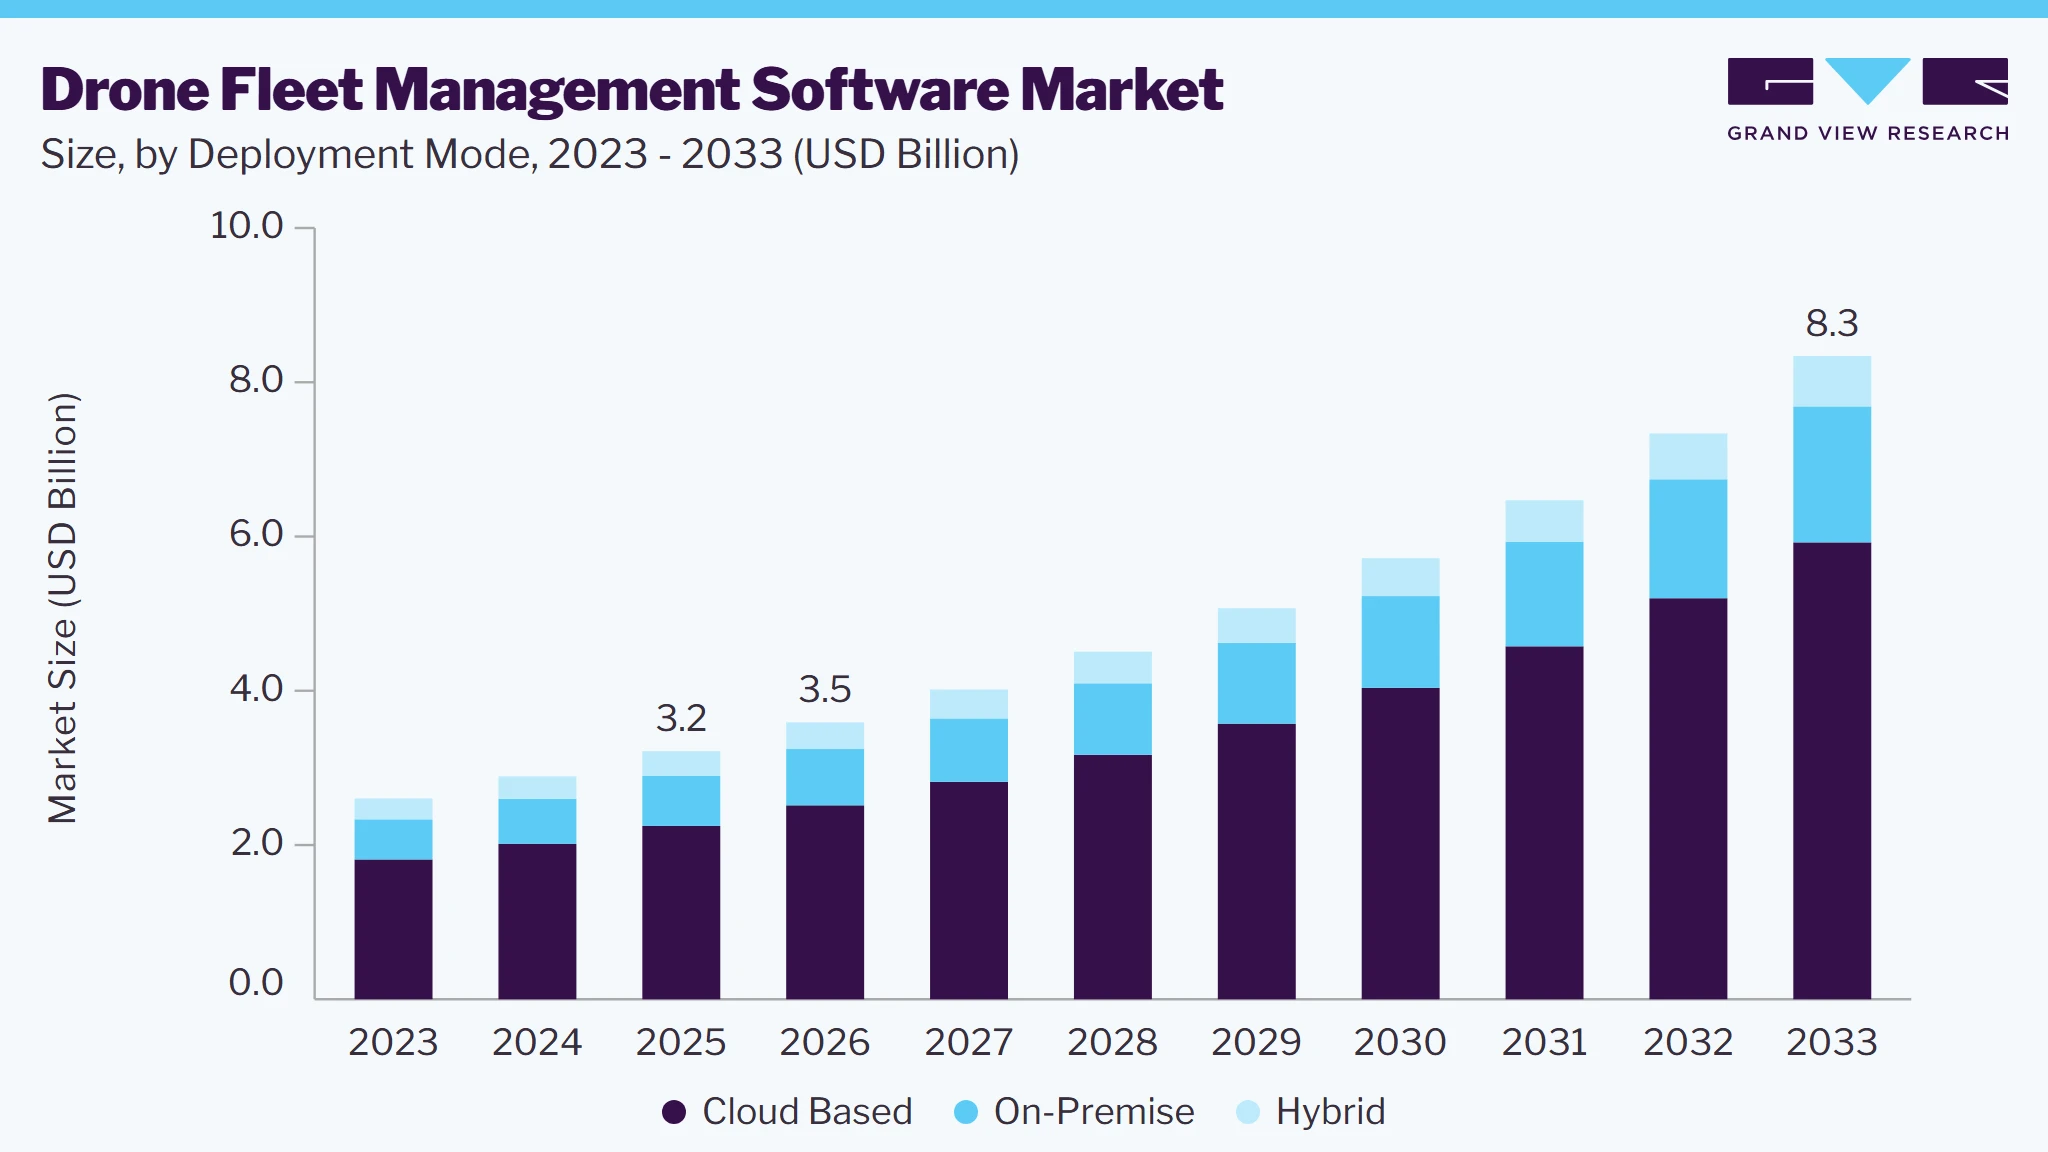 To learn more about this report, Download Free Sample Report
Market Dynamics
Although data security concerns, regulatory complexity, integration challenges, high software implementation costs, and interoperability issues across different drone platforms remain key restraints, the development of autonomous drone operations, AI-driven fleet optimization, drone-in-a-box systems, and advanced analytics is creating significant opportunities for market participants.
The industry is primarily driven by the increasing deployment of drones across surveying and mapping, inspection and monitoring, agriculture, construction, energy and utilities, logistics, defense, and public safety applications. As organizations operate larger and more geographically distributed fleets, the need for centralized systems to monitor drone locations, schedule flights, coordinate missions, manage pilots, and track asset performance is increasing. In parallel, the growing adoption of automated flight planning, real-time telemetry, remote fleet monitoring, and multi-drone mission coordination is enabling organizations to improve fleet utilization, reduce operational complexity, and enhance mission efficiency. The expansion of drone programs from individual aircraft operations toward coordinated fleet-based models is further strengthening demand for fleet management software.
Despite strong growth prospects, the market faces challenges associated with fragmented drone regulations, data security requirements, software integration, and interoperability across different drone platforms. Fleet management platforms need to integrate with diverse drone hardware, flight controllers, sensors, communication systems, cloud platforms, and existing enterprise software, which can increase implementation complexity and costs. Differences in airspace regulations, remote identification requirements, flight authorization processes, and operational restrictions across countries can further complicate fleet management. In addition, organizations may face cybersecurity risks associated with connected drones, real-time telemetry, cloud-based platforms, and remotely operated systems. These factors can increase deployment timelines and create barriers for smaller organizations adopting advanced fleet management solutions.
AI and predictive analytics can analyze flight, telemetry, battery, maintenance, and mission data to identify operational anomalies, optimize flight schedules, predict maintenance requirements, and improve fleet utilization. Autonomous fleet-management platforms can enable remote deployment, automated mission execution, charging, and recovery, reducing the need for continuous manual intervention. Furthermore, integration with digital airspace management systems, cloud infrastructure, real-time data platforms, and enterprise workflow systems creates opportunities for software providers, drone manufacturers, autonomous technology companies, connectivity providers, and technology integrators to develop more comprehensive fleet-management solutions.
Market Concentration & Characteristics
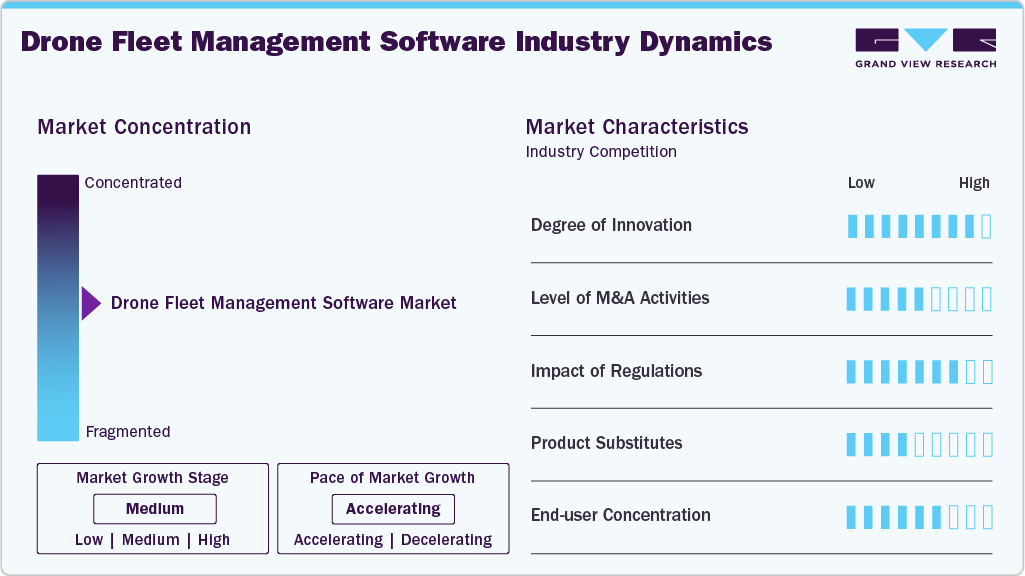
The market is moderately concentrated, with competition led by established drone technology and software companies offering capabilities across fleet monitoring, flight planning, mission management, asset management, regulatory compliance, remote operations, and data analytics. The market is characterized by continuous advancements in cloud-based fleet platforms, real-time telemetry, autonomous flight management, AI-enabled analytics, remote operations, drone-in-a-box systems, digital airspace integration, and multi-drone coordination. High software development and integration requirements, cybersecurity considerations, regulatory complexity, interoperability challenges, and the need to support diverse drone platforms create barriers to entry. These factors enable established software providers to strengthen their competitive positions through technological innovation, platform integrations, strategic partnerships, enterprise contracts, and long-term customer relationships.
 To learn more about this report, Download Free Sample Report
Key players operating in the industry are focused on improving real-time fleet visibility, automated flight planning, mission coordination, asset utilization, maintenance management, regulatory compliance, and operational analytics. The growing deployment of drones across various applications is encouraging organizations to adopt centralized software platforms capable of managing increasingly larger and more complex drone fleets.
Analyst Perspective
The industry is supported by the increasing adoption of drones across commercial, industrial, defense, public safety, and infrastructure applications and the growing need for centralized fleet management capabilities. Despite challenges related to regulatory complexity, cybersecurity risks, software integration requirements, interoperability across different drone platforms, and implementation costs, continued advancements in cloud-based platforms, AI-enabled analytics, autonomous fleet operations, drone-in-a-box systems, real-time telemetry, and digital airspace management are expected to create new growth opportunities. The increasing shift from manually operated individual drones toward centrally managed and increasingly autonomous fleets is expected to further strengthen demand for advanced drone fleet management software.
Deployment Mode Insights
The cloud-based segment held a significant share of the market in 2025, driven by the increasing adoption of centralized and remotely accessible platforms for managing distributed drone fleets. Cloud-based solutions enable organizations to monitor drone locations and status in real time, plan and schedule missions, manage flight and maintenance data, coordinate multiple operators, and access fleet information across different locations.
The on-premise segment is witnessing continued demand in the market, driven by organizations that require greater control over operational data, system infrastructure, and security. On-premise solutions are particularly relevant for defense and security organizations, government agencies, and enterprises managing sensitive flight, mission, and fleet information that may be subject to strict data governance and cybersecurity requirements.
Enterprise Size Insights
The large enterprises segment held a significant share of the market in 2025, driven by the extensive deployment of drones across construction and infrastructure, energy and utilities, defense, agriculture, logistics, and industrial operations. Large organizations typically manage larger and geographically distributed drone fleets, creating greater requirements for centralized fleet monitoring, mission planning, maintenance management, regulatory compliance, data analytics, and multi-user access. Higher technology budgets, established IT infrastructure, and the need to integrate drone operations with existing enterprise systems further support adoption among large enterprises.
The small & medium enterprises (SMEs) segment is witnessing significant growth, driven by the increasing adoption of drones for surveying and mapping, inspection, agriculture, construction, and specialized commercial operations. The availability of cloud-based and subscription-based fleet management platforms is reducing upfront technology and infrastructure requirements, making advanced fleet-management capabilities more accessible to smaller organizations. Growing demand for automated flight planning, real-time monitoring, compliance management, and operational analytics is further encouraging SMEs to adopt software solutions as their drone fleets expand.
Fleet Size Insights
The small fleet segment held a significant share of the market in 2025, driven by the widespread adoption of drone operations among commercial operators, SMEs, contractors, and specialized service providers. Organizations operating smaller fleets increasingly require software for centralized flight planning, real-time tracking, mission scheduling, pilot coordination, compliance management, and asset monitoring. The availability of scalable cloud-based platforms and subscription-based solutions is further enabling small fleet operators to access fleet-management capabilities without significant upfront infrastructure investments.
The medium fleet segment is witnessing significant growth, supported by the expansion of enterprise drone programs across construction, infrastructure, agriculture, energy, utilities, and inspection applications. Organizations operating medium-sized fleets require more sophisticated capabilities for coordinating multiple drones, scheduling missions, managing pilots, monitoring fleet performance, and optimizing maintenance activities.
Functionality Insights
The fleet tracking & monitoring segment held a significant share of the market in 2025, driven by the increasing need for real-time visibility into drone location, flight status, battery levels, telemetry, and overall fleet performance. Organizations operating multiple drones use centralized monitoring platforms to track fleet activity, identify operational issues, improve drone utilization, and enhance mission safety.
The flight planning & scheduling segment is witnessing significant growth, driven by the increasing complexity of coordinating multiple drones, missions, operators, and operating locations. Fleet management platforms enable organizations to plan flight routes, schedule missions, allocate drones and pilots, manage airspace restrictions, and optimize flight operations.
End Use Insights
The agriculture segment held a significant share of the market in 2025, driven by the increasing deployment of drone fleets for crop monitoring, field mapping, spraying, precision agriculture, and assessment of large agricultural areas. Fleet management software enables agricultural operators to schedule recurring missions, monitor multiple drones, manage flight routes, track equipment performance, and maintain operational records across geographically distributed farms.
 To learn more about this report, Download Free Sample Report
The construction & infrastructure segment is witnessing significant growth, driven by the increasing use of drone fleets for site surveying, mapping, progress monitoring, asset inspection, and infrastructure assessment. Construction companies and infrastructure operators are adopting fleet management platforms to coordinate multiple drone missions, schedule inspections, monitor fleet status, manage pilots and assets, and maintain consistent operational data across project sites.
Regional Insights
The North America drone fleet management software market dominated, accounting for a revenue share of 38.5% in 2025. North America is witnessing steady growth, supported by high adoption of commercial and enterprise drone operations, established drone regulations, and increasing investments in centralized fleet management and autonomous operations. The region, led by the U.S., benefits from the presence of major drone manufacturers, software providers, technology companies, defense organizations, and public safety agencies. Increasing deployment of drones across various sectors is strengthening demand for fleet tracking, flight planning, mission management, compliance, and data analytics solutions.
 To learn more about this report, Download Free Sample Report
U.S. Drone Fleet Management Software Market Trends
The drone fleet management software market in the U.S. is witnessing strong growth, supported by the expansion of commercial, industrial, defense, and public-sector drone programs. The country benefits from a well-developed ecosystem of drone manufacturers, software providers, autonomous technology companies, cloud service providers, and aviation technology firms, supporting the development and adoption of advanced fleet management platforms. Increasing requirements for real-time fleet monitoring, automated flight planning, regulatory compliance, remote operations, and multi-drone coordination are further supporting market growth.
Europe Drone Fleet Management Software Market Trends
The drone fleet management software market in Europe is witnessing steady growth, driven by increasing adoption of drones for infrastructure inspection, surveying and mapping, agriculture, energy, public safety, and industrial applications. European organizations are investing in centralized fleet management platforms to improve operational visibility, mission planning, asset management, regulatory compliance, and data analytics. Increasing focus on drone airspace integration, remote identification, autonomous operations, and standardized regulatory frameworks is further supporting demand for advanced fleet management software.
The UK drone fleet management software market is witnessing steady growth, driven by increasing commercial drone deployment, infrastructure inspection requirements, public safety applications, and investments in advanced unmanned aviation technologies. Organizations are adopting fleet management platforms for flight planning, real-time monitoring, mission coordination, pilot management, and regulatory compliance. Growing adoption of autonomous drone operations and increasing integration of drones into enterprise workflows are further supporting demand for centralized fleet management solutions.
Asia-Pacific Drone Fleet Management Software Market Trends
The drone fleet management software market in Asia-Pacific is expected to witness the fastest growth, supported by expanding drone adoption, industrial digitalization, infrastructure development, and increasing investments in autonomous and remotely operated drone fleets across China, India, Japan, South Korea, and Australia. Organizations in the region are adopting fleet management platforms to coordinate large-scale drone operations. The growing use of cloud-based platforms, AI-enabled analytics, automated flight planning, and multi-drone operations is further supporting regional market expansion.
The China drone fleet management software market is witnessing significant growth. The growing emphasis on low-altitude economy development and the expansion of large-scale drone operations are accelerating demand for advanced fleet management platforms that enable centralized monitoring, automated mission planning, real-time tracking, predictive maintenance, and efficient fleet coordination. Integration of artificial intelligence (AI), cloud computing, 5G connectivity, and advanced data analytics is transforming drone fleet operations by improving operational efficiency, flight safety, and autonomous decision-making.
Key Drone Fleet Management Software Market Company Insights
The drone fleet management software market is characterized by the presence of established drone technology and software companies. Competition is driven by continuous innovation in cloud-based platforms, real-time telemetry, AI-enabled analytics, automated flight planning, multi-drone coordination, and integration with diverse drone hardware and enterprise systems. Established players maintain strong market positions through advanced software capabilities, broad customer bases, strategic partnerships with drone manufacturers and technology providers, enterprise contracts, platform integrations, and continuous investments in autonomous and data-driven fleet management technologies.
-
AirData UAV is a prominent player in the market, offering platforms for drone fleet monitoring, flight data management, pilot and aircraft tracking, maintenance management, and operational analytics. The company strengthens its position through centralized fleet visibility, automated flight-log management, aircraft health monitoring, and analytics capabilities that support organizations managing multiple drone operations.
-
AirHub is a notable player in the market, offering solutions that support drone operations management, flight planning, fleet oversight, compliance, and operational workflows. The company strengthens its market position through integrated drone-management capabilities that help organizations coordinate missions, manage pilots and assets, maintain operational records, and improve regulatory compliance.
Key Drone Fleet Management Software Market Companies
The following key companies have been profiled for this study on the drone fleet management software market.
-
AirData UAV
-
AirHub
-
AlarisPro
-
Aloft Technologies
-
ANRA Technologies
-
Auterion
-
DJI
-
DroneDeploy
-
Dronedesk
-
DroneSense
-
FlyFreely
-
FlytBase
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: DJI; DroneDeploy; AirData UAV; Aloft Technologies; DroneSense; FlytBase; ANRA Technologies; Auterion
- Invest in advanced drone fleet management, real-time monitoring, flight planning, mission management, compliance, analytics, and autonomous operations capabilities.
- Expand platform capabilities through integrations with drone hardware, cloud platforms, enterprise systems, and airspace-management technologies.
- Strengthen market presence through enterprise contracts, government programs, strategic partnerships, technology integrations, and long-term customer relationships.
- Established presence in the drone software and technology ecosystem.
- Broad capabilities across fleet monitoring, flight planning, mission management, compliance, analytics, and autonomous operations.
- Strong customer and technology-partner networks.
- Extensive integration capabilities across drone platforms and enterprise systems.
- High technology development and platform-integration requirements.
- Dependence on evolving drone regulations and airspace-management frameworks.
- Interoperability challenges across different drone hardware and operating systems.
- Cybersecurity and data-protection requirements can increase implementation complexity.
Emerging Players: AirHub; AlarisPro; Dronedesk; FlyFreely
- Focus on specialized fleet-management, flight-operations, compliance, pilot-management, and asset-management capabilities.
- Expand functionality through cloud-based platforms, workflow automation, analytics, and integrations with drone hardware and operational systems.
- Target specialized commercial, enterprise, government, and professional drone operators through flexible and scalable software solutions.
- Specialized focus on drone operations and fleet-management workflows.
- Flexible platforms suited to specific operational and compliance requirements.
- Ability to respond quickly to evolving customer needs and regulatory requirements.
- Smaller customer and installed bases compared with leading established players.
- More limited financial and R&D resources relative to larger technology companies.
- Lower brand recognition in some international markets
Recent Developments
-
In June 2026, AirData UAV integrated its platform with LeoSight’s LeoCommand to bring real-time drone data directly into public-safety command and dispatch workflows. The integration enables agencies to combine live drone intelligence with operational coordination, supporting applications such as patrol operations, search and rescue, and Drone as a First Responder programs.
-
In May 2026, FlytBase partnered with Yarra Drones to support compliant autonomous drone operations and unmanned traffic management services in Australia. The collaboration is intended to support Australian drone operators as BVLOS operations expand, strengthening FlytBase’s capabilities in autonomous fleet management, airspace integration, and scalable remote drone operations.
Drone Fleet Management Software Market Report Scope
Report Attribute
Details
Market size in 2025
USD 3.2 billion
Estimated market size in 2026
USD 3.5 billion
Projected market size by 2033
USD 8.3 billion
Growth rate
CAGR of 12.8% from 2026 to 2033
Actual data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company share, competitive landscape, growth factors, and trends
Segments covered
Deployment mode, enterprise size, fleet size, functionality, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East and Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; China; Japan; India; South Korea; Australia; Brazil; UAE; KSA; South Africa
Key companies profiled
AirData UAV; AirHub; AlarisPro; Aloft Technologies; ANRA Technologies; Auterion; DJI; DroneDeploy; Dronedesk; DroneSense; FlyFreely; FlytBase
Customization scope
Free report customization (equivalent to up to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Drone Fleet Management Software Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global drone fleet management software market report based on deployment mode, enterprise size, fleet size, functionality, end use, and region.
-
Deployment Mode Outlook (Revenue, USD Billion, 2021 - 2033)
-
Cloud Based
-
On-Premises
-
Hybrid
-
-
Enterprise Size Outlook (Revenue, USD Billion, 2021 - 2033)
-
Large Enterprises
-
Small & Medium Enterprises
-
-
Fleet Size Outlook (Revenue, USD Billion, 2021 - 2033)
-
Small Fleet
-
Medium Fleet
-
Large Fleet
-
-
Functionality Outlook (Revenue, USD Billion, 2021 - 2033)
-
Fleet Tracking & Monitoring
-
Flight Planning & Scheduling
-
Mission Management
-
Maintenance & Asset Management
-
Pilot Management
-
Others
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Agriculture
-
Construction & Infrastructure
-
Defense & Security
-
Energy & Utilities
-
Logistics & Transportation
-
Government & Public Safety
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East and Africa
-
UAE
-
KSA
-
South Africa
-
-
Research Methodology
The drone fleet management software market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each drone fleet management software segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Deployment Mode
Revenue Capture Definition
Cloud Based
Revenue in the Cloud-Based segment is generated through the sale and subscription of cloud-hosted drone fleet management software platforms that enable organizations to remotely manage and coordinate drone operations through internet-based infrastructure. These solutions include fleet tracking and monitoring, flight planning and scheduling, mission management, asset and maintenance management, compliance management, pilot management, and data and analytics capabilities.
On-Premises
Revenue in the on-premises segment is generated through the sale and deployment of drone fleet management software installed and operated on an organization’s internal IT infrastructure. These solutions include fleet tracking and monitoring, flight planning and scheduling, mission management, asset and maintenance management, compliance management, pilot management, and data and analytics capabilities.
Hybrid
Revenue in the hybrid segment is generated through the sale and deployment of drone fleet management software that combines cloud-based and on-premises infrastructure to support centralized and flexible drone fleet operations. These solutions enable organizations to manage fleet tracking, flight planning, mission coordination, asset management, compliance, and operational analytics while retaining selected data, applications, or security functions within internal infrastructure.
Enterprise Size
Revenue Capture Definition
Large Enterprises
Revenue in the Large Enterprises segment is generated through the sale and subscription of drone fleet management software deployed by organizations operating large-scale or geographically distributed drone programs. These solutions support fleet tracking and monitoring, flight planning and scheduling, mission management, asset and maintenance management, regulatory compliance, pilot coordination, and data analytics across multiple drones and operating locations
Small & Medium Enterprises
Revenue in the Small & Medium Enterprises (SMEs) segment is generated through the sale and subscription of drone fleet management software adopted by smaller organizations and specialized drone operators managing relatively limited fleets. These solutions support fleet tracking and monitoring, flight planning and scheduling, mission management, asset management, compliance, pilot coordination, and operational analytics.
Fleet Size
Revenue Capture Definition
Small Fleet
Revenue in the Small Fleet segment is generated through the sale and subscription of drone fleet management software used by organizations and operators managing a relatively limited number of drones. These solutions support fleet tracking and monitoring, flight planning and scheduling, mission management, pilot coordination, asset management, maintenance tracking, and regulatory compliance
Medium Fleet
Revenue in the Medium Fleet segment is generated through the sale and subscription of drone fleet management software used by organizations managing multiple drones across recurring or geographically distributed operations. These solutions support fleet tracking and monitoring, flight planning and scheduling, mission management, pilot coordination, asset and maintenance management, compliance, and operational analytics.
Large Fleet
Revenue in the Large Fleet segment is generated through the sale and subscription of advanced drone fleet management software used by organizations operating large-scale and geographically distributed drone fleets. These solutions support real-time fleet tracking, automated flight planning, multi-drone mission management, asset and maintenance management, regulatory compliance, pilot coordination, remote operations, and advanced data analytics.
Functionality
Revenue Capture Definition
Fleet Tracking & Monitoring
Revenue in the Fleet Tracking & Monitoring segment is generated through software subscriptions and licensing for solutions that enable real-time tracking and centralized monitoring of drone fleets. These solutions provide visibility into drone location, flight status, telemetry, battery levels, connectivity, and operational performance, helping organizations improve fleet utilization, identify operational issues, and maintain oversight across multiple drone operations.
Flight Planning & Scheduling
Revenue in the Flight Planning & Scheduling segment is generated through software solutions that enable organizations to plan, schedule, and coordinate drone flights and missions. These solutions support route planning, flight scheduling, airspace and geofencing management, drone and pilot allocation, and automated mission planning, helping operators optimize flight operations and coordinate multiple drones across different locations
Mission Management
Revenue in the Mission Management segment is generated through software platforms that enable organizations to create, coordinate, execute, and monitor drone missions. These solutions support mission planning, task allocation, multi-drone coordination, remote mission control, real-time mission monitoring, and automated mission execution, helping organizations improve operational efficiency and mission consistency.
Maintenance & Asset Management
Revenue in the Maintenance & Asset Management segment is generated through software solutions used to monitor drone assets, schedule maintenance, track equipment condition, and manage fleet lifecycle information. These platforms support maintenance scheduling, battery tracking, equipment records, service histories, and asset utilization monitoring, helping organizations reduce downtime and improve fleet availability.
Pilot Management
Revenue in the Pilot Management segment is generated through software solutions that support the management and coordination of drone pilots and operators. These solutions include pilot scheduling, qualification and certification tracking, training records, flight-hour management, mission assignment, and operational workload coordination, helping organizations ensure appropriate pilot availability and regulatory compliance.
Others
Revenue in the Others segment is generated through additional drone fleet management capabilities that are not classified under the core functionality categories. These include compliance and regulatory management, data and analytics, reporting, workflow management, communications management, and enterprise-system integration
End Use
Revenue Capture Definition
Agriculture
Revenue in the Agriculture segment is generated through the sale and subscription of drone fleet management software used by agricultural operators to coordinate and monitor drone fleets deployed for crop monitoring, field mapping, spraying, precision agriculture, and agricultural surveying. These platforms support flight planning, fleet tracking, mission scheduling, asset management, and operational data management across multiple farms and geographically distributed agricultural sites.
Construction & Infrastructure
Revenue in the Construction & Infrastructure segment is generated through the sale and subscription of drone fleet management software used to manage drones deployed for surveying, mapping, site monitoring, progress tracking, infrastructure inspection, and asset assessment. These solutions enable organizations to coordinate multiple drone missions, monitor fleet operations, manage pilots and assets, and maintain consistent flight and inspection data across construction sites and infrastructure projects
Defense & Security
Revenue in the Defense & Security segment is generated through the sale and deployment of drone fleet management software used to coordinate drones for surveillance, reconnaissance, situational awareness, perimeter monitoring, and security operations. These platforms support real-time fleet tracking, mission planning, multi-drone coordination, remote operations, secure data management, and operational analytics, enabling defense and security organizations to manage complex and mission-critical drone fleets.
Energy & Utilities
Revenue in the Energy & Utilities segment is generated through the sale and subscription of drone fleet management software used to coordinate drone operations for inspection and monitoring of power infrastructure, pipelines, wind turbines, solar installations, oil and gas facilities, and utility networks. These solutions support flight scheduling, asset tracking, recurring inspection missions, maintenance management, and operational data collection across geographically distributed assets.
Logistics & Transportation
Revenue in the Logistics & Transportation segment is generated through the sale and subscription of drone fleet management software used to coordinate drones for delivery, cargo transportation, route planning, and logistics operations. These platforms support fleet monitoring, automated flight scheduling, mission coordination, route management, asset tracking, and real-time operational visibility, helping logistics operators manage increasingly complex and distributed drone delivery networks.
Government & Public Safety
Revenue in the Government & Public Safety segment is generated through the sale and deployment of drone fleet management software used by government agencies, law enforcement, emergency response organizations, and public safety departments. These solutions support surveillance, search and rescue, disaster response, emergency assessment, traffic monitoring, and incident management by enabling centralized fleet tracking, mission planning, pilot coordination, and real-time operational monitoring.
Others
Revenue in the Others segment is generated through the sale and subscription of drone fleet management software used across applications such as mining, telecommunications, media and entertainment, insurance, environmental monitoring, and marine operations.
Estimation Model
Layer
Key Questions
Description
Addressable Drone Fleet Base Layer
Which drone fleets require fleet management software?
Estimate the global installed base of commercial, industrial, defense, government, and public-safety drones operating as part of managed fleets. The assessment considers drone fleet size, operating frequency, application, organization type, geographic deployment, replacement cycles, and the increasing transition from individual drone operations to centralized fleet management.
Fleet Management Software Adoption Layer
What proportion of drone fleets use fleet management software?
Apply software adoption rates across addressable drone fleets, considering the use of fleet tracking, flight planning, mission management, asset management, compliance, pilot management, and operational analytics. Adoption is assessed by fleet size, enterprise size, deployment mode, end use, and regional market maturity.
Software Functionality & Deployment Layer
What software capabilities and deployment models are used by drone fleet operators?
Estimate the value associated with core fleet management functionalities, including fleet tracking and monitoring, flight planning and scheduling, mission management, maintenance and asset management, pilot management, and other capabilities. The assessment also considers cloud-based, on-premises, and hybrid deployment models.
Revenue Generation Layer
How is revenue generated from drone fleet management software?
Estimate market revenue generated through software subscriptions, licensing, platform fees, implementation, integration, maintenance, support, and related services. The assessment considers pricing structures, subscription models, fleet size, number of users and drones managed, functionality adopted, and enterprise requirements.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Drone Fleet Management Software Market Entry & Growth Strategy
Identified high-growth functionalities, deployment models, fleet sizes, end-use industries, and geographic markets.
Assessed opportunities across fleet tracking & monitoring, flight planning & scheduling, mission management, maintenance & asset management, pilot management, and other functionalities.
Supported market entry, product positioning, customer targeting, partnership identification, and long-term expansion strategies.
Highlighted opportunities across commercial, industrial, defense, and public-sector drone operations, including autonomous and remote fleet management.
Autonomous Drone Operations & Fleet Management Capability Assessment
Assessment of fleet management requirements across commercial operators, enterprises, defense & security organizations, government agencies, and public safety departments.
Evaluation of requirements for real-time fleet monitoring, automated flight planning, multi-drone coordination, remote operations, regulatory compliance, and mission management.
Identified technology gaps and high-potential opportunities across autonomous fleet operations, AI-enabled analytics, drone-in-a-box systems, predictive maintenance, and UTM integration.
Supported technology roadmap development, R&D prioritization, product differentiation, and next-generation fleet management strategies.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


