
- Home
- »
- Medical Devices
- »
-
Eye Care Service Market Size And Share Report, 2026-2033GVR Report cover

Eye Care Services Market (2026 - 2033)
Size, Share & Trends Analysis Report By Service Type (Vision Testing & Eye Exams, Surgical Interventions), By Indication (Dry Eye Syndrome), By Provider Type, By Region, And Segment Forecasts
Market Size, 2025
$179.7BMarket Estimate, 2026
$194.8BMarket Forecast, 2033
$376.4BCAGR, 2026–2033
9.9%Eye Care Services Market Summary
The global eye care service market size was valued at USD 179.7 billion in 2025 and is projected to grow from USD 194.8 billion in 2026 to USD 376.4 billion by 2033, at a CAGR of 9.9% from 2026 to 2033. North America dominated the market with the largest revenue share of 39.8% in 2025. The growth is attributed to the increasing number of individuals experiencing vision-related issues, a quickly aging population, advancements in technology, and heightened awareness regarding eye care.
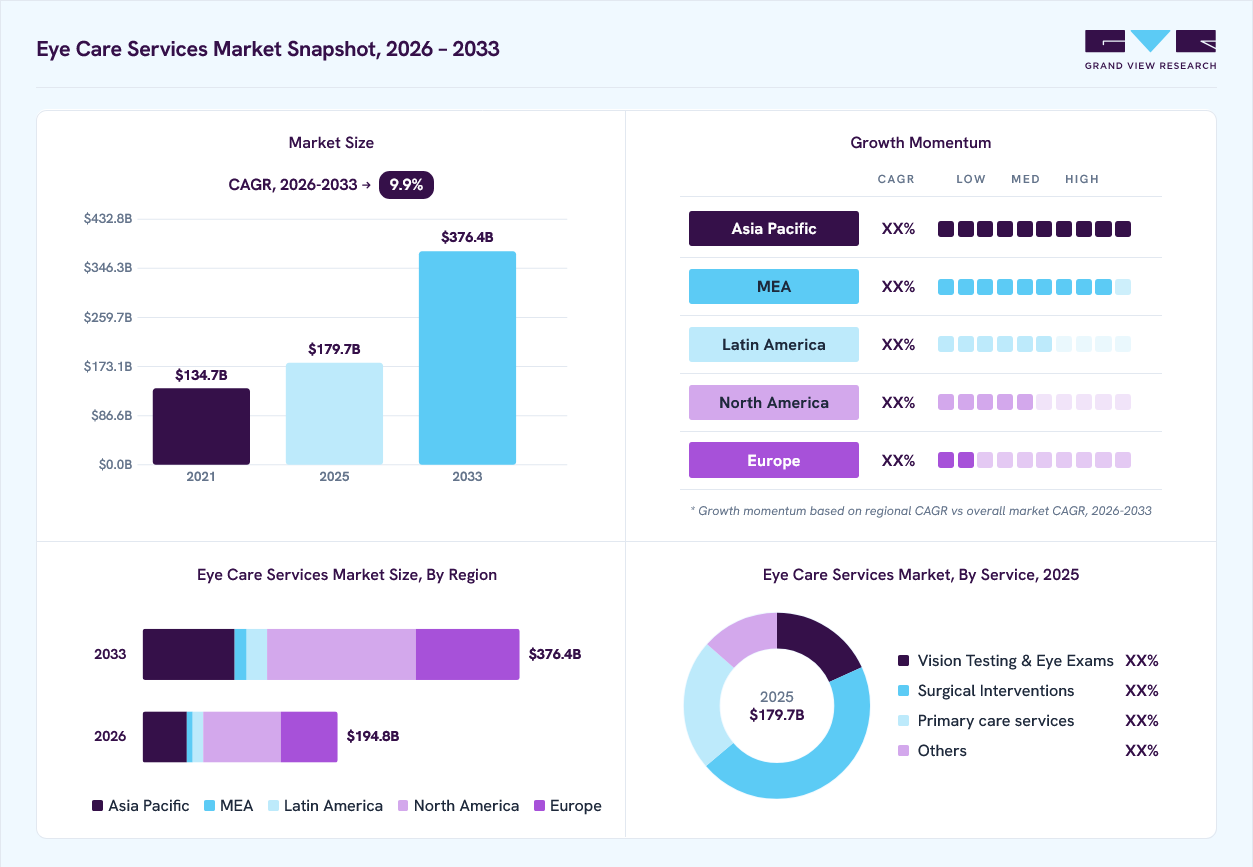 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By service: Surgical interventions segment held the largest market share of 45.8% in 2025.
- By indication: Refractive errors segment held the largest market share of 39.0% in 2025.
- By provider type: Standalone eye clinics segment held the largest market share of 34.8% in 2025.
Regional Highlights
- Largest regional market: North America (39.8% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 179.7 Billion
- Estimated market size in 2026: USD 194.8 Billion
- Projected market size by 2033: USD 376.4 Billion
- CAGR (2026-2033): 9.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The rising occurrence of vision problems, particularly vision impairment and presbyopia, offers substantial opportunities for industry. According to the World Health Organization (WHO) report published in August 2023, approximately 2.2 billion people suffer from vision impairment globally. In addition, there are an estimated 1.09 billion cases of presbyopia in the middle-aged elderly population propelling the demand for vision care services.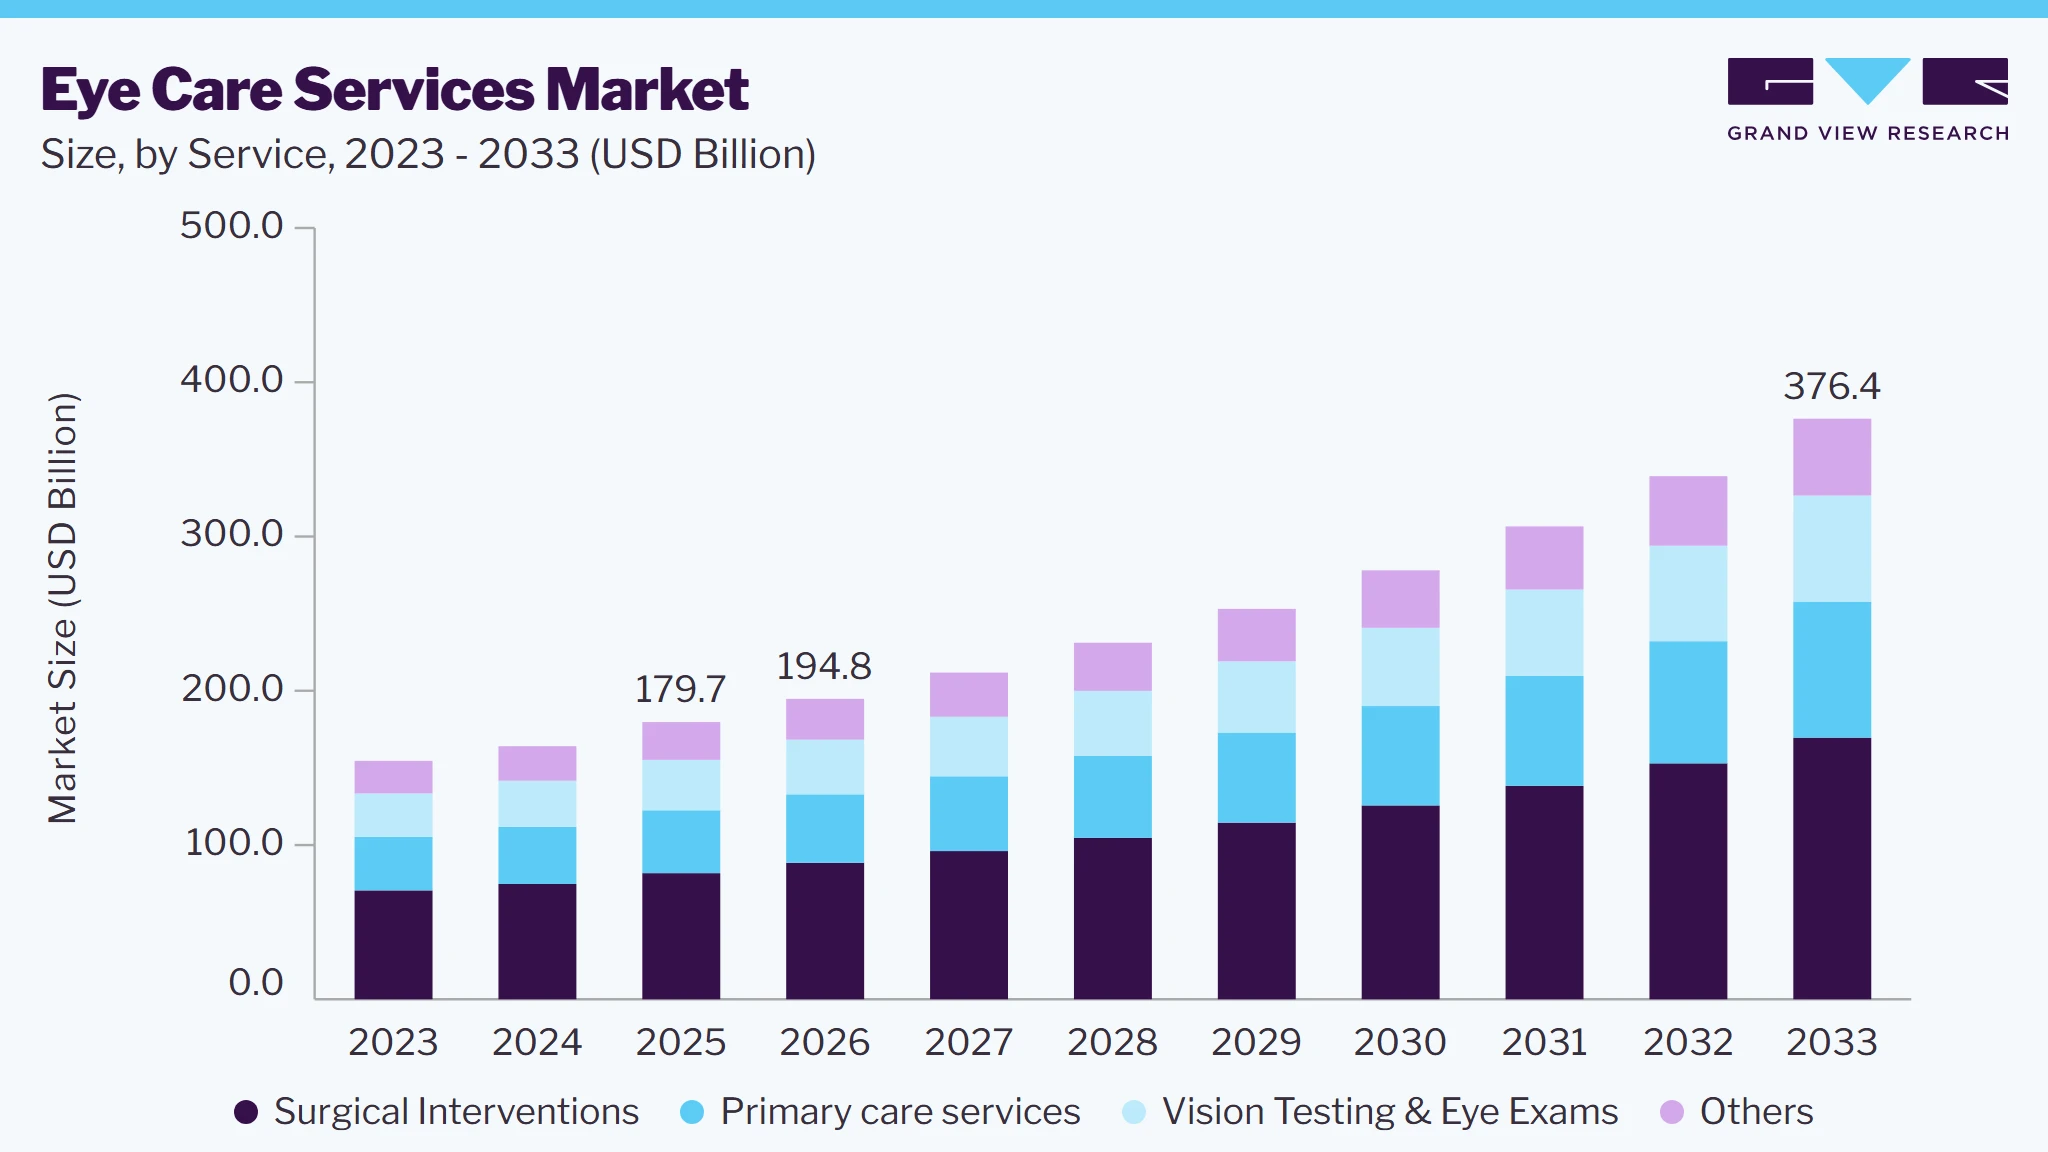 To learn more about this report, Download Free Sample Report
Technological advancements in diagnostic and surgical procedures, such as minimally invasive laser surgeries and AI-driven diagnostic tools, have enhanced treatment outcomes and patient experience, further stimulating demand. In addition, greater awareness of vision health aided by public health campaigns and routine vision screening programs has increased early diagnosis rates and the uptake of preventive care services.
Moreover, the market is also being driven by increased access to care in emerging economies, supported by both public sector initiatives and private investments in tele-optometry and mobile eye clinics. In developed regions, higher spending capacity and the expansion of insurance coverage for vision care contribute to consistent market growth.
Technological & Awareness Trend in Market
Category
Technologies/Initiatives
Impact on Market
Diagnostic Technologies
AI-based retinal imaging, Optical Coherence Tomography (OCT)
Faster, earlier, and more accurate diagnosis
Surgical Advancements
LASIK, femtosecond laser-assisted cataract surgery, SMILE
Minimally invasive, faster recovery, improved outcomes
Digital Tools
Tele-optometry, smartphone-based vision testing apps
Expanded access to remote/rural populations
Public Awareness Programs
School vision screening, World Sight Day campaigns
Increased early detection and demand for preventive care
Wearable Tech & Monitoring
Smart contact lenses, continuous IOP monitors for glaucoma
Real-time monitoring improves management of chronic cases
Integration with EHR
AI-assisted EHR analytics in ophthalmology
Streamlined care coordination and personalized treatments
Technological Innovations & Applications in Industry
Technology/Initiative
Example
Description & Impact
AI-Based Retinal Imaging
Google’s DeepMind & Moorfields Eye Hospital
AI algorithms analyze retinal scans to detect diabetic retinopathy with high accuracy, enabling early treatment and reducing blindness risk.
Tele-optometry Platforms
Opternative (now Visibly)
Online vision tests allow patients to renew prescriptions remotely, increasing convenience and access, especially during COVID-19.
Femtosecond Laser Surgery
Alcon’s LenSx Laser System
Widely adopted in cataract surgery, improves precision and reduces recovery time compared to traditional methods.
Smart Contact Lenses
Google/Verily’s Smart Lens (under development)
Designed to monitor glucose levels in tears for diabetic patients, promising non-invasive real-time health tracking.
Public Awareness Campaigns
World Sight Day & Prevent Blindness Campaigns
Global and national efforts are increasing public knowledge on eye health, resulting in higher screening rates and preventive care uptake.
Mobile Eye Clinics
Aravind Eye Care System (India)
Provides high-volume, low-cost eye exams and surgeries in rural regions, leveraging portable diagnostic tools and telemedicine for follow-up.
Furthermore, increasing public health initiatives and a focus on preventive care are raising awareness about the necessity of regular eye exams. In May 2024, the Canadian Association of Optometrists (CAO) initiated a nationwide digital campaign to highlight the significance of eye health. This campaign, backed by provincial optometry associations, encourages Canadians to book regular eye exams with their optometrists.
Initiatives Enhancing Access to Eye Care
Region
Initiative
Description & Impact
Emerging Economies
Public Sector Vision Programs
Governments launch national blindness prevention programs (e.g., India’s NPCBVI, China’s Vision 2020) to improve screening and treatment accessibility.
Mobile Eye Clinics
Portable diagnostic and surgical units deliver care to remote/rural populations, reducing travel barriers (e.g., Aravind Eye Care System in India).
Tele-optometry Platforms
Remote vision testing and consultations expand services to underserved areas, especially where specialists are scarce.
NGO and Non-Profit Partnerships
Organizations such as Orbis International provide funding, training, and infrastructure support to improve care delivery
Developed Regions
Insurance Expansion for Vision Care
Broader coverage of eye exams, corrective lenses, and surgeries under public (Medicare, NHS) and private insurance plans increases patient uptake.
Corporate Wellness & Screening Programs
Employers integrate routine vision screening and care into employee health plans, boosting preventive care participation.
Investment in Advanced Clinics & Technologies
The private sector invests in state-of-the-art diagnostic and surgical centers, enhancing treatment quality and patient experience.
Digital Health Integration
Adoption of telehealth, AI diagnostics, and electronic records improves care coordination and access, especially post-COVID-19.
In addition, policy frameworks and government initiatives play a pivotal role in shaping the accessibility, quality, and delivery of eye care services worldwide. By establishing national programs, expanding insurance coverage, and reforming regulations, countries can address key challenges such as limited access in rural areas, increasing prevalence of vision disorders, and rising healthcare costs.
Policy Impact on Eye Care Services
Country/Region
Policy Initiative
Impact on Market
India
National Programme for Control of Blindness & Visual Impairment (NPCBVI)
Massive scale-up of cataract surgeries and vision screening; improved access in rural areas; reduced blindness rates.
China
National Myopia Control Plan
Introduction of school-based vision screenings and public awareness campaigns; early detection and management of myopia in children.
U.S.
Medicare Coverage Expansion for Eye Care
Increased access to glaucoma and diabetic retinopathy screenings among seniors; growth in outpatient eye care services.
UK
NHS Vision Screening Programs
Preventive care focus led to higher early diagnosis rates and reduced long-term treatment costs; integrated digital health tools usage.
Brazil
Public-Private Partnerships in Eye Care
Enhanced reach of mobile eye clinics in underserved rural areas; improved affordability and access for low-income populations.
South Africa
Telehealth Regulatory Reforms
Enabled growth of tele-optometry services, improving access in remote regions; stimulated private sector investment in digital eye care.
Access to comprehensive vision care remains a significant challenge for many underserved and remote populations, particularly in rapidly growing urban areas. To address these gaps and improve early diagnosis and treatment of vision impairments, innovative outreach programs have become increasingly vital. For instance, in August 2024, Sightsavers introduced a Mobile Eye Health Van in Bangalore aimed at expanding access to quality eye care services, especially for underserved and remote communities. The mobile unit is equipped with advanced diagnostic tools and staffed by trained eye care professionals, enabling on-site vision screenings, cataract detection, and referrals for treatment. This initiative supports early diagnosis and timely intervention, reducing barriers such as travel distance and cost, and contributes to the broader goal of eliminating avoidable blindness in the region.
Market Dynamics
The global eye care services market is witnessing significant growth, primarily driven by the rising prevalence of vision disorders, the elderly population, and the growing incidence of chronic diseases such as diabetes, which significantly impact eye health. These factors continue to drive demand for routine eye examinations, early disease diagnosis, vision correction services, and advanced ophthalmic treatments. Market expansion is further supported by increasing awareness of preventive eye care, the growing adoption of advanced diagnostic technologies, and the rising demand for minimally invasive ophthalmic procedures such as cataract surgery, LASIK, and retinal treatments. Further, the integration of AI-based diagnostics, tele-ophthalmology, and digital screening solutions is enhancing service accessibility, improving clinical outcomes, and supporting faster, more efficient patient care across both developed and emerging healthcare markets.
The growing adoption of AI-powered diabetic retinopathy screening programs is a major growth driver for the market, significantly improving early detection of vision-threatening retinal diseases and increasing patient inflow into ophthalmic care systems. For instance, in 2025, this trend gained strong momentum with the launch of India’s first AI-driven community screening program for diabetic retinopathy by the Armed Forces Medical Services (AFMS) in collaboration with AIIMS and the Ministry of Health, utilizing the MadhuNetrAI platform for rapid retinal image analysis. In addition, AIIMS reported that its MadhuNETrAI application achieved over 95% detection accuracy, demonstrating the growing clinical reliability of AI-enabled screening models. As large-scale AI screening improves accessibility in primary care and underserved regions, more patients are being referred for advanced diagnostic imaging, retina consultations, laser therapies, and surgical interventions. This is substantially increasing demand for comprehensive eye care services, particularly in retina-focused diagnostic and treatment segments.
Case Study Published by NCBI in 2025 June: AI-Based Diabetic Retinopathy Screening Enhancing Eye Care Service Efficiency in Spain
Background
The adoption of AI-enabled diabetic retinopathy (DR) screening is emerging as a transformative factor in the global eye care services market. It improves screening efficiency, reduces diagnostic delays, and accelerates patient access to specialized ophthalmic care. A notable example is the implementation of the NaIA-RD AI screening platform at the University Hospital of Navarre, Spain, which was introduced to address the growing burden of diabetic retinopathy screening among diabetic patients. Before AI deployment, retinal images were manually reviewed by general practitioners. This created operational bottlenecks due to rising patient volumes, limited specialist availability, and time-intensive screening workflows.
AI Solution Implemented
To overcome these challenges, the hospital introduced NaIA-RD, an AI-powered platform designed to:
• Automatically analyze retinal fundus images
• Assess image quality
• Classify diabetic retinopathy severity
• Support referral decisions for ophthalmic care
Key Results and Market Impact
The implementation delivered significant improvements in screening performance and operational efficiency. A real-world comparative study reported that the number of screened patients increased from 19,828 before AI deployment to 22,962 after implementation. In addition, screening workload was reduced by approximately 4.27 times, while maintaining strong clinical accuracy with zero missed cases of sight-threatening diabetic retinopathy.
Metric
Before AI Deployment
After AI Implementation
Impact
Patients Screened
19,828
22,962
Higher screening coverage
Screening Workload
Baseline
4.27x lower
Improved operational efficiency
Sight-Threatening DR Missed
Not reported
0 cases
Strong clinical reliability
Referral Support
Manual
AI-assisted
Faster specialist referral
This case highlights the growing role of AI in expanding screening capacity, reducing diagnostic delays, and improving early disease detection. From a market perspective, AI-driven screening solutions are strengthening patient inflow into eye care systems by increasing referrals for advanced diagnostic imaging, retina consultations, laser therapies, and other ophthalmic interventions. As healthcare systems continue to adopt AI-enabled ophthalmology solutions, these technologies are expected to play a critical role in driving growth across screening, diagnostics, and treatment segments of the global eye care services market.
A growing shortage of ophthalmologists and allied eye care professionals is significantly limiting the market. Rising rates of cataracts, glaucoma, diabetic retinopathy, age-related macular degeneration, and other chronic eye conditions have sharply increased demand for diagnostic, surgical, and follow-up care. However, the supply of trained professionals has not kept pace, resulting in longer waiting lists, delayed diagnoses and treatments, reduced surgical capacity, and limited access to specialist care, especially in rural and underserved areas. These workforce shortages prevent hospitals and specialty clinics from expanding services to meet demand, constraining market growth. For instance, in the UK, the Royal College of Ophthalmologists' Workforce Census found that 76% of NHS eye units lacked enough consultant ophthalmologists, and 52% faced increasing recruitment challenges. In early 2023, over 632,000 patients were on ophthalmology waiting lists in England, with 63% of eye units estimating it would take more than a year to clear backlogs. Also, 26% of consultant ophthalmologists planned to leave the workforce within five years, further straining capacity. Similar shortages are reported in the U.S. and several European countries, where elderly populations are driving demand faster than workforce growth, limiting patient access and slowing market expansion.
The expansion of organized eye care chains into underserved and high-growth markets presents a major opportunity for the market. Despite rising demand for ophthalmic care, a significant portion of advanced eye care infrastructure remains concentrated in major urban centers, leaving substantial unmet demand across Tier-2, Tier-3, and rural regions. This is creating strong growth opportunities for organized eye hospital networks, specialty ophthalmology chains, and integrated diagnostic platforms to expand through greenfield centers, strategic acquisitions, and hub-and-spoke delivery models.
For instance, in 2025, this trend gained significant momentum with major investments and expansion initiatives, including Maxivision’s INR 500 crore expansion in Maharashtra, EssilorLuxottica’s acquisition of European ophthalmology platform Optegra, and Verlinvest’s USD 75 million investment in The Eye Foundation. These developments highlight growing investor confidence and strong commercial potential in expanding specialized eye care infrastructure. As organized providers continue to expand into underserved markets, this trend is expected to accelerate growth across surgical, diagnostic, and preventive eye care services.
Key Opportunities in the Market
Opportunity Area
Development / Example
Market Impact
Expansion of AI-Enabled Eye Disease Screening Services
In 2025, Moorfields Eye Hospital and Google Health (DeepMind) continued expanding AI-assisted retinal disease detection technologies to support faster diagnosis of retinal diseases and improve patient triage across ophthalmology services.
Enables earlier detection of retinal diseases, improves clinical efficiency, reduces ophthalmologist workload, and expands access to eye screening services, particularly in high-volume healthcare systems.
Expansion of Retail and Integrated Eye Care Networks
In January 2025, EyeCare Partners partnered with Latino Eye Institute to expand comprehensive ophthalmology and optometry services across the Chicago region, strengthening access to cataract, retina, glaucoma, pediatric ophthalmology, and optical services.
Expands geographic coverage, increases patient volumes, strengthens referral networks, and supports comprehensive eye care delivery through integrated service models.
Growing Investment in Premium Cataract and Refractive Surgery Services
In 2024, Alcon expanded its premium cataract surgery portfolio through continued commercialization of the Clareon PanOptix Pro intraocular lens (IOL) and advanced surgical technologies, supporting growing demand for premium vision correction procedures globally.
Increases procedural revenue per patient, accelerates adoption of premium surgical services, and supports growth of private ophthalmology clinics and ambulatory surgery centers through higher-value treatment offerings.
Source: Secondary Research, Grand View Research
Market Concentration & CharacteristicsThe chart below represents the relationship between industry concentration, industry characteristics, and industry participants. The industry displays a moderate level of concentration, with several key players dominating the market. There are stringent regulatory standards ensuring service quality and safety. Moreover, the industry benefits from increasing demand for ocular healthcare globally.
The industry is experiencing a high degree of innovation. The use of the eye as a diagnostic window into overall health known as oculomics combined with AI, is emerging as a powerful approach to identify diseases earlier and more accurately. For instance, in May 2025, the Alliance for Healthcare from the Eye was launched to revolutionize disease detection and coordinated care delivery by leveraging cutting-edge technologies such as oculomics and artificial intelligence AI. By integrating advanced data insights with clinical practice, the alliance seeks to transform how healthcare providers detect and manage diseases, positioning eye care as a pivotal gateway to overall health.
 To learn more about this report, Download Free Sample Report
are leveraging M&A activities to innovate and offer advanced solutions that meet the evolving needs of healthcare professionals. For instance, in May 2024, Visibly acquired Lensabl to enhance its platform with optical e-commerce, aiming to make vision care more accessible. Lensabl's expertise includes direct-to-consumer sales and a growing B2B sector, offering white-label e-commerce solutions and modernized vision plans. This merger combines Lensabl's retail offerings with Visibly's telehealth services, promising broader access to affordable vision care.
The regulatory framework for the industry involves compliance with industry-specific guidelines and standards to ensure accuracy and consistency. In May 2022, WHO introduced Eye Care in Health Systems; Guide for Action during the 75th World Health Assembly in Geneva. The guide presents a practical four-step process: conducting a situation analysis; developing an eye care strategic plan with a monitoring framework; formulating and implementing an operational plan; and establishing ongoing review mechanisms. To support these steps, WHO has developed four key tools: the Eye Care Situation Analysis Tool (ECSAT), Eye Care Indicator Menu (ECIM), Package of Eye Care Interventions (PECI), and Eye Care Competency Framework (ECCF).
The market is experiencing a significant degree of service expansion as the demand for home-based care services continues to increase. Companies are expanding their services to include a broader range of healthcare services. For instance, in February 2025, Maxivision Super Specialty Eye Hospitals entered a strategic partnership with Mumbai-based Ojas Group to form a joint venture named Ojas Maxivision Eye Hospitals. This collaboration aims to invest USD 58.41 million to expand eye care services across Maharashtra. The initiative plans to open five new centers in Mumbai within the next 24 months and gradually extend operations to other parts of the state.
Analyst Perspective
The global eye care services market is witnessing robust growth, driven by the rising prevalence of vision disorders, increasing aging population, and growing awareness regarding preventive eye health. As populations age particularly across developed and rapidly urbanizing economies the incidence of age-related eye conditions such as cataracts, glaucoma, age-related macular degeneration (AMD), and diabetic retinopathy is increasing significantly, creating sustained demand for diagnostic, surgical, and specialized ophthalmic care services. The market is also benefiting from rapid technological advancements in ophthalmology, including AI-powered diagnostics, advanced retinal imaging, minimally invasive surgical procedures, and tele-ophthalmology platforms, which are improving early disease detection, treatment accuracy, and service accessibility.
Service Type Insights
Based on service, the surgical interventions segment led the market with the largest revenue share of 45.8% in 2025. The aging global population, especially in developed and middle-income countries, is driving the demand for advanced ophthalmic surgical procedures. Technological advancements such as femtosecond lasers, minimally invasive glaucoma surgeries (MIGS), and robotic-assisted surgeries are making procedures safer, faster, and more effective, thereby increasing patient acceptance.
In addition, increased healthcare spending and the expansion of ambulatory surgical centers specializing in ophthalmology are also contributing to the rising number of surgical procedures worldwide. For instance, in June 2024, AMSURG and Comprehensive EyeCare Partners (CompEye) jointly acquired Alta Rose Surgery Center in Las Vegas, Nevada, marking the fourth outpatient surgery center under their expanding partnership. This acquisition aligned with AMSURG's strategic focus on expanding its network of ambulatory surgery centers (ASCs) following its emergence as an independent entity after separating from Envision Healthcare.
The primary care services segment is anticipated to grow at the fastest CAGR over the forecast period, attributed to the rising awareness of preventive eye health, increasing prevalence of chronic conditions such as diabetes and hypertension that affect vision, and an aging global population prone to age-related diseases such as cataracts, macular degeneration, and glaucoma. Technological advancements in diagnostic tools and tele-optometry are expanding access to eye exams, especially in underserved or rural areas. For instance, in March 2023, Orbis International, in collaboration with PBMA's H.V. Desai Eye Hospital, inaugurated a Green Vision Center (GVC) in Satara, Maharashtra, with the aim of delivering sustainable and accessible primary care services to the local community. This initiative is part of Orbis's broader strategy to establish environmentally responsible facilities across India.
In addition, the growing integration of vision care into general healthcare frameworks, especially in countries with universal health systems or expanding insurance coverage, is boosting demand for routine eye checkups, refractive error correction, and chronic disease monitoring.
Indication Insights
Based on the indication, the refractive errors segment led the market with the largest revenue share of 39.0% in 2025. The growth in the demand for vision correction is due to aging populations experiencing more vision issues such as presbyopia and cataracts. In addition, there is a rise in myopia among children and teens, attributed to increased screen time and reduced outdoor activities. Advances in technology, such as the emergence of minimally invasive surgical methods such as SMILE and the incorporation of AI in diagnostic tools, have improved the accuracy and safety of refractive surgeries. In May 2024, WHO launched the SPECS 2030 initiative to address uncorrected refractive errors, the leading cause of vision impairment globally. This initiative aims to increase the effective coverage of refractive error correction by 40% by 2030, ensuring that more individuals have access to appropriate spectacles. SPECS 2030 focuses on five strategic pillars: improving access to refractive services, building the capacity of personnel, enhancing population education, reducing the cost of refractive error services, and strengthening surveillance and research.
The glaucoma segment is expected to grow at the fastest CAGR during the forecast period. Glaucoma is a group of conditions that damage the optic nerve, and is increasingly affecting aging populations worldwide, particularly among individuals over 60. The rising geriatric population, along with increasing rates of diabetes and hypertension both risk factors for glaucoma have led to higher demand for early screening, diagnosis, and treatment. Advancements in diagnostic technologies, such as Optical Coherence Tomography (OCT) and AI-assisted imaging, have made detection more accurate and accessible, encouraging routine eye exams. In January 2025, Optegra introduced a new NHS glaucoma service at its Eye Hospital in Manchester, aiming to alleviate long waiting times at local NHS trusts. This free service is designed for glaucoma patients whose condition has progressed beyond the capabilities of their local optician practice, offering timely monitoring and specialist interventions.
Provider Type Insights
Based on the provider type, the standalone eye clinics segment led the market with the largest revenue share of 34.8% in 2025. owing to increasing technological advancements in diagnostic and surgical equipment have enabled standalone clinics to offer high-quality, cost-effective, and convenient services. Furthermore, the rising preference for outpatient care and shorter waiting times compared to hospitals supports the growth of these clinics. Urbanization and increasing disposable incomes also empower more people to invest in specialized services. In October 2023, Dr. Agarwal’s Eye Hospitals announced plans to expand its footprint in the market, with plans to invest up to USD 150 million over the next 2–3 years. The company aims to nearly double its network to 300 eye hospitals across India and Africa, focusing on regions such as Maharashtra, Delhi, Uttar Pradesh, and central India. The company is also establishing over 100 primary eye clinics in tier 2 and tier 3 towns to enhance accessibility.
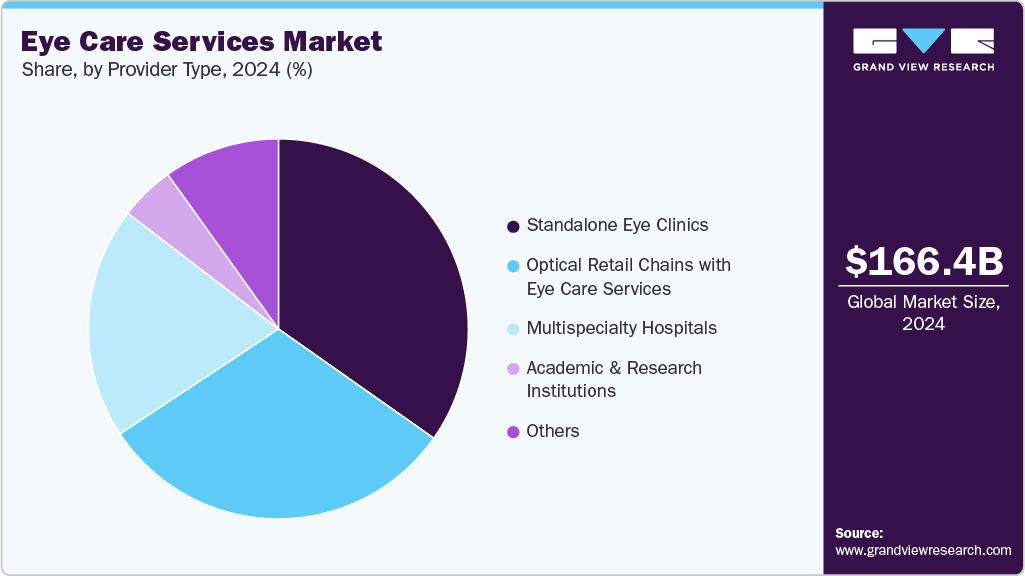 To learn more about this report, Download Free Sample Report
The academic & research institution segment is expected to grow at the fastest CAGR during the forecast period. This is driven by increasing investments in ophthalmic research, and the growing demand for advanced diagnostic and treatment technologies. These institutions play a crucial role in pioneering innovative therapies, such as gene therapy, retinal implants, and minimally invasive surgical techniques, which enhance patient outcomes and expand treatment options. Moreover, government funding, public-private partnerships, and collaborations with pharmaceutical and medical device companies further stimulate academic research growth. For instance, in December 2024, The Advanced Research Projects Agency for Health (ARPA-H) announced a groundbreaking initiative aimed at developing the first-ever complete eye transplantation procedure to restore vision for individuals who are blind or visually impaired. This initiative, known as the Transplantation of Human Eye Allografts (THEA) program, represents a significant investment in medical innovation, with ARPA-H committing up to USD 125 million to support this ambitious project.
Regional Insights
North America dominated the 39.8% market with the largest revenue share of xxx % in 2025, driven by a high prevalence of vision-related disorders, a well-established healthcare infrastructure, widespread insurance coverage, and early adoption of advanced eye care technologies. Technological advancements have also played a pivotal role, with innovations such as LASIK procedures, teleophthalmology, and AI-driven diagnostics enhancing the efficiency and accessibility of eye care. The widespread use of digital devices has led to a rise in digital eye strain and related issues, prompting greater awareness and demand for corrective eyewear and treatments.
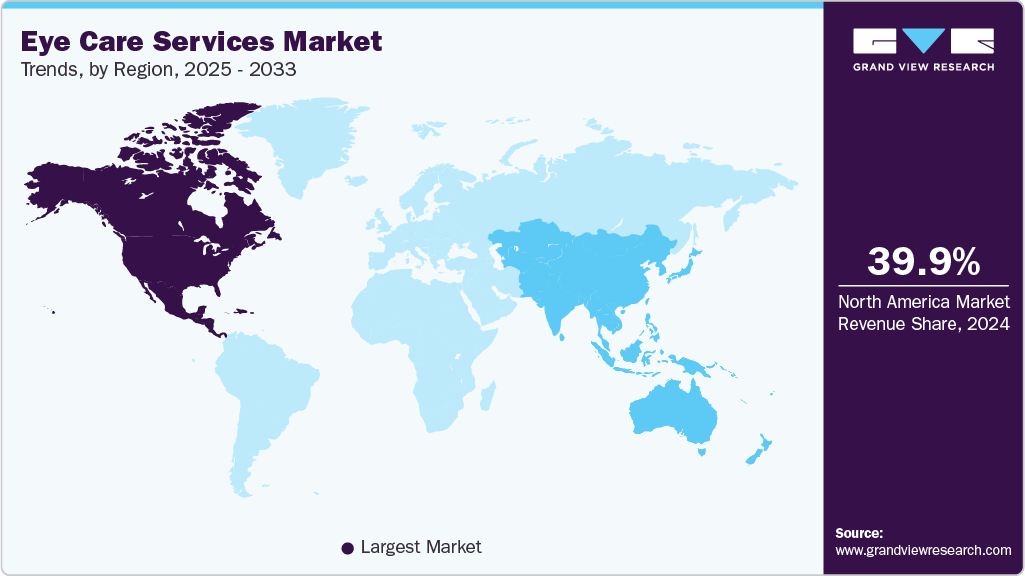 To learn more about this report, Download Free Sample Report
U.S. Eye Care Services Market Trends
The eye care service market in the U.S. held the largest share in the North America region in 2025. due to a strong emphasis on innovation, and growing strategic alliances & partnerships. In November 2024, Eye Health America (EHA) announced a strategic partnership with Bowden Eye & Associates, marking its 25th collaboration and expanding its presence into Eastern Florida. This partnership enables continuity of cutting-edge specialty eye care services to the Northeast Florida community with the compassion and expertise cultivated over the past 24 years. Moreover, the collaboration underscores EHA's momentum in nurturing meaningful affiliations across Florida, marking its second partnership in the state over the last 12 months. John Swencki, Co-CEO of EHA, emphasized the opportunity to bring innovative, patient-centered care to more communities across the Southeast, highlighting the importance of this partnership in delivering top-tier eye care services throughout the region.
Europe Eye Care Services Market Trends
The eye care services market in Europe is anticipated to grow significantly due to a rapidly aging population, technological innovations in diagnostic & treatment modalities, rising prevalence of vision impairment due to lifestyle changes, increasing awareness of eye health, and improving healthcare accessibility and insurance coverage for vision-related services. Moreover, private clinics are increasingly partnering with public health systems to address surgical backlogs, particularly in cataract surgeries. For instance, as per the report published by The Guardian in June 2024, nearly 60% of cataract surgeries are now performed in England by private providers, up from 24% five years ago. Moreover, in May 2025, EssilorLuxottica, announced its acquisition of Optegra, a prominent European ophthalmology network, in a strategic move to enhance its medical technology portfolio. This acquisition aligns with EssilorLuxottica's broader strategy to transition from a traditional eyewear company to a comprehensive med-tech entity. The integration of Optegra's clinical expertise complements EssilorLuxottica's existing capabilities in smart eyewear, diagnostic tools, and AI-powered health technologies.
The UK eye care services market is expected to grow significantly over the forecast period as the NHS provides free eye exams for certain groups, supporting preventive care. In addition, there is a growing push for digital solutions to reduce strain on the public system, with opticians offering integrated services and e-health tools. Moreover, the launch of the new Optometry First services by NHS Shropshire, Telford and Wrekin in July 2025 is expected to improve access to eye care for residents. By enabling people to get eye care services closer to home, it should reduce pressure on hospitals and help catch eye problems earlier through more convenient optometry consultations. This aims to achieve faster treatment, better outcomes, and overall improved community eye health.
Asia Pacific Eye Care Services Market Trends
The eye care services market in Asia Pacific has been estimated to be the fastest-growing region propelled by large and aging populations in countries such as China, India, and Japan. Increasing disposable income, expanding healthcare access, and a surge in awareness campaigns for vision health are accelerating market growth. Rapid urbanization and digital device overuse are also raising demand for services.
The eye care services market in India is driven by rising awareness, a high burden of cataracts and refractive errors, and a dual model of affordable and premium services. Non-profit organizations such as Aravind Eye Care are leading the way in providing scalable, cost-effective service delivery. Moreover, Centre for Sight has unveiled a compelling new brand campaign featuring fitness icon and endurance athlete Milind Soman. Launched in April 2025, the campaign challenges prevailing perceptions about aging and eye health, urging individuals to prioritize their vision care as they age. The initiative highlights often-overlooked risks such as cataracts, glaucoma, diabetic retinopathy, and gradual vision loss. It underscores the importance of regular eye check-ups, especially after the age of 40, aligning eye health with overall fitness.
Latin America Eye Care Services Market Trends
The eye care services market in Latin America is anticipated to grow significantly over the forecast period, primarily driven by the increasing demand for prescribed products among the elderly population due to the rising prevalence of eye disorders. Major players are enhancing their market presence through collaborations and acquisitions. The market is also influenced by the increasing usage of digital devices, surging demand for prescribed spectacles, and the rising prevalence of vision impairment.
Brazil eye care services market held the largest market share in 2024 due to the public health campaigns educating the population about the importance of regular eye examinations and early detection of eye conditions, leading to increased utilization of eye care services. In May 2024, the "April Brown" campaign known in Brazil as "Abril Marrom" was launched to raise awareness about eye health and preventable vision loss. Initiated in São Paulo, this nationwide initiative has become a cornerstone in promoting eye health across Brazil. The campaign aligned with the International Agency for the Prevention of Blindness's (IAPB) "2030 In Sight" strategy, emphasizing behavioral changes and universal access to eye care services. Through public awareness efforts, the campaign encouraged regular eye examinations, early detection of eye conditions, and advocated for equitable access to eye care services.
Middle East and Africa Eye Care Services Market Trends
The eye care services market in MEA is anticipated to grow significantly during the forecast period driven by the increasing prevalence of Age-related Macular Degeneration (AMD) and amblyopia, especially in the geriatric population, and rising disposable income leading to better access to healthcare services. Government initiatives focusing on health awareness and investment in innovative services, and well-equipped facilities are also significant drivers. In addition, the market benefits from the entry of international brands offering innovative solutions, including contact lenses and prescription glasses, catering to the unique needs of the region.
South Africa eye care services market is expected to grow significantly over the forecast period due to shifting consumer behavior and a growing demand for fashionable eyewear and contact lenses that serve both functional and aesthetic purposes. The rise in screen time has led to increased cases of digital eye strain, prompting demand for products such as light-blocking blue glasses. Moreover, policy initiatives, such as the National Health Insurance Act of 2023, aim to improve access to quality health care services, including eye care, by establishing a National Health Insurance Fund.
Key Eye Care Services Companies Insights
Key players operating in the eye care services market are undertaking various initiatives to strengthen their presence and increase the reach of their products and services. Strategies such as expansion activities and partnerships are key in propelling the market growth.
Key Eye Care Services Companies
The following key companies have been profiled for this study on the eye care services market.
-
Aravind Eye Care System
-
Alcon
-
Asia Pacific Eye Centre
-
Topcon Corporation
-
iCARE HEALTH SOLUTIONS
-
US Eye
-
Pamlico Capital
-
Vision Service Plan
-
Opty (HOBRASIL OPHTHALMOLOGICAL HOSPITALS)
-
Eye Associates of New Mexico
-
Providence Health Care
-
ASG Hospital Pvt. Ltd.
-
Centurion Eye Hospital
-
Al Saudi Hospital
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players e.g., Aravind Eye Care System, Alcon, Topcon Corporation, Vision Service Plan
- Expand service offerings through hospital network expansion, technology integration, partnerships, and advanced ophthalmic service development. Invest in AI-enabled diagnostics, cataract surgery innovation, retinal imaging technologies, and premium ophthalmic solutions. Strengthen patient acquisition through integrated service delivery, insurance partnerships, and digital health platforms while expanding geographic reach in high-growth markets.
- Strong brand recognition, established patient trust, advanced ophthalmic infrastructure, broad service portfolios, and strong market presence across diagnostics, surgery, and vision care. Significant financial resources support technology investments, service expansion, and strategic partnerships. Established provider and payer relationships further strengthen market position.
- High operational costs, capital-intensive technology investments, workforce shortages, and increasing reimbursement pressure can affect profitability. Large organizations may also face slower expansion into underserved markets and limited flexibility in rapidly adapting to localized market opportunities.
Emerging Players, e.g., Asia Pacific Eye Centre, iCARE HEALTH SOLUTIONS, US Eye, Pamlico Capital-backed Platforms
- Focus on regional expansion, specialty ophthalmology services, operational efficiency, and acquisition-led growth. Expand through multi-clinic networks, outpatient surgery centers, tele-ophthalmology, and AI-based screening services. Emphasize patient experience, specialized treatment offerings, and targeted expansion into high-demand local markets.
- Greater operational flexibility, faster decision-making, and the ability to rapidly expand in niche or underserved markets. Strong potential to adopt innovative care models such as digital eye care, retail-based services, and decentralized screening platforms. Ability to target high-growth ophthalmology segments such as retina care, refractive surgery, and outpatient surgical services.
- Limited brand recognition compared to large players, narrower geographic reach, and smaller operational scale. Dependence on external funding, limited bargaining power with suppliers and payers, and resource constraints may restrict large-scale expansion, technology adoption, and long-term competitive positioning.
Recent Developments
-
In May 2025, UCL and Moorfields Eye Hospital launched a new medical technology company, Cascader Limited, aiming to transform the detection and management of eye diseases through AI. This venture is a collaboration between the UCL Institute of Ophthalmology, Moorfields Eye Hospital NHS Foundation Trust, and Topcon Healthcare, combining academic research, clinical expertise, and technological capabilities.
-
In April 2025, VSP Vision, in collaboration with the healthcare innovation hub MATTER, launched the second annual VSP Vision Innovation Challenge, aiming to discover and support groundbreaking solutions that enhance eye care experience. This global competition invites both early-stage and growth-stage startups to present innovations that empower patients, expand access to care, and elevate provider capabilities.
-
In March 2025, HelpMeSee expanded its simulation-based cataract surgery training program in Latin America through new partnerships in Guatemala and Colombia. This initiative aims to address the significant shortage of trained cataract surgeons in the region by providing accessible, high-fidelity surgical training. The training program utilizes a virtual reality Eye Surgery Simulator, modeled after aviation simulation methods, to teach Manual Small Incision Cataract Surgery (MSICS).
-
In June 2024, Sankara Eye Foundation inaugurated the nation's first-of-its-kind Innovation Lab for eye care, with the aim to revolutionize ophthalmic care through advanced research, development, and training, with a particular focus on serving underserved and rural communities across India. The Innovation Lab is dedicated to developing need-based solutions that go beyond existing options, ensuring world-class eye care access for all, including the most remote villages in the country.
Eye Care Services Market Report Scope
Report Attribute
Details
Market size in 2025
USD 179.7 billion
Estimated market size in 2026
USD 194.8 billion
Projected market size by 2033
USD 376.4 billion
Growth rate
CAGR of 9.9% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Service, indication, provider type, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait
Key companies profiled
Aravind Eye Care System, Alcon, Asia Pacific Eye Centre, Topcon Corporation, iCARE HEALTH SOLUTIONS, US Eye, Pamlico Capital, Vision Service Plan.
Customization scope
Free report customization (equivalent to up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Eye Care Services Market Report SegmentationThis report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global eye care services market report based on service type, indication, provider type, and regions:
 To learn more about this report, Download Free Sample Report
-
Service Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Vision Testing & Eye Exams
-
Surgical Interventions
-
Cataract Surgery
-
Refractive Surgery
-
Glaucoma Surgery
-
Retinal Surgery
-
Corneal Surgery
-
Others
-
-
Primary care services
-
Others
-
-
Indication Outlook (Revenue, USD Million, 2021 - 2033)
-
Refractive Errors
-
Cataracts
-
Glaucoma
-
Age-related Macular Degeneration (AMD)
-
Diabetic Retinopathy
-
Dry Eye Syndrome
-
Others
-
-
Provider Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Standalone Eye Clinics
-
Multispecialty Hospitals
-
Optical Retail Chains with Eye Care Services
-
Academic & Research Institutions
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
U.K
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The eye care service market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each eye care service segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment
Revenue capture definition
By ServiceType
Vision Testing & Eye Exams
This segment includes routine eye examinations and diagnostic vision assessments used to evaluate visual acuity, detect refractive errors, and identify early-stage eye diseases. These services form the foundation of preventive eye care and are widely offered across clinics, hospitals, and optical centers.
Surgical Interventions
This segment covers medical procedures performed to treat moderate to severe ophthalmic conditions requiring surgical correction or intervention. Surgical services represent a high-value segment driven by growing demand for advanced ophthalmic treatment.
Others
Includes retina treatments, glaucoma procedures, LASIK, corneal treatments, tele-ophthalmology, and other specialized services.
Primary Care Services
This segment includes basic eye care services focused on early diagnosis, preventive screening, initial treatment, and referral support for common vision and eye health issues. These services are typically delivered through primary eye care centers and outpatient clinics.
By Indication
Refractive Errors
Includes services for diagnosing and correcting vision disorders such as myopia, hyperopia, astigmatism, and presbyopia.
Cataracts
Includes diagnosis, monitoring, and surgical treatment services for cataract-related vision impairment.
Glaucoma
Covers services for early detection, diagnosis, monitoring, and treatment of glaucoma.
Age-related Macular Degeneration (AMD)
Includes diagnostic and treatment services for AMD, a chronic retinal disease causing central vision loss.
Diabetic Retinopathy
Includes retinal screening, diagnosis, and treatment services for diabetes-related retinal damage.
Dry Eye Syndrome
Covers diagnostic and treatment services for dry eye disease caused by tear instability or reduced tear production.
Others
Includes services related to retinal disorders, corneal diseases, infections, pediatric vision disorders, and other eye conditions.
By Provider type
Standalone Eye Clinics
Includes specialized independent clinics focused exclusively on eye care consultations, diagnostics, and treatment services.
Multispecialty Hospitals
Includes hospitals offering ophthalmology services as part of broader healthcare delivery systems.
Optical Retail Chains with Eye Care Services
Includes optical retailers providing integrated services such as eye exams, eyewear solutions, and vision consultations.
Academic & Research Institutions
Includes teaching hospitals and research centers involved in advanced eye care, innovation, and clinical studies.
Others
Includes community eye care centers, mobile eye care units, and tele-ophthalmology providers.
Estimation Model
Model Details
This research methodology outlines the process for estimating the size of the global eye care services market from 2021 to 2033. The study covers key service segments, including vision testing & eye exams, surgical interventions, cataract surgery, primary care services, and other specialized ophthalmic services across major geographic regions, including North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa.
The objective is to develop a robust, defensible market estimate through a combination of bottom-up and top-down approaches, supported by primary industry validation.
A triangulated market sizing approach was used, combining:
-
Bottom-Up Analysis from patient volumes, ophthalmic procedures performed, eye clinic and hospital revenues, average treatment costs, and service utilization rates.
-
Top-Down Checks using healthcare expenditure, prevalence of vision disorders, aging population trends, diabetes burden, ophthalmologist availability, blindness prevalence, and healthcare infrastructure data.
-
Primary Research with eye hospitals, ophthalmology clinics, optical retail chains, ambulatory surgical centers, ophthalmologists, optometrists, healthcare administrators, insurers, and industry experts.
Step-By-Step Market Estimation Process
-
Eye Care Service Utilization Model
This model estimates the number of patients receiving eye care services and the associated annual spending.
Step 1: Country-level data for eye care service utilization, patient populations, prevalence of refractive errors, cataracts, glaucoma, diabetic retinopathy, AMD, and healthcare infrastructure for 2021–2025 were collected from government health agencies, ophthalmology associations, WHO databases, healthcare organizations, and public health sources.
Step 2: Eye care service utilization rates were applied to estimate the percentage of eligible patients receiving eye care services annually. Utilization rates were derived from healthcare surveys, ophthalmology registries, insurance claims databases, hospital records, and primary interviews.
Step 3: Average annual spending per eye care patient was estimated using consultation fees, diagnostic costs, procedure charges, surgical costs, reimbursement rates, provider billing data, and facility interviews.
Step 4: Market size was calculated by multiplying:
-
Number of Eye Care Patients × Average Annual Spending per Patient
Step 5: Calculations were performed at the country level and subsequently aggregated to regional and global levels.
Step 6: Historical and forecast growth rates were incorporated based on aging demographics, increasing vision impairment prevalence, rising diabetes burden, growing screen exposure, technological advancements, and expansion of organized eye care infrastructure
-
Eye Care Facility Revenue Extrapolation Model
This model estimates market size using revenues generated by eye care service providers.
Step 1: The number of active eye hospitals, standalone eye clinics, ophthalmology centers, ambulatory surgical centers, and optical retail chains with eye care services by country was identified through healthcare registries, company disclosures, industry databases, and market intelligence sources.
Step 2: Average annual revenue per eye care facility was estimated using financial reports, industry benchmarks, facility interviews, reimbursement data, and proprietary databases.
Step 3: Facility revenues were adjusted for regional differences in service mix, consultation volumes, procedure complexity, reimbursement structures, treatment pricing, and healthcare spending.
Step 4: Country-level market size was calculated by multiplying:
-
Number of Eye Care Facilities × Adjusted Average Annual Revenue per Facility
Step 5: Regional and global market values were generated through aggregation of country-level estimates.
Step 6: Annual adjustments were applied to account for expansion of eye care chains, adoption of AI-based diagnostics, tele-ophthalmology growth, new center openings, reimbursement changes, and investments in ophthalmic infrastructure.
-
Procedure Volume and Treatment Cost Model
This model estimates market size based on the volume of eye care services delivered and average treatment costs across service categories.
Step 1: Service volume data was collected from eye hospitals, specialty clinics, ambulatory surgical centers, healthcare databases, industry publications, and ophthalmology associations.
Step 2: Services were categorized into:
-
Vision Testing & Eye Exams
-
Surgical Interventions
-
Cataract Surgery
-
Primary Care Services
-
Other Eye Care Services
Step 3: Average treatment costs and procedure pricing were established using provider pricing data, reimbursement schedules, healthcare claims databases, and expert interviews.
Step 4: Revenue generated by each service category was calculated by multiplying:
-
Number of Procedures / Consultations × Average Cost per Procedure / Consultation
Step 5: Category-level revenues were aggregated to determine country, regional, and global market sizes.
Step 6: Forecast assumptions incorporated rising awareness of preventive eye care, increasing cataract surgery volumes, expansion of AI-based screening, growing demand for premium ophthalmic services, tele-ophthalmology adoption, and favorable healthcare investments.
Market Validation and Forecasting
The estimates derived from the eye care service utilization model, eye care facility revenue extrapolation model, and procedure volume and treatment cost model were cross validated through data triangulation. Findings were further verified through primary interviews with ophthalmologists, eye care service providers, hospital administrators, optical retail chains, healthcare consultants, payers, and industry experts.
Final market forecasts were developed by evaluating demographic trends, healthcare expenditure growth, vision disorder prevalence, ophthalmology workforce availability, reimbursement environments, patient awareness, and technological advancements shaping the global eye care services market.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Procedure Volume Analysis
Detailed assessment of major ophthalmic procedures including cataract surgeries, refractive surgeries (LASIK/SMILE), retina treatments, glaucoma procedures, diabetic retinopathy screenings, and routine vision examinations across major geographies.
Supports demand estimation, capacity planning, patient flow analysis, revenue forecasting, and long-term service expansion opportunities.
Technology & Innovation Analysis
Assessment of emerging ophthalmic technologies, including AI-based diagnostics, retinal imaging systems, tele-ophthalmology platforms, robotic-assisted eye surgery, premium intraocular lenses (IOLs), and digital vision screening tools.
Helps identify future growth drivers, innovation hotspots, technology adoption trends, and opportunities for competitive differentiation.
Patient Demographics & Disease Burden Analysis
Detailed study of patient population by age group, disease indication, vision impairment prevalence, diabetes burden, and aging-related ophthalmic disorders across regions.
Enables demand forecasting, service prioritization, patient segmentation, and long-term market opportunity assessment.
Frequently Asked Questions About This Report
The surgical interventions segment led with a 45.8% revenue share in 2025, and primary care services is the fastest-growing segment.
The global eye care service market size was estimated at USD 179.7 billion in 2025 and is projected to grow from USD 194.8 billion in 2026.
The global eye care services market is expected to grow at a compound annual growth rate of 9.9% from 2026 to 2033 to reach USD 376.4 billion by 2033.
Some key players operating in the eye care services market include Aravind Eye Care System, Alcon, Asia Pacific Eye Centre, Topcon Corporation, iCARE HEALTH SOLUTIONS, US Eye, Pamlico Capital, Vision Service Plan, Opty (HOBRASIL OPHTHALMOLOGICAL HOSPITALS), Eye Associates of New Mexico, Providence Health Care, ASG Hospital Pvt. Ltd., Centurion Eye Hospital, Al Saudi Hospital
The market growth is attributed to the increasing number of individuals experiencing vision-related issues, a quickly aging population, advancements in technology, and heightened awareness regarding eye care.
The refractive errors (myopia, hyperopia, astigmatism, presbyopia) segment led with a 39.0% revenue share in 2025, and glaucoma is the fastest-growing segment.
North America dominated with a 39.8% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


