
- Home
- »
- Medical Devices
- »
-
Optical Coherence Tomography Market Size Report, 2033GVR Report cover

Optical Coherence Tomography Market (2026 - 2033)
Size, Share & Trends Analysis Report By Technology (Time Domain OCT, Frequency Domain OCT), By Application (Ophthalmology, Oncology, Cardiovascular, Dermatology), By Type, By Region, And Segment Forecasts
Market Size, 2025
$2.5BMarket Estimate, 2026
$2.9BMarket Forecast, 2033
$8.5BCAGR, 2026–2033
16.5%Optical Coherence Tomography Market Summary
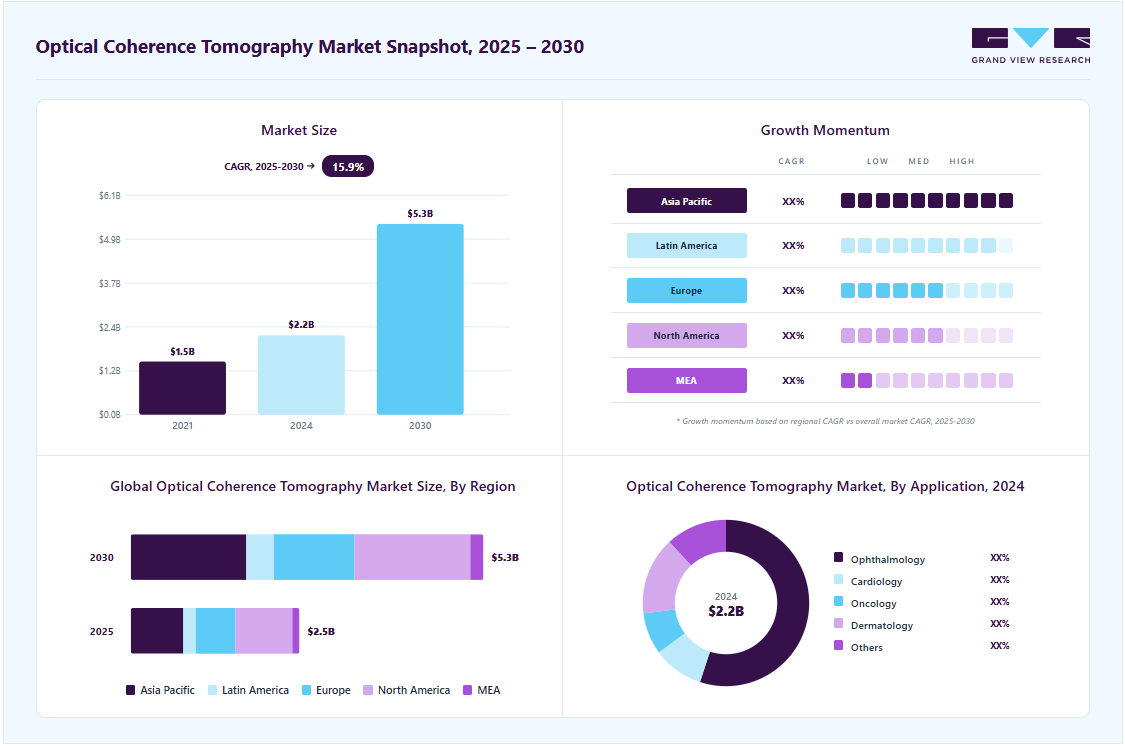
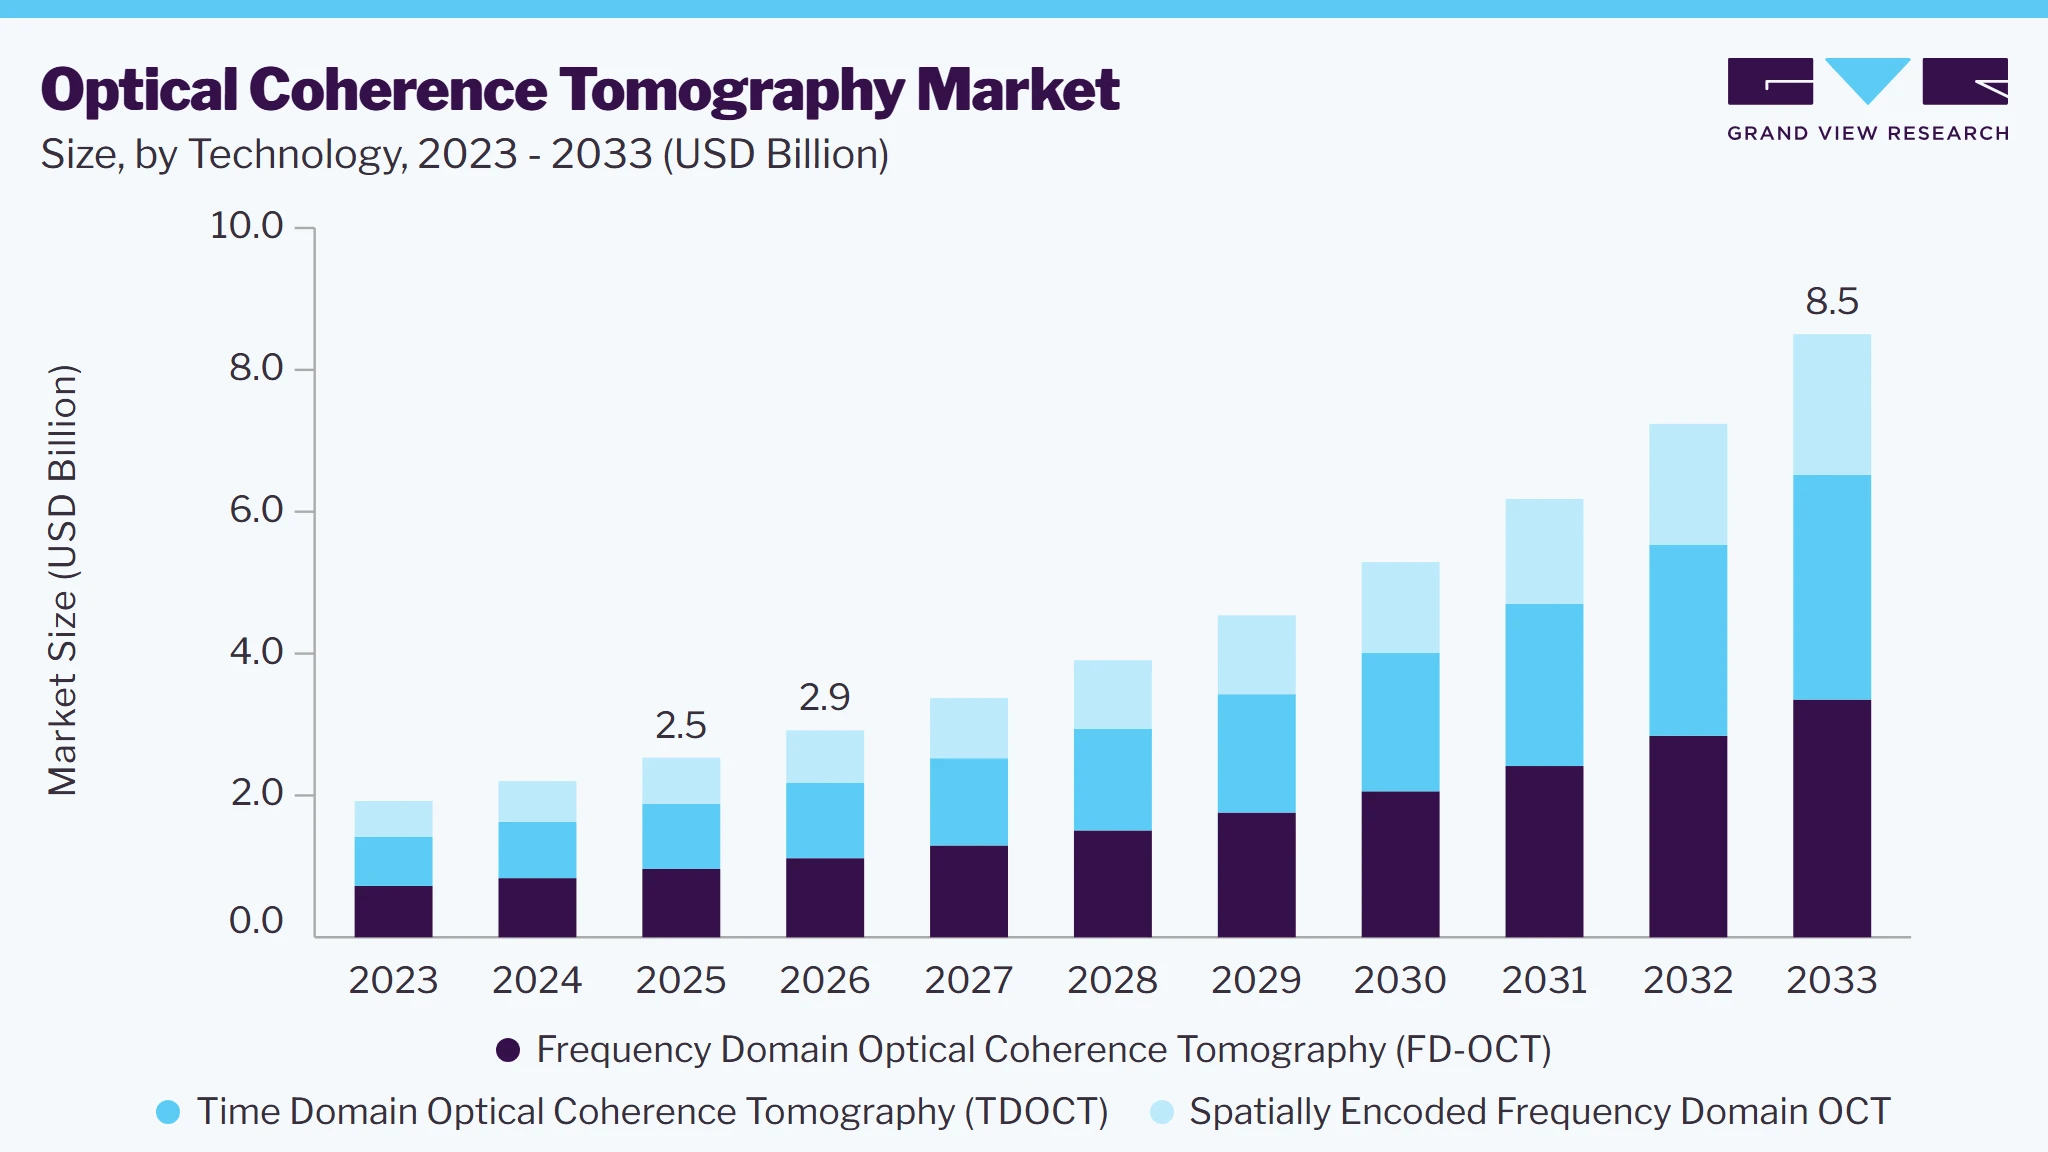
The optical coherence tomography market size was valued at USD 2.5 billion in 2025 and is projected to grow from USD 2.9 billion in 2026 to USD 8.5 billion by 2033, at a CAGR of 16.5% from 2026 to 2033. North America market dominated, with a revenue share of 33.8% in 2025. The continuous innovation and development of newer technologies, higher demand from new biomedical application areas such as drug delivery, growing demand for early diagnosis of diseases, and rising prevalence of eye disorders, are expected to drive the industry growth.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By technology: Frequency domain optical coherence tomography (FD-OCT) segment led the market with the largest revenue share of 38.0% in 2025.
- By type: Handheld segment led the market with the largest revenue share of 47.2% in 2025.
- By application: Ophthalmology segment led the market with the largest revenue share of 53.7% in 2025.
Regional Highlights
- Largest regional market: North America (33.8% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 2.5 Billion
- Estimated market size in 2026: USD 2.9 Billion
- Projected market size by 2033: USD 8.5 Billion
- CAGR (2026-2033): 16.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
According to Canadian Health Measures Survey (2021-2019), 2.6% of children aged between 6 to 19 and 1.4% of adults aged between 40 to 79 have a visual impairment that cannot be corrected. Several organizations, such as the canadian council of blind (CCB), are working towards it, with the mission of improving the quality of life of visually impaired people.
 To learn more about this report, Download Free Sample Report
Optical coherence tomography (OCT) uses light for the cross-sectional imaging of the tissue structure on the micron scale, in situ, and in real time. It is a non-invasive imaging technique, which is used to perform optical biopsies. It is used in areas where traditional imaging techniques cannot be used. OCT is based on fiber optics and can be integrated with instruments, such as endoscopes, catheters, surgical probes, and laparoscopes, which enable imaging of the body. Furthermore, OCT is a portable and compact device. All these factors are expected to drive the industry’s growth during the forecast years.
OCT is useful in the diagnosis of some major health disorders, such as cardiovascular diseases, non-melanoma skin cancer, prostate cancer, and age-related macular disease. This requires the need for non-invasive and in vivo imaging technology to monitor and diagnose the disease and its overlying condition. Continuous development of newer technologies and high demand for OCT imaging from developing countries are expected to drive industry growth.
The increasing prevalence of eye diseases is projected to fuel market growth during the forecast period. According to the World Health Organization (WHO), almost 2.3 billion people were suffering from vision loss in 2019 due to unaddressed medical conditions, such as cataracts, refractive errors, corneal opacities, glaucoma, trachoma, and diabetic retinopathy. The WHO also estimates that over 2.2 billion individuals worldwide suffer from a near- or distance-vision disability brought on by eye conditions, such as cataracts, diabetic retinopathy, refractive error, glaucoma, and other conditions. Out of which, approximately 1 billion cases could have been prevented or are yet to be addressed. The demand for cutting-edge disease diagnostic tools like OCT systems is growing as a result of the rise in these eye ailments.
Increased R&D efforts, the development of many unique products, and innovative hybridization technologies characterize the industry. One of the top OCT companies, Novacam Technologies Inc., creates and manufactures highly accurate advanced 3D metrology systems for use in biomedicine and other fields. The company’s devices use non-contact fiber-based scanning probes and low-coherence interferometry as their foundation. By collaborating with OEMs and system integrators that aim to use the vendor's cutting-edge LCI-based components in standard assemblies for vertical sectors, Novacam is actively looking for new methods to strengthen its market position.
Market Dynamics
The optical coherence tomography market is witnessing significant growth owing to the widespread acceptance of high-resolution and non-invasive imaging modalities by health care practitioners for the early diagnosis, treatment planning, and monitoring of ophthalmic, cardiovascular, oncological, dermatological, and other diseases. Optical coherence tomography employs low-coherence interferometry in creating high-resolution cross-sectional images of biological tissues to provide real-time visualization of the microstructural changes at micron level resolutions. The optical coherence tomography market consists of three different modalities namely time domain optical coherence tomography (TD-OCT), frequency domain optical coherence tomography (FD-OCT), and spatially encoded frequency domain OCT technologies that are offered on catheter based, Doppler, handheld, and table top instruments. The OCT modality finds widespread use in ophthalmology for retinal and anterior segment imaging, cardiology for intravascular imaging, oncology for tissue characterization, dermatology for skin lesion assessment, and research applications. Rising prevalence of chronic eye diseases, cardiovascular conditions, cancers, and skin diseases, alongside the growing need for non-invasive diagnostics and constant improvements in imaging speed, resolution, AI-supported image analysis, and portable OCT devices is propelling market growth. In addition, the growing healthcare infrastructure, increased use of precision medicine, and investments in imaging diagnostics are fueling global optical coherence tomography market adoption.
Increasing prevalence rates of retinal diseases, cardiovascular disorders, cancers, and dermatological disorders are among the key factors that influence the optical coherence tomography market positively. OCT technology finds its application in the identification of diseases at an early stage, tissue characterization, treatment planning, and monitoring of diseases in a non-invasive manner by avoiding exposure of patients to any form of ionizing radiation. The use of OCT technology in the diagnosis of eye diseases such as age-related macular degeneration, diabetic retinopathy, glaucoma, and retinal vascular diseases as well as intravascular OCT in coronary interventions is likely to support the optical coherence tomography market growth.
High capital investment requirements, equipment maintenance costs, and the need for specialized operator training remain major factors hindering the growth of optical coherence tomography market. Advanced OCT platforms incorporating angiography, Doppler imaging, or intravascular imaging capabilities often require substantial investments that may limit adoption among smaller healthcare facilities and emerging markets. In addition, reimbursement variability across clinical applications and limited availability of trained specialists capable of interpreting OCT images may further restrict market expansion.
Market Concentration & Characteristics
The optical coherence tomography (OCT) industry is moderately concentrated, with key players like Carl Zeiss Meditec, Topcon Corporation, and Heidelberg Engineering dominating the market. Industry characteristics include rapid technological advancements, such as AI integration and portable devices, fostering competition and innovation. The market benefits from growing applications across ophthalmology, cardiology, and oncology. Barriers to entry include high R&D costs and stringent regulatory requirements. Consolidation is evident, with mergers and acquisitions enhancing product portfolios and global reach.
The degree of innovation in the optical coherence tomography industry is exemplified by NIDEK CO., LTD.’s launch of the RS-1 Glauvas Optical Coherence Tomography in June 2024. This advanced system features a 250kHz scan speed, delivering high-quality imaging for wide and deep areas, enhanced operability, and deep learning-based analytics. Designed for glaucoma and retinal vascular disease diagnostics, it streamlines workflows while ensuring diagnostic confidence in high-volume practices. Its rapid imaging capability minimizes capture time and reduces fixation errors, resulting in clearer images and improved patient comfort, demonstrating significant advancements in OCT technology for efficient and accurate clinical applications.
 To learn more about this report, Download Free Sample Report
Regulations significantly influence the OCT industry by ensuring safety, efficacy, and quality standards for devices. Regulatory bodies like the FDA and CE authorities mandate compliance with strict guidelines for device approval, including clinical trials and performance validation. These regulations impact innovation timelines and market entry, requiring manufacturers to invest heavily in research and documentation. Additionally, evolving regulations, such as those focusing on data security and interoperability, shape product development. While stringent regulations can delay commercialization, they also enhance trust among healthcare providers and patients, ensuring OCT devices deliver accurate, reliable, and safe diagnostic solutions.
Mergers and acquisitions (M&A) in the optical coherence tomography (OCT) industry have been growing as companies seek to expand their technological capabilities, product portfolios, and market presence. In July 2024, EssilorLuxottica, owner of brands like Ray-Ban and Oakley, is acquiring an 80% stake in Heidelberg Engineering, a leader in ophthalmic diagnostics. Heidelberg specializes in OCT, confocal microscopy, and scanning lasers, with equipment widely used in diagnosing conditions such as AMD and glaucoma. The move expands EssilorLuxottica into photonics technology. Such strategic moves enable companies to improve operational efficiency and accelerate innovation, further driving competition and growth within the industry.
In the optical coherence tomography (OCT) industry, substitute products include diagnostic imaging technologies like fundus photography, ultrasound biomicroscopy (UBM), fluorescein angiography, and scanning laser ophthalmoscopy (SLO). These alternatives cater to similar diagnostic needs, such as retinal and corneal imaging, but differ in precision and application scope. UBM is effective for anterior segment imaging, while fundus photography is less detailed but widely used for retinal examinations. However, OCT's superior resolution, non-invasiveness, and ability to provide cross-sectional imaging give it a distinct advantage. Continued innovation in OCT, such as AI integration and faster scan speeds, further reduces the competitiveness of substitutes.
Regional expansion in the optical coherence tomography (OCT) industry is gaining momentum as healthcare systems integrate advanced imaging technologies to improve patient care worldwide. Notably, NHS England's initiative to roll out OCT devices in hospitals across the country by November 2024 aims to enhance diabetic retinopathy screenings. This effort supports the NHS Diabetic Eye Screening Programme, which registers around 4 million patients and conducts digital screenings every two years for 3.3 million people. The program is expected to reach 60,000 high-risk individuals showing early signs of eye disease, marking a significant expansion of OCT access for improved diagnosis and outcomes.
Analyst Perspective
The optical coherence tomography market is estimated to grow significantly during forecast period due to rising demand for precision diagnostics, minimally invasive imaging, and artificial intelligence-driven healthcare. The constant innovation in imaging speed, penetration depth, image resolution, and multimodal imaging capabilities is expanding OCT applications beyond ophthalmology into cardiology, oncology, dermatology, and translational research. Manufacturers are increasingly incorporating AI-enabled image analysis, cloud-based image management, OCT angiography, swept-source technology, and portable imaging platforms to improve diagnostic accuracy and clinical workflow efficiency. Growing investments in early disease detection, personalized medicine, and outpatient diagnostic services are expected to create significant opportunities for OCT manufacturers. As healthcare systems continue to emphasize non-invasive diagnostics and precision imaging, demand for advanced OCT technologies is expected to increase steadily worldwide.
Technology Insights
Based on technology, the frequency domain optical coherence tomography (FD-OCT) segment led the market with the largest revenue share of 38.0% in 2025. FD-OCT systems are mainly based on the measurement of the interference spectrum, hence also called spectral-domain OCT (SD-OCT). The SD-OCT uses interferometric signals to speed up imaging speed up to 50 times, thus providing a greater number of images per unit area and boosting the industry penetration during the projection years.
The time-domain OCT (TD-OCT) segment is expected to grow at the fastest CAGR of 16.40% during the forecast period. TD-OCT is the traditional technique used to examine the retinal screen of the eye. It examines the retinal thickness by measuring the distance between the internal limiting membrane and the highest hyper-reflective band. It is used in the diagnosis of several retinal conditions, such as the macular hole, macular pucker, vitreomacular traction, and macular edema.
SD-OCT, also known as spatial encoded frequency domain OCT, is anticipated to expand rapidly during the forecast period. By examining the spectrum of the interference fringe pattern, SD-OCT, a type of interferometric technology, can provide depth-resolved tissue structural data that is encoded in the size and deferral of the backscattered light. In addition, the SD-OCT technology enables ultra-high-speed OCT imaging in contrast to Temporal Domain (TD) OCT. SD-OCT is crucial in applications related to biological imaging because of its quick operation and outstanding sensitivity.
Type Insights
Based on type, the handheld segment led the market with the largest revenue share of 47.2% in 2025. Handheld OCT devices are a combination of microelectromechanical systems (MEMS) with 3D imaging to help in the early detection of multiple eye disorders like diabetic retinopathy, macular degeneration, and glaucoma.
The Doppler OCT segment is anticipated to grow at the fastest CAGR of 17.3% during the forecast period on account of the wide usage in the areas of ophthalmology, dermatology, gastrointestinal endoscopy & cardiology; the ability to image dynamic flow parameters, such as pulsatility; and reduced time of processing. Tabletop OCT devices are the traditional type of non-invasive devices used to scan the retina to check for any kind of eye disorders or the occurrence of certain symptoms. Tabletop OCTs require proper infrastructure and are non-portable.
Application Insights
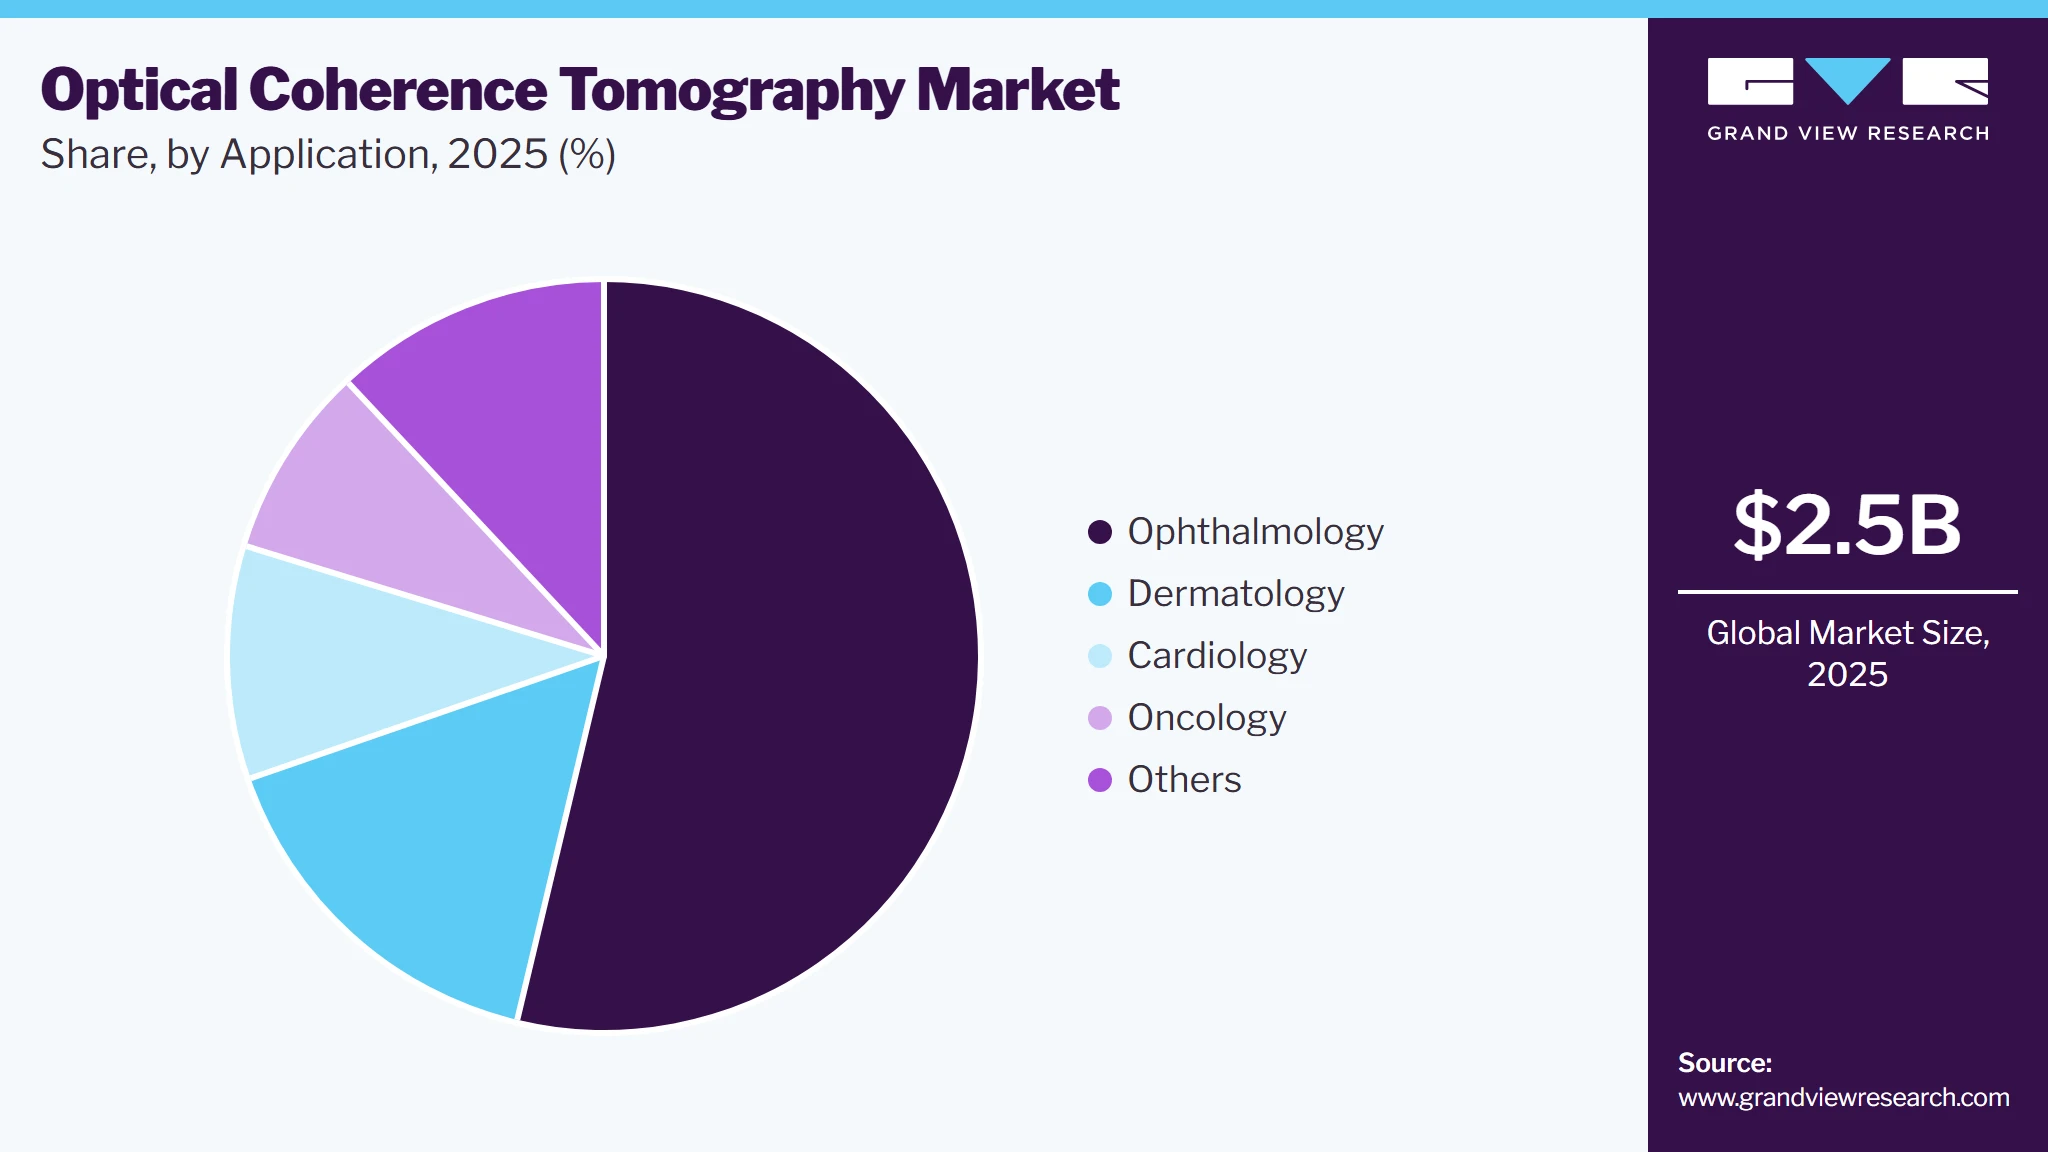
Based on application, the ophthalmology segment led the market with the largest revenue share of 53.7% in 2025. The segment is projected to witness rapid growth in the future due to the increasing incidences of choroidal and retinal disorders, which, in turn, lead to increased product adoption by ophthalmologists for imaging and diagnosing purposes. Furthermore, the rising importance and awareness about early disease diagnosis and better treatment options with OCT devices are expected to boost growth.
 To learn more about this report, Download Free Sample Report
The dermatology segment is estimated to register the fastest CAGR of 21.4% during the forecast period owing to the rising prevalence of skin disorders and the use of OCT to diagnose conditions, such as solid skin tumors. OCT has also been found to be useful in diagnosing early-stage cancer as it provides a real-time image of what lies beneath the skin in vivo.
The oncology segment is also predicted to grow at a CAGR of 19.4% over the forecast period. Cancer ranks as a primary cause of mortality and a significant barrier to growing life expectancy. The WHO estimated that around 19.3 million new cases of cancer and almost 10 million cancer-related deaths occurred in 2020 (which is 1 in every 6 deaths). Europe accounts for 22.8% of all cancer cases and 19.6% of all cancer deaths. The Americans come in second with 21.0% incidence and 14.2% worldwide mortality. Every cancer type requires an appropriate diagnosis and an accurate treatment schedule. The growing product demand can be attributed to the utilization of imaging techniques for screening cancer.
Regional Insights
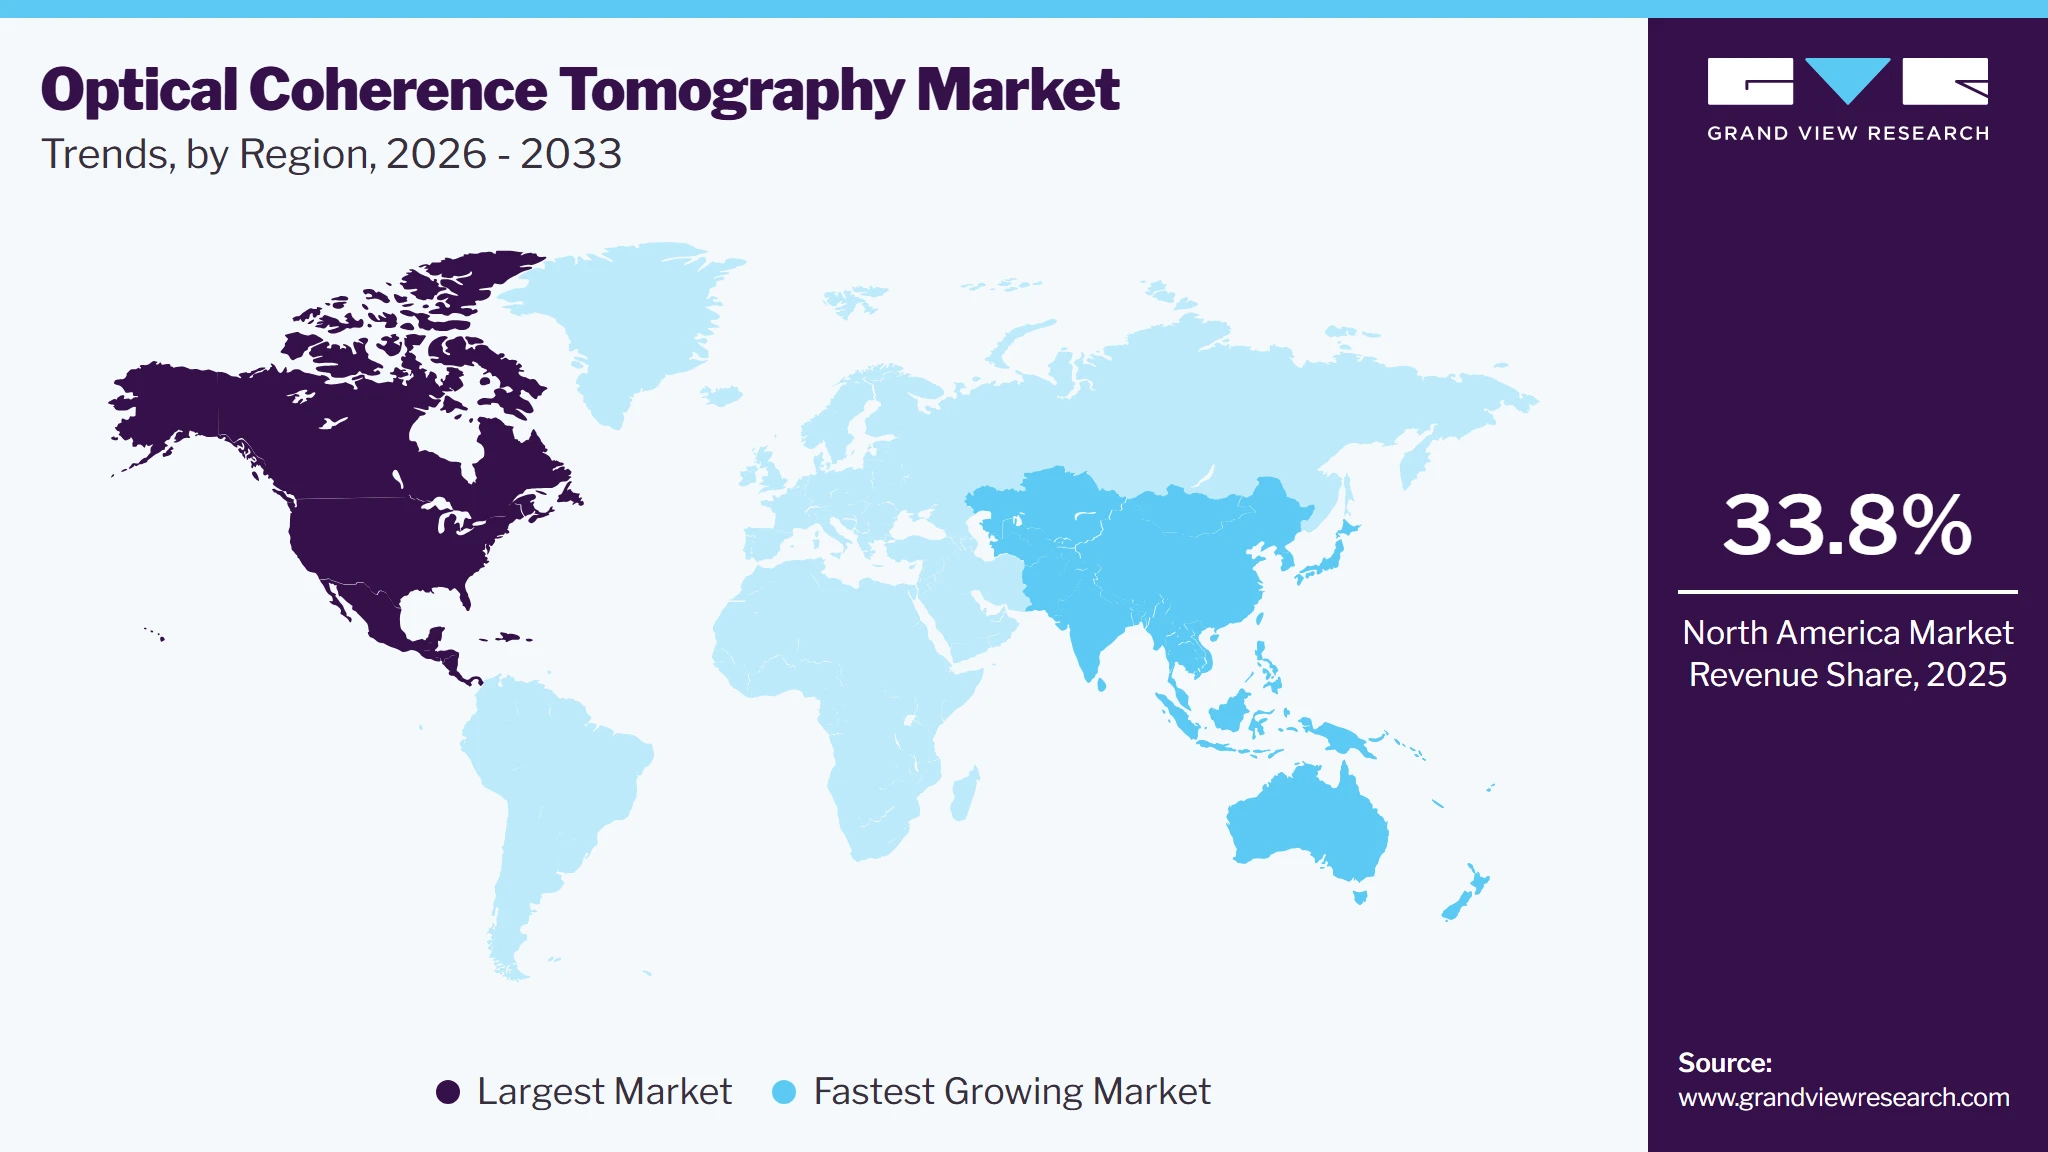
North America dominated the optical coherence tomography market with the largest revenue share of 33.8% in 2025. The growing geriatric population, increasing approvals, R&D investments, inclination towards adopting newer products in the U.S., expansion of hospitals, and the presence of well-established healthcare infrastructure are boosting the growth of the region.
 To learn more about this report, Download Free Sample Report
U.S. Optical Coherence Tomography Market Trends
The optical coherence tomography market in the U.S. held the largest share in the North America region in 2025. For instance, in May 2025, ZEISS announced advancements to its OCT technology to enhance support for the growing demand for data-driven patient care. The ZEISS Medical Ecosystem strengthens the CIRRUS 6000, integrating the largest OCT reference database in the U.S. and bolstering its cybersecurity features to provide improved performance and security in clinical environments, ensuring the reliable management and protection of patient data.
Europe Optical Coherence Tomography Market Trends
Europe optical coherence tomography market dominated the global market with 23.5% share in 2024 driven by advanced healthcare infrastructure, increasing prevalence of eye diseases, and rising demand for non-invasive diagnostic tools. The region benefits from strong investments in medical technology and widespread adoption of OCT systems in clinical settings.
The UK optical coherence tomography market is experiencing steady growth. In November 2024, NHS England (NHSE) began the phased integration of advanced OCT scans into the post-DES treatment and monitoring pathway. This move is expected to save tens of thousands of hospital appointments annually.
The optical coherence tomography (OCT) market in Franceis expanding, driven by key advancements. The CALIPSO trial demonstrated that OCT could guide percutaneous coronary intervention (PCI) for moderate to severe calcified lesions, comparing OCT-guided PCI with angiography-based methods. Additionally, the National Eye Institute hosted a scientific symposium in March 2024, highlighting the significant impact of OCT in vision health and research. These developments further support the growing adoption of OCT technology in clinical settings, contributing to market growth in France.
The German optical coherence tomography market is primarily driven by a multi-center study involving 2,500 patients, exploring OCT’s use in percutaneous coronary intervention (PCI). The study revealed that OCT delivers high-resolution images of heart vessel walls, aiding in the detection of blockages and damage, thus advancing market growth.
Asia Pacific Optical Coherence Tomography Market Trends
The Asia Pacific region is anticipated to see strong growth in the optical coherence tomography market during the forecast period. The rapid growth of this region can be attributed to various factors, such as the rising prevalence of chronic disorders, rising adoption of advanced technologies, presence of a large geriatric population pool, increasing reimbursement for surgical procedures, and high preference for minimally invasive procedures over traditional methods. Furthermore, the increasing awareness levels regarding eye disorders are also anticipated to propel the market growth in this region during the forecast period. In July 2021, Canon Singapore launched Xephilio OCT-S1, an Innovative-field swept source OCT that can capture images up to 23*20 mm in a single scan.
Theoptical coherence tomography market in Japan is expanding due to increasing adoption of advanced OCT technology in healthcare. This growth is supported by innovations in imaging techniques and a rising demand for early diagnosis of ocular diseases, contributing to enhanced market penetration and improved patient outcomes.
China optical coherence tomography market is expected to grow rapidly, driven by TowardPi's advancements in OCT technology. In 2023, TowardPi launched new features for its OCT devices, such as BMizar, which offers a scanning speed of 400,000 scans per second and a depth of 6 mm. Additionally, the Yalkaid device provides a depth of 14 mm for the anterior segment and 12 mm for the posterior segment, enhancing diagnostic capabilities and supporting the expansion of OCT adoption in the region. These innovations contribute to the market's growth and improve clinical applications.
The optical coherence tomography market in India is experiencing significant growth. In May 2022, Chhattisgarh state introduced its first OCT-based advanced technology, performing 3D OCT-guided coronary angioplasty on three patients at the Advance Cardiac Institute. Additionally, in August 2020, the Department of Cardiology in south Karnataka implemented OCT image-guided angioplasty, aiding doctors in visualizing coronary artery blockages.
Latin America Optical Coherence Tomography Market Trends
The Latin American optical coherence tomography market is growing rapidly, due to increased adoption of advanced diagnostic technologies in ophthalmology and cardiology. Rising awareness of retinal diseases, glaucoma, and heart conditions is driving the demand for OCT devices. Brazil, Mexico, and Argentina are key markets, with healthcare improvements and growing medical infrastructure supporting the market growth. The introduction of cost-effective OCT solutions and government healthcare programs also plays a role in boosting market penetration. As demand for accurate, non-invasive imaging increases, the OCT market is expected to continue its growth trajectory across the region in the coming years.
The optical coherence tomography market in Saudi Arabia is expanding due to increasing healthcare investments, advancements in medical technology, and rising awareness of eye-related diseases such as glaucoma and diabetic retinopathy. The Saudi government’s Vision 2033 plan, which includes enhancing healthcare infrastructure and promoting advanced diagnostic tools, is further driving the adoption of OCT systems.
Key Optical Coherence Tomography Company Insights
The competitive scenario in the optical coherence tomography market is highly competitive, with key players such as Carl Zeiss Meditec AG., Topcon Corporation. and others. Strategic partnerships with local distributors and region-based type variations are some of the initiatives adopted by global players. Major companies are investing in R&D for the development and launch of new products to serve industry demand. In May 2021, Abbott announced the launch of the artificial intelligence OCT coronary imaging platform powered by Ultreon 1.0 Software in Europe. The software detects calcium-based blockages automatically and measures the diameter of the vessel, thereby enhancing the precision of the physician’s decision marking at the time of coronary stenting procedures. In November 2020, Abbott announced the first OCT virtual reality product used for the training of cardiologists. In 2019, TOPCON Canada Inc. announced the launch of 3D Maestro2, which is a spectral domain OCT system with optional OCT angiography.
Key Optical Coherence Tomography Companies:
The following key companies have been profiled for this study on the optical coherence tomography market.
-
Agfa - Gevaert Group
-
Carl Zeiss Meditec AG
-
Heidelberg Engineering GmbH
-
Imalux Corp.
-
Michelson Diagnostics
-
Novacam Technologies, Inc.
-
OPTOPOL Technology S.A.
-
Metall Zug AG
-
Topcon Corporation
-
Thorlabs, Inc
-
Abbott
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Carl Zeiss Meditec AG, Heidelberg Engineering GmbH, Topcon Corporation, Abbott, Agfa-Gevaert Group)
Established companies focus on expanding comprehensive OCT portfolios spanning ophthalmic imaging, intravascular OCT, image analysis software, AI-assisted diagnostics, and integrated digital healthcare platforms. They emphasize continuous product innovation, clinical validation, global commercialization, strategic partnerships, and workflow integration to strengthen market leadership.
Extensive installed base, strong relationships with ophthalmologists, cardiologists, hospitals, and diagnostic centers, broad imaging portfolios, advanced R&D capabilities, and robust global distribution networks. Their comprehensive service infrastructure and continuous software innovation support long-term customer retention.
High dependence on capital equipment purchasing cycles, increasing pricing pressure, and lengthy regulatory approval processes for next-generation imaging technologies. Large organizational structures may reduce agility in addressing emerging niche applications.
Emerging Players (Michelson Diagnostics, Imalux Corp., Novacam Technologies Inc., OPTOPOL Technology S.A., Metall Zug AG, Thorlabs Inc.)
Emerging companies prioritize specialized OCT technologies, portable imaging systems, research-grade platforms, dermatology imaging, and next-generation optical innovations. Many focus on niche clinical applications, technological differentiation, strategic collaborations, and expansion into emerging healthcare markets.
Agile product development, specialized optical engineering expertise, differentiated imaging technologies, and flexibility in addressing emerging clinical and research applications. Strong innovation capabilities enable rapid development of advanced OCT platforms.
Limited global commercial infrastructure, lower brand recognition, smaller installed base, and restricted financial resources compared with multinational imaging companies. Dependence on distributor partnerships and regulatory approvals may slow international expansion.
Recent Developments
-
In February 2024, the Advanced Research Projects Agency for Health (ARPA-H) announced a USD 20 million initiative to develop a compact, affordable optical coherence tomography (OCT) device. This project aims to enhance early detection and intervention for eye diseases, potentially preventing severe visual impairments.
-
In October 2024, Bristol-based health tech start-up Siloton has secured USD 1,066,400 to advance its Akepa OCT chip technology, aimed at combating age-related macular degeneration (AMD), the UK’s leading cause of sight loss. The funding will support commercial roll-out, with plans to capture the first chip-based OCT image by year-end and release a research version in 2025.
-
In May 2024, Palleos Healthcare GmbH, an oncology-focused CRO, and OCT Global SA, operating under OCT Clinical, have merged to create a stronger force in clinical research. The merger, supported by Swiss XlifeSciences AG, marks a significant milestone, fostering collaboration and growth in the clinical research field.
Optical Coherence Tomography Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 2.5 billion
Market size value in 2026
USD 2.9 billion
Revenue forecast in 2033
USD 8.5 billion
Growth rate
CAGR of 16.5% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Technology, type, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; South Korea; Thailand; Australia; Brazil; Argentina; Turkey: Iran; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Agfa - Gevaert Group; Carl Zeiss Meditec AG; Heidelberg Engineering GmbH; Imalux Corp.; Michelson Diagnostics; Novacam Technologies Inc.; OPTOPOL Technology S.A.; Metall Zug AG; Topcon Corporation; Thorlabs Inc.; Abbott
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Optical Coherence Tomography Market Report Segmentation
This report forecasts revenue growth at country levels and provides an analysis on the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the optical coherence tomography market report based on technology, type, application and region:
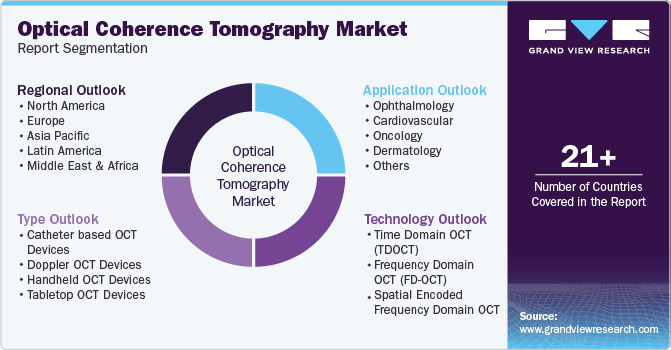 To learn more about this report, Download Free Sample Report
-
Technology Outlook (Revenue, USD Million, 2021 - 2033)
-
Time Domain OCT (TDOCT)
-
Frequency Domain OCT (FD-OCT)
-
Spatial Encoded Frequency Domain OCT
-
Fourier Domain OCT (FDOCT)
-
Others
-
-
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Catheter based OCT Devices
-
Doppler OCT Devices
-
Handheld OCT Devices
-
Tabletop OCT Devices
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Ophthalmology
-
Cardiovascular
-
Oncology
-
Dermatology
-
Others
-
-
Region Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The optical coherence tomography market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each optical coherence tomography segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Technology
Revenue capture definition
Time Domain Optical Coherence
Tomography (TDOCT)
Revenue is generated through commercialization of time-domain OCT systems utilized for high-resolution tissue imaging across ophthalmology and research applications. Although gradually replaced by faster imaging technologies, TD-OCT continues to generate revenue through legacy installed systems, service contracts, and selected clinical applications.
Frequency Domain Optical Coherence
Tomography (FD-OCT)
Revenue is derived from frequency-domain OCT systems, including spectral-domain OCT and swept-source OCT technologies, offering higher imaging speed, improved resolution, and enhanced diagnostic performance. This segment represents the largest contributor to market revenue owing to widespread clinical adoption across ophthalmology and cardiology.
Spatially Encoded
Frequency Domain OCT
Revenue is generated through advanced spatially encoded OCT technologies utilized in specialized research, industrial inspection, and emerging clinical imaging applications requiring rapid volumetric imaging and enhanced acquisition capabilities.
Segment - Type
Revenue capture definition
Catheter based
Revenue is generated through intravascular OCT systems and disposable imaging catheters utilized for coronary artery imaging, plaque characterization, stent optimization, and peripheral vascular interventions. Manufacturers benefit from recurring revenue generated through single-use catheter consumables and procedure-dependent utilization.
Doppler OCT
Revenue is derived from Doppler OCT systems capable of visualizing tissue microstructure and blood flow simultaneously, supporting ophthalmic vascular imaging, retinal perfusion assessment, and research applications.
Handheld
Revenue is generated through portable handheld OCT systems utilized for bedside imaging, pediatric ophthalmology, teleophthalmology, emergency medicine, and community healthcare settings. Increasing adoption of point-of-care diagnostics supports market growth within this segment.
Tabletop
Revenue is captured through stationary tabletop OCT systems utilized in hospitals, ophthalmology clinics, diagnostic imaging centers, and research laboratories for comprehensive retinal, anterior segment, dermatological, and cardiovascular imaging applications.
Segment - Application
Revenue capture definition
Ophthalmology
Revenue is generated through OCT utilization for diagnosis and monitoring of retinal diseases, glaucoma, diabetic retinopathy, age-related macular degeneration, macular edema, and anterior segment disorders. This represents the largest revenue-generating application segment due to widespread adoption in routine ophthalmic practice.
Cardiology
Revenue is derived from intravascular OCT systems utilized during coronary angiography and percutaneous coronary interventions for plaque characterization, lesion assessment, stent optimization, and procedural guidance.
Oncology
Revenue is generated through OCT technologies utilized for tumor visualization, tissue characterization, surgical margin assessment, and translational cancer research supporting precision oncology applications.
Dermatology
Revenue is captured through non-invasive OCT imaging utilized for diagnosis and monitoring of skin cancers, inflammatory skin disorders, wound healing assessment, and cosmetic dermatology applications.
Others
Revenue is derived from utilization across dentistry, gastroenterology, otolaryngology, neurology, biomedical research, and other emerging clinical and scientific applications.
Estimation Model
Step / Key Question
Process Steps
Data Sources
Scope Definition
What is being sized?
1. Define Optical Coherence Tomography Technology Scope
2. Scope Technology, Type, and Application Segments
3. Establish Geographic Coverage (Global/Regional)
4. Align on base year & forecast horizon (2026-2033)
FDA, EMA, PMDA, NMPA
Build the Installed Base
How large is total addressable market?
1. Estimate Installed Base Of OCT Systems Regionally
2. Segment Installed Base by Technology
3. Assess Annual Equipment Installations
4. Forecast Installed Base Growth Based On Disease Prevalence, Healthcare Infrastructure Expansion, Technology Replacement Cycles, and Adoption Of Advanced OCT Platforms
National Eye Registries, WHO, NHS, National Eye Care Screening Programs
Estimate Technology Utilization
What portion of procedures use optical coherence tomography (OCT) devices?
1. Estimate Annual Imaging Procedures by OCT System
2. Evaluate Technology Adoption Across Healthcare Settings and Specialties.
3. Analyze Repeat Treatment Cycles and Product Longevity
4. Validate Through Industry Interviews
Primary interviews, clinical surveys, industry experts
Revenue Conversion
How does volume become revenue?
1. Determine ASPs by OCT technology, system Type and Region
2. Estimate Revenue from Equipment Sales
3. Apply Regional Pricing Variations
4. Cross-validate with Company Revenues and Public Findings
Company Annual Reports, Distributor pricing sheets, procurement data, expert interviews
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Landscape Analysis
Conducted a comprehensive competitive assessment of the global optical coherence tomography market, evaluating leading manufacturers across ophthalmic OCT, intravascular OCT, research imaging systems, dermatology OCT, software platforms, and disposable imaging accessories. The study assessed product portfolios, imaging technologies, AI capabilities, regulatory approvals, pricing strategies, commercialization initiatives, distribution networks, and innovation pipelines.
Enables stakeholders to understand technology leadership, competitive positioning, commercialization strategies, product differentiation, and innovation trends shaping the global OCT market. Supports procurement decisions, supplier benchmarking, partnership evaluation, and investment planning.
Segment by Application Analysis
Conducted a detailed assessment across Time Domain OCT, Frequency Domain OCT, Spatially Encoded Frequency Domain OCT, and across ophthalmology, cardiology, oncology, dermatology, and other applications. The study analyzed imaging procedure volumes, technology adoption, clinical utilization, workflow requirements, reimbursement trends, and forecast demand by segment.
Enables stakeholders to identify high-growth clinical applications, optimize product portfolios, prioritize commercialization strategies, evaluate technology adoption trends, and identify emerging revenue opportunities across precision imaging applications.
Macroeconomic Analysis
Conducted an in-depth assessment of chronic disease prevalence, aging demographics, healthcare expenditure, ophthalmology and cardiology infrastructure, diagnostic imaging investments, reimbursement policies, regulatory developments, AI adoption, and government healthcare initiatives influencing demand for OCT technologies globally.
Enables stakeholders to understand macroeconomic, demographic, regulatory, and healthcare system factors influencing demand within the global optical coherence tomography market. The study supports long-term forecasting, investment prioritization, pricing strategy development, regional expansion planning, manufacturing capacity decisions, and market entry strategies.
Frequently Asked Questions About This Report
The global optical coherence tomography market size was valued at USD 2.5 billion in 2026 and estimated at USD 2.9 billion in 2026.
The global optical coherence tomography market is expected to grow at a CAGR of 16.5% from 2026 to 2033, reaching USD 8.5 billion by 2033.
North America market dominated, with a revenue share of 33.8% in 2025.
Some key players operating in the optical coherence tomography market include Agfa - Gevaert Group; Carl Zeiss Meditec AG; Heidelberg Engineering GmbH; Imalux Corp.; Michelson Diagnostics; Novacam Technologies Inc.; OPTOPOL Technology S.A.; Metall Zug AG; Topcon Corporation; Thorlabs Inc.; Abbott
Constant innovation and development of newer technologies, higher demand for new biomedical applications such as drug delivery, rising demand for early diagnosis of the disease, and rising prevalence of eye disorders are expected to drive the OCT market growth.
Frequency domain optical coherence tomography (FD-OCT) segment led the market with the largest revenue share of 38.0% in 2025.
Handheld segment led the market with the largest revenue share of 47.2% in 2025.
Ophthalmology segment led the market with the largest revenue share of 53.7% in 2025.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


