
- Home
- »
- Distribution & Utilities
- »
-
Fault Current Limiter Market Size & Share Report, 2026-2033GVR Report cover

Fault Current Limiter Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Superconducting, Non-Superconducting), By Voltage Range, By End-use (Power Stations, Oil & Gas), By Region, And Segment Forecasts
Market Size, 2025
$5.8BMarket Estimate, 2026
$6.1BMarket Forecast, 2033
$9.2BCAGR, 2026–2033
6.1%Fault Current Limiter Market Summary
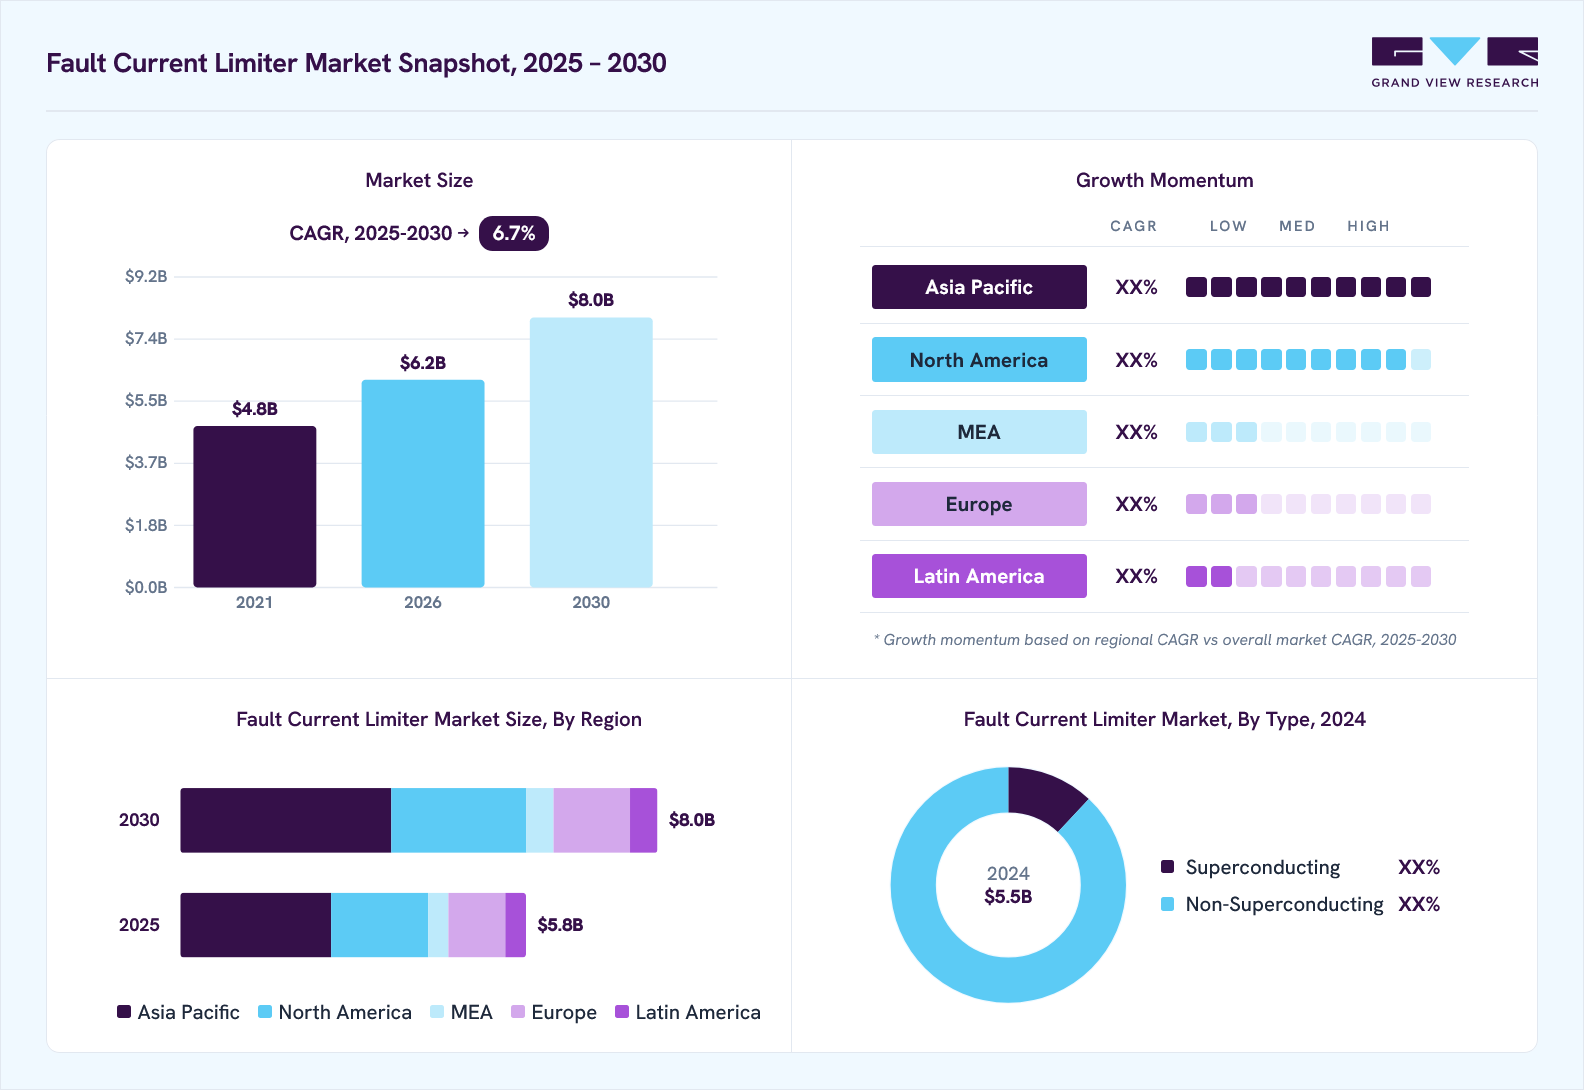
The global fault current limiter market size was valued at USD 5.8 billion in 2025 and is projected to grow from USD 6.1 billion in 2026 to USD 9.2 billion by 2033, at a CAGR of 6.1% from 2026 to 2033. Asia Pacific region dominated the fault current limiter market with the largest revenue share of 38.5% in 2025. The global market is shaped by several key trends, with technological advancements at the forefront.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Non-superconducting segment held the largest market share of 60.2% in 2025.
- By voltage range: Medium voltage range segment held the largest market share of 44.8% in 2025.
- By end-use: Power stations segment held the largest market share of 44.6% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (38.5% revenue share, 2025)
- By country: China held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 5.8 Billion
- Estimated market size in 2026: USD 6.1 Billion
- Projected market size by 2033: USD 9.2 Billion
- CAGR (2026-2033): 6.1%
Prism AI by Grand View Research Free to tryAsk a question about the fault current limiter marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
One significant trend is the growing adoption of superconducting fault current limiters (SFCLs), which use superconducting materials to limit fault currents with high efficiency and minimal energy loss. The rising demand for reliable and resilient power systems drives the Fault Current Limiter (FCL) market. FCLs are critical components that protect electrical networks from damage caused by excessive fault currents, which can result from short circuits or equipment failures. The need for advanced fault current management technologies is increasing as power grids become more complex, particularly with the integration of renewable energy. To learn more about this report, Download Free Sample Report
Growing urbanization and the push toward electrification in sectors such as transportation are placing additional strain on power infrastructure. FCLs play a crucial role by swiftly limiting excessive current during fault conditions, thereby safeguarding equipment and maintaining system stability without disrupting the power supply. Another significant factor boosting market growth is the global trend toward smart grid development and modernization. Ongoing innovations in superconducting and solid-state technologies are making FCLs more compact, energy-efficient, and economically viable, accelerating their adoption in utility, industrial, and commercial applications worldwide.
The rising incidence of electrical faults and blackouts is prompting companies to invest in advanced protection systems like fault current limiters. The growing demand for uninterrupted power supply in critical spaces such as data centers, hospitals, and manufacturing plants is further driving the adoption of FCL. The emergence of microgrids and distributed energy systems also creates a favorable environment for FCLs, as these decentralized setups require robust fault management to ensure efficient and stable operation.
The global shift towards sustainability and renewable energy is influencing the market growth. The integration of renewable energy sources, such as wind and solar, into existing power grids presents unique challenges, including variability in power generation and the need for robust protection systems to manage potential faults. Fault current limiters are critical in mitigating these challenges by ensuring that faults do not cause extensive damage or disrupt power supply. As countries worldwide accelerate their transition to cleaner energy, the demand for fault current limiters is expected to grow, supporting a more stable and resilient energy infrastructure that can accommodate diverse and renewable energy sources.
Market Dynamics
The fault current limiter market is growing as power grids become more interconnected and electricity demand continues to increase. The expansion of renewable energy projects, smart grids, data centers, and industrial facilities is creating a greater need for advanced protection systems that can safely manage higher fault current levels. Utilities are increasingly investing in grid modernization and replacing aging electrical infrastructure, which is supporting the adoption of fault current limiters. Manufacturers are developing compact, high-performance, and superconducting fault current limiters to improve system reliability and reduce maintenance requirements, making these solutions more attractive for modern power networks.
The fault current limiter market is primarily driven by the increasing complexity of modern power grids as renewable energy sources and distributed power generation continue to expand. The addition of solar farms, wind plants, battery storage systems, and new transmission interconnections raises fault current levels, placing greater stress on existing electrical infrastructure. Utilities are increasingly adopting fault current limiters to protect transformers, switchgear, and circuit breakers without the need for costly network upgrades. As investments in smart grids and grid modernization continue to grow, demand for advanced fault current protection solutions is expected to increase steadily
In 2025, SuperGrid Institute validated its resistive superconducting fault current limiter (RSFCL) for high-voltage DC networks, demonstrating its ability to effectively control fault currents in renewable energy applications. The institute stated that the technology was developed to address the growing protection challenges created by the rapid expansion of renewable energy and HVDC transmission systems. This development highlights the increasing need for advanced fault current protection solutions as power grids become more complex.
The market is restrained by the high cost of installation and the challenges of integrating these systems into existing power infrastructure. Advanced technologies such as superconducting fault current limiters require specialized materials, cooling systems, and complex engineering, increasing the overall project cost. In addition, many aging power grids were not designed to accommodate modern fault current limiting devices, making retrofitting both technically challenging and expensive. These factors slow adoption, particularly among utilities and industrial users with limited investment budgets.
The growing deployment of HVDC transmission networks and offshore renewable energy projects presents a major opportunity for the fault current limiter market. As countries invest in long-distance power transmission and connect large-scale offshore wind farms to the grid, the need for advanced fault protection is increasing. Conventional protection equipment often struggles to manage the higher fault currents in these networks, creating demand for advanced fault current limiters. Manufacturers are therefore focusing on developing compact and high-performance solutions that improve grid reliability while reducing the need for costly infrastructure upgrades.
Market Concentration & Characteristics
The global market is characterized by its rapid growth, driven primarily by the increasing demand for enhanced power grid reliability and safety. As power grids expand and become more interconnected, the risk of fault currents due to short circuits and other electrical faults has risen, necessitating the adoption of advanced technologies to protect infrastructure.
The Fault Current Limiter (FCL) market growth is moderate, and the pace of growth is accelerating. The market is characterized by high innovation, particularly in superconducting and solid state FCLs. Companies are investing in R&D to develop compact, energy-efficient, and digitally integrated FCLs suitable for smart grids and EV infrastructure. Breakthroughs in superconducting materials, cryogenic systems, and power electronics continue to push technological boundaries, making innovation a key competitive factor.
 To learn more about this report, Download Free Sample Report
The market is marked by regional diversity, with significant growth observed in areas undergoing rapid industrialization and infrastructure development, such as the Asia-Pacific region. Countries like China, India, and Japan are key markets due to their substantial investments in upgrading power infrastructure and integrating renewable energy sources. Meanwhile, developed regions like North America and Europe are focusing on grid modernization and resilience, driving demand for advanced fault current limiter solutions to maintain grid stability and meet regulatory standards. Overall, the global market is dynamic, shaped by technological innovation, regional developments, and a growing emphasis on reliable and efficient power distribution systems.
Analyst Perspective
The fault current limiter market is growing as utilities and industries invest in stronger and more reliable power networks. The increasing use of renewable energy, smart grids, and HVDC transmission is creating a greater need for advanced fault protection solutions. While high installation costs continue to limit adoption in some regions, ongoing technology improvements are making fault current limiters more efficient and practical. A key trend in the market is the growing development and deployment of superconducting fault current limiters for high-voltage and renewable energy applications. Going forward, demand is expected to increase as countries modernize aging grid infrastructure and focus on improving power system reliability and safety.
Type Insights
Based on type, the non-superconducting segment led the market with the largest revenue share of 60.2% in 2025. This dominance is primarily due to their proven reliability, lower cost, and widespread applicability across various power systems. Unlike superconducting fault current limiters, which require advanced materials and cooling systems, non-superconducting fault current limiters use more conventional technology, making them easier to integrate into existing grid infrastructure without extensive modifications. Their lower initial costs and minimal maintenance requirements make them attractive for utilities and industries looking to enhance their grid protection without significant capital expenditure. These characteristics have led to broad adoption across developed and developing regions, where upgrading and protecting aging infrastructure remains a top priority.
This category includes solid-state, inductive, and resistive FCLs, which are widely adopted due to their cost-effectiveness, technical simplicity, and proven reliability in conventional grid systems. Non-superconducting FCLs are especially preferred in developing regions where budget constraints and limited infrastructure make advanced technologies less feasible. Key trends in this segment include advancements in solid-state FCLs using power electronics and semiconductor-based switching, enabling faster response times and improved integration with smart grid systems. Manufacturers also focus on enhancing thermal management and compactness to cater to the growing needs of urban and industrial power networks.
The Superconducting Fault Current Limiter (SFCL) segment is expected to record the fastest CAGR of 7.5% from 2025 to 2033. As power grids become more complex with the integration of renewable energy sources and the expansion of urban infrastructure, the need for effective fault current management is becoming more critical. Non-superconducting fault current limiters are well-positioned to meet this demand due to their ability to handle a wide range of fault current levels and provide consistent performance in diverse environmental conditions. In addition, their compatibility with existing grid systems and ease of deployment make them a preferred choice for utilities aiming to enhance their network resilience quickly. As a result, the non-superconducting segment is likely to maintain its strong market presence and continue driving market growth.
Voltage Range Insights
Based on voltage range, the medium voltage range segment led the market with the largest revenue share of 44.8% in 2025. This segment's significant presence is primarily driven by the increasing demand for robust protection solutions in high-voltage power systems, which are integral to long-distance power transmission and large-scale industrial applications. As global energy consumption continues to rise, there is a growing need to expand and upgrade high-voltage transmission networks to accommodate greater loads and ensure efficient power distribution. High-voltage fault current limiters are essential in these systems as they protect critical infrastructure from the potentially catastrophic effects of fault currents, helping to maintain system stability and prevent widespread outages.
The medium-voltage segment is expected to record the fastest CAGR, driven by the expanding use of distributed energy resources (DERs) and microgrids and increasing industrial automation. These medium-voltage FCLs are used in secondary distribution networks, commercial facilities, and localized energy systems, where protection from medium-level fault currents is critical. Technological advancements are focused on building compact, modular FCL models with easier installation and integration into existing switchgear systems. As utilities and industries aim to improve operational flexibility and reduce outage risks, medium-voltage FCLs are becoming an essential component of modern power distribution architecture.
End-use Insights
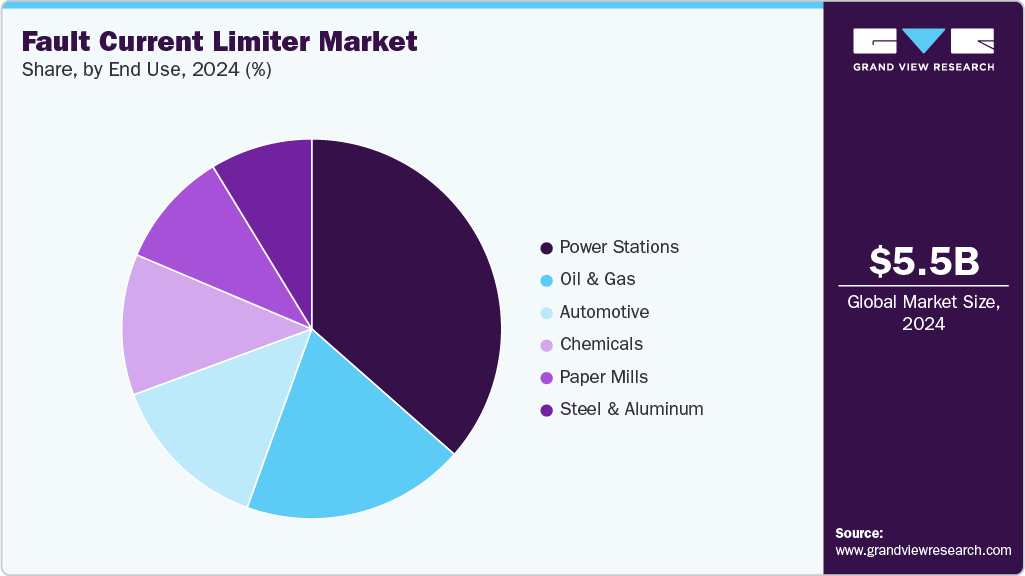
Based on end-use, the power stations segment led the market with the largest revenue share of 44.6% in 2025. This significant share is primarily due to the critical role of fault current limiters in enhancing the safety and reliability of power stations, which are central to generating and distributing electricity. Power stations, whether thermal, nuclear, or renewable, are highly susceptible to faults that can significantly damage equipment, cause extensive downtime, and lead to substantial financial losses. By integrating fault current limiters, power stations can protect their electrical infrastructure from the damaging effects of excessive fault currents, maintaining continuous operation and ensuring a stable power supply to the grid. The need to safeguard against faults becomes even more crucial as power generation facilities expand to meet rising global energy demands, further driving the adoption of fault current limiters in this segment.
 To learn more about this report, Download Free Sample Report
The automotive segment is expected to grow over the forecast period, driven by the rapid electrification of vehicles and the evolution of high-voltage EV architectures. As electric vehicles (EVs) adopt higher voltage platforms, the risk of electrical faults increases, making fault current protection critical for safety and system longevity. Using FCLs in EVs and EV charging infrastructure helps manage fault currents efficiently and protect batteries, inverters, and onboard chargers. The development of compact, solid-state FCLs that can be integrated into electric drivetrains and fast-charging stations contributes to the segment's growth. With the global push for green mobility and increasing government support for EV adoption, the demand for advanced protection technologies in the automotive sector is expected to grow rapidly, contributing significantly to the overall FCL market expansion.
The power stations segment is expected to grow at a CAGR of 6.2% over the forecast period, fueled by several factors, including the global push for energy transition and the increasing reliance on diverse energy sources. As the energy sector shifts towards renewable energy and adopts newer technologies, there is a growing emphasis on upgrading existing power infrastructure to handle more complex and variable power flows. Power stations must be equipped with advanced fault current management solutions to accommodate the integration of renewables and the challenges associated with grid stability and protection. In addition, the need to modernize aging power plants in developed regions and develop new power generation facilities in emerging economies is creating a steady demand for fault current limiters. These devices help ensure operational efficiency and safety, reinforcing their importance in power stations worldwide and driving sustained growth in this market segment.
Regional Insights
North America fault current limiter market is expected to grow at a CAGR of 6.8% over the forecast period, driven by increasing investments in smart grid technology and the modernization of electrical infrastructure. With the region's aging power grid systems and rising electricity demand, there is a heightened need for advanced solutions to manage fault currents and enhance grid reliability. In addition, the integration of renewable energy sources and the expansion of distributed generation are contributing to the rising adoption of FCLs to protect grid components from potential damage caused by fault currents. Technological advancements in FCL design, such as the development of superconducting and solid-state limiters, are also expected to bolster market growth, offering utilities more efficient and cost-effective solutions to manage fault currents. As utilities focus on enhancing grid resilience and reducing outage times, the demand for FCLs in North America is likely to continue its upward trend.
U.S. Fault Current Limiter Market Trends
The U.S. fault current limiter market held the largest share in North America in 2024 due to its extensive transmission network, high energy consumption, and strong federal and state-level initiatives to modernize the power grid. Utilities in the U.S. are actively investing in smart grid technologies and advanced fault protection systems to reduce outage risks and improve energy efficiency. With a strong focus on integrating renewable energy sources and developing smart grid technologies, the U.S. market is expected to experience steady growth, supported by regulatory mandates aimed at improving grid resilience and safety.
Europe Fault Current Limiter Market Trends
The fault current limiter market in Europe is expanding due to stringent regulations on grid safety and the ongoing transition to renewable energy sources. Countries across the region are focused on upgrading their electrical infrastructure to meet climate goals and improve energy efficiency. The integration of fault current limiters is crucial for managing the variability and complexity of power flows associated with renewable energy integration. As Europe continues to advance its smart grid initiatives and increase investments in green energy projects, the demand for fault current limiters is expected to grow significantly.
The France fault current limiter market is characterized by its robust energy infrastructure and a strong commitment to nuclear and renewable energy. As a leading producer of nuclear energy, France requires reliable fault current management solutions to protect its nuclear power plants and associated infrastructure. In addition, the country's increasing investments in renewable energy sources, particularly offshore wind, are driving the need for advanced grid protection technologies. Fault current limiters play a vital role in ensuring the stability and safety of France's electrical network, supporting its energy transition goals.
Asia Pacific Fault Current Limiter Market Trends
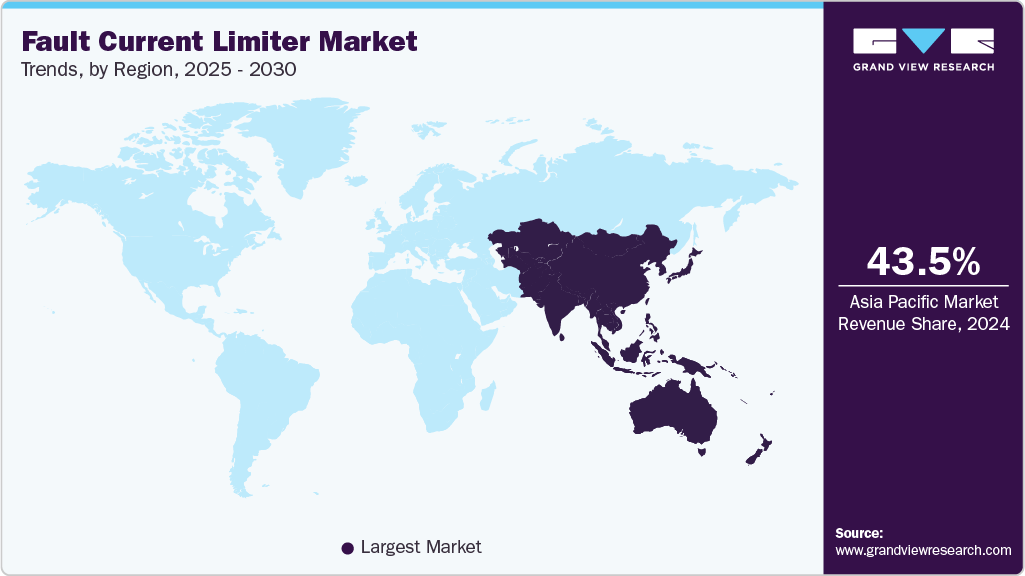
Asia Pacific region dominated the fault current limiter market with the largest revenue share of 38.5% in 2025. This dominance is largely driven by the rapid industrialization and urbanization occurring across key countries like China, India, Japan, and South Korea, which are significantly expanding their power infrastructure to meet the growing energy demands. The region’s focus on enhancing grid reliability and safety has led to substantial investments in advanced technologies, including fault current limiters, to protect electrical networks from the risks associated with increased fault currents. Moreover, the Asia Pacific region is experiencing a surge in renewable energy projects, which necessitate the integration of sophisticated fault management solutions to ensure stable and efficient power distribution.
 To learn more about this report, Download Free Sample Report
The fault current limiter market in the China held the largest share in the Asia Pacific region in 2025. In China, the fault current limiter market is expanding rapidly due to the country's ambitious plans for grid modernization and renewable energy integration. As the world's largest producer and consumer of electricity, China faces significant challenges in managing fault currents in its vast and diverse electrical network. The government’s focus on building a strong and resilient power infrastructure, coupled with substantial investments in renewable energy projects, is driving demand for advanced fault current limiters. China's commitment to reducing carbon emissions and increasing energy efficiency is likely to further stimulate market growth.
Middle East & Africa Fault Current Limiter Market Trends
The fault current limiter market in the Middle East & Africa is expected to grow rapidly over the forecast period. The market in the Middle East & Africa is gaining traction as countries invest in expanding and modernizing their power grids. With a strong emphasis on diversifying energy sources and improving grid stability, especially in countries with rapid urban growth, there is a growing need for reliable fault current management solutions. In addition, the increasing deployment of renewable energy projects, particularly in solar and wind, is driving demand for fault current limiters to manage the unique challenges posed by integrating these energy sources into the grid.
The Saudi Arabia fault current limiter market is evolving as the country undertakes major initiatives to transform its power sector under its Vision 2033 strategy. With a focus on diversifying energy sources and enhancing grid reliability, Saudi Arabia is investing in advanced technologies to support the expansion of its power infrastructure. The development of large-scale renewable energy projects, such as solar and wind farms, necessitates the use of fault current limiters to ensure grid stability and safety. As the country continues to modernize its grid and integrate new energy sources, the demand for fault current limiters is expected to grow steadily.
Key Fault Current Limiter Company Insights
The market is fragmented, characterized by the presence of numerous players ranging from well-established multinational corporations to smaller specialized companies. This fragmentation is due to the diverse applications and technologies within the market, such as superconducting and non-superconducting fault current limiters, each catering to different segments of the power industry. In addition, regional variations in power grid infrastructure and differing regulatory environments contribute to the fragmented nature of the market, with different players focusing on specific regions or types of fault current limiter technology. As a result, no single company dominates the global market, allowing for competitive dynamics and opportunities for new entrants and technological innovations. Key companies are adopting several organic and inorganic growth strategies, such as facility expansion, mergers & acquisitions, and joint ventures, to maintain and expand their market share.
-
American Superconductor specializes in advanced superconducting technologies and has pioneered Superconducting Fault Current Limiters (SFCLs) for utility grids. The company continues to focus on expanding its smart grid product portfolio and has engaged in strategic collaborations to enhance grid reliability and efficiency.
-
Nexans, a key player in the FCL space, drives through its innovation in superconducting technologies tailored for the rail and power sectors. The company invests in R&D to commercialize advanced current-limiting solutions for high-demand urban and industrial electrical networks.
Key Fault Current Limiter Companies
The following key companies have been profiled for this study on the fault current limiter market.
-
Rongxin Power Electronic Co., Ltd.
-
Applied Materials, Inc.
-
American Superconductor
-
Alsto
-
Nexans
-
Superconductor Technologies Inc.
-
ABB
-
Alstom SA
-
Zenergy Power Inc.
-
Siemens
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (ABB, Siemens, Schneider Electric, EATON, GE Vernova, Nexans, LS ELECTRIC Co., Ltd., Toshiba Energy Systems & Solutions Corporation)
- Focus on expanding grid protection and power transmission portfolios through continuous R&D and technology upgrades.
- Secure large utility and infrastructure projects through long-term contracts, strategic partnerships, and turnkey solutions.
- Invest in digital grid technologies and smart protection systems to support grid modernization initiatives.
- Expand global operations through acquisitions, regional manufacturing, and stronger distribution networks.
- Strong global presence with long-standing relationships across utility and industrial customers.
- Broad product portfolios that provide complete power protection and automation solutions.
- Strong financial resources, manufacturing capacity, and after-sales service networks.
- Proven track record in executing large-scale utility and infrastructure projects.
- Higher product and installation costs compared to smaller competitors.
- Slower adoption of niche or highly customized technologies due to complex organizational structures.
- Longer product development and decision-making cycles can delay innovation.
- Large organizational structures can reduce flexibility in responding to changing market needs.
Emerging Players (ASG Superconductors spa, GridON Ltd.)
- Focus on developing advanced superconducting and innovative fault current limiting technologies for specialized applications.
- Collaborate with utilities, research institutes, and government-funded projects to validate new technologies and accelerate commercialization.
- Target high-growth applications such as renewable energy integration, smart grids, and HVDC transmission projects.
- Expand market presence through pilot projects, strategic partnerships, and technology licensing agreements.
- Strong expertise in niche fault current limiting technologies and specialized applications.
- Greater flexibility to customize solutions for emerging grid protection requirements.
- Faster innovation cycles and quicker adoption of next-generation technologies.
- Ability to focus on advanced technologies such as superconducting and HVDC fault current limiters.
- Limited global presence and smaller customer base compared to established players.
- Lower manufacturing capacity and financial resources can restrict large-scale expansion.
- Lower brand recognition and fewer commercial deployments may affect market penetration.
- Greater dependence on pilot projects and external funding for technology commercialization.
Recent Developments
-
In July 2024, Nexperia announced the latest additions to its power device portfolio: NPS3102A and NPS3102B electronic fuses (eFuses).
-
In June 2024, Nexans and SNCF Réseau announced a strategic alliance to deploy the world’s first superconducting fault current limiter for the rail sector.
-
In February 2024, COSEL Co., Ltd. launched a PDA series of AC/DC power supply, which includes inrush current limiting and further enhances reliability for industrial applications.
Fault Current Limiter Market Report Scope
Report Attribute
Details
Market Definition
The fault current limiter market size is measured by the revenue generated from the sales of superconducting and non-superconducting fault current limiters across high-, medium-, and low-voltage applications deployed in power stations, oil & gas, automotive, paper mills, chemicals, and steel & aluminum industries.
Market size in 2025
USD 5.8 billion
Estimated market size in 2026
USD 6.1 billion
Projected market size by 2033
USD 9.2 billion
Growth rate
CAGR of 6.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD Billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, Voltage Range, End-use, Region
Regional scope
North America, Europe, Asia Pacific, Latin America, Middle East & Africa
Country scope
U.S., Canada, Mexico, Germany, France, UK, Italy, Spain, Russia, China, India, Japan, South Korea, Brazil, Argentina, Saudi Arabia, South Africa, UAE
Key companies profiled
ABB, Siemens, Schneider Electric, EATON, GE Vernova, Nexans, ASG Superconductors spa, GridON Ltd., LS ELECTRIC Co., Ltd., Toshiba Energy Systems & Solutions Corporation
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Fault Current Limiter Market Report Segmentation
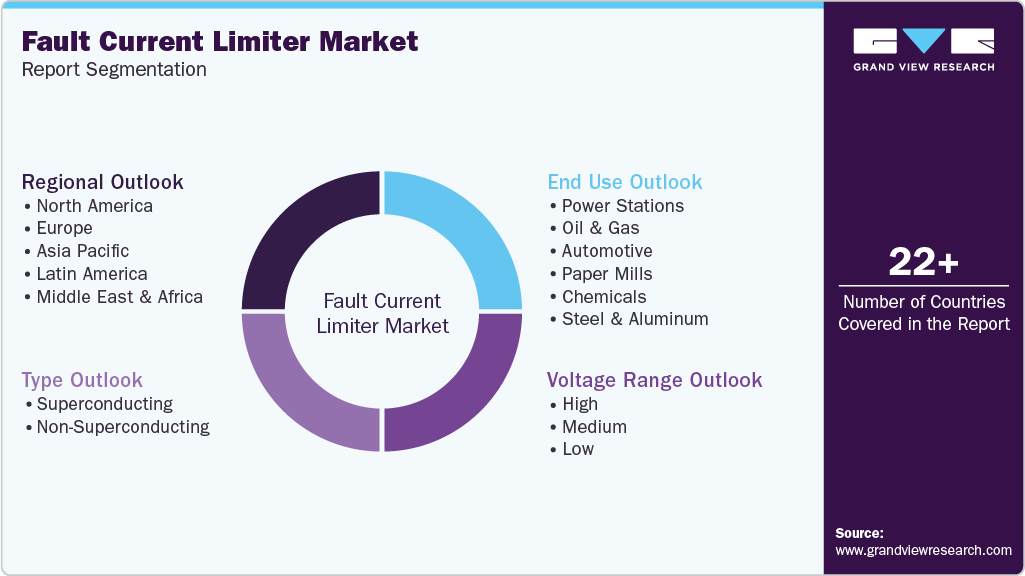
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global fault current limiter market report based on type, voltage range, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Superconducting
-
Non-Superconducting
-
-
Voltage Range Outlook (Revenue, USD Million, 2021 - 2033)
-
High
-
Medium
-
Low
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Power Stations
-
Oil & Gas
-
Automotive
-
Paper Mills
-
Chemicals
-
Steel & Aluminum
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Russia
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
UAE
-
-
Research Methodology
The fault current limiter market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each fault current limiter segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment – Type
Revenue capture definition
Superconducting
Superconducting fault current limiters use superconducting materials that offer near-zero resistance during normal operation and rapidly limit excessive fault currents during electrical faults. They are primarily used in high-voltage transmission networks, smart grids, and renewable energy systems. Revenue is generated from the sale of superconducting fault current limiters.
Non-Superconducting
Non-superconducting fault current limiters use conventional technologies such as inductive, resistive, or solid-state designs to reduce fault currents in electrical networks. They are widely deployed across utility and industrial power systems due to their simpler design and lower installation costs. Revenue is generated from the sale of non-superconducting fault current limiters.
Segment – Voltage Range
Revenue capture definition
High
High-voltage fault current limiters are designed to protect transmission networks, HVDC systems, and large utility substations from excessive fault currents. Revenue is generated from the sale of high-voltage fault current limiters.
Medium
Medium-voltage fault current limiters are used in industrial facilities, renewable energy plants, and distribution networks to protect switchgear, transformers, and electrical equipment. Revenue is generated from the sale of medium-voltage fault current limiters.
Low
Low-voltage fault current limiters are installed in commercial buildings, manufacturing facilities, and small industrial power systems to limit fault currents and improve electrical safety. Revenue is generated from the sale of low-voltage fault current limiters.
Segment – End-use
Revenue capture definition
Power Stations
Fault current limiters are used in conventional and renewable power stations to protect generators, transformers, and switchgear from high fault currents, ensuring reliable power generation and transmission. Revenue is generated from the sale of fault current limiters to power stations.
Oil & Gas
Fault current limiters are deployed in upstream, midstream, and downstream oil & gas facilities to protect critical electrical infrastructure operating under high-power conditions. Revenue is generated from the sale of fault current limiters to the oil & gas industry.
Automotive
Fault current limiters are used in automotive manufacturing plants and electric vehicle production facilities to safeguard electrical distribution systems and automated production equipment. Revenue is generated from the sale of fault current limiters to the automotive industry.
Paper Mills
Fault current limiters protect motors, transformers, and power distribution systems in paper manufacturing facilities, reducing the risk of equipment damage and production downtime. Revenue is generated from the sale of fault current limiters to paper mills.
Chemicals
Fault current limiters are installed in chemical processing plants to ensure safe and reliable operation of electrical systems in continuous-process environments. Revenue is generated from the sale of fault current limiters to the chemical industry.
Steel & Aluminum
Fault current limiters are used in steel and aluminum manufacturing plants to protect high-capacity electrical equipment such as electric arc furnaces, rolling mills, and power distribution systems from excessive fault currents. Revenue is generated from the sale of fault current limiters to the steel & aluminum industry.
Estimation Model
Layer No.
Layer Name
Key Question
Description
01
Power Grid & Industrial Demand Layer
What forms the demand base for fault current limiters?
Assess demand for fault current limiters driven by grid modernization, expansion of transmission and distribution networks, renewable energy integration, industrial electrification, and investments in critical infrastructure. Evaluate increasing fault current levels, aging grid infrastructure, power system upgrades, and the need for advanced protection systems across utilities and industrial facilities to determine the underlying market demand.
02
Fault Current Limiter Type Layer
Which types of fault current limiters are being adopted?
Analyze the adoption of superconducting and non-superconducting fault current limiters across utility and industrial applications. Assess technology maturity, fault current limiting performance, installation complexity, operating costs, maintenance requirements, and application suitability to determine type-wise market demand.
03
Voltage & End-use Deployment Layer
Where are fault current limiters being deployed?
Evaluate the deployment of high-, medium-, and low-voltage fault current limiters across power stations, oil & gas, automotive, paper mills, chemicals, and steel & aluminum industries. Analyze voltage requirements, grid connection levels, power capacity, operational risks, and protection needs to estimate voltage- and end-use-wise market contribution
04
Revenue Layer
How is market revenue generated?
Market revenue is quantified through the sale of fault current limiters across different technologies, voltage ranges, and end-use industries. The overall market value is determined by equipment sales, voltage rating, technology type, project scale, installation complexity, customization requirements, and pricing across utility and industrial applications.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Voltage-wise End-use Assessment
Evaluated the adoption of high-, medium-, and low-voltage fault current limiters across power stations, oil & gas, automotive, paper mills, chemicals, and steel & aluminum industries. Assessed deployment patterns based on protection requirements, voltage levels, and operational conditions.
Helped identify the most suitable voltage range for each end-use industry, understand deployment trends, and support product positioning and investment decisions.
Technology Benchmarking Assessment
Compared superconducting and non-superconducting fault current limiters based on fault current limiting capability, response time, installation complexity, maintenance requirements, operating costs, and application suitability. Assessed technology adoption across utility and industrial applications.
Helped identify the most suitable technology for different applications, understand technology-specific advantages, and support technology selection and investment decisions.
Competitive Landscape Assessment
Evaluated prominent fault current limiter manufacturers based on product portfolio, geographic presence, technology capabilities, manufacturing expertise, project deployments, strategic partnerships, and recent developments. Assessed competitive positioning across established and emerging market participants.
Helped benchmark key competitors, identify market leaders, and understand competitive differentiation across the fault current limiter value chain.
Frequently Asked Questions About This Report
Based on voltage, the medium segment accounted for largest revenue share of 44.8% in 2025.
The key players operating in the fault current limiter market are ABB, Siemens, Schneider Electric, EATON, GE Vernova, Nexans, ASG Superconductors spa, GridON Ltd., LS ELECTRIC Co., Ltd., Toshiba Energy Systems & Solutions Corporation, and others.
The fault current limiter market is primarily driven by increasing grid modernization, growing renewable energy integration, and the rising need to protect power systems from higher fault current levels.
The global fault current limiter market size was estimated at USD 5.8 billion in 2025 and is expected to reach USD 6.1 billion in 2026.
The fault current limiter market is expected to grow at a CAGR of 6.1% from 2026 to 2033 to reach USD 9.2 billion by 2033.
The Asia Pacific region dominated the fault current limiter market with a revenue share of 38.5% in 2025.
China dominated the Asia Pacific region market with a revenue share of 46.6% in 2025.
Asia Pacific region is anticipated to register the fastest CAGR of 6.5% over the forecast period.
Based on type, the non-superconducting segment accounted for the largest revenue share of 60.2% in 2025.
About the Author(s)
Distribution & Utilities Research Team
Energy & Power · Distribution & UtilitiesThis report was authored by the distribution & utilities research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the distribution & utilities segment of the energy & power industry. All findings are based on proprietary energy & power databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


