
- Home
- »
- Green Building Materials
- »
-
Fire Stopping Materials Market Size Report, 2026-2033GVR Report cover

Fire Stopping Materials Market (2026 - 2033)
Size, Share & Trends Analysis Report By Materials (Sealants, Coatings, Mortars, Putty, Boards), By Application (Electrical, Mechanical, Plumbing), By End-use (Residential, Commercial), By Region, And Segment Forecasts
Market Size, 2025
$1.6BMarket Estimate, 2026
$1.7BMarket Forecast, 2033
$3.0BCAGR, 2026–2033
8.6%Fire Stopping Materials Market Summary
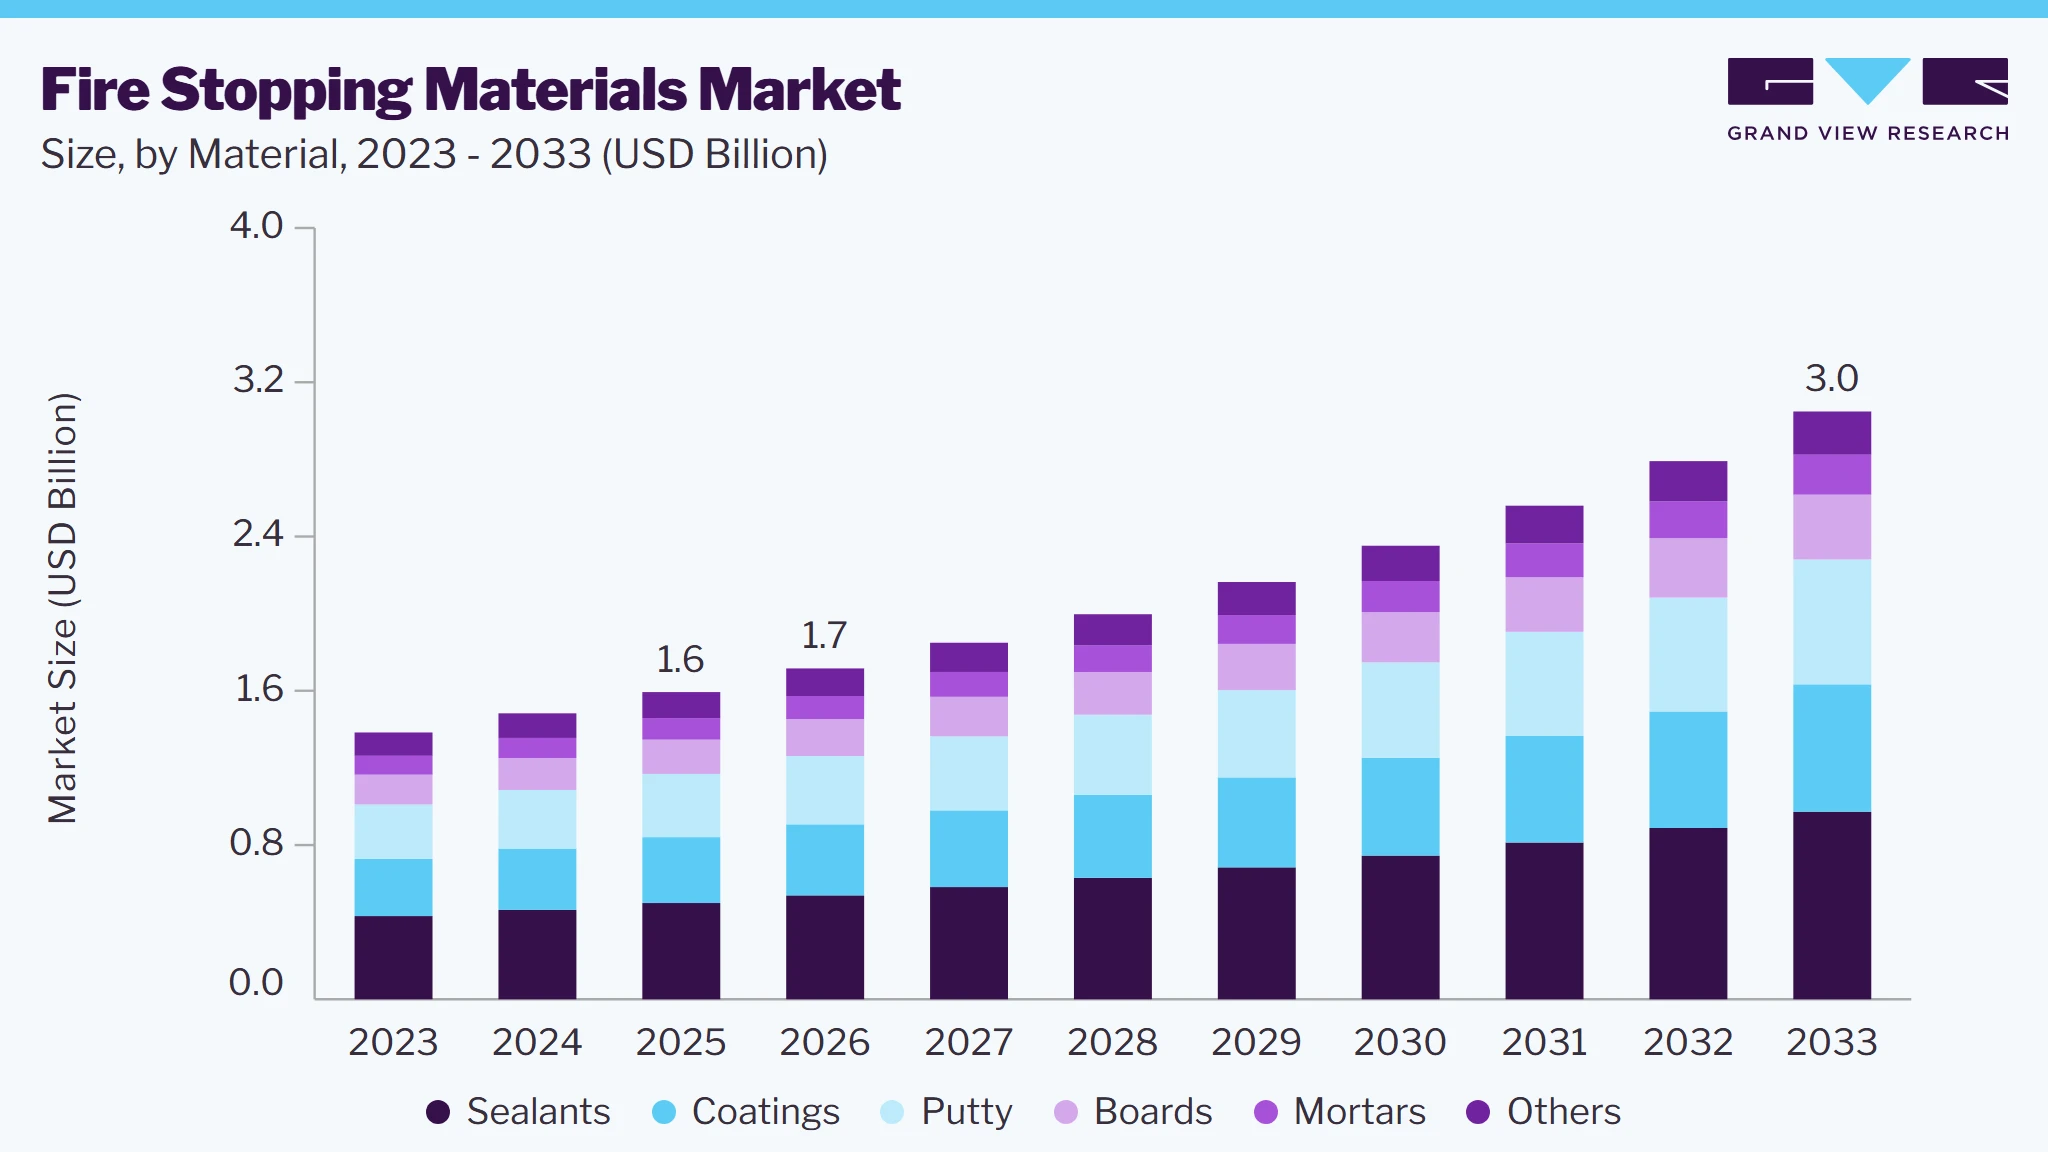
The global fire stopping materials market size was valued at USD 1.6 billion in 2025 and is projected to grow from USD 1.7 billion in 2026 to USD 3.0 billion by 2033, at a CAGR of 8.6% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 31.1% in 2025. The demand for fire stopping materials is growing in the global market due to the increasing emphasis on fire safety regulations and building codes worldwide.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By material: Sealants segment led the market with the largest revenue share of 31.3% in 2025 and is expected to grow at a CAGR of 8.8% over the forecast period.
- By end use: Commercial segment led the market with the largest revenue share of 50.9% in 2025 and is expected to grow at a CAGR of 8.3% over the forecast period.
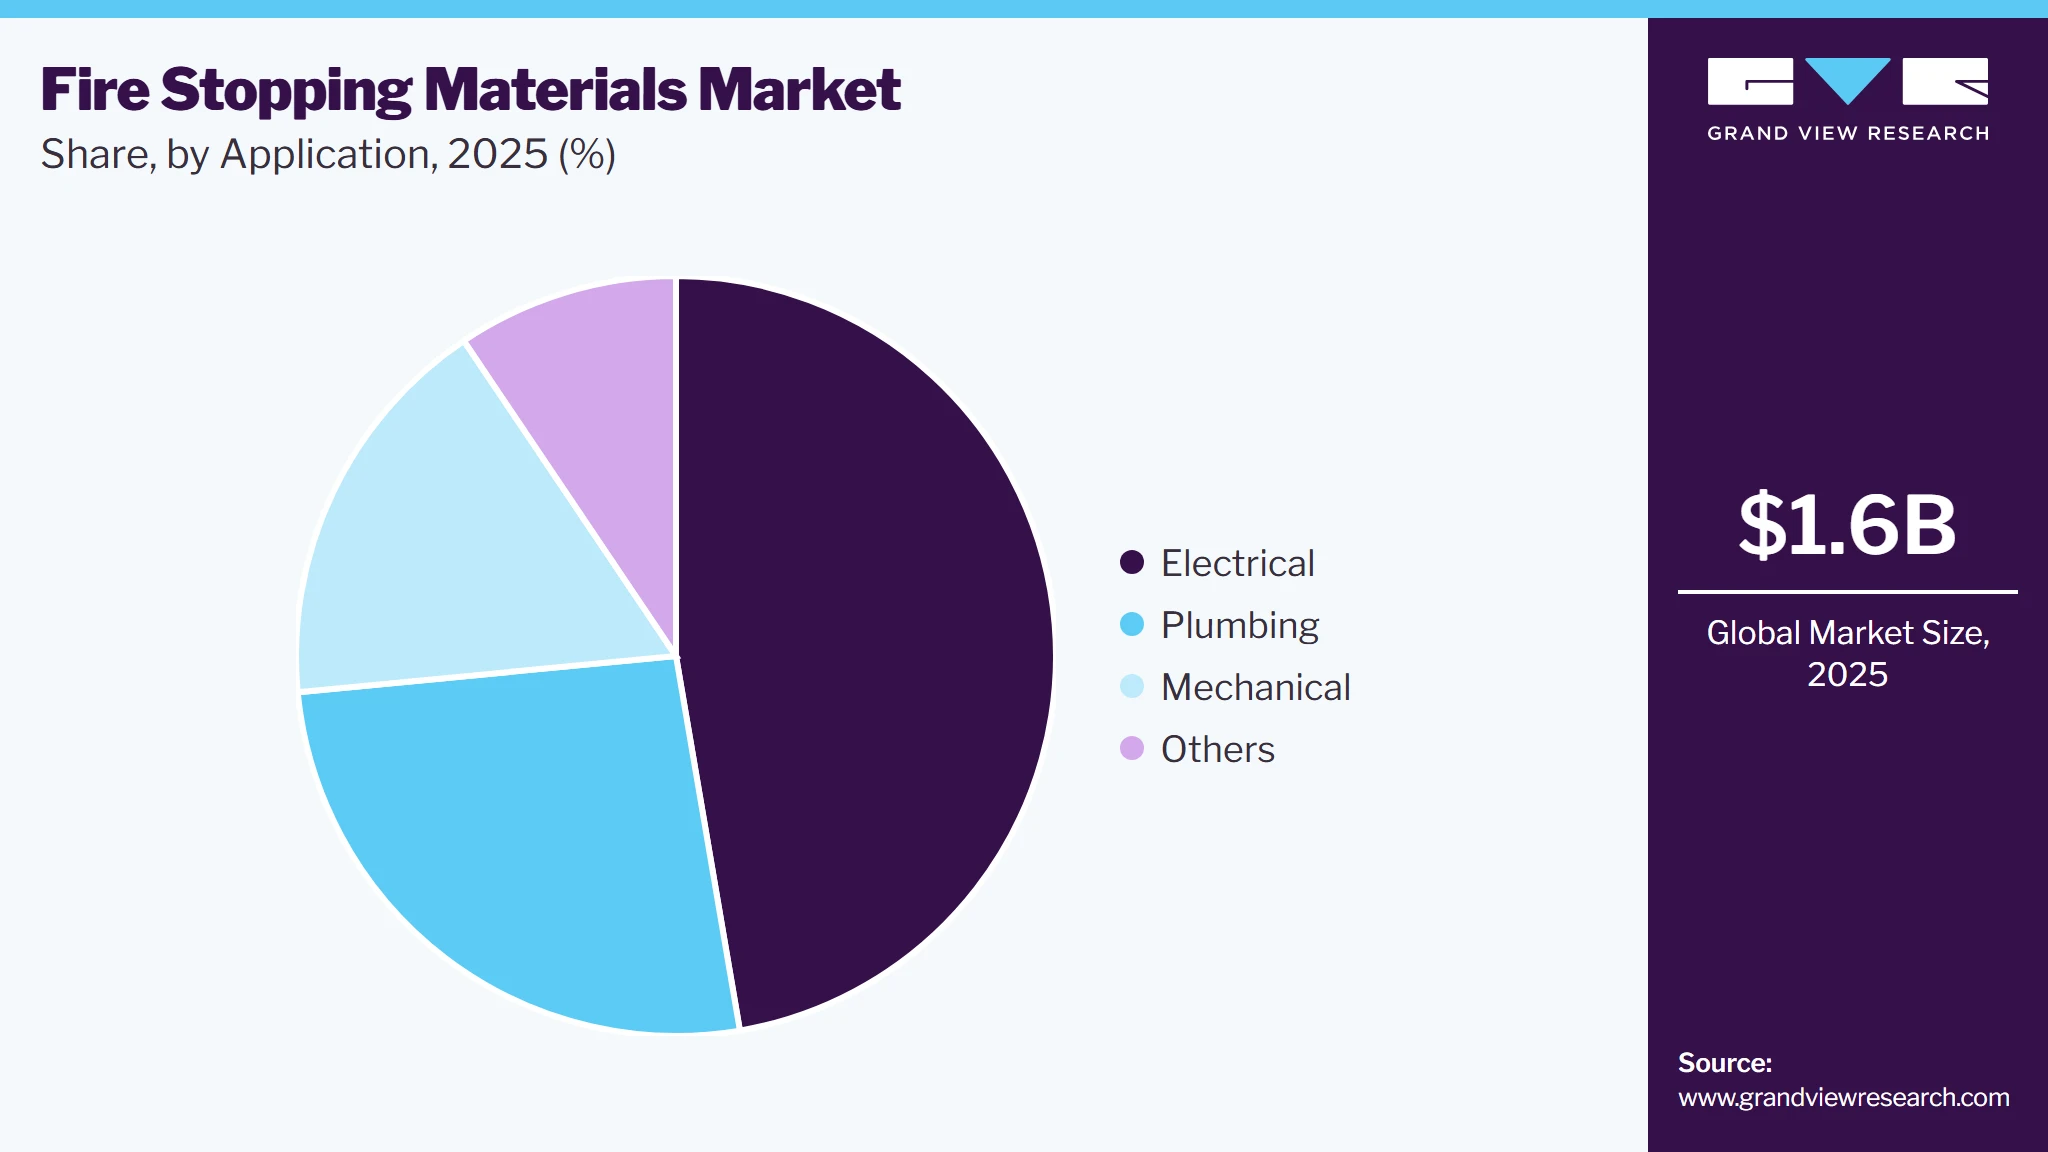
- By application: Electrical segment led the market with the largest revenue share of 47.3% in 2025 and is expected to grow at a CAGR of 8.9% over the forecast period.
Regional Highlights
- Largest regional market: North America (31.1% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 1.6 Billion
- Estimated market size in 2026: USD 1.7 Billion
- Projected market size by 2033: USD 3.0 Billion
- CAGR (2026-2033): 8.6%
Prism AI by Grand View Research Free to tryAsk a question about the fire stopping materials marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Governments and regulatory authorities are continually tightening safety standards in response to rising fire incidents, particularly in densely populated urban areas. These materials, designed to prevent the spread of flames, smoke, and toxic gases through openings and penetrations in walls, floors, and ceilings, are essential for ensuring the integrity of fire-resistance-rated structures. This regulatory push has heightened the adoption of fire-stopping solutions in both new construction and retrofit projects, driving market growth.Another significant factor contributing to the growing demand is the rapid pace of urbanization and infrastructure development. As global populations shift toward urban centers, the construction of residential buildings, commercial complexes, and industrial facilities has surged. With this growth comes the need for stringent fire safety measures to protect lives and assets. In addition, the rise in green building initiatives and the construction of high-rise buildings necessitate the use of advanced fire-stopping technologies, as these structures are particularly vulnerable to fire spread due to their design complexities.
 To learn more about this report, Download Free Sample Report
The increasing awareness of fire hazards among industries and property owners has also played a key role in driving demand. Organizations across sectors such as oil and gas, manufacturing, and healthcare are recognizing the critical importance of fire-stopping materials in mitigating risks and ensuring business continuity. The growing emphasis on liability management and risk reduction has led businesses to invest heavily in fire-resistant systems, further boosting the market.
Market Dynamics
The fire stopping materials market is witnessing steady growth as governments, building owners, and developers increasingly prioritize passive fire protection systems to enhance occupant safety and minimize property damage. Fire stopping materials, including sealants, mortars, collars, wraps, boards, and intumescent products, are widely used to seal penetrations and joints in fire-rated walls and floors, preventing the spread of fire, smoke, and toxic gases. Growing investments in commercial buildings, industrial facilities, healthcare infrastructure, transportation projects, and data centers, coupled with stringent building codes and renovation activities, continue to strengthen market demand. Additionally, advancements in certified, environmentally friendly, and easy-to-install firestop systems are expanding product adoption across both new construction and retrofit projects.
Governments across North America, Europe, Asia Pacific, and the Middle East are strengthening fire safety regulations and building codes following major fire incidents and increasing emphasis on life safety. Compliance with standards for fire-rated walls, floors, cable penetrations, HVAC ducts, and pipe openings has become mandatory across commercial, residential, and industrial buildings. This regulatory environment is encouraging architects, contractors, and developers to integrate certified fire stopping systems during construction, significantly boosting market demand.
Rapid urbanization and expanding infrastructure projects are further accelerating the adoption of fire stopping materials. The construction of high-rise residential towers, hospitals, airports, data centers, manufacturing plants, educational institutions, and transportation infrastructure requires reliable passive fire protection to maintain structural compartmentation. Increasing retrofit activities in aging buildings, where fire safety systems are being upgraded to meet modern regulations, are also creating sustained demand for advanced fire stopping solutions across developed and emerging economies.
The market faces challenges due to the relatively high cost of certified fire stopping systems and the need for skilled installation. Firestop products must be installed according to tested system designs to ensure compliance with fire resistance standards, making improper installation a significant concern. Limited availability of trained installers, varying regional certification requirements, and the additional costs associated with inspections and testing can discourage adoption, particularly in cost-sensitive construction projects and developing markets.
The increasing development of smart buildings, green infrastructure, and technologically advanced commercial facilities presents significant growth opportunities for fire stopping material manufacturers. Demand is rising for low-VOC, halogen-free, environmentally sustainable, and digitally documented firestop systems that support green building certifications while ensuring regulatory compliance. Manufacturers are also introducing innovative intumescent materials, modular firestop solutions, and digital documentation tools that simplify installation, maintenance, and inspection processes, creating new opportunities in both new construction and renovation markets.
Market Concentration & Characteristics
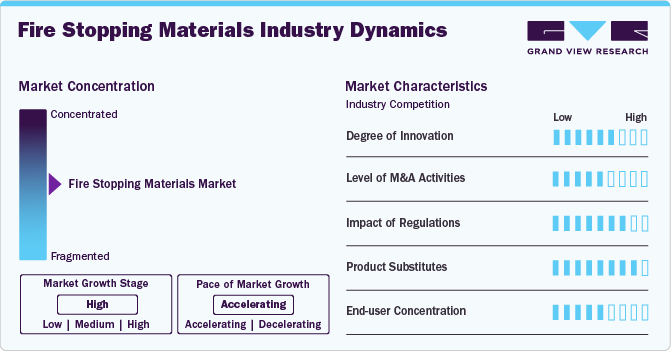
Market growth stage is high, and pace is accelerating. The fire-stopping materials industry is characterized by its dynamic growth trajectory, driven by diverse end-user applications and increasing global demand for enhanced fire safety measures. It is a fragmented yet highly competitive industry with a mix of global and regional players offering specialized products.
Products are developed to meet stringent fire safety standards such as ASTM, UL, and EN, making certification and testing a critical part of the competitive landscape. The industry is also seeing an increase in demand for sustainable and non-toxic fire-stopping solutions, aligning with the global push toward environmentally friendly construction practices.
 To learn more about this report, Download Free Sample Report
The fire-stopping materials industry is marked by intense competition among established players, mid-sized companies, and niche manufacturers. Major players dominate the global market due to their extensive product portfolios, global distribution networks, and strong R&D capabilities. These companies leverage advanced technology and economies of scale to maintain their competitive edge, offering comprehensive solutions for both new constructions and retrofitting projects.
Furhermore, advancements in fire-stopping materials, such as the development of eco-friendly, cost-effective, and high-performance solutions, are fueling their adoption. Innovations in materials, including intumescent coatings, fire-resistant sealants, and firestop collars, have enhanced the efficiency and versatility of these products. With ongoing research and development efforts, manufacturers are introducing solutions tailored to meet the diverse needs of end-users, ensuring sustained growth in the global market.
Analyst Perspective
The fire stopping materials market is expected to maintain steady growth, supported by stricter fire safety regulations, evolving building codes, and sustained investments in commercial and critical infrastructure. Beyond regulatory compliance, end users are increasingly prioritizing firestop systems that offer faster installation, proven performance, and certified compatibility with modern building services. In response, manufacturers are expanding their portfolios with application-specific solutions, advanced intumescent technologies, and digital compliance tools. Looking ahead, retrofit activity in aging buildings, along with the rapid development of data centers, healthcare facilities, transportation infrastructure, and high-rise projects, is expected to sustain demand, reinforcing fire stopping materials as a critical element of modern passive fire protection rather than simply a code compliance requirement.
Material Insights
Based on material, the sealants segment led the market with the largest revenue share of 31.3% in 2025 and is expected to grow at a CAGR of 8.8% over the forecast period. Fire stopping sealants are specialized materials, which are used to seal joints, gaps, and penetrations in buildings to prevent the spread of fire, smoke, and toxic gases. These are mainly made from fire-resistant materials, such as silicone, acrylic, or intumescent compounds. These sealants are applied to openings in fire-rated walls, floors, and ceilings to maintain the integrity of fire barriers and compartments.
Fire stopping putty is a pliable material, which is used to seal small openings and gaps in fire-rated walls, floors, and ceilings. It is designed to provide a flexible barrier against the spread of fire, smoke, and toxic gases. Fire stopping putty remains flexible even after application, allowing it to conform to irregular shapes and surfaces. This flexibility helps ensure a tight seal around penetrations, such as cables, pipes, and conduits, preventing the passage of flames and hot gases.
Application Insights
Based on application, the electrical segment led the market with the largest revenue share of 47.3% in 2025 and is expected to grow at a CAGR of 8.9% over the forecast period. Fire stopping materials play a critical role in electrical applications by providing passive fire protection to electrical installations, equipment, and wiring. One of the primary advantages of fire stopping materials in electrical applications is their ability to prevent the spread of fire. Electrical fires can start due to various factors, such as short circuits, overloaded circuits, or faulty equipment. Materials, such as sealants, putties, and wraps, create a barrier around electrical penetrants, preventing the spread of flames, smoke, and heat to other areas of the building.
 To learn more about this report, Download Free Sample Report
Mechanical systems, including HVAC (heating, ventilation, and air conditioning) duct systems, are critical for maintaining occupant comfort and safety in buildings. Fire-stopping materials create a barrier around mechanical penetrations, such as ducts and vents, preventing the spread of fire and smoke to other parts of the building. Fire-stopping materials provide an additional layer of fire protection against mechanical penetrations, complementing other fire safety measures, such as fire-rated walls, doors, and dampers. By sealing gaps and voids around penetrations, these materials help maintain the fire resistance rating of building assemblies and prevent the spread of fire through concealed spaces.
End Use Insights
Based on end use, the commercial segment led the market with the largest revenue share of 50.9% in 2025 and is expected to grow at a CAGR of 8.3% over the forecast period. Commercial buildings often house a diverse range of occupants, including employees, customers, and visitors, making fire safety a paramount concern. The potential for fire hazards in commercial settings, such as electrical faults, combustible materials, and heating systems, is higher compared to residential buildings, due to the larger scale and complexity of commercial operations. As a result, there is a growing recognition among building developers and regulatory authorities regarding the need to implement robust fire protection measures in commercial buildings.
On the other hand, industrial buildings often house high-risk activities and processes that increase the likelihood of fire incidents. These activities may include manufacturing, storage of flammable materials, chemical processing, and machinery operation. As a result, industrial buildings are particularly susceptible to fire hazards, making fire safety a top priority for facility managers and operators.
Regional Insights
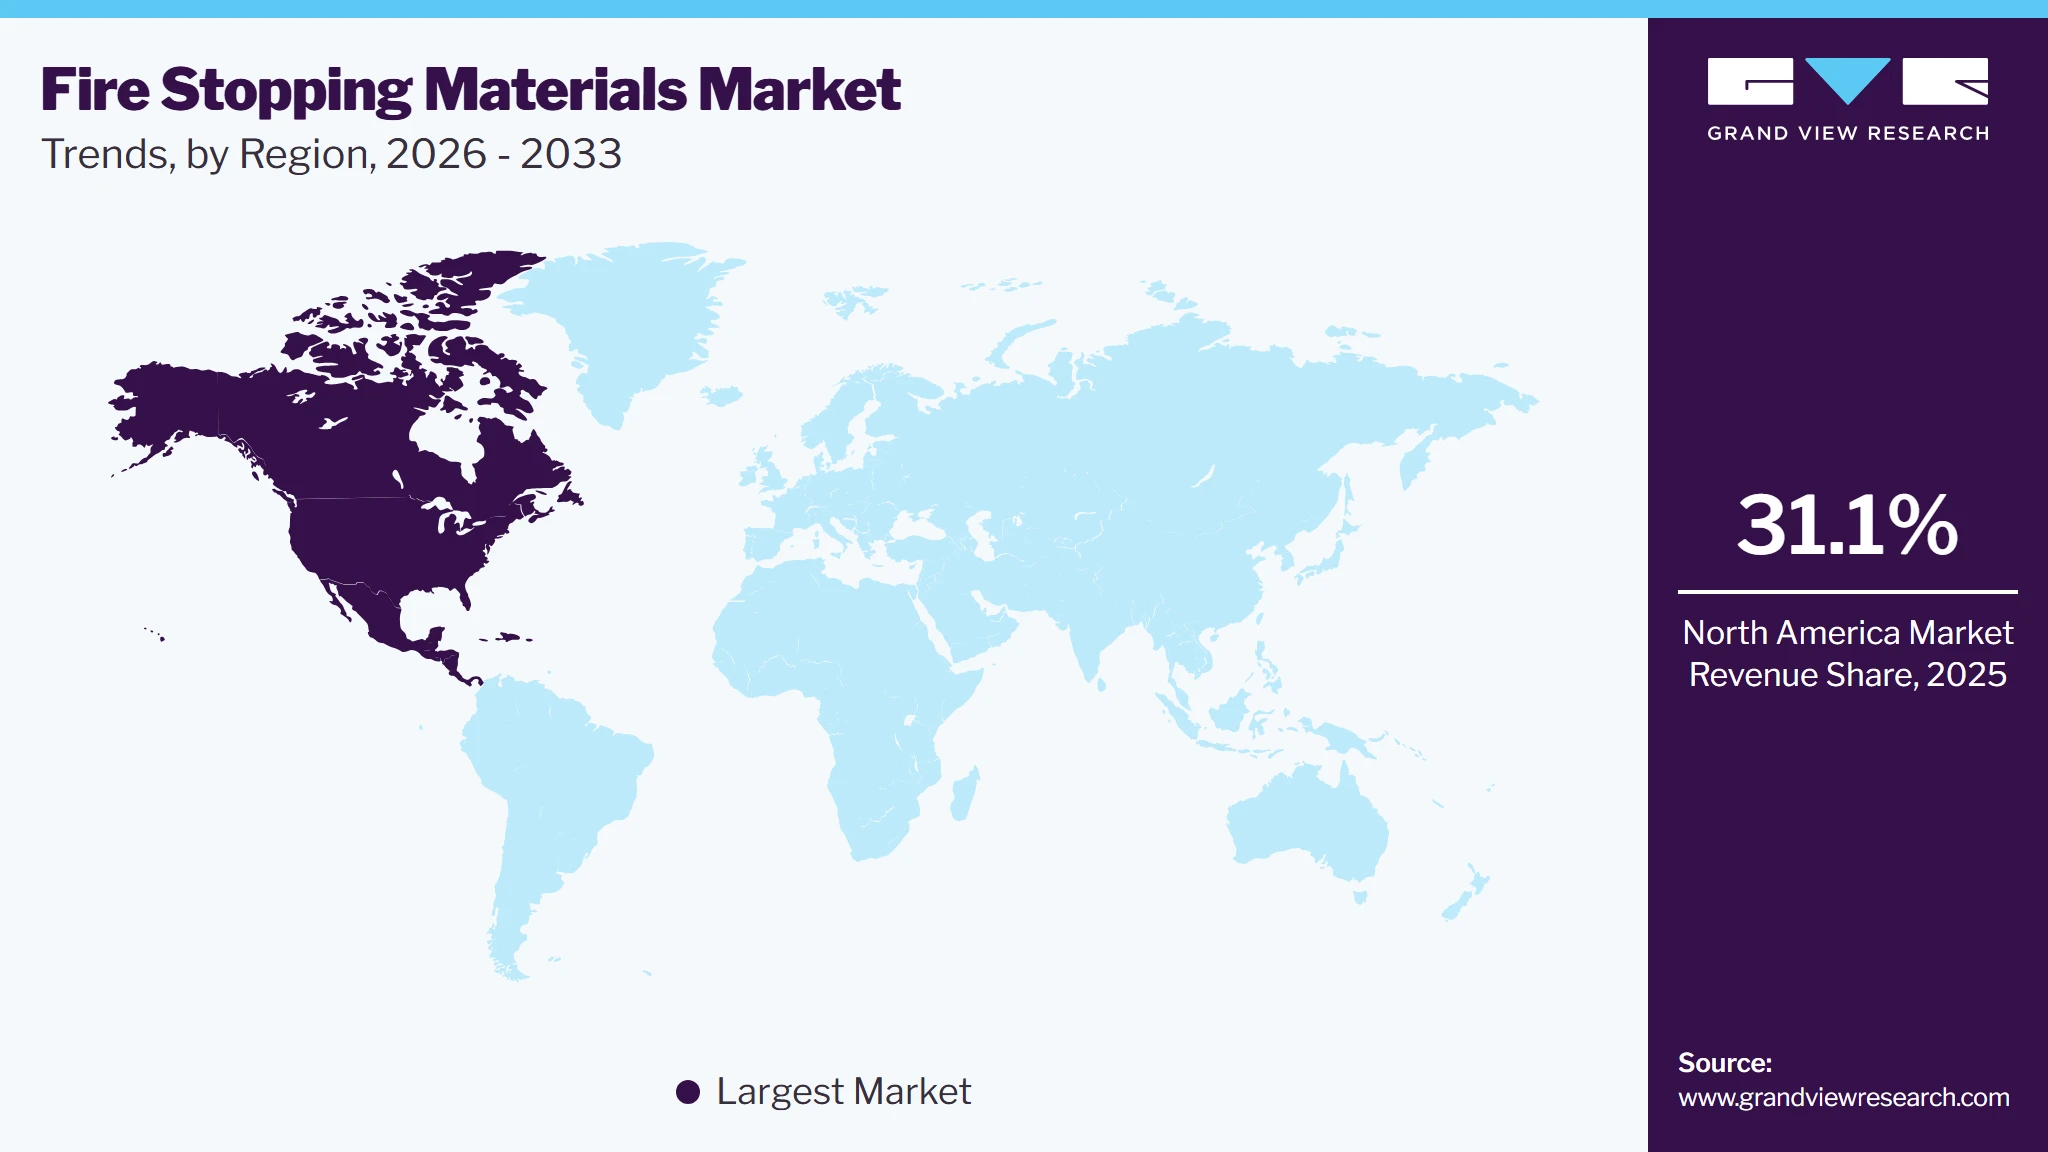
North America dominated the fire stopping materials market with the largest revenue share of 31.1% in 2025. This is attributed to the increasing number of large-scale infrastructure projects, including data centers, commercial complexes, and public facilities. The region’s advanced construction sector is placing greater emphasis on fire-resistant solutions to meet stringent safety requirements. Furthermore, the push toward retrofitting older buildings to align with modern fire safety codes is creating a sustained demand for innovative and compliant fire-stopping materials.
 To learn more about this report, Download Free Sample Report
U.S. Fire Stopping Materials Market Trends
The fire stopping materials market in U.S. held the largest share in the North America region in 2025. The USA stands out as the primary driver of demand within North America, fueled by urbanization and a surge in multi-family housing and mixed-use developments. In addition, rising awareness of wildfire hazards in regions like California has led to the adoption of advanced fire-resistant technologies in residential and commercial buildings. Federal and state-level incentives for disaster-resilient infrastructure have further propelled the market for fire-stopping solutions.
Asia Pacific Fire Stopping Materials Market Trends
The fire stopping materials market in Asia-Pacific is experiencing a surge in demand for fire-stopping materials due to rapid urbanization and infrastructure development across emerging economies. The region’s booming construction industry, particularly in high-rise residential and commercial buildings, is a key driver. In addition, governments in countries like India and Vietnam are increasingly adopting stricter fire safety regulations, further accelerating market growth.
The China fire stopping materials market is anticipated to grow at the fastest CAGR during the forecast period. China’s construction boom, driven by its massive urbanization initiatives and industrial expansion, has created substantial demand for fire-stopping materials. The country’s growing focus on fire safety in megaprojects, such as smart cities and transportation hubs, has further intensified this trend. In addition, stricter enforcement of local fire safety standards is pushing builders to adopt advanced fire-stopping solutions.
Europe Fire Stopping Materials Market Trends
The fire stopping materials market in Europe is anticipated to grow at the fastest CAGR during the forecast period. The growing adoption of fire-stopping materials is linked to the region's commitment to achieving net-zero emissions and sustainability goals. Green building certifications, such as BREEAM and LEED, require the use of fire-resistant materials, driving the market growth. In addition, the refurbishment of heritage buildings to meet updated fire safety codes is fueling the demand for adaptable fire-stopping solutions.
The Germany fire stopping materials market accounted for the largest revenue share in Europe in 2024. The focus on industrial fire safety in sectors such as automotive, manufacturing, and logistics is a significant growth driver. The stringent enforcement of national fire safety standards, coupled with the country’s high adoption of prefabricated building techniques, has increased the use of specialized fire-stopping materials. Moreover, Germany’s leadership in research and development is encouraging innovation in fire protection technologies.
Central & South America Fire Stopping Materials Market Trends
The fire stopping materials market in Central and South America is anticipated to grow at a significant CAGR during the forecast period. The growing demand for fire-stopping materials is driven by expanding urban infrastructure projects and a rising middle class investing in safer residential buildings. Countries like Brazil and Mexico are witnessing increased adoption due to government initiatives to improve fire safety in public spaces, including schools and hospitals. In addition, a growing awareness of fire hazards is driving private sector investment in fire-resistant technologies.
Middle East & Africa Fire Stopping Materials Market Trends
The fire stopping materials market in the Middle East and Africa is experiencing growth in fire-stopping materials due to the rapid development of high-rise buildings, luxury hotels, and large-scale infrastructure projects, particularly in countries like the UAE and Saudi Arabia. The rising focus on ensuring fire safety in oil and gas facilities is also a major driver. In Africa, the growth of urban centers and the increasing enforcement of fire safety regulations are pushing developers to incorporate fire-stopping materials into new construction projects
Key Fire Stopping Materials Company Insights
Some key companies in the global market include Hilti Corporation, 3M, BASF SE, RectorSeal, Sika AG, Specified Technologies, Inc., Etex Group, Morgan Advanced Materials, Knauf Insulation, and RPM International Inc. Vendors in the market are focusing on increasing their customer base to gain a competitive edge in the industry. Therefore, key players are taking several strategic initiatives, such as mergers and acquisitions and partnerships with other major companies.
-
Hilti Corporation was founded in 1941 and is headquartered in Liechtenstein. This company operates through its fourteen divisions, including, Anchor systems, Construction chemicals, Cordless systems, Cutting, sawing and grinding, Diamond corning and cutting, Direct fastening, Drilling and demolition, Firestop, Accessories, Modular support systems, Measuring systems, Screw fastening and Façade systems.
-
Knauf Insulation was founded in 1978, and is headquartered in Indiana, U.S. It operates as a subsidiary of Gebr. Knauf KG. It is engaged in the production and distribution of building & construction materials for customers in Australia, Africa, Asia, the Russian Federation, South America, the U.S., and European countries. The company operates in over 40 countries across the globe, with 28 production facilities in 15 different countries.
Key Fire Stopping Materials Companies
The following key companies have been profiled for this study on the fire stopping materials market.
-
Hilti Corporation
-
3M
-
BASF SE
-
RECTORSEAL CORPORATION
-
Sika AG
-
Specified Technologies, Inc
-
Etex Group
-
Morgan Advanced Materials
-
Knauf Insulation
-
RPM International Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Hilti Corporation; 3M; BASF SE; Sika AG; RPM International Inc.)
- Expand certified firestop product portfolios across sealants, coatings, mortars, and boards.
- Invest in R&D for advanced intumescent and sustainable fire stopping solutions.
- Strengthen global distribution networks and partnerships with contractors, EPC firms, and construction companies.
- Strong global brand presence and extensive distribution network.
- Comprehensive portfolio of fire-tested, code-compliant passive fire protection systems.
- High technical expertise, certification capabilities, and after-sales engineering support.
- High costs associated with product testing, certification, and regulatory compliance.
- Vulnerability to fluctuations in raw material and construction costs.
- Dependence on commercial and industrial construction activity for revenue growth.
Emerging Players (RECTORSEAL CORPORATION; Specified Technologies, Inc.; Etex Group; Morgan Advanced Materials; Knauf Insulation)
- Focus on niche and application-specific fire stopping solutions.
- Expand regional distribution channels and strategic partnerships.
- Develop easy-to-install, sustainable, and high-performance firestop products.
- Strong specialization in targeted passive fire protection applications.
- Greater flexibility in meeting project-specific customer requirements.
- Faster product innovation and quicker response to changing building codes.
- Limited global manufacturing and market presence.
- Lower bargaining power than multinational competitors.
- Greater reliance on regional demand and distributor networks for growth.
Recent Developments
-
In July 2022, BASF and THOR GmbH announced their collaboration by combining their expertise in non-halogenated flame retardant additives to bring solutions that are expected to enhance the sustainability and performance of specific plastic compounds, as well as meet stringent fire safety requirements.
-
In September 2020, Etex Group announced the acquisition of FSi Limited, a British company that specializes in passive fire protection solutions to strengthen its position in the market.
Fire Stopping Materials Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.6 billion
Estimated market size in 2026
USD 1.7 billion
Projected market size by 2033
USD 3.0 billion
Growth rate
CAGR of 8.6% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Material, application, end use, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; China; India; Japan
Key companies profiled
Hilti Corporation; 3M; BASF SE; RectorSeal ; Sika AG; Specified Technologies, Inc.; Etex Group; Morgan Advanced Materials; Knauf Insulation and RPM International Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Fire Stopping Materials Market Report Segmentation
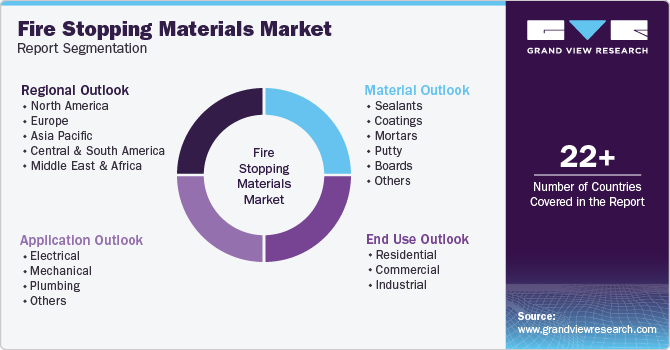
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global fire stopping materials market report based on material, application, end use and region:
 To learn more about this report, Download Free Sample Report
-
Material Outlook (USD Million, 2021 - 2033)
-
Sealants
-
Coatings
-
Mortars
-
Putty
-
Boards
-
Others
-
-
Application Outlook (USD Million, 2021 - 2033)
-
Electrical
-
Mechanical
-
Plumbing
-
Others
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Residential
-
Commercial
-
Industrial
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
Japan
-
India
-
-
Central & South America
-
Middle East & Africa
-
Research Methodology
The fire stopping materials market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each fire stopping materials segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Materials
Revenue capture definition
Sealants
Revenue generated from the sale of fire stopping sealants used to seal joints, gaps, and service penetrations in fire-rated walls and floors. They prevent the passage of fire, smoke, and toxic gases while accommodating structural movement. Sealants are widely used in commercial, residential, and industrial buildings.
Coatings
Revenue generated from the sale of fire stopping coatings applied to cables, structural steel, ducts, and construction elements to improve fire resistance. These coatings expand or insulate under high temperatures, delaying heat transfer and enhancing passive fire protection.
Mortars
Revenue generated from the sale of fire stopping mortars used to seal large openings around cable trays, pipes, and mixed service penetrations. They provide durable, fire-resistant barriers with excellent load-bearing capability and are commonly used in industrial and commercial facilities.
Putty
Revenue generated from the sale of fire stopping putty products used to seal electrical boxes, cable penetrations, and small openings in fire-rated assemblies. Putty remains flexible, allowing easy maintenance and future modifications while maintaining fire protection performance.
Boards
Revenue generated from the sale of fire stopping boards installed to create fire-resistant barriers around large service penetrations, shafts, and compartment walls. These boards offer high fire resistance, thermal insulation, and easy integration with sealants and coatings.
Others
Revenue generated from the sale of other fire stopping materials, including collars, wraps, pillows, blocks, foams, sleeves, and preformed firestop devices. These products provide specialized protection for plastic pipes, cables, ducts, and unique penetration applications.
Segment Application
Revenue capture definition
Electrical
Revenue generated from the use of fire stopping materials for electrical penetrations, including cables, cable trays, conduits, switchboards, and electrical boxes. These systems maintain fire compartment integrity while allowing safe routing of electrical infrastructure.
Mechanical
Revenue generated from the use of fire stopping materials around mechanical systems such as HVAC ducts, ventilation openings, mechanical equipment, and service penetrations. They prevent the spread of fire and smoke through building mechanical networks.
Plumbing
Revenue generated from the use of fire stopping materials for plumbing penetrations, including metal and plastic pipes, drainage systems, and water supply lines. These materials restore the fire resistance of walls and floors where plumbing services pass through.
Others
Revenue generated from fire stopping applications across telecommunications, data cabling, expansion joints, façade systems, and mixed-service penetrations. These applications ensure continuous passive fire protection in specialized building environments.
Segment - End Use
Revenue capture definition
Residential
Revenue generated from the sale of fire stopping materials used in apartments, condominiums, single-family homes, and residential complexes. These products enhance occupant safety by limiting the spread of fire and smoke between rooms and building sections.
Commercial
Revenue generated from the sale of fire stopping materials used in offices, hospitals, hotels, educational institutions, shopping malls, airports, and data centers. Commercial buildings require extensive passive fire protection to comply with stringent building safety regulations.
Industrial
Revenue generated from the sale of fire stopping materials used in manufacturing facilities, oil & gas plants, power generation facilities, chemical plants, warehouses, and other industrial infrastructure. These materials protect critical assets, maintain operational safety, and reduce fire-related risks in high-hazard environments.
Estimation Model
Layer Name
Key Question
Description
Overall Passive Fire Protection Market Assessment
What is the total addressable market for passive fire protection systems?
Estimates the overall market by evaluating demand for passive fire protection products across residential, commercial, industrial, and infrastructure sectors. Construction activity, fire safety regulations, and building stock form the foundation of market sizing.
Fire Stopping Materials Market Identification
What proportion of passive fire protection demand is represented by fire stopping materials?
Determines the share attributable to fire stopping materials by analyzing adoption of sealants, mortars, coatings, boards, putty, collars, wraps, and other firestop products across new construction and retrofit projects.
Segment-Level Revenue Allocation
How is the market distributed across product type, application, and end-use industries?
Allocates revenues across material types (sealants, coatings, mortars, putty, boards, others), applications (electrical, mechanical, plumbing, others), and end-use sectors (residential, commercial, industrial) based on installation intensity and regulatory requirements.
Regional & Company Validation
How are the estimates validated across regions and competitive participants?
Validates market estimates through regional construction activity, fire safety regulations, company revenues, product portfolios, project pipelines, distributor networks, and primary interviews with manufacturers, contractors, distributors, and industry experts to ensure accurate regional and segment-wise market sizing.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Landscape Assessment
Comprehensive profiling of leading fire stopping material manufacturers, including company overview, product portfolio, regional presence, strategic developments, partnerships, acquisitions, R&D initiatives, and competitive benchmarking.
Enables stakeholders to evaluate competitor positioning, identify market leaders and emerging players, benchmark strategic initiatives, and develop effective market entry or expansion strategies.
Product & Application-Level Analysis
Detailed market segmentation by product type (sealants, coatings, mortars, putty, boards, others), application (electrical, mechanical, plumbing, others), and end-use industry (residential, commercial, industrial), along with demand trends and growth opportunities for each segment.
Supports product portfolio optimization, targeted sales strategies, investment prioritization, and identification of high-growth application areas across diverse construction and industrial sectors.
Regional Market Intelligence
In-depth analysis of regional and country-level market dynamics, including construction activity, infrastructure investments, fire safety regulations, adoption trends, competitive landscape, and demand outlook across all major regions.
Helps businesses identify attractive regional opportunities, prioritize expansion plans, optimize resource allocation, and develop region-specific growth strategies based on regulatory and market conditions.
Frequently Asked Questions About This Report
The global fire stopping materials market size was valued at USD 1.5 billion in 2024 and is estimated at USD 1.7 billion for 2026.
The global fire stopping materials market is expected to grow at a CAGR of 8.1% from 2025 to 2030, reaching USD 2.4 billion by 2030.
Based on application type, electrical segment dominated the global fire stopping materials market in 2024 by accounting for a revenue share of 47.2% of the market in the same year. Electrical equipment and wiring can be sources of ignition owing to short circuits, overloads, or equipment malfunctions that can result in fire hazards. Hence, fire stopping materials are largely used in electrical applications type to reduce the risk of fire, thereby ensuring the safety of buildings and their occupants.
Key players operating in the market are Hilti Corporation, 3M, Etex Group, and BASF SE.
The key factors that are driving the fire stopping materials include the flourishing construction industry in emerging economies across the world. Moreover, the rising awareness regarding fire stopping materials among the end-users and the increasing fire safety regulations worldwide are further driving the growth of the market.
About the Author(s)
Green Building Materials Research Team
Advanced Materials · Green Building MaterialsThis report was authored by the green building materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the green building materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


