
- Home
- »
- Paints, Coatings & Printing Inks
- »
-
Flat Glass Coatings Market Size & Share Report, 2026-2033GVR Report cover

Flat Glass Coatings Market (2026 - 2033)
Size, Share & Trends Analysis Report By Resin (PU, Acrylic), By Technology (Water-based, Nano Coatings), By Application (Solar Power, Automotive & Transportation, Mirror), And Segment Forecasts
Market Size, 2025
$4.1BMarket Estimate, 2026
$4.9BMarket Forecast, 2033
$18.1BCAGR, 2026–2033
20.4%Flat Glass Coatings Market Summary
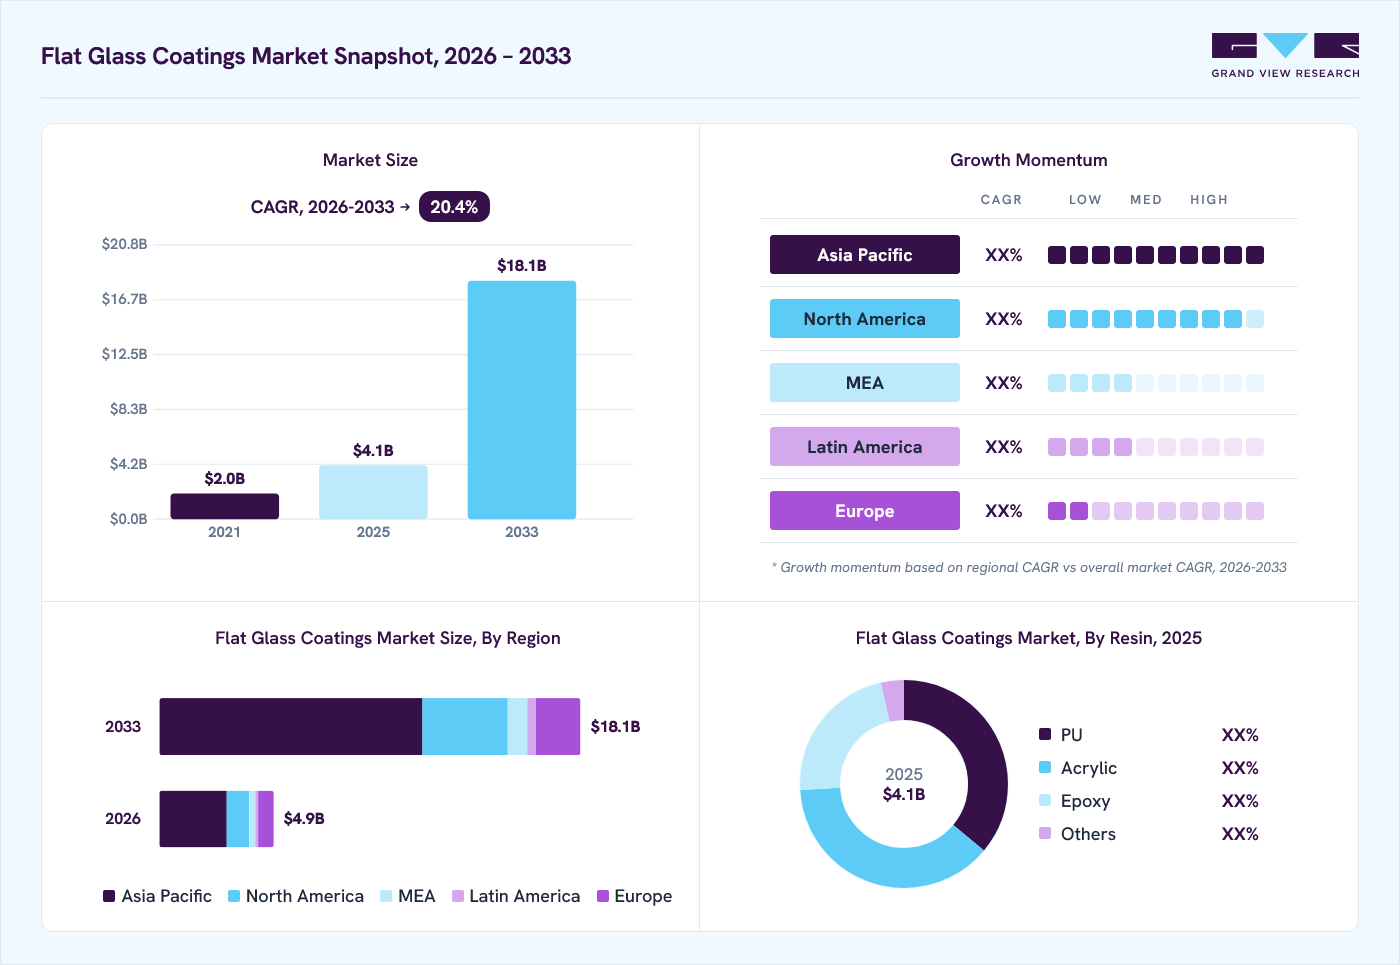
The global flat glass coatings market size was valued at USD 4.1 billion in 2025 and is projected to grow from USD 4.9 billion in 2026 to USD 18.1 billion by 2033, at a CAGR of 20.4% from 2026 to 2033. Asia Pacific dominated the global market, with a revenue share of 58.4% in 2025. Flat glass is widely used in building construction in both the commercial and residential sectors. The tremendous growth in the infrastructural developments across various emerging economies is likely to contribute to the market expansion during the forecast period.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By resin: Acrylic dominated the market with a revenue share of 38.0% in 2025.
- By technology: Water-based held a dominant position, contributing 51.3% of total revenue in 2025.
- By application: Mirror dominated the market with a revenue share of 38.8% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (58.4% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 4.1 Billion
- Estimated market size in 2026: USD 4.9 Billion
- Projected market size by 2033: USD 18.1 Billion
- CAGR (2026-2033): 20.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Rising construction spending on account of rapid urbanization across the globe and infrastructural plans by various governments will continue to augment the market growth, along with more focus on adopting green initiatives to become sustainable. The rapid growth in transport, renewable energy, social & commercial infrastructure, government accommodation, and defense infrastructure is further supporting the market growth. Furthermore, the rising number of green commercial building construction projects, particularly in North America, the Asia Pacific, and MEA regions, is anticipated to fuel product demand during the forecast period.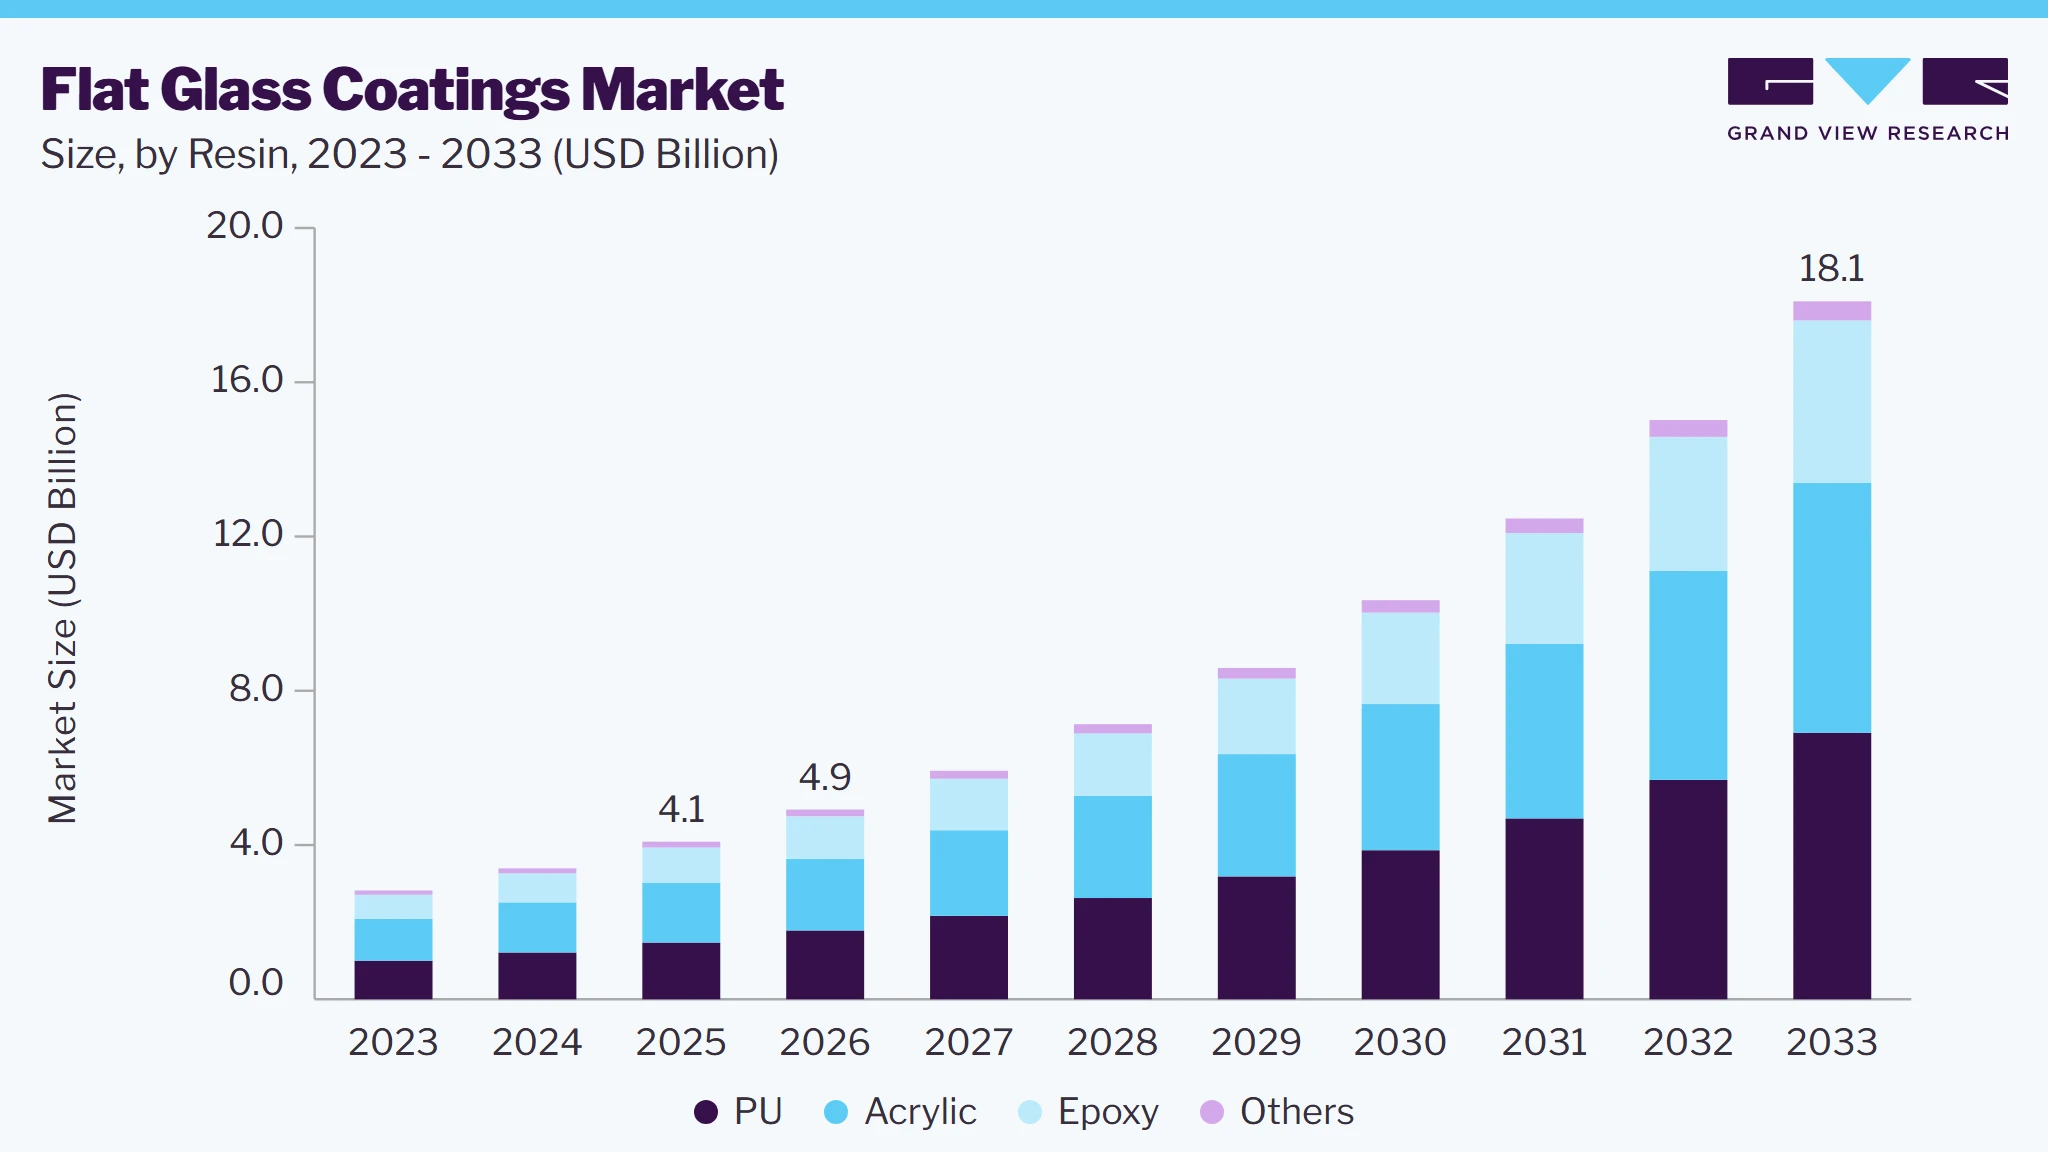 To learn more about this report, Download Free Sample Report
Glass facades are becoming popular, particularly in the commercial building construction sector. Numerous technological innovations in glass technology have improved the overall performance in light transmission, thermal insulation, and modulating solar heat. In addition, innovations, such as double-glazed, solar control, and thermal insulation, have also contributed to the increased product application in buildings.
The global demand for green buildings has grown significantly during the past few years. Green buildings serve various social, environmental, and economic benefits. Flat glass coatings play a vital role in reducing the operational costs of the building. Thus, a rise in the construction of green buildings will directly contribute to market growth.
Water-based coating dominates the overall market, followed by solvent-based coating. Solvent-based coatings emit higher amounts of volatile organic compounds while drying. These compounds can affect the health of individuals constantly exposed to such products. VOCs form the ground-level ozone layer and trap the heat, which leads to global warming. These may cause irritation to the eyes, skin, nose, throat, and respiratory tract. The VOCs emitted can lead to severe ill effects, such as cancer, leukemia, lymphoma, and various other diseases, on human health.
The construction industry has supplemented significant demand in the market. Increasing construction of amusement parks, corporate buildings, hotels, motels, hospitals, schools, and others is likely to supplement the demand for flat glass coatings in the upcoming years. Residential construction in the multi-family and single-family segments is expected to rise owing to increased demand for rental accommodation.
Market Dynamics
The flat glass coatings market is experiencing steady growth driven by increasing demand for energy-efficient buildings, advancements in solar control and low-emissivity (Low-E) glass technologies, and the expanding use of coated glass in automotive and architectural applications. Rising investments in commercial and residential infrastructure, coupled with stringent building energy efficiency regulations, are accelerating the adoption of functional glass coatings that enhance thermal insulation, UV protection, durability, and aesthetics. Furthermore, growing demand for smart buildings and sustainable construction materials continues to support innovation and market expansion.
The growing emphasis on reducing building energy consumption and greenhouse gas emissions is a key driver of the flat glass coatings market. Low-emissivity (Low-E), solar control, and reflective coatings help improve the thermal performance of buildings by minimizing heat transfer while maximizing natural daylight. These coatings reduce heating and cooling costs, enabling compliance with stringent energy-efficiency standards and green-building certification programs. As governments continue to promote sustainable construction through regulatory frameworks and incentive programs, demand for coated flat glass is expected to rise significantly.
In addition, rapid urbanization and increasing investments in commercial complexes, residential buildings, airports, healthcare facilities, and educational institutions are creating sustained demand for high-performance architectural glazing. Building owners and developers are increasingly adopting advanced coated glass solutions to improve occupant comfort, reduce energy consumption, and enhance façade aesthetics. The integration of smart glazing technologies and growing renovation activities in developed economies further strengthen the long-term growth prospects of the flat glass coatings market.
The flat glass coatings market faces challenges due to the high manufacturing and installation costs of advanced coating technologies, such as magnetron-sputtered Low-E and multifunctional coatings. These products require sophisticated deposition equipment, stringent quality control, and skilled processing, increasing production costs compared to conventional glass. Additionally, fluctuations in raw material and energy prices, coupled with the capital-intensive nature of coating facilities, can impact manufacturers' profitability and limit adoption in price-sensitive markets.
The growing adoption of smart glass, photovoltaic glazing, and advanced multifunctional coatings presents significant opportunities for the flat glass coatings market. Increasing investments in net-zero energy buildings, electric vehicles, and next-generation commercial infrastructure are creating demand for coatings that provide energy efficiency, self-cleaning properties, anti-reflective performance, anti-fog functionality, and enhanced durability. Moreover, the expansion of construction activities in emerging economies and ongoing innovations in nanotechnology-based, environmentally friendly coating solutions are expected to unlock new growth opportunities for market participants over the forecast period.
Analyst Perspective
The global flat glass coatings market is experiencing steady growth, supported by increasing demand for energy-efficient glazing solutions across the construction, automotive, solar energy, and specialty glass industries. Rising investments in green buildings, stringent building energy efficiency regulations, and growing adoption of low-emissivity (Low-E), solar control, anti-reflective, and self-cleaning coatings are driving market expansion. Continuous advancements in nanotechnology, multifunctional coating systems, and smart glass technologies are enabling manufacturers to enhance product performance while addressing evolving sustainability requirements. While fluctuations in raw material prices and the capital-intensive nature of advanced coating technologies remain key challenges, ongoing innovation and increasing demand for high-performance coated glass are expected to support long-term market growth. Asia Pacific is anticipated to remain the fastest-growing regional market, driven by rapid urbanization, infrastructure development, expanding automotive production, and increasing investments in renewable energy projects
Technology Insights
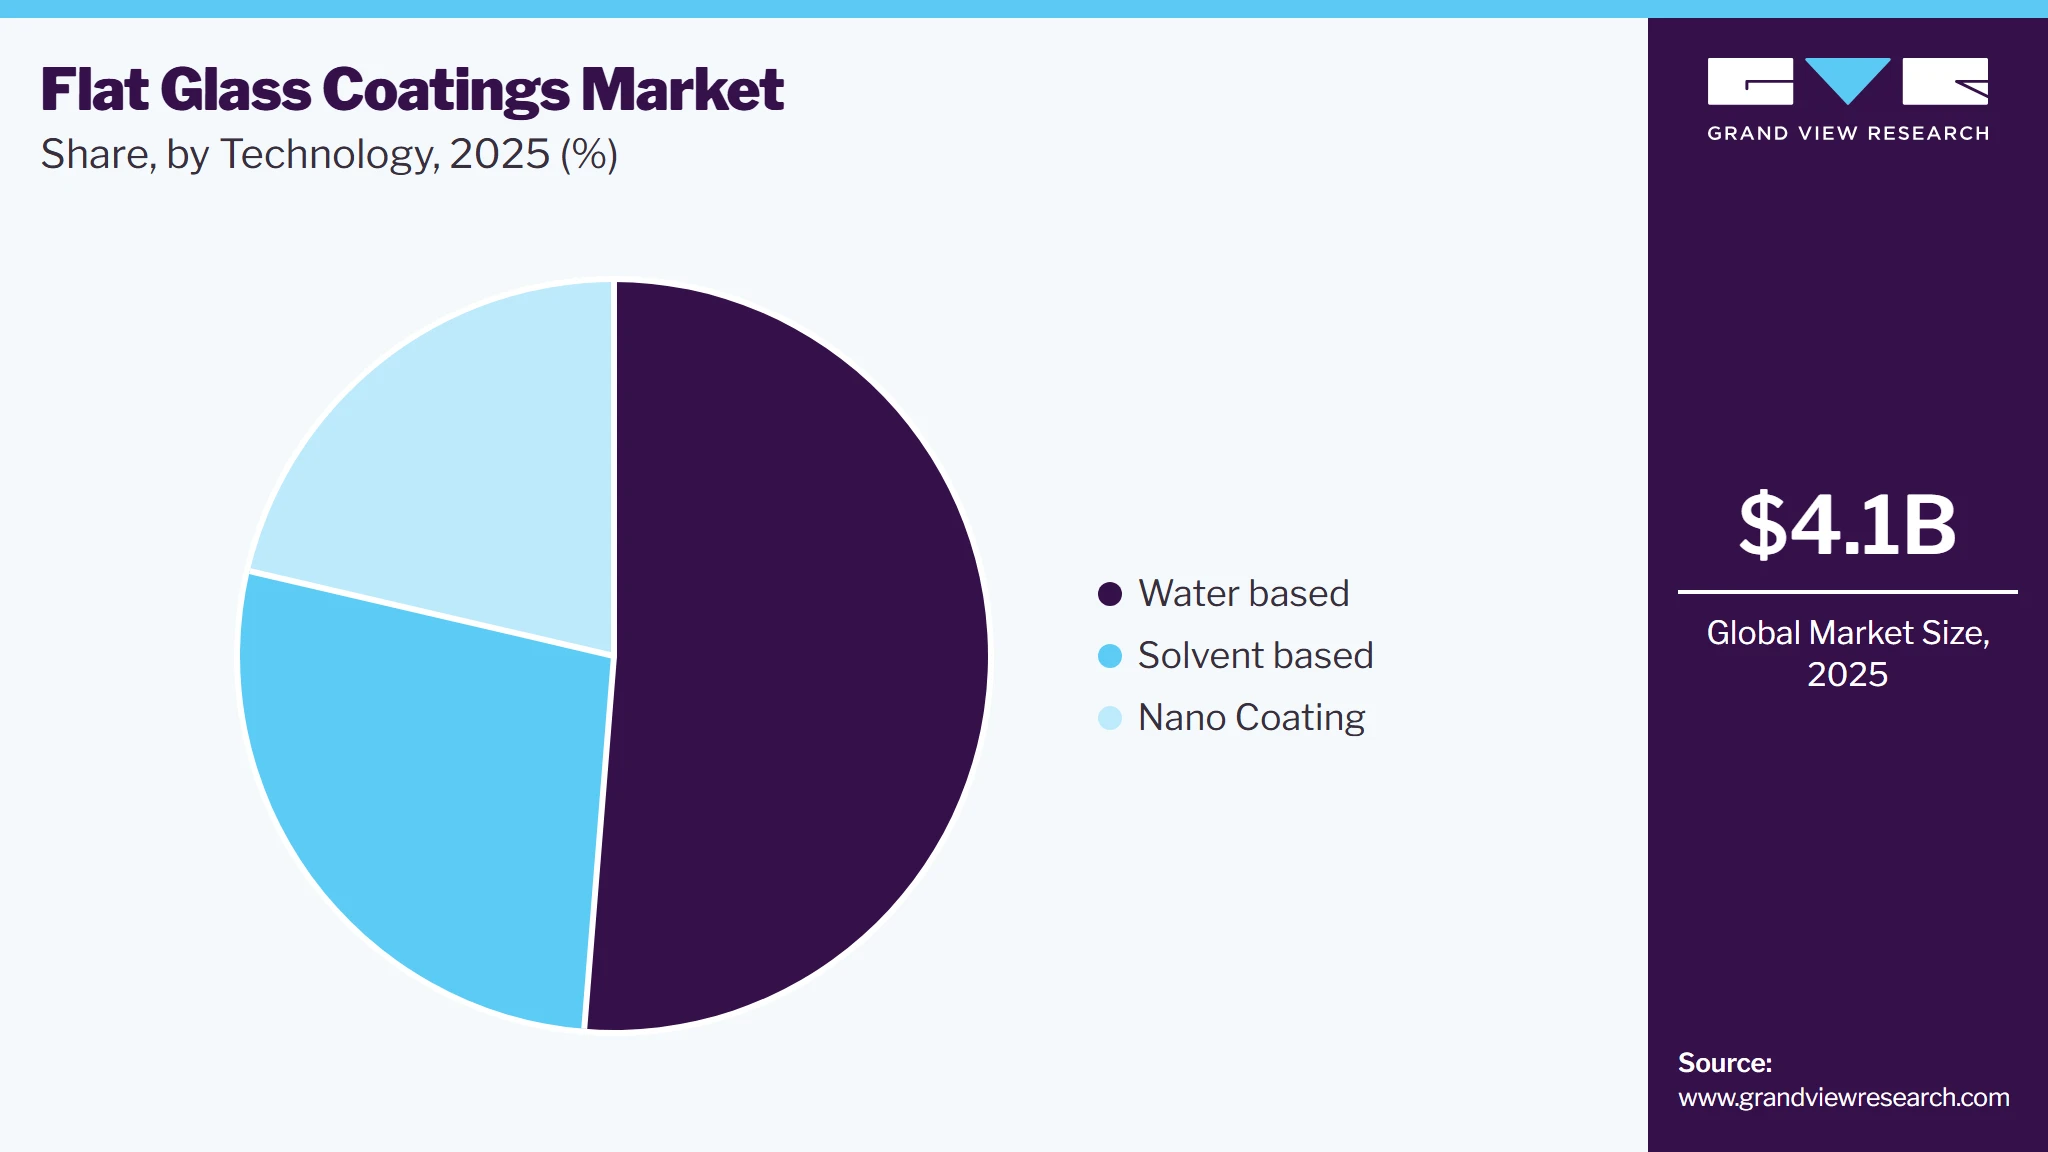
By technology, the water-based held a dominant position, contributing 51.3% of total revenue in 2025. Water-based products contain numerous added advantages over solvent-based products. Solvent-based coatings possess harmful Volatile Organic Compounds (VOCs), which are emitted into the environment. Various regulatory authorities have imposed stringent regulations on the production of solvent-based flat glass coatings.
Nano-based technology is estimated to be the fastest-growing technology segment during the forecast period, driven by ongoing research & development and rising consumer needs. Favorable growth in the automotive and electronics manufacturing sectors is expected to boost the demand for nano-based technology over the coming years.
 To learn more about this report, Download Free Sample Report
Solvent-based flat glass coatings comprise liquefying agents designed to evaporate through a chemical reaction with oxygen. Solvent-based coatings have an added advantage over water-based coatings, as they are less susceptible to environmental conditions, such as humidity and temperature fluctuations. It is widely used in applications such as mirrors, solar panels, and automotive applications.
Solvent-based coating technology is the most conventional technology for manufacturing flat glass coatings. Aliphatic hydrocarbons, lacquer thinner, toluene, and xylene are solvents used in the process of manufacturing. The global solvent market for coatings has undergone a paradigm shift due to adverse effects on the environment because of volatile organic compounds in crude oil-based solvents.
Application Insights
By application, the mirror dominated the market with a revenue share of 38.8% in 2025. Mirrors are widely used in beauty, architectural, automotive, and decorative applications. Moreover, the growing demand for smart mirrors in the global market is likely to drive the market demand for flat glass coatings during the forecast period. The smart mirror acts as an effective substitute for the rear mirror in automobile applications. It offers integrated GPS navigation, a backup camera, and bluetooth connectivity, which aids effectively in driving the vehicle. Smart mirrors are expanding their use across various non-automotive sectors, such as medical consumer goods, advertising, and retail.
On the other hand, the automotive & transportation is anticipated to be the fastest-growing segment in terms of CAGR during the forecast period. Flat glass coatings find numerous applications in the automotive industry owing to their durability & performance efficiency. Strengthening regulations regarding reduced CO2 emissions are further driving the market demand for flat glass coatings in automotive applications.
The OEM automotive coatings and refinish coatings segments are the major drivers of automotive coatings. Increasing automotive production in Brazil, India, China, Mexico & Korea, along with increasing flat glass coatings consumption in major OEMs across the U.S., Japan, U.K., Germany, France & Italy, is a key factor driving the market growth. APAC currently occupies the largest market share for flat glass coatings in automotive applications due to its leading position in automobile production in the world.
Demand for glass coating on solar panels has risen significantly on account of several benefits imparted by them to the overall performance efficiency. These anti-reflective coatings, specially designed for photovoltaic applications, are deposited on a single side. As they are single-sided, they minimize reflections without affecting the adhesion layer or the glass. Thereby, enhancing the overall output. Solvent-based flat glass coating is mostly preferred in solar applications.
Resin Insights
By resin, the acrylic dominated the market with a revenue share of 38.0% in 2025. Bio-based acrylic resins are the most widely used resins due to the high demand for eco-friendly products. Rapid urbanization and industrialization have led to a rise in construction spending in emerging nations, which, in turn, has resulted in the increased demand for acrylic resins in the architectural and industrial sectors.
On the other hand, the Polyurethane (PU) segment accounted for 34.9% of the market revenue share in 2025 and is anticipated to witness the fastest CAGR from 2026 to 2033, driven by the widespread use of PU-based flat glass coatings in solar panels, greenhouses, and other architectural systems. PU resins are used the coat flat glass as a finished coat and are primarily applied over the intermediate and primer coats to achieve a long-term, high-performance coating.
Regional Insights
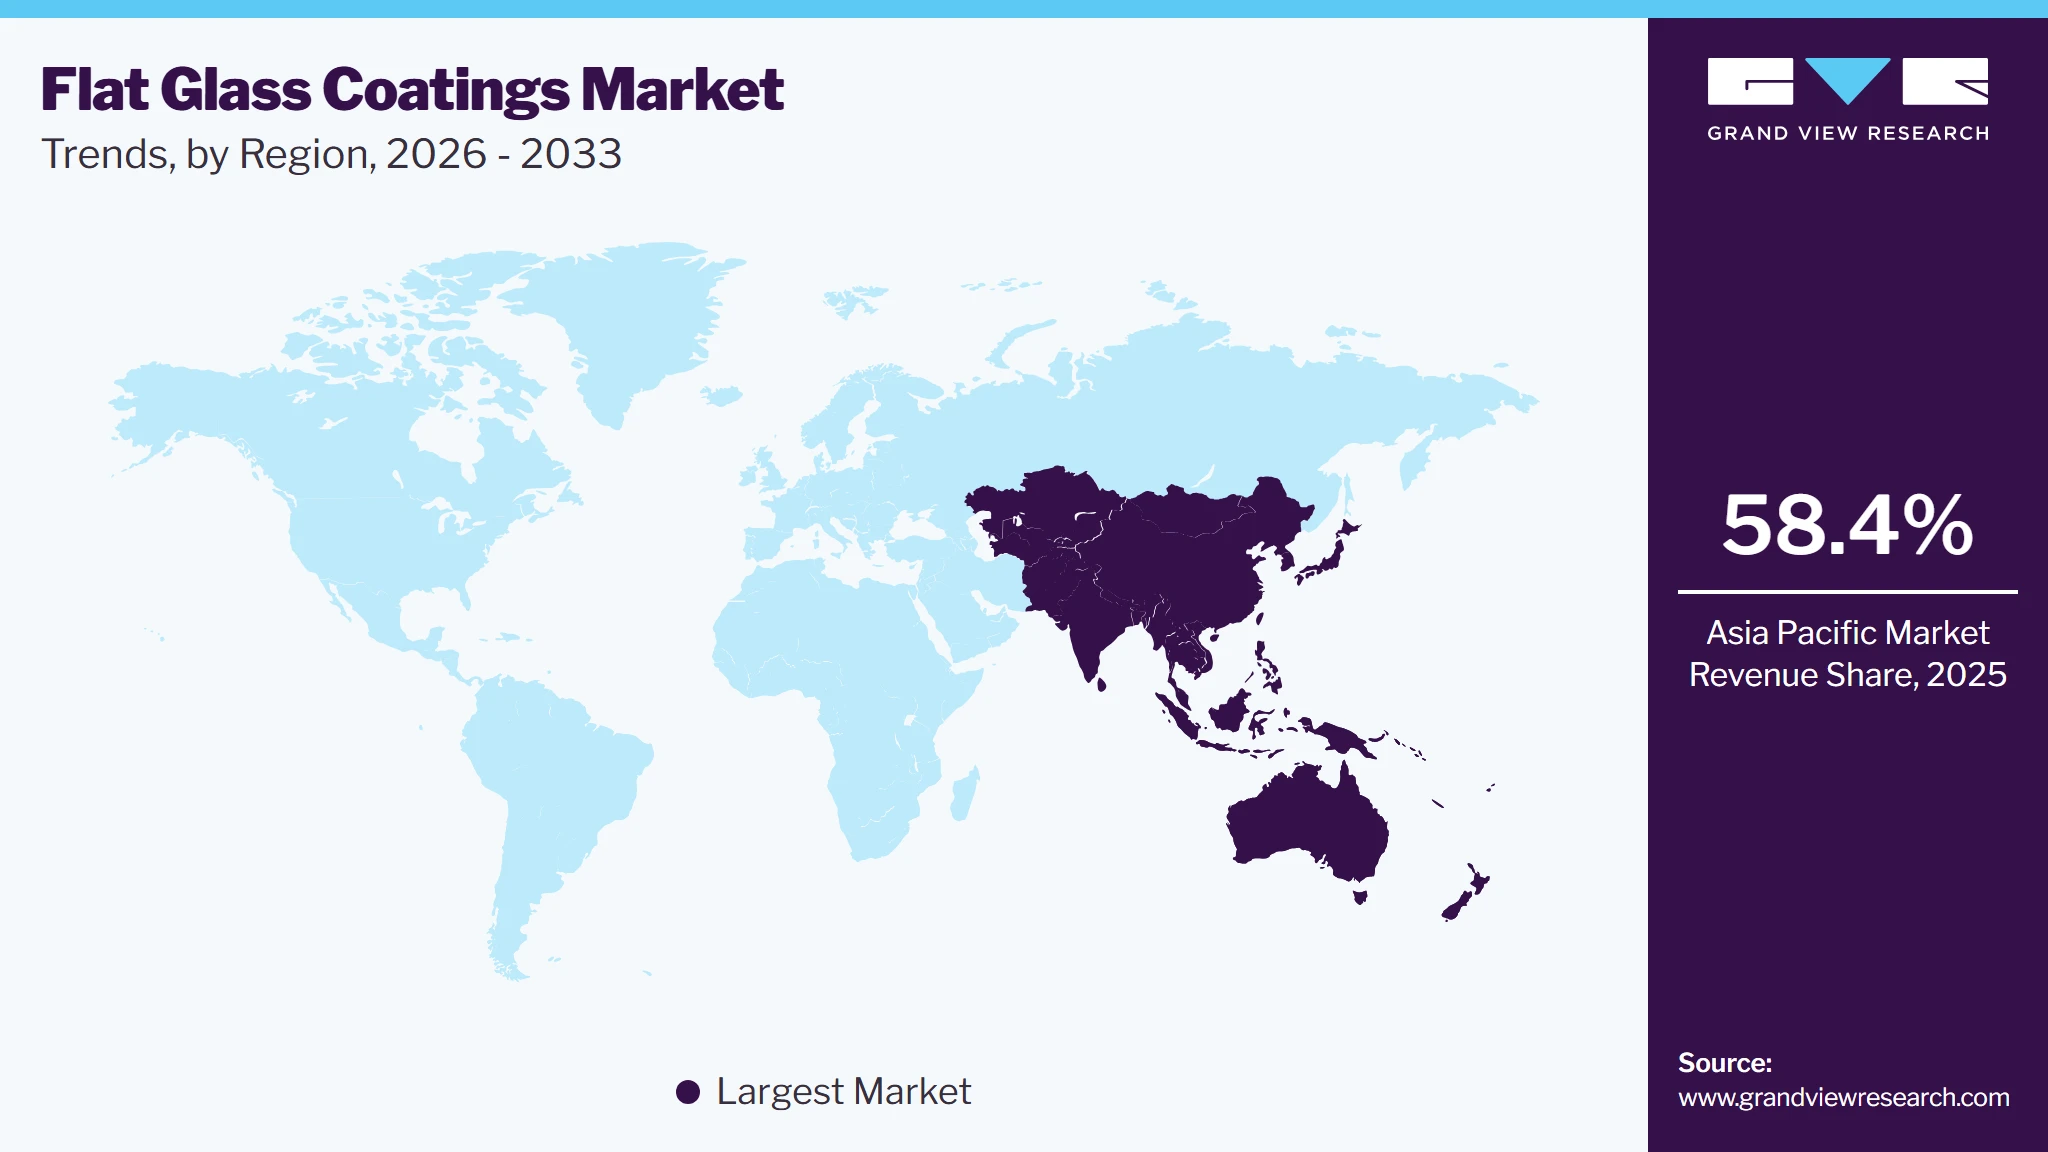
Asia Pacific dominated the flat glass coatings market with the highest revenue share of 58.4% in 2025. Developed economies in APAC, such as China, Australia, South Korea, and Japan, are anticipated to be the major contributors to the regional market growth. Moreover, rapidly developing automobile and construction industries in the region are expected to boost product demand during the forecast period.
 To learn more about this report, Download Free Sample Report
China Flat Glass Coatings Market Trends
China dominated the Asia Pacific flat glass coatings market in 2025, supported by its large flat glass manufacturing base and strong demand from the construction, automotive, and solar energy industries. The country's extensive infrastructure development and growing emphasis on energy-efficient building materials are also supporting the adoption of low-emissivity, solar-control, and other functional coatings for flat glass.
North America Flat Glass Coatings Market Trends
North America is expected to see significant growth in the coming years, driven by increased construction activity and rising demand for energy-efficient, high-performance building materials, particularly in the U.S. and Mexico. In Mexico, ongoing infrastructure investment and urban development are supporting construction activity and creating opportunities for flat glass coatings used in residential, commercial, and infrastructure applications. The country's Infrastructure Investment Plan for Development with Wellbeing 2026–2030 envisages MXN 5.6 trillion in public and mixed investment across strategic sectors, including energy, railways, highways, ports, healthcare, water, education, and airports. Growing urbanization, infrastructure development, and demand for energy-efficient buildings are expected to further support the adoption of coated flat glass across the region.
Key Companies & Market Share Insights
The global flat glass coatings market is highly competitive. Product innovation is likely to open new growth opportunities over the next few years and is also expected to intensify the market competition as manufacturers are focused on increasing their production capacities while widening their product portfolios.
Certain manufacturers have also backward integrated to produce raw materials themselves. This strategy helps lower the logistics costs and procurement hassles in the long run. Rising consumer awareness about the product benefits and manufacturing technologies has compelled suppliers to ensure high-quality levels by integrating themselves into the production. Some prominent players in the global flat glass coatings market include:
Key Flat Glass Coatings Companies:
The following key companies have been profiled for this study on the flat glass coatings market
-
Arkema, Inc.
-
Fenzi Spa
-
Ferro Corp.
-
Hesse Gmbh & Co. KG
-
The Sherwin-Williams Company
-
Vitro S.A.B. De C.V.
-
Nippon Paint Holdings Co., Ltd.
-
Bee Cool Glass Coatings
-
Yantai Jialong Nano Industry Co., Ltd.
-
NanoTech Coatings
-
3M
-
Gulbrandsen
-
Unelko Corporation
-
Apogee Enterprises, Inc.
-
PPG Industries Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Arkema, Inc.; Fenzi S.p.A.; The Sherwin-Williams Company; Nippon Paint Holdings Co., Ltd.; 3M; PPG Industries Inc.; Vitro S.A.B. de C.V.)
- Invest in advanced coating technologies such as low-emissivity (Low-E), solar control, anti-reflective, self-cleaning, and multifunctional coatings.
- Expand manufacturing capacity and regional distribution networks to strengthen global market presence.
- Focus on product innovation through R&D, sustainable coating formulations, and compliance with evolving environmental regulations.
- Establish long-term partnerships with architectural glass manufacturers, automotive OEMs, and solar panel producers to secure recurring demand.
- Extensive global manufacturing footprint and well-established distribution networks.
- Strong financial resources enabling continuous investment in innovation, acquisitions, and production expansion.
- Broad product portfolios serving architectural, automotive, solar, and specialty glass applications.
- Strong brand recognition and long-standing relationships with OEMs and major glass fabricators worldwide.
- Large organizational structures may reduce flexibility in responding to rapidly changing customer requirements.
- Significant capital investment required for advanced coating technologies and manufacturing facilities.
- Exposure to fluctuations in raw material and energy prices may impact profitability.
- Increasing environmental regulations require ongoing investment in low-VOC and sustainable coating technologies.
Emerging / Specialized Players (Bee Cool Glass Coatings; Yantai Jialong Nano Tech Coatings; Hesse GmbH & Co. KG; Gulbrandsen; Unelko Corporation; Apogee Enterprises, Inc.; Ferro Corp.)
- Focus on specialized coating solutions such as nano coatings, energy-efficient coatings, anti-fog, hydrophobic, anti-graffiti, and surface protection technologies.
- Strengthen market presence through niche applications, customized formulations, and regional customer support.
- Expand through strategic collaborations with distributors, glass processors, and construction companies.
- Invest selectively in high-growth segments including smart glass, photovoltaic glazing, and premium architectural coatings
- High operational flexibility enables faster product customization and quicker response to customer requirements.
- Strong expertise in niche coating technologies and specialty surface treatment applications.
- Ability to address emerging customer needs through innovative coating formulations.
- Lean organizational structure supports faster decision-making and targeted market penetration
- Limited production capacity and comparatively smaller global distribution networks restrict large-scale market penetration.
- Lower financial resources may constrain investments in manufacturing expansion and advanced R&D.
- Greater dependence on regional markets and third-party distributors increases commercial risk.
- Limited brand recognition compared with multinational coating manufacturers may affect participation in large infrastructure and OEM projects.
Flat Glass Coatings Market Report Scope
Report Attribute
Details
Market size in 2025
USD 4.1 billion
Estimated market size in 2026
USD 4.9 billion
Projected market size by 2033
USD 18.1 billion
Growth rate
CAGR of 20.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Resin, technology, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; France; U.K.; Turkey; Italy; Netherlands; Belgium; Spain; China; India; Japan; Malaysia; Taiwan; South Korea; Vietnam; Brazil; Chile; Saudi Arabia; South Africa
Key companies profiled
Arkema, Inc.; Fenzi Spa; Ferro Corp.; Hesse Gmbh & Co. KG; The Sherwin-Williams Company; Vitro S.A.B. De C.V.; Nippon Paint Holdings Co., Ltd.; Bee Cool Glass Coatings; Yantai Jialong Nano Industry Co., Ltd.; NanoTech Coatings; 3M; Gulbrandsen; Unelko Corporation; Apogee Enterprises, Inc.; PPG Industries Inc.
Customization scope
Free report customization (equivalent to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Segments Covered in the Report
This report forecasts revenue and volume growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global flat glass coatings market report based on resin, technology, application, and region:
-
Resin Outlook (Volume, Tons; Revenue, USD Million, 2021 - 2033)
-
PU
-
Acrylic
-
Epoxy
-
Others
-
-
Technology Outlook (Volume, Tons; Revenue, USD Million, 2021 - 2033)
-
Solvent-based
-
Water-based
-
Nano-based
-
-
Application Outlook (Volume, Tons; Revenue, USD Million, 2021 - 2033)
-
Solar Power
-
Mirror
-
Architectural
-
Automotive & Transportation
-
Other
-
-
Regional Outlook (Volume, Tons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
U.K.
-
Turkey
-
Italy
-
Netherlands
-
Belgium
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Malaysia
-
Taiwan
-
South Korea
-
Vietnam
-
-
CSA
-
Brazil
-
Chile
-
-
MEA
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The flat glass coatings market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each flat glass coatings segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Resin
Revenue capture definition
Polyurethane
Revenue is generated through the supply of polyurethane-based flat glass coatings that provide superior abrasion resistance, chemical resistance, weatherability, and UV protection. These coatings are widely used in architectural glazing, automotive glass, solar panels, and specialty glazing applications where long-term durability and optical clarity are essential
Acrylic
Business income is derived from acrylic-based coatings used to enhance scratch resistance, transparency, weather resistance, and decorative performance of flat glass. Increasing demand for energy-efficient buildings, interior glazing, mirrors, and commercial facades continues to support market growth for acrylic coating technologies
Epxoy
Sales are generated from epoxy-based flat glass coatings offering excellent adhesion, corrosion resistance, and mechanical strength. These coatings are extensively utilized in industrial glazing, protective glass panels, electronic displays, and transportation applications where high-performance surface protection is required
Other Resin
Commercial value is created through silicone, fluoropolymer, polyester, hybrid resin systems, and other specialty coatings designed for low-emissivity (Low-E), anti-reflective, self-cleaning, anti-fog, conductive, and multifunctional glass applications. Continuous product innovation and increasing adoption of high-performance coated glass across construction, automotive, renewable energy, and electronics industries continue to strengthen market opportunities
Segment - Technology
Revenue capture definition
Solvent Borne
Revenue is generated through solvent-borne coating systems that offer excellent adhesion, rapid curing, and superior durability for industrial and specialty flat glass applications. These coatings are commonly used where high-performance protective properties are prioritized despite increasing environmental regulations
Water-Borne
Business income is derived from environmentally friendly water-borne coating technologies offering reduced VOC emissions while maintaining excellent optical clarity and surface performance. Growing sustainability initiatives and stringent environmental regulations are accelerating adoption across architectural, automotive, and interior glass applications
Nano Coatings
Sales are generated from advanced nanotechnology-based coatings providing self-cleaning, anti-fingerprint, anti-fog, anti-reflective, hydrophobic, oleophobic, and antimicrobial properties. Increasing demand for smart buildings, premium automotive glazing, consumer electronics, and solar energy systems continues to support this high-value segment
Segment - Application
Revenue capture definition
Solar Panel
Revenue is generated through the application of flat glass coatings that improve light transmission, reduce surface reflection, provide self-cleaning properties, and enhance weather resistance of photovoltaic modules. Expanding investments in renewable energy infrastructure continue to drive demand for advanced solar glass coatings
Mirror
Business income is derived from protective coatings applied to mirrors to improve corrosion resistance, moisture protection, scratch resistance, and long-term durability. Growing residential construction, commercial interiors, hospitality, and furniture manufacturing contribute to sustained market demand
Architectural
Sales are supported by the widespread use of flat glass coatings in commercial buildings, residential construction, curtain walls, skylights, facades, and windows. Demand is driven by increasing adoption of Low-E, solar control, anti-reflective, and self-cleaning coatings that improve energy efficiency, occupant comfort, and building aesthetics
Automotive & Transportation
Revenue is generated through coatings used on automotive windshields, side windows, rear glass, sunroofs, rail transport, and specialty transportation glazing. Growing vehicle production, increasing adoption of electric vehicles, and demand for improved visibility, UV protection, and thermal insulation continue to support market growth
Other Applications
Commercial opportunities arise from the use of flat glass coatings in consumer electronics, appliance glass, furniture, display panels, laboratory equipment, healthcare facilities, aerospace glazing, and specialty industrial applications. Diversified end-use industries provide manufacturers with multiple avenues for long-term revenue generation
Estimation Model
Layer Name
Key Question
Description
Raw Material & Production Layer
What forms the supply base?
Assess the global production landscape for flat glass coatings by evaluating the availability of polyurethane resins, acrylic resins, epoxy resins, silicone resins, fluoropolymers, nanoparticles, solvents, pigments, curing agents, additives, and specialty chemicals used in coating formulations. The analysis examines raw material availability, coating technologies, manufacturing capacities, supplier integration, production hubs, and quality standards supporting the global supply of flat glass coatings
Application Adoption Layer
Where is flat glass coatings utilized?
Evaluate adoption across architectural glazing, automotive glass, solar panels, mirrors, consumer electronics, transportation, interior glazing, and specialty industrial applications. Market adoption is driven by increasing demand for energy-efficient buildings, renewable energy installations, premium automotive glazing, smart glass technologies, and sustainable construction practices
Consumption Intensity Layer
How much flat glass coatings is utilized?
Quantify coating consumption by analyzing coated glass production volumes, coating application rates, glazing installation, automotive manufacturing, solar panel production, refurbishment activities, and regional construction trends. The assessment estimates annual coating demand across major end-use industries and regional markets
Revenue Layer
How is market revenue generated?
Market revenue is generated through the formulation, production, application, and commercialization of flat glass coatings supplied to glass manufacturers, architectural glazing companies, automotive OEMs, solar module manufacturers, mirror producers, and industrial fabricators. Commercial performance is influenced by raw material pricing, technological innovation, coating performance, environmental regulations, energy efficiency standards, long-term supply agreements, and expanding adoption across construction, transportation, renewable energy, and specialty industrial applications
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Cross-segmentation
The assessment evaluates market performance across resin type, coating technology, application, end-use industry, and regional markets. It further analyzes demand for polyurethane, acrylic, epoxy, and specialty resin coatings across architectural glazing, automotive & transportation, solar panels, mirrors, and other specialty glass applications while assessing technology adoption for solvent-borne, water-borne, and nano coatings
Supports detailed market evaluation by identifying high-growth coating technologies, understanding application-specific demand, benchmarking regional consumption patterns, and developing targeted product development and market expansion strategies
Pricing Assessment
The study provides comprehensive pricing analysis by evaluating resin costs, specialty chemical inputs, nanoparticle additives, manufacturing economics, coating technology, regional price variations, regulatory compliance costs, and historical pricing trends across major flat glass coating categories
Supports procurement and sourcing decisions by identifying key cost drivers, optimizing supplier negotiations, evaluating regional pricing differences, improving pricing forecasts, and strengthening procurement strategies
Regional Segmentation
The study provides comprehensive country-level analysis across major flat glass coatings markets, covering manufacturing capacity, coating technology adoption, construction activity, automotive production, solar installation trends, regulatory framework, import-export dynamics, pricing trends, and demand across architectural, automotive, renewable energy, and specialty industrial applications
Enables stakeholders to identify high-growth regional markets, benchmark demand across key end-use industries, understand regional regulatory landscapes, evaluate manufacturing ecosystems, and formulate market expansion and investment strategies aligned with country-specific opportunities
Frequently Asked Questions About This Report
The global flat glass coatings market size was valued at USD 4.1 billion in 2025 and is estimated at USD 4.9 billion in 2026.
The global flat glass coatings market is expected to grow at a CAGR of 20.4% from 2026 to 2033, reaching USD 18.1 billion by 2033 by 2033.
Key factors that are driving the flat glass coatings market growth include rising construction spending on account of growing urbanization and infrastructural plans from various governments, and rapid developments in the transport, renewable energy sector.
The acrylic dominated the market with a revenue share of 38.0% in 2025.
Key players include Arkema, Inc., Fenzi Spa, Ferro Corp., Hesse GmBH & Co. KG, The Sherwin-Williams Company, Vitro S.A.B. De C.V., Nippon Paint Holdings Co., Ltd., Bee Cool Glass Coatings, Yantai Jialong Nano Industry Co., Ltd., NanoTech Coatings, 3M, Gulbrandsen, Unelko Corporation, Apogee Enterprises, Inc., and PPG Industries Inc.
The water-based held a dominant position, contributing 51.3% of total revenue in 2025.
The mirror dominated the market with a revenue share of 38.8% in 2025.
Asia Pacific market dominated, with a revenue share of 58.4% in 2025.
About the Author(s)
Paints, Coatings & Printing Inks Research Team
Bulk Chemicals · Paints, Coatings & Printing InksThis report was authored by the paints, coatings & printing inks research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the paints, coatings & printing inks segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


