
- Home
- »
- Plastics, Polymers & Resins
- »
-
Flexible Epoxy Resin Market Size & Share Report 2026-2033GVR Report cover

Flexible Epoxy Resin Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product Type (Urethane Modified, Rubber Modified, Dimmer Acid Modified), By Application (Composites, Adhesives & Sealants, Electrical & Electronics), By Region, And Segment Forecasts
Market Size, 2025
$702.0MMarket Estimate, 2026
$734.2MMarket Forecast, 2033
$1,145.9MCAGR, 2026–2033
7.7%Flexible Epoxy Resin Market Size & Trends
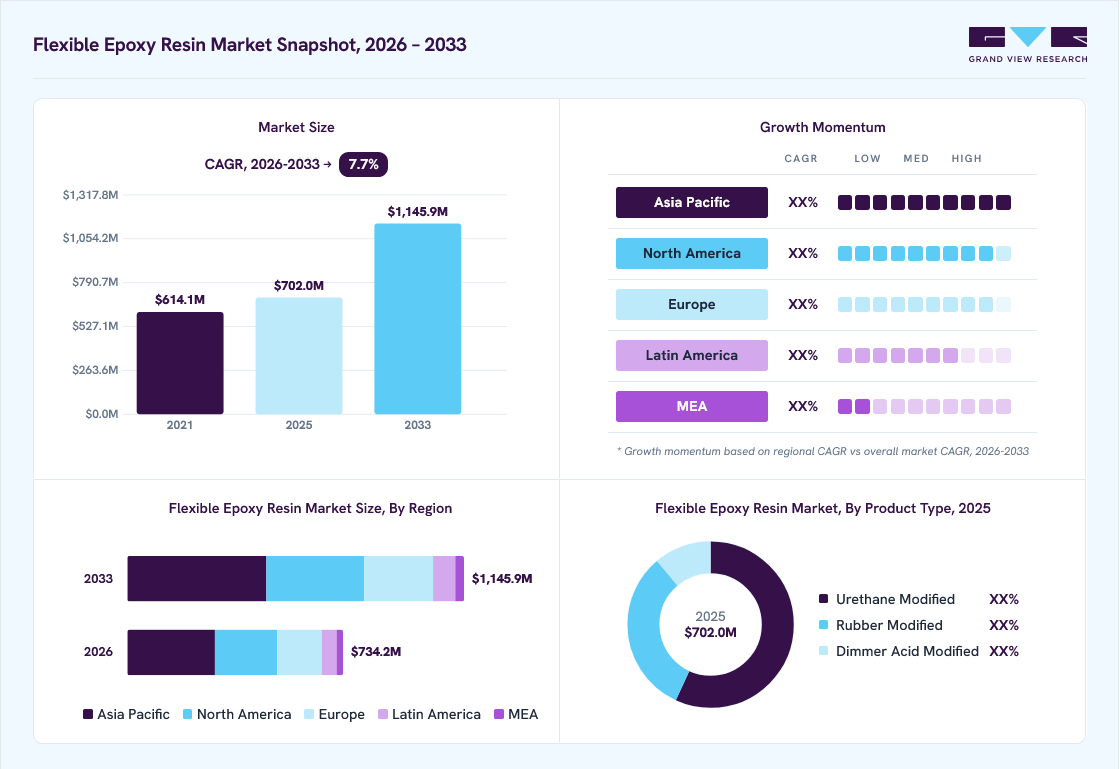
The global flexible epoxy resin market size was valued at USD 702.0 million in 2025 and is projected to grow from USD 734.2 million in 2026 to USD 1,145.9 million by 2033, at a CAGR of 7.7% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 40.5% in 2025. Increasing adoption of lightweight composites and expanding use of flexible epoxy resin across automotive, aerospace, electronics, construction, industrial coatings, and renewable energy applications are driving the flexible epoxy resin market growth.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product type: Urethane modified segment dominated the market, with a revenue share of 56.8% in 2025.
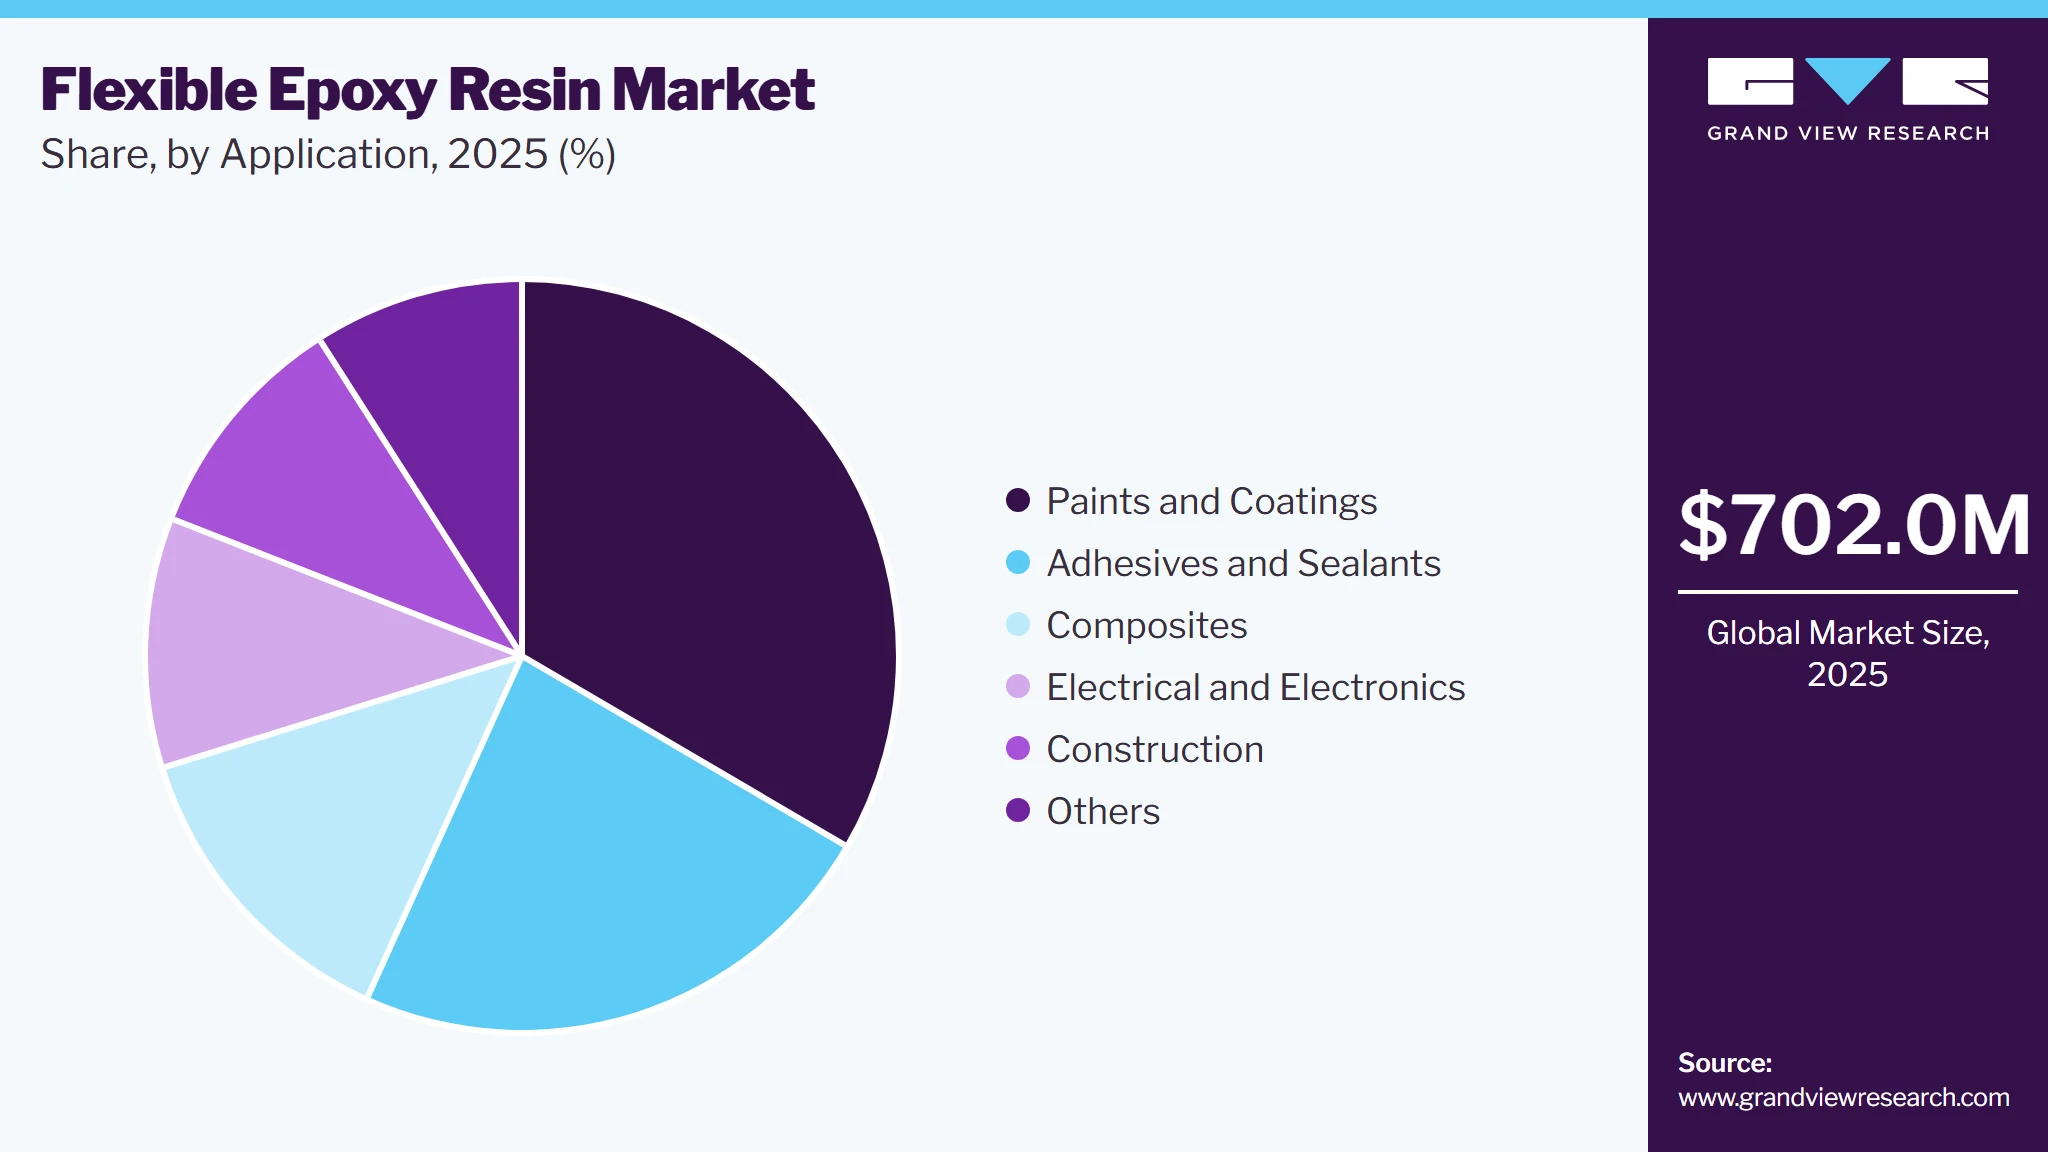
- By application: Paints and coatings segment held the largest market share of 33.4% in 2025.
Regional Highlights
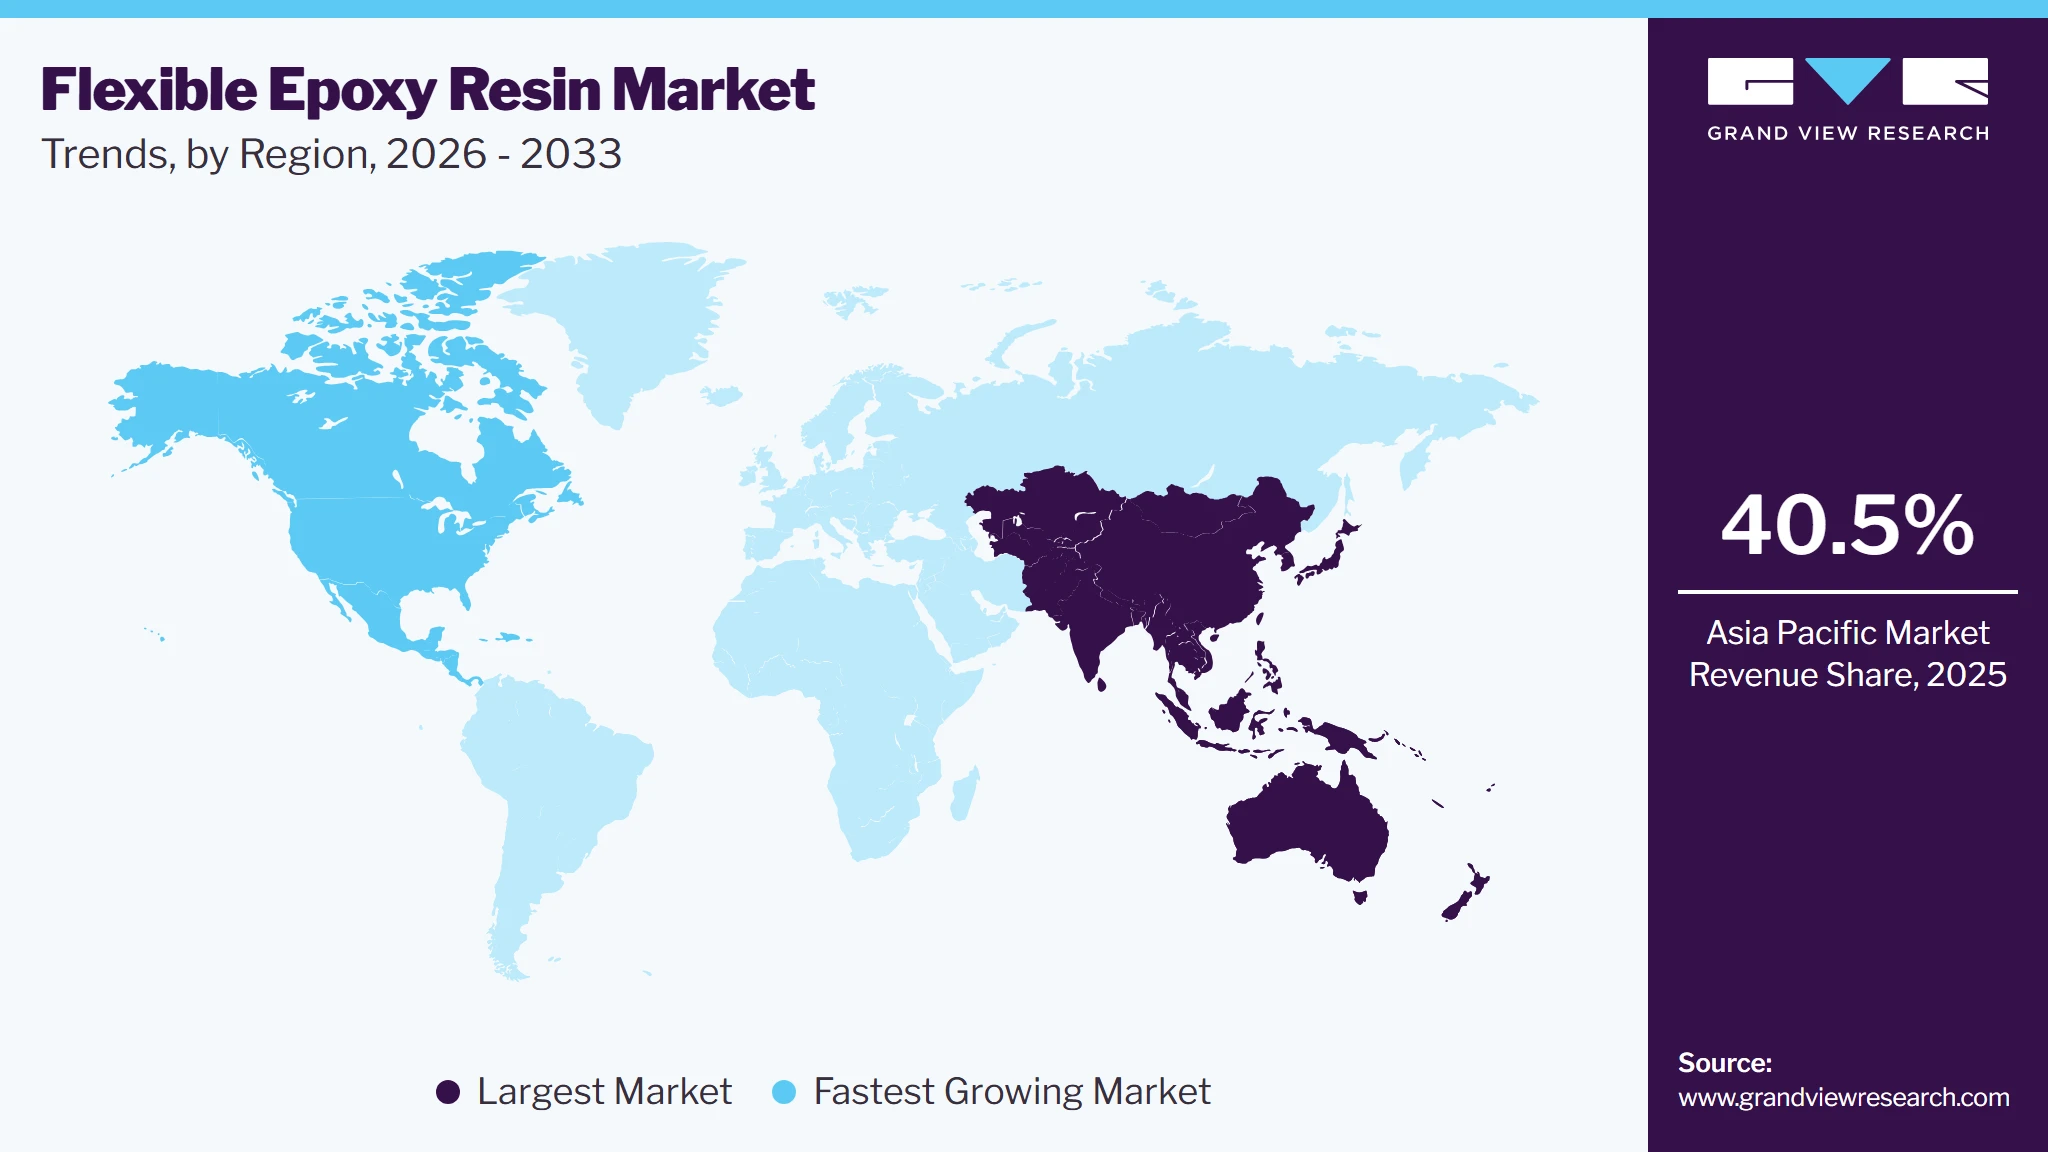
- Largest regional market: Asia Pacific (40.5% revenue share, 2025)
- Fastest-growing regional market: North America (highest CAGR, 2026-2033)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 702.0 Million
- Estimated market size in 2026: USD 734.2 Million
- Projected market size by 2033: USD 1,145.9 Million
- CAGR (2026-2033): 7.7%
Prism AI by Grand View Research Free to tryAsk a question about the flexible epoxy resin marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Rising demand for high-performance adhesive and coating systems further supports market expansion due to their superior adhesion, impact resistance, chemical durability, low-temperature curing capability, and development of low-VOC, sustainable formulations that comply with evolving environmental regulations. The growing need for lightweight, high-performance materials in industries such as automotive, aerospace, and flexible electronics is propelling market growth. Another significant factor is the increasing need for improved adhesive and coating solutions in various sectors. Flexible epoxy resins offer superior adhesion, chemical resistance, and impact strength, making them ideal for protective coatings in industrial applications. In the construction industry, these resins are employed in flooring systems, waterproofing, and repair materials, where they provide long-lasting protection against harsh environmental conditions. Such applications not only extend the life of infrastructure but also reduce maintenance costs, driving market demand further.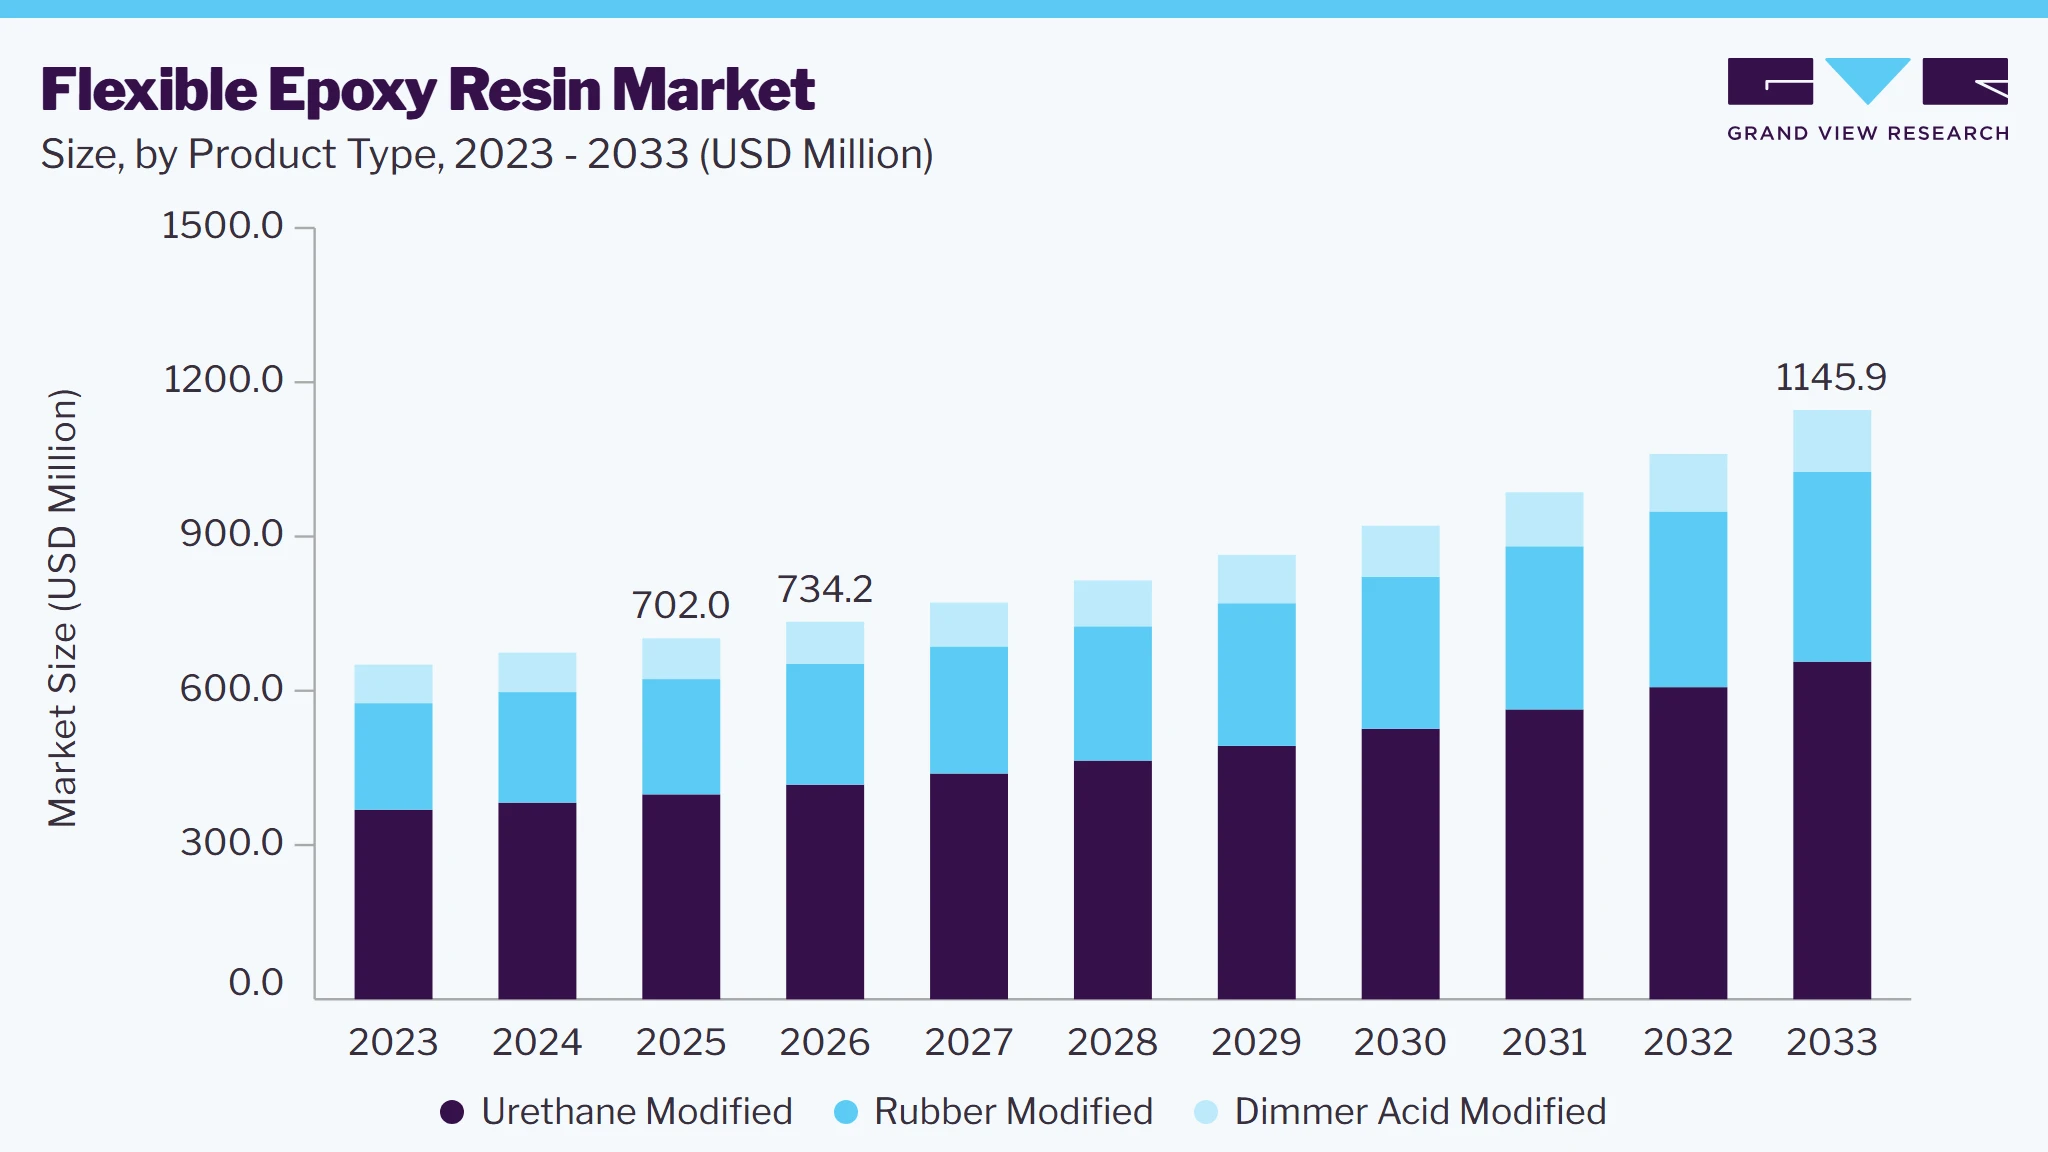 To learn more about this report, Download Free Sample Report
Innovation in resin formulations is also a key contributing factor to market growth. Manufacturers are continually developing new formulations that enhance the flexibility, durability, and environmental resistance of epoxy resins. For example, advancements in polymer chemistry have led to the creation of hybrid epoxy systems that offer improved performance at lower curing temperatures, making them more energy efficient. These innovations have opened new applications in sectors such as electronics and renewable energy, where precise material properties are essential for optimal performance.
Furthermore, regulatory pressures and the global push for sustainability have encouraged the development and adoption of eco-friendly flexible epoxy resins. Industries are increasingly seeking materials that not only perform well but also meet stringent environmental standards. This has led to investments in research and development aimed at reducing volatile organic compounds (VOCs) and incorporating bio-based components into epoxy formulations. As companies strive to reduce their carbon footprint, the market for sustainable, flexible epoxy resins is expected to expand significantly.
Moreover, global economic growth and increased infrastructure spending, particularly in emerging economies, are driving the demand for advanced materials such as flexible epoxy resins. Governments worldwide are investing in modernization projects that require high-performance construction materials, thereby creating a steady demand. As these economies continue to develop, the flexible epoxy resin industry is poised for long-term growth, fueled by ongoing innovation and an expanding range of applications across multiple industries.
Market Dynamics
Flexible epoxy resin demand is driven by the need for high-flexibility, impact-resistant formulations in coatings, adhesives, composites, and electrical applications. The market is shaped by end-use intensity in automotive, aerospace, construction, and electronics, where performance, durability, and process reliability are critical. Regional demand is concentrated in Asia Pacific and North America, supported by manufacturing depth and project-led procurement. Commercially, the market is structured around a limited set of global suppliers, niche formulators, and specialty distributors, with revenue tied to qualification cycles, custom formulation, and application-specific technical support.
The strongest market-specific driver is the rising use of flexible epoxy resin in EV battery packs, lightweight body structures, and bonded composite assemblies. These systems require electrical insulation, crack resistance, and adhesion retention under vibration, thermal cycling, and mechanical stress. Flexible epoxy grades are increasingly specified for battery encapsulation, structural bonding, and composite reinforcement because they reduce brittleness while maintaining usable cure profiles and performance stability.
Demand is also reinforced by aerospace, industrial electronics, and high-performance repair applications that need lower curing temperature, extended pot life, and controlled exotherm. Buyers are shifting toward resin systems that support thinner sections, better processing efficiency, and longer service life in demanding environments. This favors suppliers that can provide formulation support, qualification data, and end-use testing across multiple performance windows.
The market is restrained by the high cost of specialty inputs, formulation complexity, and lengthy qualification cycles. Flexible epoxy resin is rarely a plug-and-play material in aerospace, electronics, or infrastructure repair. Buyers require repeatable cure behavior, low yellowing, stable adhesion, and consistent flexibility, which increases testing time and raises conversion costs. Smaller producers often struggle to meet these thresholds at scale, while larger suppliers face margin pressure in project-based and application-specific sales. Competition from lower-cost Asia Pacific suppliers further tightens pricing in standard grades.
The clearest opportunity lies in low-VOC, low-yellowing, and lower-exotherm formulations for coatings, electronics, and repair systems. Customers are looking for cleaner chemistries that improve appearance, ease of application, and compliance with environmental requirements. Suppliers that pair sustainability with measurable performance gains can shift demand from commodity resin supply to higher-value specialty systems.
Analyst Perspective
Over the next 5 to 10 years, the flexible epoxy resin market is likely to move from conventional volume-led supply toward value-led specialty formulation. Demand will be anchored by EV battery encapsulation, lightweight composites, aerospace repair, industrial coatings, and electronics packaging, where buyers increasingly prioritize low yellowing, lower exotherm, fatigue resistance, and stable insulation over resin price alone. Sustainability will become a procurement filter as customers push for low-VOC and cleaner chemistries, while regulatory scrutiny and qualification standards will reward suppliers with strong testing data, formulation breadth, and application support. At the same time, raw material volatility and cost-based competition from Asia Pacific suppliers will continue to compress margins in standard grades. Leaders will be differentiated by integration, regional manufacturing presence, technical service, partnerships with converters and end users, and the ability to commercialize application-specific specialty systems rather than broad commodity epoxy grades.
Product Type Insights
Based on product type, the urethane modified segment led the market with the largest revenue share of 56.8% in 2025. Urethane-modified flexible epoxy resins combine the toughness of urethane with the adhesion and chemical resistance of epoxy, making them ideal for applications requiring flexibility and impact resistance. These resins are widely used in coatings, adhesives, and composite materials where enhanced durability and flexibility are critical, such as automotive, aerospace, and construction industries.
The rubber modified segment is projected to grow at the fastest CAGR of 5.7% during the forecast period. Rubber-modified epoxy resins incorporate elastomers to improve impact resistance, flexibility, and toughness while maintaining good adhesion properties. These resins are particularly used in structural adhesives, protective coatings, and high-performance composites, offering excellent crack resistance and vibration absorption in applications like electronics, marine, and industrial flooring.
Application Insights
Based on application, the paints and coatings segment led the market with the largest revenue share of 33.4% in 2025. The demand for flexible epoxy-based paints and coatings is driven by increasing industrialization and infrastructure development. Growth in the automotive and aerospace sectors, where protective coatings are crucial, further boosts market expansion. In addition, the rising focus on environmentally friendly coatings with low VOC emissions is promoting the adoption of epoxy-based formulations.
 To learn more about this report, Download Free Sample Report
The electrical & electronics segment is anticipated to grow at the fastest CAGR of 6.5% during the forecast period. The electrical and electronics industry extensively utilizes flexible epoxy resins in encapsulation, potting, and insulation applications. Their electrical insulating properties, along with resistance to moisture and high temperatures, make them suitable for printed circuit boards (PCBs), transformers, and semiconductor packaging. The miniaturization trend in the electronics industry and the growing demand for reliable, high-performance electronic components are key factors driving the adoption of flexible epoxy resins, thus benefiting the segment growth in the market.
Region Insights
The flexible epoxy resin market in North America is anticipated to grow at the fastest CAGR during the forecast period. The region's strong presence in aerospace and automotive manufacturing plays a crucial role in driving the market growth in the region. Companies such as Boeing, Lockheed Martin, General Motors, and Ford extensively use flexible epoxy resins in their manufacturing processes. Moreover, the construction and infrastructure sector in North America significantly contributes to market growth. With ongoing infrastructure renovation projects and the increasing adoption of green building practices, flexible epoxy resins are in high demand for applications such as floor coatings, bridge deck overlays, and concrete repair.
U.S. Flexible Epoxy Resin Market Trends
The flexible epoxy resin market in the U.S. is growing particularly due to its expansive use in aerospace, automotive, and construction sectors, backed by robust R&D and cutting-edge innovations from firms such as 3M and Hexion Inc. Automotive companies such as Tesla and Ford are incorporating flexible epoxy resins in electric vehicle battery encapsulation and lightweight body components. The shift toward electric vehicles has particularly accelerated this trend, as flexible epoxy resins provide excellent electrical insulation while maintaining the necessary mechanical properties.
Asia Pacific Flexible Epoxy Resin Market Trends
Asia Pacific dominated the flexible epoxy resin market with the largest revenue share of 40.5% in 2025. The region's robust manufacturing sector, particularly in countries such as China, Japan, Southeast Asia, and India, has created substantial demand for flexible epoxy resins. For instance, major electronics manufacturers such as Samsung, Sony, and Foxconn rely heavily on flexible epoxy resins to ensure their products' durability and performance in varying environmental conditions.
 To learn more about this report, Download Free Sample Report
The flexible epoxy resin market in China accounted for the largest market revenue share in the Asia Pacific in 2025. The China flexible epoxy resin market is primarily driven by its massive manufacturing sector, particularly in the electronics, automotive, and construction industries, which drives substantial demand for flexible epoxy resins. Besides, the rapid expansion of a country’s renewable energy sector, especially wind power, has significantly boosted the demand for flexible epoxy resins in the country. For instance, wind turbine blade manufacturing requires large quantities of these resins due to their excellent fatigue resistance and ability to withstand extreme weather conditions. Major wind turbine manufacturers such as Goldwind and Envision have established extensive production facilities in China, creating a robust supply chain for epoxy resin applications.
Europe Flexible Epoxy Resin Market Trends
The flexible epoxy resin market in Europe growth can be attributed to the region's robust industrial infrastructure, particularly in countries such as Germany, France, and Italy. These nations have well-established automotive, aerospace, and construction sectors that extensively use flexible epoxy resins in various applications, from composite materials to protective coatings. Besides, Europe's stringent environmental regulations and sustainability initiatives are triggering the demand for flexible epoxy resin in the region. The EU's REACH regulations and emphasis on reducing volatile organic compounds (VOC) emissions have pushed manufacturers to develop and adopt more environmentally friendly flexible epoxy resins.
The Germany flexible epoxy resin market is primarily driven by its robust automotive sector, which serves as the backbone of demand for flexible epoxy resin. Germany, being home to major automotive manufacturers such as BMW, Mercedes-Benz, Volkswagen, and Audi, extensively uses flexible epoxy resins in various applications - from composite materials for lightweight vehicle components to high-performance adhesives for structural bonding. For example, these resins are crucial in manufacturing carbon fiber reinforced plastics (CFRP) used in electric vehicle battery enclosures and structural components.
Key Flexible Epoxy Resin Company Insights
The global flexible epoxy resin industry exhibits intense competition among both established manufacturers and emerging players. Key industry players dominate significant market share through their extensive product portfolios, strong R&D capabilities, and established distribution networks. These companies frequently engage in strategic initiatives such as mergers, acquisitions, and product innovations to maintain their competitive edge.
The market is experiencing increased competition from Asia Pacific manufacturers, particularly from China and India, who are leveraging cost advantages and expanding their presence in international markets. Companies are also focusing on developing eco-friendly and sustainable flexible epoxy resin formulations to address growing environmental concerns and stringent regulations, which have become a key differentiator in the competitive landscape.
Key Flexible Epoxy Resin Companies:
The following key companies have been profiled for this study on the flexible epoxy resin market.
-
Conren Limited
-
DIC Corporation
-
Dow
-
Easy Composites
-
EPOXONIC
-
Hexion
-
INTERTRONICS
-
KUKDO Chemical (Kunshan) Co., Ltd.
-
LymTal International, Inc.
-
Mereco Technologies
-
Nan Ya Plastic Corporation
-
Olin Corporation
-
Resintech Limited
-
Sicomin Epoxy Systems
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (DIC Corporation; Dow; Hexion; KUKDO Chemical (Kunshan) Co., Ltd.; Nan Ya Plastic Corporation; Olin Corporation)
- Maintain broad product portfolios across coating, adhesive, and composite grades.
- Use direct sales, technical service, and qualification support to lock in end users.
- Invest in formulation upgrades and downstream application development.
- Strong brand credibility and global customer access.
- Better R&D depth and formulation breadth.
- More resilient position in regulated and high-specification applications.
- Higher overhead and compliance cost base.
- Slower response to niche customer requests.
- Greater exposure to price pressure in standard grades.
Emerging Players (Conren Limited; Easy Composites; EPOXONIC; INTERTRONICS; LymTal International, Inc.; Mereco Technologies; Resintech Limited; Sicomin Epoxy Systems)
- Focus on niche segments and application-specific systems.
- Use distributor-led sales, technical content, and direct customer engagement.
- Compete through customization, service, and fast product adaptation.
- Faster formulation cycles and stronger customer intimacy.
- Better agility in niche or low-volume requirements.
- Clear positioning in specialized end-use pockets.
- Limited scale and narrower geographic coverage.
- Lower bargaining power on raw materials and logistics.
- Weaker global brand recognition in large procurements.
Recent Developments
-
In April 2024, Westlake Corporation announced the launch of several innovative lower yellowing epoxy products at the American Coatings Show 2024, Indianapolis, Indiana. Among these is the Deep Pour Lower Yellowing Epoxy System, which combines Epoxy Research Resin RSL-4710 with Research Curing Agent RSC-4731. This advanced two-component system is designed for extended set times and lower exotherm temperatures, enabling easier application with pours of up to four inches in a single use.
-
In May 2023, Huntsman announced the development of innovative materials aimed at enhancing battery performance and protection, particularly for electric vehicles (EVs). The product portfolio includes polyurethane, carbon nanotube, and epoxy materials. These are intended to create high-performance composite battery structures, offering both design flexibility and production efficiency.
Flexible Epoxy Resin Market Report Scope
Report Attribute
Details
Market size in 2025
USD 702.0 million
Estimated market size in 2026
USD 734.2 million
Projected market size by 2033
USD 1,145.9 million
Growth rate
CAGR of 7.7% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product type, application, region
RegioFinal scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; France; UK; Italy; Spain; China; India; Japan; Australia; Southeast Asia; Brazil; Argentina; South Africa; Saudi Arabia; UAE
Key companies profiled
Conren Limited; DIC Corporation; Dow; Easy Composites; EPOXONIC; Hexion; INTERTRONICS; KUKDO Chemical (Kunshan) Co., Ltd.; LymTal International, Inc.; Mereco Technologies; Nan Ya Plastic Corporation; Olin Corporation; Resintech Limited; Sicomin Epoxy Systems
Customization scope
Free report customization (equivalent to up to 8 analysts' working days) with purchase-addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Flexible Epoxy Resin Market Report Segmentation
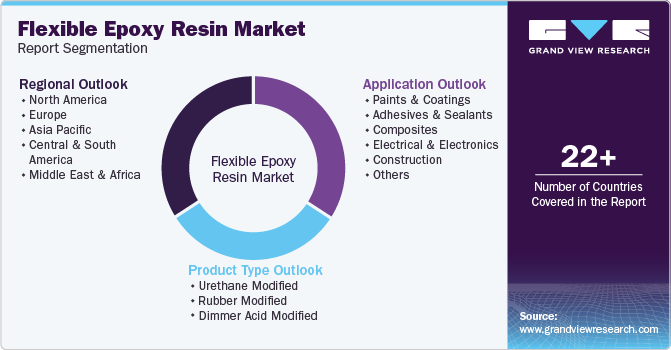
This report forecasts revenue growth at a global level and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global flexible epoxy resin market report based on product type, application, and region:
 To learn more about this report, Download Free Sample Report
-
Product Type Outlook (Revenue, USD Million, Volume, Kilotons; 2021 - 2033)
-
Urethane Modified
-
Rubber Modified
-
Dimmer Acid Modified
-
-
Application Outlook (Revenue, USD Million, Volume, Kilotons; 2021 - 2033)
-
Paints and Coatings
-
Adhesives and Sealants
-
Composites
-
Electrical and Electronics
-
Construction
-
Others
-
-
Region Outlook (Revenue, USD Million, Volume, Kilotons; 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
UK
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
Southeast Asia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
-
Research Methodology
The flexible epoxy resin market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each flexible epoxy resin segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product Type
Revenue capture definition
Urethane Modified
Revenue is captured through premium flexible epoxy grades sold into coatings, structural adhesives, and composites where toughness, impact resistance, and flexibility are required together.
Rubber Modified
Revenue is captured from epoxy systems modified with elastomeric phases to improve crack resistance, vibration tolerance, and fatigue performance in industrial and electrical uses.
Dimmer Acid Modified
Revenue is captured from specialty resin sales where improved wetting, balanced flexibility, and lower rigidity are required for coatings, sealants, and repair formulations.
Segment - Application
Revenue capture definition
Paints and Coatings
Revenue is captured from protective, decorative, and industrial coating systems that use flexible epoxy resin for adhesion, chemical resistance, and service-life extension.
Adhesives and Sealants
Revenue is captured from bonding and sealing formulations sold for structural assembly, repair, and gap-filling applications where elasticity and durability matter.
Composites
Revenue is captured from resin systems supplied into composite layups and reinforcement structures that require toughness, crack resistance, and processing stability.
Electrical and Electronics
Revenue is captured from encapsulation, potting, insulation, and circuit-related formulations where flexibility, dielectric performance, and thermal stability are key.
Construction
Revenue is captured from flooring, waterproofing, overlays, and repair materials used in infrastructure where movement tolerance and long-term adhesion are required.
Others
Revenue is captured from niche uses such as marine, tooling, maintenance, and specialty industrial formulations that do not fit the core end-use buckets.
Estimation Model
Layer Name
Key Question
Description
Demand Layer
Where does demand originate?
Measures end-use pull from coatings, adhesives, composites, electronics, and construction, where qualification and project wins determine revenue recognition.
Product Mix Layer
Which products generate revenue?
Separates urethane, rubber, and dimmer acid grades to reflect pricing dispersion, application fit, and margin contribution across the product portfolio.
Regional Layer
Which regions drive growth?
Allocates revenue by Asia Pacific, North America, Europe, and other regions to capture manufacturing concentration, procurement patterns, and supply access.
Supplier Layer
Who captures market revenue?
Reconciles producer sales, distributor throughput, and specialty converter demand to avoid double-counting in a fragmented, project-based market structure.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Expand country scope to key manufacturing hubs
Add a country-level split across major manufacturing markets and align each geography with dominant end uses, procurement behavior, and application intensity. The report structure remains intact while regional commentary becomes more commercial and actionable.
Improves regional prioritization and supports sharper sales and market entry decisions.
Add competitive benchmarking by company tier
Insert a tiered competitor view that separates large integrated suppliers from niche formulators using operating strategy, technical depth, and channel reach. The comparison is aligned with market revenue pools and core application segments.
Helps identify leadership gaps and adjacency opportunities.
Deepen end-use application commentary
Expand each application segment with revenue-capture logic, qualification drivers, and buyer requirements. This makes the segmentation more reflective of how flexible epoxy resin revenue is won across coatings, composites, electronics, and construction.
Strengthens commercial clarity and report usability.
Frequently Asked Questions About This Report
The Asia Pacific flexible epoxy resin market accounted for the largest share of 40.5% market size in 2025.
North America is the fastest-growing region over the forecast period.
Based on application, the paints and coatings segment accounted for the largest share of 33.4% market size in 2025. Growing infrastructure development, automotive and aerospace production, and industrial manufacturing, together with advances in low-VOC and waterborne technologies, are accelerating organosilicon polymer coating adoption for durable, high-performance surface protection applications.
Increasing adoption of lightweight composites and expanding use of flexible epoxy resin across automotive, aerospace, electronics, construction, industrial coatings, and renewable energy applications are driving the flexible epoxy resin market growth. Rising demand for high-performance adhesive and coating systems further supports market expansion due to their superior adhesion, impact resistance, chemical durability, low-temperature curing capability, and development of low-VOC, sustainable formulations that comply with evolving environmental regulations.
The flexible epoxy resin market is expected to grow at a CAGR of 7.7% from 2026 to 2033, reaching USD 1,145.9 million by 2033.
The key players in the flexible epoxy resin market are Conren Limited; DIC Corporation; Dow; Easy Composites; EPOXONIC; Hexion; INTERTRONICS; KUKDO Chemical (Kunshan) Co., Ltd.; LymTal International, Inc.; Mereco Technologies; Nan Ya Plastic Corporation; Olin Corporation; Resintech Limited; Sicomin Epoxy Systems
The flexible epoxy resin market size was valued at USD 702.0 million in 2025 and is estimated at USD 734.2 million for 2026.
The urethane-modified flexible epoxy resin industry led the flexible epoxy resin market in 2025 with a 56.8% share.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


