
- Home
- »
- Consumer F&B
- »
-
Frozen Dough Market Size, Share Report, 2026-2033GVR Report cover

Frozen Dough Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Bread, Biscuits & Cookies, Pizza), By Distribution Channel (Retail, Food Service), By Region (Europe, APAC, North America), And Segment Forecast
Market Size, 2025
$25.6BMarket Estimate, 2026
$26.9BMarket Forecast, 2033
$38.1BCAGR, 2026–2033
5.1%Frozen Dough Market Summary
The global frozen dough market size was valued at USD 25.6 billion in 2025 and is projected to grow from USD 26.9 billion in 2026 to USD 38.1 billion in 2033, at a CAGR of 5.1% from 2026 to 2033. North America dominated the market, accounting for the largest revenue share of 39.5% in 2025. The key factor driving the industry is the rising consumption of bakery products across the globe, leading to an increased demand for frozen doughs as they are convenient and easy to prepare.
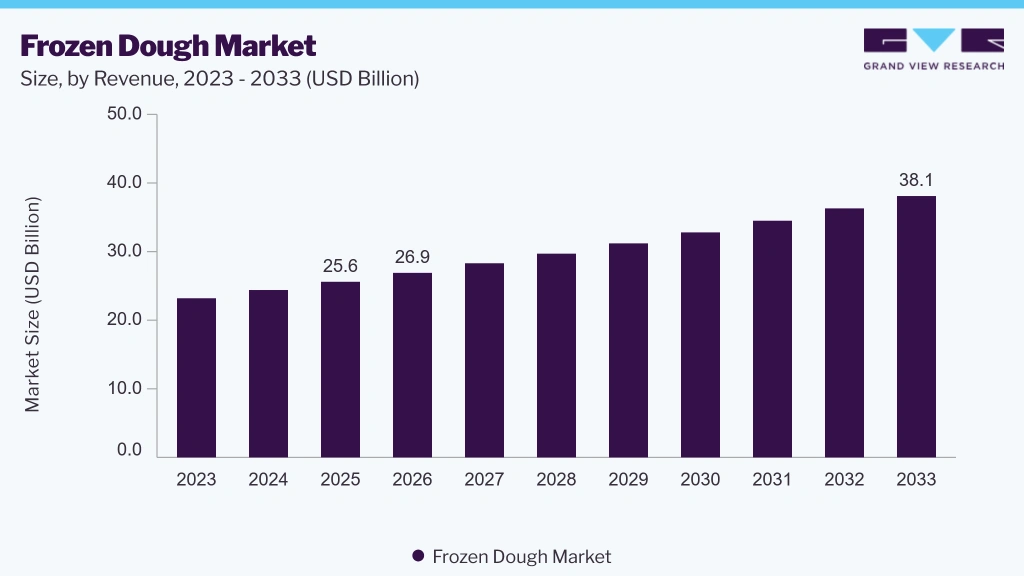 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: The bread segment held the largest revenue share of more than 37.0% in 2025.
- By distribution channel: The food services segment held the largest revenue share of more than 67.0% in 2025.
Regional Highlights
- Largest regional market: North America (39.5% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (Fastest CAGR, 2021-2033)
Market Size & Forecast
- Market size in 2025: USD 25.6 Billion
- Estimated market size in 2026: USD 26.9 Billion
- Projected market size by 2033: USD 38.1 Billion
- CAGR (2026-2033): 5.1%
Prism AI by Grand View Research Free to tryAsk a question about the frozen dough marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →In addition, as the processed food industry continues to expand globally, the frozen dough market is witnessing steady growth. Frozen dough products offer an extended shelf life, reduce preparation time, minimize food waste, and improve operational efficiency for both consumers and foodservice operators. These advantages have increased their adoption across a wide range of bakery applications, including bread, pizza crusts, rolls, cookies, pastries, and other ready-to-bake products.
Current growth of the frozen dough industry is primarily driven by rising consumer demand for convenient meal and bakery solutions. According to the American Frozen Food Institute (AFFI) and FMI – The Food Industry Association, frozen foods have become an everyday kitchen essential as consumers increasingly seek convenient meal-planning solutions, affordable food options, and ways to reduce food waste. This sustained preference for frozen foods, including frozen bakery products and pizza, is contributing to increasing demand for frozen dough across both retail and foodservice channels.
The market is also benefiting from continued investments in cold-chain infrastructure, advances in freezing technologies, and ongoing product innovation. Manufacturers are expanding their portfolios with clean-label, artisan-style, organic, whole-grain, and plant-based frozen dough products to meet evolving consumer preferences for healthier, premium bakery offerings. In addition, the rapid expansion of e-commerce grocery platforms, organized retail chains, and modern distribution networks is improving the availability and accessibility of frozen bakery products worldwide.
Furthermore, busy lifestyles, increasing urbanization, and the growing popularity of convenience foods continue to support market expansion. The versatility of frozen dough, which can be used to prepare a broad range of bakery products, including bread, pizza, cookies, rolls, pastries, and other baked goods, is further strengthening demand for these products across households, bakeries, and foodservice establishments.
However, the market faces several challenges, including competition from freshly prepared and ready-to-eat bakery products and private-label alternatives. Maintaining product quality throughout frozen storage and transportation also remains a key challenge, particularly in regions with underdeveloped cold-chain infrastructure. Nevertheless, the growing consumer preference for plant-based, clean-label, and premium bakery products, together with continued advancements in freezing, packaging, and distribution technologies, is expected to create significant growth opportunities for the market.
Analyst Perspective
The market is expected to grow steadily, driven by the expanding processed food sector and rising demand for convenient bakery and meal solutions. Frozen dough offers extended shelf life, preparation convenience, and reduced food waste, supporting its adoption across households and foodservice businesses for products such as pizza bases, bread, rolls, and cookies. Improvements in cold-chain infrastructure and distribution networks, along with the expansion of online grocery shopping, are further supporting market growth. Manufacturers are also introducing clean-label, artisan-style, and vegan frozen dough products to meet evolving consumer preferences. However, storage and transportation requirements, as well as competition from alternative bakery products, remain key challenges. Increasing demand for premium bakery products and convenience foods, along with advancements in freezing and distribution technologies, is expected to sustain long-term market expansion.
Product Insights
The bread segment dominated the global frozen dough market in 2025, accounting for more than 37.0% of overall revenue. The segment is expected to retain its leading position throughout the forecast period. Its growth is primarily driven by the widespread consumption of bread and bakery products worldwide, coupled with the increasing adoption of frozen bread dough by commercial bakeries, foodservice operators, and retail consumers. Frozen bread dough reduces preparation time, improves operational efficiency, ensures consistent product quality, and offers flexibility to produce a variety of bread products with minimal labor. In addition, manufacturers continue to introduce customized formulations, including whole-grain, artisan, and specialty bread doughs, to meet evolving consumer preferences, thereby further supporting growth in this segment.
The biscuits & cookies segment is anticipated to grow at the fastest CAGR during the forecast period. The segment's growth is driven by rising consumer demand for convenient, ready-to-bake products that deliver homemade taste and consistent quality. Frozen biscuit and cookie dough products simplify baking while reducing preparation time, making them increasingly popular among households and foodservice establishments. Growing interest in home baking, premium desserts, and indulgent snack products is further supporting demand. For instance, in July 2025, Doughlicious launched its new Cookies & Cream Cookie Dough & Gelato Bites exclusively on Gopuff, expanding its premium frozen dessert portfolio and reflecting rising consumer demand for innovative, convenient frozen cookie dough products. Continued product innovation and the expanding availability of frozen cookie dough through retail and e-commerce channels are expected to further drive the segment's growth.
Distribution Channel Insights
The foodservice distribution channel segment dominated the global frozen dough industry in 2025, accounting for more than 67.0% of overall revenue. The segment is projected to expand at a significant rate while retaining its dominant position throughout the forecast period. The segment’s growth can be attributed to the widespread use of frozen dough products in the foodservice industry, as they reduce labor requirements, preparation time, and equipment needs compared to preparing dough from raw ingredients while ensuring consistent product quality. For instance, in September 2024, Humanity Bakery showcased that its portfolio of frozen puff pastry, pizza dough, pie crusts, and related bakery products is designed to serve both retail and foodservice customers through multiple brands, reflecting the growing importance of diversified distribution strategies in the frozen bakery and dough market. Moreover, frozen dough products help improve operational efficiency, reduce food preparation time, and minimize labor costs for foodservice operators.
The retail segment is anticipated to grow at the fastest CAGR during the forecast period. The segment is further categorized into supermarkets & hypermarkets, convenience stores, bakery stores, and online channels. Among these, the online channel is expected to register the highest CAGR during the forecast period, driven by the growing popularity of e-commerce and online grocery shopping. Consumers are increasingly using online platforms to compare products, review prices, and access promotional offers while benefiting from doorstep delivery and a wider product selection. For instance, in September 2024, Platinum Equity and Butterfly announced the acquisition of Rise Baking Company, a leading supplier of bakery products serving in-store bakeries, foodservice operators, and convenience stores across North America. The acquisition reflects continued investment in expanding bakery distribution networks across multiple retail channels, supporting greater availability of frozen bakery and dough products. The growing availability of frozen dough products across digital retail platforms and organized retail stores is expected to further support the segment's growth.
Regional Insights
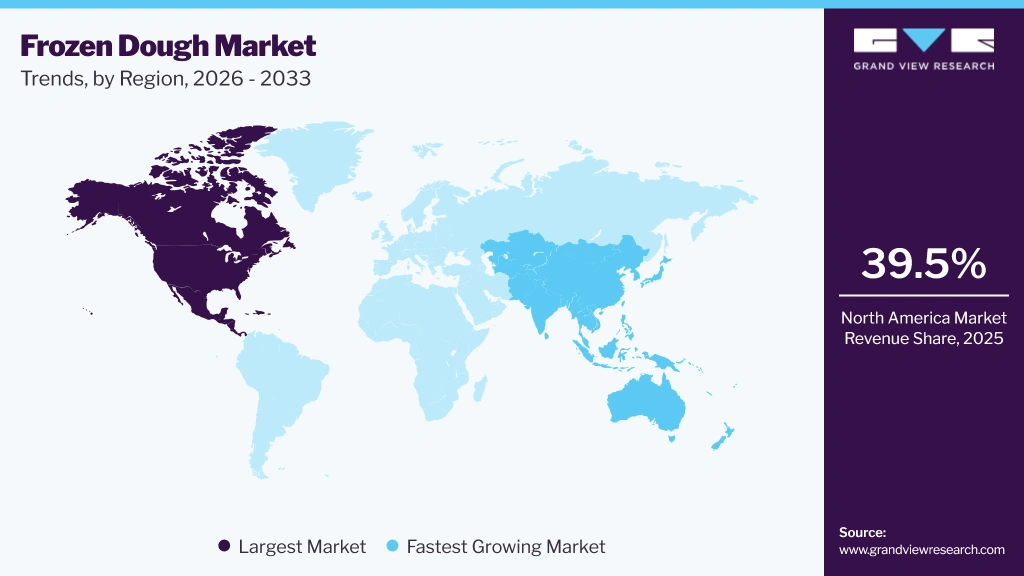
North America dominated the market, accounting for the largest revenue share of 39.5% of t revenue in 2025. The region is mainly driven by high consumer demand. Moreover, the ready availability of ready-to-cook products is a key driver of market growth. In addition, the high number of working individuals in the region drives demand for and use of such products, contributing to overall market growth. Furthermore, the high use of online food-purchasing platforms and the region's high internet penetration are expected to boost growth. The competitive landscape of the frozen dough and bakery products market is shaped by strategic acquisitions and expansions. For instance, in September 2025, Grupo Bimbo’s acquisition of Wickbold highlights the company’s efforts to broaden its bakery portfolio and strengthen its position in the global baked goods industry.
 To learn more about this report, Download Free Sample Report
Asia Pacific Frozen Dough Market Trends
The Asia Pacific frozen dough industry is expected to grow at the fastest CAGR during the forecast period. The region's growth is driven by rising consumer disposable income, which has increased spending on frozen and convenience foods. In addition, changing lifestyles, increasing urbanization, and the growing popularity of Western-style bakery products are supporting regional market growth. For instance, in September 2024, Mondelez International announced an agreement to acquire a significant majority stake in China-based Evirth, a leading manufacturer of frozen-to-chilled cakes and pastries. The acquisition aims to strengthen Mondelez's presence in China's fast-growing cakes and pastries category, reflecting increasing consumer demand for premium bakery and convenience foods in the Asia-Pacific region. The transaction was completed in November 2024. Furthermore, the expanding presence of quick-service restaurants and foodservice outlets across developing countries is expected to boost demand for frozen dough products in the region.
Key Frozen Dough Company Insights
Rising product demand has widened growth opportunities for manufacturers across the globe. Thus, major players in the industry are adopting various competitive strategies, such as product launches, partnerships & collaborations, and geographical expansions. For instance, in February 2025, SPC Group announced plans to build a USD 160 million bakery production plant in Texas, U.S. This strategic investment aims to strengthen the company’s production capacity and expand its presence in the North American bakery market.
Key Frozen Dough Companies
The following key companies have been profiled for this study of the frozen dough market.
-
ARYZTA AG
-
General Mills Inc.
-
Guttenplan’s
-
Ajinomoto Co., Inc.
-
Rich Products Corporation
-
CSM Ingredients
-
The Campbell's Company
-
Dawn Food Products, Inc.
-
GONNELLA BAKING COMPANY
-
Bridgford Foods Corporation
Recent Developments
-
In February 2025, CAULIPOWER launched the first and only frozen Dill Pickle Pizza in retail. The product debuted exclusively at Whole Foods Market nationwide during the first quarter of 2025 before expanding to additional retailers, reflecting growing consumer interest in premium and innovative frozen pizza offerings.
-
In December 2024, ARYZTA announced the installation of a new large-scale stone oven production line at its Eisleben facility in Germany. The investment is intended to expand the company's capacity for premium artisanal bakery products and to strengthen innovation in frozen bakery solutions by enhancing production capabilities.
Frozen Dough Market Report Scope
Report Attribute
Details
Market size in 2025
USD 25.6 billion
Estimated market size in 2026
USD 26.9 billion
Projected market size by 2033
USD 38.1 billion
Growth rate
CAGR of 5.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Spain; Italy; China; Japan; India; South Korea; Australia; Brazil; UAE
Key companies profiled
ARYZTA AG; General Mills Inc.; Guttenplan’s; Ajinomoto Co., Inc.; Rich Products Corporation; CSM Ingredients; The Campbell's Company; Dawn Food Products, Inc.; Gonnella Baking Company; Bridgford Foods Corporation
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Frozen Dough Market Report Segmentation
This report forecasts revenue growth at the global, regional & country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global frozen dough market report based on product, distribution channel, and region:
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Bread
-
Biscuits & Cookies
-
Pizza
-
Others
-
-
Distribution Channel Outlook (Revenue, USD Billion, 2021 - 2033)
-
Retail
-
Supermarkets & Hypermarkets
-
Convenience Stores
-
Bakery Stores
-
Online
-
-
Food Service
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Spain
-
Italy
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
-
Central & South America
-
Brazil
-
-
Middle East & Africa
-
UAE
-
-
Frequently Asked Questions About This Report
The bread product segment accounted for the largest revenue share of approximately 37.0% in 2025.
The global frozen dough market size was valued at USD 25.6 billion in 2025 and is estimated at USD 26.9 billion for 2026.
The global frozen dough market is expected to grow at a CAGR of 5.1% from 2026 to 2033, reaching USD 38.1 billion.
North America dominated the frozen dough market with a share of 39.5% in 2025. The high share of the region is attributed to easy availability and the rising preference of consumers for ready-to-cook products.
Key players are ARYZTA AG; General Mills Inc.; Guttenplan’s; Ajinomoto Co., Inc.; Rich Products Corporation; CSM Ingredients; The Campbell's Company; Dawn Food Products, Inc.; Gonnella Baking Company; and Bridgford Foods Corporation
About the Author(s)
Consumer F&B Research Team
Consumer Goods · Consumer F&BThis report was authored by the consumer f&b research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the consumer f&b segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


