
- Home
- »
- Electronic Devices
- »
-
Functional Safety Market Size. Share & Growth Report, 2033GVR Report cover

Functional Safety Market (2026 - 2033)
Size, Share & Trends Analysis Report By Device (Safety Switches, Safety Sensors), By System (Emergency Shutdown Systems, Distributed Control Systems), By Industry (Oil & Gas, Power Generation), By Region, And Segment Forecasts
Market Size, 2025
$7.4BMarket Estimate, 2026
$7.9BMarket Forecast, 2033
$12.1BCAGR, 2026–2033
6.3%Functional Safety Market Summary
The global functional safety market size was valued at USD 7.4 billion in 2025 and is projected to grow from USD 7.9 billion in 2026 to USD 12.1 billion by 2033, growing at a CAGR of 6.3% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 34.0% in 2025. The market focuses on the development, implementation, and maintenance of safety systems that ensure the safe operation of machinery, equipment, and processes in various industries. The demand for functional safety solutions is growing due to the increased integration of advanced technologies in various industries to boost efficiency and productivity.
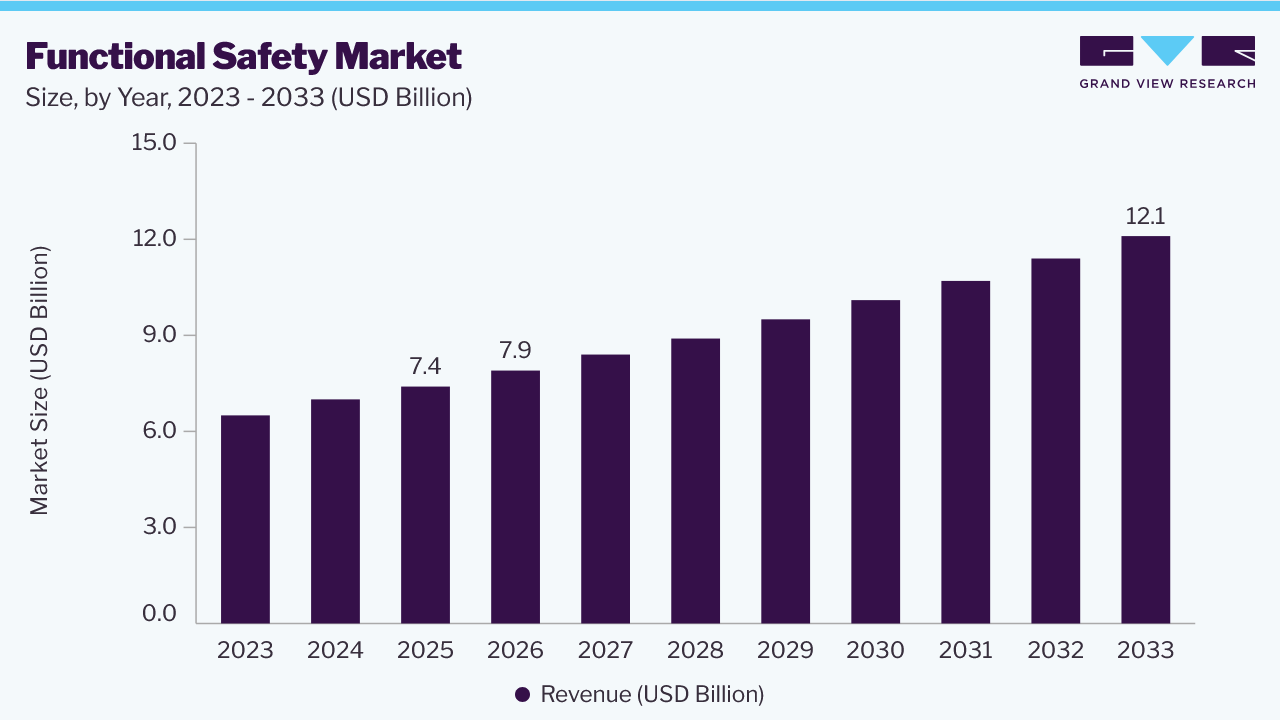 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By device: The safety sensors segment dominated the market, with a revenue share of about 25.0% in 2025.
- By system: The Emergency Shutdown Systems (ESD) segment held the largest revenue share in 2025.
- By industry: The oil & gas segment held the largest revenue share in 2025.
Regional Highlights
- Largest regional market: North America (34.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (Highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 7.4 Billion
- Estimated market size in 2026: USD 7.9 Billion
- Projected market size by 2033: USD 12.1 Billion
- CAGR (2026-2033): 6.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Industries worldwide are increasingly investing in advanced functional safety technologies to ensure the safe operation of machinery, industrial systems, and critical infrastructure. Rising awareness regarding workplace safety, asset protection, and regulatory compliance is accelerating demand for functional safety solutions across manufacturing, oil & gas, automotive, chemicals, power generation, and other industries. According to the U.S. Bureau of Labor Statistics (BLS), 5,283 fatal work injuries were recorded in the U.S. in 2023, highlighting the continued importance of implementing robust workplace safety measures. Functional safety technologies such as safety sensors, programmable safety systems, safety controllers, and emergency shutdown systems help organizations mitigate operational hazards, prevent accidents, improve worker safety, and minimize downtime.
The rapid adoption of Industry 4.0, industrial automation, and IoT-enabled systems is further increasing the importance of robust functional safety frameworks. As industrial systems become more interconnected and complex, companies are prioritizing advanced safety solutions to ensure reliable operations, safeguard employees and assets, and maintain compliance with regulatory and industry standards. Continuous advancements in industrial automation and smart manufacturing are expected to drive sustained demand for functional safety solutions over the forecast period.
Analyst Perspective
The functional safety market is expected to grow steadily, driven by increasing industrial automation, stringent safety regulations, and the adoption of intelligent industrial systems. Rising demand for safety instrumented systems (SIS), emergency shutdown systems, safety controllers, and sensors across oil & gas, chemicals, automotive, power, pharmaceuticals, and manufacturing is supporting market expansion. The growing adoption of Industry 4.0, IIoT, AI-enabled automation, and smart manufacturing is further increasing the need for reliable safety solutions. Investments in autonomous systems, EVs, robotics, and advanced manufacturing are creating additional opportunities for safety-certified hardware and software.
Device Insights
The safety sensors segment led the market with a share of 25.0% in 2025. The growing adoption of Industry 4.0, IIoT, and smart manufacturing technologies is driving demand for advanced safety sensors capable of real-time monitoring, predictive diagnostics, and enhanced machine protection. These solutions play a critical role in improving workplace safety, minimizing operational risks, and supporting efficient industrial automation. For instance, in April 2025, Omron Corporation introduced the OL-450S Safety Laser Scanner, designed to improve worker and machine safety in automated manufacturing environments. The scanner offers a wide detection angle, high-speed response, and flexible monitoring zones, enabling safer human-machine collaboration and improving safety in highly automated production environments. Continuous advancements in intelligent sensing technologies are strengthening the adoption of safety sensors across modern industrial automation environments.
The programmable safety systems segment is anticipated to grow at the fastest CAGR over the forecast period, driven by growing industrial complexity and increasing demand for flexible, intelligent safety solutions. As industrial systems become more interconnected and automated, manufacturers increasingly require programmable safety systems that can adapt to dynamic operating conditions and integrate seamlessly with existing automation infrastructure. Rising industrial automation, growing machine complexity, and the need for standards-compliant safety architectures are accelerating demand for programmable safety systems. For instance, in April 2025, Schneider introduced the Modicon M660 Industrial PC, designed to integrate seamlessly with EcoStruxure Automation Expert for software-defined industrial automation. The solution enables flexible system architectures, real-time control, and improved interoperability, supporting advanced automation and safety-critical industrial applications.
Systems Insights
The Emergency Shutdown Systems (ESD) segment held the largest revenue share in 2025. Growing emphasis on process safety and risk mitigation across high-risk industries is driving demand for Emergency Shutdown Systems. Companies are increasingly deploying advanced ESD systems to prevent hazardous incidents, protect critical assets, and minimize downtime in hazardous operating environments. Rising investments in process safety, critical infrastructure protection, and compliance with IEC 61508 and IEC 61511 standards are further accelerating adoption. For instance, Emerson Electric Co. introduced advanced simulation capabilities within its DeltaV Safety Instrumented System (SIS), enabling operators to safely test, validate, and optimize emergency shutdown logic in a virtual environment before plant deployment. The solution improves ESD reliability, enhances operator readiness, and reduces operational risks in critical industries such as oil & gas, chemicals, and power generation. Continuous advancements in safety instrumented systems and virtual testing technologies are strengthening the adoption of Emergency Shutdown Systems across critical process industries.
The turbomachinery control systems segment is expected to witness significant growth over the forecast period. Turbomachinery, including turbines, compressors, and pumps, plays a critical role in industries such as oil & gas, power generation, petrochemicals, and aerospace. Any malfunction or failure in turbomachinery systems can lead to severe consequences, including production downtime, equipment damage, environmental hazards, and personnel safety risks. Growing emphasis on operational continuity, predictive maintenance, and asset protection is driving investments in advanced turbomachinery control and safety systems. Industries are increasingly adopting integrated control solutions to improve performance, reduce operational risks, and ensure safe operation of critical rotating equipment. Continuous advancements in automation, condition monitoring, and predictive diagnostics are strengthening the adoption of turbomachinery control systems across critical industrial applications.
Industry Insights
The oil & gas segment led the market with the largest revenue share in 2025. This dominance is attributed to the highly hazardous nature of upstream, midstream, and downstream oil & gas operations. The industry’s strong focus on preventing catastrophic failures, ensuring worker safety, and minimizing environmental risks is driving demand for advanced functional safety systems such as Safety Instrumented Systems (SIS), Emergency Shutdown Systems (ESD), and Fire & Gas monitoring systems. Companies in the oil & gas sector are investing in advanced safety technologies to improve operational reliability, maintain asset integrity, comply with stringent safety regulations, and ensure business continuity. Rising investments in refinery modernization, LNG infrastructure, offshore exploration, and digital oilfield technologies are further accelerating the adoption of functional safety solutions across the oil & gas value chain.
The automotive segment is expected to grow at a rapid CAGR over the forecast period. Rising adoption of connected, electric, and autonomous vehicles is significantly driving demand for advanced functional safety technologies in the automotive sector. Modern vehicles increasingly rely on advanced sensors, electronic control units (ECUs), communication networks, and software-driven architectures to enable intelligent vehicle functions. Advanced driver assistance systems (ADAS) and autonomous driving platforms require robust safety systems to ensure hazard detection, fault tolerance, and fail-safe operation. Functional safety solutions play a critical role in ensuring vehicle reliability, minimizing system failures, and enabling safe operation of increasingly complex automotive systems. Growing investments in EV platforms, software-defined vehicles, and autonomous mobility solutions, along with rising compliance requirements under ISO 26262, are accelerating the adoption of automotive functional safety solutions.
Regional Insights
North America held the largest market share of approximately 34.0% in 2025. The increasing adoption of industrial automation, AI, and digital technologies across manufacturing, automotive, and energy sectors is driving demand for advanced functional safety solutions in the region. Companies across North America are increasingly integrating AI-enabled automation and digital safety solutions to improve operational safety, reduce system failures, and enhance process reliability in critical industries. For instance, in June 2025, Honeywell International Inc. launched AI-enabled industrial cybersecurity solutions, including Honeywell Cyber Proactive Defense and Honeywell OT Security Operations Center, while expanding its Digital Prime ecosystem to enhance operational resilience and industrial safety. The growing deployment of intelligent automation and safety-focused industrial systems continues to support market growth in North America.
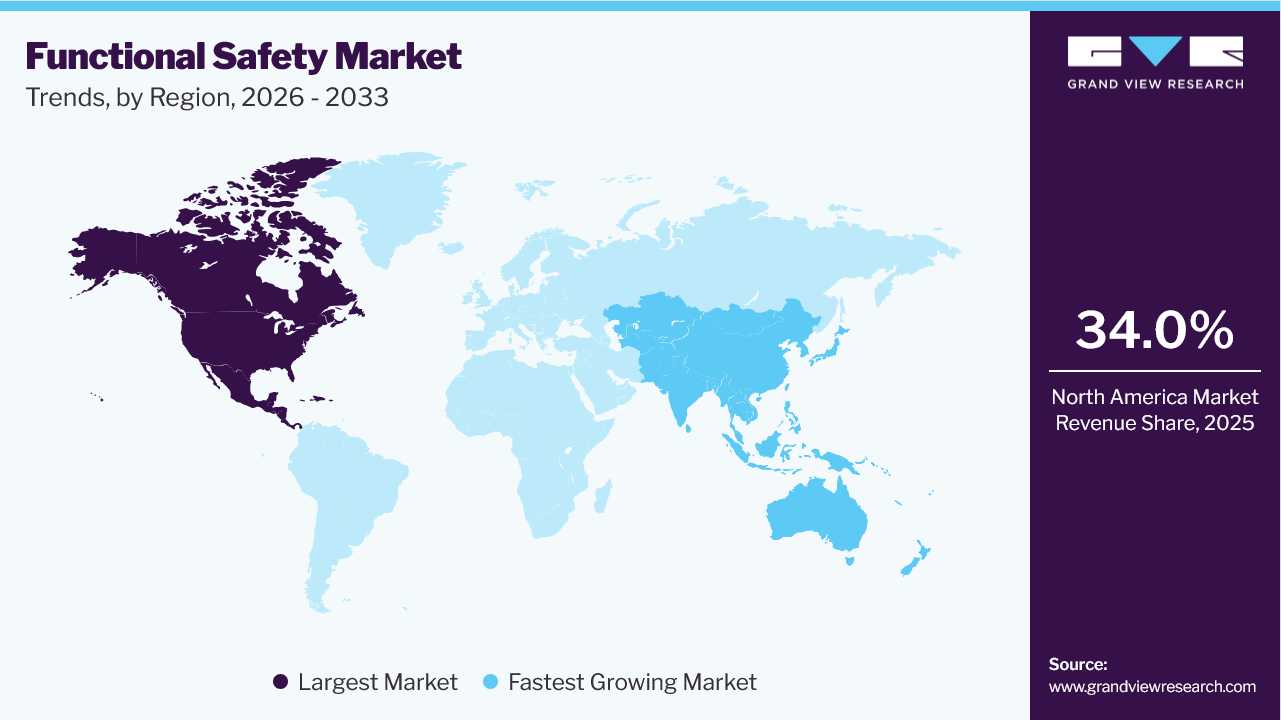 To learn more about this report, Download Free Sample Report
U.S. Functional Safety Market Trends
The U.S. accounted for a revenue share of about 27.0% in 2025. The country leads in the development of autonomous vehicles, driving the adoption of functional safety systems by necessitating advanced safety measures to ensure the reliability of autonomous systems. Autonomous vehicle manufacturers adhere to international standards such as ISO 26262, which specifies requirements for functional safety in automotive systems. Compliance with this standard ensures that safety measures are systematically integrated into the vehicle’s development process.
Asia Pacific Functional Safety Market Trends
The Asia Pacific market is anticipated to grow at the fastest CAGR during the forecast period. Rapid industrialization, increasing factory automation, and rising investments in digital infrastructure are significantly driving the adoption of functional safety solutions across the region. Industries across the Asia Pacific are increasingly deploying advanced automation and integrated control systems to improve operational efficiency, reduce system failures, and ensure safe industrial operations. For instance, in June 2026, Yokogawa Electric Corporation enhanced its OpreX Collaborative Information Server with improved usability, stronger multi-vendor integration capabilities, and enhanced system security to support advanced plant operations. The upgraded platform enables integrated human-machine interface (HMI) operations, centralized plant data management, and secure IT/OT convergence, supporting improved operational reliability and safety across complex industrial environments. Continuous advancements in industrial automation and secure digital operations are accelerating the adoption of functional safety solutions across the Asia Pacific.
The China functional safety market is expected to grow at a significant CAGR over the forecast period. China’s strategic emphasis on electric vehicles (EVs) as an essential element of sustainable transportation is driving demand for functional safety solutions in the burgeoning EV market. As China leads the global shift towards electrification in the automotive sector, ensuring the safety and reliability of electric vehicle systems is critical.
The functional safety market in India is expected to grow significantly over the forecast period. Rising industrial automation, increasing adoption of smart manufacturing technologies, and growing investments in industrial modernization are driving demand for functional safety solutions across the country. Government initiatives such as Make in India and expanded investments in manufacturing, automotive, energy, and industrial infrastructure are accelerating the deployment of advanced automation systems and the adoption of safety-critical operations. As industrial facilities become increasingly automated and interconnected, companies are prioritizing functional safety technologies to improve operational reliability, reduce system failures, ensure worker safety, and maintain compliance with evolving industrial safety standards. The growing adoption of Industry 4.0 technologies and digital manufacturing is expected to further accelerate demand for functional safety solutions in India.
Key Functional Safety Company Insights
Some of the key players operating in the market include ABB, Rockwell Automation Inc., and Honeywell International Inc.
-
ABB Ltd. is a Swedish-Swiss multinational corporation specializing in electrification, robotics, automation, and motion technologies. The company serves utilities, industrial, transport, and infrastructure sectors. Its functional safety portfolio includes programmable safety controller Pluto, safety controller Vital, safety relay Sentry, along with safety sensors, drives, and switches.
-
Honeywell International Inc. is a multinational conglomerate operating across aerospace, building technologies, industrial automation, and energy sectors. The company offers advanced functional safety solutions for critical industrial processes. Its offerings include ControlEdge HC900, Fail Safe Controller, Safety Manager, and Safety Manager SC. HIMA and DEKRA are among the emerging market participants.
-
HIMA specializes in safety-related automation solutions for process industries such as oil & gas, chemicals, and energy. The company focuses exclusively on functional safety and provides safety instrumented systems, emergency shutdown systems, and SIL-certified controllers. Its major offerings include HIMax and HIMatrix safety systems.
-
DEKRA is a global expert in testing, inspection, certification, and functional safety consulting services. The company supports organizations in achieving compliance with international functional safety standards such as IEC 61508 and ISO 26262. DEKRA provides safety engineering, risk assessment, certification, and validation services across automotive and industrial sectors.
Key Functional Safety Companies:
The following key companies have been profiled for this study on the functional safety market:
-
ABB
-
DEKRA
-
Emerson Electric Co.
-
Endress+Hauser Group Services AG
-
GE Vernova (General Electric Company)
-
HIMA
-
Honeywell International Inc.
-
Omron Corporation
-
Rockwell Automation
-
Schneider Electric
-
Siemens
-
Yokogawa Electric Corporation
Recent Developments
-
In October 2025, ABB Ltd. achieved TÜV Rheinland Functional Safety Management System (FSMS) Maturity Level 5 (ML5) certification, the highest maturity level awarded for industrial functional safety management. The certification reinforces ABB's capabilities in developing and managing safety-critical automation systems across industrial applications.
-
In October 2023, Rockwell Automation Inc. launched the latest services, systems, hardware, and industrial software and announced plans to showcase them at the Automation Fair 2023 at the Boston Convention and Exhibition Center. The event exhibited functional safety products such as FLEX 5000 I/O, GuardLogix L85ES controller, and 432ES GuardLink EtherNet/IP Adapter.
-
In April 2023, OMRON Corporation launched the NX502 automation & programmable safety systems and the NX-EIP201 EtherNet/IPTM units globally. These controllers offer advanced information and safety control. They utilize OMRON's advanced information processing and large capacity memory to reduce resource disposal losses and shorten lead times when changing production lines.
Functional Safety Market Report Scope
Report Attribute
Details
Market size in 2025
USD 7.4 billion
Estimated market size in 2026
USD 7.9 billion
Projected market size by 2033
USD 12.1 billion
Growth rate
CAGR of 6.3% from 2026 to 2033
Base year for estimation
2025
Actual data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, trends
Segments covered
Device, systems, industry, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; UK; Germany; France; Italy; China; India; Japan; Australia; South Korea; Brazil; Mexico; Argentina; UAE; Saudi Arabia; South Africa
Key companies profiled
ABB; DEKRA; Emerson Electric Co.; Endress+Hauser Group Services AG; GE Vernova (General Electric Company); HIMA; Honeywell International Inc.; Omron Corporation; Rockwell Automation; Schneider Electric; Siemens; Yokogawa Electric Corporation
Customization scope
Free report customization (equivalent to up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Functional Safety Market SegmentationThis report forecasts revenue growth at regional and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global functional safety market based on device, system, industry, and region:
-
Device Outlook (Revenue, USD Million, 2021 - 2033)
-
Safety Sensors
-
Safety Modules
-
Valves
-
Programmable Safety Systems
-
Safety Switches
-
Actuators
-
Emergency Stop Devices
-
Others
-
-
Systems Outlook (Revenue, USD Million, 2021 - 2033)
-
Emergency Shutdown Systems
-
Fire & Gas Monitoring Controls
-
Turbomachinery Controls Systems
-
Burner Management Systems
-
High Integrity Pressure Protection Systems
-
Distributed Control Systems
-
Supervisory Control and Data Acquisition Systems
-
-
Industry Outlook (Revenue, USD Million, 2021 - 2033)
-
Oil & Gas
-
Power Generation
-
Chemicals
-
Food & Beverages
-
Pharmaceuticals
-
Automotive
-
Railways
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
UK
-
Germany
-
Italy
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
Middle East & Africa
-
UAE
-
Saudi Arabia
-
South Africa
-
-
Frequently Asked Questions About This Report
North America dominated with an approximately 34.0% revenue share in 2025.
The safety sensors segment accounted for the largest revenue share of approximately 25.0% in 2025.
Key players in the market include ABB; DEKRA; Emerson Electric Co.; Endress+Hauser Group Services AG; GE Vernova (General Electric Company); HIMA; Honeywell International Inc.; Omron Corporation; Rockwell Automation; Schneider Electric; Siemens; Yokogawa Electric Corporation, and others.
The global functional safety market size was valued at USD 7.4 billion in 2025 and is estimated at USD 7.9 billion for 2026.
The global functional safety market is expected to grow at a CAGR of 6.3% from 2026 to 2033, reaching USD 12.1 billion.
About the Author(s)
Electronic Devices Research Team
Semiconductors & Electronics · Electronic DevicesThis report was authored by the electronic devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the electronic devices segment of the semiconductors & electronics industry. All findings are based on proprietary semiconductors & electronics databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


