
- Home
- »
- Advanced Interior Materials
- »
-
Andalusite Market Size, Share & Growth Report, 2026-2033GVR Report cover

Andalusite Market (2026 - 2033)
Size, Share & Trends Analysis Report By Application (Refractories, Foundry, Kiln Furniture), By Region (North America, Europe, Asia Pacific, Central & South America, Middle East & Africa), And Segment Forecasts
Market Size, 2025
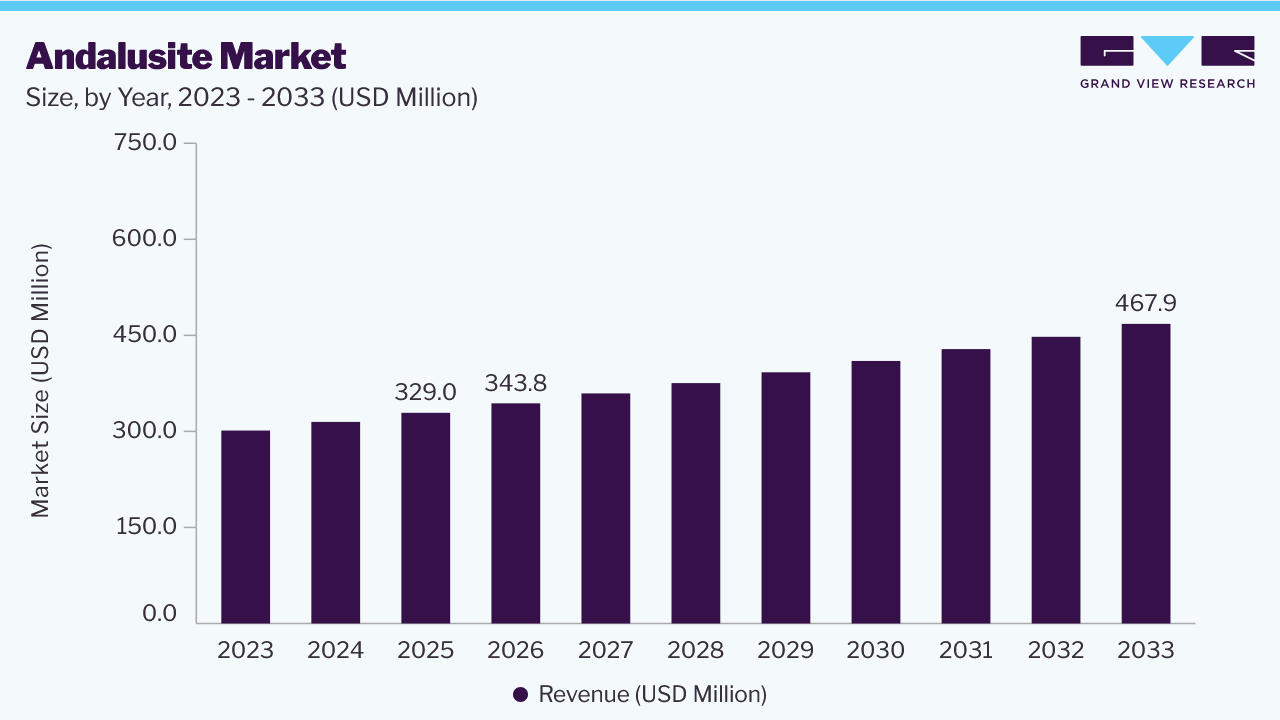
$329.0MMarket Estimate, 2026
$343.8MMarket Forecast, 2033
$467.9MCAGR, 2026–2033
4.5%Andalusite Market Summary
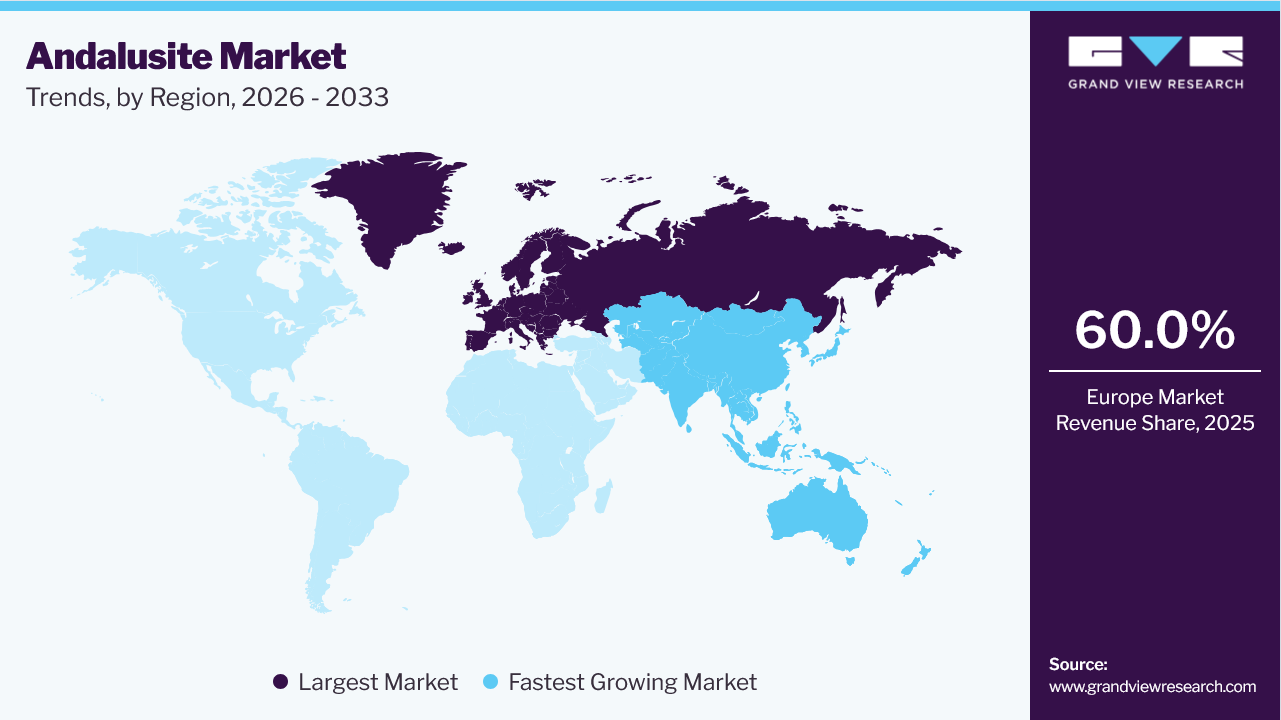
The global andalusite market size was valued at USD 329.0 million in 2025 and is projected to grow from USD 343.8 million in 2026 to USD 467.9 million by 2033, at a CAGR of 4.5% from 2026 to 2033. Europe dominated the global market, accounting for the largest revenue share of 60.0% in 2025. The increasing demand for refractories in the steel industry is expected to remain a key driver, as andalusite is primarily used in refractory production.
Key Market Trends & Insights
- By application: The refractories segment held the largest market share of over 88.0% in 2025.
Regional Highlights
- Largest regional market: Europe (60.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 329.0 Million
- Estimated market size in 2026: USD 343.8 Million
- Projected market size by 2033: USD 467.9 Million
- CAGR (2026-2033): 4.5%
Prism AI by Grand View Research Free to tryAsk a question about the andalusite marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
The phenomenal properties of andalusite, such as volume stability, high thermal shock, low porosity, and high chemical and creep resistance, along with the high level of purity, make it suitable for use in the manufacturing of refractories.The growing demand for steel across various end-use industries, such as construction, is expected to increase the use of refractories in the coming years. The strong growth of the construction industry, driven by increasing population and rapid urbanization, is likely to propel global steel consumption, thereby augmenting refractory production over the forecast period. Rising demand for cast metal products from the automotive industry is expected to drive growth in the foundry industry, which, in turn, will propel the market growth, as andalusite is an important component of foundry sand.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
The andalusite industry is primarily driven by growing demand from the refractory industry, particularly in iron and steel production, where it is widely used for its excellent thermal stability and resistance to thermal shock. According to the World Steel Association, global crude steel production reached approximately 1.89 billion tonnes in 2024, reflecting continued demand for refractory materials used in steelmaking operations. However, market growth is anticipated to be hindered by supply-demand imbalances. Andalusite production remains geographically concentrated, with major reserves in South Africa, Turkey, and Peru, which limits supply flexibility and increases dependence on a few producing regions. As a result, end users may increasingly adopt alternative refractory minerals such as bauxite and mullite, which offer wider availability and supply security.
Market Dynamics
The demand for high-performance refractory materials from the steel, foundry, glass, cement, and non-ferrous metal industries is expected to drive growth in the andalusite industry. Andalusite is one of the most preferred raw materials for refractory applications due to its excellent thermal stability, low porosity, high refractoriness, and formation of mullite at high temperature. The rising production of steel and industrial metals, along with continued investments in industrial infrastructure and manufacturing facilities, is a key factor driving rapid growth in demand for andalusite-based refractory products. Moreover, the mineral’s ability to improve refractory performance with lower energy and maintenance requirements also supports market growth.
One of the major factors driving the andalusite industry is the rising demand for refractory materials from the global steel industry. Andalusite-based refractories are used extensively for blast furnaces, ladles, tundishes, and other high-temperature applications because of their excellent thermal shock resistance and dimensional stability. Demand for high-end refractory minerals such as andalusite is growing among steel producers who are continually seeking to improve operational efficiency, extend refractory life, and reduce maintenance downtime.
The expansion of steel production capacity globally further supports this trend. For instance, in April 2025, JSW Steel commissioned a new steel production facility at Vijayanagar, India, increasing the plant's crude steel capacity and driving demand for refractory materials used in blast furnaces, ladles, and high-temperature processing units. In addition, several countries are investing in steel manufacturing and infrastructure development projects that require high-temperature processing equipment and refractory linings. As industrialization and urbanization continue across emerging economies, demand for andalusite-based refractory products is expected to grow steadily.
Major constraints for the andalusite industry include supply concentration and competition from other refractory minerals. The production of commercial andalusite is limited to a few countries, with the majority of supply coming from South Africa, which meets global requirements. Supply stability and pricing are sensitive to disruptions related to mining operations, logistics, energy availability, labor issues, or export regulations.
According to the U.S. Geological Survey (USGS), South Africa continued to account for the majority of global andalusite production, underscoring the market's reliance on a limited number of suppliers and the potential vulnerability to supply chain disruptions. This high degree of supply concentration can create procurement challenges for refractory manufacturers and end users, particularly during periods of geopolitical uncertainty, transportation bottlenecks, or mining disruptions, thereby affecting product availability and cost stability.
The growing transition toward low-carbon industrial processes is creating significant opportunities for the andalusite industry. Steel manufacturers are increasingly investing in energy-efficient production technologies, electric arc furnaces (EAFs), and decarbonization initiatives that require advanced refractory materials capable of operating under demanding thermal conditions. Andalusite's ability to improve refractory durability and reduce energy consumption positions it as a key material in next-generation industrial applications.
In 2024, the International Energy Agency (IEA) reported continued investments in low-emissions steel production projects worldwide, supporting demand for advanced refractory materials used in high-temperature industrial processes. Furthermore, the growing adoption of electric arc furnaces (EAFs) and energy-efficient steelmaking technologies is increasing the need for high-performance refractory linings capable of withstanding extreme thermal conditions. In addition, rising investments in industrial infrastructure, metal processing facilities, and manufacturing expansion across emerging economies are further driving the consumption of refractory minerals such as andalusite.
Analyst Perspective
The andalusite market is witnessing steady growth, driven by rising demand for refractory materials across the steel, foundry, cement, and glass industries. Its high thermal stability, refractoriness, and resistance to thermal shock make it suitable for demanding high-temperature applications. Increasing investments in infrastructure, industrial manufacturing, and steel production in emerging economies are further supporting market expansion. Companies focusing on reliable raw material supply, advanced processing, and global expansion are expected to gain a competitive advantage.
Application Insights
The refractories segment led the market with the largest revenue share of over 88.0% in 2025. Andalusite is used in the linings of kilns and boilers to protect equipment from high temperatures. Refractory products provide resistance to corrosion, abrasion, and other forms of attack. Refractory materials account for a significant share of the overall manufacturing segment, as finished products from the refractory market are used in various industries, including construction and automotive. Considering that manufacturing a car weighing 1.3 tons can require up to 10 kilograms of refractories in the form of bricks and mixes. Hence, the increasing production of vehicles is anticipated to augment demand for products such as steel, glass, aluminum, copper, and plastics, which, in turn, is expected to drive demand for refractories.
The foundry segment is anticipated to grow at the fastest CAGR of approximately 5.0% over the forecast period. Andalusite, when used as foundry sand, is suitable for the production of patterns, molds, and cores. Considering its anti-veining properties, such as low thermal expansion, heat resistance, and high refractoriness, it is preferred for the heavy casting of iron and steel alloys. Besides, it helps minimize issues related to sand sintering, sand washing, and metal penetration.
The kiln furniture segment is anticipated to grow at a considerable CAGR over the forecast period, driven by rising demand for kilns from the ceramics and automotive industries. Andalusite shapes are used to make kiln furniture, such as saggars and shelves, for investment casting, thermal processing, and glass. A benefit of using andalusite over other minerals is that it can be used in its raw form, while certain minerals, such as kyanite, need to be calcined for high-temperature applications
Regional Insights
The andalusite market in North America is driven by the growth of the steel and foundry industries. Positive development in the production of lightweight vehicles in Mexico and high investments by original equipment manufacturers (OEMs) in the U.S. are anticipated to boost the demand for metal casting in the region. Furthermore, increasing investments in infrastructure modernization, industrial manufacturing, and energy projects across the U.S. and Canada are driving demand for steel castings and refractory materials, further supporting regional market growth.
Europe Andalusite Market Trends
Europe dominated the global andalusite market with the largest revenue share of more than 60.0% in 2025, owing to the growth of the construction industry, where refractories are used to produce cement. Furthermore, the presence of a well-established steel, cement, glass, and ceramics manufacturing base across countries such as Germany, France, Italy, and Spain continues to drive the demand for refractory materials, thereby supporting andalusite consumption in the region.
 To learn more about this report, Download Free Sample Report
Asia Pacific Andalusite Market Trends
The andalusite market in the Asia Pacific region is expected to grow at the fastest CAGR of more than 4.5% during the forecast period. The Asia-Pacific market is dominated by China, owing to its position as the world's largest producer and consumer of refractory materials. The country continues to account for a significant share of global refractory production, supported by its extensive steel manufacturing base. The growing demand for steel in China is anticipated to augment the market growth over the coming years, as andalusite is widely used in refractory linings for steelmaking operations.
Middle East And Africa Andalusite Market Trends
The andalusite market in the Middle East and Africa is anticipated to grow at a significant CAGR during the forecast period. In the Middle East and Africa, South Africa is the largest producer and exporter of andalusite owing to its abundant mineral reserves and established mining industry. Increasing steel production in the region is driving refractory consumption and supporting demand for andalusite. Ongoing investments in infrastructure and manufacturing projects across the region are expected to further support market growth.
Key Andalusite Market Company Insights
Producers are primarily focusing on the development of new grades of andalusite for various applications. Companies are investing in operational efficiency, resource development, beneficiation technologies, and supply chain optimization to strengthen their market position and meet growing demand from the steel, foundry, glass, and cement industries.
Key Andalusite Market Companies
The following key companies have been profiled for this study on the andalusite market:
-
ANDALUCITA.COM.PE
-
Imerys
-
LKAB Minerals
-
Resco Products
-
Shijiazhuang Mining Imp & Exp Trade Co., Limited
-
African Rainbow Minerals Limited
-
ARM Andalusite.
-
RHI Magnesita
-
Vesuvius
-
Calderys
Recent Development
-
In April 2026, Imerys signed a binding agreement to acquire Great Lakes Minerals, a leading U.S.-based processor and distributor of minerals for the refractory and abrasive industries. The acquisition expands Imerys' portfolio with critical refractory minerals such as calcined bauxite, mullite, and fused alumina while strengthening its presence in the North American refractory materials market.
Andalusite Market Report Scope
Report Attribute
Details
Market size in 2025
USD 329.0 million
Estimated Market size in 2026
USD 343.8 million
Projected Market size by 2033
USD 467.9 million
Growth rate
CAGR of 4.5% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD million/billion, Volume in Kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Application, region
Regional Scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; Turkey; Russia; China; India; Australia; Brazil; South Africa
Key companies profiled
ANDALUCITA.COM.PE; Imerys; LKAB Minerals; Resco Products; Shijiazhuang Mining Imp & Exp Trade Co., Limited; African Rainbow Minerals Limited; ARM Andalusite.; RHI Magnesita; Vesuvius; Calderys
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Andalusite Market Segmentation
This report forecasts revenue and volume growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global andalusite market report based on application, and region:
 To learn more about this report, Download Free Sample Report
-
Application Outlook (Volume, Kilo Tons; Revenue, USD Million, 2021 - 2033)
-
Refractories
-
Foundry
-
Kiln Furniture
-
Others
-
-
Regional Outlook (Volume, Kilo Tons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
Turkey
-
Russia
-
-
Asia Pacific
-
China
-
India
-
Australia
-
-
Central & South America
-
Brazil
-
-
Middle East & Africa (MEA)
-
South Africa
-
-
Frequently Asked Questions About This Report
The global andalusite market size was valued at USD 329.0 million in 2025 and is estimated at USD 343.8 million in 2026.
Some of the key vendors of the global andalusite market are Imerys Refractory Minerals, Andalusite Resources, Andalusia S.A., and Resco Products.
Europe region dominated with over 60.0% revenue share in 2025.
The global andalusite market is expected to grow at a CAGR of 4.5% from 2026 to 2033, reaching USD 467.9 million.
The refractories segment accounted for the largest revenue share, at over 88.0% in 2025.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


