
- Home
- »
- Advanced Interior Materials
- »
-
Refractories Market Size, Share & Trends Report, 2026-2033GVR Report cover

Refractories Market (2026 - 2033)
Size, Share & Trends Analysis Report By End-use (Iron & Steel, Cement & Lime, Glass & Ceramics, Non-ferrous Metals), By Region (North America, Europe, Asia Pacific, Latin America, Middle East & Africa), And Segment Forecasts
Market Size, 2025
$47.9BMarket Estimate, 2026
$50.9BMarket Forecast, 2033
$96.0BCAGR, 2026–2033
9.5%Refractories Market Summary
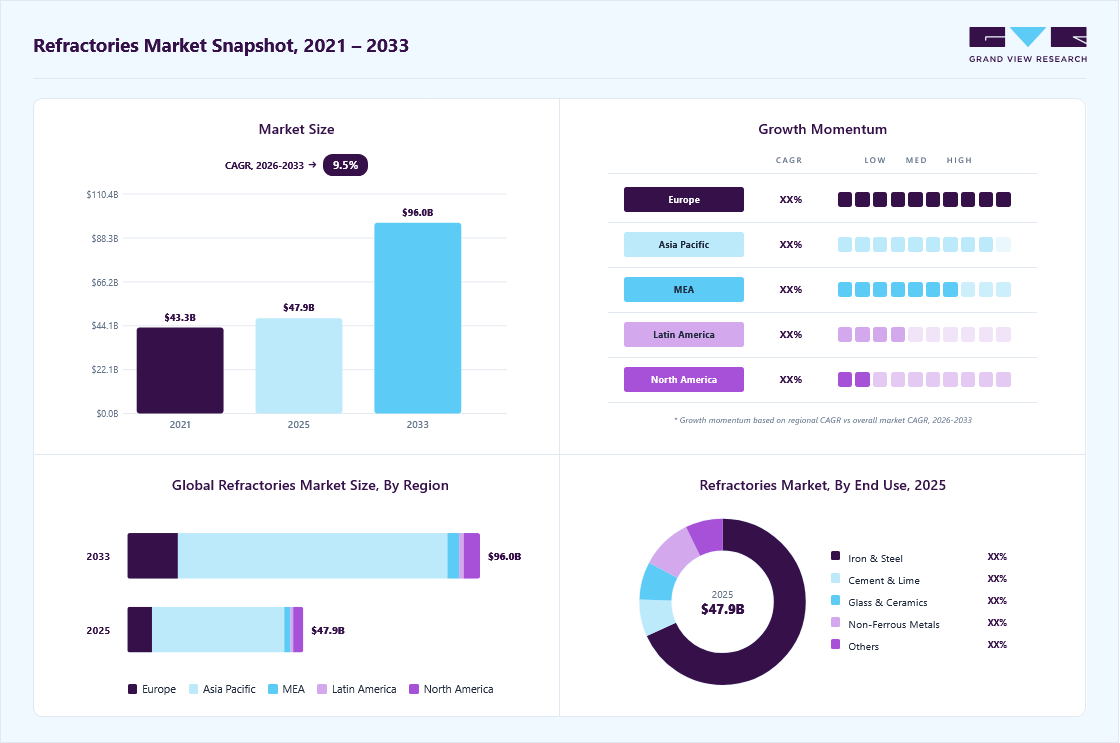
The global refractories market size was valued at USD 47.9 billion in 2025 and is projected to grow from USD 50.9 billion in 2026 to USD 96.0 billion by 2033, at a CAGR of 9.5% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 75.2% in 2025. Crude steel manufacturing through basic oxygen furnaces (BOF), electric arc furnaces (EAF), and induction furnaces (IF) requires high volumes of shaped and unshaped refractories to withstand extreme temperatures and chemical wear.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By end use: Iron & steel accounted for the largest revenue share of 67.0% in 2025.
- By end use: Glass & ceramics segment is expected to grow at the fastest CAGR of 10.0% from 2026 to 2033.
Regional Highlights
- Largest regional market: Asia Pacific (75.2% revenue share, 2025)
- Fastest-growing regional market: Europe (fastest CAGR, 2026-2033)
Market Size & Forecast
- Market Size in 2025: USD 47.9 Billion
- Estimated Market Size in 2026: USD 50.9 Billion
- Projected Market Size by 2033: USD 96.0 Billion
- CAGR (2026-2033): 9.5%
Prism AI by Grand View Research Free to tryAsk a question about the refractories market✓Every figure cited from GVR research Prefer the report? Download free sample →
As steel production and high-temperature industrial activity expand in countries such as India, China, and Vietnam, demand for refractories is expected to increase. The refractories industry is increasingly focusing on circularity, recycled raw materials, and lower-carbon refractory formulations as manufacturers seek to reduce the environmental impact associated with raw-material extraction, processing, manufacturing, and disposal. Spent refractories from steel, cement, non-ferrous metals, and other high-temperature industries can be processed and returned to refractory production, reducing dependence on virgin minerals and the quantity of material sent to landfills. RHI Magnesita identifies recycling as a major lever for reducing the carbon footprint of refractory products and reported that its recycling rate reached 12.6% in 2023.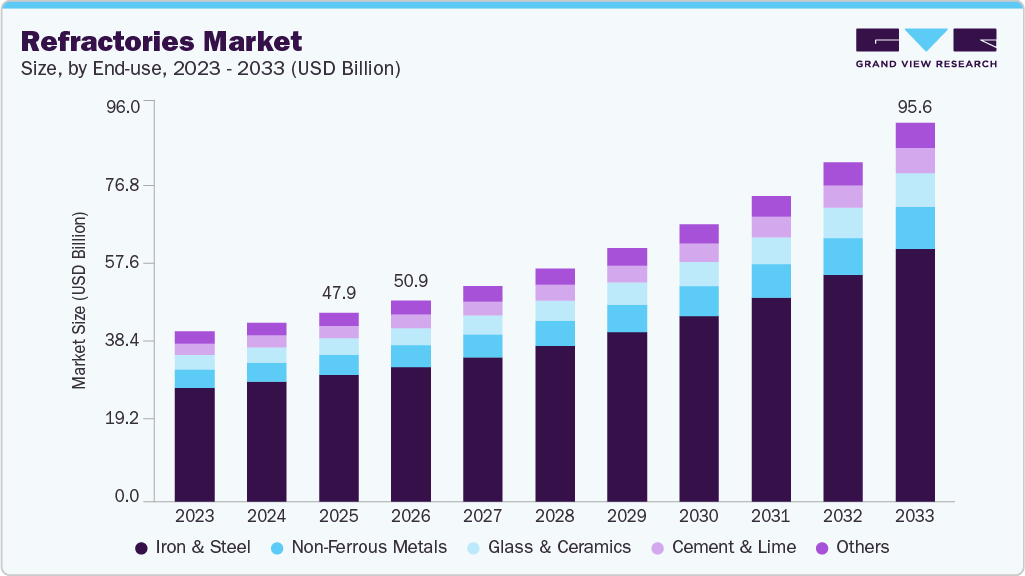 To learn more about this report, Download Free Sample Report
Technological development in refractories is increasingly shifting from conventional material replacement toward condition monitoring, predictive maintenance, digital wear measurement, and application-specific refractory design. Digital technologies allow producers to monitor lining thickness and erosion, evaluate operating conditions, and optimize replacement schedules. For example, Vesuvius uses ANTERIS laser-scanning technology to measure erosion rates and residual refractory thickness, thereby supporting more precise maintenance and lining design decisions. The adoption of automation, sensors, data analytics, and predictive models is also improving refractory management in steelmaking and other high-temperature operations. Vesuvius' digital refractory solutions integrate three-dimensional scanning with analytics to convert refractory-wear measurements into predictive information.
Market Dynamics
The expansion of steel production remains a major structural driver for refractory consumption as refractories are essential across ironmaking, steelmaking, secondary metallurgy, and continuous casting. Demand is particularly linked to furnace linings, ladles, tundish systems, runners, and other equipment exposed to molten metal, slag, thermal cycling, and chemical attack. According to the World Steel Association, global crude steel production reached approximately 1.85 billion tons in 2025, with India producing 164.9 million tons, up 10.4% from 2024, while the U.S. produced 82.0 million tons, up 3.1%. The scale of global steel production, therefore, provides a substantial recurring requirement for refractory replacement and maintenance.
The transition toward EAFs, direct reduced iron, secondary steelmaking, and more demanding steel grades is also changing refractory requirements rather than eliminating them. EAFs expose refractory linings to intense thermal conditions, slag interaction, electrical arcing, and variable operating cycles, creating demand for specialized products with improved thermal-shock resistance and wear performance. The World Steel Association estimates that approximately 30% of global steel is currently produced through EAFs, while continued development of EAF and DRI-based routes is expected to increase the importance of application-specific refractory solutions.
The availability and cost of high-grade refractory raw materials, including magnesia, alumina, bauxite, graphite, chromite, and other specialty minerals, can constrain refractory manufacturers. Raw material extraction and processing account for a significant portion of the carbon footprint of refractory products, while reliance on externally sourced materials can expose manufacturers to fluctuations in material availability, transportation costs, energy prices, and geopolitical or trade-related disruptions. RHI Magnesita notes that externally purchased refractory raw materials constitute an important source of Scope 3 emissions and that improving supplier-level carbon-footprint data remains a challenge.
The industry also faces technical limitations to increasing the utilization of recycled materials. Recovered refractories must be collected, sorted, processed, and assessed for chemical composition and contamination before they can be incorporated into new products. RHI Magnesita notes that the adoption of recycling is affected by sourcing, logistics, legislation, processing, marketing, and product design requirements. Consequently, although recycled materials can reduce raw material requirements and emissions, achieving consistent quality and performance at scale remains a constraint to wider adoption.
The transition toward green steel, EAF-based production, hydrogen-based DRI, and other low-carbon metallurgical technologies creates opportunities for refractory manufacturers to develop specialized products for new operating environments. Changes in furnace chemistry, temperature profiles, slag characteristics, operating cycles, and process configurations may require refractory formulations with improved corrosion resistance, thermal shock resistance, mechanical durability, and longer service life. The World Steel Association identifies EAF, DRI, hydrogen, electrification, and digitalization among the technologies being developed to reduce emissions from steel production.
This transition creates opportunities beyond simply supplying replacement bricks and monolithics. Refractory manufacturers can increasingly provide engineered lining systems, digital wear monitoring, predictive maintenance, recycling solutions, and process optimization services alongside refractory materials. The combination of material innovation and digital services can help steelmakers extend campaign life, reduce refractory consumption, lower downtime, and improve resource efficiency.
Analyst Perspective
The global refractories market is driven by production, maintenance, and capacity expansion across steel, cement, non-ferrous metals, glass, and other high-temperature industries. Recurring furnace relining, replacement, and modernization requirements support steady consumption, while demand for longer service life, improved wear resistance, reduced downtime, and greater process efficiency is encouraging the adoption of advanced refractory solutions. Sustainability initiatives, refractory recycling, and digital monitoring technologies are further influencing product development and industry practices.
End-use Insights
The iron & steel segment dominated the refractories industry, accounting for a revenue share of 67.0% in 2025, supported by extensive refractory consumption across ironmaking, steelmaking, secondary metallurgy, and casting operations. Refractories are required in blast furnaces, BOFs, EAFs, ladles, tundishes, converters, runners, and reheating furnaces to withstand high temperatures, molten metal, slag, thermal cycling, and chemical wear. The continued scale of steel production and recurring requirements for relining, maintenance, and replacement underpin the segment's revenue contribution.
The glass & ceramics segment is projected to grow at the fastest CAGR of 10.0% from 2026 to 2033. Growth is driven by increasing refractory requirements in glass-melting furnaces, regenerators, forehearths, and ceramic kilns, where materials are exposed to high temperatures, thermal cycling, and chemical attack. The transition toward electric and hybrid glass furnaces, along with the demand for improved furnace efficiency and service life, is expected to drive adoption of specialized refractory products.
Regional Insights
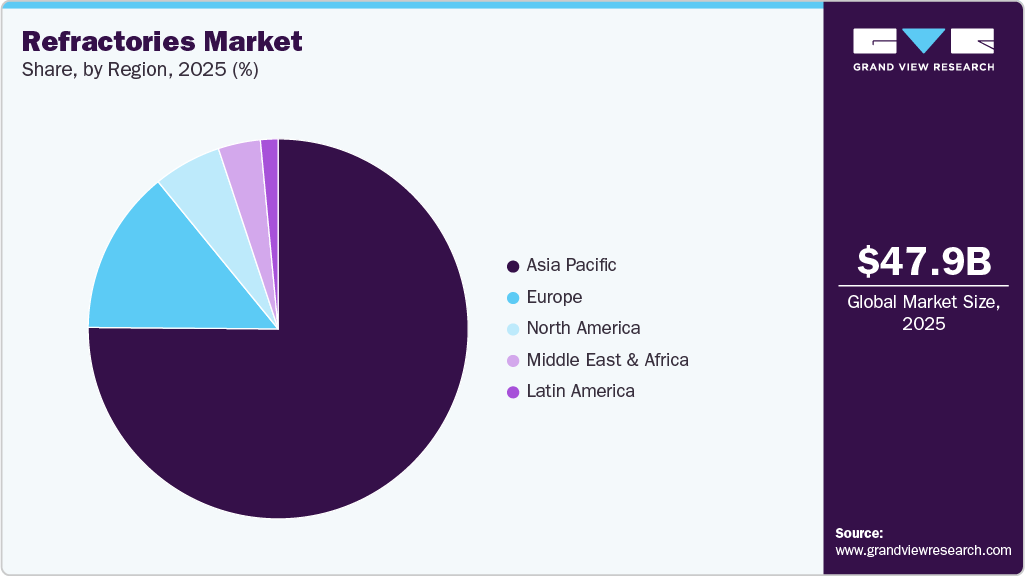
Asia Pacific dominated the refractories market with a revenue share of 75.2% in 2025. Asia Pacific remains the largest regional consumer of refractories because of its extensive concentration of steel, non-ferrous metals, cement, glass, and other thermal-processing industries. The region's demand is increasingly influenced by the scale and diversification of high-temperature manufacturing, rather than only by new construction activity. China alone produced 960.8 million tons of crude steel in 2025, while India produced 164.9 million tons and Japan 80.7 million tons. Vietnam and Indonesia also recorded increases of 12.2% and 1.9%, respectively, during the year.
 To learn more about this report, Download Free Sample Report
The China refractories market dominates Asia Pacific. China is the largest individual refractory consumer, supported by its extensive steelmaking, cement, non-ferrous metals, glass, and chemical processing base. Although crude steel output declined to 960.8 million tons in 2025 from 1,005.1 million tons in 2024, the country continued to operate an exceptionally large installed base of high-temperature industrial equipment. Meanwhile, production of refined copper, electrolytic aluminum, and other non-ferrous metals increased, creating additional demand for refractories used in smelting, refining, furnace linings, and related thermal processes.
North America Refractories Market Trends
The demand in North America is supported by the modernization of existing metallurgical assets, specialty steel production, and investment in domestic manufacturing capacity. Rather than being driven solely by new steel capacity, demand is increasingly associated with furnace upgrades, maintenance of aging assets, production of higher-value steel grades, and expansion of downstream processing. The U.S. produced 82.0 million tons of crude steel in 2025, up 3.1% from 2024, while Canada produced 11.5 million tons.
U.S. Refractories Market Trends
The U.S. refractories industry is also benefiting from investment in specialty metals, advanced manufacturing, domestic steel supply chains, and industrial processing infrastructure. These applications require refractory materials capable of operating under highly specific thermal, chemical, and mechanical conditions, increasing demand for engineered products rather than commodity-grade materials. The growing importance of domestic production of strategic materials also creates requirements for refractory-lined furnaces, reactors, kilns, and thermal-treatment equipment.
Europe Refractories Market Trends
Europe's demand is increasingly shaped by industrial modernization, furnace replacement, specialty steel production, and the conversion of conventional processes toward lower-carbon production routes. The transition is creating new technical requirements because DRI, hydrogen, EAF, and other emerging production configurations can expose refractory linings to different temperature profiles, atmospheres, slag chemistries, and operating cycles. This creates opportunities for higher-performance refractory compositions and engineered lining systems.
Latin America Refractories Market Trends
Latin America's demand is closely linked to its steel, iron ore processing, non-ferrous metallurgy, cement, and foundry industries, with Brazil and Mexico representing major regional industrial bases. Brazil produced 33.3 million tons of crude steel in 2025, while Mexico produced 13.5 million tons. The region's large installed base of steelmaking and mineral-processing equipment creates recurring demand for furnace, ladle, kiln, and casting refractories even when overall capacity additions remain selective.
Middle East & Africa Refractories Market Trends
The Middle East & Africa region is developing as a growing center for integrated steelmaking, direct reduction, non-ferrous processing, and cement production, particularly in countries with access to natural gas, iron ore, and other mineral resources. Refractory consumption is increasingly connected to the development and modernization of industrial processing facilities rather than solely to construction activity. Saudi Arabia, Iran, Egypt, the UAE, and South Africa provide important bases for steel, metals, cement, and mineral-processing operations.
Key Refractories Company Insights
Some of the key players operating in the market include Calderys and Vesuvius.
-
Calderys was established in 1906 and is headquartered in France. The company provides shaped and monolithic refractory products, along with engineering, installation, maintenance, and technical services, for steel, foundry, cement, aluminum, glass, chemicals, petrochemicals, and other high-temperature industries. Calderys develops application-specific refractory solutions for furnaces, kilns, ladles, and other thermal-processing equipment and also provides services focused on refractory performance and equipment operating life.
-
Vesuvius plc was established in 1916 and is headquartered in the United Kingdom. The company provides advanced refractory and molten-metal flow-control solutions for steel, foundry, non-ferrous metals, cement, and other industrial applications. Its product portfolio includes refractory materials, flow-control systems, and digital technologies for refractory wear measurement and process monitoring. Vesuvius also provides technical and engineering services to support refractory selection, installation, and process performance.
-
Krosaki Harima Corporation was established in 1919 and is headquartered in Fukuoka, Japan. The company manufactures shaped and unshaped refractory products for steel, cement, non-ferrous metals, glass, and other high-temperature industries. Its activities include refractory manufacturing, furnace engineering, installation, maintenance, and development of refractory materials designed for specific operating conditions. The company also provides refractory solutions for various stages of ironmaking, steelmaking, casting, and other thermal-processing operations.
Key Refractories Companies
The following key companies have been profiled for this study of the refractories market.
-
Alsey Refractories Co.
-
Calderys (HarbisonWalker International)
-
Chosun Refractories Co., Ltd.
-
CoorsTek Inc.
-
Krosaki Harima Corporation
-
Morgan Advanced Materials
-
RHI Magnesita
-
Saint-Gobain SEFPRO
-
Shinagawa Refractories Co., Ltd.
-
Vesuvius plc
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Global Players: (Calderys, CoorsTek Inc., Krosaki Harima Corporation, Morgan Advanced Materials, RHI Magnesita, Saint-Gobain SEFPRO, Vesuvius plc.)
- Expand specialized refractory portfolios for steel, glass, cement, non-ferrous metals, and other high-temperature applications.
- Integrate refractory supply with engineering, installation, maintenance, process monitoring, and technical consulting services.
- Invest in advanced materials, digital monitoring, recycling, and lower-carbon refractory solutions to improve product performance and customer efficiency.
- Strong international presence and established relationships with large industrial customers support participation in complex projects.
- Extensive application engineering capabilities enable refractory designs tailored to furnace geometry, temperature, slag chemistry, and operating cycles.
- Broad product portfolios allow suppliers to address multiple refractory formats, including bricks, castables, monolithics, and specialized fused-cast products.
- Large manufacturing and service networks can result in higher organizational and operating complexity.
- Significant exposure to steel and other capital-intensive industries makes demand sensitive to industrial production cCategory Operating Strategies Competitive Edge Weakness
- Established Global Players: (Calderys, CoorsTek Inc., Krosaki Harima Corporation, Morgan Advanced Materials, RHI Magnesita, Saint-Gobain SEFPRO, Vesuvius plc.)
- Expand specialized refractory portfolios for steel, glass, cement, non-ferrous metals, and other high-temperature applications.
- Integrate refractory supply with engineering, installation, maintenance, process monitoring, and technical consulting services.
- Invest in advanced materials, digital monitoring, recycling, and lower-carbon refractory solutions to improve product performance and customer efficiency.
- Strong international presence and established relationships with large industrial customers support participation in complex projects.
- Extensive application engineering capabilities enable refractory designs tailored to furnace geometry, temperature, slag chemistry, and operating cycles.
- Broad product portfolios allow suppliers to address multiple refractory formats, including bricks, castables, monolithics, and specialized fused-cast products.
- Large manufacturing and service networks can result in higher organizational and operating complexity.
- Significant exposure to steel and other capital-intensive industries makes demand sensitive to industrial production cycles.
- Development and qualification of new refractory materials can require lengthy customer trials before large-scale adoption.
- Regional & Specialized Players: (Chosun Refractories Co., Ltd., Shinagawa Refractories Co., Ltd.)
- Concentrate on specialized refractory products and application-specific solutions for selected industrial processes.
- Strengthen customer relationships through localized technical support, product customization, and direct engagement with plant operators.
- Expand capabilities selectively in specialized refractory segments and regional industrial markets where technical performance is a key purchasing consideration. Specialized manufacturing expertise can provide strong knowledge of refractory compositions and high-temperature applications.
- Regional presence enables closer coordination with customers and faster response to application-specific requirements.
- Focused product development can allow these companies to address niche requirements that may require customized refractory formulations. More concentrated geographic exposure can increase sensitivity to conditions in individual countries or industrial regions.
- Smaller scale relative to multinational competitors can limit access to very large international projects requiring multi-country supply capabilities.
- Dependence on specialized applications may result in greater exposure to changes in demand within individual end-use industries.
- ycles.
- Development and qualification of new refractory materials can require lengthy customer trials before large-scale adoption.
Regional & Specialized Players: (Chosun Refractories Co., Ltd., Shinagawa Refractories Co., Ltd.)
- Concentrate on specialized refractory products and application-specific solutions for selected industrial processes.
- Strengthen customer relationships through localized technical support, product customization, and direct engagement with plant operators.
- Expand capabilities selectively in specialized refractory segments and regional industrial markets where technical performance is a key purchasing consideration.
- Specialized manufacturing expertise can provide strong knowledge of refractory compositions and high-temperature applications.
- Regional presence enables closer coordination with customers and faster response to application-specific requirements.
- Focused product development can allow these companies to address niche requirements that may require customized refractory formulations.
- More concentrated geographic exposure can increase sensitivity to conditions in individual countries or industrial regions.
- Smaller scale relative to multinational competitors can limit access to very large international projects requiring multi-country supply capabilities.
- Dependence on specialized applications may result in greater exposure to changes in demand within individual end-use industries.
Recent Developments
-
In August 2026, RHI Magnesita and Khemka Refractories completed their previously announced joint venture and launched MINPRO, focused on refractory recycling and circular mineral solutions in India. The development expands RHI Magnesita's recycling activities in India's growing industrial sectors and supports greater recovery and reuse of refractory materials. The initiative reflects the industry's increasing focus on circularity and reducing dependence on virgin raw materials.
-
In April 2026, Calderys officially inaugurated its new CAPES facility in Odisha, India, which the company describes as the world's largest single-site greenfield facility for refractories and steel-casting fluxes. The first acidic and basic monolithics production lines had already entered commercial operation, while additional lines for acidic and basic bricks, steel-casting fluxes, and tap-hole clays were under development. The facility is intended to strengthen Calderys' manufacturing capabilities in India and support refractory demand from steel and other high-temperature industries across the region.
-
In July 2026, Vesuvius reported its first-half 2026 results, highlighting developments in its Steel Division and Advanced Refractories business. The company reported that Advanced Refractories performance was affected by operational challenges in North America and India and pricing conditions in EMEA, while its broader steel business benefited from improving steel production outside China, Iran, Russia, and Ukraine. Vesuvius also reported continued progress in new-product development, with its new-product sales ratio reaching 21% in H1 2026.
Refractories Market Report Scope
Report Attribute
Details
Market definition
Scope includes apparent consumption of refractories across different end uses, such as steel and cement.
Market size in 2025
USD 47.9 billion
Estimated market size in 2026
USD 50.9 billion
Projected market size by 2033
USD 96.0 billion
Growth rate
CAGR of 9.5% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2023
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Volume forecast, revenue forecast, competitive landscape, growth factors, and trends
Segments covered
End-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; France; Russia; UK; China; India; Japan; South Korea; Brazil, South Africa
Key companies profiled
Alsey Refractories Co.; Calderys (HarbisonWalker International); Chosun Refractories Co., Ltd.; CoorsTek Inc.; Krosaki Harima Corporation; Morgan Advanced Materials; RHI Magnesita; Saint-Gobain SEFPRO; Shinagawa Refractories Co., Ltd.; Vesuvius plc
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Refractories Market Report Segmentation
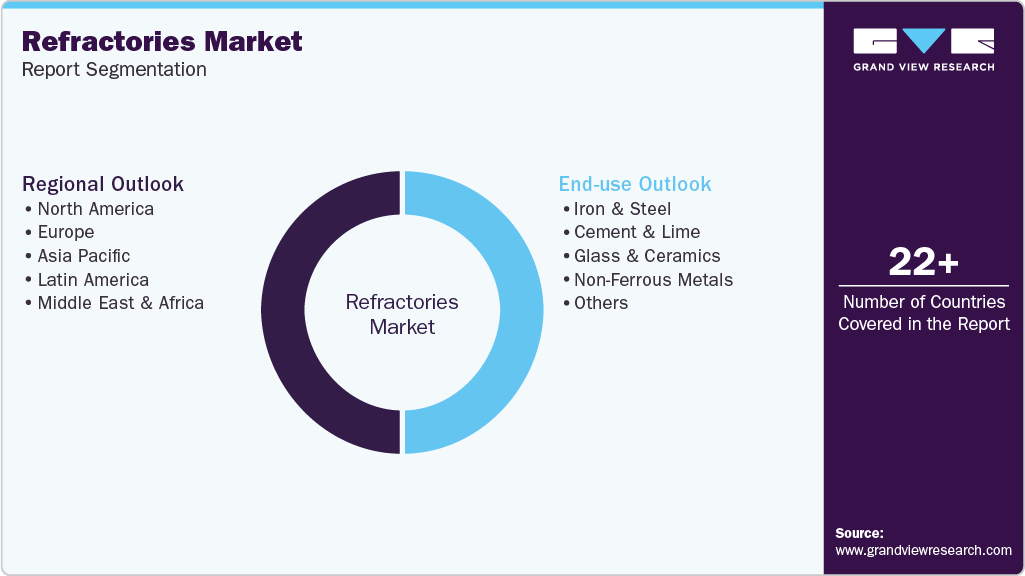
This report forecasts revenue & volume growth at the global, regional & country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global refractories market report based on end-use, and region:
 To learn more about this report, Download Free Sample Report
-
End-use Outlook (Volume, Kilotons; Revenue, USD Million/Billion, 2021-2033)
-
Iron & Steel
-
Cement & Lime
-
Glass & Ceramics
-
Non-Ferrous Metals
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million/Billion, 2021-2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
Russia
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
South Africa
-
-
Research Methodology
The refractories market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each refractories segment quantified using the revenue-capture definitions in the table below.
Segment Definition
End Use
Revenue Capture Definition
Iron & Steel
Revenue is captured from refractory consumption across ironmaking, steelmaking, secondary metallurgy, and casting operations, including blast furnaces, BOFs, EAFs, ladles, tundishes, converters, runners, and reheating furnaces.
Cement & Lime
Revenue is captured from refractory consumption in clinker and lime production, including rotary kilns, preheaters, calciners, coolers, burners, and other thermal-processing units exposed to high temperatures and abrasive materials.
Glass & Ceramics
Revenue is captured from refractory consumption in glass melting and ceramic firing operations, including melting furnaces, regenerators, forehearths, kiln linings, channels, and other high-temperature processing equipment.
Non-Ferrous Metals
Revenue is captured from refractory consumption in the production and processing of aluminum, copper, nickel, zinc, lead, and other non-ferrous metals, including smelting furnaces, converters, anode furnaces, holding furnaces, ladles, and refining equipment.
Others
Includes revenue from refractory consumption in chemicals and petrochemicals, thermal power, foundries, waste-to-energy, and other high-temperature industrial applications, including boilers, reactors, incinerators, reformers, gasifiers, and process furnaces.
Estimation Model
Layer Name
Key Question
Description
Addressable Industrial Production Base Layer
What is the potential demand base for refractories?
Quantify the production and operating base of major refractory-consuming industries, including iron & steel, cement & lime, glass & ceramics, non-ferrous metals, chemicals & petrochemicals, thermal power, and other high-temperature industries. Assess production volumes, operating capacity, technology mix, furnace and kiln configurations, utilization rates, and new capacity additions to establish the addressable refractory consumption base.
Refractory Consumption Intensity Layer
How much refractory is consumed per unit of industrial output?
Establish industry- and process-specific refractory consumption coefficients, expressed as kg or tons of refractory consumed per ton of industrial output or relevant operating unit. Account for differences in furnace technology, process temperature, lining configuration, refractory grade, campaign length, operating conditions, maintenance practices, and replacement frequency.
Refractory Demand Layer
What quantity of refractories is required?
Calculate annual refractory demand by applying the relevant consumption intensity to the corresponding industrial production base. Incorporate requirements from new capacity, initial lining, routine maintenance, relining, repair, replacement, and process-related consumption. The resulting demand is quantified in tons of refractories and segmented by product type, form, and end use.
Pricing & Revenue Layer
What is the monetary value of refractory demand?
Estimate market revenue by multiplying calculated refractory consumption volumes by applicable average selling prices (ASP). Pricing is differentiated by refractory chemistry, product form, grade, application, and end-use industry, with separate consideration of basic and non-basic, shaped and unshaped products. Regional pricing, import/export values, raw material costs, energy costs, and product performance specifications are incorporated, where relevant, to derive representative market values.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Refractory Type Segmentation & Demand Analysis
Detailed assessment of the global refractories industry across shaped and unshaped refractories, including basic, non-basic, alumina, magnesia, silica, monolithic, and other major product categories. The analysis covered product characteristics, applications, consumption patterns, and demand across key end-use industries.
Identifies changes in product preferences, application-specific demand, and opportunities for advanced refractory formulations across major consuming industries.
Refractory Trade & Supply Chain Analysis
Assessment of international trade in refractory products and related materials, covering imports, exports, major trading countries, trade values, volumes, unit values, and sourcing patterns across relevant HS codes.
Evaluates international supply dependence, major sourcing hubs, trade flows, supplier concentration, and potential supply-chain vulnerabilities across key refractory categories.
Refractory Pricing & Raw-Material Analysis
Analysis of refractory pricing based on product type, raw-material composition, manufacturing requirements, energy intensity, transportation costs, and international trade values, supplemented by assessment of major raw materials such as magnesia, alumina, bauxite, graphite, and silica.
Identifies the major factors influencing refractory prices, cost pressures across the value chain, differences between product categories, and opportunities for cost optimization.
Frequently Asked Questions About This Report
Some of the key players of the global refractories market are Alsey Refractories Co.; Calderys (HarbisonWalker International); Chosun Refractories Co., Ltd.; CoorsTek Inc.; Krosaki Harima Corporation; Morgan Advanced Materials; RHI Magnesita; Saint-Gobain SEFPRO; Shinagawa Refractories Co., Ltd.; Vesuvius plc., and others.
The key factor driving the growth of the global refractories market is the expansion of the iron & steel industry, particularly rising steel production and investments in new and upgraded high-temperature processing facilities.
The refractories market in China held the largest share in the Asia Pacific region in 2025.
The non-ferrous metals segment accounted for the second largest market revenue share of 10.8% in 2025.
By end use, the glass & ceramics segment is anticipated to register the fastest CAGR of 10.0% from 2026 to 2033.
Asia Pacific dominated the refractories market with the largest market revenue share of 75.2% in 2025.
The global refractories market size was valued at USD 47.9 billion in 2025 and is estimated at USD 50.9 billion in 2026.
The global refractories market is expected to grow at a compound annual growth rate of 9.5% from 2026 to 2033 to reach USD 96.0 billion by 2033.
By end use, iron & steel accounted for the largest market revenue share of 67.0% in 2025.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


