
- Home
- »
- Plastics, Polymers & Resins
- »
-
Graphic Film Market Size And Share, Industry Report, 2033GVR Report cover

Graphic Film Market (2026 - 2033) Size, Share & Trends Analysis Report By Product Type (Polyethylene, Polypropylene, Polyvinyl Chloride), By Film Type (Opaque, Transparent), By Manufacturing Process, By Printing Technology, By End Use Industry, By Region, And Segment Forecasts
Market Size, 2025
$34.8BMarket Estimate, 2026
$37.1BMarket Forecast, 2033
$59.4BCAGR, 2026–2033
7.0%Graphic Film Market Summary
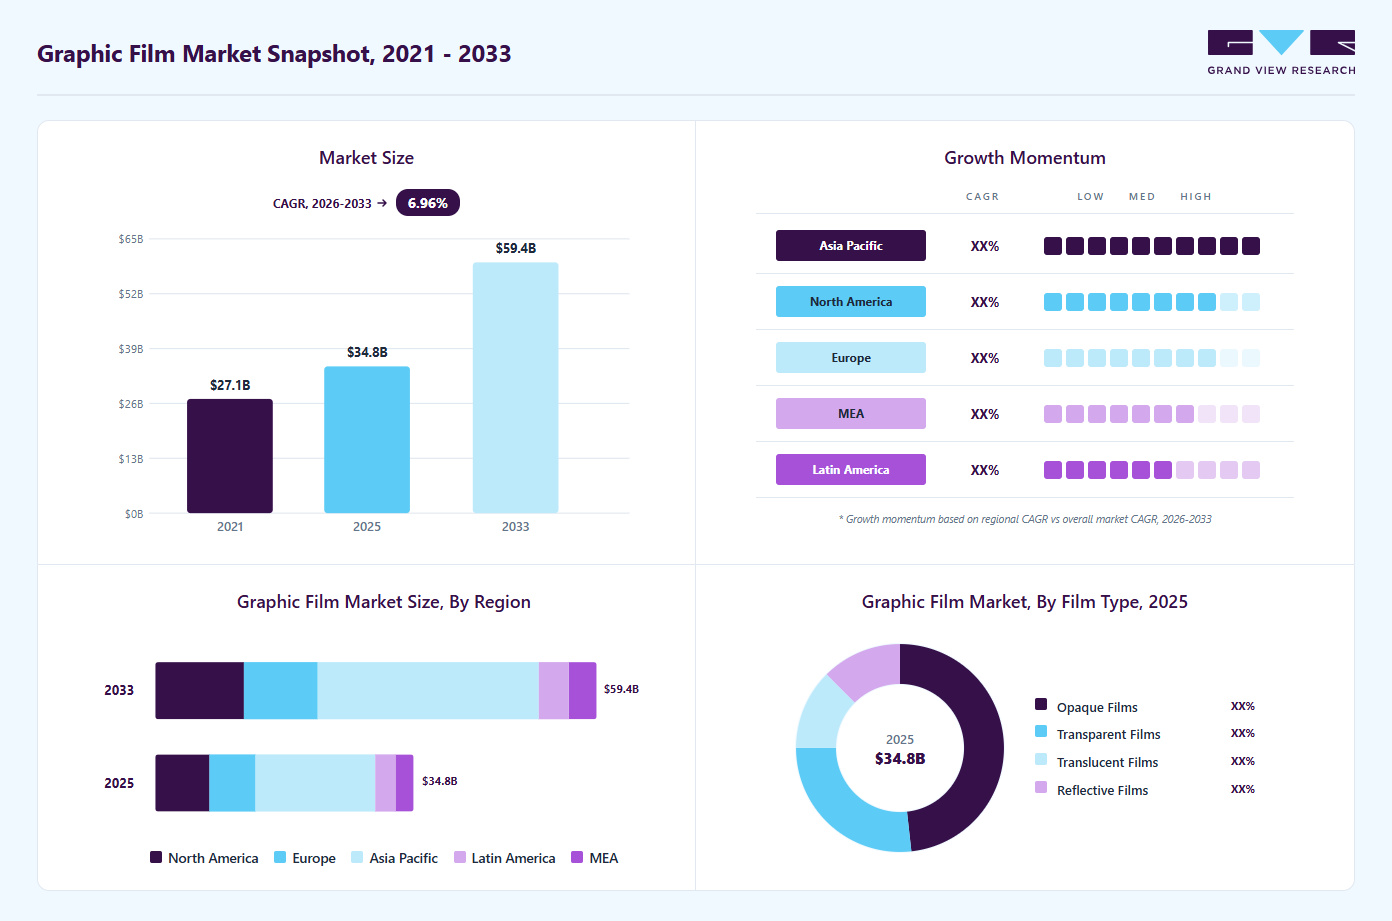
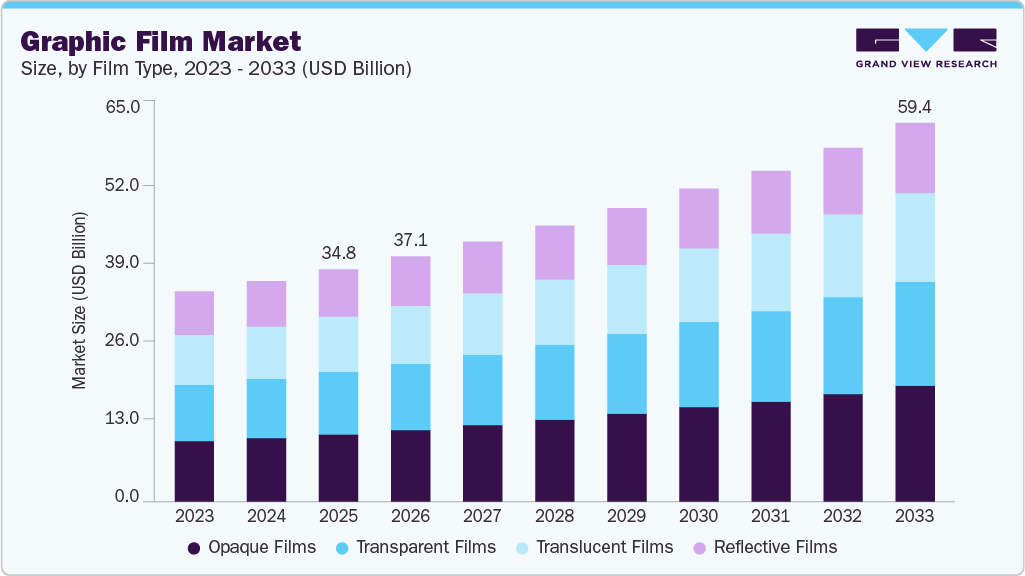
The global graphic film market size was valued at USD 34.8 billion in 2025 and is projected to grow from USD 37.1 billion in 2026 to USD 59.4 billion by 2033, at a CAGR of 7.0% from 2026 to 2033. The Asia Pacific graphic film market held the largest share of 46.3% of the global market in 2025. Graphic films offer versatility in applications, ranging from vehicle wraps and window graphics to safety signs and decorative elements.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By film type: Reflective films segment is expected to grow at the fastest CAGR of 7.7% from 2026 to 2033.
- By product type: Polyvinyl chloride segment accounted for the largest market revenue share in 2025.
- By manufacturing process: Calendered film segment accounted for the largest market revenue share in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (46.3% revenue share, 2025)
- By country: The graphic film industry in India held the largest revenue share in the Asia Pacific in 2025.
Market Size & Forecast
- Market size in 2025: USD 34.8 Billion
- Estimated market size in 2026: USD 37.1 Billion
- Projected market size by 2033: USD 59.4 Billion
- CAGR (2026-2033): 7.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
 To learn more about this report, Download Free Sample Report
These films are preferred due to their durability, high-quality printability, and ability to enhance visual appeal. The growing trend of vehicle customization and the need for effective advertising solutions are major factors driving the market. In addition, advancements in printing technologies such as digital printing are enhancing the capabilities and applications of graphic films. The market is also seeing a shift towards environmentally friendly materials and processes, with increased adoption of recyclable and biodegradable films.Market Dynamics
The market for graphic films is experiencing significant growth as there is a rising demand for visually striking advertising and branding options in retail, transportation, commercial infrastructure, and corporate sectors. Graphic films are widely utilized for vehicle wraps, outdoor advertising, promotional signage, window graphics, and point-of-sale displays because of their durability, print quality, versatility, and simple application process. An increase in investments aimed at enhancing brand visibility and outdoor marketing initiatives is greatly contributing to the growth of the market.
Moreover, the rising use of digital printing technology and tailored visual communication options is driving the demand for high-quality graphic films. Companies are more frequently using removable, printable, and weatherproof films for both short-term and long-term promotional purposes. The increase in trends related to automotive customization, fleet branding, and architectural graphics is further broadening the range of applications for graphic films in both developed and emerging markets.
The graphic films industry encounters restraints due to heightened environmental regulations linked to PVC-based films, adhesive substances, and non-recyclable plastic waste. Regulatory agencies in various regions are enforcing more stringent sustainability and emission criteria, raising compliance and production costs for producers. The rising demand for recyclable and low-VOC graphic film alternatives may also affect operational costs and pricing for products.
Market Concentration & Characteristics
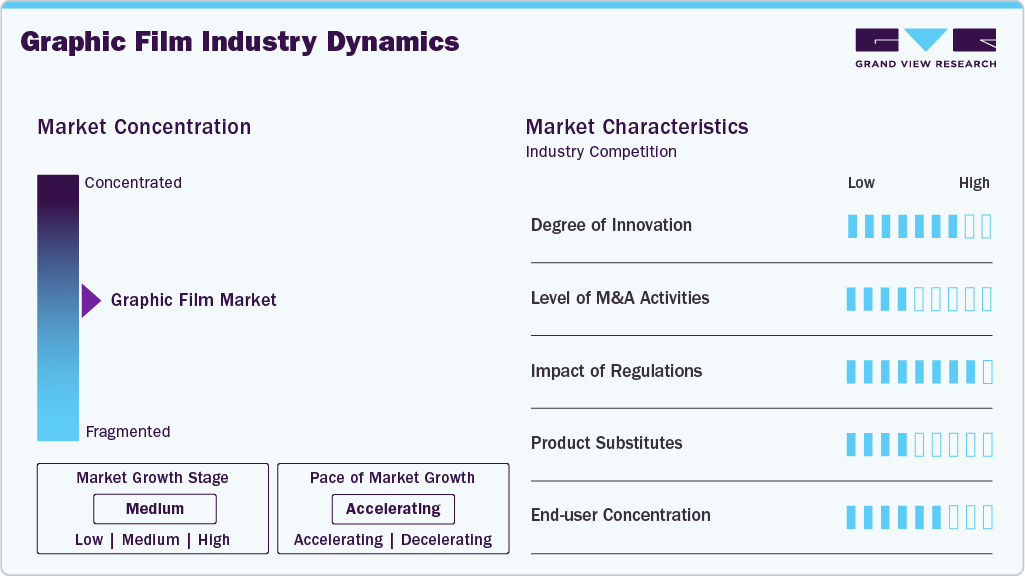
The graphic film industry shows moderate innovation, mainly driven by advances in printability, durability, and adhesive technology. Producers are launching PVC-free films, air-release adhesives, and UV-protective coatings to improve efficacy for vehicle wraps and outdoor signage. Mergers and acquisitions are also at a moderate level, with businesses engaging in acquisitions to broaden their product ranges, bolster regional distribution, and enhance their abilities in specialty films and digital printing applications.
Environmental regulations on plasticizers, VOC emissions, and PVC use are influencing product development in the graphic film sector. Producers are increasingly focusing on recyclable and low-VOC materials to meet evolving regulatory requirements, particularly in Europe and North America. Furthermore, the market faces competition from alternatives such as direct digital printing on hard boards, painted signage, and LED display technologies, even though films remain preferred for their affordability and adaptability.
 To learn more about this report, Download Free Sample Report
The graphic film industry serves a wide range of end users. The main demand comes from advertising and signage companies, commercial printing providers, automotive wrap installers, and retail branding agencies. The large number of small and medium-sized print service providers and signage firms reduces buyer concentration and prevents any single customer group from dominating the market.
Film Type Insights
The opaque films segment led the market with the largest revenue share of 48.2% in 2025. These films are highly favored for their ability to completely block light and view. This makes them ideal for a variety of applications, including vehicle wraps, promotional banners, and decorative purposes. These films provide privacy, protect underlying surfaces, and ensure vibrant, non-fading colors, which are crucial for both indoor and outdoor advertising.
Transparent films are also significant in the market due to their applications in window graphics, automotive window tinting, and packaging. These films allow visibility while providing UV protection and aesthetic appeal. Translucent films, which allow light to pass through but not detailed shapes, are commonly used in illuminated signage and backlit displays, ensuring uniform light diffusion. Reflective films, designed to reflect light, are essential for safety and security applications such as road signs, vehicle markings, and emergency exits, contributing to visibility and safety in low-light conditions.
Product Type Insights
The polyvinyl chloride (PVC) segment led the market with the largest revenue share of 48.3% in 2025. They are extensively used in various applications such as automotive wraps, signage, and decals. PVC films are preferred for their ease of installation and ability to conform to complex surfaces, making them suitable for a wide range of promotional and decorative uses.
Polyethylene films are known for their excellent resistance to chemicals and moisture, making them suitable for industrial applications and protective packaging. Polypropylene films, on the other hand, offer high clarity and strength, making them ideal for labeling, packaging, and graphic displays. The other category includes specialty films such as polyester and polycarbonate, which are used for their specific properties like high heat resistance and enhanced durability, catering to niche markets.
Manufacturing Process Insights
The calendered film segment led the market with the largest revenue share of 61.9% in 2025. Calendered films are produced by pressing the material through rollers, resulting in smooth and even films. This process is cost-effective and well-suited to high-volume production, making calendered films popular for signage, decals, and general graphic applications.
Casting, a more premium process, involves pouring the material onto a casting sheet and curing it. Cast films are generally of higher quality, offering better conformability and durability compared to calendered films. They are preferred for high-end applications such as vehicle wraps and premium advertisements due to their superior performance and longer lifespan.
Printing Technology Insights
The flexography segment led the market with the largest revenue share of 53.6% in 2025. Flexography is a widely used printing technology for printing large volumes of graphics on various substrates, including packaging films, labels, and promotional materials. It is favored for its high speed and cost-effectiveness.
Rotogravure printing is known for its high-quality output and ability to print fine details. This technology is often used for high-end packaging, decorative films, and applications where print quality is paramount. Offset printing offers excellent print quality and consistency, making it ideal for producing detailed graphics and images. It is commonly used in the production of labels, decals, and other printed materials requiring high-resolution output. Digital printing technology offers flexibility and quick turnaround times, making it suitable for short-run and customized printing.
End Use Insights
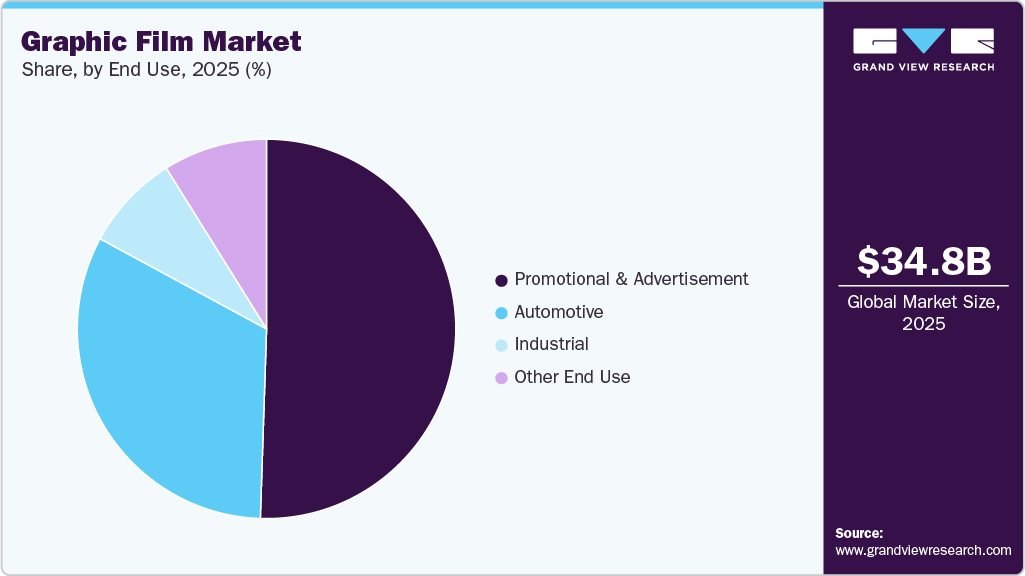
The promotional & advertising segment led the market with the largest revenue share of 50.5% in 2025. These films are widely used in creating eye-catching banners, posters, billboards, and point-of-sale displays. Their ability to deliver vibrant, high-resolution graphics makes them essential for effective marketing campaigns. In the industrial sector, graphic films are used for labeling, safety signage, and protective applications. Their durability and resistance to harsh environments make them suitable for industrial use. The "Others" category includes applications in home décor, DIY projects, and architectural films for decorative purposes, offering a cost-effective solution to enhance the visual appeal of interiors and exteriors.
 To learn more about this report, Download Free Sample Report
The automotive sector extensively uses graphic films for vehicle wraps, decals, and window tinting. These films enhance the aesthetic appeal of vehicles, provide protection against environmental elements, and serve advertising purposes. The growing trend of vehicle customization is boosting the demand for graphic films in this sector.
Regional Insights
The graphic film market in North America is driven by the high demand in the automotive and promotional sectors. The region's strong automotive industry, especially in the United States, is a major driver of market growth. In addition, the presence of leading market players and the increasing adoption of advanced printing technologies further bolster market growth. The promotional and advertising industry in North America also significantly drives demand for high-quality graphic films.
U.S. Graphic Film Market Trends
The graphic film market in the U.S. accounted for the largest market revenue share in North America in 2025. The U.S., as a major player in the North American market, is experiencing substantial growth driven by its robust automotive and advertising industries. The trend of vehicle customization and the high demand for visually appealing advertisements drive the market. In addition, stringent road-safety regulations boost the use of reflective, durable graphic films.
Asia Pacific Graphic Film Market Trends
Asia Pacific dominated the global graphic film market with the largest revenue share of 46.3% in 2025 and is projected to grow at the fastest CAGR during the forecast period. Advancements in printing technologies and the availability of cost-effective materials boost market growth in the region. The APAC market is characterized by significant investments in infrastructure and advertising, which further drive demand for graphic films.
 To learn more about this report, Download Free Sample Report
Rapid industrialization, urbanization, and the expanding automotive industry in countries like China, India, and Japan are key factors driving the market. The increasing popularity of vehicle wraps and promotional activities in emerging economies contributes to the demand for graphic films. In addition, advancements in printing technologies and the availability of cost-effective materials boost market growth in the region.
Europe Graphic Film Market Trends
The graphic film market in Europe represents a mature market with steady growth. The region's focus on sustainability and environmental regulations has led to the adoption of eco-friendly graphic films. Countries like Germany, France, and the UK are major contributors to the market, driven by their automotive industries and the need for high-quality promotional materials. The European market is also witnessing a growing demand for digitally printed films due to their customization capabilities and quick turnaround times.
Key Graphic Film Company Insights
The graphic film industry is highly competitive, with several key players operating globally. Prominent companies such as 3M, Avery Dennison Corporation, Hexis S.A.S., Orafol Group, and Arlon Graphics LLC play a crucial role in shaping the industry landscape through continuous innovation and strong global distribution networks. These companies are actively focusing on product advancements, strategic partnerships, and expansion into emerging markets to strengthen their competitive positioning and cater to the growing demand.
Key Graphic Film Companies:
The following key companies have been profiled for this study on the graphic film market.
- 3M
- Avery Dennison Corporation
- Hexis S.A.S.
- Orafol Group
- Arlon Graphics LLC
- Ritrama S.p.A.
- Mactac, LLC
- Dunmore
- The Griff Network
- Spandex AG
- FDC Graphic Films Inc.
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: 3M; Avery Dennison Corporation; Orafol Group; Arlon Graphics LLC; Mactac, LLC; Ritrama S.p.A.; Spandex AG
- Focus on the expansion of premium printable and wrap film portfolios.
- Invest in sustainable graphic film technologies and advanced adhesive solutions.
- Strengthen distribution partnerships and digital printing compatibility across global markets.
- Strong global brand recognition and extensive distribution networks.
- Advanced R&D capabilities supporting high-performance and durable graphic film products.
- Broad application presence across automotive wraps, signage, retail branding, and architectural graphics.
- High dependence on petrochemical-based raw materials and fluctuating resin prices.
- Elevated sustainability compliance and operational costs.
- Premium product pricing may limit penetration in cost-sensitive markets.
Emerging Players: Hexis S.A.S.; Dunmore; The Griff Network; FDC Graphic Films, Inc.
- Focus on niche graphic film applications and customized printing solutions.
- Expand regional distribution capabilities and customer-specific product offerings.
- Strengthen presence in specialty vehicle wrap and signage applications.
- Higher operational flexibility and faster response to changing customer requirements.
- Competitive pricing strategies and specialized application expertise.
- Strong focus on regional markets and customized visual communication solutions.
- Limited global manufacturing scale and distribution reach.
- Narrower product portfolios compared to multinational leaders.
- Lower investment capacity for large-scale R&D and sustainability initiatives.
Recent Developments
-
In February 2026, Avery Dennison introduced the MPI 1903 cast wrapping film, a premium digitally printable film designed for vehicle wraps and outdoor graphics. This latest product expands the company’s cast film offerings and boasts a high-gloss finish, improved print capabilities, and cost-effective solutions for installers and print shops. The launch of this film is intended to strengthen Avery Dennison's position in the growing vehicle wrap and commercial graphics sector while providing a range of performance options to meet diverse customer requirements.
-
In January 2025, Vision Graphics, LLC, backed by Banner Capital Management, revealed its acquisition of Queen of Wraps, a provider based in the U.S. that specializes in wraps for commercial vehicles and graphic installations. This acquisition is intended to enhance Vision Graphics' offerings in fleet branding, vehicle graphics, and large-format printing services, while also reinforcing its position in the commercial graphics and advertising sector.
Graphic Film Market Report Scope
Report Attribute
Details
Market size in 2025
USD 34.8 billion
Estimated market size in 2026
USD 37.1 billion
Projected market size by 2033
USD 59.4 billion
Growth rate
CAGR of 7.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD Million/billion, Volume in Million Square Meters, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, volume forecast, competitive landscape, growth factors, and trends
Segments covered
Product type, film type, manufacturing process, printing technology, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country Scope
U.S.; Canada; Mexico; Germany; France; UK; Italy; Spain; China; India; Japan; South Korea; Australia; Brazil; Argentina; Saudi Arabia; South Africa
Key companies profiled
3M; Avery Dennison Corporation; Hexis S.A.S.; Orafol Group; Arlon Graphics LLC; Ritrama S.p.A.; Mactac, LLC; Dunmore; The Griff Network; Spandex AG; FDC Graphic Films Inc.
Customization scope
Free report customization (equivalent up to 8 analyst’s working days) with purchase. Addition or alteration to country, regional & segment scope
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Graphic Film Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends across sub-segments from 2021 to 2033. For this study, Grand View Research has segmented global graphic film market report based on the product type, film type, manufacturing process, printing technology, end use, and region:
-
Film Type Outlook (Volume, Million Square Meters; Revenue, USD Million, 2021 - 2033)
-
Opaque Films
-
Transparent Films
-
Translucent Films
-
Reflective Films
-
-
Product Type Outlook (Volume, Million Square Meters; Revenue, USD Million, 2021 - 2033)
-
Polyethylene
-
Polypropylene
-
Polyvinyl chloride
-
Others
-
-
Manufacturing Process Outlook (Volume, Million Square Meters; Revenue, USD Million, 2021 - 2033)
-
Calendered
-
Casting
-
Others
-
-
Printing Technology Outlook (Volume, Million Square Meters; Revenue, USD Million, 2021 - 2033)
-
Flexography
-
Rotogravure
-
Offset
-
Digital
-
-
End Use Outlook (Volume, Million Square Meters; Revenue, USD Million, 2021 - 2033)
-
Automotive
-
Promotional & Advertisement
-
Industrial
-
Others
-
-
Regional Outlook(Volume, Million Square Meters; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
Italy
-
Spain
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
-
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
Detailed assessment of the graphic films market across North America, Europe, Asia Pacific, Latin America, and Middle East & Africa, including country-level demand analysis, printing technology adoption, advertising expenditure trends, automotive wrap demand, and regional manufacturing capabilities. The study also evaluated application penetration across signage, vehicle graphics, retail branding, and architectural films.
Identify high-growth regional markets and emerging demand centers. Support regional expansion, distributor alignment, and investment prioritization strategies. Enable better understanding of region-specific market dynamics and competitive intensity.
Competitive Benchmarking
Benchmarking of leading graphic film manufacturers based on product portfolio, adhesive technology, manufacturing capacity, regional presence, sustainability initiatives, pricing competitiveness, and strategic developments. Comparative assessment of operational strengths, innovation capabilities, and application penetration across global and regional market participants.
Recognize areas of competitive positioning that are lacking and compare with industry frontrunners. Assist in strategies for differentiation, assess potential partnerships, and plan for expansion. Facilitate informed strategic choices regarding product placement and market entry.
Pricing Analysis
Evaluation of pricing trends for graphic films based on film categories, material quality, uses, and geographical areas, including an analysis of the price variations for PVC resin, costs of specialty coatings, pricing of adhesives, and the dynamics of supply and demand. The assessment also included a review of past price trends and future pricing predictions for applications in signage, promotional graphics, and vehicle wraps.
Assist in refining pricing strategies and planning for procurement. Enhance insight into cost influences, competitive pricing by region, and areas experiencing margin pressure. Facilitate improved forecasting and commercial planning within graphic film applications.
Frequently Asked Questions About This Report
Key players include 3M; Avery Dennison Corporation; Hexis S.A.S.; Orafol Group; Arlon Graphics LLC; Ritrama S.p.A.; Mactac, LLC; Dunmore; The Griff Network; Spandex AG; FDC Graphic Films Inc.
The growing trend of vehicle customization and the need for effective advertising solutions are major factors driving the market. Additionally, advancements in printing technologies, such as digital printing, are enhancing the capabilities and applications of graphic films.
Asia Pacific dominated with a 46.3% revenue share in 2025.
Polyvinyl chloride (PVC) held the largest share (over 48.0%) in 2025.
The calendered film segment led with a 61.9% revenue share in 2025.
Flexography accounted for the largest revenue share of 53.6% in 2025.
Promotional & advertising held the largest revenue share of 50.5% in 2025.
The opaque film segment led the global graphic film market, accounting for 48.2% of the global revenue in 2025.
The global graphic film market size was valued at USD 34.8 billion in 2025 and is estimated at USD 37.1 billion for 2026.
The global graphic film market is expected to grow at a CAGR of 7.0% from 2026 to 2033, reaching USD 59.4 billion.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


