
- Home
- »
- Medical Devices
- »
-
Handheld Ultrasound Devices Market Size Report, 2026-2033GVR Report cover

Handheld Ultrasound Devices Market (2026 - 2033)
Size, Share & Trends Analysis Report By Technology (3D/4D, 2D, Doppler), By Application (Trauma, Urology), By End Use (Hospitals, Primary Clinics), By Region (North America, Europe, Asia Pacific, Middle East & Africa), And Segment Forecasts
Market Size, 2025
$264.8MMarket Estimate, 2026
$300.3MMarket Forecast, 2033
$728.6MCAGR, 2026–2033
13.5%Handheld Ultrasound Devices Market Summary
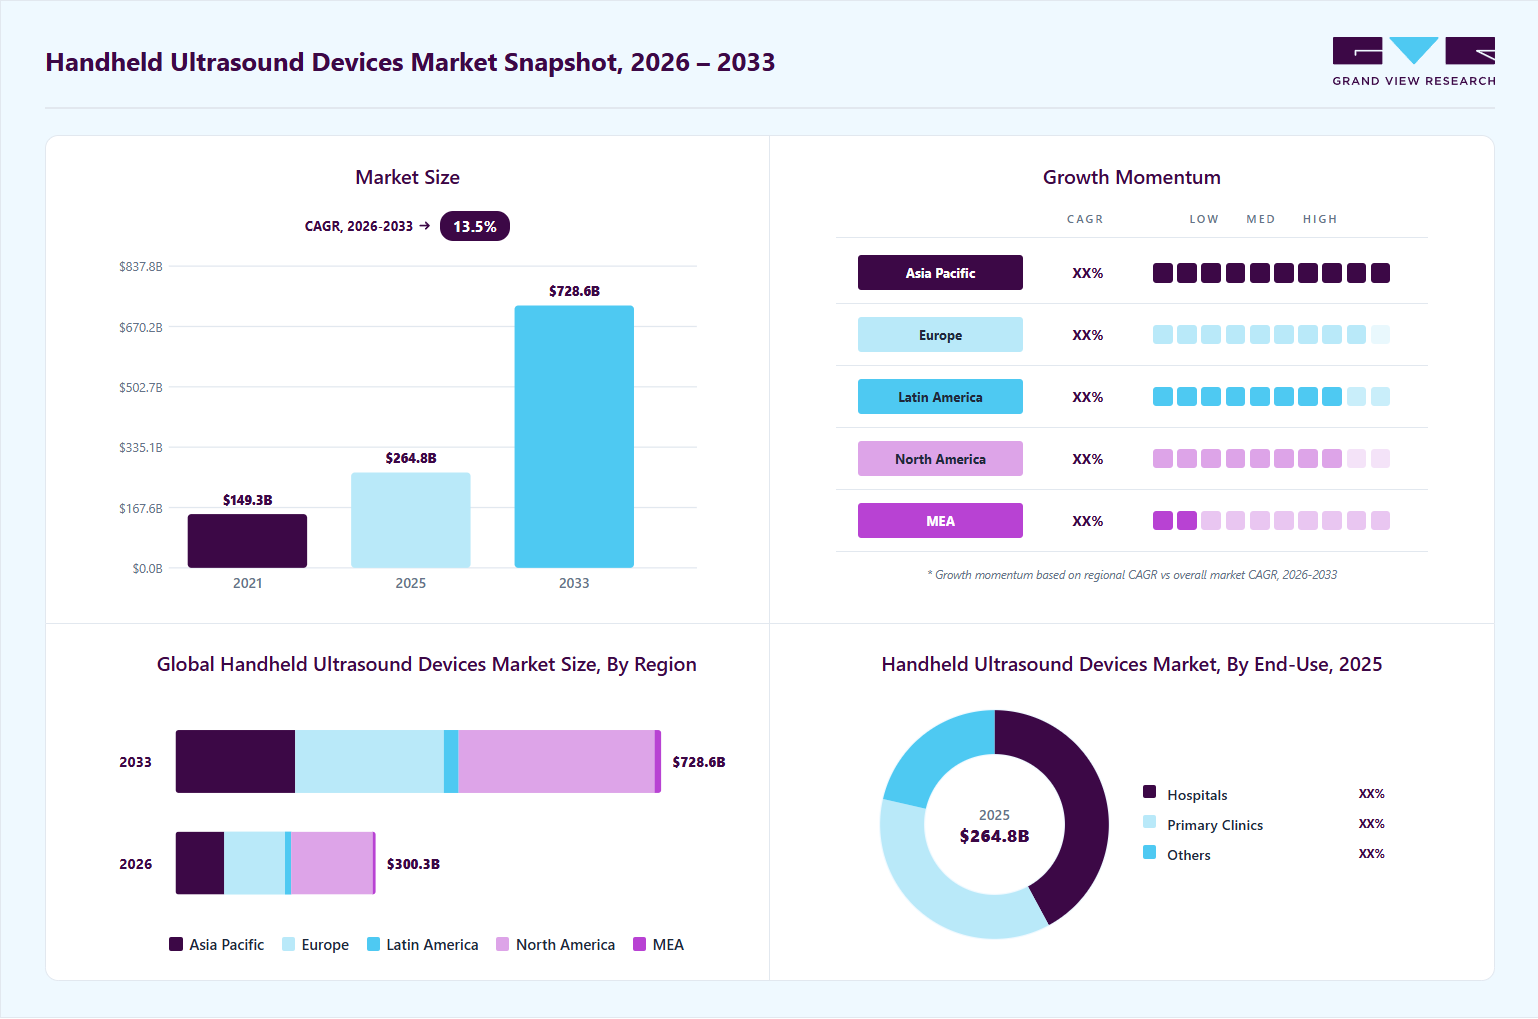
The global handheld ultrasound devices market size was valued at USD 264.8 million in 2025 and is projected to grow from USD 300.3 million in 2026 to USD 728.6 million by 2033, at a CAGR of 13.5% from 2026 to 2033. The North America held the largest share of 40.8% of the global market in 2025. The industry growth is driven by several factors, such as rapid advancements in healthcare technology and the increasing prevalence of chronic diseases, such as gastrointestinal, neurological, endocrine, cardiovascular diseases, and cancer, among older people.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By technology: 3D/4D ultrasound segment led the market with the revenue share of 46.4% in 2025.
- By application: Musculoskeletal segment led the market with the revenue share of 21.6% in 2025.
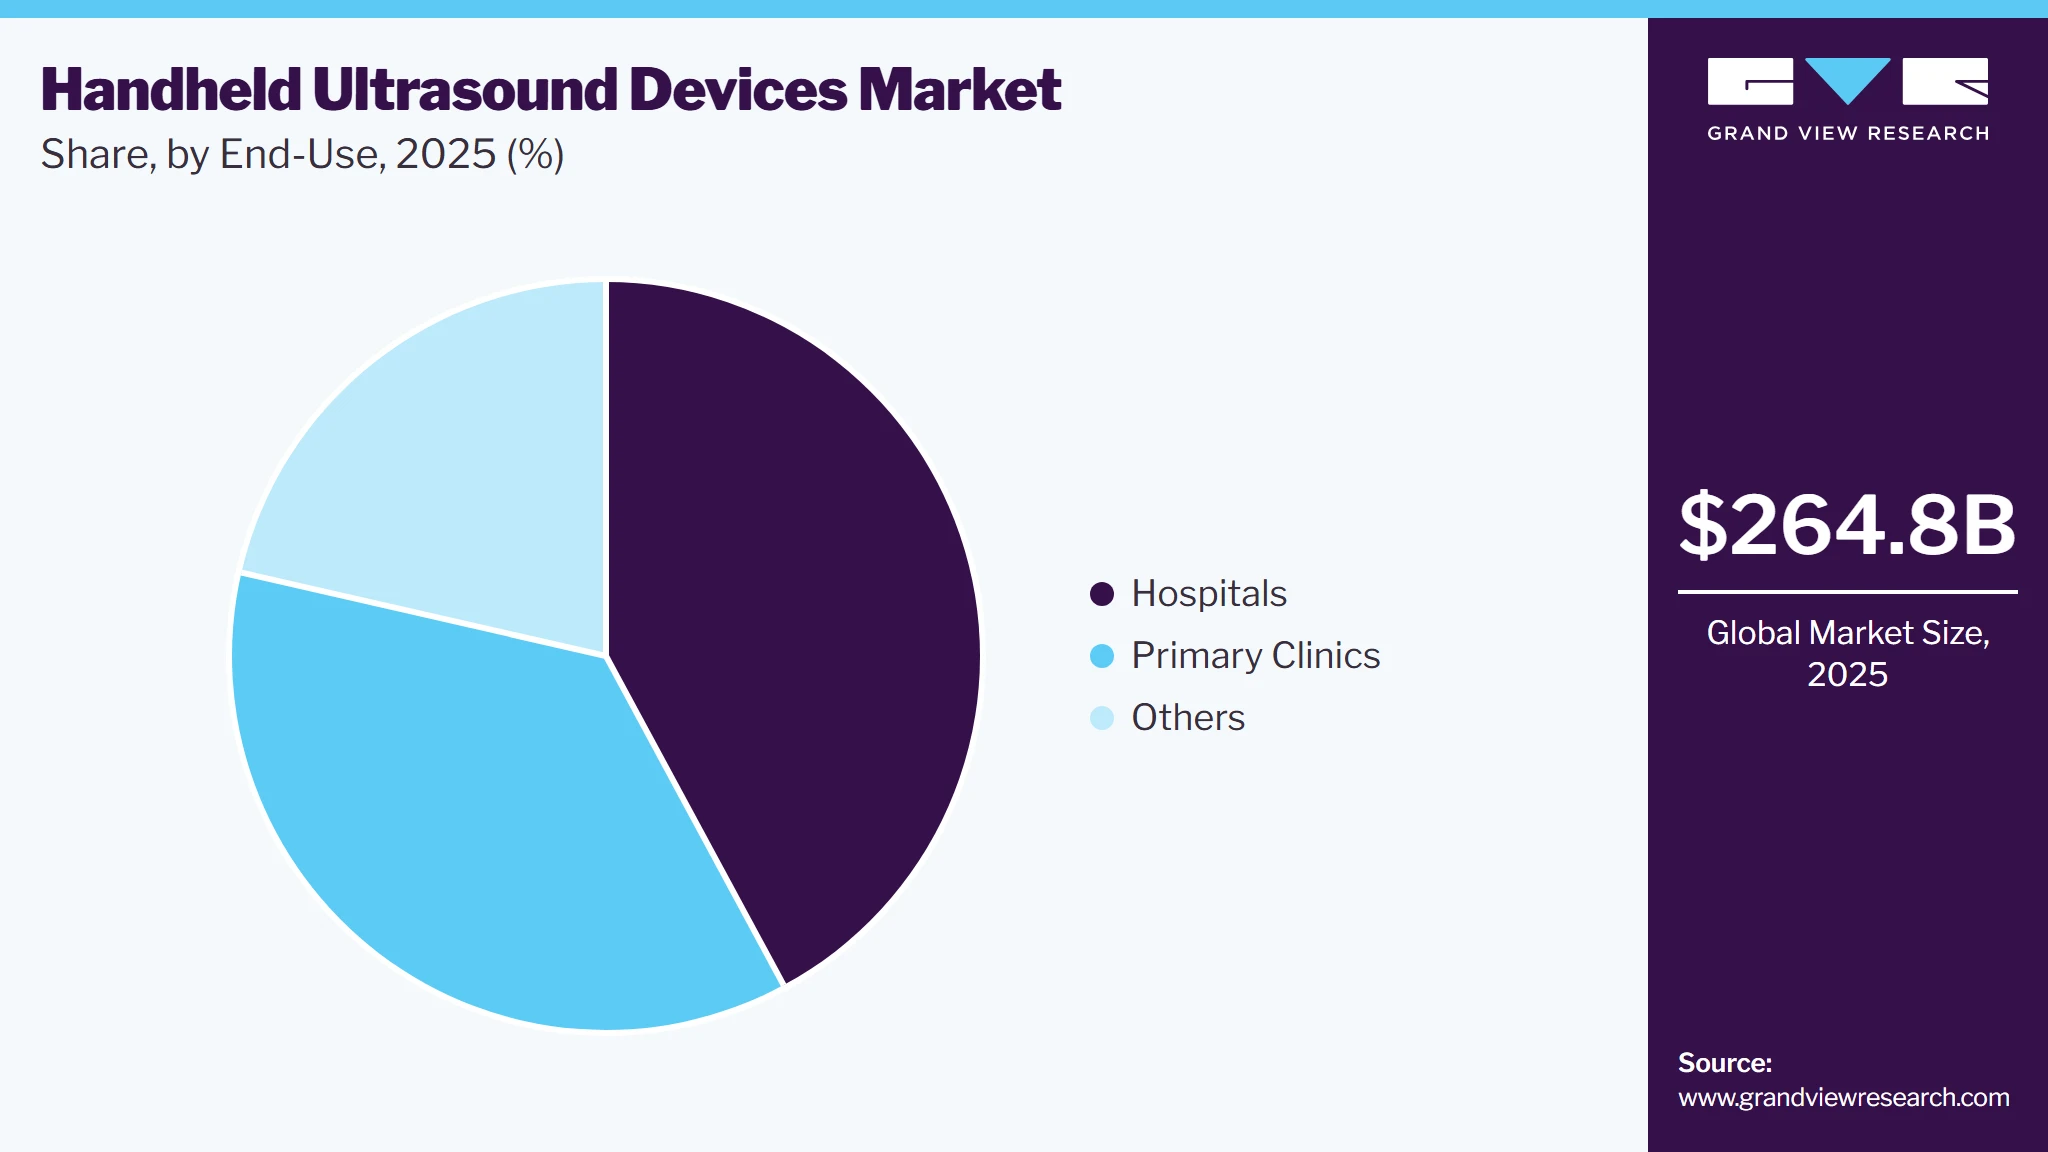
- By end-use: end use, Hospitals segment led the market with the revenue share of 42.1% in 2025.
Regional Highlights
- Largest regional market: North America (40.8% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. led the Europe market in 2025.
Market Size & Forecast
- Market size in 2025: USD 264.8 Million
- Estimated market size in 2026: USD 300.3 Million
- Projected market size by 2033: USD 728.6 Million
- CAGR (2026-2033): 13.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
In addition, the growing demand for home healthcare equipment is fueling market growth. Home ultrasound equipment can assist individuals with chronic pain get some relief and fasten the healing process after an injury. Similarly, homecare therapeutic ultrasound devices are easily accessible and often portable and handheld. Rapid technological advancements in handheld ultrasound systems are expected to enhance the diagnosis and treatment of conditions such as cardiovascular disease and cancer. Rising demand for minimally invasive treatments and advancements in imaging devices, such as 3D and 4D image detailing, accelerated processing speed, automated workflow, and Point-of-Care (PoC) solutions, is expected to boost the adoption during the forecast period. Also, the demand for early diagnosis is increasing, leading to more patients opting for handheld ultrasound devices to obtain instant results.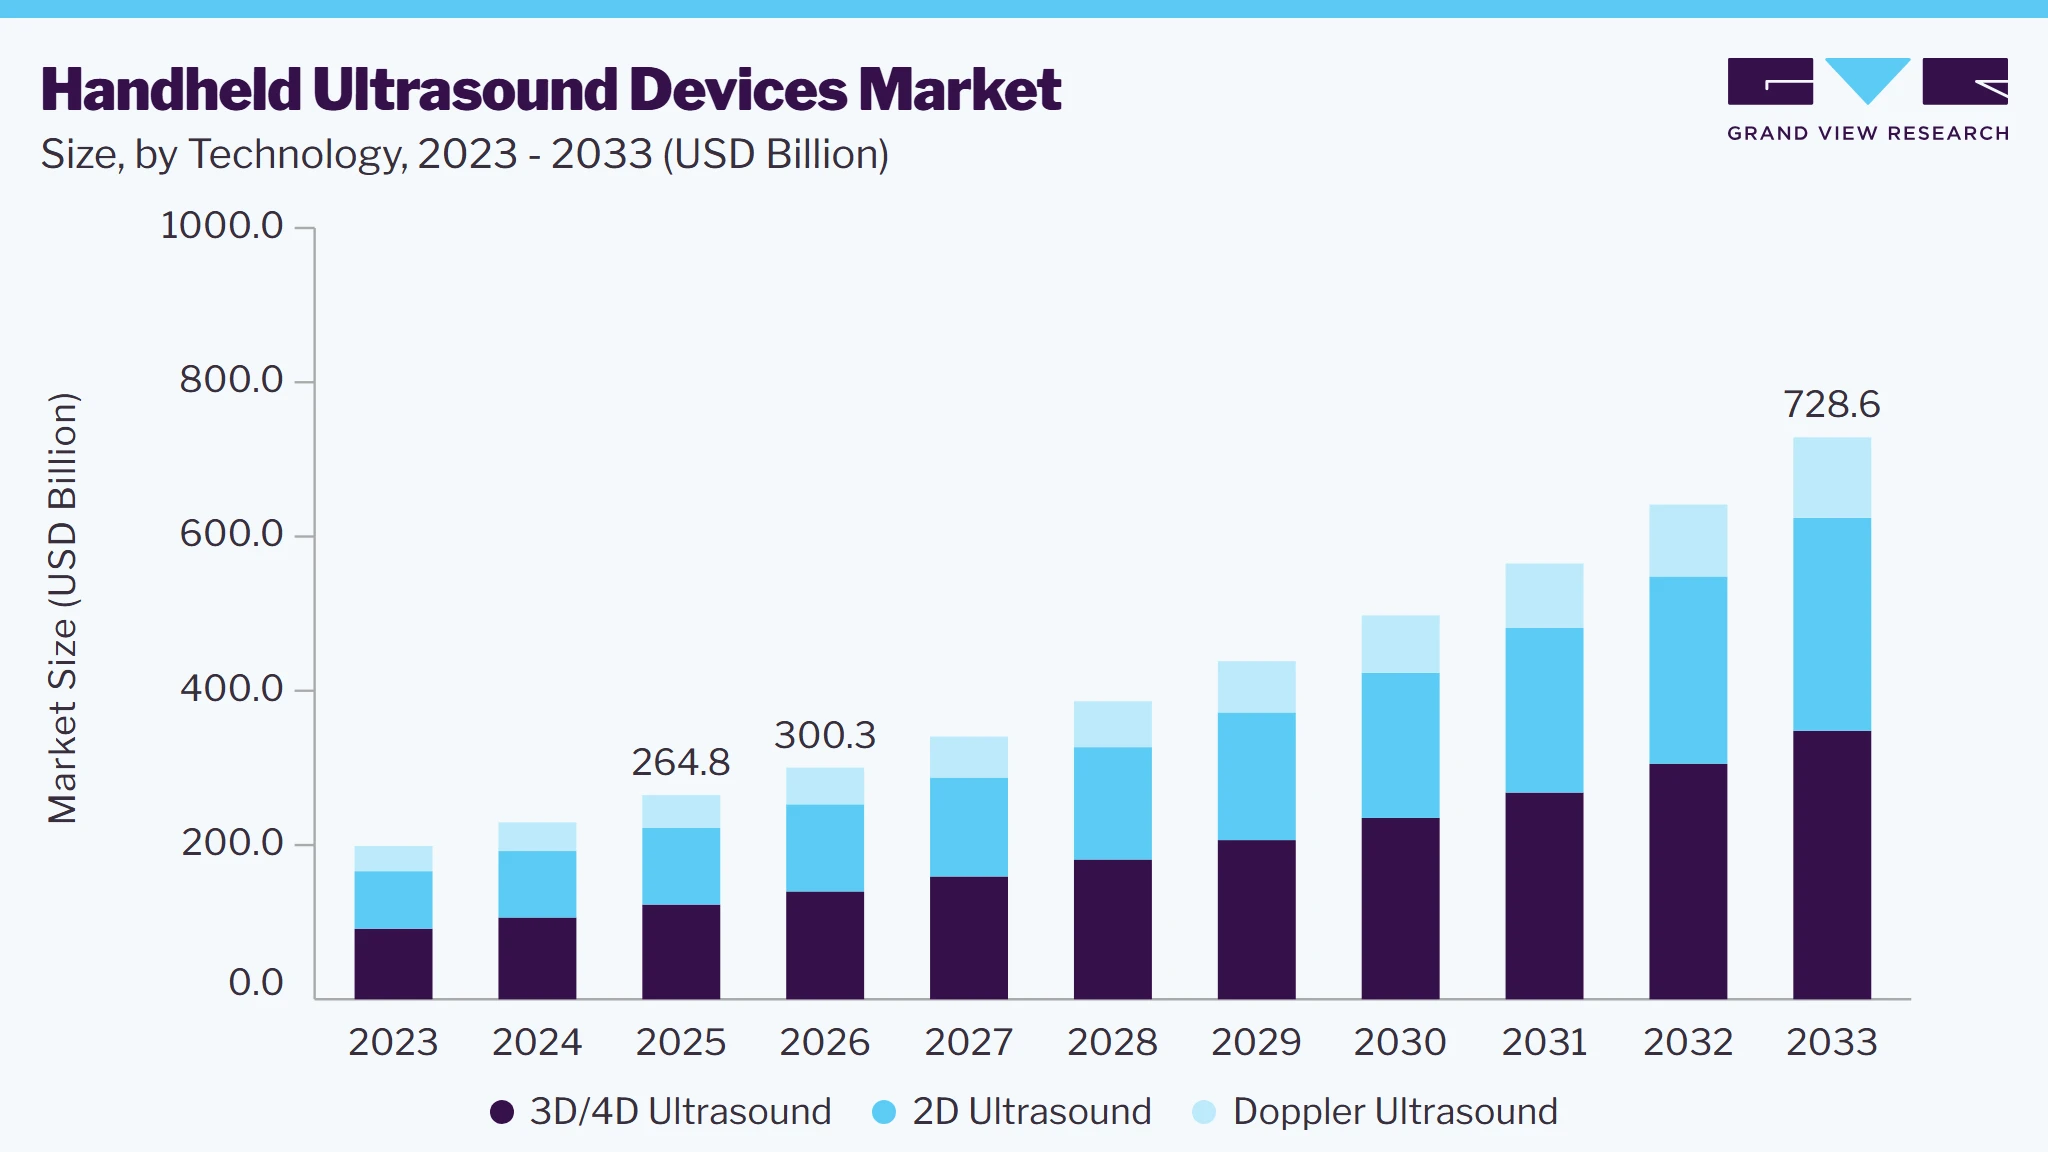 To learn more about this report, Download Free Sample Report
For instance, in November 2025, FUJIFILM Sonosite launched “Sonosite MT”, the latest evolution in its line of portable ultrasound systems. Sonosite MT is developed for seamless use both on and off the stand, offering clinicians mobility without compromising functionality. Featuring an intuitive all-touch user interface, a clinical monitor and control panel, this system delivers a familiar user experience that minimizes workflow disruption and promotes clinician adoption. Moreover, technological advancements in the market are expected to create lucrative growth opportunities in the forecast period. Several handheld ultrasound systems use AI software programs that perform calculations, such as ejection fraction and bladder volume assessment. With the help of image recognition software, structures can be automatically identified and labeled, and the quality of the images produced is continuously monitored.
Most handheld ultrasound devices employ app-based smartphone technology, typically for Android or iOS, which reduces boot times and simplifies complex knobology into easy-to-learn finger swipes and taps, lowering the entry barrier for new users. Numerous handheld ultrasound devices include Health Insurance Portability and Accountability Act (HIPAA)-compliant cloud-based storage with an interface that fosters cooperation and prompt input from distant reviewers without needing middleware.
Powerful smart gadgets allow for remote guidance and tele-ultrasound straight from the device without additional apparatus. In addition, the introduction of novel handheld ultrasound systems is fueling market growth. Due to their portability, ease of use, PoC accessibility, simplified user-friendly controls, and improved image quality with various technologies, such as Doppler imaging. Key and emerging players are developing handheld devices to cater to the market demands. For instance, in February 2023, Shenzhen Mindray Bio-Medical Electronics Co., Ltd. introduced a new handheld ultrasound system, TE Air. It is a compact-sized device with a wire-free design that fits in the pocket, flexible charging for extreme mobility, and high-level disinfection tolerance.
Market Dynamics
Handheld ultrasound devices are gaining significant traction across healthcare settings as they enable physicians, emergency care providers, primary care practitioners, and point-of-care users to perform rapid diagnostic imaging through compact, portable, and user-friendly ultrasound platforms. These devices integrate advanced technologies such as high-resolution imaging, wireless connectivity, artificial intelligence (AI)-assisted image interpretation, cloud-based data sharing, and multi-frequency transducers to deliver accurate real-time visualization in diverse clinical environments. Handheld ultrasound systems help healthcare providers address the growing demand for accessible, cost-effective, and point-of-care diagnostics by supporting faster clinical decision-making, improved patient monitoring, expanded access to imaging in remote and underserved regions, reduced dependency on conventional cart-based systems, and enhanced workflow efficiency across emergency medicine, critical care, cardiology, obstetrics, and general practice.
Healthcare professionals increasingly prefer minimally invasive surgeries as they offer several advantages, such as smaller incisions, rapid wound healing, reduced pain, and smaller or no surgical scars. Smaller incisions & lower scope of complications can significantly reduce the overall surgery cost. Moreover, minimally invasive surgeries reduce hospital stays, lowering the chance of patients contracting hospital-acquired infections. Shorter hospital stays also enable patients to return to their normal lives quicker. In addition, reduced hospital stays also help hospitals cut down expenditures, including pharmaceutical, nursing, & other related costs. Minimally invasive surgical procedures are constantly transformed based on innovative advancements, especially in cardiac, orthopedic, ophthalmic, neurological, and oral surgical procedures. The consistent technological advancements in this field provide higher-quality instruments that allow surgeons to perform surgical interventions efficiently without sacrificing patient safety. The improved product designs provide control and accuracy in the operating room. Technological advancements in minimally invasive surgical instruments to offer accuracy, portability, and cost-effectiveness are the factors encouraging key players to launch & improve advanced devices constantly.
The demand for advanced and accurate medical imaging is increasing, leading to the rapid development of advanced, portable, & digital handheld ultrasound devices. Despite the availability of advanced handheld ultrasound devices, the shortage of trained radiologists to operate them is expected to adversely impact the performance & adoption of these devices. The lack of trained radiologists may also result in procedural complications. Moreover, the lack of medical technicians, mainly in developing economies, may influence market growth negatively. The demand for medical imaging is increasing in India owing to growing disposable income, increasing prevalence of chronic diseases, growing penetration of insurance, and an aging population. However, India currently faces a shortage of trained medical staff to operate advanced medical imaging devices. In some parts of India, there is only 1 radiologist for every 100,000 people compared to the U.S., where there is 1 radiologist for every 10,000. The shortage of trained radiologists is increasing the gap between demand and supply of ultrasound imaging for disease diagnosis.
Market Concentration & Characteristics
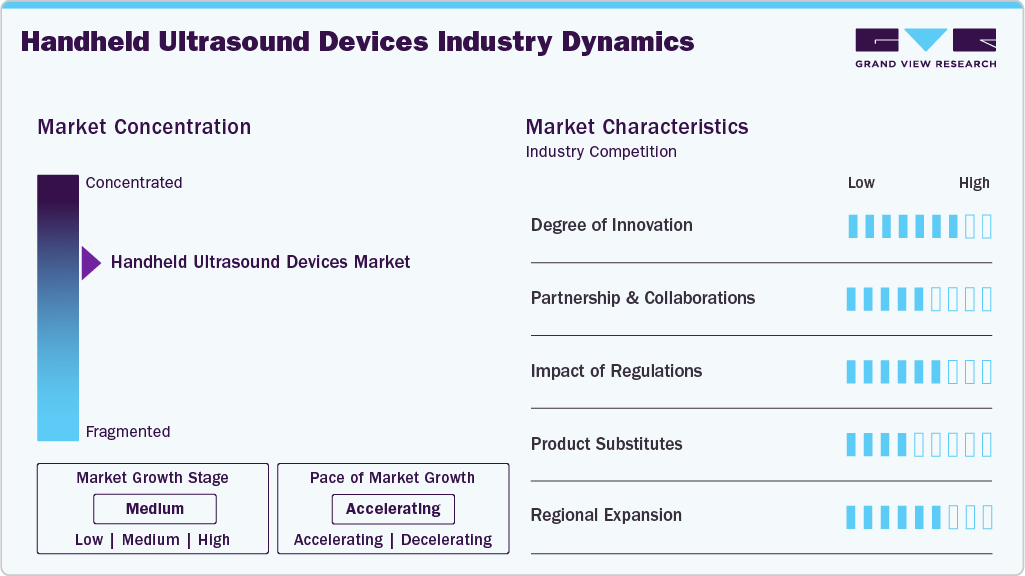
The handheld ultrasound devices industry is expanding due to several factors such as advancements in technology, the growing demand for point-of-care diagnostics, and the rise in chronic diseases. In addition, these devices are affordable and portable, which makes them more accessible to healthcare professionals in various settings including remote locations and primary care clinics. This has made them popular as they help provide quick and accurate diagnoses, enhance patient outcomes, and reduce healthcare expenses.
Companies operating in the handheld ultrasound devices industry are taking several initiatives to expand their market reach. For instance, they are actively pursuing product launches as a strategic approach to increase their product offerings and attract more customers. For instance, in September 2023, Mindray introduced its TE Air Wireless Handheld Ultrasound, which is a compact and wireless imaging solution that improves accessibility to ultrasound. This device can be easily carried in the pocket of healthcare professionals, providing comprehensive scanning capabilities across various clinical scenarios. The TE Air is the industry's first wireless handheld ultrasound device that can be connected to either a mobile device or the touch-based TE X Ultrasound System, making it more versatile and accessible.
 To learn more about this report, Download Free Sample Report
The handheld ultrasound devices industry have undergone significant innovation in recent years, driven by remarkable technological advancements. These advancements have contributed to increased adoption of these devices in various healthcare settings. For instance, in January 2024, Clarius Mobile Health, a leading global provider of wireless ultrasound solutions, received FDA approval for its latest innovation, the Clarius Bladder AI. This non-invasive tool automatically measures bladder volume within seconds, making it a valuable addition to healthcare professionals' diagnostic tools.
Manufacturers of handheld ultrasound devices are increasingly engaging in integration through merger and acquisition activities. This strategic approach enables them to augment their technological capabilities, broaden their market reach, and ensure competitiveness in the rapidly evolving healthcare landscape. For instance, in February 2023, GE Healthcare announced its agreement to acquire Caption Health, Inc., a privately held AI healthcare provider. Caption Health develops clinical applications that leverage artificial intelligence to enable early disease diagnosis and enhance ultrasound scans. This acquisition is expected to enhance GE Healthcare's AI capabilities and expand its portfolio of ultrasound solutions.
Regulations play a crucial role in the development, manufacturing, and marketing of handheld ultrasound devices. These regulations are put in place to ensure that these devices are safe and effective for patients and healthcare professionals. To ensure compliance with regulatory standards, manufacturers must follow guidelines established by regulatory bodies such as the Food and Drug Administration (FDA) in the U.S. and the European Medicines Agency (EMA) in Europe.
Handheld ultrasound devices face competition from several substitute technologies used for point-of-care imaging and bedside diagnostics. These include traditional cart-based ultrasound systems, portable laptop-style ultrasound devices, X-ray and CT imaging for deeper diagnostic applications, and emerging AI-enabled diagnostic tools. In cosmetic and wellness applications, alternative technologies such as radiofrequency (RF), microcurrent, LED therapy, and skin imaging systems may also serves as substitute to handheld ultrasound devices depending on the intended use. However, handheld ultrasound devices continue gaining adoption due to their portability, lower cost, rapid bedside assessment capability, and improved image quality.
The geographical reach of handheld ultrasound devices has been expanding at a moderate to high level, primarily driven by increased adoption in developed economies. As these devices become more affordable and accessible, they are gaining popularity in various healthcare settings across the world. For instance, in January 2024, Butterfly Network, Inc.announced the FDA clearance of its next-generation handheld point-of-care ultrasound (POCUS) system, Butterfly iQ3. The new device is the company’s third iteration of the world’s first semiconductor-based single-probe, whole-body ultrasound system.
Analyst Perspective
The handheld ultrasound devices market is positioned at the intersection of several long-term healthcare, medical technology, and digital health industry trends, including the surging demand for completely non-invasive, point-of-care diagnostics, an increasing clinical focus on immediate bed-side visualization, and continuous advancements in miniaturized acoustic wave-based technologies. Rising clinical needs related to rapid triage assessment, deep-tissue structural evaluation, vascular access guidance, emergency trauma screening, and real-time hemodynamic monitoring are creating significant opportunities for handheld ultrasound device manufacturers and software providers as healthcare professionals seek high-efficacy, highly portable imaging solutions with zero workflow downtime. Furthermore, the dual-market expansion of these platforms-spanning professional hospital installations across emergency departments, intensive care units, and specialized clinics, alongside high-growth decentralized applications in primary care, home healthcare, and remote military medicine is fundamentally transforming the medical imaging landscape.
Technology Insights
Based on technology, the 3D/4D ultrasound segment led the market with the largest revenue share of 46.4% in 2025 and is expected to grow at the fastest CAGR over the forecast period. 3D and 4D handheld ultrasound devices are widely used in cardiovascular monitoring to determine blood flow through arteries and veins. In addition, 3D/4D units are increasingly being used in breast imaging for breast cancer screening, as they provide better visualization of the coronal plane. Therefore, the growing prevalence of cancer is likely to boost the demand for 3D/4D handheld ultrasound devices. For instance, according to the American Association for Cancer Research (AACR), in 2025 over 2 million new cancer cases were diagnosed in the U.S. Also, 3D/4D ultrasound imaging is gaining acceptance in obstetrics/gynecology. These factors are expected to propel the handheld ultrasound device market during the forecast period.
The 2D ultrasound segment is also expected to grow at a significant CAGR from 2026 to 2033. The demand for 2D handheld ultrasound is primarily attributed to its easy user interface and affordable cost. 2D handheld ultrasound devices are more commonly used in obstetrics, cardiology, and women's health. 2D handheld ultrasound devices create black-and-white images that show the baby's skeletal structure and make internal organs visible. The frequent launch of new products that offer improved imaging, workflow, and ergonomic capabilities is anticipated to drive this segment.
Application Insights
Based on application, the musculoskeletal segment led the market with the largest revenue share of 21.6% in 2025, and is expected to grow at the fastest CAGR from 2026 to 2033. The identification, highlighting, and measurement of tendon structures in the foot, ankle, and knee are done automatically by an Artificial Intelligence (AI) used for musculoskeletal (MSK) imaging that operates with handheld point-of-care ultrasound devices. Technological advancements in products and the launch of novel products by industry key players are boosting the industry's growth. GE HealthCare's Vscan Air offers simple patient imaging at the point of care. It assesses diseases, such as joint effusion, tendon and ligament injuries, bone fractures, and inflammation (tendonitis) across the MSK system of the body. MSK ultrasound is utilized with Vscan Air to support injury identification and guided interventions in clinics, radiology, sports medicine, outpatient settings, or everywhere necessary.
The trauma segment is expected to grow at the significant CAGR from 2026 to 2033. Trauma physicians use point-of-care ultrasonography (POCUS) as a helpful imaging method. Rapidly identifying injuries that threaten life and necessitate action is made possible by ultrasonography. A few ultrasound applications in the trauma department include obstetrics, soft tissue/MSK, abdominal ultrasonography of the right upper quadrant and appendix, and testicular and ocular ultrasonography. When traditional diagnostic techniques either take too long or put a person in more danger, ultrasonography is utilized to quickly diagnose a small number of injuries or pathologic diseases in the emergency medicine department.
End Use Insights
Based on end-use, the hospitals segment led the market with the largest revenue share of 42.1% in 2025. This growth can be attributed to the higher number and type of ultrasound studies performed in hospitals than in any other healthcare setting. On average, a hospital may require at least three ultrasound scanners, one dedicated to general radiology, one for obstetrics and gynecology, and one for cardiac scanning. Also, the increasing number of private hospitals to address the growing burden of chronic illness is expected to drive the demand for handheld ultrasound devices. On the other hand, handheld ultrasound is becoming one of the key diagnostic tools during emergency visits and bedside monitoring.
 To learn more about this report, Download Free Sample Report
The primary clinics segment is expected to grow at the fastest CAGR of 14.1% from 2026 to 2033. In primary care, POCUS has been shown to increase the physician’s ability to detect heart failure accurately, improving management. It was also more sensitive to identifying pneumonia than the combined chest X-ray and clinical examination. POCUS is the benchmark of care for procedural guidance and enables the clinician to quickly recognize a variety of life-threatening entities and guide the management of hemodynamically unstable patients.
Regional Insights
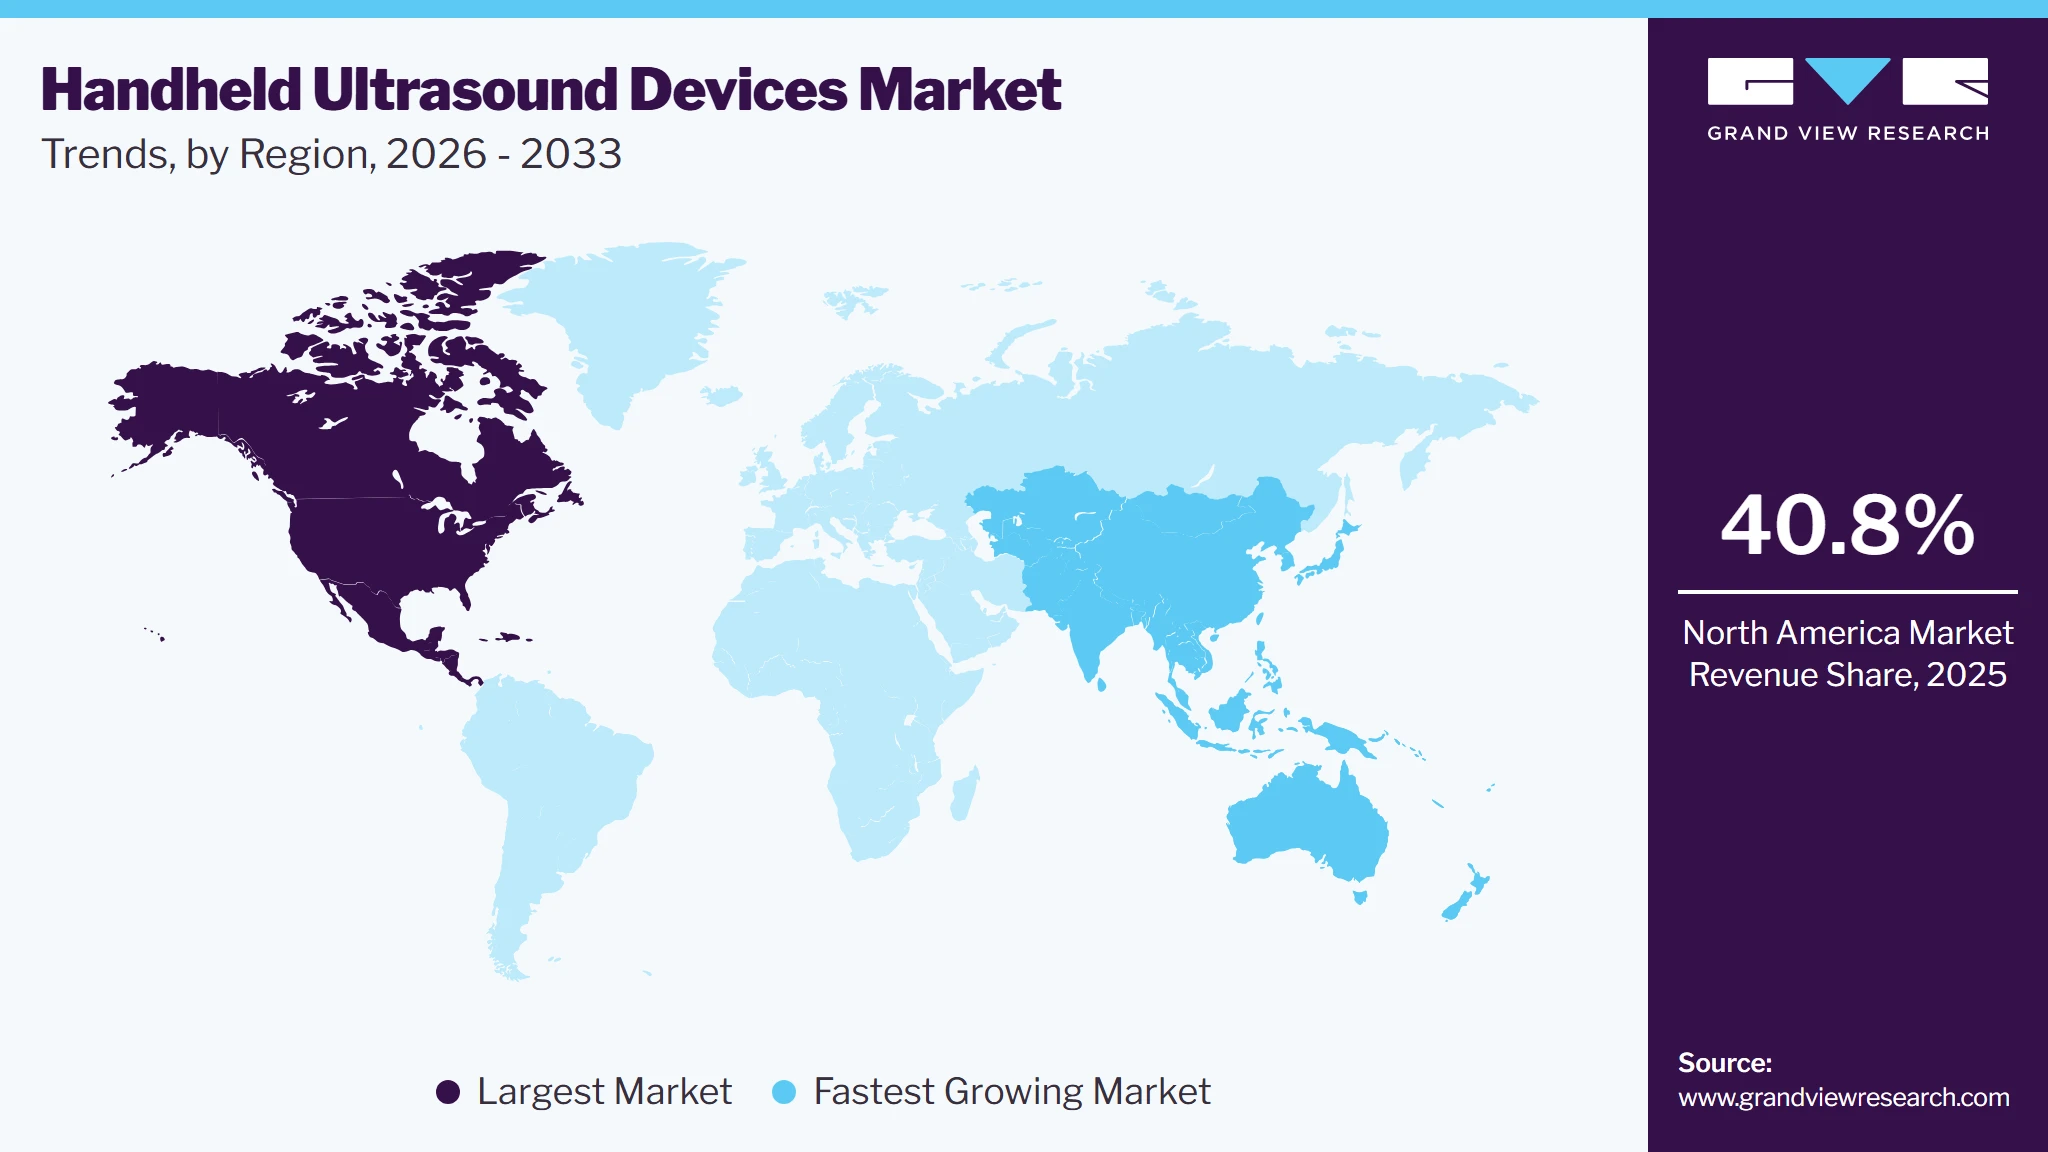
North America dominated the handheld ultrasound devices market with the largest revenue share of 40.8% in 2025 with the largest share of around 40.8%. Owing to factors such as the increased use of ultrasound technology in primary care settings, easy accessibility, and high healthcare spending in countries with effective reimbursement policies. The growing incidence of chronic disorders in this region, including breast cancer, cardiovascular disorders, and neurological diseases, has created a high demand for imaging analysis. The region is expected to maintain its dominance over the forecast period. Technological innovations and the growing incidence of chronic conditions are anticipated to propel the handheld ultrasound device market in the region.
 To learn more about this report, Download Free Sample Report
U.S. Handheld Ultrasound Devices Market Trends
The handheld ultrasound devices market in the U.S. held the largest share in the North America region in 2025. The handheld ultrasound devices market in U.S. is expected to grow over the forecast period, driven by aging demographic trends, advancing technologies, changing patient care strategies, and evolving epidemiological patterns. As the population ages, the demand for portable and affordable diagnostic solutions is increasing, making handheld ultrasound devices a popular choice for healthcare professionals. In addition, the emergence of new technologies is enhancing the capabilities of these devices, making them a valuable addition to healthcare practices.
Europe Handheld Ultrasound Devices Market Trends
Most of the European countries such as France, the UK, and Germany have a high per capita income and well-defined healthcare policies that facilitate improved diagnostic systems. Rapidly aging population in these countries is propelling the demand for advanced healthcare facilities such as ultrasound. In addition, there are constant advancements in technologies owing to large investments in healthcare research. Rising demand for healthcare devices and growing prevalence of chronic disorders & pain-associated disorders in Europe are some of the major factors anticipated to propel handheld ultrasound devices market in Europe.
The handheld ultrasound devices market in UK is expected to grow at the fastest rate over the forecast period owing to technological advancements, growing awareness regrading diagnostic imaging methods and the increasing prevalence of chronic disorders. The handheld ultrasound devices market in the UK is one of the major markets in the region. Furthermore, the presence of efficient reimbursement policies and the growing burden of chronic illness are contributing to the increasing number of scanning procedures. Furthermore, the UK market is expected to witness considerable growth over the forecast period due to the increasing geriatric population, growing prevalence of lifestyle diseases, and the presence of key players in the market.
The handheld ultrasound devices market in Germany is expected to grow over the forecast period due to the need for advanced and efficient diagnostic devices, the presence of a sophisticated healthcare system, and a highly qualified workforce. These factors are anticipated to increase the adoption of handheld ultrasound devices in Germany and drive market growth.
Asia Pacific Handheld Ultrasound Devices Market Trends
The handheld ultrasound devices market in Asia Pacific is anticipated to exhibit fastest CAGR over the forecast period. The handheld ultrasound devices market in Asia Pacific is anticipated to exhibit significant growth over the forecast period. This can be attributed to rapid growth of the population and increased R&D activity in this region. In addition, there is a high need for traditional and as well as advanced devices in Asia Pacific. Moreover, the supportive government initiatives for improving healthcare infrastructure in the region likely to contribute to the regional growth positively during the forecast period. The presence of a large population with low per capita income in Asia Pacific countries has led to a high demand for affordable treatment options.
Handheld ultrasound devices market in China is expected to grow owing to the changes in demographics & disease patterns and the growth of the private healthcare sector. The number of private hospitals is increasing every year, including those delivering specialized care, such as maternity and orthopedic treatment centers. This can be attributed to the allowance of foreign investments in the country’s healthcare sector.
The handheld ultrasound devices market in Japan is projected to experience the fastest growth, over the forecast period. This growth can be attributed to the country's strong focus on technological innovation and Research & Development (R&D), providing an ideal environment for the advancement of handheld ultrasound devices technology.
Latin America Handheld Ultrasound Devices Market Trends
The handheld ultrasound devices market in Latin America is anticipated to undergo moderate growth throughout the forecast period. This growth is driven by several factors, including the presence of rapidly developing economies (such as Brazil & Mexico). Availability of advanced imaging procedures at a reduced cost compared to North America & Europe is making Latin America more attractive for medical tourism.
The handheld ultrasound devices market in Brazil dominates the market in Latin America, over the forecast period. This growth can be attributed to the increase in the number of healthcare reforms and overall expenditure. In addition, several U.S. hospitals are affiliated with Brazilian hospitals for telemedicine, education, and second-opinion programs. Thus, an increase in demand for better healthcare facilities is anticipated to boost market growth.
Middle East & Africa (MEA) Handheld Ultrasound Devices Market Trends
The handheld ultrasound devices market in the Middle East & Africa is anticipated to experience moderate growth during the forecast period owing to the increased focus of countries like Saudi Arabia and Kuwait towards enhancing their healthcare sectors.
The handheld ultrasound devices market in Saudi Arabia is expected to grow at a significant rate owing to technological advancements and growing awareness regarding early diagnosis by imaging devices. Technological innovation is another key factor driving changes in the healthcare industry in the country at a significant rate. The country is focusing on the digitalization of healthcare by leveraging innovative technologies, such as AI, big data, and cloud computing.
Key Handheld Ultrasound Devices Company Insights
The competitive scenario in the handheld ultrasound devices market is highly competitive, with several market players competing to enhance their market positions. The major companies are undertaking various organic as well as inorganic strategies such as new product development, collaborations, acquisitions, mergers, and regional expansion for serving the unmet needs of their customers. Some of the major participants in the handheld ultrasound devices market include:
Key Handheld Ultrasound Devices Companies:
The following key companies have been profiled for this study on the handheld ultrasound devices market.
-
GE HealthCare
-
Koninklijke Philips N.V.
-
Shenzhen Mindray Bio-Medical Electronics Co., Ltd.
-
BenQ Medical Technology
-
CHISON Medical Technologies Co., Ltd.
-
Dawei Medical (Jiangsu) Corp., Ltd.
-
Viatom Technology Co., Ltd.
-
Telemed Medical Systems S.r.l.
-
Butterfly Network, Inc.
-
Pulsenmore Ltd.
-
Leltek Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (GE HealthCare, Koninklijke Philips N.V., Shenzhen Mindray Bio-Medical Electronics Co., Ltd.)
Mature companies focus on expanding handheld ultrasound portfolios across wireless, smartphone-compatible, AI-enabled, and point-of-care imaging applications for different indications.
Companies emphasize advanced imaging quality, AI-assisted workflow optimization, cloud connectivity, tele-ultrasound integration, subscription-based software ecosystems, and strategic partnerships with hospitals and healthcare systems to strengthen market positioning and clinician adoption globally.
Established manufacturers benefit from strong brand recognition, extensive distribution and service networks, broad regulatory approvals, diversified imaging portfolios, and long-standing relationships with hospitals, clinics, and healthcare providers worldwide.
Advanced technologies such as semiconductor-based ultrasound-on-chip platforms, AI-guided image acquisition, real-time cloud sharing, interoperability with healthcare IT systems, and premium imaging performance enhance customer confidence and competitive differentiation.
High R&D investments, intense market competition, rapidly changing beauty trends, and continuous product innovation requirements increase operational complexity for established companies.
Large organizations may experience slower product innovation cycles due to complex manufacturing processes, software validation requirements, reimbursement challenges, and increasing competition from portable ultrasound startups offering lower-cost solutions.
Emerging Players (Telemed Medical Systems S.r.l., Butterfly Network, Inc, Pulsenmore Ltd.)
Emerging companies focus on affordable handheld ultrasound systems, niche clinical applications, AI-assisted imaging platforms, compact wireless devices, and direct-to-clinician or digital sales models targeting underserved and point-of-care settings
These players prioritize innovation-driven strategies including telemedicine integration, cloud-based imaging platforms, portable battery-powered devices, rapid product launches, and expansion into rural healthcare, ambulatory care, home healthcare, and veterinary applications.
Emerging companies benefit from faster innovation cycles, flexibility in adopting AI-integrated solutions, user-friendly handheld ultrasound devices tailored for point-of-care and remote healthcare environments.
Their ability to integrate smartphone-based workflows, subscription software models, AI-guided diagnostics, and cost-effective imaging solutions strengthens differentiation within the competitive landscape.
Emerging companies face limited financial resources, lower brand recognition, smaller distribution networks, and restricted access to large hospital procurement networks compared to multinational imaging companies.
Challenges in manufacturing operations, obtaining regulatory certifications, maintaining quality, and sustaining long-term consumer trust may restrict broader commercial expansion.
Recent Developments
-
In December 2025, Clarius Mobile Health announced new FDA clearances for additional AI-powered ultrasound applications, including Clarius Prostate AI and Median Nerve AI, while expanding its handheld ultrasound portfolio and global distribution network.
-
In January 2025, GE HealthCare received FDA 510(k) clearance for its upgraded Voluson Expert Series ultrasound systems integrating AI-powered workflow and imaging enhancement features for women’s health applications.
-
In January 2024, Clarius Mobile Health received CE Mark approval for its Clarius PAL HD3 wireless handheld ultrasound scanner in Europe and the UK. The device integrates phased and linear arrays on a single probe head for whole-body imaging and bedside diagnostics.
Handheld Ultrasound Devices Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 264.8 million
Market size value in 2026
USD 300.3 million
Revenue forecast in 2033
USD 728.6 million
Growth rate
CAGR of 13.5% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Technology, application, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait;
Key companies profiled
GE HealthCare; Koninklijke Philips N.V.; Shenzhen Mindray Bio-Medical Electronics Co., Ltd.; BenQ Medical Technology; CHISON Medical Technologies Co., Ltd.; Dawei Medical (Jiangsu) Corp., Ltd.; Viatom Technology Co., Ltd.; Telemed Medical Systems S.r.l.; Butterfly Network, Inc; Pulsenmore Ltd.; Leltek Inc,
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Handheld Ultrasound Devices Market Report Segmentation
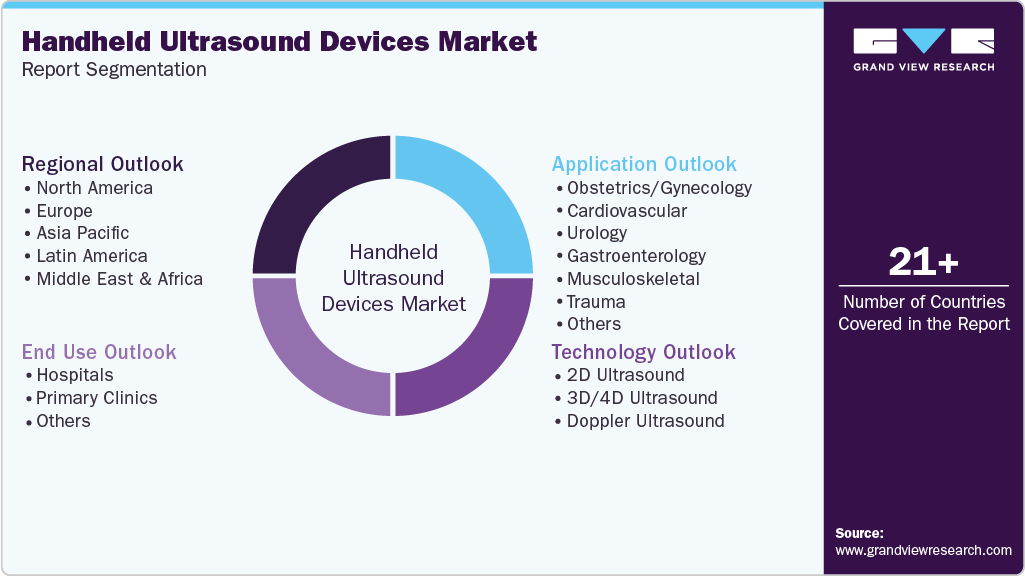
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global handheld ultrasound devices market report based on technology, application, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Technology Outlook (Revenue, USD Million, 2021 - 2033)
-
2D Ultrasound
-
3D/4D Ultrasound
-
Doppler Ultrasound
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Obstetrics/Gynecology
-
Cardiovascular
-
Urology
-
Gastroenterology
-
Musculoskeletal
-
Trauma
-
Others
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Primary Clinics
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The handheld ultrasound devices market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each handheld ultrasound devices segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Technology
Revenue capture definition
2D Ultrasound
Revenue is generated through the sale of portable, handheld devices that utilize high-frequency sound waves to produce flat, two-dimensional, black-and-white grayscale images of internal tissues and organs. Manufacturers earn revenue from initial hardware sales, durable transducers/probes, essential software licenses for image visualization, and basic maintenance or warranty contracts.
3D/4D Ultrasound
Revenue is derived from premium handheld systems equipped with advanced rendering capabilities to capture three-dimensional static images (3D) or live-streaming, real-time moving videos (4D) of internal structures. Market participants generate income from higher-margin hardware sales, specialized multi-element probes, premium software subscription upgrades for volume rendering, and cloud-based storage or sharing capabilities.
Doppler Ultrasound
Revenue flows from handheld devices integrated with specialized Doppler technology (Color, Power, or Spectral Doppler) to measure and visualize blood flow direction, velocity, and vascular resistance. Companies capture value through the sale of dual-functioning imaging probes, advanced diagnostic software plug-ins, and automated calculation packages for hemodynamic assessment.
Segment - Application
Revenue capture definition
Obstetrics/ Gynecology
Revenue is generated through point-of-care (POC) devices optimized for fetal monitoring, gestational age assessment, and pelvic health examinations. Revenue streams include specialized endocavity or curved transabdominal probes, automated biometry software packages, and integrated reporting tools tailored for quick clinical decision-making.
Cardiovascular
Revenue flows from ultra-portable devices designed for rapid cardiac screening (focused cardiac ultrasound - FOCUS) and peripheral vascular assessments. Manufacturers monetize specialized phased-array probes, AI-driven automated ejection fraction (EF) calculation software, and enterprise imaging cloud integrations for rapid cardiology review.
Urology
Revenue is captured through handheld tools designed for bedside bladder volume measurements, prostate screenings, and renal assessments. Income is driven by specialized transrectal or abdominal probes, dedicated automated bladder-volume scanning software, and disposable probe covers/consumables used during interventional procedures.
Gastroenterology
Revenue is derived from compact devices used for rapid abdominal imaging, liver assessments, and fluid detection (e.g., ascites). Monetization focuses on versatile curvilinear probes, specialized imaging modes like shear-wave elastography for liver fibrosis, and telemedicine licenses for remote specialist consultation.
Musculoskeletal
Revenue is generated through high-frequency handheld scanners optimized for high-resolution, superficial imaging of muscles, tendons, ligaments, and joints. Manufacturers earn from high-frequency linear probes, specialized needle-visualization software for ultrasound-guided injections, and orthopedic-specific digital documentation tools.
Trauma
Revenue flows from ruggedized, rapid-booting handheld units deployed in emergency medicine and critical care settings for FAST (Focused Assessment with Sonography for Trauma) exams. Income is driven by durable, multi-purpose single-probe systems, automated lung-sliding detection software, and recurring revenue from heavy-duty protective casings and mounting hardware.
Others
Revenue is captured from niche or emerging clinical applications, including endocrinology (thyroid), pulmonology, and anesthesiology (nerve blocks). Revenue is sustained through flexible software licensing, specialized regional anesthesia guidance apps, and versatile multi-frequency probe attachments.
Segment - End Use
Revenue capture definition
Hospitals
Revenue is generated from large-scale procurement contracts, fleet management agreements, and enterprise-wide software licensing across Emergency Departments, ICUs, and various wards. Manufacturers capture high-volume hardware sales, tiered enterprise software upgrades, premium tier-1 service/maintenance contracts, and deep integration with Hospital Information Systems (HIS) and PACS.
Primary Clinics
Revenue is derived from the commercialization of cost-effective, user-friendly, and versatile handheld devices for general partitioners and out-of-hospital clinicians. Revenue streams are focused on affordable hardware bundles, pay-per-use or monthly software subscriptions, basic training packages, and standard warranty extensions.
Others
Revenue flows from alternative care settings, including emergency medical services (EMS/ambulances), remote military medicine, home healthcare, veterinary clinics, and medical education institutions. Market participants monetize via ruggedized accessories, portable charging docks, remote telehealth connection subscriptions, and multi-user educational software licenses.
Estimation Model
Scope Definition
Build the Product Base
Estimate Penetration
Revenue Conversion
What is being sized?
How large is total addressable market?
What portion is transitioning to next-generation smart systems?
How does unit volume become market revenue?
PROCESS STEPS
PROCESS STEPS
PROCESS STEPS
PROCESS STEPS
• Define Handheld Ultrasound Devices Categories
• Scope Clinical Applications
• Set Geographic Boundaries
• Align on base year & forecast horizon (2026–2033)
• Profile Healthcare Facilities & Tiering
• Estimate Active Installed Base
• Apply Probe & Configuration Splits
• Model Accelerated Replacement Cycles & Greenfield Expansion
• Assess Semiconductor/Sensor Technology Adoption
• Map Multi-Specialty vs. Single-Purpose Systems
• Evaluate AI & Software Integration
• Factor in Radiopharmaceutical & Isotope Constraints
• Collect Average Selling Prices (ASPs)
• Segment by revenue streams
• Apply Multi-Channel Distribution Share
• Triangulate and Validate
DATA SOURCES
DATA SOURCES
DATA SOURCES
DATA SOURCES
WFUMB, AIUM, EFSUMB
National health service database, WHO, hospital inventory registries
Primary interviews, company filings, trade surveys
Hospital procurement/tender archives, distributor pricing sheets, import/export databases
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Landscape Analysis
Conducted a comprehensive competitive landscape assessment for the global handheld ultrasound devices market, covering major manufacturers offering wireless, smartphone-based, and AI-enabled portable ultrasound systems for point-of-care diagnostics. The study evaluated company positioning, product portfolios, regulatory approvals, strategic collaborations, distribution partnerships, technological advancements in imaging and AI integration, and expansion initiatives across hospitals, ambulatory care centers, emergency medicine, primary care, and veterinary applications. The analysis also assessed innovation trends associated with portability, cloud connectivity, tele-ultrasound capabilities, and workflow optimization adopted by leading market participants.
Enables stakeholders to understand the competitive intensity, technological positioning, and strategic developments shaping the handheld ultrasound devices market. The study supports informed decision-making related to partnerships, product differentiation, innovation investments, commercialization planning, and regional expansion strategies. It also helps manufacturers benchmark competitive capabilities, identify innovation gaps, and strengthen market penetration across point-of-care imaging applications globally.
Segment Analysis (Product and End-use)
Conducted a detailed segment-level assessment of the handheld ultrasound devices market across product categories including wireless handheld ultrasound systems, smartphone/tablet-based devices, dual-probe systems, and AI-enabled portable imaging solutions. The study evaluated adoption trends across hospitals, emergency medicine, critical care, primary care, ambulatory surgical centers, military medicine, and veterinary applications. It further analyzed purchasing trends, pricing strategies, software integration capabilities, portability advantages, reimbursement considerations, and regional demand variations influencing segment growth globally.
Enables stakeholders to gain granular insights into high-growth market segments, evolving end-user requirements, and commercialization opportunities across the handheld ultrasound devices ecosystem. The study supports portfolio optimization, targeted go-to-market strategies, healthcare channel expansion planning, and product development initiatives aligned with point-of-care imaging trends and growing demand for portable diagnostics.
Key Market Drivers Analysis
Conducted an in-depth driver analysis focused on the increasing demand for point-of-care diagnostics, rising adoption of portable imaging technologies, growing prevalence of chronic and cardiovascular diseases, and advancements in semiconductor and AI-enabled ultrasound technologies. The study evaluated trends associated with emergency and bedside imaging, telemedicine integration, healthcare digitization, rural healthcare accessibility, and increasing use of handheld ultrasound devices in non-traditional care settings. It also assessed the impact of miniaturization, cloud-based imaging platforms, and clinician preference for rapid diagnostic decision-making contributing to market growth globally.
Enables stakeholders to understand the core clinical, technological, and operational factors accelerating demand within the handheld ultrasound devices market. The study supports strategic forecasting, investment prioritization, product innovation planning, regional market expansion, and commercialization strategies aligned with evolving healthcare infrastructure needs and point-of-care diagnostic adoption trends worldwide.
Frequently Asked Questions About This Report
Some key players operating in the handheld ultrasound device market include GE HealthCare; Koninklijke Philips N.V.; Shenzhen Mindray Bio-Medical Electronics Co., Ltd.; BenQ Medical Technology; CHISON Medical Technologies Co., Ltd.; Dawei Medical (Jiangsu) Corp., Ltd.; Viatom Technology Co., Ltd.; TELEMED MEDICAL SYSTEMS S.r.l.; Butterfly Network, Inc; Pulsenmore Ltd.; Leltek Inc.; Others
Key factors that are driving the market growth include rising demand for minimally invasive surgical procedures, technological advancements, and increasing adoption of handheld ultrasound devices for diagnosis and treatment.
North America dominated the handheld ultrasound device market, accounting for 40.8% in 2025. This is attributable to increased adoption of ultrasound technology in primary care settings, improved accessibility, and the presence of high healthcare spending in countries with efficient reimbursement policies.
Asia Pacific is the fastest-growing region over the forecast period.
Musculoskeletal held the largest revenue share in 2025, while trauma is the fastest-growing area.
Hospitals held the largest revenue share in 2025, while primary clinics are the fastest-growing area.
The global handheld ultrasound market size was estimated at USD 264.8 million in 2025 and is expected to reach USD 300.3 million in 2026.
The global handheld ultrasound device market is expected to grow at a compound annual growth rate of 13.5% from 2026 to 2033 to reach USD 728.6 million by 2033.
By technology, the 3D/4D ultrasound segment led with a 46.4% revenue share in 2025, and is the fastest-growing segment.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


