
- Home
- »
- Advanced Interior Materials
- »
-
Heat Recovery Ventilator Market Size & Share Report, 2033GVR Report cover

Heat Recovery Ventilator Market (2026 - 2033)
Size, Share & Trends Analysis Report By Ventilation Rate, By Type, By Application, By Deployment, By Product Type, By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$6.0BMarket Estimate, 2026
$6.3BMarket Forecast, 2033
$9.5BCAGR, 2026–2033
6.0%Heat Recovery Ventilator Market Summary
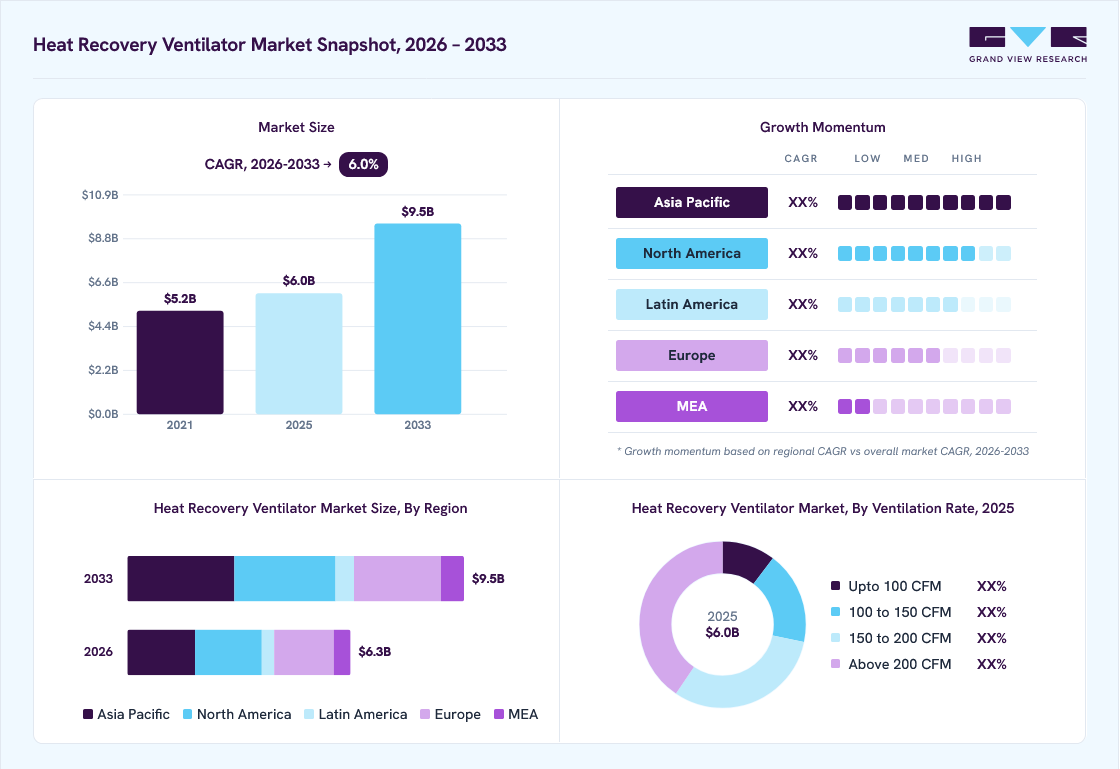
The global heat recovery ventilator market size was valued at USD 6.0 billion in 2025 and is projected to grow from USD 6.3 billion in 2026 to USD 9.5 billion by 2033, at a CAGR of 6.0% from 2026 to 2033. The market in Asia Pacific dominated with a revenue share of 30.0% in 2025. The heat recovery ventilator industry is experiencing substantial growth as consumers increasingly recognize the importance of both indoor air quality and energy efficiency.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Horizontal segment held the largest market share of 74.5% in 2025.
- By deployment: New installation segment held the largest market share of 72.3% in 2025.
- By distribution channel: Wholesale stores segment held the largest market share of 52.3% in 2025.
- By application: Commercial segment held the largest market share of 45.9% in 2025.
- By product type: Wall mounted segment held the largest market share of 43.3% in 2025.
- By ventilation rate: Above 200 CFM segment held the largest market share of 40.6% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (30.0% revenue share, 2025)
- By country: China held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 6.0 Billion
- Estimated market size in 2026: USD 6.3 Billion
- Projected market size by 2033: USD 9.5 Billion
- CAGR (2026-2033): 6.0%
Prism AI by Grand View Research Free to tryAsk a question about the heat recovery ventilator marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Heat recovery ventilators (HRVs) play a crucial role in maintaining a healthy indoor environment by exchanging stale indoor air with fresh outdoor air, while simultaneously recovering heat from the exhaust air. This process significantly reduces the energy required for heating and cooling, offering both comfort and cost savings. As energy prices continue to rise and environmental concerns become more prominent, there is a growing demand for sustainable solutions that minimize energy consumption and reduce carbon footprints, making HRVs a key component in eco-friendly building practices.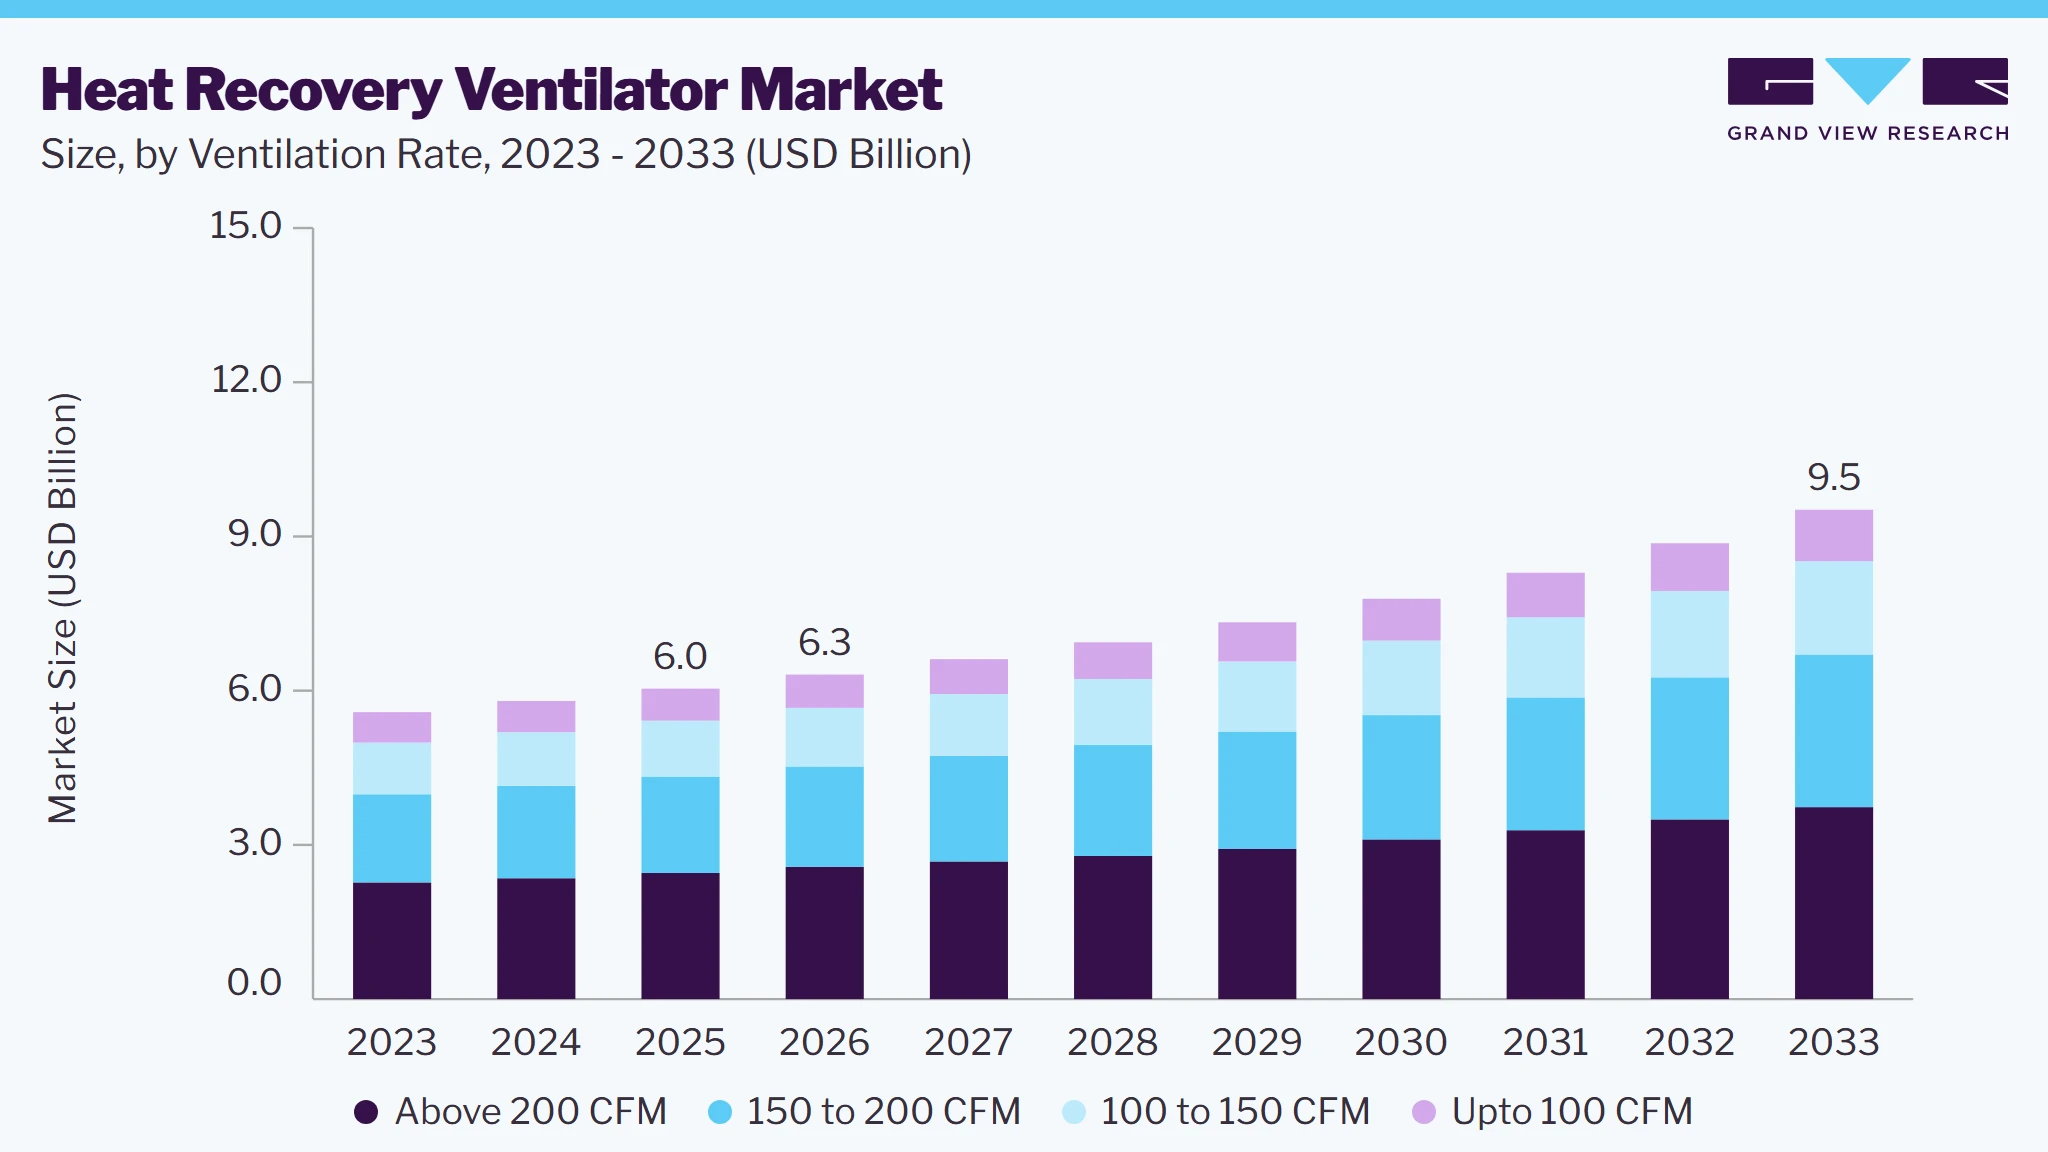 To learn more about this report, Download Free Sample Report
Another key trend in the HRV market is the growing popularity of smart, automated ventilation systems. These advanced units can be controlled remotely, often via smartphones or home automation systems, allowing for better control of air quality and energy use. Integration with smart home systems is becoming more common, as consumers seek seamless, efficient solutions that can adapt to their specific needs. As building regulations tighten and sustainability becomes more prioritized in urban planning, HRVs are expected to play a critical role in meeting new energy efficiency standards. The market is also expanding due to innovation in product designs, making them more compact, quieter, and suitable for a broader range of building types.
Market Dynamics
The global heat recovery ventilators market is poised for steady expansion amid increasingly stringent building energy efficiency standards and growing emphasis on indoor environmental quality across residential, commercial, and institutional infrastructure. The shift toward high-performance and low-carbon buildings, coupled with broader adoption of sustainable construction practices, is driving demand for ventilation systems that enhance thermal efficiency and reduce overall HVAC energy consumption. Ongoing advancements in heat exchanger technologies, airflow optimization, compact system configurations, and intelligent control platforms are improving system performance and expanding application areas. Rising investments in new construction activities, green building initiatives, and energy-efficient retrofit projects are contributing to favorable market fundamentals. Increasing awareness regarding occupant health, ventilation requirements, and lifecycle energy savings is further strengthening product adoption. Although elevated installation costs and complex integration associated with existing structures may limit penetration in certain applications, regulatory emphasis on decarbonization and energy conservation is expected to provide a favorable long-term outlook for the market.
The growing emphasis on reducing building energy consumption and maintaining superior indoor air quality is accelerating the adoption of heat recovery ventilators across residential, commercial, and institutional infrastructure. Stringent building energy codes, rising penetration of green buildings, and increasing demand for balanced ventilation systems are reinforcing the deployment of HRVs as an integral component of modern HVAC architecture. Expanding construction activity, heightened awareness regarding occupant health, and the need to comply with evolving ventilation standards are further contributing to market growth. In addition, the transition toward airtight building envelopes and high-performance structures is increasing the requirement for controlled fresh air exchange without compromising thermal efficiency.
Elevated installation costs and complexities associated with integrating HRV systems into existing buildings continue to limit market penetration. Retrofitting projects often require extensive modifications to ductwork, structural layouts, and HVAC configurations, resulting in higher capital expenditures and prolonged implementation timelines. Space constraints, maintenance requirements, and the need for skilled installation services further add to the total cost of ownership. These factors can delay purchasing decisions, particularly among small commercial facilities and residential users in cost-sensitive markets.
Continuous advancements in intelligent control systems, sensor technologies, and building automation platforms are creating significant opportunities for the heat recovery ventilators market. Integration with smart home ecosystems, demand-controlled ventilation, and remote monitoring capabilities is enhancing system efficiency and operational flexibility. Increasing investments in net-zero energy buildings, green building certifications, and energy-efficient retrofit programs are expanding the addressable market. Moreover, favorable government initiatives promoting sustainable infrastructure, coupled with rising adoption of connected HVAC systems and emphasis on lifecycle energy savings, are expected to support long-term market expansion. Emerging opportunities in multifamily residential developments, healthcare facilities, educational institutions, and commercial complexes are likely to further strengthen demand for advanced heat recovery ventilation solutions.
Market Concentration & Characteristics
The heat recovery ventilator industry is characterized by its focus on energy-efficient and sustainable building solutions. It caters to a broad range of industries, including residential, commercial, and industrial sectors, each seeking to optimize indoor air quality while reducing energy consumption. The demand for HRVs is driven by growing awareness of the importance of ventilation systems that can both conserve energy and maintain healthy living and working environments. The shift toward green building standards and eco-friendly solutions is fueling the adoption of HRVs worldwide.
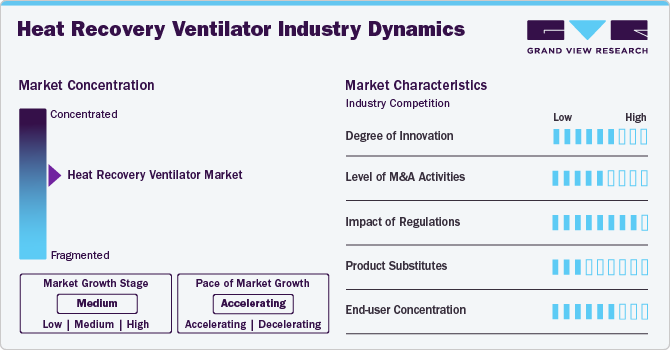
The market is moderately concentrated, with a mix of well-established players and smaller, specialized manufacturers. Major global brands dominate the market, offering a wide variety of HRV solutions, from basic models to advanced, smart-controlled systems. These companies typically focus on developing high-quality, energy-efficient products that meet or exceed international standards. They are also investing in innovative technologies to enhance the performance, ease of use, and integration of HRVs with modern smart home systems.
 To learn more about this report, Download Free Sample Report
Despite the dominance of a few large players, the heat recovery ventilator industry also sees competition from regional and local manufacturers, particularly in emerging markets. These smaller companies often offer competitive pricing and tailored solutions, targeting specific customer needs and regional preferences. As demand for HRVs continues to rise, many of these local players are increasingly focusing on customization and affordability, which allows them to carve out their own niches in the market.
Concentration levels vary by region, with North America and Europe seeing higher levels of competition among established players. However, markets in Asia-Pacific and other developing regions exhibit more fragmented structures. This presents opportunities for new entrants to leverage growth potential in these rapidly expanding regions. In addition, regional governments' emphasis on energy efficiency and green building practices is likely to further encourage market penetration by both large companies and smaller, regional players.
Analyst Perspective
The heat recovery ventilators market is poised for steady growth, driven by stricter energy efficiency regulations, growing focus on indoor air quality, and rising adoption of airtight building designs. Demand is supported by new construction and retrofit projects, particularly in regions promoting green and near-zero-energy buildings. Advances in heat exchanger design, airflow balancing, and smart building integration are shifting HRVs toward connected, energy-efficient systems. However, high installation costs and limited awareness in developing markets may constrain adoption. Overall, the market outlook remains stable, with long-term growth supported by decarbonization policies and low-energy building trends.
Ventilation Rate Insights
Based on the ventilation rate, the above 200 CFM segment led the market with the largest revenue share of 40.6% in 2025. HRVs with ventilation rates above 200 CFM are gaining popularity in large commercial and industrial applications, where high air exchange rates are essential for maintaining air quality. The growing focus on building larger, energy-efficient facilities is driving the demand for high-capacity HRVs that can effectively manage ventilation in spaces with larger occupant numbers or higher contamination levels.
The 100 to 150 CFM segment is expected to grow at a considerable CAGR of 6.9% from 2026 to 2033. HRVs with a ventilation rate between 100 to 150 CFM are well-suited for residential homes, especially medium-sized homes or apartments where balanced air exchange is needed. The demand for such systems is being driven by consumers’ increasing desire to improve indoor air quality without significant energy waste. These systems are ideal for homeowners looking to maintain comfort and air quality while adhering to energy-efficient building standards, especially in regions with moderate climates.
Type Insights
Based on type, the horizontal segment led the market with the largest revenue share of 74.5% in 2025. Horizontal HRVs are typically designed for installation in spaces where ceiling height is limited or where floor space is more readily available. They are ideal for residential applications, particularly in homes with attic or crawl space installations. These systems are compact, offering a space-saving design while delivering efficient ventilation.
The vertical HRVs are designed for installation in larger spaces or buildings with more expansive layouts, such as commercial or industrial settings. These systems are often more powerful, providing higher airflow capacities and efficient ventilation over larger areas. The vertical design helps maximize floor space and is typically used in buildings with higher ceiling heights. Vertical HRVs are particularly favored in new construction where their larger size and capacity can be effectively utilized to meet the demands of the space.
Application Insights
Based on application, the commercial segment led the market with the largest revenue share of 45.9% in 2025. Heat recovery ventilators are commonly used to improve indoor air quality while reducing energy consumption in large office buildings, schools, and healthcare facilities. HRVs help to provide continuous ventilation while reclaiming heat from exhaust air, ensuring comfortable indoor conditions without overburdening HVAC systems. These systems are especially beneficial in spaces with high occupancy and stringent air quality standards, offering both energy savings and improved employee or student productivity.
In residential applications, HRVs are typically used in homes to maintain fresh indoor air and regulate humidity levels without wasting energy. These systems are particularly effective in newer, tightly sealed homes where natural ventilation is limited. They also improve indoor air quality by removing allergens, odors, and excess moisture, creating a healthier living environment for families.
Deployment Insights
Based on deployment, the new installation segment led the market with the largest revenue share of 72.3% in 2025. The demand for heat recovery ventilators in new installations is driven by the growing trend toward energy-efficient and sustainable construction. As green building practices become more prevalent, developers and homeowners are increasingly incorporating HRVs into new homes and commercial buildings to optimize indoor air quality and energy efficiency. HRVs provide an effective way to comply with modern building codes and energy regulations, ensuring fresh air circulation without losing heating or cooling energy.
The replacement segment for heat recovery ventilators is driven by the need to upgrade outdated or inefficient ventilation systems. Older HRVs may lack the energy efficiency, smart features, and performance required to meet current standards. As awareness of energy-saving technologies increases, many property owners are opting to replace older models with newer, more efficient HRVs that offer better airflow, lower energy consumption, and enhanced control options.
Distribution Channel Insights
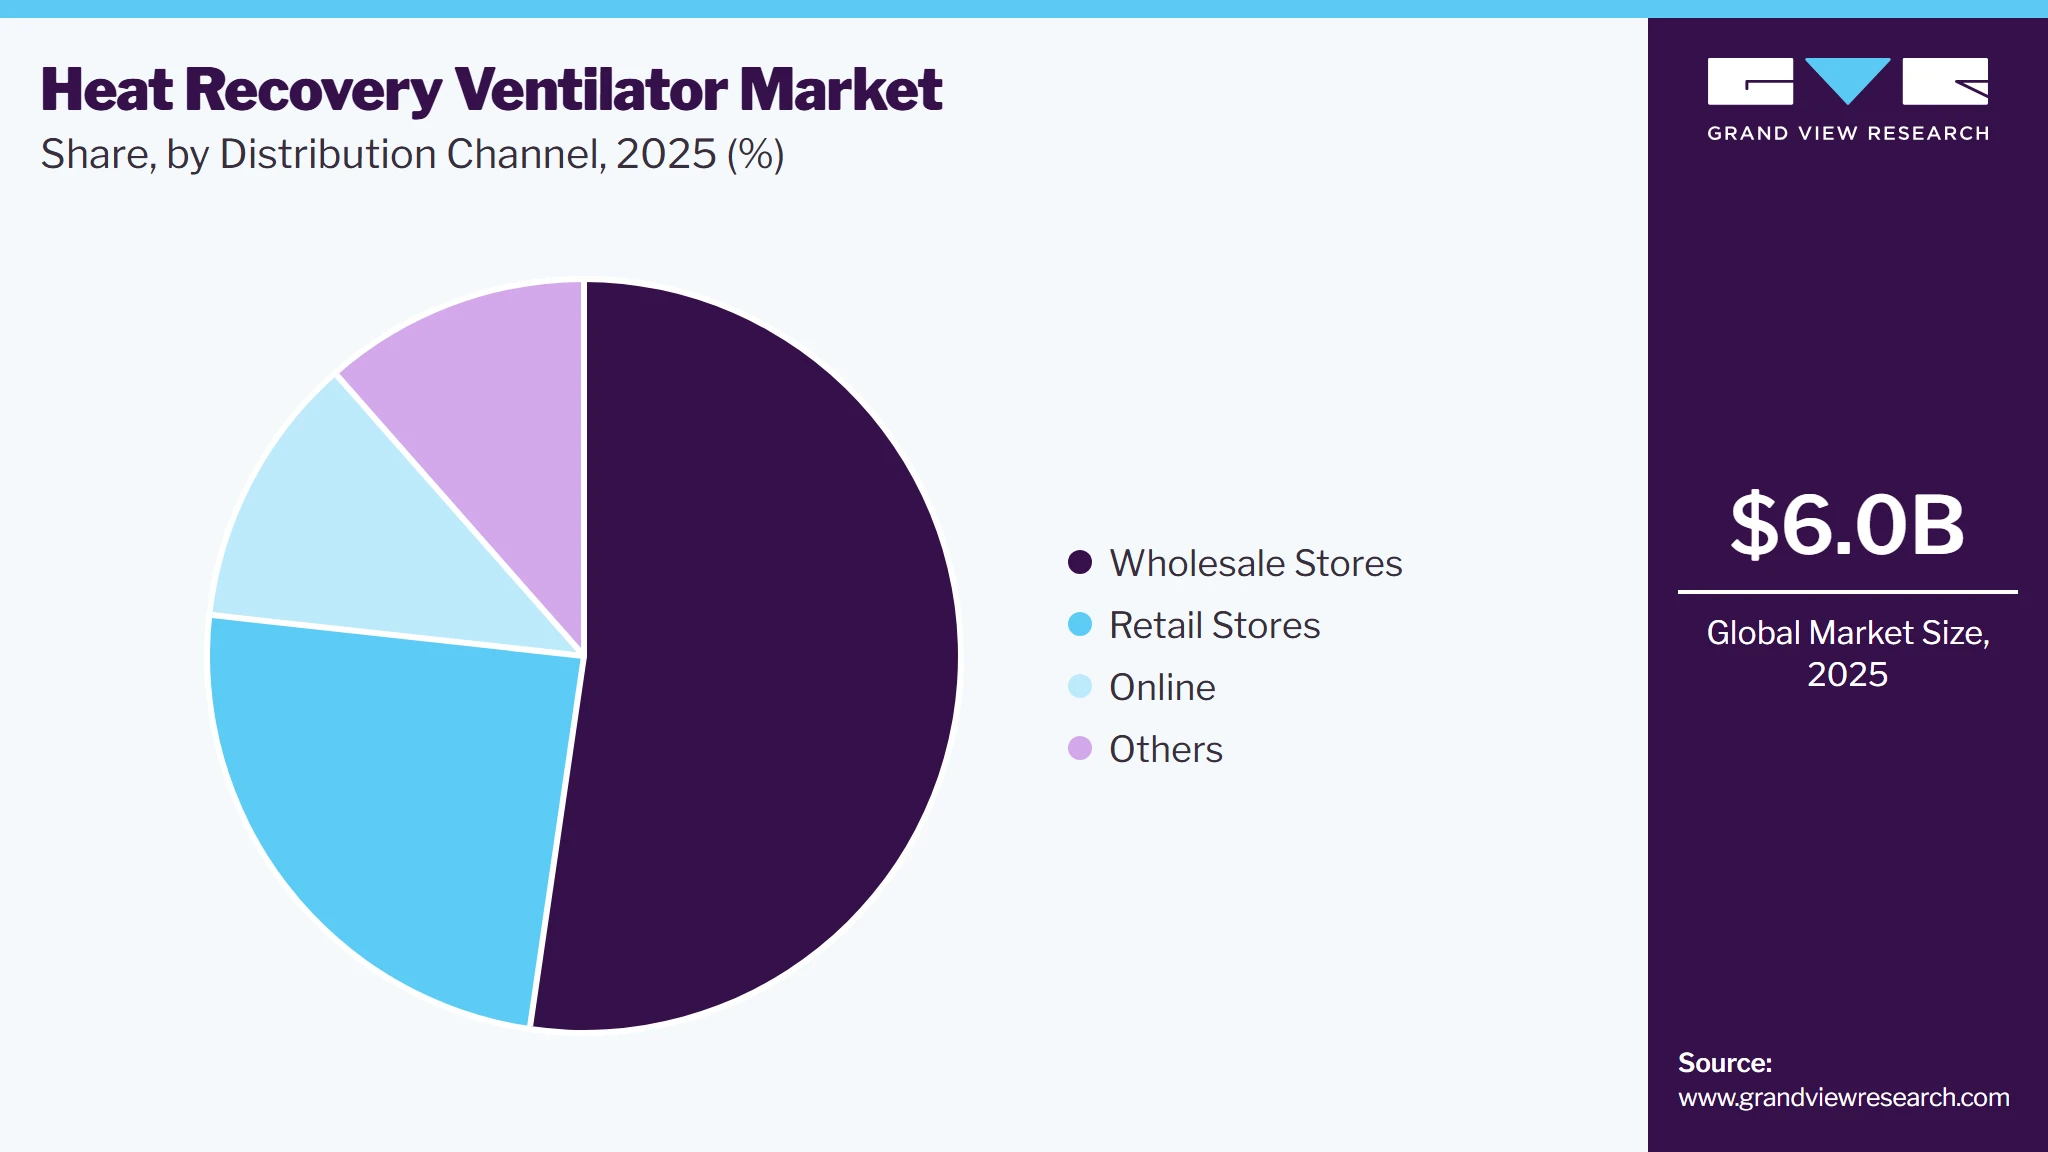
Based on the distribution channel, the wholesale stores segment led the market with the largest revenue share of 52.3% in 2025. Wholesale stores remain a significant distribution channel for heat recovery ventilators, particularly for bulk purchases by contractors, builders, and large-scale commercial projects. These stores offer HRVs at discounted rates, catering to both businesses and individual consumers looking for cost-effective options. Wholesale distributors provide a wide variety of models, often offering the advantage of bulk buying, which can lower per-unit costs.
 To learn more about this report, Download Free Sample Report
The online distribution channel for heat recovery ventilators has seen rapid growth due to the increasing consumer preference for convenient shopping and the availability of detailed product information. Many consumers now prefer researching and purchasing HRVs through e-commerce platforms, where they can compare different models, read reviews, and enjoy home delivery. Online platforms often offer competitive pricing and direct-to-consumer sales, making it an attractive option for both residential and commercial buyers seeking energy-efficient ventilation solutions.
Product Type Insights
Based on product type, the wall mounted segment led the market with the largest revenue share of 43.3% in 2025. Wall-mounted heat recovery ventilators are a popular choice for both residential and commercial applications due to their easy installation and efficient performance. These units are typically mounted on an exterior wall to facilitate the exchange of stale indoor air with fresh outdoor air. Wall-mounted HRVs are ideal for spaces with limited ceiling height or where a more visible, accessible unit is preferred.
Ceiling-mounted heat recovery ventilators (HRVs) are designed for installation in spaces where floor or wall space is limited. These units are typically found in residential or commercial buildings where discreet, efficient ventilation is required without taking up valuable space. The ceiling-mounted design ensures optimal air distribution across the room, maintaining consistent air quality while being less intrusive.
Regional Insights
North America dominated the heat recovery ventilator market with the largest revenue share of 29.9% in 2025. The North American market is expanding rapidly due to increasing demand for energy-efficient solutions and building regulations that emphasize sustainability. The U.S. and Canada are leading the adoption of HRVs, with significant growth in both residential and commercial sectors. Rising awareness about indoor air quality and energy conservation is driving the market across the region.
U.S. Heat Recovery Ventilator Market Trends
The heat recovery ventilator market in the U.S. is expected to grow at a significant CAGR of 6.0% from 2026 to 2033. In the U.S., the market is growing as energy-efficient construction practices and green building certifications become more popular. The demand for HRVs is particularly high in regions with extreme climates, where energy savings in heating and cooling are crucial.
The heat recovery ventilator market in the Canada is expected to grow at the fastest CAGR of 6.7% from 2026 to 2033. Canada’s market is driven by stringent energy efficiency standards and the desire to reduce heating costs, especially in colder regions. Canadian homes and commercial buildings increasingly incorporate HRVs to meet energy codes while ensuring proper ventilation.
Asia Pacific Heat Recovery Ventilator Market Trends
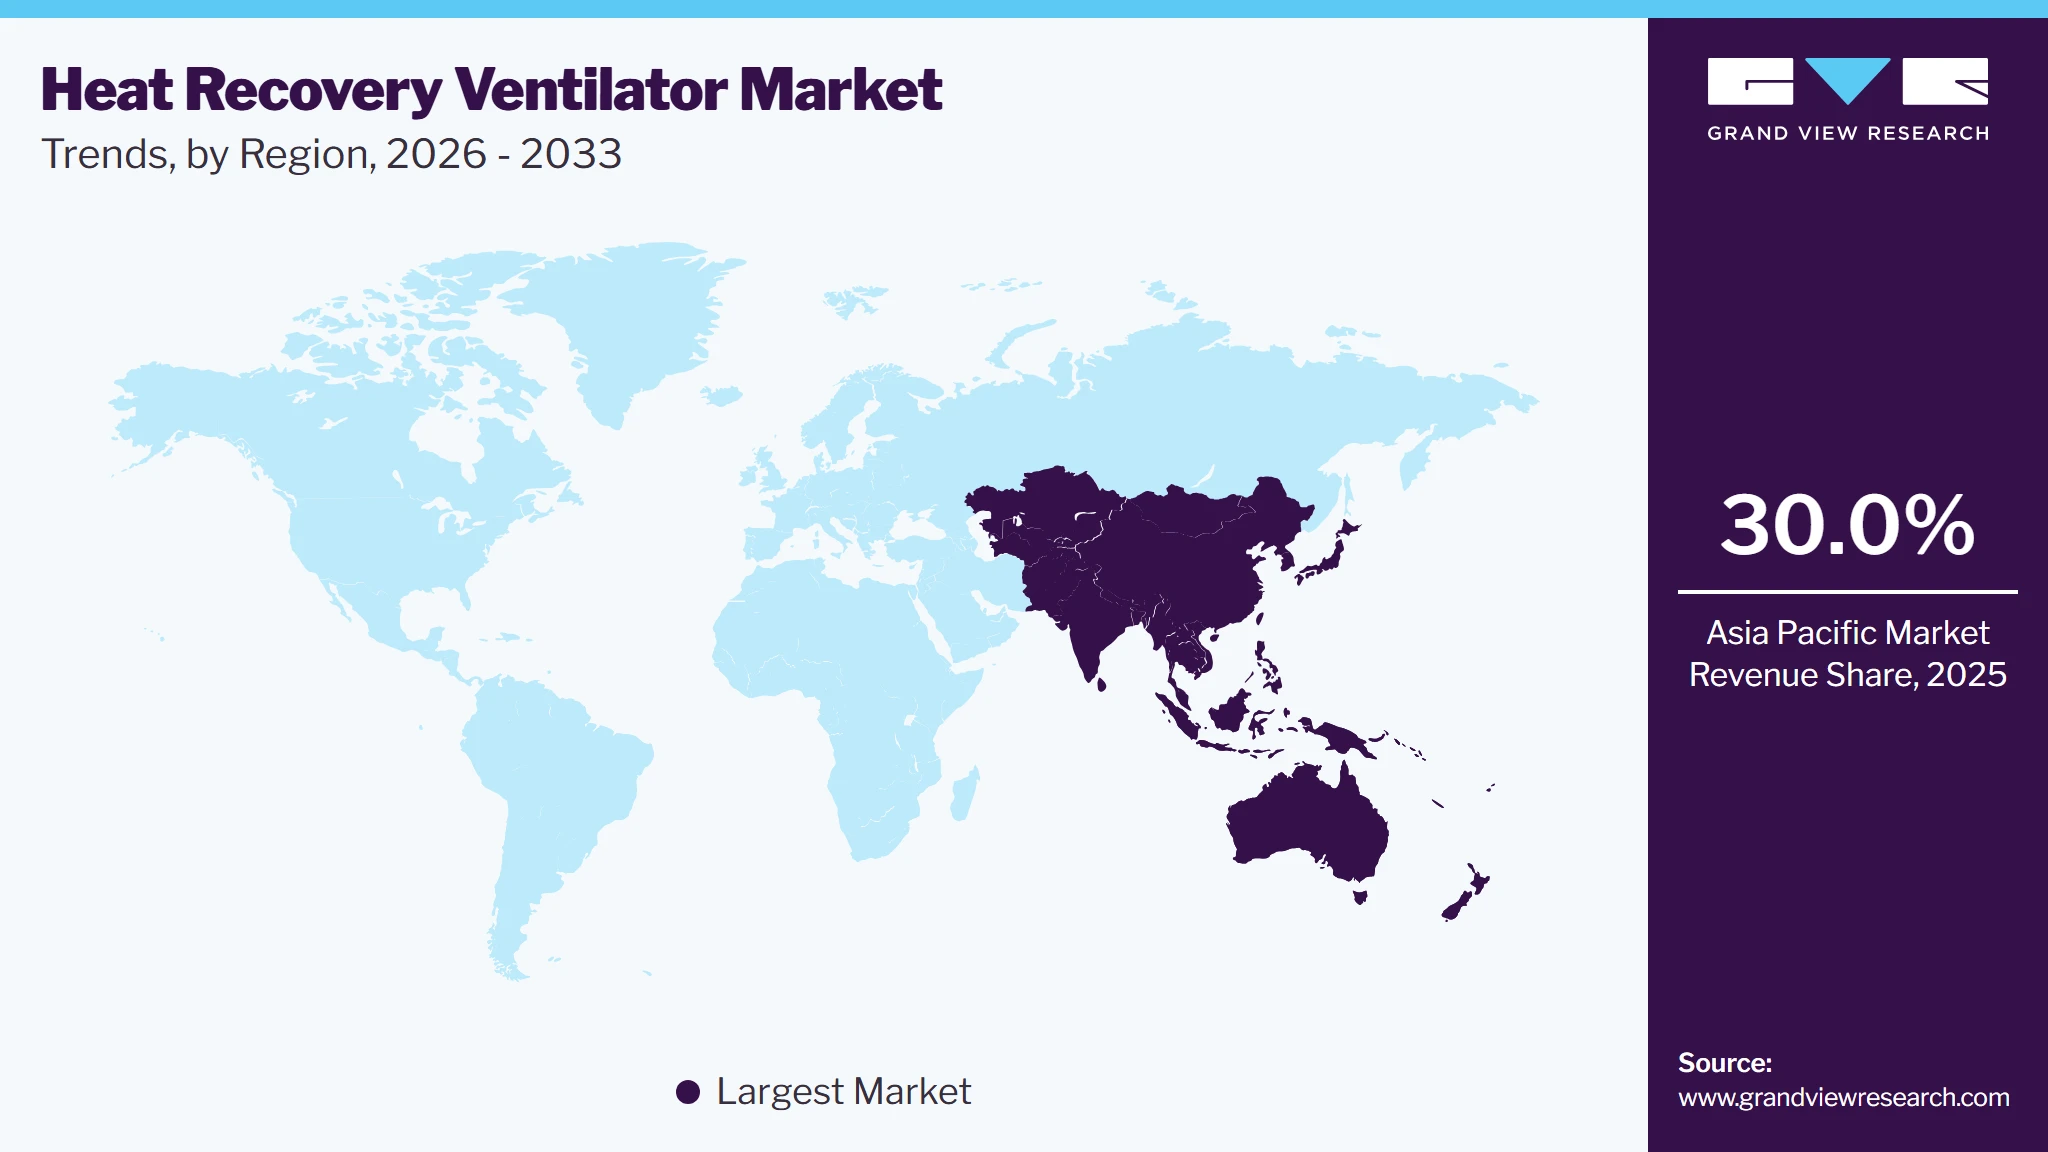
Asia Pacific dominated the heat recovery ventilator market with the largest revenue share of 30.0% in 2025. The heat recovery ventilator market in Asia Pacific is experiencing rapid growth in the HRV market, driven by urbanization, increasing construction activity, and growing awareness of energy efficiency. Countries like China and India are seeing rising demand for energy-efficient ventilation systems in both residential and commercial buildings.
 To learn more about this report, Download Free Sample Report
The heat recovery ventilator market in China held the largest share in the Asia Pacific region in 2025. In China, the market is expanding as part of the country’s broader initiative to improve energy efficiency in buildings and reduce carbon emissions. Urbanization and a growing middle class are driving demand for modern, energy-efficient homes and commercial spaces.
The heat recovery ventilator market in the India is expected to grow at the fastest CAGR of 7.2% from 2026 to 2033. The market in India is growing as the country faces challenges related to urban air quality and energy consumption. As residential and commercial construction booms, there is a rising demand for systems that can improve air quality while reducing energy usage.
Europe Heat Recovery Ventilator Market Trends
The heat recovery ventilator market in Europe is a significant market for HRVs due to the region’s strong regulatory push towards energy-efficient building practices and environmental sustainability. Many countries, particularly those in Northern Europe, are leading the adoption of HRVs in both residential and commercial buildings. The European market is also driven by increasing consumer demand for better indoor air quality and lower energy consumption.
The Germany heat recovery ventilator market accounted for the largest revenue share of 32.5% share in Europe in 2025. Germany is one of the leading markets for HRVs in Europe, driven by its robust green building initiatives and energy efficiency policies. The demand for HRVs is high in both new buildings and renovations, as the country seeks to meet ambitious sustainability goals.
The heat recovery ventilator market in UK is driven by country's broader effort to improve energy efficiency in homes and commercial properties. Strict energy regulations, including those set by the government, encourage the use of HRVs to meet energy conservation targets.
Middle East & Africa Heat Recovery Ventilator Market Trends
The heat recovery ventilator market in the Middle East and Africa are emerging markets for HRVs, as increasing urbanization and construction activities drive demand for energy-efficient building technologies. In regions like Saudi Arabia, where energy costs are high, there is a growing interest in HRVs to improve ventilation while reducing cooling and heating costs.
The Saudi Arabia heat recovery ventilator market is investing heavily in sustainable building practices, which is driving the adoption of HRVs in both residential and commercial buildings. The country’s extreme climate makes energy-efficient ventilation systems crucial for managing indoor air quality while reducing cooling costs. Government initiatives and green building standards are also contributing to the growing market in Saudi Arabia.
Latin America Heat Recovery Ventilator Market Trends
The heat recovery ventilator market in Latin America is gradually expanding, driven by increasing construction activities and a growing awareness of sustainable building practices. Countries like Brazil are witnessing rising demand for energy-efficient ventilation solutions, particularly in new residential and commercial developments.
The Brazil heat recovery ventilator market is driven by the country’s expanding construction industry and efforts to meet energy efficiency standards. The growing focus on sustainable building practices and energy conservation is leading to greater adoption of HRVs, especially in residential homes and commercial spaces.
Key Heat Recovery Ventilator Company Insights
Some of the key players operating in the market include Carrier, Daikin Industries, Ltd., among others.
-
Carrier is a leading global provider of heating, ventilation, and air conditioning (HVAC) solutions. Founded in 1902 by Willis H. Carrier, the company has a long history of innovation and industry leadership, particularly in the development of modern air conditioning systems. Carrier offers a wide range of products, including heat recovery ventilators (HRVs), air conditioners, and refrigeration solutions for residential, commercial, and industrial applications.
-
Daikin Industries, Ltd. is a Japanese multinational corporation and one of the world's leading manufacturers of air conditioning, heating, refrigeration, and ventilation equipment. Founded in 1924, Daikin has expanded its product portfolio to include energy-efficient solutions like heat recovery ventilators (HRVs), as well as air purifiers and commercial refrigeration systems.
Key Heat Recovery Ventilator Companies:
The following key companies have been profiled for this study on the heat recovery ventilator market.
-
Carrier
-
Daikin Industries, Ltd.
-
Reventon Group Sp. z o.o
-
FUJITSU GENERAL
-
American Aldes Ventilation Corporation
-
Panasoinc
-
Lennox
-
Ruskin
-
Nortek Air Solutions
-
Broan-NuTone, LLC
-
Greenheck Fan Corporation
-
Johnson Controls
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Carrier; Daikin Industries, Ltd.; Panasonic; Johnson Controls; Lennox; Nortek Air Solutions; Greenheck Fan Corporation; Broan-NuTone, LLC; FUJITSU GENERAL.)
- Prioritization of integrated HVAC and ventilation ecosystems combining heat recovery, air conditioning, and indoor air quality management within unified building solutions.
- Continuous enhancement of energy-efficient HRV systems aligned with stringent building energy codes, green certifications, and net-zero construction frameworks.
- Strengthening aftermarket revenue through long-term service agreements, system optimization contracts, and predictive maintenance offerings enabled by digital platforms.
- Extensive global distribution networks supported by strong contractor and OEM relationships across residential, commercial, and institutional segments.
- Advanced engineering capabilities enabling high thermal recovery efficiency, low-energy consumption designs, and integration with building automation systems.
- Ability to offer end-to-end HVAC solutions, improving project penetration in large-scale infrastructure and high-value commercial installations.
- Higher product and installation costs limit penetration in price-sensitive and emerging markets.
- Standardized product architectures reduce agility in addressing highly localized or niche ventilation requirements.
- Exposure to cyclicality in construction and real estate investment impacts demand stability.
Emerging & Regional Players (e.g., Reventon Group Sp. z o.o; American Aldes Ventilation Corporation; Ruskin, regional players)
- Focus on application-specific HRV solutions tailored to residential retrofits, small commercial buildings, and decentralized ventilation requirements.
- Competitive pricing models targeting mid- and low-tier HVAC projects in cost-sensitive markets.
- Expansion through regional distributor networks, HVAC contractors, and project-based procurement channels.
- Faster product development cycles enabling responsiveness to regional building codes and installation constraints.
- Cost-effective product portfolios suitable for retrofit applications and small-to-medium scale infrastructure.
- Strong specialization in ventilation components and modular HRV system designs.
- Limited global scale restricts participation in large institutional and multinational projects.
- Lower investment capacity in advanced R&D, digital integration, and smart building technologies.
- Dependence on regional demand cycles and distributor-led sales limits brand visibility and pricing power.
Recent Developments
-
In January 2025, Greenheck launched the ERVi, a compact energy recovery ventilator designed for small spaces like basements and mechanical rooms. It fits through a 30-inch door and can be ceiling-mounted for retrofit projects. Available in two models, the ERVi-10 offers 375-1,500 cfm at 18 inches high, while the ERVi-20 provides 750-2,500 cfm at 23 inches high.
-
In January 2024, Toshiba Carrier's award-winning U-Series lineup introduced a new Heat Recovery Unit, making its debut at the AHR Expo in Chicago.
-
In May 2024, Lesaffre began developing a new heat recovery unit at its historic site in Marcq-en-Barœul, in collaboration with ENGIE Solutions.
Heat Recovery Ventilator Market Report Scope
Report Attribute
Details
Market size in 2025
USD 6.0 billion
Estimated market size in 2026
USD 6.3 billion
Projected market size by 2033
USD 9.5 billion
Growth rate
CAGR of 6.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Ventilation rate, type, application, deployment, product type, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Japan; China; India; Australia; South Korea; Brazil; Argentina; Saudi Arabia; South Africa; UAE
Key companies profiled
Carrier; Daikin Industries, Ltd.; Reventon Group Sp. z o.o; FUJITSU GENERAL; American Aldes Ventilation Corporation; Panasonic; Lennox; Ruskin; Nortek Air Solutions; Broan-NuTone, LLC; Greenheck Fan Corporation; Johnson Controls
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Heat Recovery Ventilator Market Report Segmentation
This report forecasts revenue growth at global, regional & country levels and provides an analysis on the industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global heat recovery ventilator market report based on the ventilation rate, type, application, deployment, product type, distribution channel, and region:
-
Ventilation Rate Outlook (Revenue, USD Million, 2021 - 2033)
-
Upto 100 CFM
-
100 to 150 CFM
-
150 to 200 CFM
-
Above 200 CFM
-
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Vertical
-
Horizontal
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Commercial
-
Residential
-
Industrial
-
-
Deployment Outlook (Revenue, USD Million, 2021 - 2033)
-
New Installation
-
Replacement
-
-
Product Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Wall Mounted
-
Celling Mounted
-
Cabinet
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Online
-
Retail Stores
-
Wholesale Stores
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
UAE
-
South Africa
-
-
Research Methodology
The heat recovery ventilator market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each heat recovery ventilator segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Ventilation Rate
Revenue Capture Definition
Up to 100 CFM
Revenue arises from compact HRV systems deployed in low-load buildings.
100 to 150 CFM
Revenue is driven by mid-capacity HRV systems installed in apartments and small establishments, supporting balanced air exchange, humidity regulation, and moderate thermal energy recovery across moderately occupied spaces.
150 to 200 CFM
Revenue is accounted for by high-capacity HRV systems integrated into multi-unit complexes and commercial buildings requiring continuous ventilation across multiple zones along with enhanced efficiency performance.
Above 200 CFM
Revenue is linked to large-capacity HRV systems used in institutional, healthcare, educational, and high-occupancy commercial facilities where stringent air quality control, high airflow handling, and compliance with ventilation standards are essential.
Segment - Type
Revenue Capture Definition
Vertical
Revenue is derived through vertically configured HRV systems preferred in installations with limited mechanical room space, enabling compact footprint utilization while maintaining efficient heat exchange performance.
Horizontal
Revenue is driven by horizontal HRV systems integrated into centralized HVAC infrastructures, facilitating structured airflow distribution and efficient heat recovery across larger building layouts.
Segment - Application
Revenue Capture Definition
Commercial
Revenue is associated with HRV deployments in offices, hospitals, hotels, educational institutions, and retail complexes where regulatory compliance, occupant comfort, and energy efficiency optimization are critical.
Residential
Revenue is contributed by HRV systems installed in single-family and multi-family housing units designed to ensure continuous fresh air supply, reduce indoor pollutants, and lower heating and cooling energy loads.
Industrial
Revenue is supported by HRV systems applied in industrial and semi-industrial environments to manage ventilation loads, improve workplace air quality, and recover waste heat from exhaust air streams.
Segment - Deployment
Revenue Capture Definition
New Installation
Revenue is driven by HRV systems integrated into newly constructed buildings.
Replacement
Revenue is linked to retrofit-driven demand where aging or conventional ventilation systems are upgraded with HRV solutions to improve efficiency, regulatory compliance, and operational performance.
Segment - Product Type
Revenue Capture Definition
Wall Mounted
Revenue arises from decentralized wall-mounted HRV systems deployed in compact residential and small commercial environments requiring localized ventilation and space-efficient installation.
Ceiling Mounted
Revenue is derived from ceiling-integrated HRV systems installed to optimize architectural space utilization while ensuring centralized and concealed ventilation performance.
Cabinet
Revenue is accounted for by cabinet-type HRV systems offering centralized ventilation solutions with higher airflow capacity for medium to large-scale building applications.
Segment - Distribution Channel
Revenue Capture Definition
Online
Revenue is driven through digital procurement platforms and manufacturer-led e-commerce channels enabling direct access to HRV systems, components, and replacement parts.
Retail Stores
Revenue is associated with HVAC retail distribution networks catering to end-users and small contractors seeking ready-to-install HRV solutions and accessories.
Wholesale Stores
Revenue is supported by distributor-led supply chains serving EPC contractors, system integrators, and project-based procurement in commercial and institutional installations.
Others
Revenue is linked to institutional procurement, government tenders, and EPC-driven customized HVAC projects executed outside conventional retail and wholesale channels.
Estimation Model
Layer Name
Key Question
Description
Building Stock & Demand Base Layer
Which building infrastructure represents the addressable market?
Quantifies global residential, commercial, and institutional building stock across developed and emerging regions, including new construction pipelines and existing structures with ventilation requirements driven by energy efficiency and indoor air quality considerations.
Regulatory & Compliance Applicability Layer
Which buildings require heat recovery ventilation systems? Evaluates buildings subject to mandatory or voluntary energy efficiency codes, ventilation standards, and green building certification frameworks that incentivize or mandate heat recovery-based mechanical ventilation solutions.
Technology Adoption Layer
What share of compliant buildings deploy heat recovery ventilators?
Estimates adoption levels of heat recovery ventilation systems across building categories, climatic conditions, and occupancy profiles, while accounting for substitution effects from conventional HVAC ventilation and alternative energy recovery technologies.
Revenue Realization Layer
How is market revenue generated from installed heat recovery ventilator demand?
Translates installed HRV systems into revenue using system pricing benchmarks based on capacity, configuration, installation complexity, and building type, along with recurring revenue streams from maintenance, replacement, and system optimization services.
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Competitive Benchmarking
Evaluated leading heat recovery ventilator manufacturers based on product portfolio breadth, energy recovery efficiency, technological capabilities, financial strength, application focus, and global/regional footprint, while distinguishing established HVAC conglomerates from specialized and emerging ventilation system providers.
Enabled a structured view of competitive positioning across the HRV ecosystem, supporting identification of differentiation strategies, technology gaps, and evolving competitive pressures.
Regional Segmentation
Refined geographic assessment by analyzing building energy efficiency regulations, climatic conditions, construction activity, green building adoption, and HVAC modernization trends across North America, Europe, Asia Pacific, Middle East & Africa, and Latin America.
Facilitated identification of high-growth regions, regulation-driven demand clusters, and strategic expansion opportunities across both mature and developing construction markets.
Opportunity assessment
Assessed growth opportunities across residential and commercial construction, retrofit and replacement activity, net-zero and sustainable building initiatives, smart ventilation integration, and incorporation of HRVs within advanced HVAC and building automation systems.
Supported prioritization of high-value revenue segments by highlighting areas with strong regulatory backing, rising adoption potential, and long-term energy efficiency-driven demand momentum.
Frequently Asked Questions About This Report
The horizontal segment led the market and accounted for the largest revenue share of 74.5% in 2025.
The commercial segment held the largest market share, accounting for 45.9% of the global revenue in 2025.
The new installation segment dominated the market with a revenue share of 72.3% in 2025.
The wall-mounted segment accounted for the largest revenue share of 43.3% in 2025.
The wholesale stores segment led the market, accounting for 52.3% of the global revenue in 2025.
Asia Pacific dominated the heat recovery ventilator market with the largest revenue share of 30.0% in 2025.
Some of the key players operating in the heat recovery ventilator market include Carrier, Daikin Industries, Ltd., Reventon Group Sp. z o.o, FUJITSU GENERAL, American Aldes Ventilation Corporation, Panasonic, Lennox, Ruskin, Nortek Air Solutions, Broan-NuTone, LLC, Greenheck Fan Corporation, Johnson Controls.
The heat recovery ventilator market is witnessing significant growth as consumers become more aware of the importance of indoor air quality and energy efficiency.
The global heat recovery ventilator market size was valued at USD 6.0 billion in 2025 and is estimated at USD 6.3 billion for 2026.
The global heat recovery ventilator market is expected to grow at a CAGR of 6.0% from 2026 to 2033, reaching USD 9.5 billion by 2033.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


