
- Home
- »
- Pharmaceuticals
- »
-
Hemoglobinopathies Market Size And Share Report, 2033GVR Report cover

Hemoglobinopathies Market (2026 - 2033)
Size, Share & Trends Analysis Report By Disease Type (Thalassemia, Sickle Cell Disease), By Type (Diagnosis, Therapeutics, (Thalassemia, Sickle Cell Disease)), By Region, And Segment Forecasts
Market Size, 2025
$11.0BMarket Estimate, 2026
$11.9BMarket Forecast, 2033
$22.4BCAGR, 2026–2033
9.4%Hemoglobinopathies Market Summary
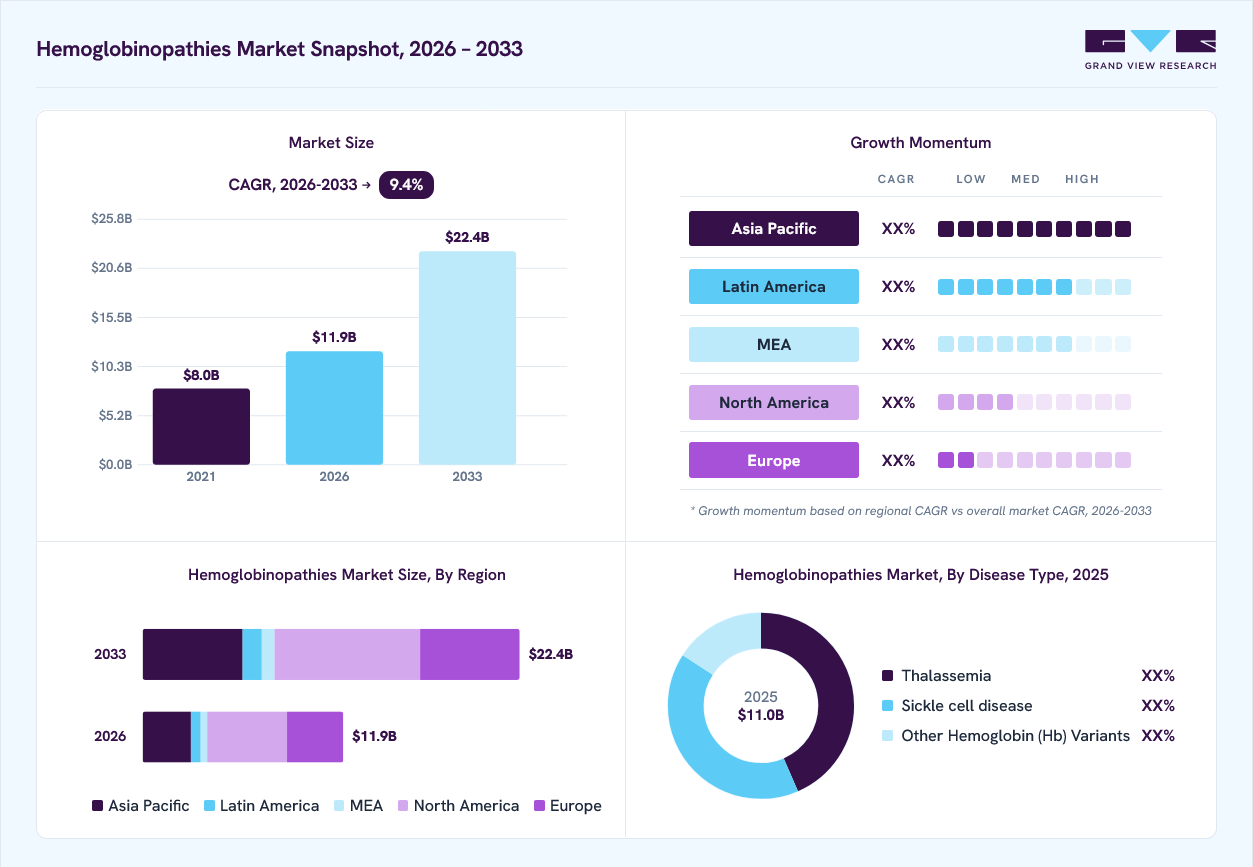
The global hemoglobinopathies market size was valued at USD 11.0 billion in 2025 and is projected to grow from USD 11.9 billion in 2026 to USD 22.4 billion by 2033, at a CAGR of 9.4% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 39.9% in 2025. The market growth is driven by the growing burden of inherited blood disorders, particularly sickle cell disease and thalassemia, across Africa, the Middle East, South Asia, and parts of the Americas.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By disease type: Thalassemia held the largest market share of 43.4% in 2025
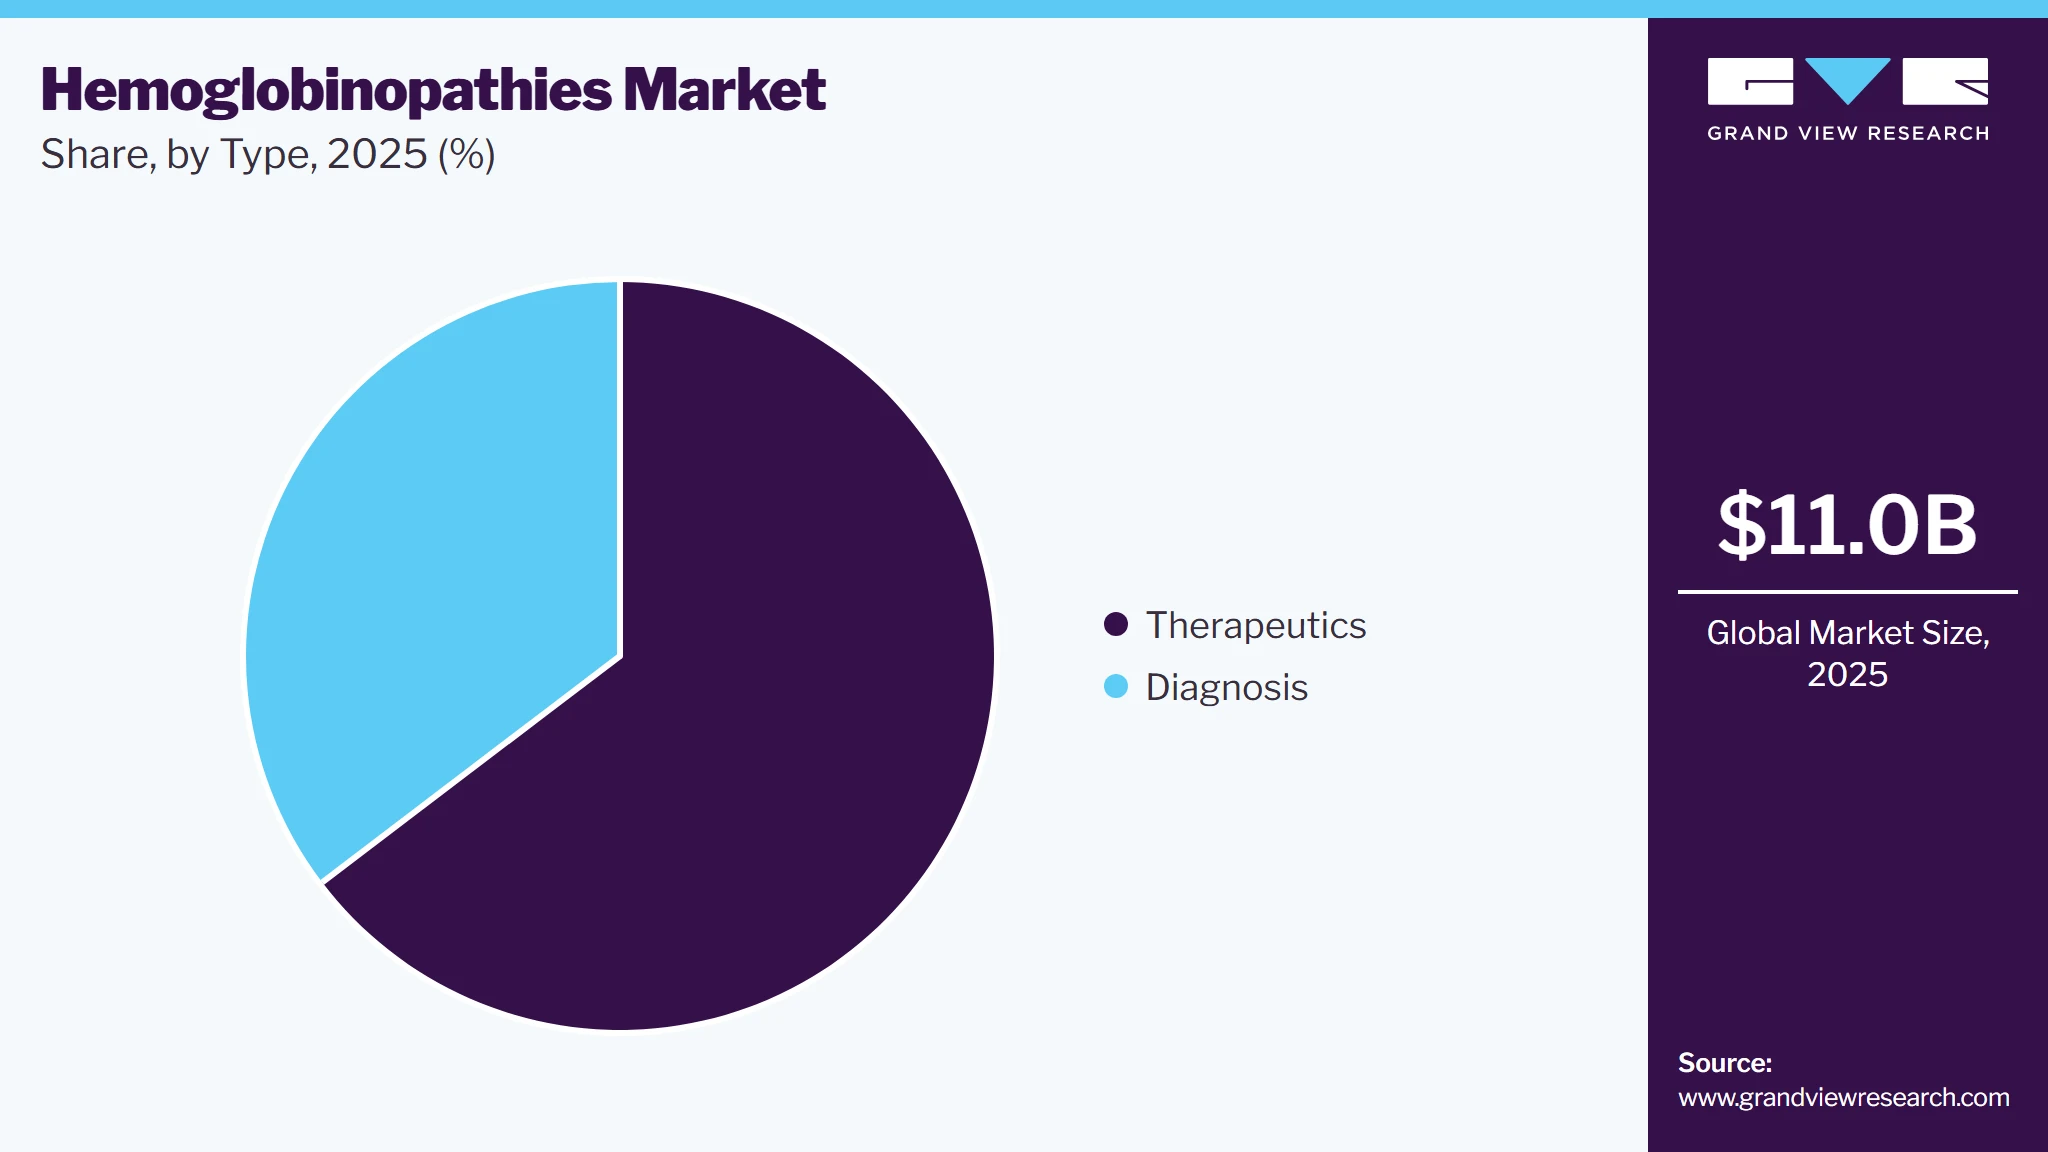
- By type: Therapeutics held the largest market share of 64.7% in 2025
Regional Highlights
- Largest regional market: North America (39.9% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market Size in 2025: USD 11.0 Billion
- Estimated Market Size in 2026: USD 11.9 Billion
- Projected Market Size by 2033: USD 22.4 Billion
- CAGR (2026-2033): 9.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Growing awareness, expansion of newborn screening programs, and wider use of genetic testing are supporting earlier diagnosis and disease management. The hemoglobinopathies industry includes disease-modifying therapies, supportive treatments, blood transfusion products, iron chelation therapies, gene-based therapies, and diagnostic solutions used for screening and patient monitoring. Regulatory support for new therapies and continued investment in genetic medicine are expanding available treatment options. Healthcare systems are also increasing the number of specialized hematology centers and rare disease programs to improve long-term patient care. However, access to treatment remains limited in many low- and middle-income countries due to therapy costs, infrastructure gaps, and shortages of specialized healthcare services. These factors continue to shape treatment adoption, research activities, and business opportunities across regional healthcare markets.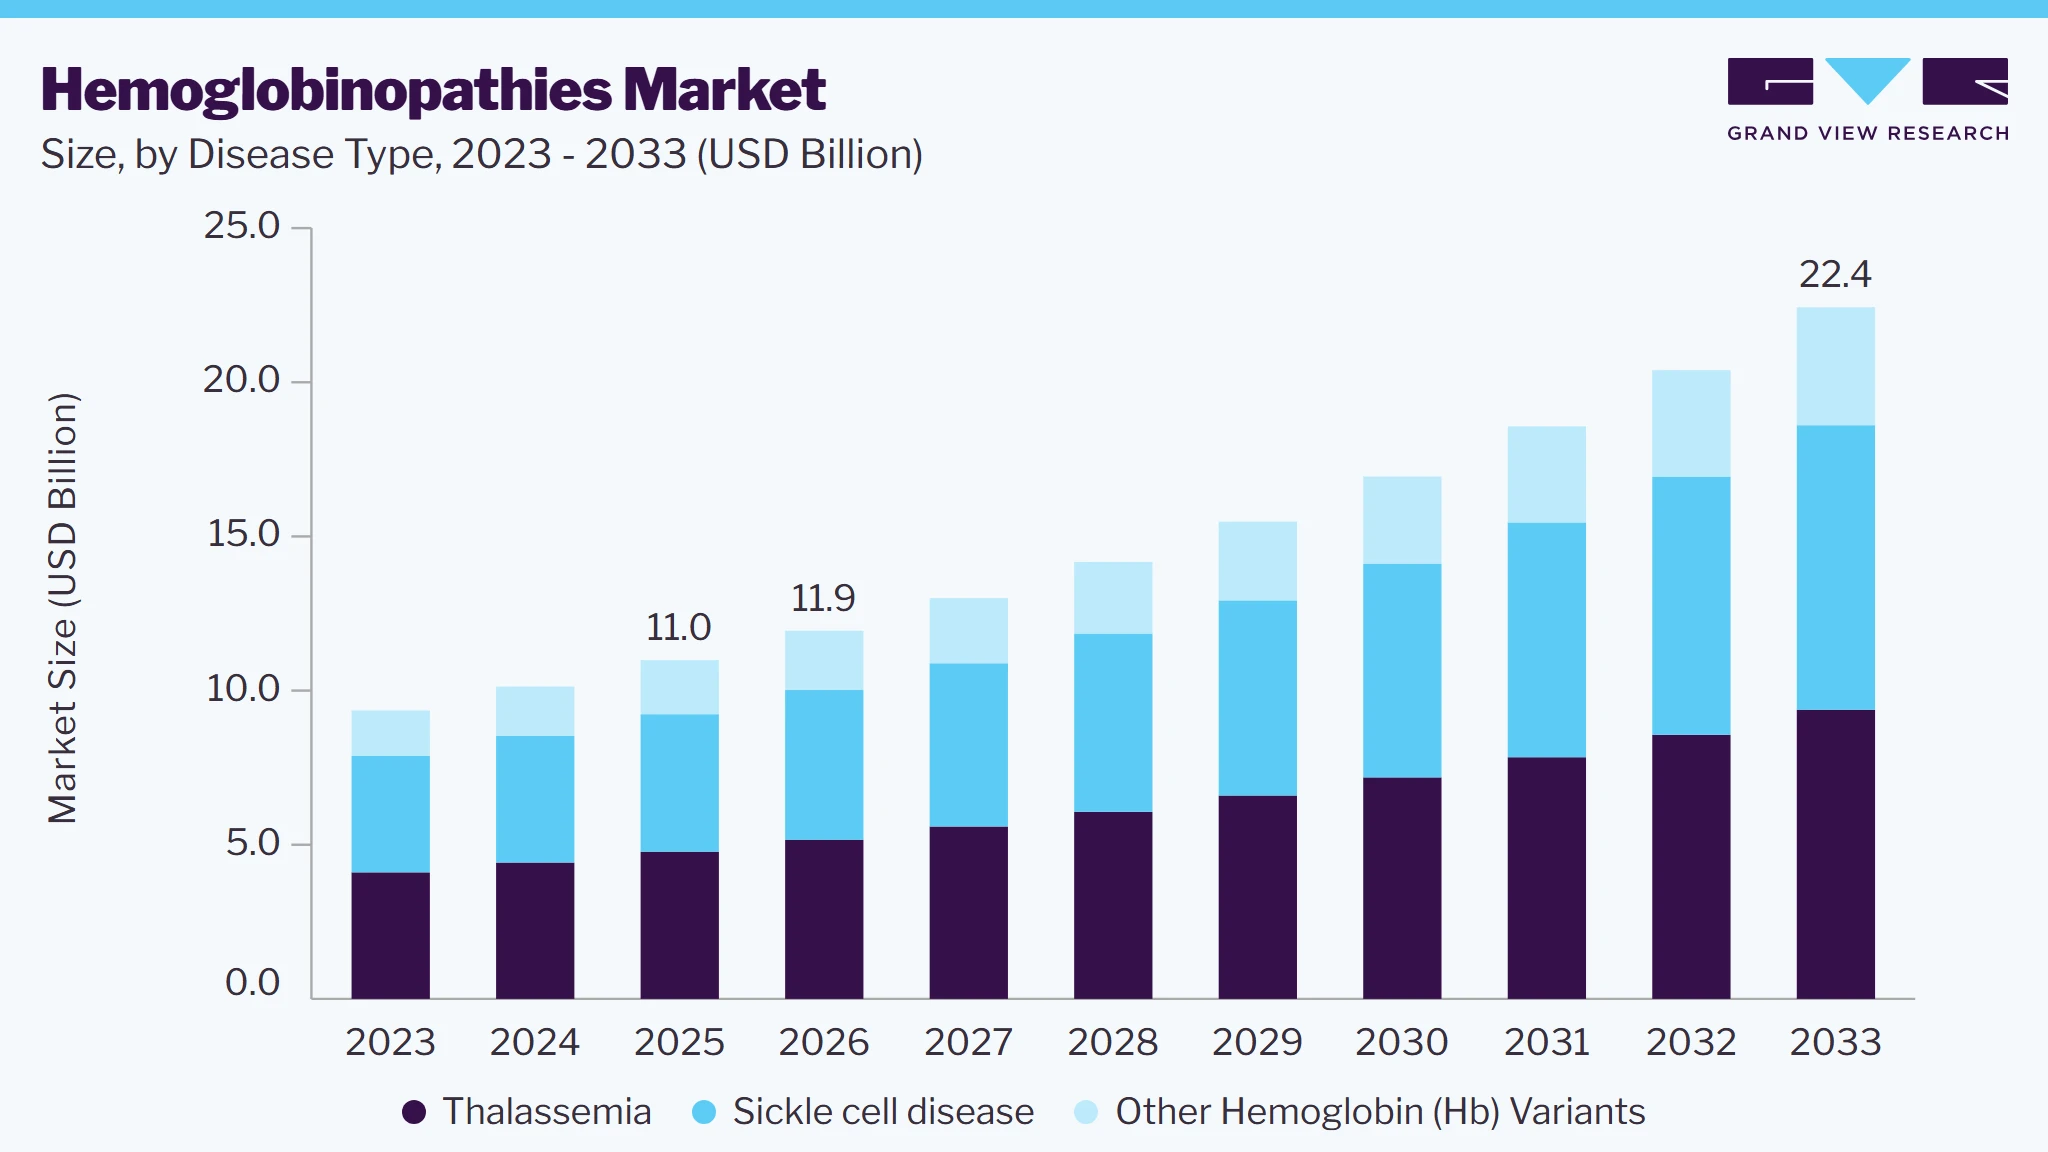 To learn more about this report, Download Free Sample Report
Market Dynamics
The hemoglobinopathies market is driven by the growing availability of gene-based therapies for sickle cell disease and transfusion-dependent beta-thalassemia. These therapies target the underlying genetic cause of disease and offer an alternative to long-term supportive care such as blood transfusions and iron chelation therapy. Regulatory agencies are supporting the review of treatments for rare diseases, while pharmaceutical companies continue to expand clinical development and manufacturing capabilities. The increasing number of specialized treatment centers and experience with gene therapy administration are also supporting market growth. At the same time, healthcare providers are strengthening referral networks for eligible patients and improving access to advanced treatment options. Continued investment in genetic medicine is expected to increase the number of available therapies over the coming years. For instance, in July 2026, Vertex Pharmaceuticals Incorporated received U.S. FDA approval for the expanded use of a gene therapy for patients aged 2 years and older with sickle cell disease and transfusion-dependent beta-thalassemia. The approval expanded eligibility by approximately 5,500 additional children in the U.S. and marked the first approved genetic therapy for children as young as 2 years with these conditions.
The adoption of advanced therapies for hemoglobinopathies remains limited by high treatment costs and the need for specialized healthcare infrastructure. Gene therapies require stem cell collection, conditioning regimens, specialized transplantation facilities, and long-term patient monitoring, making treatment available only at selected healthcare centers. Many low- and middle-income countries continue to rely on blood transfusions, iron chelation therapy, and supportive care because advanced treatment facilities are limited. In addition, access to compatible healthcare infrastructure, trained clinical teams, and reimbursement support varies across countries. These factors increase the overall cost of treatment and limit patient access, particularly in regions with limited healthcare resources. Manufacturing complexity, supply chain requirements, and extended treatment timelines also affect product availability. As a result, despite continued progress in therapy development, the use of advanced treatments remains concentrated in selected markets with established healthcare systems and specialized hematology centers. This continues to influence the pace of market expansion across different regions.
The hemoglobinopathies market offers opportunities through strategic acquisitions that strengthen gene therapy development, manufacturing, and commercialization capabilities. As more gene therapies become available for sickle cell disease and beta-thalassemia, companies are expanding their operational capacity to improve patient access and support long-term product supply. Acquisitions also help companies strengthen manufacturing infrastructure, clinical operations, and commercial distribution while reducing development risks associated with advanced therapies. This approach supports broader adoption of gene therapies by improving production capabilities and expanding treatment availability across specialized healthcare centers. Companies are also investing in technologies that improve manufacturing efficiency and supply chain management, creating additional opportunities for market growth. For instance, in June 2025, bluebird bio completed its acquisition by Carlyle and SK Capital. The transaction strengthened bluebird bio's capabilities to support the commercialization and manufacturing of gene therapies for sickle cell disease and beta-thalassemia. The acquisition also included a contingent value right linked to future net sales milestones, supporting the company's long-term commercial strategy.
Market Concentration & Characteristics
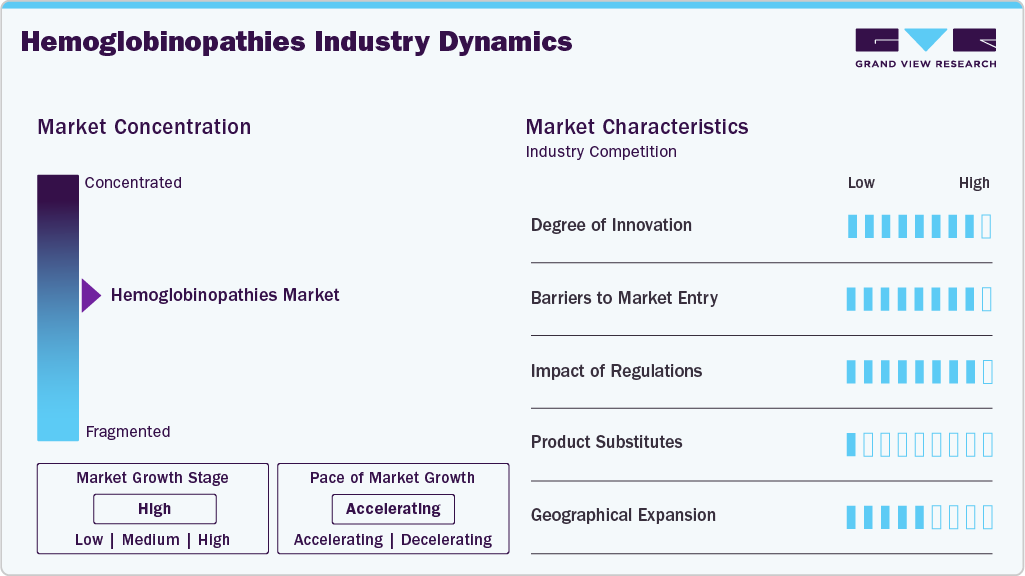
The degree of innovation is high because companies continue to develop gene editing technologies, gene therapies, and disease-modifying treatments for inherited blood disorders. Advances in molecular diagnostics and genetic testing are also improving disease detection, patient selection, and treatment monitoring, supporting continued product development across the hemoglobinopathies market.
The barriers to market entry are high due to the need for significant investment in research, clinical trials, specialized manufacturing, and regulatory compliance. Companies must also establish long-term safety data, manufacturing quality systems, and relationships with specialized treatment centers before entering the commercial market.
 To learn more about this report, Download Free Sample Report
The impact of regulations is high because therapies and diagnostic products must meet strict regulatory requirements for quality, safety, and efficacy. Orphan drug policies, gene therapy guidelines, manufacturing standards, and post-marketing monitoring requirements influence product development, approvals, commercialization, and long-term patient follow-up.
The availability of product substitutes is low because gene therapies and disease-modifying treatments target the underlying cause of hemoglobinopathies. Supportive treatments, including blood transfusions and iron chelation therapy, help manage disease complications but generally do not provide the same therapeutic approach as genetic treatments.
The level of geographical expansion is moderate as companies expand clinical trials, treatment centers, and commercial operations across North America, Europe, Asia Pacific, the Middle East, and Africa. Expansion is supported by rising diagnostic rates, improved healthcare infrastructure, and wider availability of specialized hematology services.
Analyst Perspective
The hemoglobinopathies market is moving toward therapies that address the underlying cause of inherited blood disorders, supported by continued progress in gene therapy and genetic testing. Companies are expanding clinical pipelines while healthcare systems improve diagnosis and patient management. At the same time, treatment access remains uneven because of therapy costs and infrastructure limitations. Continued regulatory approvals and investment in rare disease research are expected to support market development.
Disease Type Insights
The thalassemia segment dominated the hemoglobinopathies industry, accounting for the largest revenue share of 43.4% in 2025. The segment leads due to the large population requiring lifelong disease management, regular blood transfusions, iron chelation therapy, and continuous clinical monitoring. Established treatment guidelines, wider availability of specialized transfusion centers, and increasing access to genetic testing support early diagnosis and long-term patient management. The availability of disease-modifying therapies and the growing adoption of curative approaches, such as gene therapy, have further strengthened treatment options. In addition, government-supported screening programs and improved patient registries contribute to better diagnosis and treatment access across several countries. For instance, in December 2025, the U.S. FDA approved Aqvesme (mitapivat), the first oral treatment for anemia in adults with alpha- or beta-thalassemia, expanding available treatment options for this patient population.
The Sickle cell disease segment is projected to grow at a significant CAGR of 9.6% over the forecast period. Growth is supported by increasing newborn screening programs, broader access to disease-modifying therapies, and rising investment in gene-editing and gene therapy technologies. Growing awareness of early diagnosis and timely treatment is improving patient identification and expanding treatment uptake across developed and emerging healthcare systems. Continued clinical research, regulatory support for innovative therapies, and expansion of specialized treatment centers are strengthening the treatment ecosystem. In addition, collaborations between biotechnology companies, healthcare providers, and patient advocacy organizations are improving access to advanced therapies and long-term disease management.
Type Insights
The therapeutics segment dominated the hemoglobinopathies market, accounting for the largest share of 64.7% in 2025. The segment maintains its leading position because hemoglobinopathies require lifelong disease management through pharmacological therapies, blood transfusions, iron chelation therapy, and supportive care to manage disease progression and related complications. Increasing adoption of disease-modifying therapies and gene-based treatment approaches is expanding the range of available treatment options. Rising diagnosis rates, improved access to specialized treatment centers, and favorable regulatory support for rare disease therapies continue to support treatment adoption. In addition, growing investments in clinical research, expanding pharmaceutical pipelines, and collaborations between biotechnology companies and healthcare providers are contributing to the development and availability of novel therapies. These factors continue to support the dominance of the therapeutics segment.
 To learn more about this report, Download Free Sample Report
The diagnosis segment is expected to grow at a significant CAGR of 8.5% over the forecast period. Growth is driven by expanding newborn screening programs, increasing adoption of molecular and genetic testing, and greater awareness of early disease detection among healthcare providers. The integration of next-generation sequencing, improved laboratory infrastructure, and wider availability of carrier screening programs are supporting earlier and more accurate diagnosis. Government initiatives for prenatal and population screening, coupled with increasing access to diagnostic services in emerging markets, are further contributing to demand. Continued investment in point-of-care technologies and digital diagnostic platforms is also improving testing efficiency and accessibility.
Regional Insights
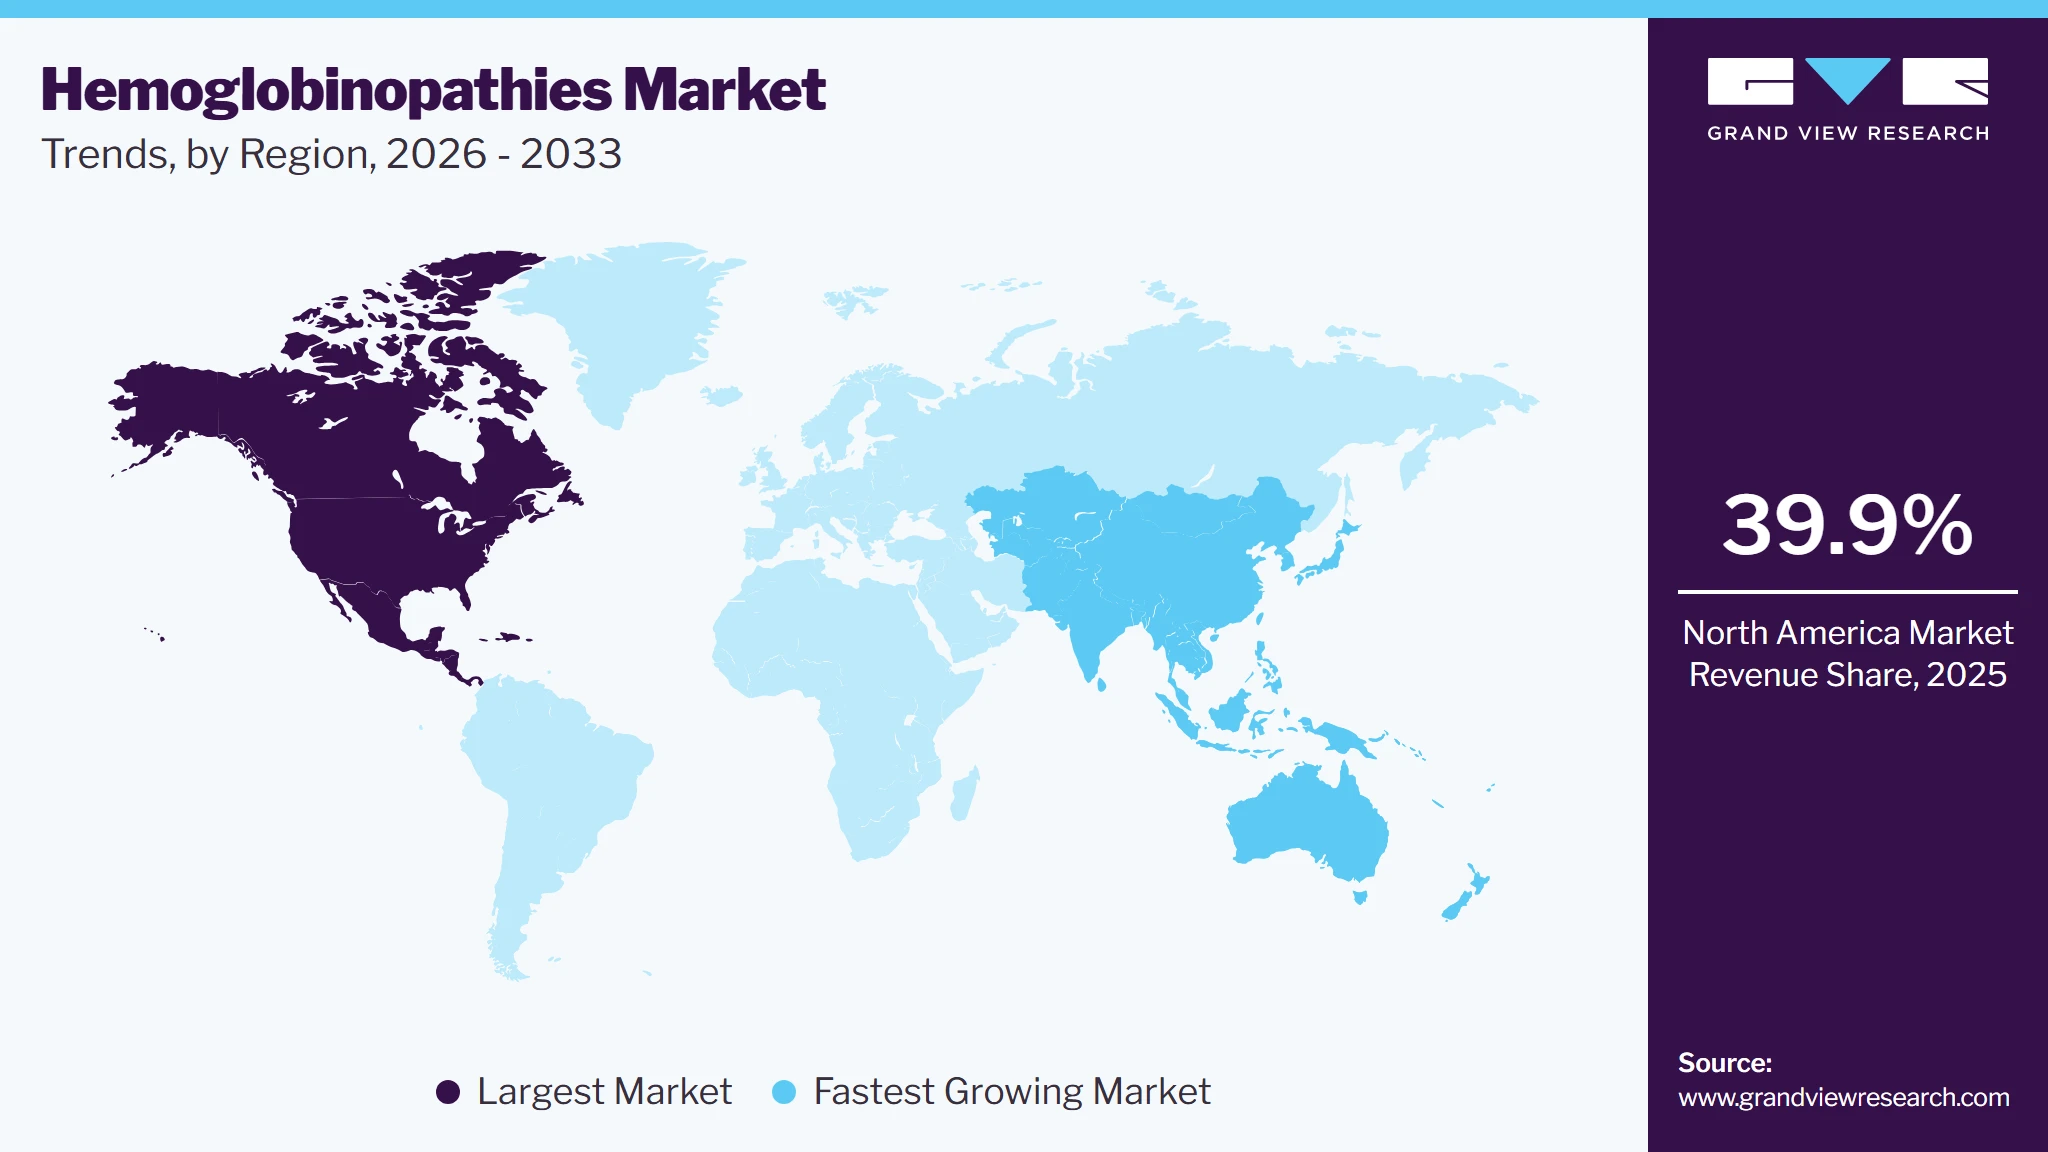
North America dominated the hemoglobinopathies market with the largest share of 39.9% in 2025, due to the availability of advanced diagnostic technologies and specialized hematology treatment centers. The region has a well-established clinical network for managing sickle cell disease and thalassemia across different stages of care. Growing adoption of gene therapies and molecular diagnostic testing continues to expand treatment options. Pharmaceutical companies are increasing investment in rare blood disorder research and commercial activities across the region. Clinical trial participation remains strong, supporting the introduction of new therapies. These factors continue to support the region's leading position in the market.
 To learn more about this report, Download Free Sample Report
U.S. Hemoglobinopathies Market Trends
The U.S. hemoglobinopathies industry accounted for the largest share of North America in 2025, due to the availability of specialized treatment centers and the widespread use of genetic testing. Healthcare providers continue to adopt disease-modifying therapies and advanced diagnostic methods for inherited blood disorders. Ongoing clinical research has expanded treatment options for patients with sickle cell disease and beta-thalassemia. Pharmaceutical companies continue to invest in pipeline development and commercial expansion. The presence of experienced hematology specialists supports patient access to advanced therapies. These factors continue to drive market growth in the country.
Europe Hemoglobinopathies Market Trends
Europe held a significant share of the hemoglobinopathies industry in 2025, due to established healthcare systems and increasing use of molecular diagnostics. Countries across the region continue to strengthen specialized care for patients with inherited blood disorders. The availability of advanced laboratory infrastructure supports early diagnosis and routine disease monitoring. Companies are expanding their presence through clinical research and the commercialization of new therapies. Collaboration between research institutions and healthcare providers supports continued product development. These factors contribute to stable market growth across Europe.
The UK hemoglobinopathies market is supported by growing use of genetic screening and established clinical management programs for sickle cell disease and thalassemia. Healthcare providers continue to improve disease diagnosis through advanced laboratory testing. The country has several specialized hematology centers that support long-term patient management. Research organizations and pharmaceutical companies continue to participate in clinical development programs. Increasing awareness of inherited blood disorders has improved patient identification. These factors support continued market expansion in the UK.
The hemoglobinopathies market in Germany is important in Europe, due to its advanced diagnostic infrastructure and availability of specialized healthcare services. Hospitals continue to adopt molecular diagnostic technologies for accurate disease identification. The country actively participates in clinical research focused on rare hematological disorders. Pharmaceutical companies continue to expand research collaborations and product availability. Growing use of personalized treatment approaches supports disease management. These factors contribute to steady market development in Germany.
The France hemoglobinopathies market continues to strengthen its position in Europe through improved diagnosis and specialized treatment services. Healthcare institutions are expanding the use of genetic testing for inherited blood disorders. Clinical research activities continue to support the development of new treatment options. Hospitals provide multidisciplinary care for patients requiring long-term disease management. The availability of specialized hematology expertise supports treatment planning and follow-up. These factors continue to support market growth across the country.
Asia Pacific Hemoglobinopathies Market Trends
The Asia Pacific hemoglobinopathies industry is projected to grow at the fastest CAGR of 11.0% during the forecast period. The region has a large patient population affected by thalassemia and sickle cell disease, creating consistent demand for diagnosis and treatment. Expanding healthcare infrastructure is improving access to specialized hematology services across several countries. Healthcare providers are increasing the use of genetic testing and disease screening programs. Pharmaceutical companies continue to expand clinical research and commercial activities across the region. These factors support the rapid regional market growth.
The Japan hemoglobinopathies market is important in Asia Pacific, due to its advanced diagnostic capabilities and established healthcare infrastructure. Healthcare providers continue to adopt molecular testing for accurate diagnosis of inherited blood disorders. Research institutions are involved in clinical studies focused on gene and cell therapies. Pharmaceutical companies are expanding development activities for rare hematological diseases. Hospitals provide specialized care for patients requiring long-term disease management. These factors support steady market growth.
The hemoglobinopathies market in China is witnessing growth, due to increasing diagnosis of thalassemia, particularly in southern provinces where disease prevalence is higher. Healthcare providers are expanding access to genetic screening and laboratory testing for early disease identification. Investment in hospital infrastructure has improved the availability of specialized hematology services. Domestic and international pharmaceutical companies continue to expand clinical research activities in the country. Growing awareness of inherited blood disorders has increased patient diagnosis and treatment. These factors continue to support market expansion,
Latin America Hemoglobinopathies Market Trends
The Latin America hemoglobinopathies industry is growing with improving access to diagnostic services and disease management programs. Healthcare providers are increasing the use of laboratory testing for early identification of inherited blood disorders. Demand for supportive therapies continues to rise as diagnosis rates improve across the region. Pharmaceutical companies are expanding their commercial presence through partnerships with healthcare institutions. The availability of specialized treatment centers is gradually improving in major countries. These factors support continued market development across Latin America.
The Brazil hemoglobinopathies market accounts for a significant share of Latin America due to the presence of a large population affected by sickle cell disease. Hospitals continue to strengthen diagnosis through expanded use of laboratories and genetic testing. Specialized hematology centers provide long-term treatment and disease monitoring for affected patients. Clinical research activities continue to increase across leading healthcare institutions. Pharmaceutical companies are expanding access to disease-modifying therapies through commercial partnerships. These factors continue to support market growth in Brazil.
Middle East & Africa Hemoglobinopathies Market Trends
The Middle East & Africa hemoglobinopathies industry is growing due to the relatively high prevalence of sickle cell disease and thalassemia in several countries. Healthcare providers are increasing the use of newborn screening and genetic diagnostic services for early disease detection. Demand for blood transfusion services and supportive therapies remains steady across the region. Specialized treatment centers are expanding patient management capabilities for inherited blood disorders. Pharmaceutical companies continue to strengthen their presence through regional partnerships and product availability. These factors contribute to continued market growth across the region.
The Saudi Arabia hemoglobinopathies market is growing, due to the relatively high burden of inherited blood disorders, particularly sickle cell disease and thalassemia. Healthcare providers continue to expand genetic testing and specialized hematology services for early diagnosis and treatment planning. Hospitals are increasing the use of molecular diagnostic technologies for patient management. Clinical research activities are supporting the evaluation of new treatment options for rare blood disorders. The availability of specialized treatment centers has improved access to comprehensive patient care. These factors continue to support the market growth.
Key Hemoglobinopathies Company Insights
The hemoglobinopathies market is fragmented, with pharmaceutical companies, biotechnology firms, and diagnostic manufacturers competing through product development, clinical research, and strategic collaborations. Vertex Pharmaceuticals Incorporated, Beam Therapeutics Inc., Editas Medicine, Inc., and Fulcrum Therapeutics, Inc. focus on gene editing and genetic medicine for sickle cell disease and beta-thalassemia. Novartis AG, Bristol Myers Squibb, and Emmaus Life Sciences, Inc. offer therapies and continue expanding their hematology portfolios. Thermo Fisher Scientific Inc., Sebia Group, F. Hoffmann-La Roche Ltd., Abbott Laboratories, and Siemens Healthineers AG support the market through diagnostic instruments, testing solutions, and laboratory technologies used for disease detection and monitoring. Genetix Biotherapeutics Inc. and Novo Nordisk A/S are involved in research collaborations and pipeline development, contributing to ongoing innovation and broader treatment options for patients with hemoglobinopathies.
Key Hemoglobinopathies Companies
The following key companies have been profiled for this study on the Hemoglobinopathies market.
-
Vertex Pharmaceuticals Incorporated
-
Genetix Biotherapeutics Inc.
-
Novartis AG
-
Emmaus Life Sciences, Inc.
-
Bristol Myers Squibb
-
Novo Nordisk A/S
-
Beam Therapeutics Inc.
-
Editas Medicine, Inc.
-
Fulcrum Therapeutics, Inc.
-
Thermo Fisher Scientific Inc.
-
Sebia Group
-
F. Hoffmann-La Roche Ltd.
-
Abbott Laboratories
-
Siemens Healthineers AG
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Novartis AG
- Mature players focus on expanding treatment portfolios for sickle cell disease and beta-thalassemia through product approvals, clinical studies, and strategic collaborations.
- These companies also strengthen relationships with healthcare providers, research institutes, and regulatory agencies to improve product availability and support long-term business growth.
- These companies benefit from established manufacturing facilities, broad commercial networks, diversified product portfolios, financial resources, and experience in regulatory compliance.
- Their presence across therapeutic and diagnostic segments enables integrated solutions for disease diagnosis, treatment, and patient monitoring.
- Mature companies face high research and manufacturing costs, lengthy regulatory review timelines, pricing pressure, and competition from new gene-editing technologies and biosimilar products.
- Large organizational structures may also slow decision-making and delay the adoption of new technologies in changing healthcare environments.
Emerging Players: Beam Therapeutics Inc.
- Emerging players prioritize the development of gene editing, gene therapy, and disease-modifying treatments for inherited blood disorders.
- Their strategies include advancing clinical pipelines, forming licensing and research collaborations, securing funding, and expanding clinical trial programs to support product development and future commercialization.
- These companies benefit from focused research programs, specialized technology platforms, flexible development models, and collaborations with academic institutions and pharmaceutical companies.
- Their emphasis on genetic medicine enables the development of targeted therapies that address the underlying cause of hemoglobinopathies.
- Emerging companies often have limited commercial infrastructure, manufacturing capacity, and financial resources compared with established pharmaceutical companies.
- They also face clinical development risks, regulatory uncertainty, funding requirements, and challenges associated with scaling production and expanding market access after product approval.
Recent Developments
-
In July 2026, the U.S. FDA expanded the approval of CASGEVY (exagamglogene autotemcel) for patients aged two years and older with sickle cell disease, extending access to gene therapy for younger pediatric patients.
-
In May 2026, Vertex Pharmaceuticals Incorporated announced a reimbursement agreement in Germany for its gene therapy for eligible patients with sickle cell disease and transfusion-dependent beta-thalassemia. The agreement expanded commercial access to the therapy for eligible patients in Germany.
-
In June 2025, Emmaus Life Sciences, Inc. received U.S. FDA approval for updated labeling of its sickle cell disease therapy. The revised label included additional pharmacokinetic information, confirmation of body weight-based dosing, administration with or without food, and updated prescribing information to support clinical use.
Hemoglobinopathies Market Report Scope
Report Attribute
Details
Market size in 2025
USD 11.0 billion
Estimated market size in 2026
USD 11.9 billion
Projected market size by 2033
USD 22.4 billion
Growth rate
CAGR of 9.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, trends
Segments covered
Disease type, type, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; Australia; South Korea; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key company profiled
Vertex Pharmaceuticals Incorporated; Genetix Biotherapeutics Inc.; Novartis AG; Emmaus Life Sciences, Inc.; Bristol Myers Squibb; Novo Nordisk A/S; Beam Therapeutics Inc.; Editas Medicine, Inc.; Fulcrum Therapeutics, Inc.; Thermo Fisher Scientific Inc.; Sebia Group; F. Hoffmann-La Roche Ltd.; Abbott Laboratories; Siemens Healthineers AG
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Hemoglobinopathies Market Report Segmentation
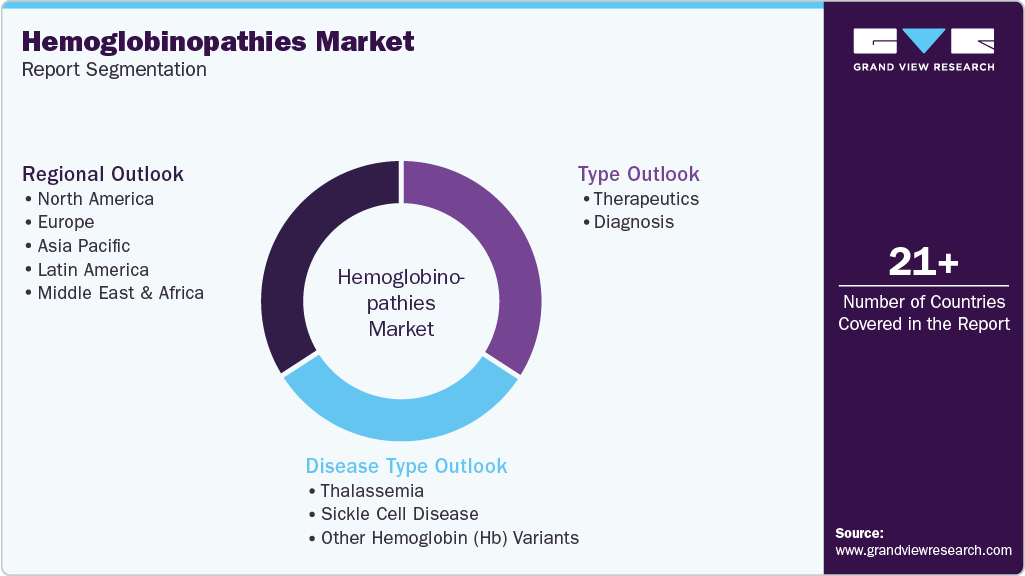
This report forecasts revenue growth at the global, regional & country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global hemoglobinopathies market report based on disease type, type, and region:
 To learn more about this report, Download Free Sample Report
-
Disease Type Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Thalassemia
-
Sickle Cell Disease
-
Other Hemoglobin (Hb) Variants
-
-
Type Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Diagnosis
-
Thalassemia
-
Blood test
-
Genetic test
-
Prenatal genetic testing
-
Pre-implantation genetic diagnosis
-
Hb Electrophoresis
-
Others
-
-
Sickle cell disease
-
Blood Test
-
Genetic Test
-
Prenatal Genetic Test
-
Electrophoresis
-
Others
-
-
Other Hemoglobin (Hb) Variants
-
Blood Test
-
Genetic Test
-
Prenatal Genetic Test
-
Electrophoresis
-
Others
-
-
-
Therapeutics
-
Thalassemia
-
Blood Transfusion
-
Iron Chelation Therapy
-
Bone Marrow Transplant
-
Others
-
-
Sickle Cell Disease
-
Blood Transfusion
-
Hydroxyurea
-
Bone Marrow Transplant
-
Others
-
-
Other Hemoglobin (Hb) Variants
-
Blood Transfusion
-
Hydroxyurea
-
Iron Chelation Therapy
-
Bone Marrow Transplant
-
Others
-
-
-
-
Regional Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
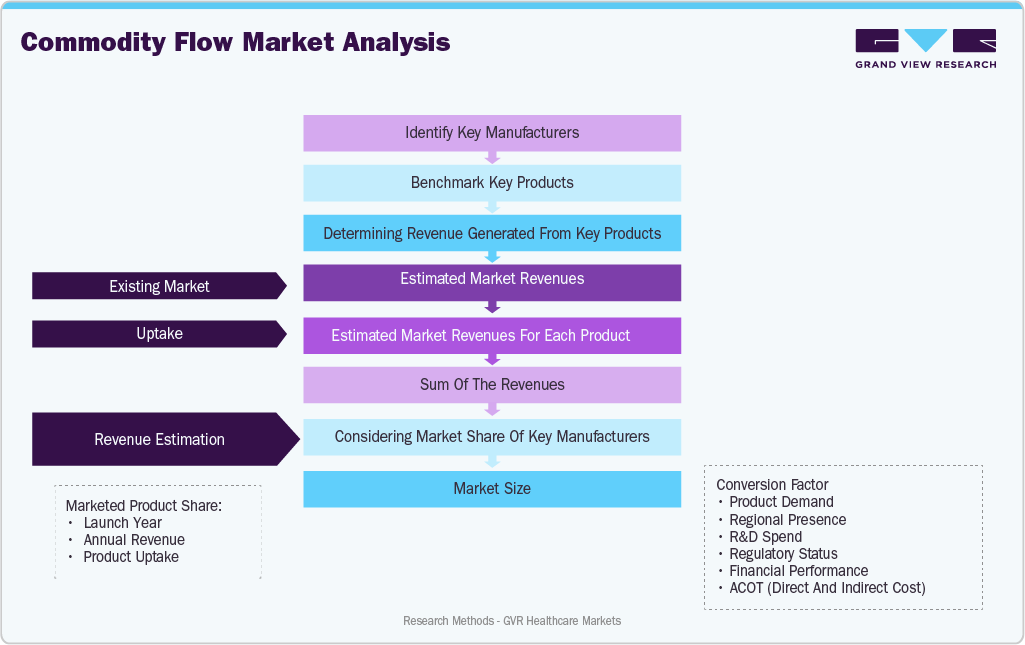
The hemoglobinopathies market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each hemoglobinopathies segment quantified using the revenue-capture definitions in the table below.
 To learn more about this report, Download Free Sample Report
The commodity flow model estimates the hemoglobinopathies market by identifying key manufacturers and marketed therapies across major regions. Commercial products, including hydroxyurea, iron chelation therapies, L-glutamine, gene therapies, and supportive treatments, are benchmarked based on product sales, pricing, geographic availability, regulatory approvals, and treatment adoption. Revenue generated from key products is assessed using company annual reports, investor presentations, SEC filings, healthcare procurement data, government publications, and industry databases. Product-level revenues are estimated for each manufacturer and aggregated to determine the existing market value. The analysis also considers prescription trends, treatment duration, and the adoption of newly approved therapies to refine estimates. The aggregated revenues are validated through primary interviews with manufacturers, distributors, hematologists, and key opinion leaders. Final market estimates are cross-verified using company market presence, product portfolios, and regional demand patterns to ensure consistent market sizing.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Global Hemoglobinopathies Treatment Market Assessment (U.S., Europe & Asia Pacific)
Conducted an assessment of the hemoglobinopathies treatment market across the U.S., Germany, the UK, China, Japan, and India. The study covered disease prevalence, diagnosis rates, treatment options, gene therapy adoption, pricing, healthcare infrastructure, and distribution channels for sickle cell disease and thalassemia therapies.
Helped the client identify countries with treatment demand, compare treatment practices, understand patient access, and evaluate regional opportunities. The study also supported product planning by identifying markets with increasing diagnosis rates and expanding use of advanced therapies.
Hemoglobinopathies Therapeutics Pipeline & Competitive Assessment
Delivered a competitive assessment of marketed products and pipeline therapies for hemoglobinopathies. The study covered clinical development, gene therapies, disease-modifying treatments, licensing activities, research collaborations, manufacturing capabilities, and product positioning across sickle cell disease and thalassemia treatment segments.
Helped the client compare pipeline products, assess competitor activities, identify partnership opportunities, and understand product positioning. The study also supported portfolio planning and business decisions related to the hemoglobinopathies treatment market.
Emerging Market Hemoglobinopathies Diagnosis & Treatment Assessment
Conducted a country-level assessment of diagnosis and treatment infrastructure across Brazil, Saudi Arabia, South Africa, India, Indonesia, and Mexico. The study evaluated laboratory capacity, genetic testing availability, hematology centers, treatment access, referral networks, and patient management practices for inherited blood disorders.
Helped the client identify markets with improving diagnosis and treatment access, understand infrastructure gaps, and evaluate regional expansion opportunities. The study also supported planning for resource allocation, market entry, and collaboration with healthcare providers in developing markets.
Frequently Asked Questions About This Report
The global hemoglobinopathies market size was valued at USD 11.0 billion in 2025 and is estimated at USD 11.9 billion in 2026.
The global hemoglobinopathies market is expected to grow at a CAGR of 9.4% from 2026 to 2033, reaching USD 22.4 billion by 2033.
By disease type the thalassemia segment accounted for the largest revenue share, 43.4% in 2025, while the sickle cell disease segment is the fastest-growing, with a CAGR of 9.6% over the forecast period.
Key players include Vertex Pharmaceuticals Incorporated, Genetix Biotherapeutics Inc., Novartis AG, Emmaus Life Sciences, Inc., Bristol Myers Squibb, Novo Nordisk A/S, Beam Therapeutics Inc., Editas Medicine, Inc., Fulcrum Therapeutics, Inc., Thermo Fisher Scientific Inc., Sebia Group, F. Hoffmann-La Roche Ltd., Abbott Laboratories, and Siemens Healthineers AG.
Key factors include expanding gene therapy approvals and development programs, increasing prevalence of sickle cell disease and thalassemia, wider adoption of newborn screening and genetic testing, growing regulatory support for rare disease therapies, and increasing investments in genetic medicine and specialized hematology centers.
North America dominated the global hemoglobinopathies market with a 39.9% revenue share in 2025.
Asia Pacific is projected to be the fastest-growing regional market, registering a CAGR of 11.0% during the forecast period.
The therapeutics segment held the largest revenue share of 64.7% in 2025, while the diagnosis segment is projected to be the fastest-growing, expanding at a CAGR of 8.5% during the forecast period.
The market is witnessing increasing adoption of gene therapies, gene-editing technologies, disease-modifying therapies, molecular diagnostics, and genetic testing, supported by expanding specialized treatment centers and continued investment in precision medicine.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


