
- Home
- »
- Plastics, Polymers & Resins
- »
-
High Performance Plastics Market Size & Share Report, 2033GVR Report cover

High Performance Plastics Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Fluoropolymers, Polyamides, PPS, SP, LCP), By Application (Transportation, Electrical & Electronics, Industrial, Medical), By Region, And Segment Forecasts
Market Size, 2025
$28.8BMarket Estimate, 2026
$31.2BMarket Forecast, 2033
$62.0BCAGR, 2026–2033
9.3%High Performance Plastics Market Trends
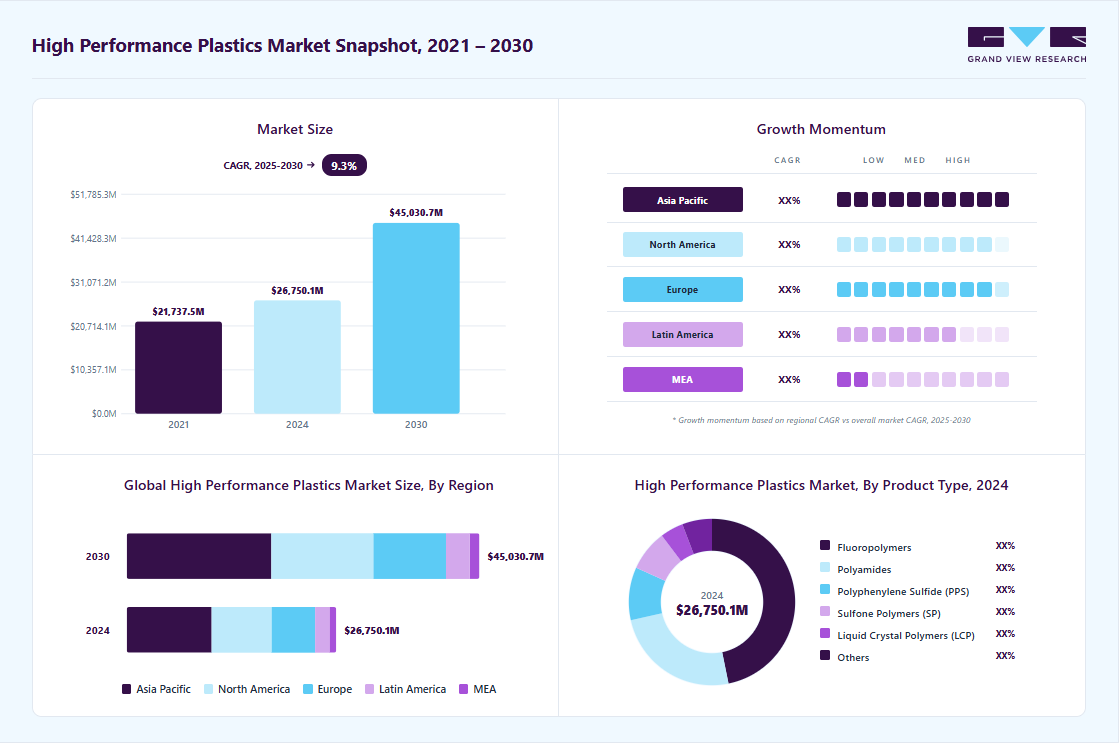
The global high performance plastics market size was valued at USD 28.8 billion in 2025 and is projected to grow from USD 31.2 billion in 2026 to USD 62.0 billion by 2033, at a CAGR of 9.3% from 2026 to 2033. Asia Pacific dominated the market, accounting for the largest global share of 40.5% in 2025. Increasing adoption of electric vehicles and expanding use of high performance plastics across battery casings, lightweight structural components, thermal management systems, aerospace structures, and under-the-hood automotive applications are driving the high performance plastics market growth.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Fluoropolymers segment held the largest revenue share of 47.3% in 2025.
- By application: Transportation segment held the largest revenue share of 44.1% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (40.5% revenue share, 2025)
- By country: The China held the largest share of Asia Pacific in 2025.
Market Size & Forecast
- Market size in 2025: USD 28.8 Billion
- Estimated market size in 2026: USD 31.2 Billion
- Projected market size by 2033: USD 62.0 Billion
- CAGR (2026-2033): 9.3%
Prism AI by Grand View Research Free to tryAsk a question about the high performance plastics marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Rising demand for carbon-fiber-reinforced and glass-fiber-reinforced high performance plastics further supports market expansion due to their excellent strength-to-weight ratio, thermal stability, mechanical durability, and ability to improve energy efficiency while reducing emissions.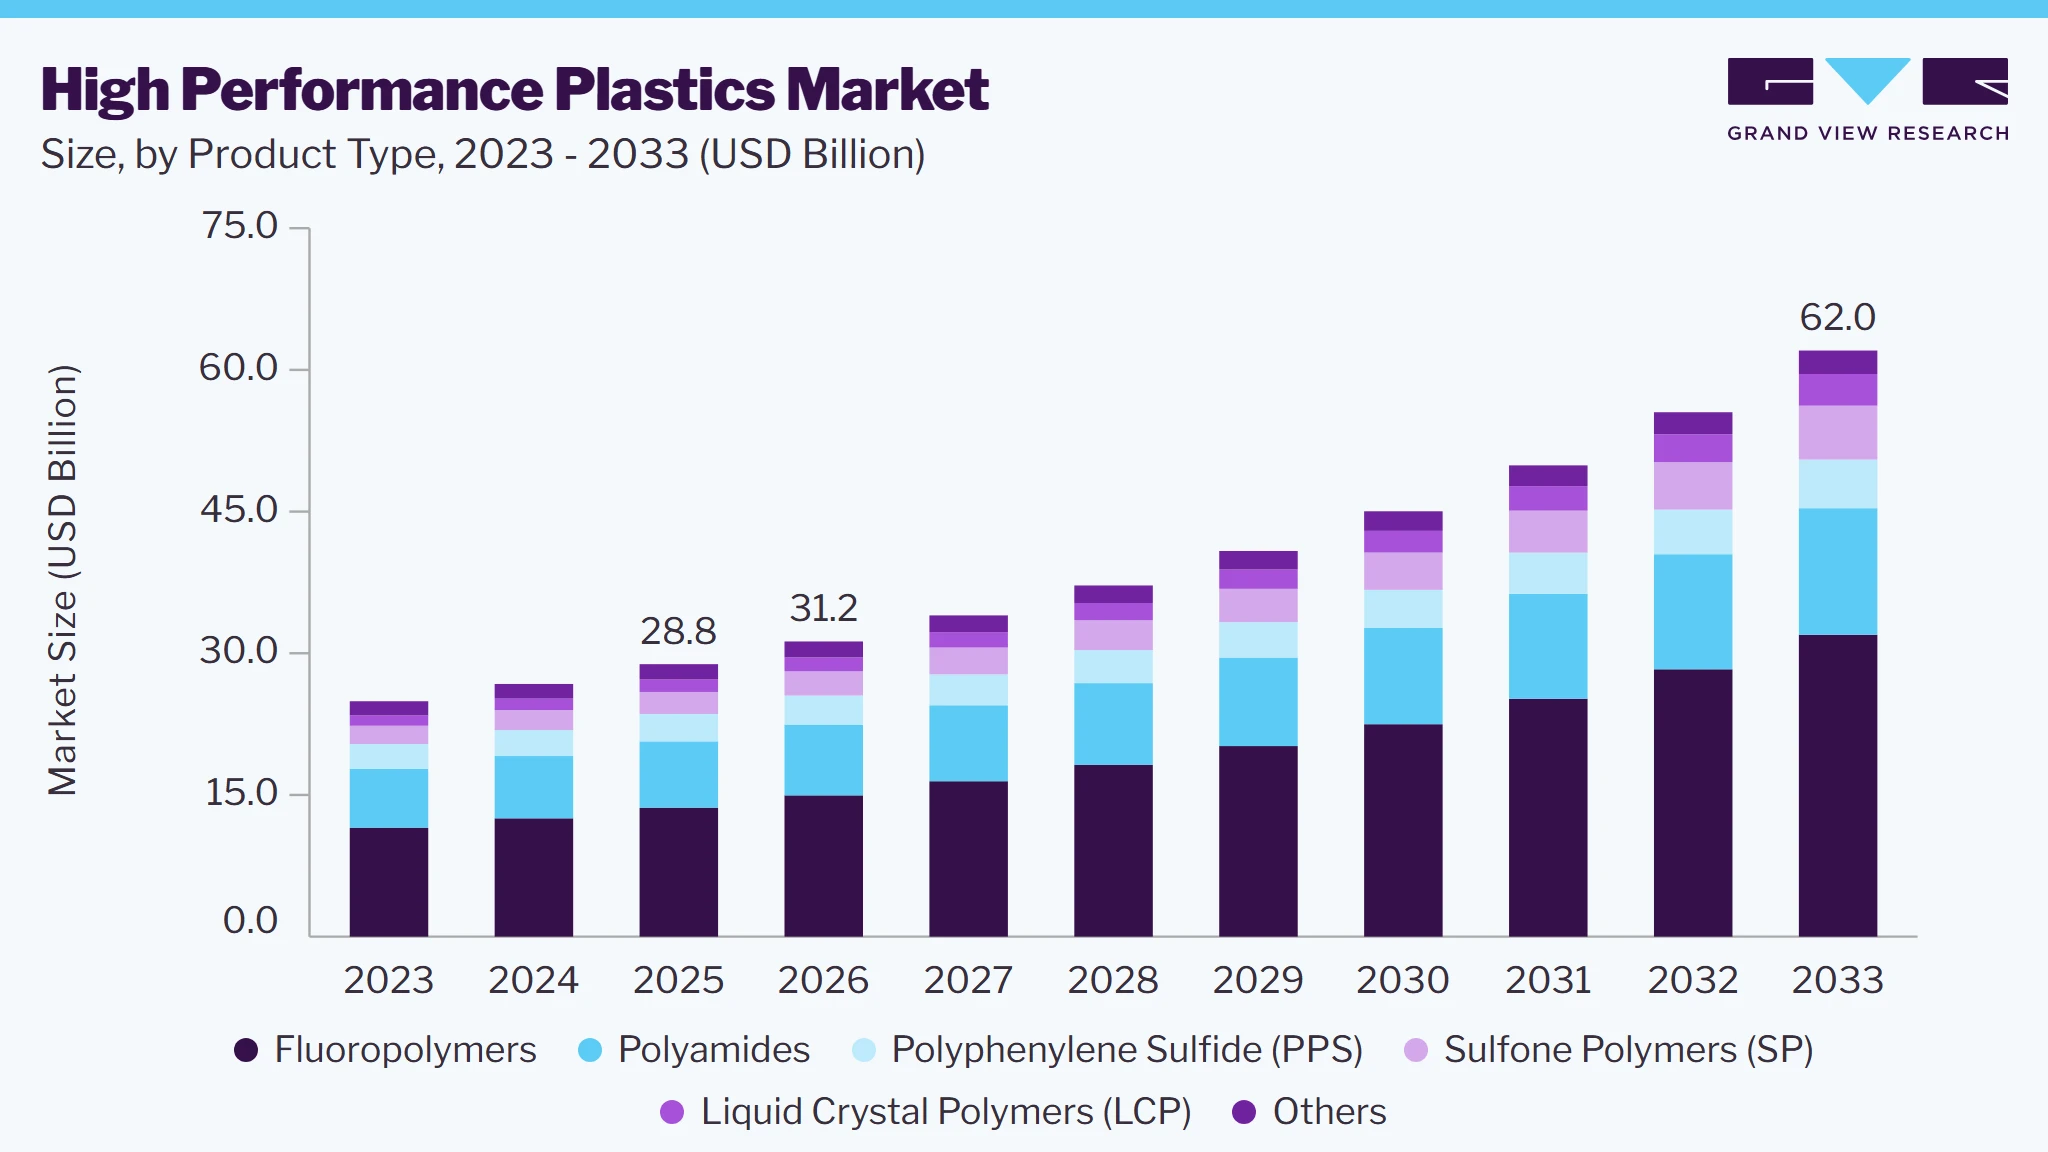 To learn more about this report, Download Free Sample Report
The high-performance plastics market is witnessing a strong shift toward lightweight and high-strength materials, particularly in aerospace and automotive applications. Manufacturers are prioritizing materials that reduce weight without compromising durability, thermal stability, and mechanical strength. The increasing use of carbon-fiber-reinforced and glass-fiber-reinforced high-performance plastics in structural and under-the-hood automotive components is replacing traditional metals. In aerospace, regulatory mandates for fuel efficiency and emission reductions are driving demand for advanced polymers that can withstand extreme temperatures while reducing overall aircraft weight. This trend aligns with the broader shift toward energy efficiency and sustainability across industries.
 To learn more about this report, Download Free Sample Report
Market Dynamics
High performance plastics demand is shaped by qualification-led adoption in aerospace, transportation, electronics, and medical systems, where thermal stability, chemical resistance, and weight reduction justify premium pricing. Demand is concentrated in Asia Pacific, especially China, Japan, South Korea, and Taiwan, while North America and Europe remain important for EV, aerospace, and regulated industrial applications. The commercial structure is fragmented at the resin level but concentrated among a small group of global suppliers with strong application engineering, long customer approval cycles, and localized converting or compounding networks. This favors suppliers that can secure design-in positions and long-term supply contracts.
The strongest market driver is the widening use of high performance plastics in EV and power electronics architectures. Automakers are replacing metals with PPS, fluoropolymers, LCP, and related high temperature grades in battery casings, connectors, bus bars, thermal components, and structural parts because these materials support lighter designs, better insulation, and higher heat tolerance. As EV platforms expand, resin demand is increasingly tied to system level performance requirements rather than simple material substitution. This raises the value of application specific formulations and strengthens demand for premium grades with strict dimensional and flame performance targets.
A second layer of demand comes from electronics miniaturization and semiconductor intensity. Asia Pacific remains the center of global electronics and chip manufacturing, which supports large scale use of fluoropolymers and LCP in high frequency connectors, insulation coatings, wafer processing equipment, and compact device housings. As 5G infrastructure, wearable devices, and high density consumer electronics scale up, customers need polymers that combine low dielectric loss, cleanliness, and thermal stability. That requirement lifts average selling prices and rewards suppliers that can deliver qualified grades with reliable regional supply.
The main restraint is the high cost and complexity of resin synthesis, compounding, and qualification. Fluoropolymers, PPS, LCP, sulfone polymers, and polyamides often require specialized feedstocks, precise process control, and application testing before commercial release. That creates long lead times, high working capital needs, and limited flexibility for price sensitive customers. In addition, demand is concentrated in a few premium end uses, so volume growth can remain uneven when OEM build rates soften or project approvals slow. These factors keep adoption selective and reinforce the bargaining power of large, approved suppliers.
A clear opportunity lies in recyclable, lower carbon, and application tailored high performance grades for EV, electronics, and healthcare systems. Customers are increasingly asking for lighter parts, lower energy losses, and longer service life, which creates room for bio based additives, recycled content in noncritical components, and more efficient processing platforms. Suppliers that combine technical approvals with sustainability credentials can win replacement programs and higher margin custom formulations.
Analyst Perspective
The high-performance plastics market is moving from broad material substitution toward solution-led, application-specific commercialization. EV platforms, semiconductor manufacturing, advanced electronics, and aerospace remain the core demand engines, but the value pool is shifting toward qualified grades with tighter performance windows, cleaner processing, and stronger sustainability credentials. Over the next 5 to 10 years, the market should evolve from a pure performance and volume model into a more innovation-driven and specification-intensive structure. Leaders will be defined by polymer chemistry depth, local manufacturing presence, long approval cycles, and the ability to co-develop parts with OEMs and tier suppliers. Partnerships, intellectual property, and regional supply resilience will matter more as customers seek stable supply and lower lifecycle emissions. Margins may face pressure from feedstock volatility, export constraints, and high qualification costs, but suppliers that can combine premium performance with recyclable or lower carbon solutions should capture the strongest long-term opportunities.
Product Insights
Based on product, the fluoropolymers high performance plastics segment led the market with the largest revenue share of 47.3% in 2025 due to their exceptional chemical resistance, low friction, and high thermal stability. With the rapid expansion of the semiconductor industry, particularly in Asia Pacific and North America, these advanced polymers are being widely used in wafer processing equipment, chemical storage systems, and high-purity fluid handling components. The rise of extreme ultraviolet (EUV) lithography and advanced chip fabrication techniques has increased the need for materials that can withstand aggressive cleaning agents and high temperatures without degradation. As semiconductor manufacturers push for higher production efficiency and miniaturization, fluoropolymers are becoming indispensable in ensuring operational reliability and contamination control.
The increasing deployment of 5G networks and the rapid expansion of IoT ecosystems are fueling demand for liquid crystal polymers (LCP) due to their excellent electrical properties and high-frequency signal transmission capabilities. LCPs offer low dielectric loss, high heat resistance, and dimensional stability, making them ideal for miniaturized electronic components such as flexible circuits, connectors, and antennas in 5G infrastructure and smart devices.
As global telecom operators accelerate 5G rollout and IoT applications expand into smart homes, automotive connectivity, and industrial automation, LCPs are emerging as a critical material for ensuring reliable, high-speed data transmission with minimal energy loss. This shift is significantly driving innovation and investment in LCP-based materials.
Application Insights
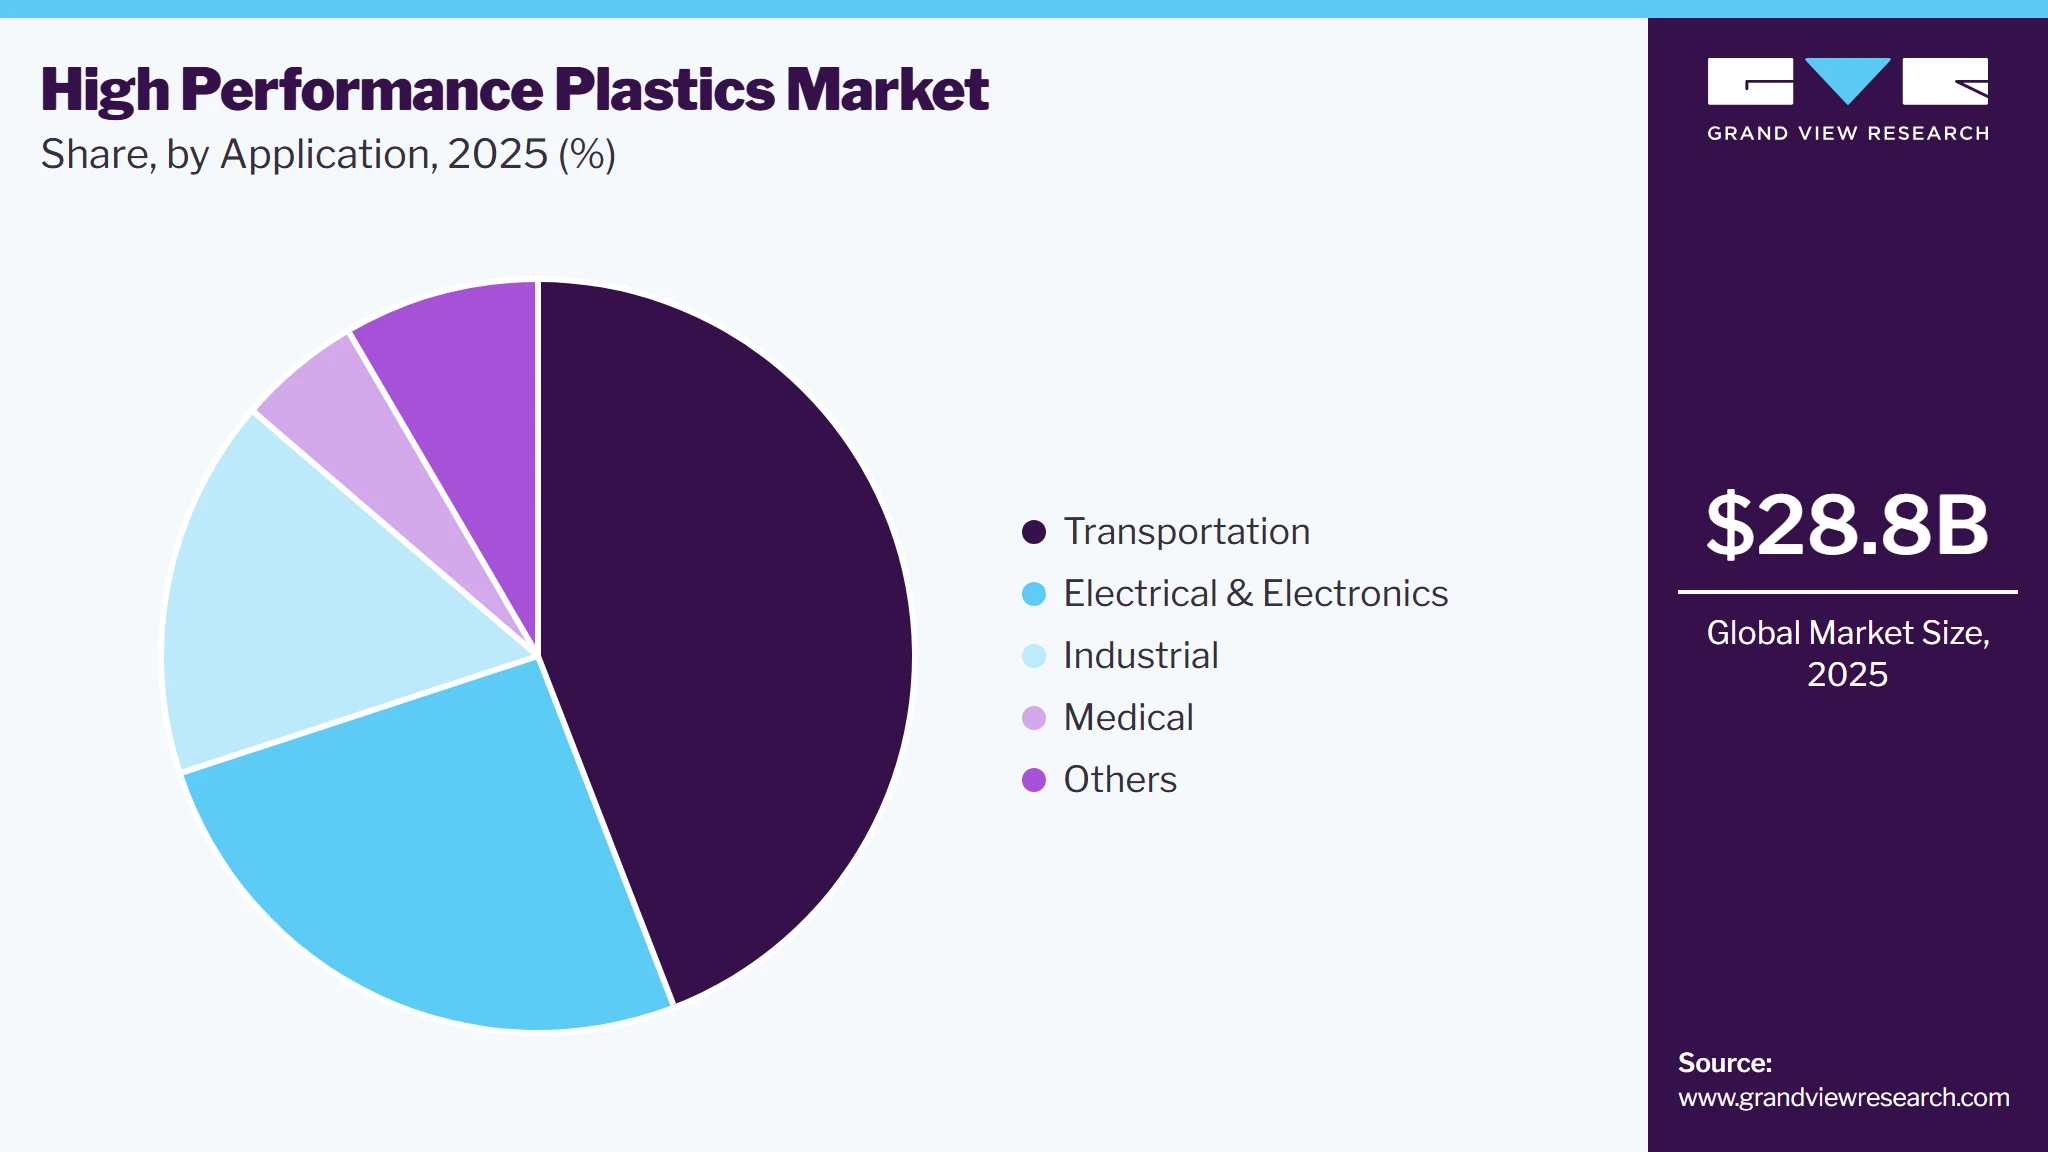
Based on application, the transportation segment led the market with the largest revenue share of 44.1% in 2025. The transportation industry is undergoing a major transformation, with automakers and aerospace manufacturers prioritizing lightweight materials to enhance fuel efficiency and reduce carbon emissions. High-performance plastics, including polyetheretherketone (PEEK), polyphenylene sulfide (PPS), and polyimides, are increasingly replacing metals in structural, under-the-hood, and interior components due to their high strength-to-weight ratio, thermal resistance, and durability. With stricter regulatory mandates such as Euro 7 emission standards and the U.S. government’s push for vehicle electrification, demand for high-performance plastics in transportation is growing rapidly. This trend is not only improving vehicle performance and battery range but also reducing overall production costs through material consolidation and design flexibility.
 To learn more about this report, Download Free Sample Report
The demand for high-performance plastics in the electrical and electronics industry is rising as manufacturers seek advanced materials capable of withstanding high temperatures and providing superior insulation in compact, high-power devices. With the proliferation of miniaturized electronics, power-hungry processors, and next-generation wearable technology, there is an urgent need for polymers such as polyetherimide (PEI) and polyaryletherketone (PAEK) that offer excellent thermal stability, dielectric strength, and flame resistance.
Regional Insights
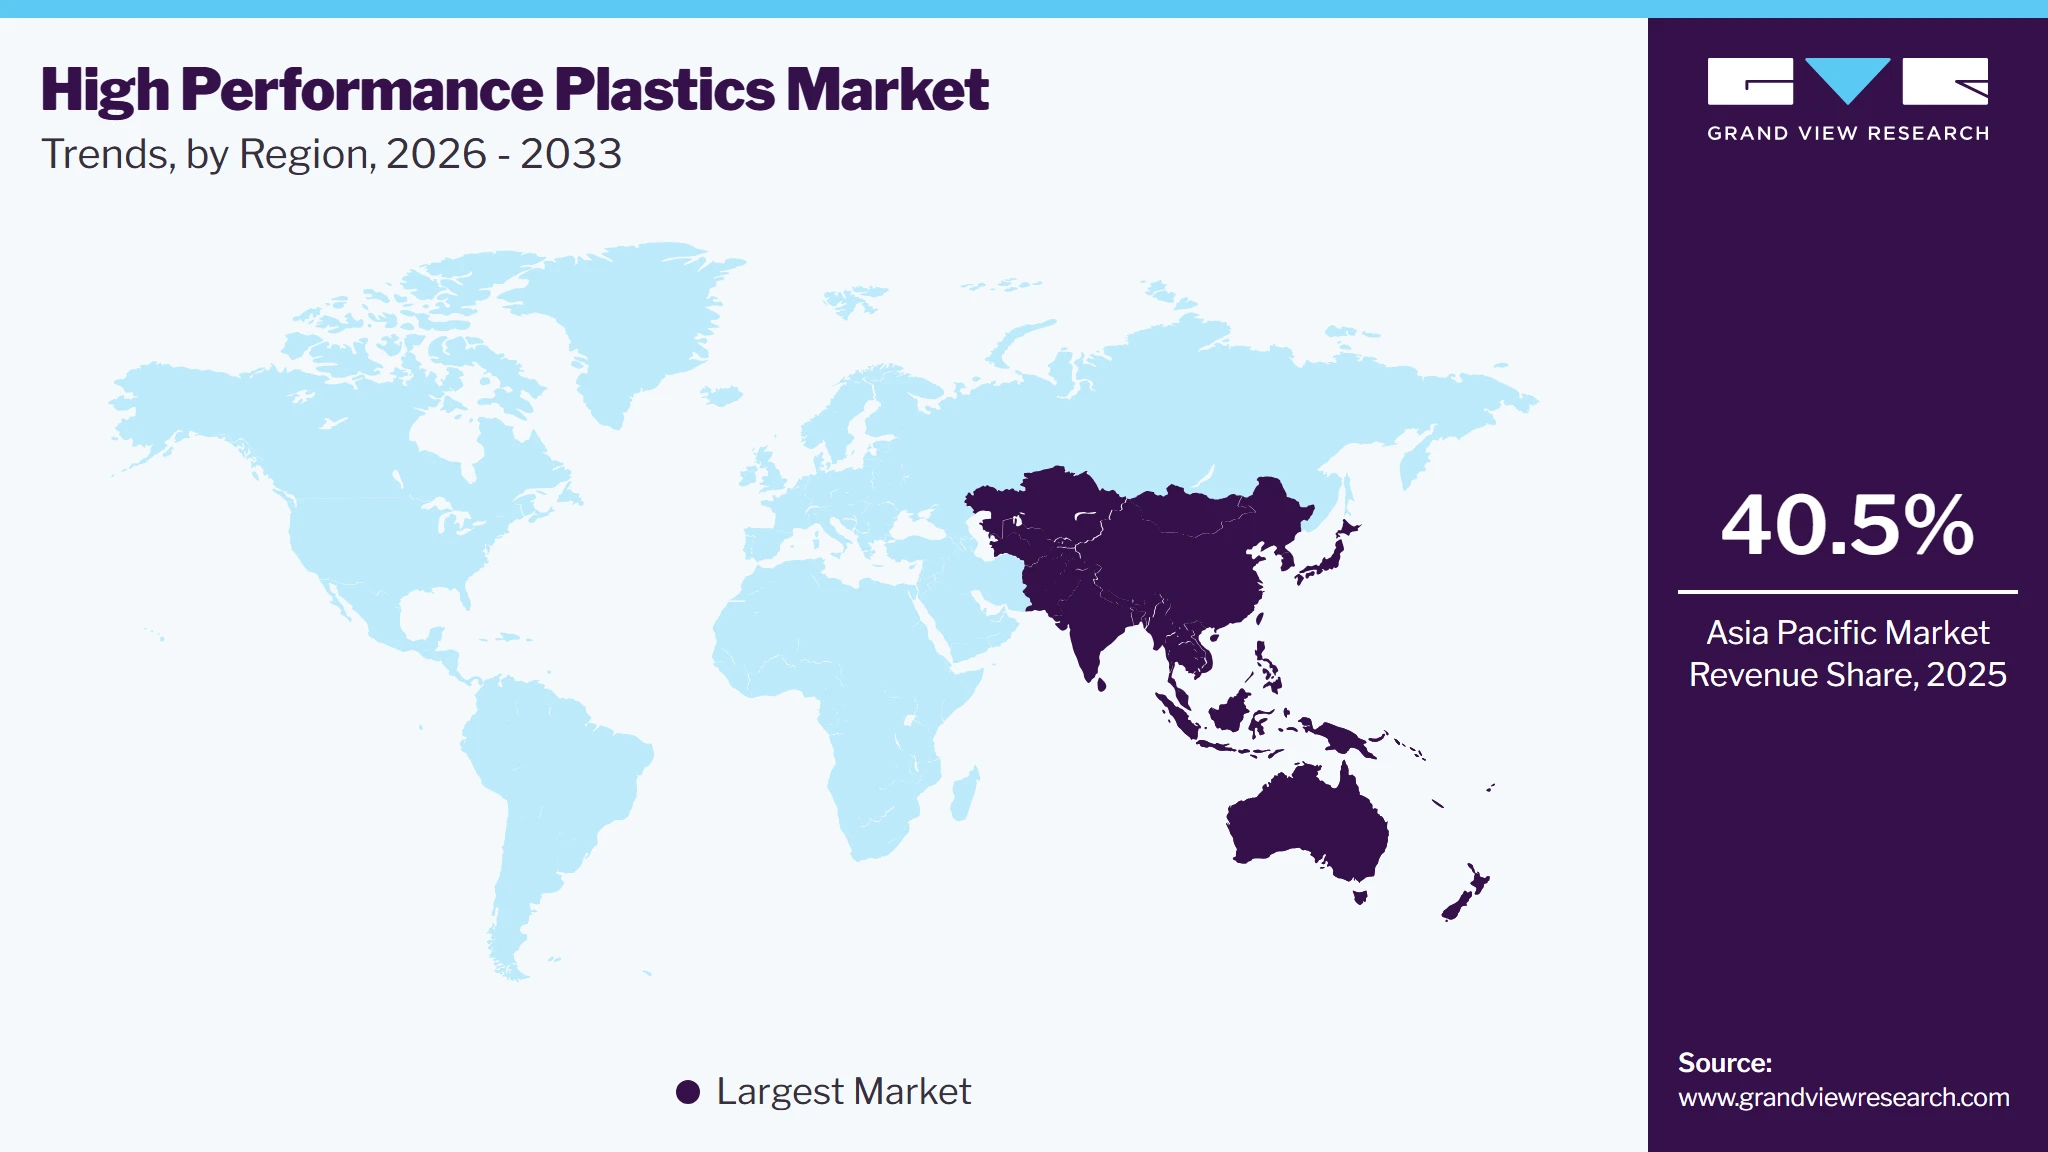
Asia Pacific dominated the high performance plastics market with the largest revenue share of 40.5% in 2025, which is attributable to the region’s dominance in semiconductor and consumer electronics manufacturing. Countries such as South Korea, Japan, and Taiwan are leading producers of advanced microchips, where high-performance polymers such as LCP and PEEK play a crucial role in high-speed connectors, insulation coatings, and miniaturized circuit components. In addition, the region's expanding 5G infrastructure and growing demand for high-end smartphones, wearable technology, and smart appliances are further boosting the need for advanced polymer solutions. With government incentives supporting semiconductor production and electronic exports, particularly in Taiwan and South Korea, Asia Pacific remains a key market for high-performance plastics used in next-generation electronics and connectivity solutions.
 To learn more about this report, Download Free Sample Report
China High Performance Plastics Market Trends
The high performance plastics market in China accounted for the largest market revenue share in the Asia Pacific in 2025.
North America High Performance Plastics Market Trends
The high-performance plastics market in North America is being driven by significant investments in the aerospace and defense sectors, where advanced materials are essential for lightweight, durable, and high-temperature-resistant components. With increasing defense budgets in the U.S. and Canada, there is growing demand for high-performance polymers in aircraft interiors, structural components, and missile systems.
In the U.S., the rapid expansion of the electric vehicle (EV) industry is a major driver for the high-performance plastics market, particularly as automakers seek lightweight, heat-resistant materials for battery casings, power electronics, and structural components. With the Biden administration’s strong push for EV adoption through tax incentives, infrastructure investment, and stringent emissions regulations, major automotive manufacturers and battery suppliers are increasing their reliance on advanced polymers such as PPS, LCP, and fluoropolymers. These materials not only enhance thermal management and electrical insulation but also contribute to longer battery life and vehicle range. As the U.S. continues to invest heavily in domestic battery production and sustainable transportation, demand for high-performance plastics in this sector is expected to grow substantially.
Europe High Performance Plastics Market Trends
Europe’s high-performance plastics market is being propelled by strict environmental policies and the push for sustainable materials across industries. The European Green Deal and various national sustainability mandates are compelling manufacturers to adopt advanced polymers that are not only high-performing but also recyclable or bio-based. The automotive sector, driven by the EU’s strict CO₂ emission targets and the upcoming Euro 7 standards, is increasingly shifting toward lightweight polymers to improve fuel efficiency and lower emissions.
China’s high-performance plastics market is being driven by its rapid industrial expansion and the growing need for advanced materials in high-tech manufacturing. The country’s strong presence in automotive, aerospace, and medical device production is fueling demand for high-strength, chemically resistant, and heat-resistant polymers. As China intensifies efforts to become self-sufficient in semiconductor manufacturing, investments in high-performance plastics for chip packaging, printed circuit boards, and high-frequency connectors are increasing.
Key High Performance Plastics Company Insights
The high performance plastics market is highly competitive, with several key players dominating the landscape. Major companies include BASF SE, SABIC, Evonik Industries, Victrex Plc, Kuraray Co., Ltd., Dupont, Arkema S.A., SEKISUI CHEMICAL CO., LTD., HPP GmbH, Solvay, Celanese Corporation, and Daikin Industries, Ltd. The high performance plastics market is characterized by a competitive landscape with several key players driving innovation and market growth. Major companies in this sector are investing heavily in research and development to enhance the performance, cost-effectiveness, and sustainability of their types.
Key High Performance Plastics Companies
The following key companies have been profiled for this study on the high performance plastics market.
-
All4Labels
-
CCL Industries
-
Amcor Plc
-
Avery Dennison
-
Multi-Color Corporation
-
Mondi plc
-
Huhtamaki Group
-
Neenah, Inc
-
Berry Global
-
3M
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (BASF SE, SABIC, Evonik Industries, Victrex Plc, Kuraray Co., Ltd., DuPont, Arkema S.A., SEKISUI CHEMICAL CO., LTD., Solvay, Celanese Corporation, Daikin Industries, Ltd.)
- Maintain broad portfolios across high temperature polymers, fluoropolymers, engineering plastics, and compounded solutions.
- Invest in regional application labs, technical service, and long cycle OEM qualification programs.
- Use global manufacturing and distribution networks to secure supply continuity in aerospace, EV, electronics, and medical markets.
- Strong scale, customer approvals, and deep penetration across multiple end use industries.
- Established intellectual property, product depth, and application engineering capability.
- Better feedstock access, integration, and pricing leverage versus smaller specialty suppliers.
- High capital intensity and energy exposure raise operating cost pressure.
- Long qualification cycles can slow product refresh and commercialization speed.
- Broad portfolios can dilute focus in niche fast moving technical segments.
Emerging Players (HPP GmbH)
- Focus on niche high performance processing and customized engineered plastic solutions.
- Serve selected industrial customers through flexible production and close technical co development.
- Compete through small batch responsiveness, speed, and application specific modifications.
- Faster customization for specialized technical requirements.
- Greater agility in low volume, high specification projects.
- Closer customer collaboration in design and processing support.
- Limited global scale and narrower distribution reach.
- Lower bargaining power on raw materials and logistics.
- Heavier dependence on a small set of regional and application specific accounts.
Recent Developments
-
In January 2025, Toray Industries announced the expansion of its production capacity for PICASSO spunbond, a nonwoven fabric crucial for hygiene products like diapers and sanitary items, by adding a new production line at its Indonesian subsidiary, P.T. Toray Polytech Jakarta. This investment addresses the growing demand in Asian markets, particularly Indonesia, and enhances Toray's supply capabilities in the hygiene material sector. The new line, slated to begin production in September 2026, will increase annual production capacity by approximately 18,000 tons.
-
In October 2024, 3P - Performance Plastics Products, a French industrial group specializing in high-performance plastic solutions, acquired ICM Industrie, another French industrial group specializing in precision machining and plastic and composite supply.
High Performance Plastics Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 28.8 billion
Market size value in 2026
USD 31.2 billion
Revenue forecast in 2033
USD 62.0 billion
Growth rate
CAGR of 9.3% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, region
RegioFinal scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; India; Japan; South Korea; Australia Brazil; Argentina; Saudi Arabia; UAE; South Africa
Key companies profiled
All4Labels; CCL Industries; Amcor Plc; Avery Dennison; Multi-Color Corporation; Mondi plc; Huhtamaki Group; Neenah, Inc; Berry Global; 3M
Customization scope
Free report customization (equivalent to up to 8 analysts' working days) with purchase addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global High Performance Plastics Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented global high performance plastics market report on the basis of product, application, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, Volume Kilotons, 2021 - 2033)
-
Fluoropolymers
-
Polyamides
-
Polyphenylene Sulfide (PPS)
-
Sulfone Polymers (SP)
-
Liquid Crystal Polymers (LCP)
-
Others
-
-
Application Outlook (Revenue, USD Million, Volume Kilotons, 2021 - 2033)
-
Transportation
-
Electrical & Electronics
-
Industrial
-
Medical
-
Others
-
-
Regional Outlook (Revenue, USD Million, Volume Kilotons, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
UAE
-
South Africa
-
-
Research Methodology
The high performance plastics market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each high performance plastics segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product Type
Revenue capture definition
Fluoropolymers
Revenue is captured from premium resin, compound, and finished intermediate sales into semiconductor wet processing, chemical handling, seals, wire and cable, and harsh environment industrial systems.
Polyamides
Revenue is captured from heat resistant and reinforced polyamide sales into transportation parts, electrical housings, industrial wear components, and selected medical device subassemblies.
Polyphenylene Sulfide (PPS)
Revenue is captured from flame resistant PPS sold for connectors, pumps, valves, filtration parts, and EV powertrain or electronics applications requiring dimensional stability.
Sulfone Polymers (SP)
Revenue is captured from transparent, hydrolysis resistant sulfone resin sales into medical devices, water systems, electrical insulation, and precision industrial components.
Liquid Crystal Polymers (LCP)
Revenue is captured from resin and compound sales into miniaturized connectors, antennas, high frequency circuits, and thin wall electronics that require low dielectric loss.
Others
Revenue is captured from high performance grades not separately tracked, including PEI, PEEK, polyimides, PAI, and custom blends sold into specialty projects.
Segment - Application
Revenue capture definition
Transportation
Revenue is captured from material sales into EV battery systems, aerospace interiors, under the hood parts, structural assemblies, connectors, and lightweight mobility components.
Electrical & Electronics
Revenue is captured from polymers used in semiconductors, consumer devices, industrial electronics, connectors, insulation systems, and high frequency or high heat assemblies.
Industrial
Revenue is captured from engineered plastics sold into pumps, valves, chemical processing, filtration, machinery, and high wear or corrosive operating environments.
Medical
Revenue is captured from resin and compound sales into surgical tools, diagnostic parts, drug delivery systems, and sterilization resistant medical components.
Others
Revenue is captured from specialty uses outside the core end uses, including niche consumer, defense, and precision equipment applications with lower volume but higher value content.
Estimation Model
Layer Name
Key Question
Description
Demand Screening
Where does demand originate?
End-use shipment and equipment build rates establish baseline polymer pull, because design-in volumes drive first-pass revenue capture.
Product Mix Layer
Which products create value?
Segment revenue splits by resin family, since fluoropolymers and LCP command higher realization than commodity-adjacent grades.
Regional Weighting
Which regions dominate demand?
Manufacturing concentration in Asia Pacific, North America, and Europe shapes conversion, pricing, and approval intensity.
Commercial Validation
How are estimates verified?
Distributor channels, direct contracts, and customer approvals calibrate price, volume, and timing assumptions against trade data.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Cross-segmentation by product and application
Built a cross-segment view linking fluoropolymers, PPS, LCP, and sulfone polymers with transportation, electronics, industrial, and medical demand pools. The analysis highlighted the highest value combinations and the most qualified end use channels.
Improved visibility into premium revenue pools and commercialization priorities. Supported portfolio positioning, target account selection, and application development planning.
Regional demand and supply mapping
Added regional demand mapping across Asia Pacific, North America, and Europe with attention to electronics manufacturing, EV adoption, aerospace activity, and technical supply concentration. The output emphasized where design in activity is most durable.
Helped identify priority regions for sales, technical service, and manufacturing alignment. Strengthened regional investment and account coverage decisions.
Competitive benchmarking and company ranking
Delivered a competitive benchmark separating mature multinational suppliers from smaller niche players based on scale, integration, technical depth, and customer reach. The assessment also highlighted operating strategy, edge, and weakness patterns.
Clarified market structure and competitive gaps. Supported positioning analysis, partner screening, and supplier comparison.
Frequently Asked Questions About This Report
The Asia Pacific High Performance Plastics market accounted for the largest share of 40.5% market size in 2025.
India was the leading High Performance Plastics market and is expected to grow at a compound annual growth rate of 12.0%.
Based on application, the transportation segment accounted for the largest share of 44.1% market size in 2025.
The liquid crystal polymers (LCP) segment, based on product type, is expected to grow at a CAGR of 11.6% for the forecast period.
The high performance plastics market was valued at USD 28.8 billion in the year 2025 and is estimated at USD 31.2 billion in 2026.
The high performance plastics market is expected to grow at a compound annual growth rate of 9.3% from 2026 to 2033 to reach around USD 62.0 billion by 2033.
The fluoropolymers high performance plastics industry led the high performance plastics market in 2025 with a 47.3% share.
Some key players operating in the high performance plastics market include BASF SE, SABIC, Evonik Industries, Victrex Plc, Kuraray Co., Ltd., Dupont, Arkema S.A., SEKISUI CHEMICAL CO., LTD., HPP GmbH, Solvay, Celanese Corporation, and Daikin Industries, Ltd.
The shift toward EVs is driving the need for high-performance plastics in battery casings, lightweight components, and thermal management systems, helping improve efficiency and range.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


