
- Home
- »
- Next Generation Technologies
- »
-
Home Insurance Market Size, Share & Trends Report, 2033GVR Report cover

Home Insurance Market (2026 - 2033)
Size, Share & Trends Analysis Report By Coverage (Comprehensive, Dwelling), By Distribution Channel (Tied Agents & Branches, Brokers), By End-use (Landlords, Tenants), By Region (North America, Europe, MEA), And Segment Forecasts
Market Size, 2025
$284.9BMarket Estimate, 2026
$306.9BMarket Forecast, 2033
$563.2BCAGR, 2026–2033
9.1%Home Insurance Market Summary
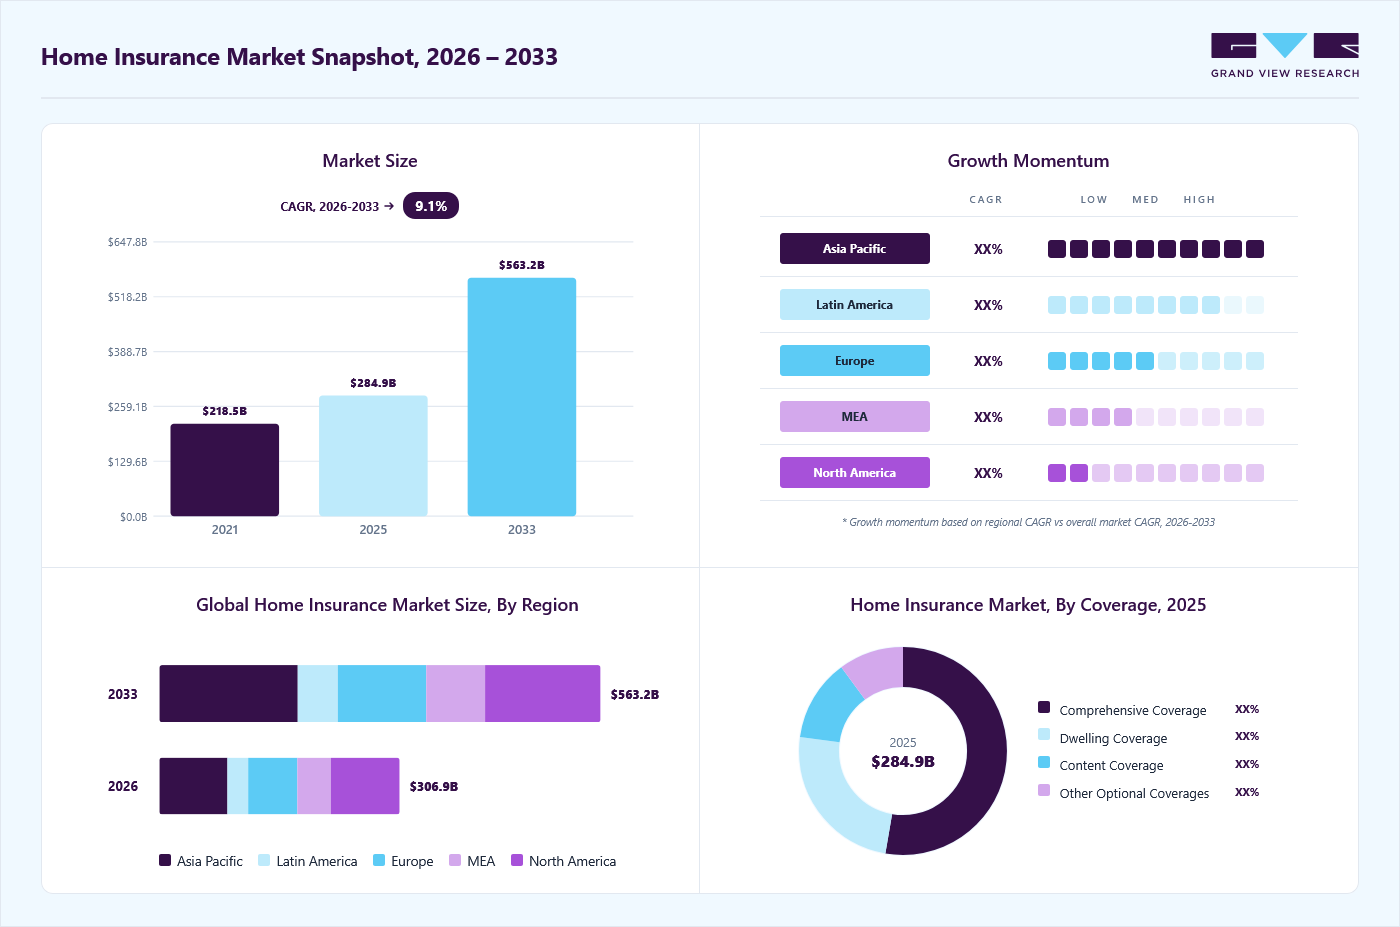
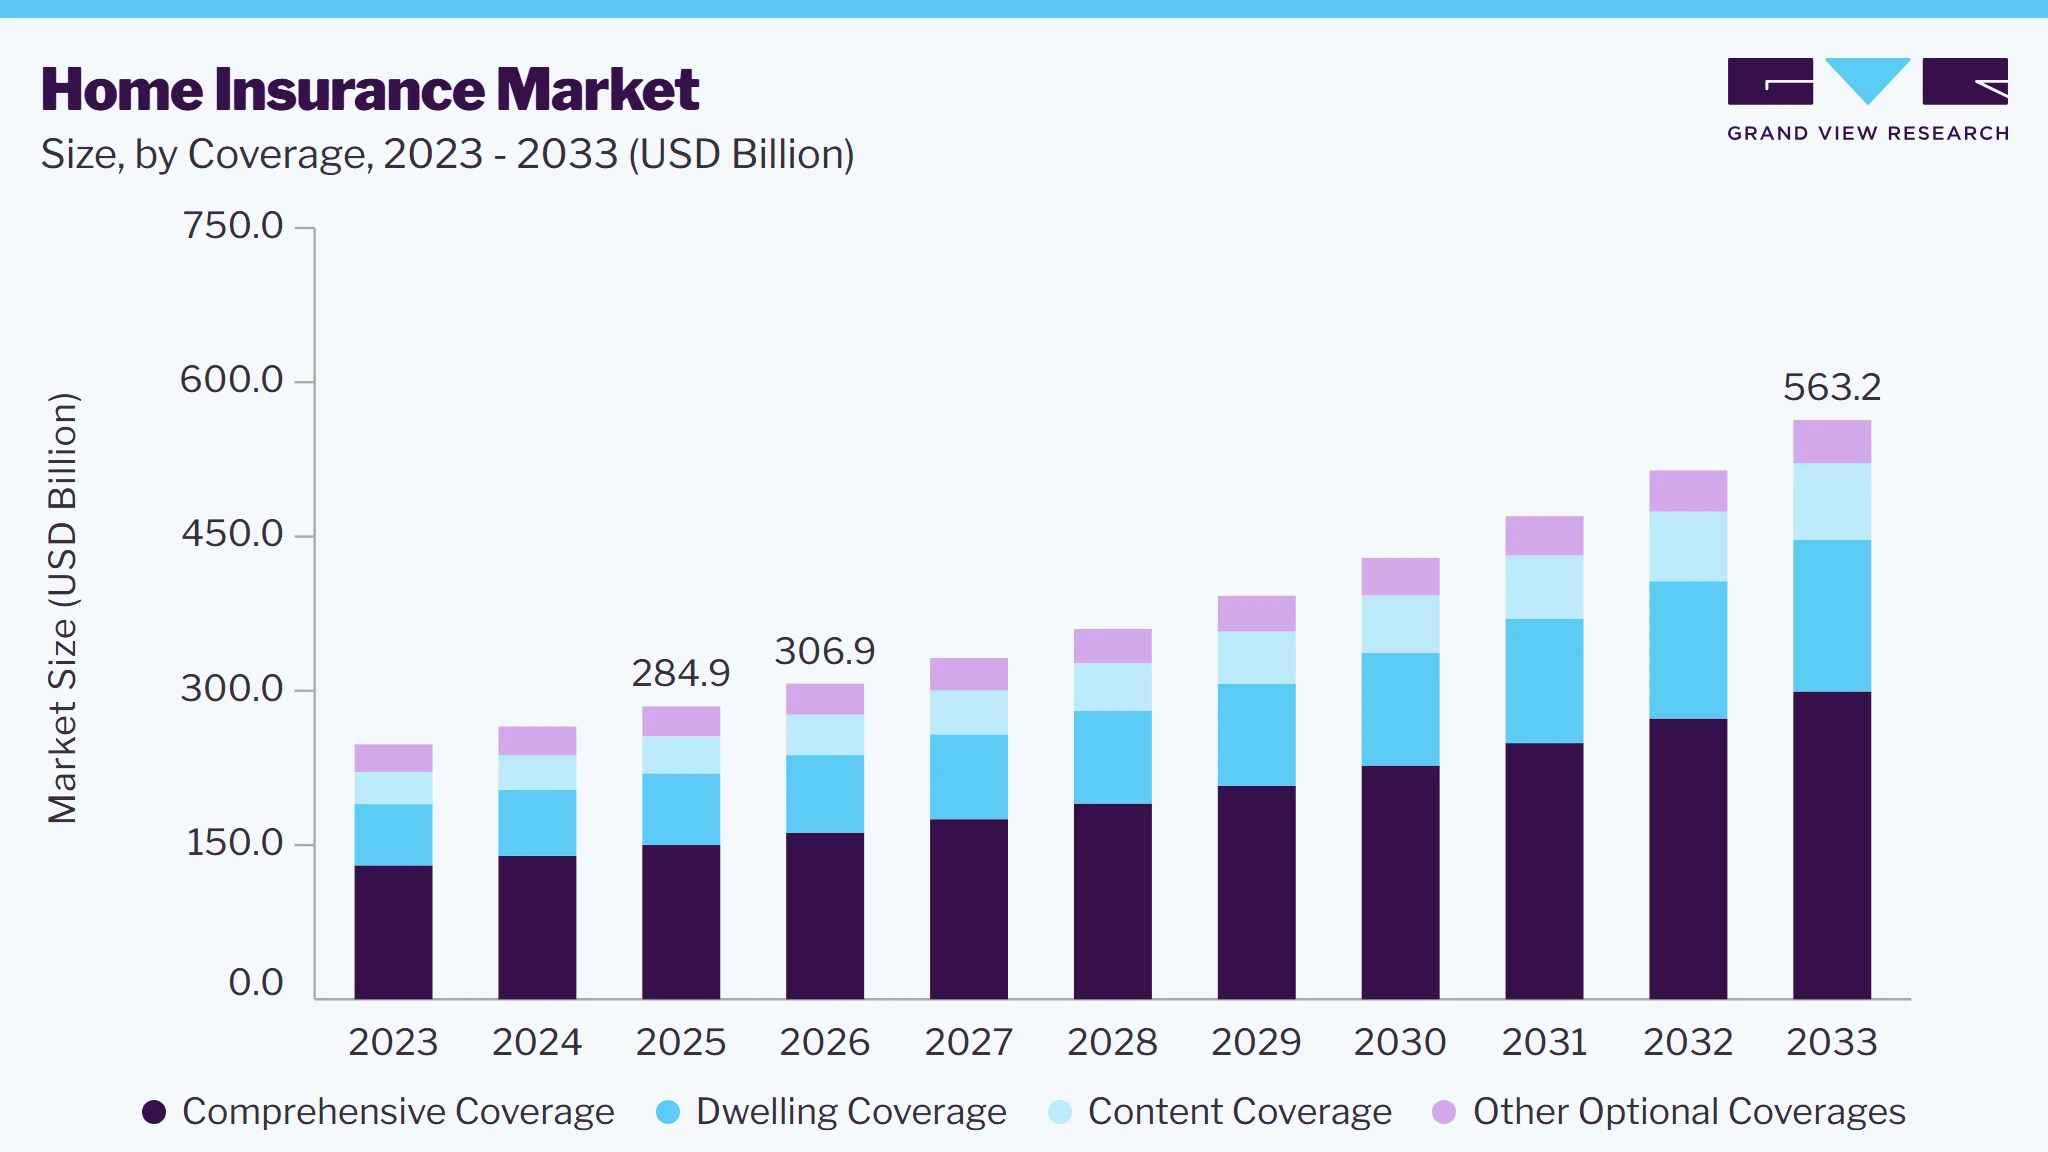
The global home insurance market size was valued at USD 284.9 billion in 2025 and is projected to grow from USD 306.9 billion in 2026 to USD 563.2 billion by 2033, at a CAGR of 9.1% from 2026 to 2033. The North American market accounted for 29.0% of revenue in 2025. Home insurance provides financial protection to an individual against damage and losses to their residence.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By coverage: Comprehensive coverage segment led the market, accounting for 52.6% of global revenue in 2025.
- By distribution channel: Tied agents segment led the market, accounting for 48.2% of global revenue in 2025.
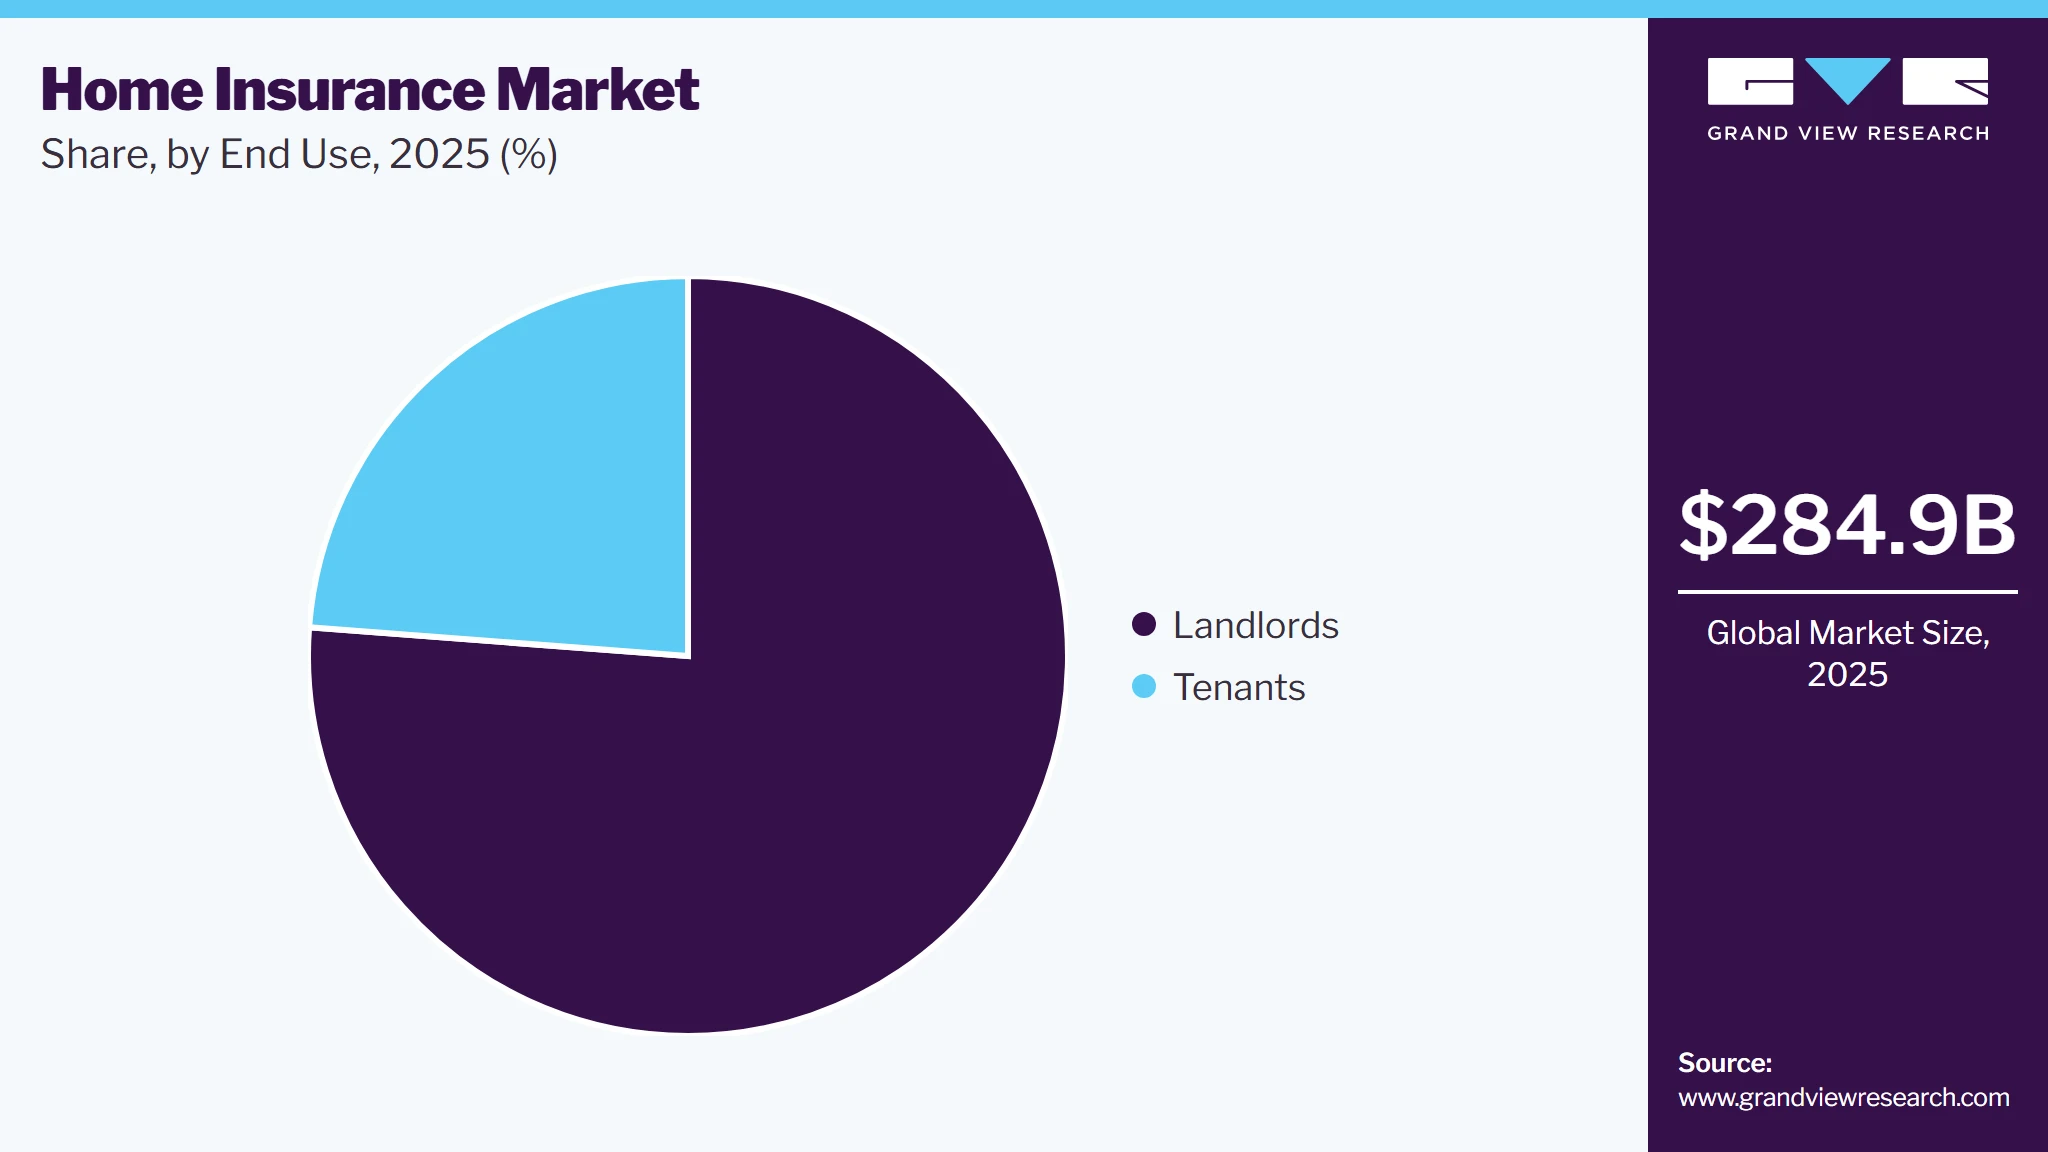
- By end use: Landlords segment led the market, accounting for 76.2% of global revenue in 2025.
Regional Highlights
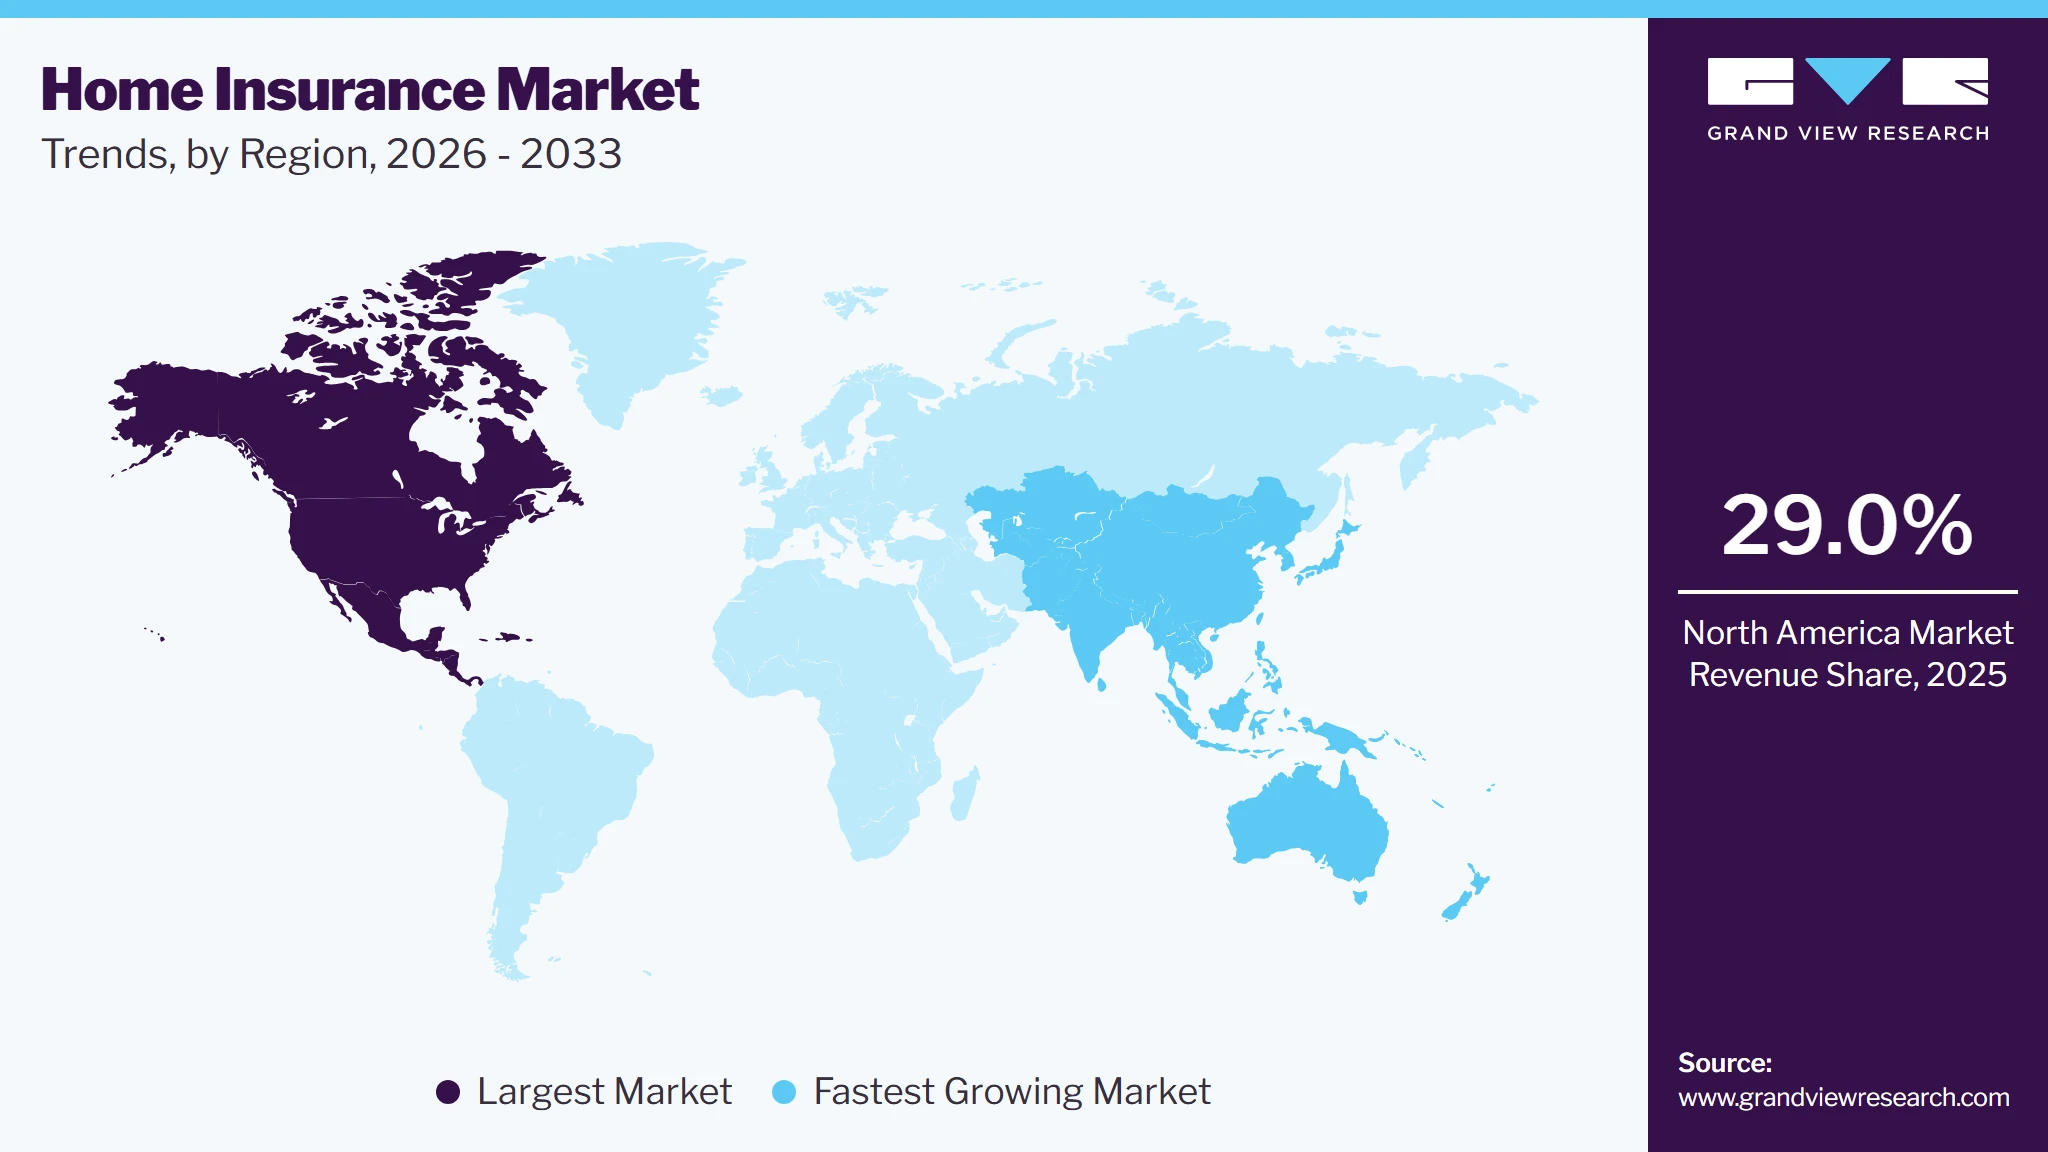
- Largest regional market: North America (29.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 284.9 Billion
- Estimated market size in 2026: USD 306.9 Billion
- Projected market size by 2033: USD 563.2 Billion
- CAGR (2026-2033): 9.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Home insurance is also known as household insurance, private property insurance, or homeowner’s insurance. Home insurance covers not only damages to the property of individuals but also the legal responsibility or liability for any property damage and injuries caused by policyholders.The increasing demand for customized home insurance products is expected to drive market growth. Nowadays, customers are focusing on adopting insurance products tailored to their specific preferences and needs. As a result, insurance providers are also responding by providing more flexibility and expanding coverage options. Various factors, such as the rising need for comprehensive insurance coverage and the increasing awareness of the risks and challenges of home ownership, are expected to drive the adoption of home insurance products over the forecast period.
 To learn more about this report, Download Free Sample Report
The market is witnessing an increase in the adoption of technologies, such as big data, blockchain, data analytics, Artificial Intelligence (AI), Application Programming Interface (API), and geolocation, among others. These technologies are providing innovative opportunities for home insurance providers in the market. Furthermore, by leveraging these technological developments, home insurance companies will be able to enhance the distribution platform’s productivity. The technology-integrated insurance products will enable businesses to manage renters’ insurance and additional living expenses. In addition, digital transformation enables home insurance businesses to create personalized customer experiences.
Another key factor driving market growth is the increasing urbanization and the expansion of residential real estate. As more people move to urban areas and invest in new homes, the demand for home insurance rises accordingly. This trend is particularly notable in developing regions where urban development is rapidly progressing. The surge in home ownership, coupled with the growing need for financial protection, is significantly boosting the market.
On the other hand, a significant factor restraining market growth is the rising incidence of fraudulent claims. This issue increases insurance companies' overall costs, which, in turn, leads to higher premiums for policyholders. The fear of fraud can also lead insurers to implement stricter underwriting processes, making it more difficult for consumers to obtain coverage. These challenges not only increase costs but also reduce accessibility, thereby limiting the market’s growth potential.
Market Dynamics
The market continues to expand due to rising homeownership rates, rising property values, and growing awareness of the need for financial protection against property-related risks. Home insurance provides coverage for damage caused by natural disasters, fire, theft, and vandalism, as well as liability claims, helping homeowners and tenants mitigate financial losses and safeguard valuable assets. Increasing frequency and severity of climate-related events, including floods, hurricanes, wildfires, and storms, are driving demand for comprehensive insurance coverage across residential properties.
The increasing demand for customized, flexible home insurance products is significantly driving the market by enabling insurers to better align coverage offerings with individual customer needs. Policyholders are increasingly seeking tailored insurance solutions that provide specific protection for dwelling structures, contents, liability, and additional living expenses tailored to their lifestyle and risk exposure. In response, insurers are enhancing product flexibility by offering modular policies, add-on covers, and usage-based insurance options. The rising awareness of financial risks associated with home ownership, coupled with increasing consumer expectations for personalization, is further accelerating the adoption of customized home insurance solutions across both developed and emerging markets.
A key restraint on the market is the rising incidence of fraudulent claims and increasing claims-related losses. Insurance fraud leads to significant financial burdens on insurers, increasing overall operational costs and prompting higher premium rates for policyholders. In response, insurers are implementing stricter underwriting standards, enhanced verification processes, and advanced fraud detection technologies, which can make policy access more complex for consumers. In addition, the growing frequency of natural catastrophes such as floods, storms, and wildfires is increasing claim payouts, further impacting insurer profitability.
The expansion of InsurTech solutions and the integration of smart home technologies present significant growth opportunities for the market. The increasing adoption of connected devices, such as smart sensors, security systems, water leak detectors, and fire monitoring systems, is enabling insurers to shift toward proactive risk-prevention models. Insurers are leveraging IoT-enabled data to offer usage-based pricing, real-time risk monitoring, and personalized premium structures. In addition, the rise of digital insurance platforms and ecosystem partnerships with technology providers is enhancing distribution efficiency and customer engagement.
Market Concentration & Characteristics
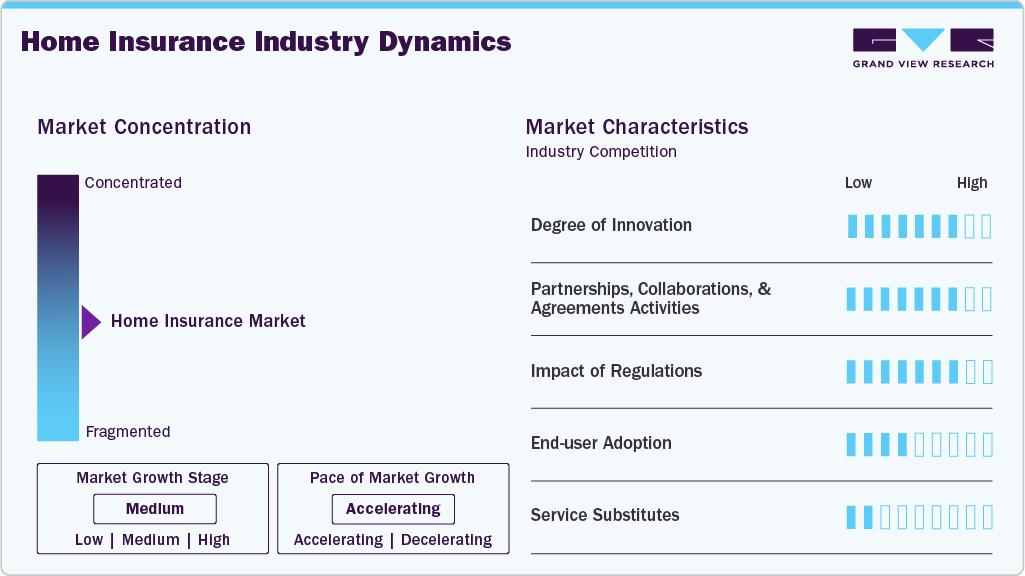
The home insurance industry is moderately consolidated, with several large global insurers, regional insurance providers, and specialized property & casualty (P&C) companies accounting for a significant share. Leading players compete based on underwriting expertise, claims management efficiency, product portfolio breadth, pricing competitiveness, digital distribution capabilities, and brand trust. Major insurers dominate the market through strong financial strength, diversified risk portfolios, extensive agent and broker networks, and advanced digital platforms that enable scalable policy issuance and claims processing. However, regional insurers and niche providers continue to maintain a strong presence, particularly in domestic homeowner segments, tenant insurance, and specialized coverage offerings tailored to local regulatory and risk environments.
 To learn more about this report, Download Free Sample Report
Strategic collaborations, bancassurance partnerships, InsurTech alliances, mergers and acquisitions, and digital platform expansions are commonly observed across the industry as companies aim to strengthen market penetration and improve customer acquisition efficiency. Leading players are increasingly integrating advanced technologies, such as AI-based underwriting, predictive analytics for catastrophe risk modeling, automated claims processing systems, IoT-enabled smart home risk monitoring, and digital customer engagement platforms, to enhance operational efficiency and improve loss ratios.
Analyst Perspective
The home insurance industry continues to benefit from rising homeownership rates, increasing property values, and greater awareness of financial protection against property damage, theft, liability claims, and natural disasters. However, rising catastrophe losses, evolving regulatory requirements, inflation-driven increases in repair and reconstruction costs, and affordability concerns are influencing the pace and direction of market growth.
Coverage Insights
The comprehensive coverage segment led the market, accounting for 52.6% of global revenue in 2025. Comprehensive insurance products enable policyholders to restore or replace their home belongings if they are damaged in an accident or stolen. Moreover, comprehensive insurance coverage includes protection against natural disasters, vandalism, and fire, among others.
The dwelling coverage segment is expected to register the fastest growth from 2026 to 2033. Dwelling coverage is experiencing robust growth, driven by increased investment in residential real estate and rising awareness of the importance of safeguarding home structures. This segment benefits from higher construction costs and a growing number of homeowners seeking comprehensive protection against various perils, ensuring the sustained expansion of dwelling market coverage.
Distribution Channel Insights
The tied agents & branches segment accounted for the largest market revenue share of 48.2% in 2025. Tied agents and branches have established customer relationships and are often seen as a trusted source of information and advice. This allows them to effectively market and sell home insurance policies to customers, increasing their market share. In addition, tied agents and branches have the backing of a large insurance company, which provides them with resources and support to market and sell home insurance policies effectively. This helps them to remain competitive in the market, thus driving the segment’s growth.
The brokers segment is expected to grow rapidly from 2026 to 2033. The broker segment in the market is expanding due to its pivotal role in providing personalized advice and tailored insurance solutions. Brokers' expertise in navigating complex insurance products and their ability to offer customized plans are increasingly valued by consumers, leading to a significant rise in demand for broker-mediated insurance services.
End Use Insights
The landlords segment accounted for the largest market revenue share of 76.2% in 2025. The growing population, along with rising migration to cities, has led to a surge in rental property activity. This surge in rental property activity has prompted landlords to opt for home insurance to secure their assets. Moreover, home insurance protects landowners against the financial losses resulting from injuries, accidents, natural disasters, and other liability issues. The aforementioned factors are contributing to segment growth.
 To learn more about this report, Download Free Sample Report
The tenants segment is expected to grow significantly from 2026 to 2033. The tenant segment is witnessing considerable growth as more individuals opt for rental properties, particularly in urban areas. The growing awareness of the need for renters' insurance to protect personal belongings and provide liability coverage is driving demand in this segment, contributing to overall market expansion.
Regional Insights
North America dominated the global home insurance market with the largest revenue share of 29.0% in 2025. The market is growing steadily due to rising home-ownership rates and increased natural disaster activity. The adoption of advanced technologies by insurers to streamline operations and enhance customer experience further propels market growth, positioning North America as a significant contributor to the global home insurance industry.
 To learn more about this report, Download Free Sample Report
U.S. Home Insurance Market Trends
The home insurance market in the U.S. is expected to grow significantly from 2026 to 2033. The market is expanding robustly, driven by high home-ownership rates and frequent natural disasters that necessitate comprehensive coverage. Technological advancements in insurance products and distribution channels are enhancing market efficiency and customer satisfaction, driving market growth.
Europe Home Insurance Market Trends
The home insurance market in Europe is poised for significant growth from 2026 to 2033. The regional market is growing steadily, driven by stringent regulatory frameworks and heightened awareness of insurance benefits among homeowners. The increasing adoption of smart home technologies and a focus on sustainability are further supporting market growth, making Europe a key region in the global market.
The UK home insurance market is expected to experience significant growth in the coming years, driven by rising awareness regarding property protection, increasing frequency of climate-related events such as floods and storms, and strong insurance penetration across residential properties.
Asia Pacific Home Insurance Market Trends
The home insurance market in the Asia Pacific is poised for fastest growth from 2026 to 2033, driven by rapid urbanization, rising homeownership rates, increasing disposable incomes, and growing awareness regarding financial protection against natural disasters such as floods, typhoons, earthquakes, and cyclones. Governments across countries such as China, India, Japan, and Australia are also supporting residential infrastructure development and promoting financial inclusion, which is encouraging greater adoption of home insurance products.
China home insurance market held a substantial market share in 2025. The market is driven by rapid urbanization, rising homeownership rates, and increasing awareness regarding property protection against natural disasters such as floods, earthquakes, and typhoons.
The home insurance market in India held a substantial market share in 2025. India’s home insurance market is experiencing steady growth, driven by rising residential construction activity, higher disposable incomes, and greater awareness of financial protection against theft, fire, floods, and other property-related risks.
Key Home Insurance Company Insights
Some of the major players in the market include Allianz, AXA Group, Nationwide Mutual Insurance Company, American International Group, Inc., Allstate Insurance Company, Liberty Mutual Insurance Company, and Chubb, among others. These companies are at the forefront of driving innovation in the home insurance industry through strategic initiatives such as digital transformation, partnerships, acquisitions, and investments in advanced risk assessment technologies. By expanding their product portfolios and enhancing customer engagement through online platforms and mobile applications, they aim to meet the growing demand for comprehensive, customized home protection solutions. Their focus on AI-driven underwriting, smart home integration, climate risk analysis, and faster claims processing is playing a crucial role in improving customer experience and strengthening market competitiveness amid rising property-related risks and evolving consumer expectations.
-
Allianz has emerged as a prominent player in the market, offering a broad portfolio of property protection solutions tailored for homeowners and renters across multiple regions. The company continues to invest heavily in digital insurance platforms, AI-driven underwriting, and advanced risk analytics to enhance customer experience and streamline claims management. Allianz is also focusing on expanding its smart home insurance offerings and climate risk protection capabilities to address the increasing frequency of natural disasters and property-related losses.
-
AXA Group is leveraging its extensive insurance expertise and global distribution network to drive market growth. The company offers comprehensive home protection solutions covering property damage, theft, liability, and natural catastrophe risks for residential customers worldwide. AXA continues to invest in digital transformation initiatives, strategic partnerships, and personalized insurance services to improve policy accessibility and customer engagement. Its focus on data analytics, automation, and preventive risk management solutions has further enhanced operational efficiency and enabled the company to deliver more customized and responsive home insurance offerings.
Key Home Insurance Companies
The following key companies have been profiled for this study on the home insurance market.
-
Zurich
-
Chubb
-
American International Group, Inc.
-
Liberty Mutual Insurance
-
Admiral
-
State Farm Mutual Automobile Insurance Company
-
Allstate Insurance Company
-
Allianz
-
PICC
-
Nationwide
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Allianz; AXA Group; Chubb; Allstate Insurance Company; Liberty Mutual Insurance Company; State Farm Mutual Automobile Insurance Company
- Mature players focus on offering comprehensive home insurance products covering dwelling, contents, liability, and natural catastrophe risks, supported by strong underwriting capabilities.
- They emphasize digital transformation through AI-based underwriting, automated claims processing, predictive catastrophe modeling, and smart home integration to proactively prevent risk.
- Strong global or national brand presence, high customer trust, and large policyholder bases.
- Advanced risk management capabilities supported by deep actuarial expertise and access to large-scale claims data.
- High operational complexity due to large legacy systems and extensive product portfolios.
- Exposure to rising catastrophe losses, inflationary repair costs, and increasing claims severity.
Emerging Players: Admiral Group; PICC Property and Casualty Company Limited
- Emerging players focus on cost-competitive home insurance offerings, simplified policy structures, and strong digital-first distribution models.
- They emphasize regional expansion, partnerships with aggregators, and online direct-to-customer platforms to increase market penetration.
- Greater agility in product innovation and pricing adjustments compared to large incumbents.
- Strong regional presence and better understanding of local regulatory and risk environments.
- Limited capital strength compared to global insurers, restricting large catastrophe exposure.
- Smaller scale of operations leading to weaker bargaining power with reinsurers and distribution partners.
Recent Developments
-
In May 2026, Asda and Allianz announced an expanded strategic partnership to launch home and motor insurance products for Asda customers across the UK. Under the partnership, Asda will manage marketing and customer engagement, while Allianz UK will handle underwriting, administration, and claims management through online platforms, contact centers, and price comparison websites. The initiative strengthens Asda’s growing financial services portfolio and introduces preferential insurance rates and savings for Asda Rewards members purchasing policies directly through Asda. The collaboration also reflects Allianz UK’s strategy to expand its retail insurance presence and enhance customer access to digital, value-driven home insurance solutions.
-
In May 2026, Porch Group announced the expansion of its homeowners insurance platform with the launch of Homeowners of America (HOA) operations in Michigan, marking its entry into the 22nd U.S. state. This expansion is part of Porch Group’s broader strategy to scale its insurance footprint, strengthen distribution through independent agents, and drive long-term premium growth and cash flow. The company continues to leverage data-driven underwriting capabilities and a vertically integrated home services ecosystem to improve risk selection and policyholder engagement. By combining disciplined underwriting with agent-focused distribution and targeted geographic expansion, Porch Group aims to enhance its position in the competitive U.S. homeowners insurance market.
Home Insurance Market Report Scope
Report Attribute
Details
Market size in 2025
USD 284.9 billion
Estimated market size in 2026
USD 306.9 billion
Projected market size by 2033
USD 563.2 billion
Growth rate
CAGR of 9.1% from 2026 to 2033
Actual data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company market share, competitive landscape, growth factors, and trends
Segments covered
Coverage, distribution channel, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; China; India; Japan; South Korea; Australia; Brazil; KSA; UAE; South Africa
Key companies profiled
Zurich; Chubb; American International Group, Inc.; Liberty Mutual Insurance; Admiral; State Farm Mutual Automobile Insurance Company; Allstate Insurance Company; Allianz; PICC; Nationwide
Customization scope
Free report customization (equivalent to up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Home Insurance Market Report Segmentation
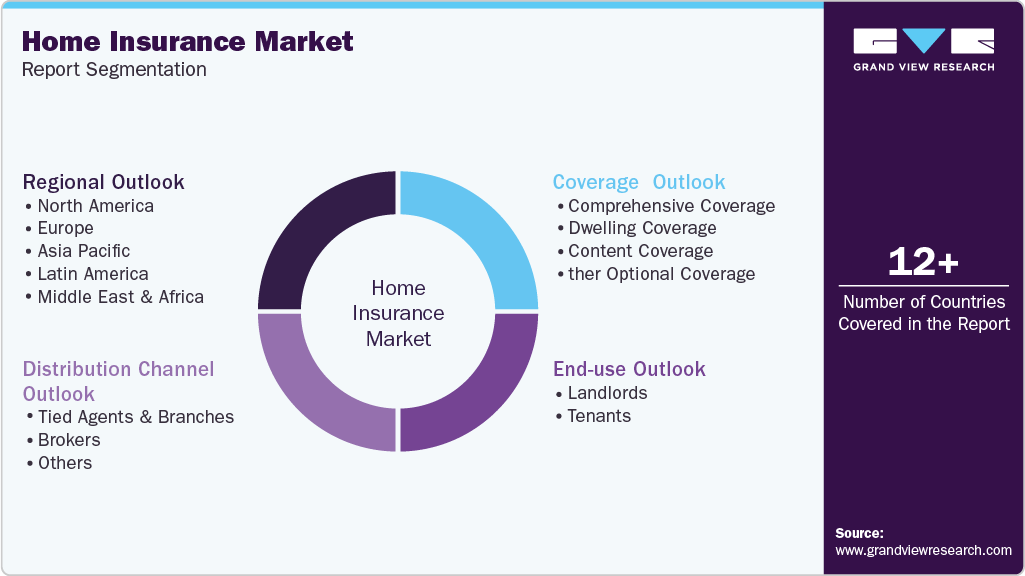
The report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the home insurance market based on coverage, distribution channel, end use, and region.
 To learn more about this report, Download Free Sample Report
-
Coverage Outlook (Revenue, USD Billion, 2021 - 2033)
-
Comprehensive Coverage
-
Dwelling Coverage
-
Content Coverage
-
Other Optional Coverage
-
-
Distribution Channel Outlook (Revenue, USD Billion, 2021 - 2033)
-
Tied Agents & Branches
-
Brokers
-
Others
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Landlords
-
Tenants
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East & Africa (MEA)
-
UAE
-
KSA
-
South Africa
-
-
Research Methodology
Segment Definition
Segment - Type
Revenue capture definition
Comprehensive Coverage
This segment includes home insurance policies that provide broad protection against a wide range of covered risks, including damage to the dwelling and personal belongings, liability claims, and additional living expenses resulting from events such as fire, theft, storms, vandalism, and certain natural disasters.
Dwelling Coverage
This segment includes insurance coverage specifically designed to protect the physical structure of a home, including walls, roofs, floors, attached garages, and built-in fixtures, against losses resulting from covered perils such as fire, windstorms, hail, and other property-related damages.
Content Coverage
This segment includes insurance policies or policy components that cover personal belongings and household possessions within the insured property, such as furniture, electronics, appliances, clothing, and valuables, against risks including theft, fire, and accidental damage as specified in the policy.
Other Optional Coverages
This segment includes supplementary home insurance coverages that can be added to standard policies, such as flood, earthquake, identity theft protection, sewer backup, and home business coverage.
Segment - Distribution Channel
Revenue capture definition
Tied Agents & Branches
This segment includes home insurance policies distributed through exclusive or captive agents, insurer-owned branches, and company representatives who primarily sell products from a single insurer.
Brokers
This segment includes home insurance products sold through independent insurance brokers and intermediary firms that represent multiple insurance carriers and help customers compare policies, coverage options, and premium rates.
Other Distribution Channels
This segment includes home insurance policies distributed through direct-to-consumer digital platforms, insurer websites, mobile applications, and bancassurance channels, among others.
Segment - End Use
Revenue capture definition
Tenants
This segment includes renters and leaseholders who purchase insurance coverage to protect personal belongings, liability exposures, and additional living expenses arising from covered losses, while the building structure itself is generally insured by the property owner.
Landlords
This segment includes residential property owners who purchase insurance policies to protect owned homes, rental properties, and associated structures against risks such as property damage, liability claims, loss of rental income, and other covered events affecting the insured property.
Estimation Model
Layer
Key Question
Purpose
Residential Property Opportunity Layer
Who represents the potential customer base?
Identify the total number of residential properties and households that could benefit from home insurance coverage, including homeowners, landlords, and tenants across target geographies.
Insurable Housing Stock Layer
Which properties can be insured?
Determine the proportion of residential properties that satisfy insurance eligibility criteria.
Insurance Penetration Layer
Who actively purchases home insurance?
Estimate the percentage of eligible homeowners, landlords, and tenants that maintain active insurance policies, supported by regulatory requirements.
Monetisation Layer
How much revenue is generated?
Calculate total market revenue based on policy adoption rates, average annual premiums, coverage types.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Home Insurance Market Opportunity Assessment
Country/region-wise home insurance industry sizing and growth forecasts across North America, Europe, Asia Pacific, and the Rest of the World
Assessment of regulatory frameworks impacting markets, including underwriting regulations, catastrophe risk guidelines, mortgage-linked insurance requirements, and consumer protection laws
Identified region-specific growth opportunities driven by rising homeownership, urbanization, climate-related risks, and increasing insurance penetration.
Supported insurer expansion strategies and product portfolio planning.
Competitive Benchmarking and Strategic Positioning in the Home Insurance Market
Benchmarking of key competitors across products, distribution channels, digital capabilities, underwriting practices, and innovation strategies.
Comparative assessment of market share, risk management capabilities, and claims processing efficiency.
Identified competitive white spaces in digital insurance adoption, smart home integration, and personalized insurance offerings.
Supported strategic positioning, partnership development, and InsurTech collaboration strategies. Enabled data-driven competitive strategy formulation.
Competitive Benchmarking and Strategic Positioning in the Home Insurance Market
Benchmarking of key insurers across pricing strategies, product portfolios, distribution models, and technological innovation.
Comparative assessment of market share, capabilities, and strategies
Identified market gaps across digital distribution, embedded insurance models, and AI-driven underwriting.
Supported strategic expansion, mergers & acquisitions planning, and ecosystem partnership development.
Frequently Asked Questions About This Report
The global home insurance market size was estimated at USD 284.9 billion in 2025 and is expected to reach USD 306.9 billion in 2026.
The global home insurance market is expected to grow at a compound annual growth rate of 9.1% from 2026 to 2033 to reach USD 563.2 billion by 2033.
Key factors that are driving the market growth include global growth in households and an increase in the number of accidents and natural disasters.
North America dominated the home insurance market with a share of 29.0% in 2025. The North American home insurance market is growing steadily due to rising home ownership rates and increased natural disaster occurrences.
Some key players operating in the home insurance market include Zurich, Chubb, American International Group, Inc., Liberty Mutual Insurance, Admiral, State Farm Mutual Automobile Insurance Company, Allstate Insurance Company, Allianz, PICC, and Nationwide.
Based on coverage, the comprehensive coverage segment led the market and accounted for 52.6% of the global revenue in 2025.
The tied agents & branches segment accounted for the largest market revenue share of 48.2% in 2025.
The landlords segment accounted for the largest market revenue share of 76.2% in 2025. The increasing population, along with the rise in migration in cities, has led to a surge in rental property activities, thereby contributing to the growth of the market.
The U.S. home insurance market dominated the market with a share of 85.2% in 2025.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


