
- Home
- »
- Pharmaceuticals
- »
-
Human Papillomavirus Vaccines Market Report, 2026-2033GVR Report cover

Human Papillomavirus Vaccines Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Bivalent, Quadrivalent, Nonavalent), By Disease (Cervical Cancer, Anal Cancer), By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$9.2BMarket Estimate, 2026
$10.0BMarket Forecast, 2033
$17.0BCAGR, 2026–2033
7.8%Human Papillomavirus Vaccines Market Summary
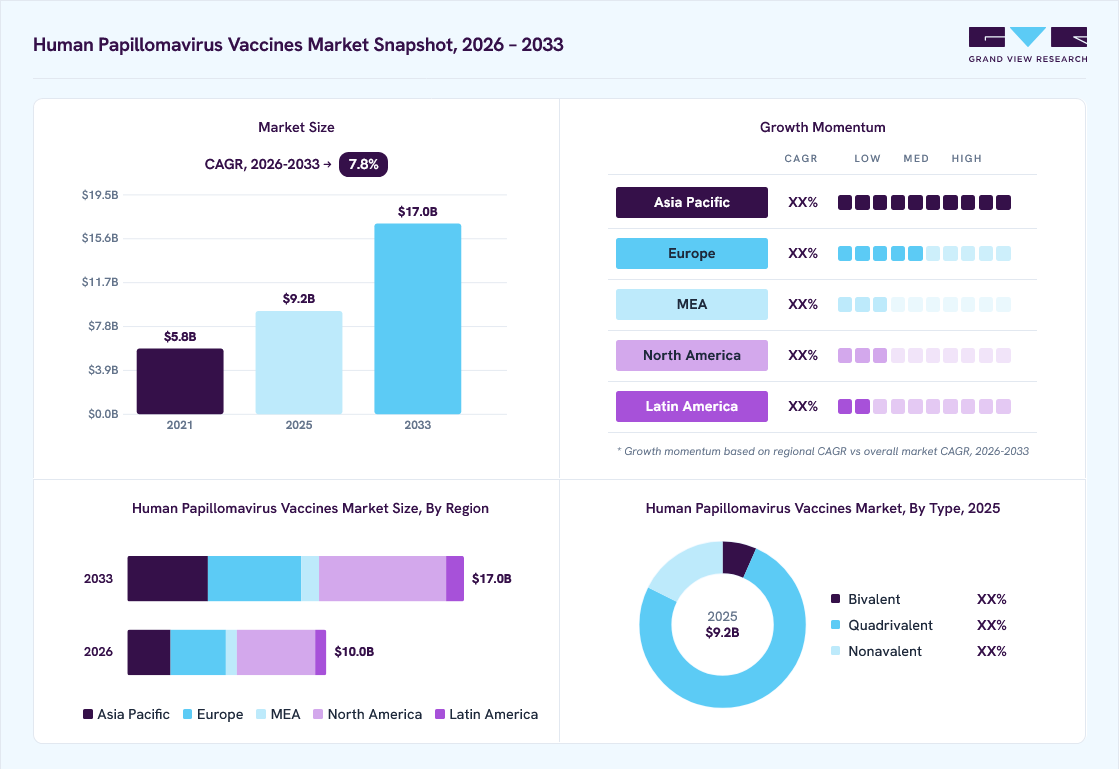
The global human papillomavirus vaccines market size was valued at USD 9.2 billion in 2025 and is projected to grow from USD 10.0 billion in 2026 to USD 17.0 billion by 2033, at a CAGR of 7.8% from 2026 to 2033. The market in North America dominated with a revenue share of 39.6% in 2025. The rising global incidence of HPV-related infections and cancers is a major force driving the growth of the market.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Quadrivalent segment held the largest market share of 75.7% in 2025.
- By disease: Cervical cancer segment held the largest market share of 63.8% in 2025.
- By distribution channel: Hospitals and retail pharmacies segment held the largest market share of 53.9% in 2025.
Regional Highlights
- Largest regional market: North America (39.6% revenue share, 2025)
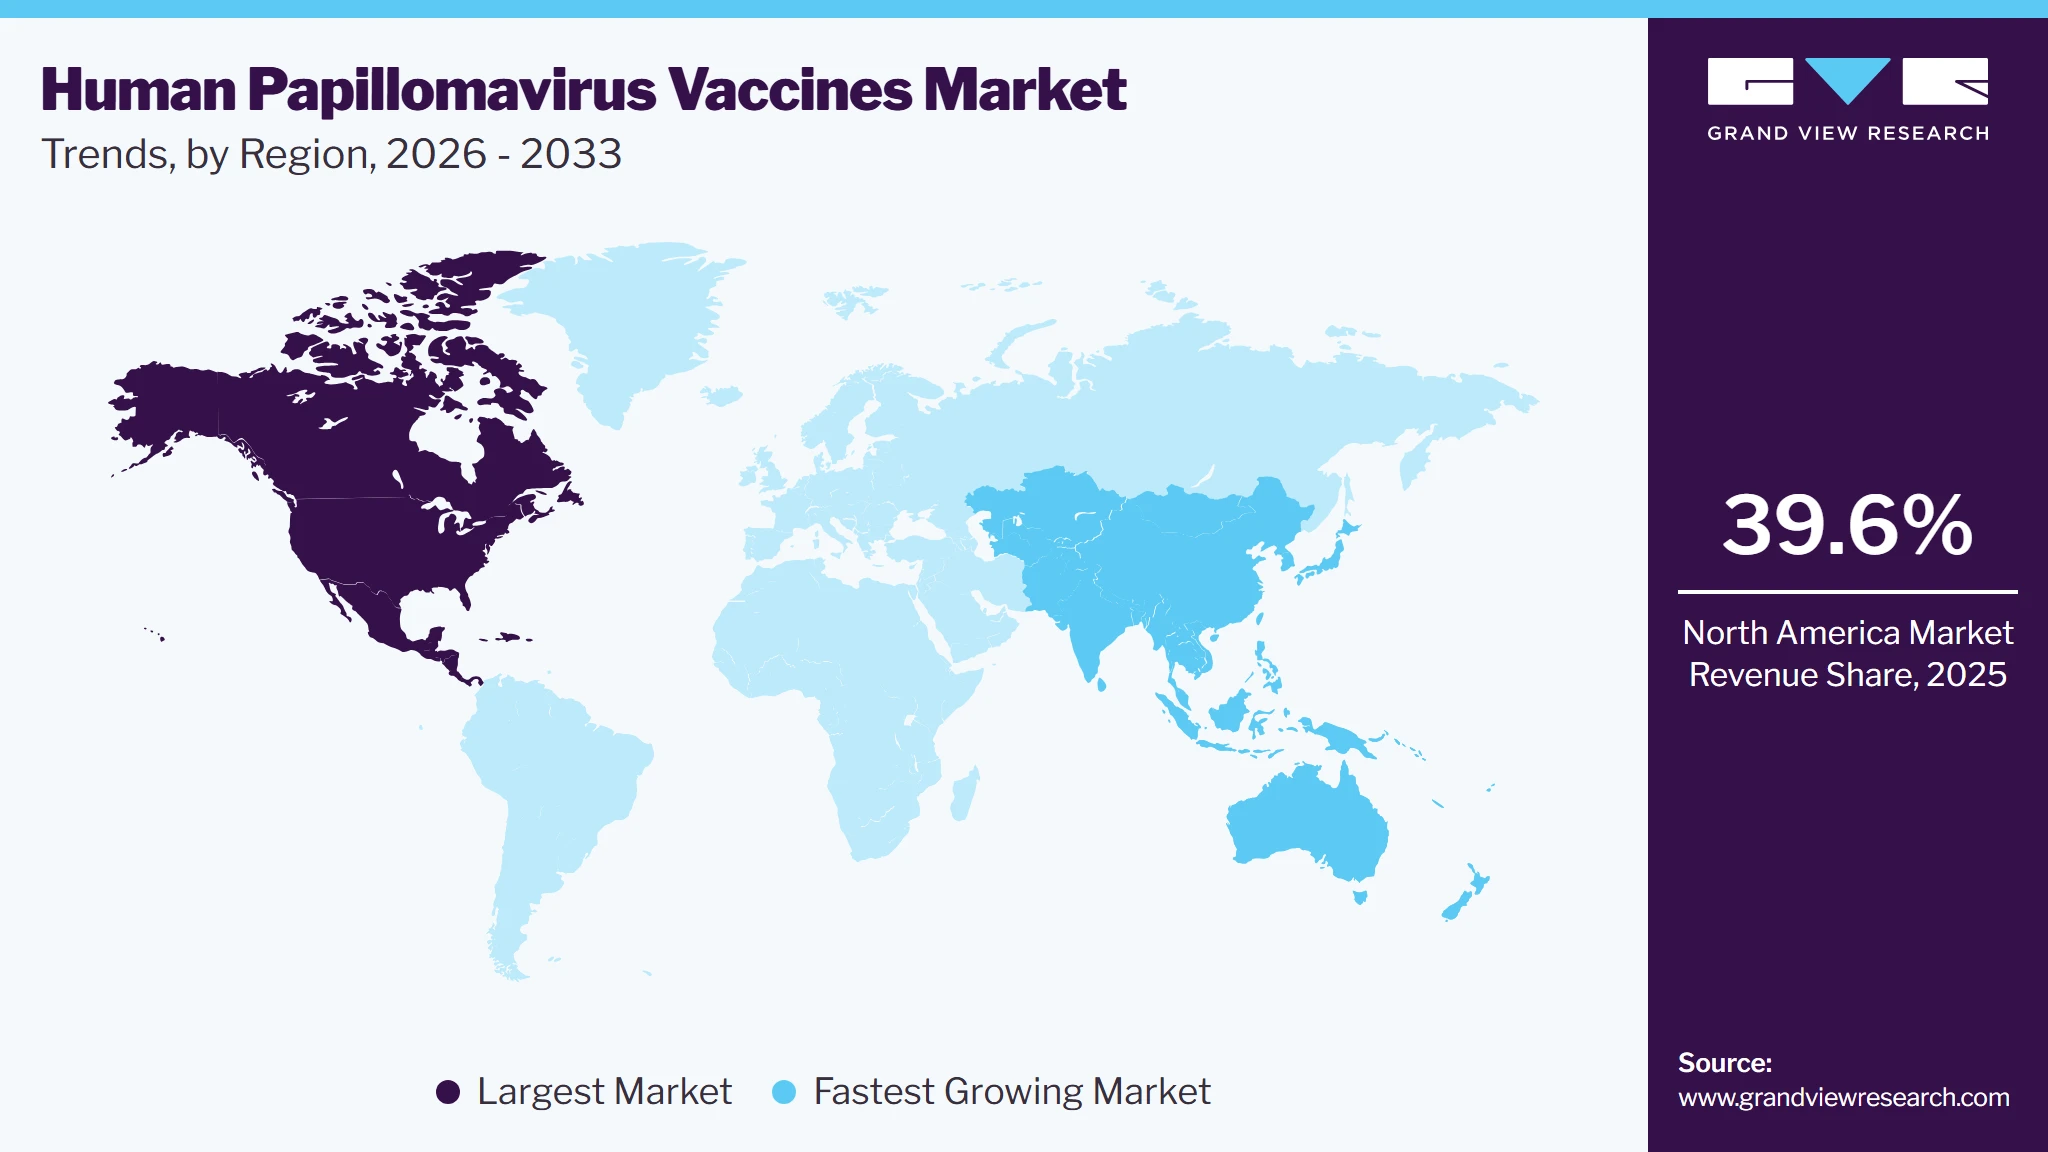
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 9.2 Billion
- Estimated market size in 2026: USD 10.0 Billion
- Projected market size by 2033: USD 17.0 Billion
- CAGR (2026-2033): 7.8%
Prism AI by Grand View Research Free to tryAsk a question about the human papillomavirus vaccines marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Human papillomavirus is the primary cause of cervical cancer, which ranks as the fourth most prevalent cancer among women worldwide. It is also associated with several other malignancies, including anal, oropharyngeal, and penile cancers. According to the report published in March 2024, World Health Organization (WHO), cervical HPV prevalence is highest in sub-Saharan Africa at 24%, followed by Latin America and the Caribbean (16%), Eastern Europe (14%), and South-East Asia (14%).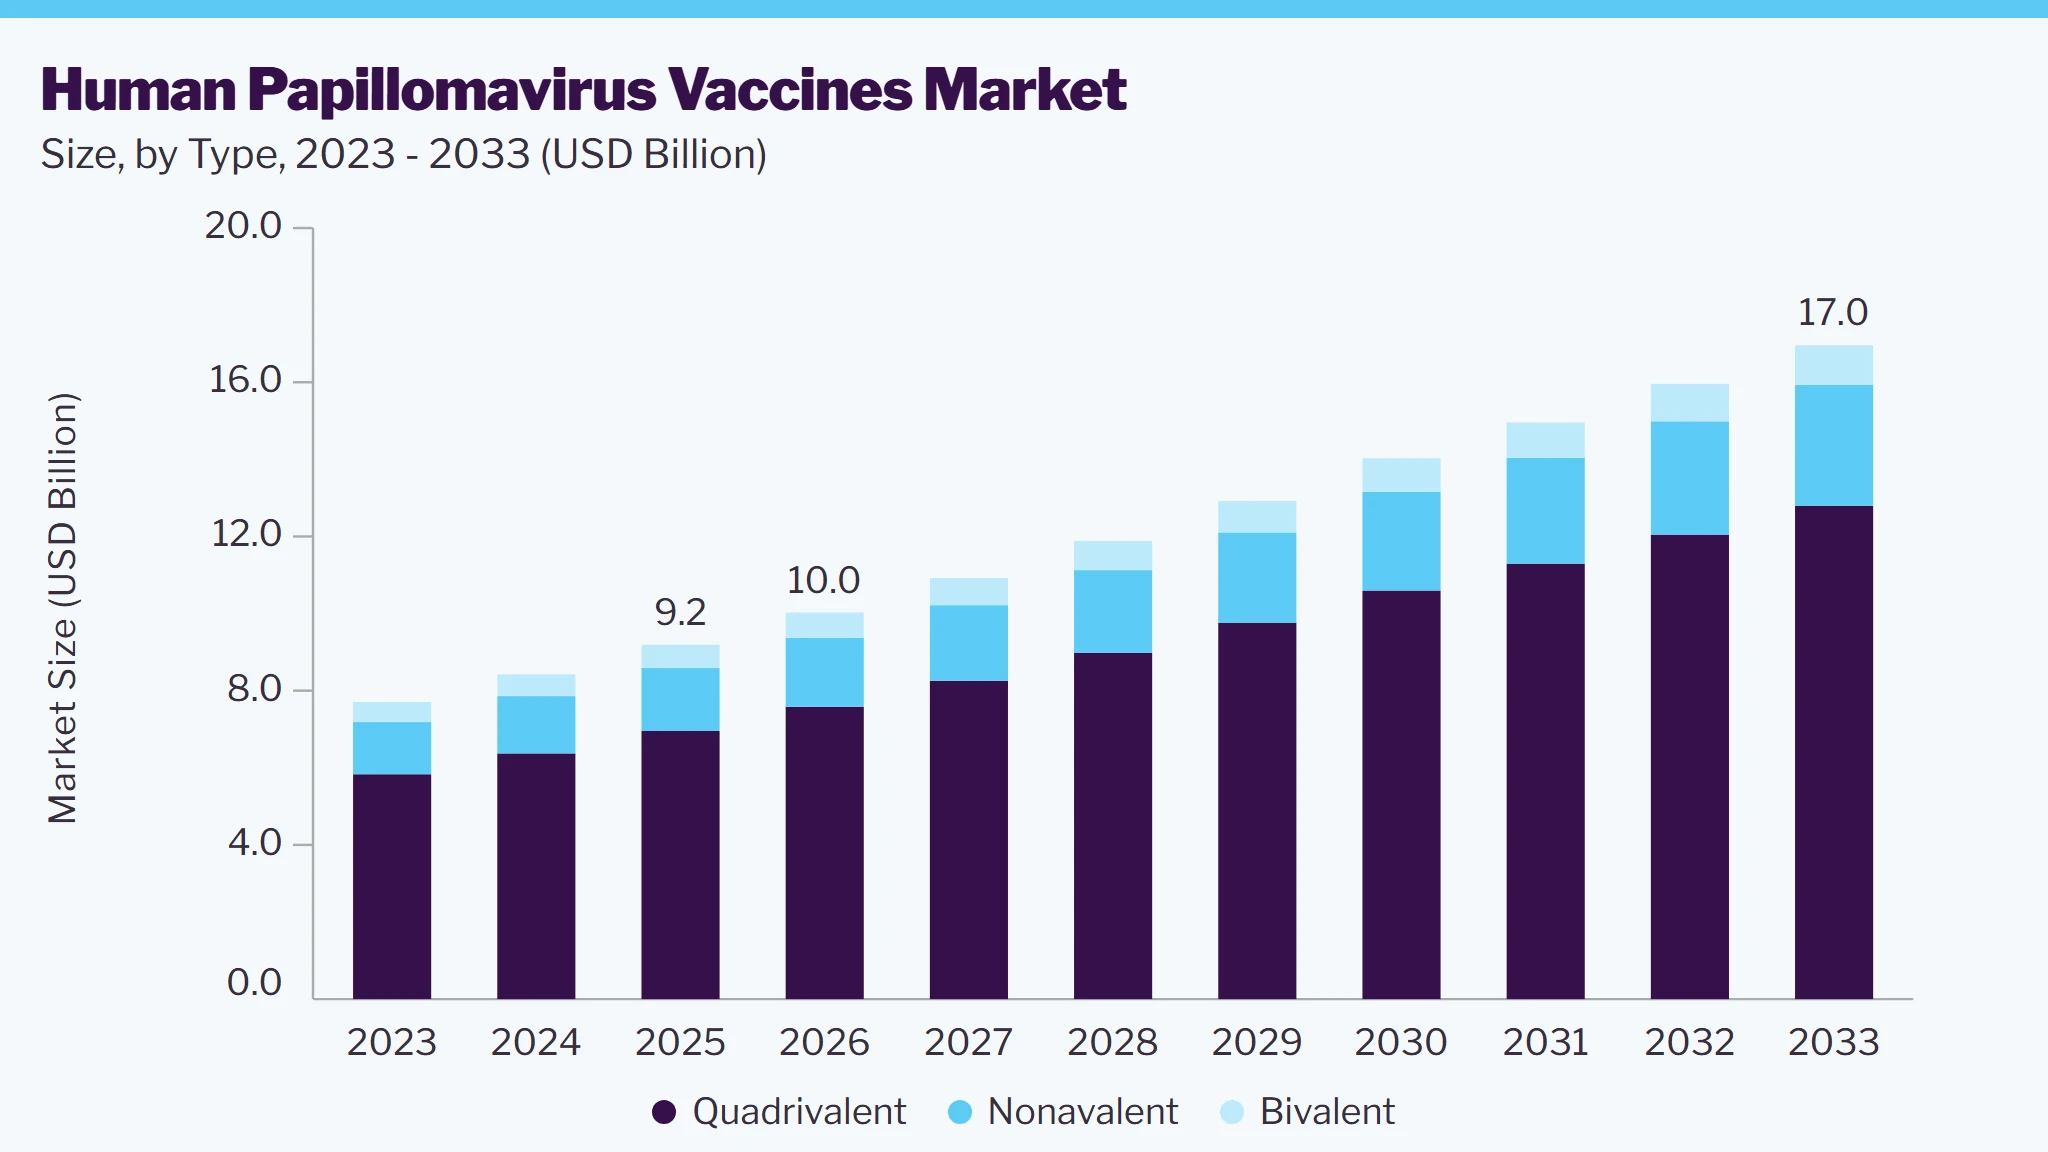 To learn more about this report, Download Free Sample Report
This concerning pattern has heightened awareness among governments and the general population, intensifying the demand for preventive healthcare interventions. As a result, many national immunization programs-particularly in low- and middle-income countries-have expanded with the support of global health organizations such as Gavi. With more countries adopting HPV vaccines as part of routine immunization, the market is poised for steady growth, fostering advancements in both preventive and therapeutic solutions.
Robust government support and international public health initiatives are playing a pivotal role in expanding the HPV vaccines industry. Many governments have incorporated HPV vaccines into national immunization schedules, often offering them at no cost to the public to ensure widespread access. Programs such as the WHO’s Global Strategy to Eliminate Cervical Cancer by 2030 aim to achieve 90% vaccination coverage among girls by the age of 15, dramatically driving demand. Organizations like Gavi, the Vaccine Alliance, work to reduce vaccine prices and expand access in low- and middle-income countries. In addition, funding from global stakeholders such as the Bill & Melinda Gates Foundation and UNICEF supports distribution, logistics, and outreach. This institutional backing not only improves vaccination rates but also creates a favorable regulatory and financial environment for pharmaceutical companies, encouraging further innovation and investment. As these coordinated efforts continue, they strengthen the infrastructure supporting HPV prevention and treatment globally.
Market Dynamics
The human papillomavirus (HPV) vaccines market is driven by increasing immunization programs, growing awareness regarding HPV-associated cancers, and expanding government initiatives to improve vaccination coverage. HPV vaccines play a significant role in preventing infections caused by high-risk HPV strains responsible for cervical, anal, vaginal, vulvar, oropharyngeal cancers, and genital warts. National immunization programs across developed and developing countries continue to incorporate HPV vaccination for adolescents, while several countries are expanding recommendations to include boys and young adults. Improvements in healthcare infrastructure, broader access to preventive healthcare services, and increasing investments in vaccine manufacturing are supporting market growth. Pharmaceutical companies are also focusing on expanding manufacturing capacity, geographic reach, and regulatory approvals to address the growing demand for HPV vaccines. In addition, recommendations from public health organizations and school-based vaccination programs are contributing to higher vaccine adoption across multiple regions. The market continues to benefit from ongoing efforts to improve vaccine accessibility, strengthen immunization coverage, and reduce the global burden of HPV-related diseases, supporting steady demand for prophylactic HPV vaccines during the coming years.
The expansion of national immunization programs and the increasing focus on preventing HPV-related cancers are major factors driving the human papillomavirus (HPV) vaccines market. Governments and public health organizations are strengthening routine vaccination programs to reduce the incidence of cervical cancer and other HPV-associated diseases. Several countries have expanded recommendations to include both girls and boys, increasing the eligible vaccination population and supporting higher immunization coverage. School-based vaccination initiatives, public awareness campaigns, and favorable reimbursement policies are further improving vaccine accessibility across developed and emerging economies. In addition, recommendations from healthcare organizations and continuous efforts to improve early disease prevention have increased acceptance of HPV vaccination among healthcare providers and parents. Pharmaceutical companies are also expanding manufacturing capacity and geographic presence to meet growing demand from public immunization programs. These initiatives support consistent vaccine procurement through government agencies and healthcare systems while improving access in underserved populations. As countries continue to prioritize preventive healthcare and cancer control strategies, demand for HPV vaccines is expected to remain strong during the coming years. For instance, in March 2025, Merck announced that the U.S. FDA approved GARDASIL 9 for the prevention of HPV-related recurrent respiratory papillomatosis (RRP) caused by HPV types 6 and 11, expanding the vaccine's approved indications and supporting broader vaccine utilization.
Limited vaccination coverage across several low- and middle-income countries remains a key challenge for the human papillomavirus (HPV) vaccines market. Although HPV vaccination has demonstrated significant clinical benefits, many countries continue to face barriers related to vaccine affordability, limited healthcare infrastructure, and inadequate cold-chain distribution systems. Rural and underserved regions often experience restricted access to preventive healthcare services, reducing vaccination rates among eligible populations. In addition, shortages of trained healthcare professionals and insufficient public awareness regarding HPV-related diseases contribute to lower vaccine acceptance. Vaccine hesitancy associated with misinformation and cultural perceptions further limits immunization coverage in several regions. Budget constraints within national healthcare systems may also delay the introduction or expansion of HPV vaccination programs, particularly where competing public health priorities exist. Variations in reimbursement policies and healthcare spending create uneven vaccine access across countries, affecting overall market penetration. Addressing these challenges requires continued investment in healthcare infrastructure, education campaigns, and funding support for national immunization programs. For instance, in 2025, the World Health Organization (WHO) stated that many low-income countries continued to experience challenges in achieving HPV vaccination targets due to funding limitations, supply constraints, and gaps in healthcare delivery infrastructure.
The expansion of HPV vaccination programs across emerging economies presents a significant opportunity for market growth. Governments across Asia Pacific, Latin America, the Middle East, and Africa are increasingly incorporating HPV vaccines into national immunization schedules to reduce the burden of cervical cancer and other HPV-related diseases. Financial support from international organizations, improving healthcare infrastructure, and rising healthcare expenditure are increasing access to preventive vaccination in these regions. Pharmaceutical companies are expanding manufacturing capacity, strengthening regional distribution networks, and pursuing regulatory approvals to improve vaccine availability in underserved markets. In addition, gender-neutral vaccination policies and catch-up vaccination programs for older adolescents and young adults are increasing the eligible patient population. Public-private partnerships and school-based vaccination campaigns continue to improve awareness and vaccination coverage, creating additional demand for HPV vaccines. These developments provide manufacturers with opportunities to expand their geographic presence while supporting government efforts to improve long-term cancer prevention. For instance, in January 2025, Gavi, the Vaccine Alliance, continued supporting the expansion of HPV vaccination programs across eligible lower-income countries through financial assistance and vaccine procurement initiatives aimed at increasing immunization coverage and improving access to HPV vaccines.
Market Concentration & Characteristics
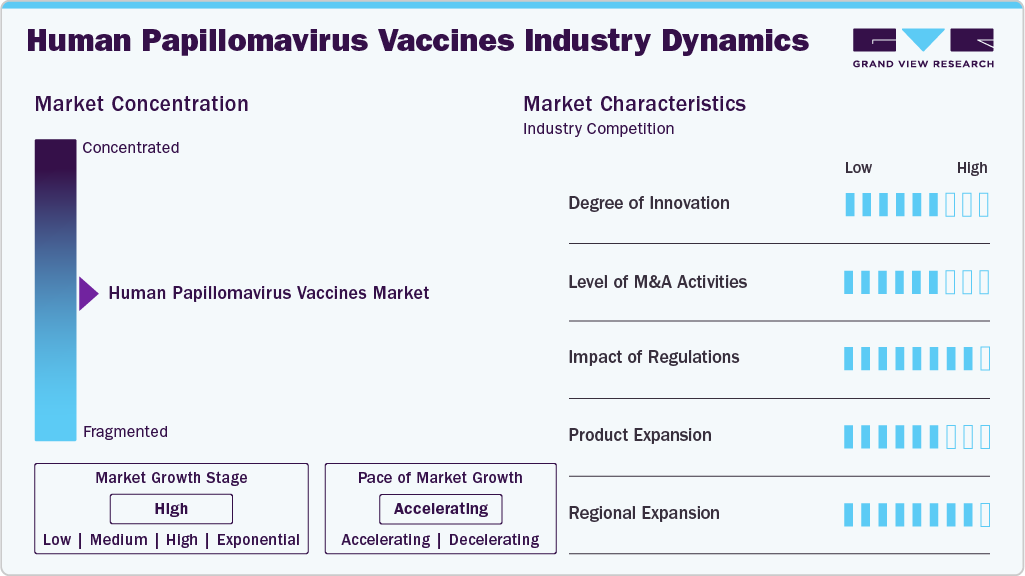
The HPV vaccines industry is experiencing notable innovation, particularly in multivalent vaccine formulations and emerging therapeutic vaccines. Advances in mRNA technology and immune-modulating therapies are expanding the treatment landscape. R&D efforts are also focused on improving vaccine stability and delivery methods, making them more accessible. These innovations are crucial for broadening protection and targeting persistent HPV infections more effectively.
Mergers and acquisitions are increasingly shaping the HPV market, as major pharmaceutical companies seek to expand their product portfolios and pipeline capabilities. Strategic acquisitions of biotech firms with novel HPV therapies or vaccine technologies enable rapid market entry and reduce time-to-market for new innovations. These M&A activities also support geographic expansion and scale-up of manufacturing, enhancing competitiveness, and reinforcing market presence globally.
 To learn more about this report, Download Free Sample Report
Regulatory frameworks have a strong impact on the HPV market, influencing vaccine approval, pricing, and distribution. Agencies like the FDA and EMA have streamlined approval pathways for high-priority vaccines, while WHO prequalification facilitates use in global immunization programs. Stringent safety and efficacy standards ensure public trust, but differing regional guidelines can slow global launches. Harmonized regulatory policies would significantly benefit faster adoption and global accessibility.
Product expansion in the HPV space includes both preventative and therapeutic innovations. New multivalent vaccines offering broader strain coverage are being introduced, while research into therapeutic vaccines and antiviral treatments is expanding the curative aspect of the market. Manufacturers are also developing pediatric and gender-neutral formulations, increasing the eligible population. Expanded product lines enhance market penetration, meet diverse needs, and drive sustainable revenue growth.
The HPV vaccines industry is rapidly expanding into emerging regions, driven by high disease burden and improved healthcare infrastructure. Partnerships with global health organizations facilitate access in Africa, Asia, and Latin America through subsidized pricing and education campaigns. Local manufacturing and government-led immunization programs are key to boosting coverage. Regional expansion not only addresses healthcare gaps but also opens significant new revenue streams for manufacturers.
Table 1 HPV vaccine recommendations by age, recommendations by the federal Advisory Committee on Immunization Practices (ACIP), June 2024
Age at Vaccine Initiation
ACIP Recommendation
Vaccine Schedule
9-14 years old
2-dose series
Dose 1: first shot
Dose 2: given 6 to 12 months after the first shot
9-14 years old
3-dose series*
Dose 1: first shot
Dose 2: given less than 5 months after the first shot
Dose 3: at least 4 months after second shot
15-45 years old**
3-dose series
Dose 1: first shot
Dose 2: given 1-2 months after first shot
Dose 3: given 6 months after second shot
Rapid technological advancements and increased research and development activities are accelerating innovation in the HPV vaccines sector. The emergence of next-generation vaccines like Gardasil 9, which offers protection against nine HPV strains, highlights the trend toward broader and more effective immunization. Researchers are also exploring therapeutic vaccines aimed at treating existing infections and related cancers, expanding the market beyond prevention. The success of mRNA technology during the COVID-19 pandemic has spurred interest in applying similar platforms to HPV vaccines and treatments. In addition, innovations in cold-chain logistics, needle-free delivery systems, and thermostable formulations are improving vaccine accessibility and uptake in remote or under-resourced regions. These advancements not only improve efficacy and patient compliance but also attract substantial investment from biotechnology firms and pharmaceutical giants. As the R&D pipeline grows more sophisticated, the availability of novel, affordable, and more accessible HPV solutions will significantly expand the global market footprint.
 To learn more about this report, Download Free Sample Report
Increased public awareness and education about HPV and its health implications are driving higher vaccination rates and market growth. Historically, cultural stigma and limited knowledge about HPV transmission and consequences hindered vaccine acceptance, especially among adolescents and their parents. However, targeted awareness campaigns-led by health ministries, NGOs, schools, and media-are changing perceptions by focusing on the vaccine’s role in preventing cancer rather than sexually transmitted infections. School-based programs, celebrity endorsements, and social media outreach have proven effective in shifting public attitudes. Moreover, healthcare providers are now more proactive in recommending HPV vaccination as part of routine adolescent care. Digital tools such as SMS reminders, mobile apps, and online appointment booking systems further boost engagement. This widespread awareness is reducing vaccine hesitancy and fostering informed health decisions, thereby increasing demand not only for vaccines but also for screening and therapeutic treatments. In turn, this contributes significantly to the expansion of the HPV care market.
Emerging markets are increasingly contributing to the growth of the HPV vaccines industry, largely due to expanding access and strategic partnerships. High disease burden in regions such as Africa, Asia, and Latin America has prompted pharmaceutical companies and global health organizations to collaborate on large-scale vaccination campaigns. These partnerships often include technology transfers, local manufacturing agreements, and subsidized pricing models to help reduce logistical and financial barriers. In addition, regulatory harmonization and streamlined clinical trial processes in emerging economies make these regions attractive for new product launches. Governments in these countries are also implementing school-based immunization programs and public-private partnerships to ensure broader coverage. The success of such initiatives not only improves population health but also establishes a sustainable market for future therapeutics. As demand in mature markets stabilizes, the growth potential in underserved regions positions emerging economies as a key frontier for market expansion and innovation in HPV prevention and treatment.
Analyst Perspective
The human papillomavirus vaccines market is becoming an integral part of global preventive healthcare, supported by the expansion of national immunization programs, increasing awareness of HPV-related cancers, and broader recommendations for gender-neutral vaccination. The market is consolidating around manufacturers with established vaccine development, manufacturing, and global supply capabilities. Merck & Co., Inc. continues to maintain a leading position through the widespread adoption of GARDASIL 9, while GlaxoSmithKline plc (GSK) and Serum Institute of India Pvt. Ltd. are expanding vaccine accessibility across multiple regions. At the same time, companies such as Moderna, Inc., Inovio Pharmaceuticals Inc., and Bharat Biotech International Ltd. are advancing next-generation vaccine technologies and expanding regional manufacturing capabilities, supporting long-term market development and broader access to HPV vaccination.
Type Insights
Based on type, the quadrivalent segment led the market with the largest revenue share of 75.7% in 2025, due to its broad protection against four HPV types: 6, 11, 16, and 18. These types are responsible for around 70% of cervical cancers and approximately 90% of genital warts, which has made the quadrivalent vaccine a cornerstone of HPV vaccination programs globally. Its market growth is driven by increasing awareness of HPV-related cancers and genital warts, as well as expanding immunization initiatives in both high-income and developing countries. Moreover, the established track record of the quadrivalent vaccine, particularly Gardasil, has made it a preferred choice for national immunization programs. Healthcare providers and governments recognize the vaccine’s cost-effectiveness and its ability to address multiple HPV strains simultaneously. Despite the rise of nonavalent vaccines offering even broader protection, the quadrivalent vaccine continues to see strong demand, especially in regions with established immunization infrastructures. This segment's growth remains robust as it contributes significantly to global efforts in reducing HPV-related diseases.
The nonavalent segment is projected to register the fastest CAGR during the forecast period, driven by its expanded protection against nine HPV types-6, 11, 16, 18, 31, 33, 45, 52, and 58. These types are associated with a wider spectrum of cancers, including cervical, vulvar, vaginal, anal, penile, and oropharyngeal cancers, making the nonavalent vaccine a highly comprehensive preventive option. The growth is further supported by increasing government support, WHO recommendations, and growing inclusion of the nonavalent vaccine in national immunization programs. Rising public awareness, improved healthcare access, and greater availability through organizations such as the Pan American Health Organization (PAHO) are accelerating uptake, particularly in low- and middle-income countries. As a result, the nonavalent vaccine segment is poised for rapid expansion, addressing a critical gap in HPV-related disease prevention.
Disease Insights
Based on disease, the cervical cancer segment led the market with the largest revenue share of 63.8% in 2025, due to heightened awareness and proactive prevention strategies. Cervical cancer remains one of the most common cancers caused by HPV, particularly types 16 and 18, which account for about 70% of cases. As a result, the global healthcare community has prioritized cervical cancer prevention through HPV vaccination, especially in adolescent girls. Government-backed vaccination initiatives, public health campaigns, and school-based programs have significantly improved vaccine coverage in both developed and developing nations. Moreover, the World Health Organization’s (WHO) goal to eliminate cervical cancer as a public health problem by increasing HPV vaccination rates has further boosted market momentum. Technological advancements and the introduction of vaccines with broader HPV strain coverage, such as the nonavalent vaccine, also support growth. This segment continues to be a primary driver of demand within the HPV vaccines industry due to its high disease burden and preventability.
The oropharyngeal (head and neck) cancers segment is projected to register the fastest CAGR during the forecast period, driven by the increasing incidence of HPV-associated throat cancers, especially in high-income countries. Unlike traditional risk factors such as tobacco and alcohol use, HPV-related oropharyngeal cancers are now recognized as a leading cause of head and neck malignancies, particularly in males. This shift in disease dynamics has spurred public health authorities and researchers to advocate for gender-neutral HPV vaccination, further expanding the target population. As awareness about the link between HPV and oropharyngeal cancer grows, more countries are integrating HPV vaccines into routine immunization schedules for boys as well as girls. The broader strain coverage offered by nonavalent vaccines, including protection against HPV types 16 and 18, which are most strongly associated with these cancers, is also fueling segment growth.
Distribution Channel Insights
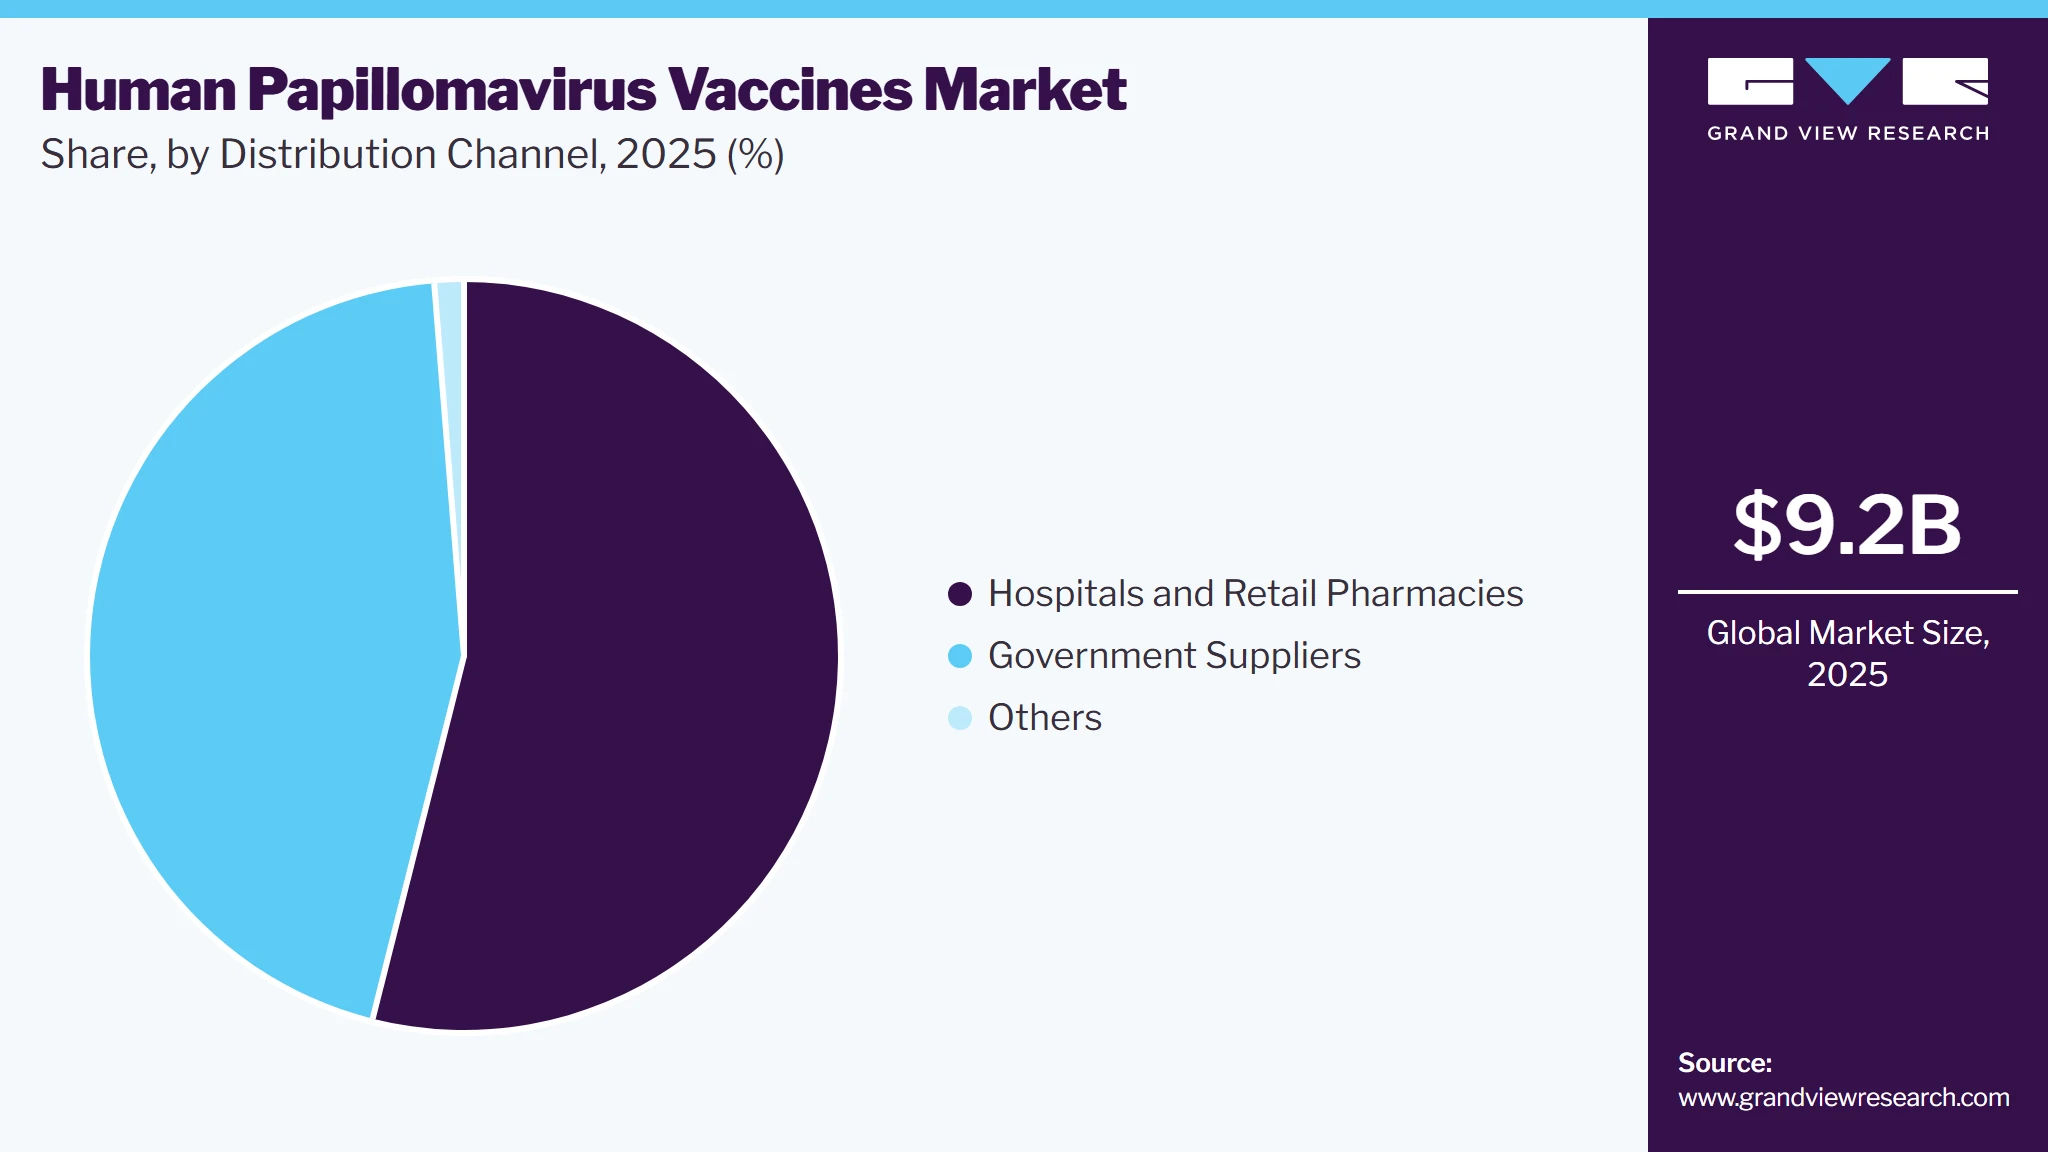
Based on distribution channel, the hospitals and retail pharmacies segment led the market with the largest revenue share of 53.9% in 2025 and is expected to grow at the fastest CAGR over the forecast period. This growth is largely attributed to the increasing accessibility, convenience, and trust associated with these healthcare settings. Hospitals are central to organized immunization drives, particularly in urban and semi-urban areas, where structured healthcare infrastructure supports efficient vaccine administration. Meanwhile, retail pharmacies are playing an increasingly important role by offering walk-in vaccination services, extended hours, and widespread geographic presence, which enhance patient reach and compliance. Governments and health agencies are also partnering with these channels to expand HPV vaccine coverage, particularly through public-private collaborations. In many regions, retail pharmacies have become authorized vaccine providers, accelerating the decentralization of immunization services. Furthermore, growing awareness about HPV-related diseases and strong public health initiatives have led to increased footfall in these settings, solidifying this segment as both a dominant and fast-growing distribution channel.
 To learn more about this report, Download Free Sample Report
The government suppliers segment is expected to grow at the fastest CAGR over the forecast period. Governments, often in collaboration with international health organizations such as the WHO, GAVI, and PAHO, are implementing large-scale vaccination programs to curb the burden of HPV-related diseases such as cervical cancer. This segment is expanding due to increased public health funding, national immunization initiatives, and procurement of HPV vaccines through revolving funds and bulk purchasing agreements that ensure cost-effective access. Government-run schools and public health clinics serve as key delivery points for these vaccines, facilitating widespread coverage, especially among adolescent girls and boys. Strategic campaigns promoting vaccine awareness and safety have further supported acceptance in communities. Although government suppliers may face logistical challenges in remote regions, ongoing efforts to improve cold chain infrastructure and healthcare delivery systems continue to strengthen their role in market expansion and equitable vaccine access.
Regional Insights
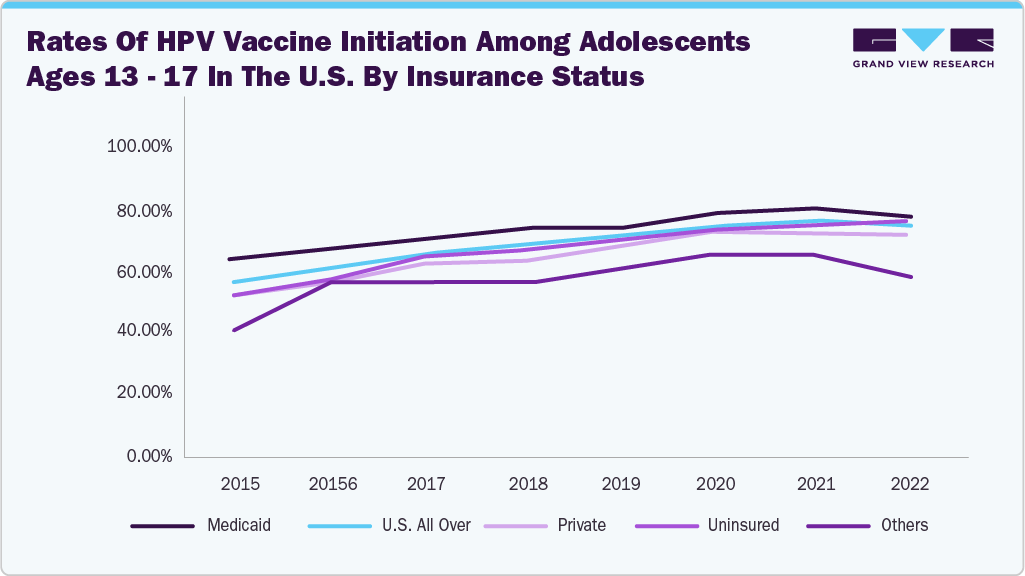
North America dominated the human papillomavirus vaccines market with the largest revenue share of 39.6% in 2025. The region’s dominance is driven by widespread immunization programs and strong public health initiatives. As reported by the CDC, in 2023, 78.5% of adolescent girls and 75% of boys in the United States received at least one dose of the HPV vaccine. Despite this progress, overall initiation rates saw a slight decline in 2022-the first drop since 2013, particularly among certain subgroups of adolescents aged 13-17. This trend underscores the need for renewed focus on equitable outreach and education efforts across all communities.
 To learn more about this report, Download Free Sample Report
U.S. Human Papillomavirus Vaccines Market Trends
The human papillomavirus vaccines market in the U.S. held the largest share in the North America region in 2025. U.S. human papillomavirus (HPV) vaccines industry growth is robust, which is driven by public financing. Programs like Vaccines for Children (VFC) enable the CDC to buy vaccines at reduced costs and distribute them to providers, ensuring access for uninsured, underinsured, Medicaid-eligible, and American Indian or Alaska Native children up to age 18. Medicaid also covers ACIP-recommended vaccines for individuals under 21 through the EPSDT program. For adults over 21, Medicaid ensures coverage of approved vaccines with no out-of-pocket expenses. In addition, Section 317 of the Public Health Service Act provides federal funding to states and local agencies to expand vaccine access for uninsured adults, helping close critical coverage gaps and support widespread immunization efforts.
Europe Human Papillomavirus Vaccines Market Trends
The human papillomavirus (HPV) vaccines industry in Europe is expanding, supported by rising vaccination rates. According to gov.uk, in England during the 2022 - 2023 academic year, 75.7% of Year 9 females received their first dose of the HPV vaccine-a 6.1 percentage point increase from 69.6% when the same group was in Year 8 the year before. Among Year 9 males, first-dose coverage reached 69.7%, reflecting continued progress in gender-inclusive immunization and strengthening market potential across the region.
The UK human papillomavirus (HPV) vaccines industry growth is being driven by government-led immunization programs and rising public awareness. The National Health Service (NHS) offers free HPV vaccination to adolescents, contributing to high coverage rates among both girls and boys. Recent data shows improved uptake, especially among Year 9 students, reflecting effective school-based delivery. Continued investment in preventive healthcare, public education, and expanded vaccine eligibility supports long-term market expansion and highlights the UK’s leadership in HPV-related disease prevention.
Germany human papillomavirus (HPV) vaccines industry growth is anticipated to grow over the forecast period. As of 2021, only 54% of 15-year-old girls and 27% of boys were fully vaccinated against HPV, falling short of the WHO's 90% goal for girls by 2030. The COVID-19 pandemic further impacted uptake, with first-dose vaccinations among girls aged 9-14 dropping over 21% below 2019 levels in 2021 and 2022. Despite these challenges, Germany's immunization program has led to significant declines in HPV-related diseases, including a 51.1% reduction in high-grade cervical lesions and a 75% decrease in vaginal precancer/cancer prevalence. Efforts such as school-based vaccination programs in regions like Bremen have shown promise in increasing uptake among underserved populations. To enhance coverage, health authorities are considering strategies like early preventive check-ups and digital reminder systems. With sustained initiatives, Germany aims to improve vaccination rates and strengthen its HPV prevention efforts.
Asia Pacific Human Papillomavirus Vaccines Market Trends
The Asia Pacific human papillomavirus (HPV) vaccines industry is experiencing significant growth, with only about half of the region’s countries fully implementing national HPV vaccination programs. Many still lack reliable coverage data. However, countries like Singapore and Brunei stand out, having achieved over 90% first-dose coverage among girls by age 15. Their success is driven by strong healthcare infrastructure and effective public health initiatives, setting a benchmark for regional vaccination efforts.
The human papillomavirus (HPV) vaccines industry in Japan is experiencing significant growth driven by increasing public awareness, government initiatives, and a rising incidence of HPV-related diseases such as cervical cancer. Reinstated vaccination programs and enhanced healthcare infrastructure have further boosted vaccine uptake, particularly among young women. Technological advancements in vaccine development and expanding research into therapeutic options are also contributing to market expansion. In addition, growing support from international health organizations and improved accessibility are expected to sustain strong market growth in the coming years.
China human papillomavirus (HPV) vaccines industry is witnessing substantial growth, driven by several key factors. Government initiatives, such as the China Action Plan for Accelerated Elimination of Cervical Cancer (2023 - 2030), aim to increase vaccination rates through pilot programs offering free HPV vaccines in various provinces. The introduction of domestically produced vaccines, like Wantai's bivalent HPV vaccine, has enhanced accessibility and affordability, with prices dropping in some regions. Despite challenges like vaccine hesitancy and supply shortages, ongoing efforts to expand public awareness and infrastructure are expected to sustain market growth.
Latin America Human Papillomavirus Vaccines Market Trends
The Latin America human papillomavirus (HPV) vaccines industry is witnessing significant growth driven by several key factors. Government initiatives, such as the inclusion of HPV vaccines in national immunization programs, have increased vaccine accessibility and public awareness. International support from organizations such as PAHO and UNICEF has facilitated vaccine procurement at reduced costs, making them more affordable for countries in the region. Technological advancements, including the development of at-home HPV screening tests, have improved early detection and prevention efforts. Despite challenges like vaccine hesitancy and limited knowledge about HPV, ongoing educational campaigns and healthcare provider recommendations are helping to overcome these barriers.
The human papillomavirus (HPV) vaccines industry in Brazil is expanding due to several key factors. Government-led vaccination initiatives, including school-based programs targeting girls aged 9 to 13, have increased vaccine accessibility and coverage. Public health campaigns have raised awareness about the link between HPV and cervical cancer, driving higher vaccine uptake. Enhanced healthcare infrastructure, with increased vaccine distribution through clinics and schools, has improved access, particularly in underserved regions. In addition, international partnerships with organizations like PAHO and UNICEF have reduced vaccine costs, further expanding coverage.
Middle East & Africa Human Papillomavirus Vaccines Market Trends
The Middle East and Africa (MEA) human papillomavirus (HPV) vaccines industry is witnessing rapid expansion, driven by several key factors. Government initiatives, such as the introduction of HPV vaccines into national immunization programs, have increased vaccine accessibility. International support from organizations like Gavi, the Vaccine Alliance, has facilitated vaccine procurement at reduced costs, making them more affordable for countries in the region. Technological advancements, including the development of at-home HPV screening tests, have improved early detection and prevention efforts. Despite challenges like vaccine hesitancy and limited knowledge about HPV, ongoing educational campaigns and healthcare provider recommendations are helping in overcoming these barriers. As a result, countries in the MEA region are witnessing substantial market growth, with projected compound annual growth rates (CAGR) indicating continued expansion in the coming years.
The human papillomavirus (HPV) vaccines industry in Saudi Arabia is witnessing substantial growth, propelled by several key factors. The Ministry of Health's integration of the HPV vaccine into the national immunization schedule in March 2022, followed by its expansion to younger age groups in September 2022, has significantly increased vaccine accessibility. This initiative is part of a broader effort to combat cervical cancer, which accounts for approximately 179 deaths annually in the country. Moreover, the government's commitment to preventive healthcare is evident through subsidized screening programs, including pap smears, making them more accessible to the public. Despite these advancements, challenges such as vaccine hesitancy persist, with studies indicating that 34% of parents express reluctance to vaccinate their adolescent daughters. Addressing these concerns through targeted educational campaigns and healthcare provider recommendations is essential to further enhance vaccine uptake and reduce the burden of HPV-related diseases in Saudi Arabia.
Key Human Papillomavirus Vaccines Company Insights
Key market players are adopting market strategies, such as new product launches, collaborations, and geographical expansions, to increase their global footprint. For instance, in March 2024, Merck announced at the EUROGIN 2024 HPV Congress its plans to begin clinical development of a novel investigational multi-valent Human Papillomavirus (HPV) vaccine aimed at offering broader protection against a wider range of HPV types. In addition, the company revealed its intention to launch clinical trials involving both females and males to assess the efficacy and safety of a single-dose regimen of GARDASIL9 (9-valent recombinant HPV vaccine), in comparison to the currently approved three-dose schedule.
Key Human Papillomavirus Vaccines Companies:
The following key companies have been profiled for this study on the human papillomavirus vaccines market.
-
Merck & Co., Inc.
-
GlaxoSmithKline plc (GSK)
-
Serum Institute of India Pvt. Ltd.
-
Sanofi Pasteur SA
-
Pfizer Inc.
-
Inovio Pharmaceuticals Inc.
-
Walvax Biotechnology Co., Ltd.
-
Bharat Biotech International Ltd.
-
Johnson & Johnson Services, Inc.
-
Moderna, Inc.
-
Gilead Sciences, Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Merck & Co., Inc., GlaxoSmithKline plc (GSK), Serum Institute of India Pvt. Ltd., Sanofi Pasteur SA, Pfizer Inc.)
- Focus on expanding HPV vaccine portfolios through regulatory approvals, manufacturing capacity expansion, and inclusion in national immunization programs. Strengthen partnerships with governments, public health agencies, and international organizations to improve vaccine accessibility and vaccination coverage across developed and emerging markets.
- Strong brand recognition and established vaccine manufacturing capabilities. Extensive global distribution networks, broad regulatory approvals, and long-term supply agreements with governments and public health organizations support consistent market presence.
- High manufacturing and regulatory compliance costs associated with vaccine production. Dependence on government procurement and national immunization budgets may affect revenue growth in certain regions.
Emerging Players (Inovio Pharmaceuticals Inc., Walvax Biotechnology Co., Ltd., Bharat Biotech International Ltd., Johnson & Johnson Services, Inc., Moderna, Inc., Gilead Sciences, Inc.)
- Focus on developing next-generation HPV vaccines using novel technologies, expanding clinical development programs, and increasing regional manufacturing capabilities. Strengthen strategic collaborations, licensing agreements, and research partnerships to accelerate product development and enter new geographic markets.
- Ability to introduce differentiated vaccine technologies and expand into underserved markets. Flexible research and development strategies support innovation and address regional demand for preventive HPV vaccination.
- Limited commercial HPV vaccine portfolios and lower global market presence compared to established manufacturers. Ongoing clinical development, regulatory approvals, and manufacturing scale-up may delay broader market penetration.
Recent Developments
-
In April 2025, Bulgaria expanded its national HPV vaccination program in collaboration with the Ministry of Health and the Bulgarian HPV Coalition, marking a major step forward in the country's efforts to prevent at least six types of cancer-cervical, vaginal, vulvar, anal, penile, and head & neck-all of which can be caused by the common HPV virus.
-
In February 2025, the Pan American Health Organization (PAHO) announced that starting July 2025, the 9-valent HPV vaccine will be accessible to countries across the Americas through its Revolving Fund for Access to Vaccines. This initiative aims to provide more affordable and efficient access to the vaccine, which offers protection against nine strains of the human papillomavirus (HPV) linked to various cancers, including cervical, anal, and oropharyngeal cancers.
-
In November 2024, Merck announced new clinical and real-world findings for its 9-valent Human Papillomavirus (HPV) vaccine, GARDASIL 9 (Human Papillomavirus 9-valent Vaccine, Recombinant), highlighting data on the burden and incidence of various HPV-related cancers and diseases.
Human Papillomavirus Vaccines Market Report Scope
Report Attribute
Details
Market size in 2025
USD 9.2 billion
Estimated market size in 2026
USD 10.0 billion
Projected market size by 2033
USD 17.0 billion
Growth rate
CAGR of 7.8% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, disease, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Norway; Sweden; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait.
Key companies profiled
Merck & Co., Inc., GlaxoSmithKline plc (GSK), Serum Institute of India Pvt. Ltd., Sanofi Pasteur SA, Pfizer Inc., Inovio Pharmaceuticals Inc., Walvax Biotechnology Co., Ltd., Bharat Biotech International Ltd., Johnson & Johnson Services, Inc., Moderna, Inc., Gilead Sciences, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Human Papillomavirus Vaccines Market Report Segmentation
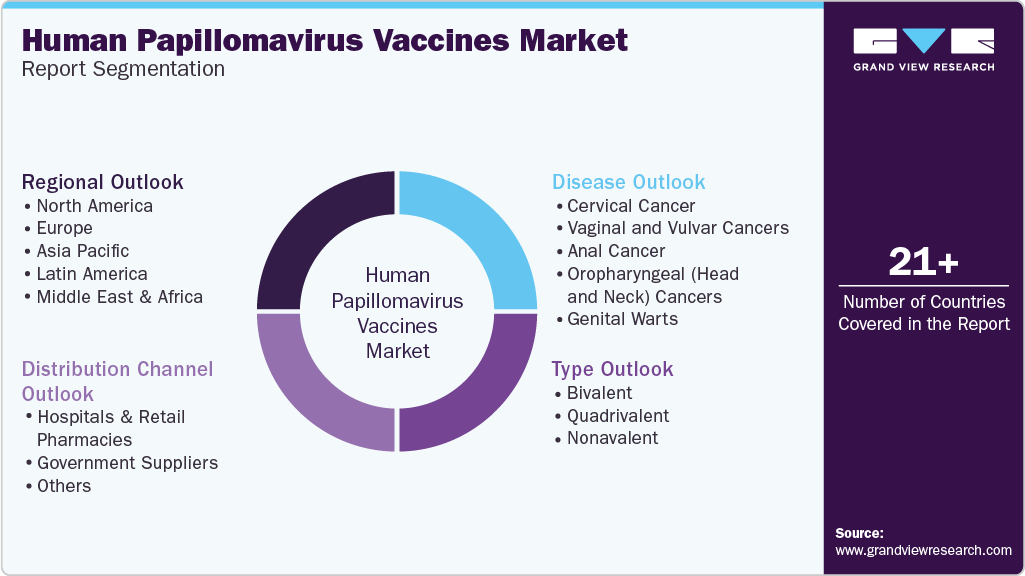
This report forecasts revenue growth and provides an analysis of the latest trends in each of the sub-segments from 2021 to 2033. For this report, Grand View Research has segmented the global human papillomavirus vaccines market report based on type, disease, distribution channel, and region.
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Bivalent
-
Quadrivalent
-
Nonavalent
-
-
Disease Outlook (Revenue, USD Million, 2021 - 2033)
-
Cervical Cancer
-
Vaginal and Vulvar Cancers
-
Anal Cancer
-
Oropharyngeal (Head and Neck) Cancers
-
Genital Warts
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals and Retail Pharmacies
-
Government Suppliers
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
Russia
-
Iceland
-
Finland
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
Singapore
-
Israel
-
-
Research Methodology
The human papillomavirus vaccines market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each human papillomavirus vaccines segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Bivalent
This segment includes prophylactic HPV vaccines designed to protect against HPV types 16 and 18, which are responsible for the majority of cervical cancer cases. It covers revenue generated from vaccines supplied through national immunization programs, hospitals, clinics, pharmacies, and private healthcare providers for preventive vaccination.
Quadrivalent
This segment includes HPV vaccines that provide protection against HPV types 6, 11, 16, and 18. It comprises revenue generated from vaccines administered to prevent cervical cancer, other HPV-related cancers, and genital warts through public immunization programs, hospitals, vaccination centers, and retail pharmacies.
Nonavalent
This segment includes HPV vaccines that protect against nine HPV types, covering additional high-risk oncogenic strains beyond quadrivalent vaccines. Revenue includes vaccine sales through government procurement, hospitals, clinics, retail pharmacies, and other healthcare providers for the prevention of multiple HPV-related diseases.
Segment - Disease
Revenue capture definition
Cervical Cancer
This segment includes HPV vaccine revenue associated with the prevention of cervical cancer caused by persistent infection with high-risk HPV types. It covers vaccines administered through routine immunization programs, catch-up vaccination initiatives, hospitals, clinics, and private healthcare providers for eligible individuals.
Vaginal and Vulvar Cancers
This segment includes HPV vaccine revenue related to preventing HPV infections associated with vaginal and vulvar cancers. It covers vaccines supplied through public immunization programs and private healthcare channels for individuals eligible to receive prophylactic HPV vaccination against these HPV-related malignancies.
Anal Cancer
This segment includes HPV vaccine revenue associated with preventing HPV infections linked to anal cancer. It comprises vaccines administered through national immunization programs, hospitals, clinics, vaccination centers, and other healthcare providers serving eligible populations for preventive vaccination.
Oropharyngeal (Head and Neck) Cancers
This segment includes HPV vaccine revenue associated with preventing HPV infections linked to oropharyngeal and other HPV-related head and neck cancers. It covers vaccines administered through government immunization programs, hospitals, clinics, and private healthcare providers for eligible age groups.
Genital Warts
This segment includes HPV vaccine revenue associated with preventing genital warts primarily caused by HPV types 6 and 11. It comprises vaccines distributed through public immunization programs, hospitals, clinics, pharmacies, and other authorized healthcare providers offering preventive vaccination services.
Segment - Distribution Channel
Revenue capture definition
Hospitals and Retail Pharmacies
This segment includes HPV vaccines distributed through hospital pharmacies, retail pharmacies, vaccination clinics, and healthcare systems. Revenue comprises vaccines supplied for routine immunization, physician-recommended vaccination, private prescriptions, and outpatient preventive healthcare services.
Government Suppliers
This segment includes HPV vaccines procured and distributed by government agencies, national immunization programs, public health departments, and international procurement organizations. Revenue covers vaccines supplied for school-based vaccination campaigns, public immunization initiatives, and government-funded preventive healthcare programs.
Others
This segment includes HPV vaccines distributed through channels not classified under hospitals, retail pharmacies, or government suppliers. It comprises vaccines supplied through community vaccination centers, occupational healthcare providers, non-governmental organizations, academic institutions, military healthcare systems, and other authorized vaccination providers.
Estimation Model
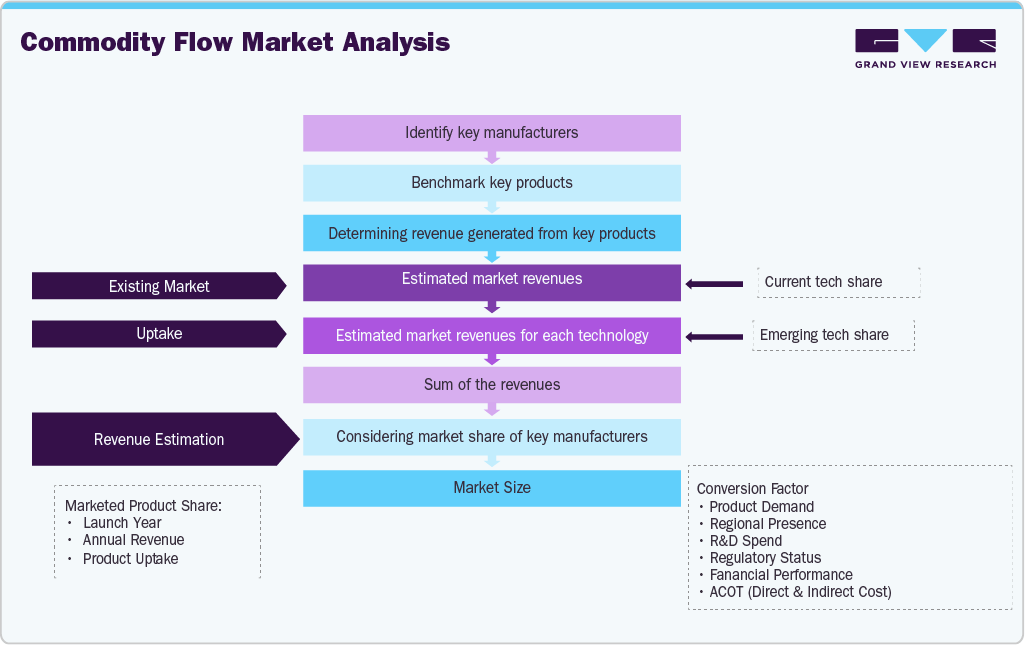
The human papillomavirus vaccines market was estimated using a commodity flow market analysis approach. The study identified major vaccine manufacturers and benchmarked their marketed HPV vaccines based on vaccine type, geographic availability, regulatory approvals, and distribution channels. Product-level revenues were estimated using company annual reports, investor presentations, government procurement databases, immunization program data, and public health publications. Revenue generated from bivalent, quadrivalent, and nonavalent vaccines was analyzed across key regions and adjusted based on vaccination coverage, public procurement, private-sector demand, and manufacturer market share. Country-level vaccination initiatives, national immunization schedules, and vaccine adoption trends were incorporated to estimate regional demand. Primary interviews with vaccine manufacturers, distributors, healthcare professionals, and industry experts were conducted to validate assumptions. The final market size was derived through bottom-up revenue aggregation and cross-verified using top-down analysis, industry databases, regulatory publications, and publicly available financial information.
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
HPV Vaccines Competitive Landscape & Pipeline Assessment
Conducted a targeted assessment of the global HPV vaccines market, evaluating approved vaccines, late-stage pipeline candidates, vaccine technologies, regulatory progress, and competitive positioning. The study analyzed key participants including Merck & Co., Inc., GlaxoSmithKline plc (GSK), Serum Institute of India Pvt. Ltd., Sanofi Pasteur SA, Pfizer Inc., and emerging developers such as Moderna, Inovio Pharmaceuticals, Walvax Biotechnology, and Bharat Biotech to assess product development, manufacturing capabilities, and market expansion strategies.
Helped the client identify growth opportunities, evaluate competitive positioning, benchmark pipeline development, and prioritize licensing, partnership, and regional expansion opportunities within the HPV vaccines market.
HPV Vaccine Technology & Product Benchmarking Study
Delivered a comprehensive benchmarking assessment of HPV vaccine technologies, comparing bivalent, quadrivalent, and nonavalent vaccines based on strain coverage, clinical performance, regulatory approvals, manufacturing capabilities, geographic availability, and immunization program adoption. The study evaluated product differentiation, pipeline innovations, and technology trends supporting future vaccine development.
Enabled the client to assess product competitiveness, identify technology gaps, benchmark vaccine portfolios, and prioritize investments in next-generation vaccine platforms, manufacturing expansion, and geographic market opportunities.
HPV Vaccine Manufacturing & Supply Chain Feasibility Assessment
Conducted a strategic assessment of the HPV vaccine manufacturing ecosystem, evaluating production capacity, raw material sourcing, fill-finish capabilities, regulatory compliance, cold-chain distribution infrastructure, and regional manufacturing networks. The study analyzed supply agreements, government procurement programs, manufacturing expansion plans, and distribution capabilities supporting large-scale vaccination initiatives across global markets.
Supported strategic manufacturing planning by identifying production capabilities, evaluating supply chain risks, strengthening procurement and distribution strategies, and improving long-term manufacturing scalability and vaccine availability across public and private immunization programs.
Frequently Asked Questions About This Report
The global human papillomavirus vaccines market size was valued at USD 9.2 billion in 2025 and is estimated to reach USD 10.0 billion in 2026.
The global human papillomavirus vaccines market is projected to grow at a CAGR of 7.8% from 2026 to 2033, reaching USD 17.0 billion by 2033.
North America dominated the human papillomavirus vaccines market with the largest revenue share of 39.6% in 2025.
Key factors driving market growth include the expansion of national immunization programs, increasing focus on cancer prevention, rising awareness of HPV-associated diseases, broader adoption of gender-neutral vaccination policies, growing government support for vaccination initiatives, and improved access to vaccines through public healthcare systems.
Asia Pacific is the fastest-growing region over the forecast period.
The Quadrivalent HPV Vaccines segment led the market with the largest revenue share of 75.7% in 2025.
Cervical cancer segment led the market with the largest revenue share of 63.8% in 2025.
The Hospitals and Retail Pharmacies segment held the largest market share of 53.9% in 2025.
Key players operating in the Human Papillomavirus Vaccines market include Merck & Co., Inc., GlaxoSmithKline plc (GSK), Serum Institute of India Pvt. Ltd., Sanofi Pasteur SA, Pfizer Inc., Inovio Pharmaceuticals Inc., Walvax Biotechnology Co., Ltd., Bharat Biotech International Ltd., Johnson & Johnson Services, Inc., Moderna, Inc., and Gilead Sciences, Inc.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


