
- Home
- »
- Organic Chemicals
- »
-
Hydrofluoric Acid Market Size & Growth Report, 2026-2033GVR Report cover

Hydrofluoric Acid Market (2026 - 2033)
Size, Share & Trends Analysis Report By Grade (Anhydrous, Diluted), By Application (Fluorocarbon, Metal Pickling, Fluorinated Derivatives, Glass Etching, Oil Refining), By Region (North America, EU, APAC), And Segment Forecasts
Market Size, 2025
$1.2BMarket Estimate, 2026
$1.3BMarket Forecast, 2033
$1.9BCAGR, 2026–2033
5.4%Hydrofluoric Acid Market Summary
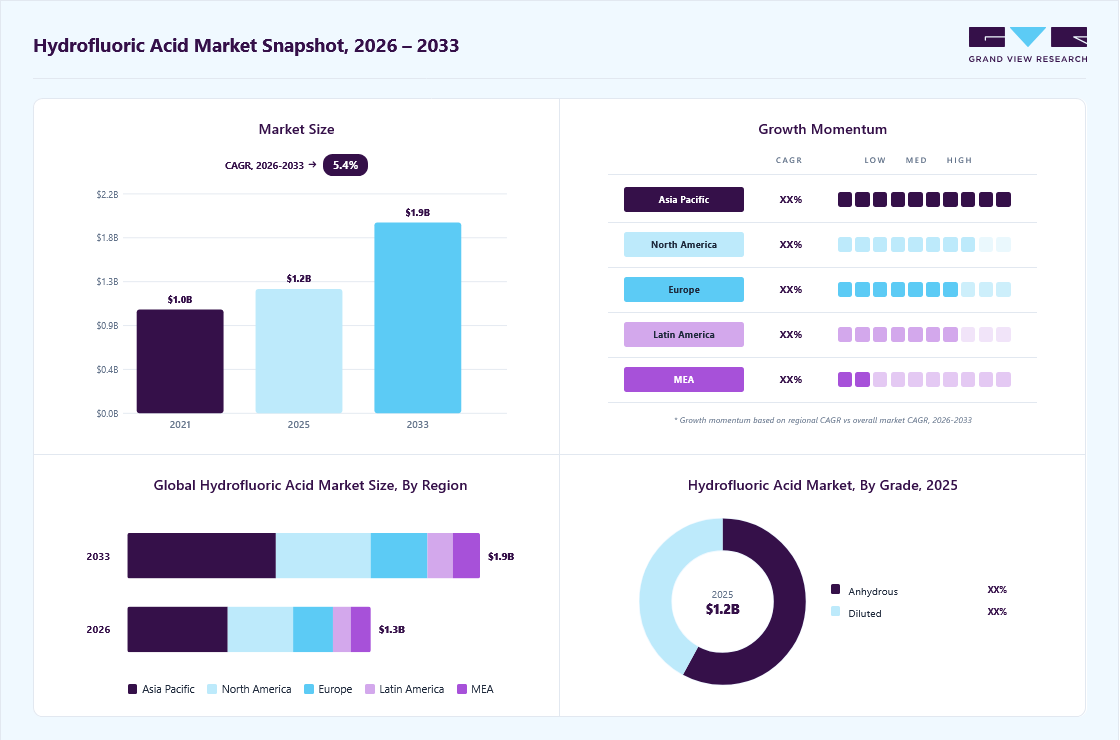
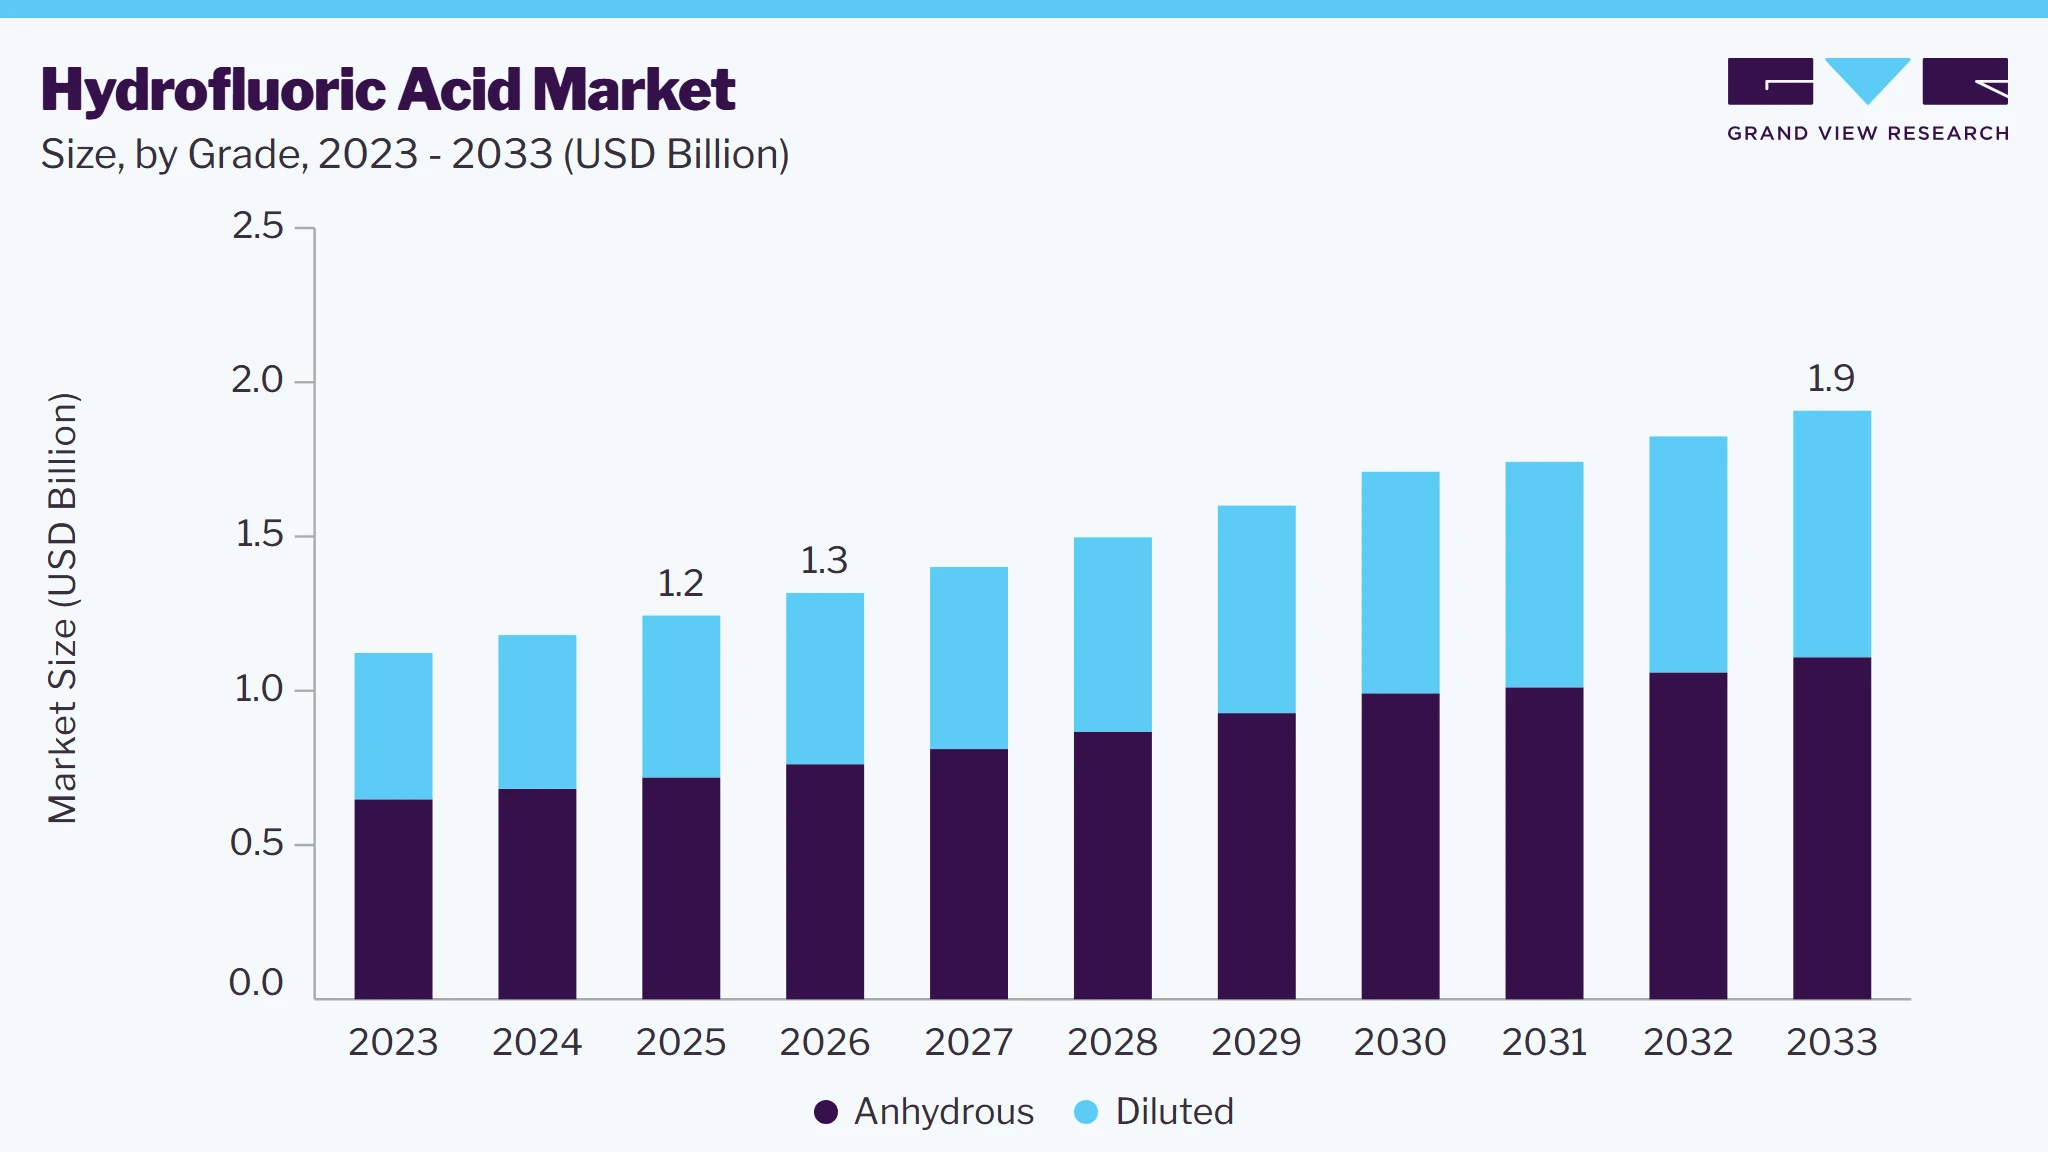
The global hydrofluoric acid market size was valued at USD 1.2 billion in 2025 and is projected to grow from USD 1.3 billion in 2026 to USD 1.9 billion by 2033, at a CAGR of 5.4% from 2026 to 2033. The market in Asia Pacific dominated with a revenue share of 41.1% in 2025. The growth is attributed to the growing product utilization in several end-use applications, such as refrigerants, metal, fluorocarbon, aluminum, plastics, and oil refining among others.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By grade: Anhydrous segment held the largest market share of 57.8% in 2025.
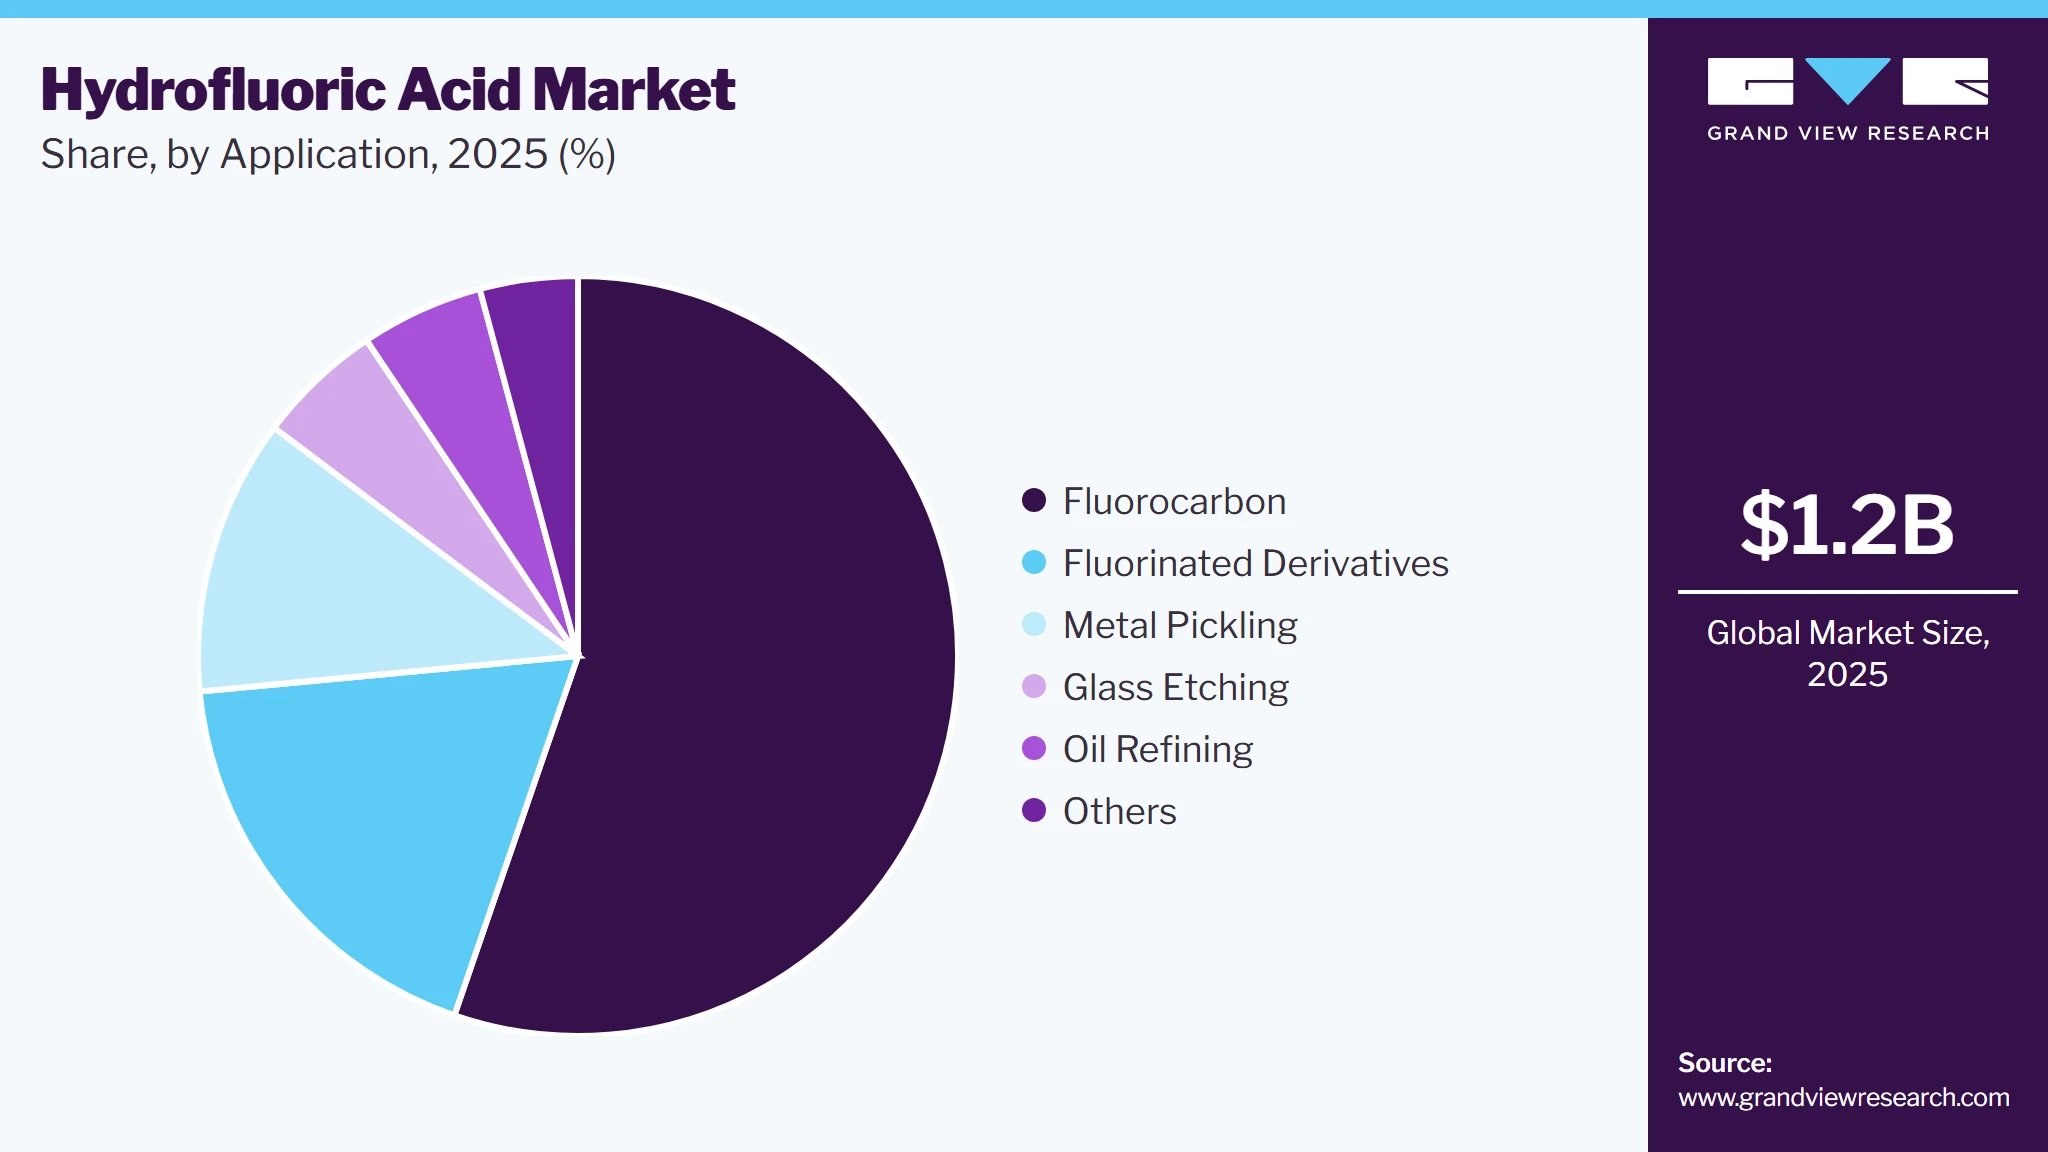
- By application: Fluorocarbon segment held the largest market share of 55.3% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (41.1% revenue share, 2025)
- By country: China held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 1.2 Billion
- Estimated market size in 2026: USD 1.3 Billion
- Projected market size by 2033: USD 1.9 Billion
- CAGR (2026-2033): 5.4%
Prism AI by Grand View Research Free to tryAsk a question about the hydrofluoric acid marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →Moreover, the growing demand for high-grade acids is likely to boost the product demand over the forecast period. Hydrofluoric acid is widely used in the chemical industry for the production of various fluorine components, such as fluorides, fluoropolymers, and fluorocarbon among others.
 To learn more about this report, Download Free Sample Report
Hydrofluoro-olefins and hydrofluorcarbons are also used extensively in refrigerants worldwide due to their high-quality attributes. It is also used in manufacturing aluminum fluoride that has wide application in numerous aluminum products. The key raw materials used to manufacture hydrofluoric acid include fluorspar and sulphuric acid. Fluorspar is a source of fluorine that can be found naturally and artificially with the help of hydrothermal. It is widely used in the manufacturing process of uranium fuel, aluminum, steel, gasoline, refrigerants, and insulating foams among others.
The product is produced by heating purified fluorspar with concentrated sulfuric acid to make gas. It is then condensed by cooling and dissolving in water. Moreover, it is generally used in plastic containers since it is highly reactive to glass and moderately reactive to metals. It is sold in different packaging options, such as drums, IBCs, and jerrycans, according to the quantity and needs of the customer. These containers are built with the highest safety standards and offer tailored products.
Market Dynamics
The hydrofluoric acid market is driven by its indispensable role in the production of fluorochemicals, petroleum refining, metal processing, and specialty chemical manufacturing. Rising demand for fluorocarbons and fluorinated derivatives across refrigeration, electronics, and automotive industries continues to strengthen market expansion. Increasing investments in semiconductor manufacturing and high-purity chemical production are further supporting consumption of hydrofluoric acid, particularly in advanced industrial applications. However, the highly corrosive and hazardous nature of hydrofluoric acid presents significant challenges related to transportation, storage, and workplace safety, resulting in stringent regulatory oversight and elevated compliance costs. Environmental concerns associated with fluorine-containing compounds are also encouraging manufacturers to adopt safer handling practices and improve production efficiency. Despite these constraints, ongoing technological advancements in fluorochemical processing, capacity expansions in emerging economies, and growing demand for high-performance materials are creating new opportunities for market participants, enabling sustained growth through product innovation, operational optimization, and strategic investments across key end-use industries.
Hydrofluoric acid serves as a critical raw material in the production of fluorochemicals, making it an indispensable component of several high-growth industries. The expanding use of fluorocarbons in refrigeration, air conditioning, and heat pump systems, along with increasing demand for fluorinated intermediates used in pharmaceuticals, agrochemicals, and specialty chemicals, continues to support market growth. As industries prioritize higher-performance materials with improved chemical stability and thermal resistance, the need for hydrofluoric acid remains closely linked to the expansion of fluorochemical manufacturing worldwide.
The transition toward energy-efficient cooling technologies and the modernization of industrial manufacturing are further reinforcing demand for hydrofluoric acid. Growing investments in chemical production facilities, particularly across Asia Pacific and the Middle East, are strengthening regional supply chains and creating additional consumption opportunities.
The hazardous and highly corrosive properties of hydrofluoric acid continue to be a major constraint on market growth. Exposure to even minimal amounts can lead to severe health consequences, including deep tissue damage and systemic poisoning, requiring strict safety protocols across manufacturing, transportation, storage, and application processes. Consequently, producers must adhere to comprehensive occupational health, environmental protection, and transportation regulations that differ across jurisdictions. Meeting these standards increases operational complexity and requires ongoing investment in dedicated storage facilities, workforce training, emergency preparedness, and specialized safety systems. For small and mid-sized manufacturers, these additional requirements can place considerable financial strain, limiting their ability to expand operations or compete effectively.
The rapid expansion of semiconductor manufacturing presents a significant long-term growth opportunity for the hydrofluoric acid market. High-purity hydrofluoric acid is widely used in wafer cleaning, surface preparation, and precision etching processes required during semiconductor fabrication. As governments and private organizations continue investing in domestic semiconductor production to strengthen supply chain resilience, demand for ultra-high-purity process chemicals is expected to increase steadily. The growth of artificial intelligence, electric vehicles, cloud computing, and advanced consumer electronics is further accelerating semiconductor production, directly supporting hydrofluoric acid consumption.
Analyst Perspective
The hydrofluoric acid market is driven by its critical applications in fluorochemicals, oil refining, metal treatment, and semiconductor manufacturing. Rising demand for high-purity hydrofluoric acid, particularly from the electronics and semiconductor sectors, is reshaping market dynamics. Although strict safety standards and handling complexities continue to present operational challenges, industry participants are adopting advanced manufacturing practices and enhanced safety measures to improve efficiency. Asia Pacific remains the dominant regional market, supported by robust industrial infrastructure and extensive fluorochemical production.
Grade Insights
By grade, anhydrous segment dominated the form segment with a market share of 57.8% in 2025. This is attributed to theincreased product inclusion in the formulation of surfactants, fluorochemicals, and fluoropolymers among others. It is used as a catalyst in petroleum alkylation. It is also used as a reagent in the acidolysis of the benzyl group in cysterine peptides. It improves production capabilities at lower temperatures, which, in turn, has a positive impact on the demand for anhydrous grade. Diluted or aqueous hydrofluoric acidis used in stainless steel pickling, metal coatings, glass etching, quartz purification, and exotic metal extraction.
It is also used to remove native silicon dioxide from wafers. It is commonly used in research due to its ability to etch silicon compounds. The product is highly corrosive to the skin and is toxic, which is creating a barrier to global market growth. The inhalation of a certain unit of anhydrous grade may cause severe respiratory issues. Thus, a specific range of acid up to 100 mg m3 is allowed for exposure to ensure the safety of the workers. Anhydrous hydrofluoric acid is gaining demand domestically as well in metal cleaners and wheel cleaners. This, in turn, is expected to trigger the segment growthover the forecast period.
Application Insights
Based on application, fluorocarbon segment projected the largest share of 55.3% in 2025. This is attributed to the rising demand for fluorocarbons from air conditioning systems and refrigerants, thus boosting production, especially in developing economies. The hydrofluoric acid demand in fluorocarbon is increasing as it is a non-chlorinated alternative to ozone-depleting chlorofluorocarbons. It is extensively used in the pickling of stainless steel and the semiconductor industry as a cleaning agent and an etchant.
 To learn more about this report, Download Free Sample Report
It is used for various applications, such as in the purification of quartz, graphite, and ferrosilicon, ceramic production, metal pickling, glass etching, and cleaning chemical solutions among others. The product is also used in treatment metals by removing stains and layers from the surface and offers shine and finish to the surface of the material.It is extensively used to improve fuel efficiency during the alkylation process in the petrochemical industry. Hydrofluoric acid alkylation units are process units utilized in petroleum refining to convert alkenes and isobutane (primarily butylene or propylene) into alkylate, which is further utilized to make gasoline.
The product is also used as a raw material in the production of aluminum, and the growing demand for aluminum products from different industries worldwide is anticipated to boost the market growth in the coming years. Hydrofluoric acid is considered to be a highly corrosive and toxic substance in nature. Inhalation or direct contact with hydrofluoric acid can cause severe health impacts. These types of restraints can decrease the adoption of industrial-grade hydrofluoric acid, which can further hamper the product demand.
Regional Insights
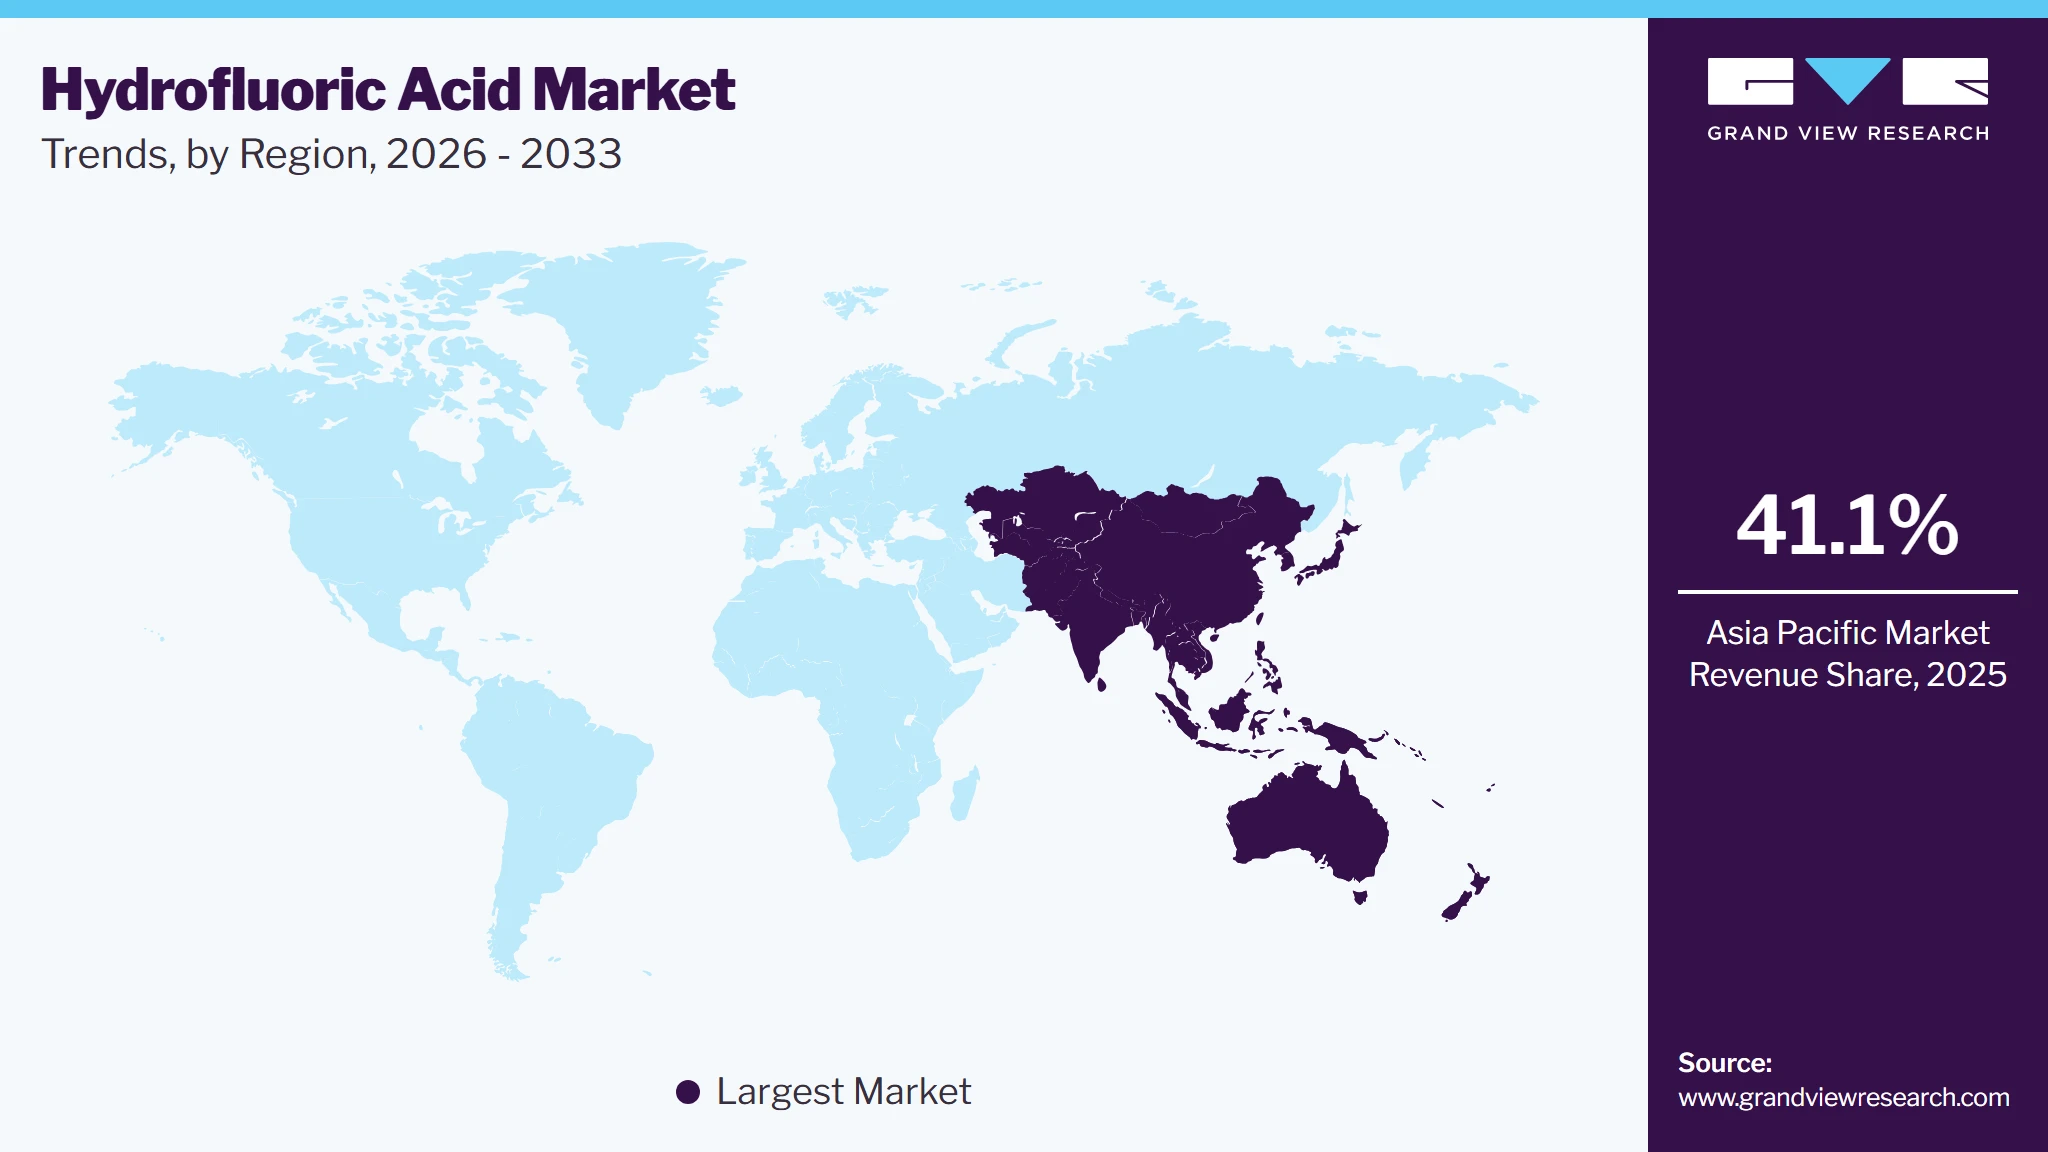
Asia Pacific accounted for 41.1% of the hydrofluoric acid market revenue in 2025, making it the largest regional market. This is attributed to the presence of numerous manufacturers of fluorocarbons across the region. The industry is expected to be the fastest-growing market over the forecast period. The rising demand for metal and electronics & semiconductors in China is positively impacting the product demand in the country. Furthermore, the rising utilization in national defense, industrial, and civil production industries is expected to boost marketgrowth.
 To learn more about this report, Download Free Sample Report
The market in Europe is likely to propel due to the increasing production of fluorochemicals across the region. The industry is growing across North America on the account of the increasing imports and the growing levels of R&D activities to make a better environmentally friendly product with the same performance. The manufacturing of hydrofluoric acid is significant in the Central & South America and the Middle East and Africa regions; however, the consumption level is comparatively lower than the other developed regions across the globe.
Key Companies & Market Share Insights
The competition in the market is highly dependent upon the product mix, the number of sellers, and geographical location. Key manufacturers are engaged in R&D activities to produce non-toxic products. Online distribution of products is growing rapidly compared to direct sales; however, direct sales still hold a larger market value due to easy access offered to customers. Key industry participants are focusing on mergers and acquisitions to increase their presence throughout the value chain. These players are simultaneously involved in several activities including the production and marketing of the final product to reduce the overall operational cost.Some prominent players in the global hydrofluoric acid market include:
Key Hydrofluoric Acid Companies:
The following key companies have been profiled for this study on the hydrofluoric acid market.
-
Daikin
-
Dongyue Group
-
Sinochem
-
Yingpeng Chemical
-
Honeywell International Inc.
-
Stella Chemifa Corp.
-
Koura Global
-
Lanxess
-
Solvay
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Daikin Industries, Honeywell International Inc., Solvay, LANXESS AG, Koura Global, Sinochem, Stella Chemifa Corporation)
- Focus on vertically integrated operations by securing fluorspar feedstock and downstream fluorochemical manufacturing.
- Invest in capacity modernization, process automation, and environmental compliance to improve production efficiency.
- Establish long-term supply agreements with automotive, electronics, refrigeration, and specialty chemical manufacturers.
- Expand high-purity hydrofluoric acid production for semiconductor and advanced industrial applications while strengthening global presence.
- Extensive global manufacturing footprint supported by established distribution and supply chain networks.
- Diversified product portfolios serving multiple end-use industries, reducing business concentration risk.
- Strong financial capabilities that support continuous investments in research, innovation, and capacity expansion.
- Well-established customer relationships and regulatory expertise create high barriers to market entry.
- High fixed operating costs associated with large-scale manufacturing facilities and infrastructure.
- Significant compliance expenses due to stringent environmental, transportation, and workplace safety regulations.
- Slower decision-making processes result from complex organizational structures.
- Exposure to fluctuations in raw material prices, energy costs, and cyclical demand from downstream industries.
Emerging & Regional Players (Dongyue Group, Yingpeng Chemical)
- Expand regional production capacity to meet growing domestic and neighboring market demand.
- Emphasize cost-efficient manufacturing and localized sourcing to improve price competitiveness.
- Develop strategic partnerships with downstream fluorochemical manufacturers and industrial customers.
- Invest progressively in production technology and quality improvements to enter higher-value application segments.
- Competitive production costs supported by efficient manufacturing operations.
- Greater flexibility to respond quickly to regional customer requirements and changing market conditions.
- Strong positioning in rapidly industrializing markets with increasing fluorochemical demand.
- Ability to scale operations through targeted capacity expansion and focused investment strategies.
- Limited international market presence compared to established multinational competitors.
- Smaller capital base restricts large-scale investments in advanced technologies and global expansion.
- Lower brand recognition among multinational customers operating in highly regulated industries.
- Higher dependence on regional economic conditions and local regulatory policies for business growth.
Hydrofluoric Acid Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.2 billion
Estimated market size in 2026
USD 1.3 billion
Projected market size by 2033
USD 1.9 billion
Growth rate
CAGR of 5.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, Volume in kilotons and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Grade, application, and region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; U.K.; Germany; France; Italy; China; India; Japan; South Korea; Brazil; Argentina; South Africa; Saudi Arabia
Key companies profiled
Daikin; Dongyue Group; Sinochem; Yingpeng Chemical; Honeywell International Inc.; Stella Chemifa Corp.; Koura Global; Lanxess; Solvay
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Hydrofluoric Acid Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2018 to 2030. For the purpose of this study, Grand View Research has segmented the global hydrofluoric acid market report on the basis of grade, application, and region:
-
Grade Outlook (Volume, Kilotons; Revenue, USD Million, 2018 - 2030)
-
Anhydrous
-
Diluted
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Million, 2018 - 2030)
-
Fluorocarbon
-
Fluorinated Derivatives
-
Metal Pickling
-
Glass Etching
-
Oil Refining
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2018 - 2030)
-
North America
-
The U.S.
-
Canada
-
Mexico
-
-
Europe
-
U.K.
-
Germany
-
France
-
Italy
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
-
Research Methodology
The hydrofluoric acid Market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each hydrofluoric acid segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Grade
Revenue capture definition
Anhydrous
Includes revenue generated from high-purity anhydrous hydrofluoric acid supplied for fluorochemical manufacturing, petroleum alkylation, semiconductor processing, metal treatment, and specialty chemical production where concentrated acid is required.
Diluted
Represents income derived from diluted hydrofluoric acid formulated for glass etching, metal cleaning and pickling, surface treatment, industrial maintenance, and laboratory applications requiring controlled acid concentration and safer handling.
Application
Revenue capture definition
Fluorocarbon
Includes revenue generated from hydrofluoric acid utilized as a primary feedstock in the production of refrigerants, fluoropolymer intermediates, and other fluorocarbon compounds for cooling, automotive, and industrial applications.
Fluorinated Derivatives
Represents income derived from hydrofluoric acid consumed in the synthesis of fluorinated chemicals, specialty intermediates, pharmaceuticals, agrochemicals, lithium battery materials, and high-performance fluorine-containing compounds.
Metal Pickling
Covers revenue from hydrofluoric acid supplied for stainless steel pickling, oxide scale removal, alloy surface treatment, and precision metal finishing processes that improve corrosion resistance and surface quality.
Glass Etching
Captures revenue from hydrofluoric acid used in decorative glass engraving, architectural glass processing, electronic display manufacturing, optical component fabrication, and precision surface texturing applications.
Oil Refining
Includes revenue generated from hydrofluoric acid employed as a catalyst in alkylation units within petroleum refineries to produce high-octane gasoline blending components and enhance fuel quality.
Other Applications
Represents sales generated from hydrofluoric acid used in semiconductor wafer cleaning, quartz purification, chemical synthesis, industrial cleaning formulations, analytical laboratories, and various niche manufacturing processes.
Estimation Model
Layer Name
Key Question
Description
Hydrofluoric Acid Production Layer
What forms is the supply base?
Identify the global production capacity of hydrofluoric acid by evaluating fluorspar mining output, acid-grade fluorspar availability, sulfuric acid integration, manufacturing technologies, production facilities, product grades (anhydrous and diluted), purification capabilities, packaging configurations, and regional manufacturing capacities across key producing countries.
Application Adoption Layer
Where are hydrofluoric acid utilized?
Estimate the distribution of hydrofluoric acid demand across fluorocarbons, fluorinated derivatives, metal pickling, glass etching, oil refining, semiconductor manufacturing, and other industrial applications by analyzing production activity, downstream processing requirements, technological advancements, regulatory standards, and end-use industry expansion across major regional markets.
Consumption Intensity Layer
How much hydrofluoric acid is consumed?
Assess hydrofluoric acid consumption across principal end-use industries by evaluating fluorochemical production volumes, petroleum refining activity, stainless steel processing, glass manufacturing, electronics fabrication, specialty chemical output, and industrial processing requirements to estimate annual demand across leading geographic markets.
Revenue Layer
How is market revenue generated?
Market revenue is generated through the sale of anhydrous and diluted hydrofluoric acid supplied to fluorochemical manufacturers, petroleum refineries, metal processing facilities, glass manufacturers, semiconductor producers, specialty chemical companies, and other industrial users through direct contracts, distribution partners, and integrated chemical supply networks across global markets.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional segmentation
The study delivers detailed country-level analysis across key hydrofluoric acid production and consumption markets. It evaluates fluorspar availability, hydrofluoric acid manufacturing capacity, downstream fluorochemical production, trade flows, regulatory framework, end-use industry demand, and regional growth prospects.
Enables informed expansion strategies by identifying high-growth countries, production centers, supply-demand trends, trade dynamics, and investment potential across major regional markets.
Competitive Benchmarking
Comparative assessment of leading hydrofluoric acid manufacturers based on product portfolio, production capacity, product purity, manufacturing technologies, geographic footprint, distribution capabilities, sustainability initiatives, research and development activities, strategic collaborations, and recent business developments.
Supports competitive positioning by highlighting production strengths, technological expertise, operational capabilities, product differentiation, and strategic initiatives adopted by leading market participants.
Opportunity Assessment
Comprehensive evaluation of emerging growth opportunities driven by expanding fluorochemical production, increasing semiconductor fabrication, rising demand for specialty fluorinated chemicals, refinery modernization, growth in stainless steel processing, and investments in advanced manufacturing technologies.
Assists long-term business planning by identifying high-potential application areas, emerging demand centers, technology-driven opportunities, evolving industrial requirements, and attractive investment prospects across the hydrofluoric acid value chain.
Frequently Asked Questions About This Report
Based on application, fluorocarbon segment projected the largest share of 55.3% in 2025. The increasing demand for refrigerants, fluoropolymers, and other fluorochemical products across automotive, electronics, and industrial applications continues to reinforce the segment's market leadership.
Asia Pacific accounted for 41.1% of the hydrofluoric acid market revenue in 2025, making it the largest regional market. The region is supported by its strong fluorochemical manufacturing base, abundant fluorspar resources, expanding semiconductor industry, and robust demand from metal processing and petroleum refining sectors.
Anhydrous is the fastest growing grade segment with a CAGR of 5.5% in the forecast period, supported by increasing demand from fluorochemical manufacturing, petroleum refining, and semiconductor applications, where high-purity anhydrous hydrofluoric acid is essential for efficient processing and superior product performance.
Metal pickling is the fastest growing application segment with a CAGR of 5.9% in the forecast period, due to increasing stainless steel production, expanding metal fabrication activities, and rising demand for high-quality surface treatment processes across automotive, construction, and industrial manufacturing sectors.
The global hydrofluoric acid market size was valued at USD 1.2 billion in 2025 and is estimated at USD 1.3 billion for 2026.
The global hydrofluoric acid market is expected to grow at a CAGR of 5.4% from 2026 to 2033, reaching USD 1.9 billion by 2033.
By grade, anhydrous segment dominated the form segment with a market share of 57.8% in 2025,due to its extensive use in fluorochemical manufacturing, petroleum refining, and semiconductor processing, where high-purity hydrofluoric acid is essential.
Some prominent players in the Hydrofluoric Acid market include Daikin; Dongyue Group; Sinochem; Yingpeng Chemical; Honeywell International Inc.; Stella Chemifa Corp.; Koura Global; Lanxess; Solvay.
The hydrofluoric acid market is primarily driven by rising demand from the fluorochemical industry, particularly for the production of refrigerants and fluorinated derivatives. Increasing semiconductor manufacturing, petroleum refining activities, and stainless steel pickling applications are also supporting sustained market growth across key industrial regions.
About the Author(s)
Organic Chemicals Research Team
Bulk Chemicals · Organic ChemicalsThis report was authored by the organic chemicals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the organic chemicals segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


