
- Home
- »
- Advanced Interior Materials
- »
-
Investment Casting Market Size, Growth Report, 2026-2033GVR Report cover

Investment Casting Market (2026 - 2033)
Size, Share & Trends Analysis Report By Material (Alumina-based, Zirconia-based), By Application (Aerospace & Defense, Oil & Gas, Medical, Mechanical Engineering, Automation, Transportation), By Region, And Segment Forecasts
Market Size, 2025
$17.4BMarket Estimate, 2026
$18.3BMarket Forecast, 2033
$24.9BCAGR, 2026–2033
4.5%Investment Casting Market Summary
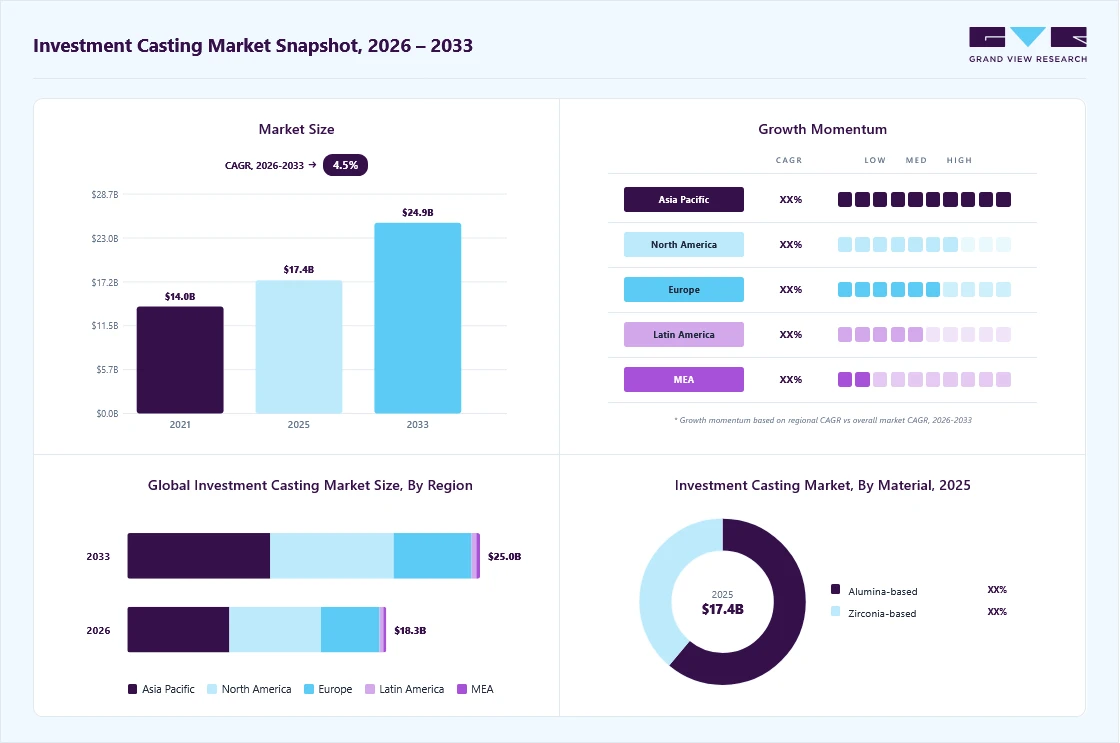
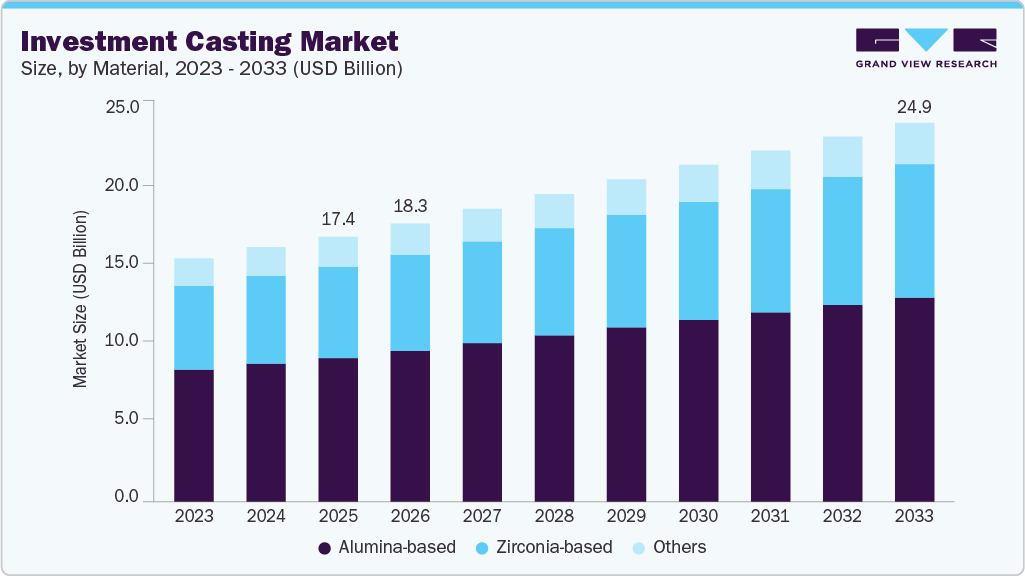
The global investment casting market size was valued at USD 17.4 billion in 2025 and is projected to grow from USD 18.3 billion in 2026 to USD 24.9 billion by 2033, at a CAGR of 4.5% from 2026 to 2033. Asia Pacific dominated the global market, accounting for the largest revenue share of 39.2% in 2025. The market is growing steadily due to rising aerospace, automotive, and industrial demand.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By material: Alumina-based segment accounted for the largest market revenue share of over 54% in 2025.
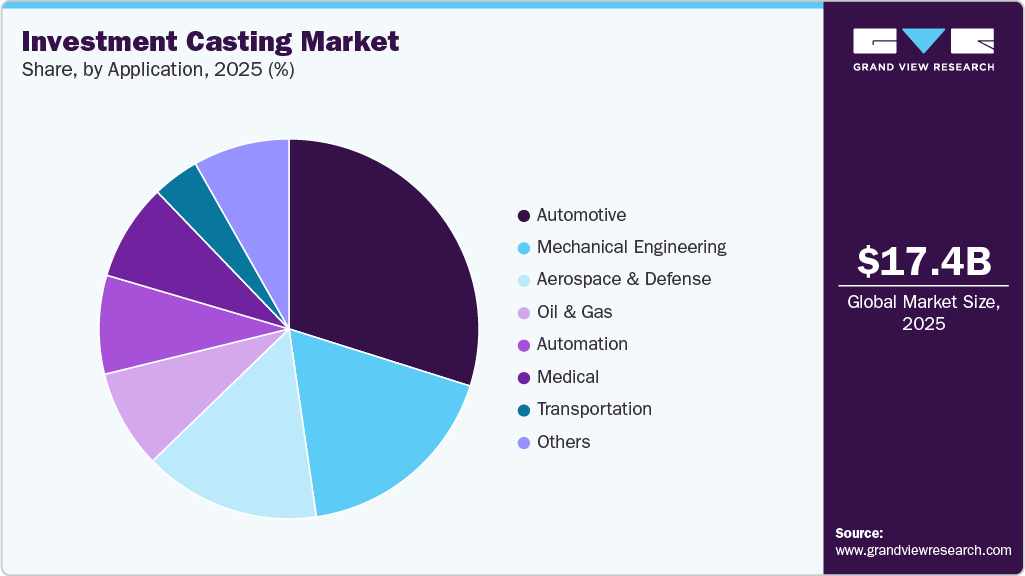
- By application: Automotive segment accounted for the largest market revenue share of over 29% in 2025.
Regional Highlights
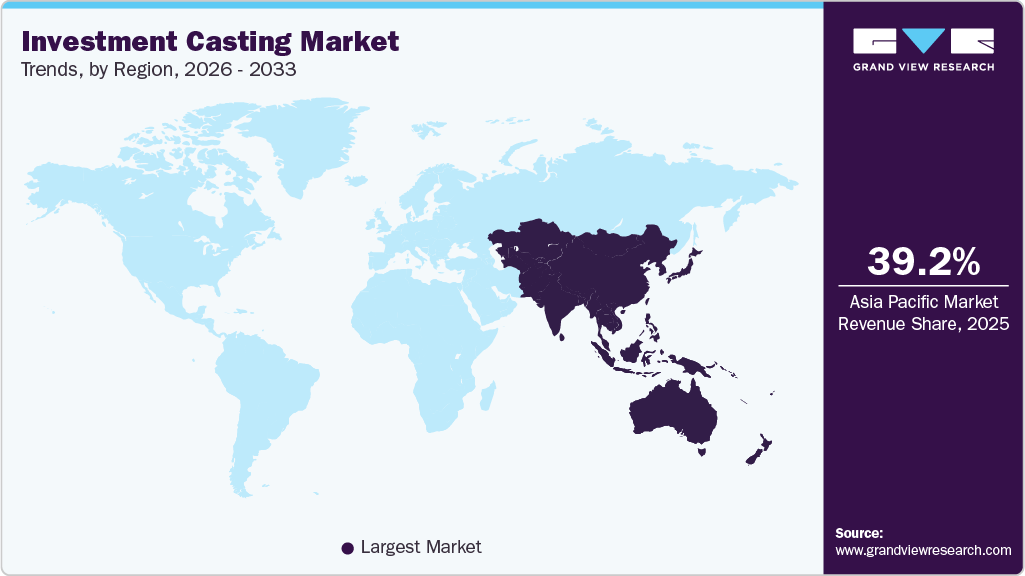
- Largest regional market: Asia Pacific (39.2% revenue share, 2025)
- By country: The China investment casting industry is a major contributor to the global market.
Market Size & Forecast
- Market size in 2025: USD 17.4 Billion
- Estimated market size in 2026: USD 18.3 Billion
- Projected market size by 2033: USD 24.9 Billion
- CAGR (2026-2033): 4.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
In 2025, global aircraft deliveries increased, with Boeing alone delivering 600 units in the year. At the same time, electric vehicle production reached around 17 million units worldwide, driven by rising EV adoption in China, the U.S., and Europe. These trends are boosting the need for lightweight, high-precision components that investment casting enables. Advancements in 3D printing and digital simulation are also making the process faster and more efficient, encouraging wider use across industries. Technological advancements are making the investment casting process faster, more precise, and cost-effective. Additive manufacturing is increasingly being used to create wax patterns or ceramic molds, shortening development timelines and reducing tooling costs. Computer-aided design (CAD), simulation tools, and automation enhance dimensional accuracy and consistency in complex parts. These developments are especially beneficial in industries with low tolerance for error, such as aerospace, medical devices, and defense.
 To learn more about this report, Download Free Sample Report
The medical device industry is another growing end-use segment for investment casting. With aging populations and rising healthcare access, demand for surgical instruments, dental fixtures, and orthopedic implants is increasing. Investment casting supports manufacturing bio-compatible, corrosion-resistant parts in stainless steel, titanium, and cobalt-chrome alloys. The technique offers design flexibility and a smooth surface finish, essential for medical applications requiring precision, cleanliness, and patient safety.
Lastly, the energy and industrial sectors further boost demand for investment cast parts. Applications in gas turbines, valves, impellers, and pump housings rely on the mechanical strength and thermal resistance that investment casting provides. As global infrastructure projects expand and renewable energy installations grow, especially in wind and thermal power, the need for robust and durable components is rising. Countries investing heavily in energy infrastructure, such as China, the U.S., and India, are expected to sustain long-term demand for investment cast components.
Drivers, Opportunities & Restraints
The investment casting industry is primarily driven by the growing demand for precision-engineered components in the aerospace, automotive, and medical sectors. As industries strive for lightweight yet high-performance parts, investment casting offers superior dimensional accuracy and intricate designs using a wide range of alloys. The surge in commercial aircraft production and the rising trend of electric vehicles have also accelerated the adoption of this casting process, especially for turbine blades, orthopedic implants, and engine components.
Several emerging opportunities are shaping the future of the investment casting industry. Integrating 3D printing for pattern making significantly reduces lead times and enhances customization capabilities. Demand is also rising in renewable energy applications, such as wind turbines and fuel cell components. In addition, expanding defense spending in various regions creates long-term prospects for castings used in weapon systems and naval ships. Emerging economies are investing in industrial infrastructure, further contributing to market growth.
Despite its advantages, the investment casting industry faces some restraints. High initial setup costs and longer production cycles than alternative methods can discourage small-scale manufacturers. Volatility in raw material prices, especially for specialty alloys, impacts cost predictability.
Material Insights
The growing demand for high-temperature, high-precision metal components is a major driver of alumina-based materials in investment casting. These materials are extensively used in ceramic shell systems due to their superior refractoriness, chemical stability, and resistance to molten metal penetration. Rising production of aerospace engines, industrial turbines, and advanced automotive components is increasing the use of alumina-based shells, particularly for casting stainless steel, titanium, and superalloys. In August 2025, multiple aerospace suppliers in India and Southeast Asia announced capacity expansions for precision-casting facilities to support increasing aircraft component localization programs, thereby directly strengthening demand for alumina-based refractory systems.
The growing production of high-performance alloys and reactive metals is a major growth driver for zirconia-based materials in investment casting. These materials provide excellent thermal stability and chemical inertness, making them suitable for prime coats used in aerospace, defense, and medical castings. In August 2025, suppliers like Doncasters announced the commissioning of new, fully automated shell lines to enhance the production capacity, quality, and reliability of components for the aerospace sector.
Application Insights
Investment casting delivers a range of core benefits that make it a preferred manufacturing process across high-precision industries. Its key strengths include exceptional dimensional accuracy and tight tolerances, often within ±0.003″-0.005″, which significantly reduces the need for post-machining and accelerates time-to-assembly in complex systems. The process also provides excellent surface finish and design flexibility, enabling components with intricate geometries, internal passages, and thin walls that would be difficult or impossible to produce with traditional sand or die casting methods. These attributes support a wide range of materials from stainless and carbon steels to high-performance superalloys, allowing engineers to tailor parts to specific performance requirements.
 To learn more about this report, Download Free Sample Report
Rising investments in aerospace and defense manufacturing infrastructure continue to support the development of specialized investment casting facilities worldwide. Governments and private manufacturers are increasingly prioritizing the localized production of critical components, such as turbine blades, structural housings, and propulsion parts, to strengthen supply chain resilience. These projects focus on improving access to high-quality superalloy and titanium castings that meet stringent aviation and defense certification standards.
Regional Insights
Asia Pacific accounted for the largest market revenue share of over 39.2% in 2025. The market in the Asia Pacific is witnessing strong growth due to rising demand from automotive, aerospace, and industrial machinery sectors across countries like China, India, Japan, and South Korea. The growing focus on lightweight, fuel-efficient vehicles and the increasing production of complex engine and structural components are pushing manufacturers to adopt investment casting. The medical sector is also expanding, with greater demand for precision instruments and implants, while energy and infrastructure projects continue to require durable, high-performance metal components.
 To learn more about this report, Download Free Sample Report
North America Investment Casting Market Trends
The investment casting market in North America is experiencing steady growth due to the region's strong aerospace and defense sector. Aircraft manufacturers increasingly use investment casting techniques to produce high-precision, complex metal components that meet strict performance and safety standards. The demand for lightweight yet durable parts in jet engines, turbines, and structural assemblies has encouraged manufacturers to adopt investment casting for its ability to deliver intricate geometries with minimal material waste. In addition, defense fleets' modernization programs support sustained procurement of high-performance cast components, strengthening market growth.
The investment casting market in the U.S. is driven by the country’s robust aerospace manufacturing base, which places a premium on lightweight, high-strength components with complex geometries. Major aircraft and defense contractors rely on investment casting to meet the precise specifications required for turbine blades, fuel system parts, and airframe structures. The growth of commercial aviation and continued defense spending contribute to steady order volumes for cast parts. Technological advancements in ceramic molds and metal alloys are also enhancing the performance and efficiency of cast components, reinforcing their use across aerospace platforms.
Europe Investment Casting Market Trends
The investment casting market in Europe is experiencing growth, contributed to by the defense and medical industries. Defense contractors require durable, high-performance components for military aircraft, naval systems, and armored vehicles. Investment casting enables the production of intricate parts with tight tolerances that meet strict reliability and strength standards. At the same time, the expanding medical sector across Western and Northern Europe is increasing the demand for precision surgical tools, dental devices, and orthopedic implants. These applications require smooth finishes and biocompatible materials, making investment casting an ideal manufacturing method.
Latin America Investment Casting Market Trends
The investment casting market in Latin America is experiencing gradual growth driven by expanding industrial activity and transportation manufacturing, especially in countries like Brazil and Mexico. Automotive production is rising as global automakers increase investments in regional manufacturing hubs, leading to greater demand for precision-cast components such as engine parts, brake systems, and suspension assemblies. Mechanical engineering applications dominate the current market share, with components used in pumps, valves, and heavy machinery seeing consistent demand across agriculture, construction, and manufacturing sectors.
Middle East & Africa Investment Casting Market Trends
The investment casting market in the Middle East & Africa is growing due to steady demand from the oil and gas sector, which forms the industrial backbone of countries like Saudi Arabia, the UAE, and Qatar. These industries require precision-cast components such as valves, turbine blades, and pump housings that can withstand harsh operating conditions. Investment casting offers the accuracy and material strength needed for such critical applications. As oilfield services and energy infrastructure continue to expand, the need for durable and complex metal parts supports ongoing growth in the market.
Key Investment Casting Company Insights
Some of the key players operating in the market include Alcoa Corporation, Impro Precision Industries Limited, and others.
-
Alcoa Corporation is a major American materials company with deep roots in the global aluminum industry. The company has grown into a vertically integrated producer that spans bauxite mining, alumina refining, aluminum smelting and casting, and related energy operations. This broad value chain enables the company to serve a wide range of markets, including automotive, aerospace, industrial, packaging, and construction, while also advancing sustainability commitments, such as lower-carbon production and expanded use of low-emission products.
-
Impro Precision Industries Limited is a global manufacturer of high-precision, high-complexity, and mission-critical components used across diverse sectors, including automotive, aerospace, medical, energy, and industrial markets. Founded in 1998, the company has grown into one of the world’s leading producers of precision components by integrating casting, machining, and surface treatment services within a unified business model that supports customers from design through delivery.
Key Investment Casting Companies:
The following key companies have been profiled for this study on the investment casting market.
- Alcoa Corporation
- CIREX
- Dongying Giayoung Precision Metal Co., Ltd.
- Impro Precision Industries Limited
- JW CASTING
- MetalTek
- Milwaukee Precision Casting
- Precision Castparts Corp.
- RLM Industries, Inc.
- Uni Deritend Ltd
- WANGUAN
- ZOLLERN GmbH & Co. KG
Recent Development
-
In September 2024, 3D Systems introduced QuickCast Air, a new advanced software tool in its investment casting portfolio, specifically designed to optimize material removal from the interior of casting patterns. This innovation significantly reduces material consumption, lowers pattern production costs, speeds up build times, and improves the burnout process and draining efficiency. The technology allows foundries and manufacturers, particularly in sectors like aerospace, defense, and energy, to produce large, high-precision investment casting patterns much faster and at a fraction of the cost associated with traditional tooling, all without constraints on geometric complexity.
Investment Casting Market Report Scope
Report Attribute
Details
Market size in 2025
USD 17.4 billion
Estimated Market size in 2026
USD 18.3 billion
Projected Market size by 2033
USD 24.9 billion
Growth rate
CAGR of 4.5% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative Units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, competitive landscape, growth factors, and trends
Segments covered
Material, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; Russia; France; Spain; Italy; China; India; Japan; South Korea; Australia; Singapore; Brazil; Argentina; Saudi Africa; UAE
Key companies profiled
Alcoa Corporation; CIREX; Dongying Giayoung Precision Metal Co., Ltd.; Impro Precision Industries Limited; JW CASTING; MetalTek,; Milwaukee Precision Casting; Precision Castparts Corp.; RLM Industries, Inc.; Uni Deritend Ltd.; WANGUAN; ZOLLERN GmbH & Co. KG
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Investment Casting Market Report Segmentation
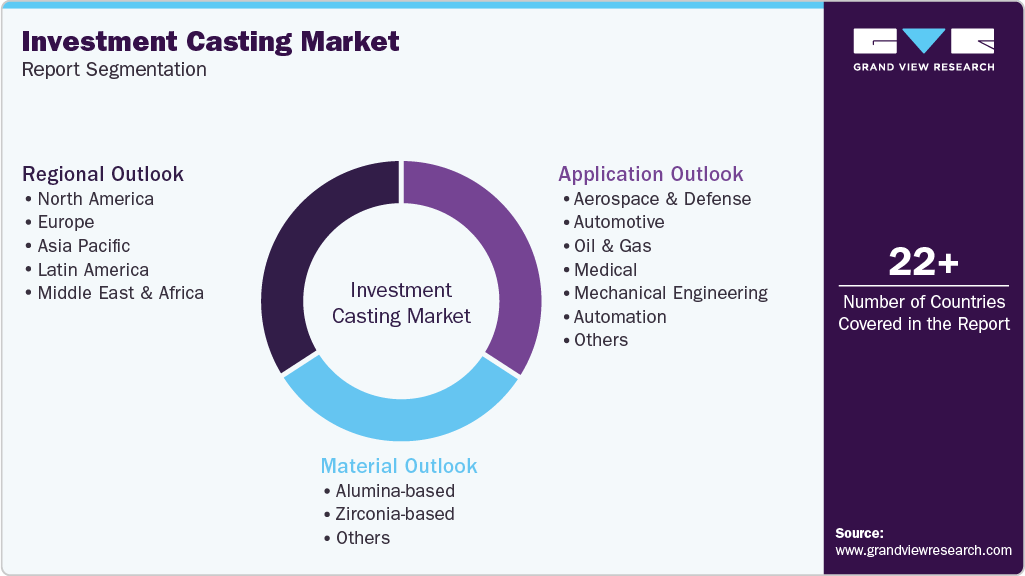
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global investment casting market report based on material, application, and region:
 To learn more about this report, Download Free Sample Report
-
Material Outlook (Revenue, USD Million, 2021 - 2033)
-
Alumina-based
-
Tabular Alumina
-
White Fused Alumina
-
Calcined Alumina
-
Others
-
-
Zirconia-based
-
Fused Silica-based
-
Other Oxides
-
Non-Oxides
-
-
Others
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Aerospace & Defense
-
Automotive
-
Oil & Gas
-
Medical
-
Mechanical Engineering
-
Automation
-
Transportation
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
Russia
-
France
-
Spain
-
Italy
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
Singapore
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Africa
-
UAE
-
-
Frequently Asked Questions About This Report
The global investment casting market size was valued at USD 17.4 billion in 2025 and is estimated at USD 18.3 billion for 2026.
The global investment casting market is expected to grow at a CAGR of 4.5% from 2026 to 2033, reaching USD 24.9 billion by 2033.
The automotive segment dominated the market with a revenue share of over 29.0% in 2025.
Key players include Alcoa Corporation; CIREX; Dongying Giayoung Precision Metal Co., Ltd.; Impro Precision Industries Limited; JW CASTING; MetalTek,; Milwaukee Precision Casting; Precision Castparts Corp.; RLM Industries, Inc.; Uni Deritend Ltd.; WANGUAN; ZOLLERN GmbH & Co. KG.
The global investment casting market is driven by rising demand for precision-engineered components in aerospace, automotive, and medical sectors. Advancements in casting technologies and material capabilities further support market growth.
Asia Pacific dominated with a 39.2% revenue share in 2025.
Alumina-based segment held the largest share (over 54.0%) in 2025.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


