
- Home
- »
- Medical Devices
- »
-
Kidney Transplant Market Size And Share Report, 2026-2033GVR Report cover

Kidney Transplant Market (2026 - 2033)
Size, Share & Trends Analysis Report By Transplant Type (Living Donor, Deceased Donor), By Preservation Method (Static Cold Storage, Hypothermic Machine Perfusion, Normothermic Machine Perfusion), By Region, And Segment Forecasts
Market Size, 2025
$9.8BMarket Estimate, 2026
$10.5BMarket Forecast, 2033
$17.2BCAGR, 2026–2033
7.3%Kidney Transplant Market Summary
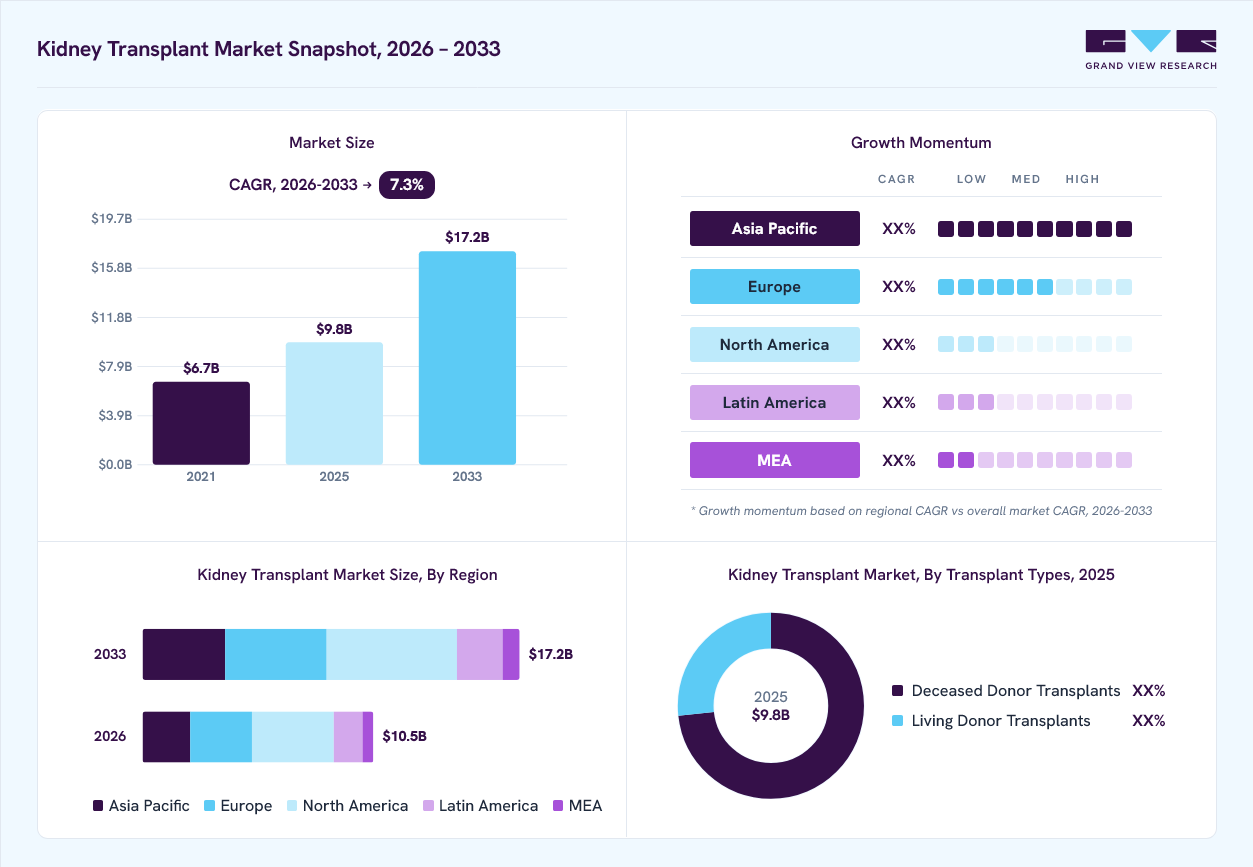
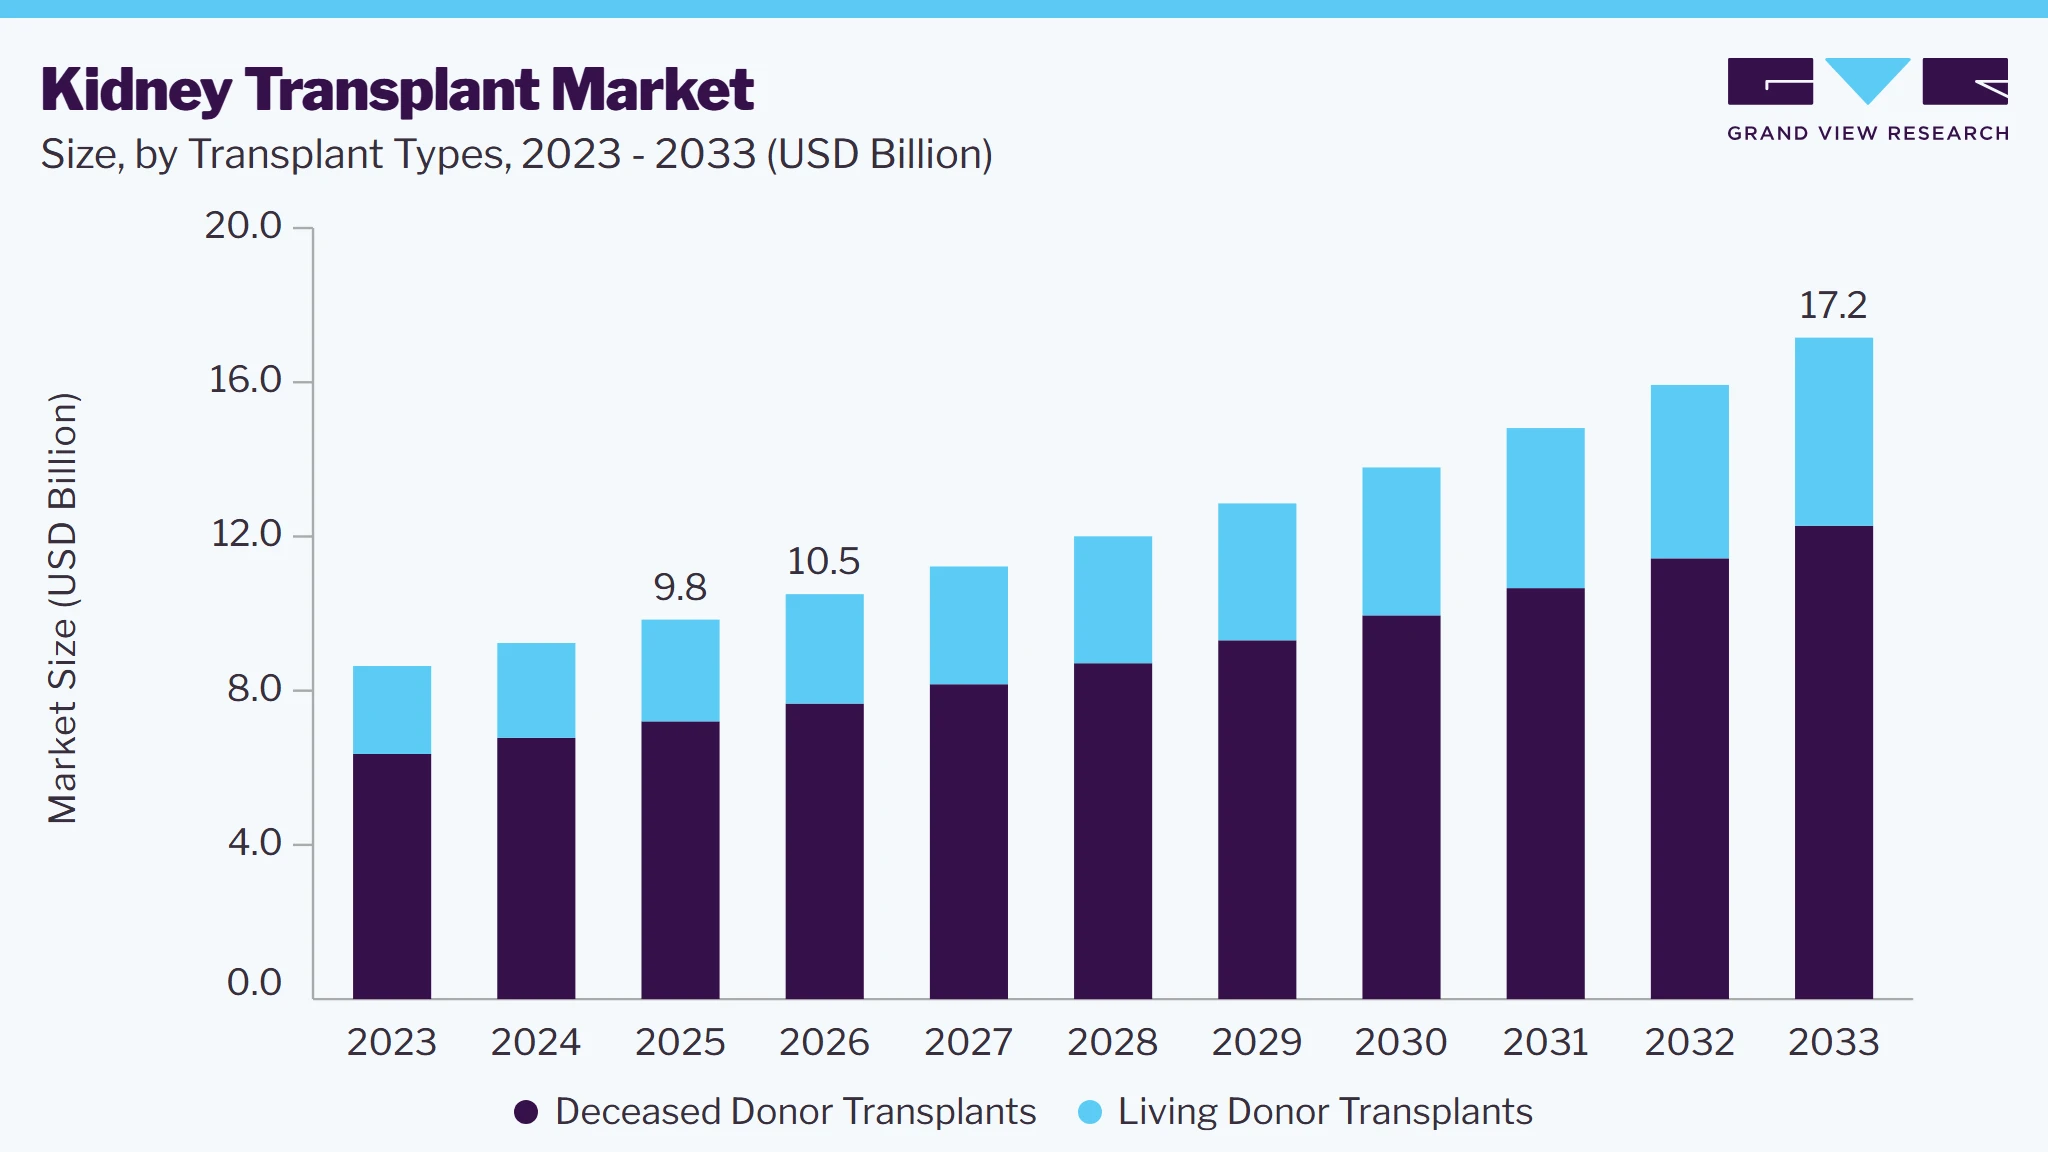
The global kidney transplant market size was valued at USD 9.8 billion in 2025 and is projected to grow from USD 10.5 billion in 2026 to USD 17.2 billion by 2033, at a CAGR of 7.3% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 35.6% in 2025. The market is driven by the increasing prevalence of end-stage renal disease (ESRD) and chronic kidney conditions worldwide, which heighten the demand for transplants.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By transplant type: Deceased donor transplants segment dominated the market, with a revenue share of 73.2% in 2025.
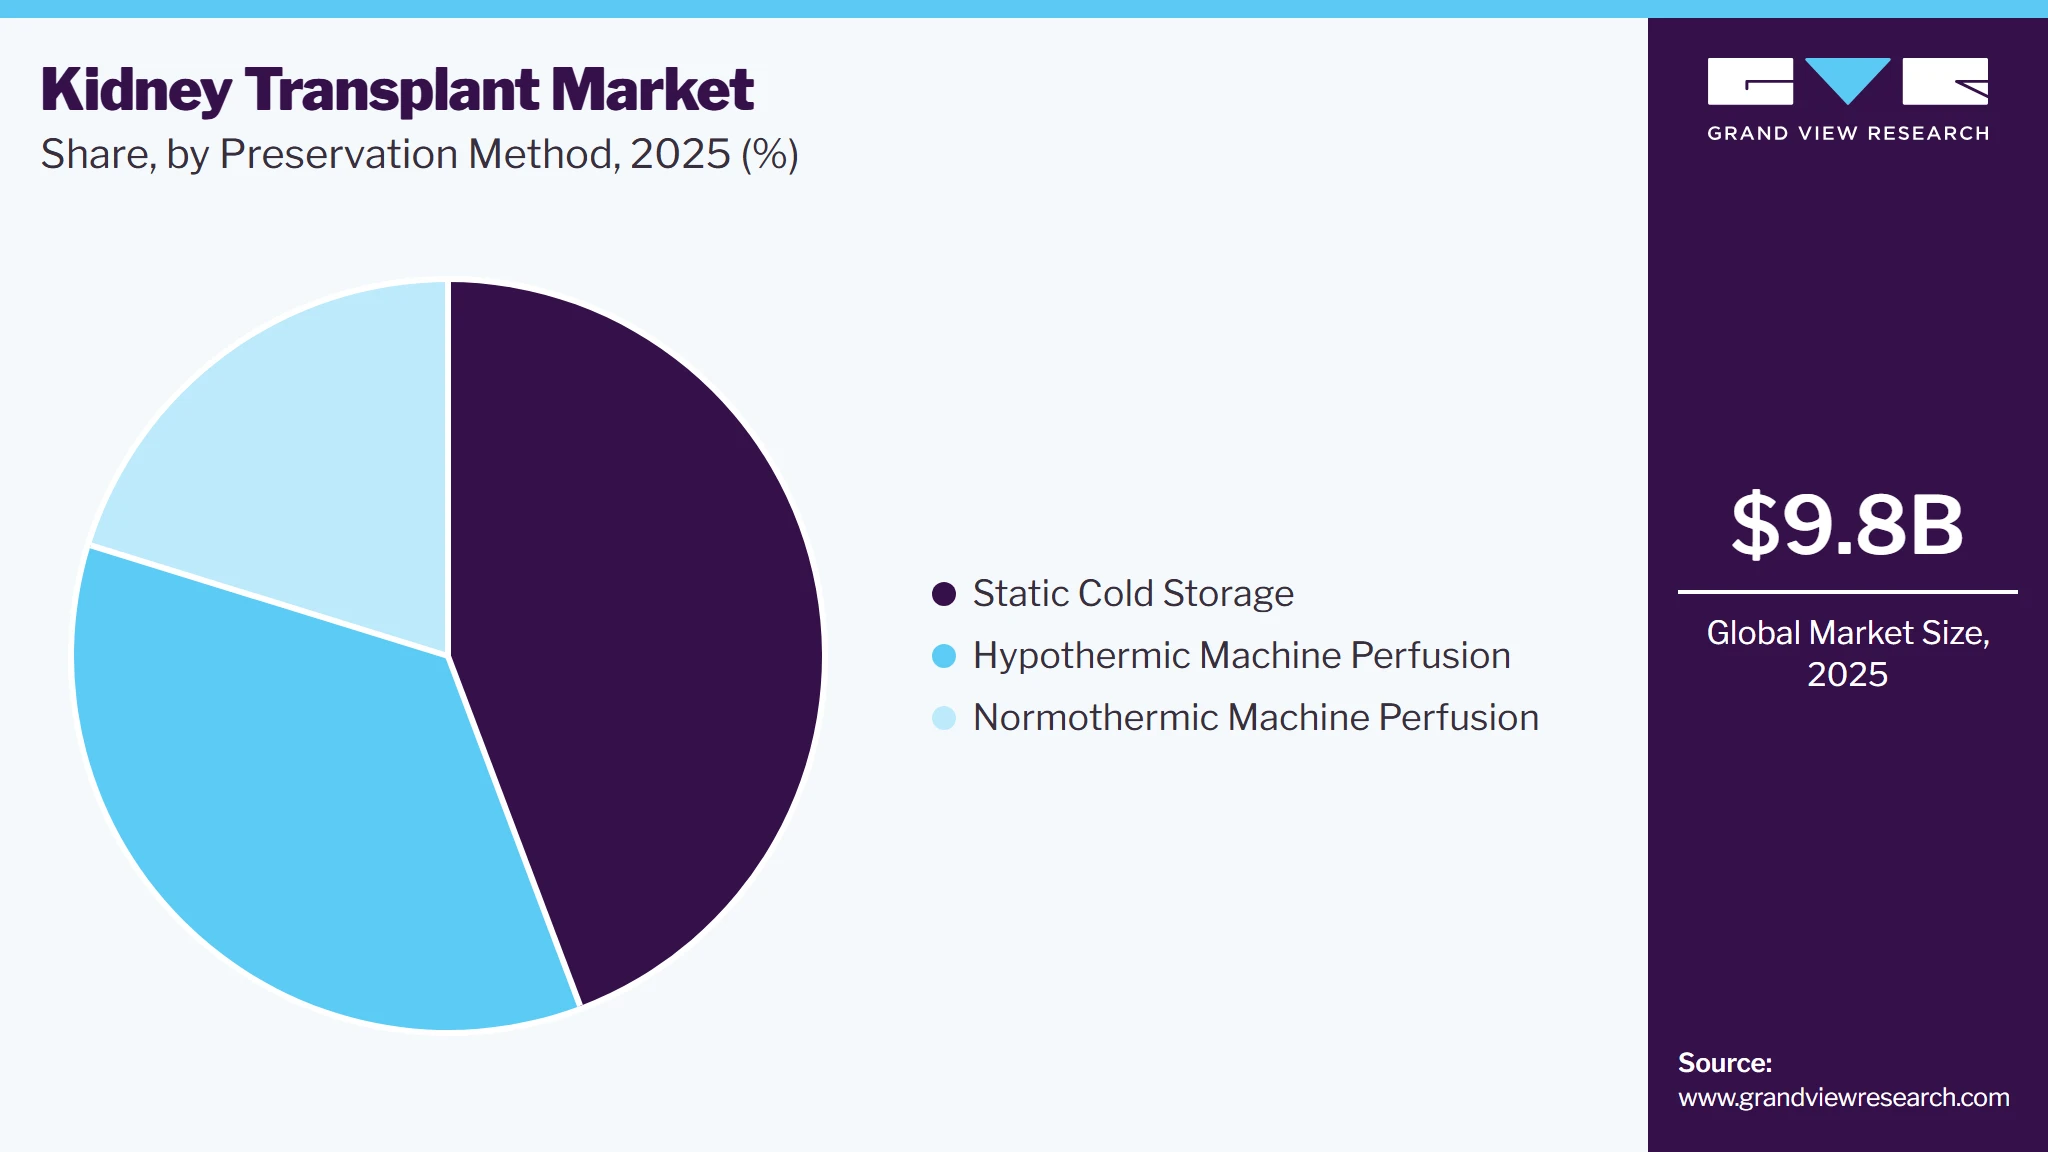
- By preservation method: static cold storage (SCS) segment held the largest market share of 44.3% in 2025.
Regional Highlights
- Largest regional market: North America (35.6% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 9.8 Billion
- Estimated market size in 2026: USD 10.5 Billion
- Projected market size by 2033: USD 17.2 Billion
- CAGR (2026-2033): 7.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Advancements in surgical techniques, immunosuppressive drugs, and organ preservation technologies have significantly improved outcomes, further boosting the market. Rising awareness of organ donation, government initiatives, and supportive healthcare policies encourage higher transplant rates. However, challenges like organ shortages and high treatment costs persist.
The kidney transplant market is characterized by increasing demand due to the rising prevalence of chronic kidney disease (CKD) and end-stage kidney disease (ESKD), driven by underlying conditions such as diabetes and hypertension. According to the Centers for Disease Control and Prevention, 1 in 7 Americans, or 37 million people, suffer from CKD. Many are unaware of their condition until it progresses to a critical stage, requiring dialysis or a kidney transplant. Dialysis, while life-sustaining, is not a cure and comes with severe side effects, such as infection and cardiovascular strain. For these patients, kidney transplantation remains the only curative option.
 To learn more about this report, Download Free Sample Report
However, the demand for kidneys far exceeds supply, creating a critical shortage. In the U.S. alone, over 90,000 people are currently on the kidney transplant waiting list, yet a thousand patients are removed from the list monthly because they either succumb to their illness or become too sick for transplantation. While most transplants (approximately two-thirds) come from deceased donors, living donors account for around 6,000 transplants annually. Altruistic donors, who donate to strangers, contribute only 300 to 400 kidneys each year, highlighting the challenge of finding compatible living donors. As of 2020, only 14.2% of ESKD patients had access to a living donor, further underscoring the scarcity of suitable donors.
In regions like Jordan, the shortage is exacerbated by the lack of a functional brain death donation program and limited living donors. Patients face prolonged wait times and uncertainty. To address this challenge, innovative strategies like Kidney Paired Exchange (KPE) are being implemented. KPE allows living donors who are incompatible with their intended recipient to donate their kidney to another recipient in need, creating a chain of compatible transplants. This system expands transplant opportunities for patients who would otherwise remain on the waiting list.
The kidney transplant market continues to evolve, with research and development efforts focused on alternative solutions such as xenotransplantation and 3D bioprinting to address long-term challenges. These advancements, coupled with collaborative global initiatives, aim to reduce the disparity between organ supply and demand, offering hope to millions of patients worldwide.
Market Dynamics
The kidney transplant market is witnessing steady growth due to increased prioritization of kidney transplantations as the first-line modality for treating ESKD by healthcare systems. Kidney transplantation is a surgical procedure that involves replacing a diseased kidney with a healthy kidney from a living or deceased donor. Kidney transplantation is associated with better survival rates, improved quality of life and reduction in long-term reliance on dialysis therapy. Market includes living and deceased kidney transplantation procedures aided by innovative techniques of organ preservation such as SCS, HMP and NMP that have a significant impact on organ viability, reduction of ischemic damage and improvement of graft performance before transplantation. Increasing prevalence of chronic kidney disease, growing need for organ transplantation, increased organ donation rates and adoption of innovative techniques of organ preservation are some of the factors contributing to market growth. Additionally, innovations in machine perfusion systems, organ preservation solutions, real-time organ monitoring and transplant logistics are leading to increased donor organs utilization, reduction of DGF and improved transplant outcomes.
With the rising burden of CKD and ESKD along with the rising awareness about the clinical and financial advantages of kidney transplantation over dialysis, there is a strong force behind the demand for kidney transplantations. The governments and other health care bodies are working hard on developing initiatives in the organ donations, transplant infrastructure, and donor-recipient matching system due to the growing transplant list. Additionally, the adoption of innovative techniques for organ preservation, especially machine perfusion techniques, has increased the use of kidneys from extended criteria and circulation death donors.
Despite advancements in transplantation and organ preservation, market growth continues to be constrained by the persistent shortage of donor kidneys relative to the growing number of patients awaiting transplantation. Moreover, the process of kidney transplantation involves a lot of healthcare expenses such as those incurred in procuring healthcare personnel, surgery, preservation technology, immunosuppressant drugs, post-transplantation follow-up, among others.
Market Concentration & Characteristics
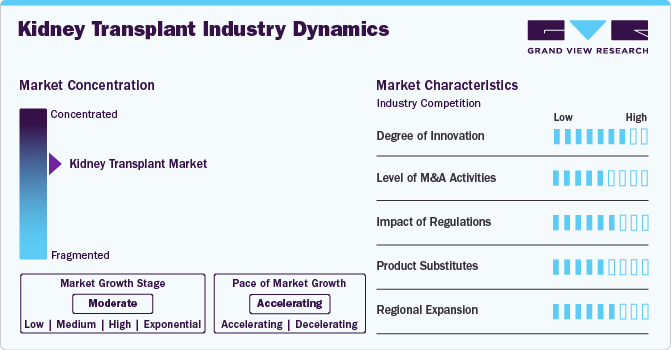
The kidney transplant market exhibits moderate industry concentration, with key players driving innovation and adoption of advanced organ preservation and transplantation technologies. TransMedics Group, Inc. is renowned for its Organ Care System, enabling optimized organ preservation and viability during transport. XVIVO specializes in advanced organ preservation solutions, enhancing organ functionality for transplantation. OrganOx Limited develops normothermic perfusion devices like metra, improving the preservation and assessment of kidneys before transplant. These companies address challenges like organ shortages and optimize transplant success rates. Their contributions significantly influence market growth by improving outcomes and accessibility in the global kidney transplant ecosystem.
The kidney transplant industry saw a significant advancement in May 2024, as a study revealed a potential treatment for antibody-mediated rejection (AMR), a primary cause of transplant failure. Led by Georg Böhmig and Katharina Mayer from MedUni Vienna, the trial involved 22 patients treated with felzartamab, a monoclonal antibody initially designed for multiple myeloma. The randomized, placebo-controlled study demonstrated promising outcomes, showing that felzartamab effectively improved kidney transplant results. After six months, biopsy and molecular analyses confirmed the drug’s potential as a safe and efficient solution for combating AMR in kidney transplants.
 To learn more about this report, Download Free Sample Report
Regulations are essential in the kidney transplant industry, ensuring patient safety, transplant efficacy, and ethical practices. They govern organ procurement, allocation, and transplant procedures, setting standards for donor matching, preservation, and post-transplant care. Strict regulations help minimize the risk of transplant-related complications and prevent organ trafficking. They also promote research and innovation, ensuring that new treatments and technologies, such as gene editing and immunotherapies, undergo rigorous testing before approval. By fostering transparency and accountability, regulations contribute to the sustainability of the kidney transplant market and improve patient outcomes globally.
Mergers and acquisitions (M&A) play a crucial role in shaping the kidney transplant industry by allowing companies to diversify their portfolios, expand their market presence, and drive innovation. For instance, in September 2021, Sanofi finalized a merger with Kadmon Holdings, Inc., a biopharmaceutical company focused on developing therapies for unmet medical needs. This acquisition aligns with Sanofi’s strategy to grow its General Medicines assets and enhance its transplant portfolio by adding Rezurock (belumosudil).
In the kidney transplant industry, alternatives to traditional transplant procedures are emerging. One key substitute is the development of bioengineered kidneys and advanced dialysis technologies, which aim to reduce reliance on organ donations. Research into stem cell therapies and xenotransplantation, such as transplanting genetically modified pig kidneys, also offers potential solutions to address the organ shortage. Additionally, wearable artificial kidneys and implantable devices are being explored as substitutes to enhance patients' quality of life and provide temporary or long-term renal function support. These innovations are gradually shaping the future of kidney transplant alternatives.
The kidney transplant market is witnessing significant growth globally, with advancements in medical technology and increased access to transplant services. For example, Nizam’s Institute of Medical Sciences (NIMS) in Hyderabad completed 1,000 kidney transplants over the past decade. In 2024, they performed 101 transplants, including 55 from living donors and 46 from deceased donors. These procedures were provided free of charge through the Aarogyasri program, funded by the Telangana government. Established in 1989, the NIMS renal transplant program has accelerated since 2015 with the Jeevandan cadaver transplant initiative, significantly expanding its reach and impact in the region.
Analyst Perspective
There are major changes occurring in the kidney transplant market due to the efforts being made by the healthcare industry towards making effective use of the organs, ensuring the survival of the grafts and increasing the accessibility of the transplantation process. Although the static cold storage method is widely utilized in preserving donor organs, there is increased interest in hypothermic and normothermic machine perfusion based on the medical evidence available about the effectiveness of such techniques. The manufacturers are continually making improvements in their devices which include portable perfusion units, automated preservation devices, oxygenated perfusion and digital organ monitoring solutions among others. With government backing of organ donation programs and increased use of innovative preservation technology, there will be continuous growth in the kidney transplant market.
Transplant Type Insights
Based on transplant types, the deceased donor transplants segment led the market with the largest revenue share of 73.2% in 2025. This is due to the rising prevalence of end-stage renal disease (ESRD), expanded organ donation programs, and advancements in organ preservation technologies. The adoption of hypothermic and normothermic machine perfusion (HMP & NMP) has significantly improved organ viability, reducing discard rates and enhancing transplant success. Additionally, the increasing use of Donation after Circulatory Death (DCD) kidneys, AI-driven organ matching, and innovative biomarker-based viability assessments are expanding the donor pool. With continued policy initiatives, technological innovations, and regenerative medicine advancements, the market is expected to witness steady growth, improving accessibility and outcomes for patients in need of kidney transplants.
The living donor transplants segment is projected to grow at the fastest CAGR during the forecast period. The segment is driven by the increasing demand for transplants due to the rising prevalence of end-stage renal disease (ESRD) and long waiting times for deceased donor kidneys. Advancements in minimally invasive donor nephrectomy (including robotic-assisted surgery) have made donation safer and more appealing. Additionally, growing public awareness, government incentives, and post-donation support programs are encouraging more individuals to become living donors, improving transplant success rates and long-term patient outcomes.
Preservation Method Insights
Based on preservation method, the static cold storage (SCS) segment led the market with the largest revenue share of 44.3% in 2025. This is primarily owing to its cost-effectiveness, simplicity, and ability to maintain organ viability for up to 24-36 hours. It is the preferred choice for long-distance organ transportation, ensuring broad accessibility for transplant centers. Advancements in preservation solutions like UW (University of Wisconsin), HTK (Histidine-Tryptophan-Ketoglutarate), and Celsior have improved kidney viability by minimizing ischemic damage. Research into oxygenation-enhanced storage and metabolic support additives is further refining SCS efficiency. Despite the rise of perfusion-based alternatives, SCS remains dominant due to its low infrastructure requirements and proven reliability in kidney transplantation.
 To learn more about this report, Download Free Sample Report
The normothermic machine perfusion (NMP) segment is expected to grow at the fastest CAGR during the forecast period. The segment growth is majorly driven by its ability to enhance organ viability and improve post-transplant outcomes, especially for marginal and extended criteria donor (ECD) kidneys. Unlike cold storage, NMP maintains the kidney at physiological temperature, providing continuous oxygenation and nutrients, which helps reduce ischemia-reperfusion injury and allows for organ assessment before transplantation. The growing need to expand the donor pool, improve graft function, and reduce delayed graft function (DGF) is fueling NMP adoption. Advancements in real-time biomarker monitoring, portable perfusion devices, and AI-driven organ evaluation are further supporting its clinical integration.
Regional Insights
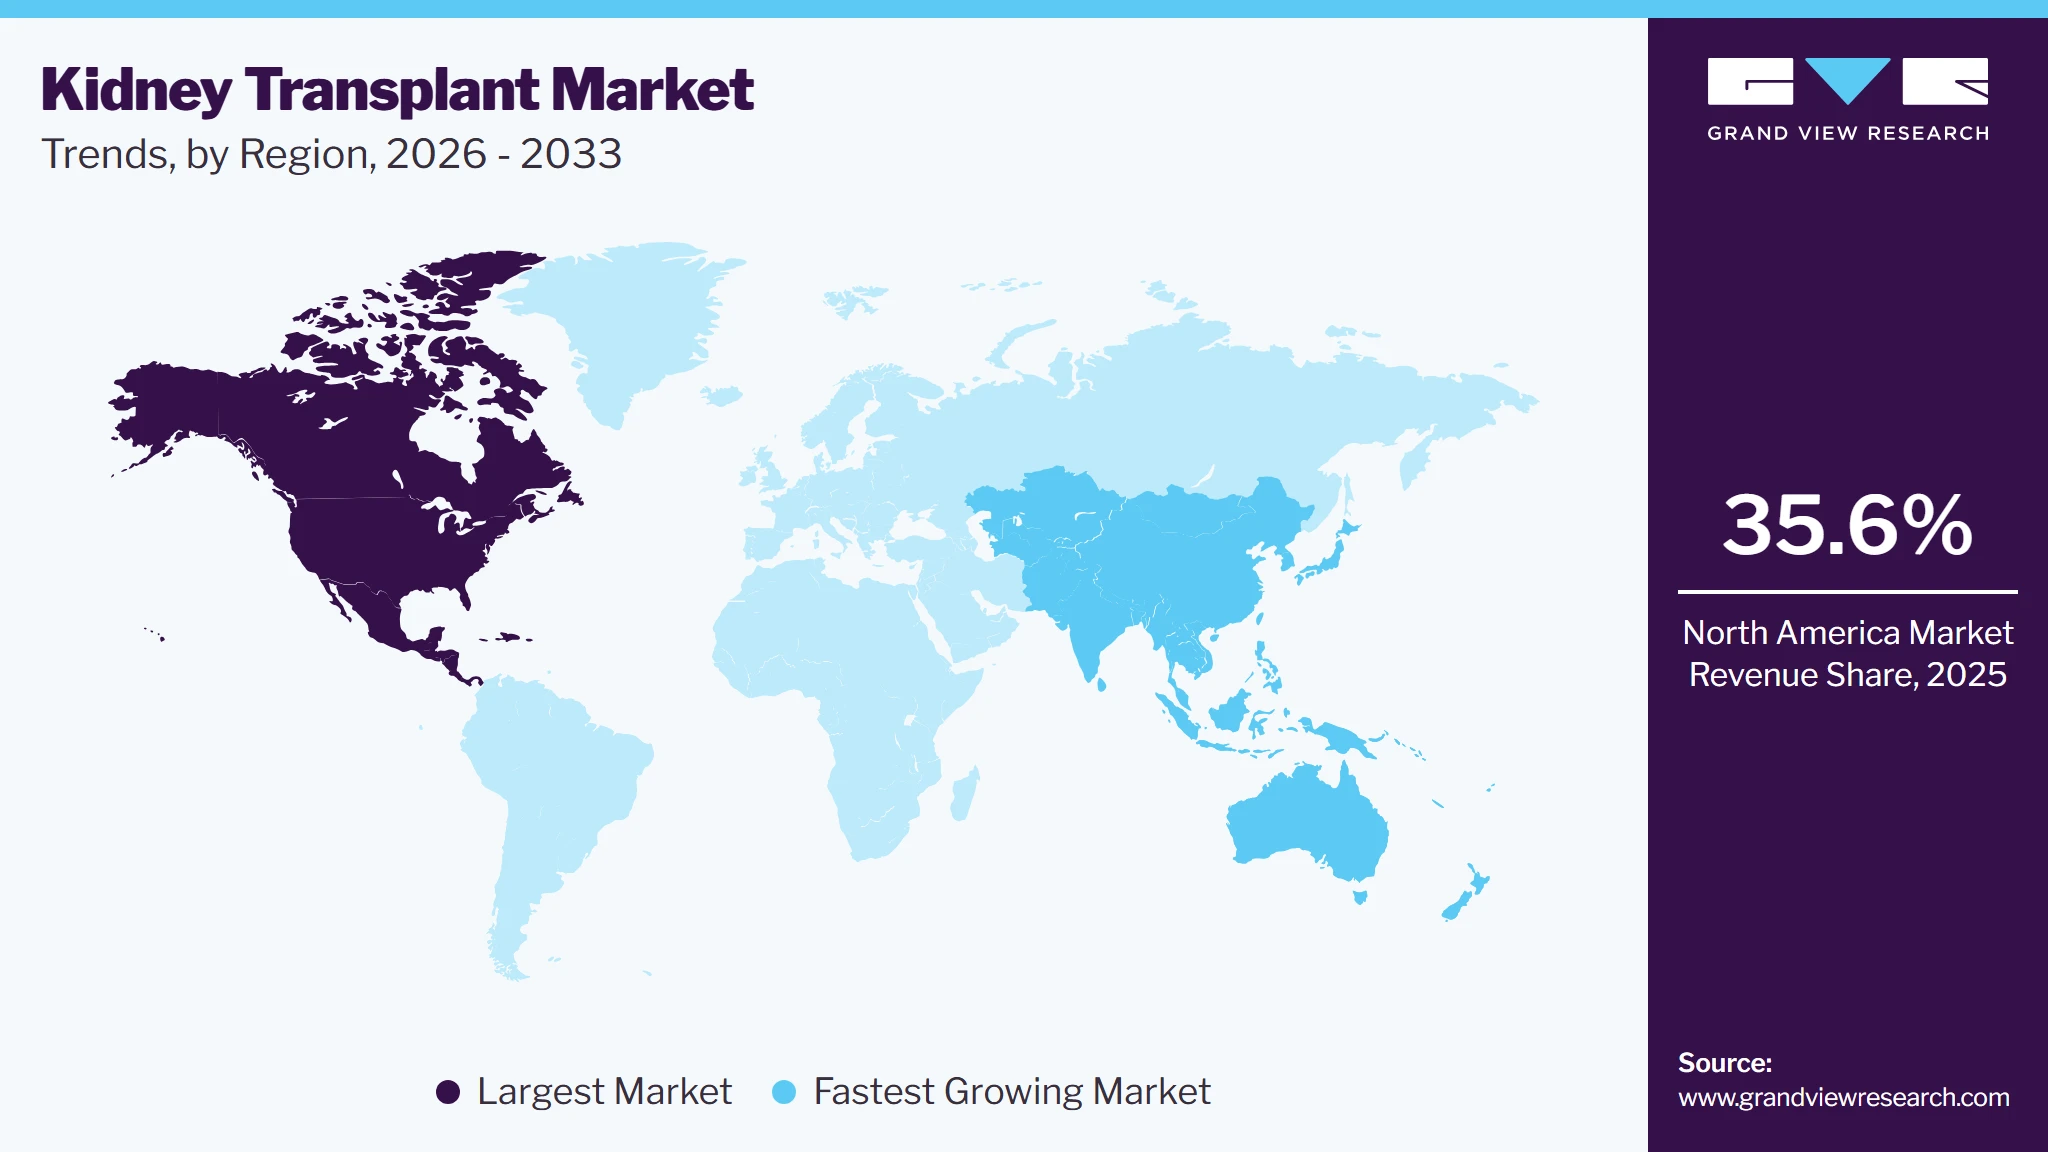
North America dominated the kidney transplant market with the largest revenue share of 35.6% in 2025. The region's dominance is attributed to advanced healthcare infrastructure and high surgical volumes. According to the American Hospital Association Statistics 2024, the U.S. has around 6,120 operational hospitals performing 40-50 million surgeries annually, including treatments for cardiovascular diseases, cancer, and trauma. These factors, coupled with increasing organ transplantation rates and innovative technologies, drive market growth. Additionally, strong support from organizations like UNOS and robust organ donation programs enhance transplant accessibility, further solidifying North America’s leading position in the global kidney transplant market.
 To learn more about this report, Download Free Sample Report
U.S. Kidney Transplant Market Trends
The kidney transplant market in the U.S. held the largest share in the North America region in 2025. The U.S. kidney transplant market is set to grow, supported by one of the world’s most effective organ donation and recovery systems. UNOS collaborates with the organ donation community to enhance outcomes and save lives. In 2023, over 6,900 living donor transplants occurred, with many donating kidneys and some contributing liver segments. Deceased donors exceeded 16,000, yet the demand remains high, with 104,799 people needing lifesaving transplants, including 59,029 active waiting list candidates. A total of 46,630 transplants and 23,286 donors (living and deceased) were recorded from January to December 2023, reflecting ongoing efforts to address this critical need.
Europe Kidney Transplant Market Trends
The European kidney transplant market is anticipated to expand in the forecast period, mainly due to the widespread prevalence of chronic diseases, which account for 80% of the total disease burden in the EU (as of December 11, 2024). LUMC became the first European hospital to administer reprogrammed stem cells to patients receiving new donor kidneys. The initial phase of the study aims to assess the safety of the therapy, while future research will explore its potential in preventing donor kidney rejection.
The UK kidney transplant market is growing significantly, driven by the rising prevalence of chronic diseases like diabetes and an aging population. The UK Department of Health & Social Care projects a one-million increase in individuals aged 85+ between 2021 and 2036. As of March 2024, 5,898 patients awaited kidney transplants, far exceeding those waiting for other organs. Liver transplant patients ranked second at 639, followed by 297 waiting for both kidney and pancreas transplants.
The kidney transplant market in France is growing, driven by significant healthcare investment ensuring high-quality, patient-centered services. In 2021, France allocated 12.31% of its GDP to healthcare (World Bank). With a population of 67 million (2020), France's universal healthcare system, funded through income-based taxation, reimburses 70% of general healthcare costs and 100% for costly or chronic conditions like chronic kidney disease (CKD). CKD affects nearly 3 million individuals, with a 2% annual increase in prevalence. Among these, 89,692 patients undergo dialysis or have received kidney transplants.
Germany kidney transplant market is supported by advancements like Oncocyte Corporation's October 2024 announcement regarding partnerships with top transplant hospitals in the U.S. and Germany. These institutions have adopted GraftAssure, a research-use-only assay detecting early graft damage through donor-derived cell-free DNA (dd-cfDNA). Oncocyte aims to commercialize its intellectual property by developing a kitted test and expanding its market presence. The “land-and-expand” strategy focuses on partnerships with transplant centers and research institutions to increase adoption of molecular diagnostics in the USD 1 billion transplant market. GraftAssure remains a research-use product, with FDA clearance sought for clinical application.
Asia Pacific Kidney Transplant Market Trends
The kidney transplant market industry in the Asia Pacific is anticipated to grow at the fastest CAGR from 2026 to 2033. The Asia Pacific kidney transplant market is expanding rapidly, driven by high healthcare expenditure and a growing aging population. North and East Asia, including Japan, South Korea, and Taiwan, have significant healthcare investments, with Japan spending 10.9% of its GDP on health. Taiwan leads globally in treated end-stage kidney disease (ESKD) prevalence. In South Korea, 108,873 patients received kidney replacement therapy (KRT) in 2019, with 19.4% undergoing kidney transplants. The region's shift from glomerulonephritis to metabolic diseases has increased ESKD cases. Government healthcare spending, comprising 50-60% of total expenditures, further supports the growing demand for kidney transplantation services.
The kidney transplant market in Japan is expanding as innovative approaches drive advancements. In October 2024, a Japanese medical team applied for approval to conduct a clinical study on temporary pig kidney transplants for unborn children with severe kidney disease. This groundbreaking procedure, the first in Japan, is slated for 2026. Led by Jikei University School of Medicine and the National Center for Child Development, the study involves injecting 2-millimeter pig kidneys into two unborn children diagnosed with Potter sequence, enabling urine production immediately after birth. Post-delivery, a tube will manage urine discharge, marking a significant step in transplant innovation.
The kidney transplant market in China is poised for growth in the Asia Pacific region. In December 2024, Chinese scientists achieved a breakthrough by successfully keeping a monkey alive for over six months with a single gene-edited pig kidney. The experiment, conducted at Tongji Hospital, involved transplanting the organ into a macaque monkey with removed kidneys. The kidney functioned normally for five months before complications arose due to immune rejection, highlighting challenges similar to human-to-human transplants, which require lifelong immunosuppressants. Led by Chen Gang, this achievement marks a benchmark for long-term survival, paving the way for clinical trials using pig organs, ideal due to their size and metabolic similarities to human organs.
India’s kidney transplant market is poised for significant growth. As of November 2024, the country has approximately 600 kidney transplant centers, with 75 in the public sector and the rest privately operated. In 2023, India performed 13,642 kidney transplants-11,791 from living donors and 1,851 from deceased donors, including three cardiac death (DCD) donations, according to Dr. Anil Kumar (NOTTO). However, with an end-stage kidney disease (ESKD) burden affecting at least 200,000 patients annually in a population of 1.5 billion, these figures reveal a substantial gap between demand and supply.
Latin America Kidney Transplant Trends
The kidney transplant market in Latin America is dominated by Brazil and Argentina. Between January and November 2021, Brazil conducted over 12,000 organ transplants, ranking second globally after the U.S. This achievement persisted despite pandemic challenges, supported by Brazil's SUS, which provides comprehensive transplant care. Similarly, Argentina has performed 15,774 kidney transplants since 1998, with 89% in adults and 11% in children. Most transplants involve deceased donors, with strokes (52%) and traumatic brain injuries being the primary causes, highlighting the market's growing importance.
Middle East & Africa Kidney Transplant Market Trends
The kidney transplant market in the Middle East and Africa is advancing, driven by King Faisal Specialist Hospital and Research Centre (KFSHRC). Since 1981, KFSHRC has performed 5,000 transplants, including 80 pediatric procedures in 2023, the highest globally. Over 3,000 transplants have been conducted since 2010, with 1,250 in the last three years alone. Its Kidney Paired Donation program has revolutionized transplantation by addressing donor-patient compatibility issues. Advanced minimally invasive robotic surgeries enhance precision, while one-year survival rates range from 97% to 99%. KFSHRC is the leading transplant center in the region and ranks 20th globally in academic medical centers.
The kidney transplant market in Saudi Arabia is anticipated to expand in the forecast period, supported by the Saudi Center for Organ Transplantation’s efforts. The second phase of the National Kidney Exchange Program aims to raise living donor rates from 10% to 30%, reducing wait times and enhancing transplant success rates. The "Minna W Feena" program is a crucial initiative, offering improved treatment options and alleviating the challenges faced by kidney failure patients in the Kingdom.
Key Kidney Transplant Company Insights
The competitive scenario in the kidney transplant market is highly competitive, with key players such as TransMedics Group, Inc., XVIVO, and OrganOx Limited holding significant positions. The major companies are undertaking various organic as well as inorganic strategies such as new product development, collaborations, acquisitions, mergers, and regional expansion for serving the unmet needs of their customers.
Key Kidney Transplant Companies
The following key companies have been profiled for this study on the kidney transplant market.
-
TransMedics Group, Inc.
-
XVIVO
-
OrganOx Limited
-
Paragonix Technologies
-
Waters Medical Systems
-
Organ Recovery Systems
-
Bridge to Life Ltd.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (XVIVO, Organ Recovery Systems, Bridge to Life Ltd.)
Established companies focus on comprehensive organ preservation portfolios comprising machine perfusion systems, preservation solutions, disposable perfusion consumables, and transplant logistics technologies. They emphasize clinical evidence generation, regulatory approvals, global transplant partnerships, and continuous innovation in preservation technologies.
Strong relationships with transplant centers and organ procurement organizations, broad preservation product portfolios, established clinical validation, and recurring revenue from consumables and service contracts. Extensive experience in organ preservation supports long-term market leadership.
Dependence on transplant procedure volumes, limited donor organ availability, lengthy regulatory pathways, and capital purchasing cycles may constrain revenue growth. Premium pricing can also limit adoption among smaller transplant programs.
Emerging Players (TransMedics Group, OrganOx Limited, Paragonix Technologies, Waters Medical Systems)
Emerging companies prioritize next-generation portable perfusion systems, real-time organ monitoring, automated preservation technologies, and innovative transport solutions. They focus on expanding clinical indications, improving organ utilization, and strengthening partnerships with transplant centers globally.
Innovative preservation platforms, rapid technology development, growing clinical evidence, and expanding adoption of portable machine perfusion systems enable these companies to gain market share in advanced organ preservation.
Smaller installed base, limited commercialization outside key markets, dependence on regulatory approvals, and relatively limited global service infrastructure compared with established competitors.
Recent Developments
-
In November 2024, the United Therapeutics Corporation announced the world's first successful transplant of a UKidney into a living human. This milestone follows previous successful xenotransplants, including two UHeart transplants in 2022 and 2023, and a UThymoKidney transplant earlier in 2024.
-
In September 2024, eGenesis secured USD 191 million in Series D funding to advance its lead product, EGEN-2784, into first-in-human kidney transplant studies. The financing, led by Lux Capital, will also support pipeline development and production scaling. This follows their March 2024 milestone of the first successful porcine kidney transplant in a living patient.
Kidney Transplant Market Report Scope
Report Attribute
Details
Market size in 2025
USD 9.8 billion
Estimated market size in 2026
USD 10.5 billion
Projected market size by 2033
USD 17.2 billion
Growth rate
CAGR of 7.3% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Transplant type, preservation method, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; South Korea; Thailand; Australia; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
TransMedics Group, Inc.; XVIVO; OrganOx Limited; Paragonix Technologies; Waters Medical Systems; Organ Recovery Systems; Bridge to Life Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Kidney Transplant Market Report Segmentation
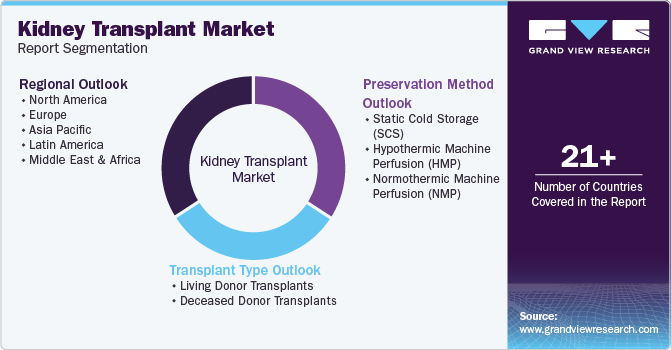
This report forecasts revenue growth at country levels and provides an analysis on the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the kidney transplant market report based on transplant type, preservation method, and region:
 To learn more about this report, Download Free Sample Report
-
Transplant Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Living Donor Transplants
-
Deceased Donor Transplants
-
Donation after Brain Death (DBD)
-
Donation after Circulatory Death (DCD)
-
-
-
Preservation Method Outlook (Revenue, USD Million, 2021 - 2033)
-
Static Cold Storage (SCS)
-
Hypothermic Machine Perfusion (HMP)
-
Normothermic Machine Perfusion (NMP)
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The kidney transplant market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each kidney transplant segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Transplant Types
Revenue capture definition
Living Donor Transplants
Revenue is generated through utilization of organ preservation systems, preservation solutions, disposable perfusion consumables, and transport accessories supporting planned living donor kidney transplantation. Manufacturers benefit from demand for reliable preservation technologies that maintain graft quality during procurement and implantation while optimizing surgical scheduling and transplant outcomes.
Deceased Donor Transplants
Revenue is derived from preservation technologies utilized for kidneys recovered from deceased donors, including expanded criteria and donation after circulatory death (DCD) organs. Market participants generate recurring revenue through machine perfusion systems, preservation solutions, disposable perfusion sets, monitoring accessories, and service agreements supporting higher transplant volumes and improved organ utilization.
Segment - Preservation Method
Revenue capture definition
Static Cold Storage (SCS)
Revenue is generated through preservation solutions, sterile storage containers, transport devices, and cold storage accessories used to preserve donor kidneys between procurement and transplantation. Manufacturers benefit from widespread adoption due to its simplicity, low cost, and established clinical practice.
Hypothermic Machine Perfusion (HMP)
Revenue is derived from hypothermic perfusion systems, disposable perfusion circuits, oxygenation modules, preservation solutions, and service contracts utilized to continuously perfuse donor kidneys at low temperatures. Manufacturers benefit from increasing adoption driven by improved graft preservation, reduced delayed graft function, and enhanced utilization of marginal donor organs.
Normothermic Machine Perfusion (NMP)
Revenue is generated through advanced normothermic perfusion platforms that maintain donor kidneys under near-physiological conditions while enabling functional assessment and viability testing prior to transplantation. Market participants capture premium revenue through capital equipment sales, disposable consumables, monitoring technologies, software, and maintenance services supporting next-generation organ preservation.
Estimation Model
Title
Guiding Question
Process Steps
Data Sources
Scope Definition
What is being studied?
- Define Kidney Transplant Market Scope - Scope Transplant Types, and Preservation Method Segments - Establish Geographic Coverage - Align base year & forecast horizon (2020-2030)
WHO, UNOS, Eurotransplant, OPTN
Estimate Kidney Transplant Volume
How large is total addressable market?
- Estimate Annual Living and Deceased Donor Kidney Transplant Procedures - Segment Transplant Volumes by Preservation Technology Utilized - Assess Adoption Rate by Preservation Method - Forecast Installed Base Growth
WHO, UNOS, Eurotransplant, OPTN
Estimate Technology Utilization
What portion of procedures use disposable devices?
- Assess Utilization of Preservation Technologies Across Transplant Centers - Evaluate Average Disposable Consumables Used per Transplant - Analyze Machine Utilization Ratios and Preservation Duration - Validate Through Industry Interviews
Primary research, clinical surveys, industry papers
Revenue Conversion
How does volume become revenue?
- Determine ASPs for Preservation Technology by Region - Estimate Revenue from Kits and Services - Apply Regional Pricing Variations - Cross-validate with Company Revenues and Public Findings
Primary research, distributor pricing sheets, government databases, company annual reports
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Landscape Analysis
Conducted a comprehensive competitive assessment of global kidney preservation technology providers, evaluating machine perfusion systems, preservation solutions, transport devices, disposable perfusion consumables, regulatory approvals, pricing strategies, clinical evidence, manufacturing capabilities, distribution networks, and ongoing technology innovations.
Enables stakeholders to understand technology leadership, competitive positioning, procurement dynamics, and commercialization strategies shaping the kidney transplant preservation market. Supports supplier benchmarking, investment planning, partnership evaluation, and product differentiation.
Segment by Application Analysis
Conducted a detailed assessment across living and deceased donor transplantation while evaluating adoption of static cold storage, hypothermic machine perfusion, and normothermic machine perfusion technologies. The study analyzed transplant volumes, technology penetration, preservation practices, procurement trends, and forecast demand by preservation method.
Enables stakeholders to identify high-growth preservation technologies, optimize product portfolios, prioritize commercialization strategies, and align innovation efforts with evolving transplant practices.
Macroeconomic Analysis
Conducted an in-depth assessment of chronic kidney disease prevalence, end-stage kidney disease incidence, organ donation rates, transplant funding, healthcare expenditure, reimbursement policies, transplant legislations, and investment in transplant infrastructure influencing demand for advanced kidney preservation technologies worldwide.
Enables stakeholders to understand the macroeconomic regulatory, demographic, and healthcare system factors influencing demand within the global kidney transplant preservation market. The study supported forecasting, manufacturing capacity planning, pricing strategy development, and regional expansion analysis.
Frequently Asked Questions About This Report
Asia Pacific is the fastest-growing region over the forecast period.
Deceased donor transplants segment dominated the market, with a revenue share of 73.2% in 2025.This is due to the rising prevalence of end-stage renal disease (ESRD), expanded organ donation programs, and advancements in organ preservation technologies.
The static cold storage (SCS) segment led the market with the largest revenue share of 44.3% in 2025 while normothermic machine perfusion (NMP) segment is second fastest growing market
The global kidney transplant market is expected to grow at a CAGR of 7.3% from 2026 to 2033, reaching USD 17.2 billion by 2033.
The global kidney transplant market size was valued at USD 9.8 billion in 2025 and is estimated at USD 10.5 billion in 2026.
Some key players operating in the kidney transplant market include TransMedics Group, Inc., XVIVO, OrganOx Limited, Paragonix Technologies, Waters Medical Systems, Organ Recovery Systems, Bridge to Life Ltd.
North America dominated the kidney transplant market with a share of 35.6% in 2025.
Key factors that are driving the kidney transplant market growth include growing organ donation awareness and initiatives, advancements in transplant techniques and immunosuppressive therapies, expanding use of machine perfusion technologies, and government and private funding support.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


