
- Home
- »
- Distribution & Utilities
- »
-
LPG Tankers Market Size, Share & Trends Report 2026-2033GVR Report cover

LPG Tankers Market (2026 - 2033)
Size, Share & Trends Analysis Report By Vessel Size (Large, Medium, Small), By Refrigeration & Pressurization (Ethylene, Full Refrigeration, Semi Refrigeration, Full pressurized), By Region, And Segment Forecasts
Market Size, 2025
$3.4BMarket Estimate, 2026
$3.6BMarket Forecast, 2033
$5.6BCAGR, 2026–2033
6.6%LPG Tankers Market Summary
The global LPG tankers market size was valued at USD 3.4 billion in 2025 and is projected to grow from USD 3.6 billion in 2026 to USD 5.6 billion by 2033, at a CAGR of 6.6% from 2026 to 2033. Europe dominated the market, accounting for a revenue share of 29.8% in 2025. A strong rise in shale gas production is likely to propel the market growth over the coming years.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By vessel size: Very large gas carriers segment dominated the market, with a revenue share of 28.1% in 2025.
- By refrigeration & pressurization: Full pressurized segment held the largest market share of 33.8% in 2025.
Regional Highlights
- Largest regional market: Europe (29.8% revenue share, 2025)
- By country: Russia held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 3.4 Billion
- Estimated market size in 2026: USD 3.6 Billion
- Projected market size by 2033: USD 5.6 Billion
- CAGR (2026-2033): 6.6%
Prism AI by Grand View Research Free to tryAsk a question about the LPG tankers marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Crude oil price volatility, coupled with developments in hydraulic fracturing and horizontal drilling methods resulted in major companies shifting their attention towards the production of oil and gas from shale rock. Change in focus on the production of shale gas is further projected to enhance market growth over the estimated period.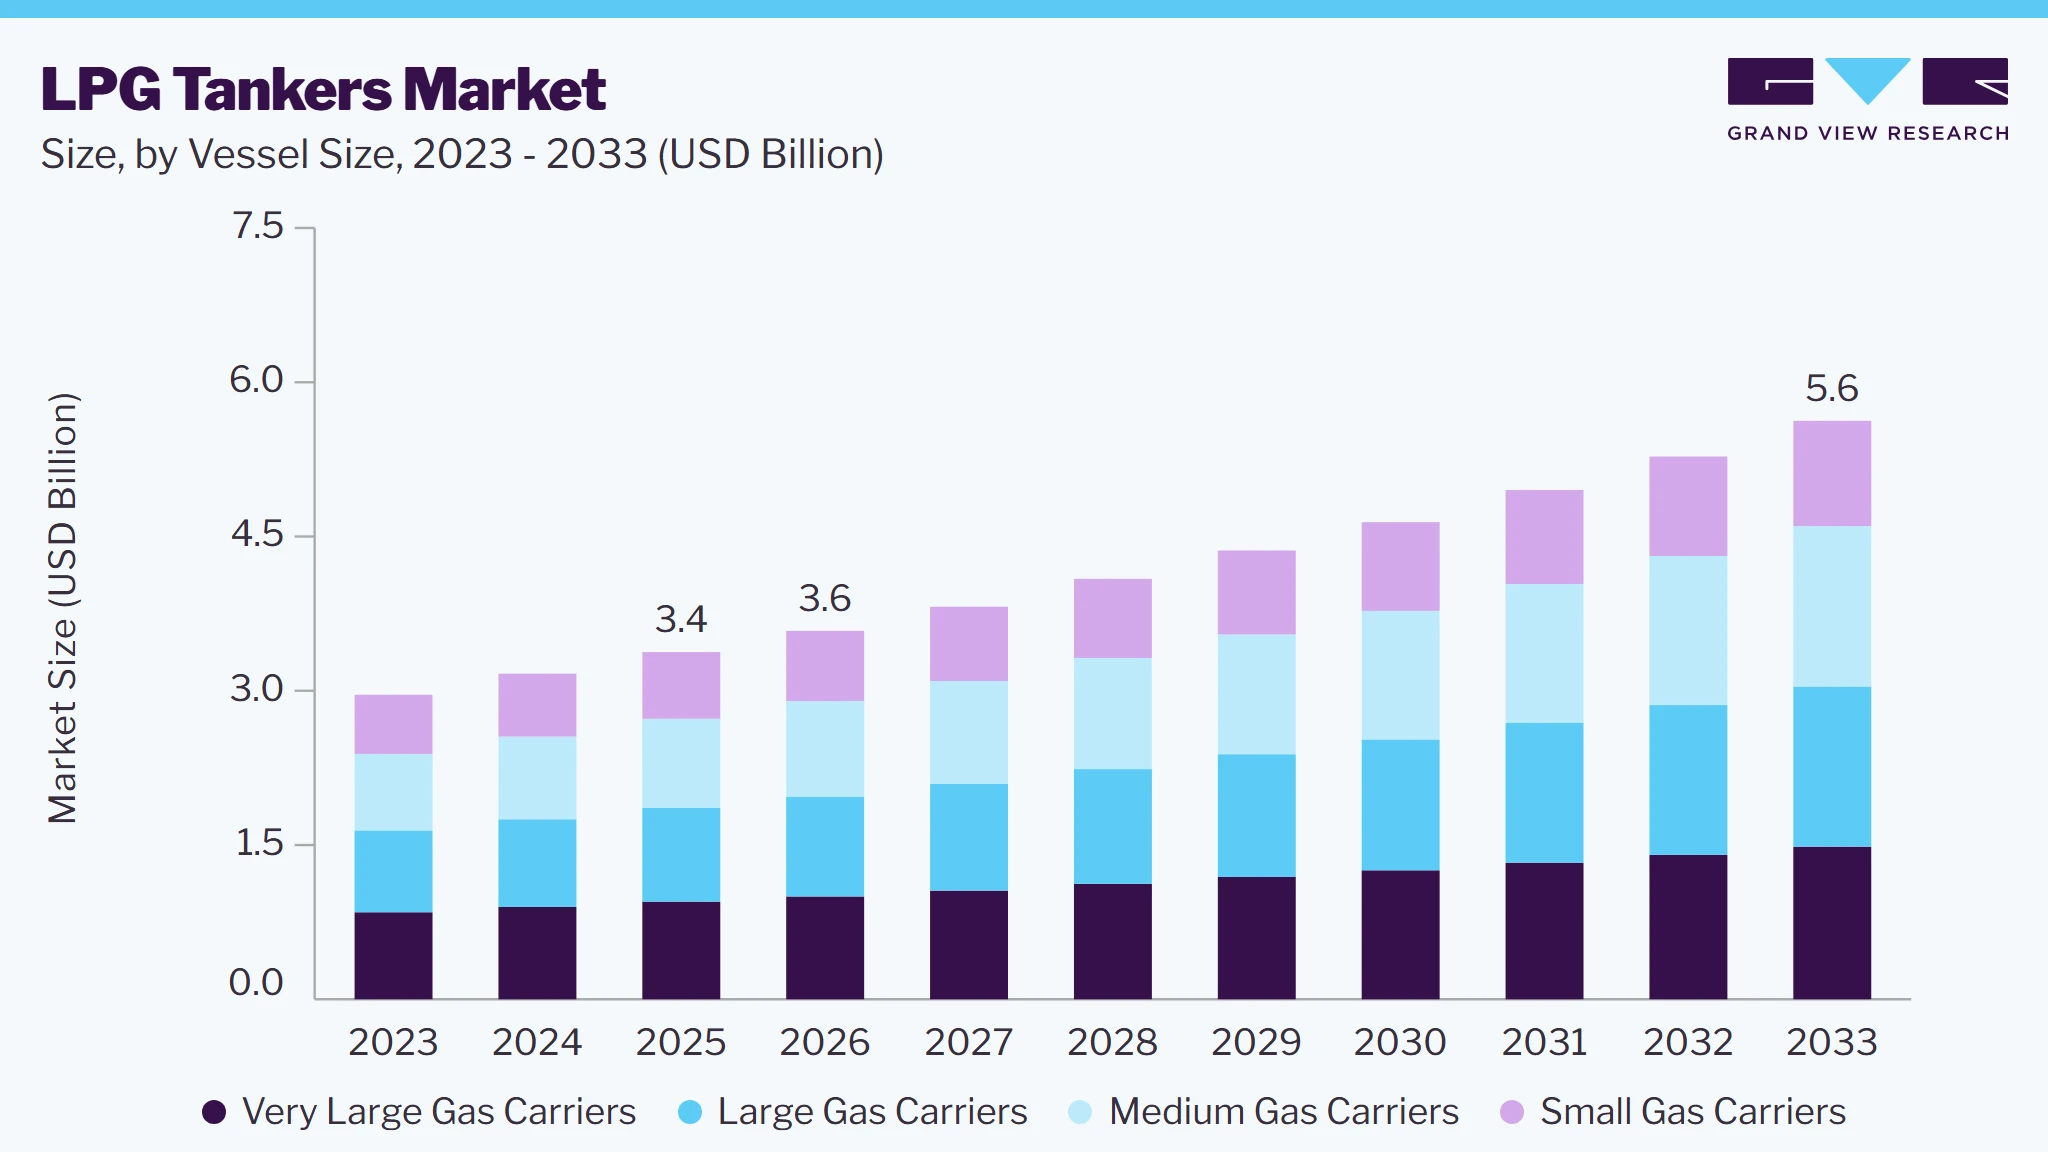 To learn more about this report, Download Free Sample Report
The growing trade relationships between the U.S. and the APAC region for shale gas, owing to the reduced cost of transportation, are likely to outgrow the demand for liquified petroleum gas (LPG) tankers over the forecast period.
 To learn more about this report, Download Free Sample Report
Instability in crude oil prices caused an increasing demand for liquefied petroleum gas from petrochemical industries, which is likely to fuel demand for liquefied petroleum gas tankers over the estimated period. However, volatile crude oil prices resulted in amplified prices of LPG, resulting in weaker demand, which is projected to hinder market growth over the projected period.
3 points
Market Dynamics
The LPG tankers market is primarily driven by rising investment in new LPG carrier construction, supported by the expansion of global seaborne liquefied petroleum gas (LPG) trade, rising LPG production, and expanding export and import infrastructure. Rising demand for very large gas carriers (VLGCs), large gas carriers (LGCs), medium gas carriers (MGCs), and small gas carriers (SGCs) is encouraging shipowners to expand and modernize their fleets, resulting in higher newbuild vessel orders. Furthermore, technological advancements in cargo containment systems, dual-fuel propulsion technologies, digital vessel management solutions, and fuel-efficient ship designs are improving operational efficiency, regulatory compliance, and environmental performance, thereby supporting long-term demand for new LPG tanker construction.
The continued growth in global LPG production and international seaborne trade is the primary driver of the LPG tankers market. Increasing LPG exports from major producing countries and rising import demand across the Asia Pacific, Europe, and other energy-importing regions are encouraging shipowners to invest in new LPG carriers to support fleet expansion and replacement. Expanding investments in LPG export terminals, import infrastructure, and marine transportation networks are further strengthening demand for new vessel procurement.
In addition, growing emphasis on fleet modernization is accelerating investments in technologically advanced LPG carriers equipped with dual-fuel propulsion systems, improved cargo containment technologies, digital fleet management platforms, and energy-efficient vessel designs. Increasing shipyard order books, long-term fleet renewal strategies, and the replacement of aging vessels continue to support new tanker construction and market growth.
The LPG tanker market faces challenges posed by stringent international regulations governing the design, construction, and operation of gas carriers. Compliance with safety, environmental, and emissions standards increases vessel development costs and extends construction timelines. In addition, fluctuations in steel prices and other critical shipbuilding materials increase manufacturing costs, reducing shipbuilders' profit margins and potentially delaying new vessel investments. Supply chain disruptions and limited shipyard capacity may further affect vessel delivery schedules.
Growing investments in fleet modernization present significant opportunities for the LPG tankers market. Shipowners are increasingly placing orders for next-generation LPG carriers featuring dual-fuel engines, advanced cargo containment systems, digital vessel management platforms, predictive maintenance technologies, and energy-efficient propulsion systems to improve operational performance and comply with evolving environmental regulations. Furthermore, increasing demand for low-emission vessels, ammonia-ready ship designs, and digitally integrated marine technologies is expected to create new opportunities for shipowners, shipbuilders, and marine equipment suppliers, supporting long-term growth in new LPG tanker sales.
Analyst Perspective
The LPG tankers market is witnessing steady growth driven by increasing global seaborne LPG trade, expanding export and import infrastructure, and rising demand for new LPG carriers. Growing LPG production and international trade are encouraging shipping companies to invest in very large, large, medium, and small gas carriers equipped with advanced cargo handling and fuel-efficient propulsion technologies. While fluctuations in shipbuilding material costs, evolving environmental regulations, and limited shipyard capacity remain key challenges, advancements in vessel design, cargo containment systems, and energy-efficient propulsion technologies are enhancing the performance and environmental compliance of new LPG tankers. Over the forecast period, companies that expand manufacturing capacity, invest in next-generation vessel technologies, and strengthen their global order books are expected to reinforce their competitive positions and capitalize on growing demand for new LPG tankers.
Vessel Size Insights
Based on vessel size, the very large gas carriers segment led the market with the largest revenue share of 28.1% in 2025. Very large gas carriers are widely used for the transportation of LPG for longer distances across various countries. Growing LPG trade relationships between countries, such as the Middle East and Asian countries, Western Africa and Europe, and the United States, is the major factor boosting the segment growth. However, the LGC is anticipated to take over the forecast period by a small margin. Large gas carriers also have a significant share in the global market.
In addition, the ongoing trade relationships between major LPG-producing nations and growing investments in shipbuilding technology are expected to further enhance the market's expansion. With a focus on environmental sustainability and innovations in carrier design, the VLGC market is well-positioned to capitalize on the rising global energy demands and shifting fuel preferences.
Refrigeration & Pressurization Insights
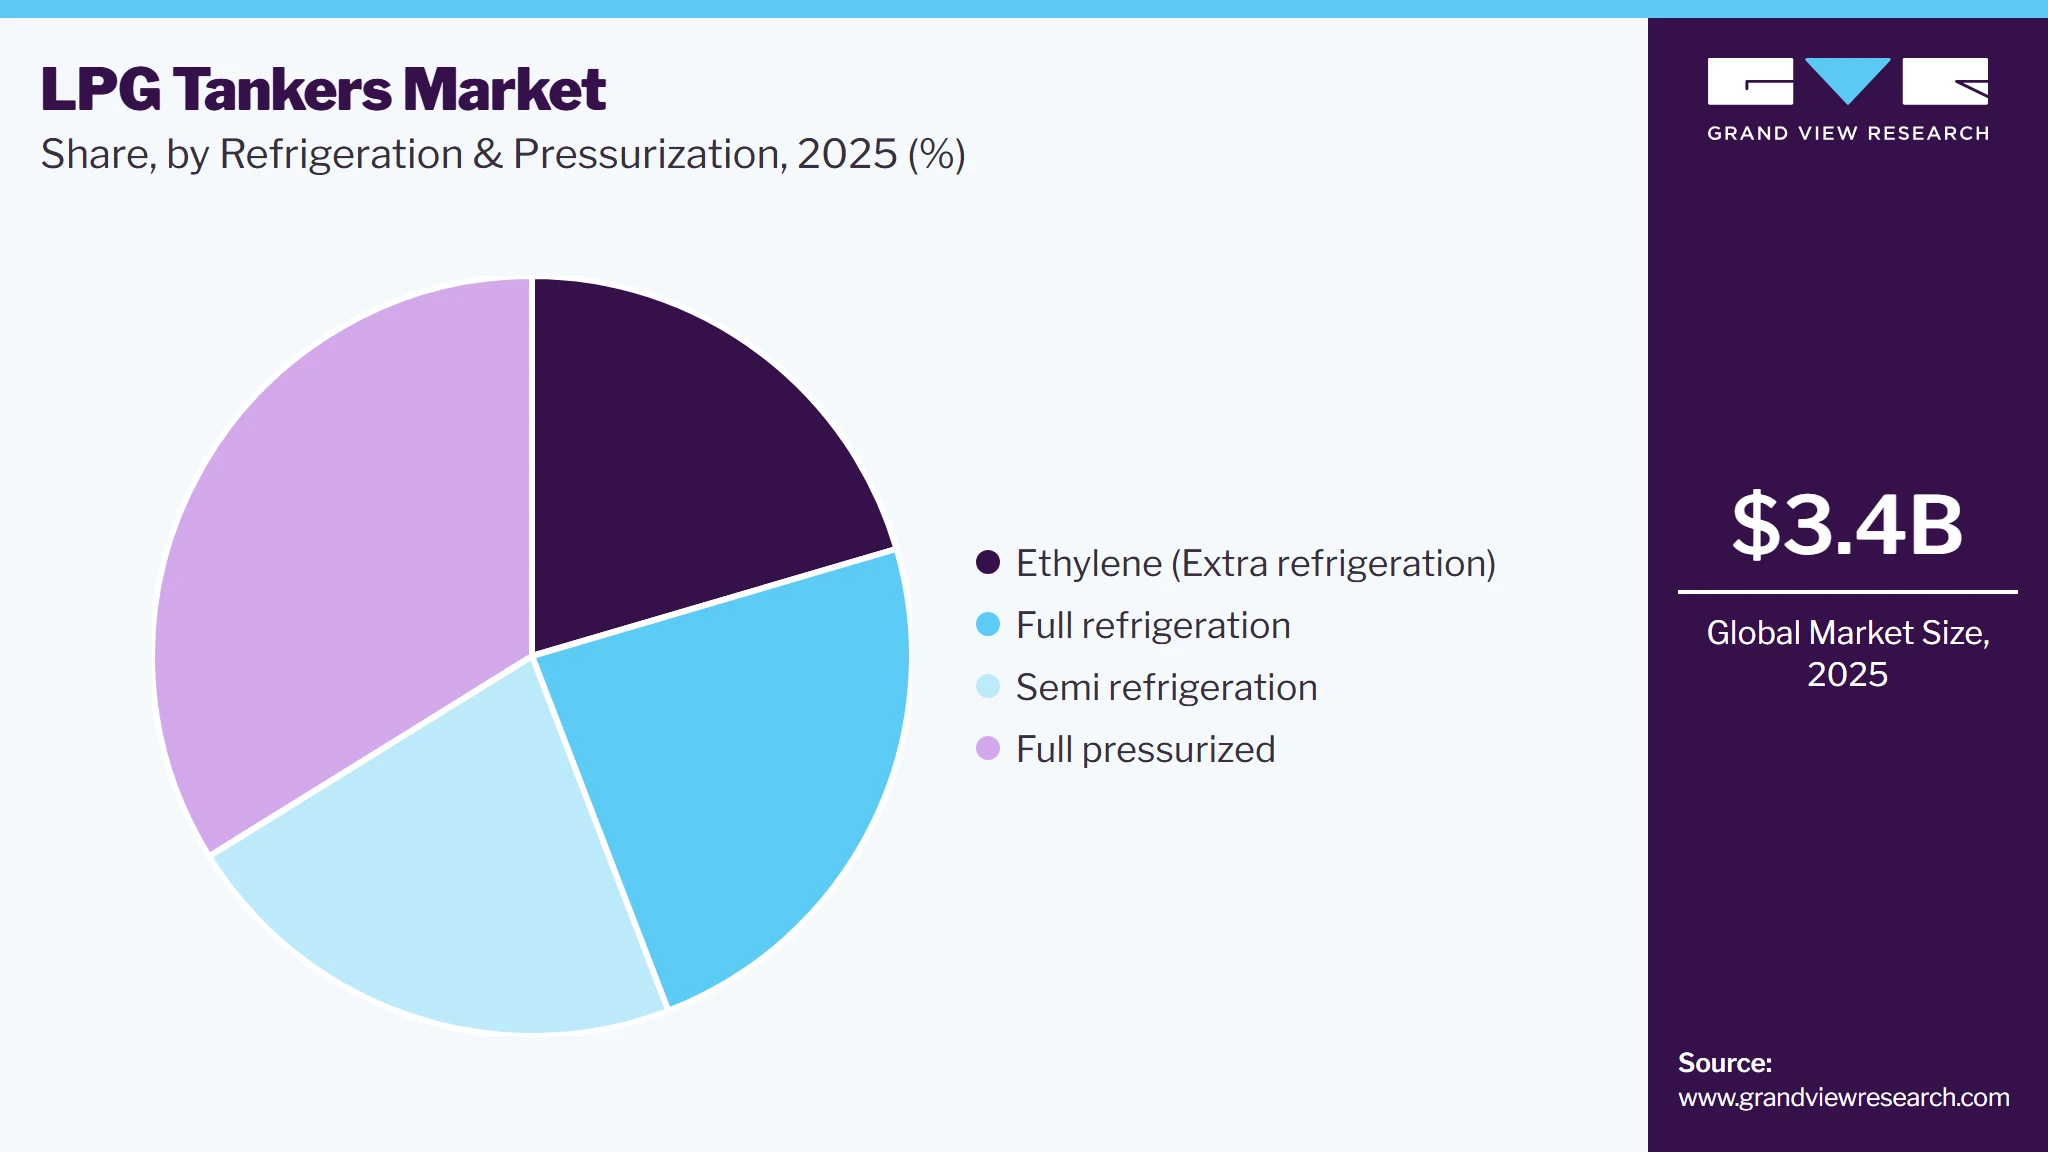
Based on refrigeration & pressurization, the full pressurized segment led the market with the largest revenue share of 33.8% in 2025. The full pressurized segment will maintain its lead throughout the forecast period. The market is anticipated to have steady growth in all segments as the amount of LPG transported increases. Fully refrigerated types are VLGCs that are capable of transporting 15,000 m3 to 85,000 m3 of gas and are suitable for long distances. Vessels used in such ships are proficient in bearing a minimum working temperature of -500 C and a maximum working pressure of around 0.28 kg/cm2. Carriers for ethylene are observed as a discrete segment in the industry since they need extra refrigeration for safe transportation across the world.
 To learn more about this report, Download Free Sample Report
The semi-refrigerated segment is expected to grow at a steady CAGR over the forecast period. These vessels are similar to full-pressure vessels as they have a Type C tank. In this case, the pressure vessel is usually rated for a maximum working pressure of 57 bars. The size of the ship is up to 7,500 m3, and is mainly used for transporting liquid gas. Decompression can reduce the thickness of the tank compared to a fully pressurized container but at the expense of additional freezing systems and tank insulation. The tanks of these ships are made of steel that can withstand temperatures of up to 10 °C and can be cylindrical, conical, or spherical. A small ship carrier is generally the full-pressure type. The semi-refrigerated techniques are used for the shipment spaces around 7,500m3.
Regional Insights
The North America LPG tankers market is driven by several key factors, notably the region's abundant shale gas reserves, which significantly bolster LPG production and exports. As one of the top exporters of LPG globally, North America benefits from increasing domestic and international demand for liquefied petroleum gas, particularly for residential heating and cooking applications.
U.S. LPG Tankers Market Trends
The LPG tankers market in the U.S. is driven by the growing trend towards cleaner energy sources that further enhance the appeal of LPG as an alternative fuel, contributing to its rising consumption in the U.S. In addition, the establishment of strong trade relationships with countries in Asia and Europe facilitates ongoing export opportunities, thereby stimulating the need for efficient LPG transportation solutions. These dynamics collectively position the North American LPG tanker industry for sustained growth in the coming years.
Europe LPG Tankers Market Trends
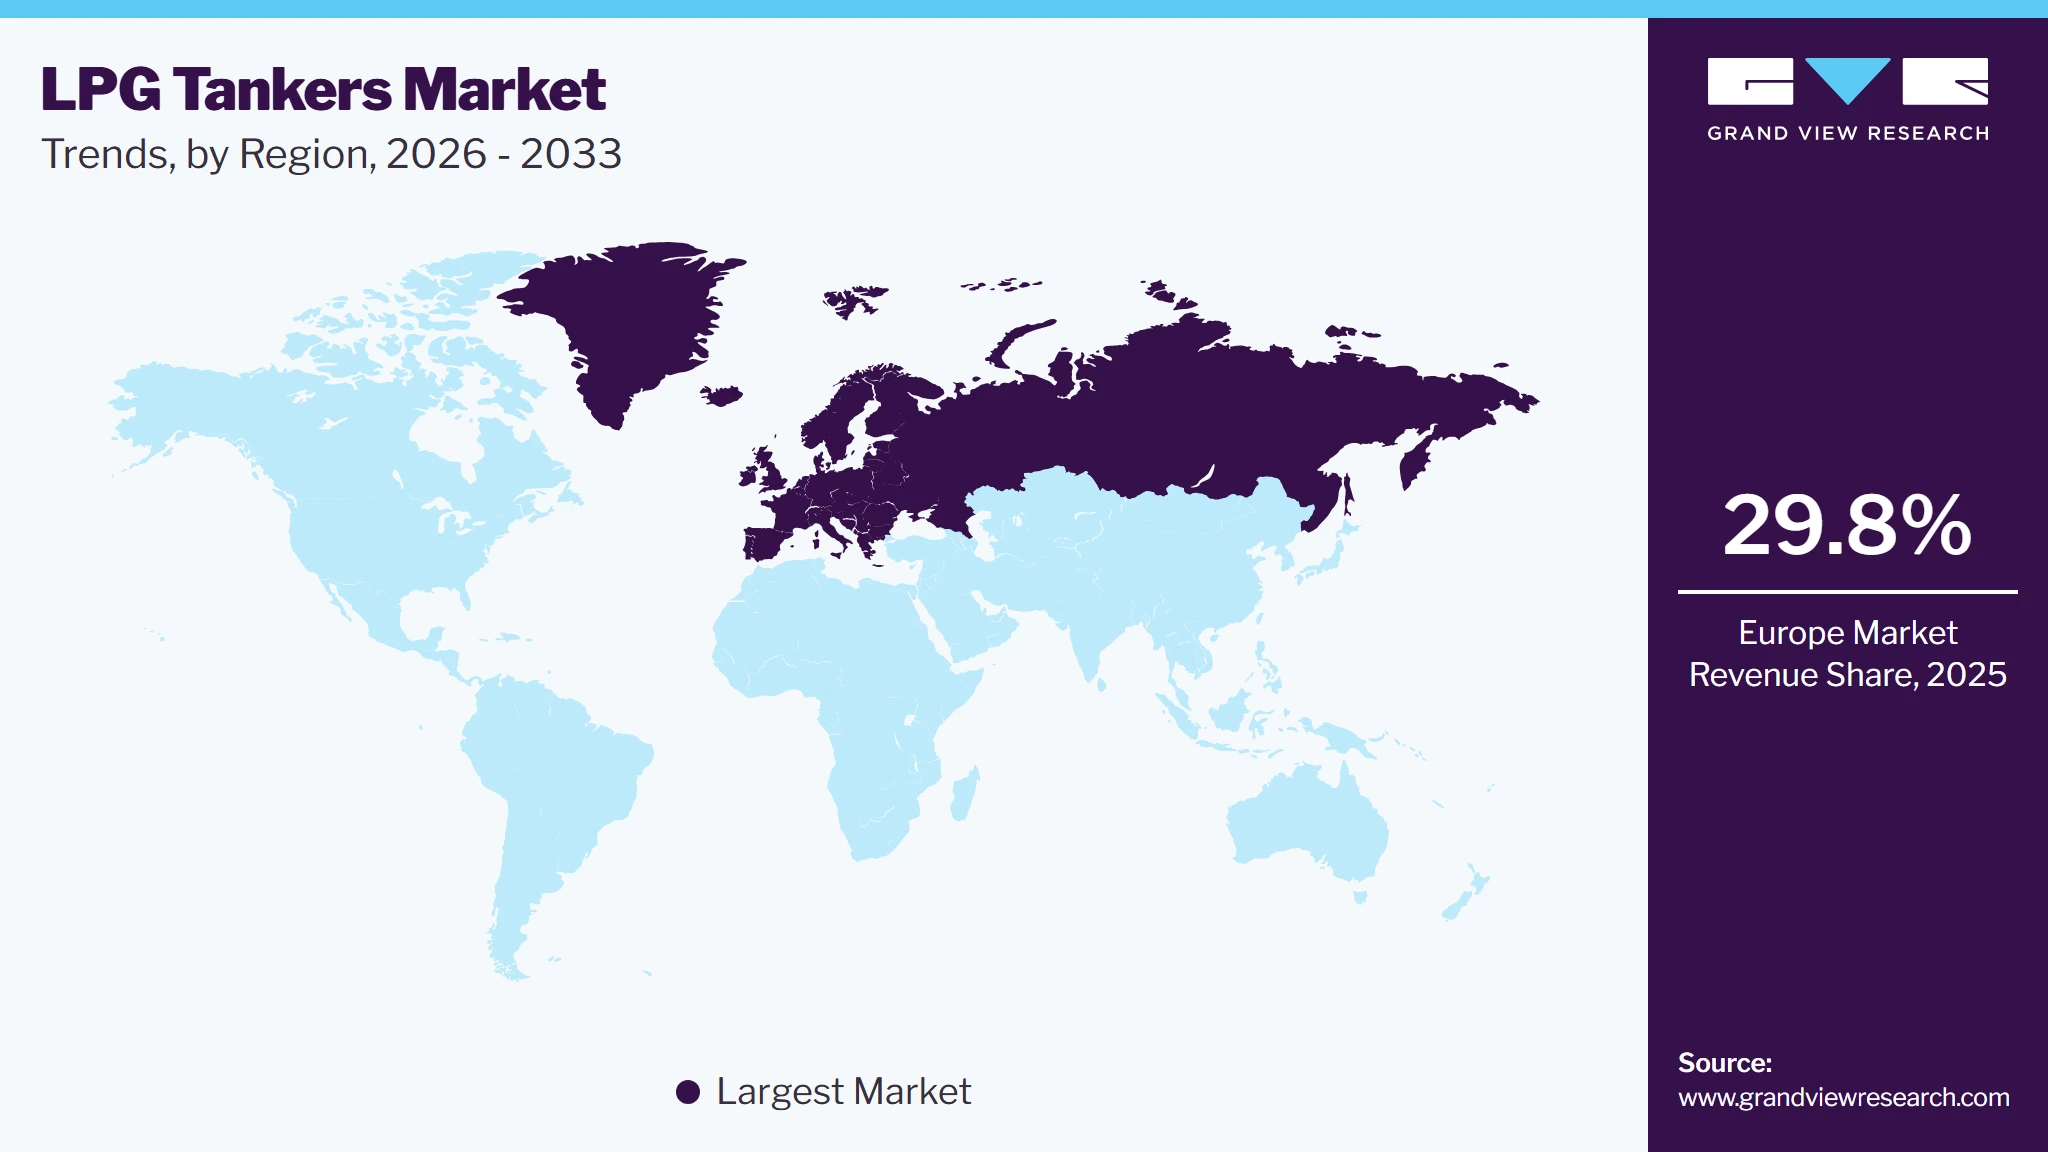
Europe dominated the LPG tankers market with the largest revenue share of 29.8% in 2025. The market in Europe is primarily driven by a rise in the demand for LPG due to government initiatives and low domestic production for LPG, which leads to higher demand for LPG tankers to facilitate import. North America, the Middle East, and Western Africa are the key regional markets for LPG tankers on account of the growing exports of liquefied petroleum gas to regions, such as Europe and the Asia Pacific. North America is one of the top exporters of LPG in the world, after Qatar and Australia. The presence of abundant proven reserves of shale gas in the region drives the market.
 To learn more about this report, Download Free Sample Report
The LPG tankers market in Europe is primarily driven by a significant increase in demand for liquefied petroleum gas, largely fueled by government initiatives aimed at promoting cleaner energy sources and reducing reliance on fossil fuels. With many European countries facing low domestic LPG production, the need for imports has surged, leading to heightened demand for LPG tankers to facilitate this trade. In addition, the region's focus on technological advancements and innovative shipping solutions supports the expansion of the market.
The LPG tankers market in Russia held the largest share in the Europe region in 2025. The LPG tankers market in Russia is characterized by its significant role as a key player in the European LPG supply chain, driven by the country's substantial liquefied petroleum gas production capabilities. Russia's strategic position allows it to serve as a major exporter of LPG, particularly to European markets, where demand is rising due to government initiatives promoting cleaner energy sources and limited domestic production. However, the market faces challenges, including geopolitical tensions and economic sanctions that have affected trade dynamics and investment flows.
The LPG tankers market in Italy is influenced by several dynamic factors, primarily driven by the country's increasing reliance on liquefied petroleum gas as a cleaner energy source. As Italy's domestic LPG production is limited, the nation heavily depends on imports to meet its energy needs, which significantly boosts demand for LPG tankers.
Asia Pacific LPG Tankers Market Trends
The LPG tankers market in the Asia-Pacific region is experiencing significant growth, driven by rapid industrialization and urbanization in developing countries such as China, India, and Japan. As these nations increasingly rely on liquefied petroleum gas for residential, industrial, and transportation needs, the demand for LPG tankers has surged. The absence of extensive gas pipeline networks in the region necessitates the importation of LPG via maritime routes, further fueling the need for efficient tanker solutions.
The LPG tankers market in China is a crucial segment of the broader Asia-Pacific LPG industry, characterized by rapid growth driven by the country's increasing demand for liquefied petroleum gas. As one of the largest consumers and importers of LPG, China relies heavily on maritime transportation to meet its energy needs, given the lack of extensive pipeline infrastructure. The market is supported by robust domestic production and a thriving petrochemical sector, which further stimulates demand for LPG tankers.
The LPG tankers market in Japan is driven by the country's increasing reliance on liquefied petroleum gas as a key energy source, particularly due to its limited domestic natural gas production. As Japan seeks to diversify its energy portfolio and reduce carbon emissions, LPG has emerged as a cleaner alternative for heating, cooking, and industrial applications. The absence of extensive pipeline infrastructure necessitates the import of LPG via maritime routes, creating a robust demand for LPG tankers.
Central & South America LPG Tankers Market Trends
The LPG tankers market in Central and South America is driven by the combination of rising consumption and infrastructural developments. The establishment of trade agreements with major LPG-producing nations is facilitating imports, thereby enhancing regional supply chains. However, challenges such as fluctuating global LPG prices and competition from alternative energy sources may impact market stability.
Middle East & Africa LPG Tankers Market Trends
The LPG tankers market in the Middle East and Africa is experiencing significant trends driven by increasing demand for liquefied petroleum gas as a cleaner energy source. In the Middle East, countries like Saudi Arabia are leveraging their substantial reserves of crude oil and natural gas to boost LPG production, with major companies such as Saudi Aramco leading the way. This growth is supported by rising domestic consumption and export opportunities, particularly to neighboring regions.
Key LPG Tankers Company Insights
The LPG tankers industry is characterized by a competitive landscape featuring several key players that dominate the industry. Major companies include Samsung Heavy Industries, Mitsubishi Heavy Industries, HD Hyundai Heavy Industries, Hanwha Ocean, and Mitsui OSK Lines, which are recognized for their advanced shipbuilding capabilities and significant market shares.
Key LPG Tankers Companies:
The following key companies have been profiled for this study on the LPG tankers market.
- BW Group
- Dorian LPG Ltd.
- EXMAR
- Hyundai Heavy Industries Co., Ltd
- Kawasaki Heavy Industries, Ltd
- Mitsubishi Heavy Industries, Ltd.
- Namura Shipbuilding Co., Ltd.
- PT Pertamina (Persero)
- StealthGas Inc.
- The Great Eastern Shipping Co. Ltd.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., BW LPG Limited, Dorian LPG Ltd., EXMAR NV, Navigator Holdings Ltd., Kuwait Oil Tanker Company S.A.K., The Great Eastern Shipping Company Limited)
- Focus on operating large fleets of LPG carriers, including VLGCs, MGCs, and pressurized vessels, supported by long-term charter agreements and global shipping networks.
- Emphasize fleet modernization, operational efficiency, digital fleet management, safety compliance, and strategic expansion through vessel acquisitions and long-term customer contracts with LPG producers, traders, and energy companies.
- Benefit from extensive global shipping networks, established customer relationships, diversified fleets, and strong operational expertise.
- Large fleet sizes, long-term charter coverage, and economies of scale enable higher vessel utilization, stable revenue generation, and reliable transportation services across international LPG trade routes.
- Face high capital requirements for fleet expansion, vessel maintenance, and compliance with evolving maritime safety and environmental regulations.
- Profitability is influenced by freight rate volatility, fluctuating LPG trade volumes, bunker fuel prices, and geopolitical disruptions affecting global shipping routes.
Emerging & Specialized Players (e.g., StealthGas Inc., HD Hyundai Heavy Industries Co., Ltd., Kawasaki Heavy Industries, Ltd., Mitsubishi Heavy Industries, Ltd.)
- Focus on specialized LPG carrier operations, technologically advanced vessel construction, and customized shipbuilding solutions designed to meet evolving customer requirements and international maritime standards.
- Emphasize innovation in fuel-efficient ship designs, advanced cargo containment systems, digital ship technologies, and energy-efficient propulsion solutions while expanding partnerships with global shipping companies.
- Benefit from technological expertise, engineering capabilities, specialized vessel designs, and the ability to deliver customized, high-value LPG carriers.
- Strong R&D capabilities and manufacturing flexibility enable rapid adoption of advanced shipbuilding technologies and compliance with increasingly stringent environmental regulations.
- Limited shipping fleet presence or narrower service offerings compared to major global fleet operators may restrict market influence in transportation services.
- Growth depends on shipbuilding order cycles, capital-intensive manufacturing investments, changing customer procurement strategies, and fluctuations in global demand for new LPG carriers.
Recent Developments
-
In October 2024, Hyundai Mipo secured a contract to build two LPG carriers, each with a capacity of 45,000 cubic meters, for a shipowner based in Oceania. The deal, valued at $164 million, includes scheduled deliveries in the latter half of 2027.
-
In July 2024, PT Pertamina International Shipping (PIS) entered into a new partnership with global commodity trader BGN to enhance its fleet of large LPG tankers. This collaboration focuses on the joint development and operation of new vessels specifically designed for transporting liquefied petroleum gas.
LPG Tankers Market Report Scope
Report Attribute
Details
Market definition
The LPG tankers market size represents the total annual revenue generated from the sale of new LPG tankers, including very large, large, medium, and small gas carriers equipped with fully pressurized, semi-refrigerated, fully refrigerated, or ethylene-capable cargo systems.
Market size in 2025
USD 3.4 billion
Estimated market size in 2026
USD 3.6 billion
Projected market size by 2033
USD 5.6 billion
Growth rate
CAGR of 6.6% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Vessel Size, refrigeration & pressurization, region.
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S, Canada, Mexico, Germany, UK, Russia, France, Italy, India, China, Japan, Australia, Brazil, South Africa; Saudi Arabia
Key companies profiled
BW LPG Limited, Dorian LPG Ltd., EXMAR NV, StealthGas Inc., Navigator Holdings Ltd., Kuwait Oil Tanker Company S.A.K., The Great Eastern Shipping Company Limited, HD Hyundai Heavy Industries Co., Ltd., Kawasaki Heavy Industries, Ltd., and Mitsubishi Heavy Industries, Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global LPG Tankers Market Report Segmentation
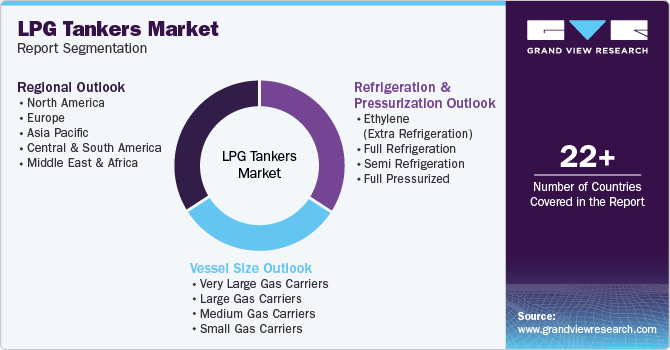
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global LPG tankers market report based on vessel size, refrigeration & pressurization, and region:
 To learn more about this report, Download Free Sample Report
-
Vessel Size Outlook (Revenue, USD Million, 2021 - 2033)
-
Very Large Gas Carriers
-
Large Gas Carriers
-
Medium Gas Carriers
-
Small Gas Carriers
-
-
Refrigeration & Pressurization Outlook (Revenue, USD Million, 2021 - 2033)
-
Ethylene (Extra refrigeration)
-
Full refrigeration
-
Semi refrigeration
-
Full pressurized
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
Italy
-
Spain
-
France
-
Russia
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
UAE
-
-
Research Methodology
The LPG tankers Market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each LPG tankers segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Vessel Size
Revenue Capture Definition
Very Large Gas Carriers (VLGCs)
VLGCs are primarily designed for long-distance transportation of liquefied petroleum gas (LPG) between major exporting and importing countries. Market revenue is attributed to the sale of new Very Large Gas Carriers equipped for high-capacity LPG transportation.
Large Gas Carriers (LGCs)
Large Gas Carriers are designed to transport LPG across regional and international trade routes where cargo volumes are lower than those required by VLGCs. Revenue is generated through the sale of new Large Gas Carriers used for regional and international LPG transportation.
Medium Gas Carriers (MGCs)
Medium Gas Carriers are designed to transport LPG and petrochemical gases along regional and medium-distance trade routes. Market revenue is generated from the sale of new Medium Gas Carriers that serve diverse liquefied gas transportation requirements.
Small Gas Carriers (SGCs)
Small Gas Carriers are primarily used for short-haul, coastal, and domestic transportation of LPG. Revenue is generated from the sale of new Small Gas Carriers that support regional LPG distribution networks.
Refrigeration & Pressurization
Revenue Capture Definition
Ethylene (Extra Refrigeration)
Ethylene carriers are specially designed to transport ethylene, LPG, and other liquefied gases at extremely low temperatures using advanced refrigeration systems. Market revenue is attributed to the sale of new ethylene-capable LPG carriers equipped with specialized cryogenic cargo systems.
Full Refrigeration
Fully refrigerated LPG tankers are designed to transport large volumes of LPG at atmospheric pressure over long-distance trade routes. Revenue is generated through the sale of new, fully refrigerated LPG tankers equipped with advanced refrigeration and cargo-handling systems.
Semi Refrigeration
Semi-refrigerated LPG tankers combine moderate-pressure and refrigeration technologies to transport LPG and petrochemical gases across regional and medium-distance routes. Market revenue is generated through the sale of new semi-refrigerated LPG tankers.
Full Pressurized
Full-pressurized LPG tankers are designed to transport LPG under high pressure without Refrigeration and are primarily deployed for short-haul and coastal distribution. Revenue is generated from the sale of new, fully pressurized LPG tankers that support regional LPG transportation.
Estimation Model
Layer Name
Key Question
Description
LPG Demand & Transportation Base Layer
What forms the demand base?
Identify global LPG production, export-import volumes, and seaborne trade requiring marine transportation. Assess international trade flows, export terminal capacity, import infrastructure, and regional LPG consumption patterns to establish the addressable demand for marine LPG carriers.
LPG Tanker Manufacturing & Supply Layer
Where are LPG tankers supplied and operated?
Estimate global production capacity of LPG tankers across major shipbuilding regions. Analyze shipyard capacity, manufacturing capabilities, vessel order books, engineering expertise, component suppliers, and supply chain infrastructure to assess market supply dynamics.
Fleet Procurement & Technology Adoption Layer
How extensively are LPG tankers utilized?
Analyze demand for new LPG tankers across shipping companies and fleet operators. Evaluate fleet replacement cycles, procurement strategies, vessel size preferences, refrigeration technologies, regulatory requirements, and investments influencing new tanker purchases.
Revenue Layer
How is market revenue generated?
Revenue is generated through the sale of new LPG tankers, including Very Large, Large, Medium, and Small Gas Carriers. Market value is determined by new vessel orders, average selling prices, shipbuilding capacity, fleet replacement demand, technological advancements, and investments in fleet expansion.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
LPG Tankers Competitive Landscape Assessment
Detailed competitive landscape analysis covering LPG tanker owners, fleet operators, and shipping companies involved in the transportation of liquefied petroleum gas. The study profiled key market participants based on geographic presence, organizational structure, fleet size, vessel portfolio (VLGCs, LGCs, MGCs, and SGCs), operational networks, chartering capabilities, strategic partnerships, fleet expansion initiatives, and investments in fuel-efficient vessel technologies.
Enabled evaluation of competitive positioning, fleet capabilities, operational strengths, chartering expertise, global shipping networks, and market participation across the LPG tanker value chain.
Fleet Deployment & Technology Assessment
Evaluation of global marine LPG carrier demand across international shipping routes, export terminals, import infrastructure, and regional maritime transportation networks. Included assessment of vessel sizes, refrigeration and pressurization technologies, fleet utilization trends, freight market dynamics, maritime regulations, environmental compliance requirements, and regional shipping activities across major markets.
Highlighted fleet deployment trends, technology adoption patterns, and regional transportation opportunities. Supported strategic planning, fleet optimization, chartering strategies, market entry evaluation, and long-term investment prioritization.
Opportunity Assessment
Identification of high-growth opportunities associated with expanding global LPG trade, increasing vessel charter demand, fleet modernization, and the adoption of fuel-efficient and digitally connected LPG carriers. Assessed emerging opportunities arising from increasing LPG exports, stricter maritime environmental regulations, advanced propulsion technologies, and investments in international maritime transportation infrastructure.
Enabled prioritization of high-value growth opportunities and emerging transportation segments. Supported long-term business planning, fleet expansion strategies, capital investment decisions, and technology adoption initiatives aligned with evolving global LPG logistics requirements.
Frequently Asked Questions About This Report
Europe dominated the market with revenue share of 29.8% in 2025.
Russia dominated the Europe market with a revenue share of 21.5% in 2025.
The LPG tankers market size was valued at USD 3.4 billion in 2025 and is estimated at USD 3.6 billion in 2026.
The LPG tankers market is expected to grow at a CAGR of 6.6% from 2026 to 2033, reaching USD 5.6 billion by 2033.
Very large gas carriers segment dominated the market, with a revenue share of 28.1% in 2025., while medium gas carriers segment is expected to be the fastest-growing market.
Based on refrigeration & pressurization, full pressurized accounted for largest revenue share of 33.8% in 2025.
The key players operating in the LPG tankers market include BW LPG Limited, Dorian LPG Ltd., EXMAR NV, StealthGas Inc., Navigator Holdings Ltd., Kuwait Oil Tanker Company S.A.K., The Great Eastern Shipping Company Limited, HD Hyundai Heavy Industries Co., Ltd., Kawasaki Heavy Industries, Ltd., and Mitsubishi Heavy Industries, Ltd.
The key driver of the global LPG tankers market is the increasing global seaborne trade of liquefied petroleum gas, supported by expanding LPG export capacity, rising fleet deployment, and growing investments in international maritime transportation infrastructure.
About the Author(s)
Distribution & Utilities Research Team
Energy & Power · Distribution & UtilitiesThis report was authored by the distribution & utilities research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the distribution & utilities segment of the energy & power industry. All findings are based on proprietary energy & power databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


