
- Home
- »
- Next Generation Technologies
- »
-
Manufacturing Automation Market Size Report, 2026-2033GVR Report cover

Manufacturing Automation Market (2026 - 2033)
Size, Share & Trends Analysis Report By Technology, By Component, By Deployment, By End-use, By Industry Vertical, By Application, By Solution, By Enterprise Size, By Region, And Segment Forecasts
Market Size, 2025
$15.4BMarket Estimate, 2026
$17.3BMarket Forecast, 2033
$9.3BCAGR, 2026–2033
9.7%Manufacturing Automation Market Summary
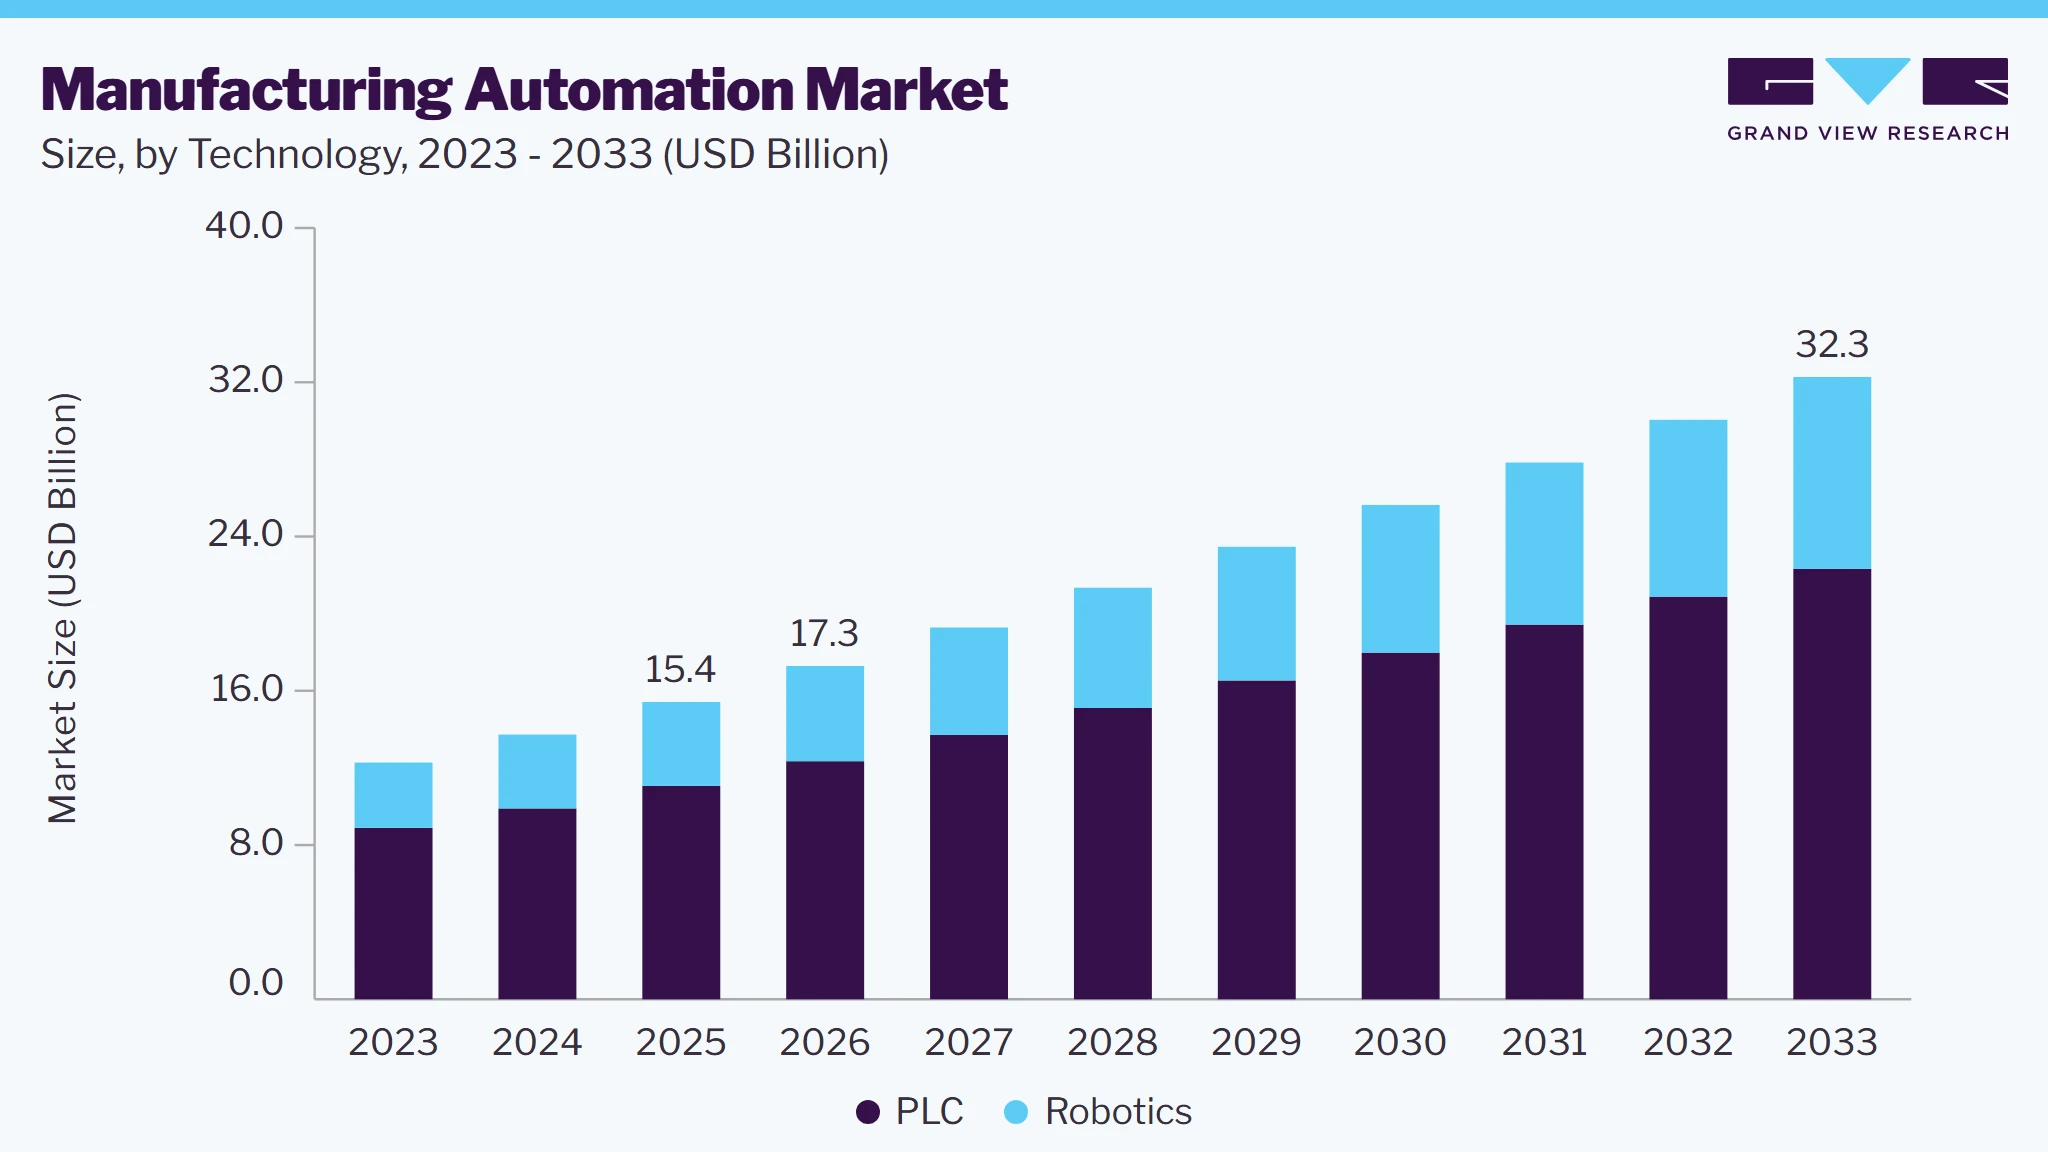
The global manufacturing automation market size was valued at USD 15.4 billion in 2025 and is projected to grow from USD 17.3 billion in 2026 to USD 32.3 billion by 2033, at a CAGR of 9.3% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenueIIoT), machine learning, cloud computing, digital twins, and edge computing that enable intelligent, connected, and data-driven manufacturing operations. share of 38.4% in 2025. The manufacturing automation market is primarily driven by the rapid adoption of Industry 4.0 and smart manufacturing technologies, increasing demand for productivity and cost optimization, and the growing need for flexible and resilient manufacturing operations.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By component: The hardware segment accounted for the largest market share of 49.3% in 2025.
- By technology: The PLC segment dominated the market, with a share of 71.7% in 2025.
- By deployment: The on-premises segment dominated the market in 2025.
- By end use: The discrete manufacturing segment dominated the market in 2025.
- By application: The assembly line automation segment dominated the market in 2025.
- By industry vertical: The automotive segment dominated the market in 2025.
- By solution: The control systems segment dominated the market in 2025.
- By enterprise size: The large enterprises segment dominated the market in 2025.
Regional Highlights
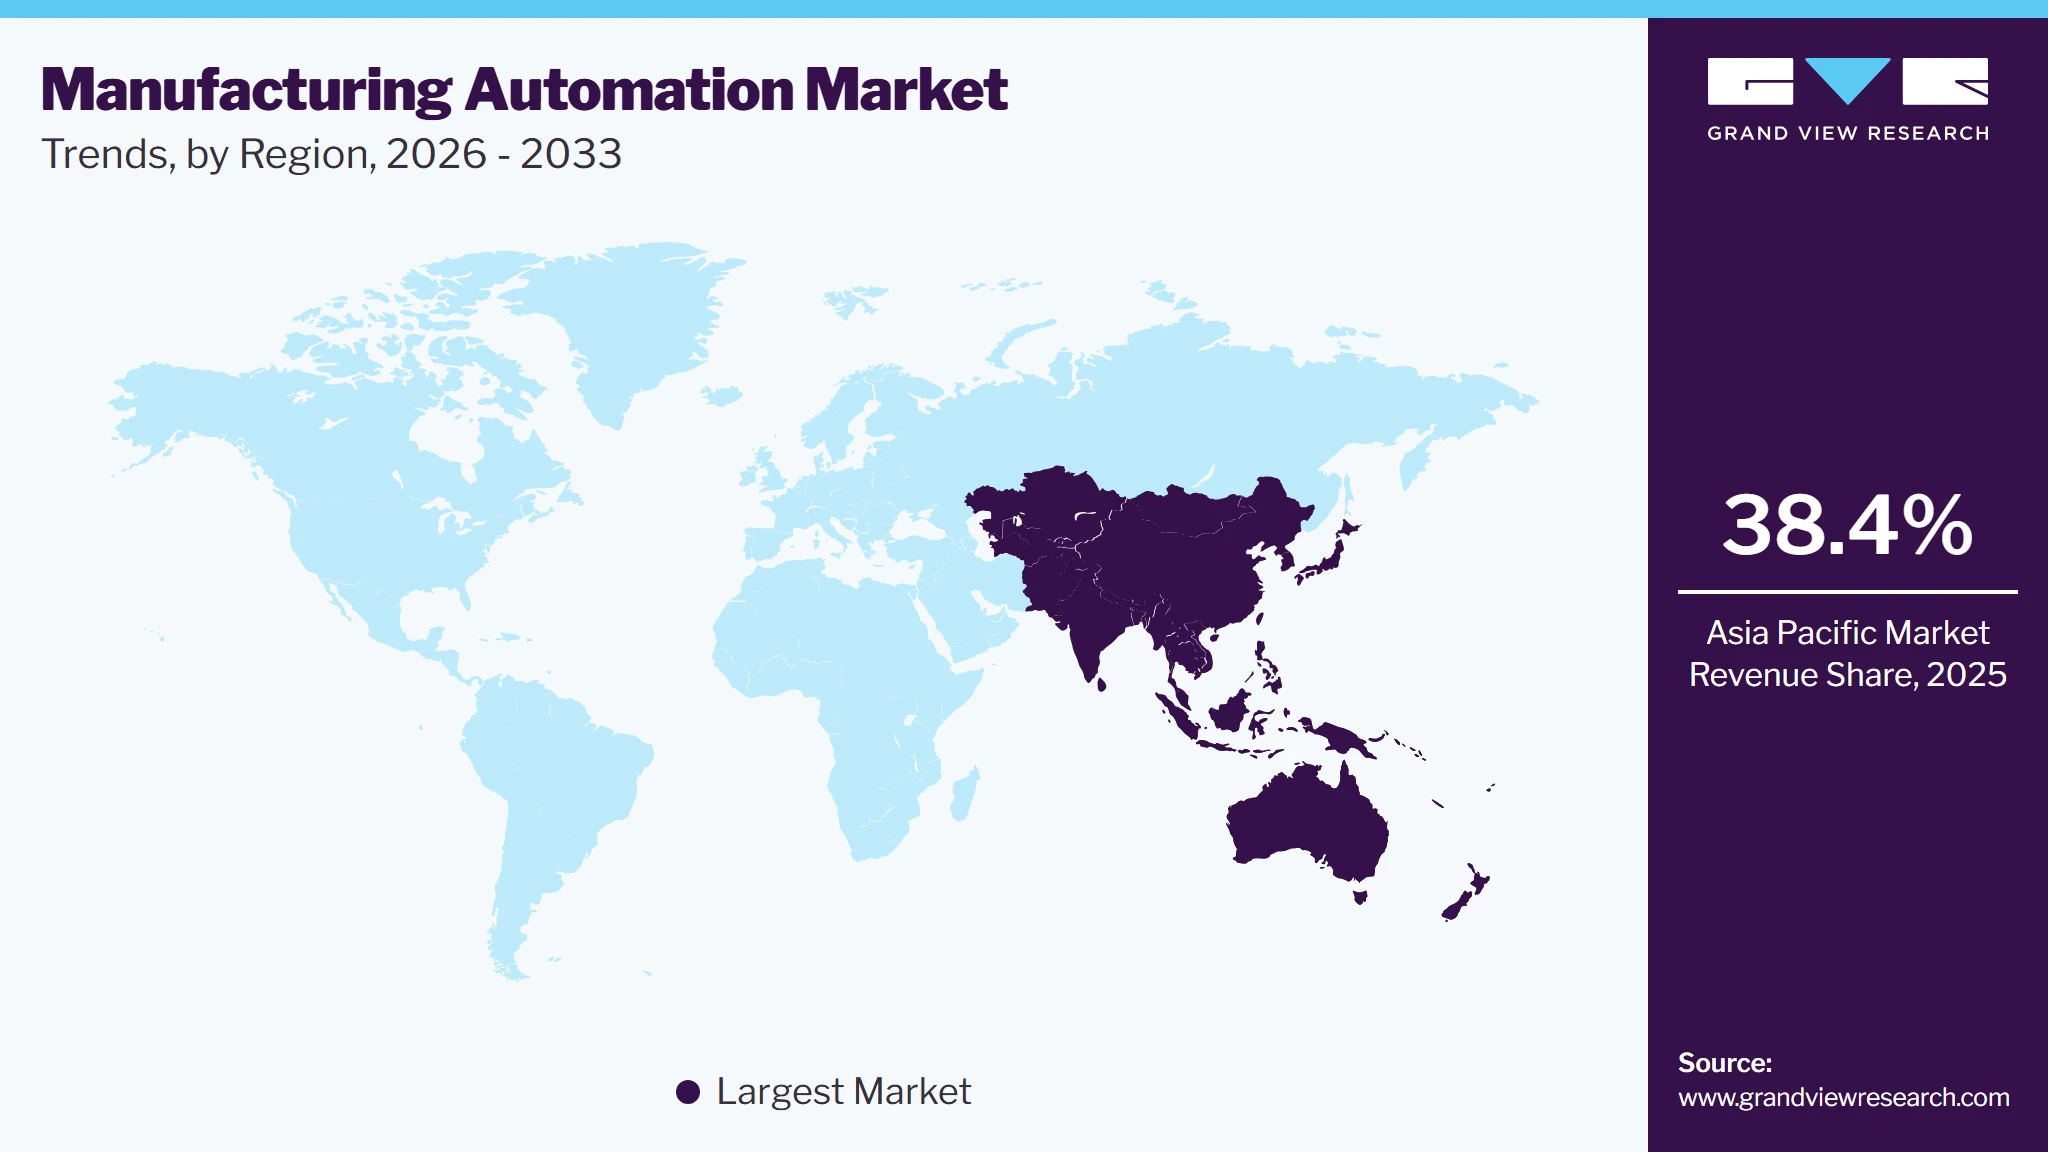
- Largest regional market: Asia Pacific (38.4% revenue share in 2025)
- Fastest growing regional market: Asia Pacific (highest CAGR 10.7%, 2026-2033)
- By Country: China held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 15.4 Billion
- Estimated market size in 2026: USD 17.3 Billion
- Projected market size by 2033: USD 32.3 Billion
- CAGR (2026-2033): 9.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Additionally, growing advancements in industrial robotics, artificial intelligence (AI), machine vision, and Industrial Internet of Things (IIoT) technologies, along with government initiatives promoting digital transformation are further accelerating the adoption of manufacturing automation solutions across industries.
In addition, rapid technological advancements and the adoption of new systems and networking architectures are expected to further fuel the market growth in the coming years. The growing demand for operational efficiency and productivity improvement drives market growth. Automation technologies, such as robotics, artificial intelligence (AI), and machine learning (ML), help manufacturers streamline processes, reduce manual intervention, and minimize human errors. By optimizing production lines, these solutions contribute to faster production cycles, cost savings, and consistent quality. This trend is expected to enhance the market expansion in the coming years.
 To learn more about this report, Download Free Sample Report
In addition, manufacturers worldwide face rising labor costs and a shortage of skilled workers, driving them to invest in automation technologies. The integration of advanced technologies into manufacturing processes, characterized by the increasing demand for interconnected systems that facilitate real-time data analysis and decision-making, which is essential for optimizing production processes, is driving the market expansion.
Furthermore, the increasing adoption of sustainable manufacturing practices is accelerating market growth. Companies are adopting automation to reduce energy consumption, minimize waste, and optimize resource use, aligning with global efforts toward greener production. Automation technologies help monitor energy usage and improve resource efficiency, thus supporting the shift toward more eco-friendly manufacturing processes and driving growth in markets with strict regulatory requirements.
Moreover, rising labor costs and workforce shortages are expected to drive market growth in the coming years. This ongoing trend is compelling companies to invest in automation technologies. In addition, the rising consumer demand for customized products necessitates flexible manufacturing systems that can quickly adapt to changing market demands, thereby fueling market expansion.
Market Dynamics
The manufacturing automation market is experiencing robust growth, driven by the accelerating digital transformation of manufacturing facilities, increasing deployment of collaborative robots and autonomous production systems, and the growing emphasis on predictive maintenance, real-time process optimization, and sustainable manufacturing practices. Rising investments in factory modernization, the need to address labor shortages, and the growing focus on predictive maintenance, operational resilience, and sustainable manufacturing are further supporting market expansion across diverse industries.
The rapid adoption of smart factory initiatives is a key driver of the manufacturing automation market. Manufacturers are increasingly integrating technologies such as industrial robotics, Industrial Internet of Things (IIoT), artificial intelligence (AI), machine vision, and advanced control systems to improve production efficiency, product quality, and operational visibility. These technologies enable real-time monitoring, automated decision-making, and optimized production workflows.
Automation solutions also help manufacturers reduce manual intervention, minimize production errors, and improve equipment utilization. By leveraging predictive maintenance and data analytics, companies can identify potential equipment failures before they occur, reducing unplanned downtime and maintenance costs while increasing overall productivity.
Furthermore, the growing demand for flexible manufacturing and mass customization is encouraging investments in intelligent automation systems. Industries such as automotive, electronics, pharmaceuticals, food & beverage are increasingly modernizing production facilities to improve responsiveness to changing market demands while maintaining consistent quality and operational efficiency.
The high upfront cost of implementing manufacturing automation systems remains a significant restraint for market growth. Deploying industrial robots, programmable logic controllers (PLCs), sensors, software platforms, and communication infrastructure requires substantial capital investment, making automation projects challenging for small and medium-sized enterprises (SMEs).
Beyond equipment costs, manufacturers often incur additional expenses for system integration, employee training, cybersecurity, and ongoing maintenance. Integrating new automation technologies with legacy production systems can be technically complex and may require production downtime, increasing implementation risks and costs.
Additionally, the shortage of skilled professionals capable of designing, operating, and maintaining advanced automation systems creates operational challenges. These factors can delay the adoption of automation, particularly in developing economies where financial and technical resources are more limited.
The increasing adoption of AI-driven predictive maintenance and autonomous manufacturing presents significant growth opportunities for the manufacturing automation market. AI and machine learning technologies enable manufacturers to analyze equipment performance in real time, predict failures before they occur, and optimize maintenance schedules, resulting in improved asset reliability and reduced operational costs.
Manufacturers are also investing in autonomous production systems, collaborative robots (cobots), and intelligent quality inspection solutions to improve production flexibility and reduce dependence on manual labor. These technologies support continuous production, faster changeovers, and greater adaptability to customized manufacturing requirements. Furthermore, the expansion of Industry 4.0 initiatives, digital twin technology, and cloud-based manufacturing platforms is creating new opportunities for automation vendors. Moreover, the demand for intelligent, connected, and AI-enabled manufacturing automation solutions is expected to grow steadily across both developed and emerging markets.
Market Concentration & Characteristics
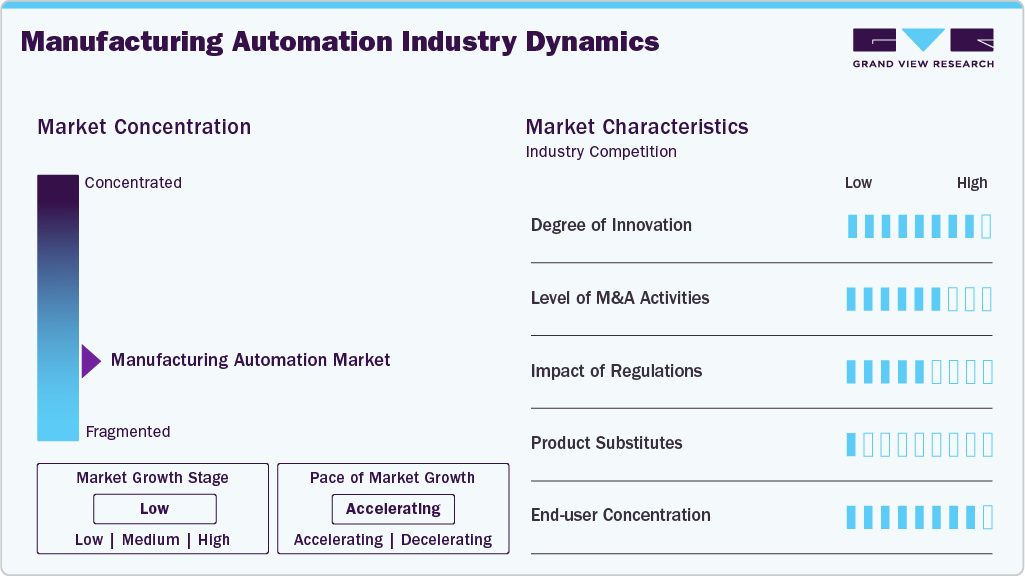
The manufacturing automation market is moderately fragmented, comprising global industrial automation companies, robotics manufacturers, control system providers, industrial software vendors, sensor and machine vision suppliers, and specialized system integrators. The market is witnessing a moderate-to-high level of mergers and acquisitions, as established players acquire software developers, AI, robotics, and industrial IoT companies to strengthen their digital automation capabilities, expand solution portfolios, and enhance their global market presence. The ecosystem is highly technology-driven, supported by advancements in artificial intelligence (AI), Industrial Internet of Things (IIoT), machine learning, cloud computing, digital twins, and edge computing that enable intelligent, connected, and data-driven manufacturing operations.
 To learn more about this report, Download Free Sample Report
Regulatory influence in the manufacturing automation market is moderate to high, primarily shaped by industrial safety standards, machine compliance regulations, cybersecurity requirements for operational technology (OT), environmental regulations, and government initiatives promoting smart manufacturing, digital transformation, and energy-efficient industrial operations. Product substitution is relatively low as manufacturing automation solutions are deeply integrated into production processes and deliver substantial improvements in productivity, quality, operational efficiency, and cost reduction. Demand remains highly diversified across automotive, electronics, food & beverage, pharmaceuticals, chemicals, metals & mining, aerospace, and other industrial sectors, driven by increasing factory modernization, labor shortages, supply chain optimization, and growing investments in Industry 4.0 technologies.
Analyst Perspective
The manufacturing automation market is experiencing strong structural growth, driven by the increasing modernization of legacy manufacturing infrastructure, rising demand for mass customization and shorter product life cycles, and the growing need to improve overall equipment effectiveness (OEE) across production facilities. Manufacturers are increasingly adopting advanced automation to reduce downtime, streamline workflows, and enhance precision in high-mix, low-volume production environments, further accelerating the transition toward intelligent and adaptive manufacturing systems.
Technology Insights
Based on technology, the PLC segment dominated the market with the largest revenue share of 71.7% in 2025 and is expected to grow at a considerable CAGR over the forecast period, owing toits widespread adoption across various sectors, including automotive, food processing, and pharmaceuticals. Their ability to withstand harsh industrial environments while offering flexibility in programming makes them an essential component of modern manufacturing systems. As manufacturers upgrade their facilities with advanced automation technologies, the segment is expected to grow significantly in the coming years.
The robotics segment is expected to witness the fastest CAGR from 2024 to 2030, driven by the growing demand for robotic automation in enhancing productivity and safety in manufacturing environments. Robots can perform repetitive tasks with high precision, reducing human error and workplace injuries. In addition, the rapid advancements in robotics technology-including collaborative robots (cobots) that work alongside human operators-are expected to drive adoption rates higher across various industries.
Component Insights
Based on component, the hardware segment led the market with the largest revenue share of 49.3% in 2025 and is expected to grow at a considerable CAGR over the forecast period. The demand for hardware solutions is driven by ongoing investments in upgrading existing infrastructure with state-of-the-art technology that supports complex automation tasks. As manufacturers strive for enhanced operational efficiency through integrated hardware-software ecosystems, the segment is expected to contribute significantly to market growth. Furthermore, ongoing investments in smart factories and Industry 4.0 initiatives drive the robust demand for advanced hardware solutions, prioritizing automation and connectivity, thereby driving segmental growth.
The services segment is expected to witness the fastest CAGR of 11.0% from 2024 to 2030. The increasing need for specialized services such as system integration, maintenance, and support for automation technologies fuels this growth. As manufacturers implement more complex automated systems, the demand for expert services that ensure optimal performance and uptime will rise. Furthermore, the shift towards subscription-based service models in automation solutions will likely enhance customer engagement and satisfaction, contributing to this segment's rapid expansion.
Deployment Insights
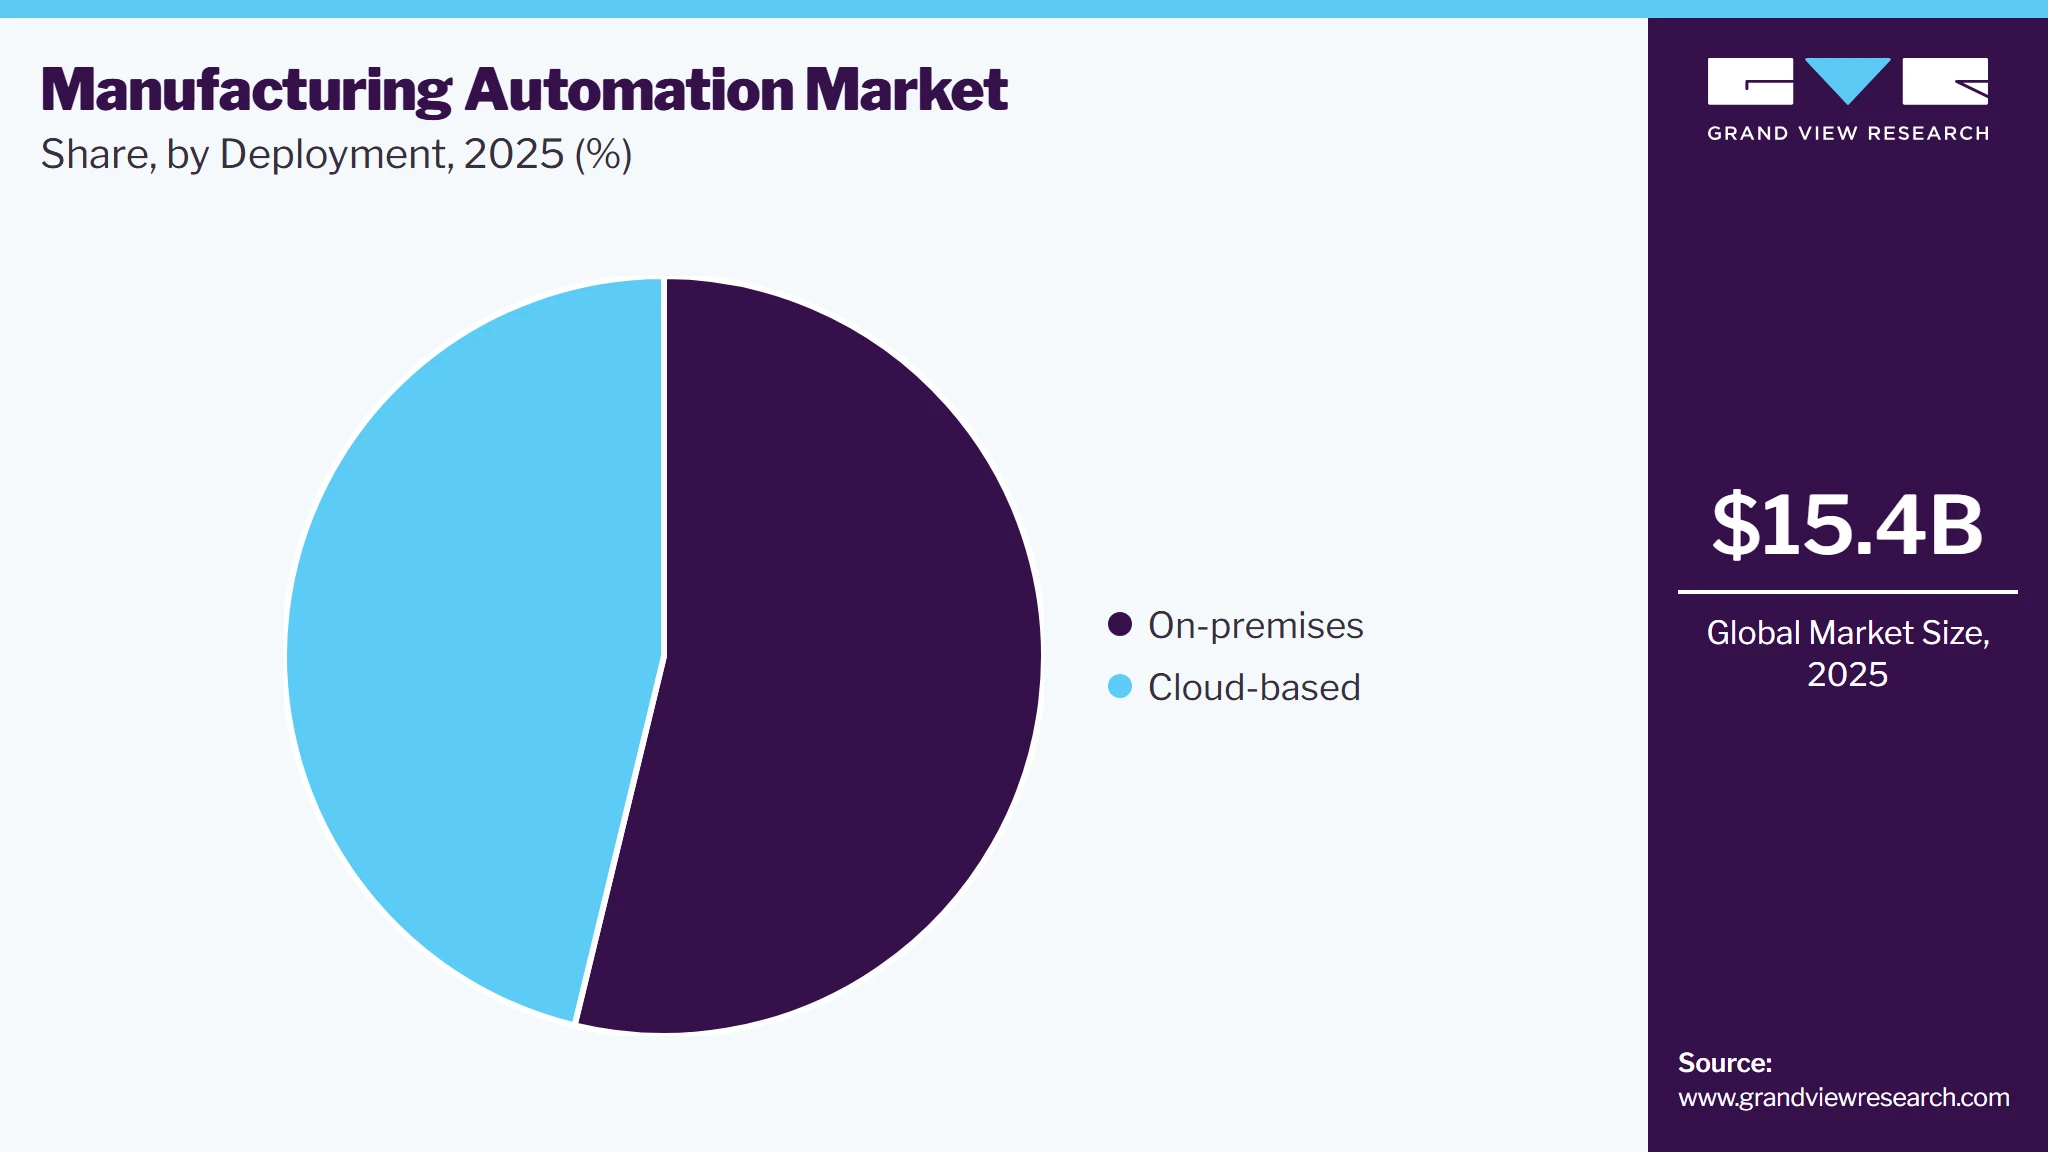
Based on deployment, the on-premises segment dominated the market with the largest revenue share of 53.7% in 2025. This growth can be attributed to several factors, including data security concerns and regulatory compliance requirements that necessitate local data storage. Many organizations prefer on-premises solutions because they offer greater control over their systems and data management processes. Furthermore, industries with stringent compliance mandates often find on-premises systems more suitable for meeting their specific needs, further fueling segmental growth.
The cloud-based segment will record the fastest growth from 2024 to 2030. This growth can be attributed to the increasing adoption of cloud technologies across various industries, enabling companies to enhance operational efficiency, reduce costs, and improve scalability. As organizations increasingly rely on cloud solutions for data management and analytics, the demand for cloud-based manufacturing automation is expected to surge in the coming years. This trend aligns with the broader digital transformation initiatives many businesses undertake to remain competitive in a rapidly evolving market.
End-use Insights
Based on end use, the discrete manufacturing segment led the market with the largest revenue share of 57.2% in 2025 and is expected to grow at a considerable CAGR over the forecast period. This growth can be attributed to its reliance on advanced technologies that enhance efficiency and productivity. Integrating automation solutions in discrete manufacturing allows for precise control over production processes, reducing waste and improving quality. As industries increasingly adopt smart manufacturing practices driven by Industry 4.0 initiatives, the demand for automation solutions in discrete manufacturing is expected to grow rapidly.
The process manufacturing segment is anticipated to grow fastest from 2024 to 2030.The increasing complexity of regulatory requirements and the need for consistent product quality drive investments in process automation solutions. Furthermore, technological advancements such as IoT (Internet of Things) and AI (Artificial Intelligence) enable real-time monitoring and control of processes, further enhancing operational efficiencies and driving segmental growth.
Industry Vertical Insights
Based on industry vertical, the automotive segment dominated the market with the largest revenue share of 26.2% in 2025. This growth is largely attributed to its reliance on automated processes for vehicle assembly and production efficiency. Major automotive manufacturers are investing extensively in robotics on assembly lines, which has led to improved output and enhanced safety standards within factories. This is expected to contribute to segmental growth in the coming years.
The healthcare segment is anticipated to record the fastest growth from 2024 to 2030, driven by the increasing demand for efficient and high-quality healthcare services, which necessitates the adoption of advanced automation technologies to streamline operations, reduce human error, and enhance patient outcomes. In addition, the rise of personalized medicine and complex drug formulations requires sophisticated manufacturing processes that can be optimized through automation and investments in robotics, artificial intelligence (AI), and Internet of Things (IoT) technologies, which are expected to surge in the coming years, thereby driving segmental growth.
Application Insights
Based on application, the assembly line automation segment dominated the market with the largest revenue share of 30.3% in 2025. This growth can be attributed to its foundational role in mass production processes across numerous industries, such as automotive and electronics. Assembly lines enable high-volume production with consistent quality by streamlining workflows through mechanization and automation techniques. Companies have invested heavily in modernizing their assembly lines with smart technologies that enhance productivity while reducing waste.
The material handling segment is anticipated to record the fastest growth from 2024 to 2030. Organizations increasingly recognize its importance in optimizing supply chain operations. Automated solutions such as Automated Guided Vehicles (AGVs) and conveyor systems are widely adopted for their ability to enhance efficiency in transporting materials within facilities. E-commerce has also propelled demand for effective material handling solutions accommodating fast-paced order fulfillment processes.
Solution Insights
Based on the solution, the control systems segment dominated the market with the largest revenue share of 45.4% in 2025. This growth can be attributed to its critical role in managing automated processes across various industries. Control systems ensure precision and reliability in manufacturing operations, allowing companies to monitor performance metrics and make real-time adjustments. Industries increasingly focus on optimizing production lines through data-driven decision-making, driving segmental growth.
The robotics and autonomous segment is anticipated to record significant growth from 2024 to 2030, driven by advancements in AI and machine learning technologies. The increasing demand for flexible automation solutions that adapt quickly to changing production requirements pushes manufacturers toward robotic systems capable of performing complex tasks with minimal human intervention. Furthermore, as labor shortages become more pronounced across various sectors, companies are turning towards robotics as a viable solution for maintaining productivity levels while ensuring safety in hazardous environments.
Enterprise Size Insights
Based on enterprise size, the large enterprises segment dominated the market with the largest revenue share of 64.3% in 2025. This growth can be attributedto the substantial investments made by large corporations in advanced technologies. These enterprises typically have more resources for automation solutions, enabling them to enhance efficiency, reduce operational costs, and improve product quality. Adopting Industry 4.0 principles has further propelled large enterprises to integrate sophisticated automation systems into their operations.
 To learn more about this report, Download Free Sample Report
The small and medium enterprise segment (SME’s) is anticipated to record the fastest growth from 2024 to 2030. This growth can be attributed to several factors, including increased accessibility of automation technologies that were previously only affordable for larger firms. Advances in cloud computing and IoT have enabled SMEs to implement cost-effective automation solutions without significant upfront investment. Moreover, government initiatives promoting digital transformation among SMEs are expected to expand this segment further as these businesses strive for greater efficiency and competitiveness.
Regional Insights
The North America region is projected to grow at a CAGR of over 8% from 2024 to 2030, driven by the increasing demand for operational efficiency and productivity improvements across various industries. Adopting advanced technologies such as robotics, artificial intelligence (AI), and the Internet of Things (IoT) has been a significant trend, enabling manufacturers to optimize their processes and reduce labor costs. The push towards smart factories and Industry 4.0 initiatives has also accelerated investments in automation solutions.
U.S. Manufacturing Automation Market Trends
The manufacturing automation market in the U.S. accounted for a revenue share of over 63% in 2023. In the U.S., there is a growing emphasis on sustainability and energy efficiency, prompting manufacturers to adopt automated solutions that minimize waste and optimize resource utilization, thereby driving market growth. In addition, the ongoing trade tensions and supply chain disruptions have also led companies in the U.S. to reconsider their operational strategies, further driving the demand for automation.
Europe Manufacturing Automation Market Trends
The manufacturing automation market in Europe accounted for the highest revenue share of over 30% in 2023. In Europe, the trend towards digital transformation is growing, with many companies implementing Industry 4.0 practices to enhance connectivity between machines and systems. Furthermore, the aging workforce in Europe has created a pressing need for automation to fill skill gaps while maintaining production levels. Innovations in robotics technology, particularly collaborative robots (cobots), are gaining traction as they allow human workers to work alongside machines safely.
Asia Pacific Manufacturing Automation Market Trends
Asia Pacific dominated the manufacturing automation market, accounting for the largest revenue share of 38.4% in 2025. Countries in the region are at the forefront of adopting advanced manufacturing technologies such as AI-driven robotics and smart sensors. The trend toward digitalization in manufacturing processes is fueled by government initiatives to enhance competitiveness through innovation.
 To learn more about this report, Download Free Sample Report
China Manufacturing Automation Market Trends
The manufacturing automation market in the China held the largest share in the Asia Pacific region in 2025.
Key Manufacturing Automation Company Insights
Some key players operating in the market include ABB Ltd. and Rockwell Automation, Inc..
-
ABB Ltd. is one of the key players in electrification and automation technologies and specializes in providing innovative solutions that enhance productivity and efficiency across various industries, including manufacturing, utilities, transportation, and infrastructure. Their portfolio includes robotics, industrial automation systems, and digital solutions that leverage artificial intelligence and machine learning to optimize operations.
-
Rockwell Automation Inc. offers a wide range of products, including programmable logic controllers (PLCs), human-machine interfaces (HMIs), sensors, and data analytics software. The company emphasizes innovation, which enables real-time data access for better decision-making. With a strong focus on smart manufacturing and Industry 4.0 initiatives, the company aims to empower businesses to achieve greater agility and competitiveness.
Omron Corporation and Honeywell International, Inc. are some of the emerging market participants.
-
Omron Corporation is a player in automation technology and manufacturing solutions. The company specializes in various products, including industrial automation equipment, electronic components, and healthcare devices. It focuses on integrating advanced technologies such as artificial intelligence and IoT into its automation solutions.
-
Honeywell International, Inc. operates in various sectors, including aerospace, building technologies, performance materials and technologies, and safety and productivity solutions. The company focuses on enhancing operational efficiency and safety for its clients across diverse industries such as oil and gas, manufacturing, healthcare, and logistics. With a strong commitment to sustainability and innovation, the company aims to provide smart solutions that optimize processes while reducing environmental impact.
Key Manufacturing Automation Companies
The following are the leading companies in the manufacturing automation market.
- ABB Ltd.
- FANUC CORPORATION
- Honeywell International, Inc.
- Mitsubishi Electric Corporation
- Motoman (Yaskawa America, Inc.)
- Omron Corporation
- Reko Automation Inc.
- Rockwell Automation Inc.
- Schneider Electric
- Teradyne, Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (ABB Ltd., FANUC CORPORATION, Honeywell International, Inc., Mitsubishi Electric Corporation, Yaskawa Electric Corporation)
- Focus on end-to-end industrial automation solutions, including robotics, control systems, industrial software, and digital manufacturing platforms.
- Invest heavily in R&D, global expansion, and ecosystem partnerships with system integrators and industrial clients across automotive, electronics, energy, and process industries.
- Strong global footprint, advanced technology portfolios across robotics, control systems, and industrial software, deep domain expertise, and long-standing relationships with large industrial customers.
- High R&D capabilities enable continuous innovation in AI-driven automation, energy-efficient systems, and connected manufacturing solutions.
- High product and system complexity, significant capital intensity, and dependence on cyclical industrial demand.
- Strong competition among incumbents, long sales cycles, and high customization requirements increase operational and integration challenges.
Emerging & Specialized Players (REKO Automation Inc., Motoman)
- Focus on niche automation solutions such as custom robotics integration, machine-specific automation, retrofit solutions, and specialized industrial applications.
- Emphasize cost-effective, flexible, and application-specific automation systems tailored for SMEs and mid-sized manufacturers.
- Strong agility, ability to offer customized and cost-efficient solutions, faster deployment cycles, and close customer relationships. Expertise in specific industries or applications enables targeted innovation and responsive service support.
- Limited global scale and brand recognition compared to established players.
- Restricted R&D budgets and weaker technology portfolios in advanced AI, IIoT, and large-scale industrial platforms.
Recent Developments
-
In June 2024, Honeywell International, Inc. launched its Battery Manufacturing Excellence Platform (Battery MXP), an AI-powered software solution aimed at revolutionizing large-scale battery manufacturing, designed to optimize giga factory operations from the outset by improving battery cell yields and accelerating facility startups.
-
In April 2024, Honeywell International, Inc. announced several key developments in its automation solutions, highlighting advancements in digital transformation and sustainability initiatives. The company unveiled new products designed to enhance operational efficiency and safety across various industries, including manufacturing and logistics.
-
In September 2023, ABB Ltd. announced a significant investment of $280 million to expand its manufacturing footprint in Europe and build a new state-of-the-art ABB Robotics European Campus in Sweden. The investment aims to enhance ABB's ability to meet the growing demand for robotics and automation solutions close to its European customers.
Manufacturing Automation Market Report Scope
Report Attribute
Details
Market size in 2025
USD 15.4 billion
Estimated market size in 2026
USD 17.3 billion
Projected market size by 2033
USD 32.3 billion
Growth rate
CAGR of 9.3% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Component, deployment, technology, end-use, application, industry vertical, solution, enterprise size, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; China; Australia; Japan; India; South Korea; Brazil; South Africa; Saudi Arabia; UAE
Key companies profiled
ABB Ltd.; FANUC CORPORATION; Honeywell International, Inc.; Mitsubishi Electric Corporation; Motoman (Yaskawa America, Inc.); Omron Corporation; Reko Automation Inc.; Rockwell Automation Inc.; Schneider Electric; Teradyne, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Manufacturing Automation Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global manufacturing automation market report based on component, technology, deployment, end use, industry vertical, application, solution, enterprise size, and region:
-
Component Outlook (Revenue, USD Million, 2021 - 2033)
-
Hardware
-
Software
-
Services
-
Professional Services
-
Managed Services
-
-
-
Technology Outlook (Revenue, USD Million, 2021 - 2033)
-
PLC
-
Robotics
-
-
Deployment Outlook (Revenue, USD Million, 2021 - 2033)
-
On-premises
-
Cloud-based
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Discrete Manufacturing
-
Process Manufacturing
-
-
Industry Vertical Outlook (Revenue, USD Million, 2021 - 2033)
-
Automotive
-
Consumer Electronics
-
Healthcare
-
Transportation and Logistics
-
Others
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Assembly Line Automation
-
Material Handling Automation
-
Welding and Fabrication Automation
-
Transportation and Logistics
-
Packaging Automation
-
Others
-
-
Solution Outlook (Revenue, USD Million, 2021 - 2033)
-
Control Systems
-
Monitoring and Diagnostics
-
Robotics and Autonomous Systems
-
-
Enterprise Size Outlook (Revenue, USD Million, 2021 - 2033)
-
SMEs
-
Large Enterprises
-
-
Regional Outlook (Revenue, USD Million, 2021 - 20332021 - 20332021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
Australia
-
Japan
-
India
-
South Korea
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
-
Research Methodology
The manufacturing automation market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each manufacturing automation segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Component
Revenue capture definition
Hardware
Revenue is generated through the sale of industrial robots, PLCs, sensors, actuators, drives, machine vision systems, HMIs, and other automation hardware components.
Software
Revenue is generated through licensing and subscriptions of MES, SCADA, industrial analytics platforms, digital twin software, and automation management systems.
Services
Revenue is generated through installation, integration, maintenance, training, consulting, and technical support services for automation systems.
Segment - Technology
Revenue capture definition
PLC
Revenue is generated through the sale, installation, programming, upgrades, and maintenance of programmable logic controllers and associated automation control systems.
Robotics
Revenue is generated through industrial robot sales, collaborative robots (cobots), robotic arms, autonomous mobile robots (AMRs), robotic integration, software, and maintenance services.
Segment - Deployment
Revenue capture definition
On-premises
Revenue is generated through the deployment, licensing, implementation, and maintenance of automation software and control systems installed within manufacturing facilities.
Cloud-based
Revenue is generated through subscription-based cloud automation platforms, remote monitoring solutions, industrial IoT platforms, analytics services, and cloud-hosted manufacturing applications.
Segment - End Use
Revenue capture definition
Discrete Manufacturing
Revenue is generated through automation solutions deployed in the production of individual products such as automobiles, electronics, machinery, aerospace components, and consumer goods.
Process Manufacturing
Revenue is generated through automation systems used in continuous and batch production industries including chemicals, pharmaceuticals, food & beverage, oil & gas, pulp & paper, and utilities.
Segment - Industry Vertical
Revenue capture definition
Automotive
Revenue is generated through automation solutions for vehicle assembly, welding, painting, material handling, quality inspection, and powertrain manufacturing.
Consumer Electronics
Revenue is generated through automation systems used for electronics assembly, semiconductor manufacturing, PCB production, testing, inspection, and packaging.
Healthcare
Revenue is generated through automation solutions supporting pharmaceutical manufacturing, medical device production, laboratory automation, and packaging operations.
Transportation and Logistics
Revenue is generated through warehouse automation, automated material handling systems, autonomous guided vehicles (AGVs), conveyor systems, sorting solutions, and logistics automation.
Others
Revenue is generated through automation deployments across industries such as metals & mining, chemicals, energy, food & beverage, textiles, pulp & paper, and construction materials.
Segment - Application
Revenue capture definition
Assembly Line Automation
Revenue is generated through automated assembly systems, robotic assembly cells, conveyor systems, and integrated production line solutions.
Material Handling Automation
Revenue is generated through automated storage and retrieval systems (AS/RS), conveyors, robotic picking systems, AGVs, AMRs, and warehouse automation solutions.
Welding and Fabrication Automation
Revenue is generated through robotic welding systems, automated cutting, fabrication equipment, laser processing systems, and welding control software.
Transportation and Logistics
Revenue is generated through automation solutions for internal factory logistics, warehouse management, automated sorting, palletizing, and distribution operations.
Packaging Automation
Revenue is generated through automated machinery for filling, labeling, sealing, palletizing, inspection, and packaging integrated into manufacturing processes.
Others
Revenue is generated through other automation applications, including machine tending, quality inspection, predictive maintenance, process monitoring, and industrial inspection systems.
Segment - Solution
Revenue capture definition
Control Systems
Revenue is generated through the sale and implementation of distributed control systems (DCS), programmable logic controllers (PLCs), SCADA systems, HMIs, and industrial control software.
Monitoring and Diagnostics
Revenue is generated through industrial monitoring platforms, condition monitoring systems, predictive maintenance software, machine health diagnostics, and industrial analytics solutions.
Robotics and Autonomous Systems
Revenue is generated through industrial robots, collaborative robots, autonomous mobile robots, robotic software, fleet management platforms, and robotic integration services.
Segment - Enterprise Size
Revenue capture definition
SME’s
Revenue is generated through the deployment of scalable and cost-effective automation hardware, software, cloud platforms, and managed services adopted by small and medium-sized enterprises.
Large Enterprises
Revenue is generated through large-scale automation projects, enterprise-wide digital manufacturing platforms, robotics deployments, industrial software, and long-term automation service contracts across multiple production facilities.
Estimation Model
Layer Name
Key Question
Description
Industrial Demand & End-User Layer
Who drives demand for manufacturing automation?
Represents the demand side of the market, including automotive, electronics, pharmaceuticals, food & beverage, chemicals, aerospace, metals & mining, and logistics industries. Demand is driven by the increasing need for productivity improvement, labor shortage mitigation, quality enhancement, cost optimization, and rapid adoption of smart manufacturing and Industry 4.0 transformation initiatives across global manufacturing sectors.
Technology & Enabling Systems Layer
What technologies enable manufacturing automation?
Includes core enabling technologies such as industrial robotics, programmable logic controllers (PLCs), SCADA systems, AI and machine learning, Industrial IoT (IIoT), machine vision systems, edge computing, cloud platforms, digital twins, sensors, motion control systems, industrial communication protocols, cybersecurity solutions, and predictive analytics tools that support intelligent and connected manufacturing operations.
Automation Platforms & Solution Delivery Layer
How is manufacturing automation deployed and operated?
Covers the systems, platforms, and solutions used to design, deploy, and operate automation in manufacturing environments, including control systems, robotics platforms, manufacturing execution systems (MES), distributed control systems (DCS), human-machine interfaces (HMI), industrial software platforms, warehouse automation systems, material handling systems, and system integrators enabling end-to-end production automation.
Revenue Generation & Monetization Layer
How is revenue generated in the manufacturing automation market?
Revenue in the manufacturing automation market is generated from the sale of hardware, such as robots, PLCs, sensors, and control systems, used in production automation. Revenue streams further include software solutions, including MES, SCADA, and industrial analytics platforms, offered through licensing or subscription models. Additionally, services such as system integration, installation, maintenance, consulting, and managed services contribute significant recurring revenue through long-term industrial contracts.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Market Sizing, Competitive Landscape & Growth Opportunity Assessment
Assessed the global manufacturing automation market size, historical and forecast growth trends, and detailed segmentation by component (hardware, software, services), technology (PLC, robotics, control systems), deployment (on-premises, cloud-based), end-use (discrete manufacturing, process manufacturing), industry vertical (automotive, electronics, healthcare, logistics, others), application (assembly, material handling, welding, packaging, others), solution (control systems, monitoring & diagnostics, robotics & autonomous systems), and enterprise size (SMEs, large enterprises).
Supports strategic market entry and expansion decisions, identifies high-growth segments such as robotics, AI-driven automation, and smart factories, improves capital allocation across industries, enables data-driven product development, and strengthens long-term revenue forecasting and investment planning.
Competitive Benchmarking & Strategic Positioning Analysis
Benchmarked leading manufacturing automation companies such as ABB Group, FANUC, Siemens AG, Rockwell Automation, Schneider Electric, Mitsubishi Electric, based on robotics capabilities, industrial software portfolios, control systems strength, AI and IIoT integration, global manufacturing presence, and service ecosystems.
Supports competitive differentiation in robotics, control systems, and industrial software; identifies technology gaps in AI-driven automation and digital manufacturing platforms; enhances M&A and partnership strategies; improves ecosystem positioning; and strengthens innovation-led competitive advantage.
Regional Market Demand & Industrial Adoption Analysis
Analyzed regional demand across North America, Europe, Asia Pacific, Latin America, and Middle East & Africa, evaluating factors such as industrialization rate, manufacturing output, labor cost pressures, automation penetration, government initiatives (Industry 4.0, smart factories), smart factories, supply chain maturity, infrastructure readiness, and adoption of robotics and IIoT technologies.
Supports geographic expansion strategy, identifies high-growth manufacturing hubs such as China, India, Germany, Japan, and the US, improves localization and deployment strategies, enables region-specific industrial partnerships, and strengthens long-term global manufacturing footprint planning.
Frequently Asked Questions About This Report
The global manufacturing automation market size was valued at USD 15.4 billion in 2025 and is estimated at USD 17.3 billion for 2026.
The global manufacturing automation market is expected to grow at a CAGR of 9.3% from 2026 to 2033, reaching USD 32.3 billion by 2033.
Some key players operating in the manufacturing automation market include ABB Ltd., FANUC CORPORATION, Honeywell International, Inc., Mitsubishi Electric Corporation, Motoman (Yaskawa America, Inc.), Omron Corporation, Reko Automation Inc., Rockwell Automation Inc., Schneider Electric, and Teradyne, Inc.
Key factors that are driving the manufacturing automation market growth include the growing adoption of Industry 4.0, the commercialization of next-generation networks (NGNs) and the growing emphasis on optimum utilization of resources along with improved efficiency.
The PLC segment dominated the market, with a share of 71.7% in 2025.
The on-premises segment dominated the market in 2025.
The discrete manufacturing segment dominated the market in 2025.
The assembly line automation segment dominated the market in 2025.
Asia Pacific dominated with a 38.4% revenue share in 2025.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


