
- Home
- »
- Next Generation Technologies
- »
-
MEA Sovereign AI Market Size & Share Report, 2026-2033GVR Report cover

MEA Sovereign AI Market (2026 - 2033)
Size, Share & Trends Analysis Report By Component (Hardware, Software, Services), By Deployment Model (Cloud, On premises, Hybrid), By Technology, By End Use, By Country, And Segment Forecasts
Market Size, 2025
$2.9BMarket Estimate, 2026
$3.4BMarket Forecast, 2033
$13.0BCAGR, 2026–2033
20.8%MEA Sovereign AI Market Summary
The MEA sovereign AI market size was valued at USD 2.9 billion in 2025 and is projected to grow from USD 3.4 billion in 2026 to USD 13.0 billion by 2033, growing at a CAGR of 20.8% from 2026 to 2033. The market is driven by rising investment in sovereign AI infrastructure, growing adoption of localized large language models, increasing demand for in-country AI computing capacity, strengthening data residency and digital sovereignty regulations, and expanding government-industry collaborations to build national AI ecosystems.
Key Market Trends & Insights
- By component: The hardware segment dominated the market, with a revenue share of over 48.0% in 2025.
- By deployment model: The on-premises segment dominated the market, with a revenue share of 43.0% in 2025.
- By technology: The machine learning segment held the largest revenue share in 2025.
- By end use: The government & public sector segment held the largest revenue share in 2025.
Market Size & Forecast
- Market size in 2025: USD 2.9 Billion
- Estimated market size in 2026: USD 3.4 Billion
- Projected market size by 2033: USD 13.0 Billion
- CAGR (2026-2033): 20.8%
Prism AI by Grand View Research Free to tryAsk a question about the MEA sovereign AI marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Growing demand for Arabic-native AI models is driving investments in localized large language models and generative AI platforms across the Middle East. Governments and enterprises are increasingly seeking AI systems capable of understanding regional languages, cultural contexts, and sector-specific requirements. The development of Arabic-focused models is reducing dependence on globally developed AI platforms while improving the relevance of AI applications for local users. Technology companies are collaborating with regional organizations to expand Arabic datasets, model training capabilities, and specialized AI applications. This trend is positioning language localization and cultural intelligence as important components of the region's sovereign AI strategy.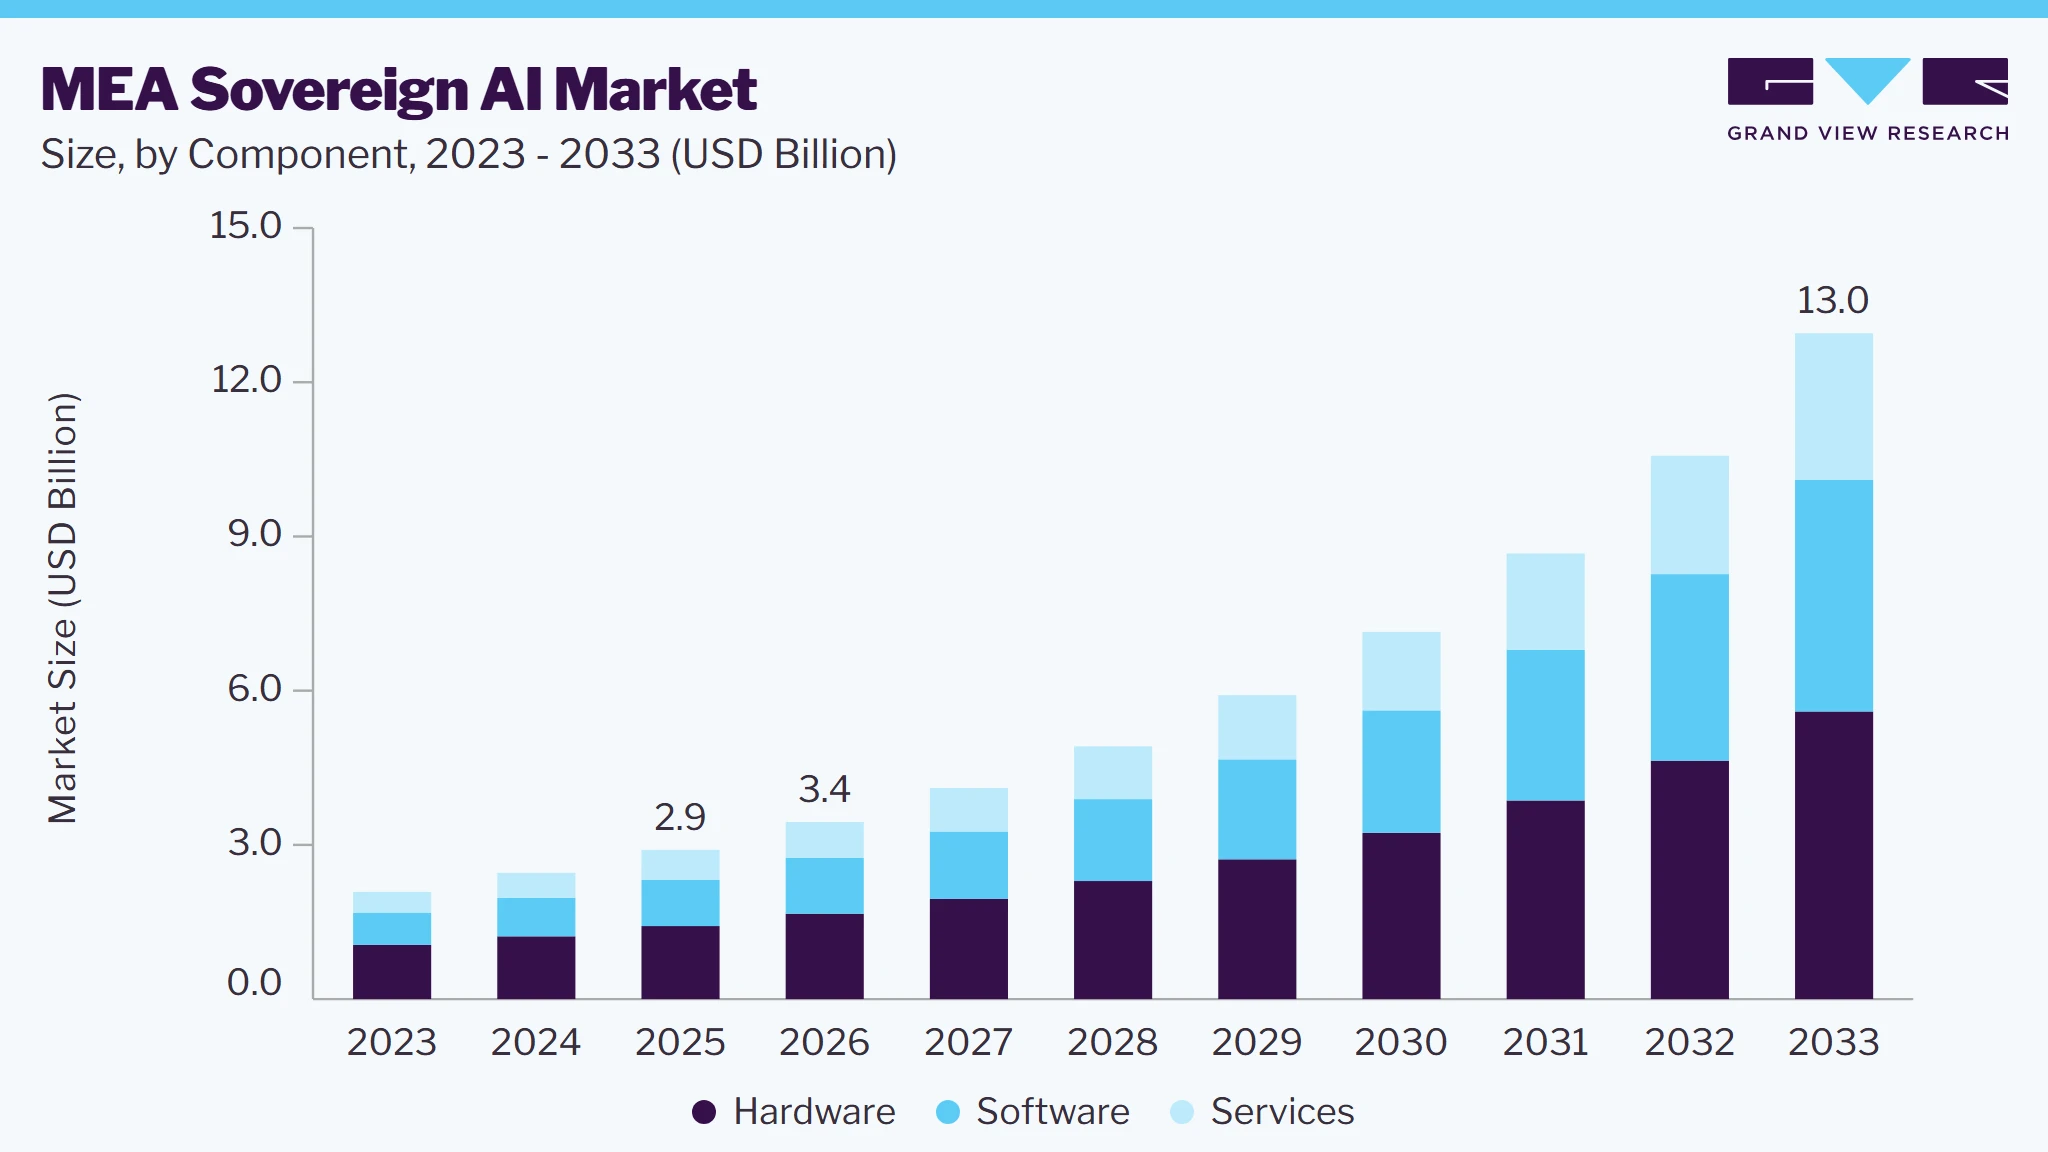 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Government-led initiatives are increasingly driving the formation of integrated sovereign AI ecosystems across major MEA economies. National AI strategies are combining infrastructure investments, regulatory frameworks, research programs, workforce development, and partnerships with global technology providers. Public-sector organizations are also encouraging collaboration among cloud companies, semiconductor providers, telecom operators, universities, and AI startups to accelerate the development of domestic capabilities. These initiatives are creating stronger pathways for AI technologies to transition from pilot projects into large-scale government and enterprise deployments. The trend is increasing national participation across the AI value chain and strengthening the region's long-term technological competitiveness.
The rapid expansion of sovereign AI infrastructure is increasing attention toward energy availability, cooling requirements, water consumption, and infrastructure resilience across MEA markets. Large AI facilities require substantial electricity and advanced cooling systems, creating additional planning requirements for countries developing high-density GPU infrastructure. The resource intensity of AI is encouraging stakeholders to evaluate renewable power, efficient cooling technologies, and alternative data-center designs alongside computing capacity. Infrastructure resilience is also becoming increasingly important as governments seek to protect strategic AI facilities and maintain uninterrupted access to critical digital services. This is driving a broader transition toward sustainable, resilient, and resource-aware sovereign AI infrastructure planning.
Market Dynamics
The MEA market is being supported by increasing public-sector spending on dedicated computing facilities, GPU clusters, national data centers, and sovereign cloud services. Rising requirements for data localization, information security, regulatory adherence, and domestic processing are encouraging organizations to retain sensitive workloads within national borders. Growing adoption of Arabic foundation models, generative applications, machine learning, and autonomous AI systems is creating demand for region-specific training data and specialized computing resources. Government agreements with telecom companies, cloud providers, chip manufacturers, and AI developers are accelerating investments in locally controlled technology capabilities. Meanwhile, electricity availability, advanced cooling, high-speed networks, and physical protection are influencing the design and expansion of large-scale AI facilities across the region.
Government spending on sovereign AI infrastructure, GPU clusters, AI data centers, high-performance computing facilities, and national cloud services is increasing across the MEA region. Saudi Arabia and the UAE are allocating substantial capital toward large-scale computing capacity to support domestic AI training, inference, and enterprise workloads. Investments from government entities and sovereign investment institutions are further supporting the development of advanced computing facilities and digital infrastructure. This sustained funding is strengthening demand for AI accelerators, servers, storage systems, networking equipment, cloud platforms, and data-center services.
The expansion of dedicated computing facilities is encouraging technology providers to establish regional operations and deliver solutions aligned with national requirements. Increasing procurement of AI hardware, computing capacity, data storage, cybersecurity solutions, and cloud infrastructure is supporting broader investment across the market. Government-led projects are also creating opportunities for international technology companies to participate through infrastructure agreements, technology partnerships, and local deployment initiatives. Continued public and sovereign investment is therefore expected to remain a key catalyst for the development of domestic AI computing capacity and national technology capabilities.
The development of Arabic-language foundation models, generative AI platforms, machine learning applications, speech technologies, and region-specific AI solutions presents significant growth opportunities across MEA. Increasing demand for AI systems that understand regional languages, cultural contexts, regulatory requirements, and sector-specific use cases is encouraging investment in localized model development. Government agencies and enterprises are increasingly evaluating relevant AI applications for public services, financial services, healthcare, education, telecommunications, and business operations. This shift is creating opportunities across model development, training datasets, inference services, natural language processing, AI software, and supporting computing infrastructure.
The expansion of localized AI capabilities can also reduce reliance on externally developed models for sensitive government and enterprise applications. Growing demand for Arabic content generation, translation, speech recognition, document processing, and intelligent automation is driving additional demand for specialized AI technologies. Regional developers can benefit from access to local datasets, government programs, research initiatives, and strategic technology partnerships. As adoption increases, localized AI is expected to create new commercial opportunities across AI platforms, model services, data solutions, cybersecurity, cloud computing, and specialized applications.
Limited access to advanced GPUs, AI accelerators, semiconductor components, high-density servers, and specialized computing equipment can constrain the expansion of sovereign AI capabilities across MEA. Large-scale AI facilities also require substantial amounts of electricity, cooling capacity, network bandwidth, and physical infrastructure, thereby increasing project development costs. Export controls and licensing requirements for advanced AI processors can further affect procurement schedules and restrict access to certain high-performance computing technologies. These factors can create challenges for countries seeking to rapidly expand domestic AI training and inference capacity.
Dependence on imported hardware can increase procurement costs, supply-chain exposure, infrastructure lead times, and project execution risks. Countries with limited domestic semiconductor manufacturing and advanced data-center capabilities may face additional challenges in securing critical components and maintaining sufficient computing capacity. High power consumption and cooling requirements can also place pressure on infrastructure planning, particularly for large GPU-intensive facilities. Consequently, hardware availability, supply-chain constraints, energy requirements, and infrastructure readiness may limit the pace of sovereign AI deployment and capacity expansion across the region.
Market Concentration & Characteristics
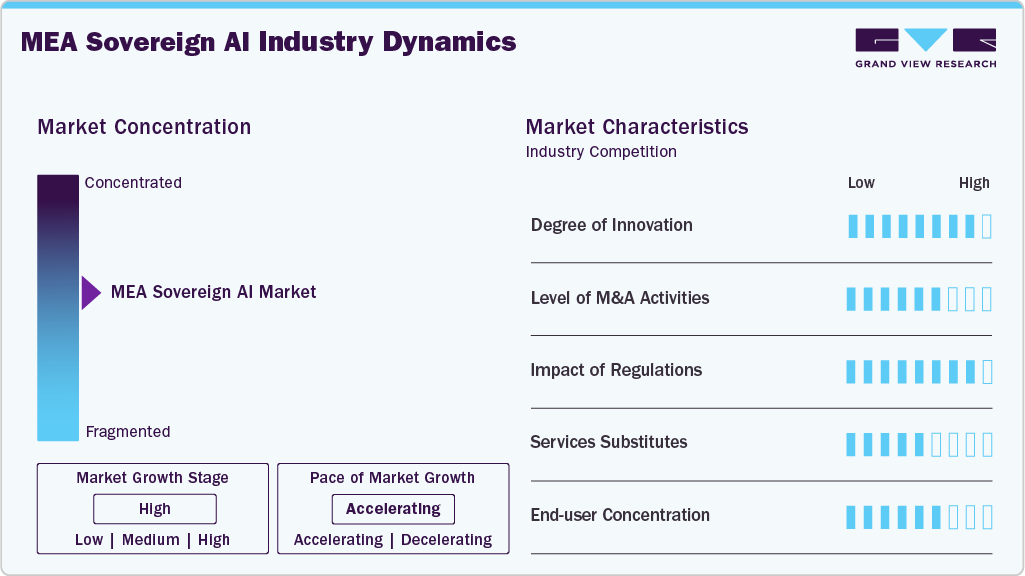
The MEA sovereign AI industry is moderately concentrated, with Saudi Arabia and the UAE accounting for a significant share of regional investments in AI infrastructure and national computing capabilities. The market is largely shaped by government programs, sovereign investment, AI data centers, GPU capacity, national cloud services, and locally developed AI models. Qatar and other Gulf countries are also increasing investments in computing facilities, AI applications, and digital infrastructure to strengthen domestic capabilities. High capital requirements and strong government participation make large-scale infrastructure projects an important characteristic of the regional market.
 To learn more about this report, Download Free Sample Report
The competitive landscape includes regional AI companies, telecom operators, cloud providers, data-center operators, semiconductor suppliers, and international technology firms. International companies remain important for advanced GPUs, servers, cloud technologies, AI software, and other specialized components required for large-scale deployments. The market is characterized by high infrastructure costs, lengthy project development periods, data localization requirements, cybersecurity priorities, and growing demand for Arabic-language AI solutions. Increasing investment in AI computing, cloud platforms, networking, security, and localized applications is expected to broaden competition across the region.
Analyst Perspective
The market is progressing from individual AI projects toward large-scale national deployments, supported by expanding government budgets and long-term infrastructure programs. Rising demand for domestic GPU capacity, high-performance computing, sovereign cloud, localized datasets, and Arabic-language models is creating opportunities across both infrastructure and software segments. Growing collaboration between regional organizations and international technology providers is enabling access to advanced computing and AI capabilities while maintaining greater control over sensitive workloads. Continued investment in AI data centers, cybersecurity, data governance, and local technical capabilities is expected to strengthen the region's position as a major market for sovereign AI adoption.
Component Insights
The hardware segment dominated the market, accounting for over 48.0% of revenue in 2025, driven by rising investments in AI data centers, increasing deployment of GPU accelerators, expanding high-performance computing capacity, growing demand for AI servers and networking equipment, and government-led development of sovereign computing infrastructure. The deployment of dedicated computing facilities is increasing demand for GPUs, AI accelerators, servers, storage systems, and high-speed networking hardware across MEA. Growing requirements for local AI model training and inference are further encouraging investments in high-density computing equipment. The expansion of national AI infrastructure is also increasing the procurement of specialized hardware required to process sensitive workloads within domestic jurisdictions. As countries strengthen their sovereign computing capabilities, continued investment in AI hardware capacity and supporting data-center equipment is expected to sustain the segment's leading position.
The software segment is expected to see significant growth over the forecast period, owing to the increasing adoption of sovereign AI platforms, localized AI models, generative AI applications, AI agents, and secure machine learning solutions. Rising demand for data governance, model management, cybersecurity, and regulatory compliance is encouraging organizations to deploy software designed for domestic AI environments. Government agencies and enterprises are also increasing investments in AI development platforms, natural language processing, computer vision, and automated decision-making applications. The growing deployment of Arabic-language and sector-specific models is further driving demand for specialized AI software across government, financial services, healthcare, telecommunications, and other industries. As regional organizations expand their use of AI, demand for scalable software platforms, model orchestration, application management, and AI security solutions is expected to increase.
Deployment Model Insights
The on-premises segment accounted for a significant market revenue share of 43.0% in 2025, supported by rising requirements for data sovereignty, strict information security, regulatory compliance, and direct control over sensitive AI workloads. Government agencies and regulated enterprises are increasingly deploying AI infrastructure within dedicated facilities to retain data and computing operations within national borders. On-premises environments also provide greater control over GPU resources, model training, data access, network security, and system configuration, which is important for sovereign AI applications. Growing investments in national AI data centers and high-performance computing facilities are further supporting demand for privately managed deployments across the region. The segment is therefore benefiting from the increasing preference for secure, locally controlled AI infrastructure among government and enterprise users.
The cloud segment is projected to grow significantly over the forecast period, driven by rising demand for scalable AI computing, sovereign cloud platforms, flexible GPU access, and secure remote infrastructure. Growing investments in national cloud environments are enabling governments and enterprises to deploy AI workloads while maintaining greater control over data storage and processing. The expansion of cloud-based AI services, model training, inference platforms, and AI application development is further increasing demand for distributed computing resources. Cloud deployment also provides organizations with greater flexibility to scale computing capacity according to workload requirements without making equivalent investments in physical infrastructure. Consequently, rising adoption of localized cloud services, AI-as-a-Service, GPU-as-a-Service, and managed AI platforms is expected to accelerate the segment's growth across regions.
Technology Insights
The machine learning segment accounted for over 29.0% of market revenue in 2025, driven by increasing adoption of predictive analytics, automated decision-making, intelligent process optimization, and data-driven applications across government and enterprise environments. The growing use of machine learning for fraud detection, cybersecurity, public service automation, financial analysis, healthcare, and industrial applications is driving demand for locally controlled AI capabilities. Government initiatives focused on developing domestic AI capabilities are also encouraging investment in model training, regional datasets, computing resources, and machine learning platforms. The increasing availability of GPU infrastructure and specialized computing facilities is improving the capacity to develop and deploy complex machine learning models within national jurisdictions. As organizations expand AI adoption across critical applications, machine learning is expected to remain a major technology segment within the market.
The generative AI segment is projected to experience substantial growth, driven by increasing demand for localized large language models, Arabic-language AI, automated content generation, intelligent assistants, and AI agents across government and enterprise applications. Rising investments in sovereign computing infrastructure are enabling organizations to train and deploy generative models within national jurisdictions while maintaining greater control over sensitive data. Government agencies are also exploring generative AI for document processing, citizen services, knowledge management, translation, public-sector automation, and decision support. The growing development of region-specific datasets and foundation models is further supporting the deployment of generative AI solutions aligned with local languages and regulatory requirements. Consequently, increasing investment in AI model development, GPU computing, cloud platforms, data infrastructure, and application software is expected to accelerate generative AI adoption across the MEA region.
End Use Insights
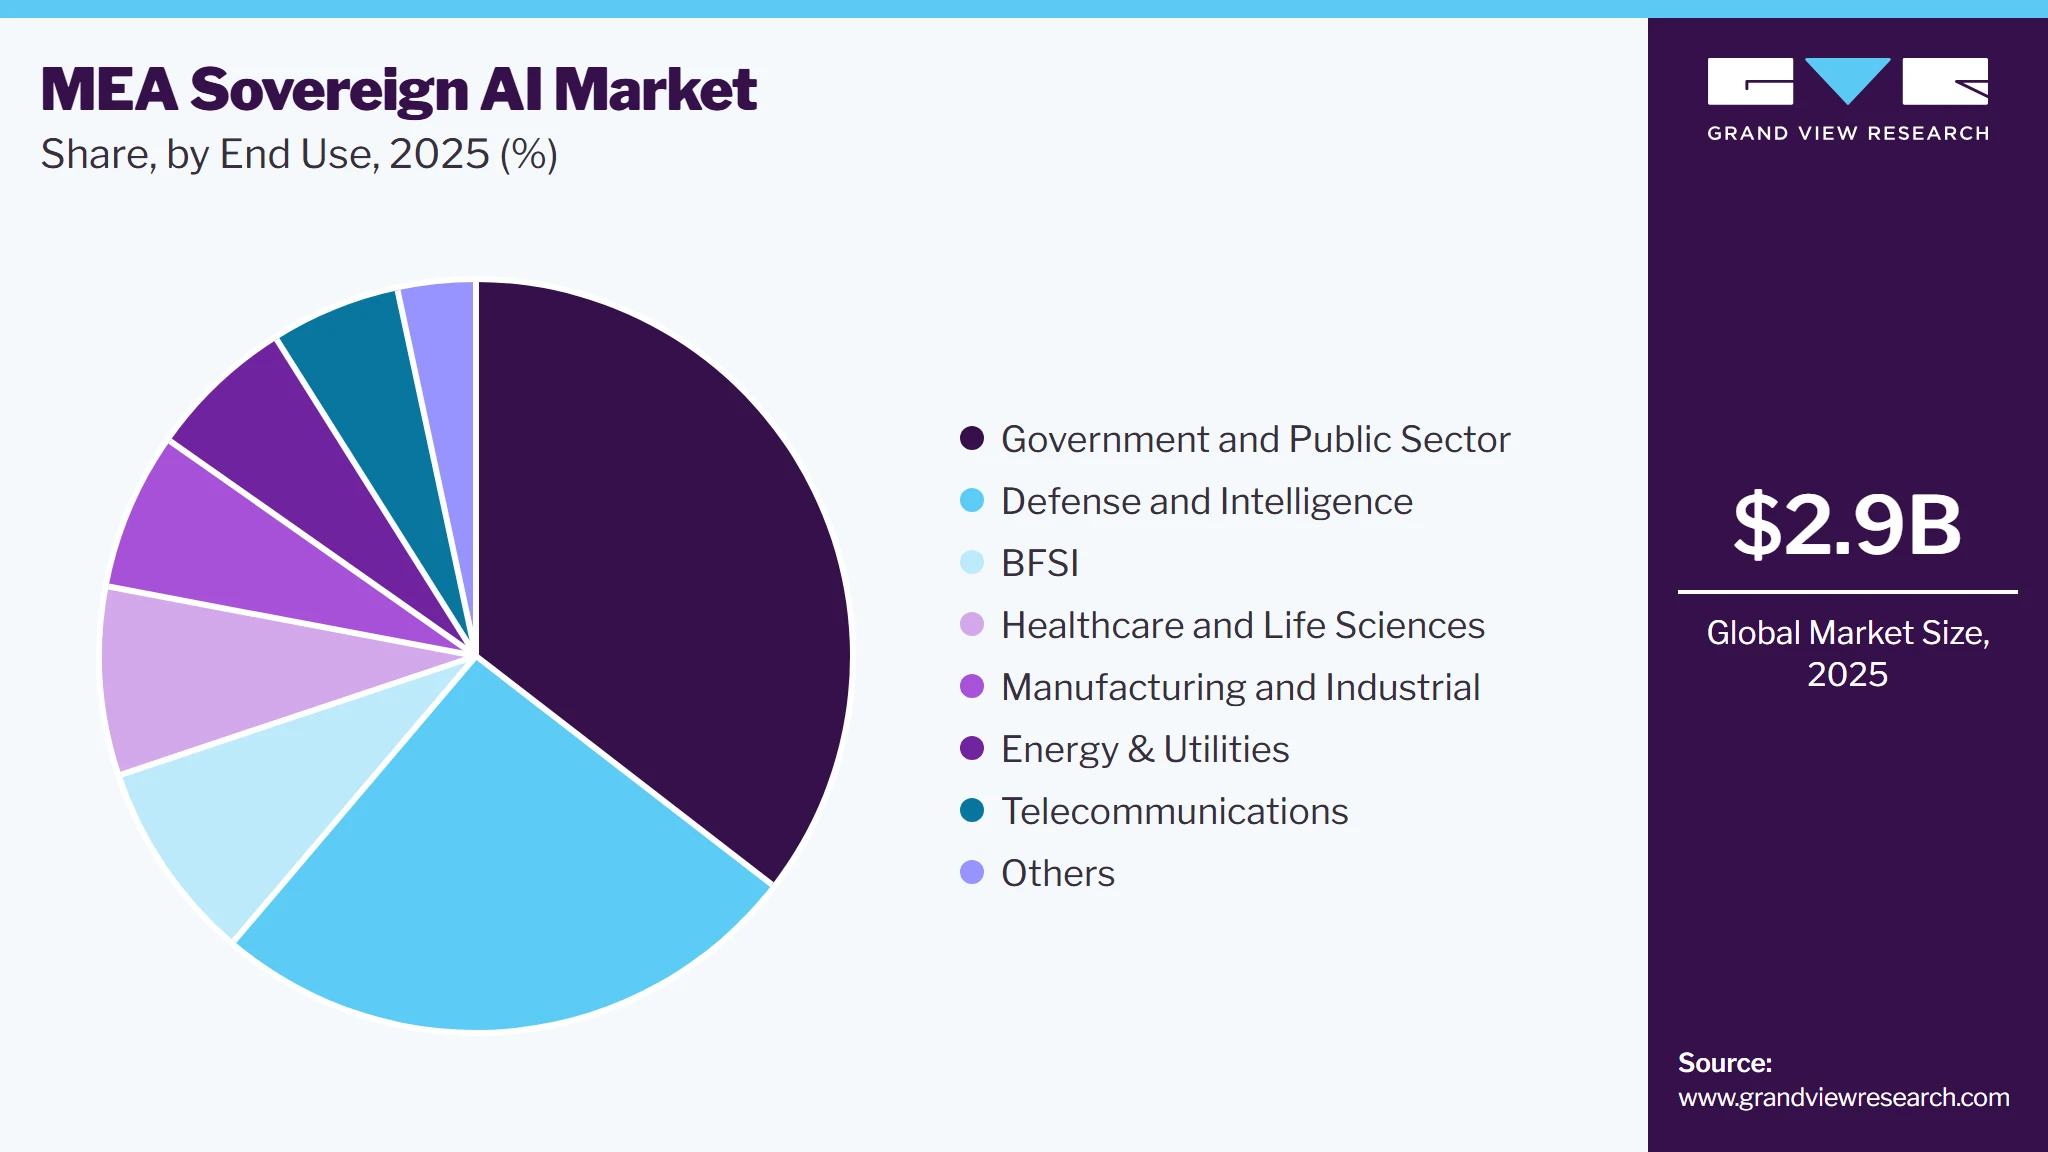
The government and public sector segment accounted for the largest market revenue share of over 35.0% in 2025. The segment's leading position was supported by rising government spending on national AI programs, secure computing infrastructure, data sovereignty, public service automation, and AI-enabled decision-making. Governments are also deploying sovereign AI for defense, public administration, healthcare, education, citizen services, and critical infrastructure management, increasing demand for locally controlled AI capabilities. Rising focus on national security, regulatory compliance, sensitive data protection, and domestic AI capacity is further encouraging public agencies to develop and operate AI workloads within national jurisdictions. Continued implementation of national AI strategies and government-led infrastructure projects is expected to sustain demand for AI hardware, software, cloud services, computing facilities, and cybersecurity solutions across the public sector.
 To learn more about this report, Download Free Sample Report
The telecommunications segment is expected to experience substantial growth during the forecast period, owing to the increasing deployment of AI-enabled network management, rising demand for localized cloud and edge computing, expanding 5G infrastructure, growing adoption of AI-driven cybersecurity, and increased investment in sovereign digital infrastructure. Telecom operators are increasingly integrating AI into network optimization, predictive maintenance, customer service, fraud detection, and traffic management to improve operational efficiency. The expansion of 5G and edge computing is also creating demand for distributed AI processing closer to users and connected devices. Rising investments in national connectivity infrastructure are further supporting the deployment of secure data centers, private networks, AI computing resources, and localized processing capabilities. As telecom providers strengthen their digital infrastructure, demand for AI platforms, computing hardware, network security, and data management solutions is expected to increase across the MEA region.
Country Insights
The KSA sovereign AI market is gaining momentum through the rapid development of Arabic-focused foundation models, generative AI platforms, and locally trained machine learning systems tailored to the requirements of the Saudi government and enterprises. Increasing demand for Arabic natural language processing, intelligent assistants, automated document analysis, and sector-specific AI applications is encouraging investment in domestic datasets and model development capabilities. These developments are strengthening local AI capabilities while creating demand for AI software, model training services, specialized computing resources, data management, and cybersecurity solutions.
UAE Sovereign AI Market Trends
The sovereign AI market in the UAE is witnessing robust growth, supported by government-led AI investments, national computing initiatives, sovereign cloud deployments, and the expansion of advanced data center infrastructure. Increasing adoption of GPU computing, Arabic-language models, generative AI, AI agents, and secure local processing is strengthening domestic capabilities for sensitive government and enterprise workloads. Strategic collaborations among UAE government entities, telecom operators, cloud providers, and AI technology companies are further accelerating investment in localized computing capacity, data governance, cybersecurity, and AI application development.
Key MEA Sovereign AI Company Insights
Some key companies in the sovereign AI industry are G42, HUMAIN, Core42, Presight, NVIDIA., and others.
-
Core42 specializes in sovereign cloud, AI computing infrastructure, high-performance computing, data governance, and secure AI deployment for governments and regulated industries. Its Sovereign Public Cloud combines cloud computing capabilities with UAE-specific controls for data residency, security, compliance, and governance, while its AI infrastructure supports model training and inference. In July 2026, Core42 and e& UAE also launched Sovereign AI Compute, providing on-demand GPU infrastructure within the UAE.
-
Presight is a UAE-based AI company specializing in big-data analytics, machine learning, predictive intelligence, and AI-powered applications for governments and enterprises. Its solutions address areas including public safety, crisis management, energy, smart infrastructure, and digital sovereignty, with a strong focus on processing large and sensitive datasets. The company therefore contributes primarily to the AI software, analytics, data intelligence, and government application segments of the market.
Key MEA Sovereign AI Companies
-
G42
-
HUMAIN
-
Core42
-
Presight
-
e&
-
stc Group
-
DataVolt
-
Aramco
-
NVIDIA
-
Microsoft
-
AWS
-
Oracle
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: G42, Microsoft, Amazon Web Services (AWS), Alphabet (Google), Oracle
- Mature players focus on expanding sovereign cloud infrastructure, AI computing capacity, national data centers, foundation models, and secure AI platforms through government partnerships, regional investments, and enterprise deployments across MEA.
- Their competitive advantage is supported by large-scale computing infrastructure, established cloud platforms, advanced AI capabilities, extensive regional operations, strong government relationships, and broad enterprise technology portfolios.
- These companies face challenges from strict data localization requirements, government procurement complexities, geopolitical considerations, high infrastructure costs, and growing preference for locally controlled AI technologies.
Emerging Players: HUMAIN, Core42, Presight, e&, DataVolt
- Emerging players focus on developing localized AI models, sovereign computing facilities, GPU infrastructure, AI-ready data centers, secure cloud platforms, and region-specific AI applications aligned with national AI strategies.
- Their competitive advantage comes from strong government backing, regional market knowledge, localized technology capabilities, faster decision-making, strategic partnerships, and direct alignment with national data sovereignty requirements.
- These companies face limitations related to dependence on imported AI chips and advanced computing technologies, comparatively smaller international customer bases, high capital requirements, limited global scale, and reliance on strategic government investments.
Recent Developments:
-
In July 2026, e& UAE partnered with Core42 to deliver Sovereign AI Compute, providing enterprises and government organizations with secure, in-country access to GPU infrastructure to build, train, fine-tune, and deploy AI applications. The offering combines Core42’s Sovereign AI Cloud with e& UAE’s national-scale digital infrastructure and secure connectivity, enabling sensitive AI workloads and data to remain within the UAE. The partnership strengthens the UAE’s sovereign AI ecosystem by expanding access to scalable, secure AI infrastructure for sectors including government, healthcare, financial services, energy, education, and manufacturing.
-
In July 2026, HUMAIN partnered with Canadian AI company Cohere to develop AI computing infrastructure and support sovereign AI models and enterprise AI solutions in Saudi Arabia. Under the partnership, HUMAIN will allocate at least 50 MW of dedicated AI computing capacity, with the infrastructure expected to become operational in Q4 2027 and potentially expand over the following five years. The collaboration will also support the development of sovereign Arabic-language AI models and sector-specific solutions, strengthening Saudi Arabia’s domestic AI infrastructure and sovereign AI capabilities.
-
In July 2026, Magna AI collaborated with Arabic.AI to accelerate the development and deployment of Arabic-native sovereign AI capabilities across Saudi Arabia. The partnership combines Magna AI’s sovereign AI infrastructure, platforms, security, governance, and AI Factory capabilities with Arabic.AI’s sovereign Arabic large language models, agentic AI platforms, and Arabic-native AI technologies. The collaboration is expected to support secure, production-ready AI deployments for government and enterprise organizations while strengthening Saudi Arabia’s data sovereignty and domestic AI capabilities.
MEA Sovereign AI Market Report Scope
Report Attribute
Details
Market size in 2025
USD 2.9 billion
Estimated market size in 2026
USD 3.4 billion
Projected market size by 2033
USD 13.0 billion
Growth rate
CAGR of 20.8% from 2026 to 2033
Actual data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Component, deployment model, technology, end use, region
Country scope
KSA; UAE; South Africa
Key companies profiled
G42; HUMAIN; Core42; Presight; e&; stc Group; DataVolt; Aramco; NVIDIA; Microsoft; AWS; Oracle
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
MEA Sovereign AI Market Report Segmentation
This report forecasts revenue growth at regional and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the MEA sovereign AI market report based on component, deployment model, technology, end use, and region.
-
Component Outlook (Revenue, USD Billion, 2021 - 2033)
-
Hardware
-
Software
-
Services
-
-
Deployment Model Outlook (Revenue, USD Billion, 2021 - 2033)
-
Cloud
-
On premises
-
Hybrid
-
-
Technology Outlook (Revenue, USD Billion, 2021 - 2033)
-
Generative AI
-
Multimodal AI
-
Machine Learning
-
Computer Vision
-
Natural Language Processing (NLP)
-
Others
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Government and Public Sector
-
Defense and Intelligence
-
Healthcare and Life Sciences
-
BFSI
-
Telecommunications
-
Manufacturing and Industrial
-
Energy & Utilities
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
Middle East and Africa (MEA)
-
KSA
-
UAE
-
South Africa
-
Research Methodology
The MEA sovereign AI market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing—reconciling supply-side and demand-side estimates—and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each MEA sovereign AI segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Component
Revenue capture definition
Hardware
The hardware segment comprises physical computing infrastructure such as AI accelerators, GPUs, CPUs, AI servers, networking equipment, storage systems, and high-performance computing (HPC) resources used to develop and deploy sovereign AI. It includes dedicated infrastructure that enables secure AI training, inference, and data processing within national jurisdictions.
Software
This segment includes sovereign AI platforms, foundation models, AI development frameworks, orchestration software, analytics tools, and AI governance solutions. It covers software applications that enable secure AI development, deployment, management, and compliance across sovereign environments.
Services
Services include consulting, system integration, deployment, managed services, maintenance, training, and technical support associated with sovereign AI implementations. These services assist organizations in designing, operating, and optimizing secure AI ecosystems throughout their lifecycle.
Segment - Deployment Model
Revenue capture definition
Cloud
The cloud segment consists of sovereign cloud environments that provide scalable AI computing, storage, and application hosting while ensuring compliance with national data regulations. It enables secure access to AI capabilities through cloud-based infrastructure managed within approved jurisdictions.
On-premises
This on-premises segment covers AI infrastructure deployed within an organization's own facilities or government-controlled data centers. It provides maximum control over sensitive data, AI models, and computing resources for highly regulated environments.
Hybrid
Hybrid segment combines on-premises infrastructure with sovereign cloud resources to balance security, scalability, and operational flexibility. It enables organizations to distribute AI workloads according to performance, compliance, and data sensitivity requirements.
Segment - Technology
Revenue capture definition
Generative AI
The generative AI segment includes AI technologies capable of generating text, images, code, audio, video, and other digital content using foundation models and large language models (LLMs). It supports content creation, automation, simulation, and knowledge generation within sovereign AI environments.
Multimodal AI
This multimodal AI segment encompasses AI systems capable of processing and integrating multiple data formats, including text, images, audio, video, and sensor data. It enables richer contextual understanding and more advanced decision-making across complex sovereign AI applications.
Machine Learning
Machine learning refers to AI algorithms that learn from structured and unstructured data to generate predictions, classifications, recommendations, and automated decisions. It forms the core analytical technology supporting intelligent automation and data-driven operations.
Computer Vision
The computer vision segment includes AI technologies that analyze and interpret images, videos, and visual information captured from cameras and sensors. It supports applications such as surveillance, defense, industrial inspection, healthcare imaging, and autonomous systems.
Natural Language Processing (NLP)
This Natural Language Processing (NLP) segment comprises AI technologies that enable machines to understand, interpret, generate, and respond to human language. It supports multilingual communication, document analysis, conversational AI, and intelligent search capabilities.
Others
The others segment includes emerging AI technologies such as reinforcement learning, knowledge graphs, symbolic AI, federated learning, explainable AI, and other specialized AI techniques. These technologies complement core AI capabilities across diverse sovereign AI use cases.
Segment - End Use
Revenue capture definition
Government and Public Sector
The government and public sector segment comprise sovereign AI solutions deployed by government agencies, public institutions, and regulatory bodies to improve public services, digital governance, cybersecurity, and administrative operations. It supports secure AI adoption while maintaining national control over sensitive information.
Defense and Intelligence
This defense and intelligence segment includes AI applications used for military operations, intelligence analysis, surveillance, cybersecurity, command systems, and national security missions. It focuses on highly secure AI capabilities that support strategic defense objectives.
Healthcare and Life Sciences
Healthcare and life sciences cover sovereign AI applications used for medical diagnostics, clinical decision support, biomedical research, drug discovery, healthcare administration, and population health management. The segment emphasizes secure handling of sensitive health and research data.
BFSI
The BFSI segment includes banks, financial institutions, insurers, and payment service providers utilizing sovereign AI for fraud detection, risk management, compliance, customer intelligence, and operational automation. It prioritizes regulatory compliance, financial data protection, and secure AI deployment.
Telecommunications
This telecommunications segment encompasses telecom operators and communication service providers deploying sovereign AI for network optimization, predictive maintenance, cybersecurity, customer service, and intelligent network management. It supports secure digital communication infrastructure and resilient network operations.
Manufacturing and Industrial
Manufacturing and industrial includes sovereign AI solutions used for production optimization, predictive maintenance, quality inspection, supply chain management, robotics, and industrial automation. The segment focuses on improving operational efficiency while protecting industrial data and intellectual property.
Energy & Utilities
The Energy & Utilities segment consists of AI deployments across electricity, oil & gas, renewable energy, water, and utility operations to optimize asset performance, grid management, predictive maintenance, and energy forecasting. It supports secure management of critical national infrastructure.
Others
This others segment includes sovereign AI deployments across sectors such as retail, education, transportation, agriculture, media, logistics, aerospace, and other industries adopting secure AI technologies. It captures emerging commercial applications beyond the primary end-use industries.
Estimation Model
Layer No.
Layer Name
Key Questions
Description
01
National AI Readiness & Sovereignty Demand Layer
Who drives sovereign AI demand across MEA?
Assess national AI strategies, data sovereignty policies, cybersecurity priorities, and digital transformation programs across major MEA countries to identify demand from governments, defense, regulated industries, and critical infrastructure.
02
Sovereign AI Infrastructure & Compute Investment Layer
Who invests in sovereign AI infrastructure?
Evaluate investments in AI data centers, GPUs, HPC, sovereign cloud, networking, and AI computing infrastructure supporting domestic AI development and deployment across MEA.
03
AI Platform, Model & Solution Adoption Layer
Who deploys sovereign AI technologies?
Measure adoption of LLMs, generative AI, machine learning, AI agents, Arabic AI models, and AI governance platforms across government and key industries in MEA.
04
MEA Sovereign AI Revenue Realization Layer
How much revenue is generated?
Estimate revenue from AI hardware, software, cloud services, infrastructure, platform licensing, implementation, and managed services across MEA sovereign AI deployments.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Sovereign AI Infrastructure Assessment
Assessed AI data centers, GPUs, HPC, sovereign cloud, and AI accelerators across key MEA markets.
Identifies infrastructure gaps, investment priorities, and growth opportunities.
Country-Level Market Assessment
Evaluated Saudi Arabia, UAE, Qatar, South Africa, Egypt, and other MEA markets based on AI investments and national programs.
Highlights high-potential countries, market maturity, and investment hotspots.
Industry-Specific AI Adoption Analysis
Analyzed adoption across government, defense, BFSI, healthcare, telecom, energy, and manufacturing.
Provides insights into sector demand, adoption trends, and commercial opportunities.
Localized AI & Arabic Model Assessment
Evaluated Arabic AI models, LLMs, generative AI, and AI agents across MEA.
Identifies opportunities in localized models, datasets, and AI applications.
Sovereign Cloud & AI Software Assessment
Assessed sovereign cloud, AI platforms, governance, and cybersecurity solutions.
Supports technology planning, partnerships, and software investment decisions.
Frequently Asked Questions About This Report
The global MEA sovereign AI market size was valued at USD 2.9 billion in 2025 and is estimated at USD 3.4 billion for 2026.
The global MEA sovereign AI market is expected to grow at a CAGR of 20.8% from 2026 to 2033, reaching USD 13.0 billion in 2033
The hardware segment led with a 48.0% revenue share in 2025, while software is the fastest-growing segment.
The machine learning segment led with a 29.0% revenue share in 2025, while the generative AI segment is the fastest-growing.
Key factors driving market growth include government investments in AI infrastructure, data sovereignty requirements, national AI strategies, the expansion of sovereign data centers, and demand for localized AI models.
Some key players operating in the MEA sovereign AI market include G42, HUMAIN, Core42, Presight, e&, stc Group, DataVolt, Aramco, NVIDIA, Microsoft, AWS, and Oracle.
The on-premises segment led with a 43.0% revenue share in 2025, while the cloud segment is the fastest-growing.
The government & public sector segment held the largest revenue share in 2025.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


