
- Home
- »
- Plastics, Polymers & Resins
- »
-
Mechanical Recycling Of Plastics Market (2026 - 2033)GVR Report cover

Mechanical Recycling Of Plastics Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Polyethylene (PE), Polyethylene Terephthalate (PET), Polypropylene (PP)), By Application (Packaging, Automotive), By Region, And Segment Forecasts
Market Size, 2025
$39.9BMarket Estimate, 2026
$43.0BMarket Forecast, 2033
$72.1BCAGR, 2026–2033
7.6%Mechanical Recycling Of Plastics Market Summary
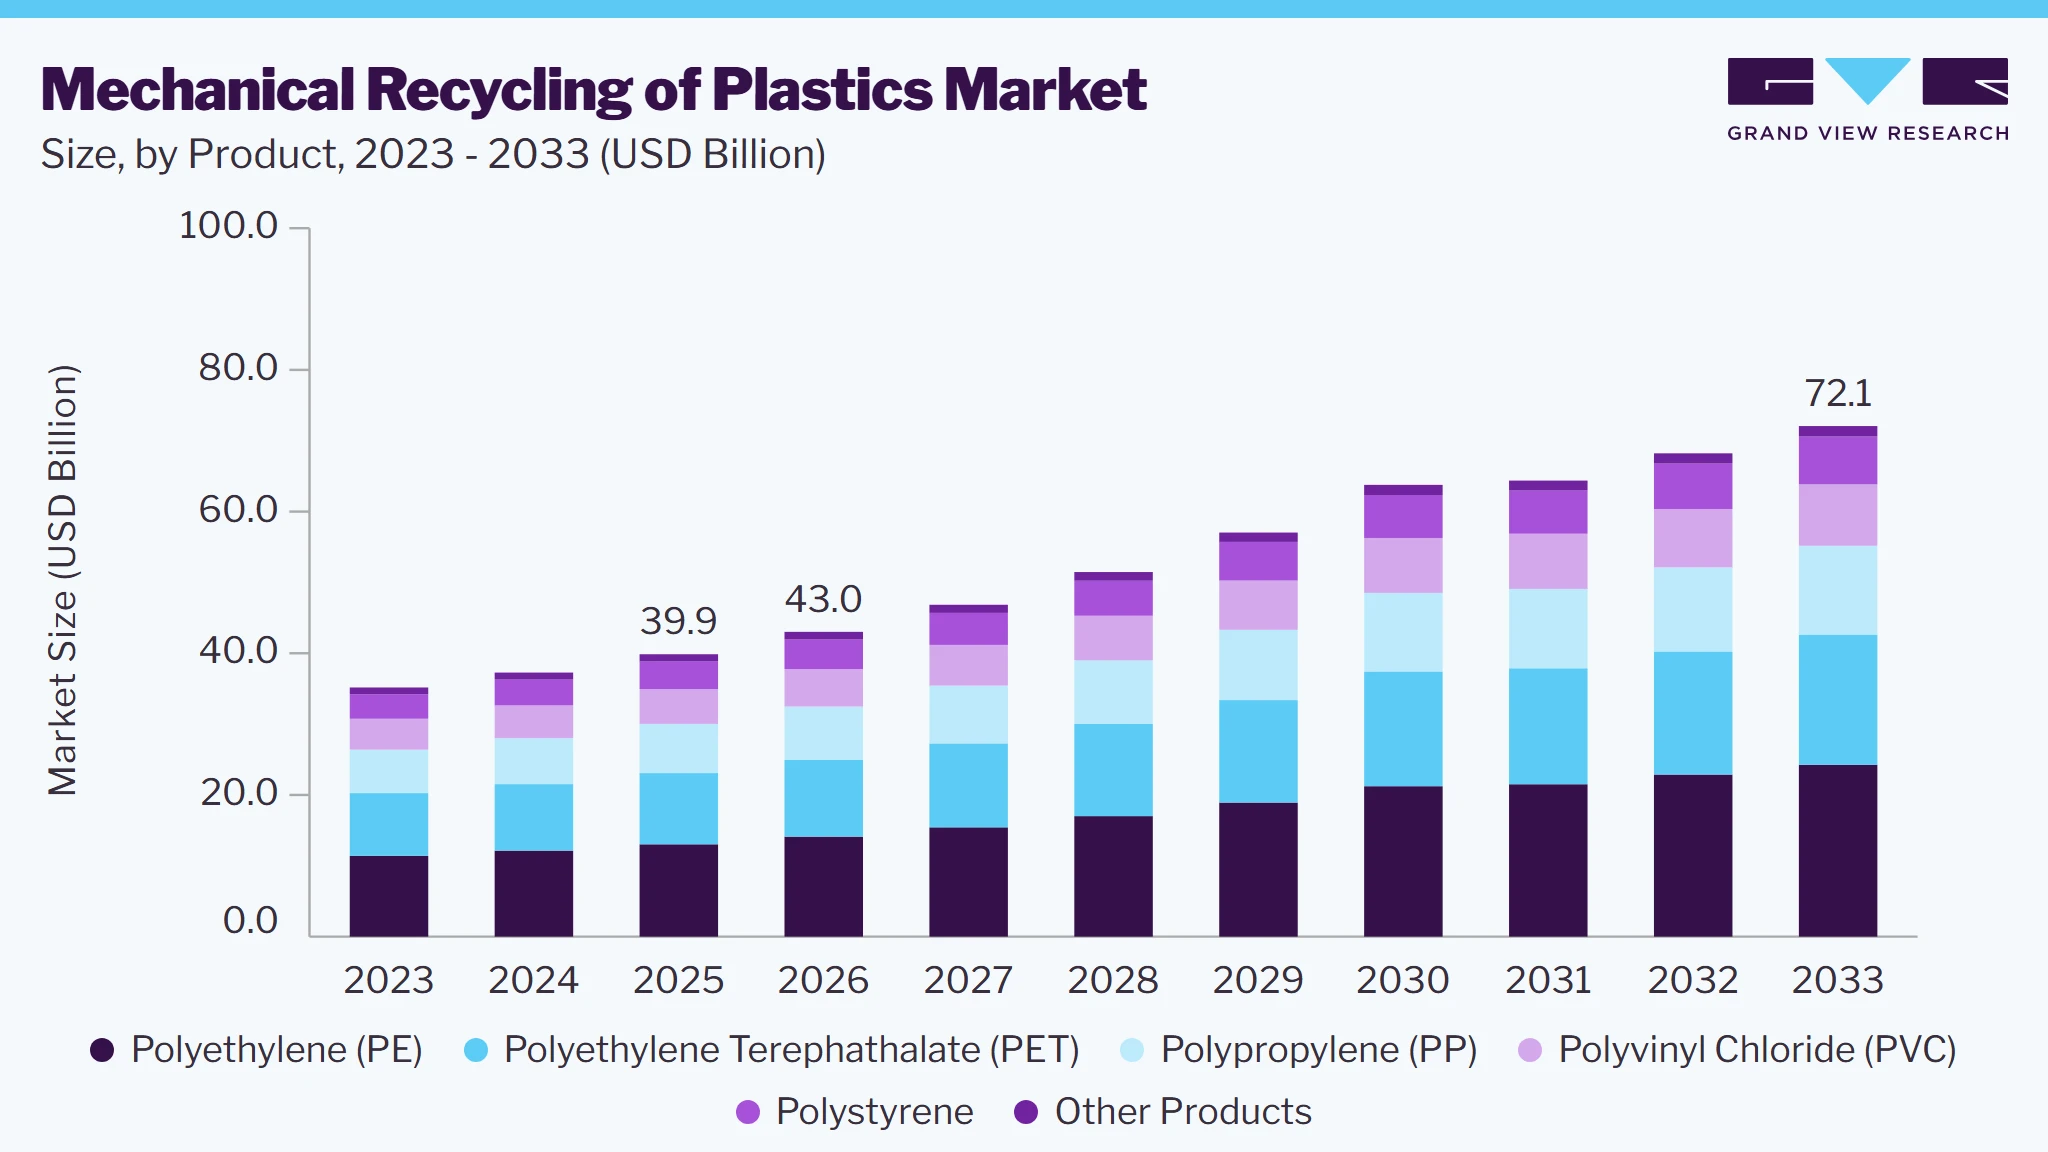
The global mechanical recycling of plastics market size was valued at USD 39.9 billion in 2025 and is projected to grow from USD 43.0 billion in 2026 to USD 72.1 billion by 2033, at a CAGR of 7.6% from 2026 to 2033. The market in Europe dominated with a revenue share of 33.7% in 2025. Rising threat of non-biodegradable plastic pollution globally is driving demand for sustainable plastic waste management solutions owing to increasing environmental concerns, stricter sustainability initiatives, and growing emphasis on circular economy practices and resource conservation.
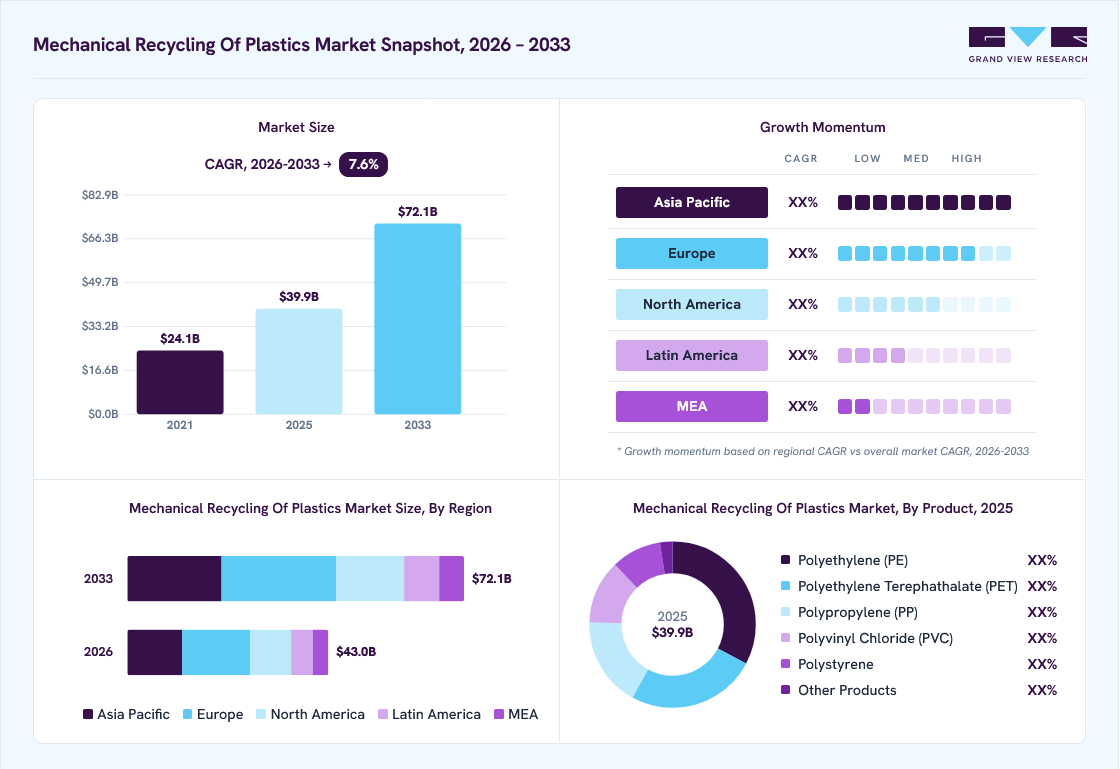 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Polyethylene (PE) segment held the largest market share of 32.7% in 2025.
- By application: Packaging segment held the largest market share of 35.1% in 2025.
Regional Highlights
- Largest regional market: Europe (33.7% revenue share, 2025)
- By country: Germany held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 39.9 Billion
- Estimated market size in 2026: USD 43.0 Billion
- Projected market size by 2033: USD 72.1 Billion
- CAGR (2026-2033): 7.6%
Prism AI by Grand View Research Free to tryAsk a question about the mechanical recycling of plastics marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →In recent years, the market has seen a shift towards circular economy models, where plastics are reused and recycled multiple times. Governments, particularly in Europe and North America, are pushing for stricter regulations on plastic waste management, encouraging industries to adopt sustainable recycling practices.
 To learn more about this report, Download Free Sample Report
Large consumer brands are also pledging to increase the use of recycled plastics in their packaging, boosting demand for mechanical recycling. The trend towards greater transparency and traceability in recycling processes is also growing, with companies investing in technologies that ensure the quality and purity of recycled plastics.
Market Dynamics
The mechanical recycling of plastics market is experiencing significant growth, driven by the increasing adoption of circular economy practices and sustainable plastic waste management strategies. Rising implementation of recycling models that enable plastic reuse, resource recovery, and waste reduction is supporting market expansion. Stricter government regulations on plastic waste management, particularly across developed economies, are encouraging industries to strengthen recycling practices. Additionally, growing commitments by consumer brands to increase recycled plastic content in packaging, coupled with rising investments in advanced recycling technologies that enhance material quality, traceability, and process transparency, are accelerating demand for mechanical recycling solutions globally.
The mechanical recycling of plastics market is witnessing strong growth, driven by stringent government regulations aimed at reducing plastic waste and promoting sustainable waste management practices. Increasing implementation of extended producer responsibility (EPR) programs, single-use plastic restrictions, and mandatory recycling policies is encouraging industries to adopt mechanical recycling solutions to improve resource efficiency, reduce landfill waste, and support circular economy objectives.
Market growth is further supported by rising environmental awareness and increasing consumer preference for sustainable products containing recycled plastic content. Growing commitments by manufacturers to meet regulatory requirements and corporate sustainability goals are accelerating the adoption of mechanical recycling services across packaging, consumer goods, automotive, and other end-use industries, supporting long-term market expansion throughout the forecast period.
Contamination of plastic waste streams remains a major restraint for the mechanical recycling of plastics market. Mixed polymers, food-contaminated plastics, and the presence of non-recyclable materials reduce the quality and performance of recycled plastics, limiting their suitability for high-value applications. Additionally, extensive sorting, cleaning, and separation processes require advanced technologies and increase operational costs, reducing the economic viability of recycling operations. Inefficient waste collection and segregation systems in several regions further constrain processing efficiency and scalability. These challenges hinder the widespread adoption of mechanical recycling, particularly in developing economies with limited recycling infrastructure.
Expansion of recycling infrastructure across emerging markets is creating significant growth opportunities for the mechanical recycling of plastics market. Rapid urbanization, industrialization, and increasing plastic waste generation are driving demand for sustainable waste management solutions and efficient recycling systems. Growing government initiatives to strengthen waste management infrastructure and promote circular economy practices are encouraging investments in mechanical recycling facilities. Additionally, increasing participation of recycling companies through technology transfer, infrastructure development, and processing expertise is improving recycling capacity, supporting the production of high-quality recycled plastics, and driving long-term market growth across developing economies.
Analyst Perspective
The mechanical recycling of plastics market is expected to shift from a volume-driven to a value-driven, technology-enabled industry, supported by stricter recycling regulations, circular economy initiatives, and rising demand for high-quality recycled polymers. Packaging will remain the primary demand sector, while automotive, construction, electronics, textiles, and consumer goods increasingly adopt recycled plastics to meet sustainability and regulatory requirements. Growth will be driven by AI-enabled sorting, automated recovery, digital traceability, contamination reduction, and food-grade and application-specific recycled resins. Companies with integrated collection, sorting, and recycling capabilities, strong supply networks, partnerships, and advanced technologies will be better positioned to secure quality feedstock and strengthen competitiveness. However, inconsistent waste quality, feedstock availability, contamination, virgin plastic pricing, regulatory changes, and competition from chemical recycling will continue to affect profitability. Long-term success will depend on innovation, efficiency, supply chain integration, and the ability to deliver certified, high-performance recycled materials that meet evolving customer and regulatory expectations.
Product Insights
Based on product, thepolyethylene (PE) segment led the market with the largest revenue share of 32.7% in 2025. This can be attributed to the rising global production and consumption of PE, especially in packaging, which is a significant driver for the mechanical recycling of PE plastics. PE, being one of the most commonly used plastics, contributes a substantial portion of plastic waste. Governments and regulatory bodies are setting stricter recycling targets for PE materials, particularly in the packaging sector, which relies heavily on PE for products like plastic bags, bottles, and wraps. Moreover, brand owners and retailers are committing to incorporating higher percentages of recycled PE into their products, driven by consumer demand for sustainable packaging solutions. This is increasing the need for effective mechanical recycling technologies that can process PE efficiently and produce high-quality recycled material suitable for reuse in new products.
The polyethylene terephthalate (PET) segment is expected to grow at a significant rate over the forecast period. The surge in demand for sustainable packaging, particularly in the beverage and food industries, is a major driver for the mechanical recycling of PET plastics. PET is widely used in the production of bottles, containers, and packaging films, making it a significant contributor to plastic waste. As consumers and regulatory bodies push for eco-friendly packaging, brands are increasingly using recycled PET (rPET) to reduce their environmental footprint. Government regulations, such as mandatory recycled content in packaging, are further fueling the demand for PET recycling. The clear recyclability of PET, combined with its ability to retain quality through multiple recycling cycles, positions it as a key material in the transition towards a circular economy, boosting the need for advanced mechanical recycling processes.
Application Insights
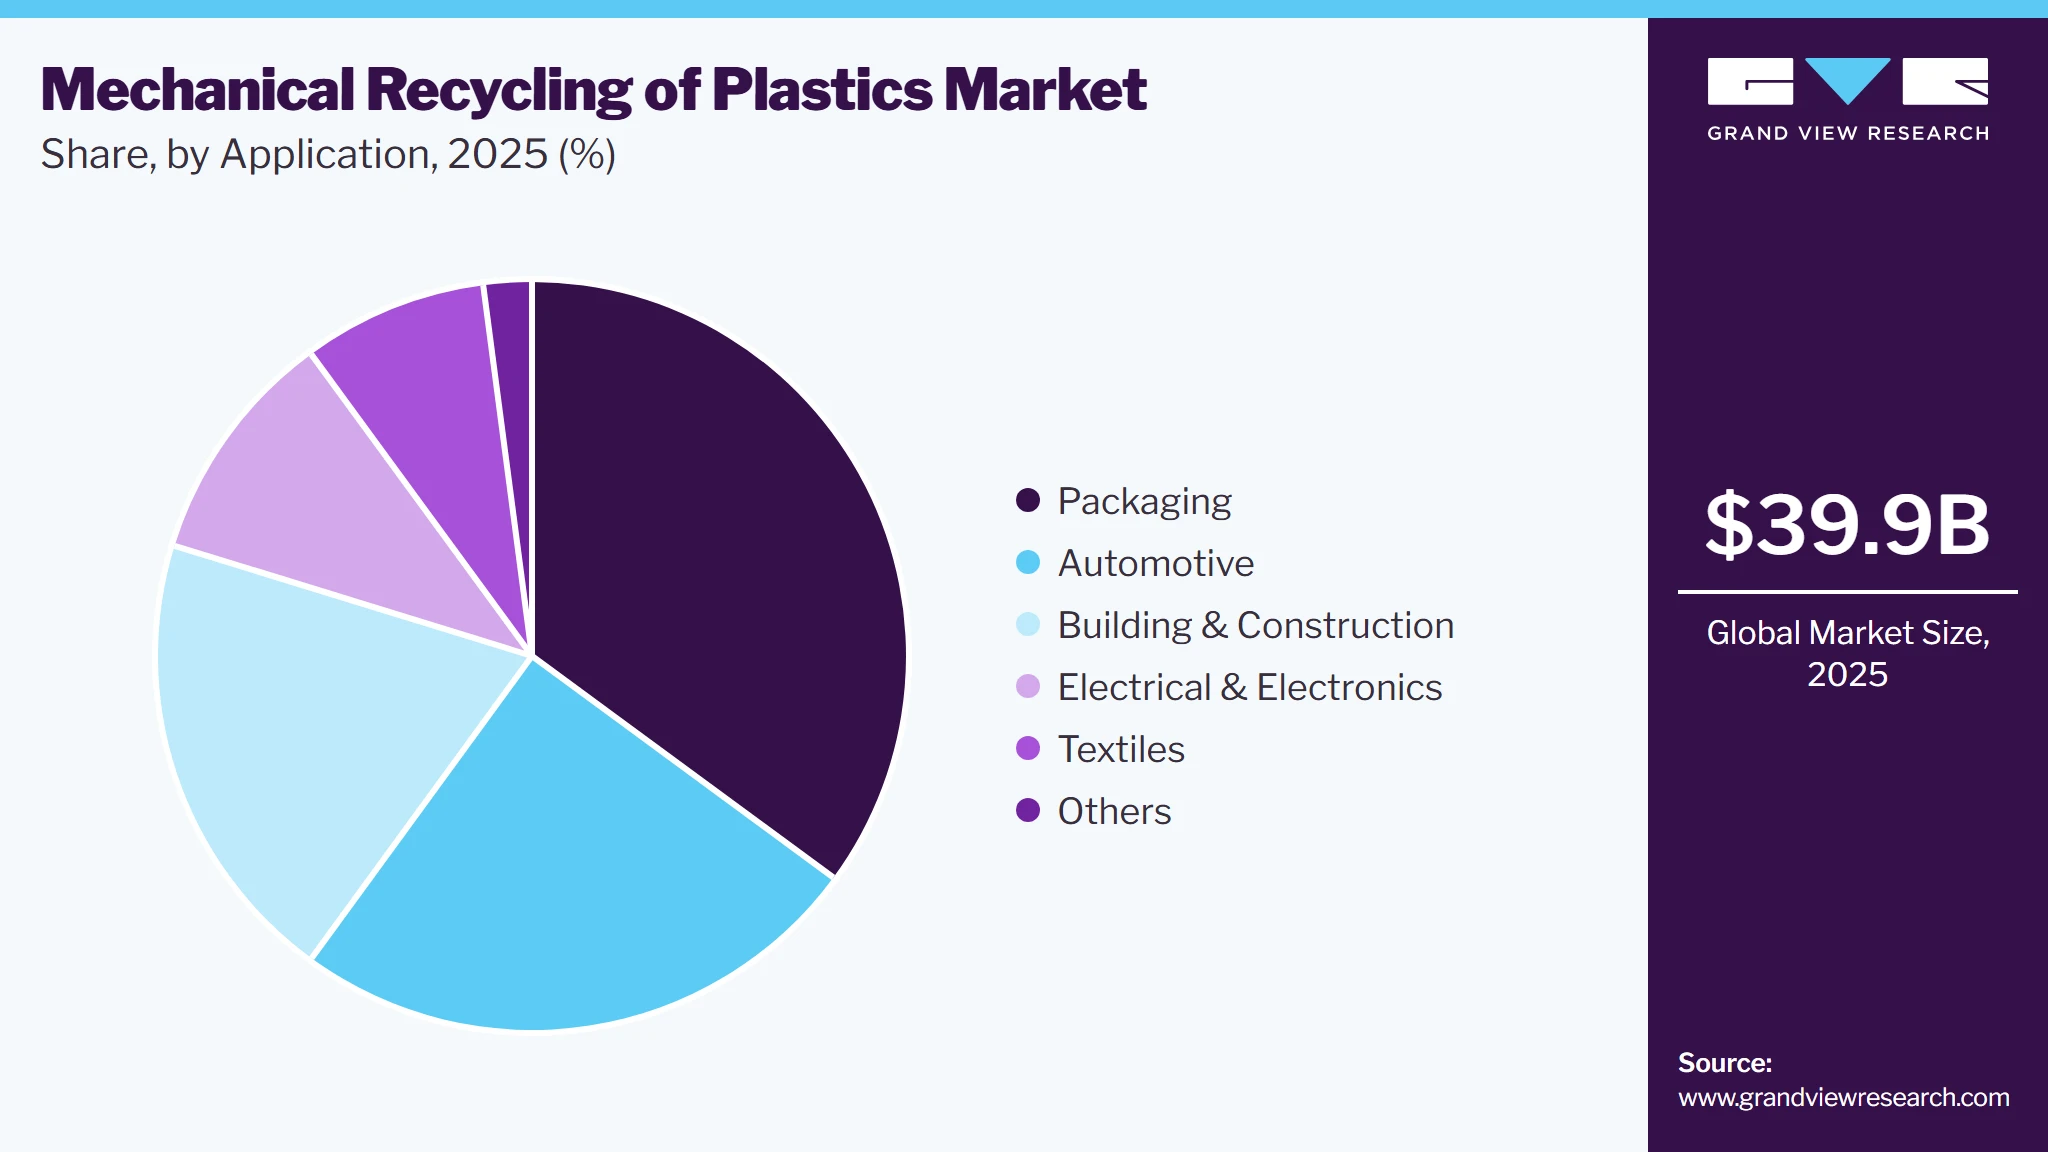
Based on application, the packaging segment led the market with the largest revenue share of 35.1% in 2025. The push for reducing plastic waste and creating more sustainable packaging solutions is a key driver in the mechanical recycling of plastics within the packaging market. Packaging is one of the largest contributors to plastic waste, with single-use plastics being a major concern. Governments worldwide are imposing stricter regulations on the use of virgin plastics, encouraging the use of recycled materials in packaging production. In addition, global brands and retailers are committing to ambitious sustainability goals, such as using 100% recyclable or reusable packaging by 2030. This is increasing the demand for mechanical recycling solutions, which can transform post-consumer packaging waste into high-quality recycled materials, reducing reliance on virgin plastics and contributing to a more circular economy.
 To learn more about this report, Download Free Sample Report
The automotive segment is poised to grow at a significant CAGR from 2026 to 2033. The increasing focus on sustainability and lightweighting in the automotive industry is a significant driver for the mechanical recycling of plastics. Automakers are under growing pressure to reduce the environmental impact of their vehicles, both during production and at the end of their life cycle. Mechanical recycling offers an efficient way to reuse plastic components from scrapped vehicles, such as bumpers, interior panels, and under-the-hood parts. Furthermore, regulatory mandates in regions like Europe are promoting the use of recycled materials in vehicle manufacturing, aiming to lower carbon emissions and meet circular economy goals. The ability to recycle and reuse automotive plastics not only reduces waste but also helps automakers cut material costs while enhancing their sustainability credentials, driving increased demand for mechanical recycling solutions in the sector.
Regional Insights
The North America mechanical recycling of plastics market is boosted by the drive towards corporate sustainability commitments and extended producer responsibility (EPR) programs. Major consumer brands and manufacturers are facing growing pressure from both consumers and regulators to reduce their use of virgin plastics and increase the incorporation of recycled content.
U.S. Mechanical Recycling Of Plastics Market Trends
The U.S. mechanical recycling of plastics market is propelled by the drive to reduce plastic waste. It is increasingly influenced by state-level legislation, particularly in states like California and New York, which have enacted ambitious recycling mandates and plastic waste reduction targets. Companies are facing mounting pressure from environmental groups and eco-conscious consumers to adopt sustainable practices, pushing the demand for mechanically recycled plastics.
Europe Mechanical Recycling Of Plastics Market Trends
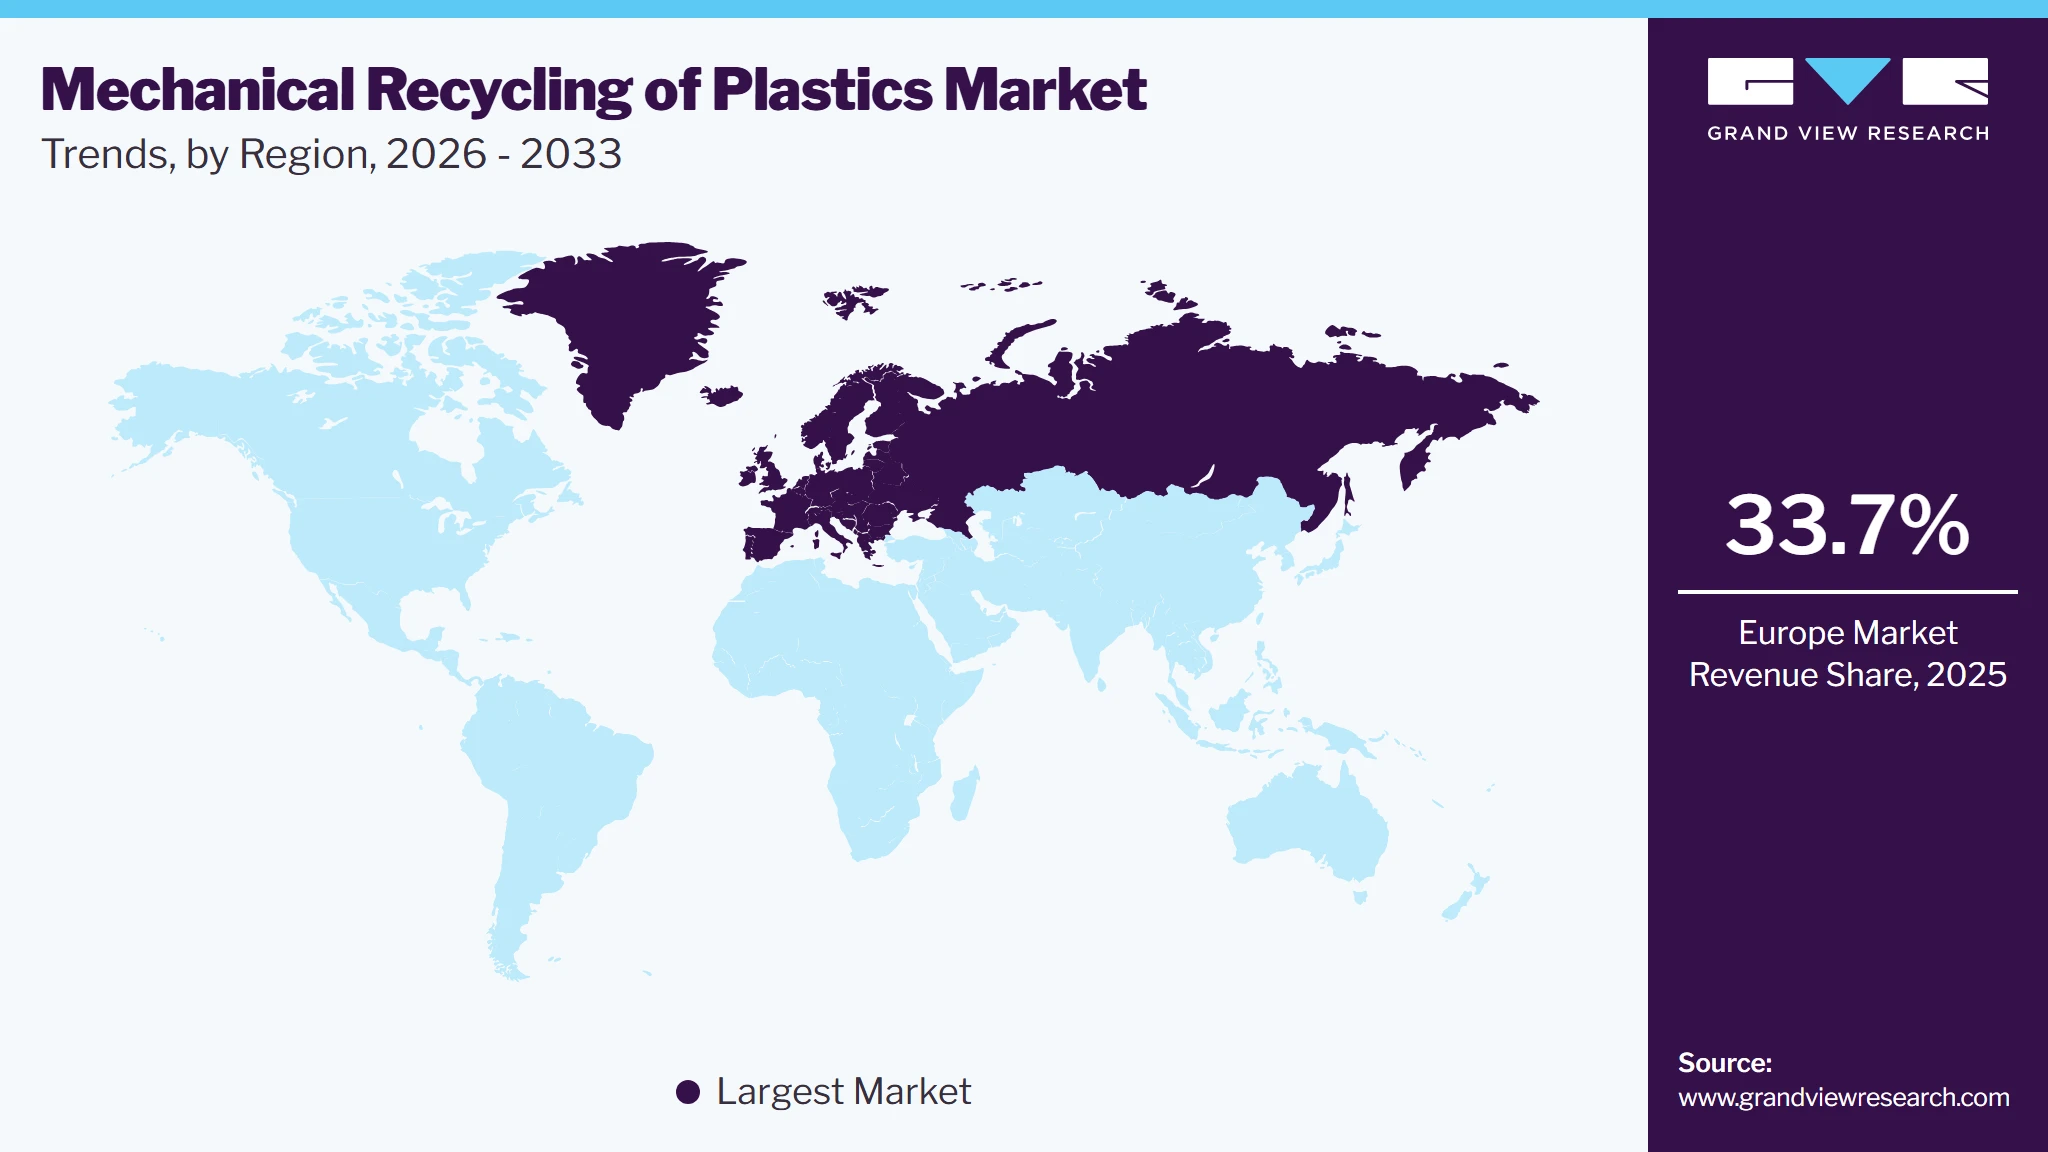
Europe dominated the mechanical recycling of plastics market with the largest revenue share of 33.7% in 2025. Europe’s stringent regulatory landscape is a major driver for the mechanical recycling of plastics. The European Union's policies, such as the Circular Economy Action Plan and the Single-Use Plastics Directive, are pushing industries to drastically reduce plastic waste and increase recycling rates. These regulations are coupled with aggressive recycling targets, requiring member states to implement robust mechanical recycling systems.
 To learn more about this report, Download Free Sample Report
The mechanical recycling of plastics market in Germany accounted for the largest market revenue share in the Europe in 2025. Germany mechanical recycling Of plastics market is driven by the well-established recycling infrastructure and leadership in environmental policies, which are key drivers for the market growth. The country has implemented one of the most advanced waste management systems globally, driven by stringent recycling laws like the Verpackungsgesetz (Packaging Act), which enforces high recycling quotas for plastic packaging. German industries, particularly automotive and packaging, are adopting recycled plastics to meet sustainability targets and reduce reliance on virgin materials.
Asia Pacific Mechanical Recycling Of Plastics Market Trends
Asia Pacific mechanical recycling of plastics market is driven by the rapid industrialization and urbanization across Asia Pacific, which require efficient plastic waste management, making mechanical recycling a key solution. With countries like China, India, and Southeast Asian nations producing vast amounts of plastic waste, governments are implementing stricter regulations and waste management policies to address this growing environmental challenge.
Key Mechanical Recycling Of Plastics Company Insights
The market is highly competitive, with several key players dominating the landscape. Major companies include BASF, TOMRA Systems ASA, Trinseo, TotalEnergies, Eastman Chemical Company, Dow, Coperion GmbH, Covestro AG, LG Chem, and LyondellBasell Industries Holdings B.V. The market is characterized by a competitive landscape with several key players driving innovation and market growth. Major companies in this sector are investing heavily in research and development to enhance the performance, cost-effectiveness, and sustainability of their products.
Key Mechanical Recycling Of Plastics Companies:
The following key companies have been profiled for this study on the mechanical recycling of plastics market.
- BASF
- TOMRA Systems ASA
- Trinseo
- TotalEnergies
- Eastman Chemical Company
- Dow
- Coperion GmbH
- Covestro AG
- LG Chem
- LyondellBasell Industries Holdings B.V
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (BASF, TOMRA Systems ASA, TotalEnergies, Dow, LyondellBasell Industries Holdings B.V.)
- Focus on strengthening their position in the mechanical recycling of plastics market through integrated recycling operations, advanced sorting technologies, recycled polymer production, and circular plastics initiatives.
- Strong emphasis is placed on expanding recycling capacity, improving recycled resin quality, increasing recycled content across product portfolios, and forming strategic partnerships with waste management companies, converters, and brand owners.
- Continuous investments in recycling infrastructure, material innovation, and global commercialization support long-term market expansion.
- Extensive expertise in polymer manufacturing, large-scale recycling operations, automated sorting technologies, and integrated value chains enables the production of high-quality recycled plastics for packaging, automotive, construction, and consumer goods applications.
- Strong global manufacturing networks, advanced research and development capabilities, established customer relationships, financial strength, and broad sustainability portfolios provide sustainable competitive differentiation and recurring revenue opportunities across global recycling markets.
- High capital requirements for recycling infrastructure, exposure to fluctuations in recycled polymer demand and feedstock availability, and dependence on evolving environmental regulations present operational and financial challenges.
- Competition from low-cost virgin plastics, increasing compliance costs, and continuous investments in recycling technologies, digitalization, and facility modernization may impact profitability and long-term market competitiveness.
Emerging Players (Trinseo, Eastman Chemical Company, Covestro AG, LG Chem, Coperion GmbH)
- Focus on expanding their presence in the plastics recycling market through advanced recycling technologies, high-performance recycled materials, process innovation, and circular economy partnerships.
- Emphasis is placed on scaling recycling technologies, developing customized recycled polymer solutions, expanding regional operations, and strengthening collaborations with packaging, automotive, and consumer goods manufacturers.
- Strategic investments in technology development, pilot projects, and sustainable material innovation support commercial growth and market penetration.
- Strong expertise in advanced polymer technologies, process engineering, specialty materials, and innovative recycling solutions enables these companies to improve recycled material quality, processing efficiency, and resource recovery.
- Their operational flexibility, technology-driven business models, sustainability-focused product portfolios, and strategic collaborations with global manufacturers strengthen their competitive positioning in high-growth recycling markets.
- Limited commercial-scale recycling capacity compared with established industry leaders, relatively lower market penetration in mechanical recycling, and dependence on continued technology commercialization may restrict rapid expansion.
- High investment requirements for scaling recycling technologies, regulatory compliance, feedstock quality variability, and reliance on strategic partnerships can constrain long-term growth.
- Additionally, continuous investments in capacity expansion and process optimization are required to compete effectively with established global recycling companies.
Recent Developments
-
In January 2024, IIT Bombay, India announced the development of a new single screw extruding mechanical recycling machine named GolDN. It enables continuous melt mixing of waste polymers and inorganic fillers, simulating real-life processing conditions more effectively than conventional machines. This innovation significantly reduces costs, making the equipment approximately 6-8 times cheaper, at around INR 500,000 (approximately USD 6,000), by simplifying the design and utilizing local manufacturing.
-
In October 2020, LyondellBasell Industries, a global player in the chemical industry, signed a Memorandum of Understanding (MoU) with Shakti Plastic Industries, India's prominent plastic recycler. This collaboration aims to establish a fully automated mechanical recycling plant in India, which will process post-consumer rigid plastic waste and produce 50,000 tons of recycled PE and polypropylene (PP) annually. This output is equivalent to the plastic waste generated by 12.5 million people.
Mechanical Recycling Of Plastics Market Report Scope
Report Attribute
Details
Market size in 2025
USD 39.9 billion
Estimated market size in 2026
USD 43.0 billion
Projected market size by 2033
USD 72.1 billion
Growth rate
CAGR of 7.6% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Norway; Sweden; China; India; Japan; South Korea; Australia; Brazil; Argentina; Saudi Arabia; South Africa; UAE
Key companies profiled
BASF; TOMRA Systems ASA; Trinseo; TotalEnergies; Eastman Chemical Company; Dow; Coperion GmbH; Covestro AG; LG Chem; LyondellBasell Industries Holdings B.V
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Mechanical Recycling Of Plastics Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented Mechanical Recycling of Plastics market report on the basis of Product, Application, and Region:
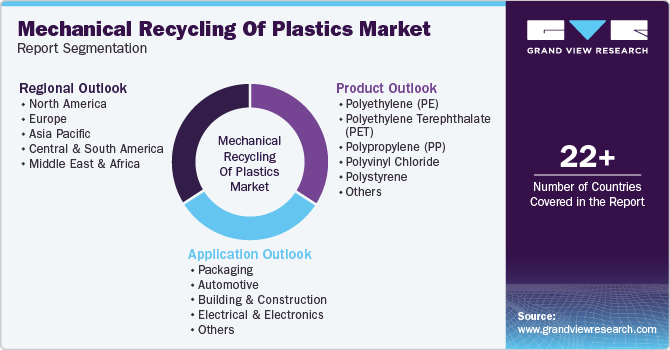 To learn more about this report, Download Free Sample Report
-
Product Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Polyethylene (PE)
-
Polyethylene Terephthalate (PET)
-
Polypropylene (PP)
-
Polyvinyl Chloride
-
Polystyrene
-
Others
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Packaging
-
Automotive
-
Building & Construction
-
Electrical & Electronics
-
Textiles
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Norway
-
Sweden
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
-
Research Methodology
The mechanical recycling of plastics market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each Mechanical Recycling of Plastics segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Polyethylene (PE)
Revenue is captured through the collection, sorting, washing, and reprocessing of post-consumer and post-industrial polyethylene waste into recycled resins for packaging, construction, agriculture, consumer goods, and industrial applications. Demand is driven by high consumption volumes, established collection systems, cost-effective processing, regulatory support, and increasing adoption of recycled PE across circular economy initiatives.
Polyethylene Terephthalate (PET)
Revenue is captured through the recycling of PET bottles, containers, trays, and packaging waste into recycled PET (rPET) resins for food and beverage packaging, textiles, automotive, and consumer goods. Growth is supported by high collection rates, deposit return schemes, food-grade recycling technologies, recycled content mandates, and increasing demand for sustainable packaging materials.
Polypropylene (PP)
Revenue is captured through the collection and mechanical recycling of polypropylene packaging, automotive components, household products, and industrial plastics into recycled PP resins. Demand is driven by increasing PP consumption, advancements in sorting technologies, expanding automotive and packaging applications, corporate sustainability commitments, and rising adoption of recycled polypropylene across end-use industries.
Polyvinyl Chloride (PVC)
Revenue is captured through the recycling of PVC waste generated from construction materials, pipes, cables, flooring, and window profiles into reusable raw materials for building and industrial applications. Growth is supported by increasing construction waste recycling, regulatory initiatives promoting PVC recovery, improved separation technologies, and growing emphasis on resource conservation and landfill diversion.
Polystyrene (PS)
Revenue is captured through the collection, densification, and recycling of polystyrene packaging, containers, insulation materials, and consumer products into recycled materials for packaging, construction, and industrial applications. Demand is driven by advancements in foam densification technologies, increasing recycling infrastructure, regulatory pressure to reduce plastic waste, and expanding recovery of post-consumer polystyrene.
Other Products
Revenue is captured through the recycling of engineering plastics and other polymer waste streams, including ABS, polycarbonate, nylon, acrylics, and mixed plastics, into recycled materials for automotive, electronics, industrial, and consumer applications. Growth is supported by technological advancements in sorting and processing, increasing industrial recycling initiatives, and expanding circular economy adoption.
Segment - Application
Revenue capture definition
Packaging
Revenue is captured through the supply of mechanically recycled plastics for rigid and flexible packaging applications, including bottles, containers, films, trays, and caps. Demand is driven by recycled content mandates, sustainability commitments, high plastic consumption, regulatory support, and increasing adoption of circular packaging solutions across food, beverage, and consumer goods industries.
Automotive
Revenue is captured through the use of recycled plastics in automotive interior, exterior, under-the-hood, and non-structural components to reduce vehicle weight and improve sustainability. Growth is supported by increasing vehicle production, OEM sustainability targets, regulatory requirements, and rising demand for lightweight, cost-effective recycled materials.
Building & Construction
Revenue is captured through the application of recycled plastics in pipes, window profiles, insulation, flooring, roofing, decking, and other construction materials. Demand is driven by growing infrastructure development, green building initiatives, construction waste recycling, regulatory support, and increasing preference for durable and sustainable building materials.
Electrical & Electronics
Revenue is captured through the utilization of recycled plastics in electrical housings, electronic casings, cable insulation, connectors, and appliance components. Growth is supported by rising electronic waste recycling, increasing sustainability initiatives among manufacturers, regulatory compliance, and demand for recycled engineering plastics with consistent performance characteristics.
Textiles
Revenue is captured through the conversion of recycled plastic resins, particularly recycled PET, into fibers, yarns, fabrics, carpets, and apparel. Demand is driven by increasing adoption of sustainable textiles, growing consumer preference for recycled materials, corporate sustainability commitments, and expanding use of recycled fibers in fashion and home furnishing applications.
Others
Revenue is captured through the application of mechanically recycled plastics in agriculture, consumer goods, industrial products, furniture, household items, logistics, and other end-use sectors. Growth is supported by expanding adoption of recycled materials, increasing waste reduction initiatives, advancements in recycling technologies, and broader implementation of circular economy practices across industries.
Estimation Model
Layer Name
Key Question
Description
Top-Down Mechanical Recycling of Plastics Product Demand Assessment Layer
What defines market boundaries?
This layer begins with global demand for recyclable plastic products, including polyethylene (PE), polyethylene terephthalate (PET), polypropylene (PP), polyvinyl chloride (PVC), polystyrene (PS), and other polymers across packaging, automotive, construction, electrical & electronics, textiles, and consumer goods industries. Demand is filtered based on polymer consumption, post-consumer and post-industrial waste generation, recyclability, collection rates, regulatory mandates, circular economy initiatives, and sustainability commitments across major regional markets.
Product and Application Validation Layer
Where is demand generated?
This layer evaluates demand distribution across packaging, automotive, building & construction, electrical & electronics, textiles, and other end-use applications. Market demand is validated based on recycled polymer requirements, material quality standards, collection efficiency, processing feasibility, recycled content targets, regulatory compliance, and increasing adoption of recycled plastics across high-volume industrial applications.
Recycling Process and Revenue Conversion Layer
Who captures market revenue?
This layer converts product and application demand into mechanical recycling market revenue by applying recycling process efficiencies across collection, sorting, washing, shredding, extrusion, pelletization, and recycled resin production. Revenue allocation considers polymer type, contamination levels, processing complexity, operational costs, recycled resin quality, material recovery rates, technology adoption, service pricing, and value-added recycling capabilities throughout the recycling value chain.
Regional Commercial Cross-Check Layer
How are assumptions validated?
This layer validates market assumptions by comparing Asia Pacific's leadership in plastic consumption, manufacturing output, and recycling capacity; Europe's demand driven by stringent environmental regulations, recycled content mandates, and circular economy policies; and North America's growth supported by advanced recycling infrastructure, EPR programs, and corporate sustainability initiatives. It also assesses emerging opportunities across Latin America and the Middle East & Africa, supported by expanding recycling infrastructure, increasing waste collection systems, government recycling policies, and rising investments in sustainable plastic waste management.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
Detailed market assessment across North America, Europe, Asia Pacific, Latin America, and Middle East & Africa, including country-level demand analysis, recycling infrastructure, regulatory landscape, feedstock availability, end-use consumption, and regional growth opportunities for mechanical recycling of plastics.
Enables identification of high-growth regions, investment hotspots, regulatory impacts, and region-specific expansion strategies while supporting market entry and capacity planning decisions.
Trade Assessment
Comprehensive analysis of global imports, exports, trade flows, key exporting and importing countries, recycled plastic feedstock movement, regulatory restrictions on plastic waste trade, and the impact of trade policies on supply chain dynamics.
Enables supply chain optimization, identification of sourcing opportunities, evaluation of trade-related risks, and strategic planning for international market expansion and procurement.
Pricing Analysis
Detailed assessment of recycled plastic resin pricing by polymer type (PE, PET, PP, PVC, PS, and others), regional price trends, feedstock cost dynamics, processing costs, collection and sorting expenses, and comparison with virgin plastic prices.
Assists procurement planning, pricing strategy development, cost optimization, profitability assessment, and evaluation of the economic competitiveness of recycled plastics.
Frequently Asked Questions About This Report
Europe dominated with a 33.7% revenue share in 2025.
The global mechanical recycling of plastics market is expected to grow at a CAGR of 7.6% from 2026 to 2033, reaching USD 72.1 billion by 2033.
The global mechanical recycling of plastics market size was valued at USD 39.9 billion in 2025 and is estimated at USD 43.0 billion for 2026.
The UK was the leading mechanical recycling of plastics market and is expected to grow at a compound annual growth rate of 8.8%.
The polyethylene (PE) segment, based on product, is expected to grow at a CAGR of 8.0% for the forecast period.
The polyethylene (PE) led the mechanical recycling of plastics market in 2025 with a 32.7% share. Growing demand for sustainable and recyclable plastic materials is driving polyethylene (PE) adoption owing to its high consumption volume, excellent recyclability, cost-effectiveness, established collection infrastructure, and broad applications across packaging, construction, agriculture, and consumer goods industries
The key players in the mechanical recycling of plastics market are BASF, TOMRA Systems ASA, Trinseo, TotalEnergies, Eastman Chemical Company, Dow, Coperion GmbH, Covestro AG, LG Chem, and LyondellBasell Industries Holdings B.V
Based on application, the packaging segment accounted for the largest share of 35.1% market size in 2025. Rising demand for sustainable packaging solutions, coupled with increasing recycled content mandates, is driving packaging adoption owing to high plastic consumption, strong recyclability, established collection systems, and broad applications across food, beverage, personal care, and consumer goods industries.
Rising threat of non-biodegradable plastic pollution globally is driving demand for sustainable plastic waste management solutions owing to increasing environmental concerns, stricter sustainability initiatives, and growing emphasis on circular economy practices and resource conservation.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


