
- Home
- »
- Paints, Coatings & Printing Inks
- »
-
Medical Coatings For Implants Market Report, 2026-2033GVR Report cover

Medical Coatings For Implants Market (2026 - 2033)
Size, Share & Trends Analysis Report By Technology (PVD, Plasma Spray), By Product (Hydroxyapatite, Nanoparticle), By Application (Cardiovascular Implants, Dental Implants), And Segment Forecasts
Market Size, 2025
$1.8BMarket Estimate, 2026
$2.0BMarket Forecast, 2033
$3.8BCAGR, 2026–2033
10.1%Medical Coatings For Implants Market Trends
The global medical coatings for implants market size was valued at USD 1.8 billion in 2025 and is projected to grow from USD 2.0 billion in 2026 to USD 3.8 billion by 2033, at a CAGR of 10.1% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 40.0% in 2025. The rising product demand is fueled by an increase in the number of various medical implant procedures, such as cardiovascular, orthopedic, and dental implants.
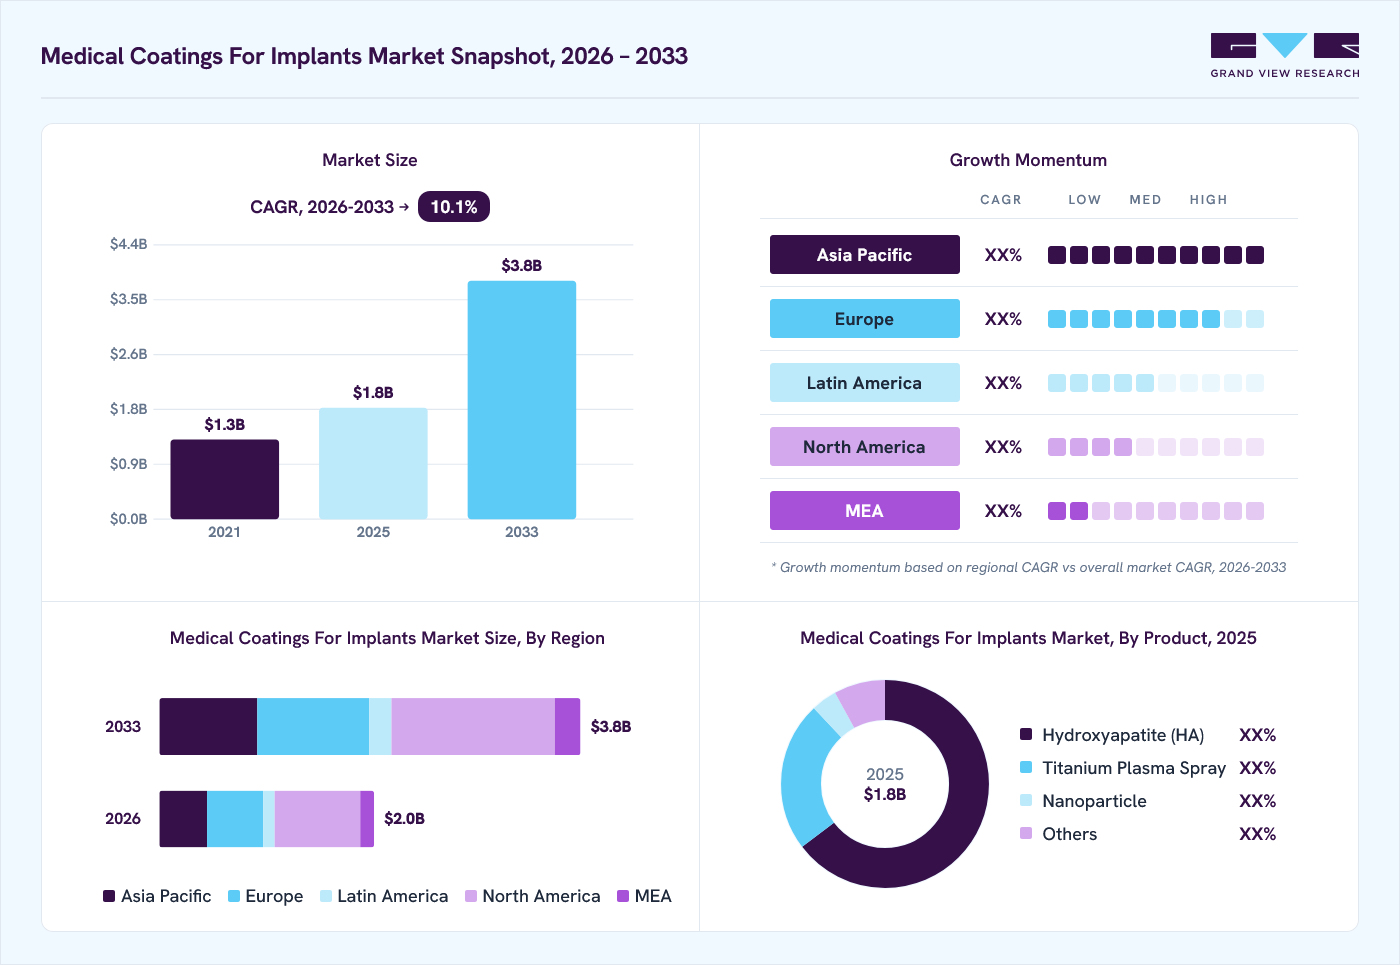 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
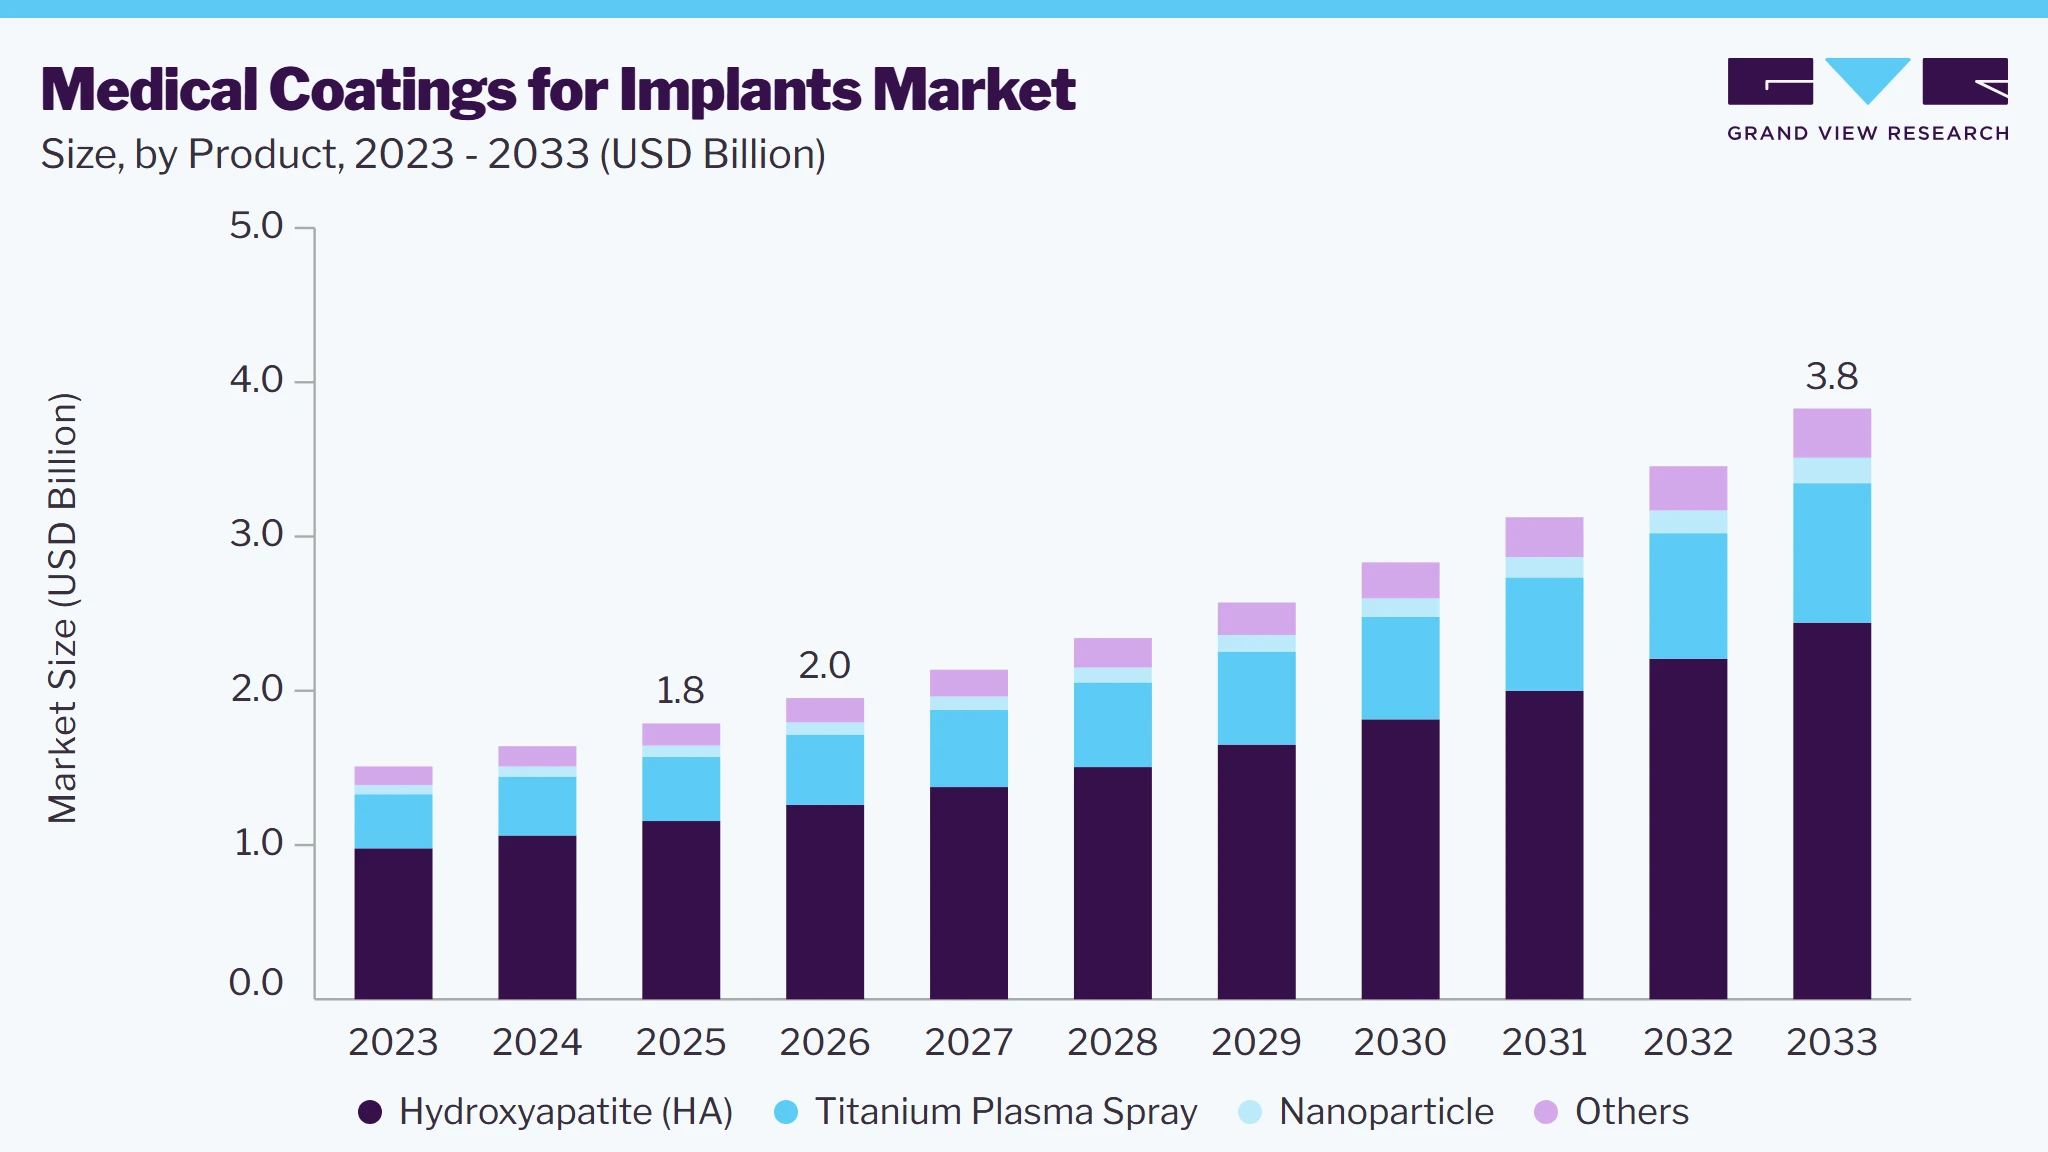
- By product: Hydroxyapatite (HA) segment dominated the market with a share of 64.6% in 2025.
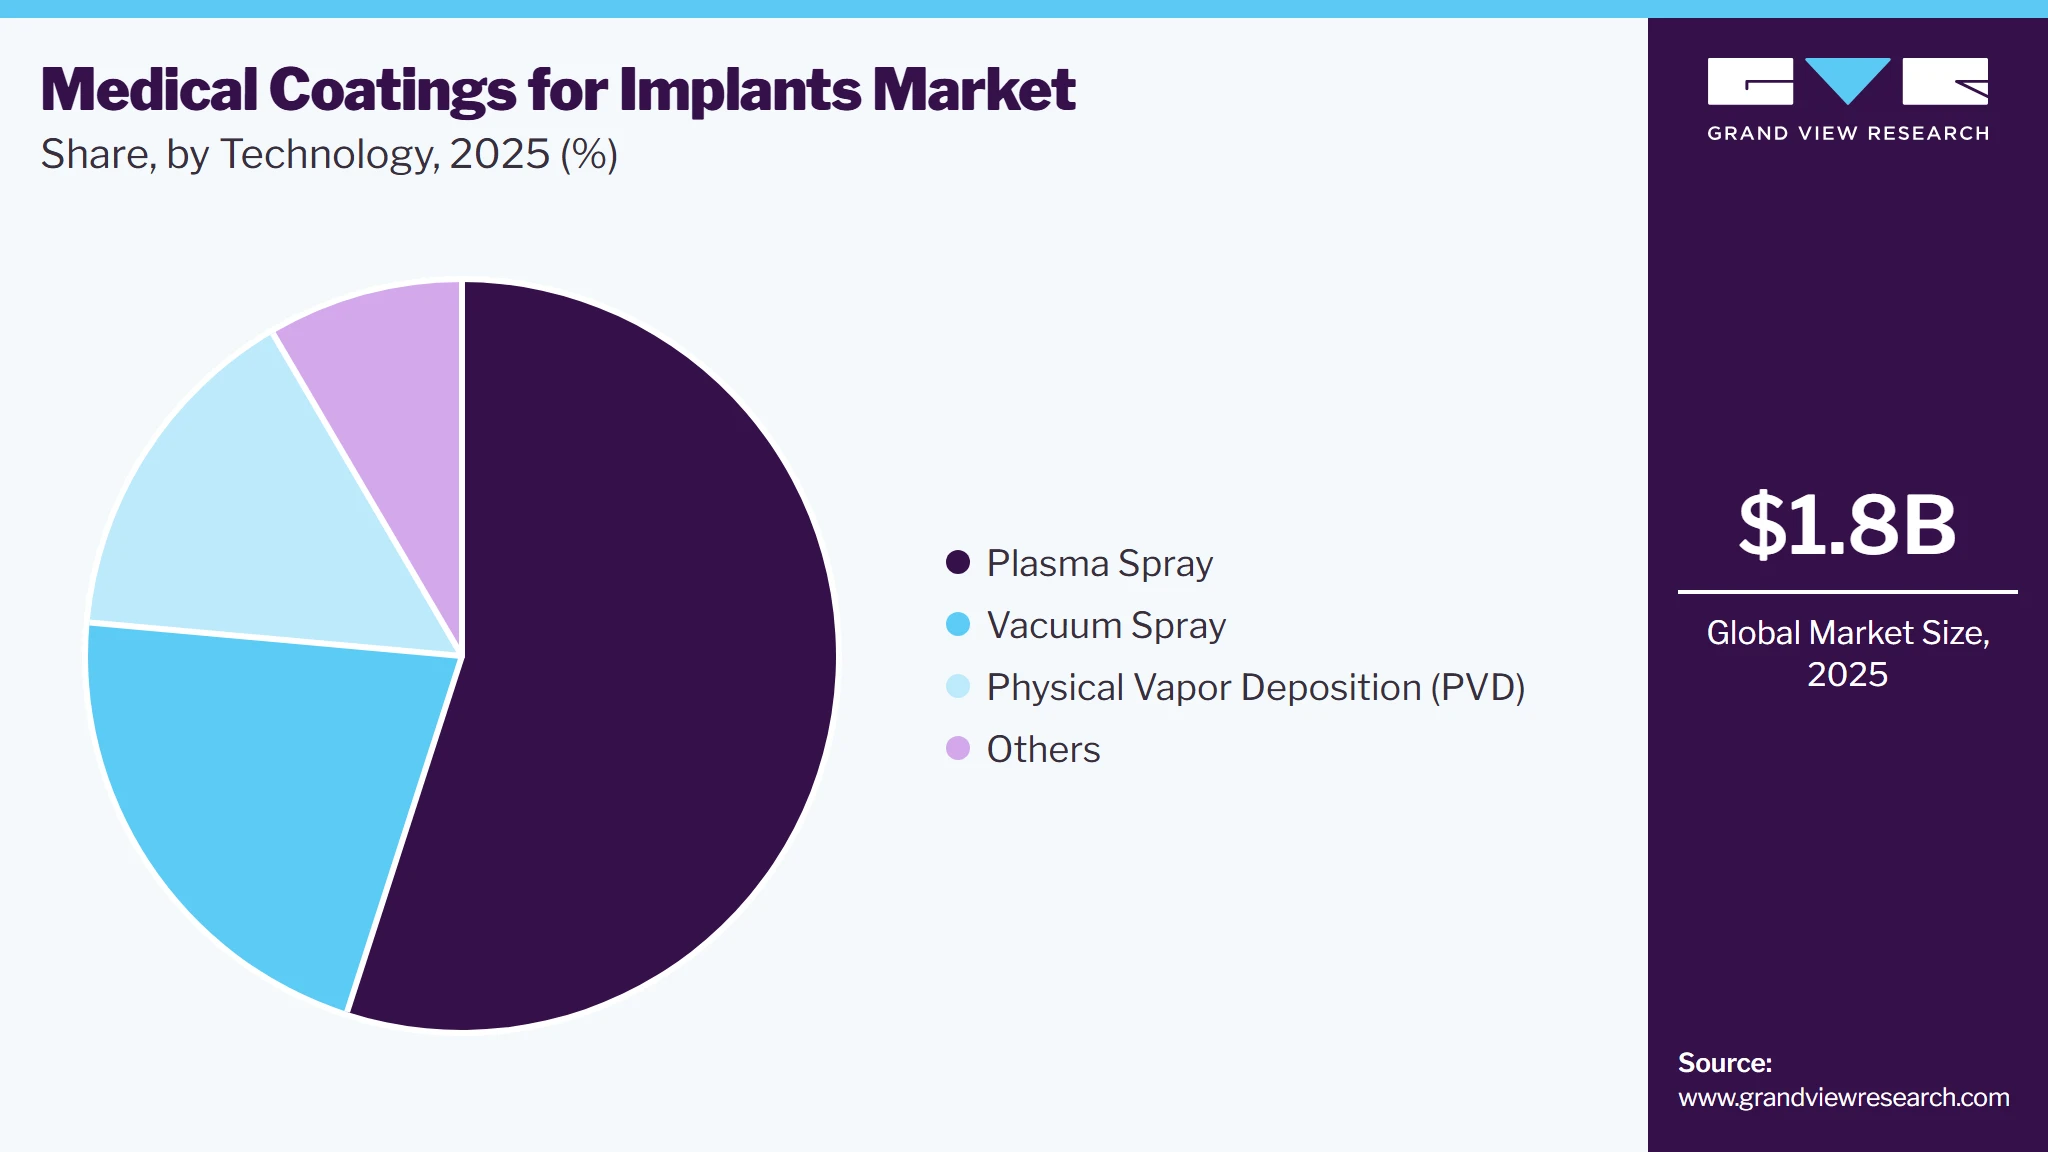
- By technology: Plasma spray held the largest market share of 55.0% in 2025.
- By application: Orthopedic implant screws segment accounted for the largest market share of 52.8% in 2025.
Regional Highlights
- Largest regional market: North America (40.0% revenue share, 2025)
- By country: The China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 1.8 Billion
- Estimated market size in 2026: USD 2.0 Billion
- Projected market size by 2033: USD 3.8 Billion
- CAGR (2026-2033): 10.1%
Prism AI by Grand View Research Free to tryAsk a question about the medical coatings for implants marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →A steady rise in the utilization of implants for cases such as bone fracture and bone dislocation, mostly in the elderly, is expected to boost product demand in the coming years. A fast-rising healthcare expenditure is another major factor enabling market expansion. As per the Centers for Medicare & Medicaid Services, healthcare spending accounted for approximately 19.7% of the U.S. GDP in 2020.As per the same source, healthcare spending in the country is projected to witness an average growth rate of 5.4% from 2019 to 2028 and reach USD 6.2 trillion by 2028. The strong growth is expected to be driven by a rapidly rising need for healthcare services for the country's aging population (of and above 65 years of age), an extensive prevalence of chronic diseases & disorders, and technological developments. The growing prevalence of cardiovascular diseases is enabling the global demand for cardiovascular implants. Cardiac implants are considered a great asset for heart patients as they help monitor patient’s heartbeat and detect irregularities in the cardiac rhythms.
 To learn more about this report, Download Free Sample Report
Implantable Cardioverter-defibrillator (ICD) is one such cardiac implant that supports cardiac patients with programs, such as high-energy shock and low-energy pacing. Thus, the increasing prevalence of cardiovascular diseases, coupled with advancements in surgical techniques, and rising awareness about preventive care are expected to create significant demand for cardiovascular implants, which, in turn, is projected to fuel demand for medical coatings. The titanium prices are affected by the high cost of the aforementioned extraction process and the presence of several stringent government regulations pertaining to the metals and mining sector. This further impacts the overall cost of titanium alloy.
This, in turn, is expected to act as a market restraint. Several import tariffs imposed by the U.S. government due to the current trade war between the country and China are expected to further result in raw material price volatility. These factors are poised to slow down industry growth substantially. Rising consumption of junk foods and improper eating habits are causing tooth decay, creating demand for solutions, such as dental implants. In addition, the increasing geriatric population along with the burden of dental diseases, and a rising demand for cosmetic dentistry are further propelling the need for dental implants. This, in turn, will positively influence industry growth.
Market Dynamics
The medical coatings for implants market is experiencing strong growth, driven by the increasing number of orthopedic, dental, cardiovascular, and neurological implant procedures worldwide. Medical coatings improve implant performance by enhancing biocompatibility, reducing infection risks, minimizing wear, and extending implant lifespan. Rising healthcare expenditure, an aging population, and growing demand for minimally invasive surgeries are accelerating the adoption of advanced implant coatings. In addition, continuous innovations in antimicrobial, hydrophilic, and bioactive coating technologies are supporting long-term market expansion.
The growing prevalence of musculoskeletal disorders, osteoporosis, dental diseases, and age-related conditions is significantly increasing the demand for implant surgeries. Medical coatings are widely used to improve osseointegration, reduce friction, prevent bacterial adhesion, and enhance the longevity of orthopedic and dental implants. Rising healthcare investments, improved access to advanced surgical procedures, and the expanding geriatric population are further driving demand for coated implants across hospitals and specialty clinics.
The market faces challenges due to the high costs associated with developing and validating advanced coating technologies. Medical coatings must meet rigorous regulatory standards related to biocompatibility, safety, durability, and long-term clinical performance before commercialization. Lengthy approval processes, extensive clinical testing, and strict quality control requirements increase product development timelines and costs. Additionally, concerns regarding coating delamination and long-term implant performance remain key challenges for manufacturers.
The increasing focus on preventing implant-associated infections is creating significant opportunities for antimicrobial and bioactive medical coatings. Silver-based, antibiotic-eluting, hydroxyapatite, and nanotechnology-enabled coatings are gaining traction for their ability to reduce infection rates and accelerate tissue integration. The expansion of healthcare infrastructure in emerging economies, rising demand for customized implants, and ongoing research into multifunctional coating technologies are expected to create substantial growth opportunities for the medical coatings for implants market over the forecast period.
Analyst Perspective
The global medical coatings for implants market is positioned for steady growth, driven by the rising volume of orthopedic, dental, cardiovascular, and other implant procedures worldwide. Medical coatings play a critical role in enhancing implant biocompatibility, improving osseointegration, reducing wear and corrosion, and minimizing the risk of implant-associated infections. Hydroxyapatite (HA) coatings remain one of the largest product segments due to their extensive use in orthopedic and dental implants to promote bone integration. Increasing healthcare expenditure, an aging population, growing adoption of minimally invasive procedures, and continuous advancements in antimicrobial, bioactive, and nanotechnology-based coating solutions are further supporting the long-term growth of the medical coatings for implants market.
Application Insights
Orthopedic implant screws segment projected the largest share of 52.8% in 2025. Orthopedic implant screws are essential in the process of orthopedic fixation. Pedicle screws are a type of orthopedic screws, which are primarily used in spine fusion surgeries to correct deformities and treat trauma. They are inserted to hold the vertebrae together and keep the spine stable. Pedicle screws are made of titanium alloy and are often associated with risks involving breaking, loosening, and/or falling of screws. To remedy that, these implants are sprayed with titanium plasma-sprayed (TPS) coatings, which provide good corrosion resistance, adhesion, wear strength, and reduce allergic reactions.
Improper weight lifting techniques in material handling and also while working out in gyms often lead to spine disorders, which is expected to drive the market for pedicle screws and influence the consumption of medical coatings in implants. Demand for dental implants has been increasing, owing to the rising prominence of the American promotion company, Ultimate Fighting Championship (UFC), which has boosted the popularity of Mixed Martial Arts (MMA).
MMA has become one of the fastest-growing sports globally and is anticipated to increase in popularity further due to extensive investments pouring into it. For instance, in December 2021, One Championship, the Asian MMA company, closed a USD 150 million equity financing round led by Qatar Investment Authority and Guggenheim Investments. Since injuries are frequently associated with MMA, the developing MMA sector is expected to drive the market for dental implants and positively impact market expansion.
Regional Insights
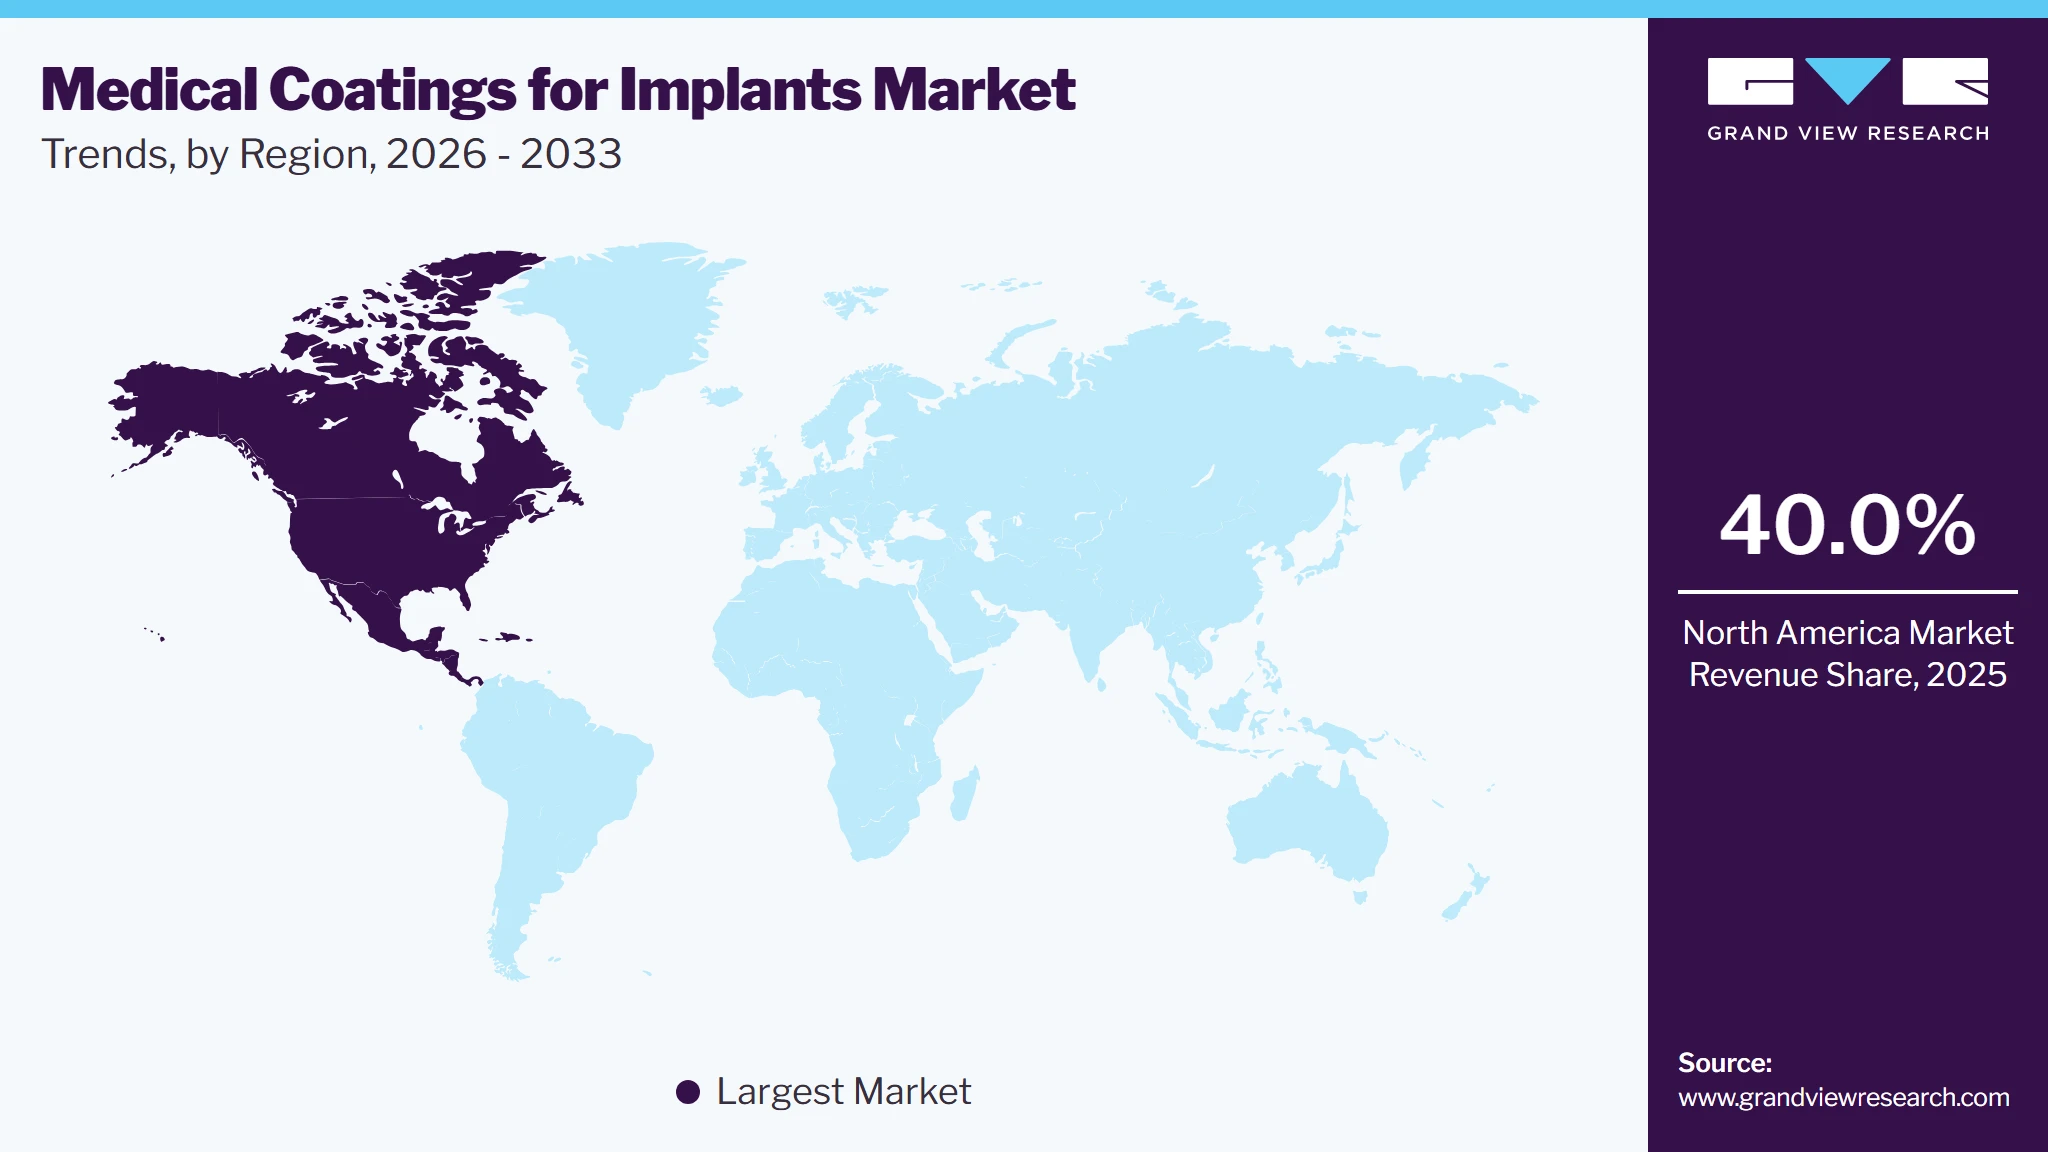
North America accounted for 40.0% of the medical coatings for implants market revenue in 2025, making it the largest regional market. Cosmetic surgeries are gaining popularity due to rapid urbanization, changing lifestyles, and rising image consciousness among consumers in the region, due to the growing usage of social media platforms. According to the American Society of Plastic Surgeons (ASPS), the popularity of cosmetic surgery among men is increasing due to the introduction of non-surgical procedures, such as soft tissue fillers, which provide quicker recovery time. Hydroxyapatite is used as a soft tissue filler for facial wrinkles. It lasts for a relatively long period. U.S. held the highest market revenue share in North America in 2025.
 To learn more about this report, Download Free Sample Report
Since the social stigma associated with men undergoing cosmetic surgeries has been steadily fading away, it is expected to result in high demand for soft tissue fillers, which will directly propel market growth in similar applications. Asia Pacific is expected to witness significant gains from 2024 to 2030 on account of rising demand for medical coatings in various countries, including India, China, and Japan. The increasing volume of body implant surgeries is anticipated to boost product demand further in this region.
Product Insights
Hydroxyapatite (HA) segment dominated the product segment with a market share of 64.6% in 2025.. Hydroxyapatites are widely consumed in implants, such as dental and orthopedics for bone adjustments. These coatings present prominent applications in the integration of medical implants within the human body. Though metallic implants offer required mechanical strength, they need a good osteophilic surface for bonding to the skeleton. This is provided by hydroxyapatite coatings, which help natural bones affix to implants. These coatings are normally used for low load-bearing dental and orthopedic implants owing to their low fatigue strength.
Biofilm formation, infection risks, and microbial colonization are the major complications encountered by medical implants. These are also some of the predominant factors causing implant failures, leading product manufacturers to develop antimicrobial nanoparticles for use in implant coatings. Nanoparticle composites, such as silver nanoparticles, are incorporated with hydroxyapatite into implants to inhibit bacterial growth in them. This assures that implants have enhanced integration possibilities with the body of patients.
Technology Insights
Plasma spray held the largest share of 55.0% of the technology segment in 2025. Plasma spraying produces thick-layered coatings, from a few tens to a few hundred microns on ceramic or metal implants. It is usually used to spray titanium (Ti) coatings, Hydroxyapatite (HA) coatings, and Ti/HA dual coatings on implants used in orthopedic, trauma, dental, and other applications. Plasma-sprayed coatings are applied on the bone-contacting surface for biological fixation of implants, surface roughness, and maintaining the similarity of chemical composition to bone minerals. Vacuum spray technology offers prominent applications for implants.
 To learn more about this report, Download Free Sample Report
During fracture healing, when an implant is inserted, the bone, in order to grow, has to offer the trabaculae an excellent surface to adhere to it. Trabeculae are small rods inserted inside the bone to provide support during bone healing. This requires the implant to provide a porous surface while still being able to withstand enormous loads. Vacuum plasma spray coating provides them with a suitable adhesive property and smooth surface to bond well with the substrate and is used in bone-in growth applications.
Key Companies & Market Share Insights
Key manufacturers are striving to adapt to changes in terms of technologies and new product developments to offer the best medical coatings solution and gain a competitive edge over others.
Key Medical Coatings For Implants Companies
The following key companies have been profiled for this study on the medical coatings for implants market.
-
Himed
-
Hydromer
-
DOT GmbH
-
Lincotek Group S.p.A.
-
Medicoat AG
-
CAM Bioceramics B.V.
-
APS Materials, Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Himed; Hydromer; Lincotek Group S.p.A.; Medicoat AG; CAM Bioceramics B.V.)
- Expand manufacturing capacity for advanced implant coatings, including hydroxyapatite, antimicrobial, and bioactive coatings.
- Invest in R&D for next-generation coating technologies that improve osseointegration, corrosion resistance, and infection prevention.
- Strengthen partnerships with orthopedic, dental, and cardiovascular implant OEMs through long-term supply agreements and co-development projects.
- Expand global presence through acquisitions, technology licensing, and regional manufacturing and coating service facilities.
- Strong expertise in medical-grade coating technologies and regulatory compliance.
- Established relationships with leading medical device manufacturers worldwide.
- Advanced coating capabilities supported by proprietary technologies and quality certifications.
- Robust R&D capabilities enabling continuous product innovation and customized coating solutions.
- High investment requirements for R&D, regulatory approvals, and advanced manufacturing facilities.
- Lengthy product qualification and validation processes delay commercialization.
- Dependence on the cyclical medical device and implant markets.
- Exposure to stringent global regulatory and quality compliance requirements.
Emerging & Regional Players (DOT GmbH; APS Materials, Inc.)
- Focus on specialized coating services and customized implant surface solutions for niche medical applications.
- Enhance competitiveness through flexible production, rapid prototyping, and customer-specific coating development.
- Expand regional customer base through collaborations with medical device startups, research institutes, and local implant manufacturers.
- Invest in advanced coating technologies and quality improvements to enter high-value implant segments.
- High operational flexibility and ability to deliver customized coating solutions.
- Faster response to customer-specific design and development requirements.
- Strong technical expertise in niche coating technologies and specialized implant applications.
- Ability to build close relationships with regional OEMs and research organizations.
- Limited manufacturing scale compared with global coating providers.
- Smaller international distribution and customer network.
- Lower financial capacity for large-scale expansion and extensive clinical validation.
- Greater dependence on regional demand and a limited portfolio of implant applications.
Medical Coatings For Implants Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.8 Billion
Estimated market size in 2026
USD 2.0 Billion
Projected market size by 2033
USD 3.8 Billion
Growth rate
CAGR of 10.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Volume in Ton, revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, technology, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; India; Japan; South Korea; Indonesia; Brazil; Argentina; Saudi Arabia; South Africa
Key companies profiled
Himed; Hydromer; DOT GmbH; Lincotek Group S.p.A.; Medicoat AG; CAM Bioceramics B.V.; APS Materials, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Medical Coatings For Implants Market Report Segmentation
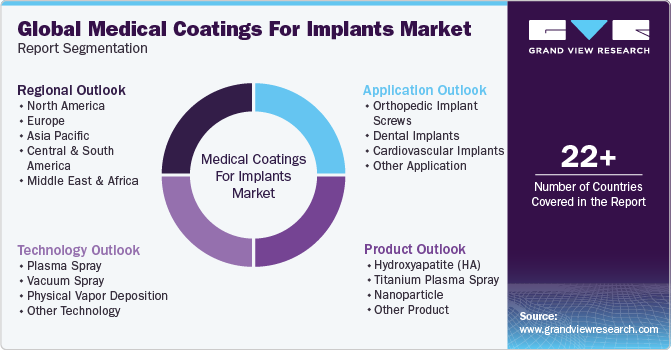
This report forecasts revenue and volume growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the medical coatings for implants market report on the basis of product, technology, application, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Volume, Tons, Revenue, USD Million, 2021 - 2033)
-
Hydroxyapatite (HA)
-
Titanium Plasma Spray
-
Nanoparticle
-
Other Product
-
-
Technology Outlook (Volume, Tons; Revenue, USD Million, 2021 - 2033)
-
Plasma Spray
-
Vacuum Spray
-
Physical Vapor Deposition
-
Other Technology
-
-
Application Outlook (Volume, Tons; Revenue, USD Million, 2021 - 2033)
-
Orthopedic Implant Screws
-
Pedicle Screws
-
Sacroiliac SI Joint Screws
-
Other Orthopedic Implant Screws
-
-
Dental Implants
-
Cardiovascular Implants
-
Other Application
-
-
Regional Outlook (Volume, Tons, Revenue, USD Million; 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
U.K.
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Indonesia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The medical coatings for implants market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each medical coatings for implants segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment – Product
Revenue capture definition
Hydroxyapatite (HA)
Captures revenue from hydroxyapatite-based coatings applied to orthopedic, dental, and other implants to enhance biocompatibility, osseointegration, and long-term implant stability.
Titanium Plasma Spray
Represents revenue generated from titanium plasma spray coatings used to improve implant fixation, surface roughness, wear resistance, and bone integration in medical implants.
Nanoparticle
Accounts for revenue associated with nanoparticle-based coatings provide antimicrobial properties, improved biocompatibility, enhanced corrosion resistance, and controlled surface functionality for implants.
Other Product
Includes revenue from ceramic, polymeric, diamond-like carbon (DLC), bioactive glass, silver-based, and other specialty coatings used to improve implant performance and durability.
Segment – Technology
Revenue capture definition
Plasma Spray
Includes revenue generated from plasma spray coating technologies used to deposit bioactive and wear-resistant coatings, particularly hydroxyapatite and titanium, on medical implants.
Vacuum Spray
Represents revenue associated with vacuum spray coating processes that produce uniform, high-performance coatings with improved adhesion, corrosion resistance, and mechanical durability.
Physical Vapor Deposition (PVD)
Covers revenue from PVD-applied coatings that enhance implant hardness, wear resistance, corrosion protection, and biocompatibility for orthopedic, dental, and cardiovascular applications.
Other Technology
Accounts for revenue generated through chemical vapor deposition (CVD), electrophoretic deposition, sol-gel coating, ion implantation, and other advanced coating technologies used for medical implants.
Segment – Application
Revenue capture definition
Orthopedic Implant Screws
Measures revenue derived from coatings applied to orthopedic screws, plates, joint replacements, and trauma fixation devices to improve osseointegration, reduce wear, and minimize infection risk.
Dental Implants
Covers revenue generated from coatings used on dental implants to enhance bone integration, improve surface bioactivity, and increase implant longevity.
Cardiovascular Implants
Represents revenue earned from coatings applied to cardiovascular implants, including stents, heart valves, and vascular devices, to improve hemocompatibility, reduce thrombosis, and enhance device performance.
Other Application
Includes revenue associated with coatings used for spinal, craniofacial, neurological, ophthalmic, and other implantable medical devices requiring enhanced biocompatibility, antimicrobial protection, and long-term durability.
Estimation Model
Layer No.
Layer Name
Key Question
Description
01
Medical Coatings for Implants Production Layer
What forms is the supply base?
Identify the global production capacity of medical coatings for implants by evaluating coating material manufacturers, raw material availability (hydroxyapatite, titanium, ceramics, polymers, nanoparticles), coating technologies, production capabilities, quality standards, and manufacturing facilities supplying the medical implant industry.
02
Application Adoption Layer
Where are medical coatings for implants utilized?
Estimate the distribution of medical coatings for implants across key applications, including orthopedic implants, dental implants, cardiovascular implants, spinal implants, neurological devices, and other implantable medical devices by analyzing procedure volumes, implant demand, and regional adoption trends.
03
Consumption Intensity Layer
How much medical coatings for implants is consumed?
Assess the consumption of medical coatings by evaluating implant production volumes, surgical procedure rates, demand for coated implants, replacement procedures, and coating usage intensity across major medical device segments and regional healthcare markets.
04
Revenue Layer
How is market revenue generated?
Market revenue is generated through the sale and application of medical coatings for implants, including hydroxyapatite, titanium plasma spray, nanoparticle, antimicrobial, and other specialty coatings supplied to orthopedic, dental, cardiovascular, and other implant manufacturers through direct OEM partnerships, contract coating providers, and medical device supply networks.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Cross-Segmentation Analysis
Detailed cross-segmentation assessment evaluating the relationship between product (Hydroxyapatite (HA), Titanium Plasma Spray, Nanoparticle, and Others), technology (Plasma Spray, Vacuum Spray, Physical Vapor Deposition (PVD), and Others), and application (Orthopedic Implant Screws, Dental Implants, Cardiovascular Implants, and Other Implants). The analysis identifies technology adoption by product type, application-specific coating preferences, utilization intensity, and revenue contribution across each product–technology–application combination.
Supports product portfolio optimization, technology selection, and market prioritization by identifying the highest-value product–technology–application combinations, enabling better R&D planning, manufacturing investments, and commercialization strategies.
Competitive Benchmarking
Comparative evaluation of leading medical coatings for implants manufacturers based on coating portfolio, coating technologies, manufacturing capabilities, regulatory compliance, geographic presence, end-user focus, innovation pipeline, sustainability initiatives, and recent strategic developments across major markets.
Assists competitive intelligence and strategic decision-making by providing insights into market positioning, technological capabilities, product differentiation, and competitive advantages.
Opportunity Assessment
Comprehensive assessment of emerging opportunities across antimicrobial, bioactive, nanotechnology-based, and next-generation implant coatings, along with growth potential in orthopedic, dental, cardiovascular, and personalized implant applications across key regional markets.
Helps identify high-growth technologies and application areas, supporting investment decisions, product innovation, market expansion, and long-term revenue growth.
Frequently Asked Questions About This Report
The global medical coatings for implants market size was valued at USD 1.8 billion in 2025 and is estimated at USD 2.0 billion for 2026.
The global medical coatings for implants market is expected to grow at a CAGR of 10.1% from 2026 to 2033, reaching USD 3.8 billion by 2033.
Some key players operating in the medical coatings for implants market include Himed, Hydromer, DOT GmbH, and Lincotek Group S.p.A.
Key factors that are driving the medical coatings for implants market growth include the increasing prevalence of orthopedic and cardiovascular diseases and rise in global healthcare expenditure.
The plasma spray segment dominated the market with a 55.0% revenue share in 2025, driven by its superior coating adhesion, excellent wear resistance, and widespread use in orthopedic and dental implants to enhance osseointegration and implant longevity.
Orthopedic implant screws accounted for the largest revenue share of 52.8% in 2025, driven by the rising prevalence of musculoskeletal disorders, increasing joint replacement and trauma fixation procedures, and the growing aging population worldwide.
North America dominated with a 40.0% revenue share in 2025.
The nanoparticle segment is projected to register the fastest CAGR of 11.1% during the forecast period, driven by increasing demand for antimicrobial and multifunctional coatings that improve biocompatibility, reduce infection risks, and enhance the long-term performance of implantable medical devices.
The hydroxyapatite (HA) based coatings under product segment dominated the medical coatings for implants market with a share of 64.6% in 2025. This is attributable to the wide use of hydroxyapatite-based coatings in bone repair and bone regrowth applications.
About the Author(s)
Paints, Coatings & Printing Inks Research Team
Bulk Chemicals · Paints, Coatings & Printing InksThis report was authored by the paints, coatings & printing inks research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the paints, coatings & printing inks segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


