
- Home
- »
- Paints, Coatings & Printing Inks
- »
-
Medical Device Hydrophilic Coatings Market Size, Growth Report, 2026-2033GVR Report cover

Medical Device Hydrophilic Coatings Market (2026 - 2033)
Size, Share & Trends Analysis Report By Formulation (Water-based, Solvent-based, Radiation-curable), By Substrate (Polymers, Glass), By Application (Catheters, Guidewires, Needles), By Region, And Segment Forecasts
Market Size, 2025
$4.9BMarket Estimate, 2026
$5.0BMarket Forecast, 2033
$8.4BCAGR, 2026–2033
7.5%Medical Device Hydrophilic Coatings Market Summary
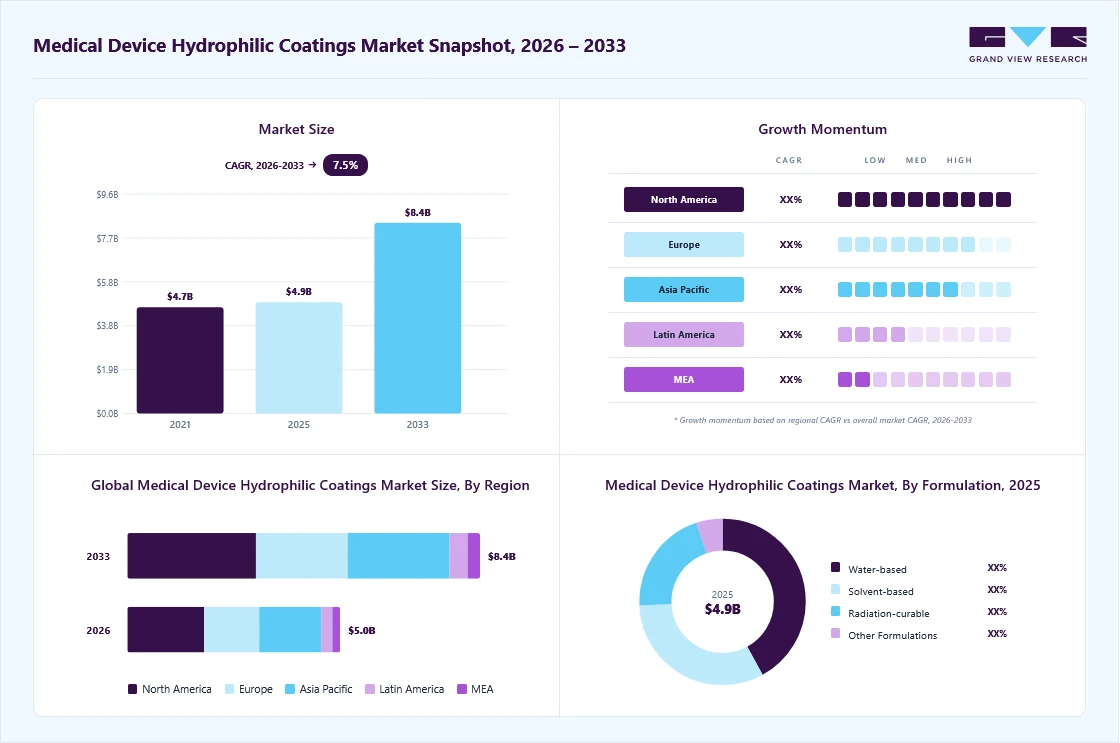
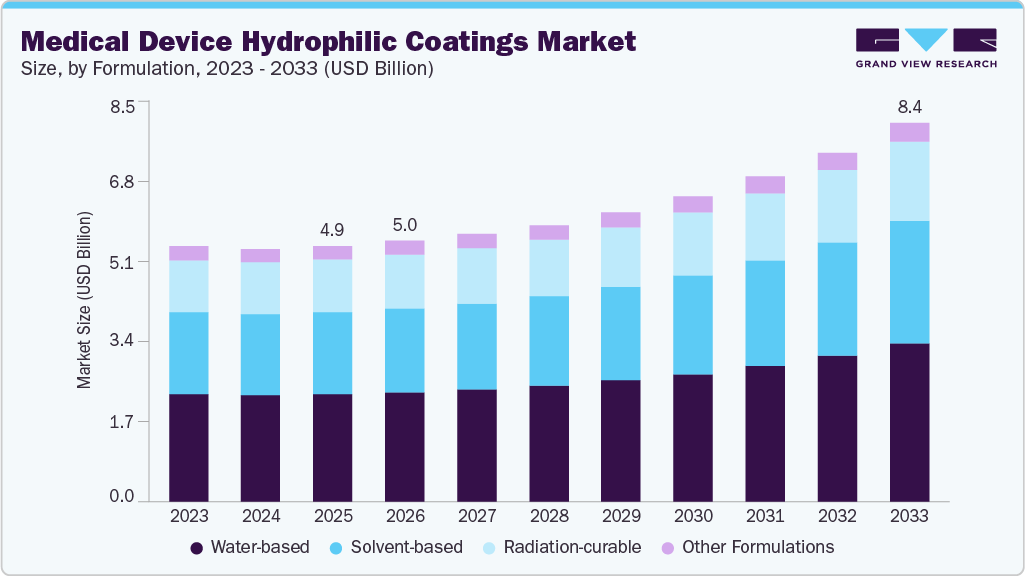
The global medical device hydrophilic coatings market size was valued at USD 4.9 billion in 2025 and is projected to grow from USD 5.0 billion in 2026 to USD 8.4 billion by 2033, at a CAGR of 7.5% from 2026 to 2033. North America dominated the global market, accounting for the largest revenue share of 36.0% in 2025. The industry is primarily driven by the rising volume of minimally invasive procedures across cardiovascular, neurovascular, urology, and ophthalmology specialties, where superior lubricity is critical to improving device trackability and reducing tissue trauma.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By formulation: Radiation-curable segment is expected to grow at the fastest CAGR of 7.8% from 2026 to 2033 in terms of revenue.
- By substrate: Polymers segment held the largest revenue share of 55.3% in 2025.
- By application: Catheters segment held the largest revenue share of 34.8% in 2025.
Regional Highlights
- Largest regional market: North America (36.0% revenue share, 2025)
- By country: The China medical device hydrophilic coatings industry is a major contributor to the global market.
Market Size & Forecast
- Market size in 2025: USD 4.9 Billion
- Estimated market size in 2026: USD 5.0 Billion
- Projected market size by 2033: USD 8.4 Billion
- CAGR (2026-2033): 7.5%
Prism AI by Grand View Research Free to tryAsk a question about the medical device hydrophilic coatings marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →Increasing clinical emphasis on patient comfort, reduced insertion force, and lower complication rates is accelerating adoption across catheters, guidewires, and delivery systems. The expansion of interventional cardiology procedures in high-growth markets, coupled with OEM outsourcing to specialized coating providers such as Surmodics, Inc. and Hydromer, is strengthening the commercial deployment of advanced water-based and durable hydrophilic formulations. Significant growth opportunities exist in the development of next-generation multifunctional coatings that combine hydrophilicity with antimicrobial, antithrombotic, or drug-eluting properties, particularly for long-term and implantable applications. The increasing shift toward water-based and radiation-curable systems presents avenues for regulatory-aligned innovation and improved manufacturing efficiency. Emerging medical device manufacturing hubs in Asia Pacific and Eastern Europe further create expansion opportunities for coating service providers and material innovators such as dsm-firmenich and Freudenberg Medical seeking strategic OEM partnerships.
 To learn more about this report, Download Free Sample Report
The market faces technical and regulatory challenges related to coating durability, particulate generation, delamination risks, and performance consistency under repeated sterilization cycles. Increasing scrutiny from regulatory authorities regarding biocompatibility, extractables and leachables, and long-term stability elevates compliance costs and extends validation timelines. Furthermore, pricing pressures from large medical device OEMs, coupled with the need for customized formulations and stringent quality assurance, compress margins for specialized players including Biocoat Incorporated and AST Products, Inc.
Market Concentration & Characteristics
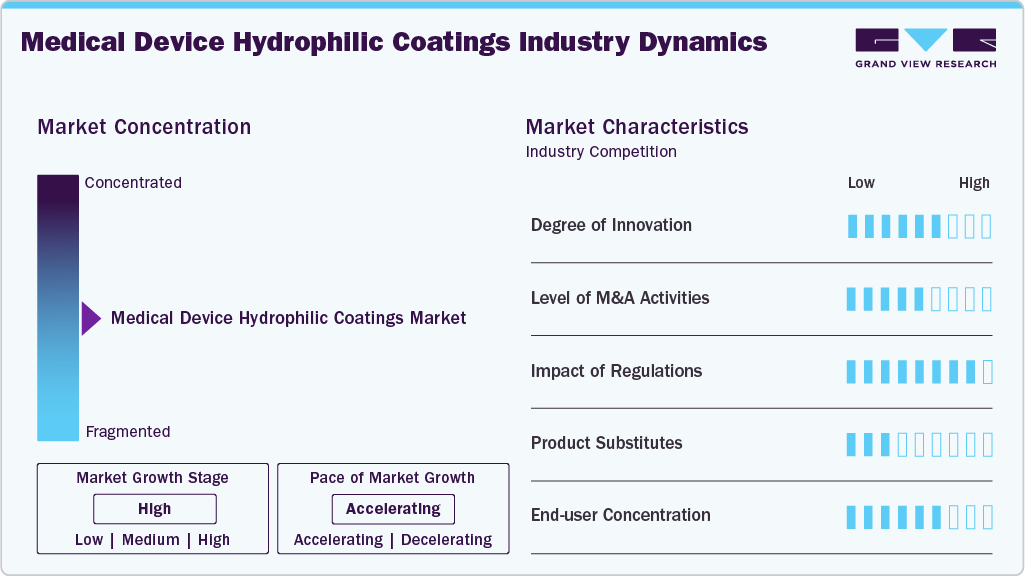
The competitive landscape of the global medical device hydrophilic coatings industry is moderately consolidated, led by specialized coating technology providers with strong intellectual property and deep OEM integration. Companies such as Surmodics, Inc. and Hydromer maintain leadership positions through advanced lubricious coating platforms and long-standing relationships with cardiovascular and minimally invasive device manufacturers. Diversified life sciences players like dsm-firmenich leverage broad biomaterials expertise and regulatory capabilities to compete in high-value and implantable applications, while vertically integrated firms such as Freudenberg Medical strengthen competitive positioning through combined coating and device manufacturing capabilities.
 To learn more about this report, Download Free Sample Report
At the same time, Chinese manufacturers including Yifan Pharmaceutical, Xinfa Pharmaceutical, and Jiangxi Tongde Chemical Technology are gaining traction through cost-efficient manufacturing and expanding production capacities, intensifying competition in bulk and mid-grade segments. Niche players such as Biocoat Incorporated and Joninn ApS address specialized pharmaceutical and cosmetic applications, while overall competition is driven by technological differentiation, pricing pressure, and increasing demand for high-quality and sustainable medical device hydrophilic coatings products.
Formulation Insights
Water-based formulations dominated the global medical device hydrophilic coatings market, accounting for the largest revenue share of 42.0% in 2025, primarily due to their superior regulatory alignment, low VOC emissions, and strong compatibility with polymer-based substrates widely used in catheters and guidewires. Their ability to deliver consistent lubricity, biocompatibility, and scalable processing without the environmental and safety constraints associated with solvent systems has made them the preferred choice among OEMs and coating specialists such as Surmodics, Inc. and Hydromer. Increasing regulatory scrutiny across North America and Europe, combined with sustainability-driven procurement strategies, further reinforced the commercial dominance of water-based technologies.
Solvent-based formulations continue to serve niche applications requiring enhanced adhesion and durability on complex metallic substrates; however, their growth remains comparatively moderate due to environmental compliance pressures. Radiation-curable coatings are emerging as a high-growth segment, driven by faster curing cycles, improved manufacturing throughput, and suitability for precision devices where thermal sensitivity is a concern. Other formulations, including plasma-enhanced and hybrid systems, cater to specialized performance requirements but collectively represent a smaller share of the market. Overall, formulation innovation is increasingly focused on durability under sterilization, multifunctionality, and process efficiency.
Application Insights
Catheters captured the largest revenue share of 34.8% in 2025 in the global medical device hydrophilic coatings market, driven by their extensive utilization across cardiovascular, urology, neurovascular, and peripheral interventions. High procedural volumes, combined with the critical need to minimize insertion force, reduce vessel trauma, and enhance trackability through complex anatomies, have made hydrophilic coatings an essential performance attribute in catheter design. Leading coating providers such as Surmodics, Inc. and Hydromer maintain strong partnerships with major OEMs to deliver durable, polymer-compatible lubricious coatings that meet stringent regulatory and sterilization requirements, thereby reinforcing the segment’s revenue dominance.
Guidewires represent the second most significant application segment, where ultra-low friction and coating integrity are critical for precise navigation in interventional cardiology and neurovascular procedures. Needles are witnessing steady adoption of hydrophilic coatings to improve patient comfort and reduce penetration force, particularly in specialty and biopsy applications. Lenses, especially in ophthalmology, require controlled wettability and optical clarity, while implantable devices present emerging opportunities for multifunctional coatings with enhanced biocompatibility and thromboresistance. Other medical devices, including introducers and endoscopic tools, contribute incremental demand, collectively supporting sustained market expansion across diverse clinical applications.
Substrate Insights
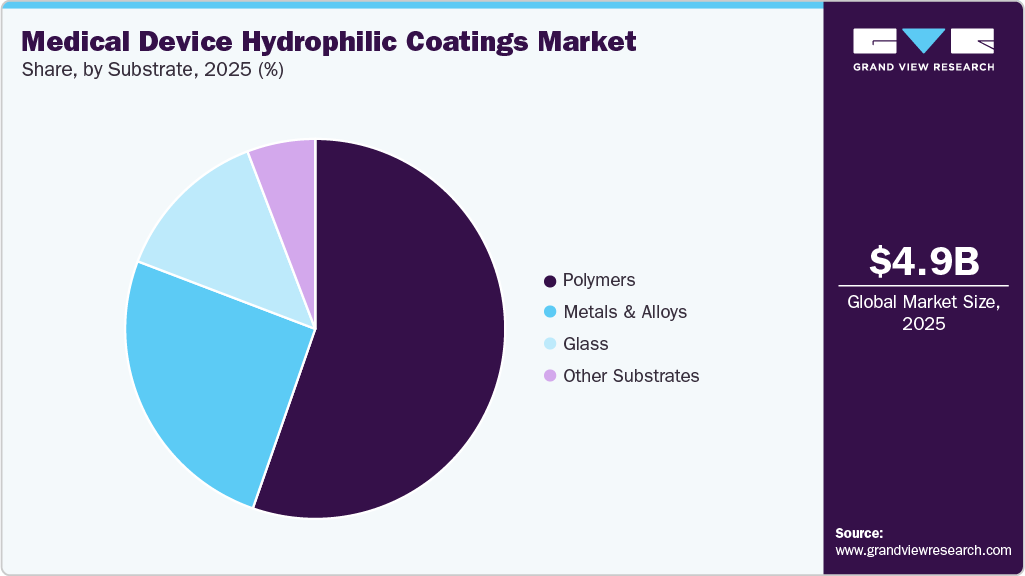
Polymers held the largest revenue share of 55.3% in 2025 in the global medical device hydrophilic coatings market, primarily due to their widespread use in minimally invasive devices such as catheters, guidewires, and delivery systems. Materials including polyurethane, Pebax, PTFE, and nylon dominate interventional device manufacturing because of their flexibility, biocompatibility, and design versatility; however, their inherently higher friction coefficients necessitate hydrophilic surface modification to enhance lubricity and procedural efficiency. As a result, coating providers such as Surmodics, Inc. and Biocoat Incorporated have developed polymer-optimized formulations that ensure strong adhesion, durability, and sterilization resistance, reinforcing the segment’s commercial leadership.
 To learn more about this report, Download Free Sample Report
Metals & alloys represent the second key substrate segment, particularly in guidewires, needles, and implantable components manufactured from stainless steel and nitinol, where coatings reduce insertion force and improve navigation performance. Glass substrates are primarily utilized in ophthalmic lenses and diagnostic applications, requiring specialized thin-film coatings for optical clarity and wettability control. Other substrates, including ceramics and composite materials, serve niche and emerging applications. Overall, substrate-specific formulation compatibility, adhesion performance, and long-term stability remain critical competitive differentiators across this segment.
Regional Insights
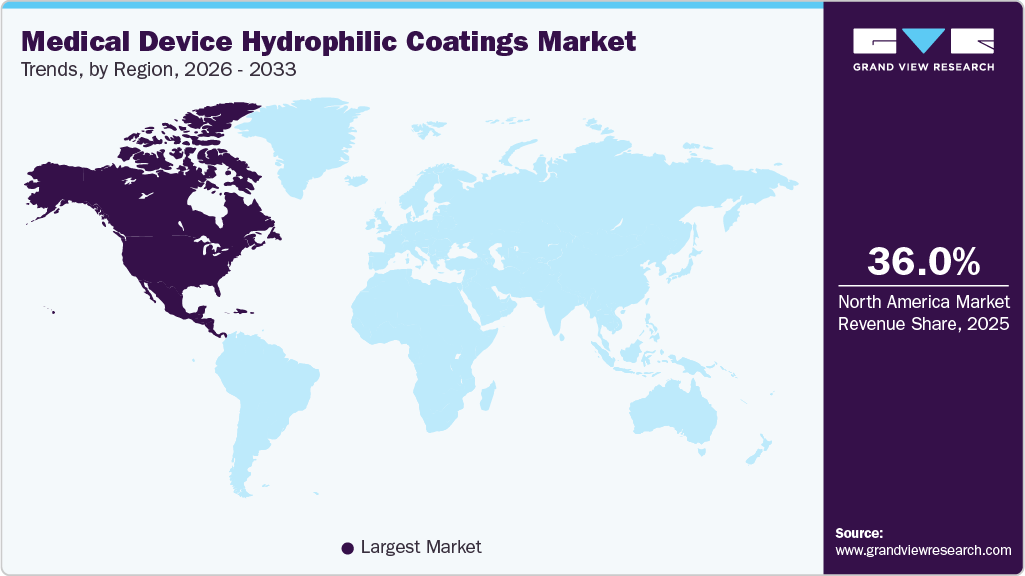
North America medical device hydrophilic coatings market accounted for 36.0% of the global industry in 2025, driven by high procedural volumes in cardiovascular and minimally invasive surgeries, advanced healthcare infrastructure, and the strong presence of leading OEMs and coating technology providers such as Surmodics, Inc. The region benefits from robust R&D investments, early adoption of next-generation coating technologies, and stringent regulatory standards that favor high-performance, biocompatible, and water-based formulations.
 To learn more about this report, Download Free Sample Report
U.S. Medical Device Hydrophilic Coatings Market Trends
Themedical device hydrophilic coatings market in the U.S. dominated the North American market with a 69.6% share in 2025, supported by its large interventional cardiology and urology procedure base, concentration of global medical device manufacturers, and strong innovation ecosystem. Favorable reimbursement frameworks and consistent FDA regulatory pathways further facilitate the rapid commercialization of advanced hydrophilic coating technologies.
Asia Pacific Medical Device Hydrophilic Coatings Market Trends
Themedical device hydrophilic coatings market in Asia Pacific captured 29.1% of the global market in 2025 and represents the fastest-growing region, driven by expanding healthcare access, rising chronic disease burden, and rapid growth of medical device manufacturing hubs. Increasing investments in hospital infrastructure and cost-competitive contract manufacturing are accelerating regional adoption of hydrophilic coating technologies.
Chinamedical device hydrophilic coatings market accounted for 39.5% of the Asia Pacific market in 2025, supported by strong domestic device production, government-backed healthcare expansion initiatives, and rising demand for minimally invasive procedures. Local manufacturing scale and growing technical capabilities are positioning China as both a high-consumption and emerging innovation center in coating applications.
Europe Medical Device Hydrophilic Coatings Market Trends
Themedical device hydrophilic coatings market in Europe held 26.0% of the global market in 2025, characterized by a mature medical device industry and stringent regulatory oversight under MDR frameworks. Demand is primarily driven by cardiovascular and neurovascular interventions, alongside a growing emphasis on sustainable and low-VOC coating formulations across major economies.
Germany medical device hydrophilic coatings market represents a key contributor within Europe, supported by its strong medical engineering base, export-oriented device manufacturing sector, and advanced hospital infrastructure. The country’s focus on precision engineering and regulatory compliance underpins steady demand for high-quality, durable hydrophilic coating solutions.
Middle East & Africa Medical Device Hydrophilic Coatings Market Trends
Themedical device hydrophilic coatings market in the Middle East & Africa region is witnessing gradual growth, driven by expanding private healthcare investments, increasing specialty hospital development, and rising awareness of minimally invasive treatment options. While market penetration remains comparatively lower than in developed regions, improving healthcare expenditure and infrastructure modernization are creating long-term opportunities.
Latin America Medical Device Hydrophilic Coatings Market Trends
Themedical device hydrophilic coatings market in Latin America demonstrates moderate growth potential, supported by expanding access to interventional procedures in countries such as Brazil and Mexico. However, pricing sensitivity, regulatory variability, and healthcare budget constraints continue to influence procurement dynamics, positioning the region as an emerging but cost-sensitive market for hydrophilic coating providers.
Key Medical Device Hydrophilic Coatings Company Insights
Key players operating in the market are undertaking various initiatives to strengthen their presence and increase the reach of their products and services. Strategies such as expansion activities and partnerships are key in propelling the market growth. Key players, such as Hydromer, dsm-firmenich, Surmodics, Inc., Freudenberg Medical, Biocoat Incorporated, and Harland Medical Systems, Inc. are dominating the market.
-
Hydromer is a U.S.-based, FDA-registered, and ISO 13485/ISO 9001 certified provider of advanced surface modification and hydrophilic coating solutions for medical devices, with more than four decades of experience in the industry. Founded in 1980 and headquartered in Concord, North Carolina, the company develops, formulates, and manufactures custom lubricious, thromboresistant, antimicrobial, and other specialty coatings that enhance device performance across polymers, metals, glass, and complex geometries, while also supporting regulatory submissions and technology transfer for OEM partners. Hydromer’s offerings include contract coating services, bespoke R&D formulation support, proprietary coating equipment, and turnkey solutions that help medical device manufacturers accelerate product development and commercialization, particularly in high-growth segments like catheters, guidewires, and diagnostic instruments.
Key Medical Device Hydrophilic Coatings Companies:
The following key companies have been profiled for this study on the medical device hydrophilic coatings market.
- Hydromer
- dsm-firmenich
- Surmodics, Inc.
- Freudenberg Medical
- Biocoat Incorporated
- Harland Medical Systems, Inc.
- Innovative Surface Technologies
- AST Products, Inc.
- Aculon
- Joninn ApS
Recent Developments
-
In February 2026, Freudenberg Medical announced the launch of its latest hydrophilic coating solution, LUBRITEQ, designed for various medical devices.
-
In September 2025, Freudenberg Medical announced the opening of its second production facility in Costa Rica. The newly developed facility aims to significantly improve its manufacturing capabilities to enhance its presence in one of the most dynamic MedTech hubs worldwide.
-
In January 2025, Harland Medical Systems announced the commencement of operations in Costa Rica. This facility offers high-performance coatings services, as well as medical equipment maintenance and support at the local level.
Medical Device Hydrophilic Coatings Market Report Scope
Report Attribute
Details
Market size in 2025
USD 4.9 billion
Estimated Market size in 2026
USD 5.0 billion
Projected Market size by 2033
USD 8.4 billion
Growth rate
CAGR of 7.5% from 2026 to 2033
Base year for estimation
2025
Historical data
2018 - 2024
Forecast period
2026 - 2033
Quantitative units
Volume in kilotons; revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Volume & revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Formulation, substrate, application, region
Regional scope
North America; Europe; Asia Pacific; Middle East & Africa; Latin America
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; India; Japan; South Korea; Brazil; Argentina; South Africa; Saudi Arabia
Key companies profiled
Hydromer; dsm-firmenich; Surmodics, Inc.; Freudenberg Medical; Biocoat Incorporated; Harland Medical Systems, Inc.; Innovative Surface Technologies; AST Products, Inc.; Aculon; Joninn ApS
Customization scope
Free report customization (equivalent up to 8 analysts’ working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Medical Device Hydrophilic Coatings Market Report Segmentation
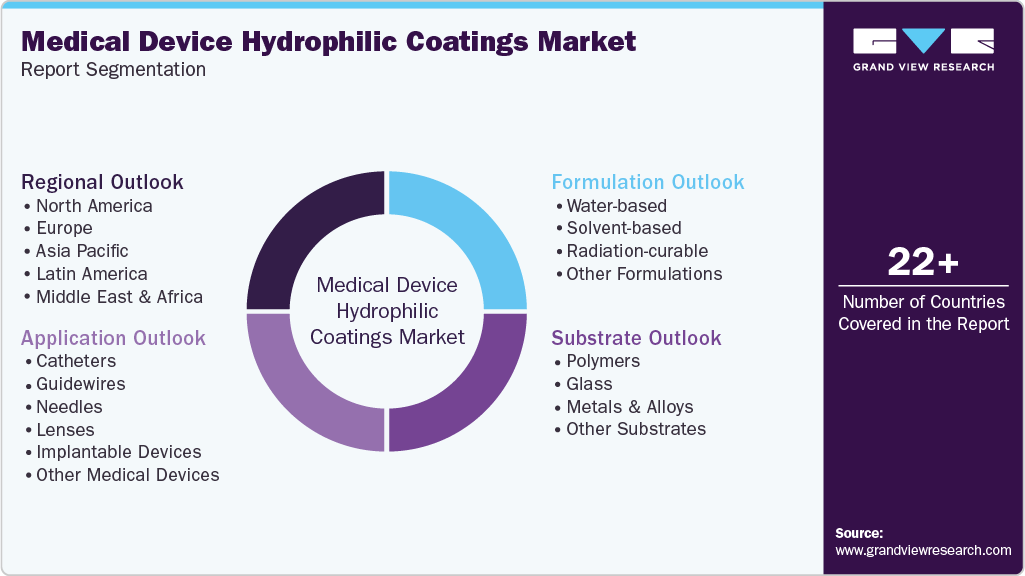
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2018 to 2033. For this study, Grand View Research has segmented the global medical device hydrophilic coatings market report based on formulation, substrate, application, and region:
 To learn more about this report, Download Free Sample Report
-
Formulation Outlook (Volume, Kilotons; Revenue, USD Million, 2018 - 2033)
-
Water-based
-
Solvent-based
-
Radiation-curable
-
Other Formulations
-
-
Substrate Outlook (Volume, Kilotons; Revenue, USD Million, 2018 - 2033)
-
Polymers
-
Glass
-
Metals & Alloys
-
Other Substrates
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Million, 2018 - 2033)
-
Catheters
-
Guidewires
-
Needles
-
Lenses
-
Implantable Devices
-
Other Medical Devices
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2018 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
-
Latin America
-
Brazil
-
Argentina
-
-
Frequently Asked Questions About This Report
Key players include Hydromer; dsm-firmenich; Surmodics, Inc.; Freudenberg Medical; Biocoat Incorporated; Harland Medical Systems, Inc.; Innovative Surface Technologies; AST Products, Inc.; Aculon; Joninn ApS.
North America dominated with a 36.0% revenue share in 2025.
Water-based segment held the largest share (over 42.0%) revenue share in 2025.
The catheters segment dominated the market and accounted for the largest revenue share of 34.8% in 2025.
The global medical device hydrophilic coatings market is expected to grow at a CAGR of 7.5% from 2026 to 2033, reaching USD 8.4 billion by 2033.
The global medical device hydrophilic coatings market size was valued at USD 4.9 billion in 2025 and is estimated at USD 5.0 billion for 2026.
The polymers segment dominated the medical device hydrophilic coatings market with a 55.3% revenue share in 2025 due to the extensive use of polymer-based materials such as polyurethane, Pebax, and PTFE in high-volume minimally invasive devices, including catheters and delivery systems. Their inherent flexibility and design versatility, combined with higher surface friction that necessitates lubricious coating application, significantly drive hydrophilic coating demand across this substrate category.
The market is primarily driven by the rising global volume of minimally invasive procedures, particularly in cardiovascular, neurovascular, and urology segments, where enhanced lubricity is critical to improving device navigation and reducing patient trauma. The increasing regulatory emphasis on biocompatibility and low-VOC formulations, coupled with OEM outsourcing to specialized coating providers, is accelerating adoption of advanced hydrophilic coating technologies.
About the Author(s)
Paints, Coatings & Printing Inks Research Team
Bulk Chemicals · Paints, Coatings & Printing InksThis report was authored by the paints, coatings & printing inks research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the paints, coatings & printing inks segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


