
- Home
- »
- Plastics, Polymers & Resins
- »
-
Medical Fluoropolymers Market Size Report, 2026-2033GVR Report cover

Medical Fluoropolymers Market (2025 - 2033)
Size, Share & Trends Analysis Report By Product (ETFE, PTFE, PVDF, Fluoroelastomers), By Application (Medical Tubing, Catheters, Medical Bags, Drug Delivery Device), By Region, And Segment Forecasts
Market Size, 2025
$618.1MMarket Estimate, 2026
$675.0MMarket Forecast, 2033
$1,257.8MCAGR, 2026–2033
9.3%Medical Fluoropolymers Market Summary
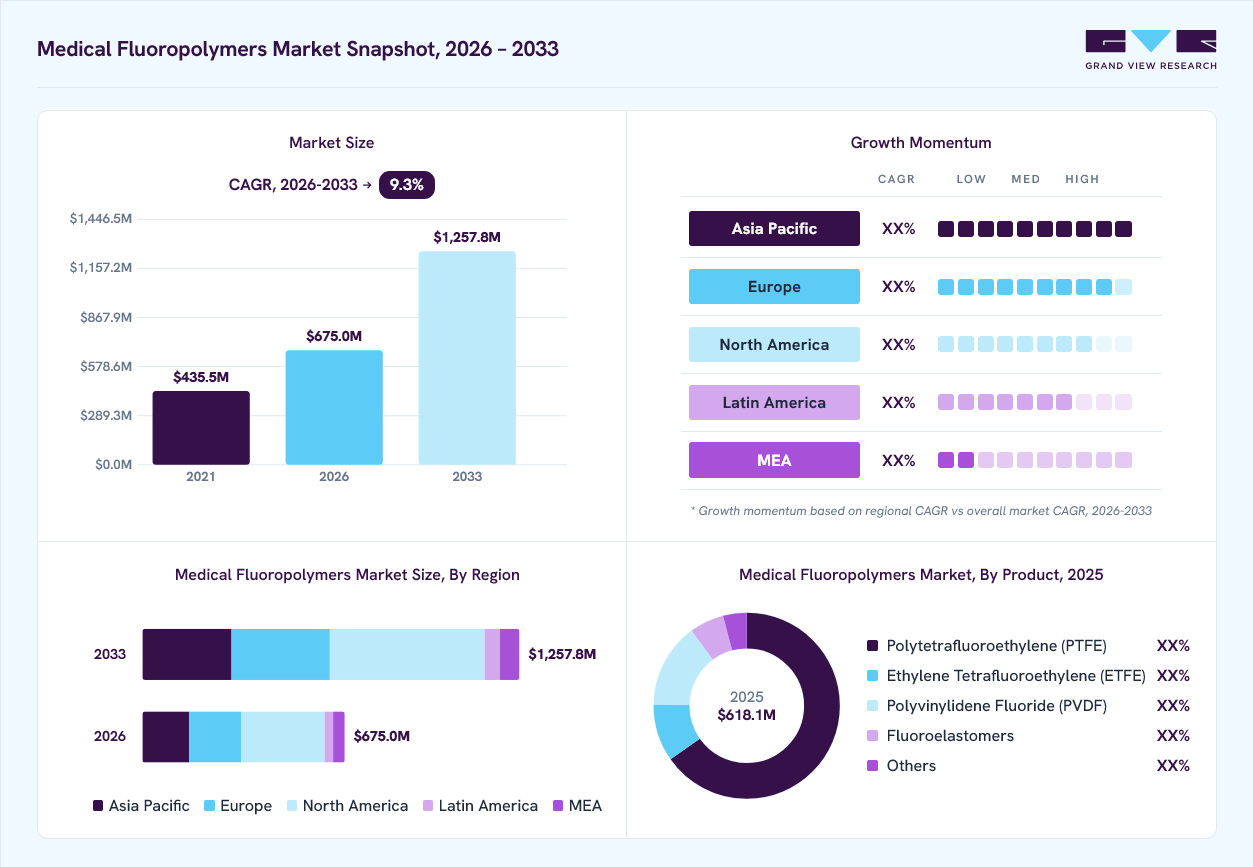
The global medical fluoropolymers market size was valued at USD 618.1 million in 2025 and is projected to grow from USD 675.0 million in 2026 to USD 1,257.8 million by 2033, at a CAGR of 9.3% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 41.2% in 2025. Increasing demand for advanced medical technology and devices, and growing healthcare investments in emerging economies, are expected to drive the demand for medical fluoropolymers over the forecast period.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Polytetrafluoroethylene (PTFE) segment led the market with the largest revenue share of 65.1% in 2025.
- By application: Medical tubing segment led the market with the largest revenue share of 37.6% in 2025.
Regional Highlights
- Largest regional market: North America (41.2% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 618.1 Million
- Estimated market size in 2026: USD 675.0 Million
- Projected market size by 2033: USD 1257.8 Million
- CAGR (2026-2033): 9.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The global market for medical fluoropolymers is witnessing consistent growth, fueled by their essential function in improving safety, performance, and dependability in healthcare applications. Medical-grade fluoropolymers, including PTFE, FEP, and PVDF, provide outstanding chemical resistance, biocompatibility, and thermal stability-making them suitable for catheters, surgical tools, tubing, and implantable devices. As healthcare systems around the globe grow and focus on minimally invasive techniques, infection control, and the integration of advanced materials, the demand for fluoropolymers continues to increase.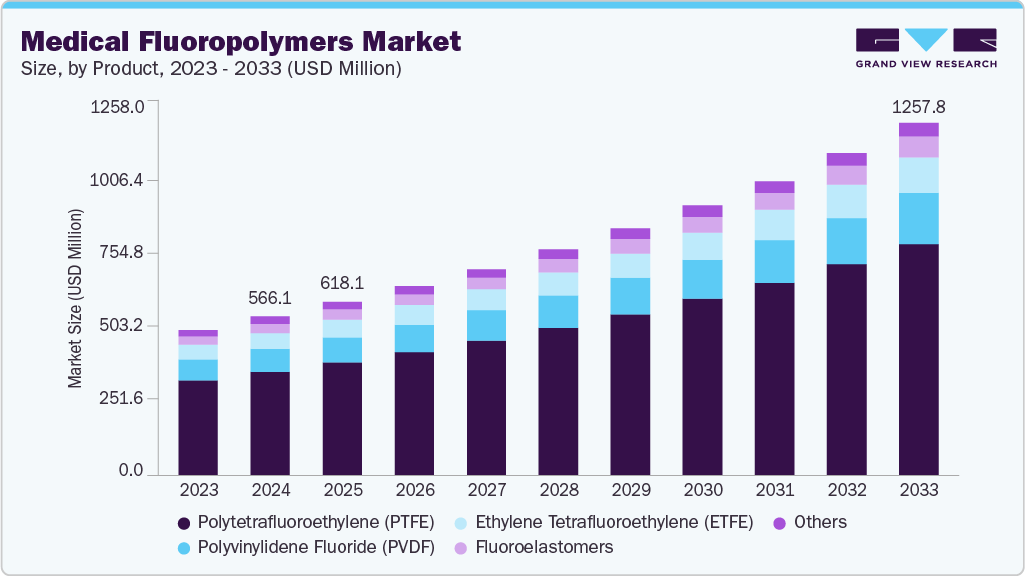 To learn more about this report, Download Free Sample Report
Moreover, ongoing advancements in medical device manufacturing and heightened regulatory attention on material safety are promoting the use of fluoropolymers within the medical industry.
Market Dynamics
The market is shaped by a tightly qualified demand base, where revenue is concentrated in tubing, catheters, medical bags, and drug delivery systems that require chemical inertness, sterilization tolerance, and low-friction performance. Demand is strongest in North America, while Asia Pacific is expanding on healthcare investment and device localization. Commercial structure remains relationship-led, with value captured through validated grades, long qualification cycles, and supplier switching barriers. Growth is therefore less dependent on broad volume expansion and more on penetration into critical medical device programs and regulated application niches.
Medical fluoropolymers are gaining faster adoption as device makers redesign products for smaller profiles, smoother delivery, and higher sterilization resistance. PTFE and ETFE are preferred in catheter liners, tubing, and drug delivery assemblies because they combine low friction with chemical inertness and thermal stability, supporting repeatable performance in critical procedures. This makes fluoropolymer grades a qualification priority rather than a discretionary material choice.
The same shift is deepening use across drug delivery and implant-adjacent systems, where material consistency, biocompatibility, and contamination control determine approval outcomes. As hospitals and device OEMs move toward single-use and higher-performance components, demand is increasingly tied to application-specific resin grades, custom extrusion, and regulatory validation. This raises the share of premium, specification-driven revenue in the market.
The market faces a structural restraint from high manufacturing cost, complex processing, and long medical validation cycles. Medical-grade fluoropolymers must pass strict material, sterilization, and traceability requirements, which delays commercialization and raises compliance expense. At the same time, rising scrutiny on PFAS chemistries is forcing producers to defend material choice more aggressively, while alternative high-performance thermoplastics and silicones continue to pressure adoption in cost-sensitive applications.
A clear opportunity exists in cleaner, PFAS-compliant fluoropolymer formulations paired with thinner-walled and radiation-resistant processing. Device OEMs are looking for materials that support safety, recyclability, and tighter dimensional control without losing performance. Suppliers that can combine compliant chemistry with advanced extrusion and application support are positioned to win share in next-generation tubing, catheter, and delivery platforms.
Market Concentration & Characteristics
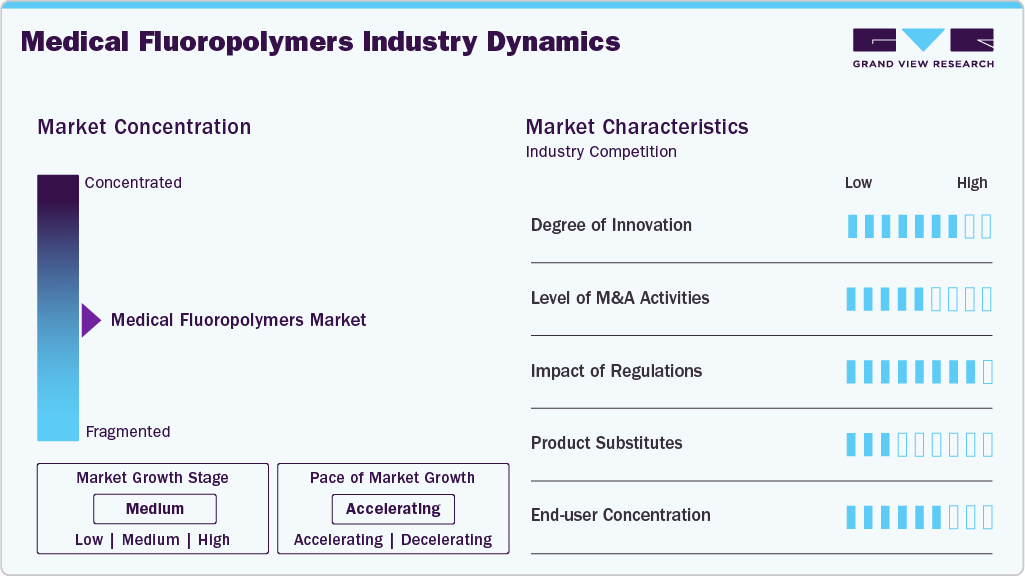
The global market for medical fluoropolymers is currently undergoing steady growth, driven by an increasing need for sophisticated, biocompatible materials in medical devices and diagnostics. The market is somewhat consolidated, with several international players enhancing their development through innovation in materials, collaboration through strategic partnerships, and expertise in regulatory compliance. Leading companies such as The Chemours Company, Daikin Industries, Ltd., Solvay SA, 3M Company, W. L. Gore & Associates, Inc., Saint-Gobain, and Zeus Industrial Products, Inc. are instrumental in influencing the market. These organizations utilize their fluoropolymer technology, particularly in PTFE, FEP, and PFA, to create solutions that improve performance, safety, and durability in vital healthcare applications, which include catheter assemblies, surgical tubing, and implantable components.
Competition stems from alternative materials like high-performance thermoplastics (such as PEEK and PPSU) and medical-grade silicones. Thermoplastics are appreciated for their durability, ability to be sterilized, and lower pricing, making them appropriate for a variety of reusable and disposable medical devices. Conversely, silicones provide outstanding flexibility, biocompatibility, and ease of processing, which makes them well-suited for implants and soft-tissue interactions. Moreover, developments in bio-based polymers and materials sourced sustainably are gaining popularity, particularly in situations where environmental factors and cost-effectiveness are important, posing additional competitive challenges to the adoption of fluoropolymers.
 To learn more about this report, Download Free Sample Report
Regulatory frameworks are essential in defining the market, especially given the stringent safety and performance requirements in the healthcare sector. In key markets like the U.S. and EU, medical components made from fluoropolymers must adhere to regulations set by organizations such as the U.S. FDA (21 CFR Part 820), the European Medical Device Regulation (MDR 2017/745), and relevant ISO standards like ISO 10993 for biocompatibility. These regulations affect everything from the composition of materials and sterilization processes to labeling and traceability. Moreover, the rising regulatory focus on PFAS substances is driving manufacturers to explore cleaner and compliant fluoropolymer chemistries, which are shaping their material choices and innovation approaches within the industry.
Analyst Perspective
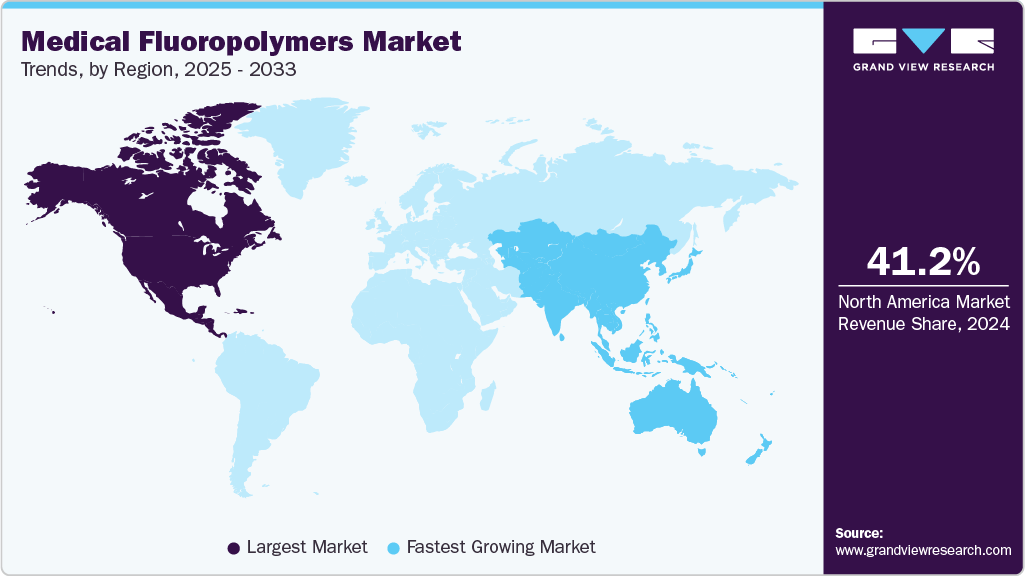
The medical fluoropolymers market is evolving from a material-supply model to an application-qualification model, where revenue depends on compliance, custom processing, and device-specific performance. Demand will remain strong for catheters, medical tubing, medical bags, and drug delivery devices, with value shifting toward cleaner chemistries and PFAS-compliant formulations. North America will remain the largest market, while Asia Pacific is expected to grow faster with expanding healthcare infrastructure and device manufacturing. Market leaders will be distinguished by regulatory expertise, technical partnerships, and production capabilities rather than price. Raw material volatility, qualification timelines, substitute materials, and environmental regulations will continue to challenge profitability.
Product Insights
Based on the product, the polytetrafluoroethylene (PTFE) segment led the market with the largest revenue share of 65.1% in 2025. Polytetrafluoroethylene (PTFE) is a synthetic fluoropolymer of tetrafluoroethylene that has numerous applications. PTFE is mainly used for the manufacturing of gaskets, pump interiors, washers, and seals on account of exhibiting chemical resistance and inertness properties. PTFE is expected to increase its application in the manufacturing of chips and encapsulation devices for quartz heaters. The growth of PTFE can be attributed to its easy blending properties with numerous fillers such as carbon graphite, glass bead, and molybdenum disulfide for enhancing certain properties.
ETFE (Ethylene Tetrafluoroethylene) is a fluorine-based plastic with enhanced strength and corrosion resistance over a wide temperature range. Due to its unique chemical and physical properties, ETFE is widely used in the chemical, architectural, electrical/electronic, construction, automotive, and health care industries. ETFE offers the best wear resistance, impact toughness, and radiation resistance of any fluoropolymer. ETFE is a melt-processable material and has mechanical qualities comparable to completely fluorinated polymers.
Due to its chemical resistance, polyvinylidene fluoride (PVDF) is utilized in biomedical sciences as an artificial membrane in immunoblotting. PVDF membranes are also utilized as membrane filtration devices in the biomedical industry. PVDF coatings exhibit resistance to abrasion and weathering, have high dielectric strength, and can extinguish the product in case of fire.
Applications Insights
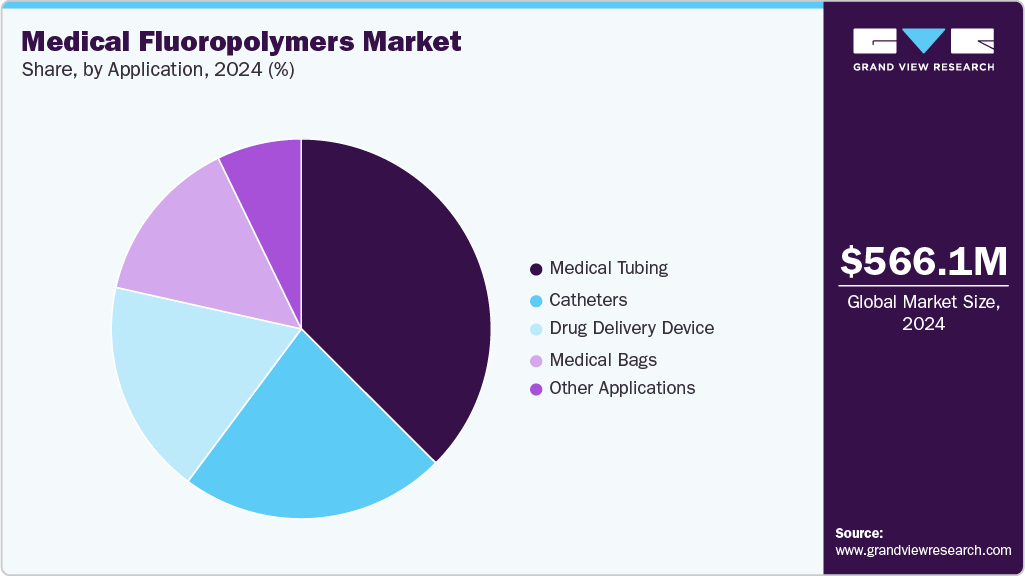
Based on application, the medical tubing segment led the market with the largest revenue share of 37.6% in 2025. Medical tubing is designed for several applications, such as anesthesiology, respiratory equipment, peristaltic pumps, biopsy, check pump functions, and diagnosing congenital heart defects, to allow clinicians to administer fluids and devices or allow for gas flow. These are also used in diagnostic instruments and bio-processing fluid transfer.
 To learn more about this report, Download Free Sample Report
The demand for medical fluoropolymers in catheters is dominated by polytetrafluoroethylene (PTFE) owing to its superior properties such as flexibility, clarity, firmness, and pliability. In addition, the enhanced mechanical and thermal properties offered by PTFE as compared to traditional materials such as rubber are expected to open up new avenues for market growth.
The implanted medical device with extended drug delivery has had a significant impact on the development of stand-alone reservoir-based delivery systems. Implant surgery is intrusive and might result in irritation or infection. The use of active therapies in conjunction with medical devices can help to lessen or eliminate the trauma of implantation.
Regional Insights
North America dominated the medical fluoropolymers market with the largest revenue share of 41.2% in 2025. The medical fluoropolymers market in North America is projected to witness significant growth in the coming years, owing to the increased demand for medical fluoropolymers for developing drug delivery devices, medical tubing, catheters, medical bags, etc. The increase in health care infrastructure spending is one of the vital reasons fueling the growth of the medical fluoropolymers market in North America.
 To learn more about this report, Download Free Sample Report
U.S. Medical Fluoropolymers Market Trends
The medical fluoropolymers market in the U.S. held the largest share in the North America region in 2025, fueled by the nation's advanced healthcare system, a high level of innovation in medical devices, and robust regulatory oversight. There is especially strong demand in areas such as catheter systems, surgical instruments, diagnostic devices, and implantable products, where biocompatibility and performance are essential. The U.S. FDA’s rigorous safety and performance standards for materials encourage the usage of high-quality fluoropolymers such as PTFE, FEP, and PFA. Furthermore, the rise in investment for minimally invasive procedures, the increasing healthcare needs of an aging population, and a focus on minimizing infection risks through single-use devices are driving the transition to fluoropolymer-based components. Additionally, the push to comply with changing PFAS regulations is motivating manufacturers to utilize cleaner and compliant formulations, further strengthening the market's long-term prospects.
Europe Medical Fluoropolymers Market Trends
The medical fluoropolymers market in Europe is set for significant growth, fueled by the region's commitment to advancing technology in the healthcare industry. European governments are encouraging the enhancement of medical infrastructure through the integration of cutting-edge and high-performance materials, such as fluoropolymers, in next-generation medical devices. The regulatory backing from the EU, along with financial support for healthcare innovation and digital transformation, is hastening the expansion of the market. Europe boasts a robust base of medical device producers, along with an increasing network of health tech startups and strategic mergers and acquisitions, reinforcing the area’s leadership in the development of medical materials. Moreover, the rising demand for biocompatible, sterilizable, and PFAS-compliant materials is anticipated to further enhance the application of fluoropolymers in vital areas like diagnostics, surgical systems, and implantable devices.
Asia Pacific Medical Fluoropolymers Market Trends
The medical fluoropolymers market in Asia Pacific is anticipated to witness considerable growth in the coming years, owing to the increasing demand for medical fluoropolymers used for developing medical tubing, catheters, membranes, venous cannula, etc. The demand for the finest medical devices and components from hospitals in major economies of Asia Pacific, including China and India, is increasing owing to the rising healthcare expenditure of these countries. In addition, the improving service and safety standards in hospitals in Asia Pacific are expected to drive the growth of the medical fluoropolymers market in the region over the forecast period.
China medical fluoropolymers market is driven by the country's ongoing healthcare reforms, increased investment in medical facilities, and a heightened demand for advanced medical technologies. As China aims for self-reliance in the production of high-quality medical devices, the necessity for high-performance materials such as fluoropolymers is on the rise, particularly in areas like surgical tools, tubing, diagnostic equipment, and implantable devices. Government initiatives that promote local innovation, alongside regulatory enhancements that align with international standards (such as reforms from China’s National Medical Products Administration), are contributing to market expansion. Furthermore, the growth of private healthcare providers and the increasing healthcare demands of an aging population are boosting the need for biocompatible, chemically inert, and sterilization-compatible materials-key benefits of medical fluoropolymers in the Chinese market.
Key Medical Fluoropolymers Companies Insights
Key players operating in the medical fluoropolymers market are undertaking various initiatives to strengthen their presence and increase the reach of their products and services. Strategies such as expansion activities and partnerships are key in propelling the market growth.
Key Medical Fluoropolymers Companies:
The following key companies have been profiled for this study on the medical fluoropolymers market.
-
Daikin Industries, Ltd.
-
The Chemours Company
-
Solvay SA
-
Arkema
-
Adtech Polymer Engineering Ltd.
-
Dongyue Group Limited
-
Saint-Gobain
-
W. L. Gore & Associates, Inc.
-
Hitachi, Ltd.
-
Holscot Fluoropolymers Ltd.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Daikin Industries, Ltd.; The Chemours Company; Solvay SA; Arkema; Dongyue Group Limited; Saint-Gobain; W. L. Gore & Associates, Inc.)
- Maintain broad fluoropolymer portfolios across PTFE, ETFE, PVDF, and related grades.
- Serve OEMs through long qualification programs and application support.
- Use global manufacturing and technical service networks to protect supply continuity.
- Strong scale in qualified medical and industrial fluoropolymer production.
- Better regulatory depth and customer trust in high-specification programs.
- Broader integration across resin, compounding, and downstream supply.
- Higher exposure to PFAS scrutiny and compliance cost.
- Slower response to niche or custom medical specifications.
- Greater dependence on mature product lines and legacy capacity.
Emerging Players (Adtech Polymer Engineering Ltd.; Hitachi, Ltd.; Holscot Fluoropolymers Ltd.)
- Focus on niche medical grades, custom extrusion, and smaller qualification programs.
- Compete through application-specific support and faster customization.
- Use selective geographic or customer partnerships to gain market access.
- Greater agility in low-volume or special-specification demand.
- Faster adaptation to customized medical device requirements.
- More focused positioning in specialty or regional supply channels.
- Limited global reach and narrower customer coverage.
- Lower bargaining power versus large OEMs and distributors.
- Smaller scale makes regulatory and commercialization costs harder to absorb.
Recent Developments
-
In June 2023, Arkema, a manufacturer of PVDF fluoropolymers, submitted feedback on the public consultation regarding the EU's restriction proposal put forth by five nations, which seeks to prohibit the production, utilization, and marketing of PFAS.
Medical Fluoropolymers Market Report Scope
Report Attribute
Details
Market size in 2025
USD 618.1 million
Estimated market size in 2026
USD 675.0 million
Projected market size by 2033
USD 1,257.8 million
Growth rate
CAGR of 9.3% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; France; UK; Italy; China; India; Japan; South Korea; Brazil; GCC Countries
Key companies profiled
Daikin Industries, Ltd.; The Chemours Company; Solvay SA; Arkema; Adtech Polymer Engineering Ltd.; Dongyue Group Limited; Saint-Gobain; W. L. Gore & Associates, Inc.; Hitachi, Ltd.; Holscot Fluoropolymers Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Medical Fluoropolymers Market Report Segmentation
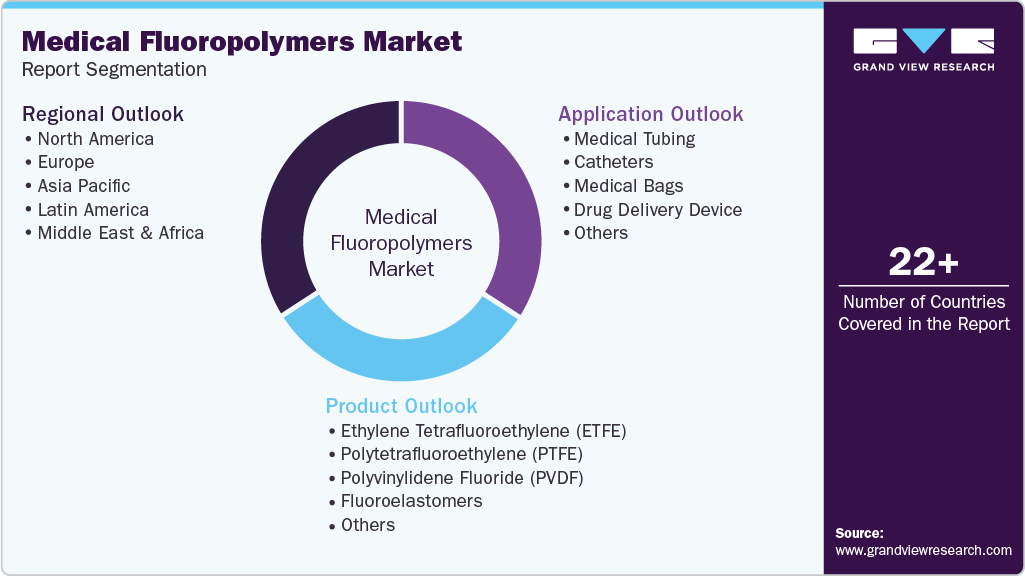
This report forecasts volume & revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global medical fluoropolymers market report on the basis of product, application, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Ethylene Tetrafluoroethylene (ETFE)
-
Polytetrafluoroethylene (PTFE)
-
Polyvinylidene Fluoride (PVDF)
-
Fluoroelastomers
-
Others
-
-
Applications Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Medical Tubing
-
Catheters
-
Medical Bags
-
Drug Delivery Device
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
UK
-
Italy
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
GCC Countries
-
-
Research Methodology
The medical fluoropolymers market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each medical fluoropolymers segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Ethylene Tetrafluoroethylene (ETFE)
Revenue is captured through sales of medical-grade ETFE resins and converted components used in tubing, liners, and protective layers where thin-wall strength, wear resistance, and sterilization tolerance support high-value device qualification.
Polytetrafluoroethylene (PTFE)
Revenue is generated through PTFE resin supply, dispersion grades, and converted medical components used in catheters, tubing liners, seals, and low-friction interfaces that require long qualification cycles and premium pricing.
Polyvinylidene Fluoride (PVDF)
Revenue is captured through PVDF resin and film sales into filtration, membrane, and diagnostic-related medical uses, where chemical resistance, dielectric strength, and processing flexibility support niche but defensible demand.
Fluoroelastomers
Revenue is earned from elastomer grades and compounded medical parts used where sealing, flexibility, and resistance to aggressive sterilization or fluid exposure create recurring replacement demand in regulated device assemblies.
Others
Revenue includes specialty fluoropolymer grades, custom compounds, and proprietary formulations sold into low-volume applications that require tailored performance, validated supply, and application-specific processing support.
Segment - Application
Revenue capture definition
Medical Tubing
Revenue is captured through resin consumption, extrusion, and finished tubing supply for fluid transfer, respiratory, anesthesiology, and diagnostic applications where product performance and regulatory compliance drive repeat orders.
Catheters
Revenue is generated through liner materials, jacket layers, and specialty tubing grades used in catheter systems, with monetization concentrated in high-specification, clinically validated, and low-friction product formats.
Medical Bags
Revenue is captured through film, sheet, and flexible container grades used in drug storage, collection, and transfer systems where chemical inertness, seal integrity, and sterility support premium positioning.
Drug Delivery Device
Revenue is earned from precision components, reservoirs, delivery system parts, and coated interfaces where dimensional control and biocompatibility determine adoption in implant-adjacent and controlled-release systems.
Others
Revenue includes surgical tools, diagnostic assemblies, membranes, and other regulated medical uses that do not fit the primary categories but still require high-performance fluoropolymer inputs.
Estimation Model
Layer Name
Key Question
Description
Demand Validation Layer
Where is demand generated?
This layer anchors the estimate to validated medical device consumption, because qualification status and end-use intensity define accessible revenue.
Product Mix Layer
Which grades drive revenue?
Revenue varies by PTFE, ETFE, PVDF, and fluoroelastomer adoption, so product-level mix captures grade-specific pricing and conversion economics.
Application Mapping Layer
Which applications consume materials?
Tubing, catheters, bags, and drug delivery devices monetize differently, depending on replacement cycles, specification lock-in, and processing depth.
Regional Normalization Layer
Where is revenue concentrated?
Regional demand reflects regulation, healthcare investment, and manufacturing localization, which reshape qualification patterns and supplier pricing power.
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Add country-level forecast split for the U.S., Germany, China, India, and Brazil
The report can be expanded to include country-level demand, pricing, and application trends for each priority market, with separate analysis for local manufacturing, import reliance, and medical device consumption patterns.
Improves decision-making for regional entry, channel selection, and investment prioritization.
Add deeper application split across catheter liners, tubing, bags, and drug delivery components
The report can be extended to break each application into sub-use cases, with revenue logic tied to qualification intensity, resin grade preference, and customer purchasing behavior.
Clarifies revenue pockets and identifies higher-margin use cases.
Add competitive benchmarking for key companies by product focus and regional strength
The report can be customized with a structured competitor matrix covering product portfolio breadth, medical certifications, geographic presence, and strategic positioning across the value chain.
Supports faster competitive assessment and partner shortlisting.
Frequently Asked Questions About This Report
The global expanded polypropylene foam market size was valued at USD 618.1 million in 2025 and is projected to grow from USD 675.0 million in 2026.
Some of the key players operating in the medical fluoropolymers market include Daikin Industries, Ltd., The Chemours Company, Solvay SA, Arkema, Adtech Polymer Engineering Ltd., Dongyue Group Limited, and Saint-Gobain.
Key factors driving the medical fluoropolymers market growth include an increase in demand for advanced medical technology and devices and increasing healthcare investments across emerging economies.
Based on application, the medical tubing segment led the market with the largest revenue share of 37.6% in 2025.
The Asia Pacific medical fluoropolymers market is expected to grow at a rapid CAGR of 9.7% over the forecast period.
The market is shaped by a tightly qualified demand base, where revenue is concentrated in tubing, catheters, medical bags, and drug delivery systems that require chemical inertness, sterilization tolerance, and low-friction performance.
A clear opportunity exists in cleaner, PFAS-compliant fluoropolymer formulations paired with thinner-walled and radiation-resistant processing. Device OEMs are looking for materials that support safety, recyclability, and tighter dimensional control without losing performance. Suppliers that can combine compliant chemistry with advanced extrusion and application support are positioned to win share in next-generation tubing, catheter, and delivery platforms.
The global medical fluoropolymers market is expected to grow at a compound annual growth rate of 9.3% from 2026 to 2033 to reach USD 1,257.8 million by 2033.
North America dominated the medical fluoropolymers market with the largest revenue share of 41.2% in 2025.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


