
- Home
- »
- Medical Devices
- »
-
Medical Thawing System Market Size Report, 2025-2030GVR Report cover

Medical Thawing System Market (2025 - 2030)
Size, Share & Trends Analysis Report By Type (Manual, Automated), By Sample (Blood, Embryo, Ovum, Semen), By End-use (Hospitals, Tissue Banks), By Region, And Segment Forecasts
Market Size, 2024
$221.9MMarket Estimate, 2026
$257.9MMarket Forecast, 2030
$355.9MCAGR, 2025–2030
8.3%Medical Thawing System Market Trends
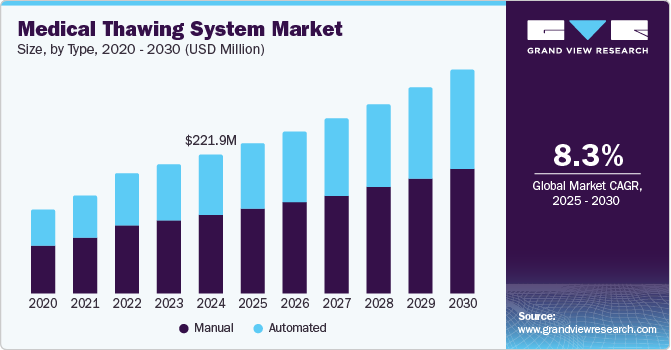
The global medical thawing system market size was valued at USD 221.9 million in 2024 and is projected to grow from USD 257.9 million in 2026 to USD 355.9 million by 2030, at a CAGR of 8.3% from 2025 to 2030. North America dominated the market, accounting for a revenue share of 47.3% in 2024. As awareness regarding blood donation rises, there has been a notable increase in blood donors, thereby amplifying the demand for thawing systems integral to blood banks and transfusion centers. The urgency to have thawed blood products rapidly available, particularly for managing hemorrhagic cases, has catalyzed the advancement of thawing technologies that ensure a swift and safe thawing process while maintaining the integrity of critical biological materials.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Technological advancements significantly drive market growth, as the emergence of automated thawing systems has revolutionized conventional practices, improving both efficiency and safety throughout the thawing process. These systems facilitate controlled temperature management and agitation, significantly reducing thaw times while ensuring the efficacy of plasma and other cellular products. The Organ Procurement and Transplantation Network 2023 report highlights a significant evolution in organ transplantation, with approximately 46,632 procedures performed-a notable 8.7% increase from the previous year-underscoring the growing necessity for dependable thawing solutions to ensure optimal preparation of tissues and organs prior to transplantation.
Furthermore, the shift toward portable thawing devices reflects broader trends in decentralized healthcare delivery models. The ability to thaw blood products and tissues at point-of-care locations, including ambulances and emergency rooms, is critical, particularly in trauma cases where time is of the essence. This flexibility ultimately enhances patient outcomes and expands the applicability of thawing technologies across various medical settings, aligning well with the growing emphasis on accessible healthcare solutions.
As research and clinical applications in this sector gain traction, the demand for cutting-edge thawing technologies that facilitate the preparation of living cells and tissues is likely to rise. Coupled with sustained government initiatives and positive reimbursement cycles for plasma donation, the market growth highlights the critical intersection between technology, healthcare, and patient care.
Market Dynamics
Some of the causes of chronic diseases are serious trauma, sepsis, loss of blood, poisoning, drug abuse, leukemia, and other acute illnesses. Serious organ failure is associated with acute illnesses that are associated with degradation of organ functioning. Glomerular diseases, diabetes, and hypertensive nephrosclerosis may result in kidney failure. Similarly, cirrhosis leads to liver failure and likewise coronary heart disease may lead to heart failure. Obesity, alcohol and drug abuse, and smoking may lead to such conditions, which could ultimately result in organ failure.
Thus, global demand for tissue and organ transplantation, mainly for bone marrow, heart, liver, kidney, and lungs, is very high. According to the U.S. Government Information on Organ Donation and Transplantation, about 112,000 candidates were registered on the U.S. national transplant waiting list by March 2020.
An increase in the number of geriatric population due to improved and advanced healthcare facilities has also contributed to the high demand for organ transplantation. Thus, the increase in the number of acute illnesses and rise in the geriatric population are factors leading to an increase in organ failures globally, therefore driving demand for thawed blood.
The high cost of these devices is a major hindrance to the market. The way in which the healthcare industry and its delivery are financed and reimbursed influences the price at which medical innovation emerges and gains acceptance. Many devices are reimbursed at a level significantly greater than their cost.
The cost barrier in developing countries is much higher than in developed countries. In many developing countries, only 5–15% of the people have access to assistive devices and technologies. The major reason for inadequate access to these devices is the excessive cost.
Inadequate reimbursement policies are proving to be a disincentive to innovation, slowing the introduction of advanced automation solutions in price-sensitive regions and limiting broader patient access.
Type Insights
Manual thawing systems led the market with a revenue share of 56.6% in 2024, owing to their cost-effectiveness and extensive product variety. Manual thawing systems are particularly appealing to budget-constrained healthcare facilities, largely because of their straightforwardness and adaptability in thawing protocols, which maintain their popularity even amidst advancements in automated systems.
Automated systems are expected to grow at the fastest CAGR of 8.6% over the forecast period. Automated thawing systems offer consistent and precise temperature control, significantly reducing the risk of damage to biological materials. By minimizing human error associated with manual methods and achieving rapid thawing in under three minutes, these systems are essential for time-sensitive medical procedures, including organ transplantation, while also adhering to stringent regulatory standards.
Sample Insights
The blood segment dominated the market and accounted for a share of 52.6% in 2024. The demand for rapid thawing of blood products in emergency and surgical settings is escalating, driven by the increasing volume of surgical procedures and the critical need for thawed blood in hemorrhage cases. Technological advancements in safe thawing processes, alongside greater awareness and a growing donor base, further enhance this requirement.
The embryo segment is expected to register the fastest CAGR of 9.0% over the forecast period. The growing adoption of in vitro fertilization (IVF) has led to a substantial increase in embryo transfers and a rising demand for reliable thawing solutions. In 2023, India performed approximately 160,000 IVF cycles, reflecting a trend fueled by advancements in reproductive technology and heightened awareness among couples facing infertility challenges.
End-use Insights
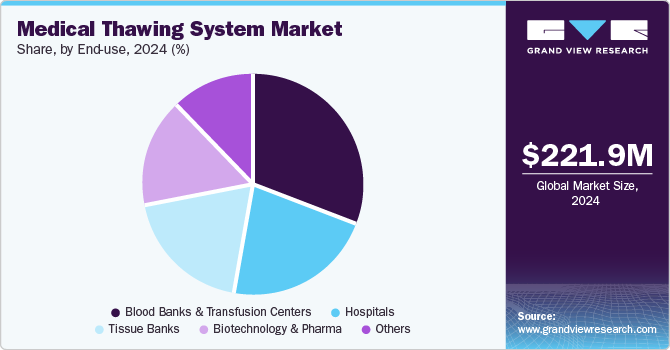
Blood banks & transfusion centers held the largest share of 31.4% in 2024. The demand for rapid thawing of blood products, especially fresh frozen plasma and red blood cells for emergency transfusions, is increasing. As surgical procedures and trauma cases rise, the need for efficient thawing solutions becomes critical. Advancements in thawing technology further enhance safety and reduce thawing time, ensuring effective patient care.
 To learn more about this report, Download Free Sample Report
Tissue banks are projected to grow at the fastest CAGR of 8.5% over the forecast period. The demand for efficient thawing solutions for stored human tissues, such as skin, bone, and corneas, is rising due to the recovery and storage efforts of tissue banks. Advancements in regenerative medicine and an emphasis on tissue transplantation underscore the necessity for specialized thawing technologies that preserve tissue integrity.
Regional Insights
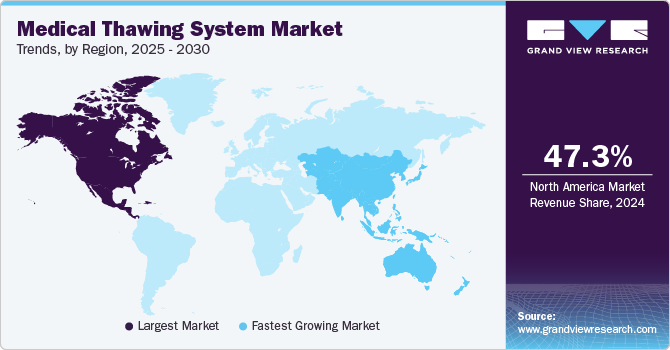
North America medical thawing system market dominated the global market with a revenue share of 47.3% in 2024. North America experiences a high prevalence of chronic diseases, driving demand for efficient thawing solutions for blood and plasma products. The region’s robust healthcare infrastructure and leading manufacturers enhance access to innovative thawing technologies. Furthermore, rising awareness of blood and plasma donation, alongside government initiatives, significantly supports market growth and adoption.
 To learn more about this report, Download Free Sample Report
U.S. Medical Thawing System Market Trends
The U.S. medical thawing system market dominated the North America medical thawing system market with a revenue share of 81.9% in 2024. The presence of over 14 million active blood donors underscores the critical need for efficient thawing solutions to facilitate timely transfusions. Supportive government initiatives and heightened awareness of blood donation are driving market growth. Leading companies such as GE Healthcare and Helmer Scientific promote innovation and product availability to meet rising demands.
Europe Medical Thawing System Market Trends
Europe medical thawing system market held substantial market share in 2024. The growing prevalence of chronic diseases demands efficient thawing solutions for blood and tissue products. Europe’s stringent regulatory standards enhance confidence in quality medical devices. Moreover, increasing awareness of organ donation and advancements in regenerative medicine are driving demand for reliable thawing systems in hospitals and tissue banks.
The medical thawing system market in UK is expected to grow in the forecast period. The National Health Service underscores the critical role of efficient thawing systems for timely access to blood products in emergencies. Moreover, increasing awareness of organ donation and advancements in reproductive technologies enhance the demand for reliable thawing solutions in fertility clinics, positioning the UK as a significant player in the European market.
Asia Pacific Medical Thawing System Market Trends
Asia Pacific medical thawing system market is expected to register the fastest CAGR of 6.1% in the forecast period. Rapid urbanization and advancements in healthcare infrastructure are enhancing access to cutting-edge medical technologies, including thawing systems. Moreover, growing awareness of semen and ovum cryopreservation is driving demand in reproductive health sectors. Government initiatives to improve healthcare services further bolster market growth, fostering a favorable environment for innovation and development.
The medical thawing system market in China dominated the Asia Pacific medical thawing system market in 2024. The growing demand for blood and plasma products, fueled by the rise in chronic diseases, significantly impacts market growth. Government initiatives promoting plasma donation and advancements in thawing technologies enhance efficiency and safety. The expansion of the pharmaceutical sector in China attracts manufacturers aiming to capitalize on this lucrative market opportunity.
Key Medical Thawing System Company Insights
Some key companies operating in the market include Helmer Scientific Inc.; SARSTEDT AG & Co. KG; Azenta US, Inc.; GE HealthCare; among others. Companies are prioritizing product innovation, strategic partnerships, and mergers while investing in technological advancements and expanding offerings to address the growing demand for efficient thawing solutions.
-
Helmer Scientific Inc. specializes in manufacturing medical thawing systems that ensure precise temperature control for thawing blood and plasma products. Their advanced technology enhances safety and efficiency in blood banks and laboratories, addressing the increasing demand for thawed biological materials.
-
SARSTEDT AG & Co. KG provides a comprehensive array of medical thawing solutions tailored for laboratories and healthcare facilities. Their systems effectively thaw diverse biological samples, ensuring optimal temperature control and user-friendly operation, while emphasizing innovation and quality in medical technologies.
Key Medical Thawing System Companies:
The following are the leading companies in the medical thawing system market. These companies collectively hold the largest market share and dictate industry trends.
- Helmer Scientific Inc.
- SARSTEDT AG & Co. KG
- Azenta US, Inc.
- GE HealthCare
- Boekel Scientific
- Barkey
- Cardinal Health
- Thermo Fisher Scientific Inc.
- Cytotherm
Prism AI by Grand View Research Free to tryAsk a question about the medical thawing system marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →Recent Developments
-
In March 2023, Barkey launched the Vialguard Pro, an automated solution designed to thaw multiple small volume vials vertically, building on their expertise in fluid warming for the cell and gene therapy sector.
Medical Thawing System Market Report Scope
Report Attribute
Details
Market size in 2024
USD 221.9 million
Estimated market size in 2026
USD 257.9 million
Projected market size by 2030
USD 355.9 million
Growth rate
CAGR of 8.3% from 2025 to 2030
Base year for estimation
2024
Historical data
2018 - 2023
Forecast period
2025 - 2030
Quantitative units
Revenue in USD million and CAGR from 2025 to 2030
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, trends
Segments covered
Type, sample, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S., Canada, Mexico, UK, Germany, France, Italy, Spain, Denmark, Sweden, Norway, China, Japan, India, Australia, South Korea, Thailand, Brazil, Argentina, South Africa, Saudi Arabia, UAE, Kuwait
Key companies profiled
Helmer Scientific Inc.; SARSTEDT AG & Co. KG; Azenta US, Inc.; GE HealthCare; Boekel Scientific; Barkey; Cardinal Health; Thermo Fisher Scientific Inc.; Cytotherm
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Medical Thawing System Market Report Segmentation
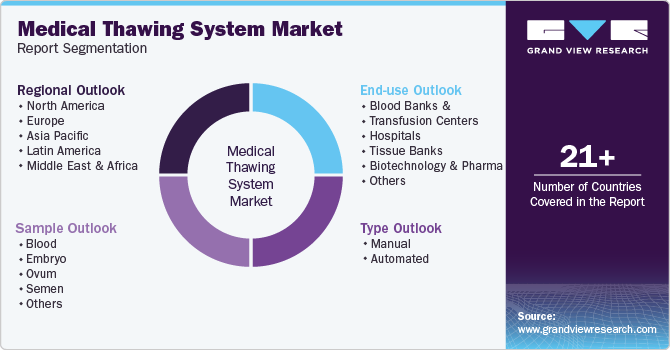
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2018 to 2030. For this study, Grand View Research has segmented the global medical thawing system market report based on type, sample, end-use, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million, 2018 - 2030)
-
Manual
-
Automated
-
-
Sample Outlook (Revenue, USD Million, 2018 - 2030)
-
Blood
-
Embryo
-
Ovum
-
Semen
-
Others
-
-
End-use Outlook (Revenue, USD Million, 2018 - 2030)
-
Blood Banks & Transfusion Centers
-
Hospitals
-
Tissue Banks
-
Biotechnology & Pharma
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2018 - 2030)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Frequently Asked Questions About This Report
Some key players operating in the medical thawing system market include Helmer Scientific (U.S.), Sartorius (Germany), Boekel Scientific (U.S.), Barkey, BioCision LLC, and Cardinal health.
Key factors that are driving the medical thawing system market growth include the rising incidence of various chronic diseases and increasing demand for faster thawing solutions. The growing demand for thawing of plasma on-demand and technological advancement in thawing systems are also contributing to the market growth.
The global medical thawing system market size was valued at USD 221.9 million in 2024 and is estimated at USD 257.9 million for 2026.
The global medical thawing system market is expected to grow at a CAGR of 8.3% from 2025 to 2030, reaching USD 355.9 million by 2030.
North America dominated with a revenue share of 47.3% in 2024.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst -

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


