
- Home
- »
- Advanced Interior Materials
- »
-
Metal Powder Market Size & Share Report, 2026-2033GVR Report cover

Metal Powder Market (2026 - 2033)
Size, Share & Trends Analysis Report By Materials (Ferrous, Non-Ferrous), By Technology (Press & Sinter, Additive Manufacturing), By Application, By Region, And Segment Forecasts
Market Size, 2025
$7.7BMarket Estimate, 2026
$8.6BMarket Forecast, 2033
$13.6BCAGR, 2026–2033
6.8%Metal Powder Market Summary
The global metal powder market size was valued at USD 7.7 billion in 2025 and is projected to grow from USD 8.6 billion in 2026 to USD 13.6 billion by 2033, at a CAGR of 6.8% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 35.5% in 2025. Increasing demand for additive manufacturing (AM) components from the aerospace industry is driving market growth.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By technology: Press & sinter segment led the market with the largest revenue share of 45.7% in 2025.
- By materials: Ferrous segment led the market with the largest revenue share of 68.8% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (35.5% revenue share, 2025)
- By country: The China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 7.7 Billion
- Estimated market size in 2026: USD 8.6 Billion
- Projected market size by 2033: USD 13.6 Billion
- CAGR (2026-2033): 6.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
AM technology is an extremely reliable system, which enables the manufacturing of highly complex designs and geometries that cannot be made from other processes.Owing to an increase in demand for AM from aerospace & defense industries, key players are investing in expanding their capacity. For instance, in July 2023, Collins Aerospace announced that it is going to invest USD 14.0 million in the expansion of the AM facility.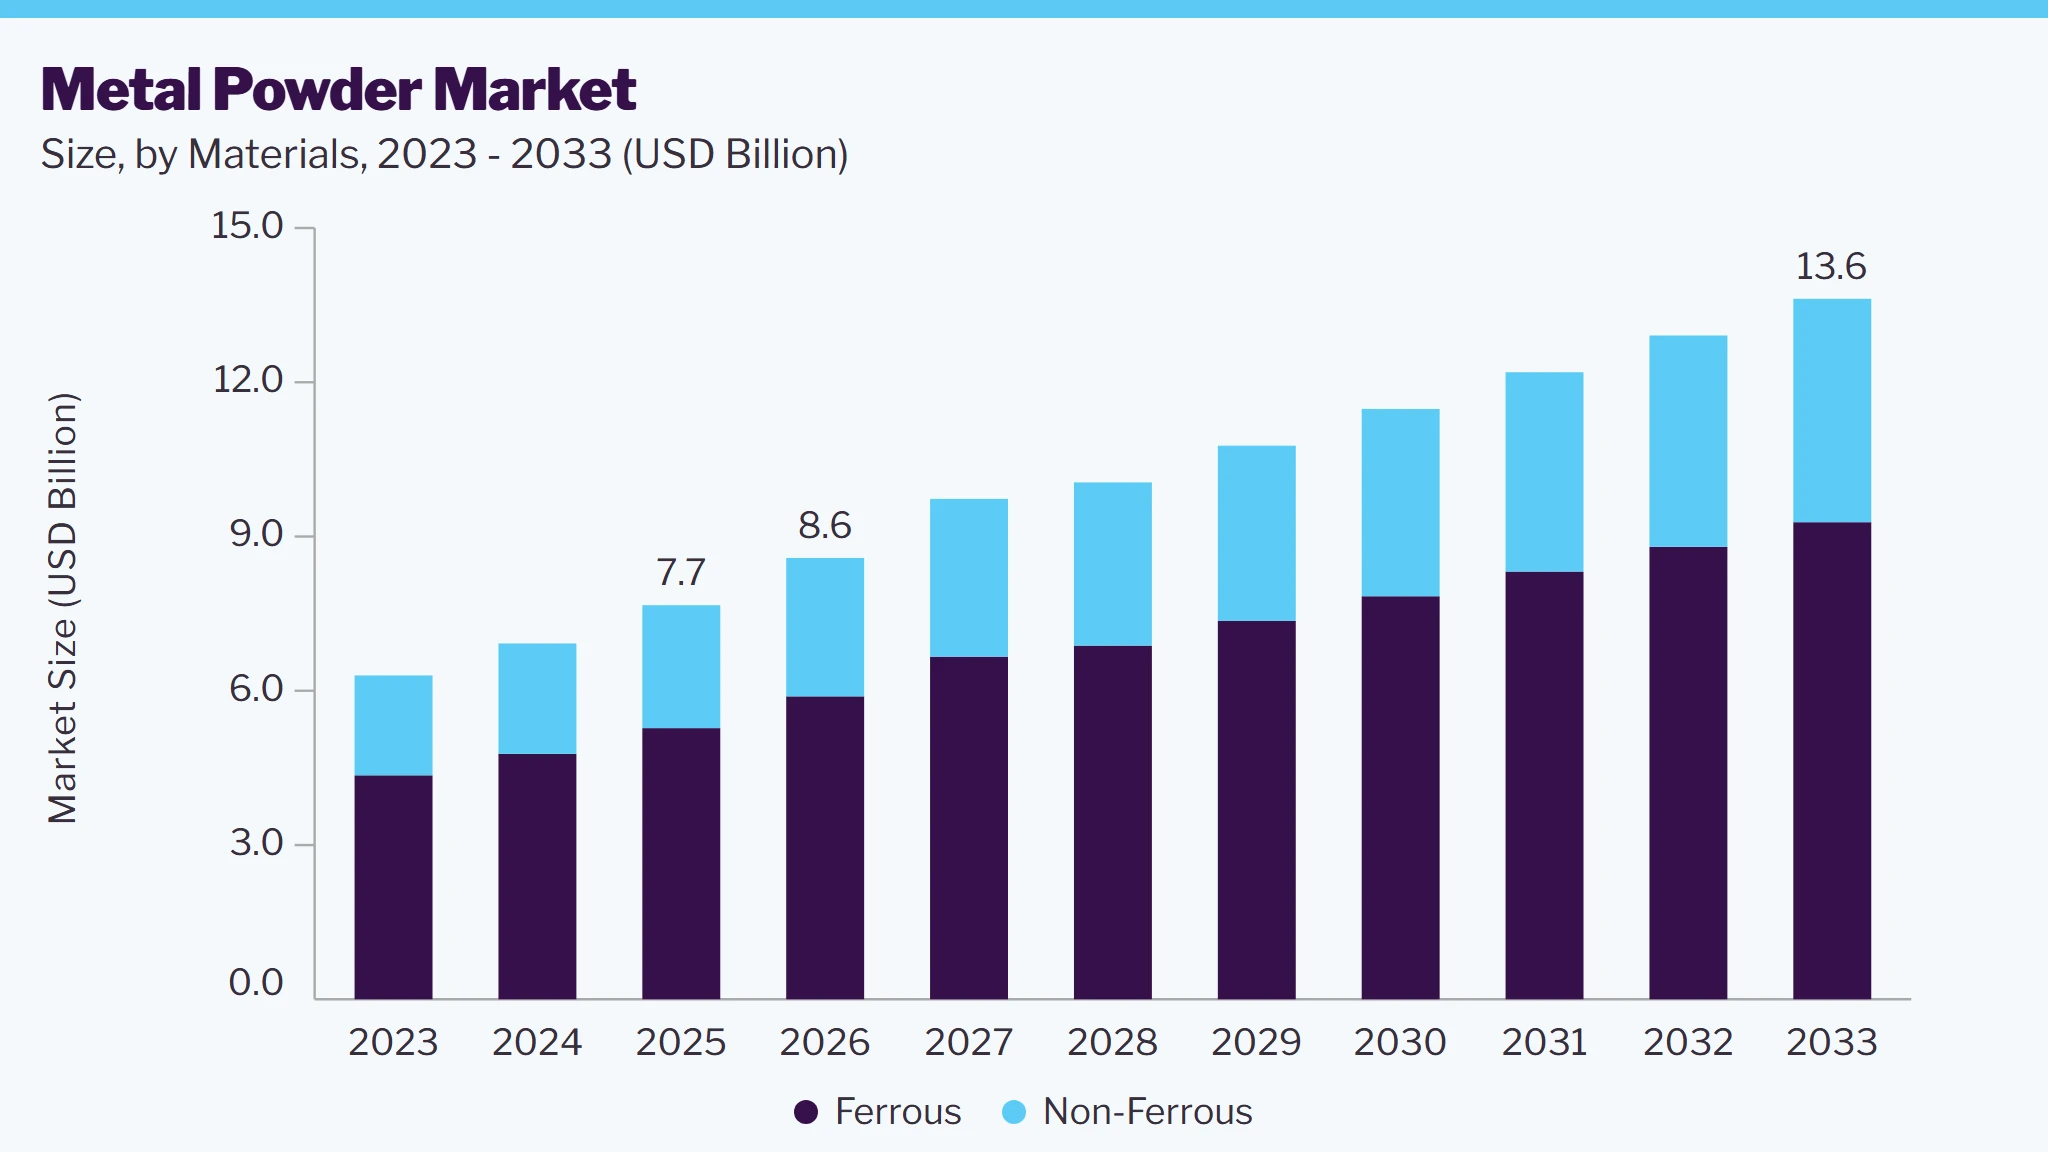 To learn more about this report, Download Free Sample Report
Product-based components are extensively used in various end use industries, including automotive, industrial, electronics, firearms, and healthcare. Powder metallurgy can produce structural, magnetic, & next-generation high-performance parts and tribological components. Growth in end use industries is expected to propel demand for powdered parts in the U.S. during the forecast period.
Rising geopolitical tensions have pushed countries to increase and upgrade their aerospace & defense equipment, which is expected to augment consumption of the product over the forecast period. For instance, the German government has invested EUR 10 billion (USD 10.83 billion) to purchase F-35 fighter jets from the U.S.
The aerospace & defense segment is an early adopter of additive manufacturing (AM). Companies such as NASA, SpaceX, and other aerospace organizations are benefiting from AM technology as it facilitates the production of prototypes with high geometric accuracy in less time and ensures minimal wastage of material. Owing to the reasons above, several aerospace & defense companies are ordering metal AM printers.
Market Dynamics
The growth of the metal powder market is being primarily driven by the rapid adoption of additive manufacturing and powder metallurgy technologies across industries such as aerospace, automotive, medical, and industrial machinery. Metal powders serve as the primary feedstock for 3D printing processes, enabling the production of lightweight, high-strength, and geometrically complex components with minimal material waste. Compared with conventional machining methods, additive manufacturing improves material utilization, shortens production cycles, and enables part customization, making it increasingly attractive for manufacturers seeking cost-efficient and sustainable production solutions. Continuous advancements in atomization technologies and powder quality are further enhancing the performance and consistency of metal powders, accelerating their adoption in high-precision applications.
The growing demand for lightweight automotive and electric vehicle (EV) components is a major factor driving the metal powder market. Automakers are increasingly using powder metallurgy to manufacture lightweight, high-strength components that improve fuel efficiency, extend EV driving range, and reduce overall vehicle weight. Metal powders enable the production of complex, precision-engineered parts with minimal material waste and excellent mechanical properties, making them ideal for gears, bearings, transmission systems, electric motors, and structural components. As global vehicle manufacturers continue to invest in electrification and sustainable mobility solutions, the demand for advanced metal powders is expected to increase steadily, supporting the market's long-term growth.
The automotive industry's shift toward vehicle lightweighting and electrification is significantly boosting the demand for metal powders. Manufacturers are increasingly adopting powder metallurgy to produce durable, high-precision components that reduce material consumption while maintaining superior strength and performance. These lightweight metal parts contribute to improved fuel economy in conventional vehicles and enhanced battery efficiency and driving range in electric vehicles. With rising EV production, stricter emission regulations, and increasing investments in advanced automotive manufacturing, the consumption of metal powders is expected to grow across a wide range of vehicle applications.
Volatility in raw material prices is a significant restraint on the metal powder market, as fluctuations in the costs of metals such as iron, aluminum, nickel, titanium, and copper directly affect manufacturing costs and profit margins. Price instability is influenced by factors such as supply chain disruptions, geopolitical tensions, mining output fluctuations, trade policies, and shifts in global demand. These unpredictable cost fluctuations make it challenging for metal powder manufacturers to maintain stable pricing and long-term supply agreements. As a result, end-use industries may face higher production costs, which could affect the adoption of metal powders, particularly in price-sensitive applications.
The increasing adoption of metal additive manufacturing across industries presents a significant growth opportunity for the metal powder market. Sectors such as aerospace, automotive, healthcare, energy, and industrial manufacturing are expanding the use of metal 3D printing to produce complex, lightweight, and customized components with high precision and reduced material waste. As manufacturers seek faster product development, lower production costs, and greater design flexibility, demand for high quality metal powders continues to rise. Ongoing advancements in additive manufacturing technologies and increasing investments in digital manufacturing are expected to further accelerate the consumption of specialty metal powders in the coming years.
Market Concentration & Characteristics
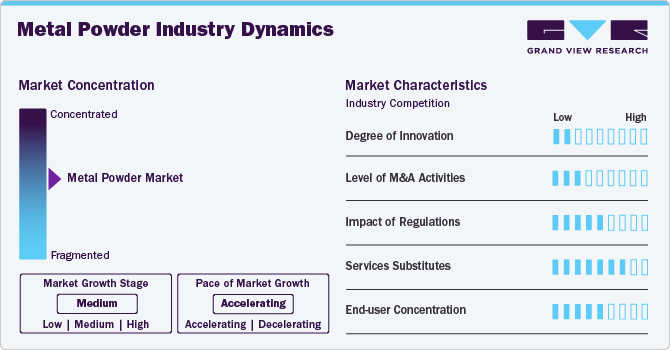
The metal powder industry is characterized by the presence of established players, including GKN PLC, Sandvik AB, and Höganäs AB. Companies use an established distribution and sales network to connect with their customers across different regions. New product development and competitive pricing are some of the key focus areas for manufacturers to strengthen their position in the market.
Growth of lightweight vehicles, technological advancements, and raw material costs influence the price of products along with macroeconomic factors. Market players formulate their strategies in line with the above factors, along with the performance of key application industries, namely automotive, oil & gas, aerospace & defence, and medical.
 To learn more about this report, Download Free Sample Report
Key players are using mergers and acquisitions activity across the globe, as large players acquire minority stakes in smaller producers that have advantages like advanced technology, efficient processes, or a solid presence in the market. Promotion of innovation, lower costs, and enhanced synergies within operations is also an essential element to enhance these activities in the industry.
The material used in AM to produce a wide range of end use products costs more than the material used in the traditional method. For instance, stainless steel as a raw material in AM costs over USD 8 per square centimetre compared to the ones used in traditional manufacturing. Thus, due to high cost of manufacturing acts as an AM market growth restraint.
Analyst Perspective
The metal powder market is set for sustained growth as advanced manufacturing technologies continue to reshape production across automotive, aerospace, healthcare, electronics, and industrial sectors. The increasing adoption of powder metallurgy and metal additive manufacturing is driving demand for high-quality metal powders that enable lightweight, high-strength, and precision-engineered components while minimizing material waste. Rapid growth in electric vehicles, industrial automation, and aerospace manufacturing is further accelerating the need for specialized metal powders used in structural parts, medical implants, tooling, and energy applications.
Material Insights
Based on materials, ferrous segment led the market with the largest revenue share of 68.8% in 2025. The segment encompasses a range of steel types and their alloys, along with iron and alloying elements such as molybdenum, nickel, and chromium. Steel is cost-effective and can be utilized in AM and blended with other materials, such as bronze.
The non-ferrous segment consists of aluminum, copper, zinc, titanium, tungsten, magnesium, and others. Aluminum's desirable traits, such as good strength and lightweight nature, are anticipated to increase its demand. It is widely used in the manufacturing of equipment, including functional parts and cycles. Aluminum-based equipment is produced using a 3D printing process called direct metal laser sintering.
Rising demand for titanium implants in the healthcare industry is projected to fuel the growth of this segment. To address deformities in the bones, human skull, and vertebrae, companies Novax DMA and CEIT Biomedical Engineering have started manufacturing medical implants made of titanium.
Technology Insights
Based on technology, press & sinter segment led the market with the largest revenue share of 45.7% in 2025. In the conventional powder metallurgy process, press and sinter are used. It is economic and produces near-net-shape components. Manufacturing a green compact involves heat treatment or compaction at temperatures lower than the melting point of the metal.
This mechanical bonding of particles contributes to increasing component strength. In addition, green compacts are sintered in a controlled atmosphere where they undergo metallurgical bonding to form their finished components. To attain accurate tolerances and a favorable finish of the surface, additional tasks such as plating, repression, or finishing can be carried out.
For the past 20 years, MIM technology has gained significant importance in the component industry. This process is based on shaping and sintering of particles similar to that used in the press or sinter. High volumes of complicated-shaped parts, with high manufacturing accuracy, can be produced through this method. There are different steps in the MIM process, e.g., mixing or processing of raw materials, injection molding, removal of bindery, and sintering.
Application Insights
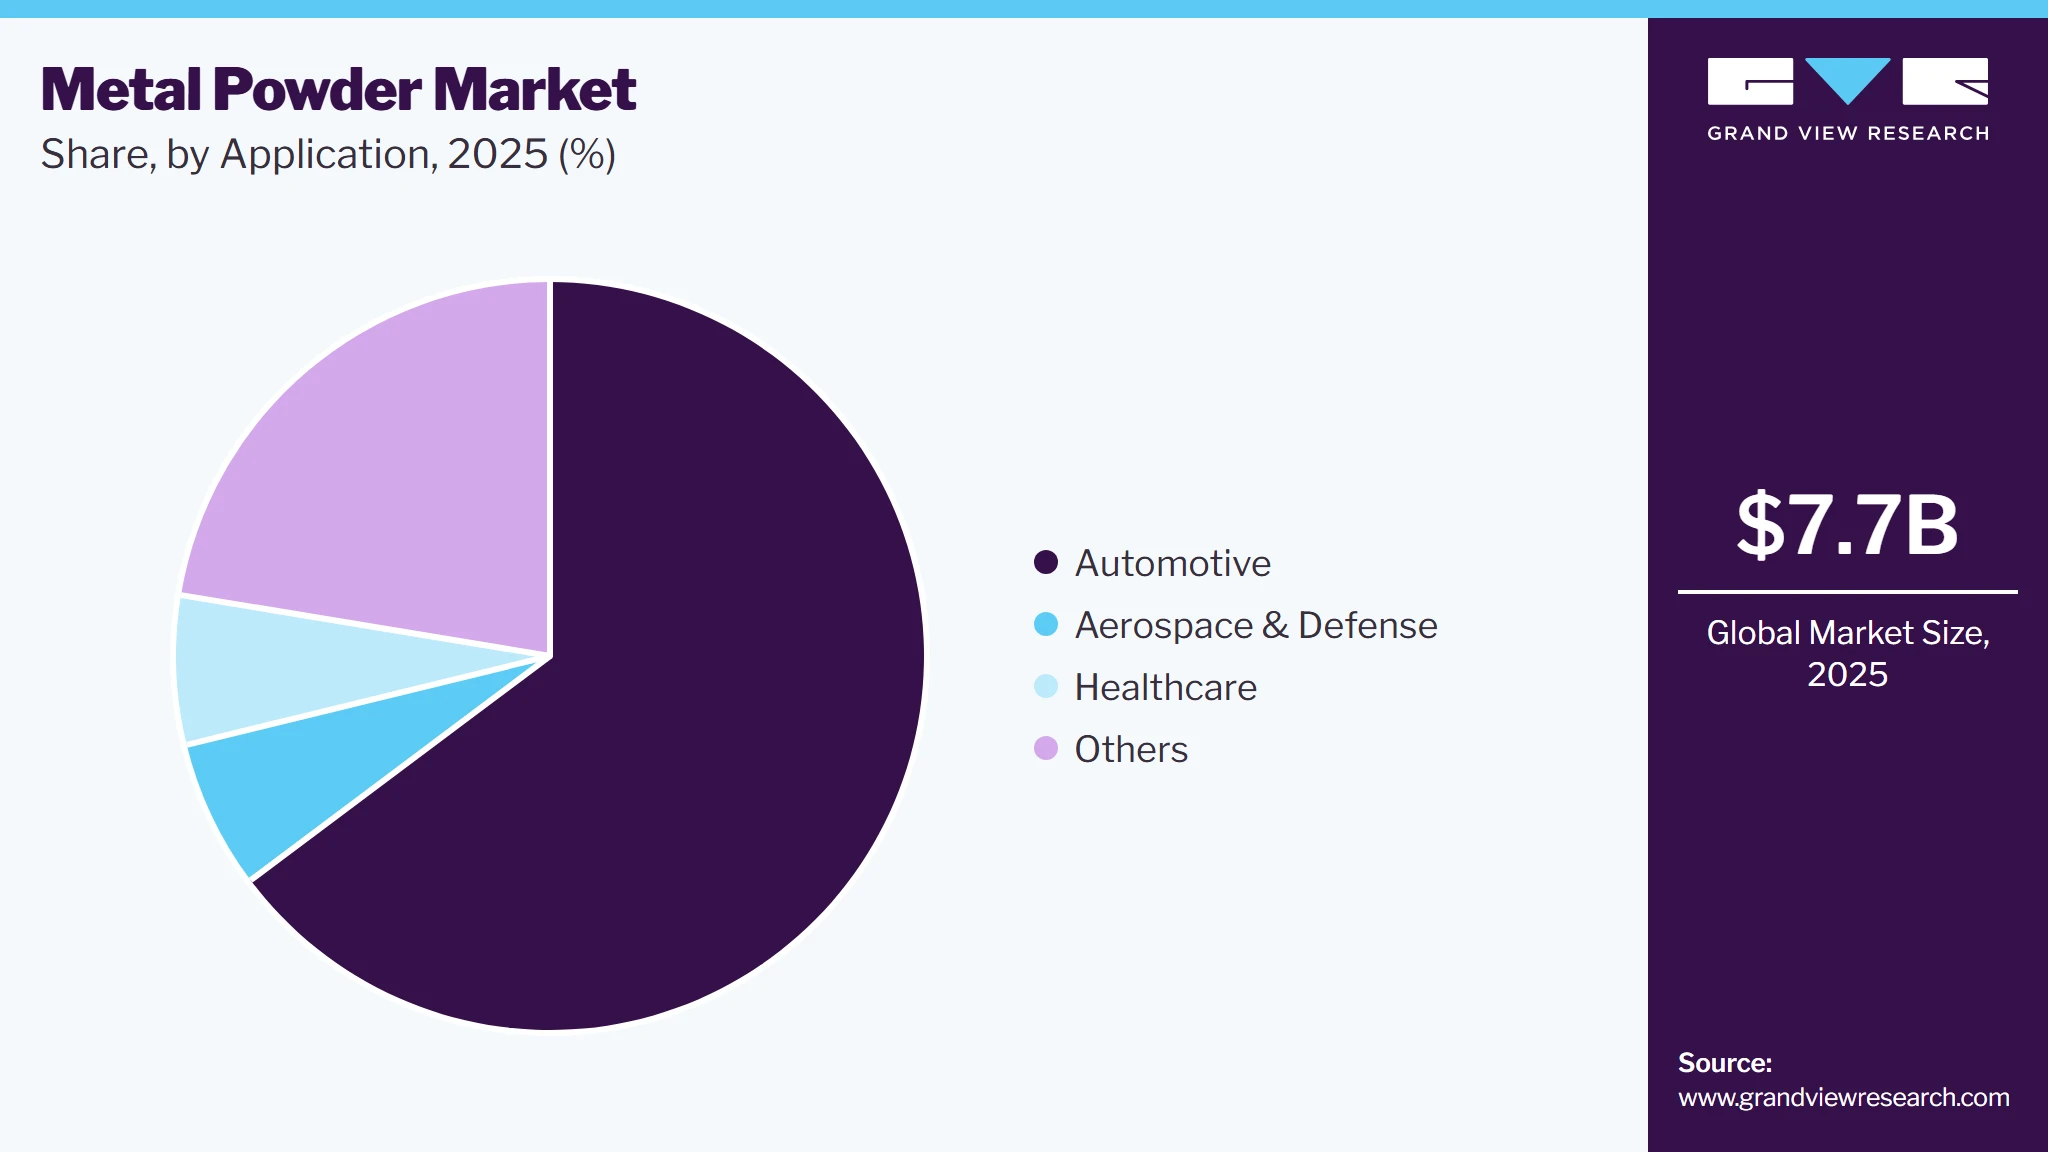
Based on application, automotive segment led the market with the largest revenue share of 64.8% in 2025. In the automotive industry, various parts and components of engines, chassis, and transmissions are manufactured using powder metallurgy technology, which is propelling the demand for metal powder.
 To learn more about this report, Download Free Sample Report
The aerospace & defense segment is an early adopter of the AM. This technology helps manufacturers to develop complex parts and prototypes. Hence, the aerospace and defense companies are purchasing new AM printers. For instance, in September 2023, GKN Aerospace ordered two 3D- 3D-printing systems from Nikon SLM Solutions.
The healthcare sector is driven by the increased awareness among consumers regarding various diseases and the rise in consumer willingness to pay more for end products. In addition, the application of metal powder technology in the health sector is driving this segment as it manufactures inserting plates, foot adapters, blacking plates, surgical blades, forceps, graspers, and Blacking Hooks.
Regional Insights
The North America metal powder industry is projected to expand at a growth rate of 5.7% from 2025 to 2033 in terms of revenue. In particular, demand for different sintered parts in transmissions and engines has been reduced due to the increasing popularity of vehicles that are both energy efficient and hybrid. Nevertheless, the market vendors are expected to have lucrative opportunities over the next few years through powder forging technology. According to the Federation of Metal Powder Industries, almost 30% of automotive coupling rods are produced through powder forging processes worldwide.
 To learn more about this report, Download Free Sample Report
Asia Pacific Metal Powder Market Trends
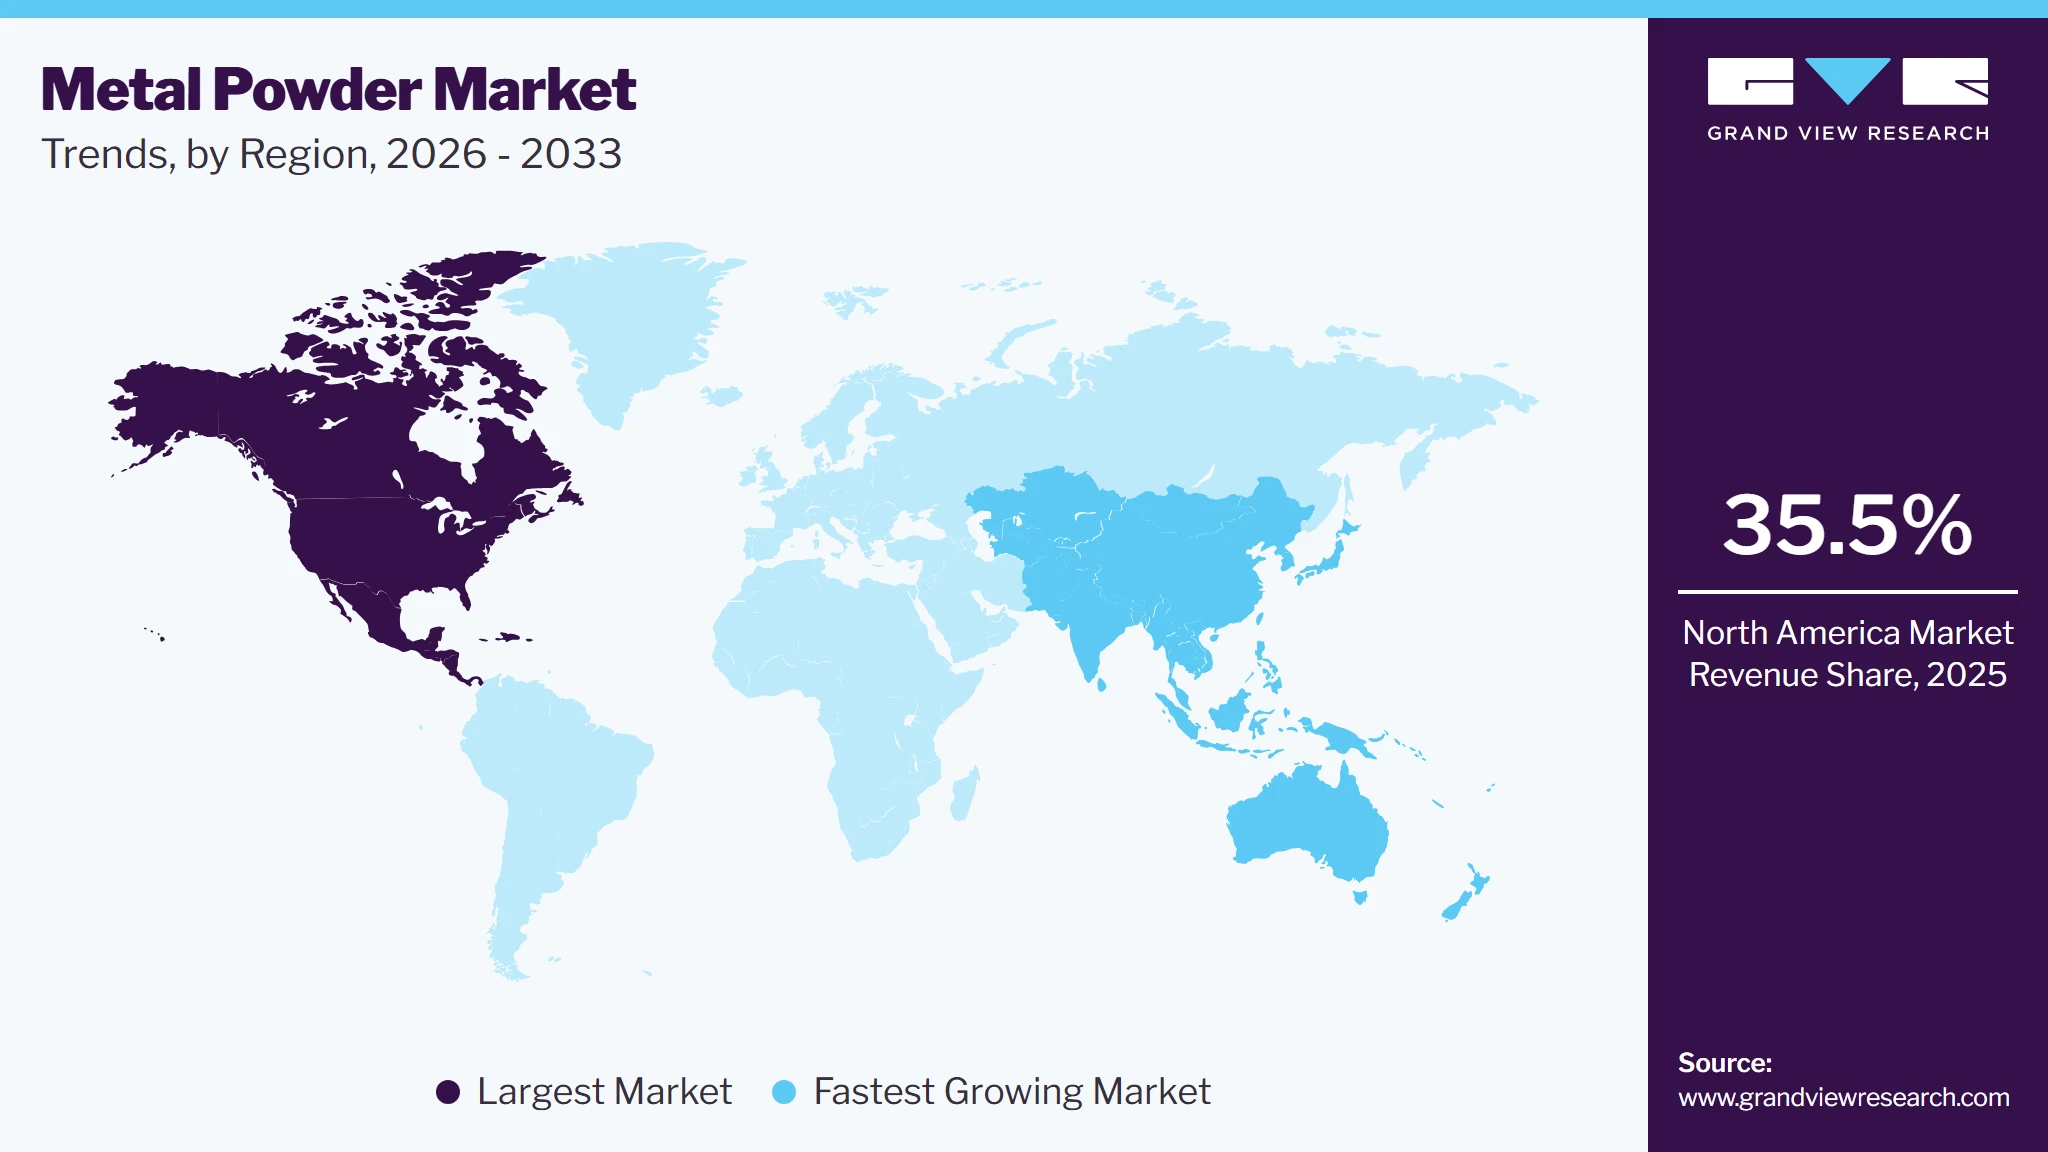
Asia Pacific dominated the metal powder market with the largest revenue share of 35.5% in 2025, amounting to 35.0%. The region saw a high demand for products, mainly in the automotive and aviation sectors, in 2023. The region's market is being driven by the presence of small and midsized component producers for press and sintered products, coupled with increasing demand for AM. The metal powder market in the China held the largest share in the Asia Pacific region in 2025.
Key Metal Powder Company Insights
Some of the key players operating in the market include GKN PLC and Sandvik AB:
-
GKN PLC is one of the leading producers and suppliers of the product, and it also produces atomized metal powders for various applications. The company annually produces around 250,000 tons of powder.
-
Sandvik AB has more than 45 years of expertise in metal powder and produces more than 400 different grades of alloys of metal powder alloys.
MolyWorks Materials Corporation, Inc. and Avimetal AM Tech Co., Ltd. are some of the emerging market participants in the industry.
-
MOLYWORKS Materials Corporation is among the emerging global manufacturers of sustainable metal powders. In 2015, the company invented “The Greyhound", a compact, alloy-agnostic, upcycling system. This system produces metal powder from metal waste streams of used powder, failed builds, old parts, and machined waste.
-
Avimetal AM Tech Co., Ltd, has advanced powder manufacturing technologies such as electrode induction gas automization, plasma automization, and vacuum induction gas automization.
Key Metal Powder Companies
The following key companies have been profiled for this study on the metal powder market.
-
MolyWorks Materials Corporation
-
Advanced Technology & Materials Co., Ltd
-
GKN PLC
-
Hoganas AB
-
POLEMA
-
Rio Tinto Metal Powders
-
Rusal
-
Sandvik AB
-
CRS Holdings Inc.
-
Liberty House Group Advanced Micro Devices
Recent Developments
-
In November 2023, 6K Additive acquired the Global Metal Powder company. This acquisition is expected to help the company in the expansion of refractory powder production and sustainable product development.
-
In October 2023, Sandvik AB announced that it is going to acquire Buffalo Tungsten, Inc. The acquisition is expected to allow Sandvik to increase its market presence in the U.S, as well as strengthen its regional capabilities within the component manufacturing value chain.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g. GKN PLC, Höganäs AB)
- Mature participants in the metal powder market primarily focus on vertically integrated manufacturing, advanced powder production technologies, and long term supply agreements with customers across automotive, aerospace, medical, electronics, industrial machinery, and additive manufacturing industries.
- These companies operate comprehensive production facilities utilizing atomization, reduction, electrolysis, and mechanical alloying processes to manufacture a broad portfolio of ferrous and non ferrous metal powders.
- Established players possess significant competitive advantages through their advanced powder production technologies, integrated manufacturing infrastructure, and large scale production capacities.
- Their ability to consistently manufacture high purity metal powders with controlled physical and chemical properties enables them to meet stringent quality requirements for aerospace, medical, automotive, and additive manufacturing applications.
- Despite their strong market positions, mature players face challenges related to high production costs, energy intensive manufacturing processes, and fluctuations in raw material prices.
- Producing high quality metal powders requires sophisticated atomization systems, furnaces, classification equipment, and advanced quality control technologies, resulting in substantial capital investment and operating expenses.
Emerging & Regional Players (e.g., MolyWorks Materials Corporation, POLEMA)
- Emerging participants in the metal powder market generally focus on specialized powder products, advanced alloy development, and high growth applications such as additive manufacturing, battery materials, medical implants, and aerospace components.
- Rather than competing directly with established manufacturers on production scale, these companies emphasize technology innovation, customized powder solutions, and flexible manufacturing capabilities.
- Emerging companies benefit from operational flexibility and the ability to establish manufacturing facilities using modern powder production technologies without extensive legacy infrastructure.
- Their operations often incorporate advanced automation, artificial intelligence based process monitoring, and precision quality control systems, enabling improved productivity and faster product development.
- Emerging participants face significant challenges related to limited production capacity, lower economies of scale, and restricted financial resources.
- Competing against established manufacturers with advanced production technologies, integrated supply chains, and extensive global distribution networks can be difficult, particularly in standardized metal powder markets.
Metal Powder Market Report Scope
Report Attribute
Details
Market definition
The market size represents the apparent consumption of metal powder-in various applications.
Market size in 2025
USD 7.7 billion
Estimated market size in 2026
USD 8.6 billion
Projected market size by 2033
USD 13.6 billion
Growth rate
CAGR of 6.8% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, volume forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Technology, materials, application, and region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S., Canada, Mexico, Germany, Italy, Spain, China, India, Japan, South Korea, Brazil
Key companies profiled
MolyWorks Materials Corporation; Advanced Technology & Materials Co., Ltd.; GKN PLC; Hoganas AB; POLEMA; Rio Tinto Metal Powders; Rusal; Sandvik AB; CRS Holdings Inc.; Liberty House Group
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Metal Powder Market Report Segmentation
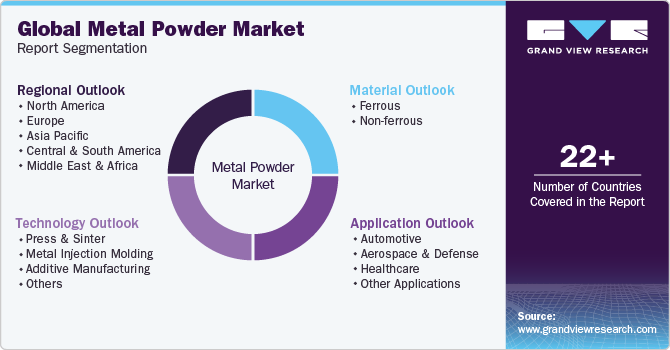
This report forecasts revenue and volume growth at the country & regional levels and provides an analysis of the industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global metal powder market report based on material, technology, application, and region:
 To learn more about this report, Download Free Sample Report
-
Material Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Ferrous
-
Non-ferrous
-
-
Technology Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Press & Sinter
-
Metal Injection Molding
-
Additive Manufacturing
-
Others
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Automotive
-
Aerospace & Defense
-
Healthcare
-
Other applications
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
-
Europe
-
Germany
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
South Korea
-
India
-
-
Central & South America
-
Brazil
-
- Middle East & Africa
-
Research Methodology
The metal powder market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each metal powder segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Technology
Revenue Capture Definition
Press & Sinter
The press and sinter segment captures revenue generated from metal powders used in conventional powder metallurgy, where powders are compacted into a desired shape and sintered to produce finished components.
Metal Injection Molding
The metal injection molding segment represents revenue generated from fine metal powders used in the production of complex, high precision components through injection molding followed by debinding and sintering.
Additive Manufacturing
The additive manufacturing segment includes revenue generated from metal powders used in three dimensional printing technologies such as selective laser melting, electron beam melting, and binder jetting. High quality metal powders enable the production of lightweight, customized, and geometrically complex components with minimal material waste.
Others
The others segment captures revenue generated from metal powders used in technologies such as thermal spraying, hot isostatic pressing, cold spraying, brazing, and advanced coating processes. These technologies support specialized manufacturing applications requiring enhanced surface properties, repair capabilities, and high performance materials.
Materials
Revenue Capture Definition
Ferrous
The ferrous segment captures revenue generated from iron based metal powders, including iron, steel, stainless steel, and alloy steel powders used across powder metallurgy, additive manufacturing, welding, friction materials, and magnetic applications.
Non-Ferrous
The non ferrous segment represents revenue generated from metal powders such as aluminum, copper, nickel, titanium, cobalt, and their alloys used in advanced manufacturing applications. These powders offer advantages including lightweight properties, corrosion resistance, high thermal conductivity, and superior mechanical performance.
Application
Revenue Capture Definition
Automotive
The automotive segment captures revenue generated from metal powders used in the production of powder metallurgy components, additive manufactured parts, friction materials, and structural components for passenger and commercial vehicles.
Aerospace & Defense
The aerospace and defense segment represents revenue generated from metal powders used to manufacture lightweight, high performance components for aircraft, spacecraft, defense equipment, and military systems.
Healthcare
The healthcare segment includes revenue generated from metal powders used in medical implants, surgical instruments, dental components, prosthetics, and customized medical devices. High purity metal powders enable the production of biocompatible, precision engineered components through additive manufacturing and metal injection molding.
Others
The others segment captures revenue generated from metal powders used in industries such as electronics, energy, industrial machinery, consumer goods, marine, and chemical processing. These applications utilize metal powders for coatings, filtration, tooling, magnetic materials, and specialized engineering components.
Estimation Model
Layer No.
Layer Name
Key Question
Description
01
Industrial Manufacturing Demand Base Layer
What forms the demand base?
Identify global demand from major metal powder consuming industries including automotive, aerospace & defense, industrial machinery, electronics, healthcare, additive manufacturing, and energy. Assess manufacturing output, powder metallurgy production, and 3D printing adoption to establish the total addressable demand for metal powders.
02
Metal Powder Application Penetration Layer
Where is metal powder utilized?
Estimate the penetration of metal powders across key applications including powder metallurgy components, additive manufacturing, metal injection molding (MIM), thermal spray coatings, welding consumables, magnetic materials, and chemical applications. Analyze the adoption of iron, steel, aluminum, copper, nickel, titanium, cobalt, and other specialty metal powders across end use industries and regions.
03
Metal Powder Consumption Intensity Layer
How much metal powder is consumed?
Analyze metal powder consumption intensity based on automotive component production, industrial manufacturing output, aerospace production, additive manufacturing capacity, and medical device manufacturing. Evaluate material usage according to powder characteristics such as particle size, purity, morphology, and alloy composition. Consumption intensity varies according to manufacturing technology, component complexity, and application specific performance requirements.
04
Revenue Layer
How is market revenue generated?
Market revenue is quantified through the sale of ferrous and non ferrous metal powders, including iron, steel, aluminum, copper, nickel, titanium, cobalt, and specialty alloy powders. Revenue generation is driven by demand from powder metallurgy, additive manufacturing, metal injection molding, thermal spraying, electronics, healthcare, and industrial manufacturing sectors. Market value is influenced by raw material prices, powder production technology, alloy composition, product quality, and regional supply demand dynamics.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
Detailed regional analysis of the metal powder market across North America, Europe, Asia Pacific, Latin America, and Middle East & Africa. Included evaluation of powder production capacities, additive manufacturing adoption, powder metallurgy growth, automotive manufacturing, aerospace investments, medical device production, industrial machinery demand, and government initiatives supporting advanced manufacturing.
Identified key manufacturing hubs, emerging demand centers, and high growth industrial markets. Enabled strategic expansion planning based on industrialization, additive manufacturing investments, and advanced manufacturing initiatives. Supported regional demand forecasting and supply chain optimization.
Competitive Benchmarking
Benchmarking analysis of leading metal powder manufacturers based on product portfolio, powder quality, particle size distribution, manufacturing technology, geographic footprint, research and development investments, sustainability initiatives, distribution network, and strategic partnerships. Included comparison of global producers supplying powder metallurgy, additive manufacturing, aerospace, automotive, and medical industries.
Assisted in evaluating competitive positioning, technological strengths, and market leadership opportunities. Supported competitive intelligence, partnership assessments, acquisition evaluations, and strategic differentiation initiatives.
Opportunity Assessment
Identification of high growth opportunities across metal additive manufacturing, electric vehicle components, aerospace parts, medical implants, industrial tooling, energy storage technologies, precision engineering, and lightweight component manufacturing.
Enabled prioritization of high return growth segments and emerging regional opportunities. Supported long term investment planning, product innovation, and strategic business development initiatives.
Frequently Asked Questions About This Report
The metal powder market size was estimated at USD 7.7 billion in 2025 and is expected to reach USD 8.6 billion in 2026.
The metal powder market is expected to grow at a compound annual growth rate of 6.8% from 2026 to 2033 to reach USD 13.6 billion by 2033.
Based on technology, press & sinter accounted for largest revenue share of 45.7% in 2025.
The key factors that are driving the metal powder market include increasing penetration of additive manufacturing in the healthcare and aerospace & defense sector and the growth of the automotive sector.
Asia Pacific dominated the market with revenue share of 35.5% in 2025.
China dominated the Asia Pacific market with revenue share of 40.6% in 2025.
Ferrous accounted for largest revenue share of 68.8% in 2025.
Healthcare is anticipated to register the fastest CAGR over the forecast period.
The key players operating in the metal powder market are MolyWorks Materials Corporation; Advanced Technology & Materials Co., Ltd.; GKN PLC; Hoganas AB; POLEMA; Rio Tinto Metal Powders; Rusal; Sandvik AB; CRS Holdings Inc.; Liberty House Group
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


