
- Home
- »
- Plastics, Polymers & Resins
- »
-
Microplastic Recycling Market Size Report, 2026-2033GVR Report cover
![Microplastic Recycling Market (2026 - 2033)Report]()
Microplastic Recycling Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Primary, Secondary), By Application (Packaging, Agriculture, Consumer Goods, Textile), By Region, And Segment Forecasts
Market Size, 2025
$319.8MMarket Estimate, 2026
$341.0MMarket Forecast, 2033
$514.9MCAGR, 2026–2033
6.1%Microplastic Recycling Market Summary
The global microplastic recycling market size was valued at USD 319.8 million in 2025 and is projected to grow from USD 341.0 million in 2026 to USD 514.9 million by 2033, at a CAGR of 6.1% from 2026 to 2033. Europe dominated the microplastic recycling market with the largest revenue share of 43.4% in 2025. The market is expected to grow in the coming years owing to increasing government regulations, environmental concerns, technological advancements, consumer awareness, and the increasing use of microplastics in different industries.

Key Market Trends & Insights
- By product: Secondary segment held the largest market share of 76.3% in 2025.
- By end use: Packaging segment held the largest market share of 62.0% in 2025.
Regional Highlights
- Largest regional market: Europe (43.4% revenue share, 2025)
- By country: Germany held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 319.8 Million
- Estimated market size in 2026: USD 341.0 Million
- Projected market size by 2033: USD 514.9 Million
- CAGR (2026-2033): 6.1%
Three ways to get this report
Buy it, customize it, or ask a question.Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Significant research and development in the U.S. regarding microplastic recycling is expected to be a major market driver in the country. Manufacturers are engaged in developing new technologies and processes for the efficient and cost-effective recycling of microplastics. Manufacturers in the country have set sustainability goals, which have increased demand for recycled plastics, including microplastics.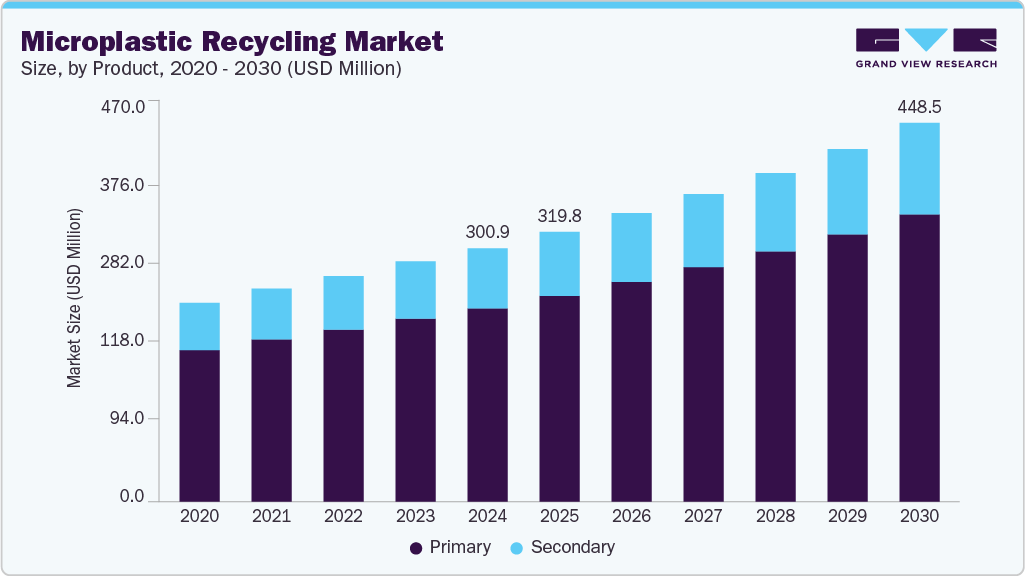
Different governments across the globe are implementing regulations to reduce plastic waste, which in turn is expected to drive the demand for microplastic recycling. In addition, increasing consumer awareness regarding the environmental impact of their actions and are seeking out sustainable products and services. This has led to increased demand for products made from recycled materials, including microplastics.
Microplastic recycling generates revenue for businesses and reduces production costs in the recycling industry. It also reduces the amount of plastic waste that ends up in landfills or oceans, thereby minimizing the impact on the environment. Furthermore, increasing demand from end-use industries, including automotive and transportation, packaging, consumer goods, textiles, and others, is creating lucrative opportunities for microplastic recycling.
Market Dynamics
The microplastic recycling market is shaped by concentrated demand from packaging, textiles, consumer goods, and automotive applications, with secondary product recovery forming the dominant revenue base. The commercial structure is still niche and technology-intensive, since value is captured through filtration, separation, chemical recycling, and closed-loop reprocessing rather than bulk commodity output. Europe remains the leading demand center, while Asia Pacific is the fastest-growing region, reflecting regulatory intensity, industrial depth, and rising waste capture requirements. This creates a market where scale depends on process efficiency, compliance alignment, and access to end-use channels.
The strongest driver is the tightening regulatory push to reduce microplastic leakage from wastewater, textiles, and consumer waste streams. Policies such as the EU Plastics Strategy, extended producer responsibility frameworks, the U.S. Microbead-Free Waters Act, and state-level plastic restrictions are forcing brands, municipalities, and processors to invest in capture and recycling infrastructure. This is particularly relevant for polyolefin-rich packaging waste and microfiber-intensive textile streams, where leakage reduction has become a compliance issue rather than a voluntary sustainability initiative. As a result, demand is shifting from pilot projects to operational systems with measurable recovery performance.
A second layer of demand support is the corporate sustainability agenda, which is expanding the commercial use case for recycled microplastic outputs. Large packaging, consumer goods, and mobility companies are under pressure to increase recycled content and document circularity outcomes across the value chain. That is strengthening demand for technologies that can recover secondary microplastics at scale, improve material purity, and support traceable recycled feedstock. In this market, buyers are not only seeking waste reduction, they are also seeking lower-carbon material pathways and reputational advantage.
The principal restraint is the difficult economics of capturing dispersed microplastics from mixed waste and wastewater streams. Microplastics are low concentration, highly fragmented, and often contaminated, which raises sorting, filtration, and reprocessing costs. That limits margin visibility and makes large-scale deployment dependent on subsidies, regulation, or long-term offtake contracts. The market structure, therefore, remains capital-intensive and operationally selective, with profitability tied to specialized equipment, high recovery rates, and reliable downstream demand. This constraint is especially strong in regions where collection infrastructure and enforcement remain uneven.
The clearest opportunity lies in integrated microfiber and microbead capture systems for industrial and municipal wastewater networks. As textile, laundry, and consumer-product regulations tighten, suppliers that combine filtration hardware, service contracts, and downstream recycling can secure recurring revenue. North America and Europe already show the regulatory and infrastructure base for adoption, while the Asia Pacific offers the largest future expansion platform. The business case improves when recovery is embedded at source, rather than treated as a post-disposal remediation step.
Market Concentration & Characteristics
The microplastic recycling market's growth is medium and accelerating. The market is characterized by a moderate degree of innovation, driven by a combination of health-conscious consumer behavior, technological advancements in production, and a shift towards ethical and sustainable practices. These drivers are reshaping the industry, developing new products and production methods that align with evolving consumer preferences and global sustainability goals.
The microplastic recycling market is experiencing moderate mergers and acquisitions (M&A) activity, indicating a strategic consolidation trend among key industry players, driven by market expansion, product portfolio diversification, and technological advancements. These strategic mergers and acquisitions are reshaping the microplastic recycling market, enabling companies to enhance their capabilities, expand their market reach, and meet the evolving demands of consumers.

The end-use concentration in the microplastics recycling market is notably high, with a significant share of demand originating from a few dominant sectors such as packaging, automotive & transportation, consumer goods, and textiles. These industries increasingly integrate recycled microplastics to meet environmental regulations and corporate sustainability goals. For instance, automotive manufacturers are utilizing recycled polymers for interior components to reduce vehicle weight and improve fuel efficiency, while the textile sector is adopting recycled microfibers in garments to respond to growing consumer demand for eco-friendly fashion. This concentration underscores a targeted yet expanding application scope across industries with high plastic consumption.
Analyst Perspective
The microplastic recycling market is moving from a fragmented compliance-led phase toward a more structured technology and infrastructure-led phase. Over the next years, demand will be shaped by tighter leakage-control regulation, stronger recycled-content expectations, and wider adoption of filtration and separation systems across packaging, textiles, wastewater, and mobility-related applications. The market will favor players that combine capture efficiency, process integration, regional compliance knowledge, and credible downstream channels. Value creation will increasingly depend on closed-loop recovery, traceable recycled outputs, and partnerships with municipalities, OEMs, and industrial users. At the same time, profitability will remain constrained by dispersed feedstock, contamination, high operating costs, and uneven regulatory execution across regions. Leaders are likely to be defined by intellectual property, application-specific engineering, and the ability to convert environmental compliance into recurring commercial demand.
Product Insights
Based on the product, the secondary segment led the market with the largest revenue share of 76.3% in 2025s. The secondary product segment led the market and accounted for more than 76.0% of the global revenue share in 2024. Secondary microplastics recycling refers to the process of recovering microplastics that have already been used and discarded, such as plastic bottles, packaging, and other waste. Recycling secondary microplastics can help minimize the amount of plastic waste in landfills, oceans, and other natural environments. In addition, secondary microplastics recycling can be cost-effective, as recycled materials are less expensive than virgin materials.
Microbeads are easily available from the personal care industry, a significant feedstock for the microplastic recycling market. Owing to technological advancements in recycling, microbeads can be recovered from waste streams and transformed into high-quality recycled materials. Also, using recycled microbeads can give manufacturers a competitive edge in meeting consumer demand for sustainable products.
End-Use Insights
Based on the product, the secondary segment led the market with the largest revenue share of 76.3% in 2025. The packaging industry is gradually shifting towards sustainable and eco-friendly packaging solutions owing to government regulations and growing consumer awareness. The use of recycled plastics, including microplastics, is seen as an effective way to reduce the environmental impact of packaging.

The automotive and transportation industry is expected to register the fastest CAGR over the forecast period 2025-2030. It is increasingly using recycled plastics and exploring the use of microplastics in various applications.
The incremental use of microplastics is driven by environmental concerns and a desire for lighter, more fuel-efficient vehicles. This includes using recycled plastics for interior components, seat covers, and even innovative materials like plastic roads. While microplastics are a concern due to potential environmental impact, they are also being investigated for their potential as lightweight materials in specific applications, particularly in interior components.
Regional Insights
North America held a considerable share in 2024. This is attributed to the region’s mature recycling infrastructure and regulatory environment, particularly in the U.S. and Canada. The presence of major recycling firms, coupled with strong government policies like the U.S. Microbead-Free Waters Act (2015) and increasing state-level bans on single-use plastics, is fostering steady growth. Moreover, North America is a hub for technological innovation, with advancements in filtration systems, chemical recycling, and microplastic capture from wastewater contributing to market sustainability. Increasing corporate sustainability initiatives and investments in circular economy models further reinforce North America’s position as a global leader in microplastic recycling.
U.S. Microplastic Recycling Market Trends
The U.S. microplastic recycling market is experiencing significant growth, driven by environmental concerns, government regulations, and technological advancements. The country has demonstrated considerable progress in developing and deploying innovative recycling solutions, including chemical recycling, pyrolysis, and advanced filtration systems to capture microplastics from wastewater and industrial discharge.
Europe Microplastic Recycling Market Trends
Europe dominated the microplastic recycling market with the largest revenue share of 43.4% in 2025. Europe continues to lead the global market due to its early adoption of environmental regulations, such as the EU Plastics Strategy and extended producer responsibility (EPR) policies. Countries like Germany and the UK have invested heavily in recycling infrastructure and innovation, making Europe a benchmark for sustainable practices. Europe’s focus on reducing microplastic leakage through green manufacturing and textile regulations continues to drive high-quality recycling outcomes.
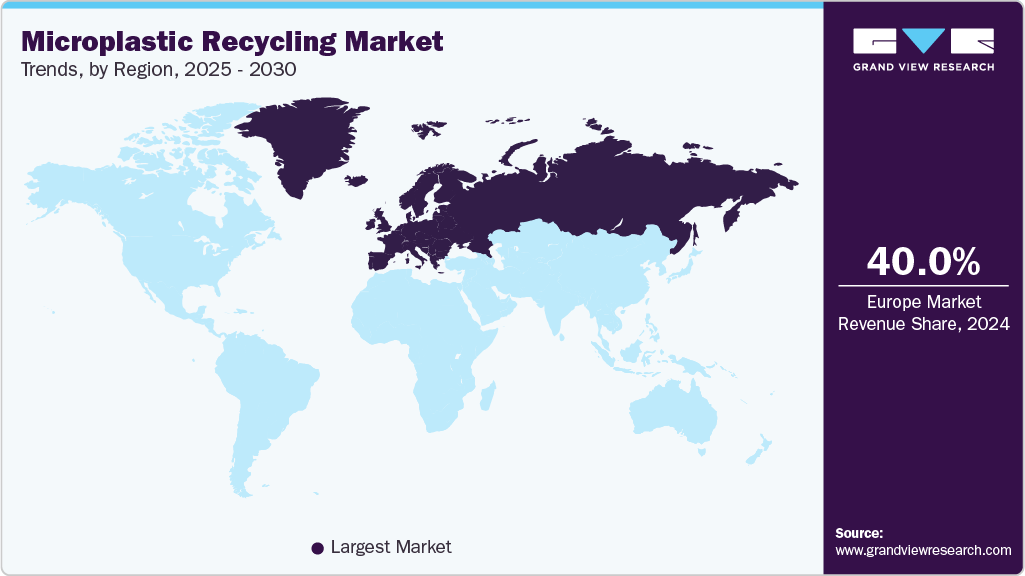
The microplastic recycling market in the Germany held the largest share in the Europe region in 2025, driven by its well-established recycling infrastructure, strong regulatory framework, and leadership in environmental innovation.
Asia Pacific Microplastic Recycling Market Trends
The Asia Pacific microplastic recycling market is anticipated to grow at a CAGR of 10.3% during the forecast period. This growth is fueled by rising plastic consumption, expanding industrial activity, and increasing awareness of environmental degradation caused by microplastic pollution. Several countries in the Asia-Pacific region are making strategic investments in recycling infrastructure. Microplastic recycling is gaining traction in various sectors, including textiles, packaging, and wastewater treatment (microfiber and microbead filtration).
China’s microplastic recycling industry is experiencing rapid growth, driven by massive plastic consumption, a large-scale manufacturing base, and a growing emphasis on environmental sustainability. Increasing demand in the packaging and textile industry is also fueling the rapid popularity among consumers for the recycled market. Stringent government measures and policies have encouraged the development of advanced recycling infrastructure capable of processing various microplastic forms, including synthetic fibers from textiles, plastic pellets, and micro-residues from industrial processes.
Key Microplastic Recycling Company Insights
Some key microplastic recycling companies include PlanetCare, ECOFARIO, Carbios, PureCycle Technologies, Ioniqa, Ocean Diagnostics, Calyxia, and Polygonesystems. These organizations have been strategically implementing various initiatives, such as technology innovation in microplastic filtration and separation, advancements in chemical recycling, environmental monitoring solutions, and the development of closed-loop systems.
-
PlanetCare is a pioneer in microplastic filtration technology. It specifically targets microfibers released from washing machines, one of the largest sources of secondary microplastics. The company has developed patented microfiber filters for household and industrial laundry applications.
-
ECOFARIO is a technology-driven company specializing in removing microplastics from wastewater through its high-performance separation technology, which uses vortex-based water treatment systems.
Key Microplastic Recycling Companies:
The following key companies have been profiled for this study on the microplastic recycling market.
-
PlanetCare
-
ECOFARIO GmbH
-
Carbios
-
PureCycle Technologies, Inc.
-
Ioniqa Technologies B.V.
-
Calyxia
-
Ocean Diagnostics, Inc.
-
OceanWorks International
-
Matter.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (PlanetCare, ECOFARIO GmbH, Carbios, PureCycle Technologies, Inc., Ioniqa Technologies B.V.)
- Focus on filtration, separation, and chemical recycling systems with clear industrial use cases.
- Build partnerships with waste handlers, manufacturers, and infrastructure operators.
- Expand through technology licensing, pilot conversions, and process commercialization.
- Stronger technical depth and more visible market positioning.
- Better ability to integrate upstream capture with downstream recycling.
- Higher credibility for compliance-linked and scale-oriented deployments.
- Higher capital intensity and longer commercialization cycles.
- Exposure to regulatory dependency and project-based revenue timing.
- Ongoing pressure to prove unit economics at scale.
Emerging Players (Calyxia, Ocean Diagnostics, Inc., OceanWorks International, Matter)
- Target narrow solution areas such as environmental monitoring, marine recovery, and specialized material innovation.
- Use partnerships, demonstration projects, and niche applications to build traction.
- Rely on flexibility and speed rather than broad infrastructure scale.
- Faster innovation cycles and sharper specialization.
- Ability to address underserved technical gaps in the value chain.
- Lower organizational complexity and quicker adaptation to customer needs.
- Limited installed base and weaker market visibility.
- Lower bargaining power in large procurement and partnership discussions.
- Greater dependence on funding, validation, and pilot-to-commercial conversion.
Recent Developments
-
In August 2024, Carbios and SASA signed a Letter of Intent for a future licensing arrangement, with SASA potentially acquiring a license for Carbios' PET biorecycling technology.
-
In April 2023, Biffa announced the acquisition of North Yorkshire based Esterpet Ltd, a recycler of Polyethylene Terephthalate (PET) plastic. Esterpet converts 25,000 tons of plastic flakes each year, generated from recycled bottles, into high-purity plastic pellets.
Microplastic Recycling Market Report Scope
Report Attribute
Details
Market size in 2025
USD 319.8 million
Estimated market size in 2026
USD 341.0 million
Projected market size by 2033
USD 514.9 million
Growth rate
CAGR of 6.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S., Canada, Mexico, Germany, UK, France, China, Japan, India, Brazil
Key companies profiled
Carbios; PureCycle Technologies, Inc.; Ioniqa Technologies B.V.; Calyxia; PlanetCare; ECOFARIO GmbH; Ocean Diagnostics, Inc.; OceanWorks International; Matter
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Microplastic Recycling Market Report Segmentation
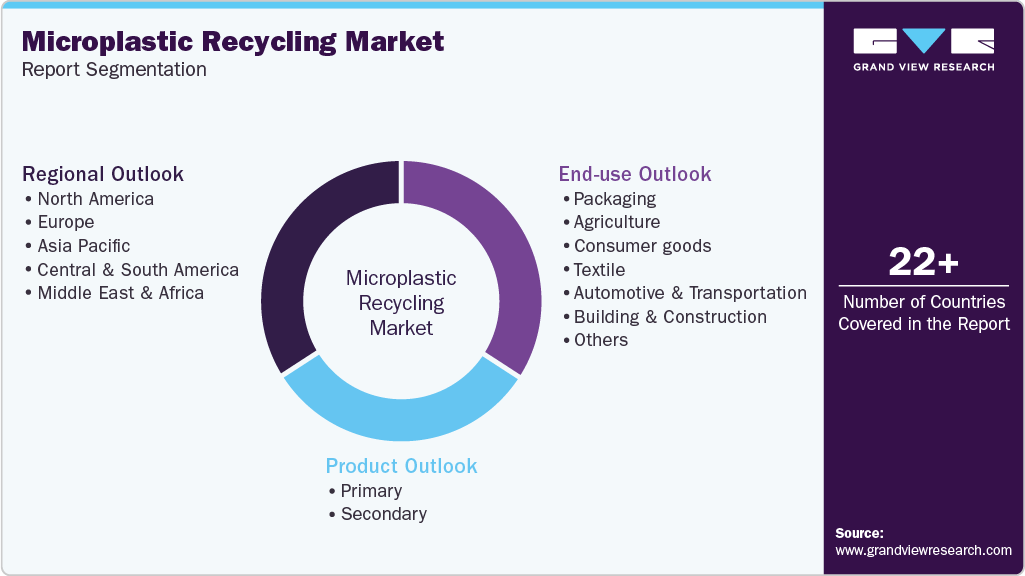
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the microplastics recycling industry report based on product, end use, and region.
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Primary
-
Secondary
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Packaging
-
Agriculture
-
Consumer goods
-
Textile
-
Automotive & Transportation
-
Building & Construction
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
-
Central & South America
-
Brazil
-
-
Middle East & Africa
-
Research Methodology
The microplastic recycling market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each microplastic recycling segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Primary
Revenue is captured from source-side recovery systems and first-pass microplastic capture solutions installed before particles enter broader waste streams. This includes equipment sales, system integration, maintenance, and service contracts tied to industrial discharge, laundry filtration, and process interception.
Secondary
Revenue is generated from collecting, separating, and reprocessing already dispersed or discarded microplastics into reusable output streams. Monetization comes from recycling fees, output sales, technology licensing, and downstream material recovery.
Segment - End Use
Revenue capture definition
Packaging
Revenue is captured from recovery of packaging-related microplastic waste and conversion into recycled feedstock for converters, brand owners, and packaging compounders seeking compliance-grade recycled material.
Agriculture
Revenue is generated from recycling microplastic contamination linked to mulch films, irrigation-related plastics, and agricultural input waste. Commercial value comes from recovery services, material resale, and waste management contracts.
Consumer Goods
Revenue is captured from household and personal product waste streams, including microplastics generated through daily use and disposal. Monetization is driven by recycling contracts, brand sustainability programs, and recycled input sales.
Textile
Revenue comes from microfiber capture, textile discharge treatment, and reprocessed fiber outputs. This segment monetizes through filtration systems, laundry partnerships, textile mill services, and recycled material sales.
Automotive & transportation
Revenue is captured through recycled plastic inputs used in vehicle interiors, lightweight components, and transportation-related material recovery programs. Income also comes from OEM partnerships and circular material supply contracts.
Building & Construction
Revenue is generated from recovery of plastic residues linked to construction materials, insulation, flooring, sealants, and demolition waste streams. Monetization depends on recovery contracts and reclaimed material sales.
Others
This residual segment captures revenue from wastewater treatment, environmental monitoring, industrial filtration, marine cleanup, and related service-based applications that do not fall under the core end-use categories.
Estimation Model
Layer Name
Key Question
Description
Demand Mapping Layer
Where is demand generated?
End-use demand is first mapped across packaging, textile, automotive, and consumer channels to establish where microplastic recovery generates commercial value and repeat purchase behavior.
Supply Lens Layer
Can supply meet demand?
Technology deployment is then layered in through capture, separation, and recycling capacity, because revenue depends on how effectively dispersed microplastics are converted into usable output.
Regional Weighting Layer
Which regions drive growth?
Regional weighting reflects regulatory intensity, infrastructure maturity, and industrial concentration, with Europe and North America weighted for current scale and Asia Pacific for acceleration.
Validation Layer
Are assumptions commercially valid?
Final validation triangulates company activity, policy direction, and end-use adoption to avoid overstating pilot-stage technologies that have not yet reached commercial breadth.
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Add country-level split for core markets
Added country-level revenue framing for the U.S., Germany, China, India, and Brazil, aligned with regulatory intensity, industrial concentration, and microplastic capture adoption patterns across the report scope.
Improves geographic precision and supports market prioritization for commercial planning.
Expand competitive benchmarking
Added a benchmarking view covering capture technology, recycling integration, and service model positioning across leading participants in the market.
Helps identify relative strategic positioning and technology gaps.
Add end-use attractiveness analysis
Added a compact end-use assessment across packaging, textile, automotive, and wastewater-related applications, based on demand concentration and commercial scalability.
Clarifies where near-term monetization is strongest.
Frequently Asked Questions About This Report
The microplastic recycling market is anticipated to grow at a CAGR of 6.1% from 2026 to 2033 to reach USD 514.9 million by 2033, owing to increasing government regulations, environmental concerns, technological advancements, and consumer awareness.
The key market players present across the microplastic recycling market include Carbios, Purecycle Technologies, Ioniqa, Calyxia, Polygonesystems, PlanetCare, ECOFARIO, Ocean Diagnostics, Oceanworks, and Matter
Key factor driving microplastic recycling market include rising plastic pollution across the oceans hampering aquatic lifestyle.
Based on end use, the packaging segment led the market with the largest revenue share of 62.0% in 2025.
Europe dominated the microplastic recycling market with the largest revenue share of 43.4% in 2025.
The microplastic recycling market is shaped by concentrated demand from packaging, textiles, consumer goods, and automotive applications, with secondary product recovery forming the dominant revenue base.
The global microplastic recycling market size was estimated at USD 319.8 million in 2025 and is projected to grow from USD 341.0 million in 2026.
Based on the product, the secondary segment led the market with the largest revenue share of 76.3% in 2025.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst


Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


