
- Home
- »
- Plastics, Polymers & Resins
- »
-
Modified Epoxy Resin Market Size & Share Report, 2033GVR Report cover

Modified Epoxy Resin Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product Type (Solvent Based, Water Based), By Application (Building & Construction, Automotive, Aerospace, Marine), By Region (North America, Europe, Asia Pacific), And Segment Forecasts
Market Size, 2025
$24.0BMarket Estimate, 2026
$25.3BMarket Forecast, 2033
$35.5BCAGR, 2026–2033
5.0%Modified Epoxy Resin Market Summary
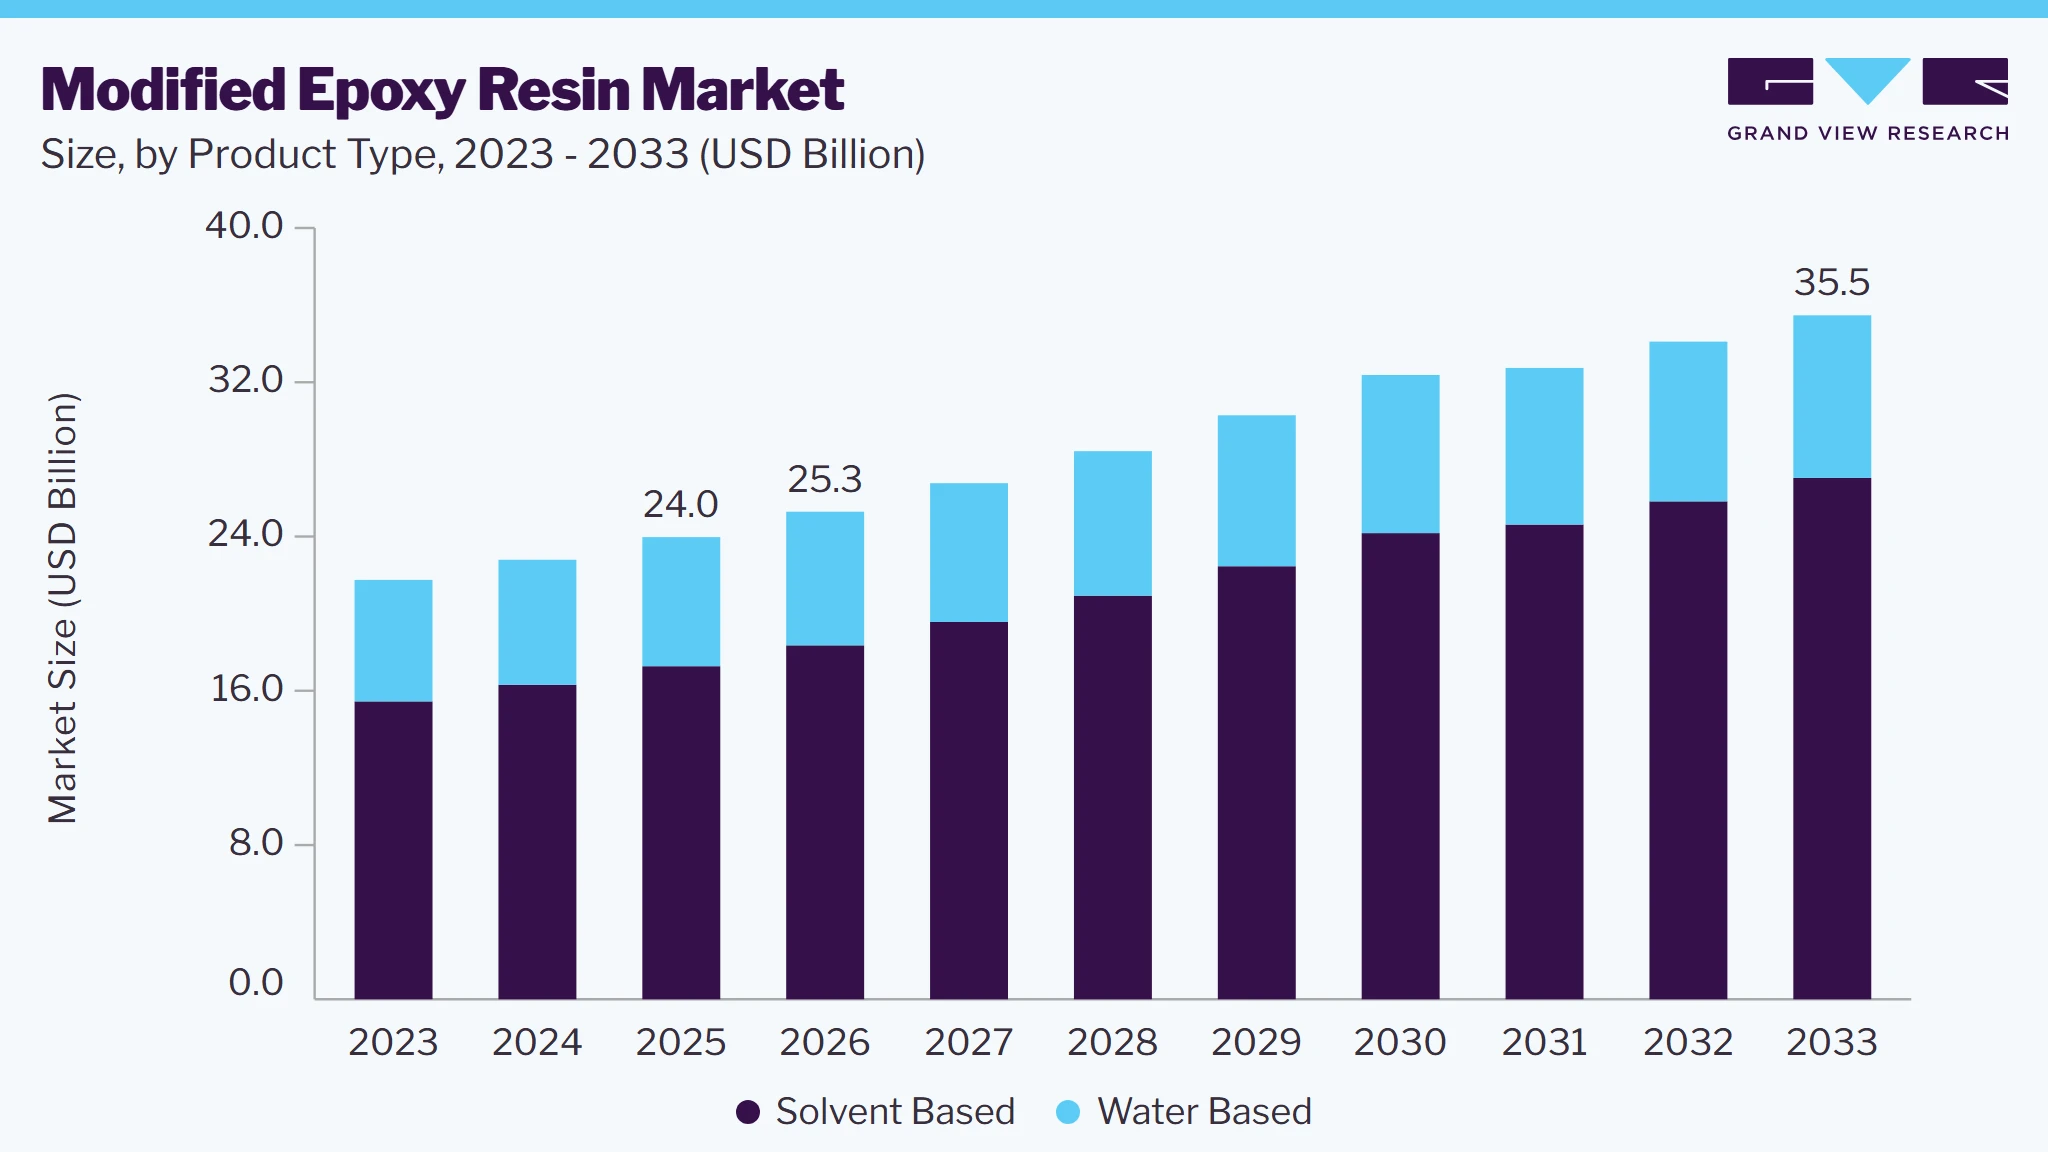
The global modified epoxy resin market size was valued at USD 24.0 billion in 2025 and is projected to grow from USD 25.3 billion in 2026 to USD 35.5 billion by 2033, at a CAGR of 5.0% from 2026 to 2033. Asia Pacific dominated the market, accounting for the largest global share of 42.6% in 2025. The growing demand for high-performance coatings across construction, infrastructure, automotive, marine, and industrial applications is accelerating the adoption of modified epoxy resins due to their excellent durability, corrosion resistance, chemical resistance, strong adhesion, and weather protection.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product type: Solvent-based modified epoxy resin segment held the largest share of 72.1% in 2025.
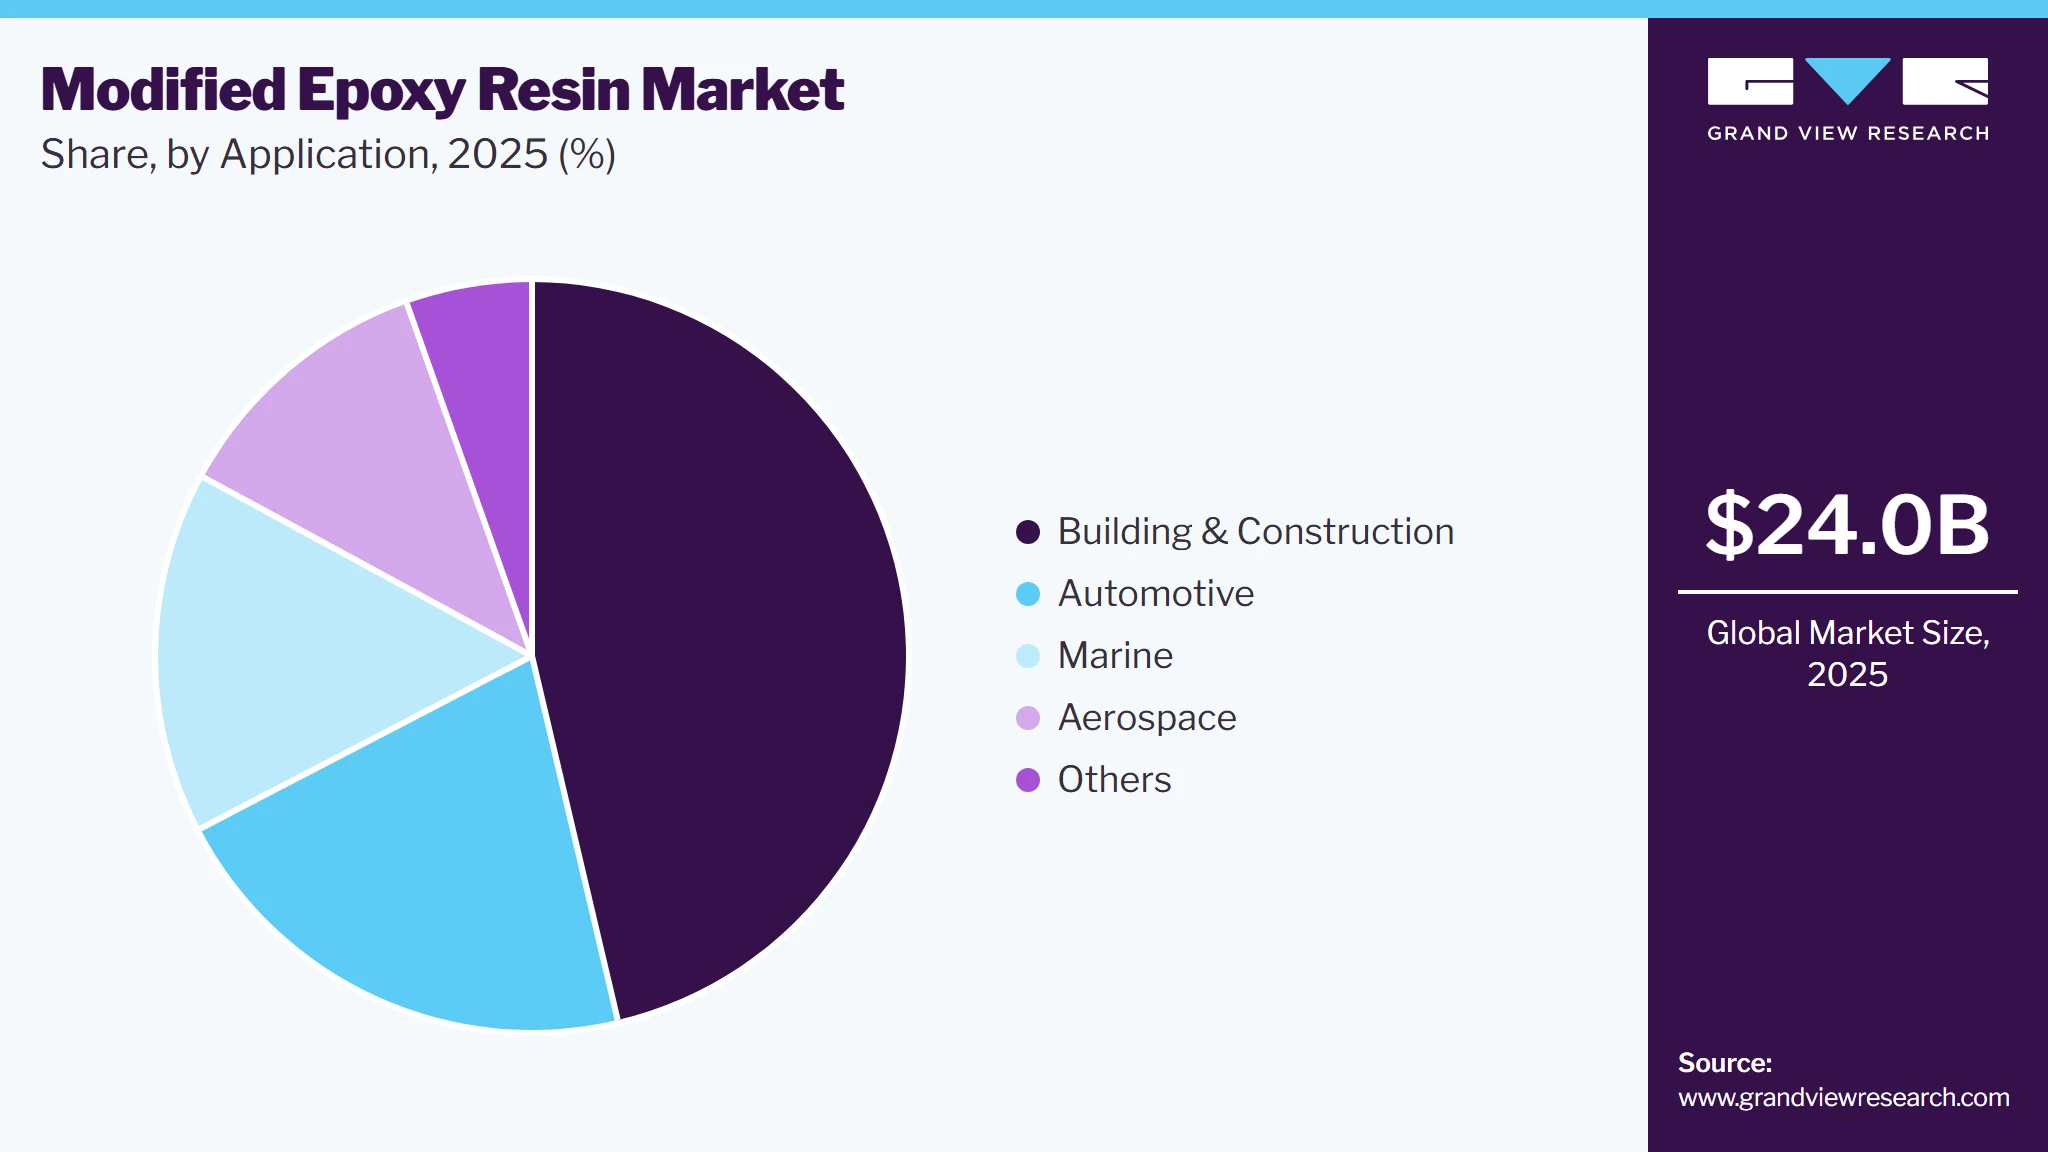
- By application: Building & construction segment held the largest revenue share of 46.3% in 2025.
Regional Highlights
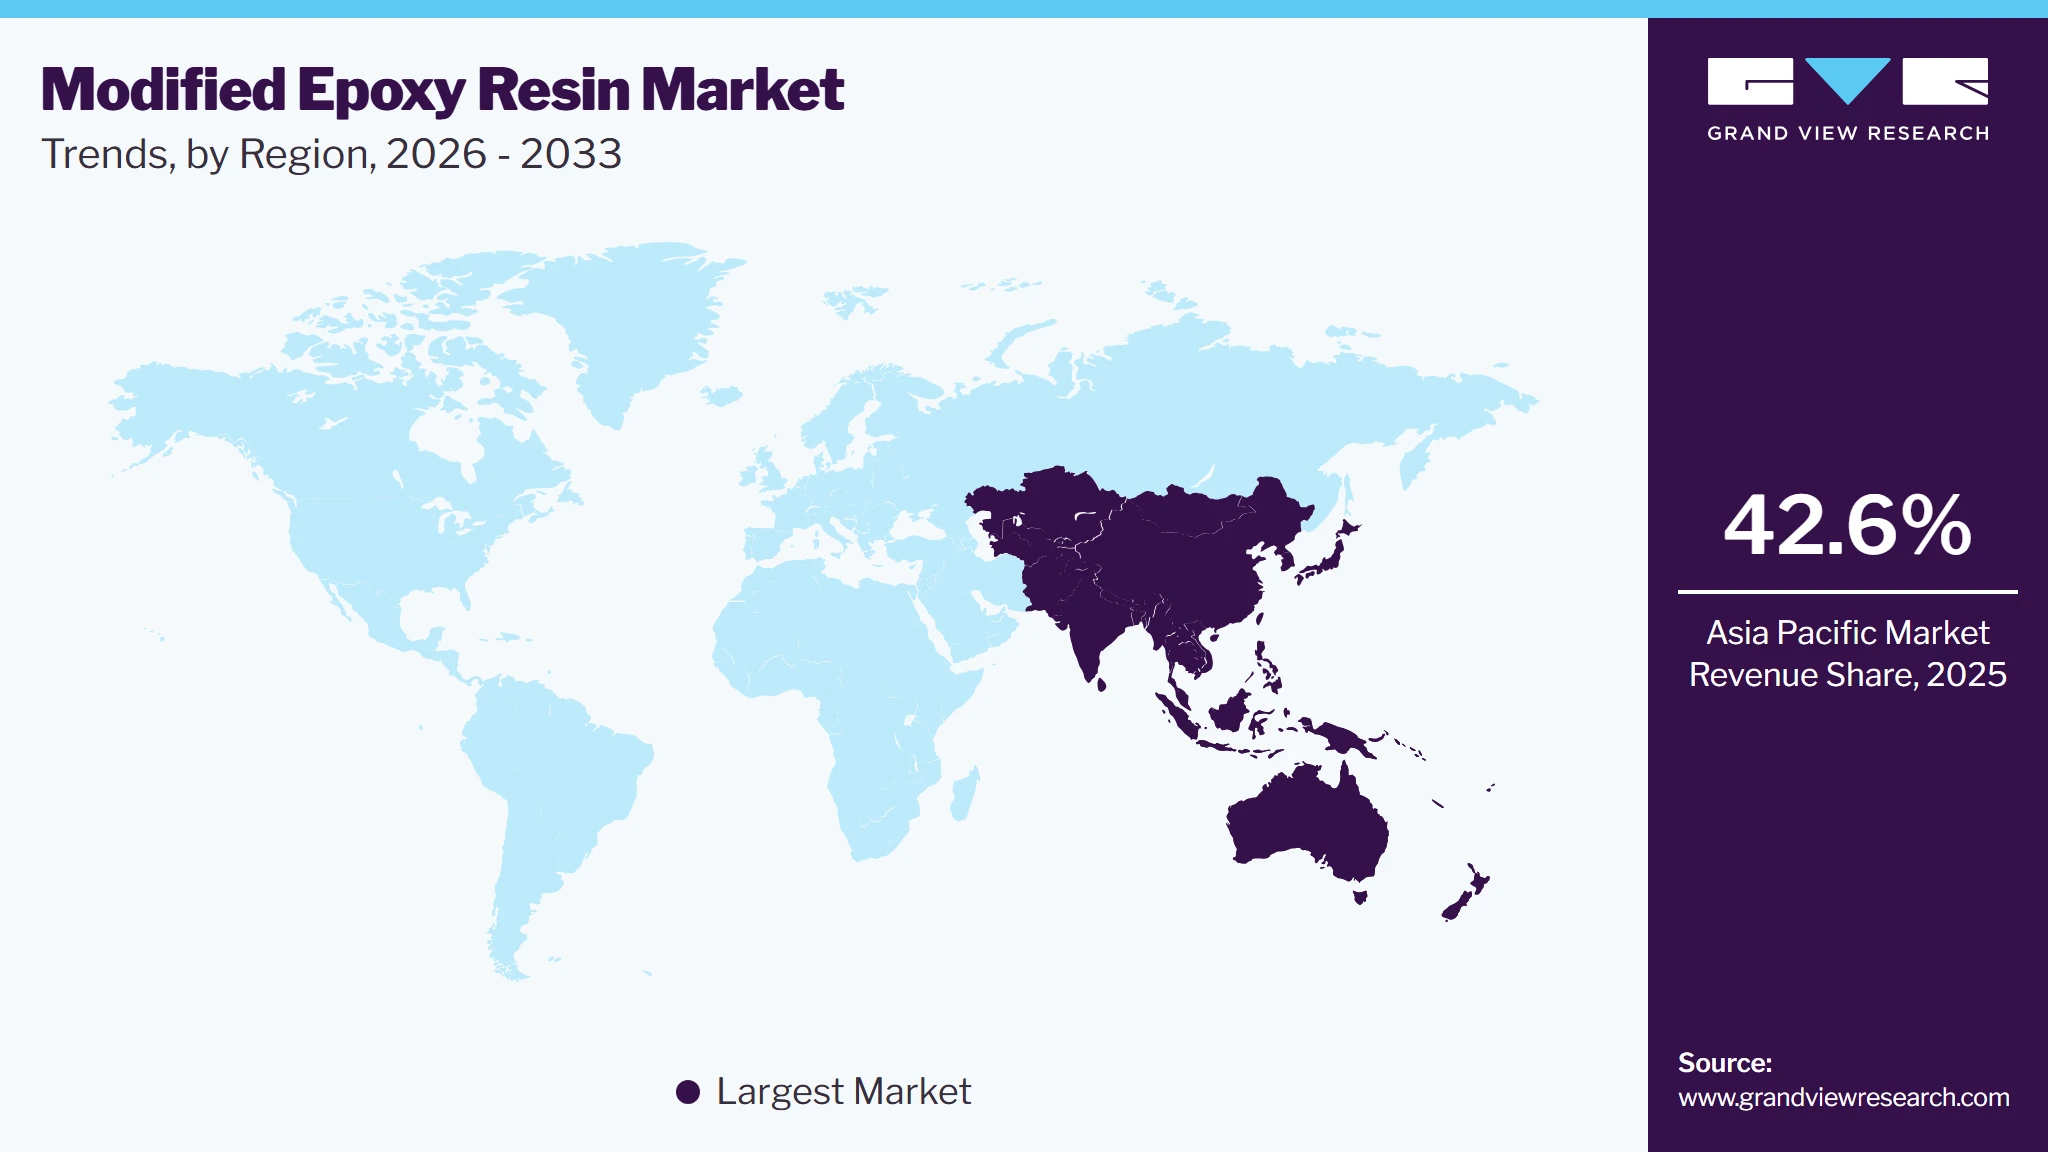
- Largest regional market: Asia Pacific (42.6% revenue share, 2025)
- By country: The China held the largest share of Asia Pacific in 2025.
Market Size & Forecast
- Market size in 2025: USD 24.0 Billion
- Estimated market size in 2026: USD 25.3 Billion
- Projected market size by 2033: USD 35.5 Billion
- CAGR (2026-2033): 5.0%
Prism AI by Grand View Research Free to tryAsk a question about the modified epoxy resin marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →Rising focus on bio-based and low-VOC formulations, coupled with advancements in nanotechnology for enhanced thermal and mechanical performance, is further supporting market growth by enabling sustainable, high-performance solutions that meet evolving regulatory and end-use industry requirements. The modified epoxy resin industry is witnessing a significant shift toward sustainable and high-performance formulations, driven by stringent environmental regulations and industry demand for enhanced material properties. Manufacturers are increasingly focusing on bio-based and low-VOC (volatile organic compound) epoxy resins to comply with sustainability targets while maintaining strength, adhesion, and chemical resistance.
 To learn more about this report, Download Free Sample Report
Advancements in nanotechnology are enabling the development of epoxy resins with superior thermal and mechanical properties, which are particularly gaining traction in aerospace, automotive, and high-performance coatings applications. This shift underscores a broader industry movement toward innovation-driven sustainability and regulatory compliance.
Market Dynamics
The modified epoxy resin market is shaped by steady demand from high-performance coatings, adhesives, and composite systems used in infrastructure, transport, and industrial maintenance. Revenue is concentrated in the Asia Pacific, where construction and manufacturing activity remains broad, while North America is expanding on the back of advanced materials demand. The commercial structure remains supplier-led, with resin makers selling into formulators, coating producers, and OEM-qualified channels. Product preference still leans toward solvent-based systems, but water-based grades are gaining share as buyers prioritize low-VOC compliance and application performance.
The strongest driver is the use of modified epoxy resins in protective coatings for buildings, bridges, pipelines, offshore assets, and industrial equipment. These formulations are valued for adhesion, corrosion resistance, moisture tolerance, and long service life, which makes them essential in harsh operating environments. As infrastructure owners extend maintenance cycles and specify longer-lasting coatings, resin demand rises across new build and refurbishment projects.
A second layer of demand comes from performance upgrades in electrical, automotive, and composite applications. Buyers increasingly require tougher systems that support lightweighting, thermal stability, and structural integrity without sacrificing processability. This is pushing formulators toward modified epoxy platforms that can be tailored for end-use specific cure behavior, durability, and environmental compliance. The shift is especially visible in high-value industrial and transportation specifications.
A major restraint is the volatility of key feedstocks such as bisphenol A and epichlorohydrin, which directly affects production economics and selling prices. Supply disruptions, crude-linked price movement, and regulatory scrutiny on hazardous inputs create margin pressure across the value chain. At the same time, the move toward BPA-free and lower-emission formulations forces manufacturers to invest in reformulation, testing, and customer qualification, which slows commercialization and raises technical cost for smaller producers.
Opportunity: Water-Based Upgrade Cycle
The clearest opportunity lies in water-based modified epoxy resins for regulated coating environments. Low-VOC requirements in construction and industrial repaint applications are accelerating substitution away from solvent-based systems, especially where odor control, emissions compliance, and sustainability targets matter. Vendors that improve early cure, corrosion resistance, and application consistency in water-based grades can win share in architectural, commercial, and maintenance coating channels.
Analyst Perspective
The modified epoxy resin market is experiencing consistent changes as end-use industries increasingly focus on high-performance materials that provide improved mechanical strength, chemical resistance, thermal stability, and durability compared to traditional epoxy systems. The growth of the market is mainly fueled by the rising applications in protective coatings, adhesives, electrical and electronics, automotive, aerospace, wind energy, and composite manufacturing, where customized resin formulations enhance product performance and extend service life. Producers are concentrating on the development of sophisticated modified epoxy systems, such as those modified with rubber, polyurethane, and silicone, while also investing in low-emission and sustainable alternatives to comply with changing environmental regulations. From an analyst's viewpoint, technological advancements, product development tailored to specific applications, and the increasing demand for lightweight, durable, and dependable materials are expected to remain pivotal factors influencing market competitiveness and long-term growth in both established and emerging markets.
Product Type Insights
Based on product type, the solvent-based modified epoxy resin segment led the market with the largest revenue share of 72.1% in 2025. The increasing demand for high-performance protective coatings in industrial and marine applications is a major factor driving the growth of solvent-based modified epoxy resins. These resins provide superior adhesion, chemical resistance, and durability, making them essential for harsh environments such as offshore structures, pipelines, and heavy machinery. Unlike water-based alternatives, solvent-based formulations cure effectively in high-humidity conditions, ensuring reliable performance in diverse climates. With global industrial expansion and stricter regulations on infrastructure longevity, the need for resilient coatings continues to drive market demand for solvent-based modified epoxy resins.
Growing environmental regulations and sustainability initiatives are accelerating the adoption of water-based modified epoxy resins, particularly in architectural and decorative coatings. These resins offer a low-VOC and low-odor alternative to traditional solvent-based systems while maintaining excellent mechanical strength and corrosion resistance. As industries worldwide shift toward eco-friendly materials, regulatory bodies are imposing stricter restrictions on solvent emissions, pushing manufacturers and end-users toward water-based solutions. In addition, advancements in formulation technology have improved the performance of water-based epoxy resins, expanding their application in industrial and commercial sectors.
Application Insights & Trends
Based on application, the building & construction segment led the market with the largest revenue share of 46.3% in 2025, due to the increasing focus on infrastructure modernization and sustainable building practices. These resins are widely used in adhesives, sealants, and protective coatings due to their high strength, moisture resistance, and thermal stability. Rapid urbanization, particularly in emerging economies, is driving large-scale construction projects that require advanced materials for improved structural durability and longevity. In addition, the growing adoption of green buildings and energy-efficient structures is encouraging the use of modified epoxy resins in flooring, insulation, and reinforced concrete applications.
 To learn more about this report, Download Free Sample Report
The transition toward electric vehicles (EVs) and lightweight automotive materials is a significant driver for modified epoxy resin demand in the automotive industry. With manufacturers striving to improve vehicle efficiency and safety, these resins are increasingly used in composite materials, adhesives, and coatings to reduce weight without compromising strength. The push for enhanced battery performance in EVs has also led to the adoption of epoxy-based encapsulants and thermal management solutions. Furthermore, the rising integration of advanced driver-assistance systems (ADAS) and smart automotive components requires reliable and durable epoxy-based adhesives, further driving market growth.
Regional Insights
The modified epoxy resin market in North America is anticipated to grow at the significant CAGR during the forecast period. The growing investments in renewable energy and electric vehicle (EV) infrastructure are driving demand for modified epoxy resins in North America. As the region shifts toward sustainability, wind energy projects are expanding rapidly, requiring high-performance epoxy resins for turbine blades and structural components. In addition, the rapid electrification of transportation, backed by government incentives and private sector investment, is boosting the use of epoxy-based adhesives, coatings, and composites in EV manufacturing. The increasing focus on lightweight materials in aerospace and automotive industries further strengthens market growth, as manufacturers seek high-strength resins to enhance fuel efficiency and durability.
U.S. Modified Epoxy Resin Market Trends
The modified epoxy resin market in the U.S. accounted for the largest market share in North America in 2025, the booming electronics and semiconductor industry is a key driver for the market growth. With the country pushing to strengthen domestic semiconductor manufacturing under the CHIPS Act, demand for advanced materials used in circuit boards, encapsulants, and insulating coatings is surging. The expansion of 5G infrastructure and data centers is also fueling the need for epoxy resins with superior thermal and electrical properties.
Asia Pacific Modified Epoxy Resin Market Trends
Asia Pacific dominated the modified epoxy resin market with the largest revenue share of 42.6% in 2025, which is attributable to rapid industrialization and large-scale infrastructure development projects. Countries like India, South Korea, and Japan are witnessing major investments in smart cities, high-speed rail, and commercial construction, all of which require high-durability coatings and adhesives. In addition, the region’s dominance in electronics manufacturing, particularly in consumer devices and printed circuit boards (PCBs), is fueling demand for epoxy resins with enhanced thermal stability and electrical insulation. The automotive industry’s expansion, supported by rising disposable income and increasing EV adoption, is further strengthening the market.
 To learn more about this report, Download Free Sample Report
China Modified Epoxy Resin Market Trends
The modified epoxy resin market in China accounted for the largest market revenue share in the Asia Pacific in 2025. China’s leadership in manufacturing and its aggressive push for technological self-sufficiency are key drivers for the market growth. As the world’s largest producer of electronics and electric vehicles, China’s demand for epoxy-based circuit board laminates, battery encapsulants, and lightweight automotive components is surging. Government policies promoting high-speed rail networks, aerospace advancements, and large-scale renewable energy projects are further increasing the need for durable, high-performance epoxy resins.
Europe Modified Epoxy Resin Market Trends
The modified epoxy resin market in Europe is expected to grow at a significant CAGR during the forecast period. Europe’s strict environmental regulations and circular economy initiatives are accelerating the shift toward sustainable and bio-based modified epoxy resins. The European Green Deal and tightened restrictions on volatile organic compounds (VOCs) are pushing manufacturers to develop low-emission and recyclable epoxy formulations.
Key Modified Epoxy Resin Company Insights
The modified epoxy resin industry is highly competitive, with several key players dominating the landscape. Major companies include Olin Corporation, Hexion Inc., Aditya Birla Chemicals, Kukdo Chemical Co., Ltd, Westlake Epoxy, Hindusthan Speciality Chemicals, Adeka Corporation, Chemex Chemicals, Nan Ya Plastics Corporation, and Huntsman Corporation. The modified epoxy resin industry is characterized by a competitive landscape with several key players driving innovation and market growth. Major companies in this sector are investing heavily in research and development to enhance the performance, cost-effectiveness, and sustainability of their types.
Key Modified Epoxy Resin Companies:
The following key companies have been profiled for this study on the modified epoxy resin market.
- Olin Corporation
- Hexion Inc.
- Aditya Birla Chemicals
- Kukdo Chemical Co., Ltd
- Westlake Epoxy
- Hindusthan Speciality Chemicals
- Adeka Corporation
- Chemex Chemicals
- Nan Ya Plastics Corporation
- Huntsman Corporation
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Olin Corporation, Hexion Inc., Aditya Birla Chemicals, Kukdo Chemical Co., Ltd, Westlake Epoxy, Adeka Corporation, Nan Ya Plastics Corporation, Huntsman Corporation)
- Maintain broad resin portfolios across solvent-based and water-based grades.
- Use integrated supply chains and long-term customer contracts to protect volume.
- Focus on technical service, qualification support, and regional distribution coverage.
- Strong scale and established brand credibility across industrial end uses.
- Better feedstock access and process integration than smaller competitors.
- Wider application support for coatings, adhesives, composites, and electrical uses.
- Higher exposure to feedstock volatility and compliance costs.
- Slower portfolio shifts when end-use requirements change rapidly.
- Greater pricing pressure in mature and highly competitive channels.
Emerging Players (Hindusthan Specialty Chemicals, Chemex Chemicals)
- Target niche accounts and regional customers with responsive supply.
- Compete through customized grades and application-specific service.
- Rely on distributor relationships and selective end-use penetration.
- Greater agility in formulation changes and customer support.
- Faster response to local demand shifts and order customization.
- Lower organizational complexity than large integrated producers.
- Limited scale and narrower geographic footprint.
- Lower bargaining power in raw material procurement.
- Weaker ability to absorb reformulation and regulatory costs
Recent Developments
-
In March 2024, Evonik launched a new epoxy curing agent that speeds up production and offers strong UV resistance. This product allows for faster curing times, increasing manufacturing efficiency, while also protecting coatings from sun damage, which extends the lifespan and appearance of the coated materials.
-
In February 2023, Huntsman introduced JEFFAMINE M-3085 amine, a mono-polyether amine with a higher molecular weight compared to its existing variants. This product aims to enhance the performance characteristics of modified epoxy resins in various applications.
Modified Epoxy Resin Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 24.0 billion
Market size value in 2026
USD 25.3 billion
Revenue forecast in 2033
USD 35.5 billion
Growth rate
CAGR of 5.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product type, application, region
RegioFinal scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; India; Japan; South Korea; Australia Brazil; Argentina; Saudi Arabia; UAE; South Africa
Key companies profiled
Olin Corporation; Hexion Inc.; Aditya Birla Chemicals; Kukdo Chemical Co., Ltd; Westlake Epoxy; Hindusthan Specialty Chemicals; Adeka Corporation; Chemex Chemicals; Nan Ya Plastics Corporation; Huntsman Corporation
Customization scope
Free report customization (equivalent to up to 8 analysts' working days) with purchase addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Modified Epoxy Resin Market Report Segmentation
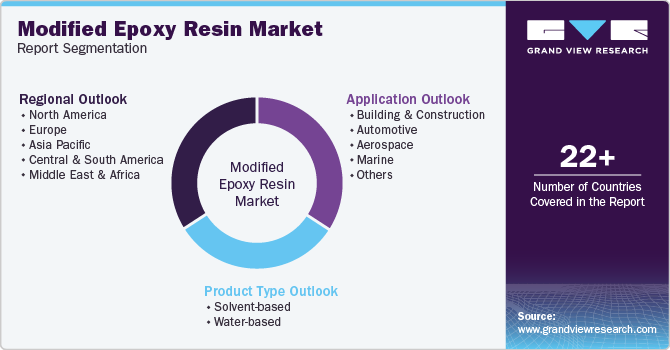
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global modified epoxy resin market report based on the product type, application, and region:
 To learn more about this report, Download Free Sample Report
-
Product Type Outlook (Volume Kilotons; Revenue, USD Million, 2021 - 2033)
-
Solvent-based
-
Water-based
-
-
Application Outlook (Volume Kilotons; Revenue, USD Million, 2021 - 2033)
-
Building & Construction
-
Automotive
-
Aerospace
-
Marine
-
Others
-
-
Regional Outlook (Volume Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
UAE
-
South Africa
-
-
Research Methodology
The modified epoxy resin market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each modified epoxy resin segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product Type
Revenue capture definition
Solvent Based
Revenue is captured through sales of solvent-borne modified epoxy resin grades supplied to coating formulators, adhesive producers, and industrial maintenance users that need strong cure performance, humidity tolerance, and high film durability.
Water Based
Revenue is captured through waterborne modified epoxy resin sales into low-VOC coatings, regulated construction systems, and environmentally compliant industrial applications where odor control, emission limits, and applicator safety influence purchasing.
Segment - Application
Revenue capture definition
Building & Construction
Revenue is captured through resin demand used in flooring, protective coatings, sealants, adhesives, concrete repair, and structural protection systems sold into commercial, residential, and infrastructure projects.
Automotive
Revenue is captured through resin sold into lightweight composites, structural adhesives, coatings, battery-related encapsulation, and assembly applications where strength, heat resistance, and durability support vehicle performance.
Aerospace
Revenue is captured through resin supplied to composite structures, laminating systems, adhesives, coatings, and interior components that require low weight, high mechanical integrity, and certified performance.
Marine
Revenue is captured through resin used in anti-corrosion coatings, offshore maintenance systems, shipbuilding adhesives, and protective layers for hulls, decks, and submerged structures exposed to salt and moisture.
Others
Revenue is captured through demand from industrial equipment, electrical insulation, wind energy, maintenance coatings, and specialty manufacturing uses that do not fit the core end-use groups.
Estimation Model
Layer Name
Key Question
Description
Demand Mapping Layer
Why map demand?
This layer maps revenue to end-use intensity across construction, automotive, aerospace, and marine demand pools, ensuring segment value reflects real consumption patterns.
Formulation Layer
Why split by chemistry?
This layer separates solvent-based and water-based revenue because product chemistry drives pricing, compliance, and customer qualification in the modified epoxy resin market.
Regional Validation Layer
Why adjust by region?
This layer adjusts estimates for Asia Pacific concentration and North American acceleration, which materially influence production allocation and commercial prioritization.
Company Calibration Layer
Why benchmark firms?
This layer benchmarks major producers against smaller specialists to correct for integration, channel reach, and application expertise differences across the value chain.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional demand split
Added a region-wise demand view covering Asia Pacific, North America, Europe, Central and South America, and the Middle East & Africa, with emphasis on end-use concentration, production presence, and commercial pull across the modified epoxy resin value chain.
Improves geographic prioritization and supports market entry planning.
Application analysis
Added application-level commentary for building & construction, automotive, aerospace, marine, and other industrial uses, with clear revenue capture logic and end-use demand drivers tied to resin performance.
Makes segment opportunity mapping more actionable and concise.
Benchmark key players
Added a structured player view for major producers and regional specialists, with operating strategies, competitive edge, and weaknesses aligned to scale, integration, and market presence.
Strengthens competitive assessment and highlights positioning differences.
Frequently Asked Questions About This Report
The Asia Pacific modified epoxy resin market accounted for the largest share of 42.6% market size in 2025.
India was the leading modified epoxy resin market and is expected to grow at a compound annual growth rate of 5.5%.
Based on application, the building & construction segment accounted for the largest share of 46.3% market size in 2025. Rising demand for residential, commercial, industrial, and infrastructure development is accelerating the adoption of modified epoxy resin in building & construction due to its excellent adhesion, mechanical strength, chemical resistance, corrosion protection, moisture resistance, and long-term durability across protective coatings, flooring systems, structural adhesives, concrete repair, waterproofing, and composite construction materials.
The solvent-based modified epoxy resin industry led the modified epoxy resin market in 2025 with a 72.1% share. The increasing demand for high-performance protective coatings in industrial and marine applications is a major factor driving the growth of solvent-based modified epoxy resins.
Some key players operating in the modified epoxy resin market include Olin Corporation, Hexion Inc., Aditya Birla Chemicals, Kukdo Chemical Co., Ltd, Westlake Epoxy, Hindusthan Speciality Chemicals, Adeka Corporation, Chemex Chemicals, Nan Ya Plastics Corporation, and Huntsman Corporation.
The growing demand for high-performance coatings in construction and infrastructure projects is driving the modified epoxy resin market, as these resins offer excellent durability, corrosion resistance, and weather protection.
The modified epoxy resin market is expected to grow at a compound annual growth rate of 5.0% from 2026 to 2033 to reach around USD 35.5 billion by 2033.
Automotive is expected to grow at the fastest CAGR of 5.5% over teh forecast period of 2026 to 2033.
The modified epoxy resin market was valued at USD 24.0 billion in the year 2025 and is estimated at around USD 25.3 billion in 2026.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


