
- Home
- »
- Inorganic Chemicals
- »
-
Nickel Chemicals Market Size & Share Report, 2026-2033GVR Report cover
![Nickel Chemicals Market (2026 - 2033)Report]()
Nickel Chemicals Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Nickel Sulfate, Nickel Oxide, Nickel Hydroxide, Nickel Chloride), By Application (Batteries, Electroplating & Surface Treatment), By Region, And Segment Forecasts
Market Size, 2025
$6.0BMarket Estimate, 2026
$6.4BMarket Forecast, 2033
$10.6BCAGR, 2026–2033
7.5%Nickel Chemicals Market Summary
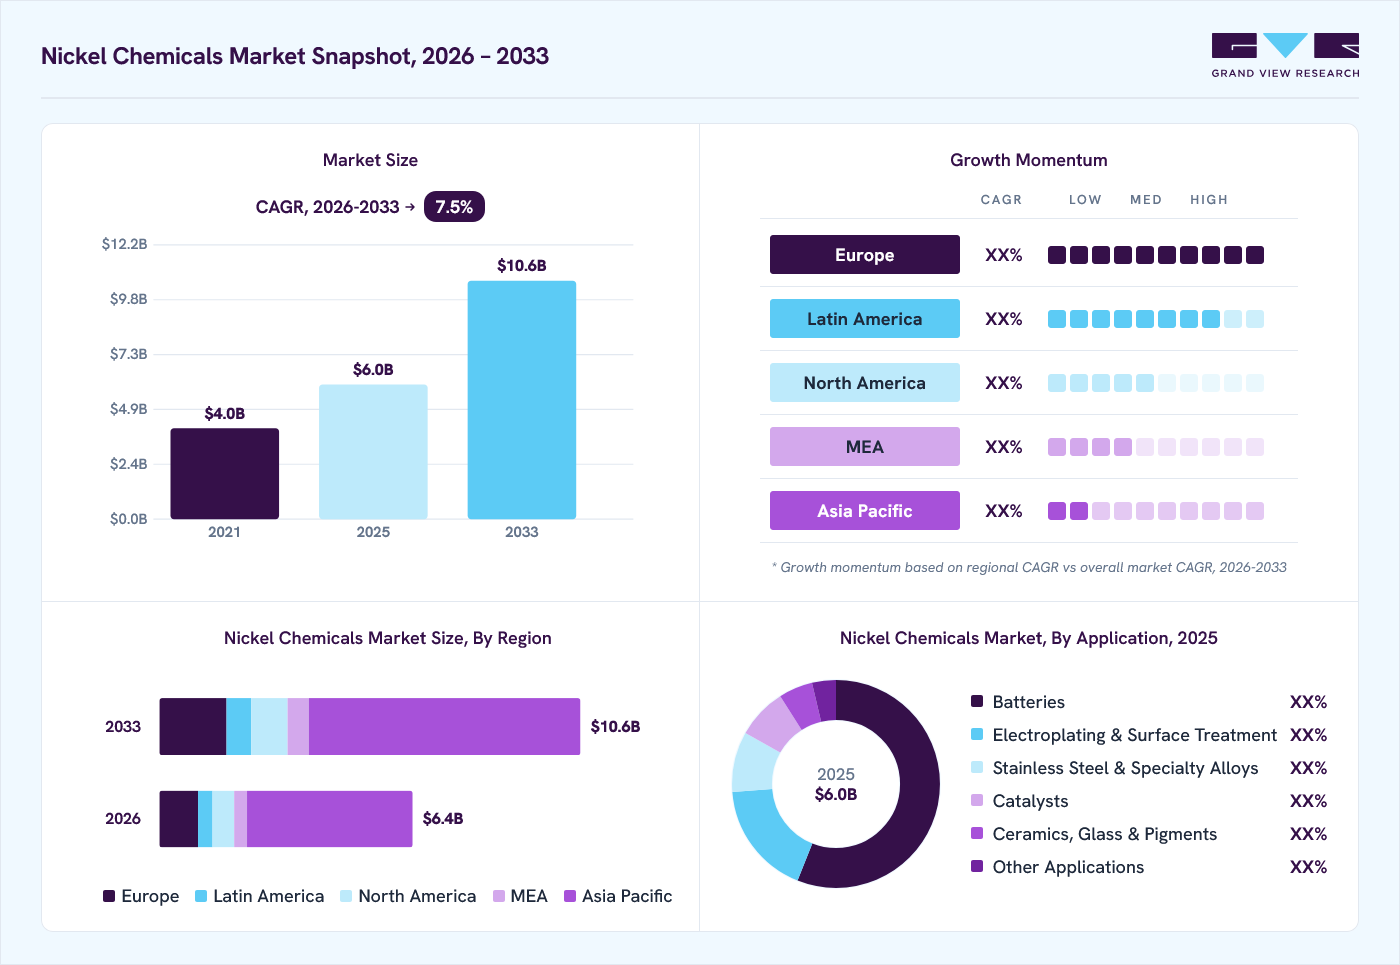
The global nickel chemicals market size was valued at USD 6.0 billion in 2025 and is projected to grow from USD 6.4 billion in 2026 to USD 10.6 billion by 2033, at a CAGR of 7.5% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 65.5% in 2025. Growth in the global market is driven by expanding battery manufacturing, rising electric vehicle adoption, and increasing demand for nickel compounds in electroplating, catalysts, electronics, ceramics, and specialty chemical applications.
Key Market Trends & Insights
- By product: Nickel sulfate held the largest revenue share of 59.5% in 2025.
- By application: Catalysts segment is expected to grow at a CAGR of 7.5% from 2026 to 2033.
Regional Highlights
- Largest Region: Asia Pacific (65.5%, revenue share, 2025)
- Fastest-growing region: Europe (highest CAGR, 2026-2033)
- By country: China held the largest share in 2025
Market Size & Forecast
- Market size in 2025: USD 6.0 Billion
- Estimated market size in 2026: USD 6.4 Billion
- Projected market size by 2033: USD 10.6 Billion
- CAGR (2026-2033): 7.5%
Three ways to get this report
Buy it, customize it, or ask a question.Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Growth in the nickel chemicals industry is supported by expanding demand for nickel sulfate, nickel chloride, nickel carbonate, nickel hydroxide, and other nickel-based compounds across battery manufacturing, electroplating, catalysts, electronics, ceramics, and specialty chemical applications.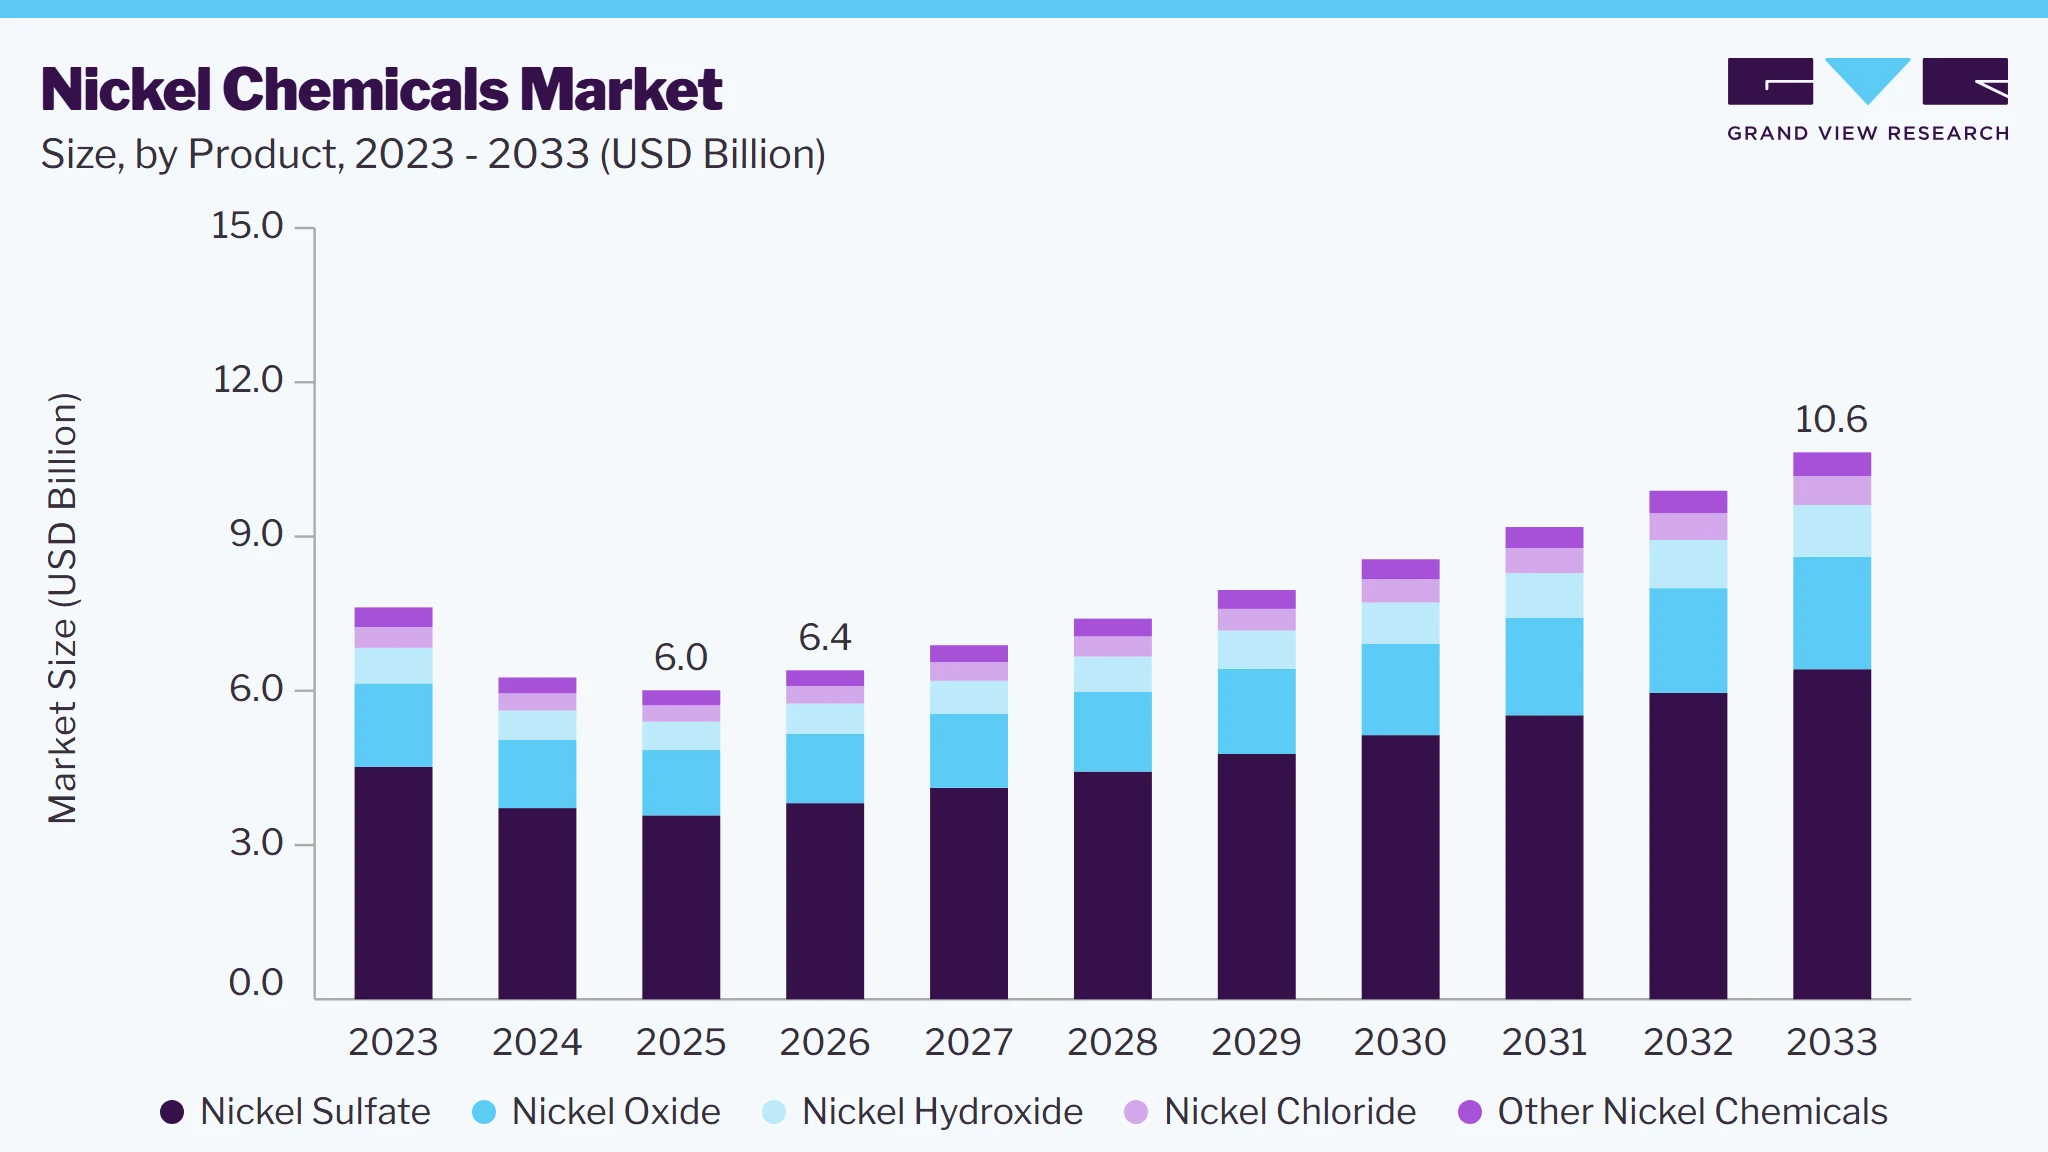
The rapid expansion of electric vehicles and energy storage systems is increasing the consumption of high-purity nickel chemicals used in the production of cathode active materials for lithium-ion batteries. At the same time, continued use of nickel compounds in surface finishing, industrial catalysts, metal treatment, and electronic components is supporting demand across non-battery applications.
Market Dynamics
The nickel chemicals industry is influenced by nickel ore and intermediate availability, nickel prices, battery production levels, electric vehicle adoption, electroplating activity, and demand from industrial and specialty chemical applications. Battery-grade nickel chemicals are particularly sensitive to developments in cathode technology, battery chemistry, production capacity, and procurement strategies among battery and precursor manufacturers.
Market development is also shaped by the transition toward localized supply chains, changes in nickel-intensive battery chemistries, environmental regulations, energy costs, and technological advances in nickel recovery and chemical processing. Investments in refining, recycling, and high-purity nickel chemical production are contributing to changes in the competitive landscape and creating opportunities for suppliers with integrated production capabilities.
The rapid expansion of electric vehicle and energy storage markets is driving demand for battery-grade nickel chemicals, particularly nickel sulfate, used in the production of nickel-containing cathode materials. Rising investments in lithium-ion battery manufacturing capacity are increasing requirements for high-purity nickel inputs and encouraging producers to expand processing and refining capabilities.
The development of nickel-rich cathode technologies has historically supported consumption of nickel-based materials because higher nickel content can contribute to greater energy density. Although battery manufacturers are increasingly diversifying chemistries, continued investment in nickel-containing battery technologies, alongside growth in stationary energy storage and electric mobility, is expected to maintain a significant demand base for battery-grade nickel chemicals.
Fluctuations in nickel prices can create uncertainty for nickel chemical manufacturers by affecting production costs, inventory valuation, procurement decisions, and selling prices. Changes in mining output, refining capacity, geopolitical conditions, and global supply-demand balances can cause substantial variations in nickel feedstock costs and place pressure on producer margins.
The increasing adoption of alternative battery chemistries also presents a structural challenge to demand growth from the battery segment. Greater use of lithium iron phosphate (LFP) and other nickel-free technologies can reduce nickel intensity in certain applications, limiting the pace at which battery-related nickel chemical consumption expands. Producers therefore face the need to diversify their application base and reduce dependence on a single end-use industry.
The growing emphasis on circularity and resource efficiency is creating opportunities for nickel chemical manufacturers to develop recycling-based production routes and recover nickel from spent batteries, industrial residues, plating solutions, and other secondary sources. Recovered nickel can be processed into chemical intermediates, helping reduce reliance on primary raw materials while supporting more sustainable supply chains.
Another opportunity lies in the production of high-purity and application-specific nickel chemicals for advanced batteries, electronics, catalysts, and specialty applications. Customers are increasingly seeking consistent particle characteristics, low impurity levels, and tighter quality specifications. Suppliers capable of providing specialized grades, improving purification technologies, and integrating recycling into their production networks can strengthen their position in higher-value market segments.
Market Concentration & Characteristics
The market comprises integrated nickel producers, chemical manufacturers, battery-material suppliers, metal-processing companies, and regional specialty chemical producers. Competition varies across product categories, with large-scale manufacturers benefiting from established access to raw materials, production infrastructure, technological capabilities, and relationships with downstream customers. The market is increasingly characterized by a shift toward high-purity, battery-grade, and application-specific products, particularly as battery and electronics manufacturers impose stricter quality requirements. Supply security, product consistency, production economics, technological expertise, and sustainability credentials are becoming important competitive factors. Companies with integrated access to nickel resources or intermediates, recycling capabilities, and downstream processing are positioned to improve supply reliability and capture opportunities in strategically important applications.
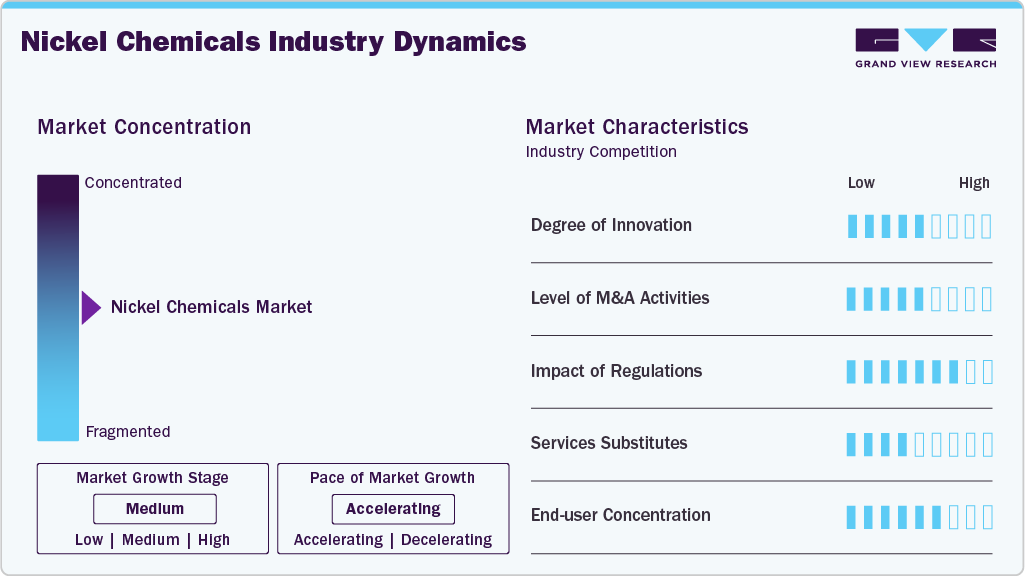
Leading companies are strengthening their positions in the nickel chemicals industry through capacity expansion, process optimization, product development, and investments in high-purity nickel compounds for battery, electroplating, catalyst, electronics, and specialty chemical applications. Increasing demand for battery-grade materials is encouraging manufacturers to improve purity levels, production efficiency, and product consistency while developing grades tailored to specific downstream requirements. Companies are also expanding partnerships with battery manufacturers, cathode-material producers, and industrial customers to secure long-term supply relationships and develop application-specific nickel chemical solutions.
Analyst Perspective
The market is expected to maintain a growth trajectory, supported by expanding battery manufacturing, rising electric vehicle adoption, and sustained demand for nickel-based compounds across electroplating, catalysts, electronics, ceramics, and specialty applications. Battery-related uses are likely to remain a major source of incremental demand, particularly for high-purity nickel sulfate used in nickel-containing cathode materials, while diversified industrial applications will provide additional market stability. From a competitive perspective, product purity, consistent quality, processing efficiency, and application-specific grades are becoming key differentiators, encouraging manufacturers to invest in capacity expansion, advanced processing, and specialized product development.
Product Insights
The nickel sulfate dominated the market, accounting for 59.5% of total revenue in 2025. Its leading position is primarily attributed to extensive use in lithium-ion battery supply chains, where it serves as a key nickel source for producing nickel-containing cathode materials. Established use in electroplating and other industrial processes further broadens its demand base, while continued investment in battery manufacturing capacity is expected to reinforce its market position.
The nickel hydroxide segment is expected to expand at a CAGR of 8.0% during the forecast period, supported by its role in rechargeable battery technologies and other electrochemical applications. Rising demand for energy storage solutions, combined with ongoing improvements in electrode materials and battery performance, is expected to create additional consumption opportunities. Demand from catalysts and specialized industrial applications will further contribute to segment expansion.
Application Insights
Batteries dominated the application segment with a revenue share of 56.0% in 2025. This position reflects the substantial use of nickel compounds in battery material production, particularly for nickel-containing cathode chemistries used in electric vehicles and energy storage systems. Expansion of battery manufacturing infrastructure and continued electrification of transportation are supporting the segment, although shifts toward nickel-free chemistries may influence its growth trajectory across different markets.the
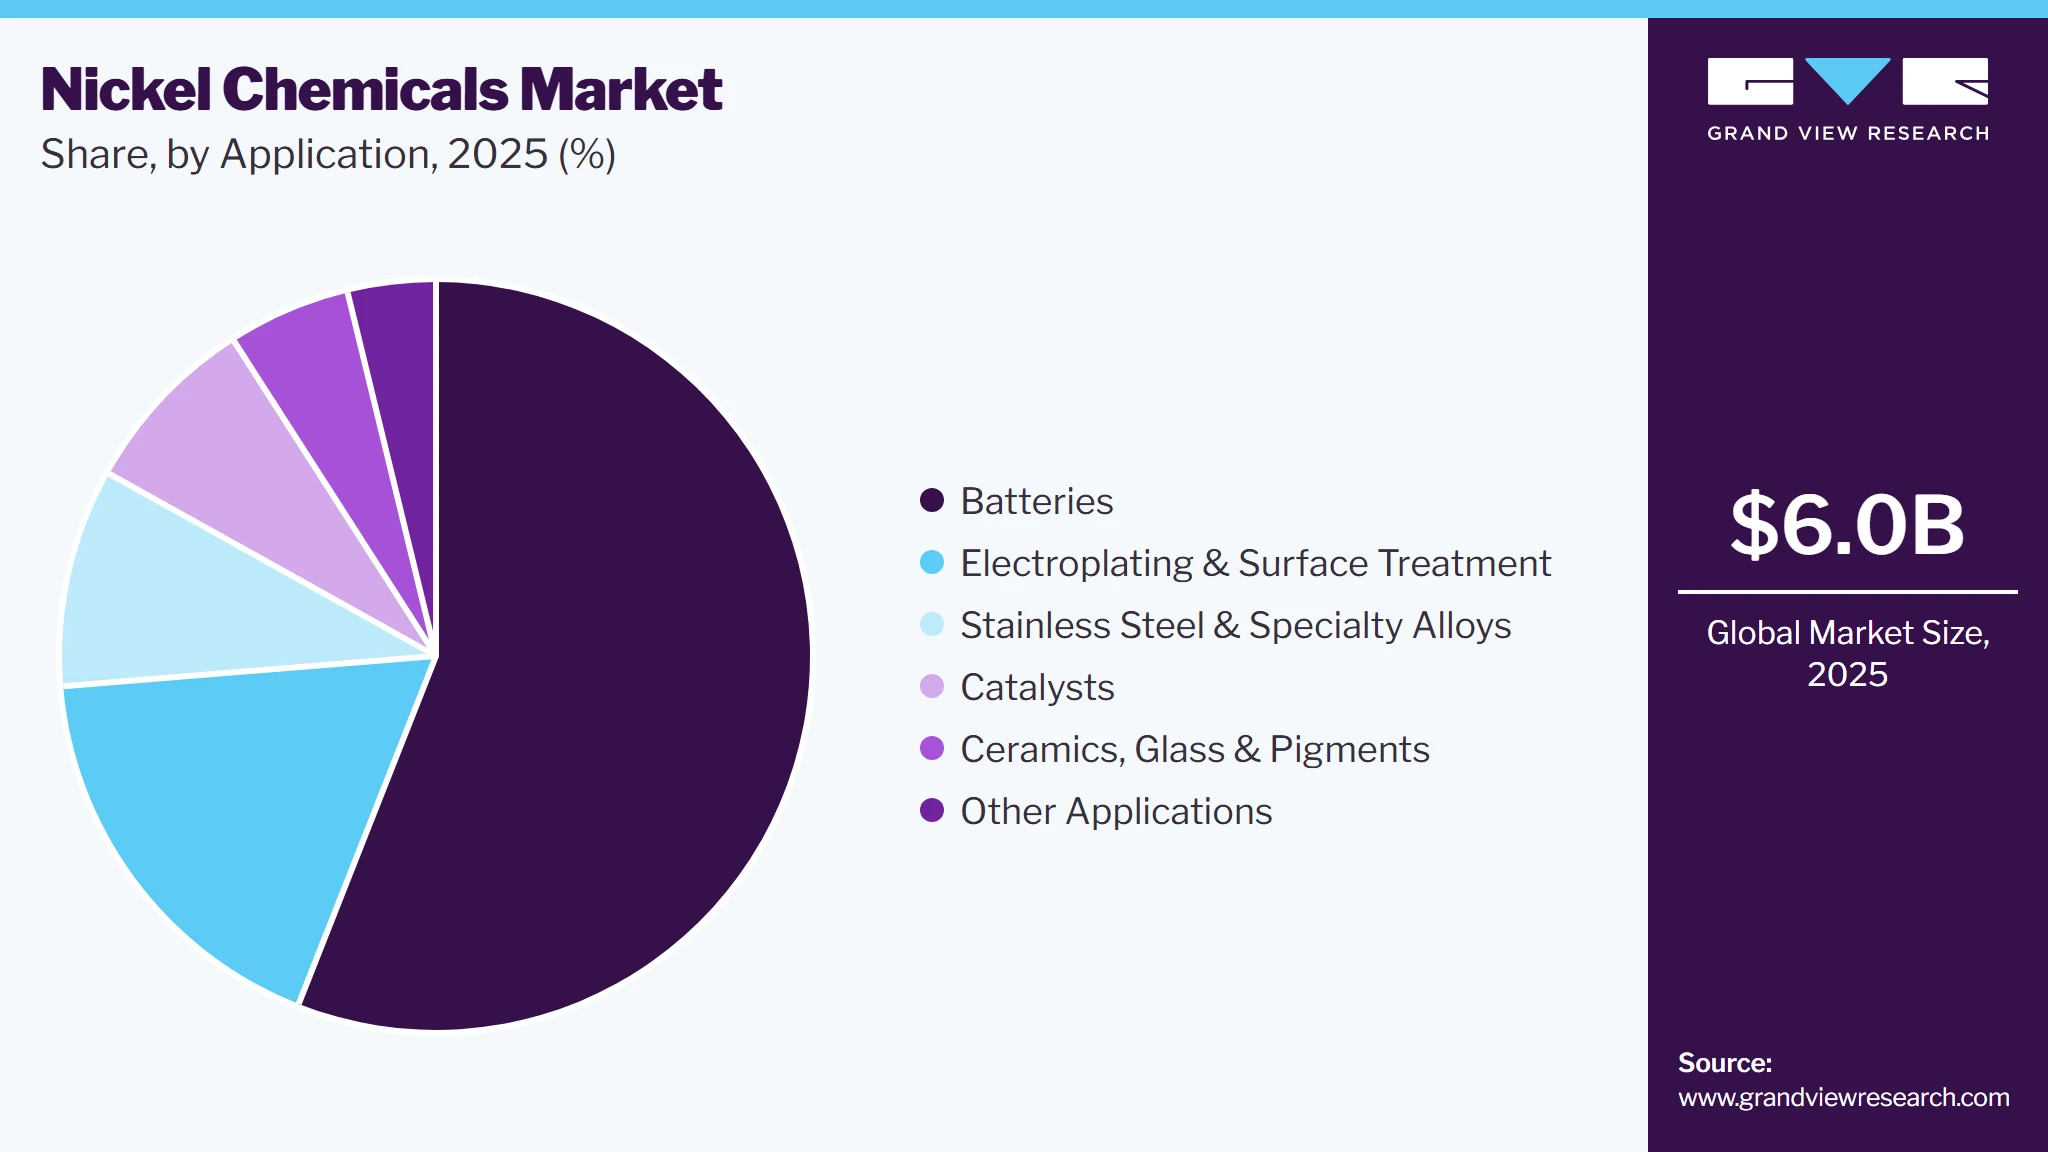
The catalysts segment is expected to grow at a CAGR of 7.5% during the forecast period, driven by the use of nickel compounds in catalyst manufacturing for hydrogenation, petrochemical processing, chemical synthesis, and other industrial processes. Increasing focus on process efficiency, catalyst performance, and cleaner industrial production is creating opportunities for nickel-based catalyst technologies, while capacity additions in chemical and refining industries are expected to generate further demand.
Regional Insights
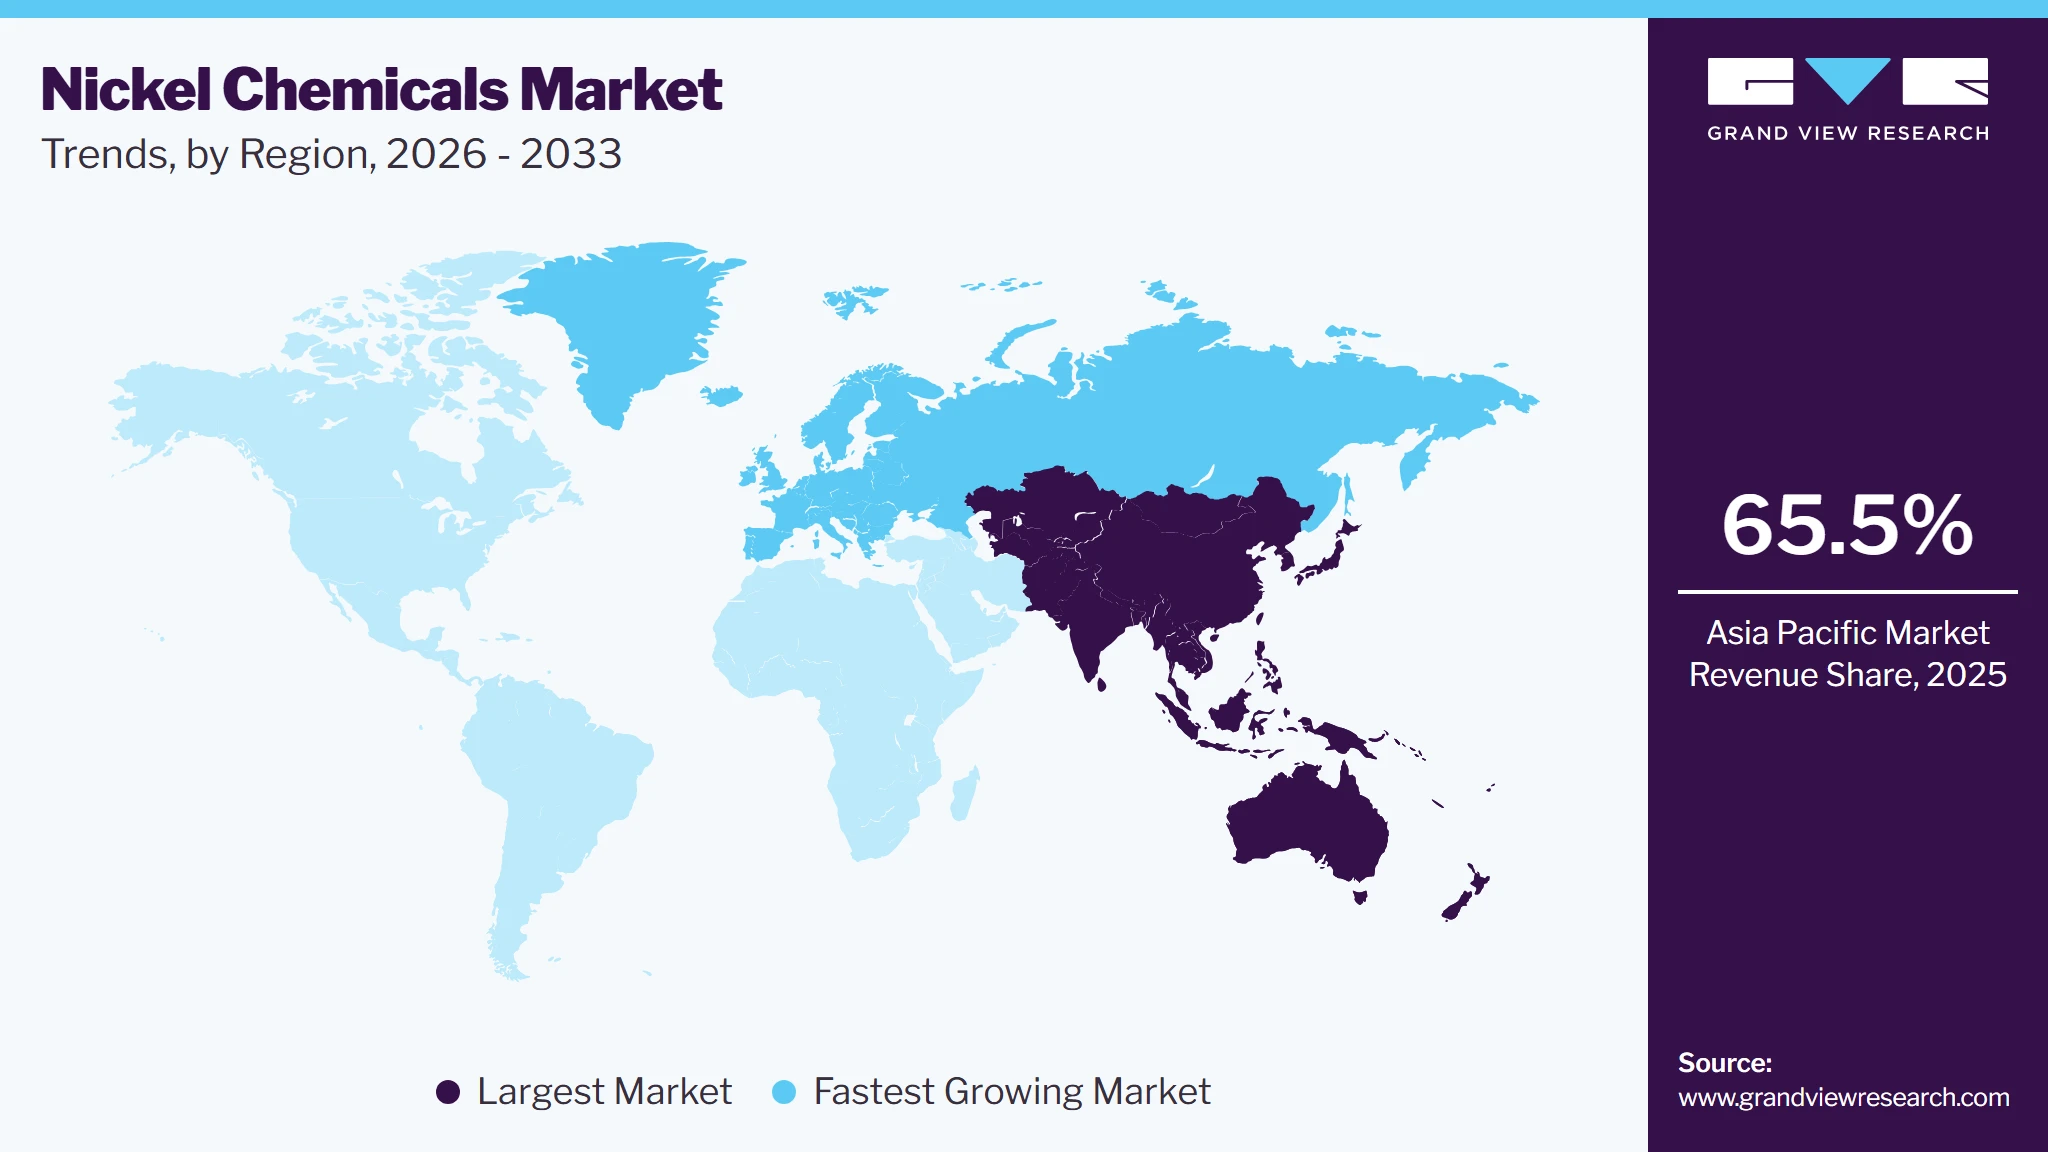
The nickel chemicals industry in Asia Pacific dominated the global market with a revenue share of 65.5% in 2025. The region’s leading position is supported by its large-scale battery manufacturing base, extensive electroplating and metal-finishing industries, and strong production of stainless steel and specialty alloys. China, Japan, South Korea, and other major Asian manufacturing economies contribute significantly to regional consumption, while continued investments in battery materials and downstream chemical processing are expected to sustain demand for nickel sulfate, nickel hydroxide, nickel chloride, and other nickel compounds.
China Nickel Chemicals Market Trends
China nickel chemicals industry represents the largest market within Asia Pacific, supported by its extensive battery-materials manufacturing capacity and well-established stainless steel, electroplating, and chemical-processing industries. The country has a strong domestic supply chain for nickel intermediates and chemicals, with manufacturers increasingly focusing on battery-grade materials, high-purity compounds, and integrated production capabilities. Growing demand for electric vehicles and energy storage systems is expected to maintain China’s importance in the regional market.
North America Nickel Chemicals Market Trends
The nickel chemicals industry in North America is supported by demand for nickel chemicals from battery materials, electroplating, catalysts, specialty alloys, and electronics-related applications. Increasing efforts to establish regional battery and critical-mineral supply chains are encouraging investments in domestic processing, refining, recycling, and production of higher-value nickel compounds. The region is also witnessing a greater emphasis on supply security and reducing dependence on imported battery-material inputs, creating opportunities for local nickel chemical producers.
The nickel chemicals industry in the U.S. is expected to grow at a CAGR of 7.3% during the forecast period, driven by growing investments in electric vehicle batteries, energy storage, aerospace and specialty alloys, electroplating, and industrial catalysts. Expansion of domestic battery-material manufacturing is increasing interest in reliable supplies of high-purity nickel compounds, particularly nickel sulfate and other materials used in cathode production. Recycling and recovery of nickel from end-of-life batteries and industrial streams are also gaining importance as manufacturers seek to strengthen domestic raw-material availability.
Europe Nickel Chemicals Market Trends
The nickel chemicals industry in Europe is expected to register the fastest CAGR of 8.2% during the forecast period. Market expansion is supported by investments in battery manufacturing, energy storage technologies, specialty chemicals, and advanced metal processing industries. The region's focus on developing localized battery supply chains and improving material circularity is encouraging demand for high-purity nickel chemicals, while recycling and recovery initiatives are expected to create additional opportunities for regional producers.
Latin America Nickel Chemicals Market Trends
The nickel chemicals industry in Latin America presents growth opportunities due to its established nickel mining and metallurgical activities, particularly in countries with significant nickel resources. The region can support the nickel chemicals value chain through greater downstream processing of nickel-bearing materials into higher-value compounds. Rising interest in mineral processing, resource utilization, and international supply-chain diversification is expected to encourage further development of nickel chemical production and related industrial applications.
Middle East & Africa Nickel Chemicals Market Trends
The nickel chemicals industry in the Middle East & Africa is supported primarily by industrial manufacturing, metal finishing, catalysts, specialty chemicals, and emerging battery-related applications. Increasing industrialization and infrastructure development are creating demand for nickel-containing materials across multiple end use sectors. Opportunities are also emerging from efforts to develop mineral-processing capabilities and strengthen regional participation in critical-mineral supply chains.
Key Nickel Chemicals Company Insights
Companies operating in the nickel chemicals industry are strengthening their competitive positions through product portfolio expansion, production capacity enhancement, process optimization, strategic collaborations, and investments in high-purity and application-specific nickel compounds. Leading manufacturers are focusing on improving product purity, consistency, production efficiency, supply reliability, and customized grades while expanding their presence across battery materials, electroplating, catalysts, electronics, ceramics, and specialty chemical applications. Increasing demand for battery-grade nickel chemicals and growing emphasis on secure and sustainable supply chains are also encouraging companies to invest in recycling, advanced processing technologies, and regional production capabilities.
-
JCB Chemicals is a participant in the market, specializing in the manufacture and supply of nickel-based compounds, including nickel sulfate, nickel chloride, nickel hydroxide, nickel carbonate, nickel acetate, nickel nitrate, nickel fluoride, and nickel oxide. The company focuses on product purity, consistent quality, reliable supply, and customized chemical solutions for applications including electroplating, surface finishing, battery production, catalysts, ceramics, chemical processing, and industrial manufacturing. Its broad portfolio of compounds and ability to serve diverse industrial applications support its competitive position in the market.
-
Shreeji Industries is a participant in the market, focusing on the manufacture and supply of nickel sulfate, nickel chloride, and other nickel-based chemicals for electroplating and industrial applications. The company offers nickel sulfate in different grades and forms, serving applications across metal finishing, electroplating, chemical processing, and related industrial sectors. Its focus on product quality, purity, consistent supply, and application-specific requirements supports its position in the market.
Key Nickel Chemicals Companies
The following key companies have been profiled for the study on the nickel chemicals market:
-
JCB Chemicals
-
SHREEJI INDUSTRIES
-
Vrik Pharma
-
Moly metal L.L.P
-
Dhruv Chemicals
-
Bluestone Metals and Chemicals
-
Sumitomo Metal Mining Co., Ltd.
-
Jinchuan Group Co., Ltd.
-
Otto Chemie Pvt. Ltd.
-
Norilsk Nickel
Company Categorization:
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Sumitomo Metal Mining Co., Ltd., Jinchuan Group Co., Ltd., Norilsk Nickel
- Expand nickel refining and chemical production capacity to meet growing demand from battery materials, electroplating, catalysts, and specialty applications.
- Invest in advanced processing, purification, and recycling technologies to improve nickel recovery, product quality, and production efficiency.
- Strengthen integrated supply chains from nickel resources and intermediates to high-purity nickel chemicals, particularly battery-grade products.
- Develop strategic partnerships and long-term supply relationships with battery manufacturers, cathode-material producers, and industrial customers.
- Integrated access to nickel resources, refining infrastructure, and downstream chemical production supports supply security and cost efficiency.
- Large-scale production capabilities enable reliable supply of nickel chemicals to battery and industrial customers across international markets.
- Strong technical and processing expertise supports the production of high-purity and application-specific nickel compounds.
- Established global customer relationships and distribution networks provide broad market access.
- Significant financial and operational resources support capacity expansion, R&D, recycling, and technological investments.
- Large-scale integrated operations can involve higher capital requirements and longer investment cycles for capacity expansion and technology upgrades.
- Exposure to fluctuations in nickel prices and changes in global mining and refining economics can affect production costs and margins.
- Dependence on energy-intensive refining and chemical-processing operations can increase exposure to energy costs and environmental compliance requirements.
- Large organizational structures may provide less flexibility in addressing small-volume or highly customized customer requirements.
Emerging Players: JCB Chemicals, Shreeji Industries, Vrik Pharma, Moly Metal L.L.P., Dhruv Chemicals, Bluestone Metals and Chemicals, Otto Chemie Pvt. Ltd.
- Expand nickel chemical portfolios across nickel sulfate, nickel chloride, nickel carbonate, nickel oxide, nickel hydroxide, and other specialty compounds to serve diverse industrial applications.
- Focus on high-purity and application-specific grades for electroplating, metal finishing, catalysts, battery materials, electronics, ceramics, and chemical processing.
- Strengthen manufacturing and sourcing capabilities to improve product availability, quality consistency, and delivery reliability.
- Develop regional distribution networks and closer customer relationships to increase penetration across domestic and export markets.
- Greater flexibility in product development and customer service enables these companies to respond to specific grade, purity, packaging, and volume requirements.
- Regional manufacturing and distribution capabilities can provide shorter lead times and cost advantages in selected markets.
- Diversified nickel chemical portfolios allow suppliers to serve multiple end-use industries rather than relying on a single application.
- Proximity to customers supports faster technical communication, product customization, and application support.
- Competitive pricing and relatively lean operating structures can help emerging suppliers compete effectively in price-sensitive industrial applications.
- Smaller production capacities and more limited global footprints can restrict their ability to serve large multinational battery and industrial customers.
- Lower financial and R&D resources compared with major integrated nickel producers may constrain investments in advanced processing and recycling technologies.
- Greater dependence on externally sourced nickel intermediates or raw materials can increase exposure to supply availability and price volatility.
- Limited international distribution and brand recognition may make it more challenging to secure large long-term contracts in established global markets.
Recent Developments
-
In April 2025, Aqua Metals developed a high-purity nickel carbonate product using its AquaRefining technology, expanding its nickel chemical portfolio for battery and metallurgical applications. The company stated that the product can be further processed into nickel metal or nickel oxide, supporting broader downstream applications and strengthening its strategy to develop recycled, battery-grade critical mineral materials.
Nickel Chemicals Market Report Scope
Report Attribute
Details
Market Definition
The nickel chemicals market comprises the production and sale of nickel-based chemical compounds, including nickel sulfate, nickel oxide, nickel hydroxide, nickel chloride, nickel carbonate, nickel acetate, and other specialty nickel compounds, which are used across batteries, electroplating and surface treatment, stainless steel and specialty alloys, catalysts, ceramics, electronics, and other industrial applications.
Market size in 2025
USD 6.0 billion
Estimated market size in 2026
USD 6.4 billion
Revenue forecast in 2033
USD 10.6 billion
Growth rate
CAGR of 7.5% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Volume in Kilotons, Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue & volume forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, region
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Finland; Russia; China; India; Japan; South Korea; Indonesia; Brazil; Argentina; Saudi Arabia; South Africa
Key companies profiled
JCB Chemicals; Shreeji Industries; Vrik Pharma; Moly Metal L.L.P.; Dhruv Chemicals; Bluestone Metals and Chemicals; Sumitomo Metal Mining Co., Ltd.; Jinchuan Group Co., Ltd.; Otto Chemie Pvt. Ltd.; Norilsk Nickel.
Customization scope
Free report customization (equivalent up to 8 analysts’ working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Nickel Chemicals Market Report Segmentation
This report forecasts revenue & volume growth at regional levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global nickel chemicals market report based on product, application & region:
-
Product Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Nickel Sulfate
-
Nickel Oxide
-
Nickel Hydroxide
-
Nickel Chloride
-
Other Nickel Chemicals
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Batteries
-
Electroplating & Surface Treatment
-
Stainless Steel & Specialty Alloys
-
Catalysts
-
Ceramics, Glass & Pigments
-
Other Applications
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Finland
-
Russia
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Indonesia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The nickel chemicals market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing—reconciling supply-side and demand-side estimates—and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each nickel chemicals segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Nickel Sulfate
Revenue is generated from the sale of nickel sulfate used primarily in battery precursor and cathode-material production, electroplating, catalysts, and other specialty chemical applications. Demand is influenced by battery manufacturing capacity, electric vehicle adoption, purity requirements, and consumption across industrial applications.
Nickel Oxide
Market revenues arise from nickel oxide used in ceramics, glass and pigments, catalysts, batteries, electronics, and specialty alloys. Demand is influenced by requirements for high-purity materials, thermal and chemical stability, and performance characteristics across industrial and advanced-material applications.
Nickel Hydroxide
Revenue is captured from nickel hydroxide used in rechargeable batteries, particularly nickel-based battery systems, as well as catalysts, electrochemical applications, and specialty materials. Demand is influenced by battery production, energy-storage requirements, product purity, and technological developments in electrochemical materials.
Nickel Chloride
Sales are generated from nickel chloride used extensively in electroplating and surface treatment, as well as catalysts, chemical synthesis, and specialty nickel compounds. Revenue growth is supported by demand for corrosion-resistant and wear-resistant coatings and increasing industrial metal-finishing activity.
Other Nickel Chemicals
Revenue is derived from nickel carbonate, nickel nitrate, nickel acetate, nickel fluoride, nickel sulfamate, and other nickel compounds used across catalysts, electronics, batteries, ceramics, chemical processing, electroplating, and specialty applications. Demand varies according to application-specific purity, performance requirements, and industrial production levels.
Segment - Application
Revenue capture definition
Batteries
Sales are generated from nickel chemicals used in the production of battery electrodes, cathode materials, and other electrochemical components. Demand is supported by electric vehicle adoption, energy-storage deployment, battery manufacturing capacity expansion, and continued use of nickel-containing battery chemistries.
Electroplating & Surface Treatment
Market revenues arise from nickel chemicals used to deposit protective and decorative nickel coatings on metal components. Demand is influenced by automotive, electronics, machinery, aerospace, and industrial manufacturing activity, along with requirements for corrosion resistance, durability, wear resistance, and improved surface performance.
Stainless Steel & Specialty Alloys
Revenue is captured from nickel chemicals used as nickel inputs or intermediates in specialty alloy and metal-processing applications. Demand is influenced by production of high-performance alloys, corrosion-resistant materials, and components used in chemical processing, energy, aerospace, and other demanding industrial environments.
Catalysts
Sales are generated from nickel chemicals used to manufacture nickel-based catalysts for hydrogenation, petrochemical processing, chemical synthesis, and other industrial processes. Demand is supported by refinery and chemical production activity, catalyst replacement requirements, and increasing emphasis on process efficiency.
Ceramics, Glass & Pigments
Revenue is derived from nickel compounds used as colorants, additives, and functional materials in ceramics, glass, pigments, and related products. Demand is influenced by construction and consumer goods production, specialty ceramic manufacturing, and requirements for specific coloration and material properties.
Other Applications
Market revenues arise from nickel chemicals used across electronics, mining, chemical processing, magnetic materials, pharmaceuticals, agriculture, and other specialty applications. Demand is influenced by technological development, industrial production, application-specific performance requirements, and the adoption of nickel-based materials in emerging end uses.
Estimation Model
Layer No.
Layer Name
Key Question
Description
01
Raw Material & Production Layer
What forms is the supply base?
Examine the availability and processing of nickel-bearing raw materials and intermediates used in nickel chemical production, including nickel matte, mixed hydroxide precipitate (MHP), mixed sulfide precipitate (MSP), nickel metal, and other nickel feedstocks. The assessment covers mining and refining, leaching, precipitation, crystallization, purification, chemical conversion, production capacity, manufacturing technology, quality control, storage, and supply-chain management. It also evaluates nickel feedstock prices, energy costs, processing efficiency, environmental requirements, recycling inputs, and capacity expansion that influence product purity, production costs, supply reliability, and scalability.
02
Form Adoption Layer
Where is nickel chemicals utilized?
Evaluate the adoption of nickel chemicals across major applications, including batteries, electroplating and surface treatment, stainless steel and specialty alloys, catalysts, ceramics, glass and pigments, electronics, and other specialty applications. Demand is influenced by battery chemistry, electric vehicle production, industrial manufacturing activity, coating requirements, catalyst demand, product specifications, and the purity and performance characteristics required for individual applications.
03
Consumption Intensity Layer
How much nickel chemicals is consumed?
Assess nickel chemical consumption across major end-use industries, including battery manufacturing, automotive, electronics, metal finishing, chemical processing, ceramics, and specialty materials. The analysis considers battery production volumes, nickel intensity by battery chemistry, electroplating activity, catalyst consumption, industrial production levels, product dosage or loading requirements, replacement cycles, capacity additions, and technological changes to estimate annual consumption across key markets.
04
Revenue Layer
How is market revenue generated?
Market revenue is generated through the production and sale of nickel sulfate, nickel oxide, nickel hydroxide, nickel chloride, and other nickel compounds across battery, electroplating, catalyst, alloy, ceramics, electronics, and specialty applications. Revenue growth is supported by battery manufacturing expansion, electric vehicle adoption, industrial metal finishing, and increasing demand for high-purity nickel compounds. Pricing and revenue realization are influenced by nickel feedstock costs, energy and processing expenses, product purity, chemical specifications, production capacity, technology, recycling inputs, customer requirements, logistics, regulatory standards, and regional supply-demand conditions.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Cross-segmentation
The assessment provides detailed cross-segmentation of the nickel chemicals market across product, grade/purity, and application. The analysis covers nickel sulfate, nickel oxide, nickel hydroxide, nickel chloride, and other nickel chemicals, with further assessment across standard and high-purity grades and applications including batteries, electroplating & surface treatment, stainless steel & specialty alloys, catalysts, ceramics, glass & pigments, and other specialty applications.
Enables identification of high-growth opportunities across specific product-grade-application combinations. Supports product development, production planning, raw material sourcing, customer targeting, and market-entry strategies by highlighting purity requirements, application-specific specifications, consumption intensity, demand trends, and growth potential.
Opportunity Assessment
Detailed evaluation of growth opportunities arising from expanding battery manufacturing, electric vehicle adoption, increasing demand for electroplating and surface treatment, growth in specialty alloys and catalysts, and rising requirements for high-purity nickel compounds. The assessment also covers opportunities associated with nickel recycling, secondary raw materials, battery-grade chemical production, advanced processing technologies, capacity expansion, and geographic supply-chain development.
Enables identification of attractive opportunities across the nickel chemicals value chain, from nickel feedstock processing and chemical conversion to downstream battery and industrial applications. Supports decisions related to capacity expansion, high-purity product development, recycling investments, regional market entry, supply-chain integration, and strategic partnerships by highlighting high-potential applications and evolving customer requirements.
Competitive Benchmarking
Comparative assessment of leading nickel chemical manufacturers and integrated nickel producers based on product portfolios, purity grades, production capacity, manufacturing footprint, raw material integration, application coverage, geographic presence, R&D capabilities, recycling initiatives, technical expertise, distribution networks, and strategic investments. The benchmarking evaluates supply capabilities, product quality, customization, production efficiency, sustainability initiatives, and downstream market positioning.
Supports benchmarking against key nickel chemical suppliers while identifying opportunities to strengthen product differentiation, purity, production efficiency, supply reliability, recycling capabilities, application coverage, and geographic reach. The analysis assists strategic decisions concerning product development, capacity expansion, vertical integration, regional distribution, customer partnerships, portfolio diversification, and long-term competitive positioning.
About the Author(s)
Inorganic Chemicals Research Team
Bulk Chemicals · Inorganic ChemicalsThis report was authored by the inorganic chemicals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the inorganic chemicals segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst


Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


