
- Home
- »
- Renewable Energy
- »
-
Offshore Wind Turbine Market Size Report, 2026-2033GVR Report cover

Offshore Wind Turbine Market (2026 - 2033)
Size, Share & Trends Analysis Report, By Capacity (Up To 3 MW, 3 MW-5 MW, Above 5 MW), By Water Depth (Shallow Water (<30 M Depth), Transitional Water (30-60 M Depth), Deepwater), By Region, And Segment Forecasts
Market Size, 2025
$22.1BMarket Estimate, 2026
$24.7BMarket Forecast, 2033
$48.6BCAGR, 2026–2033
10.2%Offshore Wind Turbine Market Summary
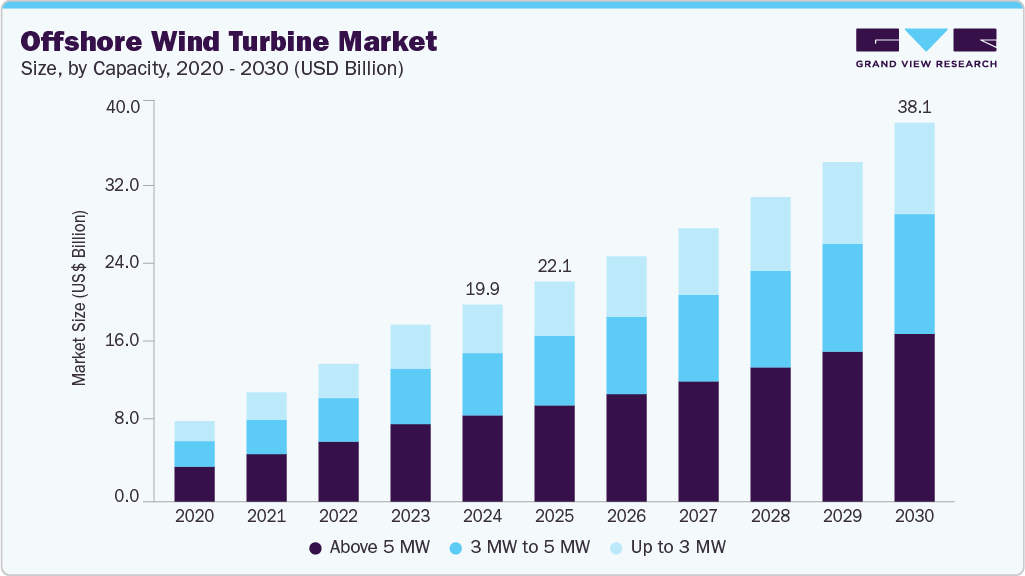
The global offshore wind turbine market size was valued at USD 22.1 billion in 2025 and is projected to grow from USD 24.7 billion in 2026 to USD 48.6 billion by 2033, at a CAGR of 10.2% from 2026 to 2033. Europe dominated the market, accounting for a revenue share of 47.7% in 2025. The rising interest in reducing the global carbon footprint and increasing demand for renewable energy are the key factors driving the industry growth.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By capacity: Above 5 MW segment led the market with the largest revenue share of 78.9% in 2025.
- By water depth: Shallow water (<30M depth) segment led the market with the largest revenue share of 58.4% in 2025.
Regional Highlights
- Largest regional market: Europe (47.7% revenue share, 2025)
- By country: The UK held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 22.1 Billion
- Estimated market size in 2026: USD 24.7 Billion
- Projected market size by 2033: USD 48.6 Billion
- CAGR (2026-2033): 10.2%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Growing efforts by government agencies and electrical companies to reduce carbon emissions are major market drivers driving market expansion. A key trend in the offshore wind turbine industry is the growing expansion of the broader industrial sector, driven by increasing demand for clean, cost-effective, and reliable electricity. Offshore wind turbines play a vital role in meeting this demand, offering a sustainable energy solution for large communities. As technology advances and costs continue to decline, offshore wind energy is becoming more accessible and economically viable.The rise in continued research, development, demonstration, and deployment of technologies to eliminate impediments to the widespread installation of turbines is likely to drive the offshore wind turbine market growth during the forecast period. According to a report by the U.S. Department of Energy in June 2024, the National Offshore Wind Research and Development Consortium (NOWRDC) has announced Solicitation 4.0, a USD 10.6 million funding opportunity to advance floating offshore wind technology in the U.S. Advances in turbine design, materials, and manufacturing processes have led to the development of more efficient and reliable turbines. This includes larger turbines with more power, which reduce the cost per megawatt of energy produced.
 To learn more about this report, Download Free Sample Report
The increase in the adoption of renewable energy across several emerging countries in regions such as South America, Asia, and Africa is expected to drive market growth in the coming years. Offshore wind turbines are gaining popularity due to their high energy production potential and ability to make a significant contribution to global efforts to reduce greenhouse gas emissions. For instance, according to a report by the Global Wind Energy Council in 2025, the world added a record 117 gigawatts of new wind power capacity, showing strong momentum in clean energy investment. This growth highlights wind power’s increasing role in meeting global energy demand and climate goals.
Market Dynamics
The offshore wind turbine market is driven by increasing investments in renewable energy infrastructure, rising demand for clean power generation, and supportive government policies promoting decarbonization and energy transition. Growing offshore wind project development, technological advancements in larger-capacity turbines, and declining installation costs are further accelerating market growth. However, high capital requirements, complex installation processes, supply chain constraints, and challenges related to grid connectivity act as key market restraints. Opportunities are emerging from floating offshore wind technology, expansion into deeper waters, and increasing adoption across new coastal regions.
The offshore wind turbine market is primarily driven by increasing investments in renewable energy projects as countries accelerate efforts to reduce carbon emissions and diversify their energy mix. Governments worldwide are setting ambitious offshore wind capacity targets, supported by favorable policies, auctions, subsidies, and long-term power purchase agreements. The ability of offshore wind farms to utilize stronger and more consistent ocean winds, along with advancements in high-capacity turbines, floating platforms, and installation technologies, is encouraging large-scale project development. Additionally, growing electricity demand and the need for reliable low-carbon power sources are further driving investments in offshore wind infrastructure.
The growing focus on large-scale offshore wind development is driving demand for advanced high-capacity offshore wind turbines. For instance, Vestas’ V236-15.0 MW offshore wind turbine, introduced to the market as one of the first 15 MW-class turbines, has secured more than 12 GW of order intake since its launch. Featuring 115.5-meter blades and a capacity factor exceeding 60%, the turbine is designed to maximize annual energy generation while reducing the number of turbines required for offshore wind projects. The commercialization of such next-generation turbines highlights the industry's shift toward larger and more efficient offshore wind systems to support the expansion of utility-scale offshore wind farms.
The offshore wind turbine market faces significant restraints due to high upfront capital investments, complex installation processes, and challenging marine operating conditions. Offshore wind projects require substantial expenditure for turbine foundations, subsea cables, specialized installation vessels, and offshore maintenance infrastructure, making project development more expensive compared with onshore wind. Factors such as supply chain constraints, limited availability of installation vessels, harsh weather conditions, and complex permitting procedures can lead to project delays and cost overruns. These challenges can impact project feasibility and slow offshore wind deployment, particularly in emerging markets.
The offshore wind turbine market is witnessing emerging opportunities from the development and commercialization of floating offshore wind technology, which enables wind farm deployment in deeper waters beyond the limitations of fixed-bottom foundations. Floating wind platforms allow access to stronger and more consistent wind resources, expanding offshore wind potential into regions with limited shallow coastal areas. Increasing investments from governments, utilities, and technology providers in pilot and commercial-scale floating wind projects are creating opportunities for turbine manufacturers, offshore engineering companies, and component suppliers. Advancements in floating foundations, mooring systems, and larger-capacity turbines are expected to improve cost competitiveness and accelerate adoption.
Market Concentration & Characteristics
The market growth stage is high, and the pace of the market growth is accelerating. The offshore wind turbine market is characterized by high innovation due to installation and maintenance innovations, technological advancements, government policies, and investment support. For Instance, in December 2022, Vestas installed its V236-15.0 MW prototype wind turbine at the Østerild National Test Centre in Denmark, marking a significant milestone by producing its first kilowatt-hour of electricity. This achievement initiates an extensive testing and verification program to ensure reliability before commencing full-scale production and commercial deployment.
The market is also characterized by the leading players' moderate to high levels of mergers and acquisition activity. This is due to increasing demand for renewable energy sources, market consolidation, and global expansion of the product. According to a report by the Institute for Mergers, Acquisitions & Alliances in November 2024, Brookfield Asset Management acquired a 12.45% stake in four of Ørsted's offshore wind farms in the UK for about $2.28 billion. This move marks Brookfield's entry into the UK offshore wind market and supports its focus on renewable energy investments.
 To learn more about this report, Download Free Sample Report
The global market is also subject to high impact of regulations, due to its multiple layers of regulatory approvals such as federal, state and local regulations to govern the development and operations. For instance, according to a report by Harbinger Land on January 2025, following laws like the National Environmental Policy Act (NEPA) and working with local authorities is crucial. This helps companies get project approvals faster and avoid problems with environmental regulations.
There are a limited number of direct product substitutes for offshore wind turbine. Limited number of direct energy substitute are there for the wind turbine market. While other renewable energy sources like onshore wind, solar, and wave energy are not a direct substitute for the specific advantages offered by offshore wind turbines.
The end use concentration for the offshore wind turbine market is relatively low. Offshore wind turbines are primarily used by utility companies and independent power producers to generate electricity for the grid. This electricity is served to a wide range of end-users, including residential, commercial, and industrial consumers.
Analyst Perspective
The offshore wind turbine market is transitioning toward larger-capacity turbines, with manufacturers increasingly focusing on 10 MW+ platforms to improve project economics and reduce the number of turbines required per offshore wind farm. The market is witnessing strong growth momentum due to rising government commitments toward renewable energy expansion and increasing investments in utility-scale offshore wind projects. However, high capital costs, supply chain constraints, and project financing challenges continue to impact deployment timelines and profitability. A key emerging trend is the rapid adoption of floating offshore wind technology, which is enabling development in deeper waters and expanding offshore wind potential beyond conventional fixed-bottom installations.
Capacity Insights
Based on capacity, the above 5 MW segment led the market with the largest revenue share of 78.9% in 2025 and is estimated to grow at the fastest CAGR over the forecast period. Higher power rating turbines are in high demand to make offshore wind power generation more energy-efficient and economically sustainable. According to offshore WIND.biz, December 2024, Offshore wind turbines are getting bigger, allowing each one to produce more electricity. However, some Asian manufacturers are planning even larger turbines, potentially up to 22 MW. This trend helps generate more power from fewer turbines. Large-scale offshore wind projects benefit from economies of scale, making them more cost-effective in terms of power generation per megawatt-hour (MWh).
3 MW to 5 MW is another significant application that is expected to grow significantly over the forecast period. The expansion of offshore wind projects with capacities ranging from 3 MW to 5 MW represents a key component of the offshore wind market. Offshore wind projects ranging from 3 MW to 5 MW provide a good blend of scale and flexibility. They are adaptable to diverse wind conditions and water depths, making them useful for a wide range of applications. For instance, according to the U.S. Department of Energy's August 2024 report, the average capacity of new wind turbines in the U.S. grew to 3.4 MW in 2023, continuing a long-term trend of increasing capacity. More of the newly installed turbines are now 3.5 MW or larger in size, which allows wind farms to produce the same amount of power with fewer turbines. Moreover, the widespread use and standardization of turbines of this size facilitate production, installation, and maintenance, reducing overall project risk.
Water Depth Insights
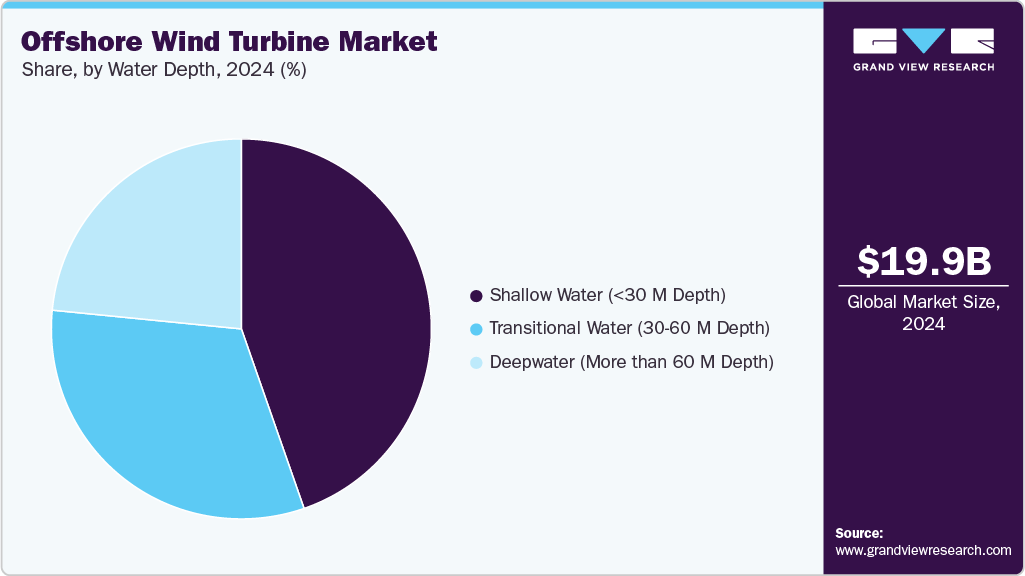
Based on water depth, the shallow water (<30M depth) segment led the market with the largest revenue share of 58.4% in 2025 and is expected to grow at the fastest CAGR over the forecast period. The presence of considerably less demanding weather and ease of maintenance makes it a suitable choice for the establishment of offshore wind farms. Moreover, shallow water installations are less expensive than deep-water any other installations, making them a cost-effective choice for large population centers seeking to source more of their power from clean sources. For instance, according to a report by SceinceDirecrt, research indicates that foundation costs for water depths of 40-50 m can be almost twice as high as those for depths of 10-20 m. The market is predicted to expand internationally as investments in renewable energy increase. This factor is expected to boost the shallow water installation market.
 To learn more about this report, Download Free Sample Report
The transitional water (30-60 M Depth) segment is anticipated to experience significant growth in the offshore wind turbine industry. This is driven by access to stronger, more consistent winds; in addition, advancements in foundation technology, such as the increasing use of jacket foundations and innovative suction bucket jackets in projects like East Anglia ONE and Borkum Riffgrund, are enabling economically viable deployments in these depths.
Regional Insights
North America has experienced a gradual growth in the offshore wind turbine industry. The market is driven by the ambitious renewable energy targets set by several states and the federal government of North America. For instance, according to an article published by the Department of Environmental Conservation, New York State aims to get 70% of its electricity from renewables by 2030 and be completely carbon-free by 2040. A key part of this plan is developing 9,000 MW of offshore wind by 2035, which can power up to 6 million homes. In addition, some government policies and growing awareness regarding sustainability are also increasing the demand for the offshore wind turbine market.
U.S. Offshore Wind Turbine Market Trends
The U.S. dominates the North America Offshore Wind Turbine and is expected to grow significantly over the forecast period. The increasing demand for dependable and scalable energy sources in the U.S. is driving the growth of the offshore wind turbine industry. For instance, according to an article by ENERGY CURATED in July 2024, The U.S. offshore wind industry is projected to see substantial investment, with estimates reaching $65 billion by 2030. This growth is expected to create around 56,000 jobs in the United States. This initiative is expected to significantly affect the economy.
Europe Offshore Wind Turbine Market Trends
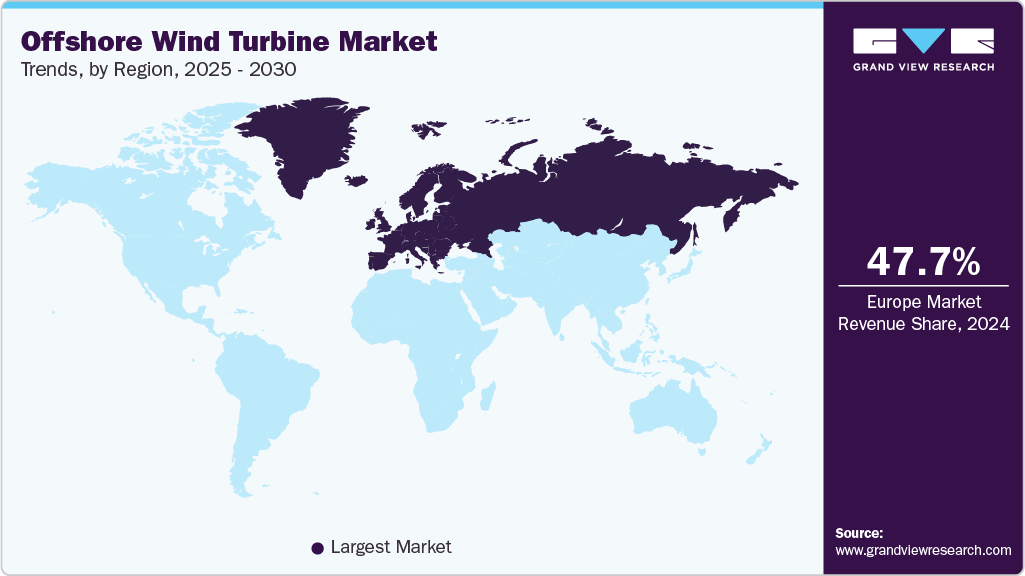
Europe dominated the offshore wind turbine market with the largest revenue share of 47.7% in 2025. Governments across Europe are providing various subsidies, grants and tax breaks to support the development of offshore wind projects. Moreover, the European Union (EU) has set ambitious renewable energy targets, aiming to become climate-neutral by 2050. This is expected to drive the installation of offshore wind turbines across the region.
 To learn more about this report, Download Free Sample Report
The offshore wind turbine market in UK held the largest share in the Europe region in 2025. The demand for the offshore wind turbine industry is rising due to various government policies, incentives, and investment support. For instance, according to an article by the UK Energy Research Centre in April 2024, the UK has implemented the Contracts for Difference (CfD) scheme, providing long-term revenue certainty for offshore wind projects. This mechanism has attracted a broader range of investors by reducing financial risks, leading to increased investment in the sector. In addition, energy security and economic growth due to the offshore wind turbine market are increasing the demand for the market.
Asia Pacific Offshore Wind Turbine Market Trends
Asia Pacific is expected to experience the fastest CAGR over the forecast period. The offshore wind turbine market in the region is experiencing significant growth due to several key drivers. With an increasing focus on sustainable energy sources around the world, offshore wind power has emerged as a lucrative alternative for a variety of countries, including China, India, and Japan, driving regional market growth.
The China Offshore Wind Turbine market held a substantial market share in 2024. The increasing demand for coastal energy and geographical advantages are driving the country's offshore wind turbine market. According to an article published by ScienceDirect in October 2022, with an extensive coastline exceeding 18,000 km and over 6,000 islands, China possesses significant offshore wind resources, estimated at 758 GW, approximately three times its onshore wind potential. Developing offshore wind farms in coastal areas alleviates the pressure on long-distance power transmission projects from the resource-rich western regions.
Key Offshore Wind Turbine Company Insights
The offshore wind turbine market is highly competitive, with several key players dominating the landscape. Major companies include General Electric, Equinor ASA, Iberdrola, S.A., Mitsubishi Heavy Industries, Ltd, and Goldwind. The offshore wind turbine market is categorized by a competitive landscape with several key players driving innovation and market growth. Major companies in this sector are investing heavily in research and development to enhance the performance, cost-effectiveness, and sustainability of their products.
-
GE Vernova provides offshore wind turbines, including the Haliade-X, designed for high energy production in strong offshore winds, contributing to the growth of offshore wind power globally. Their technology focuses on reliability and efficiency to lower the cost of offshore wind energy for customers.
-
Equinor has been in the offshore wind industry for over five decades and intends to be a global offshore wind energy major. They have wind farms in Germany and UK that power over one million European homes, and the Dogger Bank offshore wind farm will power 6 million British homes..
Key Offshore Wind Turbine Companies
The following key companies have been profiled for this study on the offshore wind turbine market.
-
General Electric Company
-
Equinor ASA
-
Iberdrola, S.A.
-
Mitsubishi Heavy Industries, Ltd
-
Goldwind
-
Naval Group
-
Nordex SE
-
Siemens
-
ABB
-
MODEC, Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Siemens, Goldwind, Vestas, GE Vernova, Envision Group, Nordex SE)
- Focus on developing high-capacity offshore wind turbines (10 MW+ platforms) to improve energy output and reduce project costs.
- Expand global presence through partnerships with offshore wind developers, utilities, and governments.
- Invest in R&D for advanced turbine designs, digital monitoring, predictive maintenance, and improved reliability.
- Strengthen supply chains and manufacturing capabilities to support large-scale offshore wind deployment.
- Strong brand recognition and extensive offshore wind project experience.
- Proven turbine technologies with large installed bases and operational track records.
- Advanced capabilities in developing large-capacity turbines suitable for utility-scale projects.
- Established relationships with global developers, EPC contractors, and utilities.
- Strong after-sales service networks and lifecycle support capabilities.
- High development and manufacturing costs associated with next-generation offshore turbines.
- Exposure to project delays, supply chain disruptions, and rising raw material costs.
- Intense competition and pricing pressure, particularly from Asian manufacturers.
- Dependence on large offshore wind projects, which are sensitive to regulatory and financing uncertainties.
Emerging Players (Ming Yang Smart Energy Group Co., Ltd., Shanghai SMEC Enterprise Co., Ltd., DEC, Doosan Enerbility)
- Target regional offshore wind markets through localized manufacturing and government-supported projects.
- Develop cost-competitive turbine solutions to compete with global suppliers.
- Expand offshore capabilities through partnerships, technology collaborations, and domestic project participation.
- Focus on improving turbine capacity and adapting designs to regional wind conditions.
- Competitive pricing due to lower manufacturing costs and regional supply chain advantages.
- Strong presence in high-growth offshore wind markets, particularly Asia Pacific.
- Ability to customize turbine solutions for local project requirements.
- Support from domestic renewable energy policies and infrastructure programs.
- Limited global offshore project references compared with leading players.
- Lower brand recognition in mature offshore wind markets such as Europe.
- Smaller international service and maintenance networks.
- Challenges in scaling manufacturing capacity and meeting global certification requirements.
Recent Developments
-
In May 2025, DEME, a clean energy company, acquired Norwegian offshore wind contractor Havfram for USD 1,028.9, including all of Havfram's shares. This acquisition is expected to help DEME expand its reach in the offshore wind energy market and improve its ability to install turbines and foundations.
-
In March 2025, Italian engineering company Saipem partnered with the Divento consortium, which includes Plenitude, CDP, and Copenhagen Infrastructure Partners. Together, they plan to use Saipem’s STAR 1 floating wind technology for offshore wind projects in Sicily and Sardinia to generate 1.6 terawatt-hours of electricity per year.
-
In October 2024, Skyborn Renewables, backed by Global Infrastructure Partners (GIP), partnered with Ørsted on the US's South Fork Wind and Revolution Wind offshore wind farms. This partnership was formed after GIP acquired Eversource Energy's 50% stake in these projects.
Offshore Wind Turbine Market Report Scope
Report Attribute
Details
Market Definition
The offshore wind turbine market includes revenue generated from the sales of offshore wind turbines used for electricity generation across different turbine capacity ranges and water depth installations.
Market size in 2025
USD 22.1 billion
Estimated market size in 2026
USD 24.7 billion
Projected market size by 2033
USD 48.6 billion
Growth rate
CAGR of 10.2% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD Million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Capacity, Water depth, Region
Regional scope
North America, Europe, Asia Pacific, Latin America, Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; France; UK; Italy; Spain; The Netherlands; Denmark; China; India; Japan; South Korea; Indonesia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE
Key companies profiled
Siemens, Goldwind, Ming Yang Smart Energy Group Co., Ltd., Vestas, GE Vernova, Envision Group, Shanghai SMEC Enterprise Co., Ltd., DEC, Nordex SE, Doosan Enerbility
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Offshore Wind Turbine Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global offshore wind turbine market report based on capacity, water depth, region.
 To learn more about this report, Download Free Sample Report
-
Capacity Outlook (Revenue, USD Billion, 2021 - 2033)
-
Up to 3 MW
-
3 MW to 5 MW
-
Above 5 MW
-
-
Water Depth Outlook (Revenue, USD Billion, 2021 - 2033)
-
Shallow Water (<30 M Depth)
-
Transitional Water (30-60 M Depth)
-
Deepwater (More than 60 M Depth)
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Spain
-
Italy
-
The Netherlands
-
Denmark
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Indonesia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
UAE
-
Saudi Arabia
-
-
Research Methodology
The offshore wind turbine market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each offshore wind turbine segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Capacity
Revenue capture definition
Up to 3 MW
Up to 3 MW Offshore Wind Turbines are offshore wind turbine systems with rated power capacity of up to 3 MW designed for electricity generation in marine environments. Revenue is generated from the sales of low-capacity offshore wind turbines used in small-scale offshore wind projects, demonstration installations, and near-shore applications.
3 MW to 5 MW
3 MW to 5 MW Offshore Wind Turbines are offshore wind turbine systems with rated power capacity ranging from 3 MW to 5 MW, designed to deliver higher energy output for commercial offshore wind farms. Revenue is generated from the sales of medium-capacity offshore wind turbines used across utility-scale offshore wind projects in shallow and transitional waters.
Above 5 MW
Above 5 MW Offshore Wind Turbines are high-capacity offshore wind turbine systems with rated power exceeding 5 MW, developed for large-scale offshore wind power generation. Revenue is generated from the sales of advanced high-capacity turbines used in utility-scale offshore wind farms, including deepwater and large offshore installations.
Segment - Water Depth
Revenue capture definition
Shallow Water (<30 M Depth)
Shallow Water Offshore Wind Turbines (<30 M Depth) are offshore wind turbine systems installed in coastal areas with water depths below 30 meters, typically using fixed-bottom foundations such as monopiles or gravity-based structures. Revenue is generated from the sales of offshore wind turbines deployed in near-shore projects with relatively simpler installation requirements.
Transitional Water (30-60 M Depth)
Transitional Water Offshore Wind Turbines (30-60 M Depth) are offshore wind turbine systems installed in moderate water depths ranging from 30 to 60 meters, requiring advanced foundation technologies such as jackets or optimized fixed-bottom structures. Revenue is generated from the sales of offshore wind turbines used in projects requiring enhanced structural designs and deeper offshore deployment.
Deepwater (More than 60 M Depth)
Deepwater Offshore Wind Turbines (>60 M Depth) are offshore wind turbine systems installed in water depths exceeding 60 meters, primarily utilizing floating foundations or advanced offshore support structures. Revenue is generated from the sales of offshore wind turbines deployed in deepwater offshore wind farms, enabling access to high-quality wind resources in areas farther from shore.
Estimation Model
Layer Name
Key Question
Description
Offshore Wind Turbine Demand Layer
What drives the demand for offshore wind turbines?
Identify key demand drivers for offshore wind turbines, including renewable energy targets, decarbonization initiatives, offshore wind capacity expansion, electricity demand growth, and investments in large-scale wind projects. Assess factors such as government policies, offshore wind auctions, energy transition strategies, and grid infrastructure development that influence market demand.
Offshore Wind Turbine Capacity Layer
What capacity range of offshore wind turbines is adopted?
Analyze the adoption of offshore wind turbines across different capacity ranges, including up to 3 MW, 3 MW to 5 MW, and above 5 MW turbines. Assess capacity preferences based on project scale, energy output requirements, technological advancements, installation costs, and the increasing deployment of high-capacity turbines for utility-scale offshore wind farms.
Offshore Wind Turbine Water Depth Layer
Where are offshore wind turbines deployed?
Evaluate offshore wind turbine installations across different water depth categories, including shallow water (<30 m), transitional water (30-60 m), and deepwater (>60 m) applications. Assess deployment trends based on seabed conditions, foundation technologies, offshore accessibility, floating wind adoption, and availability of suitable coastal areas.
Revenue Layer
How is market revenue generated?
Market revenue is quantified through the sales of offshore wind turbine systems across different capacity ranges and water depth applications. The overall market value is determined by turbine installations, offshore wind project investments, replacement demand, technological upgrades, and adoption across utility-scale renewable energy projects.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Landscape Assessment
Benchmarked key offshore wind turbine manufacturers based on turbine capacity portfolio, offshore technology capabilities, installed project base, manufacturing capabilities, geographic presence, supply chain strength, and strategic initiatives. Evaluated the competitive positioning of established and emerging players.
Supported competitor benchmarking, identification of leading offshore wind turbine suppliers, and assessment of strategic growth opportunities driven by offshore wind expansion and renewable energy investments.
Offshore Wind Water Depth Assessment
Assessed offshore wind turbine deployment across shallow water (<30 m), transitional water (30–60 m), and deepwater (>60 m) applications. Evaluated foundation technologies, floating offshore wind adoption, installation requirements, and regional deployment trends.
Enabled identification of high-growth offshore wind opportunities, understanding of technology preferences by water depth, and evaluation of market potential in emerging deepwater offshore wind regions.
Offshore Wind Turbine Technology Assessment
Analyzed offshore wind turbine solutions based on capacity ranges, including up to 3 MW, 3–5 MW, and above 5 MW turbines, along with technology advancements such as high-capacity platforms, floating wind systems, blade innovations, and digital monitoring capabilities. Evaluated technology adoption trends and project suitability.
Helped understand technology evolution, adoption of next-generation turbines, and factors influencing turbine selection for utility-scale offshore wind projects across different marine environments.
Frequently Asked Questions About This Report
The global offshore wind turbine market size was estimated at USD 22.1 billion in 2025 and is expected to reach USD 24.7 billion in 2026.
The global offshore wind turbine market is expected to grow at a CAGR of 10.2% from 2026 to 2033 to reach USD 48.6 billion by 2033.
The Europe region dominated the offshore wind turbine market with a revenue share of 47.7% in 2025.
UK dominated the Europe region market with a revenue share of 32.5% in 2025.
Asia Pacific is anticipated to register the fastest CAGR of 10.4% over the forecast period.
Based on capacity, the above 5 MW segment accounted for largest revenue share of 78.9% in 2025.
Based on water depth, the shallow water (<30M depth) segment accounted for largest revenue share of 58.4% in 2025.
The key players operating in the offshore wind turbine market are Siemens, Goldwind, Vestas, GE Vernova, Envision Group, Nordex SE, Ming Yang Smart Energy Group Co., Ltd., Shanghai SMEC Enterprise Co., Ltd., DEC, Doosan Enerbility, and others.
The offshore wind turbine market is driven by increasing renewable energy investments, government decarbonization targets, expansion of offshore wind projects, advancements in high-capacity turbine technology, and growing adoption of floating offshore wind solutions.
About the Author(s)
Renewable Energy Research Team
Energy & Power · Renewable EnergyThis report was authored by the renewable energy research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the renewable energy segment of the energy & power industry. All findings are based on proprietary energy & power databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


