
- Home
- »
- Conventional Energy
- »
-
Oil & Gas Automation & Instrumentation Market Report, 2033GVR Report cover

Oil & Gas Automation & Instrumentation Market (2026 - 2033)
Size, Share & Trends Analysis Report By Technology (Distributed Control Systems, Supervisory Control and Data Acquisition, Programmable Logic Controllers), By Operation, By Region, And Segment Forecasts
Market Size, 2025
$19.8BMarket Estimate, 2026
$21.0BMarket Forecast, 2033
$35.7BCAGR, 2026–2033
7.9%Oil & Gas Automation & Instrumentation Market Summary
The global oil & gas automation & instrumentation market was valued at USD 19.8 billion in 2025 and is projected to grow from USD 21.0 billion in 2026 to USD 35.7 billion in 2033, at a CAGR of 7.9% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 36.0% in 2025. The oil & gas automation & instrumentation market is witnessing steady growth, driven by the industry’s increasing focus on maximizing production efficiency, improving operational safety, and reducing operating costs amid volatile energy prices.
Key Market Trends & Insights
- By technology: The distributed control systems (DCS) segment held the largest market share of around 31.0% in 2025.
- By operation: The downstream segment held the largest market share of around 41.0% in 2025.
Regional Insights
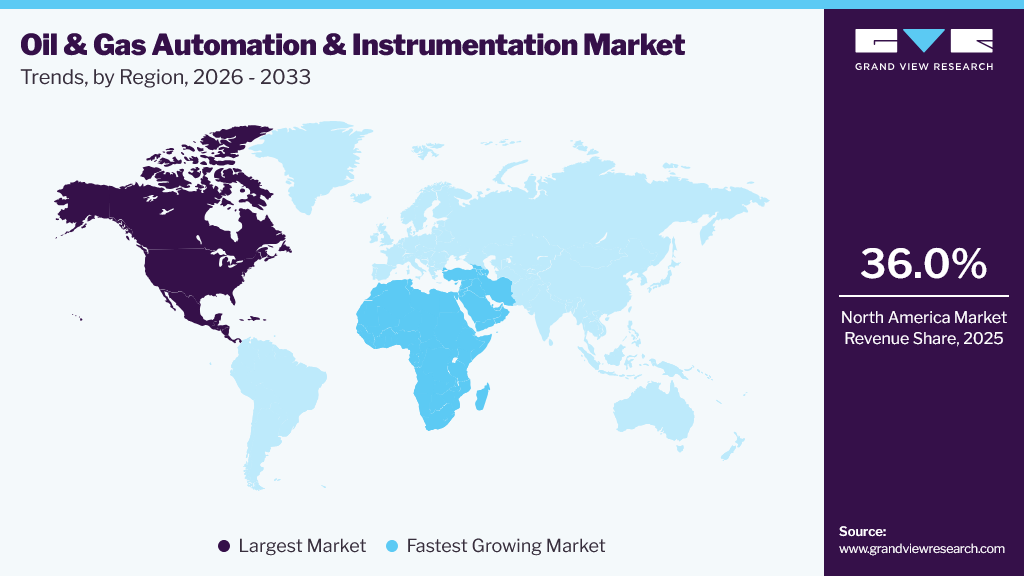
- Largest regional market: North America (36.0% revenue share, 2025)
- Fastest-growing regional market: Middle East and Africa (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 19.8 Billion
- Estimated market size in 2026: USD 21.0 Billion
- Projected market size by 2033: USD 35.7 Billion
- CAGR (2026-2033): 7.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The oil and gas companies are accelerating investments in automation and advanced instrumentation solutions to optimize exploration, production, transportation, storage, and refining operations through real-time monitoring, process control, and data-driven decision-making. The growing need to minimize unplanned downtime, enhance asset reliability, and comply with stringent environmental and safety regulations is further strengthening demand for automated control systems and intelligent field instruments.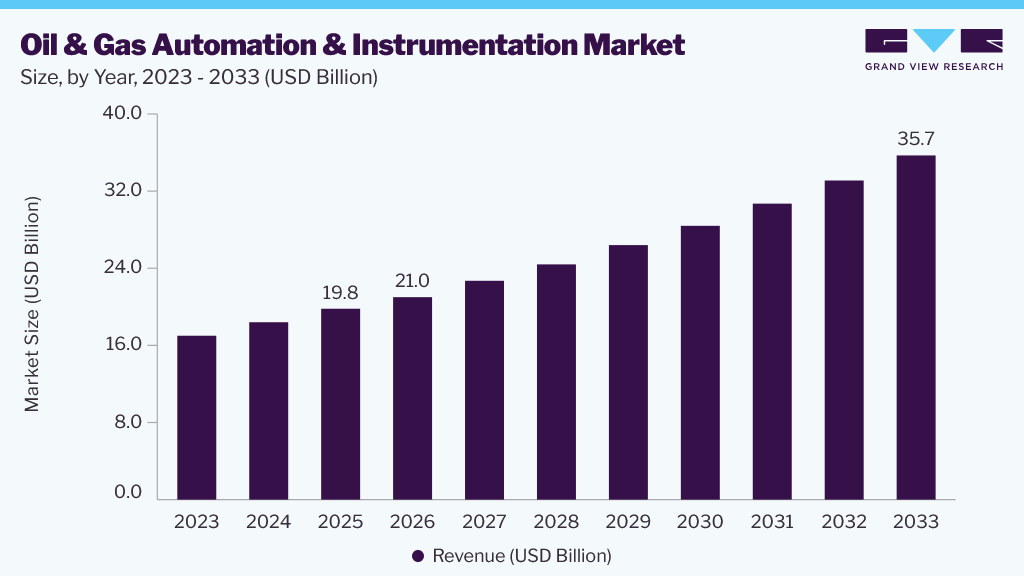 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Market demand is also fueled by the rising global consumption of crude oil and petroleum products, increasing upstream exploration and production (E&P) activities, and sustained investments in pipeline infrastructure and refinery modernization. Operators are replacing conventional manual processes with integrated automation platforms, distributed control systems (DCS), supervisory control and data acquisition (SCADA) systems, programmable logic controllers (PLCs), industrial sensors, and advanced analytical instruments to improve productivity while reducing human intervention and operational risks.
Furthermore, the ongoing digital transformation of the oil and gas industry is creating significant opportunities for market expansion. The adoption of Industrial Internet of Things (IIoT), artificial intelligence (AI), machine learning, digital twins, predictive maintenance, cloud-based monitoring, and advanced analytics is enabling operators to achieve greater process optimization and asset performance. Growing investments in shale oil and gas production, offshore developments, LNG infrastructure, and the modernization of aging oilfields are expected to sustain strong demand for automation and instrumentation solutions throughout the forecast period.
Analyst Perspective
The global oil and gas automation and instrumentation market is expected to grow steadily, driven by the increasing emphasis on operational efficiency, safety, and real-time process control across upstream, midstream, and downstream operations. The growing use of digital technologies and automation in exploration and production is adding to the growth of market demand. Furthermore, the modernization of aging oilfield equipment and the expansion of shale gas operations have opened new avenues for instrumentation. However, the high cost of implementation and integration issues with existing systems may hinder market growth to some degree.
Technology Insights
The distributed control system (DCS) segment held the largest market share, at around 31.0%, in 2025. DCS is widely deployed to manage continuous and complex processes across oil and gas facilities. These systems enable centralized monitoring and control of multiple operations, improving process efficiency, operational reliability, and overall plant performance. In addition, DCS enhances process visualization, streamlines workflow management, and reduces manual intervention. Ongoing modernization and expansion of existing oil and gas facilities are expected to support segment growth, driven by the increasing need for dependable process control in large-scale operations. DCS continues to maintain its market leadership owing to its proven reliability, scalability, and ability to operate effectively in mission-critical industrial environments.
The industrial internet of things (IIoT) solutions segment is expected to register the fastest growth over the forecast period. The segment is witnessing strong growth as oil and gas operators transition toward connected, data-driven, and intelligent operations. IIoT solutions enable seamless integration of field devices with control systems, facilitating real-time monitoring, remote asset management, and informed decision-making. Companies are increasingly leveraging IIoT for predictive maintenance, asset tracking, and performance optimization, helping reduce unplanned downtime and operating costs. Rising deployment of smart sensors, cloud-based platforms, and remote monitoring technologies is expected to accelerate adoption further. As digital transformation and process automation become strategic priorities across the oil and gas industry, demand for IIoT-based automation solutions is projected to grow steadily throughout the forecast period.
Operation Insights
Downstream operations accounted for the largest market share in the oil & gas automation & instrumentation market in 2025. Downstream operations, including refining, petrochemical processing, and fuel distribution, are highly dependent on automation and instrumentation to manage continuous, complex, and safety-critical processes. Refineries require extensive deployment of distributed control systems (DCS), programmable logic controllers (PLCs), SCADA systems, process analyzers, flow meters, and pressure transmitters to optimize production, improve energy efficiency, and ensure compliance with stringent environmental and safety regulations. In addition, with the ongoing refinery modernization and capacity expansion projects, the demand for automation solutions across downstream facilities is expected to remain buoyant in the coming years. The trend is supported by continued investments from leading automation providers. For example, in October 2024, Honeywell introduced its Experion® Operations Assistant, an AI-enabled digital solution designed to enhance operator productivity and streamline operations at refineries and process plants. Such developments highlight the industry’s increasing focus on intelligent automation, therefore reinforcing the dominant position of the segment.
The upstream segment is expected to register the fastest growth in the oil & gas automation & instrumentation market over the forecast period. Upstream operations, including exploration, drilling, and production activities, require continuous monitoring of drilling conditions, reservoir behavior, well integrity, and production flow rates to ensure safe and efficient operations. Consequently, automation and instrumentation solutions are increasingly deployed to enhance process control, improve operational efficiency, and strengthen safety across complex field environments. These technologies enable real-time monitoring, remote operation, and precise control of critical processes, helping operators minimize risks in harsh, high-pressure, and geographically remote locations. Rising investments in exploration and production (E&P), increasing development of offshore and unconventional oil and gas resources, and growing efforts to maximize recovery from mature oilfields are expected to accelerate demand for advanced automation solutions.
Regional Insights
North America dominated the oil & gas automation & instrumentation market, accounting for approximately 36.0% of global revenue in 2025. The region’s dominance is attributed to a well-established oil and gas industry, widespread adoption of advanced automation technologies, and the strong presence of leading automation and industrial software providers. Significant investments in shale oil and gas production, offshore developments, and pipeline infrastructure continue to drive demand for sophisticated control systems, field instrumentation, and real-time monitoring solutions. Oil and gas operators across the region are increasingly investing in automation to improve operational efficiency, strengthen safety, minimize unplanned downtime, and optimize production performance. Furthermore, the continuous modernization of aging oilfield infrastructure, the growing deployment of Industrial Internet of Things (IIoT) technologies, and the expansion of digital oilfield initiatives are expected to reinforce North America's leadership in the global oil & gas automation & instrumentation market throughout the forecast period.
 To learn more about this report, Download Free Sample Report
Middle East and Africa Oil & Gas Automation & Instrumentation Market Trends
The Middle East & Africa oil & gas automation & instrumentation market is expected to register the fastest growth during the forecast period. The region is home to some of the world's largest crude oil and natural gas reserves, with national oil companies and international operators increasingly investing in automation technologies to improve production efficiency, operational reliability, and asset performance. Digital transformation initiatives across upstream, midstream, and downstream operations, coupled with the modernization of refineries, gas processing facilities, and pipeline infrastructure, are accelerating the adoption of advanced automation and instrumentation solutions. The growing emphasis on reducing operational downtime, enhancing workplace safety, and optimizing processes through real-time monitoring and intelligent control systems is further supporting market growth. Additionally, the region's continued dependence on hydrocarbon exports is expected to sustain long-term investments in automation technologies. For instance, in October 2025, Yokogawa Electric Corporation and Aramco successfully commissioned multiple autonomous control AI agents at the Fadhili Gas Plant in Saudi Arabia, enabling real-time optimization of acid gas removal operations and reducing energy and chemical consumption, thereby demonstrating the growing adoption of AI-driven process automation across the region.
Key Oil & Gas Automation & Instrumentation Company Insights
The oil & gas automation & instrumentation market is characterized by the presence of global, regional, and niche solution providers competing through technological innovation, strategic partnerships, acquisitions, and product portfolio expansion. Leading companies are increasingly investing in digital automation, artificial intelligence (AI), Industrial Internet of Things (IIoT), robotics, and cloud-enabled monitoring solutions to strengthen their competitive positions and address the growing demand for intelligent oilfield operations.
Key Oil & Gas Automation & Instrumentation Companies
The following key companies have been profiled for this study on the oil & gas automation & instrumentation market.
-
ABB
-
Yokogawa Electric Corporation
-
Weatherford
-
Baker Hughes Company
-
Siemens
-
Emerson Electric Co.
-
Honeywell International Inc.
-
Schneider Electric
-
Rockwell Automation
-
Endress+Hauser
Recent Developments
-
In November 2025, Emerson, in collaboration with Interwell, introduced the world's first retrievable electric gas lift system, the Adaptive Gas Lift System (AGLS). The solution enables real-time monitoring and optimization of gas lift performance without invasive interventions, improving production efficiency, operational safety, and overall well performance in upstream oil and gas operations.
-
In October 2025, Yokogawa Electric Corporation's subsidiary, Yokogawa China, signed a Memorandum of Cooperation (MoC) with Sinopec Engineering (Group) Co., Ltd. to collaborate on engineering, procurement, and construction (EPC) projects. The partnership aims to enhance plant engineering capabilities while expanding the deployment of advanced automation, process control, and instrumentation solutions across oil and gas facilities worldwide.
Oil & Gas Automation & Instrumentation Market Report Scope
Report Attribute
Details
Market size in 2025
USD 19.8 billion
Estimated market size in 2026
USD 21.0 billion
Projected market size by 2033
USD 35.7 billion
Growth rate
CAGR of 7.9% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Technology, operation, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; China; Japan; India; Australia; South Korea; Brazil; Argentina; South Africa; Saudi Arabia; UAE
Key companies profiled
ABB; Yokogawa Electric Corporation; Weatherford; Baker Hughes Company; Siemens; Emerson Electric Co.; Honeywell International Inc.; Schneider Electric; Rockwell Automation; Endress+Hauser
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Oil & Gas Automation & Instrumentation Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends and opportunities across each sub-segment from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global oil & gas automation & instrumentation market report based on technology, operation, and region:
-
Technology Outlook (Revenue, USD Billion, 2021 - 2033)
-
Distributed Control Systems (DCS)
-
Supervisory Control and Data Acquisition (SCADA)
-
Programmable Logic Controllers (PLC)
-
Advanced Process Control (APC)
-
Safety Instrumented Systems (SIS)
-
Industrial Internet of Things (IIoT) Solutions
-
Others
-
-
Operation Outlook (Revenue, USD Billion, 2021 - 2033)
-
Upstream
-
Midstream
-
Downstream
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia
-
South Korea
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
-
Frequently Asked Questions About This Report
The global oil & gas automation & instrumentation market size was valued at USD 19.8 billion in 2025 and is estimated at USD 21.0 billion for 2026.
North America dominated with an approximately 36.0% revenue share in 2025.
The distributed control systems (DCS) segment accounted for the largest revenue share of approximately 31.0% in 2025.
Key players in the market include ABB, Yokogawa Electric Corporation, ALSTOM SA, Weatherford, Baker Hughes Company, Siemens, Emerson Electric Co., Honeywell International Inc., and others
The global oil & gas automation & instrumentation market is expected to grow at a CAGR of 7.9% from 2026 to 2033, reaching USD 35.7 billion by 2033.
About the Author(s)
Conventional Energy Research Team
Energy & Power · Conventional EnergyThis report was authored by the conventional energy research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the conventional energy segment of the energy & power industry. All findings are based on proprietary energy & power databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


