
- Home
- »
- Medical Devices
- »
-
Oncology Clinical Trials Market Size Report, 2026-2033GVR Report cover

Oncology Clinical Trials Market (2026 - 2033)
Size, Share & Trends Analysis Report By Phase Type (Phase I, Phase II, Phase III, Phase IV), By Study Design (Interventional Studies, Observational Studies), By Indication (Lung Cancer, Breast Cancer), By Region, And Segment Forecasts
Market Size, 2025
$32.5BMarket Estimate, 2026
$34.5BMarket Forecast, 2033
$58.9BCAGR, 2026–2033
7.9%Oncology Clinical Trials Market Summary
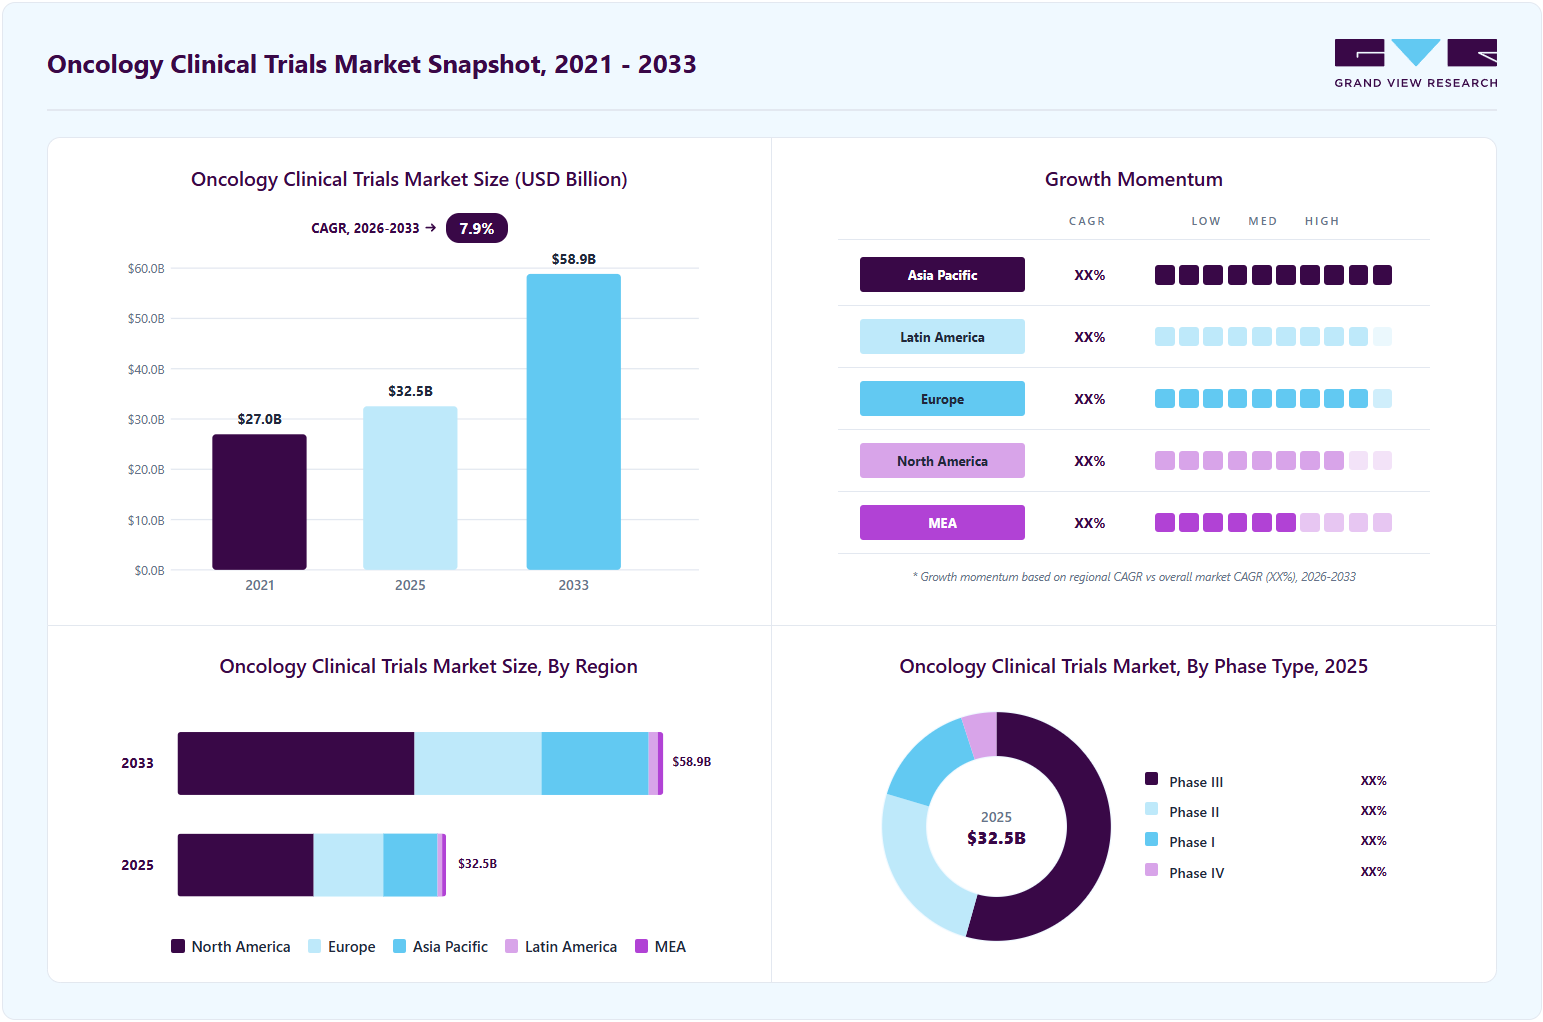
The global oncology clinical trials market size was valued at USD 32.5 billion in 2025 and is projected to grow from USD 34.5 billion in 2026 to USD 58.9 billion by 2033, at a CAGR of 7.9% from 2026 to 2033. The market in North America dominated with a revenue share of 50.6% in 2025. The market growth is primarily driven by technological advancements, rising cancer incidence, and improvements in personalized medicine and cell & gene therapies, which are enabling new approaches to developing treatments for cancer-like diseases.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By phase type: Phase III segment held the largest market share of 54.3% in 2025.
- By study design: Interventional studies segment held the largest market share in 2025.
- By indication: Lung cancer segment held the largest market share in 2025.
Regional Highlights
- Largest regional market: North America (50.6% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 32.5 Billion
- Estimated market size in 2026: USD 34.5 Billion
- Projected market size by 2033: USD 58.9 Billion
- CAGR (2026-2033): 7.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Moreover, increased funding from pharmaceutical and biotech companies, non-profit organizations, and contract research organizations (CROs) for oncology clinical trials is further supporting market growth and the development of advanced modalities.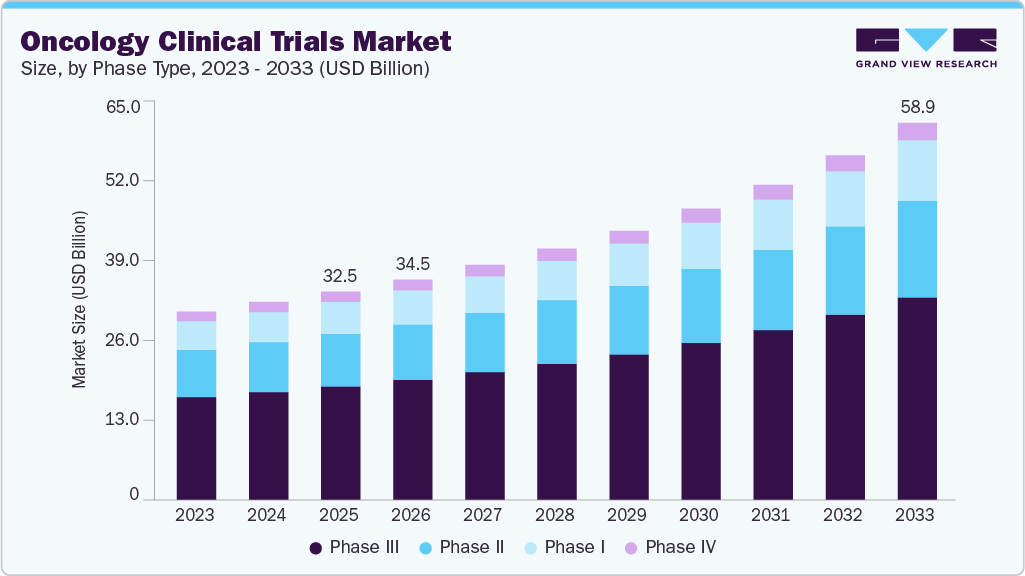 To learn more about this report, Download Free Sample Report
The rising incidence of cancer worldwide, coupled with an aging population, the rapid growth of biomarker-driven precision oncology, and the adoption of innovative trial methods, including adaptive studies, is likely to impact the growth of oncology clinical trials. Furthermore, the growing drug pipeline of immunotherapy and cell-based treatments, the use of fast-tracked approval pathways for breakthrough drugs, and the use of CROs experienced in oncology collectively fuel the oncology clinical trials market growth. These trends emerge from the need for faster patient recruitment and greater success in clinical trials among sponsors. The emergence of precision oncology is another key driver, as next-generation sequencing (NGS) panels enable the identification of rare genetic mutations such as KRAS G12C and NTRK fusions, thereby limiting patient pools but improving response rates. This trend drives the development of multiple small-scale, multi-site studies with complex patient screening programs that require bioinformatics integration and the involvement of central laboratories. Meanwhile, adaptive and platform trial designs are transforming the clinical development process by enabling mid-trial design changes, saving time and costs associated with inefficient trial methods.
In addition, immuno-oncology combination clinical trials combining checkpoint inhibitors with innovative drugs are complicated by the need to monitor immune-related adverse effects and the longer follow-up period. Furthermore, decentralized study elements such as remote visits and electronic patient-reported outcomes (ePRO) have been used more frequently to retain participants in lengthy oncology trials, especially in advanced-stage metastatic trials, where travel to multiple sites is required. In addition, the growing number of clinical trials in Asia-Pacific countries such as India and China is driven by the large number of treatment-naïve patients and the cost-effectiveness of conducting trials.
Moreover, regulatory bodies continue to expand their accelerated approval programs for oncology drugs that use surrogate markers such as progression-free survival, making phase shifts quicker and trial initiation more frequent. However, attrition rates of over 85% from Phase I to approval in oncology drugs pose a financial challenge that limits the approach of smaller biotechnology companies. In addition, strict inclusion criteria for patients and competition among ongoing clinical trials for eligible patients make recruitment difficult and delay study completion. Furthermore, opportunities arise to adopt artificial intelligence (AI) to optimize protocol development and minimize screening failures, thereby improving site efficiency. The other opportunity is to expand the use of real-world evidence and synthetic control arms to minimize reliance on large, randomized cohorts.
Opportunity Analysis
The advent of AI-powered patient recruitment, real-world evidence-based trial design, decentralized and hybrid oncology trial designs, the growing importance of rare and biomarker-driven cancers, and the emergence of trial sites in emerging markets present a robust opportunity scenario for the oncology clinical trials market. The use of AI to recruit participants for clinical trials makes trials feasible by mining electronic medical records and genomics databases to accurately identify suitable candidates. In the context of complex oncology trials, this strategy eliminates the risk that patients will fail to meet eligibility criteria during screening and speeds up the entire recruitment process, given the strict eligibility criteria in these trials. On the other hand, the integration of real-world evidence provides an avenue for clinical trial sponsors to accelerate approval processes by leveraging the regulatory agencies' growing willingness to accept external control groups and real-world evidence to supplement single-arm clinical trials, allowing clinical trials in rare cancers with few subjects to proceed faster without relying on randomized clinical trial designs with numerous participants.
Also, the growing emphasis on biomarker-defined subpopulations, such as HER2-low or MSI-high cancers, creates niches in clinical trials that require specific diagnostic collaborations and customized recruitment methods. Furthermore, developing markets such as India offer efficient trial environments with large numbers of untapped patients, enabling global sponsors to diversify geographically without compromising efficiency. In addition, digital endpoints and wearable devices facilitate longitudinal analysis in oncology trials, enabling more complex evaluations than conventional imaging-based endpoints. Nevertheless, inconsistencies in regional regulatory policies regarding the adoption of real-world evidence could impede widespread use of such strategies. Moreover, restrictions on data privacy policies regulating patient-level data exchange might hinder the development and implementation of AI-powered recruitment systems.
Impact of U.S. Tariffs on the Oncology Clinical Trials Market
Increased tariffs on pharmaceuticals, APIs, and clinical-trial inputs in the U.S., rising costs in oncology trials' supply chains, and growing trends towards localization will significantly change the dynamics of the oncology clinical trials market, as companies adjust their clinical development approaches to ensure efficiency. The increased tariffs will raise the cost of logistics and the inputs required for the production of biological drugs and targeted therapies, thereby increasing total clinical research expenses and limiting the number of studies conducted at any given time. The impact of disruptions in the supply chain due to customs delays and uncertainties in obtaining inputs creates threats to the timely distribution of investigational drugs. In addition, moving production in-house to avoid paying tariffs creates an additional competitive threat to capacity, increasing the time required to initiate oncology studies.
Furthermore, higher expenditures on diagnostic and concomitant tests contribute to rising patient costs during clinical trials, especially in oncology trials that rely on biomarker testing. Moreover, international clinical trials face budgetary challenges due to differences in tariffs across regions, making their conduct difficult. In addition, tariff-related risks affect the strategies CROs and CDMOs adopt, leading them to work with partners in the vicinity. On the other hand, financial difficulties and complexities associated with such trials could lead to fewer small biotech companies engaging in clinical trials.
Technological Advancements
 To learn more about this report, Download Free Sample Report
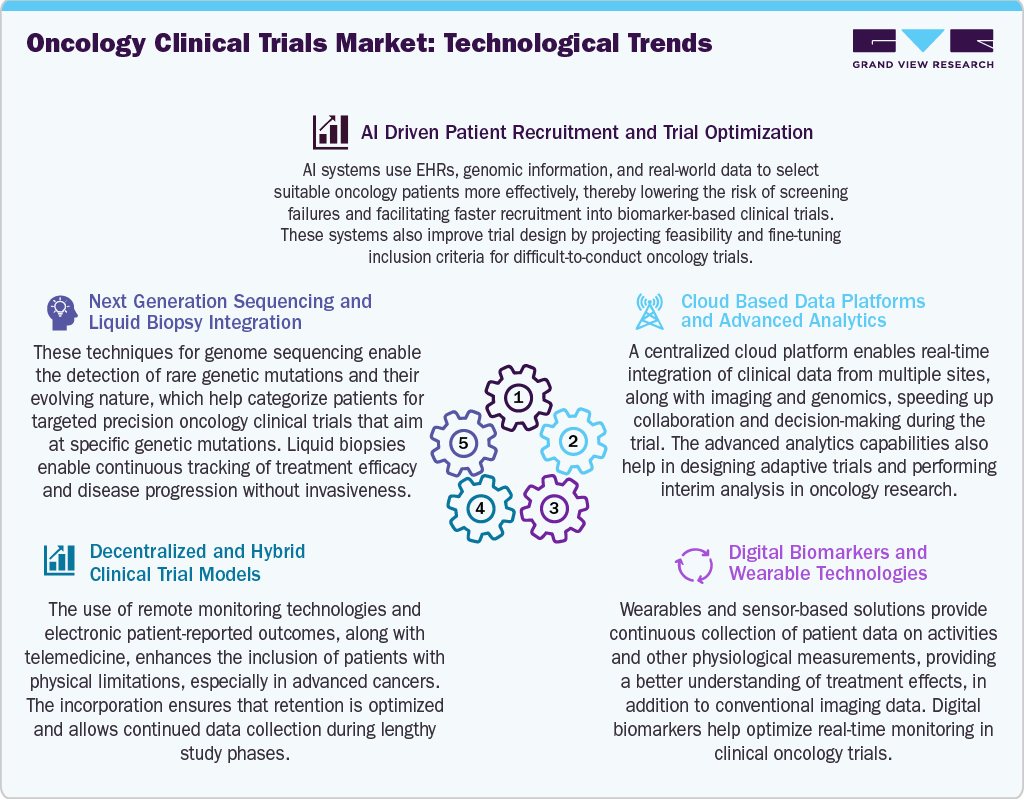
The introduction of NGS technologies, the integration of AI into clinical trial protocol design and patient enrollment processes, the growth of decentralized and hybrid trial technologies, the incorporation of digital biomarkers and wearable devices, and the utilization of sophisticated data analysis software together transform the market for oncological clinical trials. The NGS enables a comprehensive examination of a participant’s genome for rare mutations and stratifies individuals into various cohorts based on identified rare mutations to enhance efficacy rates. Moreover, protocol optimization using AI leverages historical trial data to inform better decisions on inclusion criteria and endpoints, thereby minimizing protocol amendments and increasing the success rate of clinical trials among heterogeneous oncological patient populations.
In addition, biomarkers collected from wearable devices enable continuous evaluation of patient health parameters, providing additional information on therapy effectiveness beyond traditional imaging endpoints. Similarly, cloud computing-based clinical trial systems facilitate multi-center data handling and facilitate real-time analysis, thus enhancing decision-making throughout the clinical trial process. Moreover, modern imaging technologies, supplemented by AI algorithms, help improve the accuracy of tumor response assessment, thereby minimizing variability across trial sites. Finally, automation in sample preparation and bioanalytical processes increases throughput for complex tests used in immuno-oncology studies. However, the high cost of implementing such technologies and integration issues with existing systems might discourage smaller research institutions from adopting these solutions. Furthermore, data protection concerns and regulatory requirements related to the massive collection of digital data might slow the adoption of technologies.
Pricing Model Analysis
 To learn more about this report, Download Free Sample Report
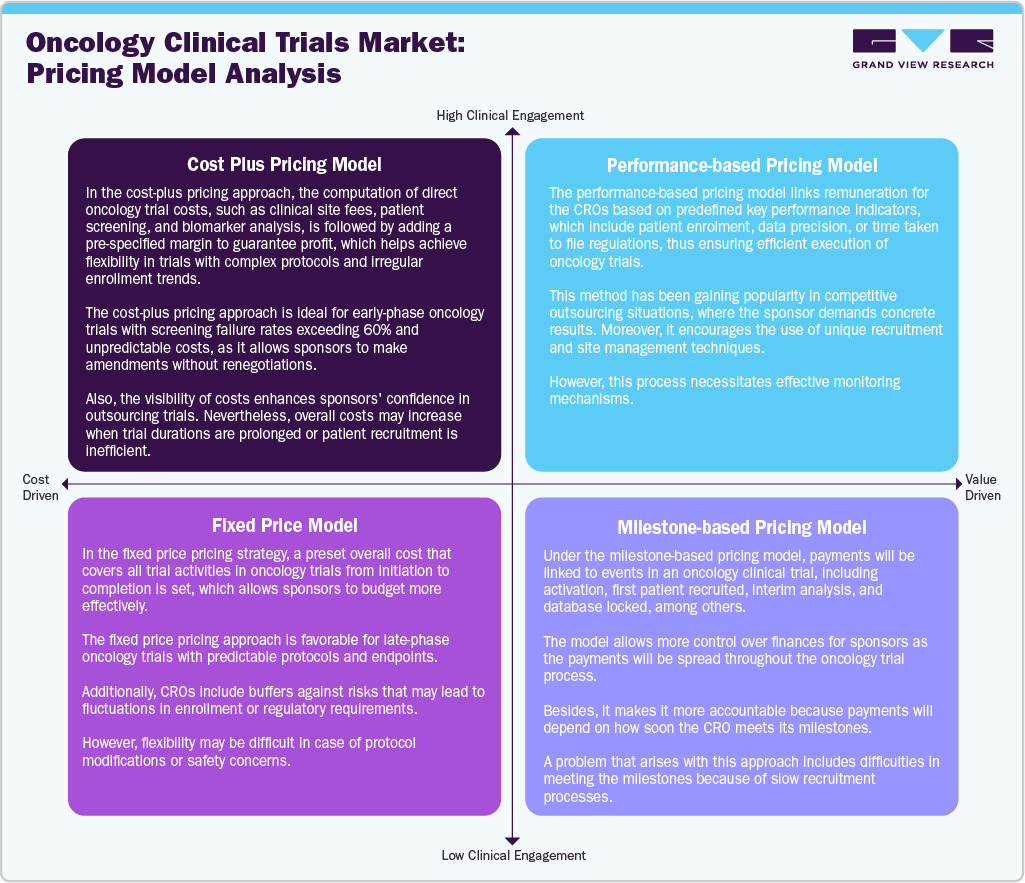
The various pricing mechanisms adopted in the clinical trials industry, like cost-plus, fixed-price, milestone-based, and performance-based pricing, together comprise the financial models of the oncology clinical trials market. The cost plus pricing mechanism is significant, especially in early phase oncology trials where there are high screening failures and protocol change rates in oncology research, as these types of pricing mechanisms allow the sponsor to be flexible in budgeting and deal with the variations associated with the trial in terms of the number of patients and assays. The fixed-price pricing model applies in late-phase oncology research, where there are no protocol changes, and enrollment remains constant. This allows sponsors to set their budget at a single point in time, while the CRO sets aside a buffer against risks.
Models based on performance metrics are gaining popularity in the context of outsourcing competitions, as sponsors seek tangible results, such as higher enrollments or better-quality data, thereby pushing CROs to improve their performance. In addition, pricing may become hybridized, with different parts of clinical trials receiving different treatments based on the varying levels of risk associated with the respective activities and their predictability. In addition, the choice of pricing model is essential for establishing a partnership with a CRO and for the approach to executing the trial, especially in precision oncology. Furthermore, the increasing complexity of immuno-oncology and cell therapy trials drives the adoption of flexible, performance-linked models. However, discrepancies between a pricing model and a study design may lead to excessive costs. The possible opportunities include implementing data-driven pricing strategies and using AI for cost forecasting.
Market Concentration & Characteristics
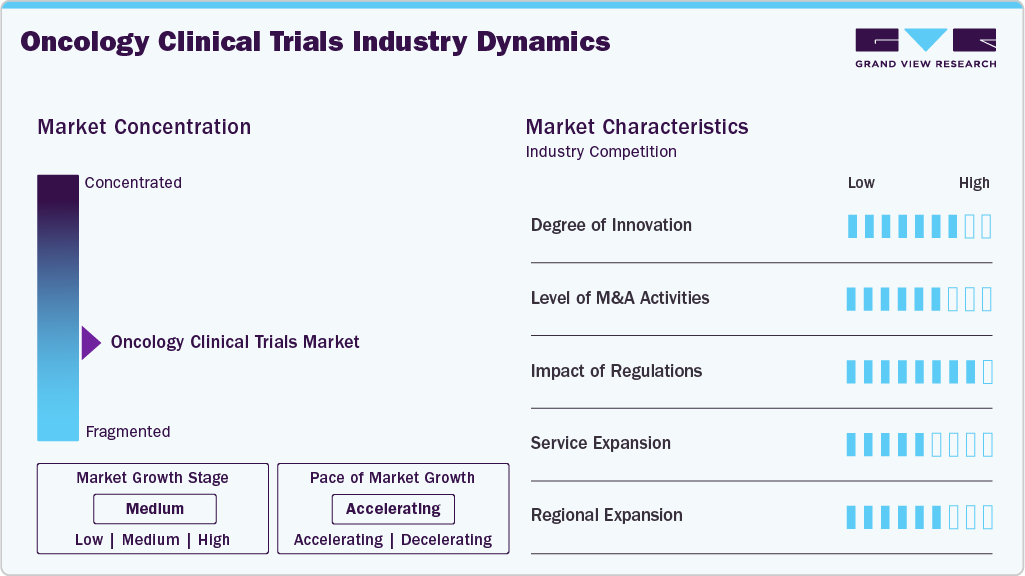
The oncology clinical trials market growth stage is medium, and the pace of growth is accelerating. The market is characterized by the degree of innovation, level of M&A activities, regulatory impact, service expansion, and regional expansion.
Innovation intensity in the oncology clinical trials industry is moving forward on the account of advances made in technologies for precision oncology, such as next-generation sequencing, liquid biopsy technologies, and AI-assisted analysis, which can help profile tumors in real time, along with automation of processes and high throughput screening, which helps make cycles shorter and more efficient in the case of large multi-site oncology trials with complex biomarkers.
The rigid regulatory environment set up by regulatory agencies such as the FDA and EMA demands thorough validation of outcomes like progression-free survival, overall survival rates, and response to biomarkers, thereby increasing trial intensity and necessitating the need for compliant CROs having capabilities in adaptive trial designs, companion diagnostics integration, and adherence to GCP, GLP, and GMP protocols.
 To learn more about this report, Download Free Sample Report
M&A activity within the industry has been on the rise, with CROs and pharmaceutical firms enhancing their capability through mergers and acquisitions in oncology-focused firms with capabilities in genomic profiling, decentralized trial techniques, and immuno-oncology, contributing towards a more diversified service offering that improves competitive strength in an industry that is experiencing high levels of demand for specialized trial execution.
In addition to trial management, service offerings include comprehensive services like protocol development, biomarker discovery, recruitment of patients using real-world data, decentralized trial techniques, and analysis of data, while specialized services, including development of companion diagnostics, measurement of immune response, and long-term patient follow-up data, become significant due to the complex nature of oncology clinical trials.
Geographic expansion is vital, as sponsors have started conducting oncology studies in regions like India and China, enabling them to take advantage of the cost efficiencies, a large and varied subject pool, and improved regulations that facilitate more efficient patient recruitment and better global study representation.
Phase Type Insights
The phase III segment dominated the oncology clinical trials market, accounting for the largest revenue share of 54.3% in 2025, owing to considerably higher operating costs associated with late-phase clinical trials, which typically enroll large numbers of patients across several countries over extended periods. The studies tend to use progression-free survival and overall survival as primary endpoints, thereby requiring long follow-up, centralized image review, and complex statistical analyses. The increased use of biomarker stratification and companion diagnostics in solid tumor studies has driven higher demand for laboratory tests in Phase III trials, especially in lung and breast cancers. There is also a growing regulatory requirement to provide comparative effectiveness and safety information for broader patient populations before approving drugs and immuno-oncology agents, which has led to larger multi-center studies. Moreover, sponsors have been implementing simultaneous regional enrollment approaches to accelerate product marketability, thereby increasing expenses for patient recruitment and site initiation. Such factors are likely responsible for the segment's growth.
The phase I segment is expected to grow at the fastest CAGR over the forecast period, driven by the increasing number of first-in-human oncology trials involving antibody drug conjugates, bispecific antibodies, radioligand therapy, and cell-based immuno-oncology. Several pharmaceutical and biotech companies are simultaneously initiating dose-escalation and dose-expansion studies in advanced solid tumors to gain earlier insight into the efficacy of the study drugs, leading to an increase in the number of early-stage trials. In addition, the preference for using adaptive design and basket studies in oncology trials is adding complexity to the number of early-stage programs being conducted. In addition, the need for biomarker screening and molecular profiling in patients in precision oncology development further increases the number of activities conducted in Phase I trials.
Study Design Insights
The interventional studies segment accounted for the largest share of the oncology clinical trials industry in 2025, owing to the large number of active oncology drug development programs involving immunotherapy, targeted therapy, antibody-drug conjugates, and cell-based therapies, which necessitated the use of interventional study designs. Interventions involve precise dosing, endpoint assessment according to protocol, and extensive biomarker monitoring; hence, sponsors have favored interventional studies in regulatory studies. The increased utilization of adaptive designs, umbrella studies, and combinational therapy in solid tumors has led to an increase in the number of global interventional oncology studies.
The observational studies segment is projected to grow at the fastest CAGR during the forecast period, attributed to the rising demand for evidence from the real-world environment, which will be used to evaluate the safety and efficacy of therapies and the outcomes that occur after the approval of medicines in oncological diseases. More pharmaceutical corporations and regulatory authorities are leveraging EHRs, patient registries, and genomic data to analyze the performance of therapies in real-world settings, not just in clinical trials.
Indication Insights
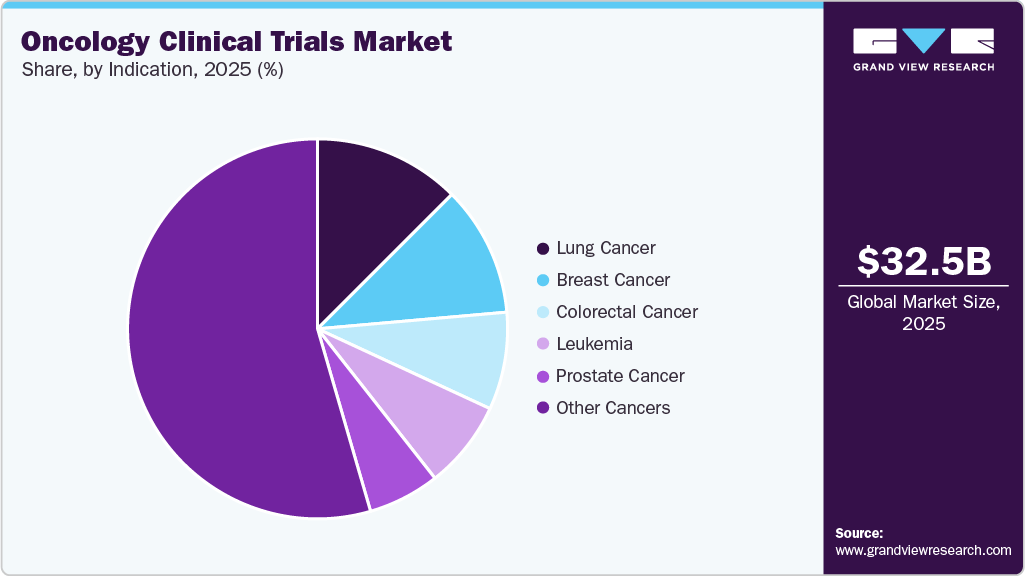
The lung cancer segment accounted for the largest revenue share of the oncology clinical trials market in 2025. The segment growth can be attributed to the prevalence of drug developers' clinical research activities in the EGFR, ALK, KRAS, ROS1, and PD-L1 biomarker populations among non-small cell and small cell lung cancers. The rise in the adoption of precision medicine in oncology has led to large-scale biomarker-stratified research studies on targeted and immune-based combination therapies in earlier lines of treatment. Commercial success in the indication extension of checkpoint inhibitors and resistance management therapies has contributed to a higher number of global multicenter lung cancer clinical trials.
 To learn more about this report, Download Free Sample Report
The breast cancer market segment is anticipated to grow at the fastest CAGR during the analysis period, owing to the strong potential of antibody-drug conjugates (ADCs), HER2-low-specific therapies, and hormone receptor-based treatments under development. The growing number of biomarker-based studies for TNBC, ESR1 mutations, and early-stage neoadjuvant therapy has led to a higher rate of clinical trials initiated. The adoption of combination therapy, including immunotherapy and targeted therapy, has increased the complexity of clinical trials.
Regional Insights
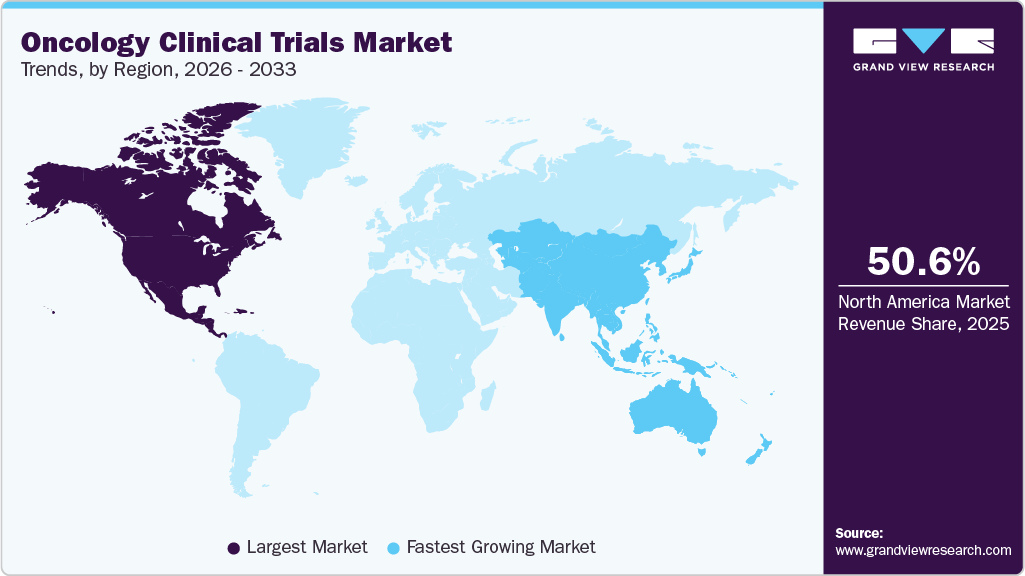
North America accounted for the largest revenue share in the global oncology clinical trials market, accounting for 50.6% in 2025. The market growth in the region is propelled by the growing trend of outsourcing biomarker driven oncology clinical trials to CROs equipped with genomic screening and adaptive trial execution capabilities, as sponsors seek to speed up enrolment in mutation-specific patient cohorts like KRAS G12C and HER2 low patients, which is facilitated by the incorporation of AI-driven patient matching technologies and laboratory testing services that streamline patient screening processes in multi-site oncology clinical trials. In addition, CROs are enhancing decentralized trial processes and real-world evidence integration to facilitate the management of lengthy, high attrition-risk oncology clinical trials, thereby ensuring continuous monitoring of endpoints in late-stage cancer trials. For instance, in January 2026, Tempus AI expanded its AI-powered precision medicine platform to offer oncology clinical trial solutions using real-world clinical and molecular data to identify patients and optimize clinical trial design. Such factors collectively drive market growth in the region.
 To learn more about this report, Download Free Sample Report
U.S. Oncology Clinical Trials Market Trends
The growth of the U.S. oncology clinical trials industry is mainly attributed to increased concentration of precision oncology trials with stratified patient populations based on biomarkers and complicated immuno-oncology combination trials, as several pharma and biotech companies rely on specialist CROs who possess expertise in areas like genomic profiling, adaptive trial designs, and advanced data analytics. This comes from the strong integration of real-world evidence and patient recruitment platforms driven by artificial intelligence, which reduces patient enrollment time in disease areas such as non-small cell lung cancer and metastatic breast cancer. In addition, CROs have increased the adoption of decentralized trials and hybrid clinical sites to ensure higher patient retention during the lengthy process of conducting an oncology trial, especially in later phases, where the frequent requirement for patients to attend clinical sites becomes increasingly difficult to meet. For instance, in February 2026, Flatiron Health expanded its clinical research offerings into precision oncology through a platform that integrates real-world data with clinical trials. These factors are likely to propel the market growth in the country.
The Canada oncology clinical trials market growth is driven by the increasing number of outsourcing of oncology clinical trials to CROs, who are equipped with an enhanced ability to conduct studies in precision oncology through biomarker-driven approaches as well as genomic testing at a centralized location, taking advantage of the highly developed healthcare system in the country and the diversity of the Canadian population, thus facilitating recruitment of patients with specific mutations like EGFR and ALK, aided by the use of real-world data from provincial cancer registries that aids in improving patient recruitment and tracking their outcomes throughout the duration of the trial. Thus, these factors affect the market growth.
Europe Oncology Clinical Trials Market Trends
The market’s growth in Europe is attributed to the increasing trend of outsourcing biomarker-driven oncology clinical trials to specialized CROs having expertise in executing early-phase oncology trials and adaptive trials, owing to sponsors taking advantage of multi-country patient pools as well as regulatory harmonization offered under the Clinical Trials Regulation, which helps in achieving faster enrollment in rare mutation cohorts. In addition, there are increasing instances of companies improving their technologies and oncology service offerings through strategic acquisitions to ensure more efficient trial execution and data handling across European sites for multi-regional oncology trials. For instance, in January 2026, Worldwide Clinical Trials entered into a definitive agreement to acquire Catalyst Clinical Research, an oncology CRO in Europe and the U.S., to enhance capabilities in early-phase oncology, expand site reach, and improve technology integration.
The Germany oncology clinical trials market is expected to witness significant growth, driven by the increased conduct of early-phase biomarker-driven oncology clinical trials, supported by high regulatory standards and advanced infrastructure for conducting clinical research in the country. The increase in clinical trials is due to sponsors tapping into Germany's expertise in precision oncology and the availability of highly specialized cancer centers to conduct oncology clinical trials in mutation-specific groups, such as those with KRAS or HER2 mutations. This includes utilizing genomics and central lab capabilities to improve patient selection in such trials. Moreover, sponsors' CROs and biotech firms are increasingly partnering with regulatory agencies to expedite approval of more complex clinical trials and to use adaptive designs for first-in-human and Phase II trials, which involve thorough safety and pharmacodynamic assessments. In addition, improved regulatory efficiency and advanced clinical research networks enable faster activation of oncology clinical trials with multiple sites, thereby enhancing patient recruitment timelines in mutation-specific groups. For instance, in April 2026, Gilead Sciences announced the acquisition of Tubulis GmbH to enhance its oncology pipeline, including the development of antibody-drug conjugate drugs through early-phase oncology clinical trials. These factors are expected to impel the market growth in the country.
The UK oncology clinical trials market is expected to grow significantly in the coming years. This growth can be attributed to the growing importance of approvals and patient access in oncology clinical trials through regulatory reform, since the pharma and biotech companies are utilizing the newly introduced frameworks to conduct more biomarker and adaptive oncology trials, which is enabled through fast-track approvals and the ethics review process that minimizes the time taken for starting the trial process. Moreover, the use of health care databases in the NHS system enables rapid subject selection and tracking in precision oncology trials, making it feasible to conduct advanced oncology studies that include targeted drugs and immuno-oncology combinations, thereby increasing patient recruitment and multi-site trials in the region.
Asia Pacific Oncology Clinical Trials Market Trends
The Asia Pacific oncology clinical trials industry is expanding rapidly, driven by increasing outsourcing of biomarker driven oncology clinical trials to CROs in China, India, and South Korea as sponsors influence the availability of large numbers of treatment naive patients and rapid enrolment in mutation specific trials like EGFR and ALK, and this is facilitated by reforms in regulation that have shortened approval times and made possible the conduct of multi center precision oncology studies in the region. In addition, the adoption of electronic health records and the centralization of genomics testing in tertiary hospitals facilitate patient recruitment and enable the conduct of intricate oncology trials using targeted agents and combinations of immunotherapy.
Moreover, the region remains a preferred choice for clinical research owing to cost benefits and a high enrolment rate, as well as the increasing availability of facilities for oncology trials, thereby improving the region's ability to undertake global distribution of clinical trials. Moreover, the growth of early-phase clinical trial facilities and investments in oncology trials in top hospitals make it easier to conduct trials locally and lessen reliance on Western countries for clinical trial sites.
China’s oncology clinical trials market experiences high growth opportunities due to the rising number of biomarker-based oncology clinical trials since the regulatory reforms that have sped up the process of approvals and promoted innovation in targeted treatments, as sponsors take advantage of the huge number of patients who have never received any treatment before to enroll them faster in mutation-specific cohorts such as EGFR and PD-L1, with this being aided by the development of the country’s CRO capabilities and genome testing services. Moreover, government backing for oncology drug discovery and hospital data systems further improves the execution of complicated oncology trials involving multiple sites.
The oncology clinical trials market in Japan is projected to grow at a considerable CAGR over the forecast period. The Japanese market is being spurred by the increasing emphasis on conducting precise oncology clinical trials based on robust genomic testing facilities and extensive collaboration between pharmaceutical firms and research institutions, as biomarker-defined cohorts for indications like gastric and lung cancers become the target for sponsor trials, which are made possible by the robust regulatory system, allowing for quick trial approval and data accuracy. In addition, combining patient records from hospitals and national cancer registries has improved patient identification and follow-up, making multi-site oncology trials more feasible, particularly for trials focusing on immuno-oncology combinations.
The India oncology clinical trials market is projected to grow considerably in the coming years. The market’s growth is fueled by outsourcing of oncology clinical trials based on biomarker-driven research to CROs, due to cost effectiveness and availability of a large pool of patients who are treatment naïve, as sponsors try to fast track enrollment in mutation-specific groups, such as EGFR and HER2, this trend is facilitated by changes in regulations that have sped up the approval process and increased transparency in the clinical trial process. In addition, the establishment of more hospitals specializing in oncology and increased use of centralized genomics testing have enabled easier identification of patients, facilitating more complex multicenter oncology clinical trials using targeted treatments and immune-oncology combinations.
Latin America Oncology Clinical Trials Market Trends
Latin America represents an emerging market for oncology clinical trials, primarily due to an increase in outsourcing of oncology clinical trials in countries like Brazil and Argentina to have cost efficient conduct of such trials in addition to getting access to diverse populations where there are large numbers of patients with advanced cancer stages, which is backed up by the improvement of regulatory timetables in addition to the increased availability of investigative sites experienced in conducting multi-center oncology trials. Moreover, the trend towards centralized laboratories, combined with electronic data capture tools, makes it easier to identify and track patients, thereby enabling the conduct of complex trials.
The oncology clinical trials market in Brazil is influenced by factors such as the growing number of global oncology clinical trials, driven by the large number of patients with late-stage cancer, which speeds patient enrollment in indications such as breast, lung, and colorectal cancers in the country. This is facilitated by regulatory developments, which have reduced the time required for trial approval and improved coordination between ethics committees and health authorities. The presence of centers for oncology research experience in executing multi-site oncology clinical trials, especially those with targeted therapy and immuno-oncology combinations. Such factors are anticipated to boost the market growth in Brazil.
Middle East and Africa Oncology Clinical Trials Market Trends
The Middle East and Africa oncology clinical trials industry is witnessing steady growth. This is mainly due to increased participation in oncology clinical trials, as sponsors explore new regions with higher cancer incidence and limited prior experience with innovative treatments. This is aided by the growth of clinical research facilities in Saudi Arabia, the UAE, and South Africa, which facilitates quick patient recruitment for indications with high unmet medical needs. In addition, the development of improved regulatory policies and increased funding towards oncology specialty hospitals makes clinical trials more feasible. Moreover, the adoption of electronic data collection platforms and central labs makes patient recruitment easier in oncology clinical trials using targeted agents and immuno-oncology combinations.
The South Africa oncology clinical trials market is growing at a steady pace due to the higher participation rate in global oncology clinical trials, owing to the significant burden of breast, cervical, and lung cancer cases, among others. Sponsors can easily recruit patients for their clinical trials based on the diversity in the patient population and the advanced stages of their diseases to increase the enrolment rate in late-stage and biomarker-driven studies. In addition, advancements in clinical trial management and the widespread adoption of electronic data capturing systems help sponsors efficiently track patients for the implementation of sophisticated oncology clinical trials.
The oncology clinical trials market in the UAE is expected to witness significant growth during the forecast period, driven by the increased involvement in oncology clinical trials, due to the active involvement of government policies in making the UAE a center for clinical trials in the region, and the use of healthcare infrastructure, along with the presence of a multi-ethnic population, to recruit patients to perform multi ethnic oncology clinical trials. In addition, the rise of oncology centers, along with the use of digital health records, helps with patient identification and tracking and enables targeted therapies and immuno-oncology trials.
Key Oncology Clinical Trials Company Insights
The key players operating across the market are adopting strategic initiatives such as service launches, mergers & acquisitions, partnerships & agreements, and expansions to gain a competitive edge in the market. For instance, in May 2025, the START Center for Cancer Research collaborated with OneOncology to expand the reach of early-phase oncology clinical trials by establishing new research sites within community oncology practices across the U.S., enabling more patients to participate in these studies outside academic institutions. These research sites will be integrated into the START Center's existing infrastructure to accelerate study initiation, ensure consistent process implementation, and improve data quality in early-phase clinical trials.
Key Oncology Clinical Trials Companies:
The following key companies have been profiled for this study on the oncology clinical trials market.
- Astrazeneca
- Merck & Co., Inc.
- IQVIA
- Gilead Sciences Inc.
- F. Hoffmann-La Roche Ltd.
- Parexel International Corporation
- Charles River Laboratories
- Syneos Health
- Medpace
- Labcorp Drug Development
- ICON plc
- Thermo Fisher Scientific (PPD)
- WuXi AppTec
Recent Developments
-
In January 2026, AstraZeneca acquired Modella to introduce AI technology in oncology clinical development. As a result, more efficient biomarker discovery and patient selection can be achieved through the use of AI technology during global oncology clinical trials.
-
In July 2025, Veeda Lifesciences partnered with Mango Sciences to incorporate AI and real-world data analysis in its clinical trial services, resulting in better patient recruitment and data-driven decisions in oncology clinical trials.
Oncology Clinical Trials Market Report Scope
Report Attribute
Details
Market size in 2025
USD 32.5 billion
Estimated market size in 2026
USD 34.5 billion
Projected market size by 2033
USD 58.9 billion
Growth rate
CAGR of 7.9% from 2026 to 2033
Actual data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Phase type, study design, indication, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; Thailand; South Korea; Australia; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait; Oman; Qatar
Key companies profiled
Astrazeneca; Merck & Co., Inc.; IQVIA; Gilead Sciences, Inc.; F. Hoffmann-La Roche Ltd.; Parexel International Corporation; Charles River Laboratories; Syneos Health; Medpace; Labcorp Drug Development; ICON plc; Thermo Fisher Scientific (PPD); WuXi AppTec
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Oncology Clinical Trials Market Report Segmentation
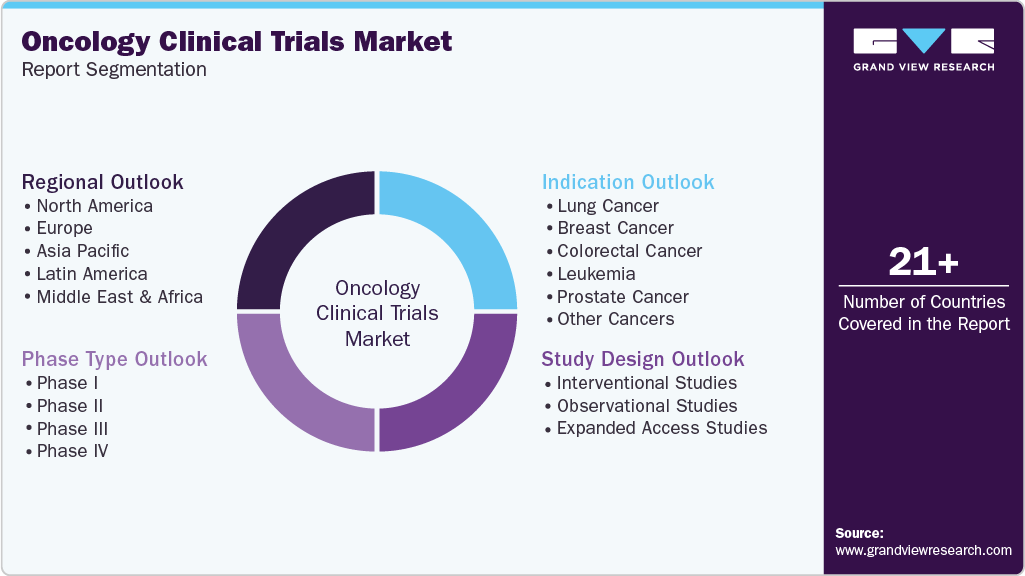
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global oncology clinical trials market report based on phase type, study design, indication, and region:
 To learn more about this report, Download Free Sample Report
-
Phase Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Phase I
-
Phase II
-
Phase III
-
Phase IV
-
-
Study Design Outlook (Revenue, USD Million, 2021 - 2033)
-
Interventional Studies
-
Observational Studies
-
Expanded Access Studies
-
-
Indication Outlook (Revenue, USD Million, 2021 - 2033)
-
Lung Cancer
-
Breast Cancer
-
Colorectal Cancer
-
Leukemia
-
Prostate Cancer
-
Other Cancers
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
UAE
-
Saudi Arabia
-
Kuwait
-
Qatar
-
Oman
-
-
Frequently Asked Questions About This Report
The global carbon footprint management market is expected to grow at a compound annual growth rate of 9.5% from 2026 to 2033 to reach USD 27.0 billion by 2033.
The key factors driving the growth of the global carbon footprint management market include stringent environmental regulations and net-zero commitments, increasing corporate focus on ESG reporting, and rising pressure from investors and consumers for sustainability. The advancements in digital technologies such as AI, IoT, and cloud-based carbon tracking solutions are accelerating adoption across industries.
The global carbon footprint management market was estimated at USD 13.1 billion in 2025 and is expected to reach USD 14.3 billion in 2026.
Based on the deployment segment, the cloud segment held the largest revenue share of more than 59% in 2025.
Some of the key participants in the global carbon footprint management market include Dakota Software, Ecova, ENGIE, IBM Corporation, Ideagen EHS, IsoMetrix, Microsoft Corporation, SAP SE, Schneider Electric, Wolters Kluwer, among others.
Asia Pacific dominated with a 55.4% revenue share in 2025.
The enterprise tier segment led with a 40.4% revenue share in 2025, and is the fastest-growing type.
The energy and utilities segment led with a 31.7% revenue share in 2025, while the IT and telecommunication segment is the fastest-growing.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


