
- Home
- »
- Consumer F&B
- »
-
Organic Food And Beverages Market Size Report 2026-2033GVR Report cover

Organic Food And Beverages Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Organic Food, Organic Beverages), By Distribution Channel (Convenience Stores, Specialty Stores, Online Sales Channel), By Region, And Segment Forecasts
Market Size, 2025
$291.2BMarket Estimate, 2026
$329.1BMarket Forecast, 2033
$875.3BCAGR, 2026–2033
15.0%Organic Food And Beverages Market Summary
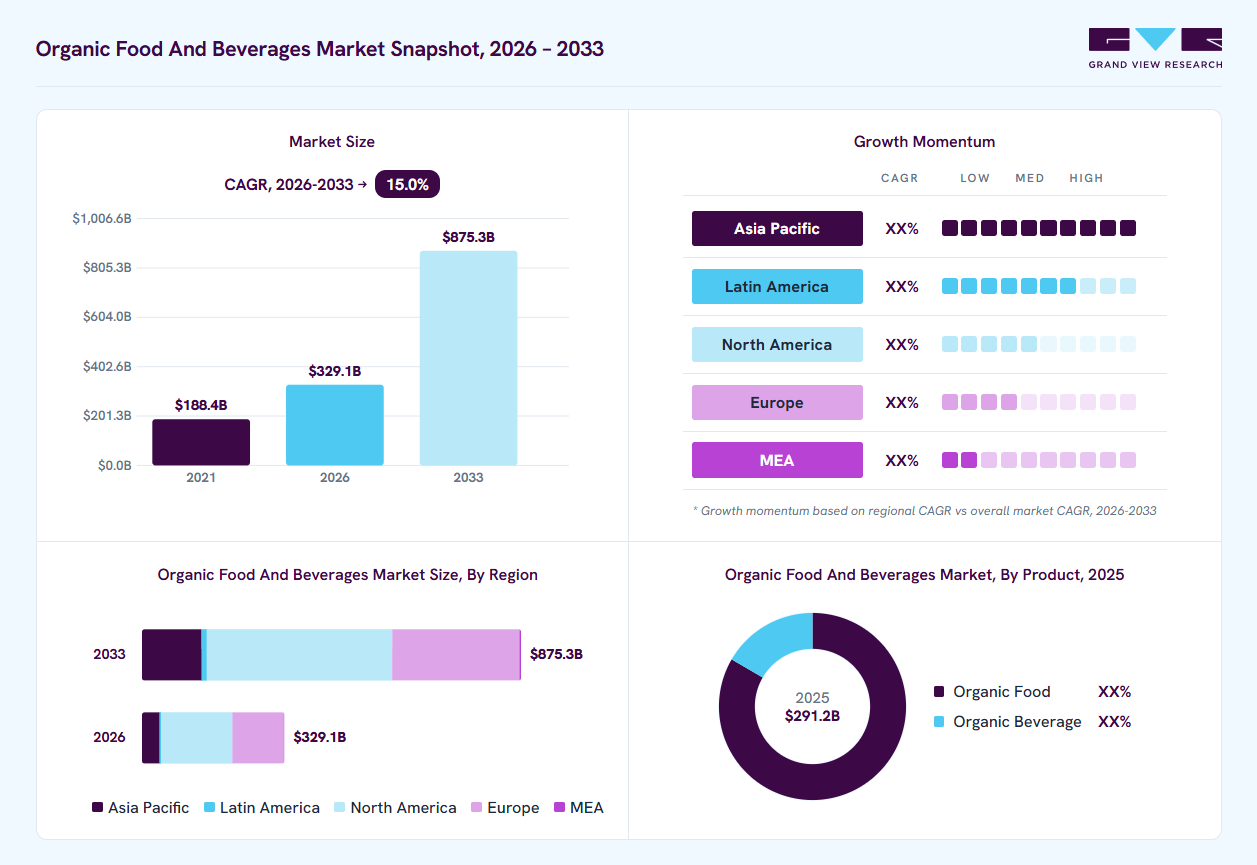
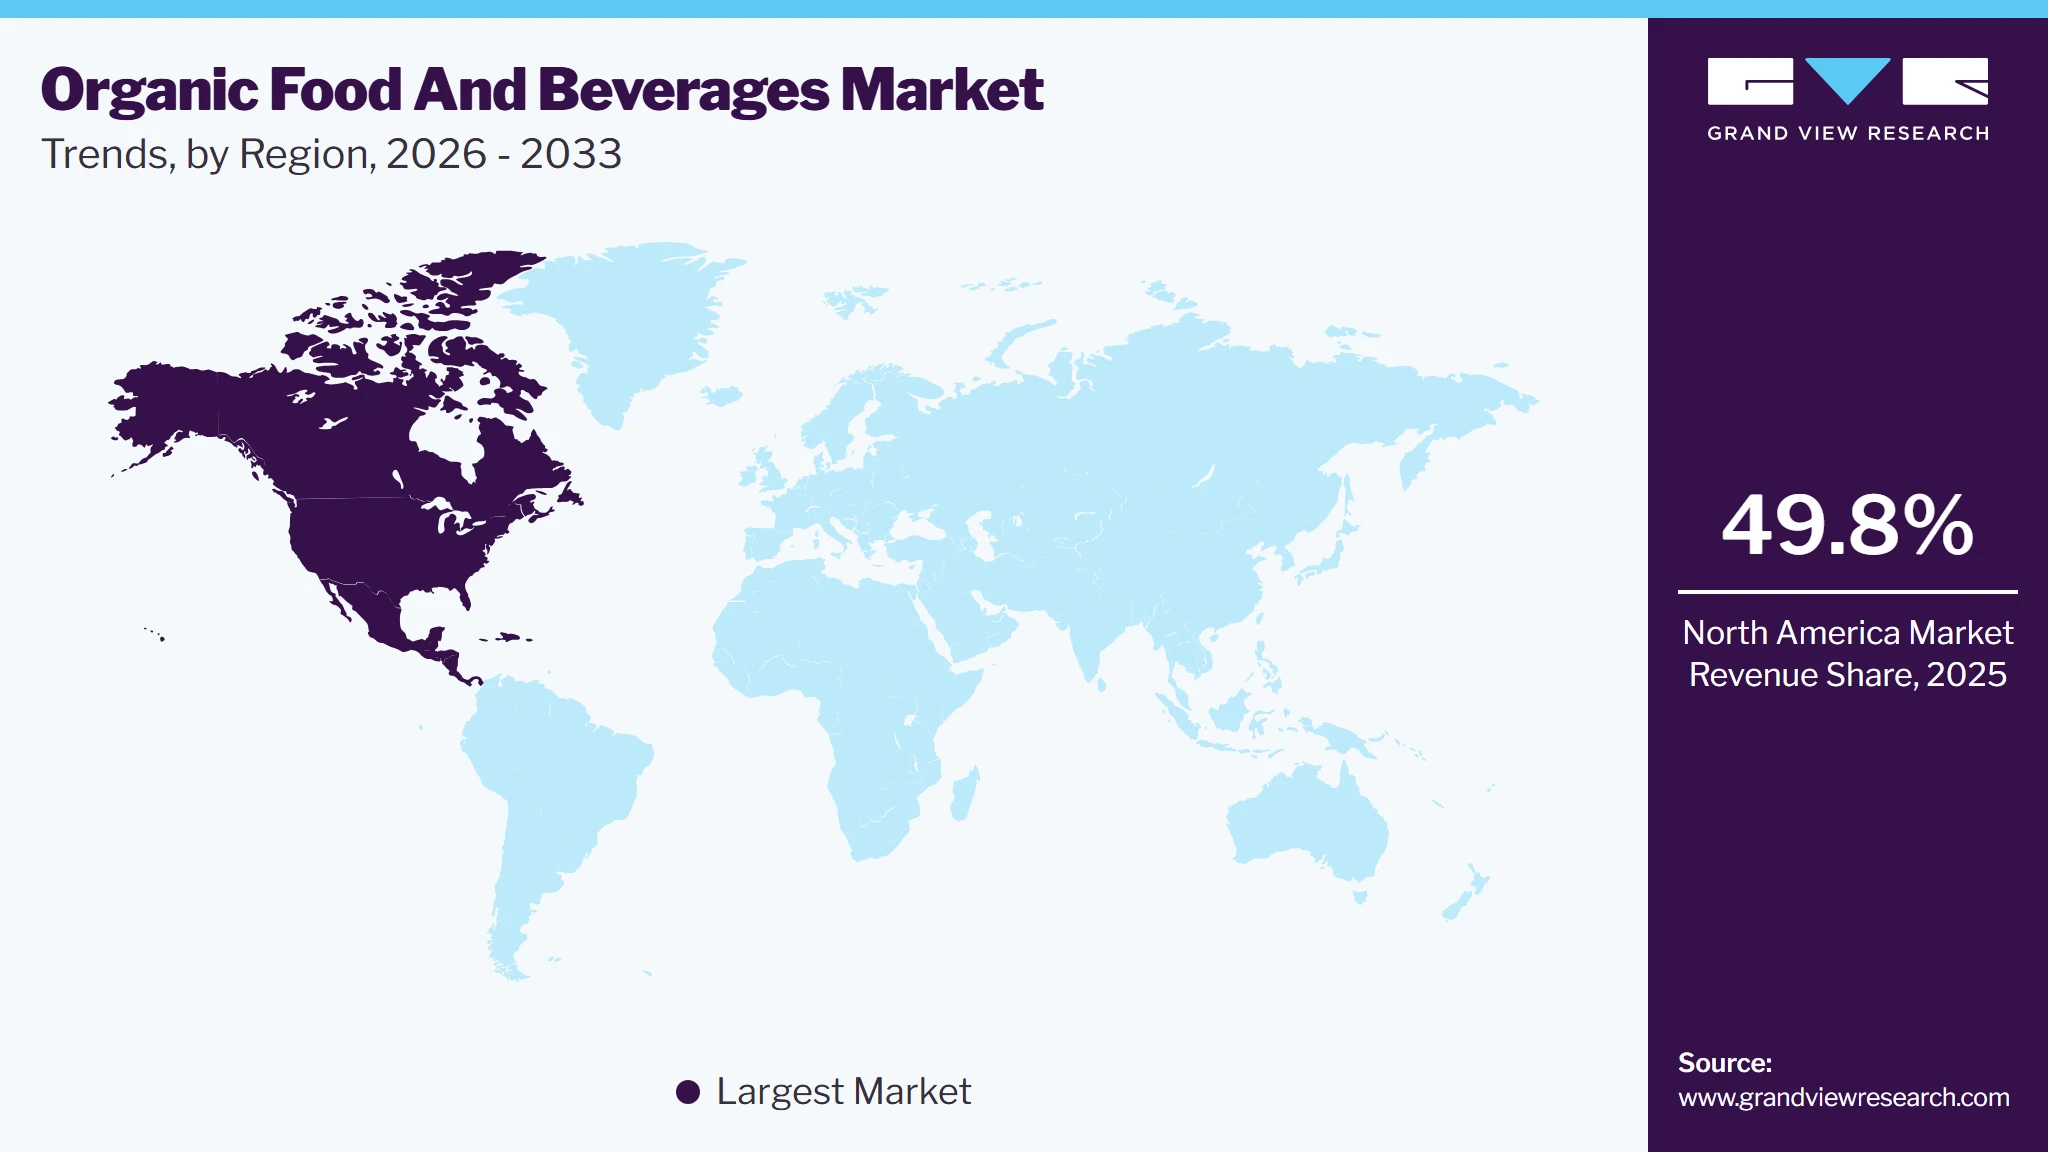
The global organic food and beverages market size was valued at USD 291.2 billion in 2025 and is projected to grow from USD 329.1 billion in 2026 to USD 875.3 billion by 2033, at a CAGR of 15.0% from 2026 to 2033. The market in North America dominated with a revenue share of 49.8% in 2025. One of the primary factors driving market expansion is growing awareness about the health benefits associated with the consumption of organic products.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Organic food segment held the largest market share of 89.4% in 2025.
- By distribution channel: Supermarkets/hypermarkets segment held the largest market share of 25.7% in 2025.
Regional Highlights
- Largest regional market: North America (49.8% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 291.2 Billion
- Estimated market size in 2026: USD 329.1 Billion
- Projected market size by 2033: USD 875.3 Billion
- CAGR (2026-2033): 15.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Sales of organic food and beverages are projected to rise as a result of the change in purchasing behavior of consumers. In addition, the rising popularity of non-GMO products among consumers is driving market growth. The market has witnessed substantial growth due to the increased accessibility of organic foods and beverages. Organic products are no longer confined to niche stores or farmers' markets. They have become readily available in mainstream supermarkets, online retailers, and even fast-food chains. This expanded distribution has made it convenient for consumers to include organic options in their regular shopping habits. In addition, there is a growing awareness and concern surrounding the environmental impact associated with conventional agricultural practices. These practices often contribute to issues, such as soil degradation, water pollution, and the loss of biodiversity. In contrast, organic farming methods prioritize sustainable practices aimed at promoting soil health, conserving water resources, and preserving wildlife habitats. This strong emphasis on environmental sustainability resonates with an increasing number of consumers who actively seek out products that align with their values of sustainability and ethical consumption.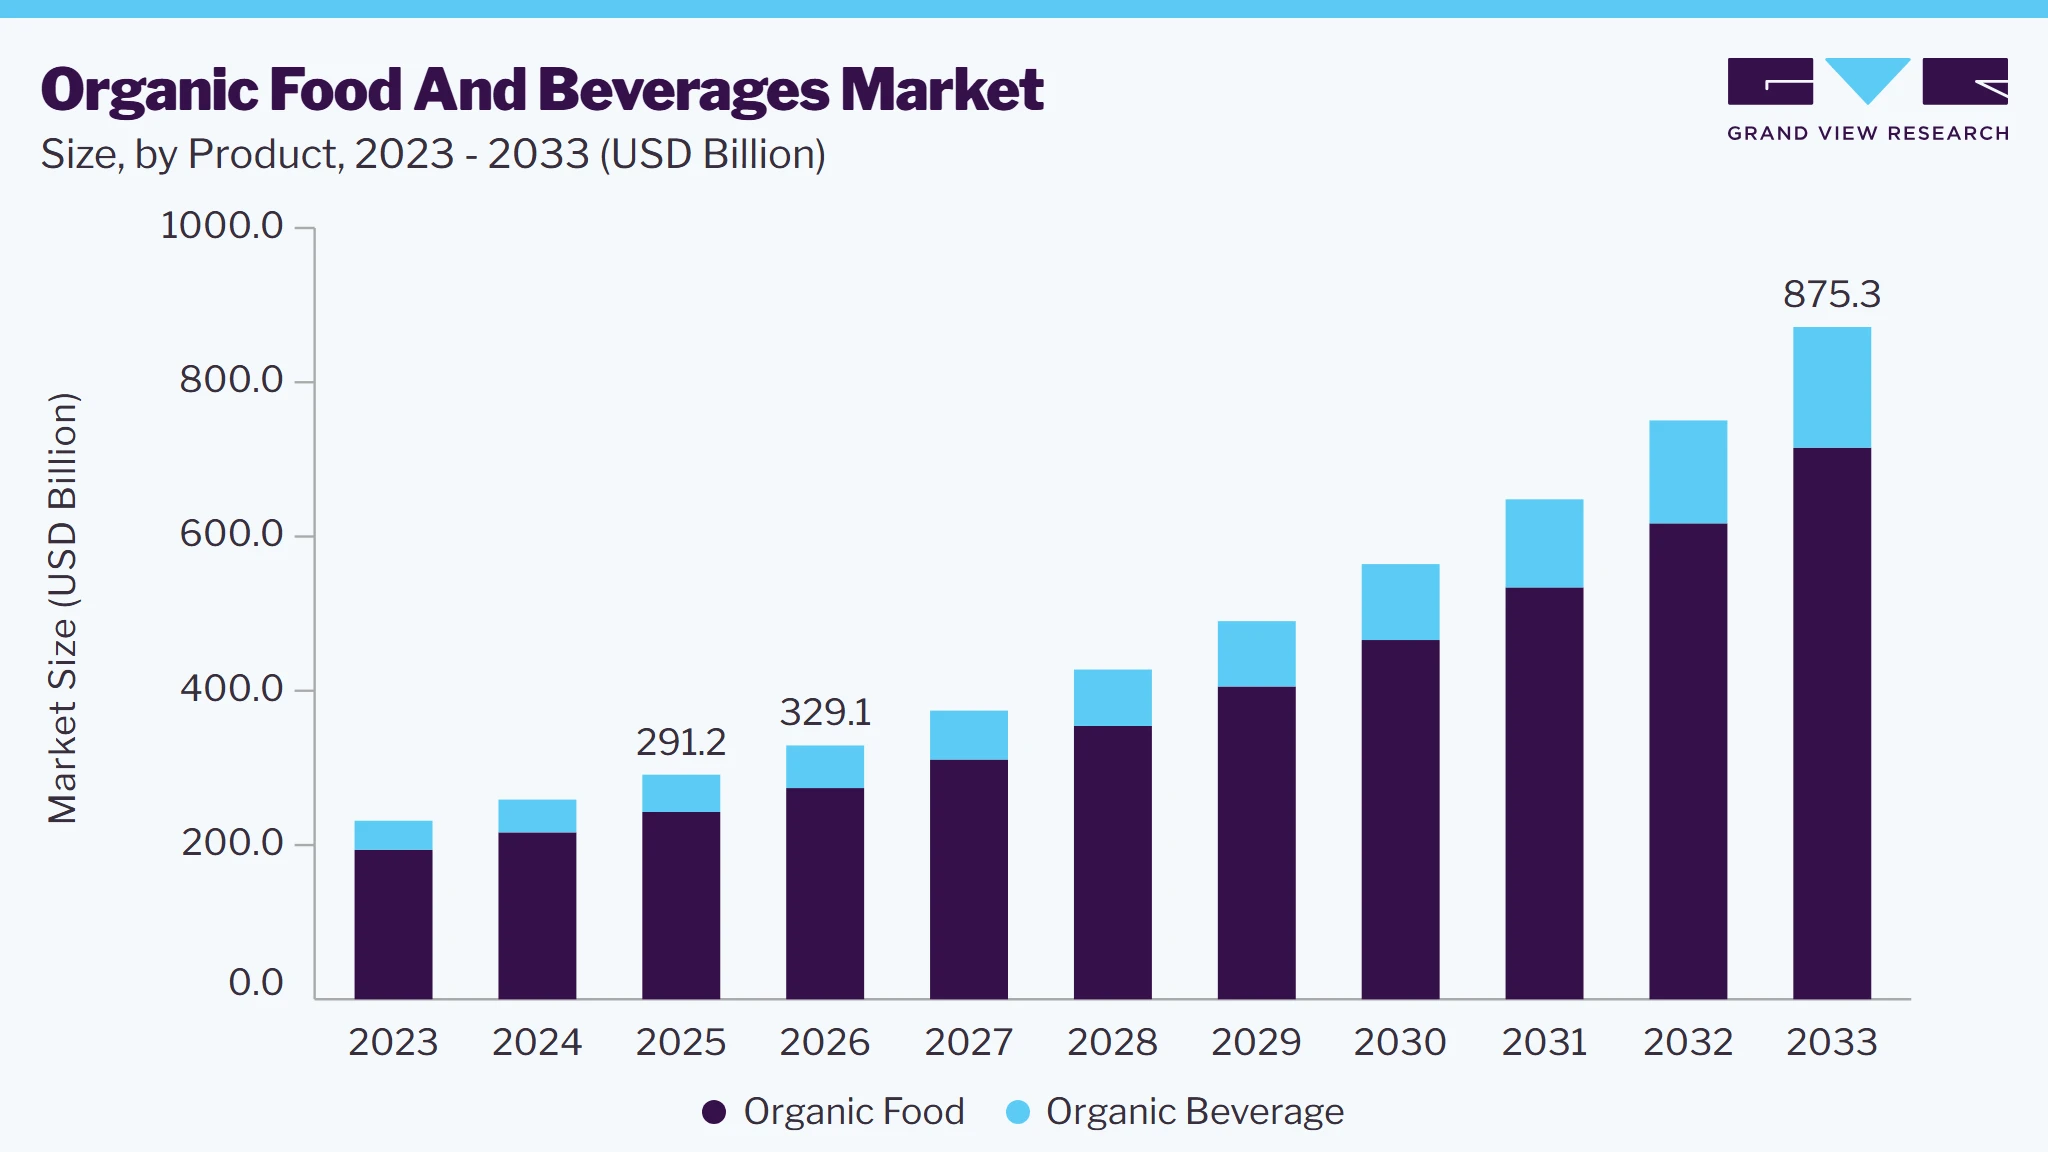 To learn more about this report, Download Free Sample Report
The demand for organic ingredients has grown over the past few years owing to the desire for improved overall health among consumers and the awareness regarding the harmful effects of synthetic ingredients. Several health risks are associated with the use of conventional foods, owing to the presence of synthetic chemicals, such as pesticides and antibiotics, in animals and plants respectively. In addition, government participation in helping consumers to understand the difference between falsely labeled products and legitimate ones has also contributed toward overall market development. The government in some parts of the globe has also issued certain guidelines barring the use of chemicals, pesticides, growth hormones, and other synthetic chemicals to promote the cultivation of organic products.
Moreover, the government in India is encouraging organic farming by offering incentives to cultivators of organic food products under the National Horticulture Mission (NHM) at Rs. 10,000/- per hectare for a maximum area of four hectares per beneficiary and organic farming certification at Rs. 5.00 lakh for a group of farmers covering an area of 50 hectares in India. The negative impact of conventional farming practices has far exceeded its positive results. Water contamination in oceans is one of the after-effects of conventional farming in addition to pesticide-resistant pests, degrading soil fertility, rampant human diseases, expensive cleanups, and dead zones. Regulatory support for biological farming and supply trade regulations are expected to have a positive influence on market growth over the long term.
The intensification of the traditional farming system has generated a need for organic farming methods to maintain healthy soil in the long run. However, the high cost of production and operations and shorter shelf life are projected to constraint the market growth over the forecast years. Moreover, premium pricing of products limiting widespread customer acceptance and limited options to choose from the product assortments are hampering the market expansion. High packaging, logistics, and distribution costs to extend shelf life are also restricting market growth.
Market Dynamics
The organic food and beverages market is experiencing sustained growth as consumers increasingly prioritize products made without synthetic pesticides, artificial fertilizers, genetically modified organisms (GMOs), or chemical additives. Rising awareness of nutrition, environmental sustainability, and food safety has encouraged demand for organic fruits, vegetables, dairy products, beverages, cereals, snacks, and packaged foods. Growing preference for clean-label products, combined with expanding retail availability and stronger certification standards, continues to support long-term market expansion across both developed and emerging economies.
The increasing focus on preventive healthcare and healthier dietary habits is a major factor driving the organic food and beverages market. Consumers are becoming more conscious of ingredient transparency, food quality, and the potential health risks associated with excessive consumption of artificial preservatives, pesticides, and chemical additives. Rising incidences of obesity, diabetes, cardiovascular diseases, and digestive disorders have further encouraged the adoption of organic food products as part of balanced lifestyles. Demand is particularly strong among younger consumers, families with children, and urban populations seeking minimally processed foods. According to the Food and Agriculture Organization (FAO), global organic agricultural land has continued to expand alongside rising consumer awareness and demand for sustainably produced food. Increasing disposable incomes, wider product availability, and supportive government initiatives promoting organic farming are expected to further strengthen market growth over the coming years.
The organic food and beverages market faces notable challenges due to the relatively high cost of organic products and limitations in supply availability. Organic farming generally requires greater labor input, longer production cycles, strict certification procedures, and lower crop yields compared with conventional agriculture, resulting in higher production costs. These additional expenses are often reflected in retail pricing, making organic products less affordable for price-sensitive consumers. Limited availability of certified organic farmland, seasonal production variability, and challenges in maintaining a consistent supply also affect product accessibility across several regions. Furthermore, certification requirements and compliance costs can discourage small-scale farmers from transitioning to organic cultivation. These factors collectively restrict broader consumer adoption, particularly in developing economies where affordability remains a key purchasing consideration.
Continuous product innovation and the rapid growth of e-commerce platforms are creating significant opportunities for the organic food and beverages market. Manufacturers are expanding their portfolios with organic plant-based beverages, functional foods, dairy alternatives, ready-to-eat meals, baby foods, and protein-rich snacks to address evolving consumer preferences. Growing demand for convenient, nutritious, and sustainably sourced products is encouraging investments in new formulations and premium product offerings. At the same time, online grocery platforms and direct-to-consumer sales channels are improving product accessibility by offering wider assortments, subscription services, and home delivery options. Increasing adoption of digital shopping, combined with greater consumer awareness of organic certifications and environmentally responsible production practices, is expected to strengthen market penetration and create new growth opportunities for organic food and beverage manufacturers worldwide.
Market Concentration & Characteristics
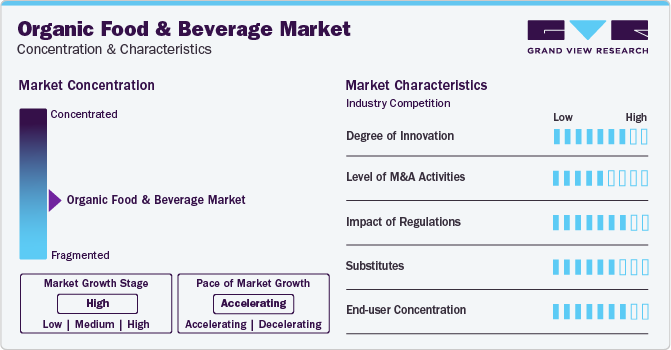
The organic food and beverage market has witnessed a remarkable degree of innovation, with a surge in novel products incorporating sustainable practices, advanced production techniques, and diverse ingredients. From plant-based alternatives to eco-friendly packaging, the industry continues to evolve, meeting consumer demands for both health-conscious and environmentally friendly choices.
 To learn more about this report, Download Free Sample Report
The market has experienced notable M&A activities, reflecting a dynamic industry landscape. Companies are strategically acquiring or merging to capitalize on the growing consumer demand for organic products, fostering innovation and market consolidation within the sector.
Stringent regulations in this market have significantly influenced industry dynamics, ensuring higher standards for production, labeling, and certification. These regulations enhance consumer trust, drive transparency, and encourage sustainable practices, ultimately fostering the growth of the organic sector while posing challenges for non-compliant businesses.
In the organic food and beverage market, the availability of substitutes is limited due to the unique characteristics of organic products, such as absence of synthetic pesticides and genetically modified organisms. While conventional alternatives exist, the distinct consumer preference for organic options and the stringent certification standards create a niche market with few direct substitutes.
The organic food and beverage market typically exhibits a dispersed end-user concentration, with a diverse consumer base seeking healthier and sustainable food options. This trend is driven by a growing awareness of environmental concerns, health consciousness, and a preference for organic and natural products among consumers from various demographic segments.
Analyst Perspective
The organic food and beverage market is entering a phase where competitive differentiation will increasingly depend on supply chain transparency, certification credibility, and portfolio diversification rather than premium positioning alone. As regulatory oversight strengthens and demand expands across both developed and emerging economies, companies with scalable organic sourcing networks, resilient agricultural partnerships, and continuous product innovation will be better positioned to capture market share. Long-term value creation is expected to favor participants that successfully balance sustainability commitments with operational efficiency, enabling consistent product availability while protecting margins in an increasingly competitive global marketplace.
Product Insights
Based on product, the organic food segment led the market with the largest revenue share of 89.4% in 2025. The trend of organic vegetables was initiated in developed regions, including North America and Europe, and has extended to emerging economies, such as India and China. North America and Europe are the largest consumers of organic foods. The consumption of organic meat, fish & poultry products is expected to grow at the highest CAGR of 16.7% from 2026 to 2033. Increasing concerns regarding artificial preservatives and additives are anticipated to augment the product demand over the forecast years.
The organic beverages segment includes non-dairy beverages, coffee & tea, beer & wine, and others including juices and soft drinks. The organic beverages segment is poised to grow exponentially as consumers opt for natural drinks over carbonated beverages owing to various health benefits. Non-dairy beverages led the segment in 2025. Increasing adoption of vegan culture is also likely to boost segment growth. Coffee & tea sales are anticipated to grow at the highest CAGR of 18.1% from 2026 to 2033 due to the high consumption of flavored tea and coffee.
Distribution Channel Insights
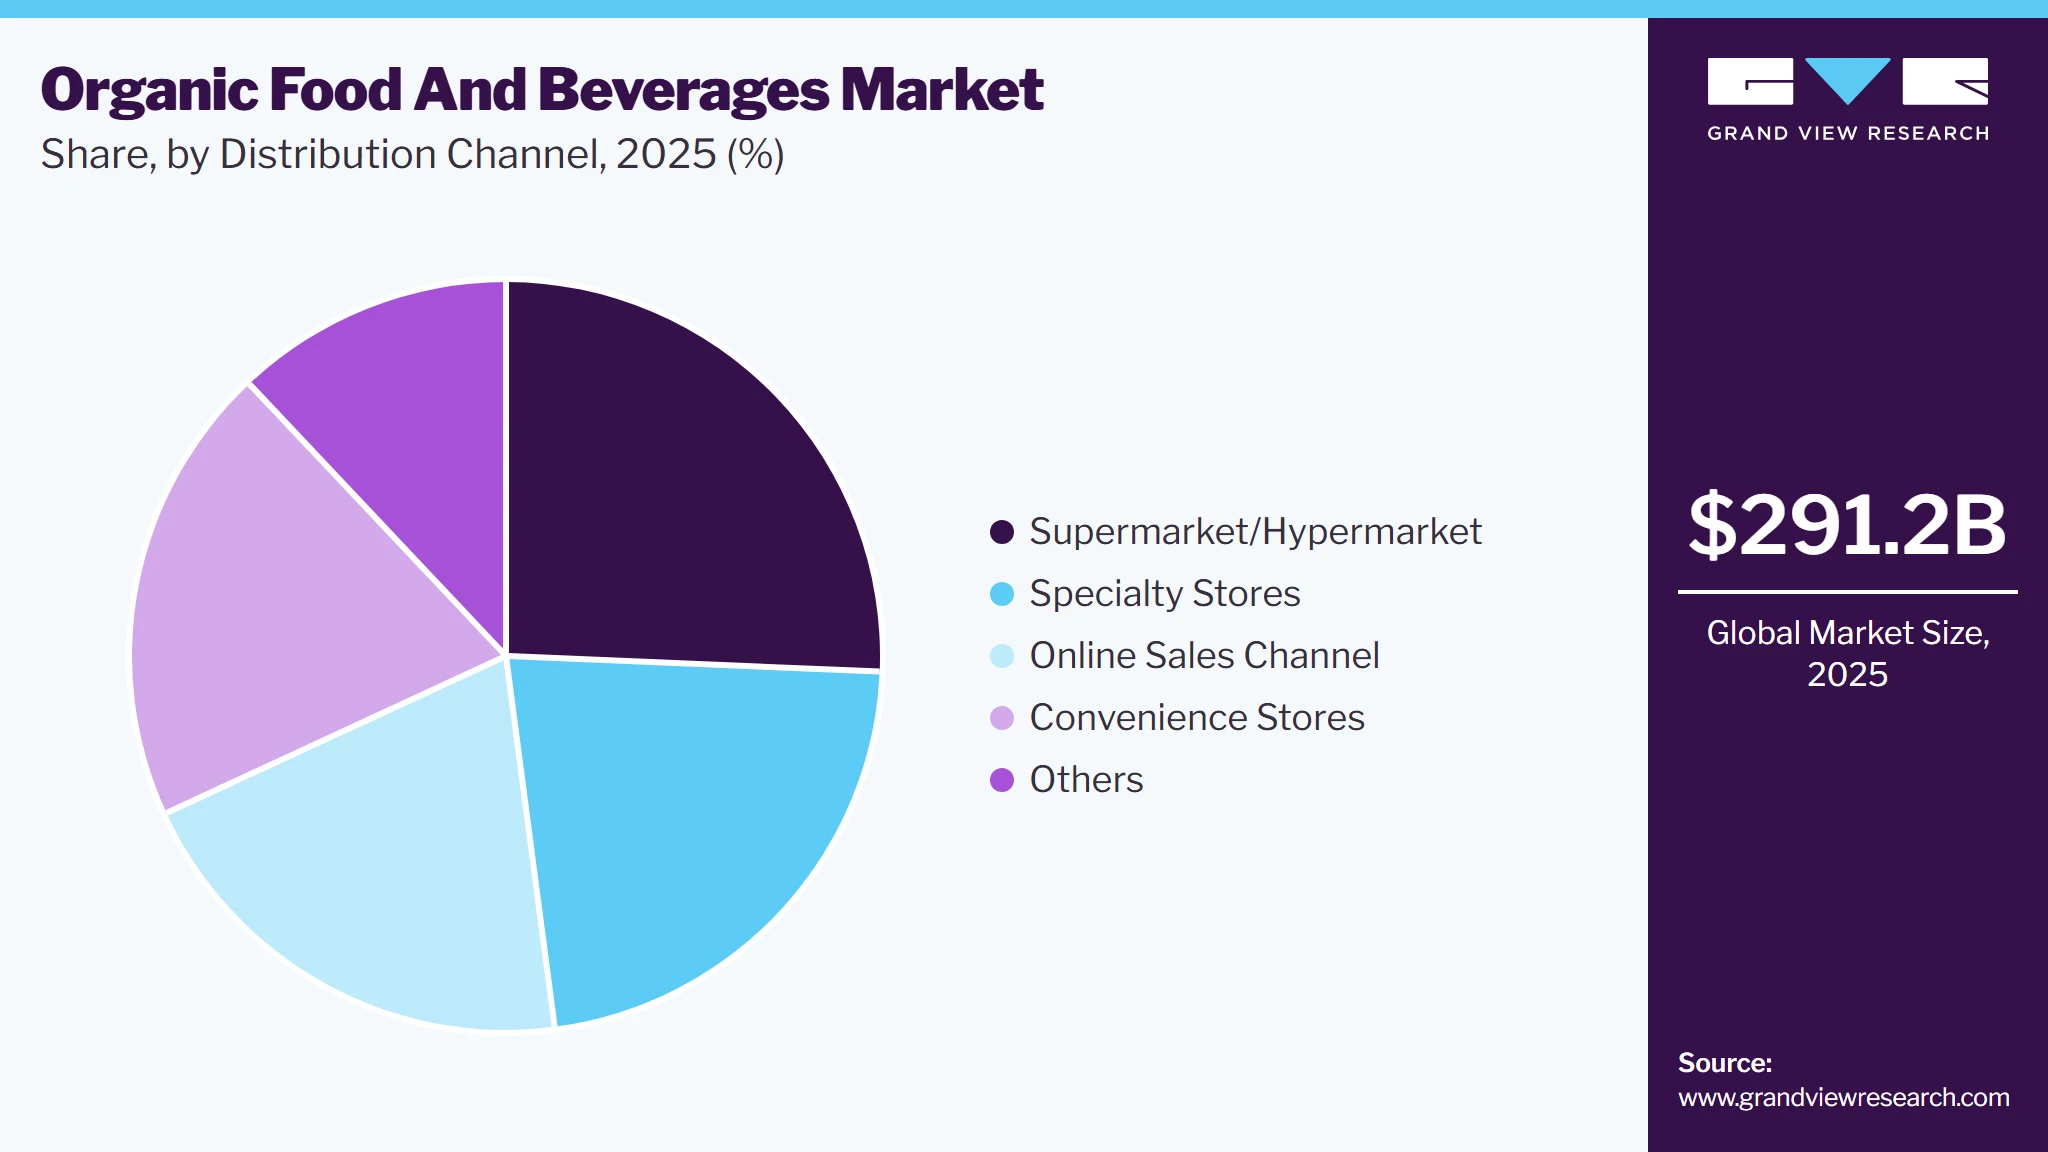
Based on distribution channel, the supermarkets/hypermarkets led the market with the largest revenue share of 25.7% in 2025. Consumers increasingly prefer purchasing organic food and beverages from large retail stores because they can find a wide variety of certified products in one place. Fresh fruits and vegetables, dairy products, and other daily essentials are commonly available, making it easier to include organic options in regular grocery shopping. Retailers are expanding their organic product portfolios by introducing private-label ranges, increasing shelf space for certified products, and working closely with certified organic suppliers. Frequent promotional offers, loyalty programs, and consistent product availability continue to encourage consumer purchases, supporting the growth of this distribution channel in the organic food and beverage market.
 To learn more about this report, Download Free Sample Report
The online distribution channel segment is projected to grow at a CAGR of 17.2% from 2026 to 2033. Rising internet penetration and target marketing done by companies to reach all customer touchpoints are likely to fuel the growth of this segment. The trend of online sales and subscription boxes for organic produce has grown significantly in the last two years, which is expected to have a positive effect on market growth. Rapid penetration of online groceries and online food delivery platforms coupled with the surge in the adoption of smartphones further triggers segment growth.
Regional Insights
Availability of farmlands for organic farming in the U.S., Australia, and Argentina has forced the regulators to frame supportive policies to increase production output of organic foods. This factor in turn is projected to have a positive impact on organic food and beverages market demand over the forecast period. The North American organic food & beverages market made a larger contribution in the global market of 49.8% in 2025 owing to the unique advantages associated with the products, such as being eco-friendly, zero chemical and residue-free, and healthier compared to conventional food.
Increasing consumer awareness regarding the benefits of non-genetically modified or engineered products intake is anticipated to fuel the North America market in the near future.
 To learn more about this report, Download Free Sample Report
The Asia Pacific organic food & beverages market is expected to grow at a CAGR of 19.0% from 2026 to 2033, driven by the rising trend of ready-to-eat foods among the working-class people as well as high millennial population in countries, such as India. China, India, and Japan are the major markets, in terms of consumer spending on food. Moreover, a substantial rise in the demand for frozen food owing to less time for preparation and cooking is opening new avenues for the regional market for organic frozen food. The Europe organic food and beverages market is anticipated to grow at a CAGR of 13.8% from 2026 to 2033. The organic food and beverages market in Europe has witnessed a significant shift in consumer attitudes toward sustainability and ethical consumption.
Many consumers are now prioritizing products that are produced in an environmentally responsible manner, which includes organic farming practices. Organic agriculture promotes biodiversity, and soil health, and reduces the use of synthetic fertilizers and pesticides, aligning with the values of environmentally conscious consumers. According to a 2023 market report by the Soil Association Certification, the organic market in the UK has shown significant growth owing to the cost-of-living crisis, with sales increasing by 1.6% in 2022. This market growth was driven by strong performance in the food service sector, which witnessed sales increase by 152%.
However, sales of organic foods and drinks in supermarkets, independent retailers, and home delivery were mixed. Furthermore, as per the findings of the Meatless Farm Report, the organic market remains on an upward trajectory despite facing obstacles. Notably, there is a remarkable surge in the demand for sustainable shopping among consumers, indicating a robust interest in eco-friendly practices. Interestingly, the report highlights that customers are increasingly seeking organic goods that are reasonably priced and easily accessible. This implies a favorable outlook for the organic market, suggesting sustained growth in the foreseeable future.
South Africa organic food & beverages market
The organic food & beverages market in South Africa is poised for growth due to an increasing awareness of sustainable farming practices and a rising demand for ethically-sourced products. Factors unique to the country's trends include a growing emphasis on biodiversity preservation, ethical farming, and the promotion of local, organic agriculture.
Canada organic food & beverages market
The organic food & beverages market in Canada is driven by government initiatives promoting organic farming practices. In March 2022, the Minister of Agriculture and Agri-Food declared a financial commitment of up to USD 103,400 to support the Organic Federation of Canada, facilitating a novel collaboration aimed at advancing sustainability and fostering growth within Canada's organic industry.
Germany organic food & beverages market
The organic food & beverages market in Germany is projected to grow at CAGR of 14.9% from 2026 to 2033. Trade expos and exhibitions contribute by serving as platforms for showcasing organic products, fostering industry connections, and educating consumers.For example, Nuremberg, Germany hosts the annual BioFach worldwide trade show for organic food and agriculture. In 2023, the expo drew over 36,000 trade visitors from 135 countries.
India organic food & beverages market
The organic food & beverages market in India is projected to grow at CAGR of 21.7% from 2026 to 2033. India exported 1,978,460.38 million tons (mt) of organic products worth USD 2,480.24 million between 2019-20 and 2021-2022. Of these exports, the U.S. received about 50% and the European Union (EU) received 37%.
Key Organic Food And Beverages Company Insights
The global organic and food beverages market is characterized by a plethora of players ranging from established organic brands to new entrants, reflecting the industry's dynamic nature. Some prominent players in this market are Hain Celestial, Dole Food Company, Inc., Danone, Nestlé, General Mills Inc., Gujarat Cooperative Milk Marketing Federation (Amul), and more. Key factors influencing competition include product innovation, certification standards, and strategic alliances to capture a share of the expanding market driven by increasing consumer demand for organic and sustainable choices.
Key Organic Food and Beverage Companies:
The following key companies have been profiled for this study on the organic food and beverages market.
- Hain Celestial
- Whole Foods Market L.P.
- Dole Food Company, Inc.
- Dairy Farmers of America, Inc.
- General Mills Inc.
- Danone
- United Natural Foods, Inc.
- Gujarat Cooperative Milk Marketing Federation (Amul)
- The Hershey Company
- Amy’s Kitchen, Inc.
- Organic Valley
- Conagra Brands, Inc.
- Nestlé
- Eden Foods
- SunOpta
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Hain Celestial; General Mills Inc.; Danone; Nestlé; Conagra Brands, Inc.; The Hershey Company; Dairy Farmers of America, Inc.; Gujarat Cooperative Milk Marketing Federation (Amul))
- Expand organic product portfolios through acquisitions, product innovation, and sustainable sourcing initiatives. Strengthen retail distribution, e-commerce presence, and certification compliance while investing in clean-label and plant-based offerings.
- Strong brand recognition, extensive global distribution networks, and diversified product portfolios. High investment capacity for R&D, marketing, and large-scale organic sourcing ensures market leadership.
- High production and certification costs, dependence on organic raw material availability, and slower adaptation to emerging niche consumer trends due to large operational structures.
Emerging & Specialty Organic Players (Organic Valley; Amy’s Kitchen, Inc.; Eden Foods; SunOpta; Whole Foods Market L.P.; United Natural Foods, Inc.; Dole Food Company, Inc.)
- Focus on premium organic products, transparent sourcing, and sustainability-driven branding. Expand through specialty retail, direct-to-consumer channels, and strategic partnerships while targeting health-conscious consumers with innovative organic offerings.
- Strong reputation in the organic segment, greater flexibility in responding to consumer preferences, and differentiated products with high authenticity and sustainability appeal.
- Limited geographic reach, lower marketing budgets, and higher dependence on premium pricing, making growth vulnerable to economic downturns and increasing competition from multinational brands.
Recent Developments
-
In October 2023, Dole Food Company, Inc. unveiled the establishment of Dole Organics, a specialized division, and introduced its 'GO Organic!' consumer brands at Fruit Attraction 2023 in Madrid in October. Focused on revitalizing the organic fresh produce category, Dole Organics aims to foster cross-sector collaboration, streamline supply chains, and ensure the ongoing continuity and consistency of organic products.
-
In April 2023, So Delicious Dairy Free, a division of Danone North America, unveiled its inaugural entry into the oatmilk segment with the introduction of Organic Oatmilk. Crafted from organic oats and various ingredients, the product is available in two variants: Original and Extra Creamy.
-
In February 2022, Amul, a dairy company in India, entered the organic food market by launching organic rice, flour, honey, chocolates, and potato products. They also plan to set up a "green college" to educate young farmers about natural and organic farming and create "organic haats" to sell organic products
-
In May 2022, Organic India, a leading organic tea and wellness brand, launched two new varieties of tea and infusion: Tulsi Detox Kahwa and Peppermint Refresh. Both teas are certified organic and vegan, and they are available in loose-leaf and teabag formats. The launch of these new teas is part of Organic India's mission to offer consumers healthy and sustainable wellness products
Organic Food and Beverage Market Report Scope
Report Attribute
Details
Market size in 2025
USD 291.2 billion
Estimated market size in 2026
USD 329.1 billion
Projected market size by 2033
USD 875.3 billion
Growth rate
CAGR of 15.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; Russia; Iceland; Finland; China; Japan; India; South Korea; Australia; Thailand; Singapore; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait; Israel
Key companies profiled
Hain Celestial; Whole Foods Market L.P.; Dole Food Company, Inc.; Dairy Farmers of America, Inc.; General Mills Inc.; Danone; United Natural Foods, Inc.; Gujarat Cooperative Milk Marketing Federation (Amul); The Hershey Company; Amy’s Kitchen, Inc.; Organic Valley; Conagra Brands, Inc.; Nestlé; Eden Foods; SunOpta
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Organic Food And Beverages Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global organic food and beverage market report on the basis of product, distribution channel, and region.
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Organic Food
-
Fruits & Vegetables
-
Meat, Fish & Poultry
-
Dairy Products
-
Frozen & Processed Food
-
Others
-
-
Organic Beverages
-
Non-dairy Beverages
-
Coffee & Tea
-
Beer & Wine
-
Others
-
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Supermarket/Hypermarket
-
Specialty Stores
-
Convenience Stores
-
Online Sales Channel
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
Australia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The organic food and beverages market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each organic food and beverages segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Organic Food
This segment includes the sales of organically produced fruits, vegetables, dairy, cereals, meat, snacks, and packaged foods. These products are made without synthetic pesticides, fertilizers, GMOs, or artificial additives.
Organic Beverage
This segment includes the sales of organically produced juices, tea, coffee, dairy and plant-based drinks. These beverages are made using certified organic ingredients without synthetic chemicals or artificial preservatives.
Estimation Model
Layer Name
Key Question
Description
Consumer Base Layer
Who prefers healthier and organic food choices?
Identify consumers prioritizing clean-label nutrition, chemical-free ingredients, sustainability, preventive wellness, and healthier diets to establish the potential organic consumer base.
Market Access Layer
Who can conveniently purchase organic products?
Assess product availability through supermarkets, specialty stores, online platforms, and certified retail networks to determine the accessible organic consumer population.
Adoption Layer
Who buys organic food and beverages?
Evaluate purchasing frequency, affordability, health awareness, and premium acceptance to estimate consumers consistently choosing certified organic food and beverages.
Monetisation Layer
How much revenue is generated?
Multiply recurring buyers by annual spending across organic categories while incorporating institutional procurement to estimate total market revenue.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Organic Food Demand & Consumption Analysis
Examined consumption patterns across organic fruits and vegetables, dairy, beverages, cereals, snacks, and packaged foods by evaluating dietary preferences, clean-label demand, and purchasing trends across key regional markets.
Enables businesses to identify fast-growing product segments, understand changing consumer preferences, and prioritize product development and market expansion initiatives.
Retail Channel & Consumer Buying Assessment
Analyzed the performance of supermarkets, specialty retailers, online platforms, direct-to-consumer channels, and organic stores while evaluating purchasing behavior, price sensitivity, and repeat buying trends.
Delivers actionable insights for optimizing distribution strategies, improving channel performance, and strengthening customer acquisition and retention across multiple sales platforms.
Organic Supply Ecosystem & Regulatory Assessment
Investigated organic certification frameworks, sustainable sourcing practices, agricultural production capacity, supply chain resilience, and trade dynamics influencing long-term market competitiveness.
Assists strategic planning by highlighting regulatory requirements, supply chain improvements, sourcing opportunities, and investment areas that support sustainable business growth.
Frequently Asked Questions About This Report
The global organic foods and beverages market size was valued at USD 291.2 billion in 2025 and is estimated at USD 329.1 billion in 2026
The organic food led with a 89.4% revenue share in 2025 and is the fastest-growing segment.
Based on the distribution channel, the supermarkets/hypermarkets led the market with the largest revenue share of 25.7% in 2025.
The global organic foods and beverages market is expected to grow at a CAGR of 15.0% from 2026 to 2033, reaching USD 875.3 billion by 2033.
North America dominated with a 49.8% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
Key players include Hain Celestial; Whole Foodss Market L.P.; Dole Foods Company, Inc.; Dairy Farmers of America, Inc.; General Mills Inc.; Danone; United Natural Foodss, Inc.; Gujarat Cooperative Milk Marketing Federation (Amul); The Hershey Company; Amy’s Kitchen, Inc.; Organic Valley; Conagra Brands, Inc.; Nestlé; Eden Foodss; SunOpta
Key factors include increasing health awareness, rising demand for natural and clean-label products, growing environmental concerns, and wider availability of organic products through retail and online channels.
About the Author(s)
Consumer F&B Research Team
Consumer Goods · Consumer F&BThis report was authored by the consumer f&b research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the consumer f&b segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


