
- Home
- »
- Plastics, Polymers & Resins
- »
-
Organosilicon Polymers Market Size Report, 2026-2033GVR Report cover

Organosilicon Polymers Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product Type (Silicone Resin, Silicone Rubber, Silicone Oil, Silicone Emulsion), By Application (Coatings, Foams, Adhesives & Sealants, Elastomers), By Region, And Segment Forecasts
Market Size, 2025
$18.6BMarket Estimate, 2026
$19.3BMarket Forecast, 2033
$27.8BCAGR, 2026–2033
5.4%Organosilicon Polymers Market Summary
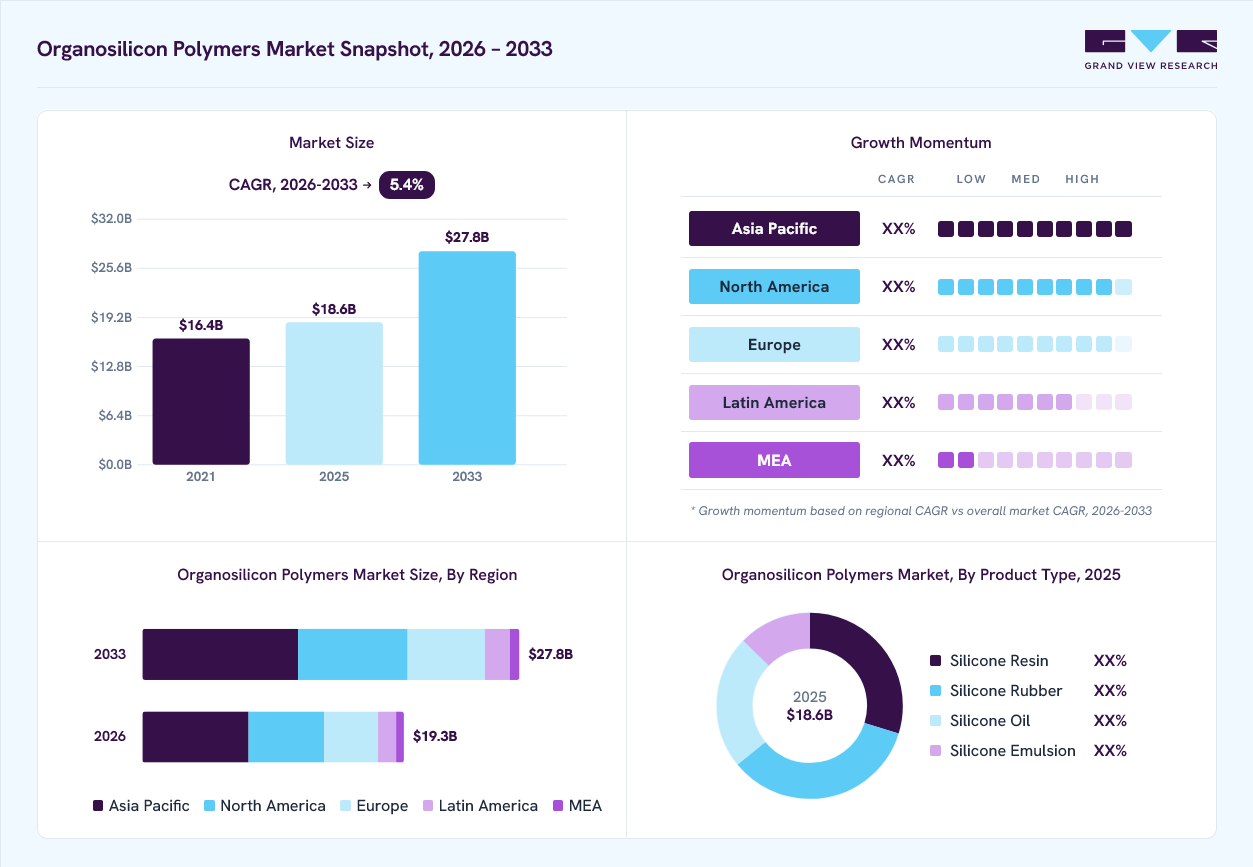
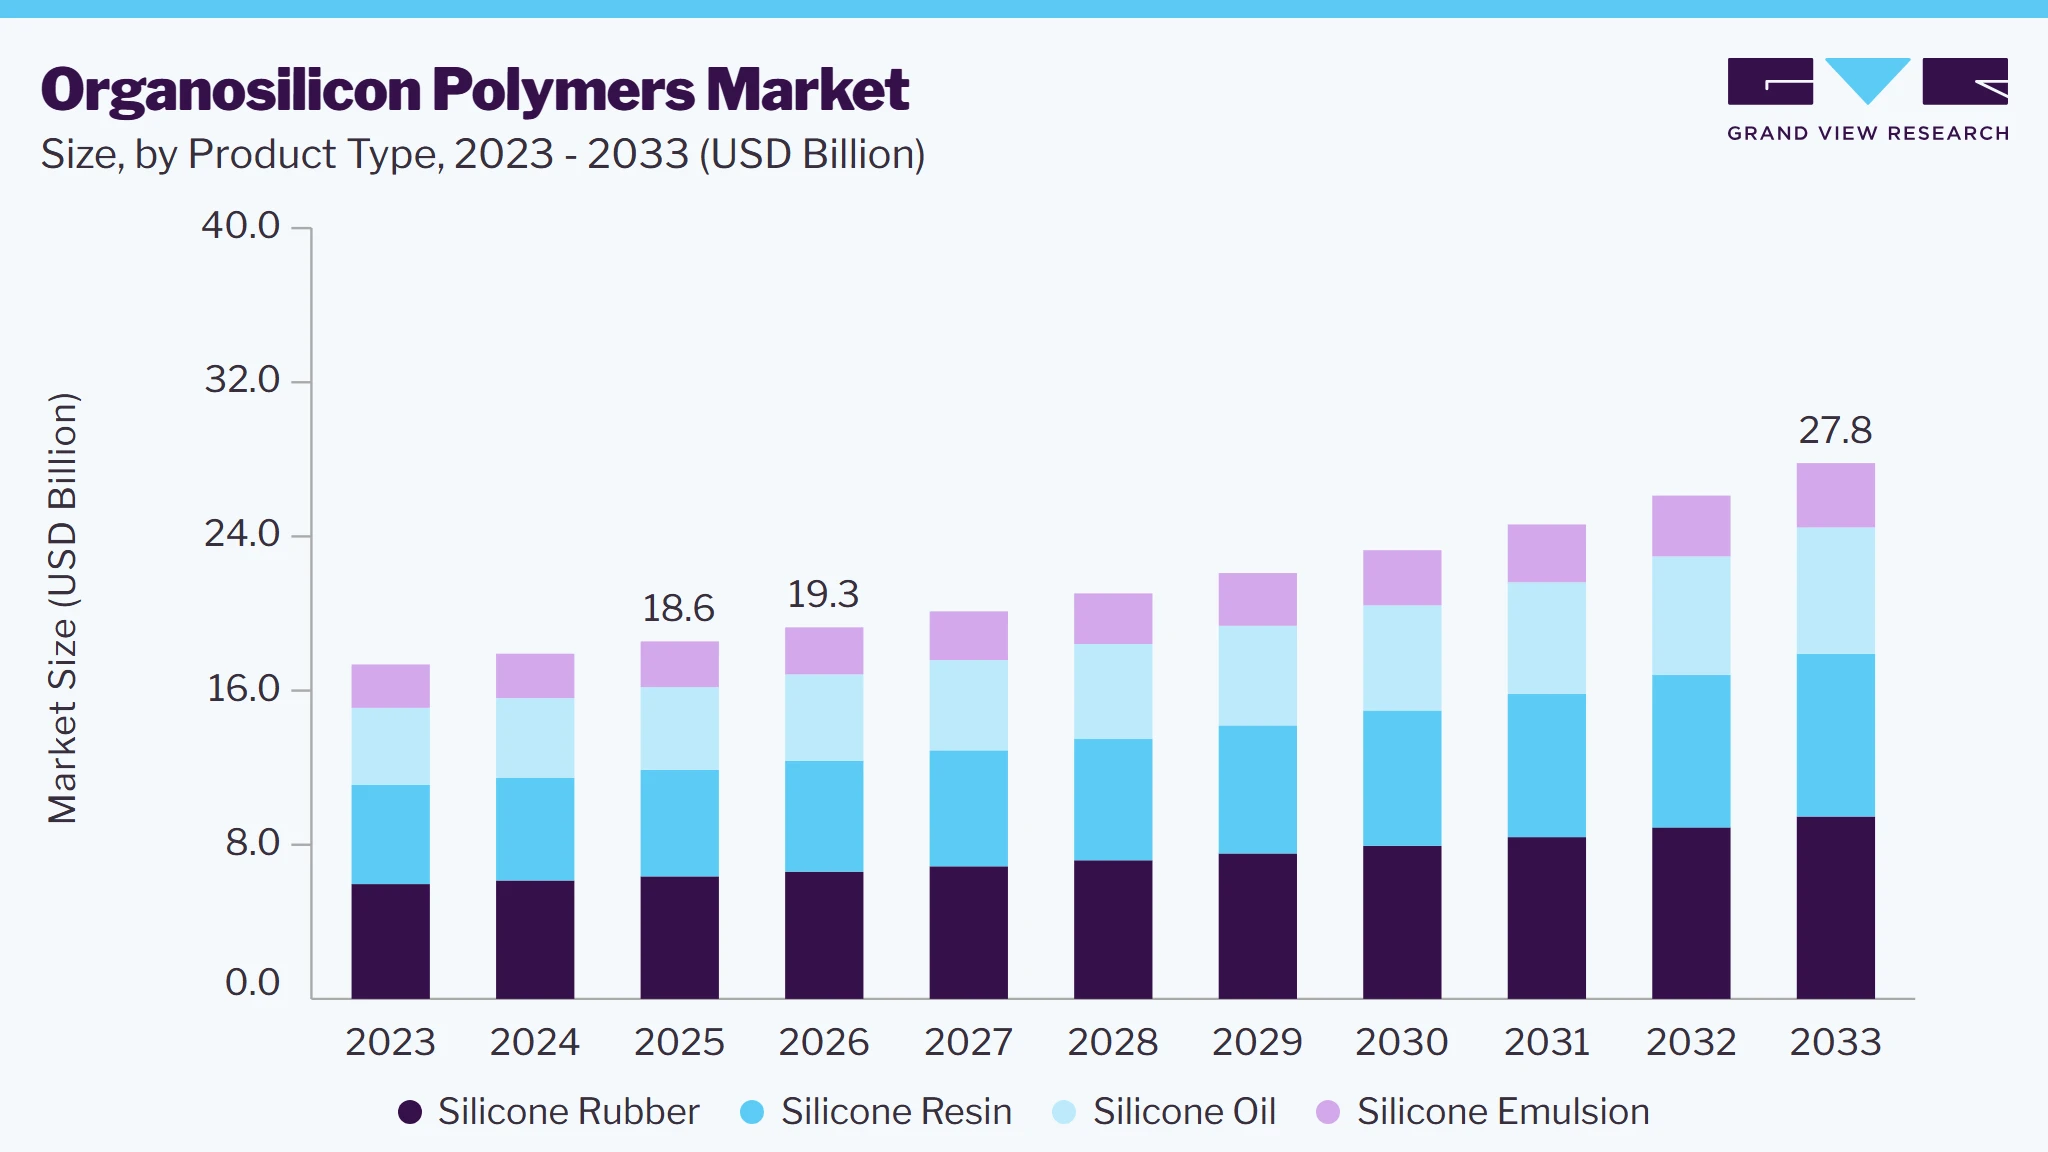
The global organosilicon polymers market size was valued at USD 18.6 billion in 2025 and is projected to grow from USD 19.3 billion in 2026 to USD 27.8 billion by 2033, at a CAGR of 5.4% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 40.5% in 2025. Increasing adoption of electronics and expanding use of organosilicon polymers across smartphones, wearables, semiconductors, automotive, aerospace, construction, and industrial coatings are driving the organosilicon polymers market growth.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product type: Silicone rubber segment dominated the market, with a revenue share of 34.3% in 2025.
- By application: Coatings segment held the largest market share of 33.4% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (40.5% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 18.6 Billion
- Estimated market size in 2026: USD 19.3 Billion
- Projected market size by 2033: USD 27.8 Billion
- CAGR (2026-2033): 5.4%
Prism AI by Grand View Research Free to tryAsk a question about the organosilicon polymers marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →Rising demand for high-performance polysiloxane coatings further supports market expansion due to their excellent thermal stability, electrical insulation, weather resistance, chemical durability, and ability to enable low-VOC, long-lasting protective solutions that meet evolving environmental regulations. The organosilicon polymers (polysiloxane) market is witnessing a strong shift toward high-performance coatings, driven by industries such as automotive, aerospace, construction, and electronics. Polysiloxane-based coatings offer superior weather resistance, thermal stability, and chemical durability compared to conventional polymer coatings. With the increasing focus on sustainability, manufacturers are also developing low-VOC (volatile organic compound) and waterborne polysiloxane coatings to meet stringent environmental regulations. As industries continue to demand long-lasting protective solutions, this trend is expected to shape the market’s growth trajectory over the coming years.
 To learn more about this report, Download Free Sample Report
Market Dynamics
The organosilicon polymers market is shaped by steady demand from electronics, high-performance coatings, adhesives, sealants, and elastomers, with Asia Pacific acting as the main demand center and manufacturing base. The market is commercially concentrated around silicone resin and coatings, which support higher-value industrial and performance-grade use cases. Growth is also supported by the shift toward low-VOC and waterborne systems, while leading global producers compete through product breadth, formulation depth, and downstream application support. This structure favors integrated suppliers with strong regional presence and specialty chemistry capabilities.
The strongest market driver is the rising use of polysiloxane materials in electronics, where thermal stability and electrical insulation are critical. Smartphones, wearables, and semiconductors increasingly require silicone-based materials for protection, heat control, and long-life reliability. As device design becomes smaller and more power dense, material performance standards continue to rise, increasing demand for silicone resin, rubber, and oil grades that can support advanced assemblies and encapsulation systems.
This demand is reinforced by the wider shift toward high-performance coatings and electronics-grade formulations across industrial supply chains. In particular, manufacturers are prioritizing materials that can maintain performance under heat, electrical stress, and harsh operating conditions. That creates a durable pull for organosilicon polymers in application environments where conventional polymers cannot meet the same durability, insulation, and weather resistance requirements.
The main restraint is the high cost of polysiloxane production, which depends on complex chemical synthesis, specialized facilities, and high-purity raw materials such as silicon metal and methyl chloride. These inputs are exposed to price swings and supply chain constraints, which can compress margins for producers and raise end-product prices. The resulting cost structure limits penetration in price-sensitive applications and makes scale efficiency essential for commercial competitiveness.
A clear opportunity lies in low-VOC, waterborne, and EV-oriented silicone formulations. The market is increasingly favoring durable coatings and advanced materials that combine sustainability compliance with thermal and electrical performance. Suppliers that can translate organosilicon chemistry into cleaner coating systems, battery insulation, and electronic encapsulation grades are positioned to capture premium demand across industrial and mobility applications.
Analyst Perspective
Over the next 5 to 10 years, the organosilicon polymers market is likely to move from broad industrial consumption toward a more value-led structure centered on electronics, high-performance coatings, medical components, and EV thermal management. The market’s core growth will come from materials that solve thermal, electrical, and durability challenges rather than from volume expansion alone. Asia Pacific will remain the most important demand and production center, while sustainability will increasingly shape purchasing decisions through low-VOC and waterborne products. Competitive advantage will depend on feedstock integration, application-specific formulation capability, IP depth, and regional manufacturing proximity. Leaders will also need stronger customer collaboration in electronics and mobility. The main challenges will remain raw material volatility, high production cost, and margin pressure in standardized grades, which will continue to separate specialty innovators from commodity suppliers.
Product Type Insights
Based on product type, the silicone rubber segment led the market with the largest revenue share of 34.3% in 2025. The increasing demand for high-performance materials in extreme industrial environments is driving the growth of silicone resins. These resins are widely used in heat-resistant paints, adhesives, and insulation materials due to their superior thermal stability and oxidative resistance. Industries such as metallurgy, power generation, and heavy machinery are increasingly adopting silicone resin-based solutions to enhance the durability of components exposed to continuous high heat and chemical stress. With the push for advanced manufacturing and energy-efficient solutions, the adoption of silicone resins in high-temperature applications is expected to expand significantly.
Silicone oil is experiencing strong growth due to its increasing use in personal care and cosmetic formulations, driven by consumer demand for high-performance skincare and haircare products. Its lightweight texture, non-greasy feel, and excellent spreadability make it a preferred ingredient in moisturizers, serums, and anti-aging products. Additionally, the growing preference for long-lasting and water-resistant cosmetics has led to a surge in demand for silicone-based formulations. As beauty and personal care brands focus on innovation and sustainability, the market for silicone oils, including bio-based and naturally derived variants, is poised for steady expansion.
Application Insights
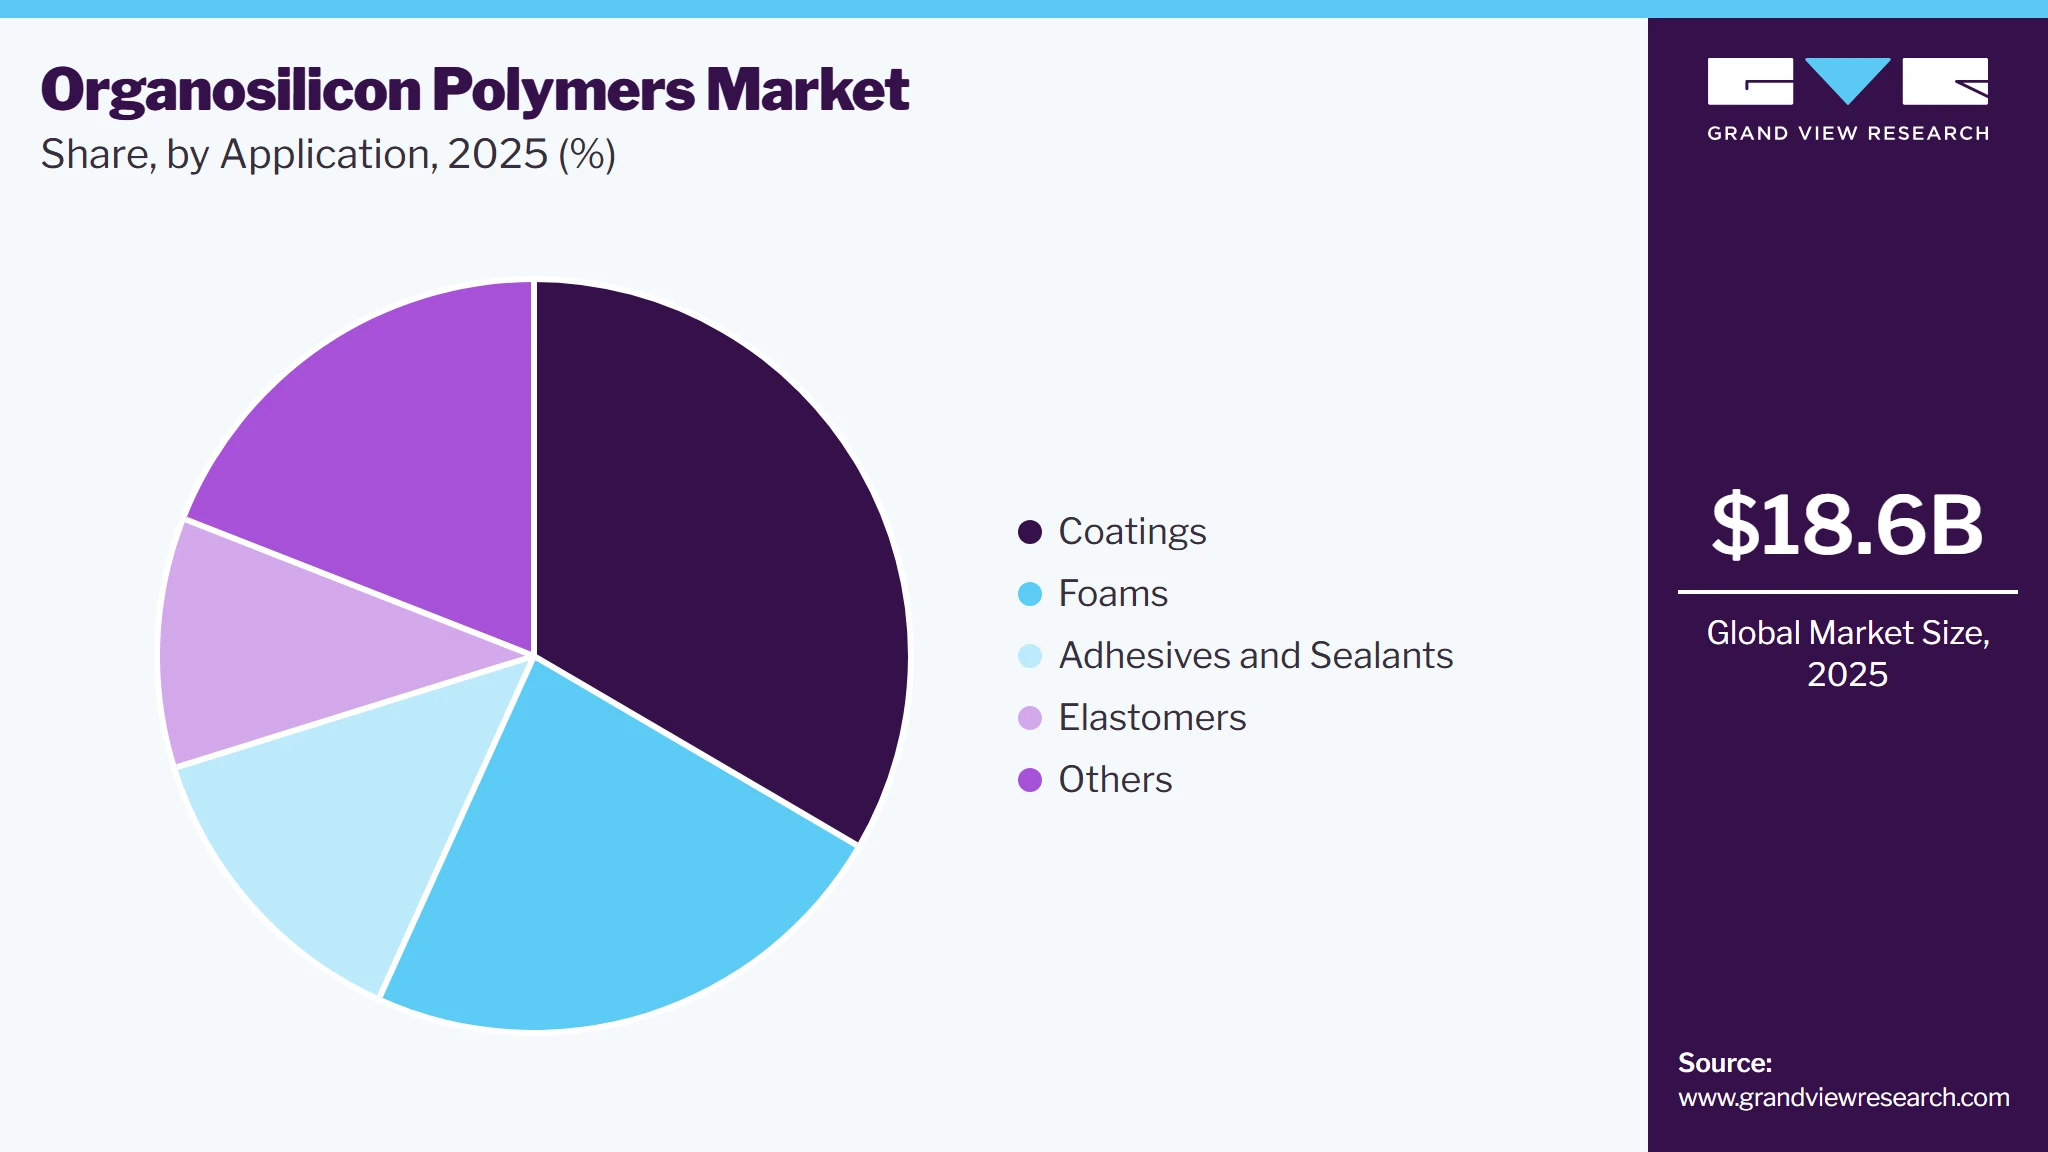
Based on application, the coatings segment led the market with the largest revenue share of 33.4% in 2025 due to the need for advanced corrosion-resistant solutions in infrastructure and industrial applications. Governments and private enterprises are heavily investing in infrastructure modernization, including bridges, highways, and offshore structures, which require long-lasting protective coatings. Silicone-based coatings offer excellent weatherability, UV resistance, and chemical durability, making them ideal for extending the lifespan of critical assets. With increasing global investments in sustainable and smart infrastructure, polysiloxane-based coatings are becoming an essential choice for long-term protection and maintenance efficiency.
 To learn more about this report, Download Free Sample Report
The medical sector is driving significant demand for silicone elastomers, particularly in next-generation medical devices and implants. These elastomers are widely used in prosthetics, medical tubing, and implantable components due to their biocompatibility, flexibility, and resistance to bacterial growth. As healthcare technology advances, the need for high-performance materials that offer durability and patient safety is rising. Additionally, the development of custom-engineered medical-grade silicone elastomers for wearable health monitoring devices and robotic-assisted surgery components is opening new avenues for market expansion.
Regional Insights
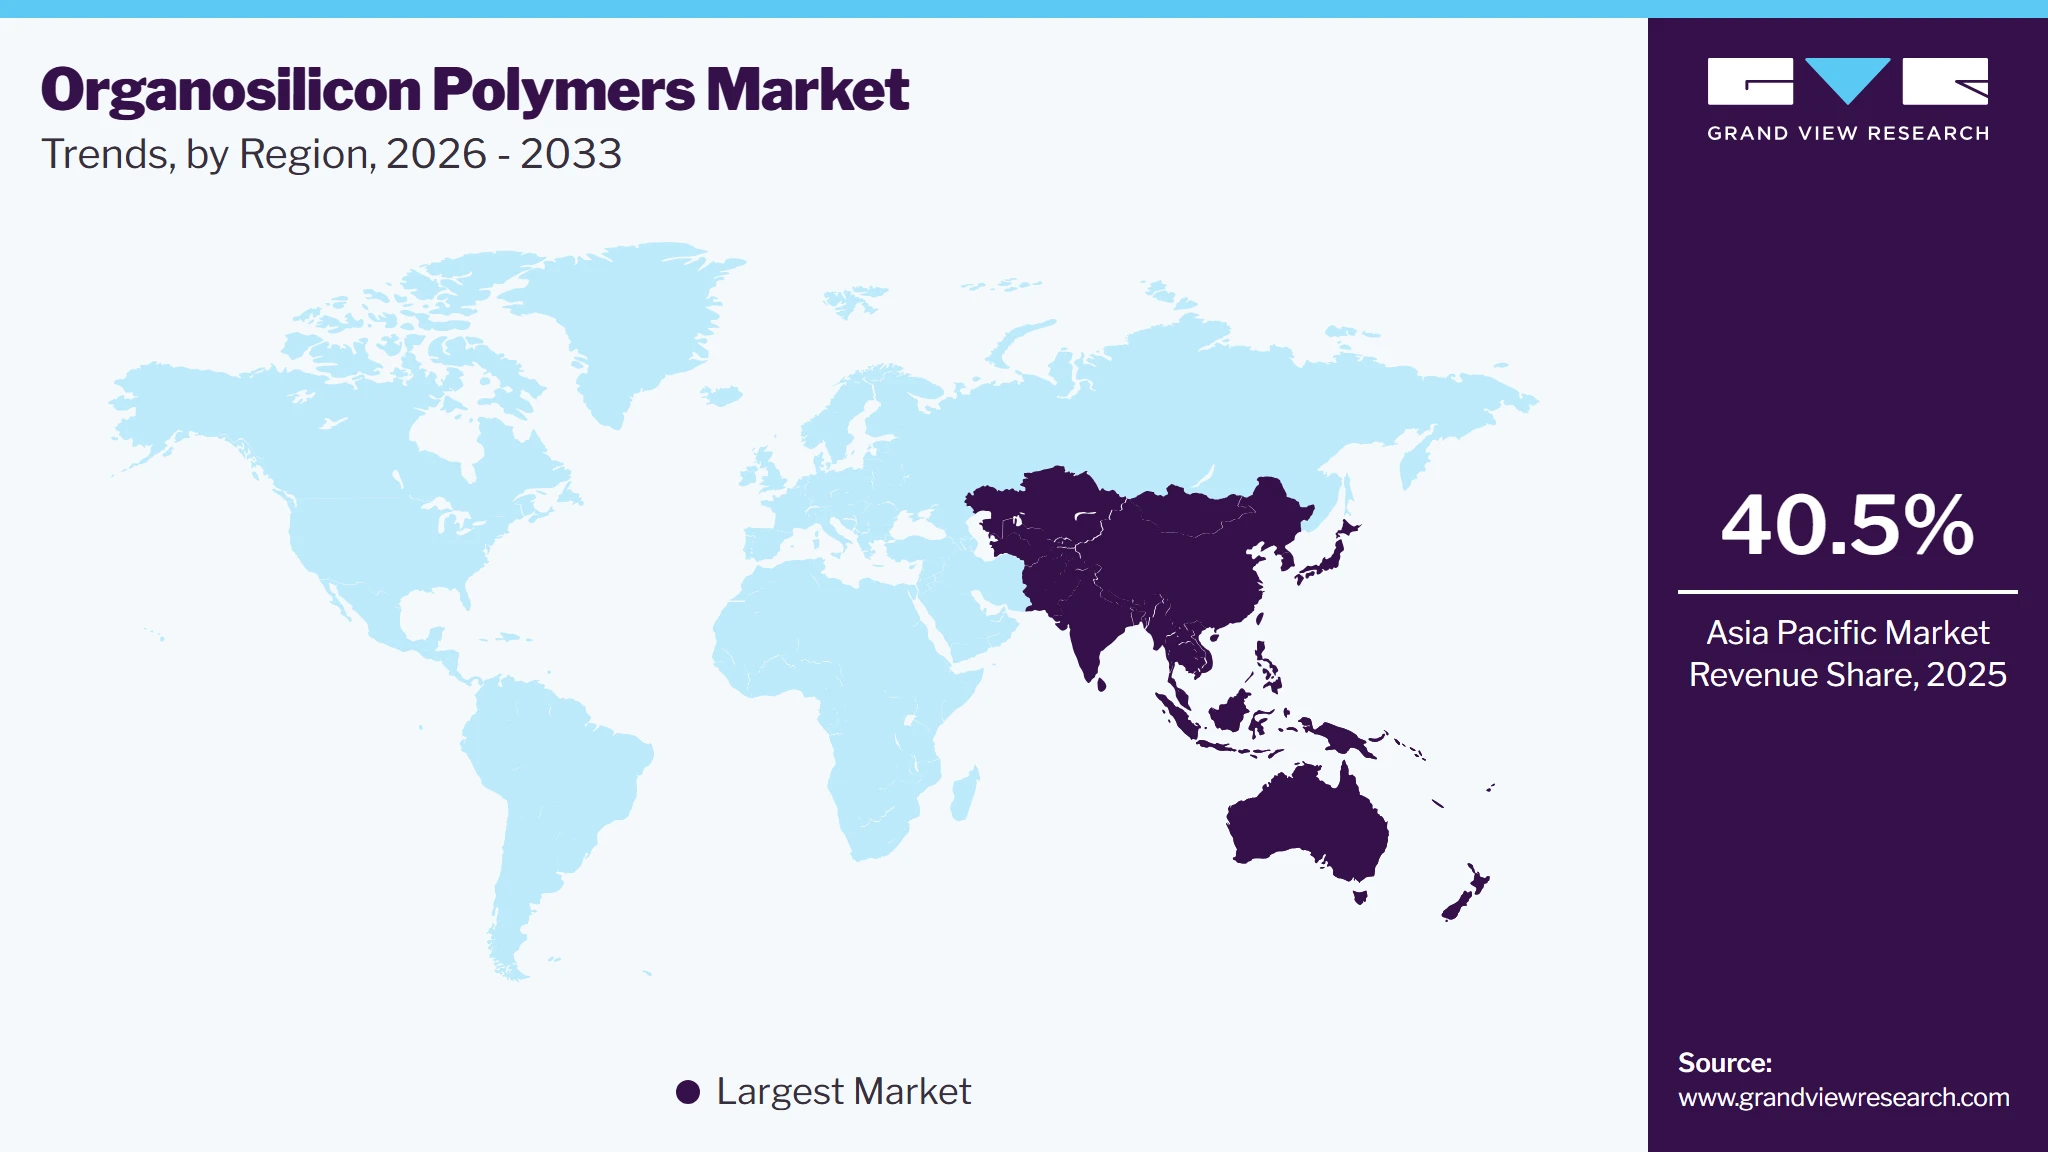
Asia Pacific dominated the organosilicon polymers market with the largest revenue share of 40.5% in 2025, which is attributable to rapid industrialization and large-scale infrastructure development projects. The organosilicon polymers market in China accounted for the largest market revenue share in the Asia Pacific in 2025. Countries such as India, Japan, and South Korea are investing heavily in transportation networks, smart cities, and renewable energy projects, creating a surge in demand for high-performance silicones used in construction materials, protective coatings, and electrical insulation. Additionally, the expansion of regional manufacturing hubs in automotive and consumer electronics is driving the need for silicone-based adhesives, sealants, and lubricants. As the region continues to industrialize, the widespread application of polysiloxane materials across multiple industries is expected to drive strong market growth.
 To learn more about this report, Download Free Sample Report
North America Organosilicon Polymers Market Trends
North America organosilicon polymers (polysiloxane) market is growing due to the increasing demand for high-performance materials in advanced manufacturing and aerospace applications. With major aircraft manufacturers and defense contractors investing in lightweight, heat-resistant, and durable materials, polysiloxane-based coatings, adhesives, and sealants are being widely adopted.
U.S. Organosilicon Polymers Market Trends
The U.S. organosilicon polymers (polysiloxane) market is experiencing a surge in demand for organosilicon polymers due to the rapid expansion of the electric vehicle (EV) sector and advancements in battery technologies. With government incentives promoting EV adoption and manufacturers increasing investments in next-generation battery materials, polysiloxane-based thermal interface materials and encapsulants are in high demand. These materials enhance the safety, efficiency, and lifespan of lithium-ion batteries by providing superior thermal management and electrical insulation. As the U.S. accelerates its transition toward clean energy and sustainable transportation, the adoption of polysiloxane in EV components and energy storage solutions is expected to rise significantly.
Europe Organosilicon Polymers Market Trends
Europe’s focus on sustainability and stringent environmental regulations is a key driver for the growth of the organosilicon polymers market. The European Union's policies on reducing carbon footprints and banning hazardous chemicals have led to increased adoption of low-VOC, bio-based, and recyclable silicone materials. Industries such as automotive, construction, and personal care are shifting toward eco-friendly silicone alternatives to comply with regulatory standards while maintaining high performance. Additionally, growing investments in green infrastructure and energy-efficient buildings are further fueling demand for polysiloxane-based insulation materials, coatings, and sealants that contribute to long-term sustainability.
China organosilicon polymers (polysiloxane) market is witnessing growth due to the rapid advancements in semiconductor manufacturing and 5G technology deployment are significantly boosting the demand for organosilicon polymers. As the world’s largest producer of consumer electronics and telecommunications equipment, China relies heavily on high-performance silicones for chip fabrication, circuit protection, and thermal management in next-generation devices. The government’s push for self-sufficiency in semiconductor production, combined with large investments in 5G infrastructure, has further increased the need for silicone-based encapsulants, adhesives, and dielectric materials. With China maintaining its leadership in tech-driven industries, the demand for polysiloxane materials in electronics and communications will continue to rise.
Key Organosilicon Polymers Company Insights
The organosilicon polymers (polysiloxane) market is highly competitive, with several key players dominating the landscape. Major companies include Akzo Nobel N.V., Dow Chemical Company, Wacker Chemie AG, 3M, Shin-Etsu Chemical Co., Ltd., BASF SE, Mitsui Chemicals, and Momentive Performance Materials. The organosilicon polymers (polysiloxane) market is characterized by a competitive landscape with several key players driving innovation and market growth. Major companies in this sector are investing heavily in research and development to enhance the performance, cost-effectiveness, and sustainability of their types.
Key Organosilicon Polymers Companies
The following key companies have been profiled for this study on the organosilicon polymers market.
-
Akzo Nobel N.V.
-
Dow Chemical Company
-
Wacker Chemie AG
-
3M
-
Shin-Etsu Chemical Co., Ltd.
-
BASF SE
-
Mitsui Chemicals
-
Momentive Performance Materials
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Dow Chemical Company, Wacker Chemie AG, 3M, Shin-Etsu Chemical Co., Ltd., BASF SE, Momentive Performance Materials.)
Expand integrated silicone portfolios across coatings, adhesives, sealants, insulation, and electronics-grade materials.
Use regional manufacturing and technical service networks to support high-spec customers.
Prioritize specialty grades and formulation support over commodity volume alone.
Strong scale, broad product coverage, and established customer relationships.
Better integration across upstream chemistry, formulation, and downstream application support.
Stronger ability to serve demanding industrial, electronics, and performance coatings customers.
High capital intensity and feedstock exposure can pressure margins.
Mature portfolios may face slower growth in commoditized grades.
Large organizations can react more slowly to niche application shifts.
Emerging Players (Akzo Nobel N.V., Mitsui Chemicals.)
Focus on selective organosilicon applications and adjacency-led entry points.
Build value through targeted coatings, sealants, and specialty chemistry positions.
Use partnerships and application-specific innovation to expand relevance.
More flexible portfolio repositioning and faster tactical execution.
Ability to target narrow, high-value segments without legacy complexity.
Strong potential to leverage broader chemical or coatings adjacency.
Lower direct exposure to the core organosilicon value chain.
Limited scale versus the largest silicone-focused incumbents.
Narrower global manufacturing and customer-service footprint.
Recent Developments
-
In January 2025, Evonik announced the launch of its new business line, Smart Effects, which resulted from the merger of its Silica and Silanes divisions, effective January 1, 2025. This strategic move aimed to enhance innovation and sustainability by combining the strengths of molecular silane chemistry and silica particle design. Smart Effects focused on delivering advanced solutions across industries such as green mobility, electronics, and carbon capture, emphasizing eco-friendly products with high value and performance.
-
In May 2024, The EU Commission announced new restrictions on the use of D4, D5, and D6 (siloxanes) under the REACH regulation due to environmental and health concerns. These chemicals, commonly used in cosmetics, cleaning products, and industrial applications, were classified as persistent, bioaccumulative, and toxic (PBT). The restrictions aimed to limit their release into the environment, with specific concentration limits set for products. Businesses were given a transition period to comply with the new rules.
Organosilicon Polymers Market Report Scope
Report Attribute
Details
Market size in 2025
USD 18.6 billion
Estimated market size in 2026
USD 19.3 billion
Projected market size by 2033
USD 27.8 billion
Growth rate
CAGR of 5.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product type, application, region
RegioFinal scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; India; Japan; South Korea; Australia Brazil; Argentina; Saudi Arabia; UAE; South Africa
Key companies profiled
Akzo Nobel N.V.; Dow Chemical Company; Wacker Chemie AG; 3M; Shin-Etsu Chemical Co. Ltd.; BASF SE; Mitsui Chemicals; and Momentive Performance Materials.
Customization scope
Free report customization (equivalent to up to 8 analysts' working days) with purchase-addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Organosilicon Polymers Market Report Segmentation
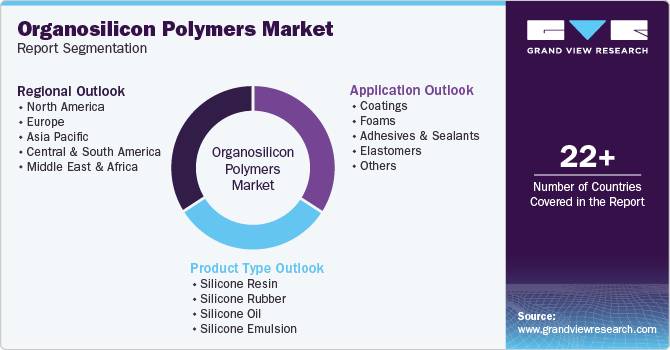
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented organosilicon polymers market report based on product type, application, and region:
 To learn more about this report, Download Free Sample Report
-
Product Type Outlook (Revenue, USD Million; Volume, Kilotons, 2021 - 2033)
-
Silicone Resin
-
Silicone Rubber
-
Silicone Oil
-
Silicone Emulsion
-
-
Application Outlook (Revenue, USD Million; Volume, Kilotons, 2021 - 2033)
-
Coatings
-
Foams
-
Adhesives & Sealants
-
Elastomers
-
Others
-
-
Regional Outlook (Revenue, USD Million; Volume, Kilotons, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
UAE
-
South Africa
-
-
Research Methodology
The organosilicon polymers market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each organosilicon polymers segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product Type
Revenue capture definition
Silicone Resin
Revenue is captured from sales of high-heat, weather-resistant resin grades used in coatings, electrical insulation, adhesives, and industrial protection systems, including specialty and high-solids formulations.
Silicone Rubber
Revenue is generated through elastomer-grade silicone compounds sold for sealing, gasketing, medical, automotive, and electronic applications where flexibility, temperature resistance, and long service life are required.
Silicone Oil
Revenue is captured from fluid-grade silicone products used in lubrication, release, defoaming, cosmetic, and thermal management applications, typically monetized by purity, viscosity, and performance specification.
Silicone Emulsion
Revenue is earned from water-dispersible silicone systems sold to coatings, personal care, textile, and surface-treatment users seeking lower-VOC performance and easier handling.
Segment - Application
Revenue capture definition
Coatings
Revenue is captured through sales into protective, architectural, industrial, and specialty coating systems where silicone chemistry improves durability, weather resistance, and thermal stability.
Foams
Revenue comes from silicone inputs used in foam formulations that require thermal control, processing stability, and performance under compression or repeated exposure.
Adhesives and Sealants
Revenue is generated from silicone-based bonding and sealing materials sold into construction, electronics, transportation, and industrial assembly workflows that require adhesion retention and environmental resistance.
Elastomers
Revenue is captured from cured and uncured silicone elastomer systems supplied for gaskets, tubing, insulation, and precision components where flexibility and heat resistance are critical.
Others
This residual segment captures specialty revenue from niche uses such as lubricants, release agents, defoamers, and surface-treatment systems not covered by the main application buckets.
Estimation Model
Layer Name
Key Question
Description
Demand Layer
Why assess end-use demand?
End-use pull from electronics, coatings, and medical systems defines baseline offtake and sets the market’s commercial scale globally.
Product Layer
Why classify product types?
Silicone resin, rubber, oil, and emulsion carry different margins, viscosities, and customer specifications across downstream coatings, sealants, and elastomer systems.
Company Layer
Why benchmark key suppliers?
Public disclosures, portfolio breadth, and application exposure help triangulate revenue where integrated silicone reporting remains incomplete across leading producers.
Regional Layer
Why evaluate regional demand?
Asia Pacific demand concentration and export-linked supply chains adjust estimates for local pricing, conversion, and competitive intensity.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Country-Level Coverage For Asia Pacific
Expanded the regional analysis to highlight China, India, Japan, and South Korea, with focused commentary on demand concentration, manufacturing depth, and downstream silicone consumption patterns.
Improves regional precision and supports localized commercial planning.
Application Analysis For Electronics And Coatings
Added application-specific commentary on high-performance coatings, thermal management, and insulation use cases, with clearer commercial logic for revenue capture across premium silicone grades.
Strengthens end-use visibility and commercial prioritization.
Sharper Competitive Benchmark
Refined the company view to separate mature and emerging players based on scale, integration, and market presence, with clearer operating and positioning differences.
Improves competitive readability and strategic comparison.
Frequently Asked Questions About This Report
The Asia Pacific organosilicon polymers market accounted for the largest share of 40.5% market size in 2025.
Based on application, the coatings segment accounted for the largest share of 33.4% market size in 2025. Growing infrastructure development, automotive and aerospace production, and industrial manufacturing, together with advances in low-VOC and waterborne technologies, are accelerating organosilicon polymer coating adoption for durable, high-performance surface protection applications.
Silicone rubber segment dominated the market, with a revenue share of 34.3% in 2025.
Some key players operating in the organosilicon polymers market include Akzo Nobel N.V., Dow Chemical Company, Wacker Chemie AG, 3M, Shin-Etsu Chemical Co., Ltd., BASF SE, Mitsui Chemicals, and Momentive Performance Materials.
The global organosilicon polymers market size was valued at USD 18.6 billion in 2025 and is estimated at USD 19.3 billion in 2026.
The global organosilicon polymers market is expected to grow at a CAGR of 5.4% from 2026 to 2033, reaching USD 27.8 billion by 2030.
The increasing use of polysiloxane in electronics, such as smartphones, wearables, and semiconductors, is driving market growth due to its excellent thermal stability and electrical insulation properties.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


